India Macro Daily(Beta Mode)
All Eyes on RBI as Policy Week Kicks Off
Market Snapshot
| Asset | Level | Change |
|---|---|---|
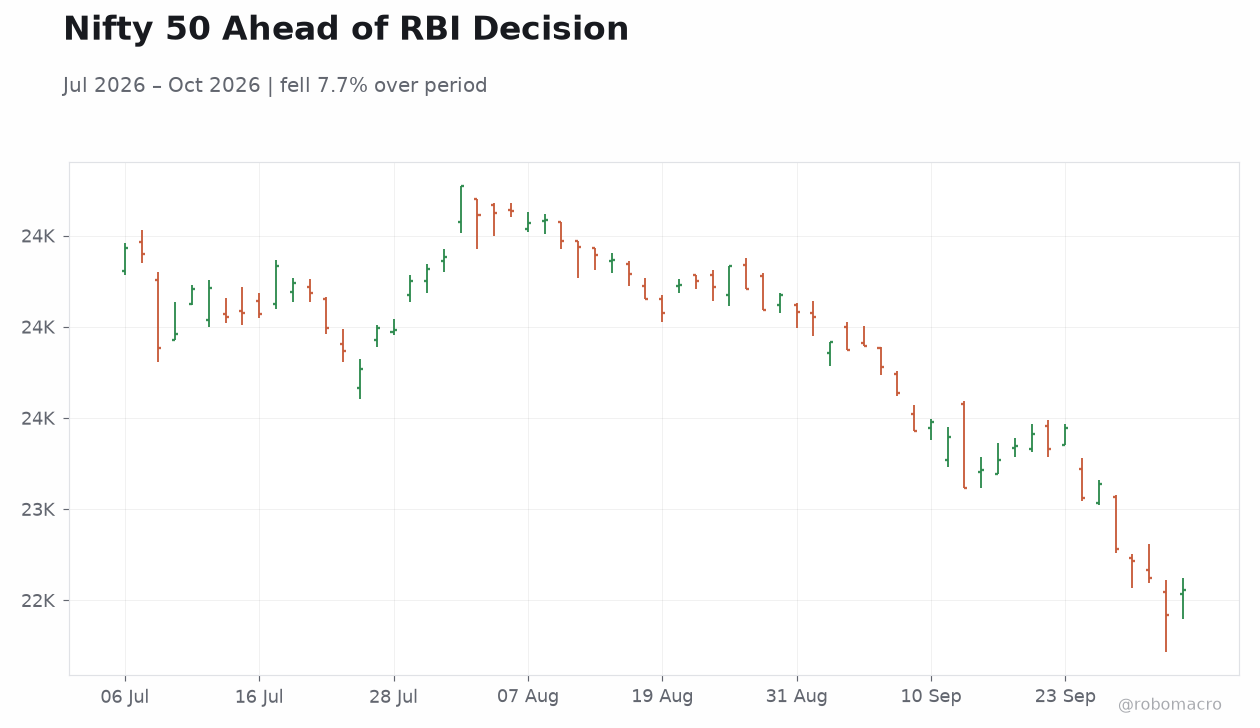
| Nifty 50 | 22,555.75 | +0.60% |
| Sensex | 72,382.47 | +0.66% |
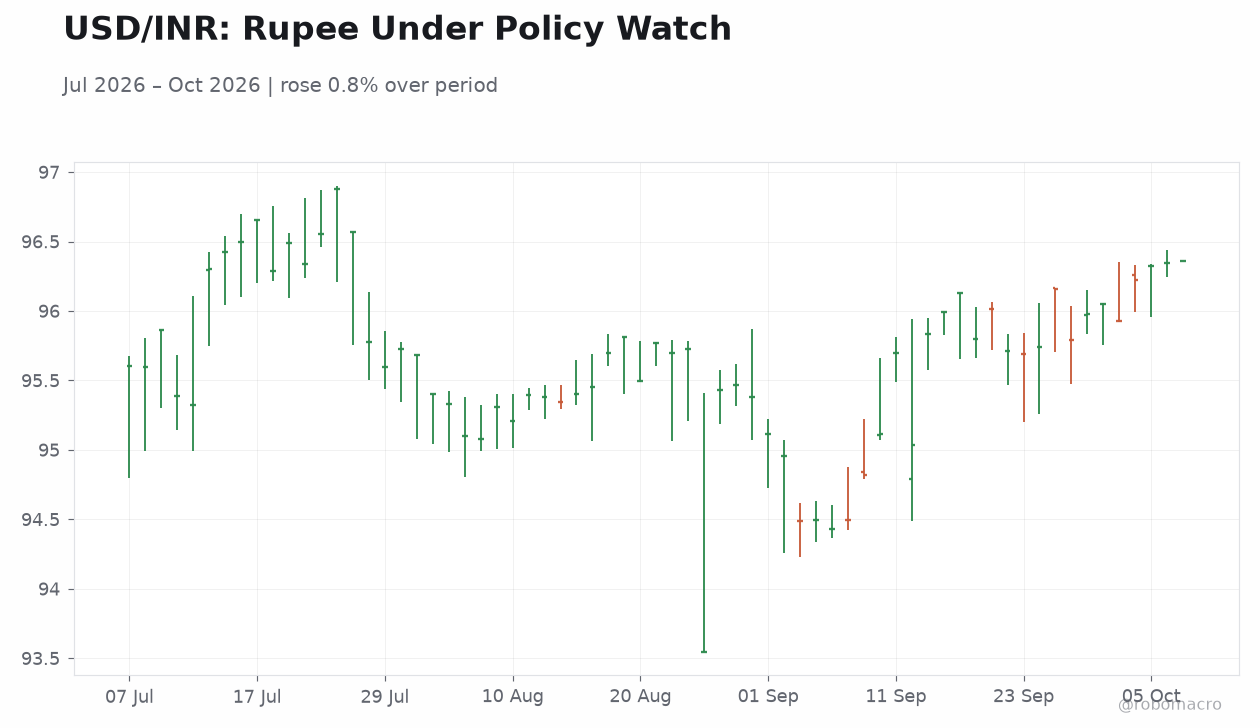
| USD/INR | 96.36 | +0.02% |
| EUR/INR | 108.47 | +0.49% |
| Reliance | 1,218.00 | +2.66% |
| HDFC Bank | 711.45 | +0.94% |
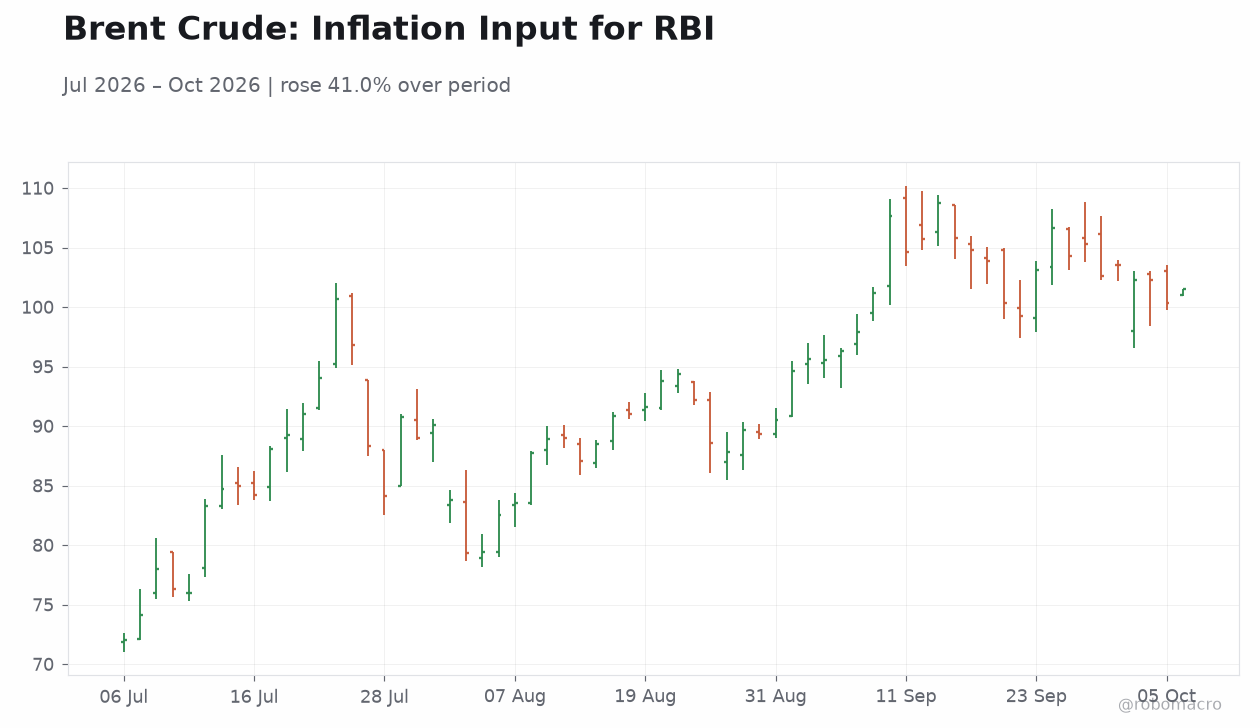
| Brent Crude | 101.46 | +1.14% |
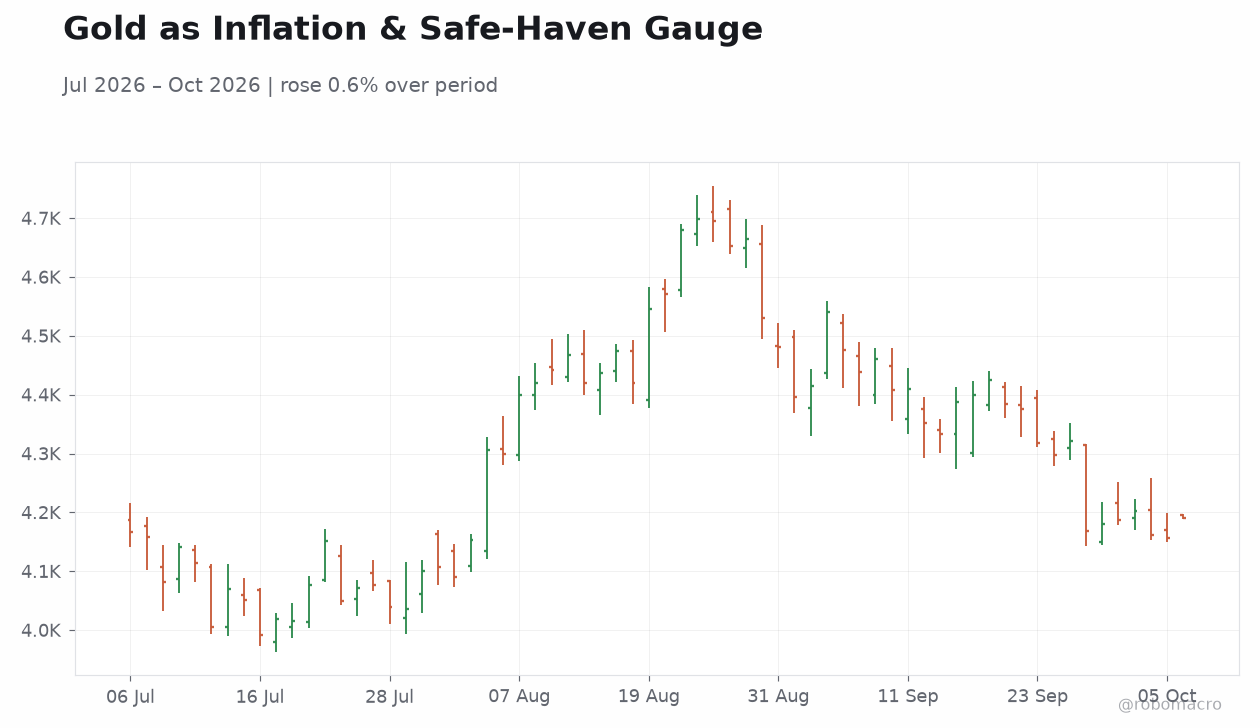
| Gold | 4,193.50 | +0.88% |
| Bitcoin | 85,408.19 | -0.44% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
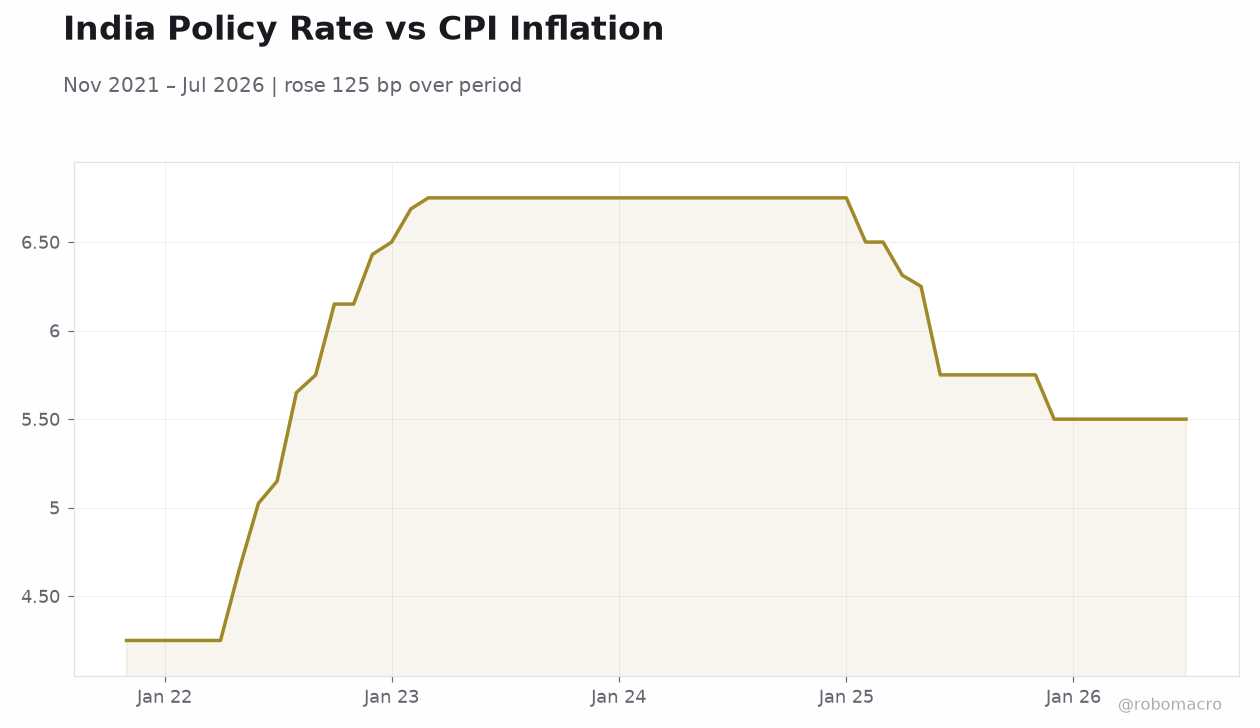 India Policy Rate vs CPI Inflation | Type: macro_line | Short-term / policy rate (%): 5.5 (2026-07-01) | Range: 4.25–6.75 | Trend(5pt): 4.25,6.5,6.75,6.25,5.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wednesday (2026-10-07) | |||
| RBI Interest Rate Decision | 5.25 | 5.50 | 00:30 |
- Equities firmed ahead of Wednesday's RBI decision, with Nifty 50 up 0.60% to 22,555.75 and Sensex gaining 0.66% to 72,382.47
- Rupee edged higher at the start of policy week after slipping to a two-month low on portfolio outflows; RBI intervention suspected
- Consensus sees the repo rate rising 25 bp to 5.50% from 5.25%, with inflation and rupee pressure shaping the debate
Yesterday's Recap
Indian equities closed higher on Monday, with the Nifty 50 advancing 0.60% to 22,555.75 and the Sensex adding 0.66% to 72,382.47, as traders positioned ahead of the Reserve Bank's policy review. Reliance Industries led large-cap gains, rising 2.66% to 1,218.00, while HDFC Bank climbed 0.94% to 711.45. The rupee ticked up at the start of policy week after slipping to an over two-month low late last week on persistent portfolio outflows, with dealers reporting likely RBI support at weaker levels.
Moneycontrol commentary suggested the prolonged equity correction may be setting up for a reversal, a sentiment gaining traction among strategists. Brent crude rose 1.14% to $101.46, keeping imported-inflation math in focus for the MPC, while gold gained 0.88% to $4,193.50 on safe-haven demand. Bitcoin slipped 0.44% to $85,408.19.
The rupee's softer tone against the dollar persisted into the week, with EUR/INR up 0.49% at 108.47. Separately, September's services PMI at 55.2 — a three-month high — reinforced the demand-recovery narrative, with firms citing stronger sales in software, transport and financial services.
The Day Ahead
The centerpiece is Wednesday's RBI interest rate decision, due at 00:30 ET, where consensus expects the repo rate to rise 25 bp to 5.50% from the current 5.25%. Attention will focus equally on the stance and the governor's press conference, particularly how the MPC balances growth support against rupee and inflation pressures. Moneycontrol's technical desk flags 23,000 as the level Nifty bulls need to reclaim, with Bank Nifty needing a break above 55,200 on policy day.
Bond traders are keeping positions light into the announcement after a recent breather, wary of liquidity-operation surprises. Any guidance on the durability of the hiking cycle will drive the next leg for rate-sensitive sectors and the currency. Expect elevated volatility in banking, autos and consumer names around the statement.
Other Economic Notes
The India-China thaw faces hard economic tests, with China's 16.3% share of global merchandise exports in 2025 dwarfing India's 1.7% — a gap that underscores how far Indian manufacturing must travel to capture supply-chain shifts. ↓ p.2