RBI Hikes to 5.50% as Crude Shock Hits Equities
5.50 RBI Interest Rate Decision
Nifty 5022,603.05-0.76%
Sensex72,638.70-0.59%
USD/INR96.76+0.40%
EUR/INR108.32-0.07%
Market Snapshot
| Asset | Level | Change |
|---|
| Nifty 50 | 22,603.05 | -0.76% |
| Sensex | 72,638.70 | -0.59% |
| USD/INR | 96.76 | +0.40% |
| EUR/INR | 108.32 | -0.07% |
| Reliance | 1,178.00 | -2.46% |
| HDFC Bank | 692.25 | -1.49% |
| Brent Crude | 103.81 | +3.60% |
| Gold | 4,173.00 | +0.78% |
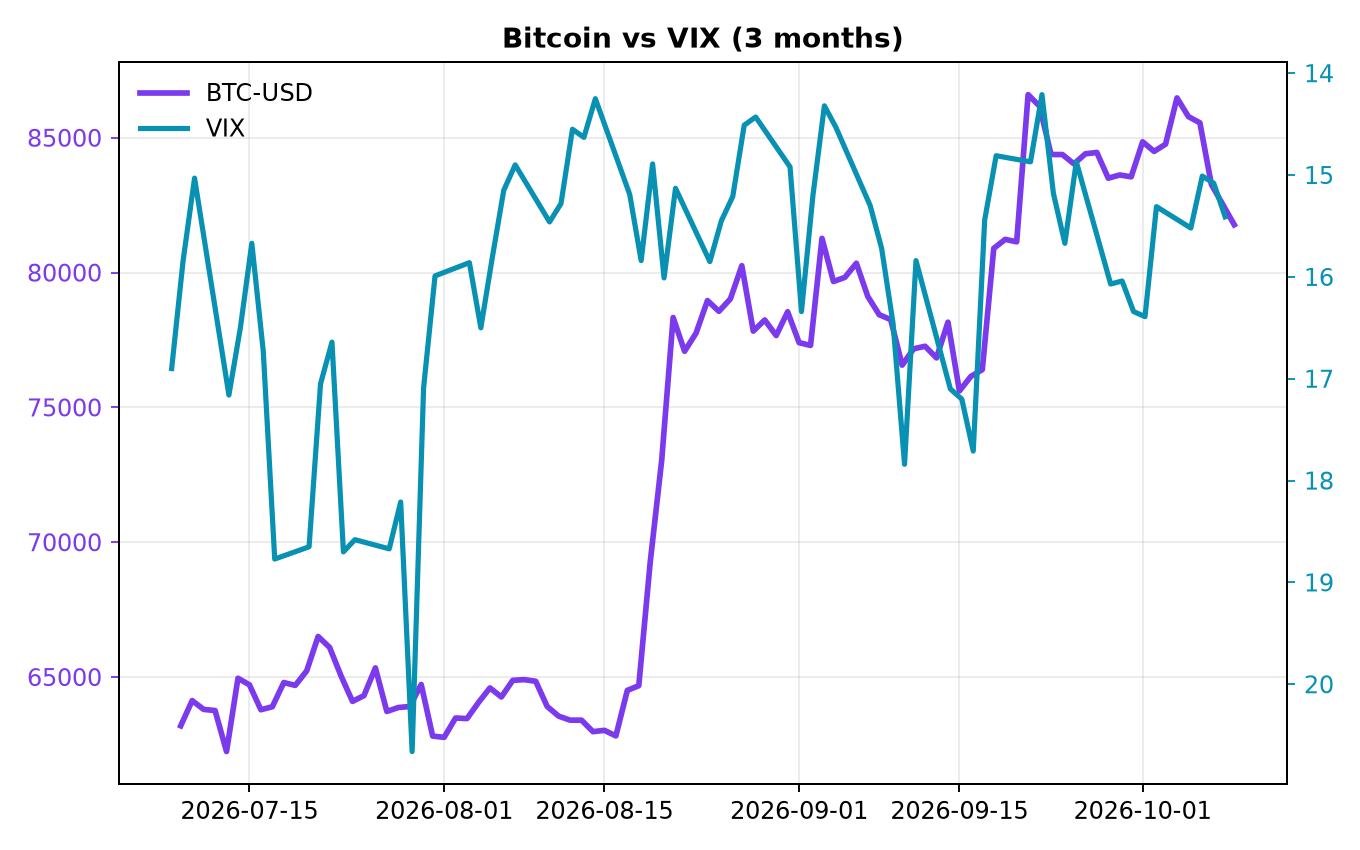
| Bitcoin | 81,691.29 | -1.90% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data |
Prior |
Cons |
Actual |
| RBI Interest Rate Decision | 5.25 | 5.50 | 5.50 |
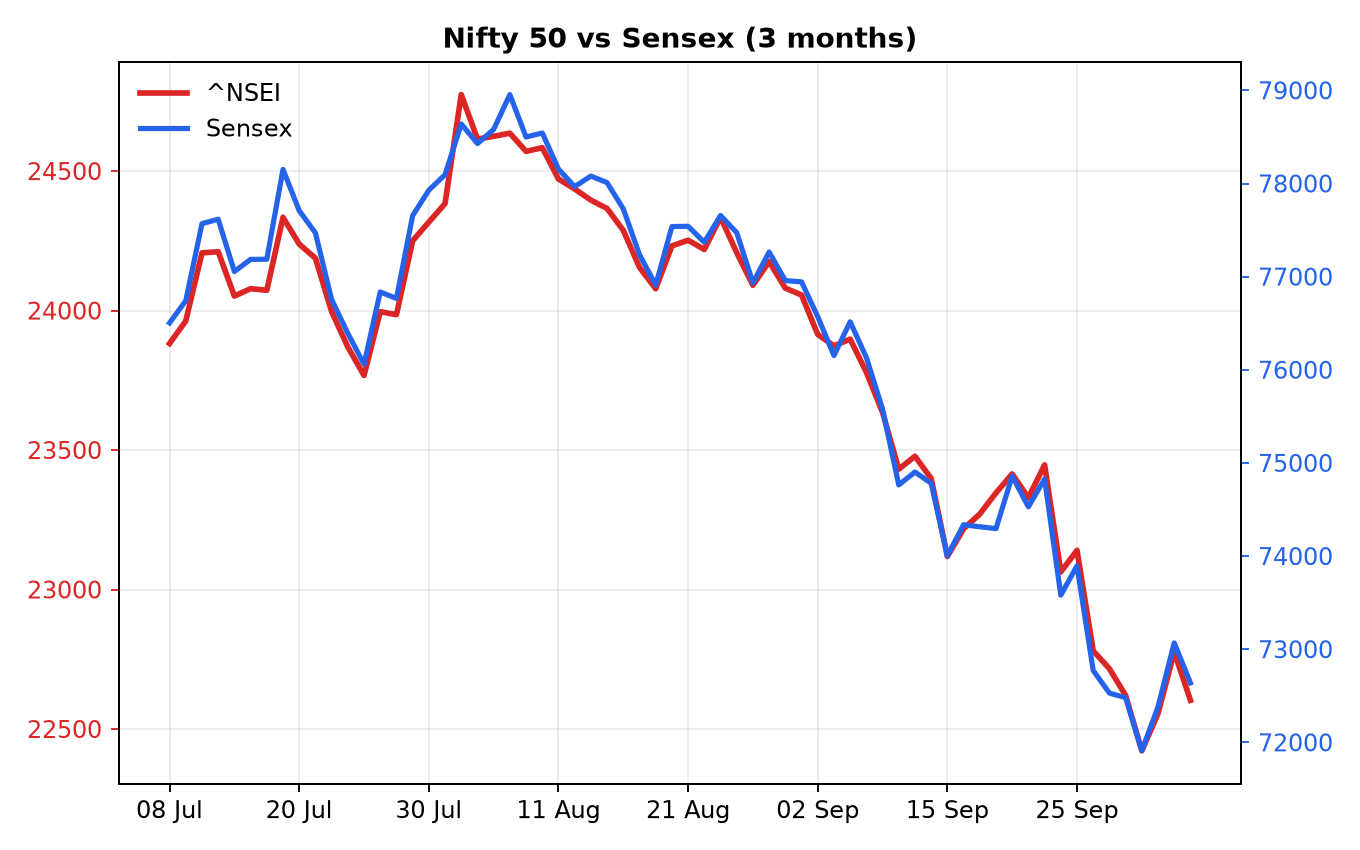
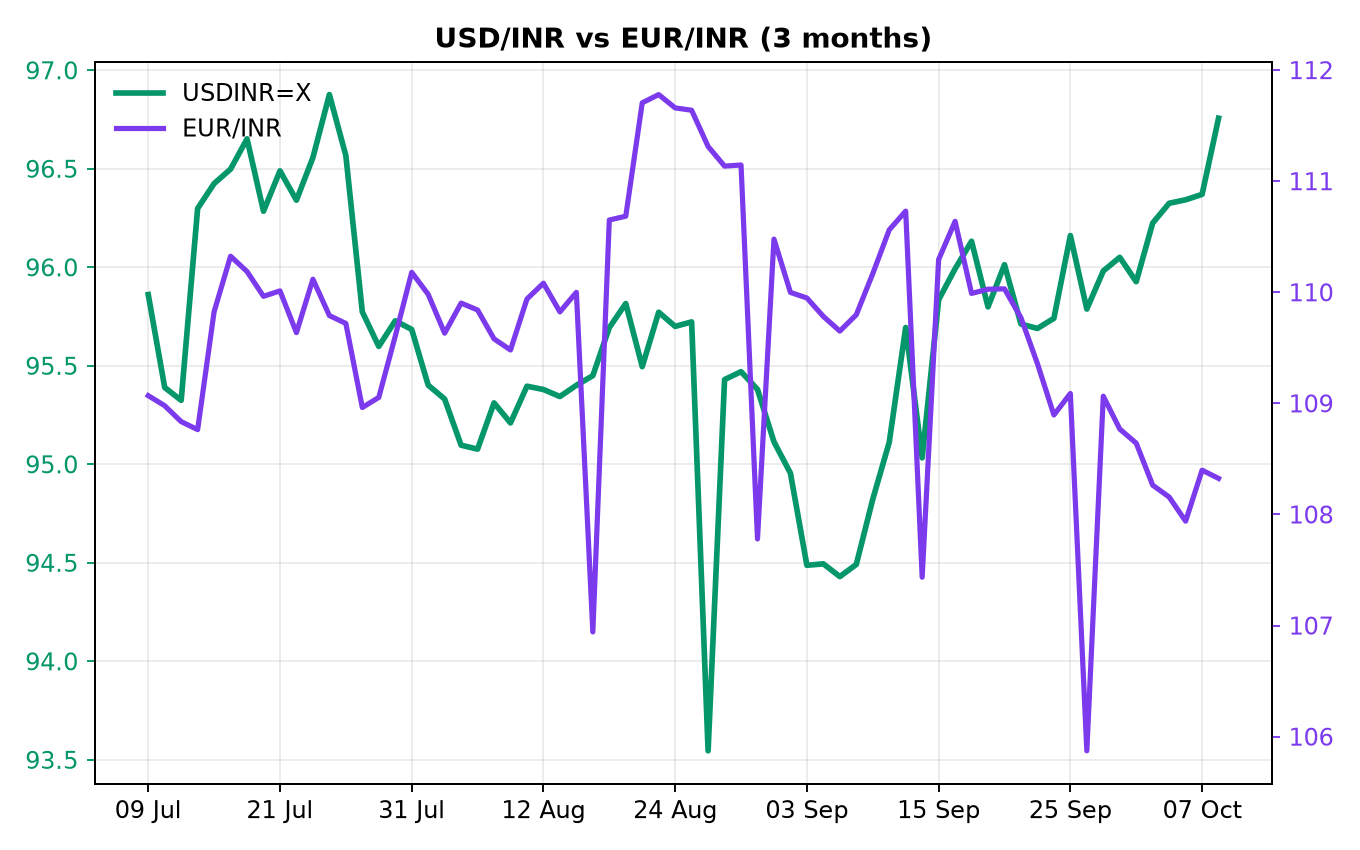
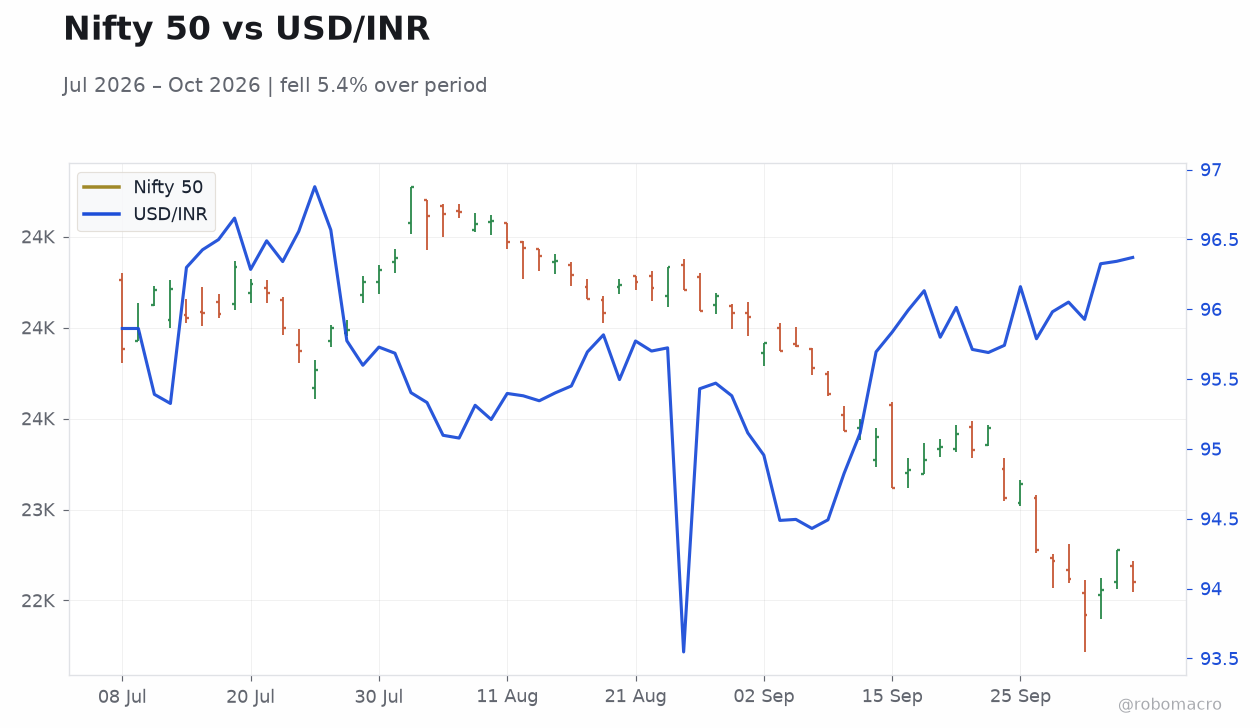 Nifty 50 vs USD/INR | Type: market_hloc | Nifty 50: 2.26e+04 (2026-10-07) | Range: 2.242e+04–2.477e+04 | Trend(5pt): 2.388e+04,2.432e+04,2.425e+04,2.312e+04,2.26e+04 | USD/INR: 96.76 (2026-10-08) | Range: 93.55–96.88 | Trend(6pt): 95.86,95.68,95.7,95.84,96.37,96.76
Today's Economic Events
| Data |
Prior |
Cons |
Time |
| No events available |
- RBI raised the repo rate 25 bp to 5.50%, its first hike since 2023, citing inflation pressure from the Middle East conflict and signalling more tightening ahead
- Nifty 50 fell 0.76% to 22,603 and Sensex lost 0.59% to 72,639 as surging crude and the policy surprise rattled risk appetite
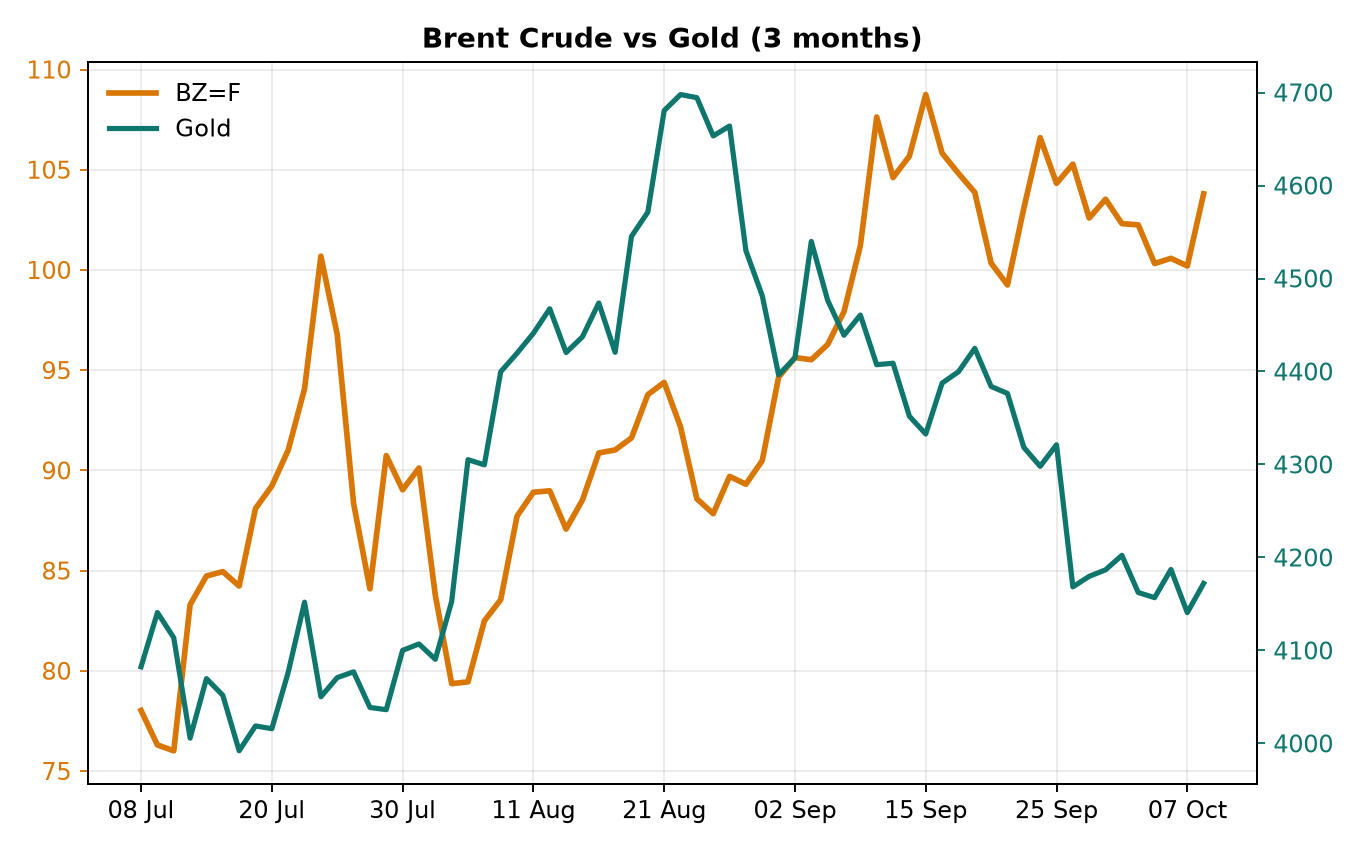
- USD/INR weakened 0.40% to 96.76 despite reported RBI intervention near the open; Brent jumped 3.60% to $103.81
Yesterday's Recap
The Reserve Bank of India delivered a 25 basis point hike on Wednesday, lifting the repo rate to 5.50% from 5.25% — the first increase in the policy rate since 2023. The move came as the Middle East conflict stoked imported inflation in Asia's third-largest economy, and the MPC's tone suggested the tightening cycle may not be over. Equities struggled into the decision: the Nifty 50 closed at 22,603.05, down 0.76%, while the Sensex settled 0.59% lower at 72,638.70 after a session that saw intraday swings of more than 1,000 points on the Sensex.
Moneycontrol reported the index fell as much as 1,050 points before recovering 450 points from the lows, with surging crude and the RBI tightening cited as the key drags. The rupee weakened 0.40% to 96.76 against the dollar, and traders told ET the central bank likely intervened near the open to support the currency. Brent crude surged 3.60% to $103.81, compounding the external balance pressure, while gold gained 0.78% to $4,173 as a haven bid persisted.
Large-caps bore the brunt: Reliance dropped 2.46% to 1,178 and HDFC Bank fell 1.49% to 692.25, with GQG's selling in ITC and Adani group names adding to the gloom as the Nifty touched a 52-week low.
The Day Ahead
The calendar shows no scheduled Indian economic releases for Thursday or Friday, leaving the market to digest the RBI's hawkish shift without fresh data. Attention turns to how the rate-sensitive sectors — banks, autos and real estate — reprice the higher-for-longer rate path, and whether Bank Nifty can reclaim the 55,200 level traders flagged ahead of the policy. Fixed-income desks will watch liquidity operations and any open-market conduct for signals on how aggressively the RBI backs the rupee while draining durable liquidity.
The India–US bond yield spread, sitting near a 22-year low despite the hike, will be a key gauge of whether the move restores carry appeal for foreign investors. Comments from RBI officials in the coming days will be scrutinised for confirmation of the follow-up hike narrative. Corporate earnings and management commentary on input costs and financing spreads will fill the data vacuum.
Page 1
Never miss an issue
Subscribe to India Macro Daily and get each new issue delivered to your inbox.
Already a member? Visit robomacro.com
to log in and manage subscriptions, or use Forgot Password to set a password.