| Asset | Level | Change |
|---|---|---|
| Nifty 50 | 22,622.70 | -0.44% |
| Sensex | 72,781.89 | -0.34% |
| USD/INR | 95.15 | -0.14% |
| EUR/INR | 106.44 | -0.19% |
| Reliance | 1,215.00 | +3.44% |
| HDFC Bank | 726.85 | +2.27% |
| Brent Crude | 105.63 | -0.41% |
| Gold | 4,176.60 | +1.67% |
| Bitcoin | 82,297.49 | +0.90% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Year-over-Year | 4.82 | 5.40 | 5.54 |
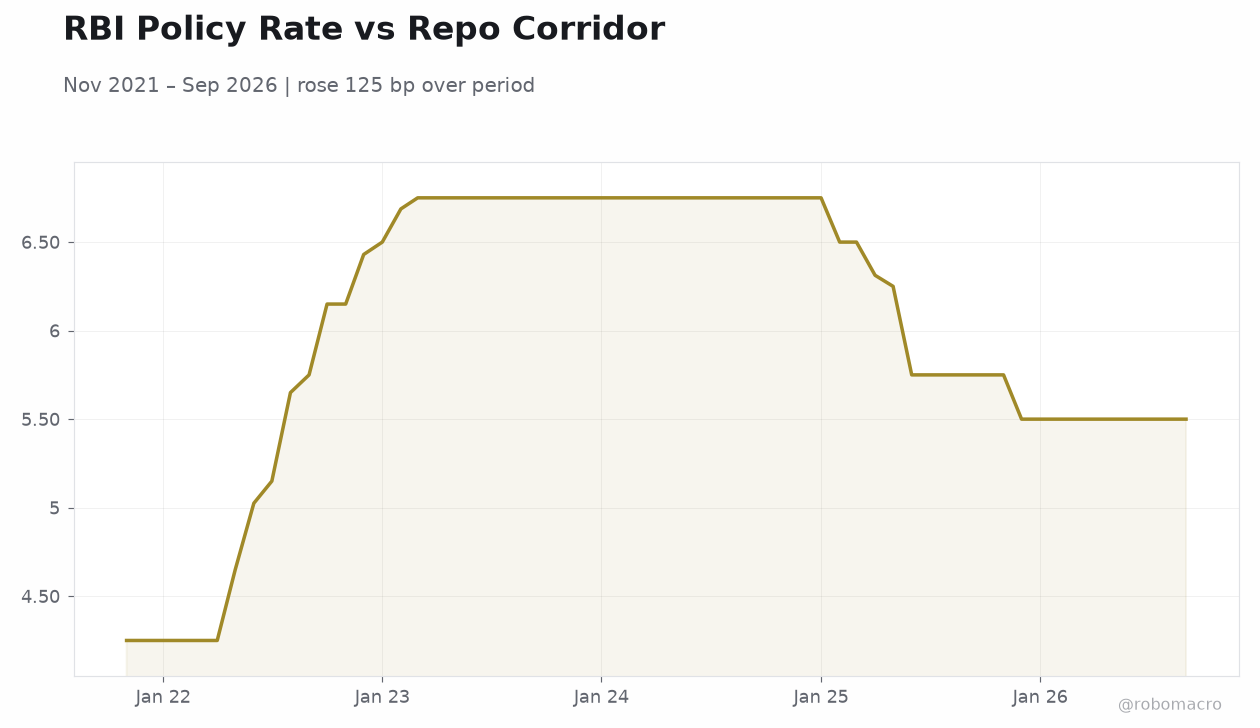
RBI Policy Rate vs Repo Corridor | Type: macro_line | Short-Term Interest Rate (%): 5.5 (2026-09-01) | Range: 4.25–6.75 | Trend(5pt): 4.25,6.5,6.75,6.25,5.5
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
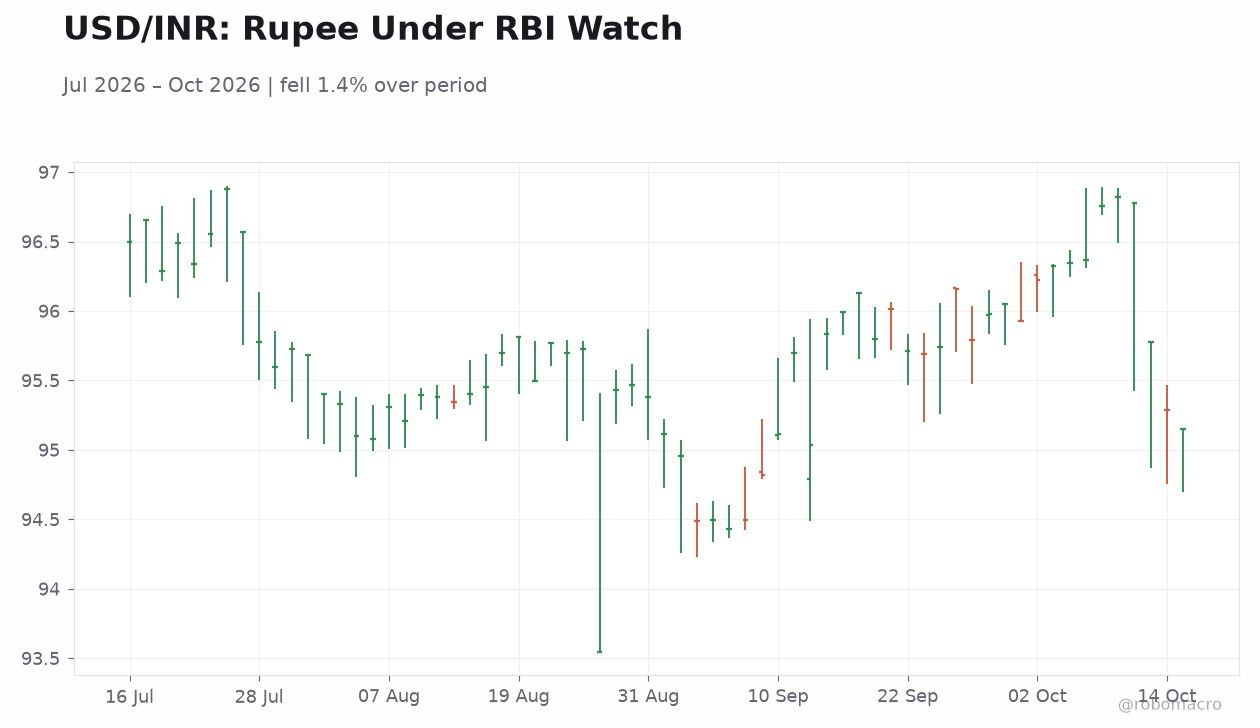
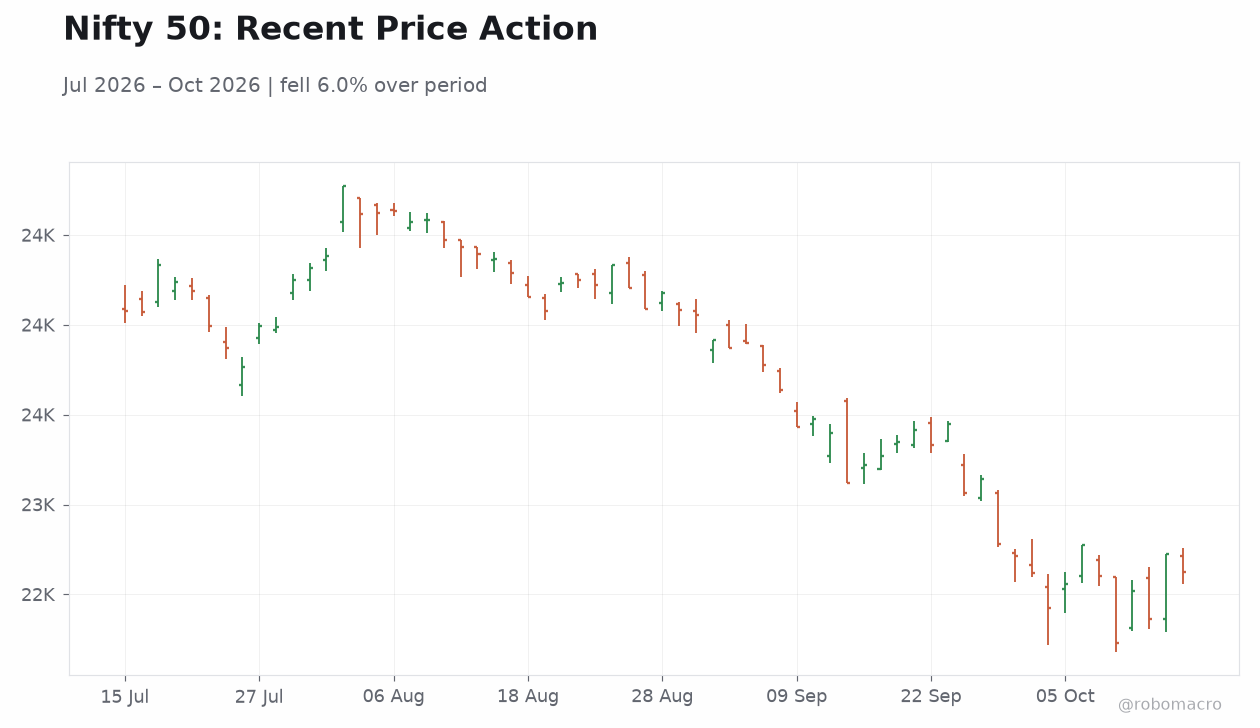
Indian equities closed lower but held up better than regional peers, with the Nifty 50 shedding 0.44% to 22,622.70 and the Sensex easing 0.34% to 72,781.89. The inflation print for the year to the September period came in at 5.54%, exceeding both the 5.4% consensus and the prior 4.82% reading, reinforcing the narrative that price pressures remain sticky above the RBI's comfort band. Currency markets were the standout story: the rupee appreciated to a one-month high against the dollar, with USD/INR last at 95.15, down 0.14% on the day, after the Reserve Bank moved to curb speculative positions and clarified the scope of its forex restrictions.
Bankers estimate the central bank has deployed roughly half of the $140 billion in FX inflows accumulated this year defending the currency, underscoring the scale of intervention. Corporate earnings provided pockets of strength, with Reliance jumping 3.44% to 1,215.00 and HDFC Bank gaining 2.27% to 726.85, keeping the broader index decline contained. Gold advanced 1.67% to 4,176.60, while Brent crude slipped 0.41% to $105.63, a modest relief for India's import bill.
The India VIX remained in focus as traders assessed whether the rupee's stabilisation would durably lower hedging costs.
The domestic calendar is light today, with no scheduled data releases, shifting attention to secondary flows and corporate results. Markets will continue to digest the inflation surprise and its implications for the RBI's policy path, with Union Bank's research arm floating the possibility of an unscheduled rate hike if rupee and inflation pressures persist. Importers are reportedly pressing on with hedging programmes despite the RBI's higher-cost deterrents, and hedging demand will be a key tell on the credibility of the central bank's FX stance.
Attention also stays on the India-US trade track, after the trade minister indicated the first phase of a bilateral deal is in the final stages of drafting. Earnings season remains in full swing, with IT names in focus given the sector's weight in index performance. Global cues, particularly US inflation data, will shape the opening direction for the rupee and bond markets.
Subscribe to India Macro Daily and get each new issue delivered to your inbox.
Already a member? Visit robomacro.com to log in and manage subscriptions, or use Forgot Password to set a password.
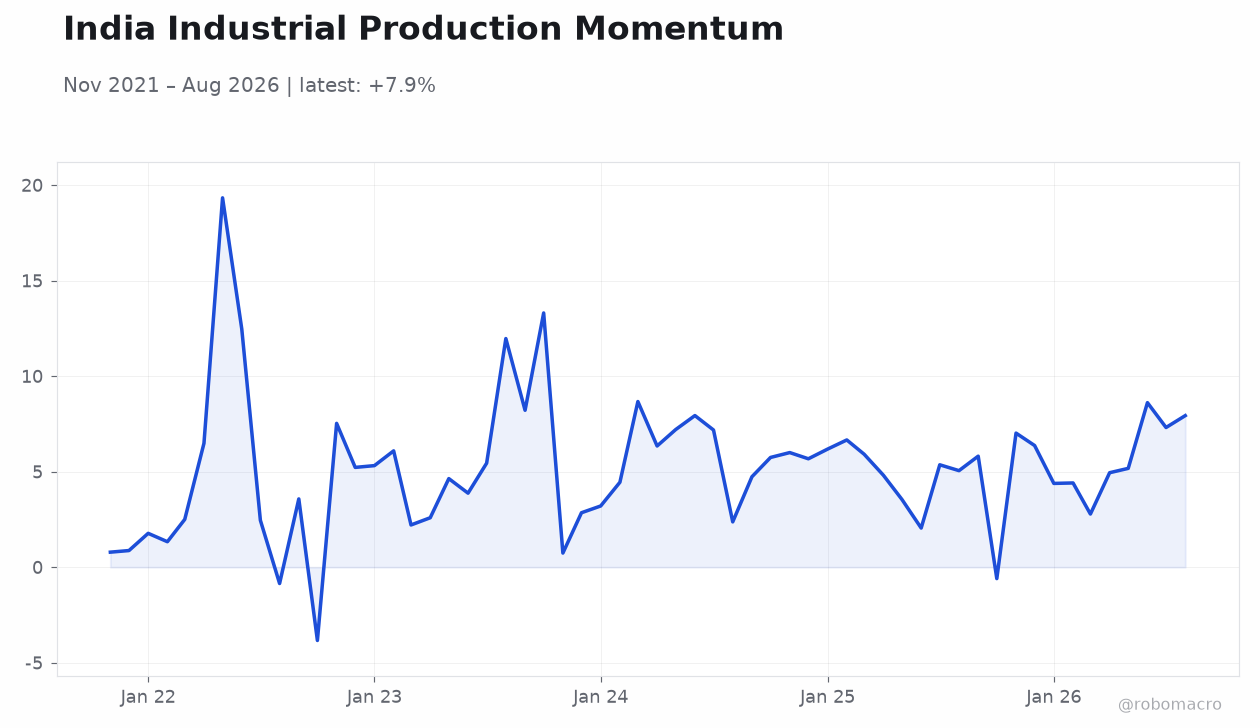
India Industrial Production Momentum | Type: macro_line | Industrial Production Index: 7.935 (2026-08-01) | Range: -3.835–19.33 | Trend(6pt): 0.7882,5.318,8.671,3.545,7.313,7.935
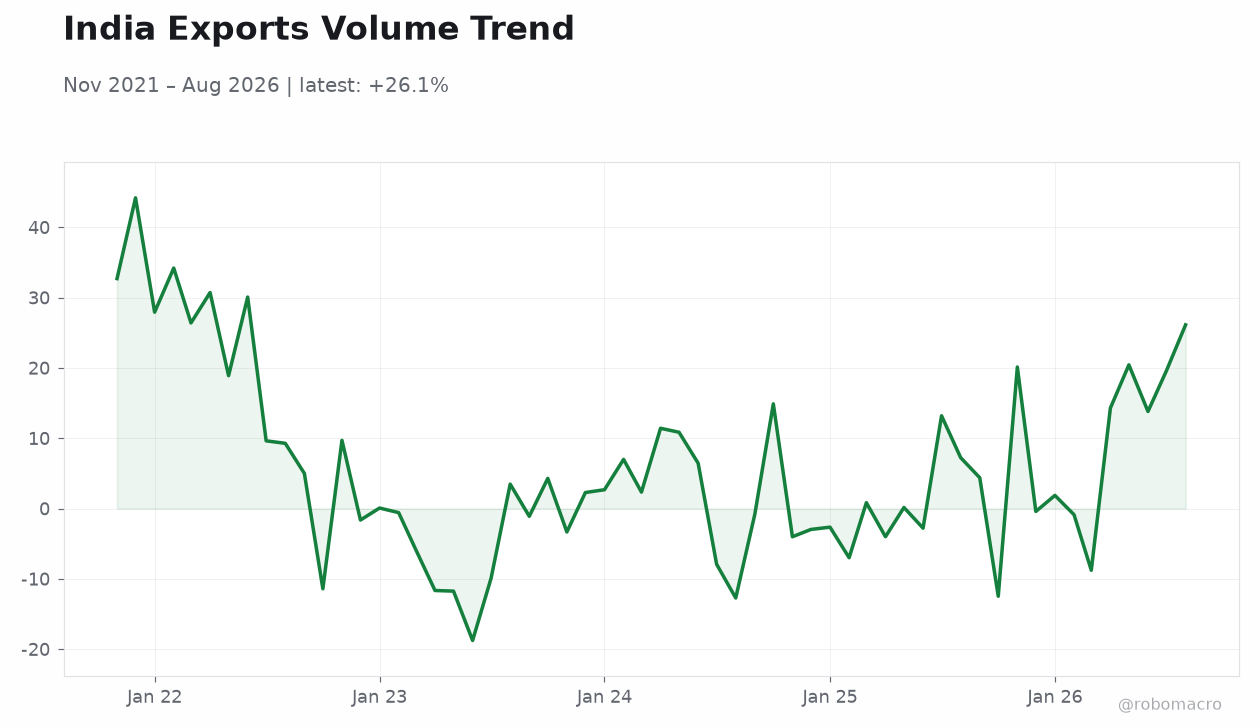
India Exports Volume Trend | Type: macro_line | Exports Value Index: 26.13 (2026-08-01) | Range: -18.76–44.2 | Trend(6pt): 32.71,0.07788,2.343,0.1547,19.62,26.13
USD/INR: Rupee Under RBI Watch | Type: market_hloc | USD/INR: 95.15 (2026-10-15) | Range: 93.55–96.88 | Trend(6pt): 96.5,95.31,95.38,95.71,95.29,95.15
Nifty 50: Recent Price Action | Type: market_hloc | Nifty 50 Index: 2.262e+04 (2026-10-14) | Range: 2.223e+04–2.477e+04 | Trend(5pt): 2.408e+04,2.464e+04,2.418e+04,2.333e+04,2.262e+04
India's growth story continues to attract upgrades, with IMF projections now showing the economy overtaking Japan to become the world's fourth-largest by 2027. Officials have attributed recent growth revisions to export gains under free trade agreements, a narrative that supports the structural bull case even as cyclical inflation complicates the near-term picture. The trade deal with the US, if concluded, would deepen tariff-free access for Indian goods and services exporters.
Meanwhile, the divergence between India's equity resilience and the sharp correction in Asian AI-linked names has drawn commentary, with Indian proxy plays on the AI theme outperforming. The policy mix debate is widening, with some analysts arguing rate hikes and tax cuts may both be needed to defend the rupee without sacrificing growth.
Global risk sentiment is being tested by a sharp unwind in Asian technology stocks, though Indian equities have decoupled to a degree, rallying on domestic earnings and the rupee's recovery. US inflation data due this week is the key external catalyst, with its implications for the dollar and emerging-market flows front and centre for the RBI. Oil has eased slightly, with Brent at $105.63, offering marginal comfort for India's external accounts, though prices remain elevated.
Gold's 1.67% rise to 4,176.60 reflects continued haven demand amid policy uncertainty. Bitcoin's 0.90% gain to 82,297.49 signals appetite for risk assets remains intact in pockets. The dollar's trajectory against the rupee, EUR/INR at 106.44, and broader EM currencies will hinge on the Fed's next moves.
↓ p.3
India's relative insulation from the AI-driven correction in North Asia is being attributed to its services-heavy index composition and domestic liquidity.
The central bank has dominated the narrative this week, first through market intervention and then through a formal clarification of the scope of its forex curbs after days of volatility. Governor commentary has been credited with lifting sentiment, and the rupee's move to a one-month high suggests the measures gained traction. The scale of intervention is notable: bankers estimate half of the $140 billion in FX inflows has already been spent defending the currency, raising questions about how long the defence can be sustained if pressure resumes.
The RBI's strategy appears to be twofold — dampening speculation through administrative measures while allowing the rupee to find a more orderly path. With CPI at 5.54% and above consensus, the inflation-targeting framework is under scrutiny, and Union Bank's research suggests an unscheduled rate hike is possible if the rupee and inflation fail to stabilise. For bond markets, the combination of intervention-driven liquidity absorption and sticky inflation argues for a higher-for-longer stance, with the 10-year yield likely to remain rangebound.
The next MPC meeting will be critical for formalising the guidance.