RoboMacro ResearchAlso todaySee the US Macro Daily

India Macro Daily(Beta Mode)

October 30, 2026 robomacro.com

Rupee Defense Drains Liquidity as Growth Forecasts Firm

6.70 Industrial Production7.60 Manufacturing Production
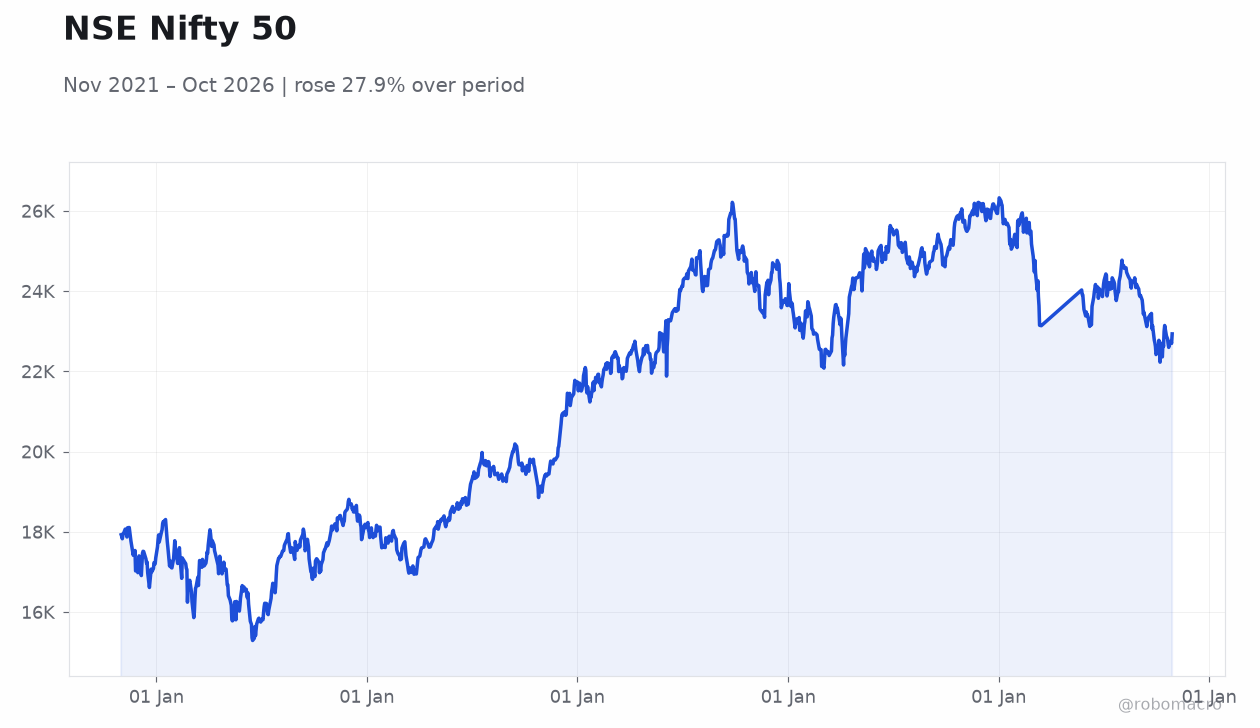
Nifty 5022,698.85-0.22%
Sensex73,246.03-0.48%
USD/INR95.21+0.03%
EUR/INR106.17+0.39%

Market Snapshot

AssetLevelChange
Nifty 5022,698.85-0.22%
Sensex73,246.03-0.48%
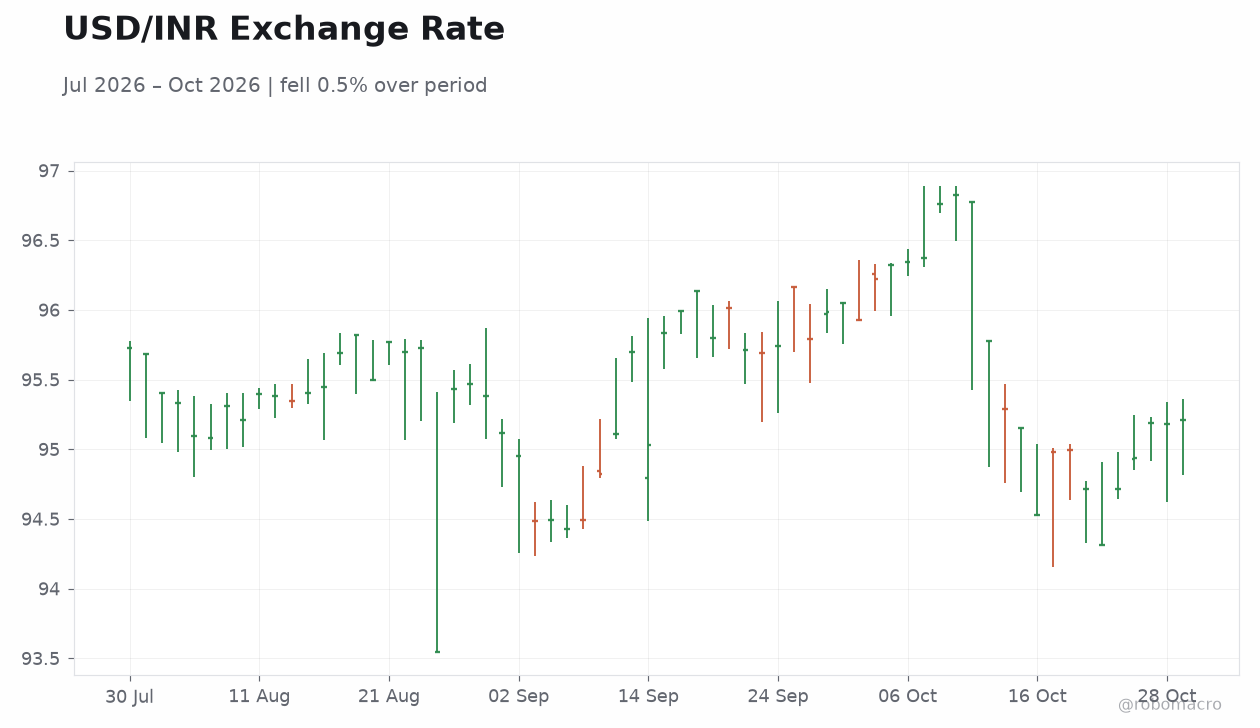
USD/INR95.21+0.03%
EUR/INR106.17+0.39%
Reliance1,167.40+0.81%
HDFC Bank683.30-0.29%
Brent Crude111.53-3.29%
Gold4,022.70-0.71%
Bitcoin76,763.98-5.54%
India 2Y Govt Yield--
India 10Y Govt Yield--

Prior Economic Events

Data Prior Cons Actual
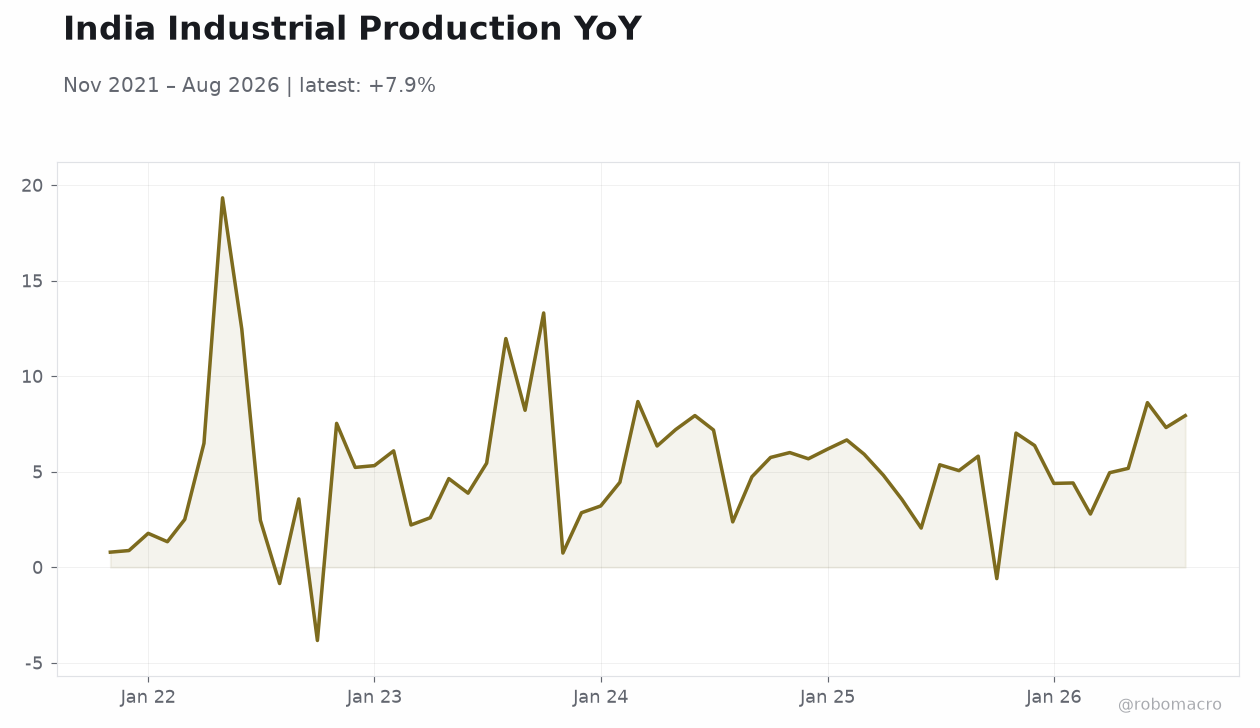
Industrial Production Year-over-Year87.206.70
Manufacturing Production Year-over-Year9-7.60
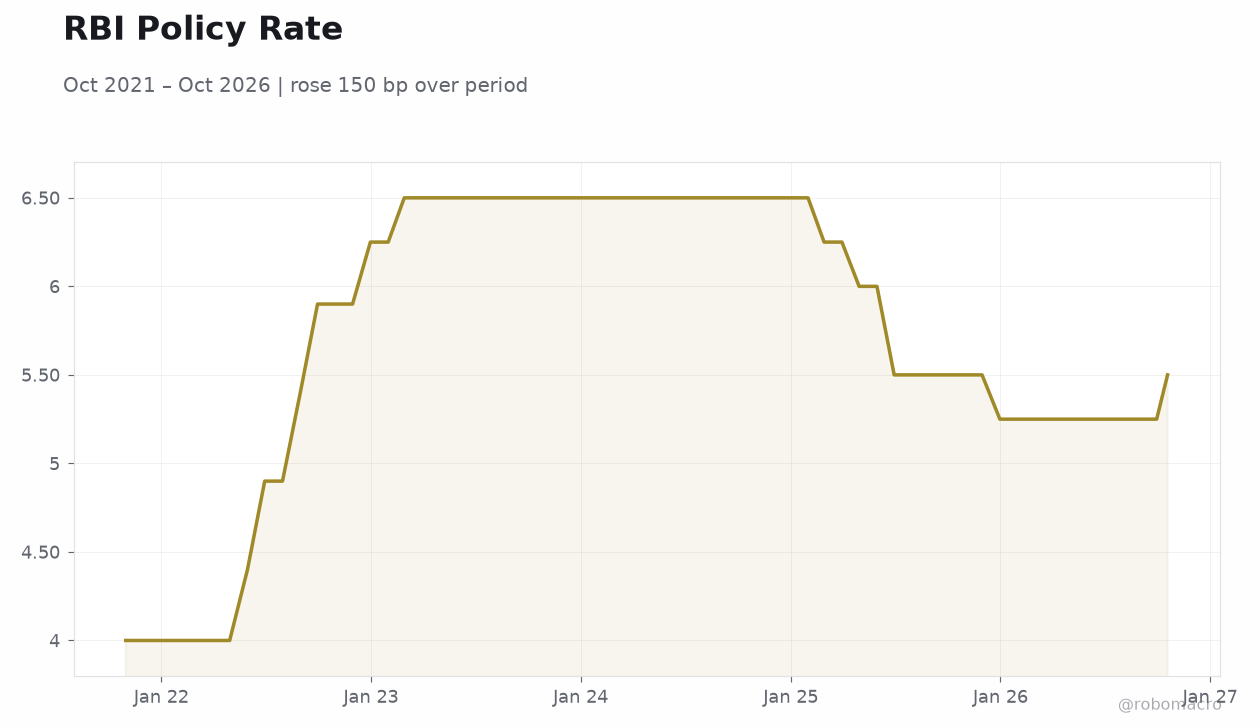
RBI Policy RateRBI Policy Rate | Type: macro_line | Policy rate %: 5.5 (2026-10-19) | Range: 4–6.5 | Trend(5pt): 4,6.25,6.5,5.5,5.5

Today's Economic Events

Data Prior Cons Time
No events available
  • RBI's October dollar sales hit $18.2bn, the highest this year, as the central bank defends the rupee amid balance-of-payments pressure.
  • Bank cash surplus has collapsed roughly 96% as liquidity tightening accompanies the FX defense, with the rupee ending flat near a two-week low.
  • Finance ministry projects FY27 growth at 7.3% and Q2 FY27 GDP at 7.35%, even as it flags inflation risks; industrial production printed 6.7% y/y.

Yesterday's Recap

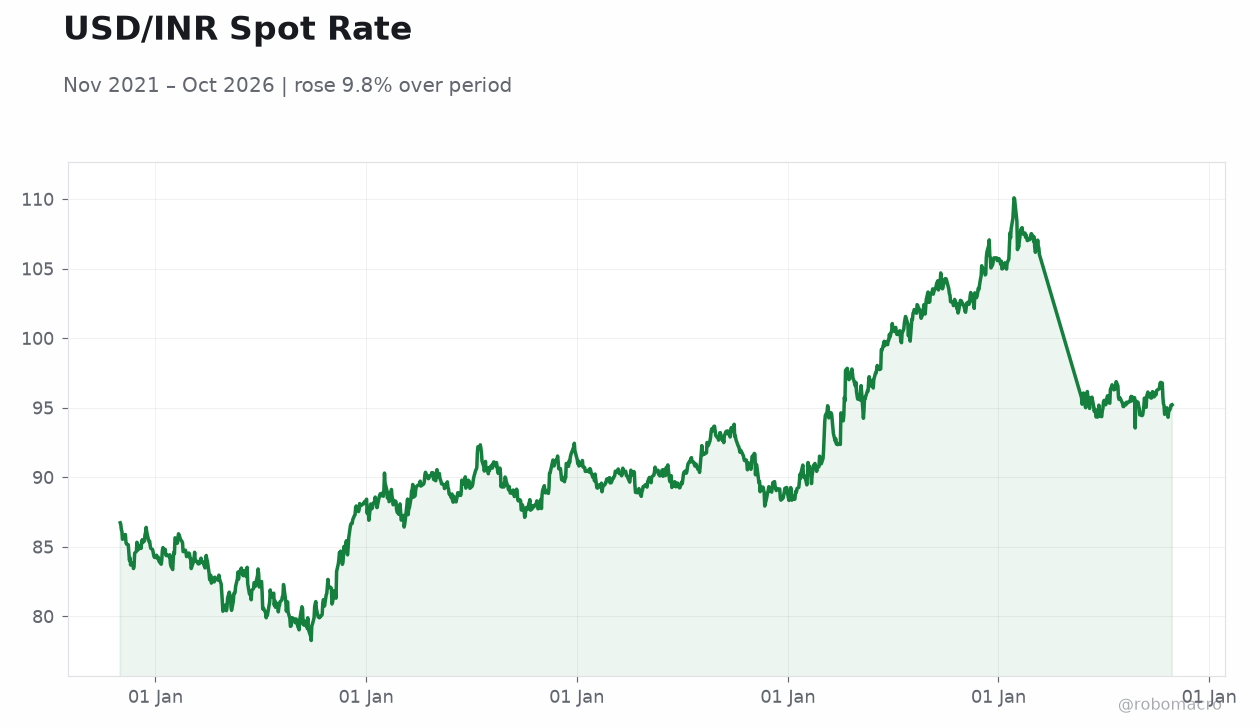
India's October industrial production printed at 6.7% y/y, below the 7.2% consensus and down from 8% previously, while manufacturing production came in at 7.6% y/y versus 9% prior — a clear sequential slowdown in factory activity. Equities softened, with the Nifty 50 down 0.22% to 22,698.85 and the Sensex off 0.48% to 73,246.03, though reports noted the Sensex settled some 650 points above its intraday low as selling was absorbed late in the session. The rupee ended flat after touching a two-week low, with USD/INR at 95.21 (+0.03%) and EUR/INR at 106.17 (+0.39%), as oil prices and RBI actions remained the dominant drivers.

Brent crude fell 3.29% to $111.53, offering marginal relief on the import bill. Reliance bucked the weak tape, gaining 0.81% to 1,167.40, while HDFC Bank slipped 0.29% to 683.30. G-Sec yields were not reported in the supplied data.

The Day Ahead

No scheduled India data releases appear on the calendar for today or tomorrow, leaving the market to trade off the industrial production miss and the liquidity backdrop. Attention shifts to the RBI's liquidity operations, where the collapse in the bank cash surplus will be watched for signs of further variable rate repo or reverse repo action. The rupee's reaction to Brent's sharp decline will be a key intraday tell, given the central bank's heavy October intervention.

With no domestic prints to anchor sentiment, global risk appetite and Fed expectations will likely dominate flows into Indian equities and the currency. Traders will also parse commentary around the finance ministry's FY27 growth projection for any signal on fiscal priorities ahead of the next MPC meeting on December 4.

Other Economic Notes

The finance ministry's 7.3% FY27 growth projection and 7.35% Q2 FY27 estimate sit well above consensus-implied trajectories, suggesting official confidence in domestic demand even as it explicitly flags inflation risks. The industrial production miss complicates that narrative, pointing to softer manufacturing momentum that could temper the growth optimism. ↓ p.2
Page 1

India Macro Daily(Beta Mode)

October 30, 2026 robomacro.com
NSE Nifty 50 NSE Nifty 50 | Type: macro_line | NSE Nifty 50: 2.294e+04 (2026-10-29) | Range: 1.529e+04–2.633e+04 | Trend(6pt): 1.793e+04,1.791e+04,2.212e+04,2.514e+04,2.27e+04,2.294e+04
USD/INR Spot Rate USD/INR Spot Rate | Type: macro_line | USD/INR Spot Rate: 95.21 (2026-10-29) | Range: 78.27–110.1 | Trend(5pt): 86.73,87.7,90.37,97.8,95.21
India Industrial Production YoY India Industrial Production YoY | Type: macro_line | IP YoY %: 7.935 (2026-08-01) | Range: -3.835–19.33 | Trend(6pt): 0.7882,5.318,8.671,3.545,7.313,7.935
USD/INR Exchange Rate USD/INR Exchange Rate | Type: market_hloc | USD/INR: 95.21 (2026-10-29) | Range: 93.55–96.82 | Trend(6pt): 95.73,95.77,95.03,96.34,95.18,95.21

Other Economic Notes (continued)

India and Mexico have launched trade pact negotiations aimed at expanding market access and investment, a diversification push that could gradually reduce reliance on any single export bloc. BCG India argued that cutting LTCG tax on equities is a short-term fix and that India must address its current account deficit structurally — a pointed critique given the BoP pressure driving the RBI's FX defense. The IMF's Julie Kozack reiterated that India should let the rupee adjust freely, adding external pressure to the intervention debate.

Global Macro News

A Fed pause is giving India's central bank breathing room, per Bloomberg, as a stable US policy path reduces the risk of abrupt capital outflows and eases pressure on the RBI's rate trajectory. The rupee nonetheless slipped even as Asian currencies drew a Fed-related lift, underscoring India-specific BoP strains that have kept USD/INR pinned near 95.2. Brent's 3.29% drop to $111.53 is a meaningful positive for India's import bill, though the IMF framed the rupee as India's first defense against energy shocks — implying the currency, not reserves alone, should absorb such pressure.

Gold fell 0.71% to $4,022.70, while Bitcoin's 5.54% slide to $76,763.98 signals a broader risk-off tone in speculative assets that could spill into EM equity flows. Alphabet's 9% earnings-driven slide weighed on global tech sentiment, a relevant read-across for India's IT services complex. The combination of a Fed pause, softer oil, and firm US equities would normally support the rupee, yet India's currency underperformance highlights the weight of the current account deficit.

Sponsored by Arbitrage Search
Page 2

India Macro Daily(Beta Mode)

October 30, 2026 robomacro.com

Continuation

RBI Watch

The RBI has held the repo rate at 5.50% since its October 7 decision, with the next MPC meeting scheduled for December 4. Its October FX package has been costly: dollar sales of $18.2bn were the highest this year, and the bank cash surplus has plunged roughly 96% as liquidity was tightened to defend the rupee — a de facto monetary squeeze that IBTimes characterized as a silent financial squeeze via higher interest rates. The RBI continues to describe the Indian economy as resilient amid global headwinds, but the liquidity drain and intervention costs raise questions about how long the defense can be sustained without impairing credit growth.

The IMF's call for free rupee adjustment contrasts with the RBI's managed approach, setting up a policy tension into December. Markets should watch for variable rate repo operations to replenish liquidity if the surplus remains depleted, and for any forward guidance at the December 4 meeting that acknowledges the growth-inflation trade-off flagged by the finance ministry.

Sponsored by Arbitrage Search
Page 3