India Macro Daily(Beta Mode)
Nifty Surges on Crude Slide, Rupee Eyed
Market Snapshot
| Asset | Level | Change |
|---|---|---|
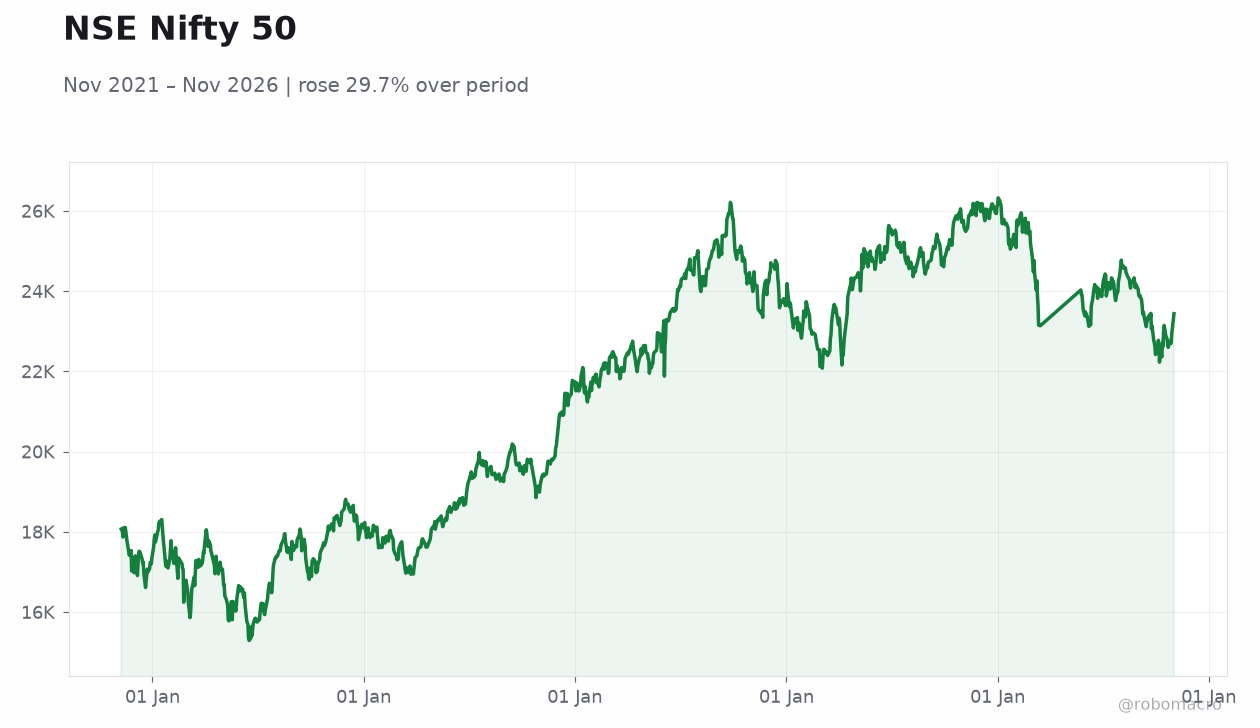
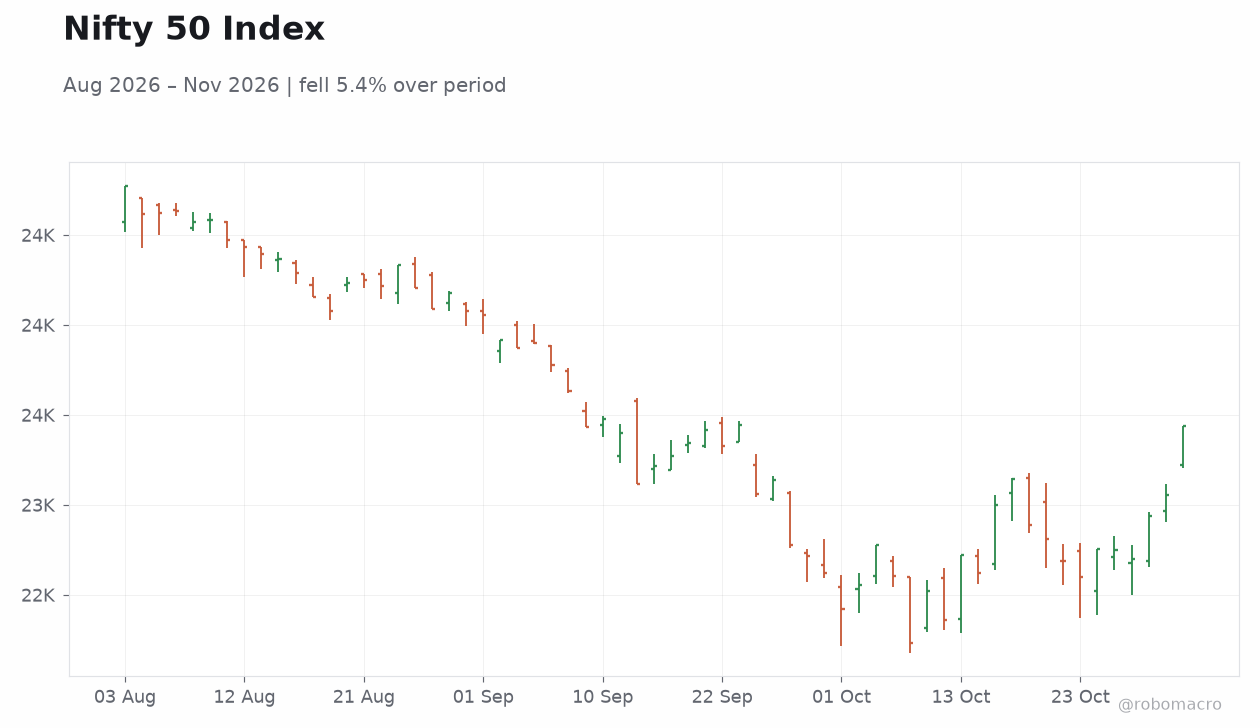
| Nifty 50 | 23,440.80 | +1.68% |
| Sensex | 75,692.78 | +1.66% |
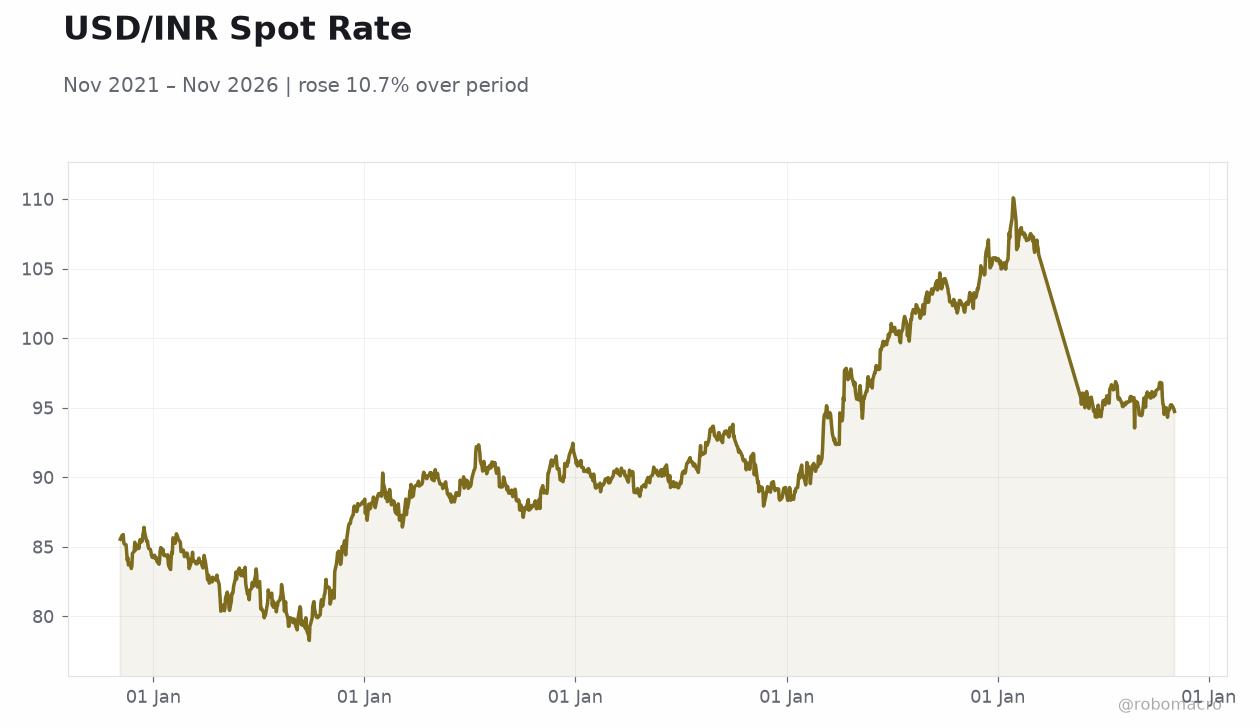
| USD/INR | 94.73 | +0.00% |
| EUR/INR | 106.33 | +0.19% |
| Reliance | 1,307.90 | +0.61% |
| HDFC Bank | 725.50 | +3.64% |
| Brent Crude | 104.20 | -0.54% |
| Gold | 3,946.20 | -0.59% |
| Bitcoin | 77,116.11 | +0.57% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
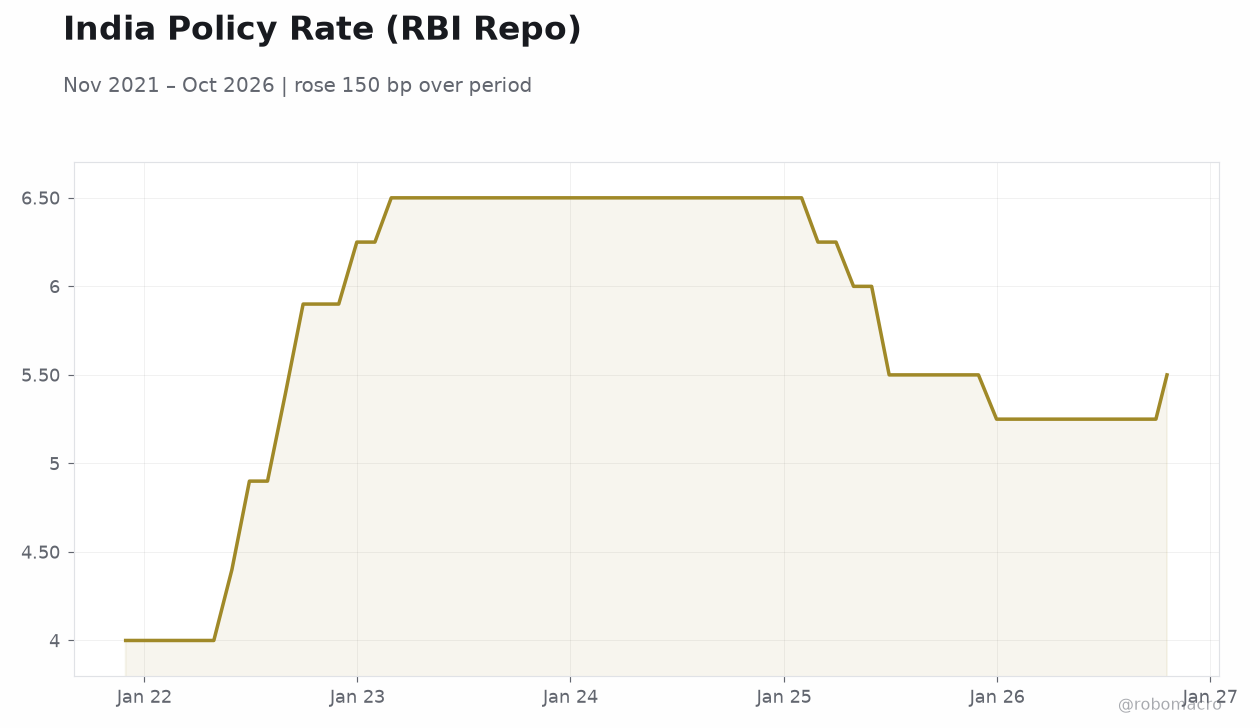 India Policy Rate (RBI Repo) | Type: macro_line | Policy Rate (%): 5.5 (2026-10-19) | Range: 4–6.5 | Trend(4pt): 4,6.5,6.5,5.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Nifty 50 jumped 1.68% to 23,440.80 and Sensex rose 1.66% to 75,692.78 as easing Brent crude and earnings optimism lifted sentiment.
- USD/INR held flat at 94.73, with RBI forex-reporting relaxations and softer oil prices supporting the rupee's rebound.
- The RBI's October 7 repo rate increase to 5.50% is now feeding through to deposit rates as liquidity tightens, with the next MPC meeting set for December 4.
Yesterday's Recap
Indian equities posted a sharp risk-on session, with the Nifty 50 climbing 1.68% to 23,440.80 and the Sensex gaining 1.66% to 75,692.78, driven by a steep correction in crude prices and optimism around corporate earnings. Brent crude slipped 0.54% to $104.20, offering relief on the import bill and inflation outlook. HDFC Bank outperformed with a 3.64% gain to 725.50, while Reliance added 0.61% to 1,307.90.
The rupee was essentially unchanged against the dollar at 94.73, though it edged 0.19% weaker versus the euro at 106.33. Gold eased 0.59% to $3,946.20, while Bitcoin firmed 0.57% to 77,116.11. No scheduled Indian data releases were recorded for the session, leaving price action to be driven by global cues and sector-specific flows.
The Day Ahead
The calendar is light for November 3, with no major Indian statistical releases scheduled, so markets will likely take direction from global risk appetite and crude price moves. Traders will continue to monitor the rupee's trajectory after the RBI's recent forex-reporting easements, which lowered the reporting threshold for small-value service exports and imports to Rs 10 lakh. Bank deposit-rate adjustments following the October rate increase will be watched for signals on liquidity conditions and transmission.
With the next MPC decision not due until December 4, positioning will hinge on incoming inflation and liquidity data rather than policy signals. Equity flows and IT-services commentary ahead of the earnings season will also be in focus.
Other Economic Notes
India's growth story remains the fastest among major economies, but the stock market's underperformance versus emerging-market peers points to an earnings drag that investors are increasingly pricing in. Prolonged food inflation, exacerbated by dwindling water supplies affecting wheat and chickpea sowing, remains a structural risk to the inflation trajectory. The RBI's forex liberalisation for small service exporters and importers is a targeted measure to ease documentation friction and support the rupee.
↓ p.2