India Macro Daily(Beta Mode)
Rupee Defence Reshapes FX Flows
Market Snapshot
| Asset | Level | Change |
|---|---|---|
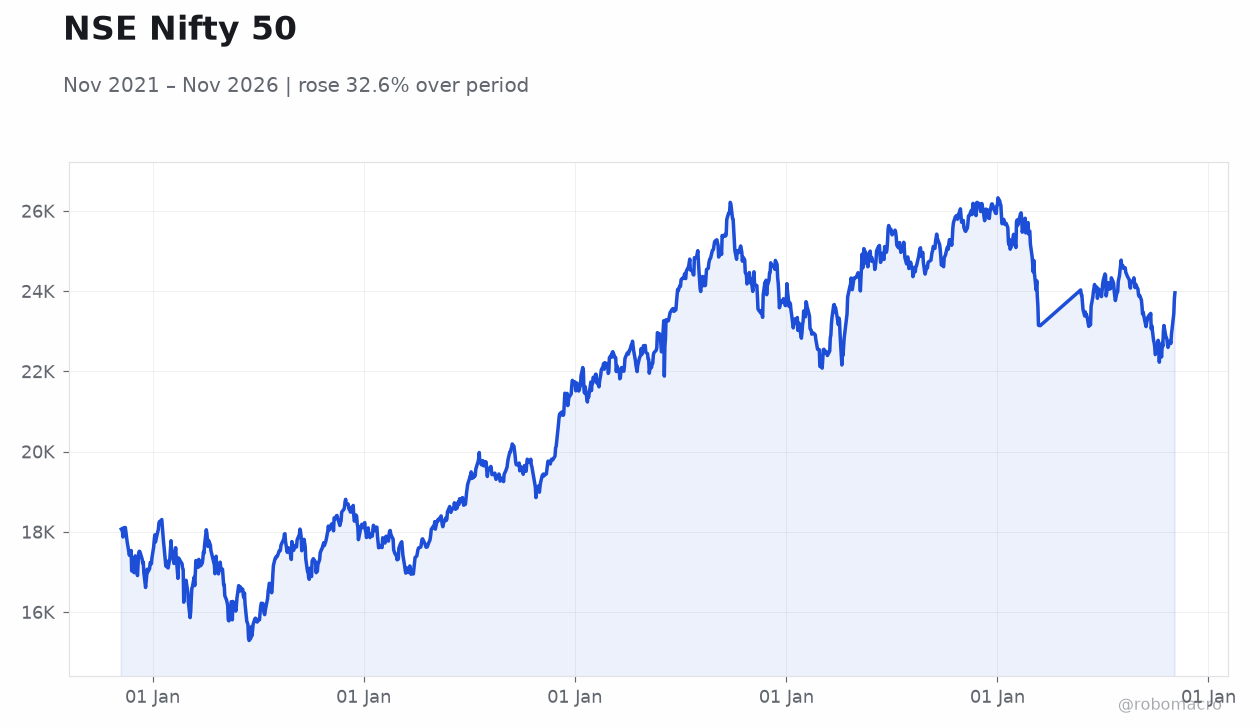
| Nifty 50 | 23,810.85 | +1.58% |
| Sensex | 76,917.85 | +1.62% |
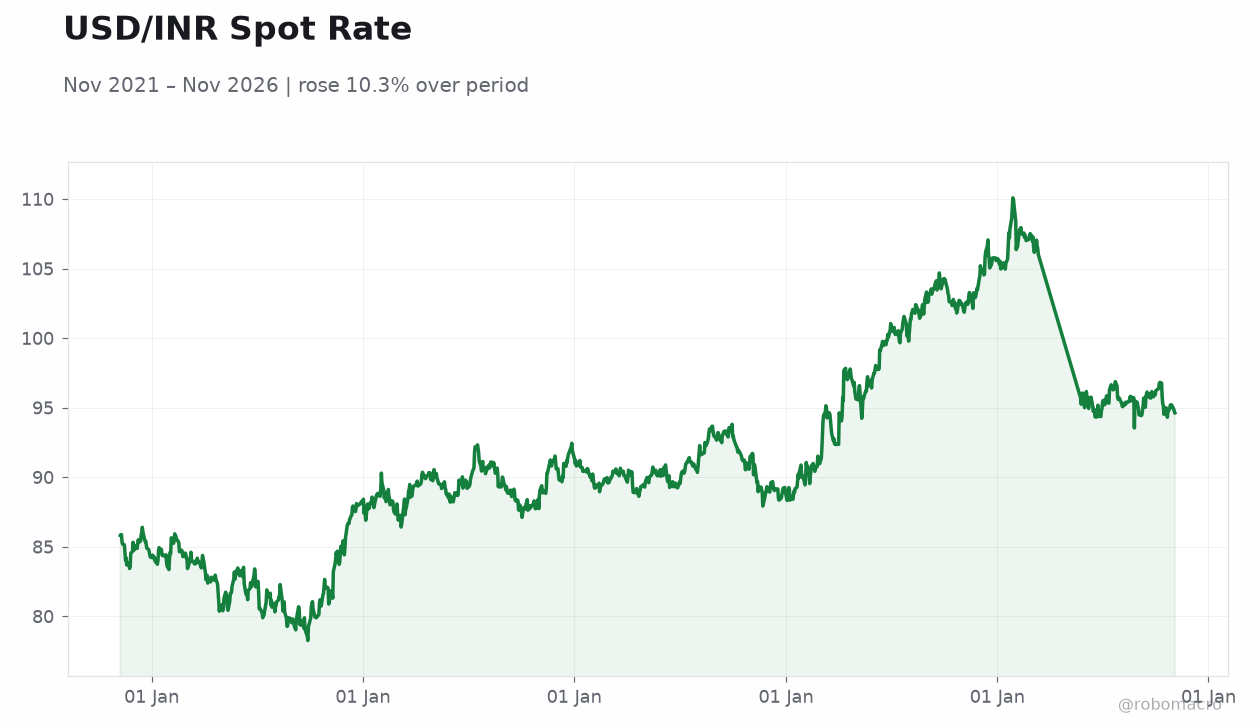
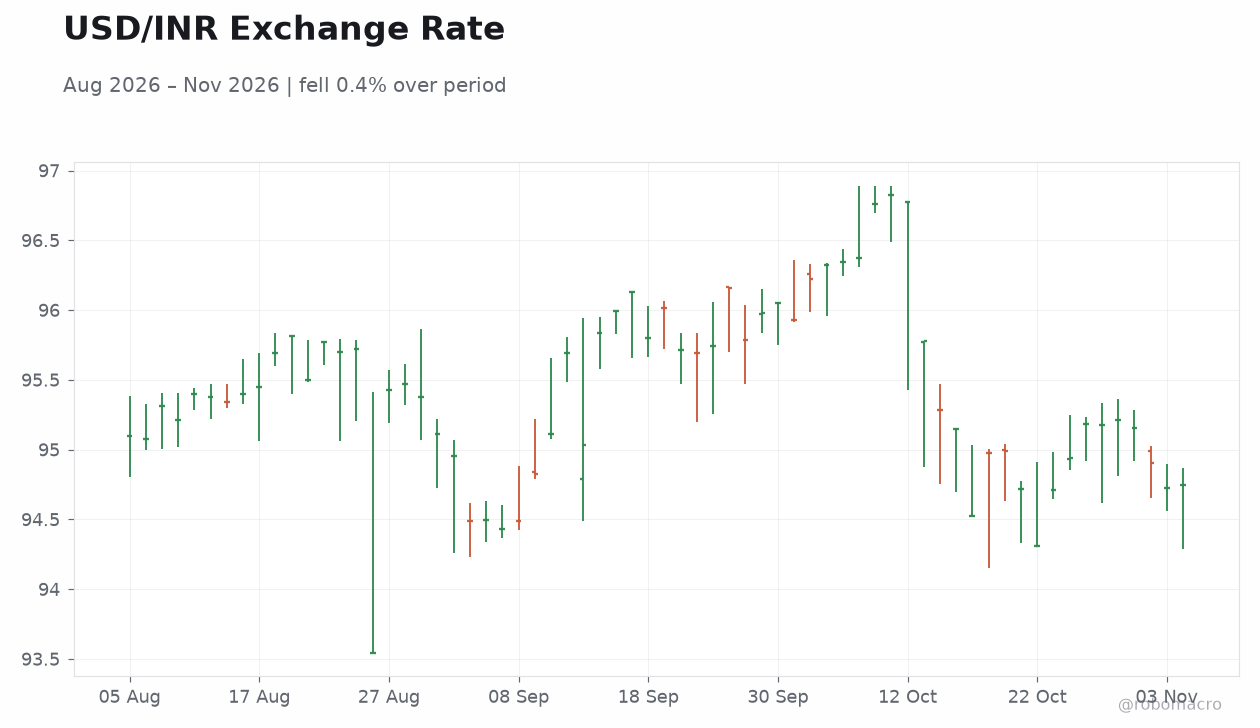
| USD/INR | 94.75 | +0.02% |
| EUR/INR | 106.32 | +0.21% |
| Reliance | 1,311.00 | +0.24% |
| HDFC Bank | 736.70 | +1.54% |
| Brent Crude | 94.55 | -8.74% |
| Gold | 4,085.60 | +3.68% |
| Bitcoin | 80,617.43 | +4.23% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
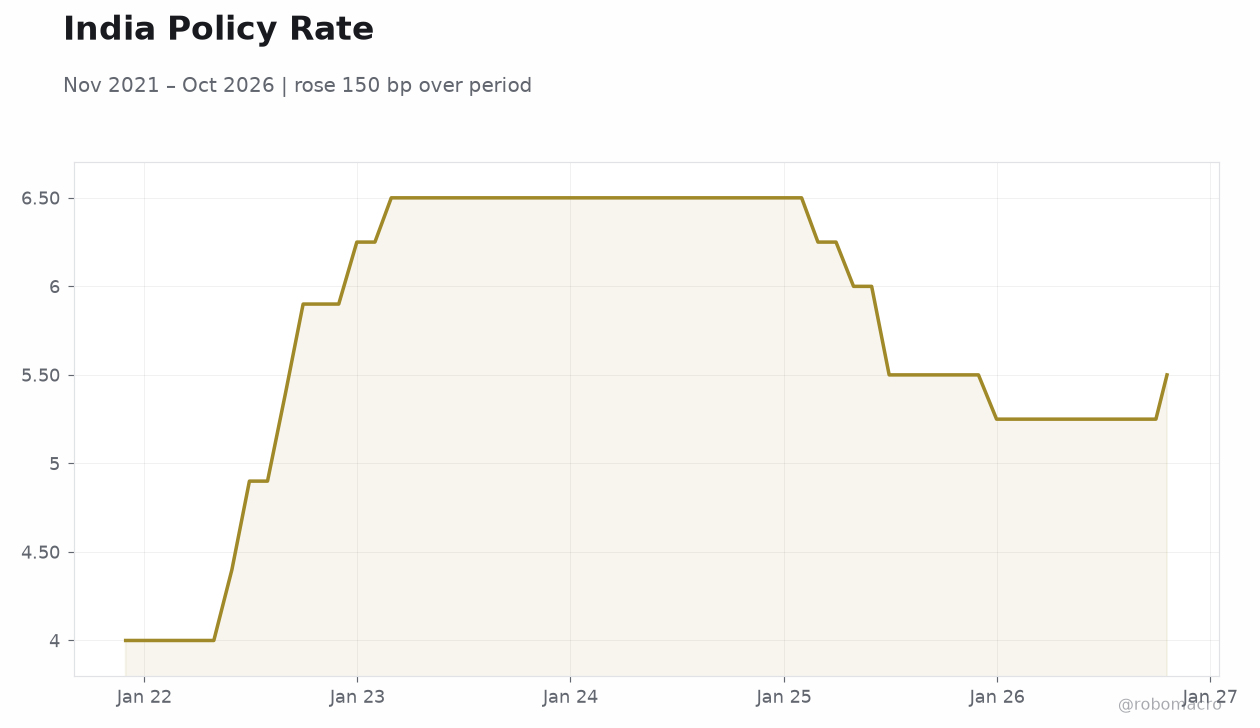 India Policy Rate | Type: macro_line | Policy Rate %: 5.5 (2026-10-19) | Range: 4–6.5 | Trend(4pt): 4,6.5,6.5,5.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Nifty reclaims 23,800 and Sensex jumps over 1,200 points as easing crude and earnings optimism lift equities.
- RBI's crackdown on rupee speculation drives corporate dollar hedging to an eight-month low, with importer purchases down 35%.
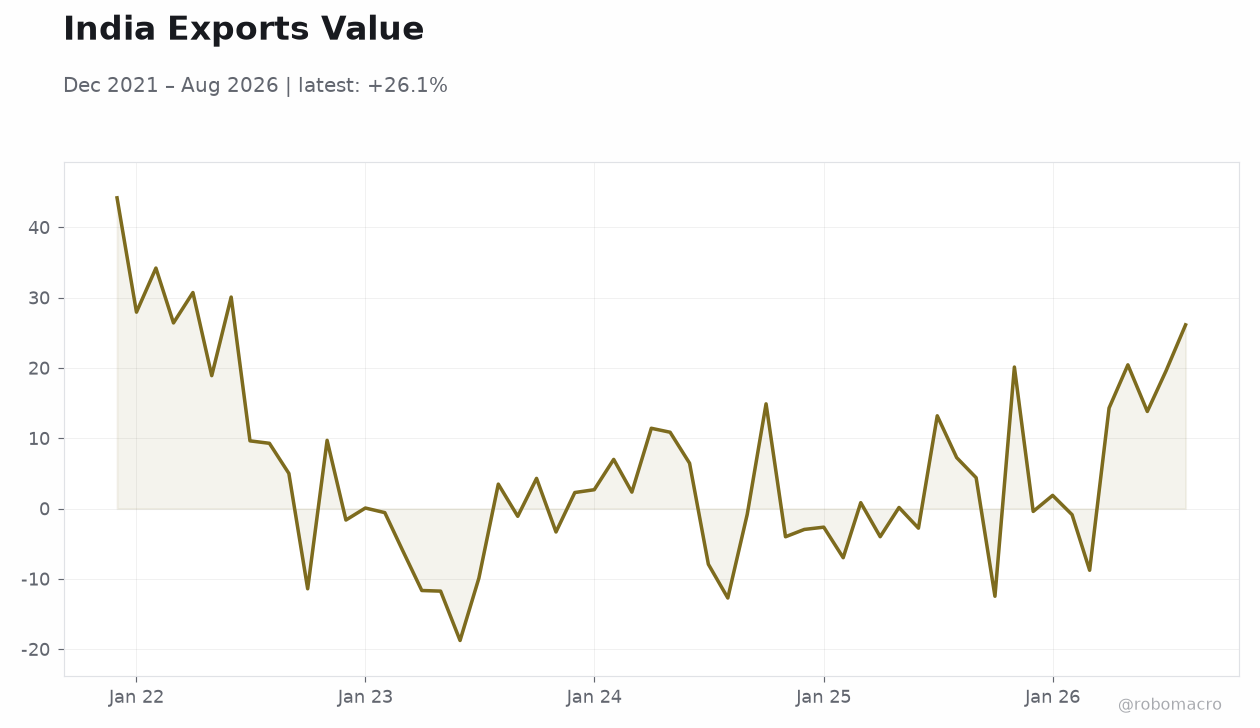
- Brent's sharp slide and softer US dollar post-midterms offer New Delhi trade negotiating room, but food inflation risks persist.
Yesterday's Recap
Indian equities staged a powerful rally, with the Sensex settling roughly 1,200 points higher and the Nifty reclaiming 23,800, up 1.58% on the session as easing crude prices and earnings optimism combined to lift risk appetite. Brent crude collapsed 8.74% to $94.55, a move that materially improves India's import bill outlook and supports the rupee narrative. The rupee extended gains against a softer dollar, with USD/INR essentially flat at 94.75 even as the greenback weakened on US midterm election uncertainty.
HDFC Bank rose 1.54% while Reliance added a modest 0.24%, underscoring the breadth of the financial-led advance. Gold surged 3.68% to $4,085.60 and Bitcoin jumped 4.23%, signalling a broader risk-on tone globally. Government bond yields were not populated in the supplied data, so no yield commentary is possible.
The Day Ahead
The calendar is empty for today, with no scheduled Indian data releases, leaving markets to digest the prior session's sharp equity rally and the crude collapse. Traders will focus on follow-through in the rupee, which has been buoyed by dollar weakness tied to US midterm elections and by the RBI's crackdown on speculative positioning. Corporate hedging behaviour will be watched closely after dollar hedging slumped to an eight-month low, a signal that importers are delaying cover in anticipation of further rupee strength.
Liquidity operations remain in focus, with the RBI's variable rate reverse repo auctions drawing strong bids. Global cues, particularly oil's trajectory and US political developments, will likely dominate sentiment ahead of the December policy meeting.
Other Economic Notes
India's growth-inflation mix is increasingly bifurcated, with consumer sentiment and the stock market telling divergent stories. Prolonged food inflation remains a structural concern, with dwindling water supplies threatening wheat and chickpea sowing and keeping pressure on the RBI's inflation-targeting framework. The central bank has established a panel to assess forex and bond markets, a recognition that market microstructure and credibility gaps need addressing.
The rupee's stability carries a fiscal cost, with the RBI's roughly $239 billion reserve bet raising questions about the price of defending the currency. ↓ p.2