RoboMacro ResearchAlso todaySee the US Macro Daily

India Macro Daily(Beta Mode)

November 16, 2026 robomacro.com

CPI Overshoots, Rate-Hike Risk Builds

6.09 Inflation Rate
Nifty 5025,144.30-0.61%
Sensex81,592.45-0.39%
USD/INR94.23+0.21%
EUR/INR103.90+0.05%

Market Snapshot

AssetLevelChange
Nifty 5025,144.30-0.61%
Sensex81,592.45-0.39%
USD/INR94.23+0.21%
EUR/INR103.90+0.05%
Reliance1,339.70+0.00%
HDFC Bank804.00-1.02%
Brent Crude95.71-0.14%
Gold3,894.30+0.21%
Bitcoin64,972.62+1.32%
India 2Y Govt Yield--
India 10Y Govt Yield--

Prior Economic Events

Data Prior Cons Actual
Inflation Rate Year-over-Year5.545.936.09
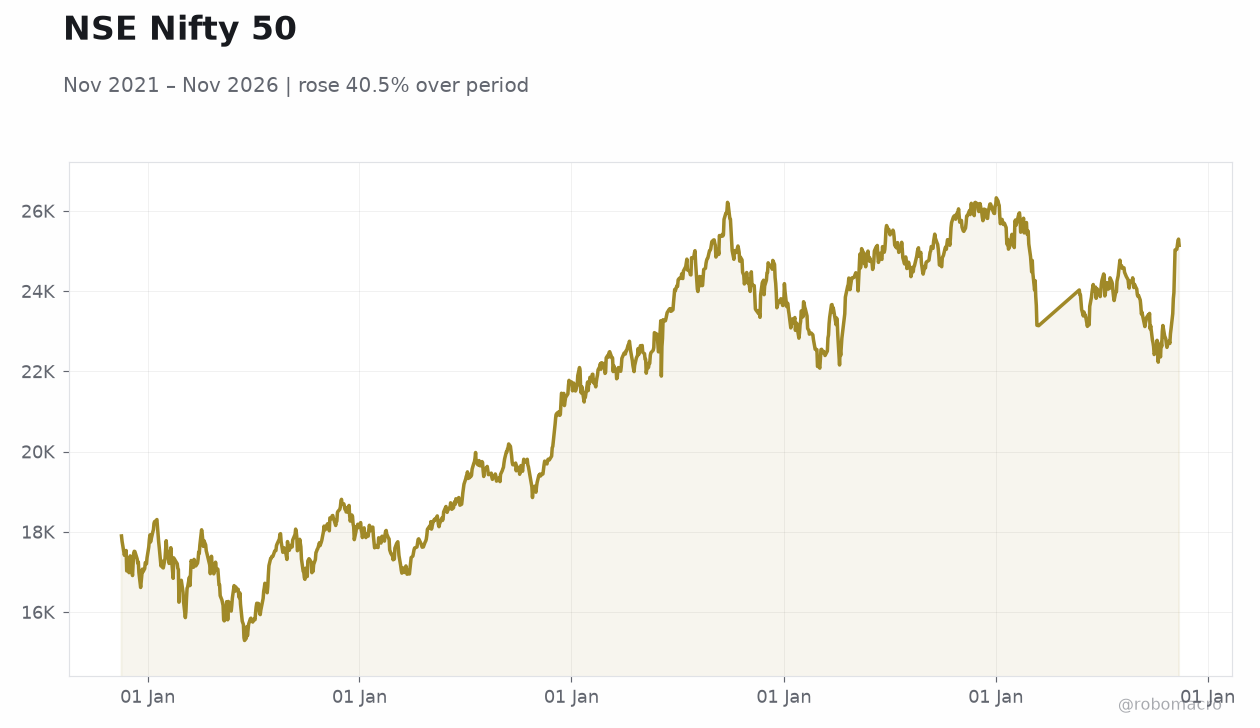
NSE Nifty 50NSE Nifty 50 | Type: macro_line | NSE Nifty 50: 2.514e+04 (2026-11-13) | Range: 1.529e+04–2.633e+04 | Trend(5pt): 1.79e+04,1.789e+04,2.227e+04,2.555e+04,2.514e+04

Today's Economic Events

Data Prior Cons Time
No events available
  • October CPI printed at 6.09% YoY, above the 5.93% consensus and up from 5.54% prior, pushing headline inflation further above the RBI's 4% target midpoint.
  • Nifty 50 fell 0.61% to 25,144.30 and Sensex slipped 0.39% to 81,592.45, with rate-sensitive financials leading losses.
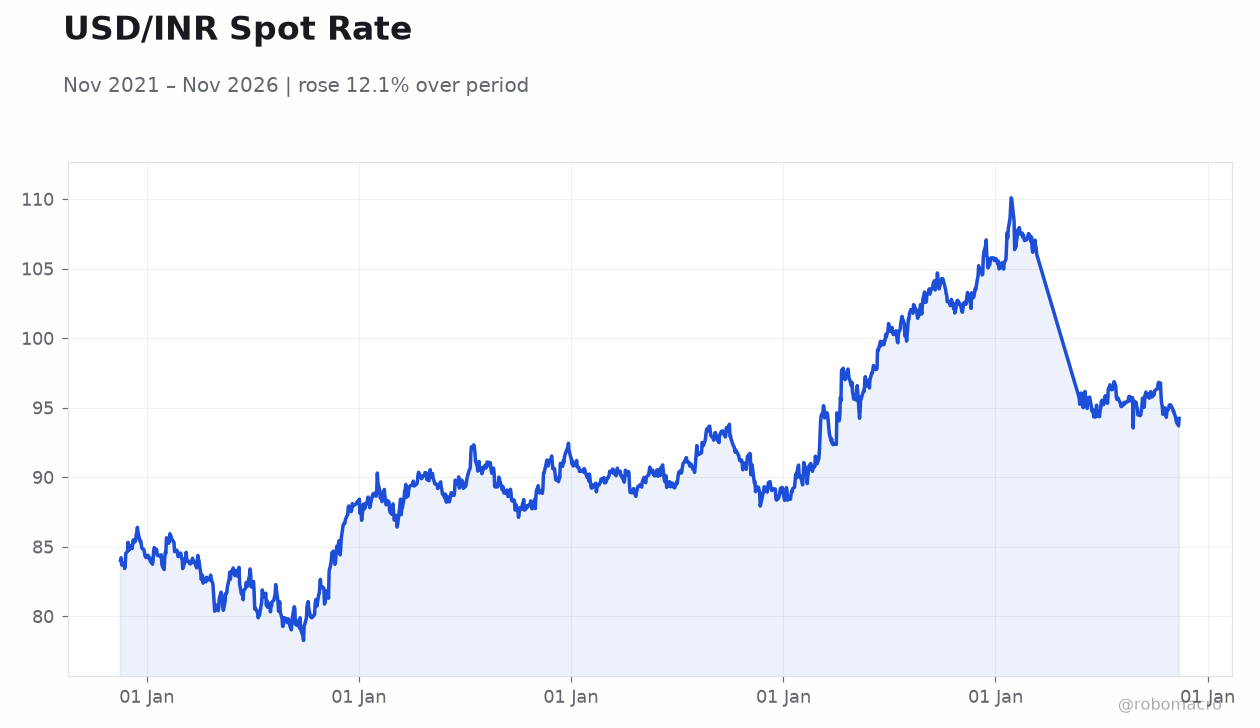
  • USD/INR weakened 0.21% to 94.23, with the inflation overshoot reinforcing expectations that the RBI's tightening cycle may extend into FY27.

Yesterday's Recap

India's October CPI, released November 12, printed at 6.09% YoY, materially above the 5.93% consensus and accelerating from 5.54% the prior month, confirming that food and household inflation pressures remain entrenched. Equity markets responded defensively, with the Nifty 50 closing at 25,144.30, down 0.61%, and the Sensex at 81,592.45, down 0.39%. HDFC Bank fell 1.02% to 804.00, reflecting rate-sensitive bank valuations under pressure, while Reliance was flat at 1,339.70.

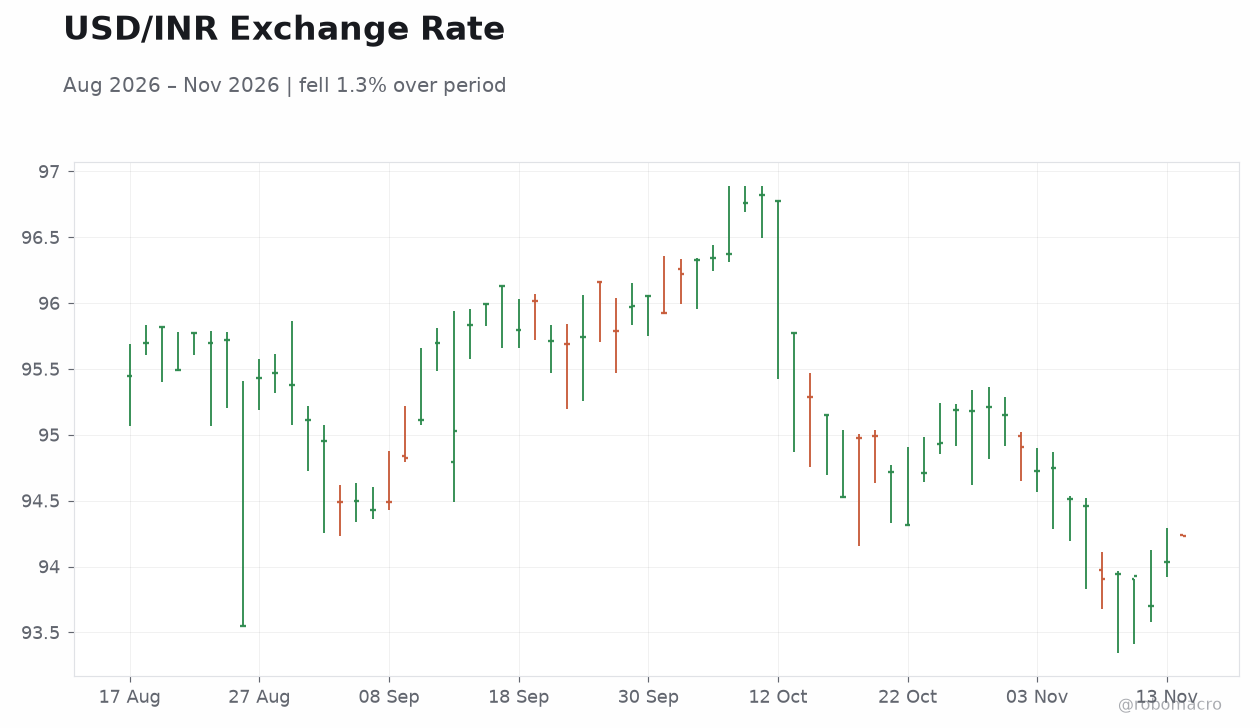
The rupee weakened to 94.23 against the dollar, a 0.21% depreciation, as the inflation surprise bolstered the case for prolonged monetary tightness. Brent crude eased 0.14% to 95.71, offering marginal relief on the imported-inflation front, while gold rose 0.21% to 3,894.30 as a hedge against sticky price pressures. G-Sec yield levels were not populated in the feed, but directionally the CPI overshoot implies upward pressure on the short end and curve-flattening risk.

The Day Ahead

No scheduled India data releases are on the calendar for November 15, leaving markets to digest the October CPI overshoot and its implications for the December 4 MPC decision. Trading will likely focus on whether the rupee can stabilize near 94.23 and whether the Nifty holds the 25,000 psychological level. Sector rotation will be watched closely, particularly financials, which bore the brunt of yesterday's selling, and IT services, where global demand signals remain the key swing factor.

With no domestic prints to anchor sentiment, global cues — crude prices, dollar strength, and US rate expectations — will drive intraday direction. Bond market participants will also watch for any RBI liquidity operations or commentary that could clarify the trajectory of the tightening cycle.

Other Economic Notes

The October CPI overshoot to 6.09% keeps headline inflation well above the RBI's 4% target midpoint and complicates the policy path into FY27. Analysts increasingly expect the central bank to maintain a tightening bias, with some commentary suggesting the RBI may keep tightening through FY27 as inflation stays sticky. ↓ p.2
Page 1

India Macro Daily(Beta Mode)

November 16, 2026 robomacro.com
USD/INR Spot Rate USD/INR Spot Rate | Type: macro_line | USD/INR Spot Rate: 94.23 (2026-11-13) | Range: 78.27–110.1 | Trend(5pt): 84.03,88.83,88.91,100.1,94.23
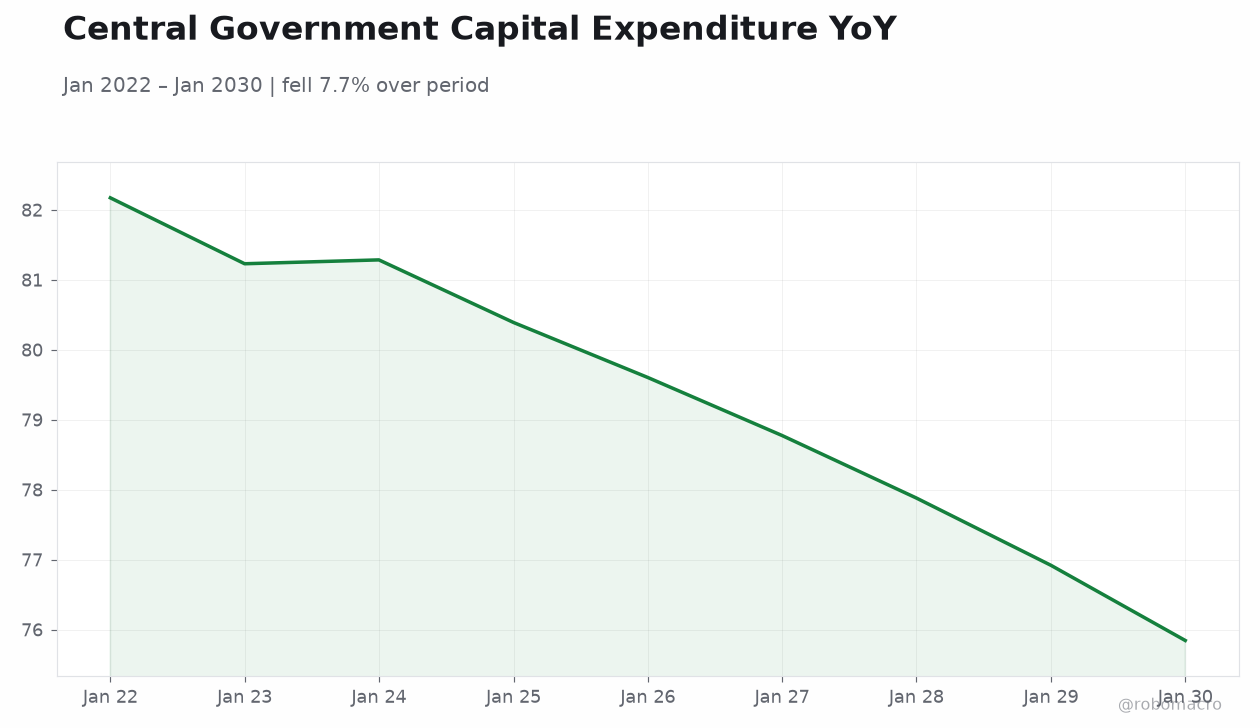
Central Government Capital Expenditure YoY Central Government Capital Expenditure YoY | Type: macro_line | Central Government Capital Expenditure YoY: 75.85 (2030-01-01) | Range: 75.85–82.17 | Trend(5pt): 82.17,81.29,79.6,77.88,75.85
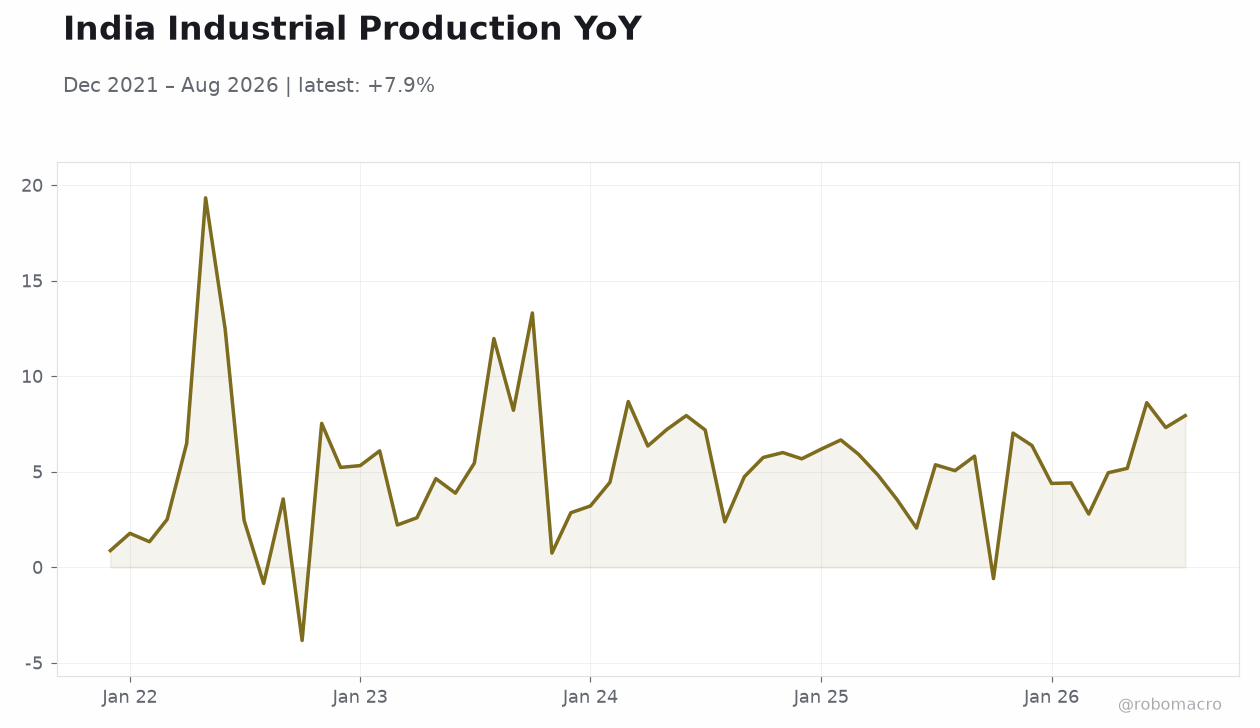
India Industrial Production YoY India Industrial Production YoY | Type: macro_line | IP YoY (%): 7.935 (2026-08-01) | Range: -3.835–19.33 | Trend(5pt): 0.8722,6.091,6.346,2.051,7.935
USD/INR Exchange Rate USD/INR Exchange Rate | Type: market_hloc | USD/INR: 94.23 (2026-11-16) | Range: 93.55–96.82 | Trend(6pt): 95.45,94.49,96.05,94.31,94.03,94.23

Other Economic Notes (continued)

India's current account deficit is projected to widen to $57 billion in FY27, a dynamic that could add pressure on the rupee already trading above 94 per dollar. The RBI has signaled it will retain the loan repayment cap for microfinance institutions and is reviewing the Rs 3 lakh income threshold for microfinance borrowers, balancing credit access against rising debt risks. Meanwhile, the central bank is pushing e-rupee wallets within banking apps to boost digital currency adoption, and Coinbase's halt on INR withdrawals underscores the friction in crypto access.

Global Macro News

Brent crude at 95.71 remains elevated, keeping imported inflation risk alive for India's energy-dependent economy even as prices eased slightly yesterday. The dollar's strength continues to weigh on emerging-market currencies, with the rupee's slide to 94.23 reflecting both domestic inflation concerns and external dollar pressure. Global rate expectations remain a critical input: any hawkish repricing in US markets would tighten financial conditions for India via capital flow and currency channels.

India faces less pressure to finalize a US trade deal following the midterm elections, according to Emkay Global, potentially reducing near-term tariff uncertainty. Chinese automaker BYD launched its luxury brand Denza in India, intensifying competition in the premium auto segment and signaling continued foreign investment interest. Bitcoin's 1.32% rise to 64,972.62 reflects resilient risk appetite in select assets even as Indian equities softened.

Gold's 0.21% gain to 3,894.30 highlights demand for inflation hedges amid sticky price pressures globally.

Sponsored by Arbitrage Search
Page 2

India Macro Daily(Beta Mode)

November 16, 2026 robomacro.com

Continuation

RBI Watch

The RBI's October 7 decision raised the repo rate by 25bp to 5.50%, and the October CPI print at 6.09% validates that hawkish stance rather than arguing for a pause. With inflation running well above target, market commentary now points to the RBI potentially tightening through FY27, and the next MPC meeting on December 4 will be scrutinized for forward guidance. The committee's communication has emphasized inflation control, and the latest data strengthens the case for maintaining a restrictive posture; any future rate reduction would be framed as a possible reversal of the October hike, not a new easing cycle.

On liquidity, the RBI continues active management, and its push to embed e-rupee wallets within banking apps signals a parallel focus on digital infrastructure. Regulatory actions — retaining the microfinance loan repayment cap and reviewing the Rs 3 lakh income threshold — show the RBI balancing credit growth against household debt risk. For markets, the bias remains toward a higher-for-longer rate path, keeping short-end yields and bank valuations under pressure.

Sponsored by Arbitrage Search
Page 3