Japan Macro Daily(Beta Mode)
Koeda Flags Higher Neutral Rate, Yen Firms
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nikkei 225 | 67,744.29 | -0.05% |
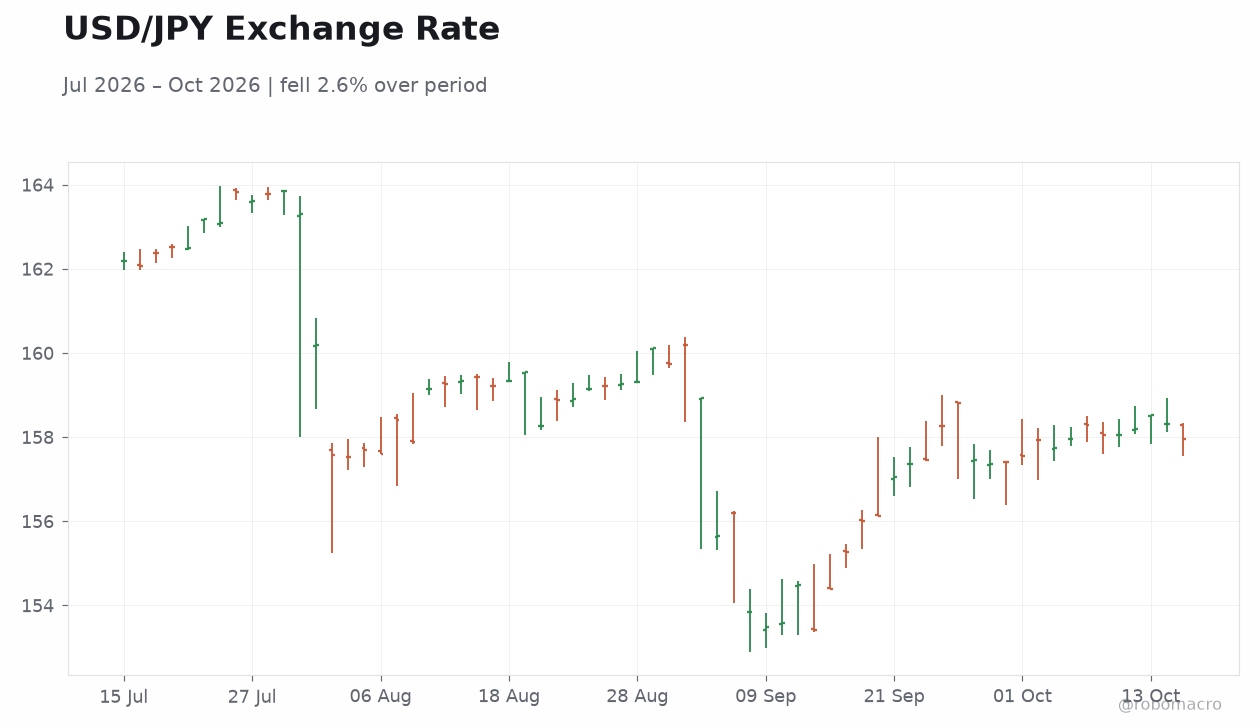
| USD/JPY | 157.95 | -0.23% |
| EUR/JPY | 177.09 | -0.13% |
| GBP/JPY | 209.59 | -0.14% |
| Gold | 4,191.10 | +2.03% |
| Brent Crude | 105.76 | -0.28% |
| Bitcoin | 81,951.82 | +0.48% |
| Japan 2Y Govt Yield | 1.93% | 0 bp |
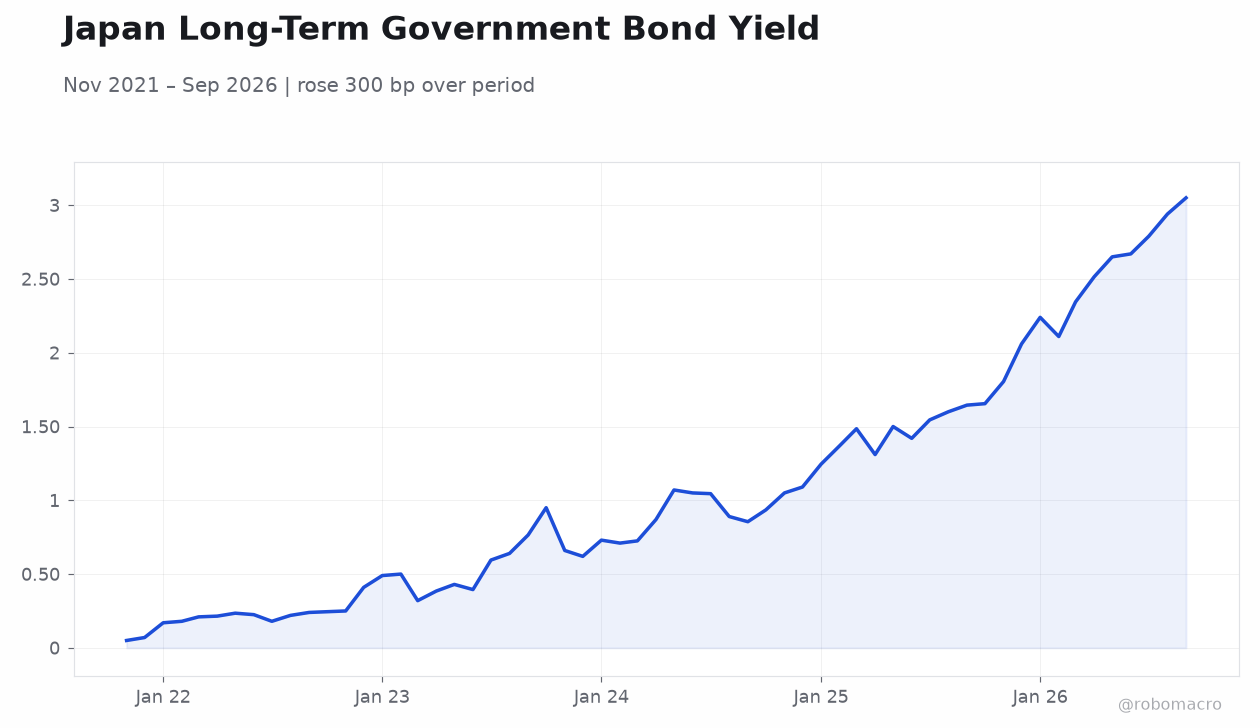
| Japan 10Y Govt Yield | 3.02% | 0 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Machinery Orders Month-over-Month | -3.70 | 3 | 5.20 |
| Machinery Orders Year-over-Year | 11.20 | 15.70 | 18.60 |
| BoJ Koeda Speech | - | - | - |
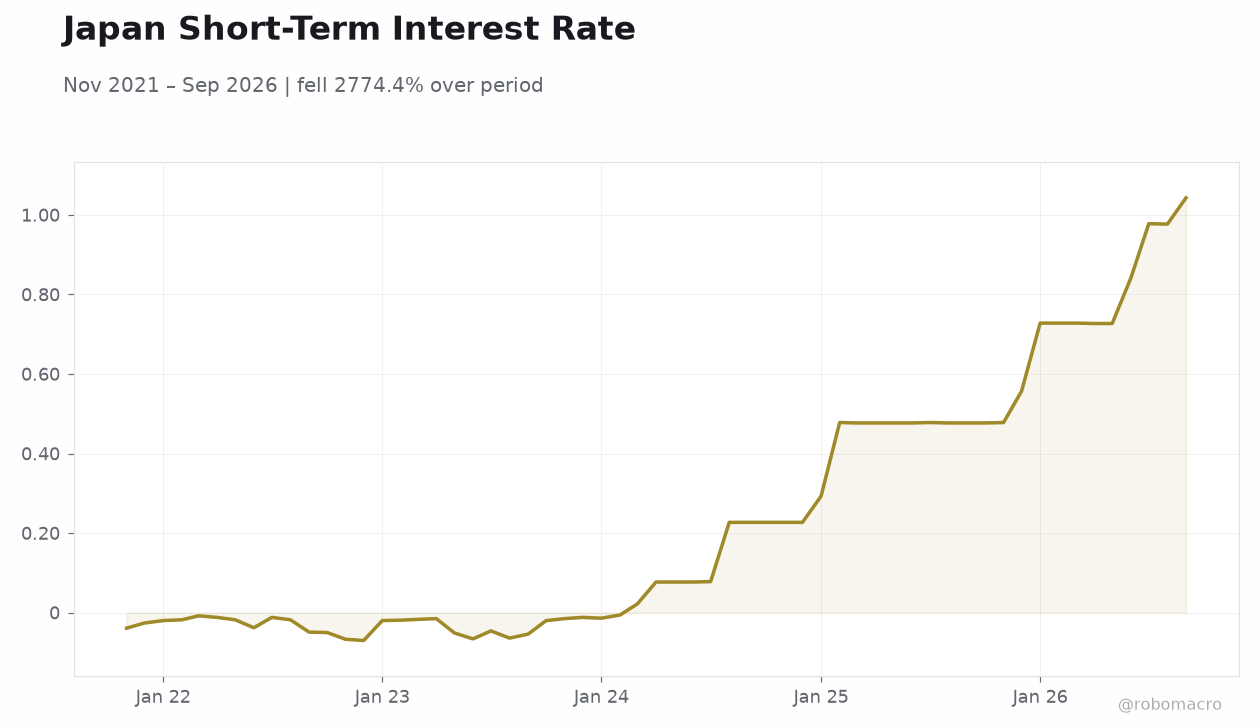 Japan Short-Term Interest Rate | Type: macro_line | Short-term rate (%): 1.043 (2026-09-01) | Range: -0.07–1.043 | Trend(6pt): -0.039,-0.02,0.022,0.477,0.978,1.043
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- BoJ board member Koeda says the neutral rate is "well above 1%," signalling openness to further hikes.
- August machinery orders beat forecasts, +5.2% m/m and +18.6% y/y, pointing to resilient capex.
- USD/JPY slips to 157.95 as hawkish BoJ commentary offsets hotter US inflation prints.
Yesterday's Recap
Japanese markets closed Wednesday with a muted tone, the Nikkei 225 easing 0.05% to 67,744.29 as investors digested a heavy slate of domestic news. Core machinery orders provided the standout data point, rising 5.2% month-over-month against a 3.0% consensus and accelerating to 18.6% year-over-year — a robust signal that corporate capital expenditure plans remain intact despite higher borrowing costs. The yen strengthened across the board, with USD/JPY falling 0.23% to 157.95, EUR/JPY down 0.13% at 177.09, and GBP/JPY off 0.14% at 209.59, as hawkish rhetoric from Bank of Japan policymakers underpinned the currency.
JGB yields were unchanged, with the 10-year holding at 3.02% and the 2-year steady at 1.93%, suggesting markets have largely priced the near-term policy path. In commodity space, gold rallied 2.03% to $4,191, while Brent crude slipped 0.28% to $105.76. Bitcoin gained 0.48% to $81,952, and the yen's firmness persisted even as US producer inflation came in hotter than expected.
The Day Ahead
Today's calendar is quiet on scheduled releases, with no major Japanese economic prints due, leaving market direction to be set by global cues and any ad-hoc official commentary. Attention shifts to follow-through from Koeda's speech and whether additional board members echo her framing of the neutral rate in coming days. Traders will watch the yen's ability to hold recent gains, particularly against a backdrop of renewed verbal intervention warnings from Finance Minister Katayama.
JGB market participants will monitor liquidity conditions and any BoJ operations after yields held steady at elevated levels. With the G20 communique flagging concerns over bond yields and FX volatility, expect officials to maintain a steady-hand posture. Positioning into next week's data flow may see modest de-risking if US yields back up further.
Other Economic Notes
The IMF's projection that Japan will fall to sixth in global GDP rankings by 2027 underscores the structural challenge of sustaining nominal growth amid a shrinking workforce. The machinery orders surge suggests firms are front-loading investment in automation and productivity-enhancing capex, a partial offset to demographic drag. ↓ p.2