Japan Macro Daily(Beta Mode)
Yen Slips as JGB Yields Grind Higher
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nikkei 225 | 62,188.63 | -1.42% |
| USD/JPY | 157.82 | -0.41% |
| EUR/JPY | 177.04 | -0.31% |
| GBP/JPY | 212.26 | -0.29% |
| Gold | 4,109.60 | +0.90% |
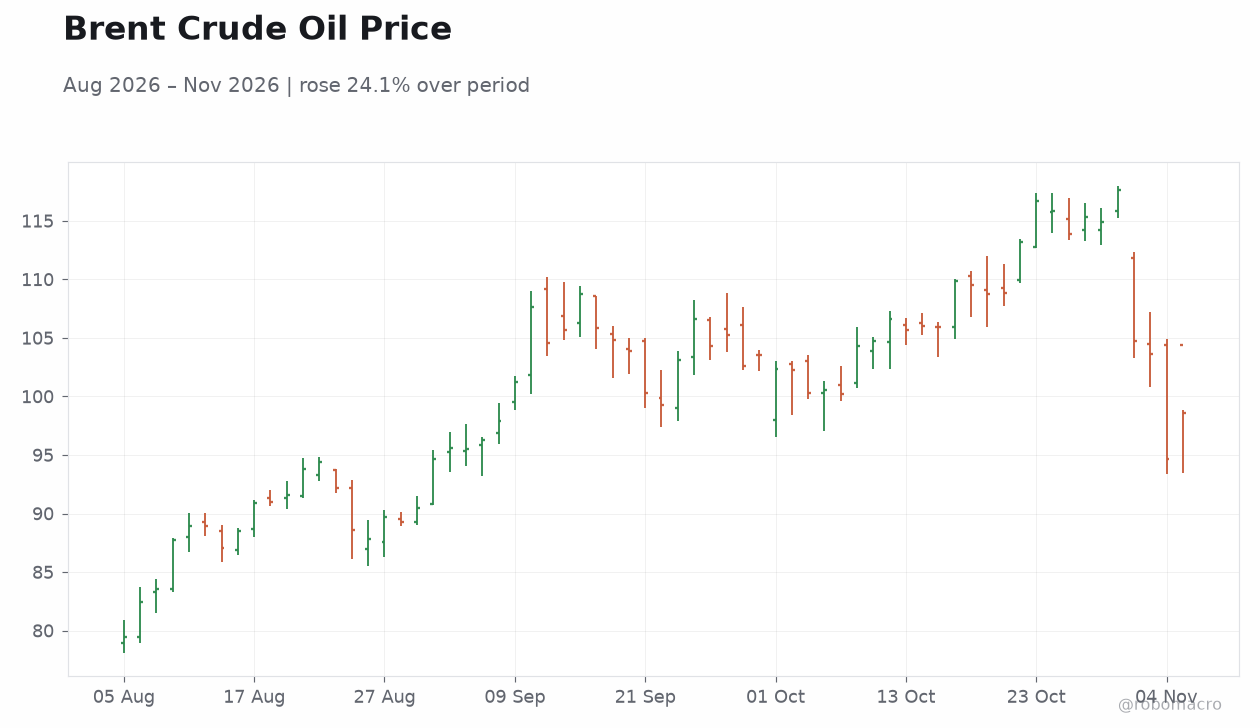
| Brent Crude | 98.43 | +4.03% |
| Bitcoin | 75,976.02 | -5.51% |
| Japan 2Y Govt Yield | 1.89% | +1 bp |
| Japan 10Y Govt Yield | 2.85% | +3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BoJ Monetary Policy Meeting Minutes | - | - | - |
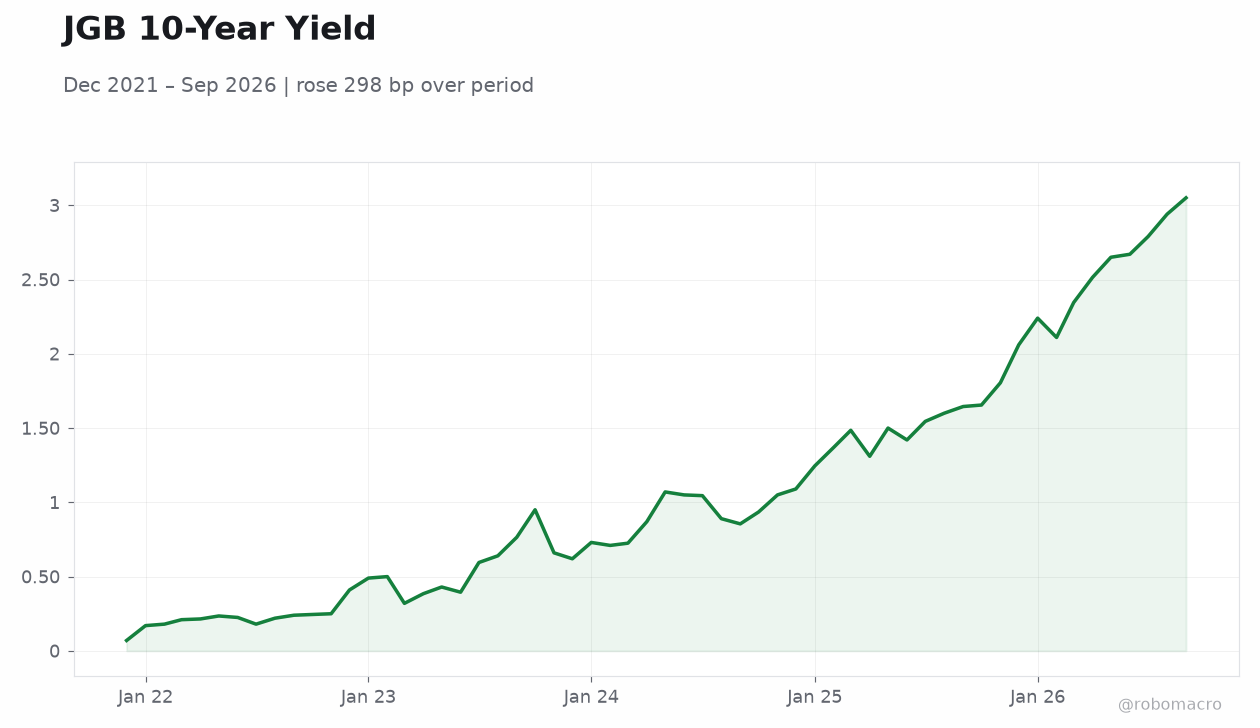
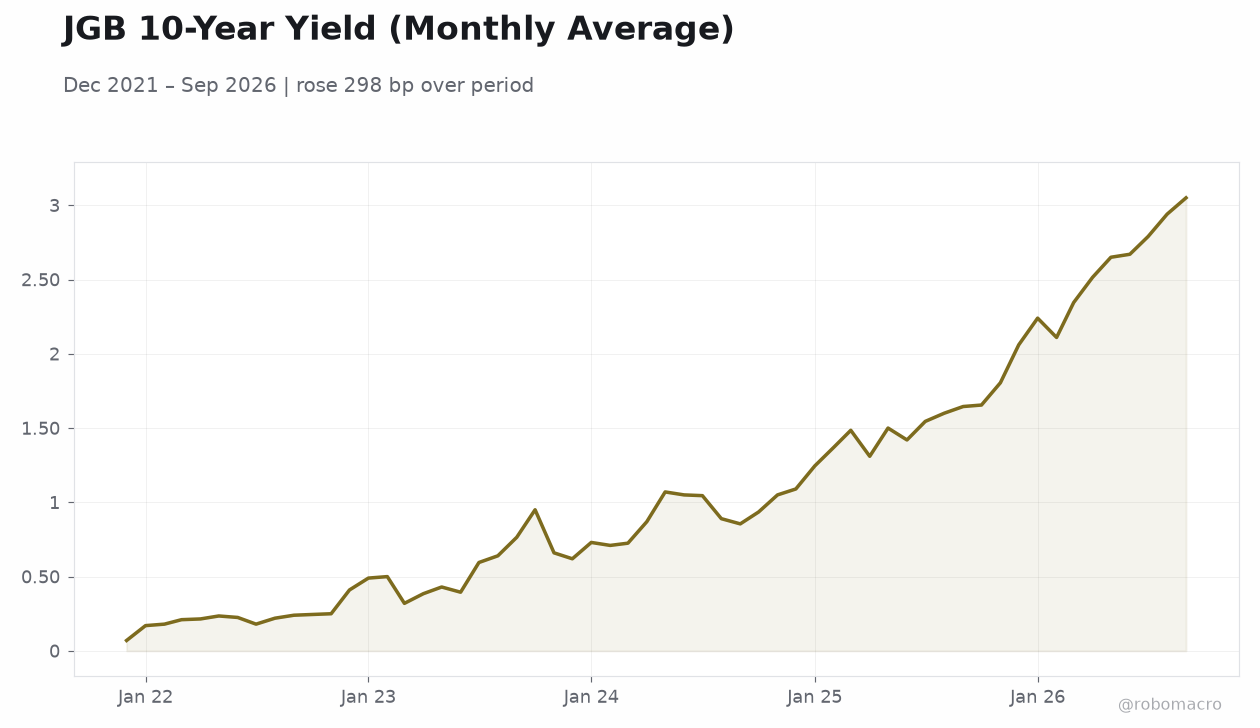
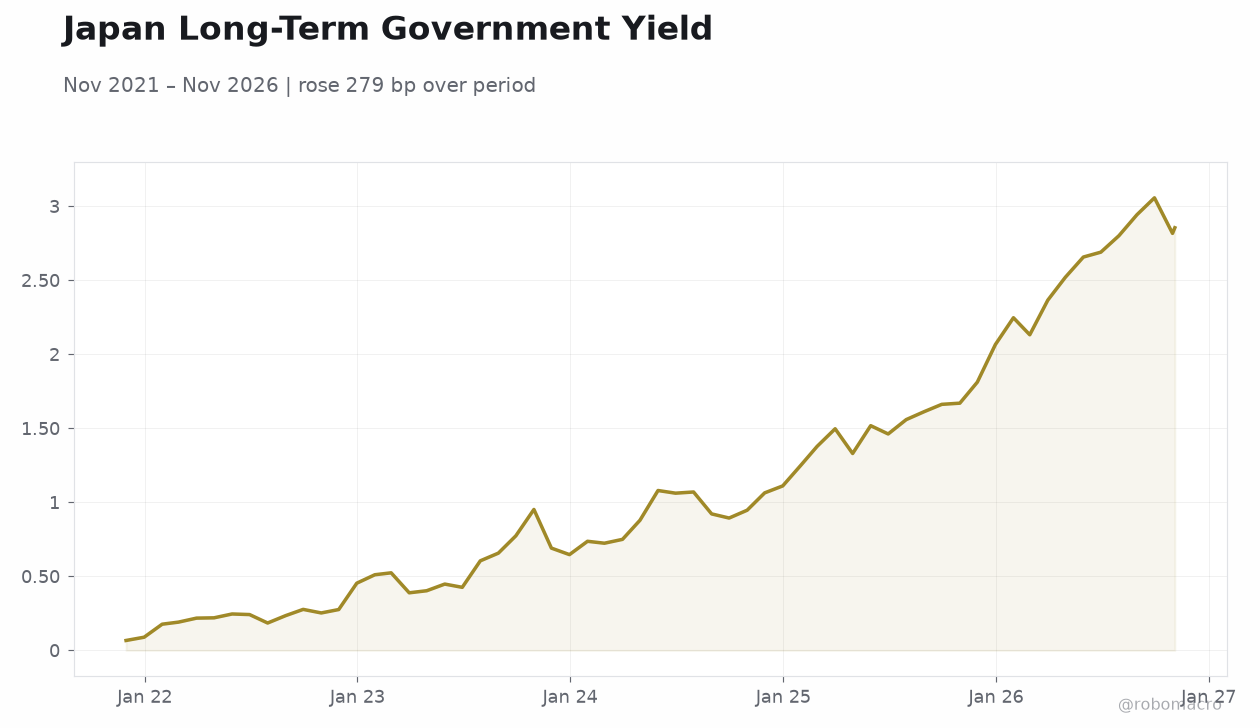 Japan Long-Term Government Yield | Type: macro_line | 10Y JGB yield (%): 2.855 (2026-11-04) | Range: 0.067–3.057 | Trend(5pt): 0.067,0.524,1.08,1.613,2.855
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
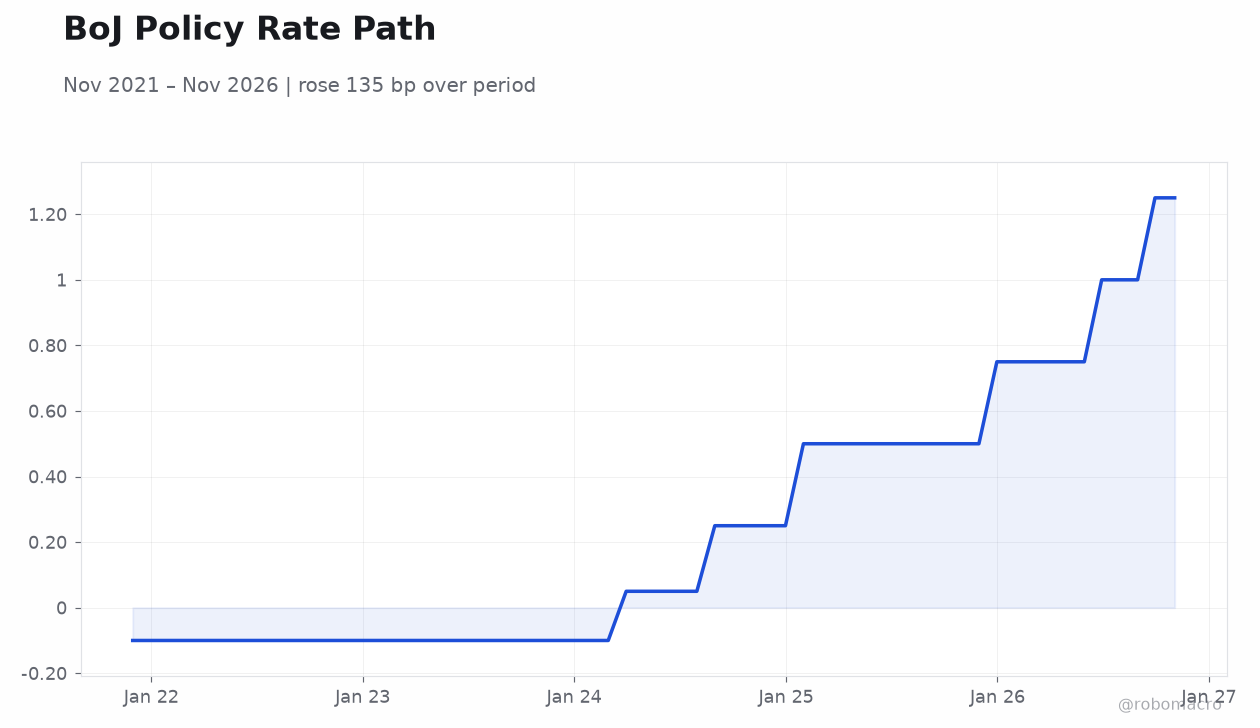
- BoJ September minutes show members agreed further rate hikes were appropriate, with one policymaker pushing for debate on the size of the next move
- Nikkei 225 fell 1.42% to 62,188.63 as risk sentiment deteriorated; USD/JPY eased 0.41% to 157.82 despite broad dollar weakness
- JGB curve bear-steepened, with the 10-year yield up 3 bp to 2.85% and the 2-year up 1 bp to 1.89%
Yesterday's Recap
The BoJ released its September Monetary Policy Meeting Minutes, which carried a hawkish tone: members concurred that it remained appropriate for the Bank to keep raising its policy interest rate, and at least one policymaker called for a debate on the size of future hikes. Japanese equities sold off sharply, with the Nikkei 225 dropping 1.42% to 62,188.63 as risk appetite deteriorated across the session. The yen initially firmed on the hawkish minutes but pared gains as the dollar recovered from its post-election sell-off, leaving USD/JPY down 0.41% at 157.82 — notably underperforming most G10 peers.
EUR/JPY slipped 0.31% to 177.04 and GBP/JPY fell 0.29% to 212.26 ahead of the BoE decision. JGB yields edged higher, with the 10-year up 3 bp to 2.85% and the 2-year up 1 bp to 1.89%, steepening the curve modestly. Cross-asset signals were mixed: gold rose 0.90% to $4,109.60 and Brent crude jumped 4.03% to $98.43, while Bitcoin tumbled 5.51% to $75,976.
The Day Ahead
The Japanese calendar is empty for November 5, leaving markets to trade off the hawkish BoJ minutes and overnight global cues. With no domestic data to anchor sentiment, JGB yields and the yen will likely take their direction from US rates and dollar dynamics following the election-driven volatility. Equity investors will watch whether the Nikkei stabilises after yesterday's 1.42% decline or extends the risk-off move.
Attention also turns to the BoE policy decision, which could shape GBP/JPY flows given the pound's recent softness against the yen. Traders will begin positioning ahead of the BoJ's December 18 meeting, the next scheduled policy decision.
Other Economic Notes
Japan's inflation backdrop remains the central macro question, with CPI running at 2.10% year-on-year as of the September 30 reading — a level that has finally reached the BoJ's target but, per local press, draws a muted public reaction. Demographic pressure continues to shape the long-run growth picture: the birth rate edged up 0.4% in the January–June period, helped by Tokyo, offering a modest but fragile positive for potential growth. ↓ p.2