Korea Macro Daily(Beta Mode)
Chip Slump Weighs as BoK Flags Consumption Risk
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| KOSPI | 5,290.53 | -0.98% |
| KOSDAQ | 699.66 | +0.45% |
| USD/KRW | 1,335.27 | +0.11% |
| Samsung | 206,000.00 | -0.96% |
| SK Hynix | 1,216,000.00 | -3.03% |
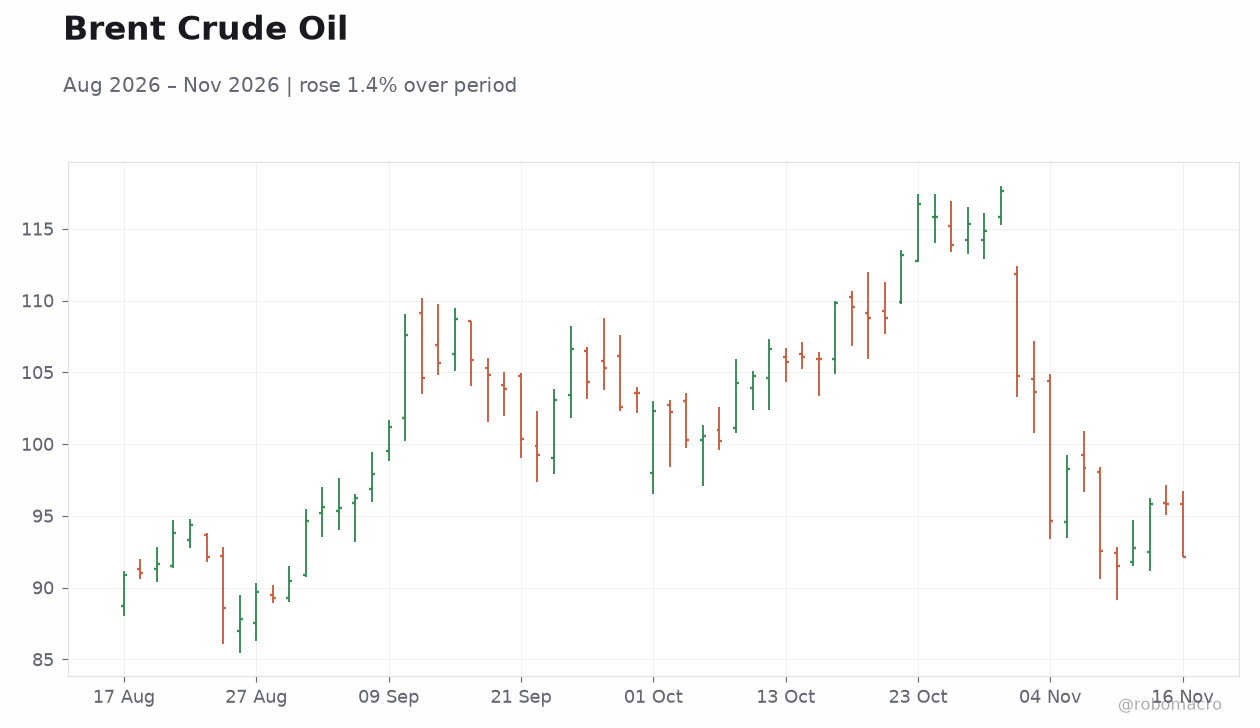
| Brent Crude | 92.16 | -3.84% |
| Gold | 3,853.10 | -0.85% |
| Bitcoin | 64,940.96 | -0.56% |
| Korea 3Y Govt Yield | 3.74% | -2 bp |
| Korea 10Y Govt Yield | 3.98% | -2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
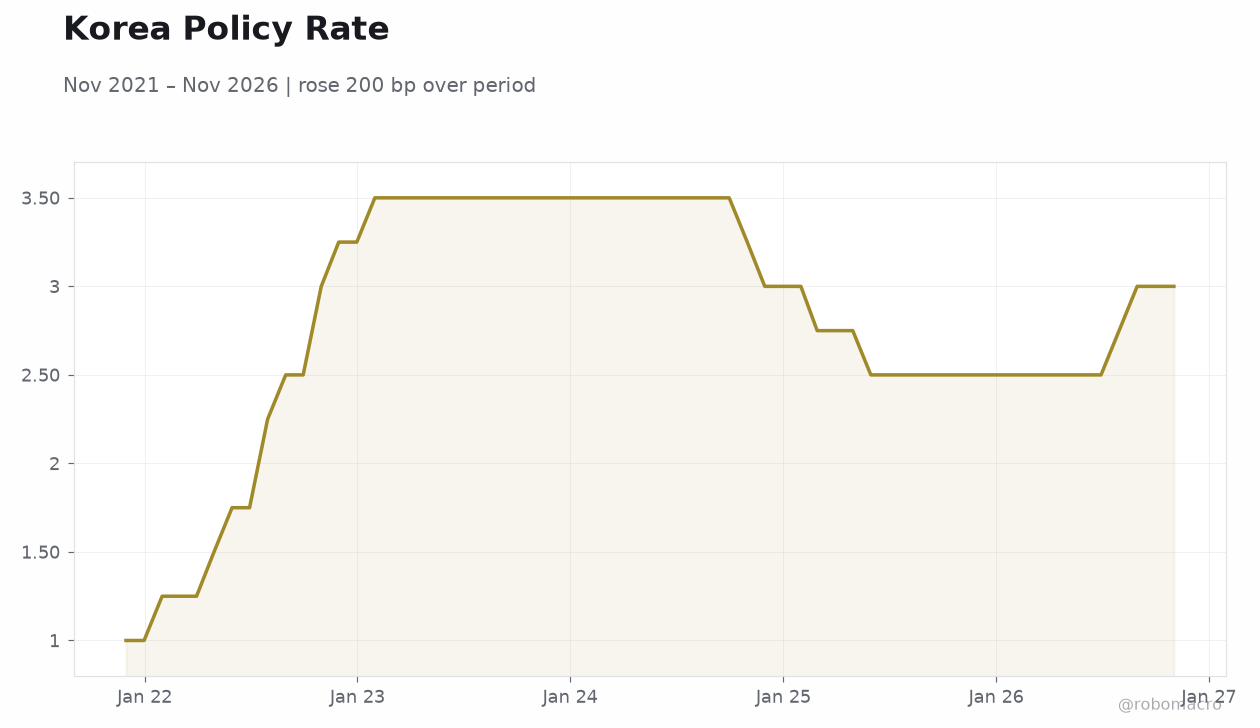 Korea Policy Rate | Type: macro_line | Policy Rate (%): 3 (2026-11-02) | Range: 1–3.5 | Trend(5pt): 1,3.5,3.5,2.5,3
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- KOSPI fell 0.98% to 5,290.53, led by SK Hynix (-3.03%) and Samsung (-0.96%), while KOSDAQ bucked the trend (+0.45%).
- Bank of Korea research warns semiconductor concentration and equity weakness are delaying the consumption recovery relative to Taiwan.
- September M2 growth slowed for a third straight month to KRW 4,283.9trn, underscoring subdued credit momentum.
Yesterday's Recap
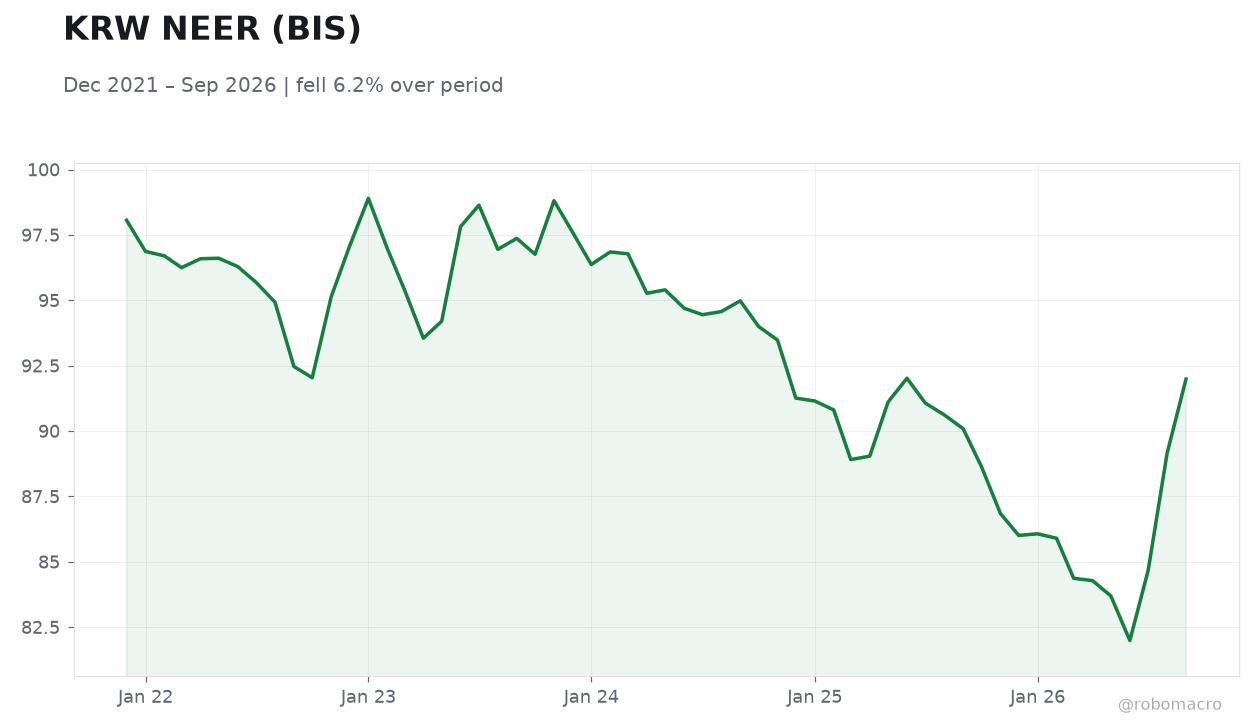
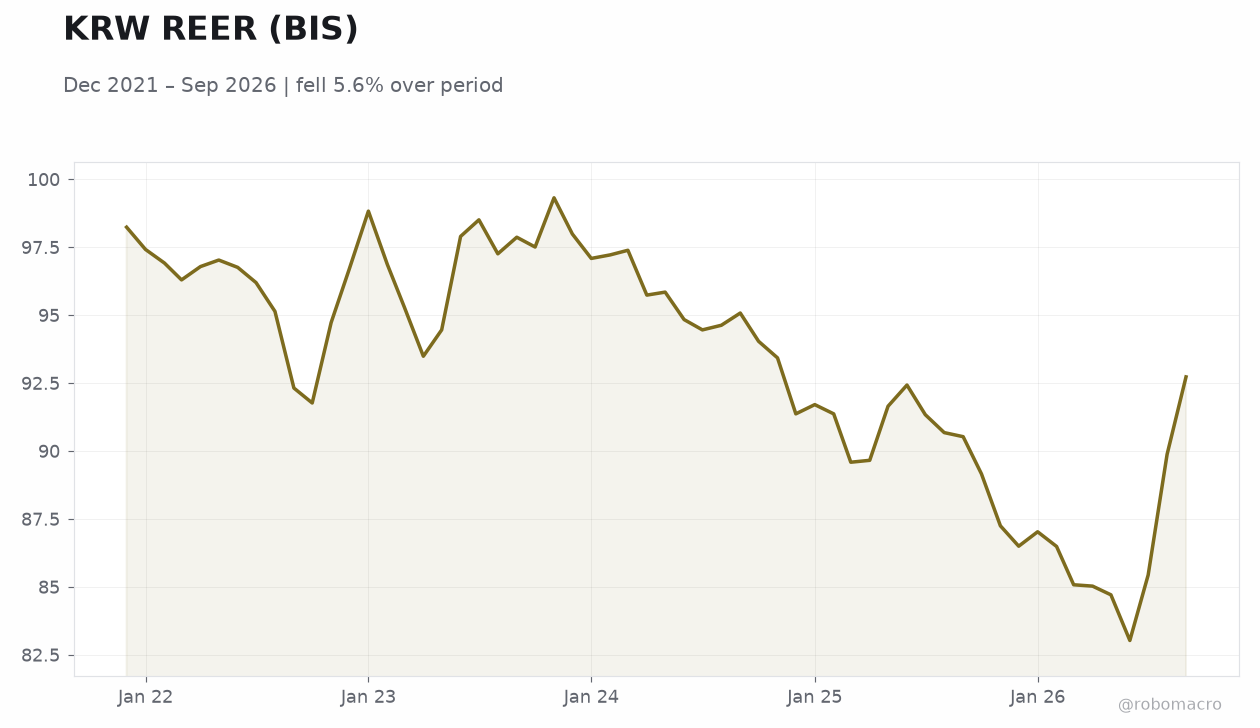
Korean equities diverged on Nov 15, with the KOSPI shedding 0.98% to 5,290.53 as semiconductor heavyweights dragged the index lower — SK Hynix dropped 3.03% and Samsung fell 0.96%. The KOSDAQ outperformed, gaining 0.45% to 699.66, suggesting rotation away from large-cap chip exposure. In FX, the won weakened modestly, with USD/KRW at 1,335.27 (+0.11%).
Note the tension in the tape: news reports attributed won weakness to an oil-price surge, yet Brent crude itself settled 3.84% lower at $92.16 — a reminder that FX and commodity moves can diverge intraday. Rates moved lower across the curve, with the 3-year yield easing 2 bp to 3.74% and the 10-year down 2 bp to 3.98%. On the data front, October import prices fell again on a stronger won and lower oil prices, while September M2 money supply growth slowed for a third consecutive month.
The BoK also disclosed expanded gold ETF holdings approaching KRW 490bn.
The Day Ahead
The domestic calendar is light on Nov 16, with no major scheduled Korean data releases, leaving markets to trade off external cues and positioning ahead of the Bank of Korea's Nov 26 policy meeting. Investors will continue to parse the implications of October import-price disinflation for the near-term CPI path, given headline CPI at 2.82% YoY. Flows will be sensitive to semiconductor sentiment after Morgan Stanley reiterated a bullish long-term KOSPI case even as it trimmed Samsung and SK Hynix targets.
With the 10-year at 3.98%, dealers will watch whether the recent bid persists amid softer oil. FX desks will monitor won direction against the dollar following the prior session's mild weakness.
Other Economic Notes
The BoK's latest research highlights a structural divergence: Korea's consumption recovery is lagging Taiwan's despite the shared AI chip boom, pointing to household balance-sheet and domestic-demand constraints that monetary easing alone may not resolve. Money-supply data reinforce this — M2 growth has decelerated for three straight months, signaling cautious credit expansion. Import-price disinflation on a firmer won and cheaper oil offers some relief to input costs but also reflects soft domestic demand.
↓ p.2