Mexico Macro Daily(Beta Mode)
Banxico Holds, Peso Weakens on Yield Spike
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| IPC Bolsa | 64,264.16 | -0.02% |
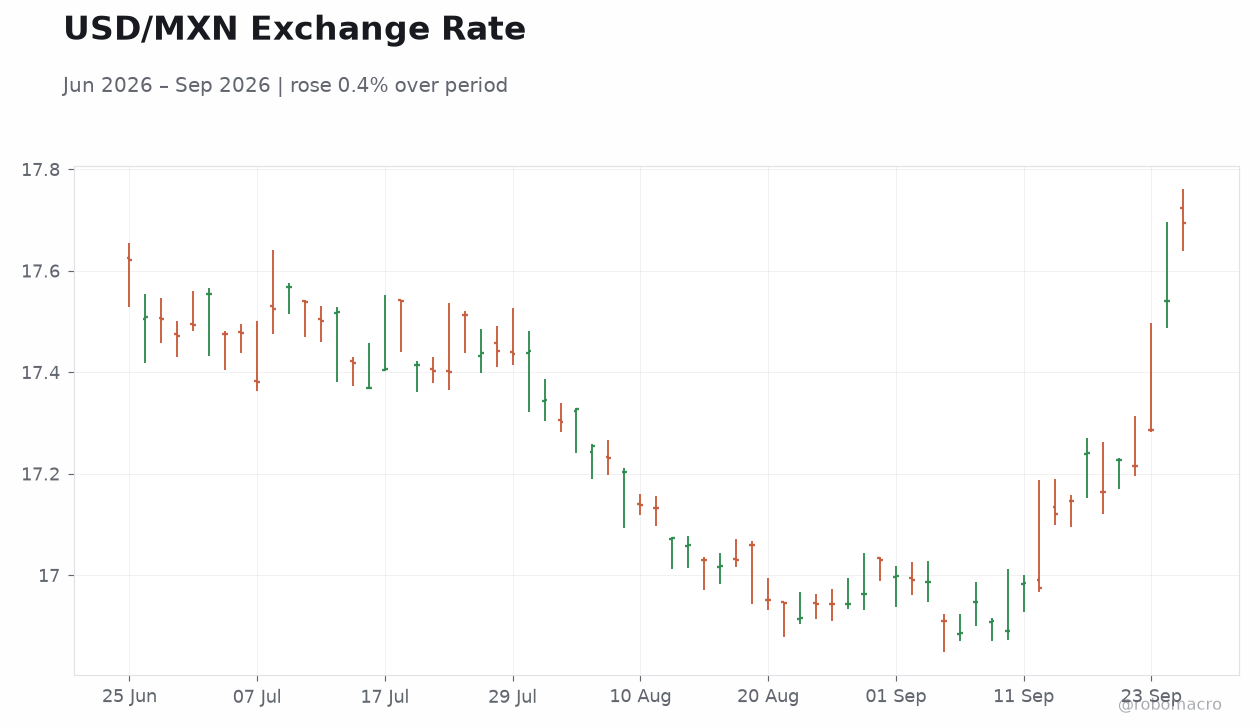
| USD/MXN | 17.54 | +1.48% |
| EUR/MXN | 20.17 | +1.03% |
| WTI Crude | 92.36 | -2.38% |
| Silver | 65.23 | +2.79% |
| Gold | 4,340.70 | +0.99% |
| Brent Crude | 98.22 | -7.86% |
| Bitcoin | 84,661.95 | +0.34% |
| Mexico 5Y Govt Yield | 9.00% | +35 bp |
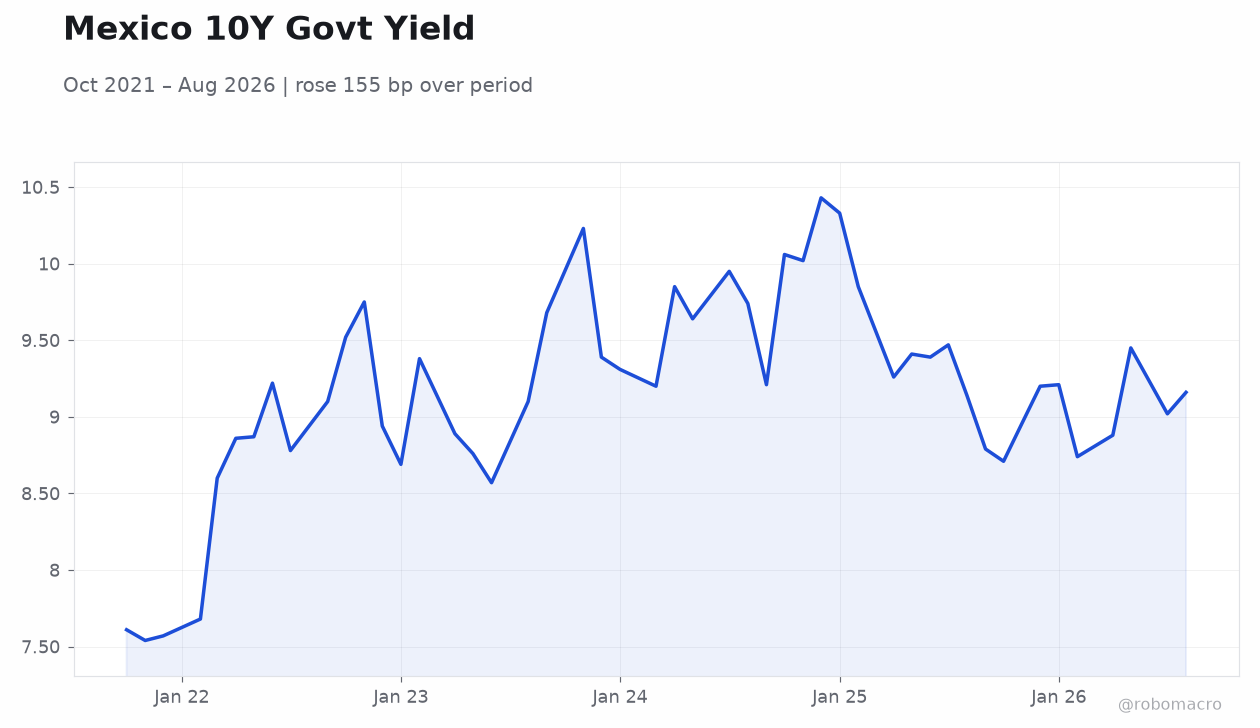
| Mexico 10Y Govt Yield | 9.35% | +19 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Central Bank Interest Rate Decision | 6.50 | 6.50 | 6.50 |
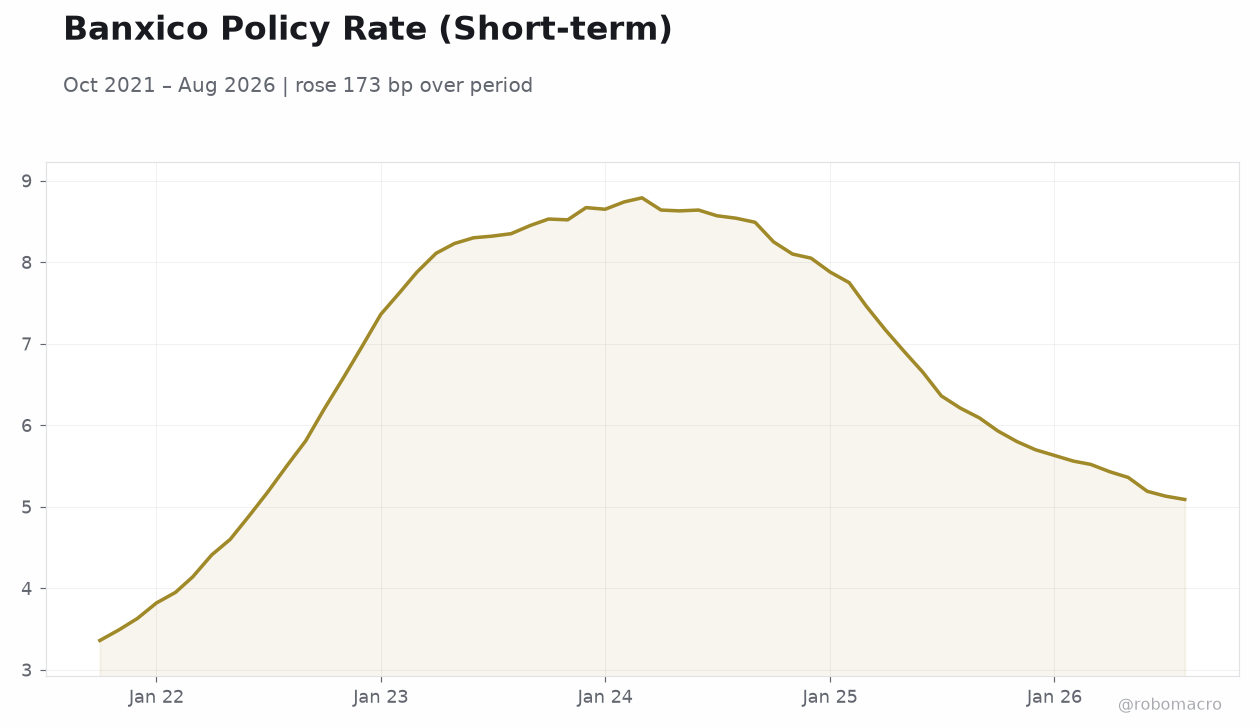 Banxico Policy Rate (Short-term) | Type: macro_line | Policy Rate %: 5.09 (2026-08-01) | Range: 3.36–8.79 | Trend(6pt): 3.36,6.96,8.74,7.17,5.19,5.09
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Banxico holds policy rate at 6.5% matching consensus
- USD/MXN climbs 1.48% as 5Y yields jump 35 bp
- Hurricane Polo tracks toward Baja California
Yesterday's Recap
Banxico left its policy rate unchanged at 6.5% on 24 September, aligning with both the prior level and market consensus. The decision triggered immediate peso depreciation, with USD/MXN advancing 1.48% to 17.54 and EUR/MXN rising 1.03% to 20.17. Front-end Mbono yields led the move higher, the 5-year yield climbing 35 bp to 9.00% while the 10-year yield added 19 bp to 9.35%.
The IPC Bolsa index edged down 0.02% to 64,264.16 as investors reassessed the pace of future easing. Oil prices fell sharply, with WTI dropping 2.38% to 92.36 and Brent declining 7.86% to 98.22, while gold and silver posted modest gains. The committee’s unanimous hold confirmed continuity in the current stance without altering near-term rate expectations.
The Day Ahead
No Mexican economic releases or Banxico speeches are scheduled for 25 September. Markets will monitor external drivers including US data prints and global commodity flows. Hurricane Polo’s approach to Baja California remains the dominant regional weather risk, with potential effects on local supply chains and energy infrastructure.
Traders will also track any updates on the India-Mexico preferential trade agreement, whose terms of reference are slated for finalization in early October. Focus stays on peso volatility and Mbono curve dynamics absent fresh domestic catalysts.
Other Economic Notes
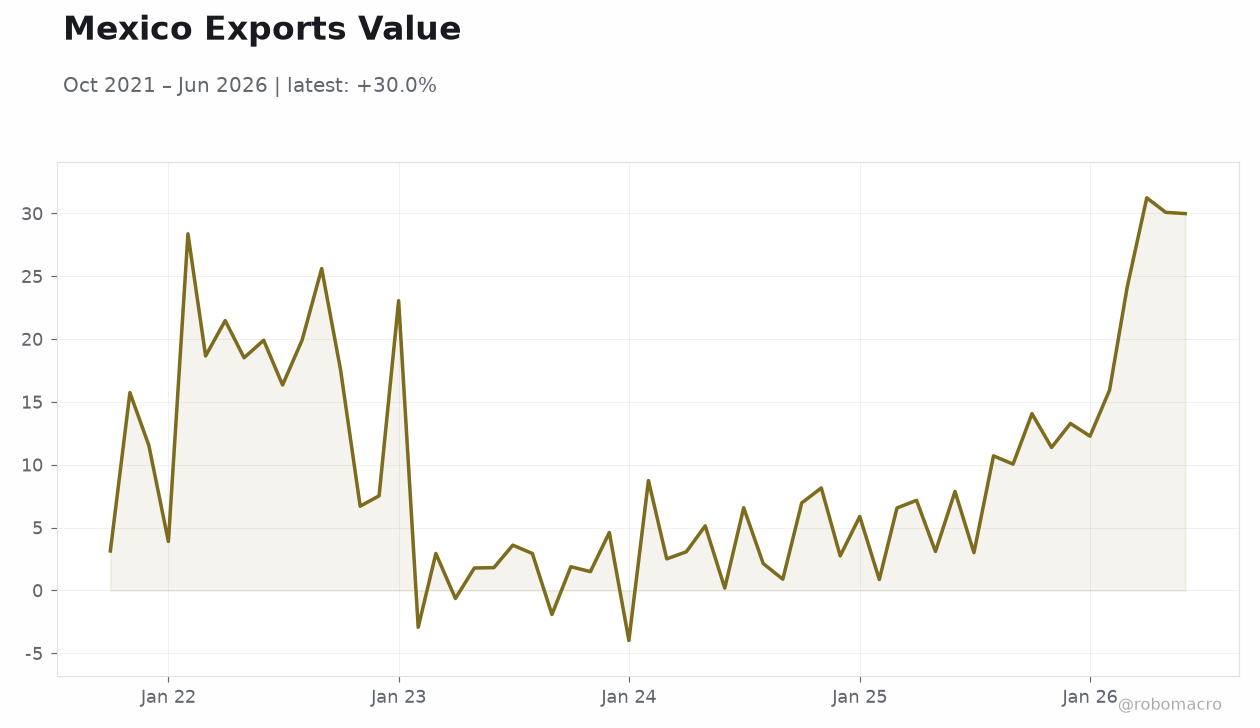
Hurricane Polo, the second-most intense east-Pacific storm on record, is fueled by unusually warm Pacific waters and threatens infrastructure and agriculture in Baja California. The prospective India-Mexico trade pact targets autos, pharmaceuticals and engineering goods, offering Mexico expanded export channels beyond North America. Nearshoring momentum continues to underpin medium-term growth prospects, though no new project announcements emerged yesterday.
Broader USMCA trade relations remain stable, with attention shifting to potential medical export opportunities involving Mexico, Brazil and India.
Global Macro News
Global central banks delivered mixed signals, with Norges Bank hiking to 4.50% and the South African Reserve Bank also raising rates amid inflation concerns. Rising global yields have narrowed Mexico’s interest-rate differential versus the Fed, pressuring carry-trade flows and contributing to peso softness. ↓ p.2