Mexico Macro Daily(Beta Mode)
Peso Slides as US Trade Talks Stall
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| IPC Bolsa | 70,249.54 | +1.43% |
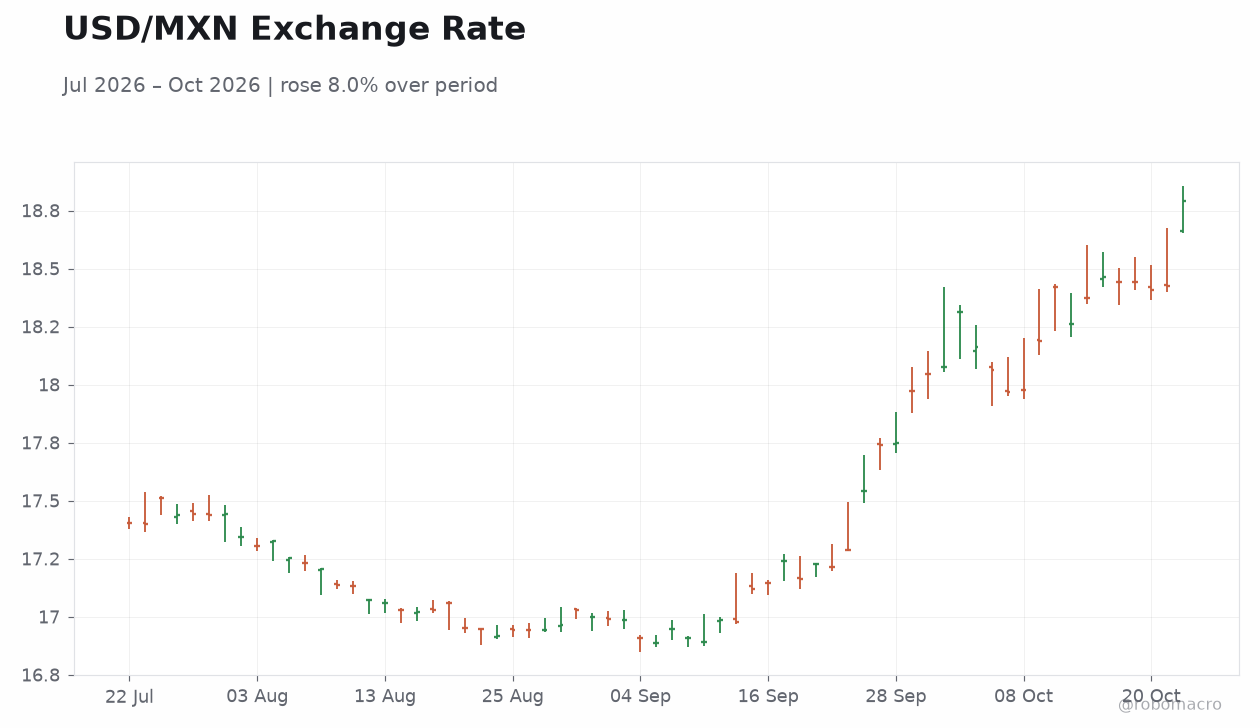
| USD/MXN | 18.80 | +2.01% |
| EUR/MXN | 20.68 | +0.13% |
| WTI Crude | 99.55 | +2.47% |
| Silver | 55.76 | -2.89% |
| Gold | 4,077.40 | -1.75% |
| Brent Crude | 112.07 | +2.99% |
| Bitcoin | 81,718.97 | -2.73% |
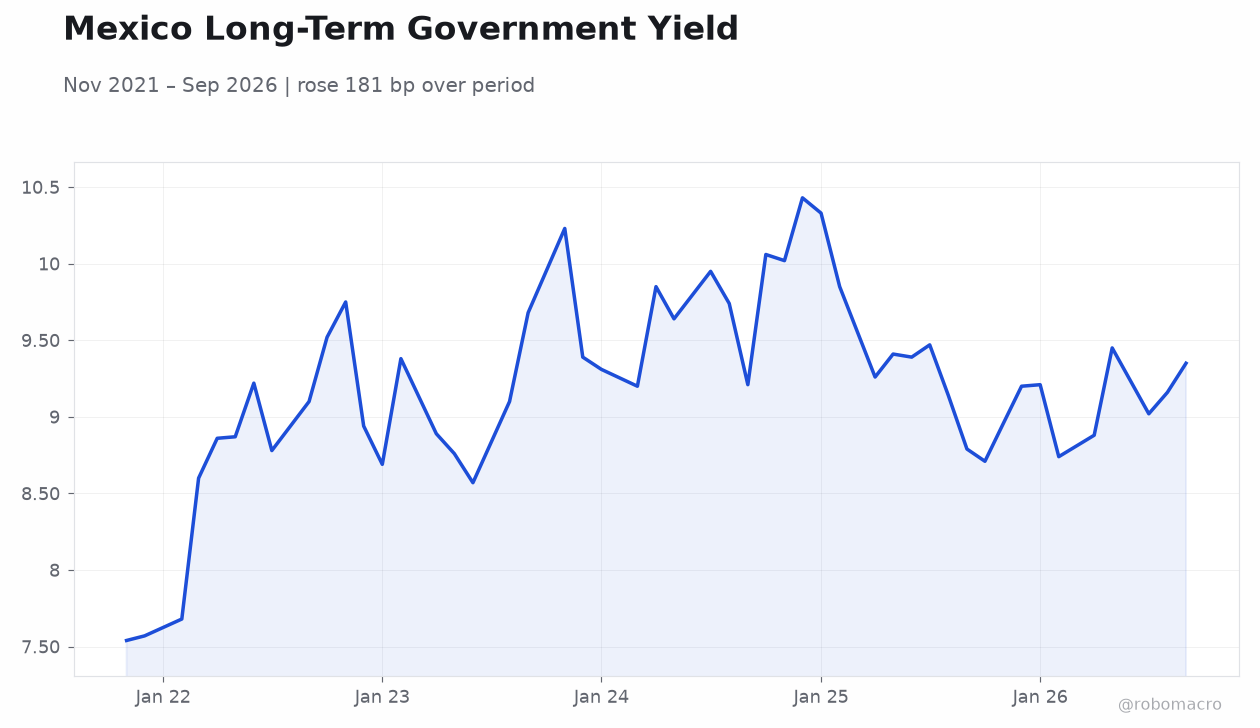
| Mexico 10Y Govt Yield | 9.25% | -10 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
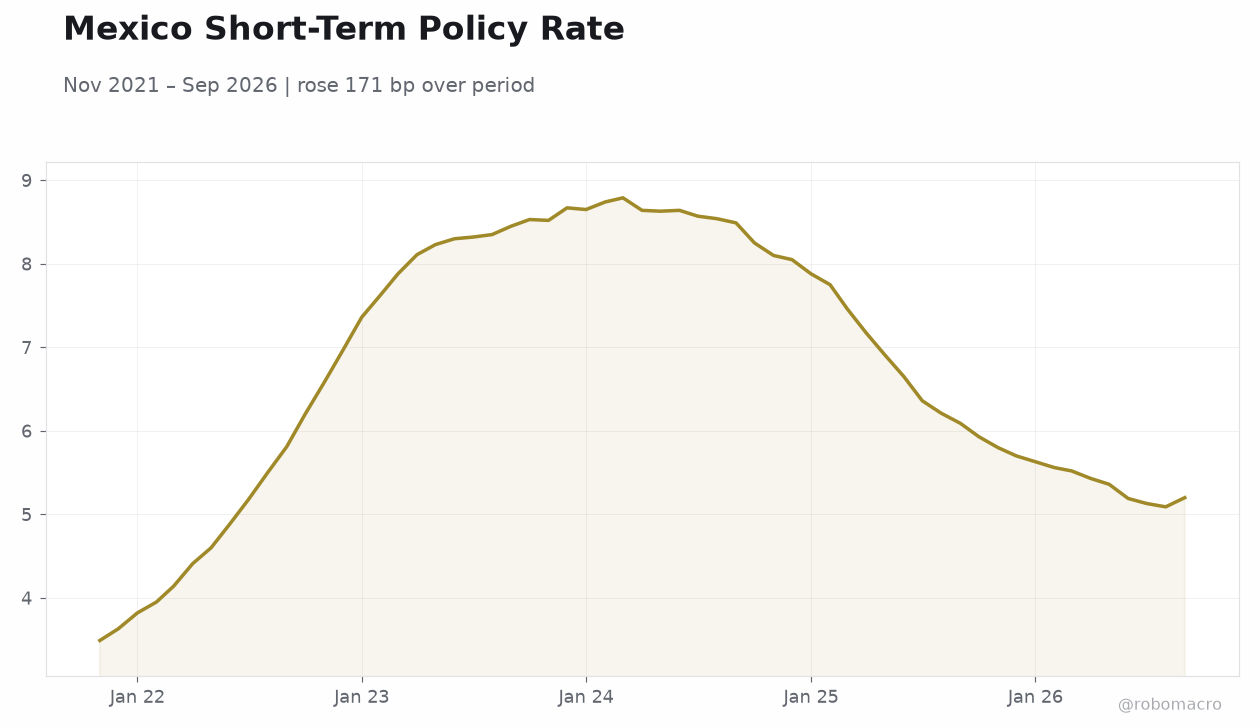 Mexico Short-Term Policy Rate | Type: macro_line | Short-term rate %: 5.2 (2026-09-01) | Range: 3.49–8.79 | Trend(6pt): 3.49,7.36,8.79,6.91,5.13,5.2
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- USD/MXN jumps 2.01% to 18.80 as US-Mexico trade negotiations hit an impasse over Lutnick's influence
- Mexico 10Y yield falls 10 bp to 9.25% despite peso weakness, suggesting duration demand remains intact
- WTI surges 2.47% to $99.55 and Brent 2.99% to $112.07, adding imported inflation pressure
Yesterday's Recap
Mexican markets delivered a split session Wednesday, with the IPC Bolsa rallying 1.43% to 70,249.54 even as the peso sold off sharply. USD/MXN climbed 2.01% to 18.80, while EUR/MXN edged up 0.13% to 20.68, reflecting broad dollar strength against the Mexican currency. The Mexico 10Y government yield eased 10 bp to 9.25%, an unusual move alongside peso weakness that points to continued domestic duration appetite rather than outright risk-off.
Precious metals retreated, with silver down 2.89% to $55.76 and gold off 1.75% to $4,077.40, while Bitcoin fell 2.73% to 81,718.97. Energy was the standout gainer, with WTI up 2.47% to $99.55 and Brent up 2.99% to $112.07. No scheduled Mexican data releases printed during the session, leaving price action driven by external flows and trade headlines.
The Day Ahead
The Mexican calendar is empty for Thursday, so attention shifts to external catalysts and headline risk around US-Mexico trade negotiations. With no domestic prints scheduled, peso direction will likely be dictated by dollar momentum and any incremental commentary from trade negotiators following the reported impasse. Energy prices near triple digits for WTI remain a live input for inflation expectations and the terms-of-trade backdrop.
Market participants will also watch whether the 10Y yield's decline extends, which would signal continued demand for Mexican duration even amid currency volatility. Absent local data, positioning flows and global risk sentiment should dominate the session.
Other Economic Notes
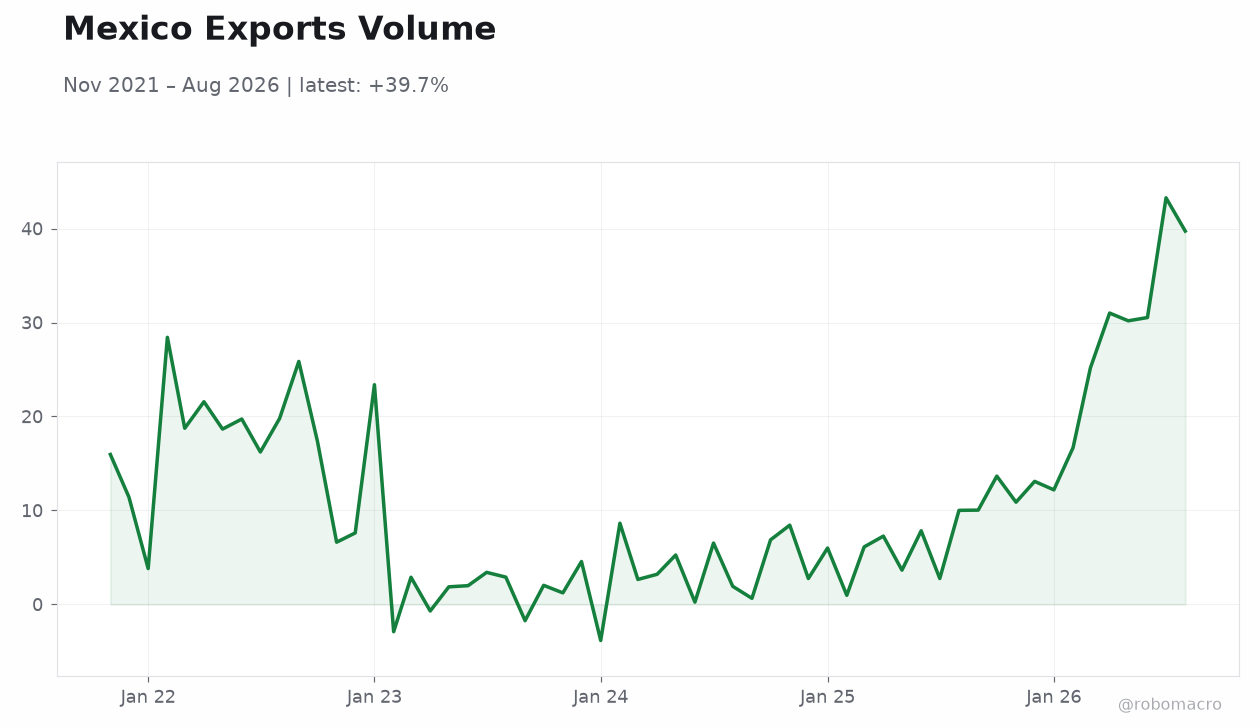
The trade impasse reported by the Financial Post is the key structural risk, with Mexican officials having previously expressed confidence that a deal was within reach before Lutnick's influence shifted the negotiating dynamic. Nearshoring momentum remains the medium-term anchor for Mexican industrial and logistics investment, but a prolonged standoff could delay capex decisions. CPI at 3.45% YoY sits comfortably within Banxico's tolerance band, giving the central bank room to look through energy-driven price pressure.
Political noise, including the treason charge against former prosecutor César Jáuregui Moreno over a US drug raid, is a reminder that security cooperation remains a sensitive bilateral file. ↓ p.2