Mexico Macro Daily(Beta Mode)
Mexico Yield Eases as Peso Strengthens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| IPC Bolsa | 69,470.99 | -0.58% |
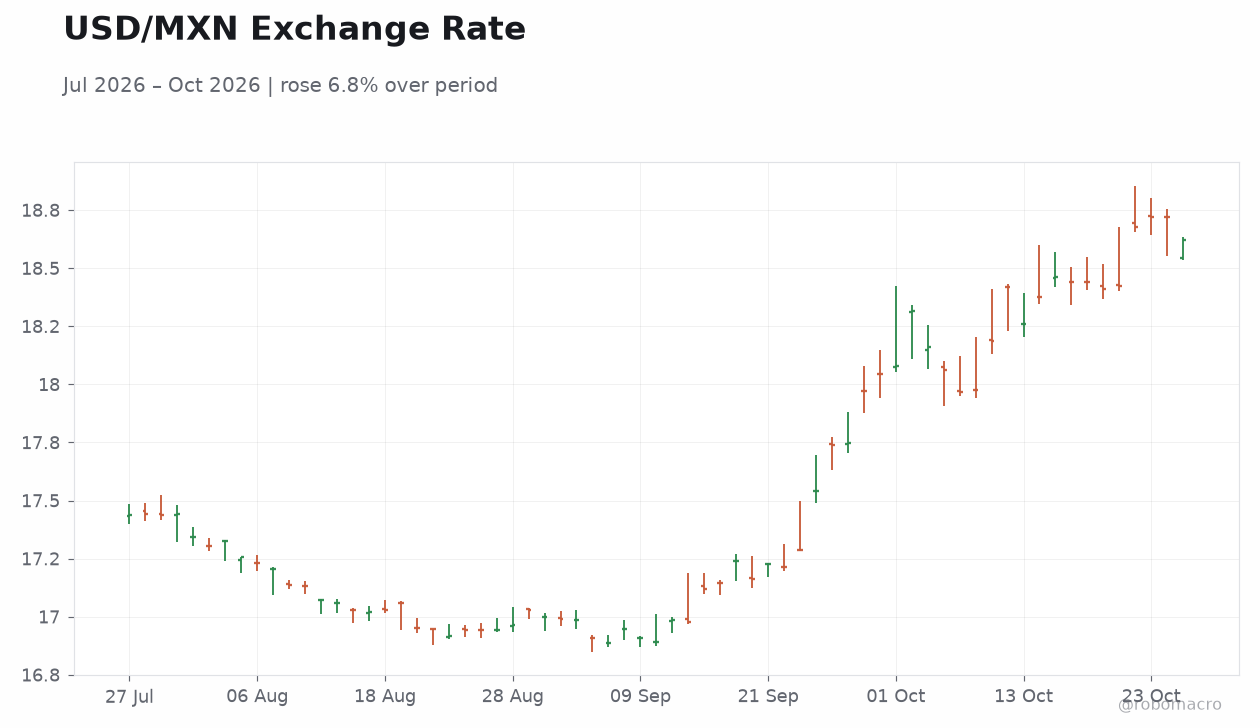
| USD/MXN | 18.62 | -0.52% |
| EUR/MXN | 20.76 | -1.14% |
| WTI Crude | 101.03 | -0.72% |
| Silver | 53.38 | -1.34% |
| Gold | 4,023.50 | -0.37% |
| Brent Crude | 109.92 | -5.09% |
| Bitcoin | 79,719.85 | -0.36% |
| Mexico 10Y Govt Yield | 9.25% | -10 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Trade Balance | 605m | - | - |
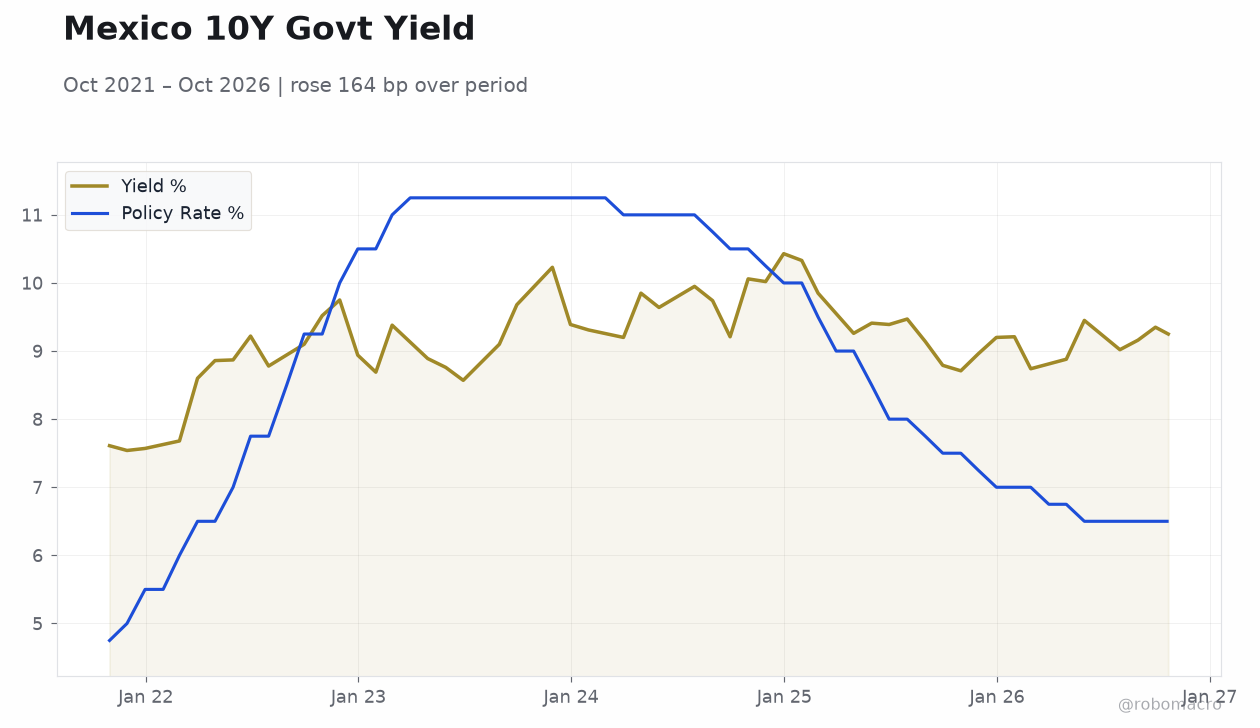 Mexico 10Y Govt Yield | Type: macro_line | Yield %: 9.25 (2026-10-22) | Range: 7.54–10.43 | Trend(6pt): 7.61,8.94,9.85,9.39,9.16,9.25 | Policy Rate %: 6.5 (2026-10-20) | Range: 4.75–11.25 | Trend(5pt): 4.75,10.5,11,8,6.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Friday (2026-10-30) | |||
| GDP Growth Quarter-over-Quarter Preliminary | 1.40 | 0.50 | 08:00 |
| GDP Growth Year-over-Year Preliminary | 2.10 | 2.40 | 08:00 |
- IPC slips 0.58% while 10-year yield falls 10 bp to 9.25% amid thin data flow.
- USD/MXN drops 0.52% to 18.62 as investors position ahead of Friday GDP prints.
- Banxico holds policy rate at 6.50% with next decision scheduled for 5 November.
Yesterday's Recap
Mexican assets posted modest declines on 26 October as the IPC Bolsa closed 0.58% lower at 69,470.99. The peso gained ground, with USD/MXN falling 0.52% to 18.62 and EUR/MXN declining 1.14% to 20.76. The Mexico 10-year government yield eased 10 basis points to 9.25%, reflecting reduced term premium after the latest inflation reading.
Trade balance data released with no meaningful surprise, leaving market focus on positioning rather than fresh surprises. Brent crude’s 5.09% drop weighed on energy-related names within the index, while gold and silver also retreated. Overall volumes remained light, consistent with limited domestic catalysts ahead of the GDP release.
The moves aligned with broader risk-off sentiment across emerging-market currencies. Nearshoring-related flows continued to underpin longer-term peso support despite the session’s softness.
The Day Ahead
Attention turns to Friday’s preliminary GDP figures due at 08:00 ET. Quarter-over-quarter growth is expected at 0.5% after the prior 1.4% print, while year-over-year growth is forecast at 2.4% versus 2.1% previously. These releases will update views on the pace of nearshoring-driven activity and domestic demand.
No other high-impact Mexican data are scheduled before the weekend. Traders will also monitor any remarks from officials on USMCA implementation ahead of bilateral meetings. Positioning in the peso and local bonds is likely to remain cautious until the numbers confirm the growth trajectory.
Light trading is anticipated into the print given the holiday-shortened week.
Other Economic Notes
Nearshoring continues to support manufacturing investment, yet softer sequential GDP would signal that capacity constraints and logistics bottlenecks are capping the upside. USMCA trade flows remain the dominant channel for Mexican exports, with any renewed US tariff rhetoric likely to pressure the peso and local yields. Inflation at 3.45% year-over-year keeps Banxico’s target range in focus, limiting room for aggressive easing even as global growth concerns mount.
↓ p.2