US Macro Daily(Beta Mode)
Equities Advance Ahead of Fed Decision
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,676.77 | +0.70% |
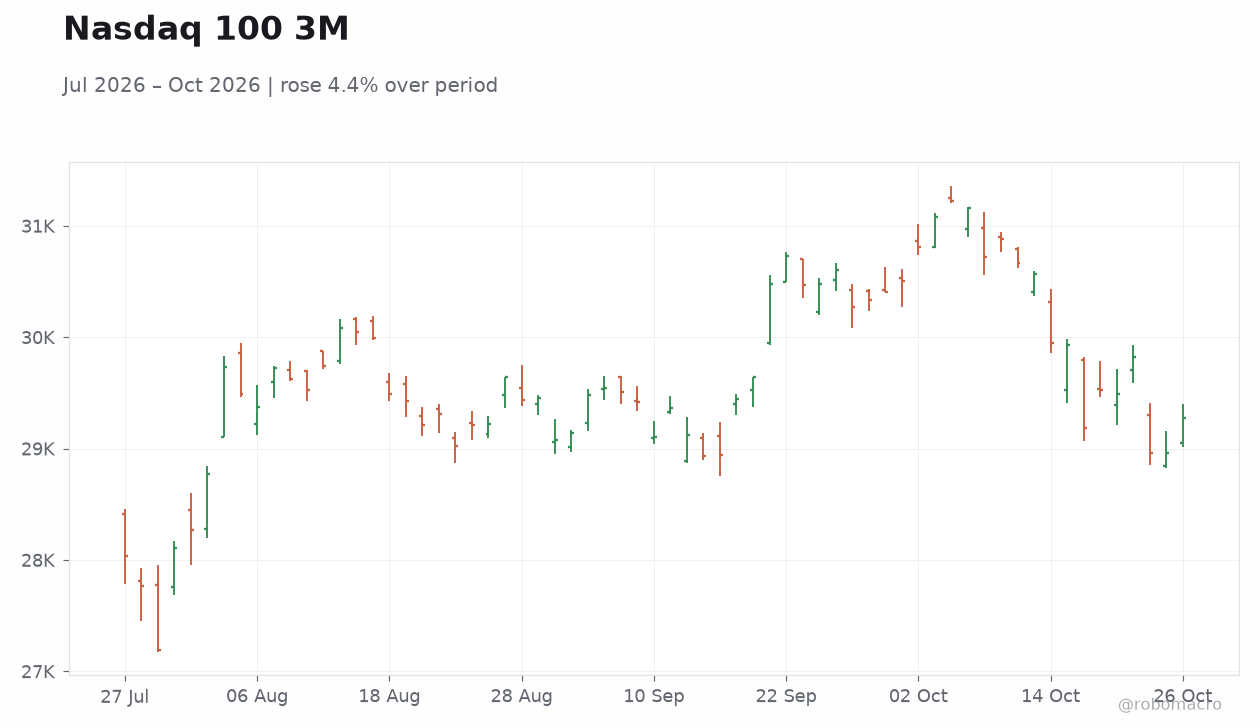
| Nasdaq 100 | 29,273.40 | +1.09% |
| Dow Jones | 52,361.58 | +0.28% |
| Russell 2000 | 2,786.42 | +0.38% |
| USD/JPY | 157.68 | +0.54% |
| EUR/USD | 1.12 | -0.60% |
| GBP/USD | 1.33 | -0.45% |
| Gold | 4,023.80 | -0.36% |
| WTI Crude | 101.12 | -0.63% |
| Bitcoin | 79,868.36 | -0.17% |
| US 2Y Treasury | 4.68% | -1 bp |
| US 10Y Treasury | 5.00% | 0 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
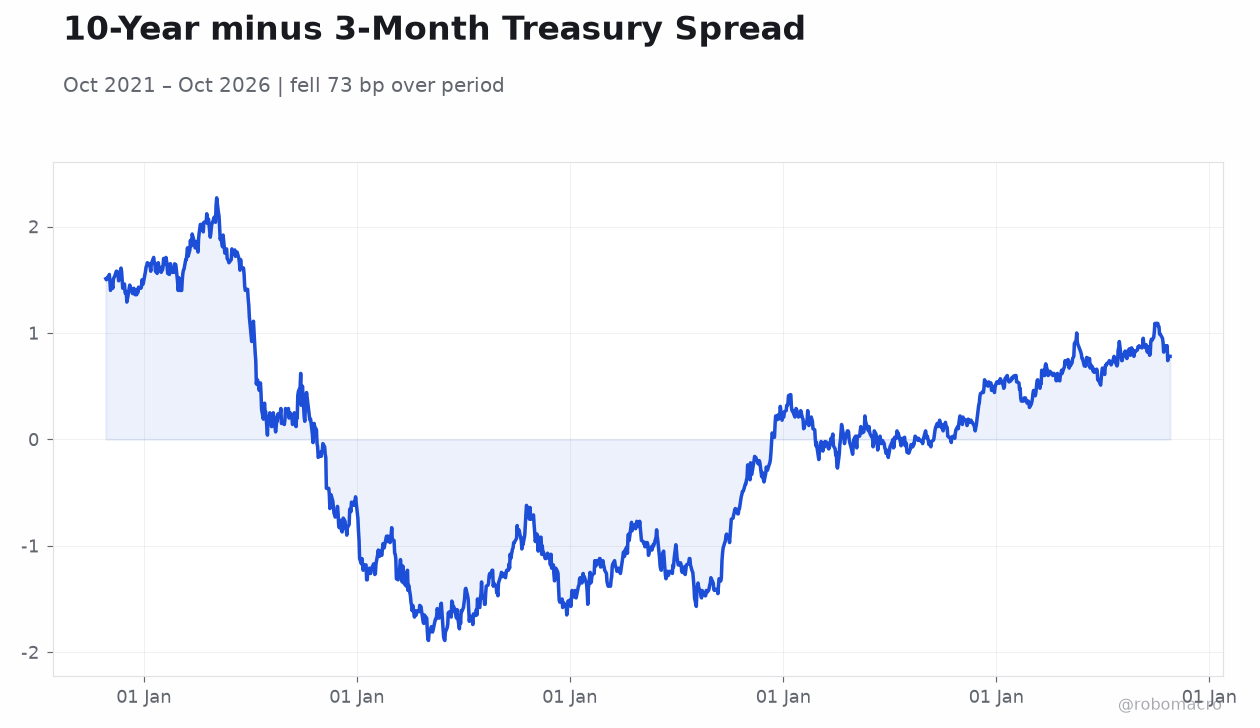
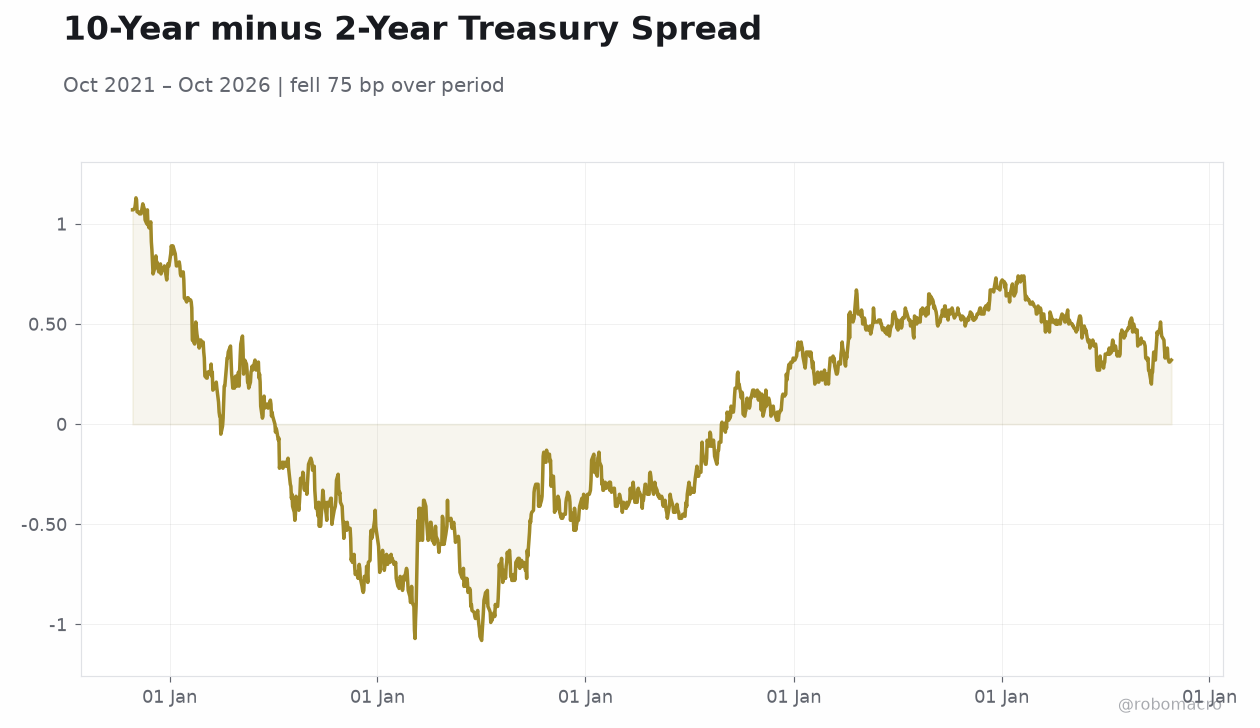 10-Year minus 2-Year Treasury Spread | Type: macro_line | 10-Year minus 2-Year Treasury Spread: 0.32 (2026-10-26) | Range: -1.08–1.13 | Trend(6pt): 1.07,-0.7,-0.26,0.49,0.31,0.32
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Equities rose across major indices with the S&P 500 gaining 0.70% as investors positioned ahead of the FOMC.
- Treasury yields held steady, with the 2-year at 4.68% and the 10-year unchanged at 5.00%.
- Attention centers on tomorrow’s policy decision amid robust growth and contained inflation.
Yesterday's Recap
US equity markets posted solid gains on October 26 despite a complete absence of scheduled economic data releases. The S&P 500 climbed 0.70% to 7,676.77 while the Nasdaq 100 advanced 1.09% to 29,273.40, reflecting renewed risk appetite. The Dow Jones rose 0.28% and the Russell 2000 added 0.38%.
Treasury yields remained anchored, with the 2-year easing 1 bp to 4.68% and the 10-year holding at 5.00%. The dollar strengthened modestly against the yen but eased versus the euro and sterling. Gold and crude oil both declined slightly, while Bitcoin traded near unchanged.
With no prints to shift expectations, trading reflected positioning for the upcoming FOMC meeting.
The Day Ahead
Markets will focus almost exclusively on the Federal Reserve’s October 28 policy announcement. The committee is expected to maintain the federal funds target range at 3.75-4.00%. Attention will center on any revisions to the dot plot and forward guidance regarding the path of rates through year-end.
Treasury market participants will scrutinize Chair Powell’s press conference for signals on inflation persistence and labor-market resilience. Equity volatility may rise if the statement language deviates from recent communications. No other major US data releases are scheduled.
Other Economic Notes
The US economy continues to expand at a moderate pace, with GDP growth running at 2.20% QoQ SAAR and 2.19% YoY. Inflation remains above target at 3.70% YoY, while the unemployment rate sits at 4.20%. Retail sales have grown 6.29% YoY, supporting the view of resilient consumer demand.
These readings suggest the Fed can afford to hold policy steady without immediate concern over overheating or sharp slowdown. Market pricing continues to reflect a high probability of no change at the October meeting.