South Africa Macro Daily(Beta Mode)
Rand Firms as Yields Ease Ahead of Trade Data
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| JSE Top 40 | 103,152.20 | -0.65% |
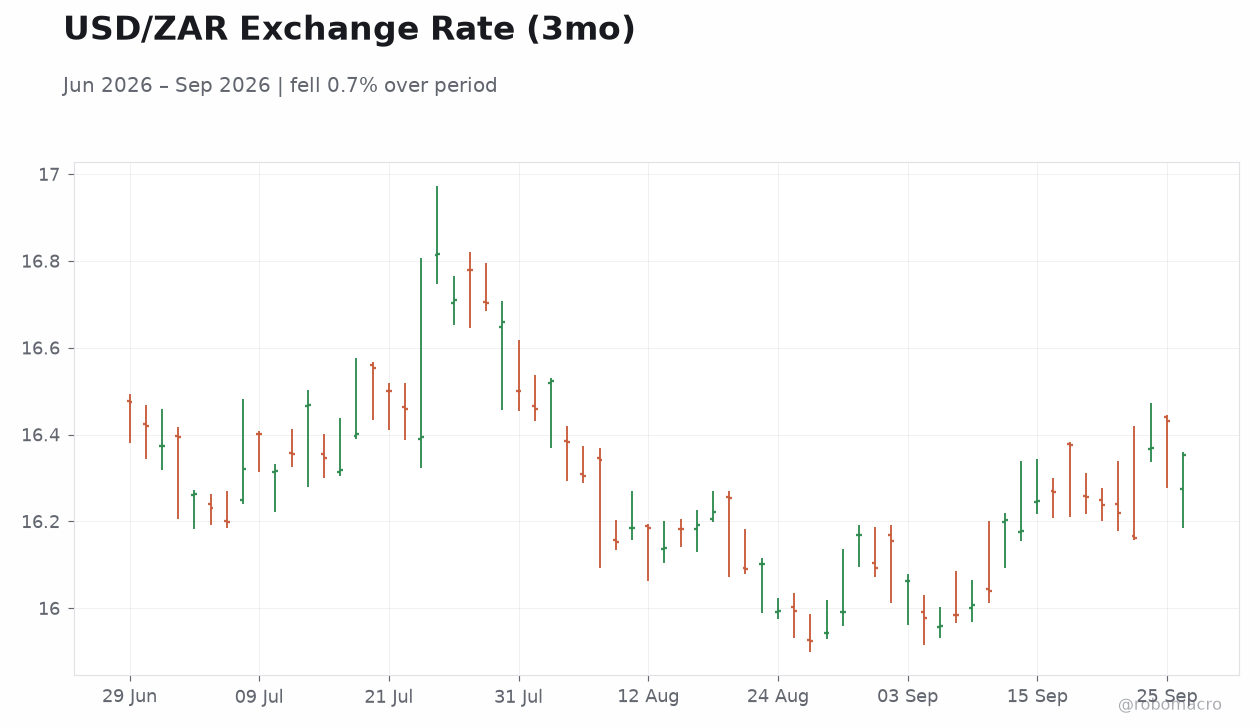
| USD/ZAR | 16.35 | -0.47% |
| EUR/ZAR | 18.62 | -0.40% |
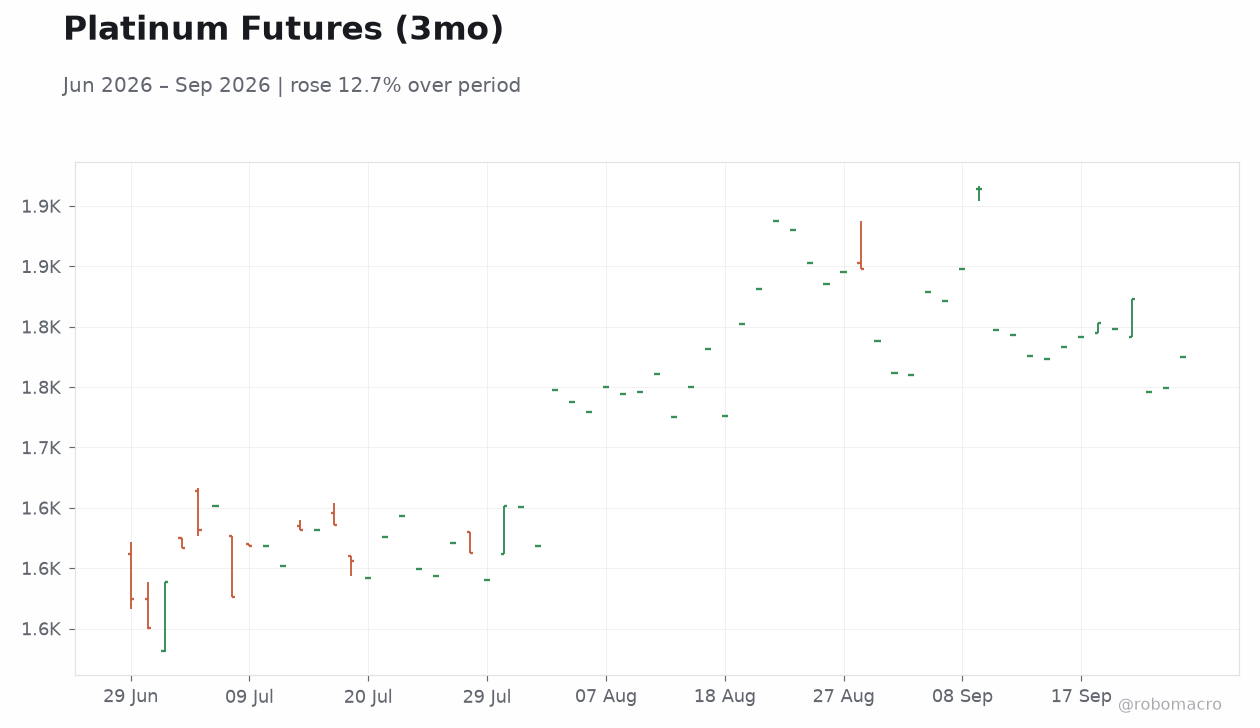
| Platinum | 1,774.70 | +1.46% |
| Gold | 4,321.20 | +0.54% |
| Brent Crude | 104.32 | -2.14% |
| Naspers | 70,938.00 | -0.34% |
| Bitcoin | 83,244.47 | -1.38% |
| South Africa 5Y Govt Yield | 8.59% | -2 bp |
| South Africa 10Y Govt Yield | 8.83% | -2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
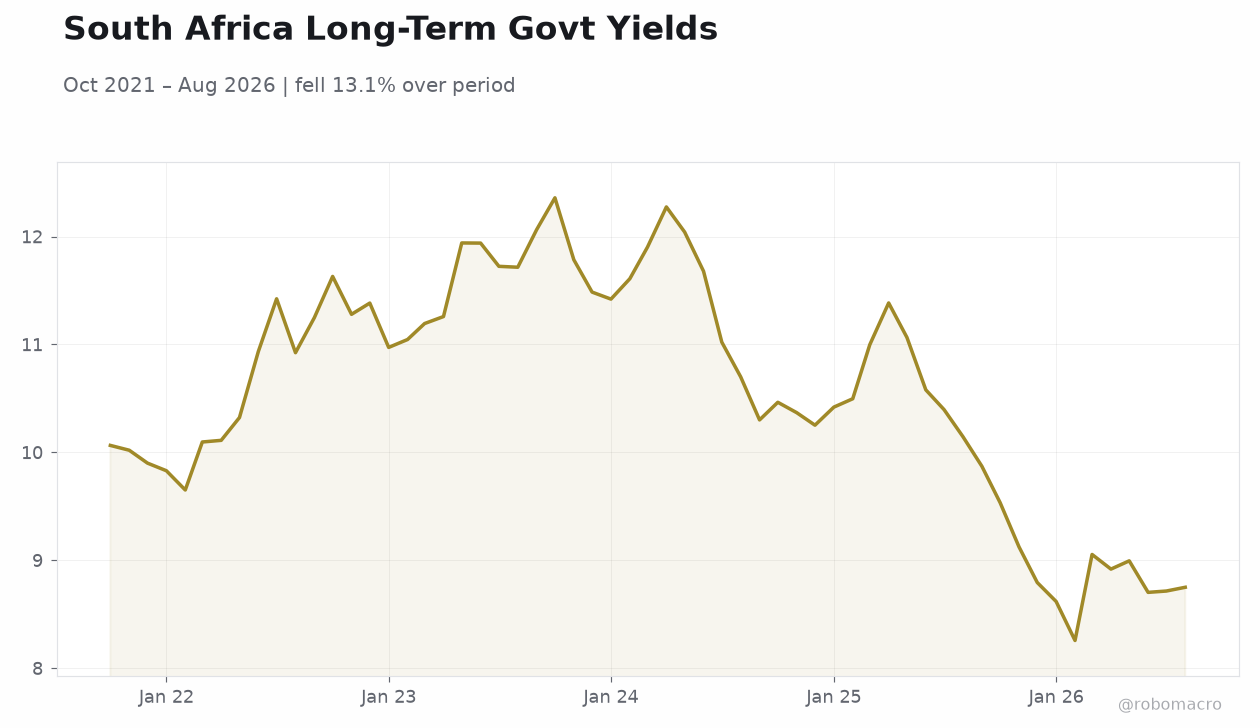 South Africa Long-Term Govt Yields | Type: macro_line | Yield %: 8.75 (2026-08-01) | Range: 8.257–12.36 | Trend(6pt): 10.06,11.38,11.61,11.38,8.703,8.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wednesday (2026-09-30) | |||
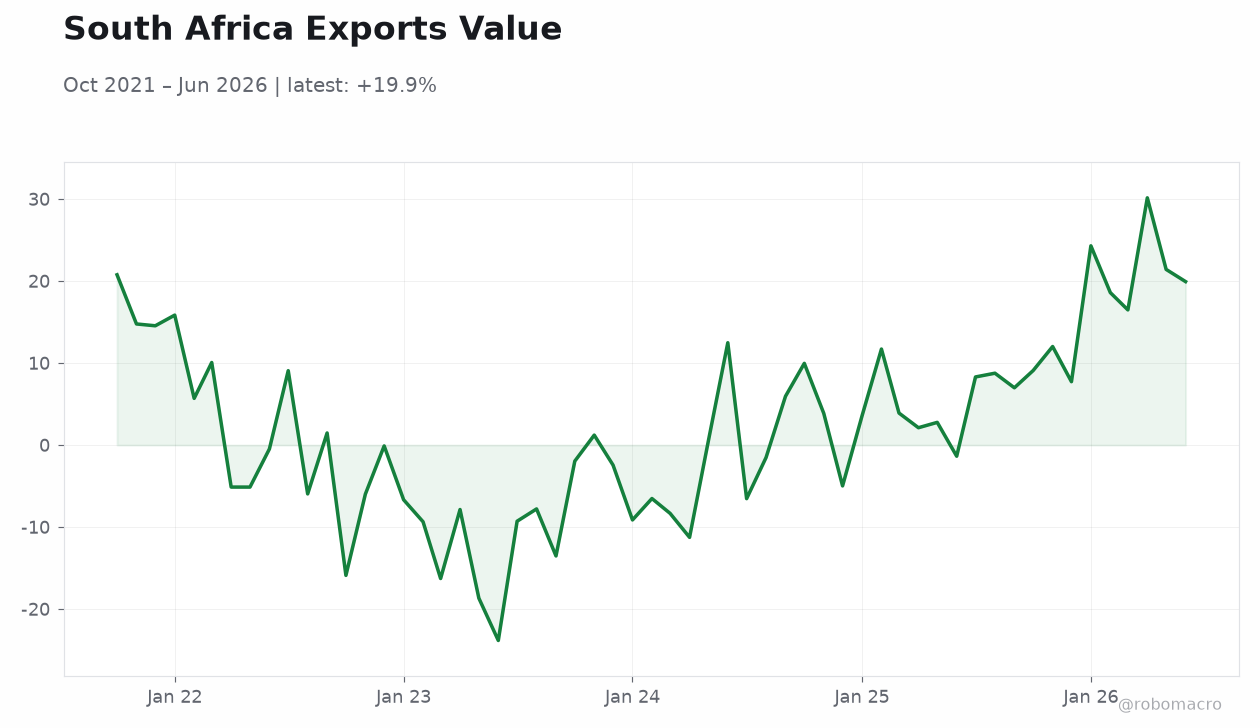
| Trade Balance | 20,140m | - | 04:00 |
- JSE Top 40 falls 0.65% to 103,152.20 while USD/ZAR drops 0.47% to 16.35
- Platinum rises 1.46% to 1,774.70 and gold gains 0.54% to 4,321.20
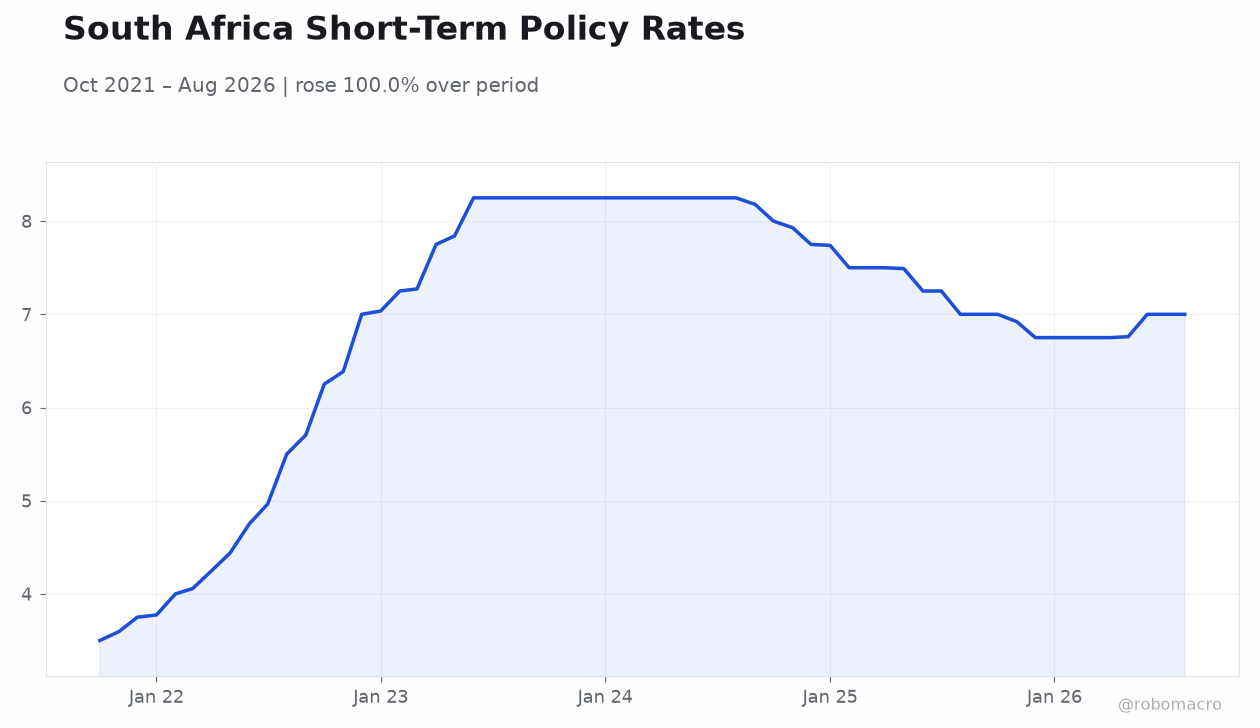
- South Africa 10-year yield eases 2 bp to 8.83% after recent SARB hike
Yesterday's Recap
South African markets closed lower on equities but firmer on the rand after the JSE Top 40 declined 0.65 percent to 103,152.20. USD/ZAR finished at 16.35 after a 0.47 percent decline while EUR/ZAR eased 0.40 percent to 18.62. Platinum advanced 1.46 percent to 1,774.70 and gold rose 0.54 percent to 4,321.20 as Brent crude fell 2.14 percent to 104.32.
The 5-year government yield declined 2 basis points to 8.59 percent and the 10-year yield also fell 2 basis points to 8.83 percent. No economic data releases occurred on 27 September. Naspers slipped 0.34 percent to 70,938.00 and Bitcoin dropped 1.38 percent to 83,244.47.
Market moves reflected absorption of the SARB’s recent repo rate increase amid limited local catalysts.
The Day Ahead
The South African Trade Balance for August prints at 04:00 ET on 30 September with the prior reading at 20.14 billion rand. Analysts expect the figure to influence short-term rand positioning if it deviates from recent surpluses. No SARB speeches or MPC minutes are scheduled.
Global risk sentiment and commodity prices will likely drive USD/ZAR flows ahead of the release. Markets will also monitor any updates on mining output given platinum and gold price gains. Load-shedding risks remain a background factor for industrial production data later in the week.
Other Economic Notes
Persistent structural pressures continue to weigh on South Africa’s growth outlook according to recent commentary highlighting brewing economic pain. Mining sector performance offers partial offset as platinum and gold prices rise while the rand’s modest strength supports import costs. Energy supply constraints remain a key drag on manufacturing and mining output with no immediate resolution signaled.
Fiscal and external balances stay in focus as the upcoming trade print could clarify trends in goods exports. Broader sentiment reflects caution ahead of global inflation prints that may affect emerging-market flows.