South Africa Macro Daily(Beta Mode)
JSE Climbs on Platinum Rally, Rand Holds
Market Snapshot
| Asset | Level | Change |
|---|---|---|
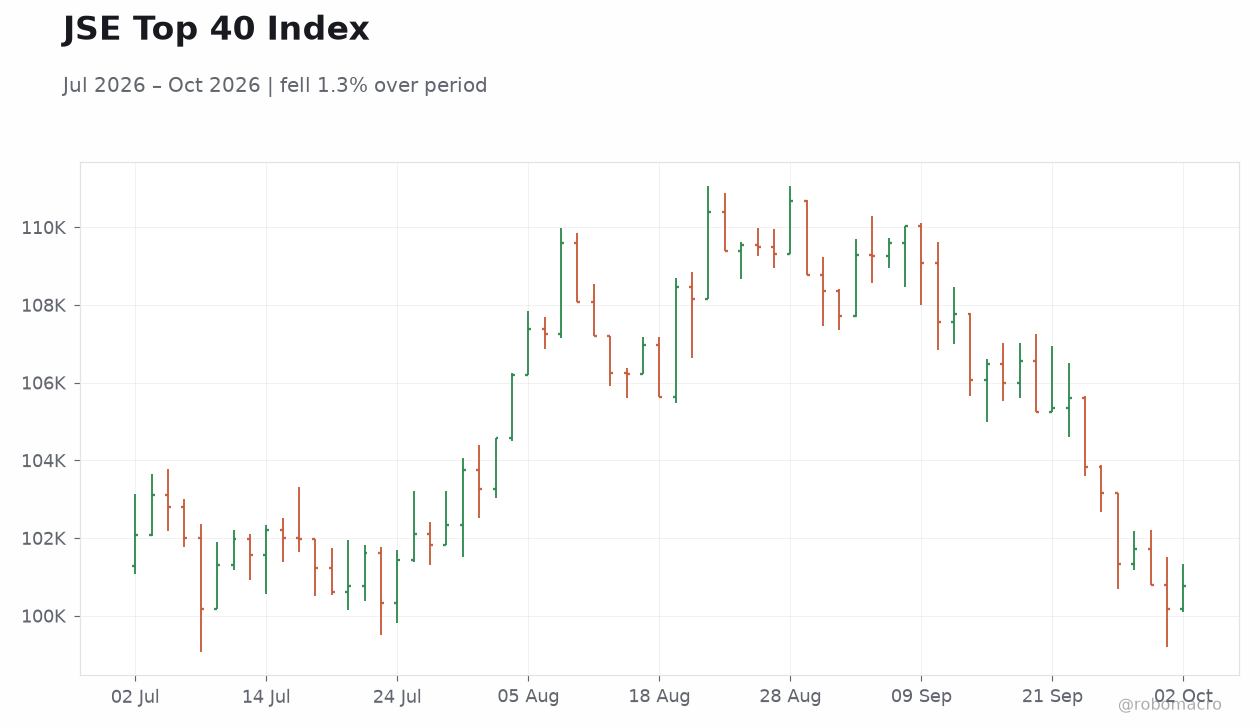
| JSE Top 40 | 100,779.60 | +0.61% |
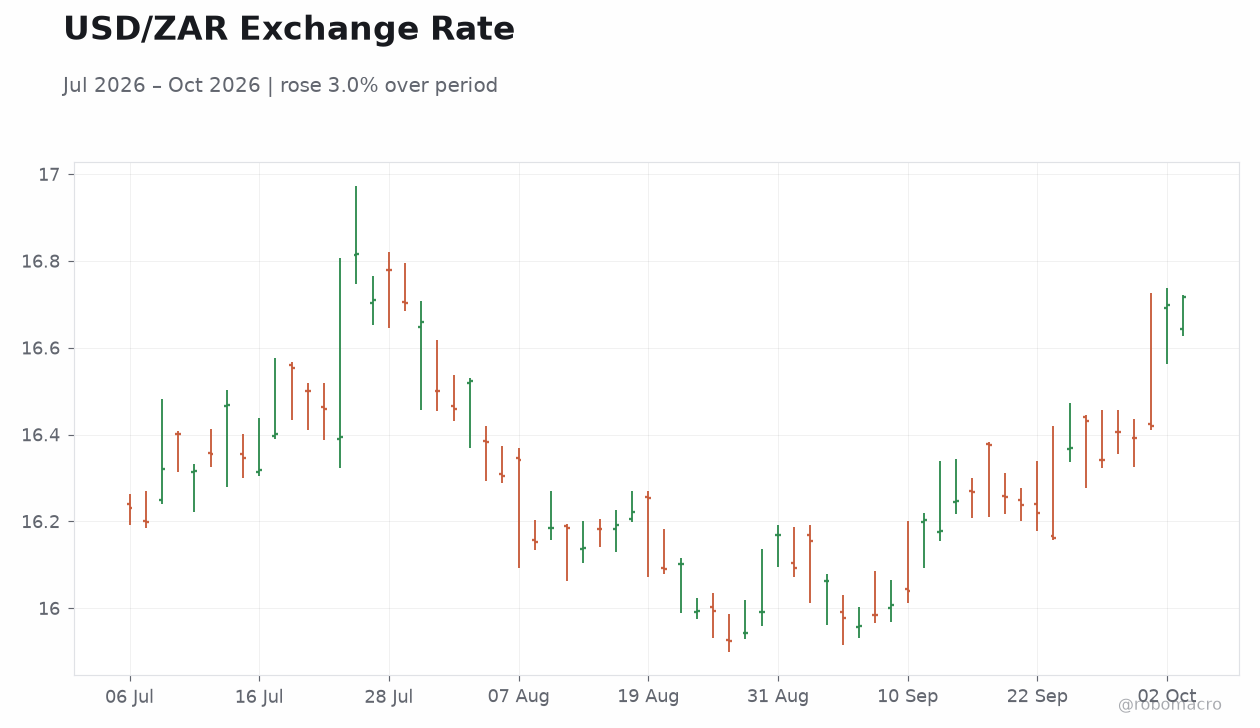
| USD/ZAR | 16.72 | +0.11% |
| EUR/ZAR | 18.78 | +0.99% |
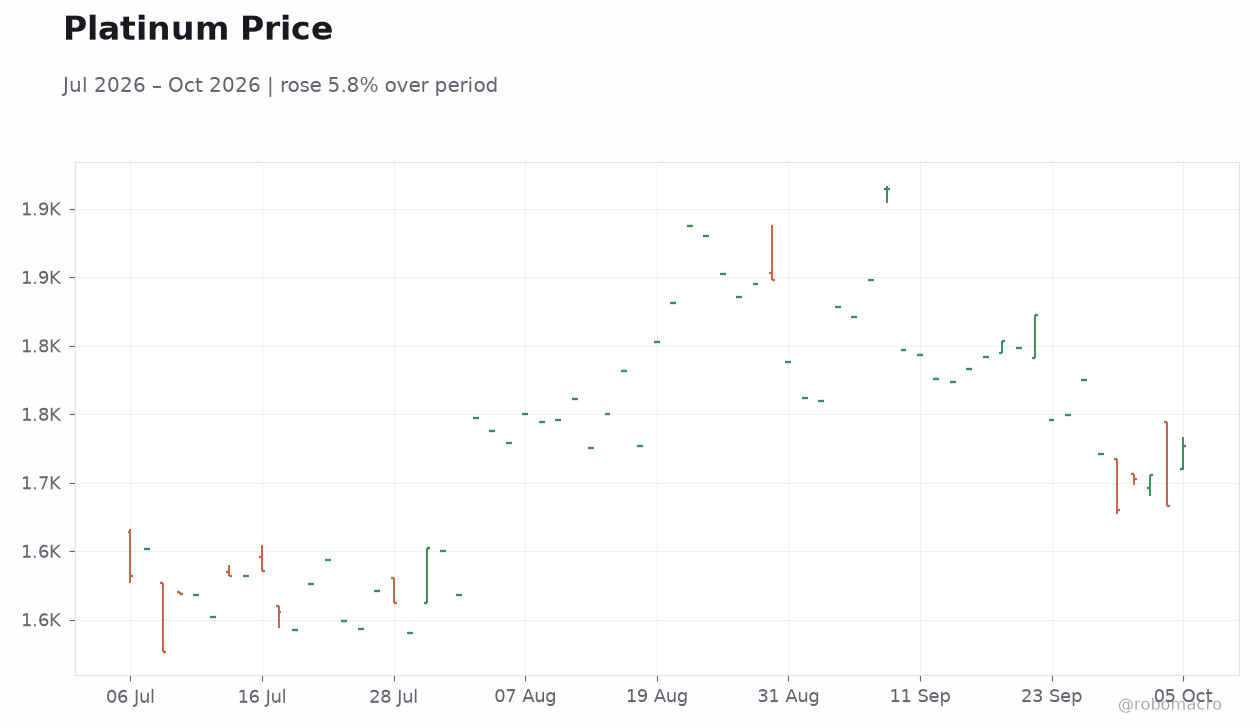
| Platinum | 1,726.10 | +2.55% |
| Gold | 4,171.20 | +0.21% |
| Brent Crude | 101.33 | -0.90% |
| Naspers | 69,551.00 | -0.68% |
| Bitcoin | 85,951.46 | +1.40% |
| South Africa 5Y Govt Yield | - | - |
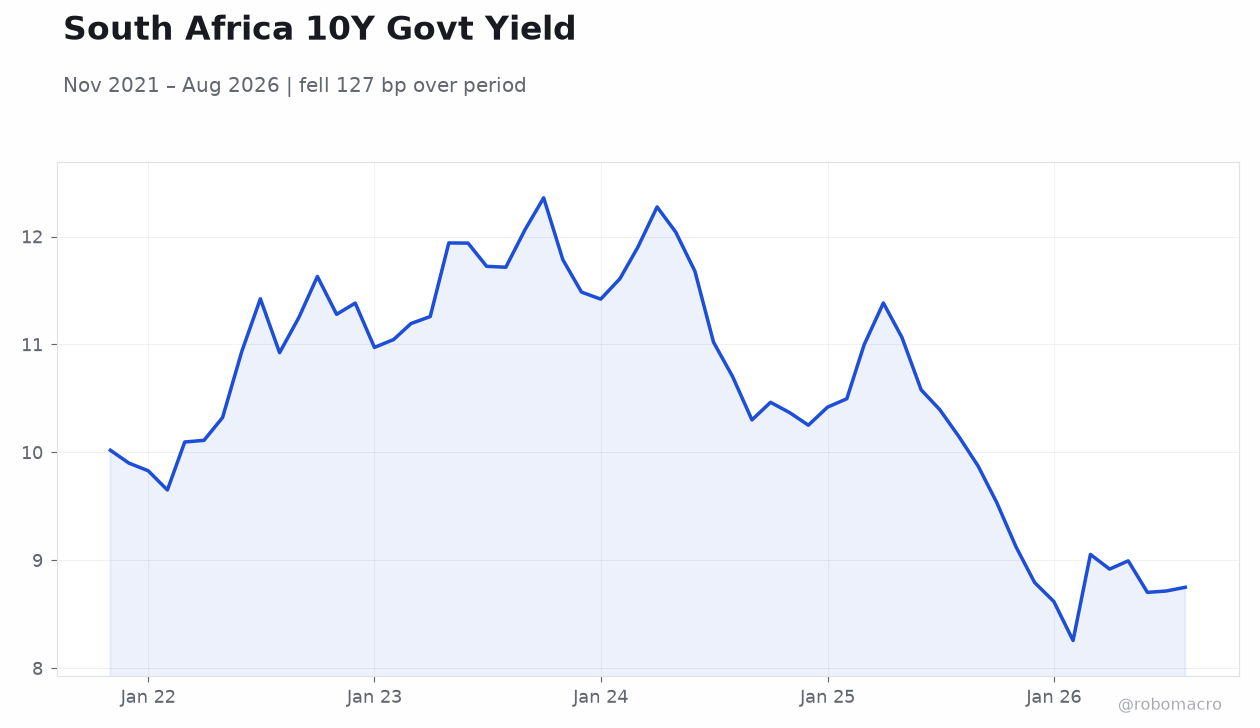
| South Africa 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
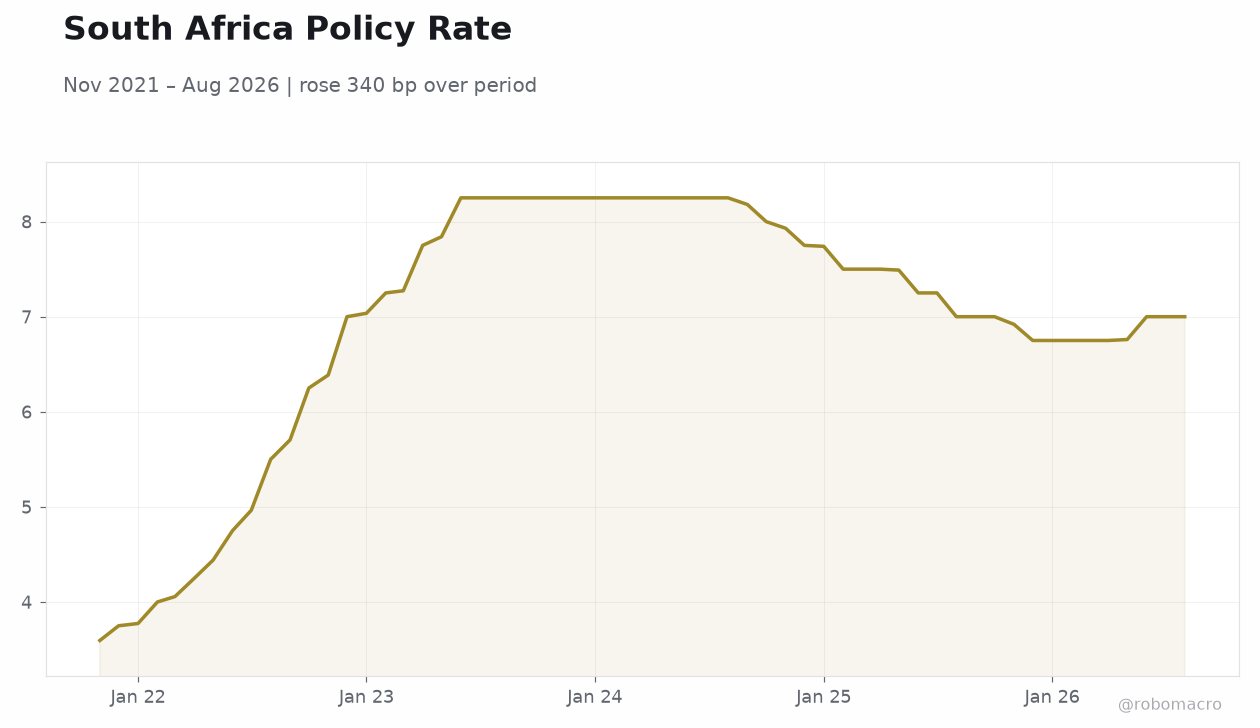 South Africa Policy Rate | Type: macro_line | Repo Rate %: 7 (2026-08-01) | Range: 3.595–8.25 | Trend(5pt): 3.595,7.036,8.25,7.49,7
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- JSE Top 40 rose 0.61% to 100,779.60 as platinum jumped 2.55%.
- USD/ZAR edged up 0.11% to 16.72 while EUR/ZAR gained 0.99%.
- No economic data released; SARB repo rate remains 7.25% and CPI YoY at 4.26%.
Yesterday's Recap
South African markets recorded no data prints on 4 October, leaving the economic calendar empty for the second consecutive session. The JSE Top 40 advanced 0.61% to close at 100,779.60, supported by a 2.55% surge in platinum to 1,726.10 and a 0.21% gain in gold to 4,171.20. Brent crude declined 0.90% to 101.33, while Naspers fell 0.68% to 69,551.00.
The rand posted modest losses, with USD/ZAR finishing at 16.72 and EUR/ZAR at 18.78. Bitcoin rose 1.40% to 85,951.46. Reports highlighted ongoing capital outflows and bilateral economic talks with Egypt, yet these developments produced no immediate shift in local asset prices.
Equity and commodity moves reflected external price drivers rather than domestic data surprises.
The Day Ahead
The calendar lists no scheduled releases or SARB communications for 5 October. Markets will therefore focus on external drivers, including any follow-through in platinum and gold prices. Rand trading is expected to remain sensitive to dollar strength and comments from the Federal Reserve.
Equity participants will monitor Naspers and mining counters for further direction. No MPC minutes or speeches are due, keeping policy expectations anchored to the current 7.25% repo rate. Investors may also track updates on the new Egypt-South Africa business council for longer-term trade implications.
Other Economic Notes
Capital outflows continued to feature in market commentary, weighing on sentiment despite the absence of fresh data. The upcoming 2027 Cricket World Cup is projected to deliver a R500 million boost to Cricket South Africa, offering a modest positive for related services and tourism sectors. Bilateral engagement with Egypt advanced through the new business council, with both presidents endorsing expanded trade and investment channels.
These developments occur against a backdrop of persistent social and governance challenges that have not yet altered near-term macroeconomic forecasts. No revisions to growth or inflation trajectories have emerged from the quiet data window.