South Africa Macro Daily(Beta Mode)
Rand Subdued, JSE Rallies on Metals
Market Snapshot
| Asset | Level | Change |
|---|---|---|
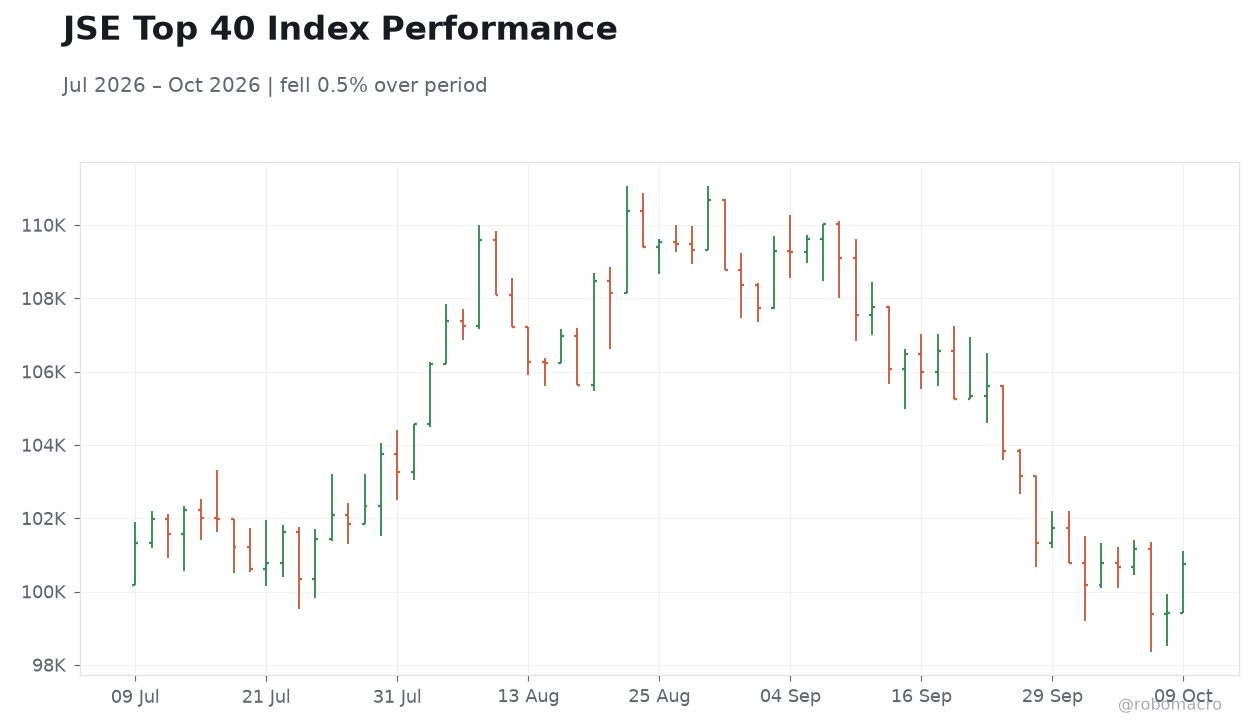
| JSE Top 40 | 100,764.30 | +1.37% |
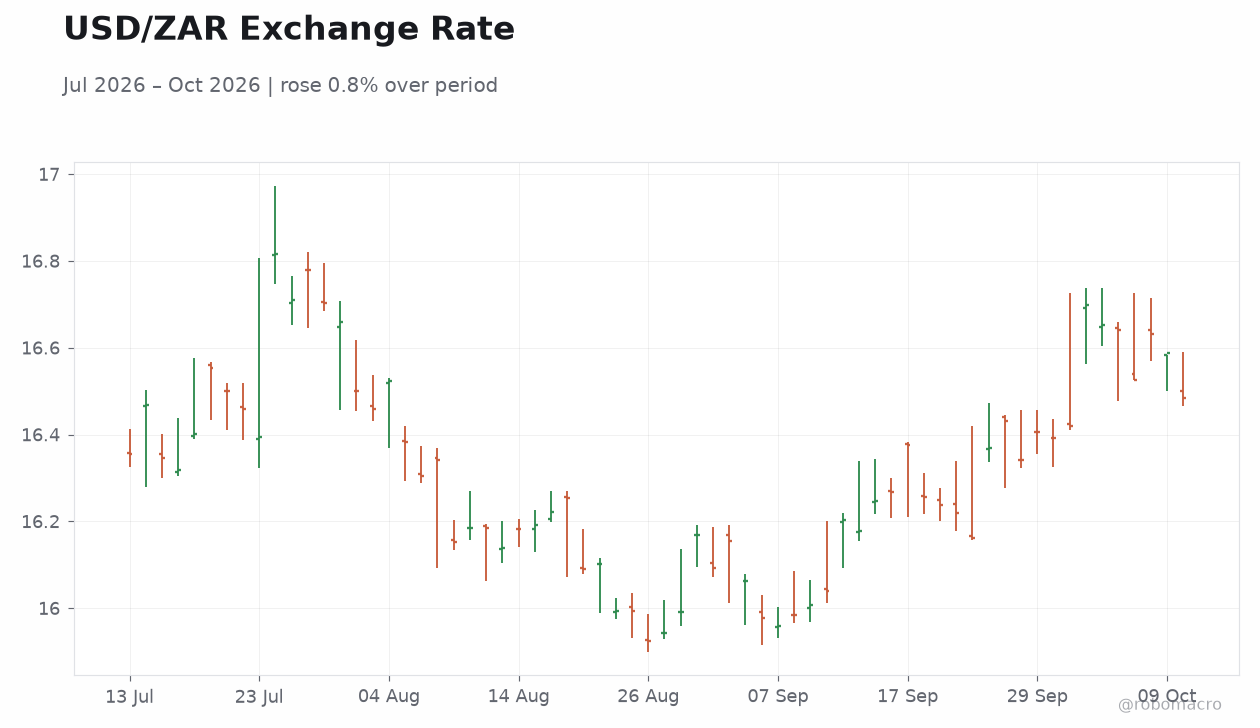
| USD/ZAR | 16.59 | -0.27% |
| EUR/ZAR | 18.48 | -0.66% |
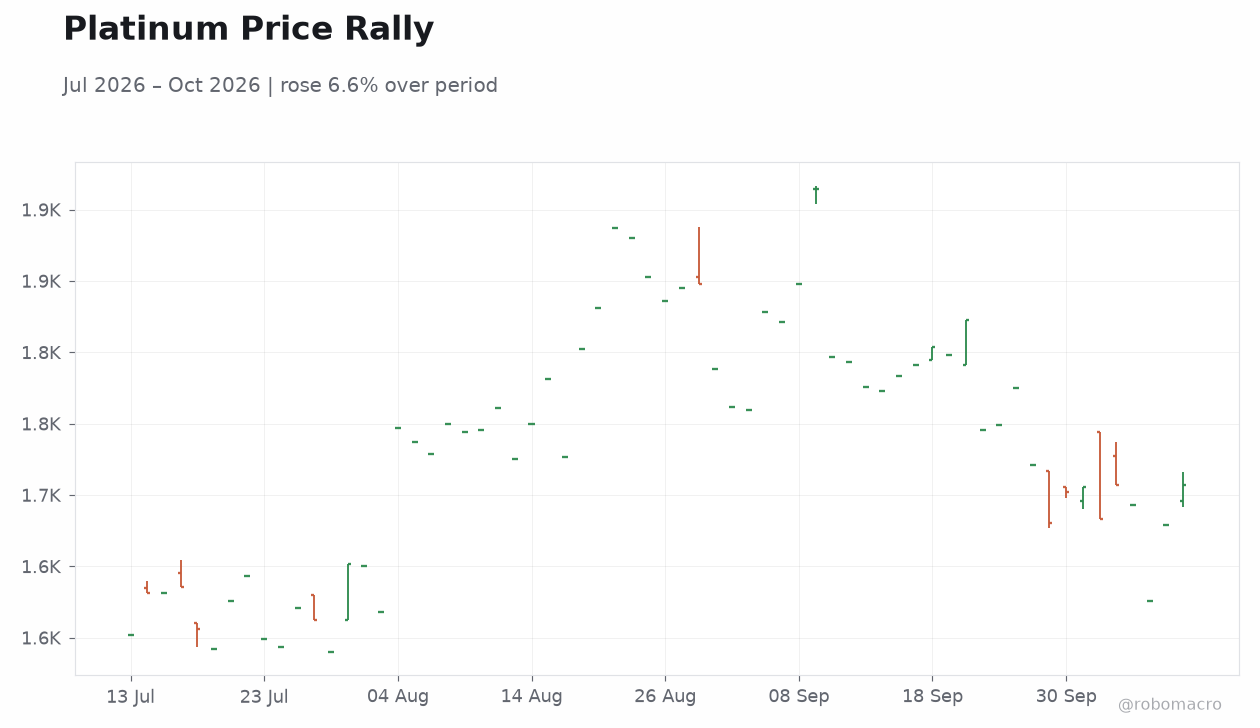
| Platinum | 1,707.80 | +1.70% |
| Gold | 4,226.90 | +0.25% |
| Brent Crude | 103.15 | -1.50% |
| Naspers | 72,169.00 | +2.84% |
| Bitcoin | 83,467.58 | +0.67% |
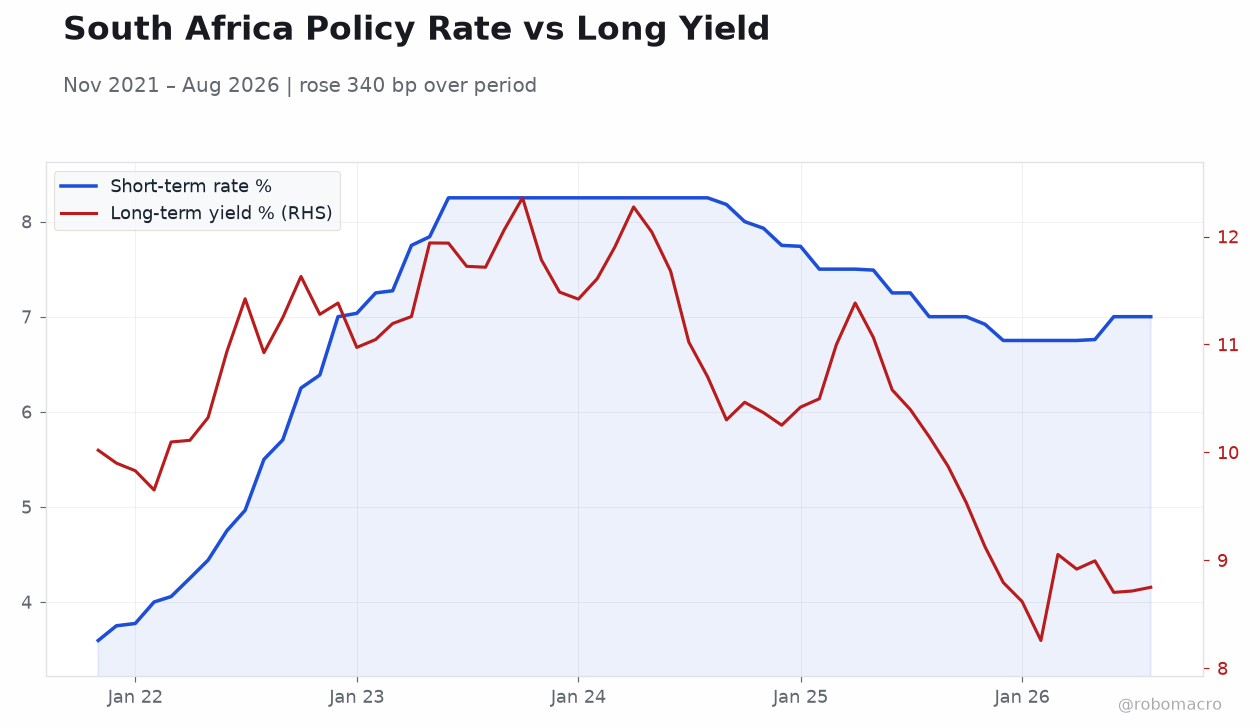
| South Africa 5Y Govt Yield | - | - |
| South Africa 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
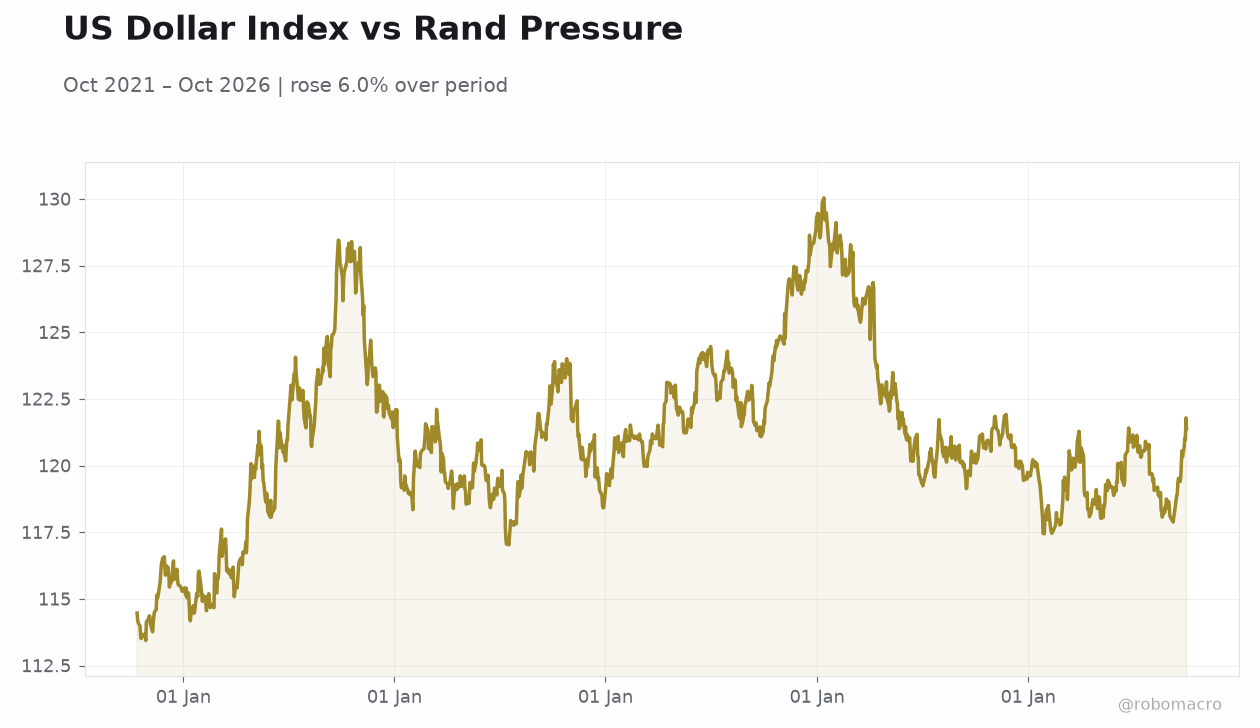 US Dollar Index vs Rand Pressure | Type: macro_line | Broad Dollar Index: 121.4 (2026-10-02) | Range: 113.4–130 | Trend(5pt): 114.5,119.4,121.6,119.7,121.4
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- JSE Top 40 gained 1.37% to 100,764.30, led by Naspers (+2.84%) and platinum (+1.70%)
- USD/ZAR eased 0.27% to 16.59; rand subdued on soft-dollar tone
- Anti-migrant unrest in Joburg and Durban risks rand, confidence
Yesterday's Recap
South African markets closed Friday on a constructive note, with the JSE Top 40 advancing 1.37% to 100,764.30. Naspers was the standout performer, surging 2.84% to 72,169.00 and providing significant index-level support. Precious metals underpinned the equity rally: platinum climbed 1.70% to 1,707.80 and gold added 0.25% to 4,226.90, lifting resource counters.
The rand, however, remained subdued, with USD/ZAR easing 0.27% to 16.59 and EUR/ZAR falling 0.66% to 18.48 — a modest appreciation analysts attribute to rangebound dollar dynamics rather than domestic catalysts. Brent crude declined 1.50% to $103.15, a tailwind for the fuel-import bill. On the data front, attention settled on the Q2 current account deficit of R205.5bn, which underscored persistent external imbalances.
Bitcoin firmed 0.67% to $83,467.58, reflecting resilient risk appetite in global crypto markets.
The Day Ahead
The calendar is light at the start of the week, with no tier-one South African data releases scheduled for Monday. Attention will instead focus on follow-through from the Constitutional Court ruling that eased migrant restrictions, a key trigger of last week's unrest in Soweto and Durban. Traders will monitor whether the government's withdrawal of asylum-processing orders restores calm, as renewed violence could pressure the rand and dampen consumer confidence.
Globally, the start of Q3 earnings season in the US will shape emerging-market sentiment, with rand-sensitive flows tracking the dollar. Locally, eyes remain on the Road Accident Fund debate after calls for reform before new revenue streams are considered. Bond desks will watch liquidity conditions at the weekly auction, while equity desks gauge whether the metals bid extends into a second session.
Other Economic Notes
The World Bank's warning that nearly 80% of sub-Saharan African countries now spend more on debt interest than on healthcare or education resonates in Pretoria, where debt-service costs consume a growing share of the budget. Refinery closures have added R76bn in additional costs to the economy, straining fuel supply and complicating the inflation outlook. The RAF's governance failures remain a fiscal sore point, with commentators urging leadership reform and credible oversight before taxpayers are asked for fresh levies.
↓ p.2