Rand Firms as Factories Falter on China Imports
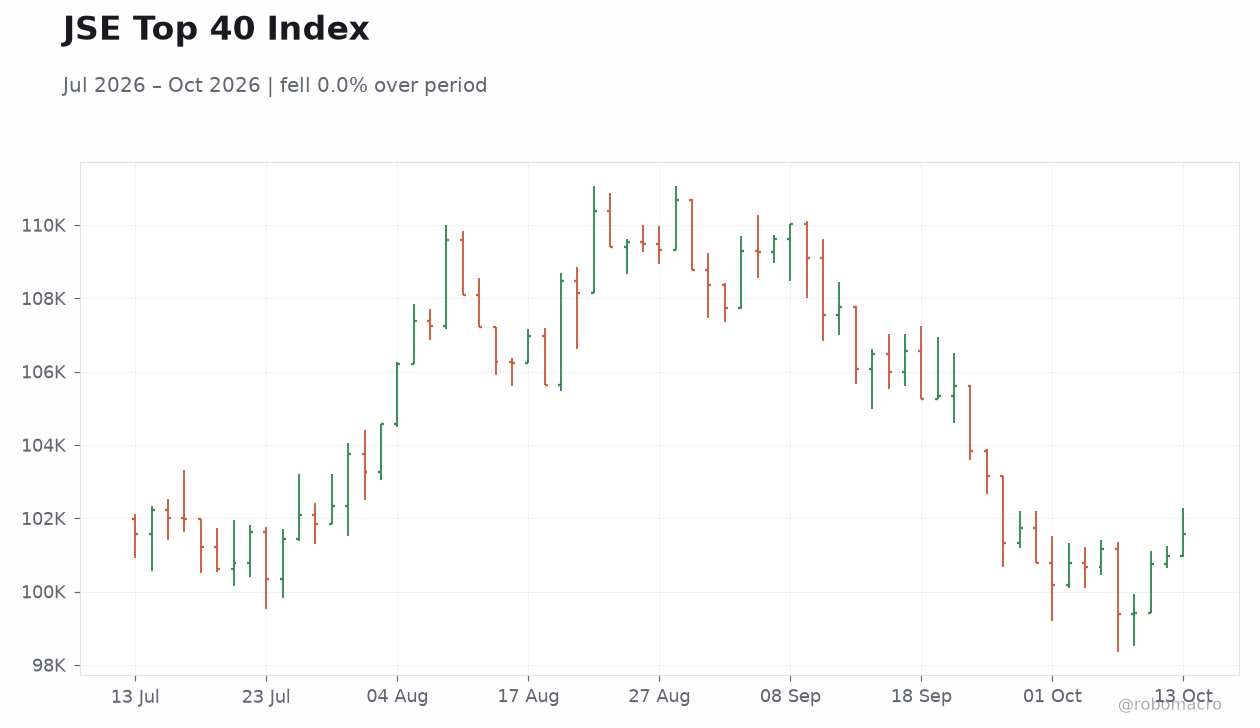
JSE Top 40101,562.40+0.59%
USD/ZAR16.54+0.25%
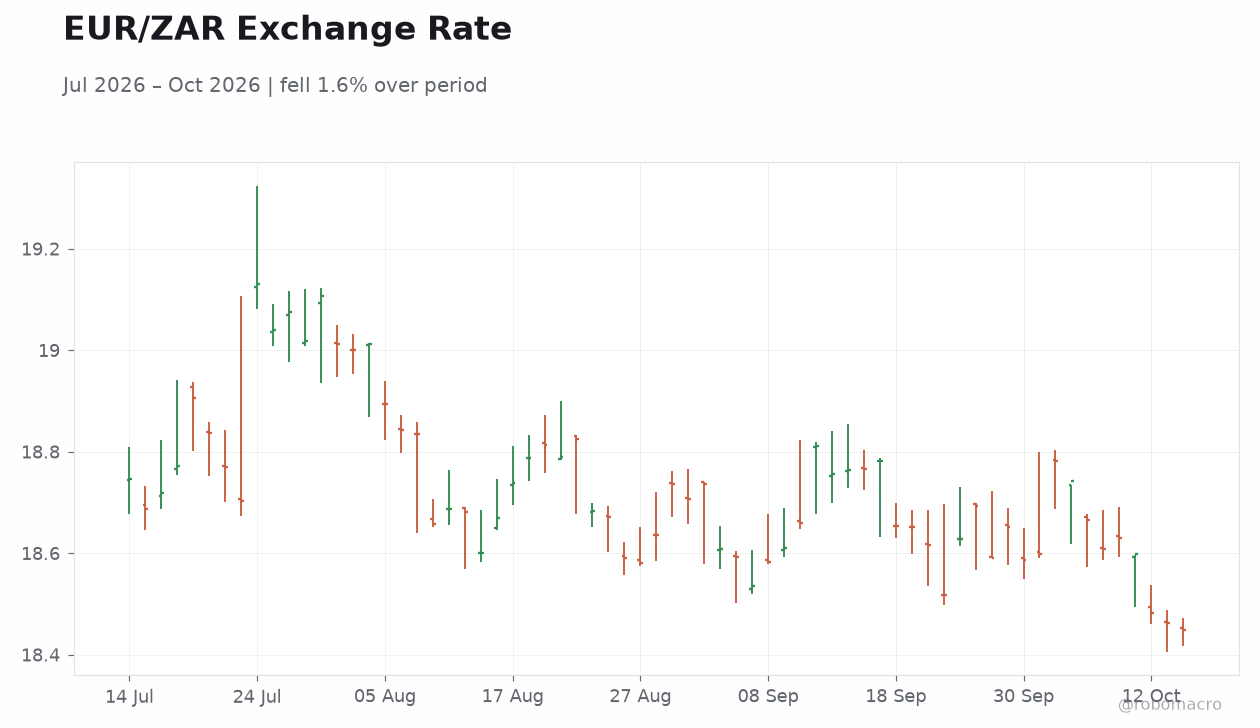
EUR/ZAR18.45-0.06%
Platinum1,657.40-1.31%
Market Snapshot
| Asset | Level | Change |
|---|
| JSE Top 40 | 101,562.40 | +0.59% |
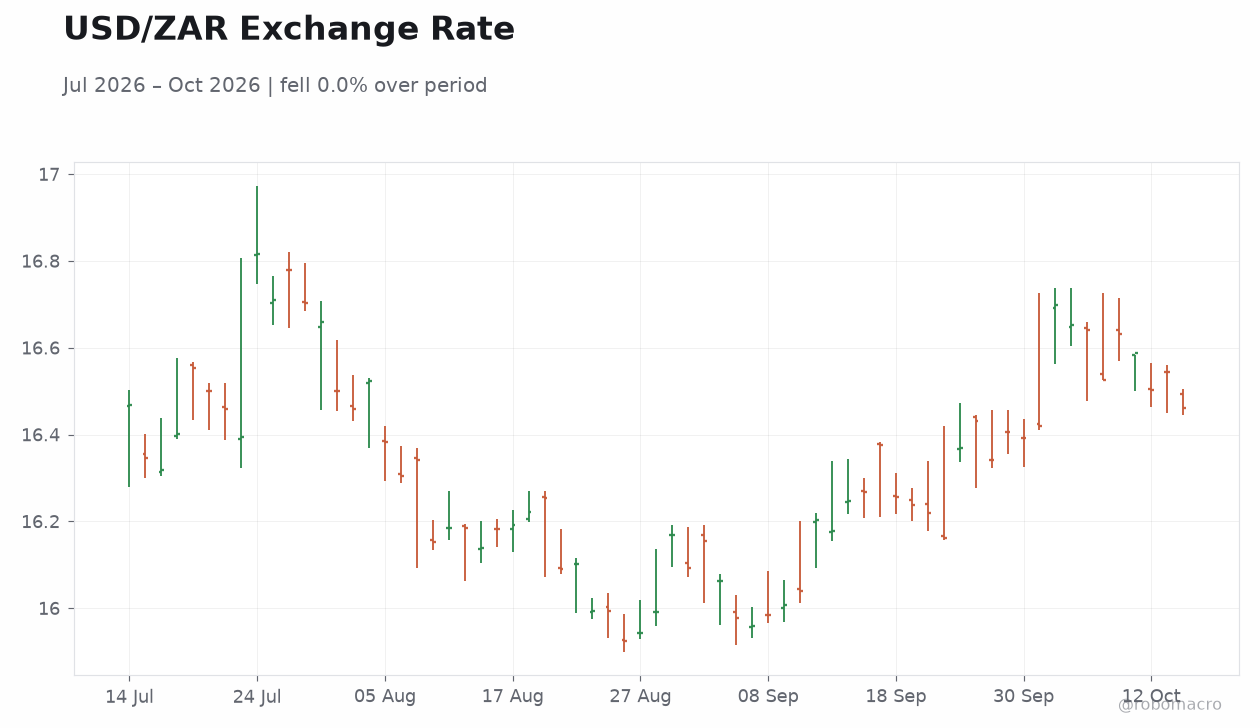
| USD/ZAR | 16.54 | +0.25% |
| EUR/ZAR | 18.45 | -0.06% |
| Platinum | 1,657.40 | -1.31% |
| Gold | 4,184.90 | +0.18% |
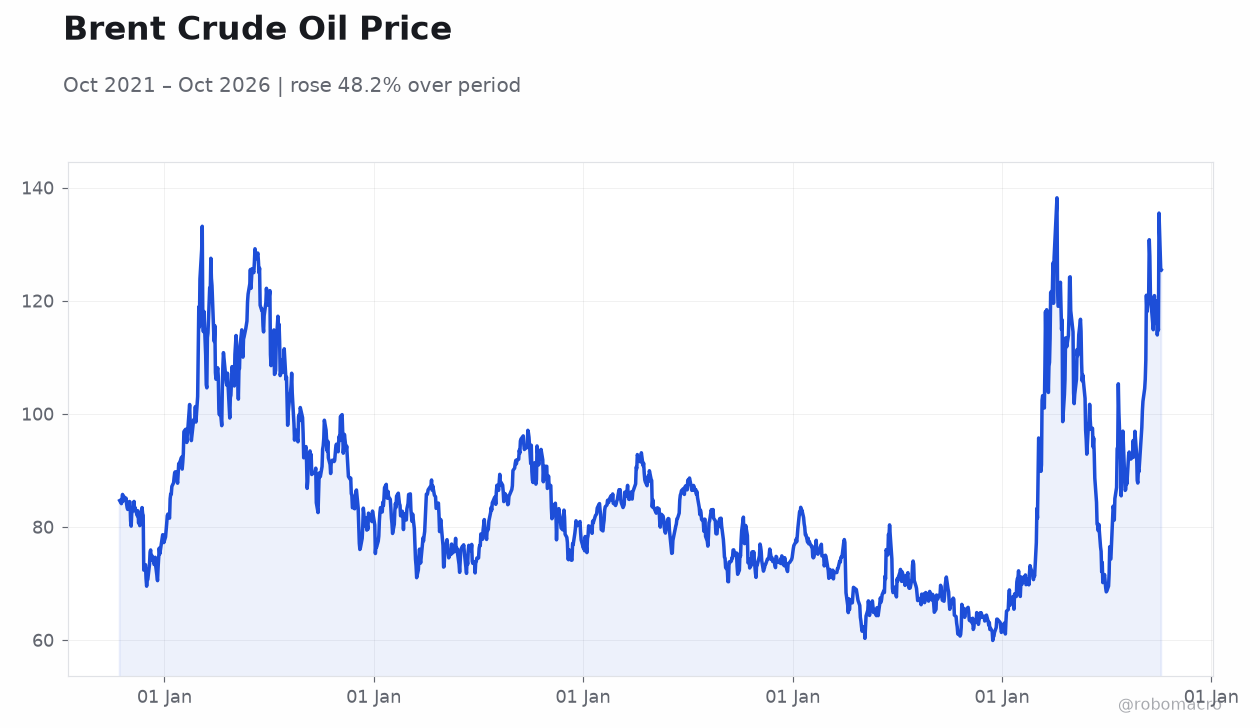
| Brent Crude | 106.31 | +0.59% |
| Naspers | 70,994.00 | -1.63% |
| Bitcoin | 83,660.66 | +2.32% |
| South Africa 5Y Govt Yield | - | - |
| South Africa 10Y Govt Yield | - | - |
Prior Economic Events
| Data |
Prior |
Cons |
Actual |
| No events available |
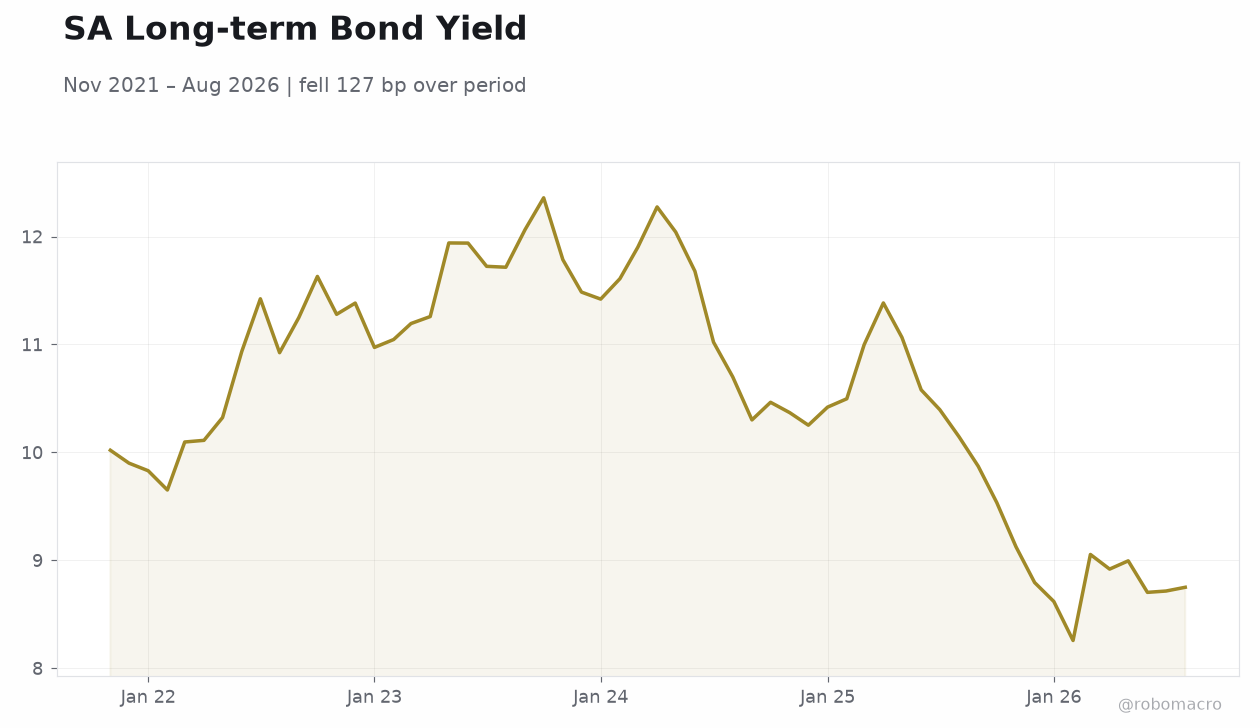 SA Long-term Bond Yield | Type: macro_line | 10Y Yield %: 8.75 (2026-08-01) | Range: 8.257–12.36 | Trend(6pt): 10.02,10.97,11.9,11.07,8.715,8.75
Today's Economic Events
| Data |
Prior |
Cons |
Time |
| No events available |
- JSE Top 40 gains 0.59% to 101,562.40; rand firms vs euro, weakens vs dollar
- Bloomberg flags SA manufacturing cratering under Chinese import pressure
- Repo at 7.25%, CPI at 4.26% keeps SARB in extended-hold mode
Yesterday's Recap
South African markets closed Monday with a constructive tone, the JSE Top 40 adding 0.59% to 101,562.40, led by broad-based buying that offset a 1.63% decline in Naspers to 70,994.00. The currency market told a two-sided story: the rand firmed against the euro, with EUR/ZAR easing 0.06% to 18.45, while USD/ZAR rose 0.25% to 16.54 as the dollar found support. Precious metals diverged sharply, with gold edging up 0.18% to 4,184.90 while platinum slid 1.31% to 1,657.40, a reminder of the demand headwinds facing South Africa's platinum belt.
Brent crude climbed 0.59% to 106.31, keeping imported fuel inflation on the SARB's radar. The dominant macro narrative came from Bloomberg's report that South African factories are cratering as Chinese imports stunt the recovery, underscoring structural pressure on manufacturing. Political developments added noise, with suspended deputy police chief Shadrack Sibiya resigning amid a corruption probe, and Pretoria confirming 364 arrests after renewed xenophobic violence that has pushed over 1,000 Nigerians to return home.
Bitcoin's 2.32% rise to 83,660.66 kept risk appetite broadly intact across emerging markets.
The Day Ahead
Attention turns to the IMF's World Economic Outlook release from Bangkok, which Africanews flags will carry a sobering message on the deepening African debt crisis, a read-across for South Africa's fiscal trajectory and bond sentiment. Traders will watch whether the rand's firming trend against the euro extends, particularly if hawkish ECB commentary from Governing Council member Pierre Wunsch lifts euro-area yield expectations and reshapes the ZAR carry calculus. The manufacturing story deserves follow-through: after Bloomberg's cratering-factories report, any industrial production or PMI-related commentary will be scrutinized for confirmation of the Chinese-import squeeze.
Platinum's 1.31% slide warrants monitoring for further downside in the metals complex that dominates export receipts. Energy supply dynamics remain a background variable for the growth outlook, with load-shedding risks still capable of denting sentiment. With no major domestic data prints scheduled, the session likely trades on global cues and positioning flows.
Page 1
Never miss an issue
Subscribe to South Africa Macro Daily and get each new issue delivered to your inbox.
Already a member? Visit robomacro.com
to log in and manage subscriptions, or use Forgot Password to set a password.