South Africa Macro Daily(Beta Mode)
Budget Anchors Bonds, Fuel Levies Cut
Market Snapshot
| Asset | Level | Change |
|---|---|---|
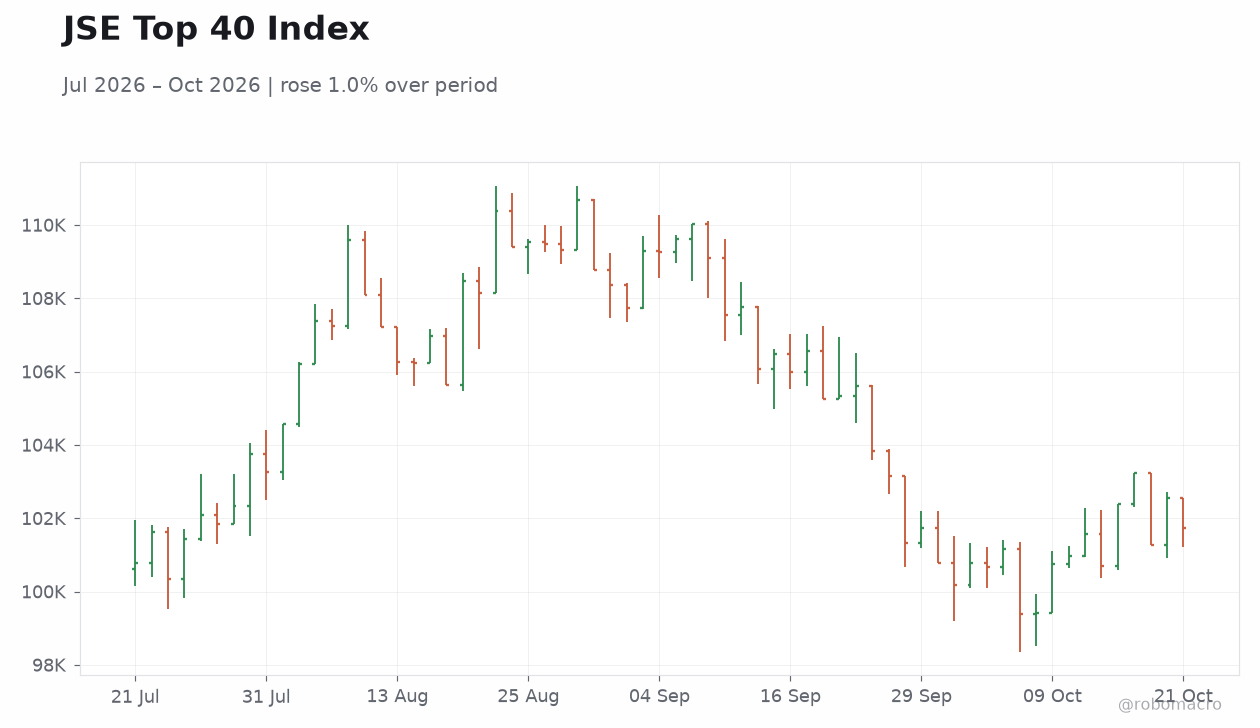
| JSE Top 40 | 101,739.30 | -0.79% |
| USD/ZAR | 16.40 | +0.07% |
| EUR/ZAR | 18.42 | +0.15% |
| Platinum | 1,625.50 | -1.28% |
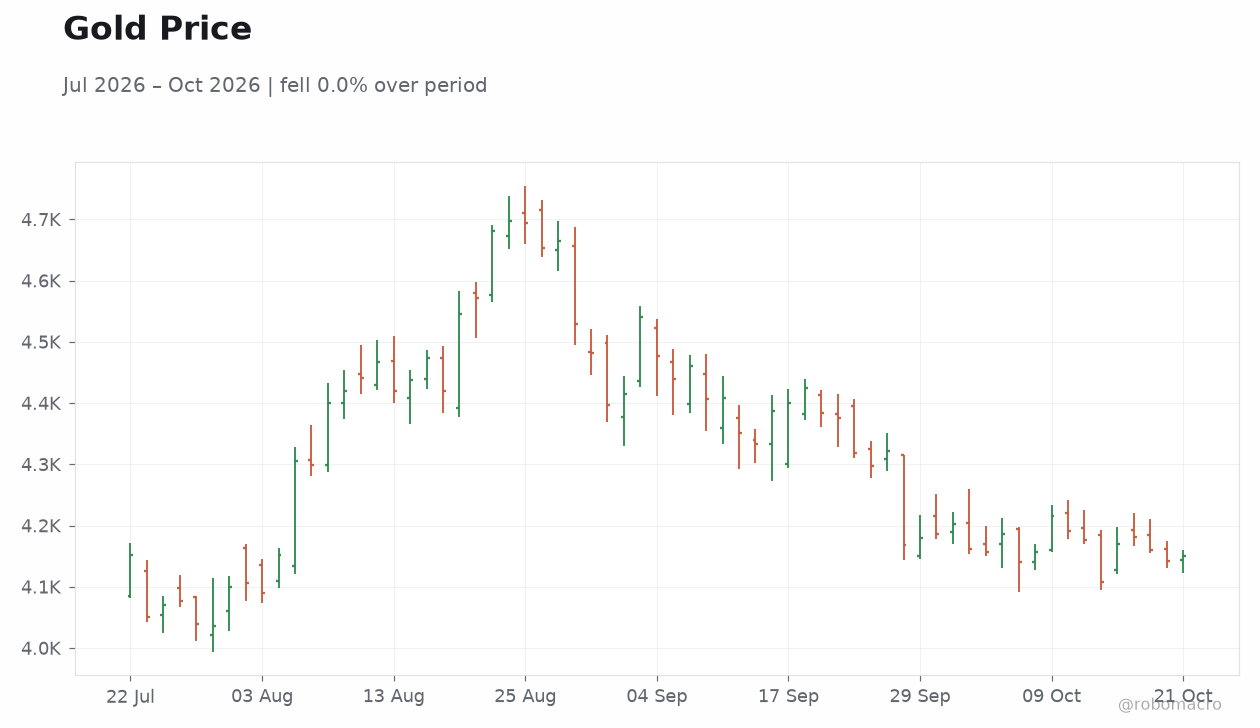
| Gold | 4,150.00 | +0.18% |
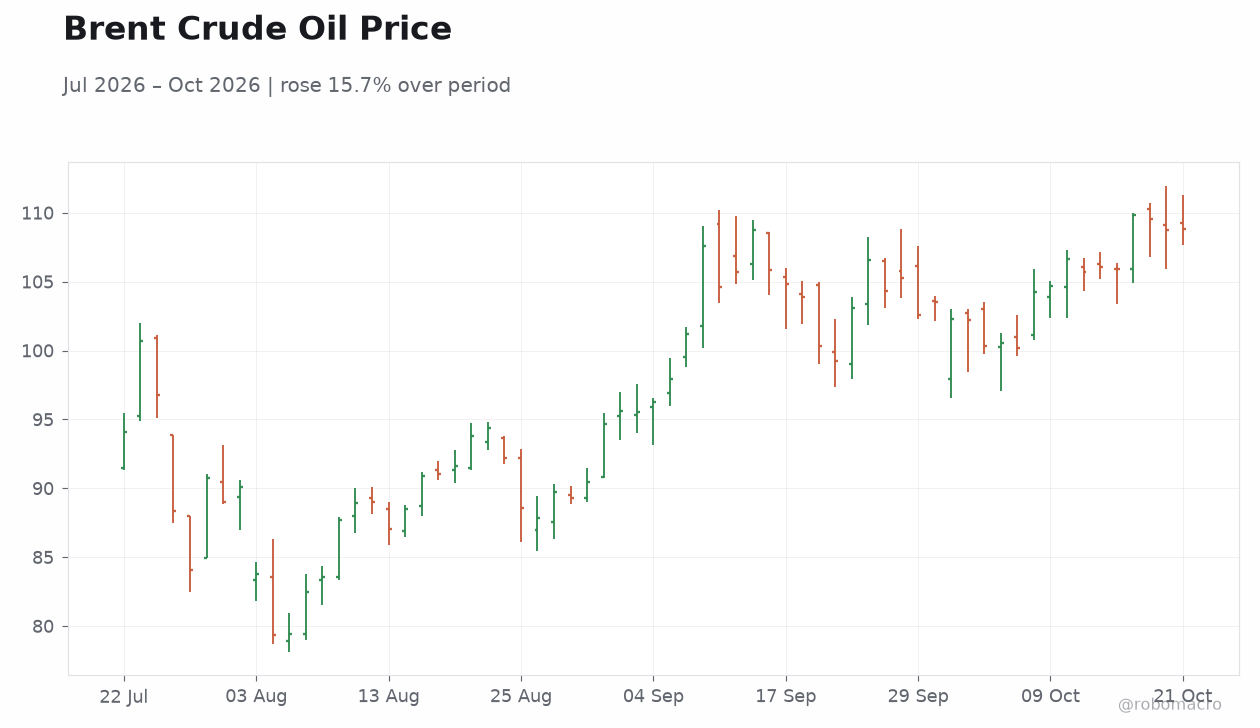
| Brent Crude | 108.82 | +0.03% |
| Naspers | 68,226.00 | -3.50% |
| Bitcoin | 82,870.05 | -0.09% |
| South Africa 5Y Govt Yield | - | - |
| South Africa 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
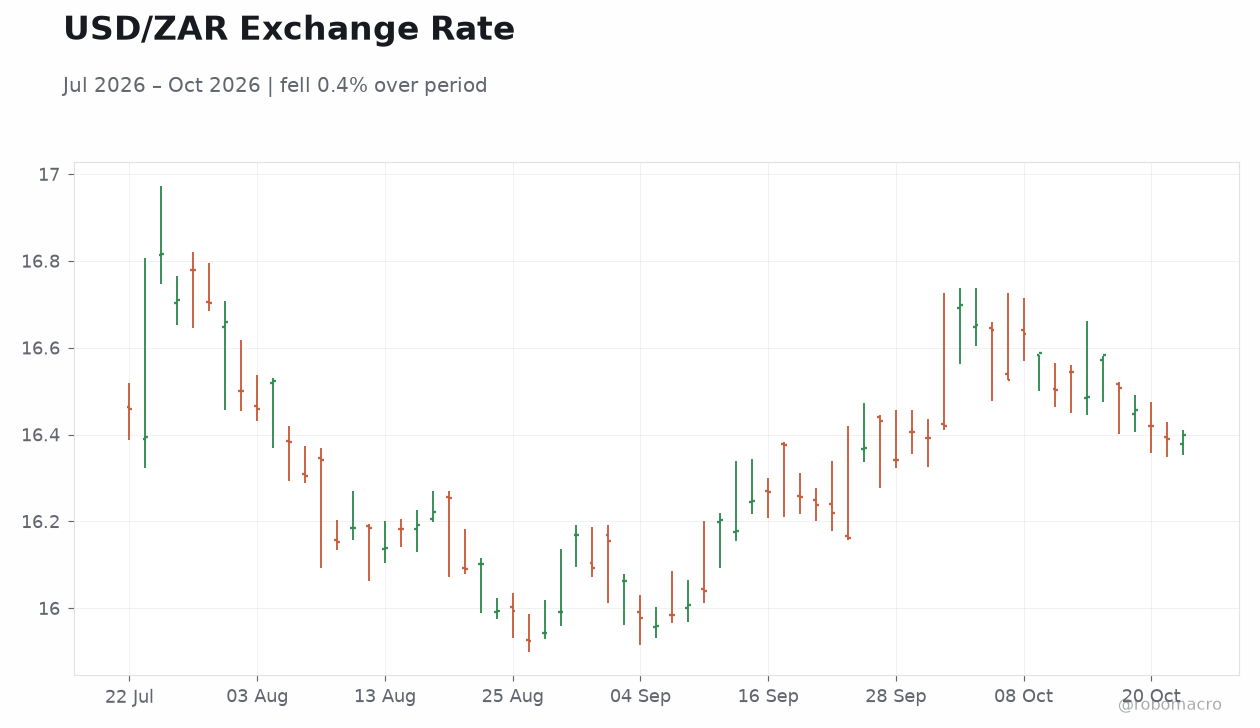 USD/ZAR Exchange Rate | Type: market_hloc | USD/ZAR: 16.4 (2026-10-22) | Range: 15.92–16.82 | Trend(6pt): 16.46,16.14,15.98,16.34,16.42,16.4
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Finance Minister Godongwana unveiled a fiscal anchor and cut weekly bond issuance in the 2026 MTBPS, triggering a bond rally even as the borrowing requirement rose by R54.2bn to fund a domestic buyback.
- Government announced R10bn in temporary fuel levy relief for two months from November as pump prices squeeze consumers.
- JSE Top 40 fell 0.79% with Naspers down 3.50%; the rand held near R16.40/$ as UBS and Daily Investor both flag fair value around R16.00.
Yesterday's Recap
The medium-term budget policy statement dominated Wednesday's session, with Godongwana introducing new fiscal sustainability rules and trimming weekly bond issuance — a combination Bloomberg characterised as "bond-friendly." The Treasury simultaneously lifted the gross borrowing requirement by R54.2bn ($3.3bn) in the current fiscal year, primarily to finance a domestic bond buyback, a nuance markets appeared to absorb constructively. Equities did not share the enthusiasm: the JSE Top 40 closed 0.79% lower at 101,739.30, dragged by Naspers' 3.50% slide to R68,226. The rand was marginally softer, USD/ZAR at 16.40 (+0.07%) and EUR/ZAR at 18.42 (+0.15%).
Commodity cues were mixed — platinum fell 1.28% to $1,625.50 while gold edged up 0.18% to $4,150.00 and Brent held at $108.82. No scheduled South African data releases printed yesterday, leaving the budget as the sole domestic catalyst.
The Day Ahead
Thursday's domestic calendar is empty, so attention shifts to the second-order effects of the MTBPS. Traders will watch whether the bond rally extends into the weekly auction and whether the R54.2bn borrowing uplift begins to pressure the long end once the initial relief fades. The fuel levy announcement — R10bn over two months from November — will be parsed for its fiscal cost and its modest disinflationary pass-through into the November and December CPI prints.
Currency desks will test the R16.00 handle that both UBS and Daily Investor cite as fair value. Abroad, German stagnation commentary from the Bundesbank and ongoing US trade tensions affecting agricultural exports remain relevant for SA's external account.
Other Economic Notes
The fuel levy cut is a targeted, time-limited intervention rather than a structural fix, and its R10bn cost must be squared with an already-elevated borrowing path. The bond buyback is a liquidity-management tool that can support secondary market functioning, but it does not reduce the stock of debt — investors should distinguish the issuance cut from the headline borrowing increase. South African cherries gaining China market access is a small but symbolically useful diversification away from US-exposed agricultural trade.
↓ p.2