South Africa Macro Daily(Beta Mode)
Rand Firms as US Trade Exclusion Weighs
Market Snapshot
| Asset | Level | Change |
|---|---|---|
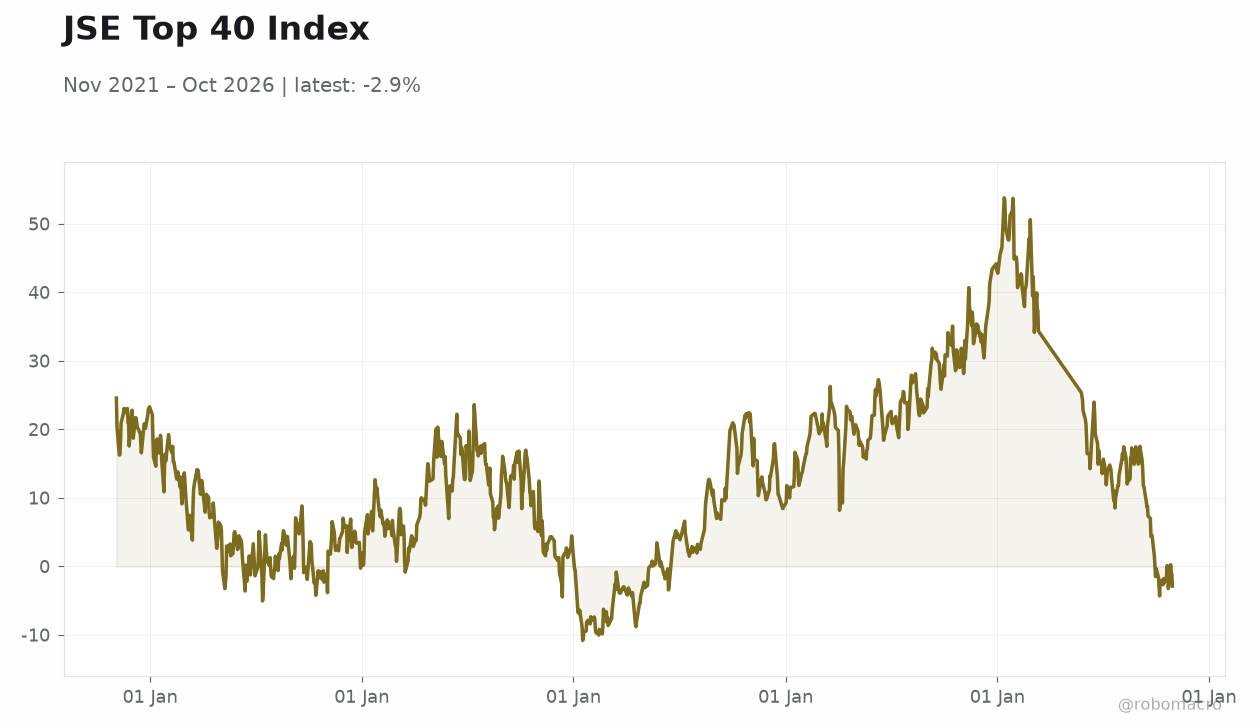
| JSE Top 40 | 101,438.70 | +2.04% |
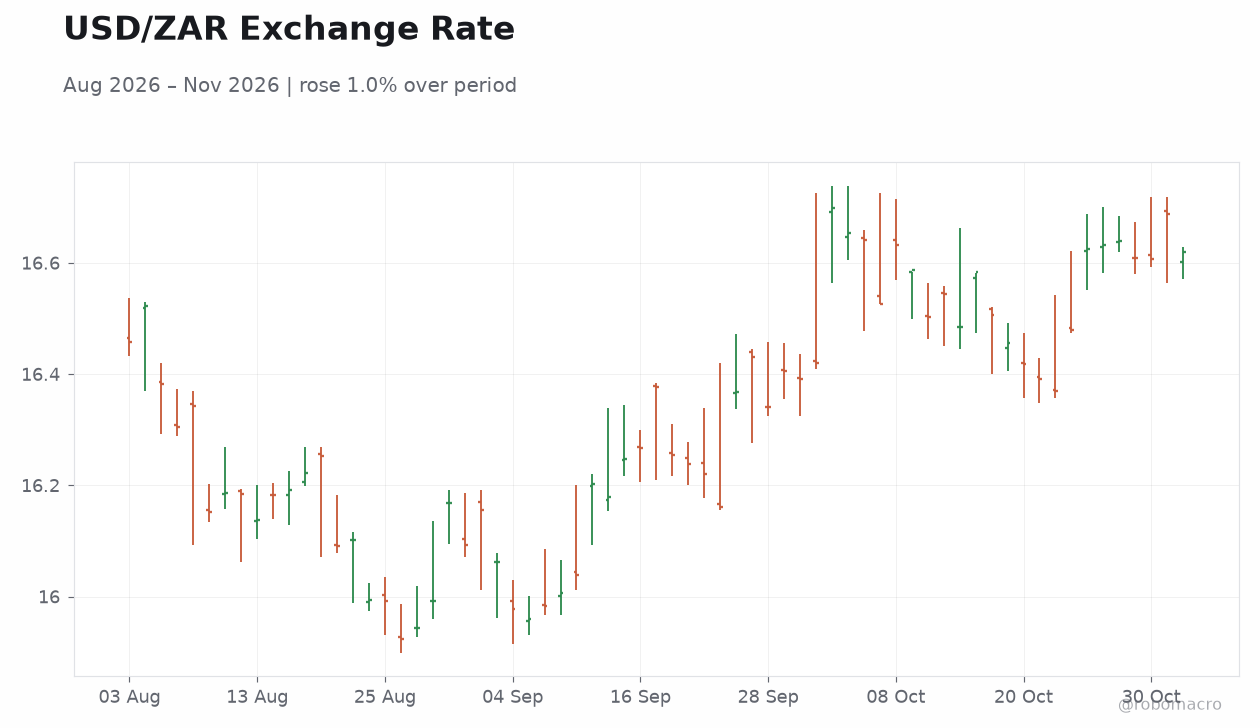
| USD/ZAR | 16.61 | -0.44% |
| EUR/ZAR | 18.59 | -0.17% |
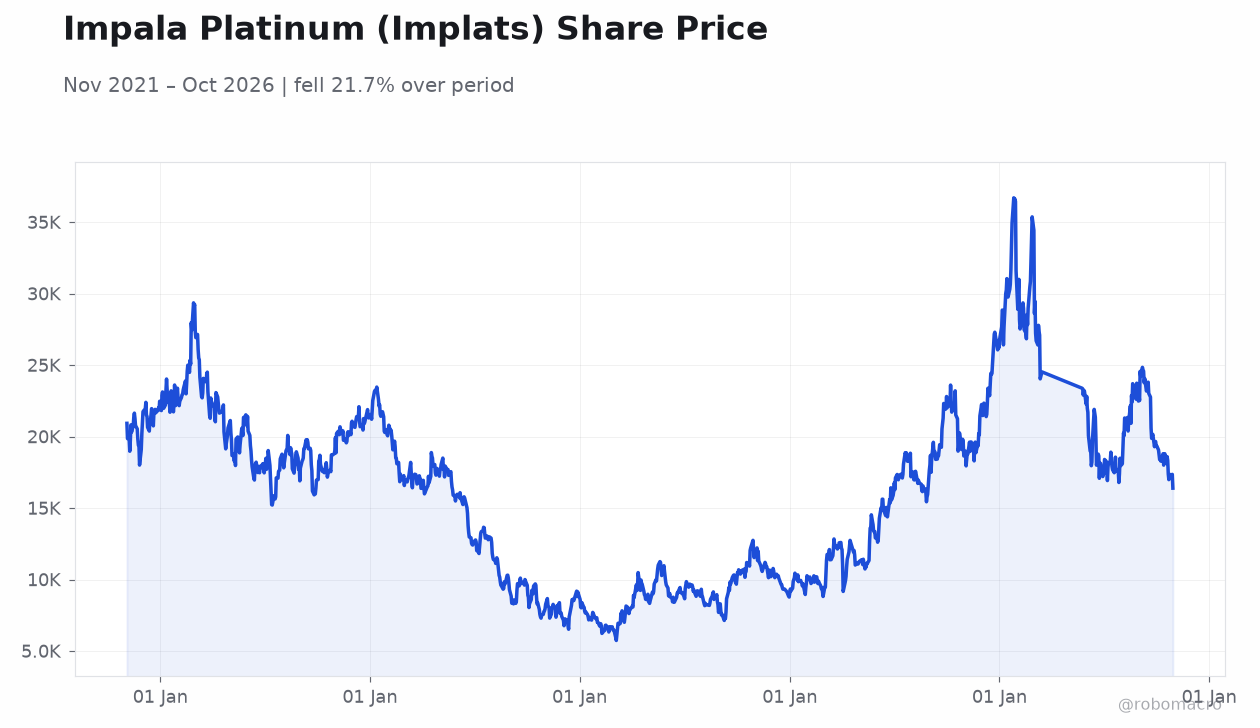
| Platinum | 1,438.40 | +0.03% |
| Gold | 3,934.30 | +0.91% |
| Brent Crude | 104.82 | -10.90% |
| Naspers | 67,860.00 | -1.61% |
| Bitcoin | 76,949.29 | -1.66% |
| South Africa 5Y Govt Yield | 8.54% | 0 bp |
| South Africa 10Y Govt Yield | 8.74% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
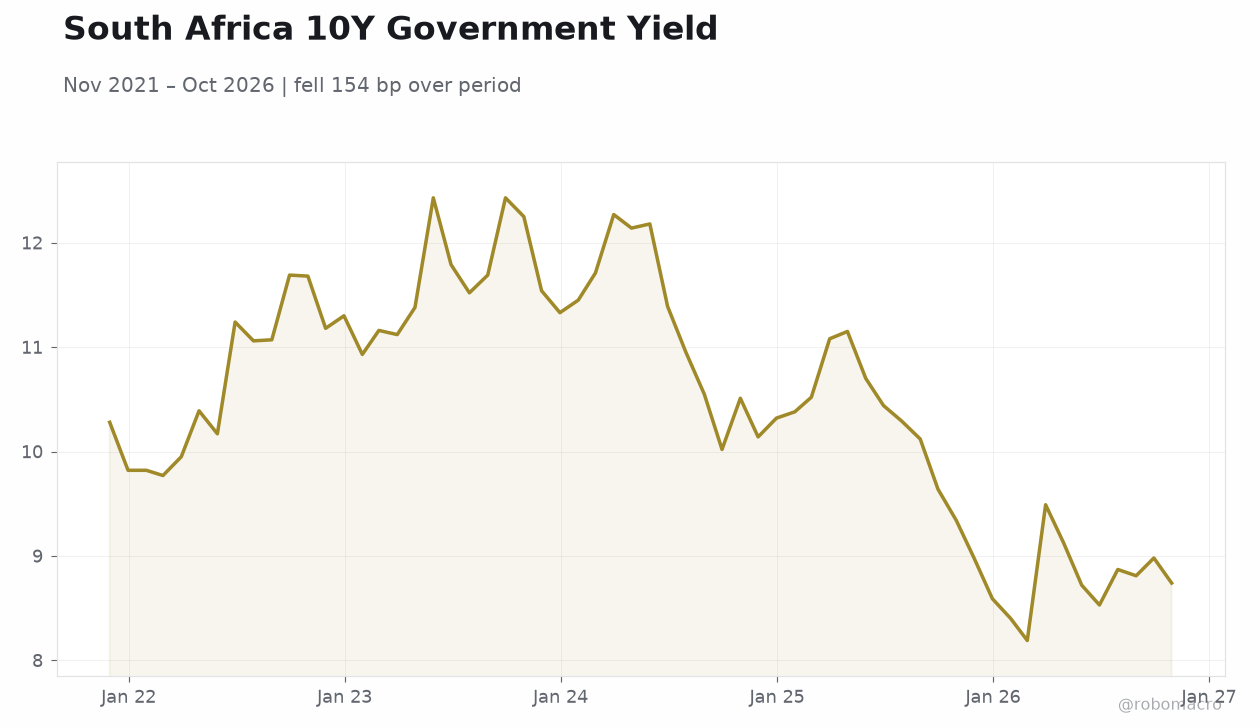 South Africa 10Y Government Yield | Type: macro_line | 10Y Yield (%): 8.74 (2026-10-30) | Range: 8.19–12.43 | Trend(5pt): 10.28,11.16,12.18,10.12,8.74
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- USD/ZAR eased 0.44% to 16.61 as the rand firmed slightly despite Washington excluding South Africa from a major Africa-US duty-free trade deal.
- JSE Top 40 surged 2.04% to 101,438.70 on broad risk appetite, even as Naspers slipped 1.61%.
- SARB remains confident current policy can return inflation to 4.55%, with the repo rate held at 7.25% ahead of the 19 November MPC.
Yesterday's Recap
South African markets opened the week with a constructive tone, with the JSE Top 40 climbing 2.04% to 101,438.70 on broad-based buying. The rand firmed 0.44% against the dollar to 16.61, shrugging off news that the US Trade Representative would exclude South Africa and Rwanda from a major Africa-US duty-free trade arrangement, citing practices inconsistent with the deal's terms. Gold advanced 0.91% to $3,934.30/oz, lending support to the precious-metals complex, while platinum was essentially flat at $1,438.40.
Brent crude collapsed 10.90% to $104.82/bbl, a sharp move that eases imported fuel-cost pressure and is rand-supportive at the margin. Naspers bucked the equity rally, falling 1.61% to R67,860, while Bitcoin slipped 1.66%. On the rates side, the 10-year government yield eased 1 bp to 8.74% and the 5-year held at 8.54%, leaving the curve broadly stable.
No scheduled domestic data releases printed on the day, so price action was driven by offshore risk sentiment and trade-headline flow.
The Day Ahead
The domestic calendar is empty for Tuesday, leaving the rand and JSE to trade off global risk appetite and US midterm-related positioning. With no local prints to digest, focus shifts to offshore catalysts — US midterm election developments, US jobs data later in the week, and Iran-related headlines — all of which FX desks have flagged as near-term drivers for USD/ZAR. Bond traders will watch whether the 10-year yield holds below 8.75% after Monday's modest easing.
Mining names remain sensitive to the gold price holding near $3,934/oz and to the sharp Brent selloff, which cuts fuel costs across the sector. Expect thin, headline-driven liquidity ahead of the 19 November SARB decision.
Other Economic Notes
The US decision to exclude South Africa from the Africa duty-free trade arrangement is a meaningful trade-policy risk, potentially affecting agricultural and manufactured exports into the US market and complicating AGOA-adjacent access. Domestic politics are in focus with local elections next week, where service delivery, crime and unemployment dominate voter concerns. ↓ p.2