South Africa Macro Daily(Beta Mode)
Rand Slides as Unemployment Hits 33.7%
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| JSE Top 40 | 104,981.30 | -0.55% |
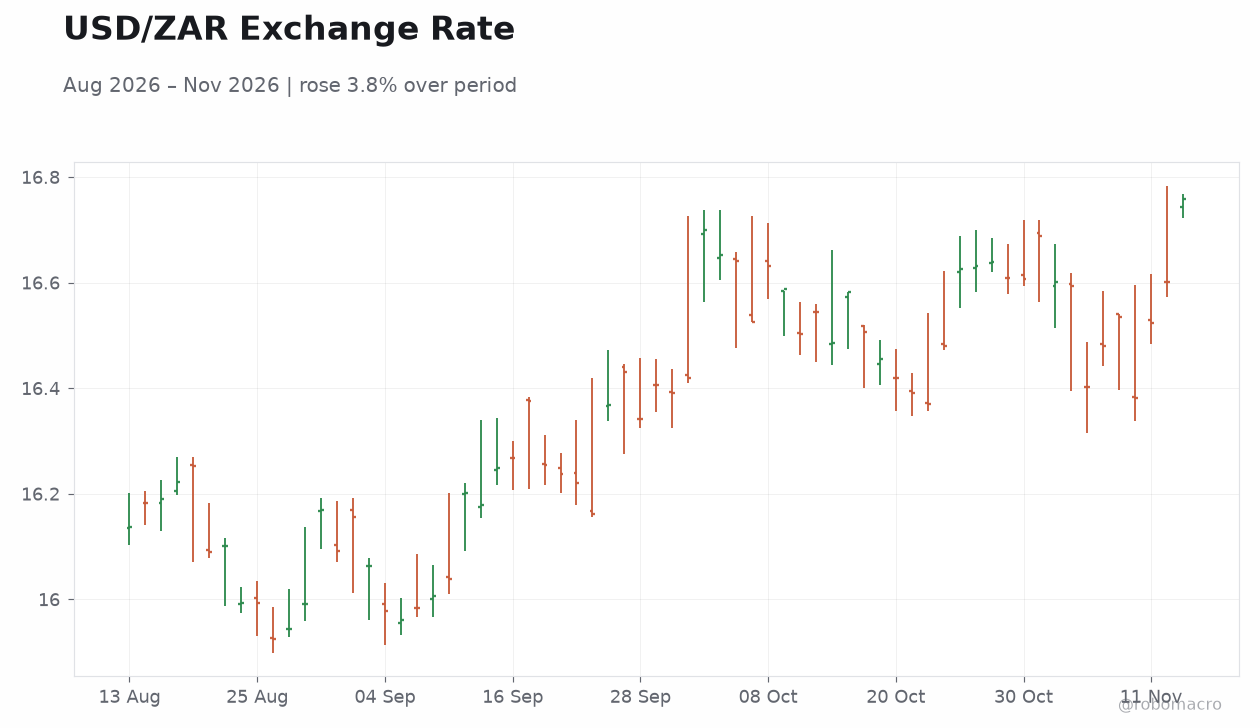
| USD/ZAR | 16.76 | +0.95% |
| EUR/ZAR | 18.53 | +0.62% |
| Platinum | 1,533.50 | -0.36% |
| Gold | 3,917.60 | -2.07% |
| Brent Crude | 95.67 | +3.14% |
| Naspers | 73,580.00 | -2.48% |
| Bitcoin | 68,714.85 | -7.10% |
| South Africa 5Y Govt Yield | 8.38% | +12 bp |
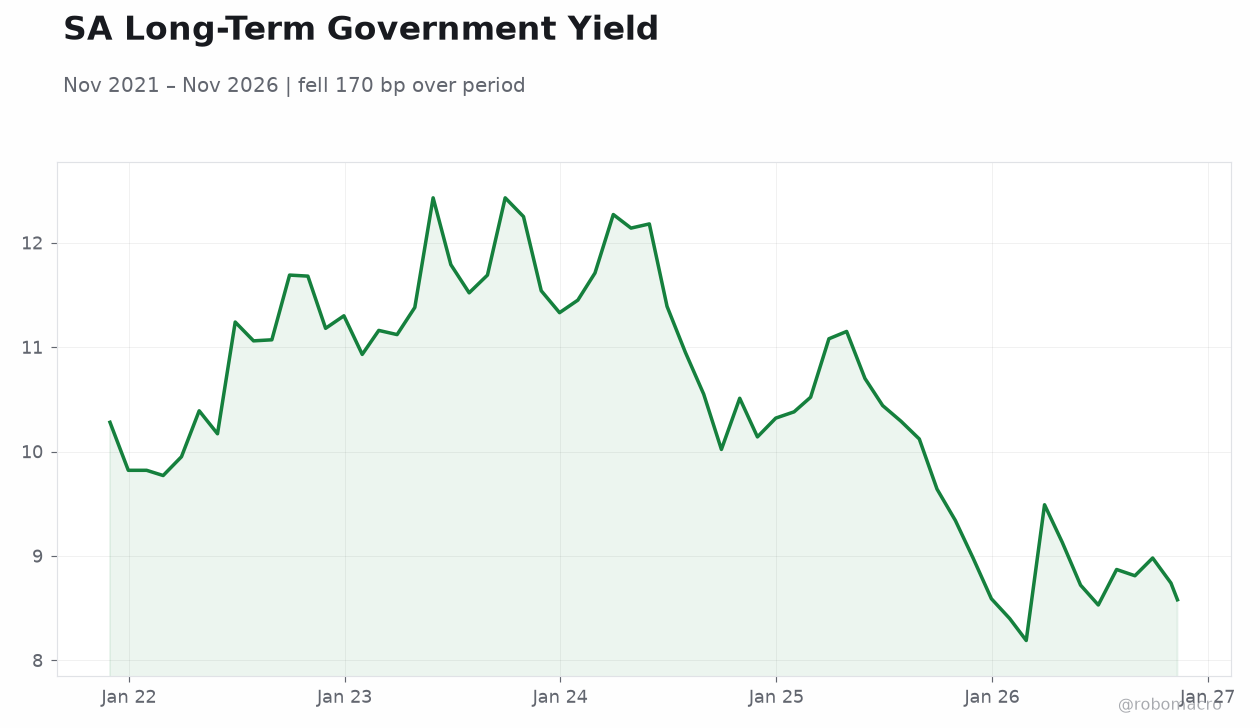
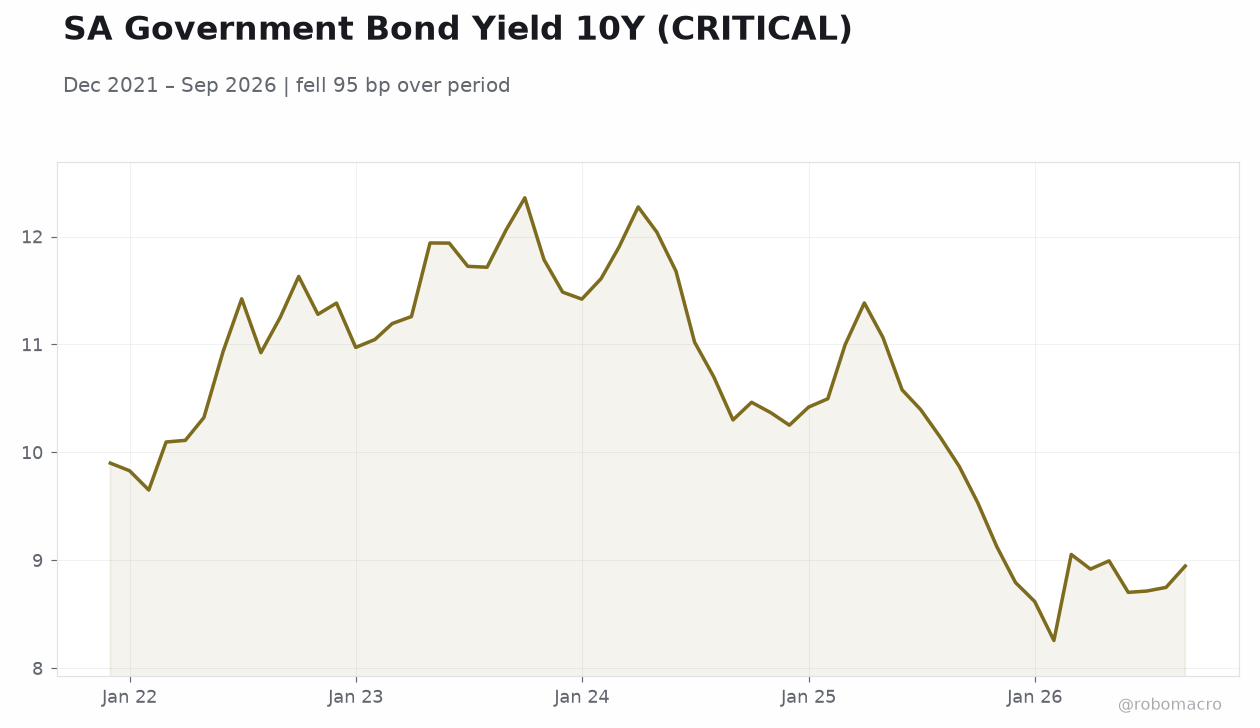
| South Africa 10Y Govt Yield | 8.58% | +11 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Headline Unemployment Rate | 33.60 | - | 33.70 |
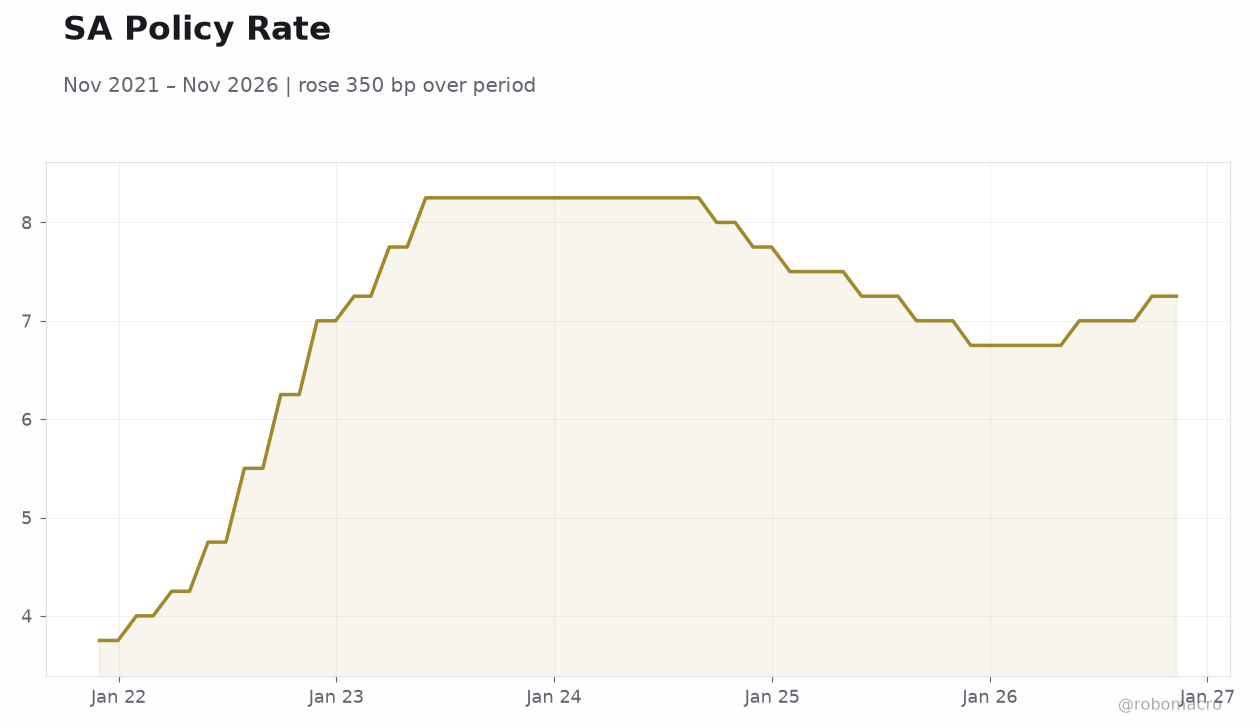 SA Policy Rate | Type: macro_line | Policy Rate (%): 7.25 (2026-11-10) | Range: 3.75–8.25 | Trend(5pt): 3.75,7.25,8.25,7,7.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- USD/ZAR jumped 0.95% to 16.76 after unemployment rose to 33.7%, underscoring persistent labour-market weakness despite job additions.
- JSE Top 40 fell 0.55% to 104,981.30, with Naspers down 2.48% and gold miners pressured as bullion dropped 2.07%.
- South Africa 10Y and 5Y yields rose 11bp and 12bp respectively, steepening the curve as fiscal and inflation risks stay elevated ahead of the SARB's 19 November MPC.
Yesterday's Recap
South Africa's headline unemployment rate printed at 33.7% for the latest reference period, marginally above the prior 33.6% reading, confirming that job creation continues to lag population growth. The rand bore the brunt of the disappointment, with USD/ZAR climbing 0.95% to 16.76 and EUR/ZAR up 0.62% to 18.53. Domestic equities tracked global risk-off sentiment lower, with the JSE Top 40 shedding 0.55% to 104,981.30 and Naspers down 2.48% as the tech-linked proxy tracked weakness in global growth names.
Precious metals offered no shelter: gold fell 2.07% to $3,917.60/oz and platinum eased 0.36% to $1,533.50/oz, weighing on the mining complex. Bonds sold off, with the 10-year yield rising 11bp to 8.58% and the 5-year up 12bp to 8.38%, reflecting both the labour-market disappointment and a hawkish global rates backdrop. Brent crude surged 3.14% to $95.67/bbl, a fresh import-cost headwind for a net oil importer.
The Day Ahead
The domestic data calendar is empty for 13 November, leaving markets to trade off global risk sentiment and positioning ahead of next week's SARB decision. Attention will centre on the 19 November MPC, where the committee must weigh inflation near 4.55% against a still-fragile growth and labour backdrop. With no local prints to anchor the rand, USD/ZAR will likely take its cue from US yields and dollar momentum.
Bond traders will watch whether the 10-year holds below 8.60% or extends the recent sell-off. Mining equities remain hostage to gold and platinum price swings. Liquidity may thin as desks position for the weekend.
Other Economic Notes
The 33.7% unemployment print reinforces the structural mismatch between skills supply and demand, keeping household consumption and credit extension subdued. South Africa's fiscal trajectory remains a key vulnerability, with elevated debt-service costs crowding out productive spending and keeping the bond curve steep. Energy supply reliability remains a swing factor for mining and manufacturing output, and any renewed load-shedding would hit already-weak GDP momentum.
↓ p.2