South Africa Macro Daily(Beta Mode)
Rand Slides Pre-CPI, SARB Decision Looms
Market Snapshot
| Asset | Level | Change |
|---|---|---|
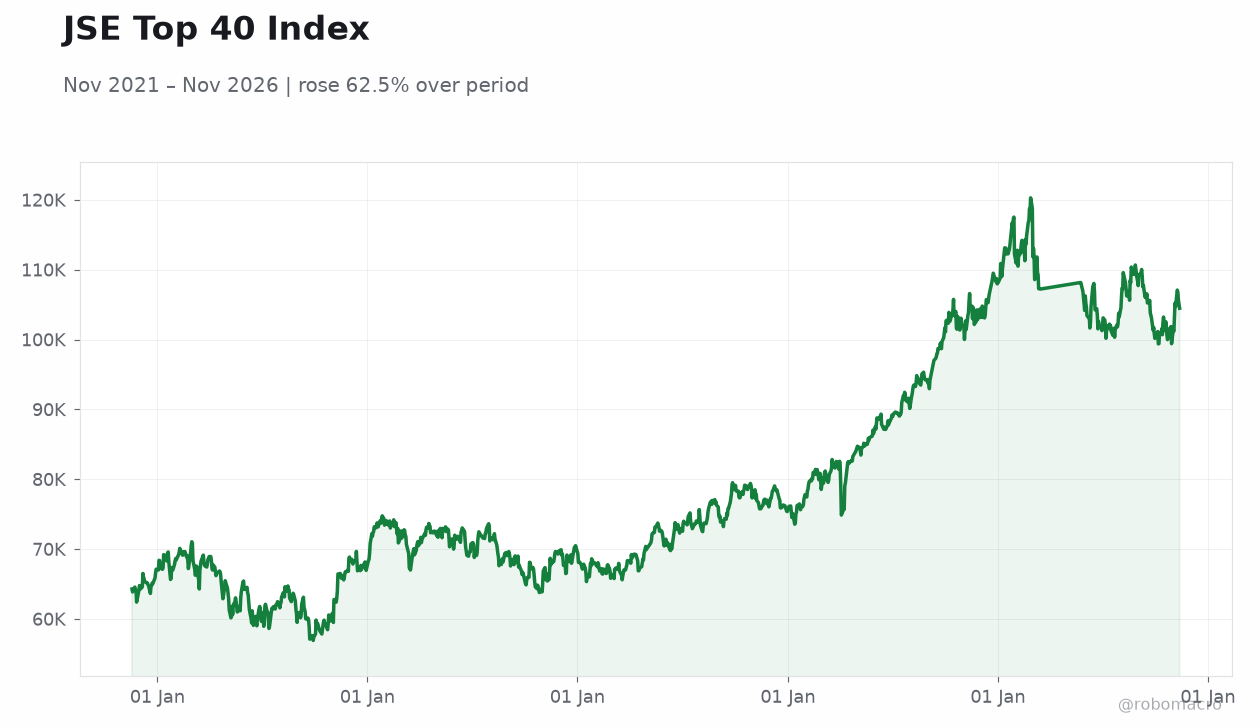
| JSE Top 40 | 103,629.00 | -0.82% |
| USD/ZAR | 16.96 | +0.19% |
| EUR/ZAR | 18.67 | +0.11% |
| Platinum | 1,470.00 | -1.24% |
| Gold | 3,872.10 | -0.37% |
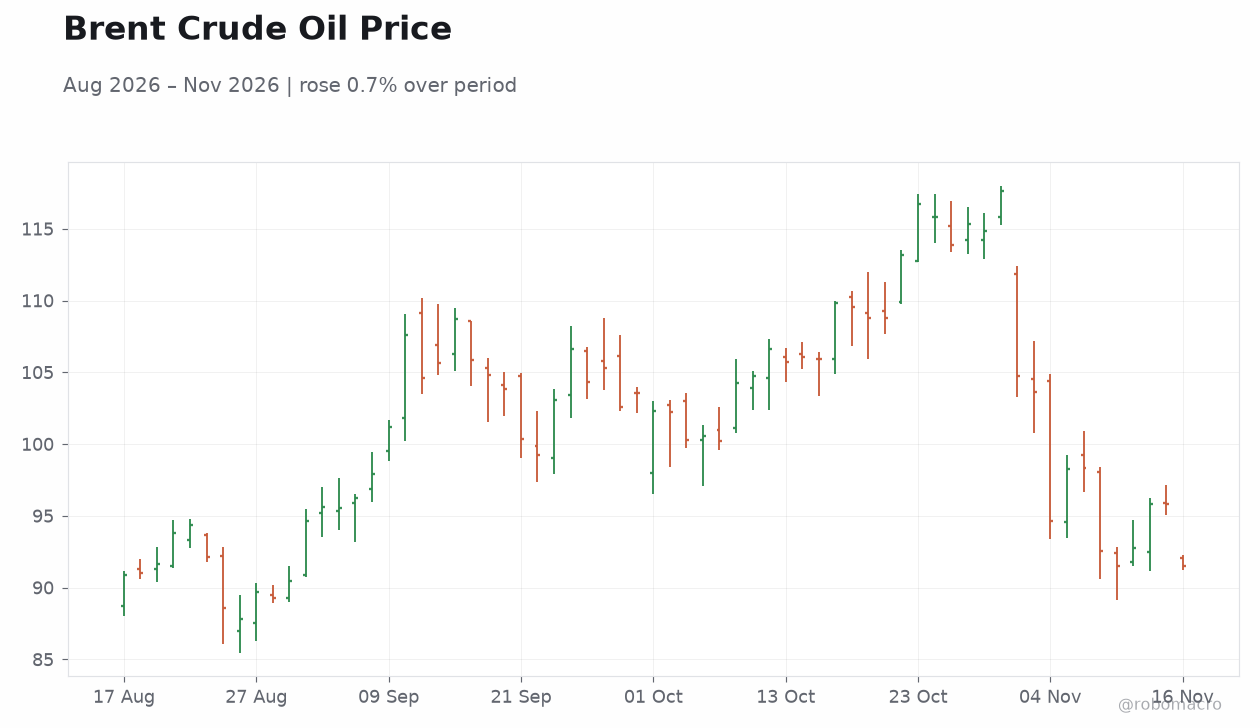
| Brent Crude | 91.63 | -4.39% |
| Naspers | 72,537.00 | -1.42% |
| Bitcoin | 64,884.75 | -0.64% |
| South Africa 5Y Govt Yield | 8.53% | +32 bp |
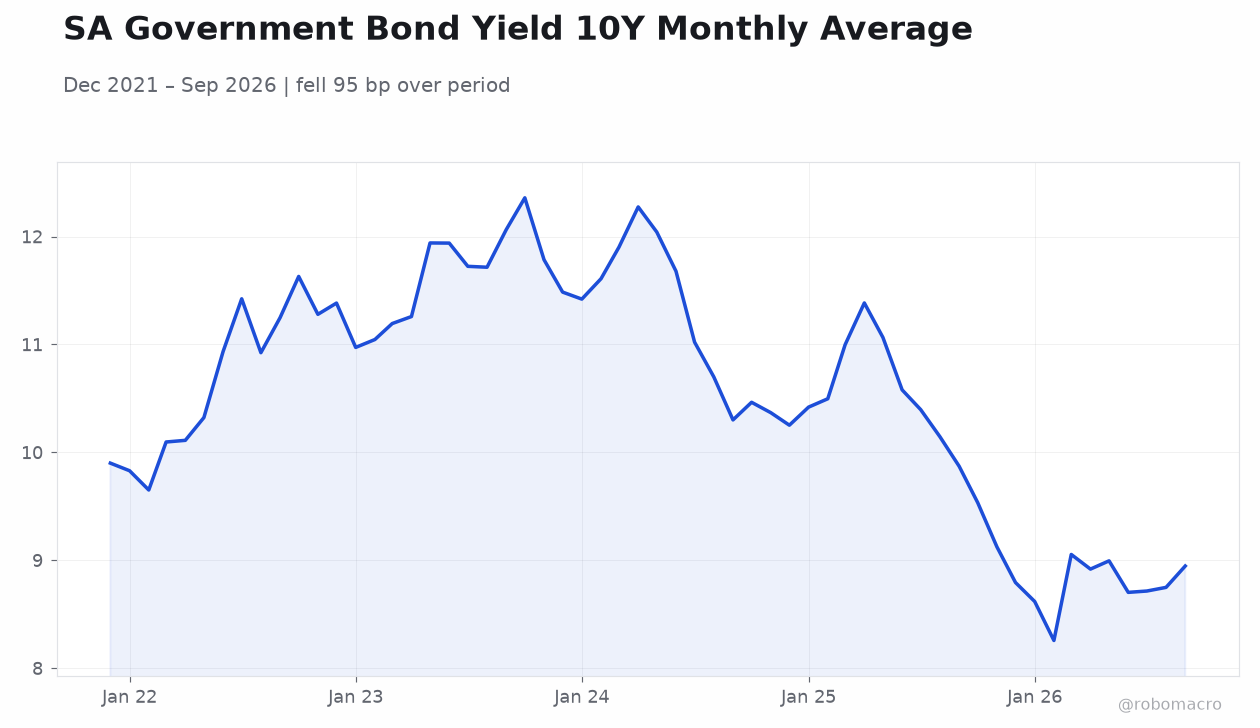
| South Africa 10Y Govt Yield | 8.75% | +9 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
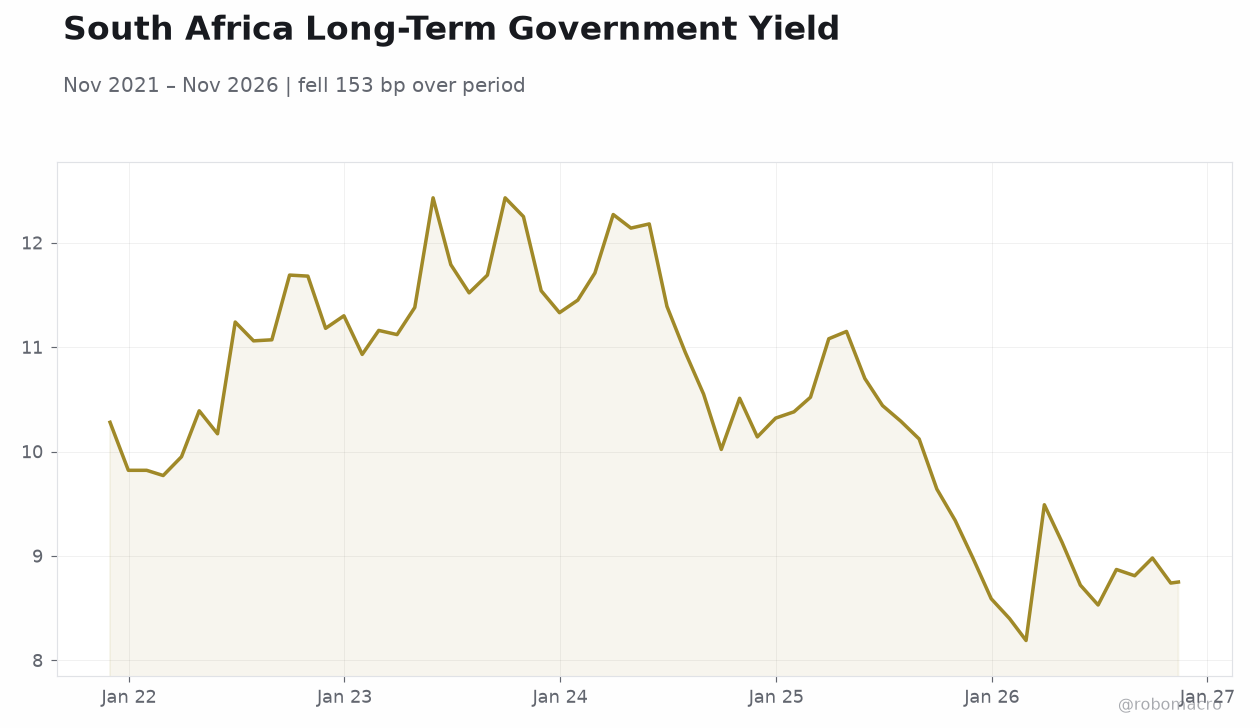 South Africa Long-Term Government Yield | Type: macro_line | 10Y Yield %: 8.75 (2026-11-13) | Range: 8.19–12.43 | Trend(5pt): 10.28,11.16,12.18,10.12,8.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wednesday (2026-11-18) | |||
| Inflation Rate Month-over-Month | 0.40 | - | 03:00 |
| Inflation Rate Year-over-Year | 4.50 | 5.10 | 03:00 |
| Thursday (2026-11-19) | |||
| Central Bank Interest Rate Decision | 7.25 | - | 08:00 |
- Rand presses toward R17/USD at a seven-month low as October CPI and Thursday's SARB decision dominate the week.
- October CPI consensus at 5.1% y/y versus 4.5% prior would mark a sharp acceleration, testing the SARB's 3-6% target band.
- SARB expected to hold the repo rate at 7.25% on Thursday, with the September +25bp hike still anchoring policy.
Yesterday's Recap
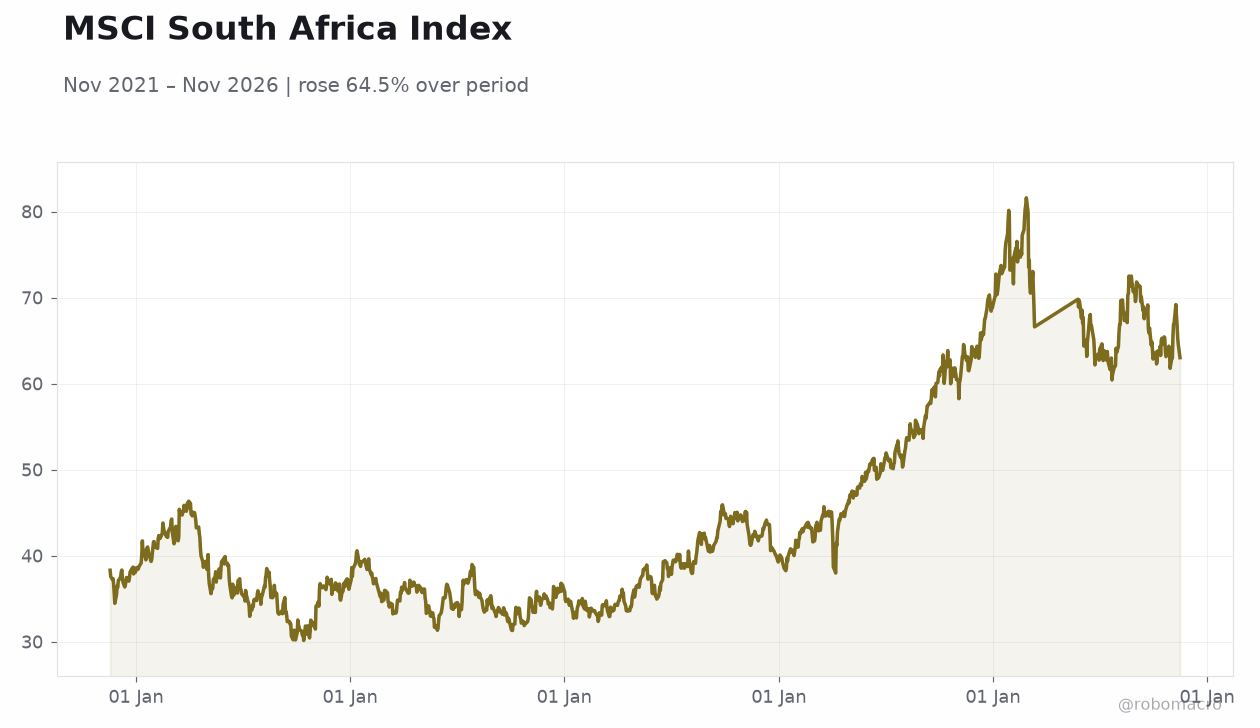
South African markets opened the week in risk-off mode with no domestic data releases on Monday, leaving positioning ahead of Wednesday's October CPI print and Thursday's SARB decision to drive flows. The JSE Top 40 fell 0.82% to 103,629, with Naspers down 1.42% to R72,537 as global tech sentiment softened. The rand weakened 0.19% to 16.96/USD, extending a slide that has taken it to a seven-month low, while EUR/ZAR edged up 0.11% to 18.67.
The curve bear-steepened sharply at the front end, with the 5-year yield jumping 32bp to 8.53% and the 10-year up 9bp to 8.75% — a move consistent with markets pricing inflation risk and reduced odds of near-term easing. Commodity-linked names lagged as Brent crude collapsed 4.39% to $91.63 and platinum fell 1.24% to $1,470, with gold off 0.37% at $3,872.10. Bitcoin slipped 0.64% to $64,884.75, offering little respite for risk appetite.
The Day Ahead
Wednesday's October CPI release at 03:00 ET is the week's first critical test, with consensus at 5.1% y/y against a 4.5% prior and month-on-month consensus not yet published versus the prior 0.4%. A print at or above 5.1% would push inflation toward the upper half of the SARB's 3-6% target band and complicate the case for any near-term reversal of September's hike. Thursday's SARB interest rate decision at 08:00 ET carries high impact, with the repo rate currently at 7.25% and consensus not yet published; economists surveyed widely expect a hold.
Markets will parse the statement for forward guidance on whether the September hike is a durable tightening or a one-off response to inflation risk. Bond and FX volatility is likely to remain elevated through both events given the front-end selloff already underway.
Other Economic Notes
The front-end yield spike — 32bp on the 5-year — signals that the market is repricing the inflation trajectory rather than growth, a dynamic that raises debt-service costs and pressures the fiscal outlook. Mining remains a drag, with platinum at $1,470 and gold softening, weighing on export earnings just as the rand weakens. Brent's 4.39% slide to $91.63 is a rare positive for import costs and the inflation outlook, though it also reflects weaker global demand expectations.
↓ p.2