South Africa Macro Daily(Beta Mode)
Rand Steadies Near Lows as CPI, SARB Decision Loom
Market Snapshot
| Asset | Level | Change |
|---|---|---|
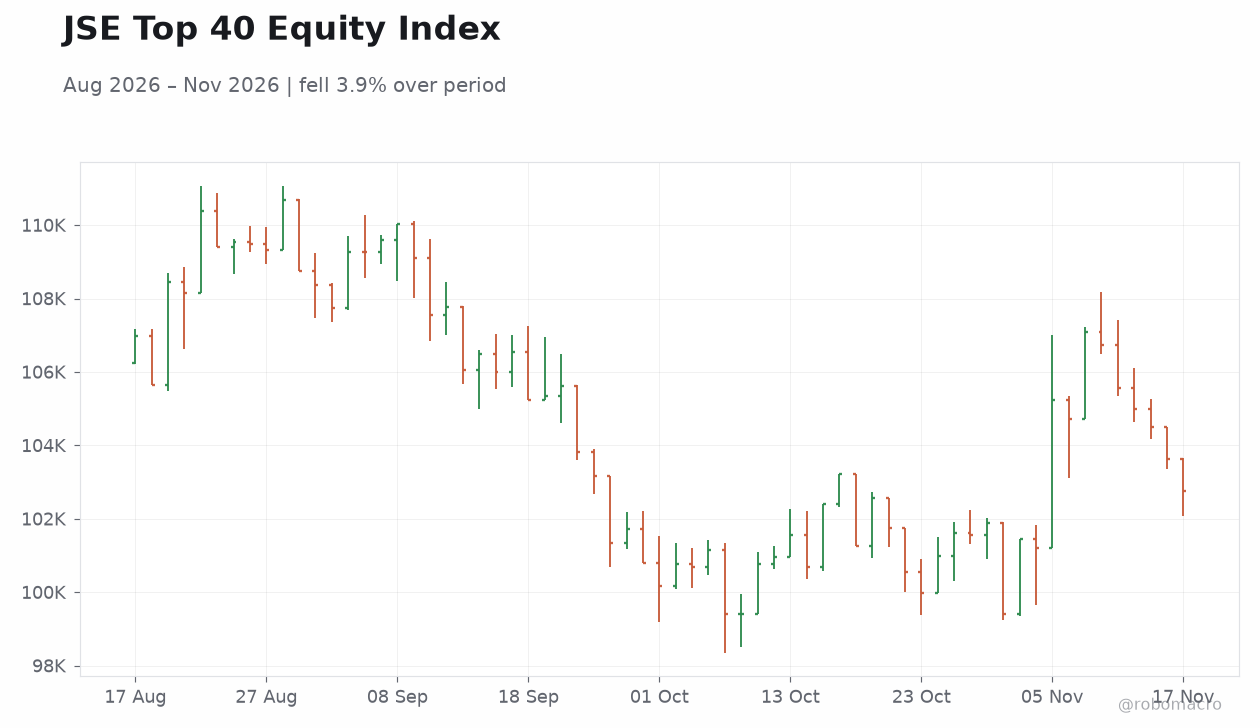
| JSE Top 40 | 102,752.10 | -0.85% |
| USD/ZAR | 16.96 | -0.04% |
| EUR/ZAR | 18.63 | -0.12% |
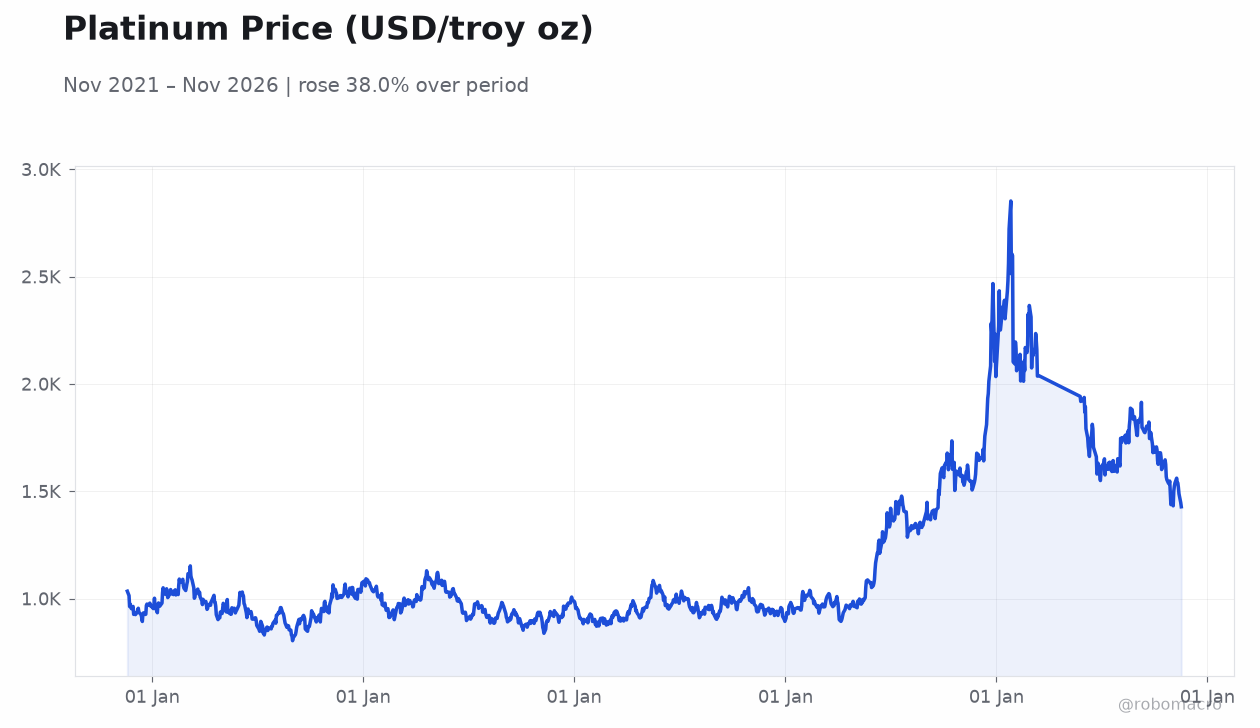
| Platinum | 1,402.60 | -3.14% |
| Gold | 3,785.50 | -1.75% |
| Brent Crude | 92.67 | +0.25% |
| Naspers | 71,741.00 | -2.46% |
| Bitcoin | 64,480.59 | -0.58% |
| South Africa 5Y Govt Yield | 8.54% | +1 bp |
| South Africa 10Y Govt Yield | 8.76% | +1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
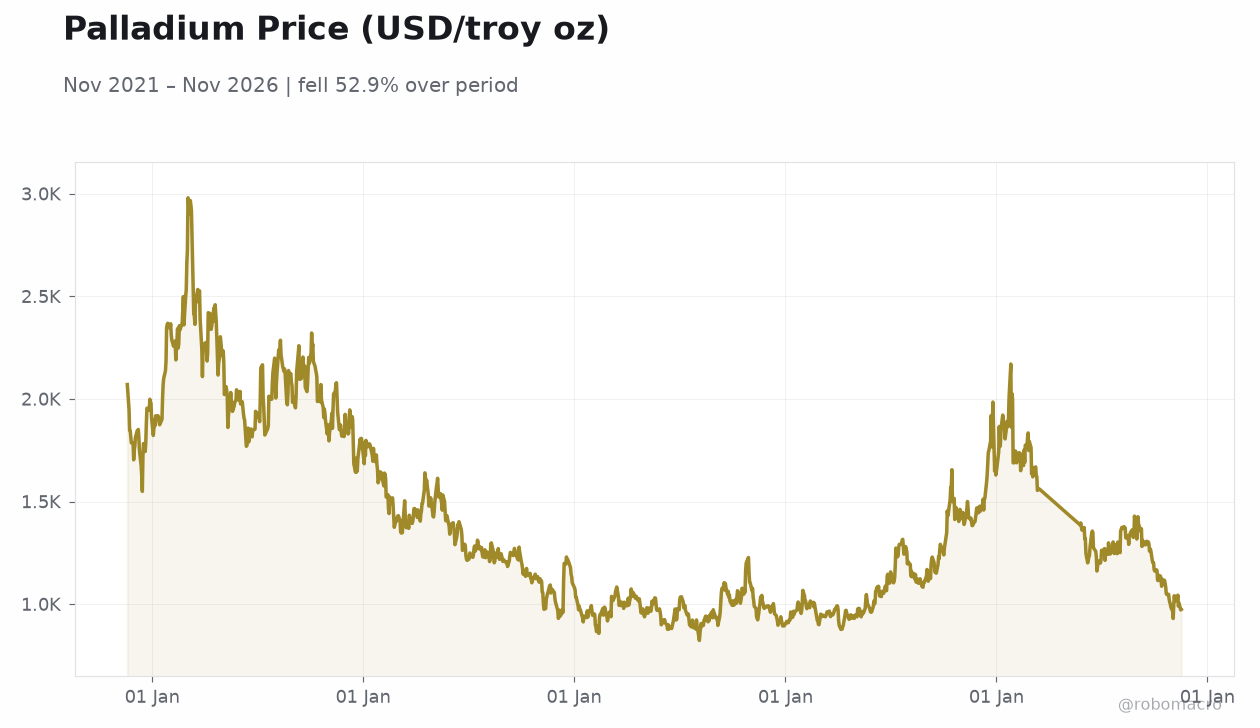 Palladium Price (USD/troy oz) | Type: macro_line | Palladium Price (USD/troy oz): 974 (2026-11-17) | Range: 822.8–2980 | Trend(6pt): 2070,1639,1029,1146,971.8,974
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Inflation Rate Month-over-Month | 0.40 | - | 03:00 |
| Inflation Rate Year-over-Year | 4.50 | 5.10 | 03:00 |
| Thursday (2026-11-19) | |||
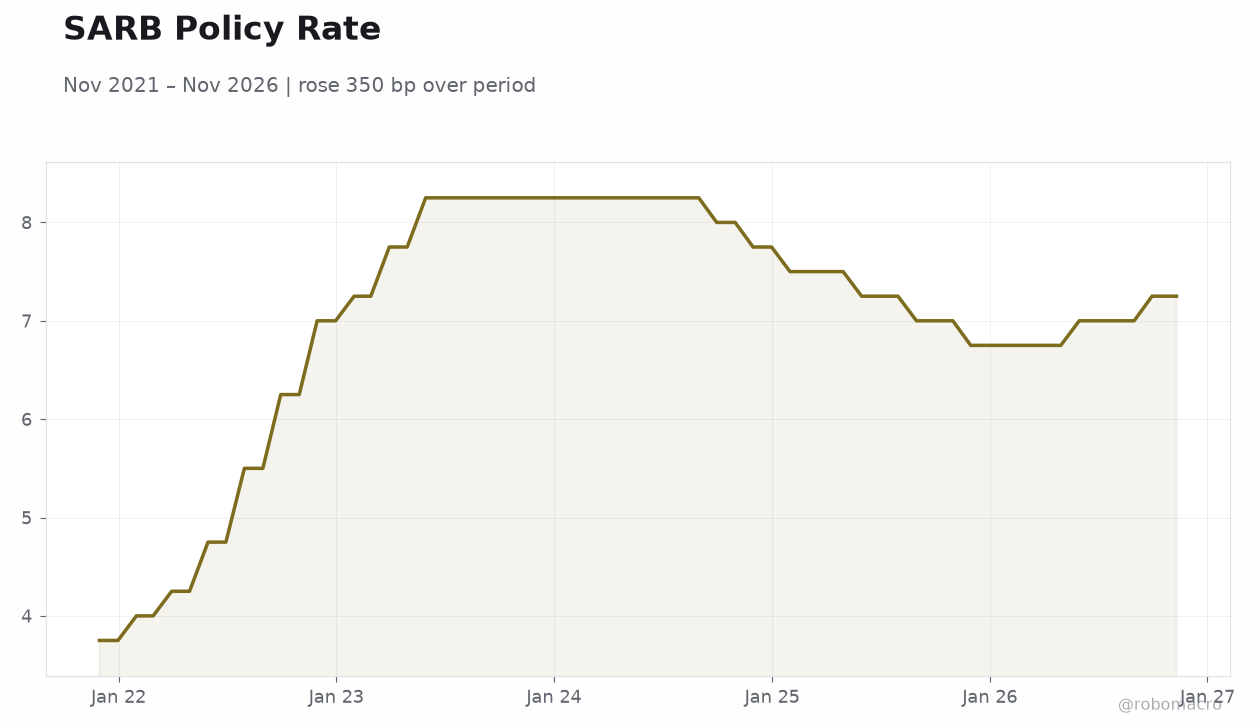
| Central Bank Interest Rate Decision | 7.25 | - | 08:00 |
- October CPI due today at 03:00 ET; consensus sees headline accelerating to 5.1% y/y from 4.5% previously, a test for the SARB ahead of Thursday's MPC.
- SARB decision Thursday 08:00 ET: repo rate at 7.25% after the September +25bp hike; economists widely expect a hold despite the inflation uptick.
- Rand near seven-month lows around 16.96/USD; JSE Top 40 off 0.85%, platinum down 3.14% and gold 1.75% as precious metals retreat.
Yesterday's Recap
No South African data releases were scheduled for Tuesday, leaving markets to trade on positioning ahead of this week's CPI print and SARB decision. The rand steadied near 16.96 per dollar after touching a seven-month low, with USD/ZAR easing 0.04% and EUR/ZAR down 0.12% on the day. Domestic equities softened, with the JSE Top 40 falling 0.85% and Naspers down 2.46% as global tech sentiment weighed.
Precious metals drove the commodity complex lower: platinum slumped 3.14% to $1,402.60/oz and gold fell 1.75% to $3,785.50/oz, pressuring the mining-heavy index. Brent crude edged up 0.25% to $92.67/bbl, offering limited support to energy names. In fixed income, the 5-year yield rose 1 bp to 8.54% and the 10-year added 1 bp to 8.76%, a muted move consistent with investors awaiting the inflation data.
News flow was dominated by the rand's slide toward R17 and speculation over Thursday's rate decision.
The Day Ahead
October CPI releases at 03:00 ET, with consensus at 5.1% y/y versus 4.5% previously; the month-on-month print follows the prior 0.4% reading. A print at or above consensus would mark a further acceleration and complicate the SARB's glide path toward the midpoint of its target range. Thursday's MPC decision at 08:00 ET is the week's dominant event, with the repo rate at 7.25% following September's 25bp hike.
Markets will parse the statement for forward guidance on whether the September tightening is complete or whether further restraint is warranted. Rand reaction is acute given the currency's proximity to seven-month lows.
Other Economic Notes
The rand's drift toward R17 reflects a stronger dollar and thin domestic risk appetite rather than idiosyncratic South African stress, but the currency remains a key inflation channel through imported fuel and food prices. Mining sector performance is fragile: platinum's 3.14% slide and gold's 1.75% decline squeeze export earnings and mining employment, a structural drag on growth. Load shedding risk persists as a supply-side constraint on industrial output and a persistent cost on the fiscus.
↓ p.2