South Africa Macro Daily(Beta Mode)
SARB Holds at 7.25% as Rand Falls, Metals Drop
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| JSE Top 40 | 98,385.10 | -0.35% |
| USD/ZAR | 17.54 | +1.59% |
| EUR/ZAR | 19.26 | +1.68% |
| Platinum | 1,294.60 | -4.82% |
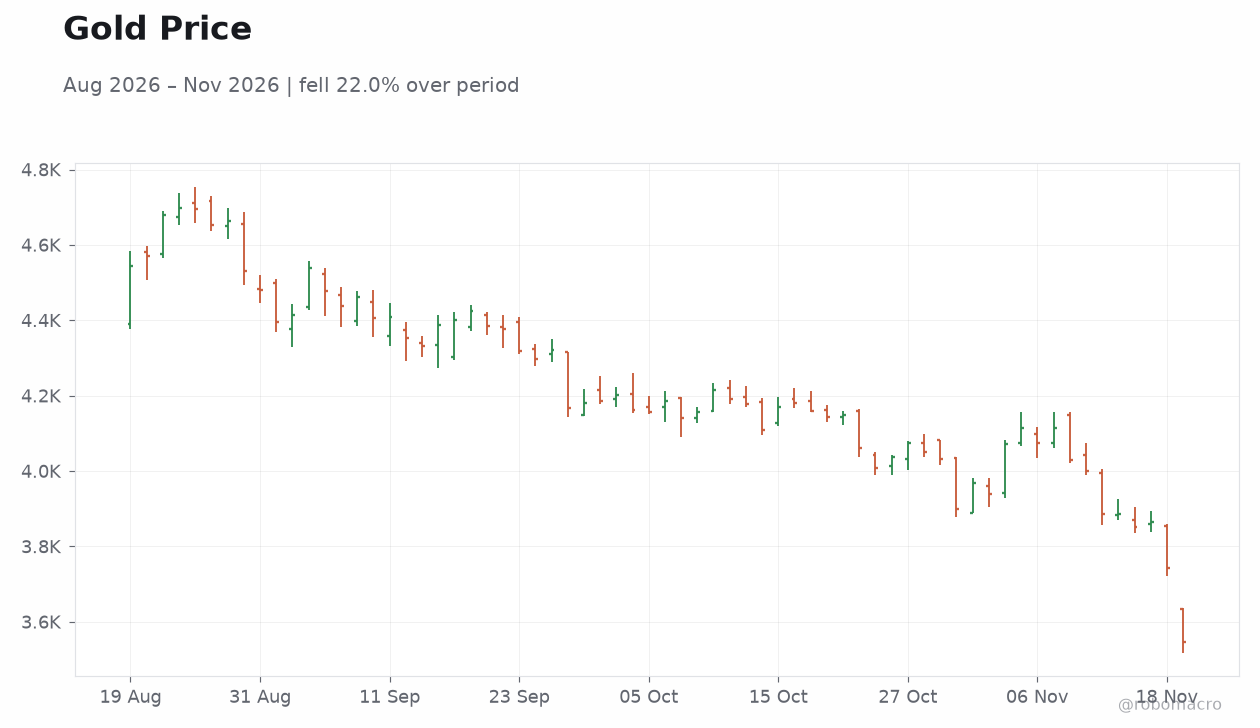
| Gold | 3,542.10 | -5.34% |
| Brent Crude | 90.04 | -2.08% |
| Naspers | 65,800.00 | -2.63% |
| Bitcoin | 61,693.85 | -2.05% |
| South Africa 5Y Govt Yield | 8.62% | +5 bp |
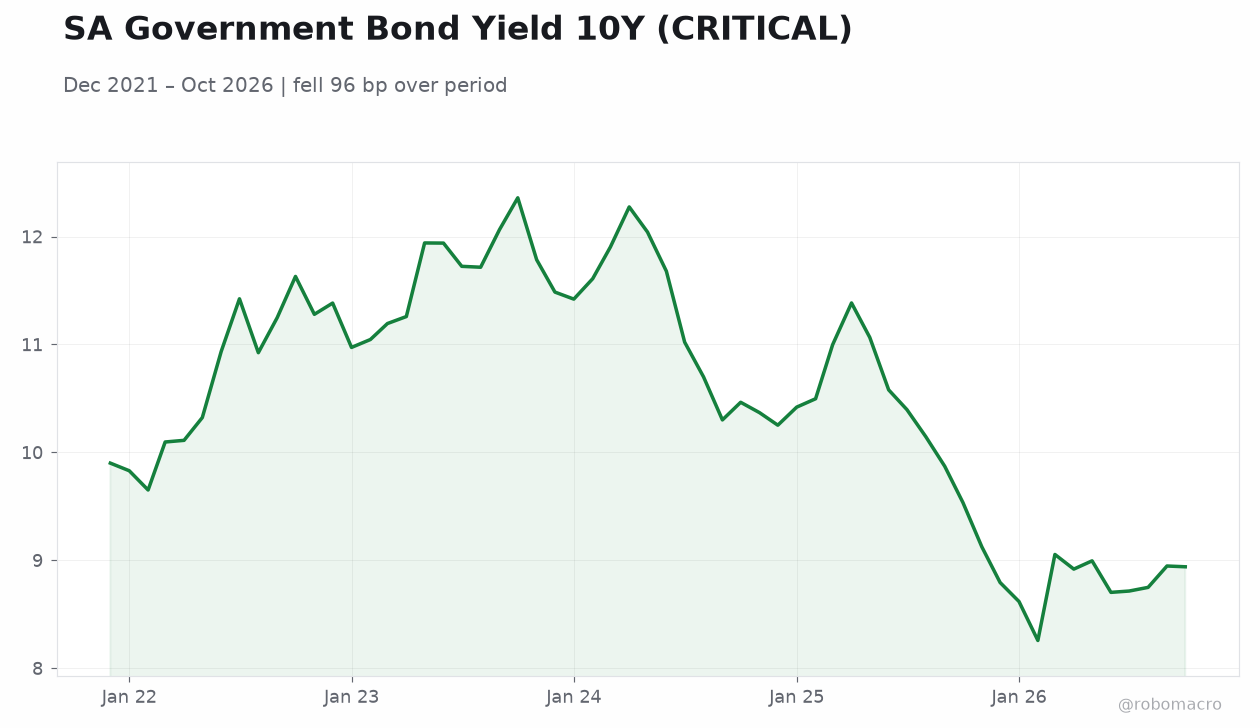
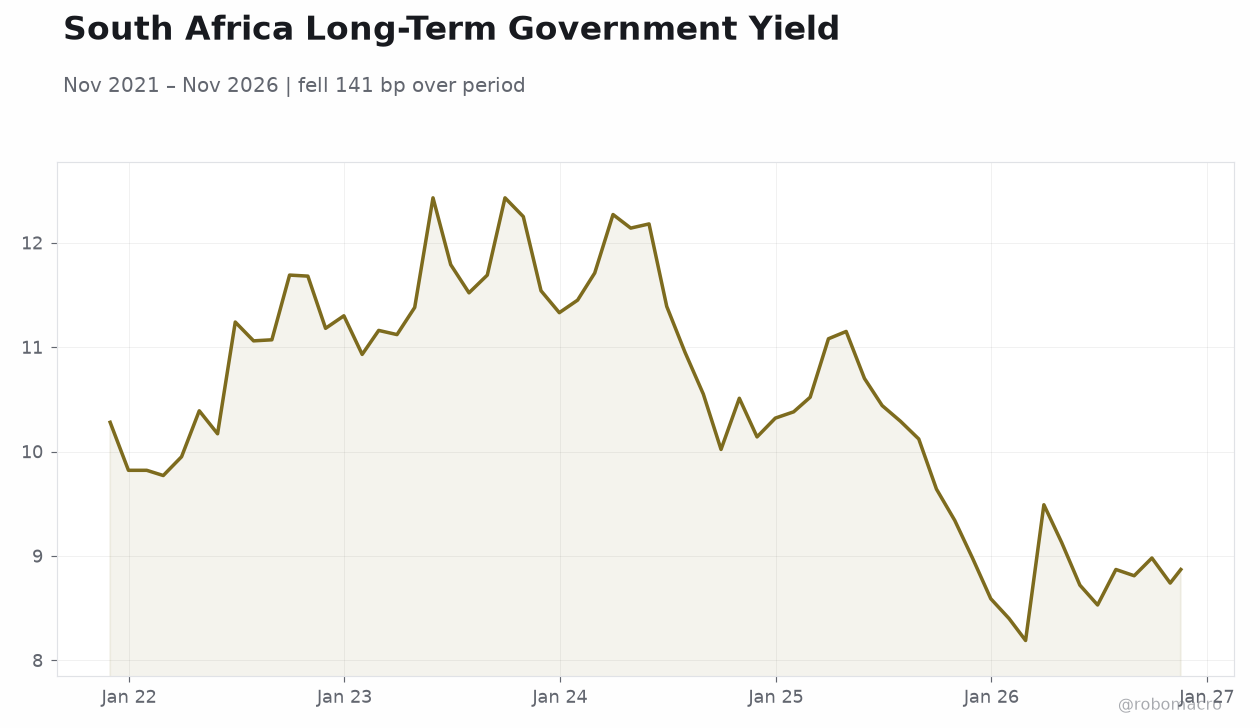
| South Africa 10Y Govt Yield | 8.87% | +7 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Month-over-Month | 0.40 | - | 0.70 |
| Inflation Rate Year-over-Year | 4.50 | 5.20 | 5.20 |
| Central Bank Interest Rate Decision | 7.25 | 7.25 | 7.25 |
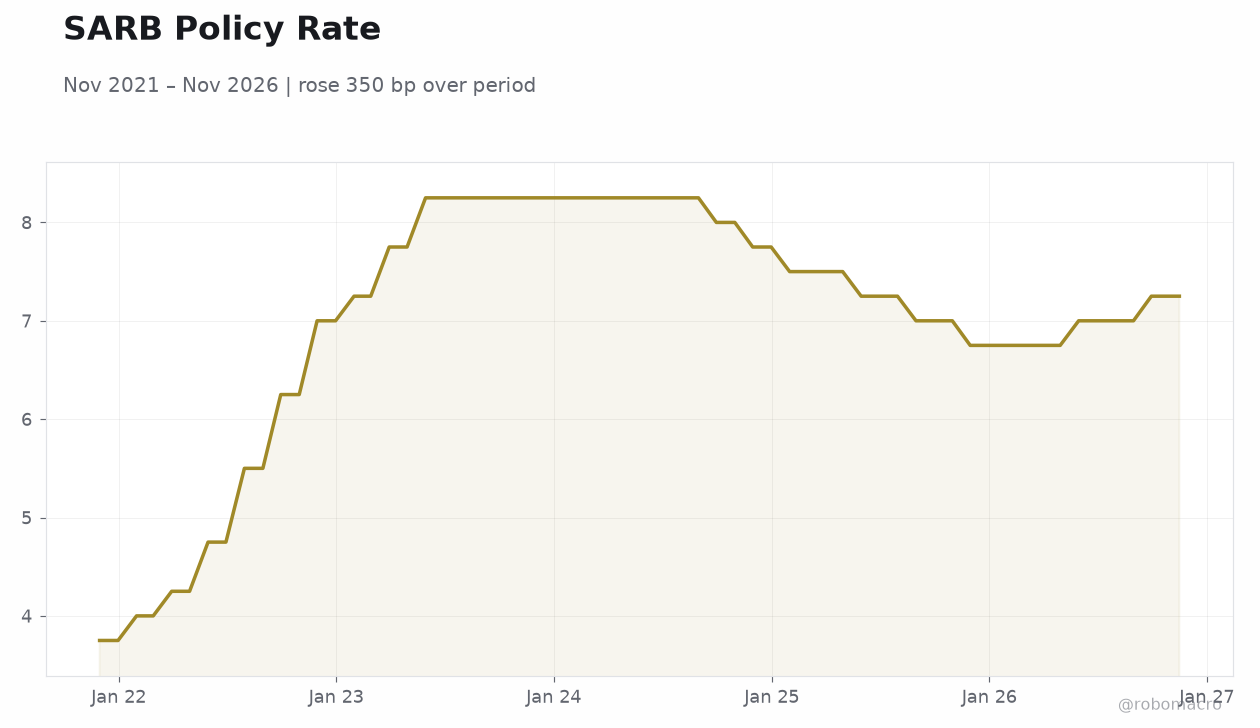 SARB Policy Rate | Type: macro_line | SARB repo rate (BIS): 7.25 (2026-11-16) | Range: 3.75–8.25 | Trend(5pt): 3.75,7.25,8.25,7,7.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- SARB held the repo rate at 7.25% on 19 November, in line with consensus, following the +25bp hike at the September decision
- October CPI accelerated to 5.2% y/y (0.7% m/m), matching consensus and extending the inflation uptrend
- Rand slumped 1.59% to 17.54/USD amid a global risk-off session; gold and platinum fell sharply, dragging JSE resources
Yesterday's Recap
South Africa's October CPI printed at 5.2% y/y, up from 4.5% previously and in line with consensus, with the month-on-month figure at 0.7% versus 0.4% prior — confirming the disinflation trend has reversed. Hours later, the SARB's Monetary Policy Committee voted to hold the repo rate at 7.25%, matching expectations and leaving policy where it was set by the September +25bp hike. Markets reacted poorly to the combination of sticky inflation and a cautious hold: the rand weakened 1.59% to 17.54/USD and 1.68% to 19.26/EUR, with USD/ZAR reportedly forming a golden cross as the rand's slide extends.
JSE Top 40 fell 0.35% to 98,385.10, with Naspers down 2.63% at R65,800. Precious metals led the rout — gold dropped 5.34% to $3,542.10/oz and platinum 4.82% to $1,294.60/oz — pressuring the mining complex. Bond yields backed up, with the 5-year at 8.62% (+5bp) and 10-year at 8.87% (+7bp), reflecting both the inflation surprise and reduced hopes for near-term easing.
The Day Ahead
No scheduled South African data releases are due today or tomorrow, leaving markets to digest Thursday's CPI and SARB decisions. Attention shifts to the rand, which sits near 17.54/USD and remains the primary transmission channel for global risk sentiment into local assets. JSE resource stocks will take their cue from overnight metal prices after gold's sharp decline.
Bond traders will watch whether the 10-year yield holds below 9%, with the +7bp move on Wednesday testing conviction. With the next MPC meeting not imminent, forward guidance from SARB officials and any commentary on the inflation trajectory will be the main domestic catalysts into month-end.
Other Economic Notes
The October CPI acceleration to 5.2% keeps inflation uncomfortably above the midpoint of the SARB's 3-6% target range, complicating the policy outlook. Food and administered price pressures appear to be driving the uptick, while the rand's weakness adds imported inflation risk. The SARB's narrow hold suggests the committee is balancing growth concerns against a deteriorating inflation profile.
Mining sector margins are under pressure from the simultaneous collapse in platinum and gold prices, a key export earner for South Africa. Electricity supply remains a structural constraint, with load-shedding risk persisting into the summer demand period.