UK Macro Daily(Beta Mode)
Oil at $100 Adds to BoE Rate Pressure
Market Snapshot
| Asset | Level | Change |
|---|---|---|
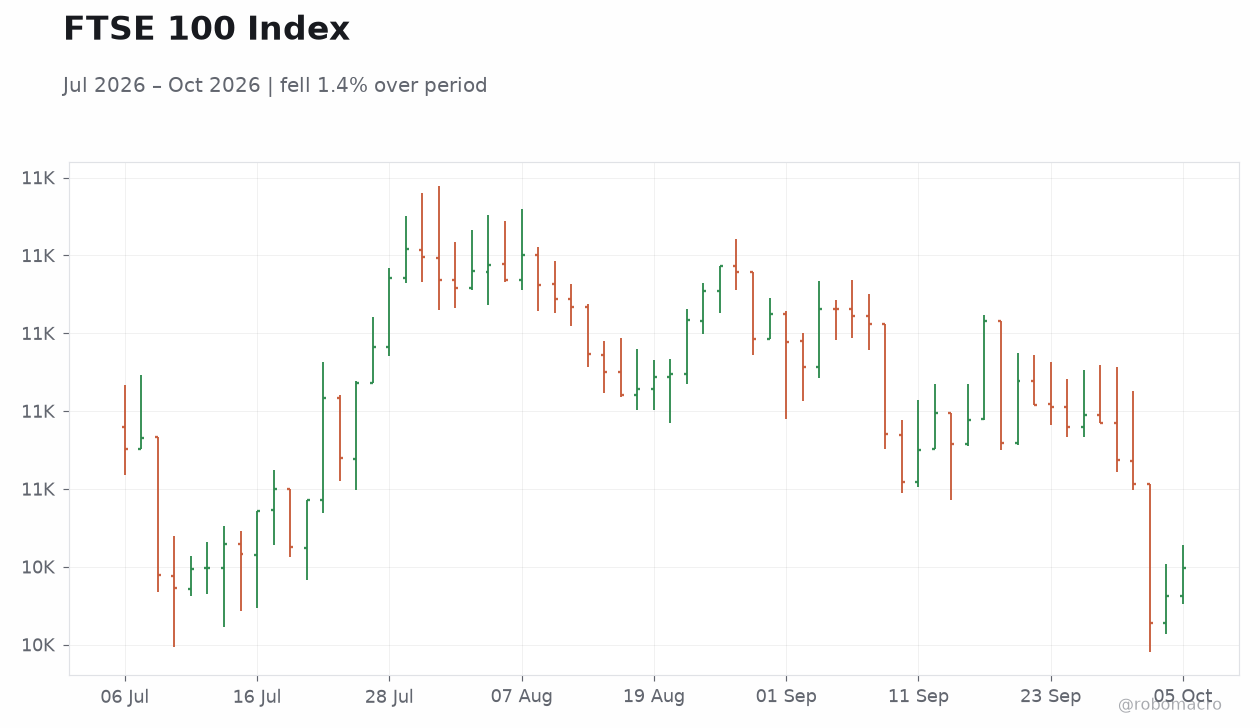
| FTSE 100 | 10,462.00 | +0.32% |
| FTSE 250 | 24,123.80 | -0.29% |
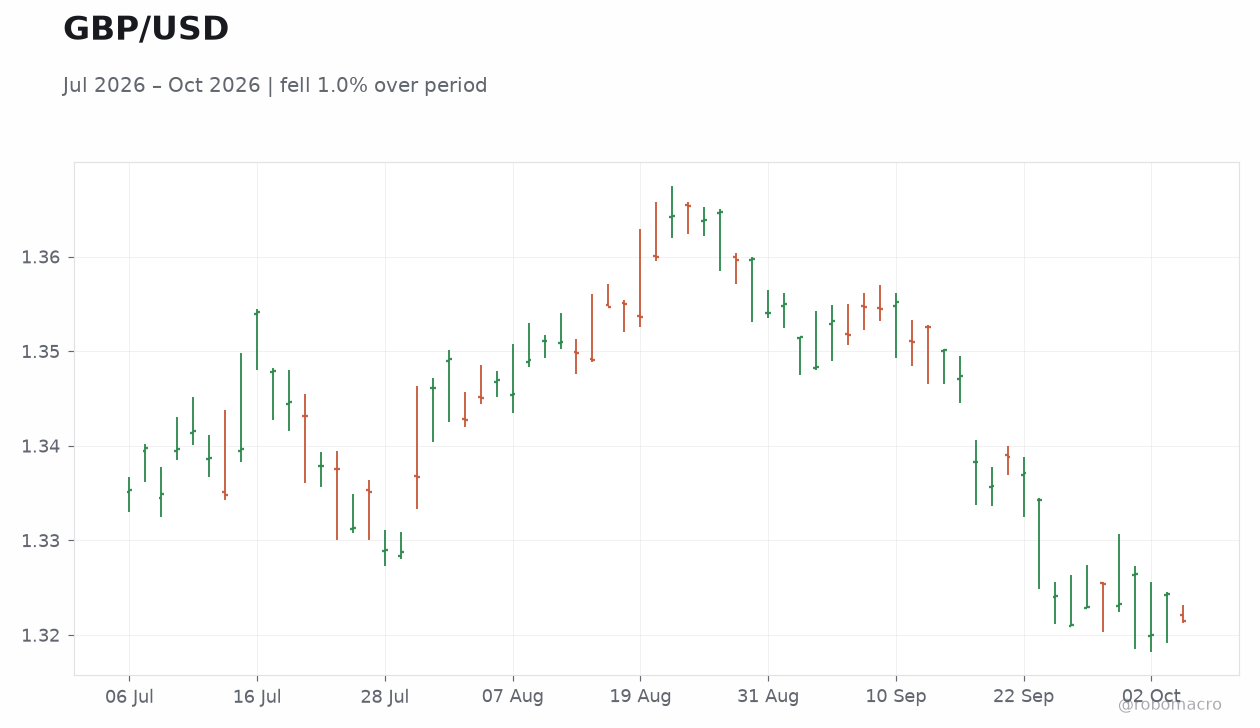
| GBP/USD | 1.32 | -0.22% |
| GBP/EUR | 1.18 | +0.12% |
| GBP/JPY | 208.85 | -0.02% |
| Brent Crude | 100.75 | +0.43% |
| Gold | 4,148.30 | -0.20% |
| UK Nat Gas | 3.08 | +0.29% |
| Bitcoin | 85,435.46 | -1.21% |
| UK 2Y Gilt | 4.60% | 0 bp |
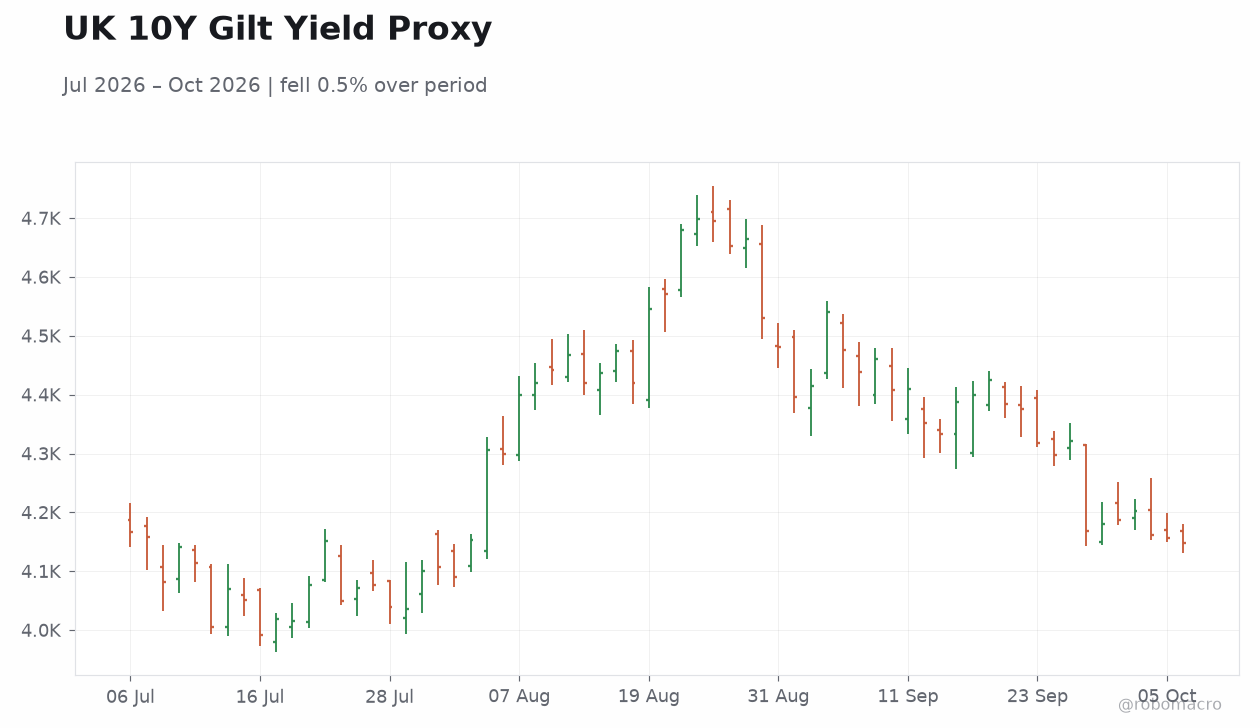
| UK 10Y Gilt | 5.42% | +2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
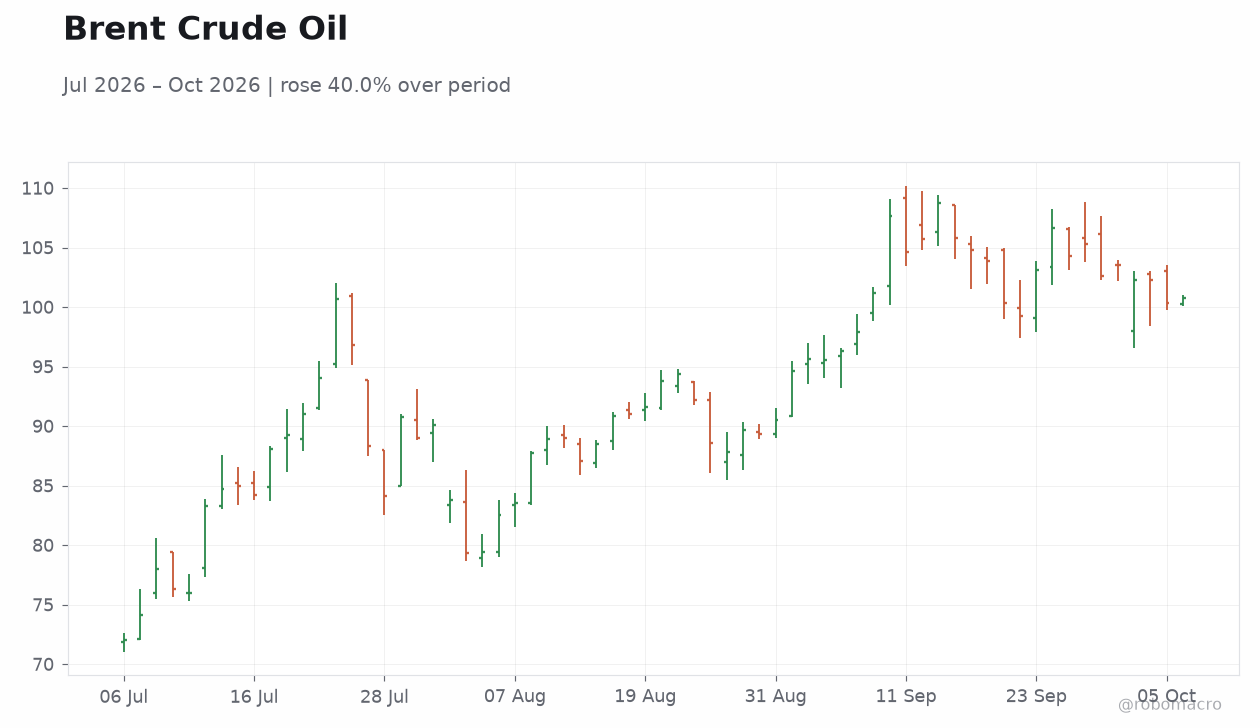 Brent Crude Oil | Type: market_hloc | USD/bbl: 100.8 (2026-10-06) | Range: 71.99–108.8 | Trend(6pt): 71.99,84.09,91.62,104.6,100.3,100.8
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| S&P Global Construction PMI | 44.30 | 45.40 | 04:30 |
| Wednesday (2026-10-07) | |||
| Lloyds House Price Index Month-over-Month | -0.20 | 0.20 | 02:00 |
| Lloyds House Price Index Year-over-Year | -0.40 | - | 02:00 |
| RICS House Price Balance | -28 | -30 | 19:01 |
- UK services firms raised prices at the fastest pace since May as input costs surged, with final September PMI at 52.1.
- FTSE 100 rose 0.32% to 10,462 while 10-year gilt yields climbed 2 bp to 5.42%; GBP/USD fell 0.22% to 1.32.
- Construction PMI due today with consensus at 45.4; housing indicators and RICS balance follow tomorrow.
Yesterday's Recap
UK markets showed modest gains amid stable policy expectations. The FTSE 100 advanced 0.32% to close at 10,462.00 while the FTSE 250 slipped 0.29%. The 2-year gilt yield held at 4.60% and the 10-year yield rose 2 bp to 5.42%.
Sterling weakened, with GBP/USD down 0.22% at 1.32 and GBP/EUR up 0.12% at 1.18. Brent crude gained 0.43% to 100.75, adding to cost pressures already visible in services. Final September services PMI printed at 52.1, above the 51.7 preliminary read, as firms reported the quickest price increases since May amid fuel and wage costs.
No UK data releases occurred on 5 October.
The Day Ahead
Attention turns to the S&P Global Construction PMI at 04:30 UK time, with consensus pointing to a rise to 45.4 from 44.3. The medium-impact print may offer an early read on building-sector momentum but is unlikely to alter BoE pricing on its own. Tomorrow brings Lloyds House Price Index month-over-month (consensus +0.2%) and year-over-year figures, followed by the RICS House Price Balance expected at -30.
No MPC speeches or minutes are scheduled. Markets will also monitor sterling reaction to any fiscal headlines ahead of the budget.
Other Economic Notes
UK fiscal headroom faces a potential £7bn hit from sustained energy prices near $100. HSBC highlighted gradual dollar gains into the budget, underscoring sterling’s sensitivity to fiscal announcements. Broader services data showed firms passing on higher costs at an accelerated rate, consistent with CPI at 3.10% and unemployment at 4.90%.
Construction and housing prints will be watched for signs of resilience or further softening in domestic demand.
Global Macro News
Brent crude held above $100 amid ongoing Hormuz tensions, directly feeding UK inflation risks and gilt yields. The World Bank projected a 2.1% contraction in the Middle East economy for 2026 tied to regional conflict. India’s finance minister stated US trade talks have reached a plateau, limiting near-term export support for UK firms.
↓ p.2