UK Macro Daily(Beta Mode)
BoE Speakers Take Stage, Gilts Firm
Market Snapshot
| Asset | Level | Change |
|---|---|---|
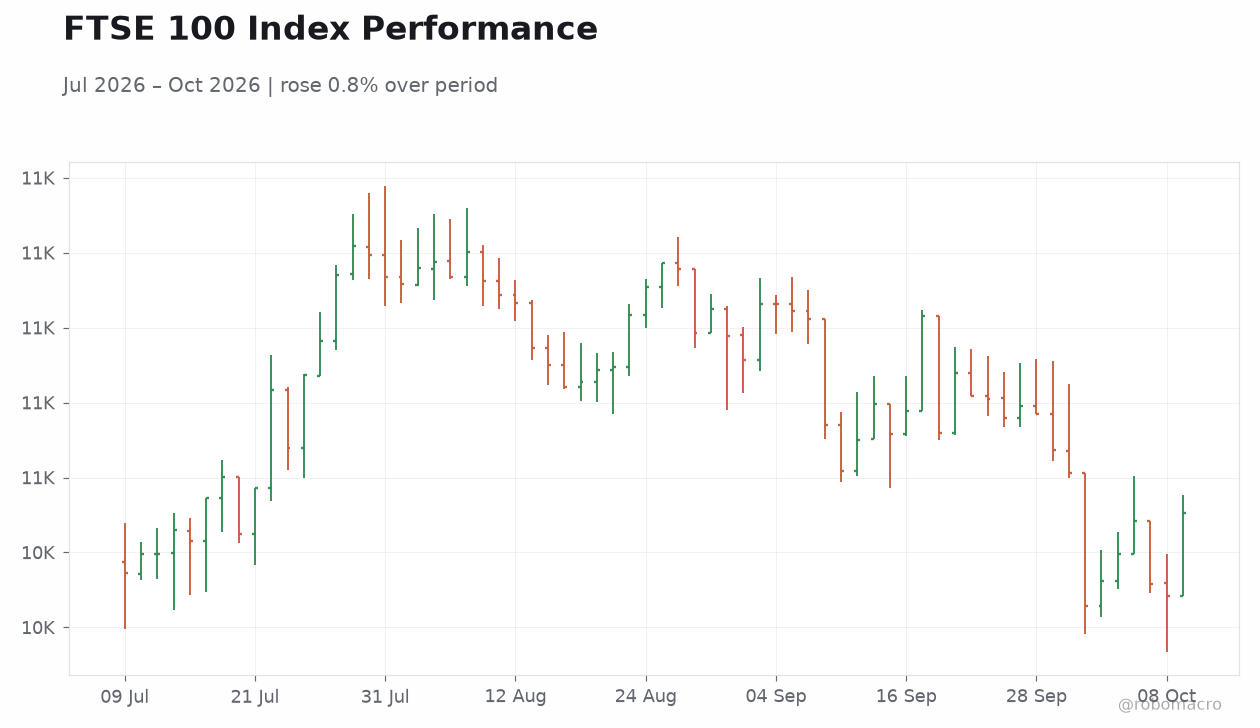
| FTSE 100 | 10,552.10 | +1.06% |
| FTSE 250 | 24,213.80 | +1.13% |
| GBP/USD | 1.32 | +0.11% |
| GBP/EUR | 1.18 | +0.16% |
| GBP/JPY | 209.67 | +0.28% |
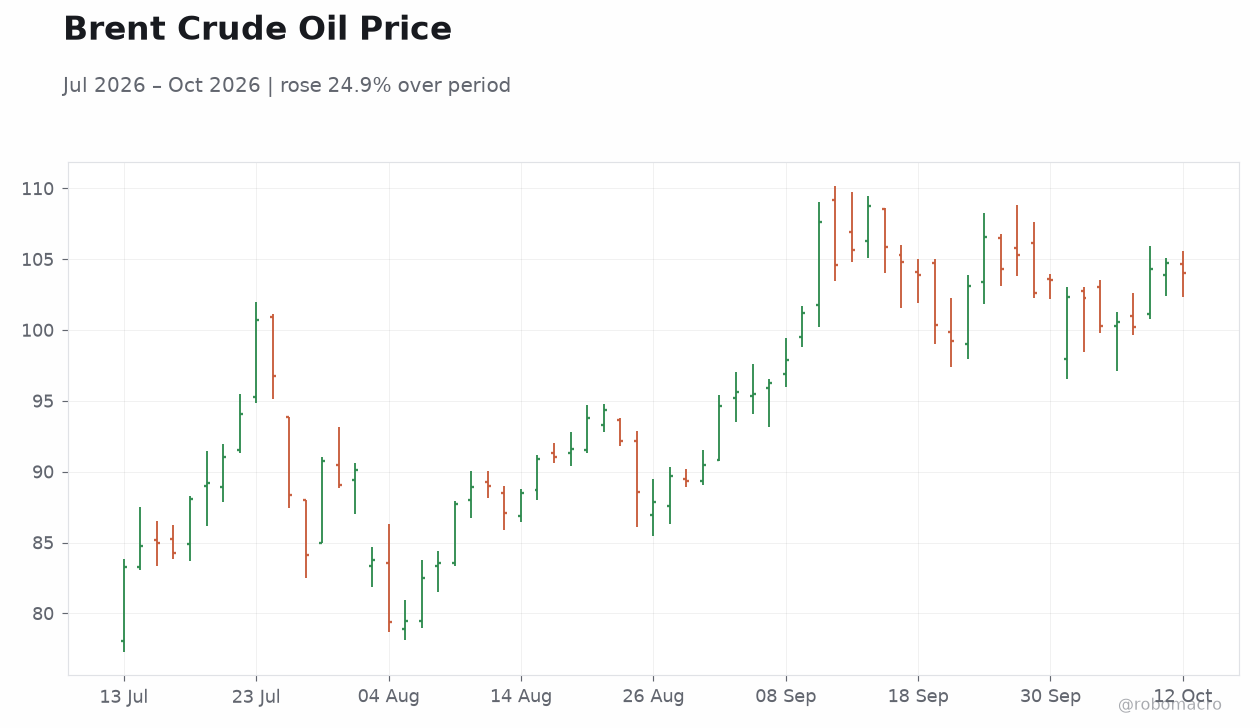
| Brent Crude | 104.00 | -0.69% |
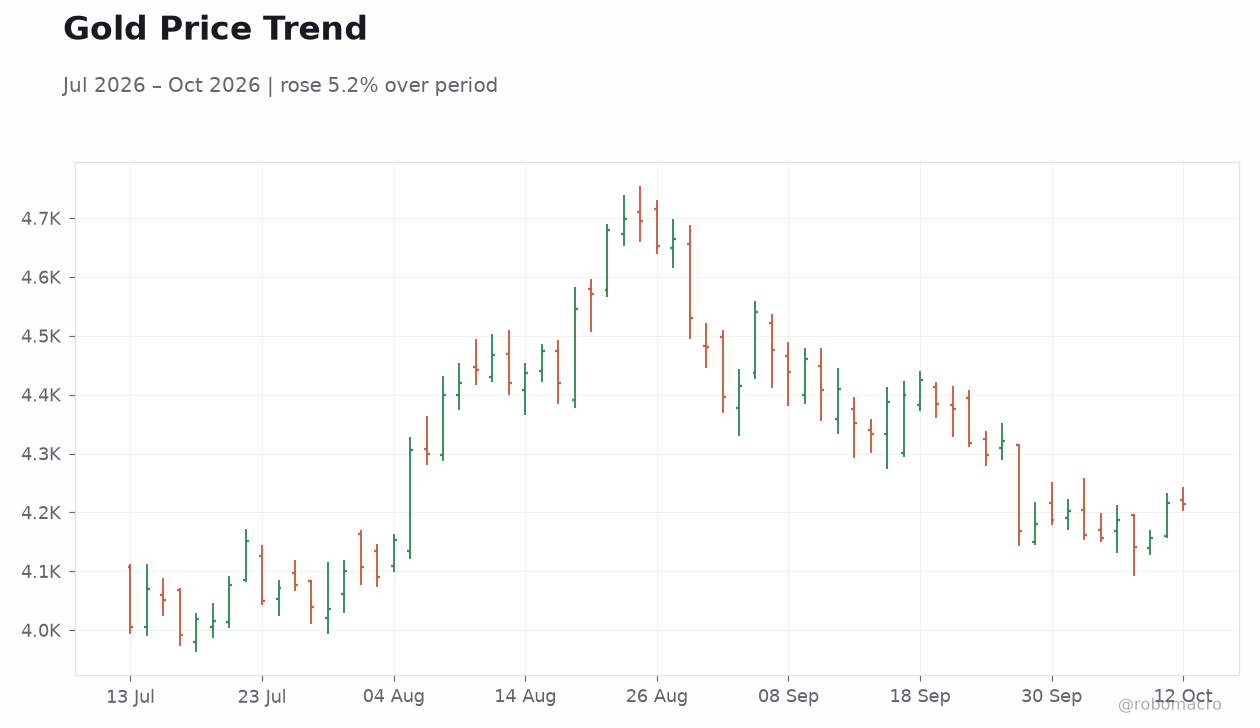
| Gold | 4,214.20 | -0.05% |
| UK Nat Gas | 3.17 | -1.65% |
| Bitcoin | 83,892.95 | +1.18% |
| UK 2Y Gilt | 4.70% | +7 bp |
| UK 10Y Gilt | 5.44% | +7 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
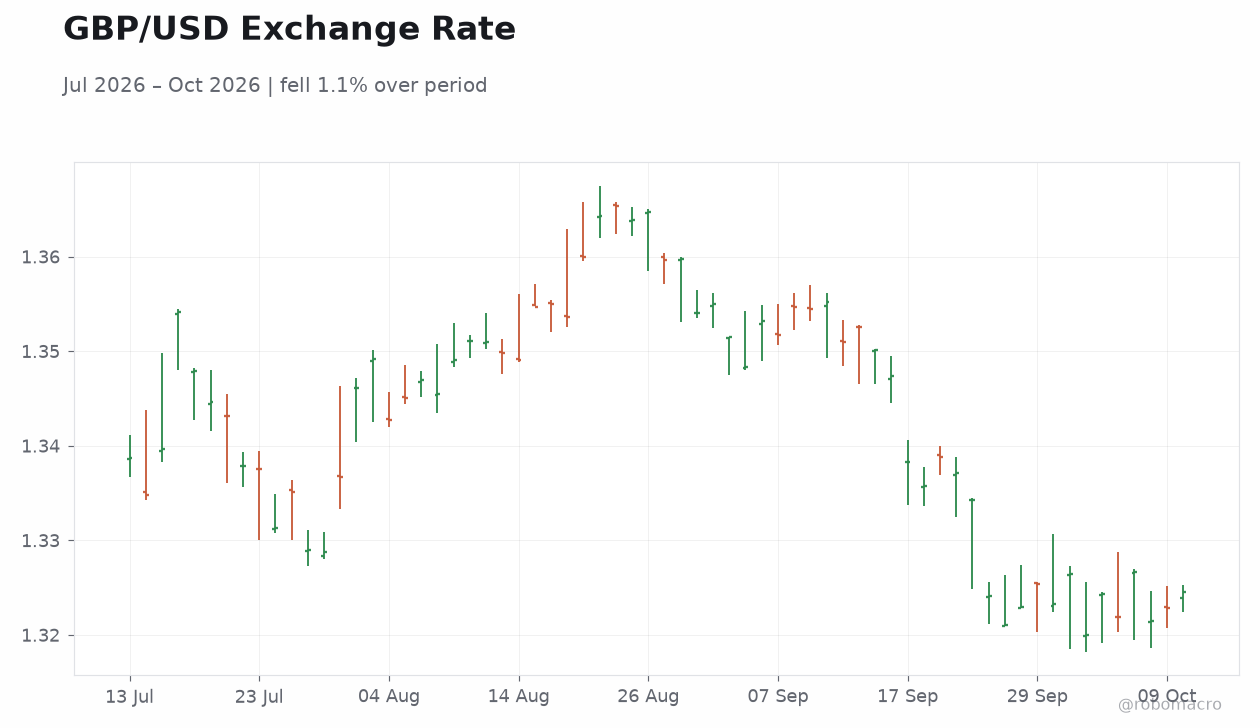 GBP/USD Exchange Rate | Type: market_hloc | GBP/USD: 1.325 (2026-10-12) | Range: 1.32–1.365 | Trend(6pt): 1.339,1.343,1.365,1.338,1.323,1.325
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| BoE Breeden Speech | - | - | 05:30 |
| BoE Mann Speech | - | - | 08:50 |
| BRC Retail Sales Monitor Year-over-Year | 0.50 | 0.70 | 19:01 |
| BoE Greene Speech | - | - | 23:00 |
| Tuesday (2026-10-13) | |||
| BoE Dhingra Speech | - | - | 12:00 |
| BoE Breeden Speech | - | - | 23:30 |
| Wednesday (2026-10-14) | |||
| BoE Gov Bailey Speech | - | - | 01:30 |
| BoE Pill Speech | - | - | 02:00 |
- Three BoE speakers today — Breeden, Mann and Greene — as markets price a November hike; MUFG sees the MPC tightening.
- Gilt yields rose 7 bp across the curve Friday, with the 10-year at 5.44% and the 2-year at 4.70%.
- FTSE 100 gained 1.06% to 10,552.10; sterling firmed against the dollar and euro.
Yesterday's Recap
Friday's session closed on a constructive note for UK risk assets, with the FTSE 100 advancing 1.06% to 10,552.10 and the FTSE 250 outperforming slightly at +1.13% to 24,213.80. The rally in equities was accompanied by a modest sell-off in fixed income: the 10-year gilt yield rose 7 bp to 5.44%, while the 2-year climbed 7 bp to 4.70%, suggesting the move reflected improved growth sentiment rather than a steepening dynamic. Sterling strengthened across the board, gaining 0.11% against the dollar to 1.32 and 0.16% versus the euro to 1.18, with GBP/JPY up 0.28% at 209.67.
The pound's resilience came despite higher domestic yields, pointing to rate expectations doing the heavy lifting — MUFG is among houses now flagging a November Bank of England hike. Commodity plays were mixed: Brent crude slipped 0.69% to $104.00 and UK natural gas fell 1.65%, a mild tailwind for the inflation outlook, while gold was essentially flat at 4,214.20. Bitcoin added 1.18% to 83,892.95, echoing the risk-on tone.
There were no scheduled UK data releases to digest, leaving the market to position ahead of a heavy week of central bank communication.
The Day Ahead
Today belongs to the Bank of England. Clare Breeden speaks at 05:30 ET, Catherine Mann follows at 08:50 ET, and Megan Greene closes the day at 23:00 ET — all flagged high-impact. With the policy rate at 3.73% and CPI at 3.10%, still above target, every nuance on the timing of further tightening matters for the front end.
The BRC Retail Sales Monitor at 19:01 ET tonight, consensus 0.7% year-over-year versus 0.5% prior, will offer an early read on consumer resilience heading into Q4. Tomorrow brings Dhingra at 12:00 ET and Breeden again late in the session, before Governor Bailey and Pill headline Wednesday. Thursday delivers the week's key macro print: monthly GDP, consensus -0.1% versus the prior 0.4% reading, alongside the three-month average and goods trade balance.
Other Economic Notes
The UK labour market remains the soft patch in the macro picture, with unemployment at 4.90% as of the June quarter — enough slack to keep wage-price dynamics from accelerating, but not so much as to force an easing bias. ↓ p.2