UK Macro Daily(Beta Mode)
BoE Chorus Intensifies Ahead of GDP Test
Market Snapshot
| Asset | Level | Change |
|---|---|---|
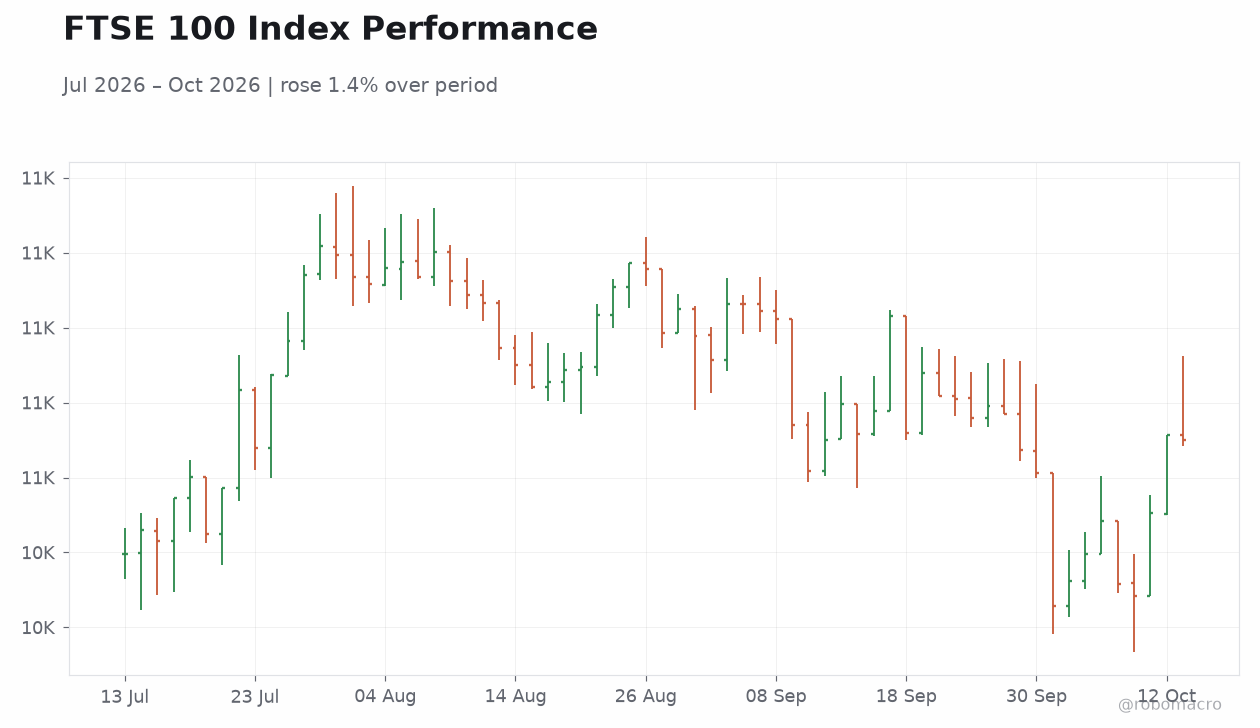
| FTSE 100 | 10,653.84 | -0.02% |
| FTSE 250 | 24,339.20 | +0.05% |
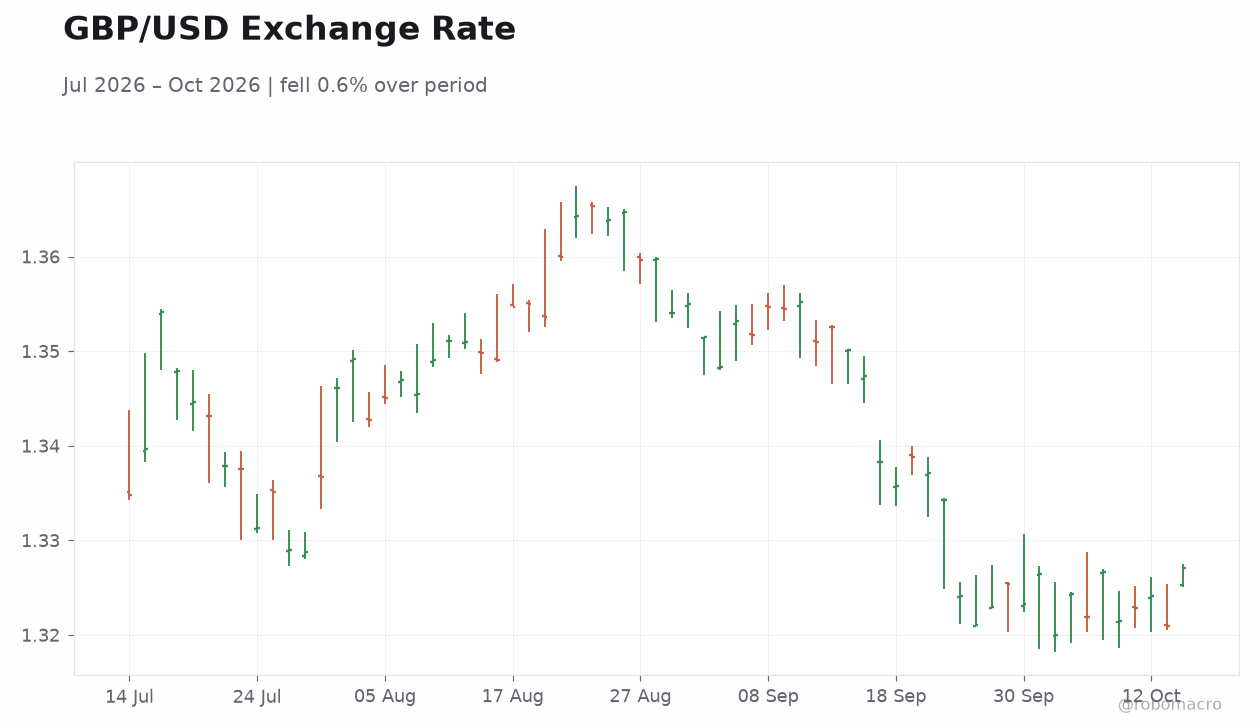
| GBP/USD | 1.33 | +0.46% |
| GBP/EUR | 1.18 | +0.01% |
| GBP/JPY | 209.40 | -0.01% |
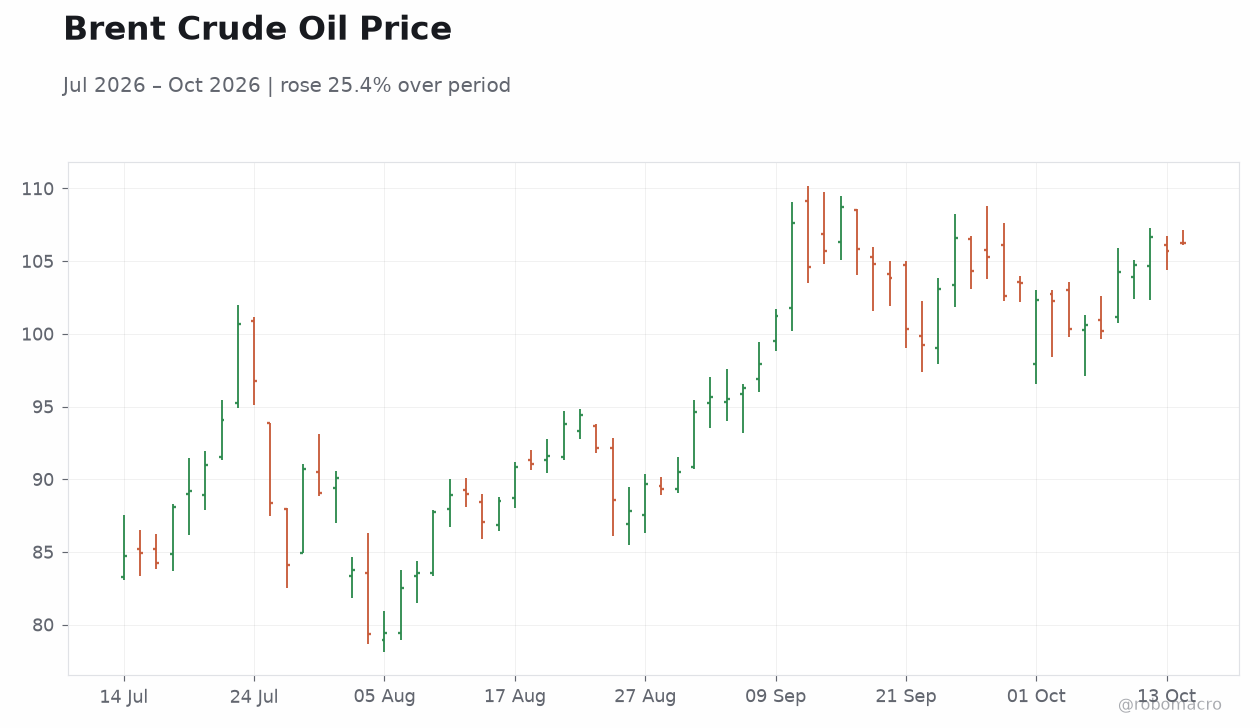
| Brent Crude | 106.25 | +0.53% |
| Gold | 4,180.30 | +0.07% |
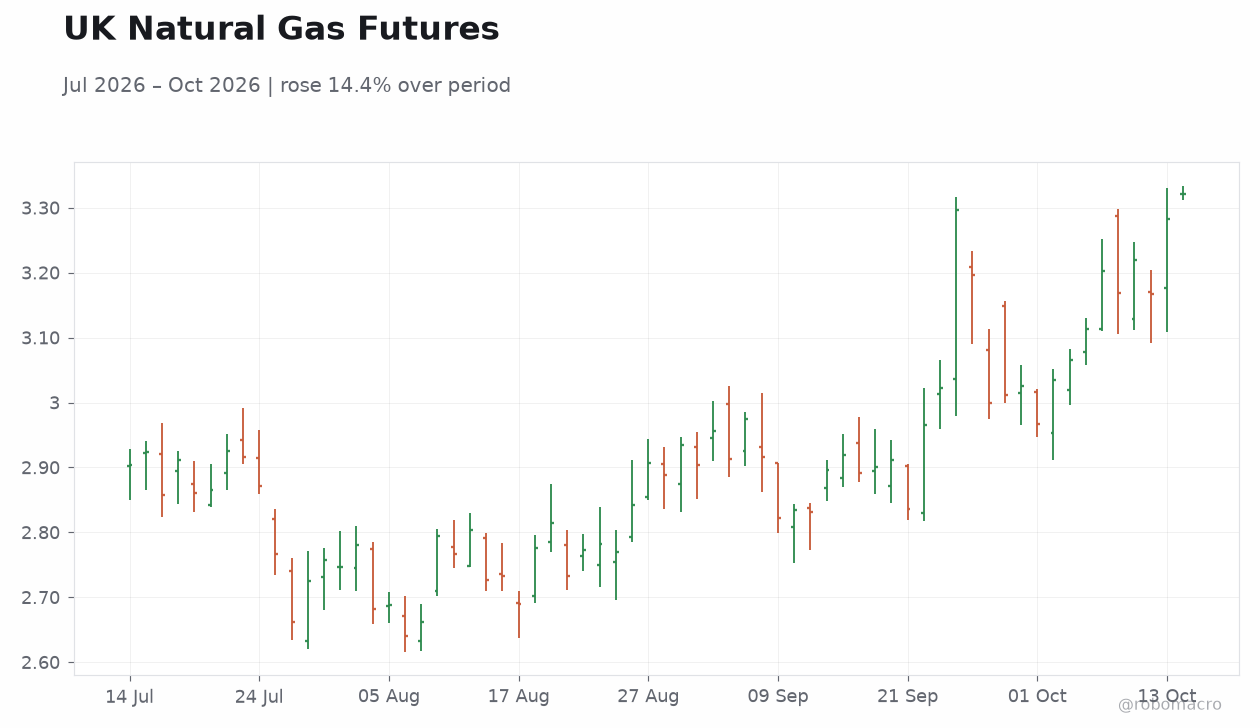
| UK Nat Gas | 3.32 | +1.07% |
| Bitcoin | 83,363.41 | +1.96% |
| UK 2Y Gilt | 4.69% | 0 bp |
| UK 10Y Gilt | 5.45% | -3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BoE Breeden Speech | - | - | - |
| BoE Mann Speech | - | - | - |
| BRC Retail Sales Monitor Year-over-Year | 0.50 | 0.70 | 1 |
| BoE Greene Speech | - | - | - |
| BoE Dhingra Speech | - | - | - |
| BoE Breeden Speech | - | - | - |
| BoE Gov Bailey Speech | - | - | - |
| BoE Pill Speech | - | - | - |
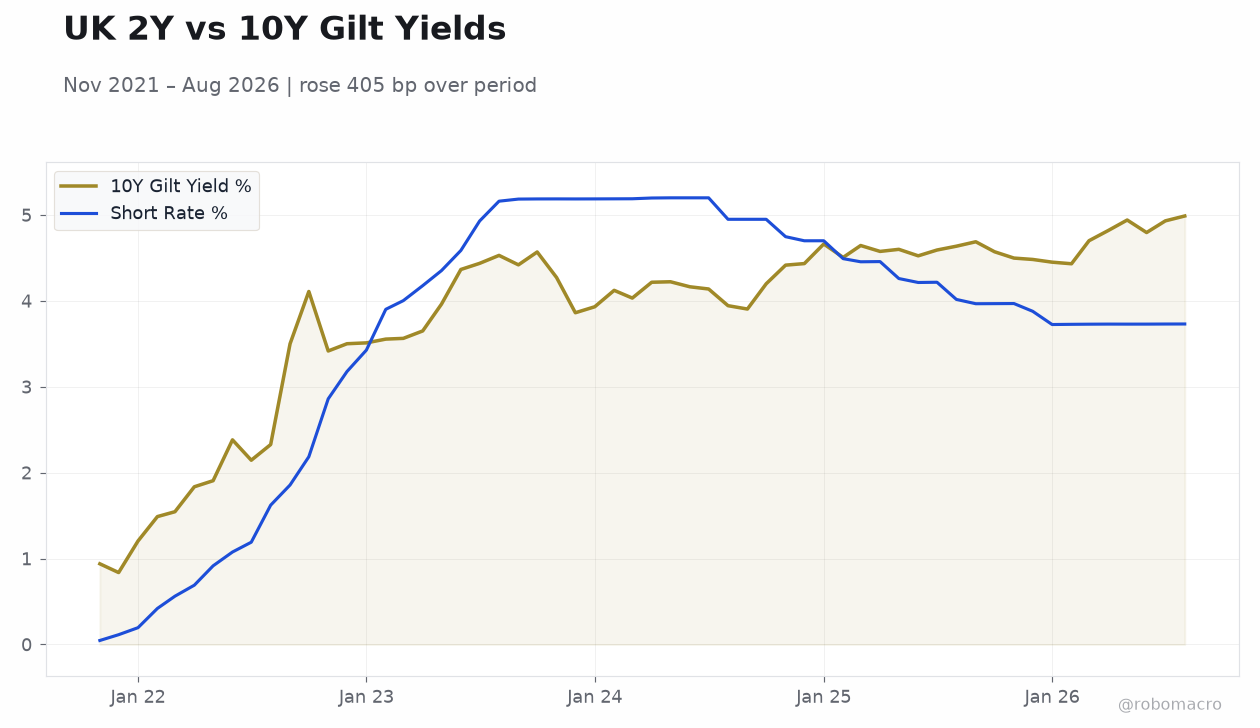 UK 2Y vs 10Y Gilt Yields | Type: macro_line | 10Y Gilt Yield %: 4.989 (2026-08-01) | Range: 0.8375–4.989 | Trend(6pt): 0.9394,3.511,4.033,4.6,4.932,4.989 | Short Rate %: 3.731 (2026-08-01) | Range: 0.0468–5.2 | Trend(6pt): 0.0468,3.428,5.189,4.26,3.731,3.731
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| BoE Pill Speech | - | - | 23:40 |
| BoE Woods Speech | - | - | 23:40 |
| Thursday (2026-10-15) | |||
| GDP Month-over-Month | 0.40 | -0.10 | 02:00 |
| GDP 3-Month Avg | 0.40 | 0.50 | 02:00 |
| Goods Trade Balance | -20,970m | -21,800m | 02:00 |
| Goods Trade Balance Non-EU | -9,660m | - | 02:00 |
| Industrial Production Month-over-Month | 0.20 | -0.10 | 02:00 |
| Manufacturing Production Month-over-Month | 0.90 | -0.10 | 02:00 |
| BoE Cleland Speech | - | - | 03:50 |
- Heavy BoE speaker slate: Bailey, Pill, Breeden, Mann, Dhingra and Greene all took the podium or will this week, keeping policy messaging in focus.
- The 10-year gilt yield eased 3 bp to 5.45% while the 2-year held at 4.69%, with sterling firming 0.46% against the dollar to 1.33.
- Thursday brings GDP, trade balance and industrial production, with consensus looking for a modest monthly contraction of 0.1%.
Yesterday's Recap
UK markets were quiet but constructive on Tuesday. The FTSE 100 closed essentially flat at 10,653.84, down 0.02%, while the FTSE 250 edged up 0.05% to 24,339.20. Sterling was the standout mover, gaining 0.46% to 1.33 against the dollar, though it was little changed against the euro at 1.18.
In fixed income, the 10-year gilt yield slipped 3 bp to 5.45%, a modest rally that suggests demand at the long end persists even as the 2-year held steady at 4.69%. On the data front, the BRC Retail Sales Monitor showed like-for-like sales growth of 1.0% year-over-year, beating both the prior 0.5% and the 0.7% consensus, offering a tentative sign of consumer resilience. The day was dominated by central bank commentary, with Breeden, Mann and Greene all speaking, followed by Dhingra early Wednesday.
Brent crude rose 0.53% to $106.25 and UK natural gas gained 1.07%, keeping energy-driven inflation dynamics alive. Gold was flat at $4,180 and Bitcoin jumped 1.96% to $83,363.
The Day Ahead
Attention turns to Thursday's data dump at 02:00 ET. Monthly GDP is expected to have contracted 0.1% in the latest month after a strong 0.4% prior print, while the three-month average is seen at 0.5%. The goods trade balance is forecast to widen to a deficit of £21.8 billion from £20.97 billion, and industrial production is expected to slip 0.1% after a 0.2% gain, with manufacturing seen matching that decline after a 0.9% rise.
These releases will shape the growth narrative into the Autumn Budget. On the speaker front, Governor Bailey and Pill speak early Thursday, with Pill also appearing late in the session alongside Woods. Any hints on the pace of quantitative tightening or the threshold for further cuts will be parsed closely given the 2s10s spread sits at 76 bp.
Other Economic Notes
The IMF's upgraded UK growth forecast has drawn mixed reactions in the domestic press, with commentary ranging from praise to warnings that positive external assessments often precede slowdowns. ↓ p.2