UK Macro Daily(Beta Mode)
Pill Cautious as GDP Data Loom
Market Snapshot
| Asset | Level | Change |
|---|---|---|
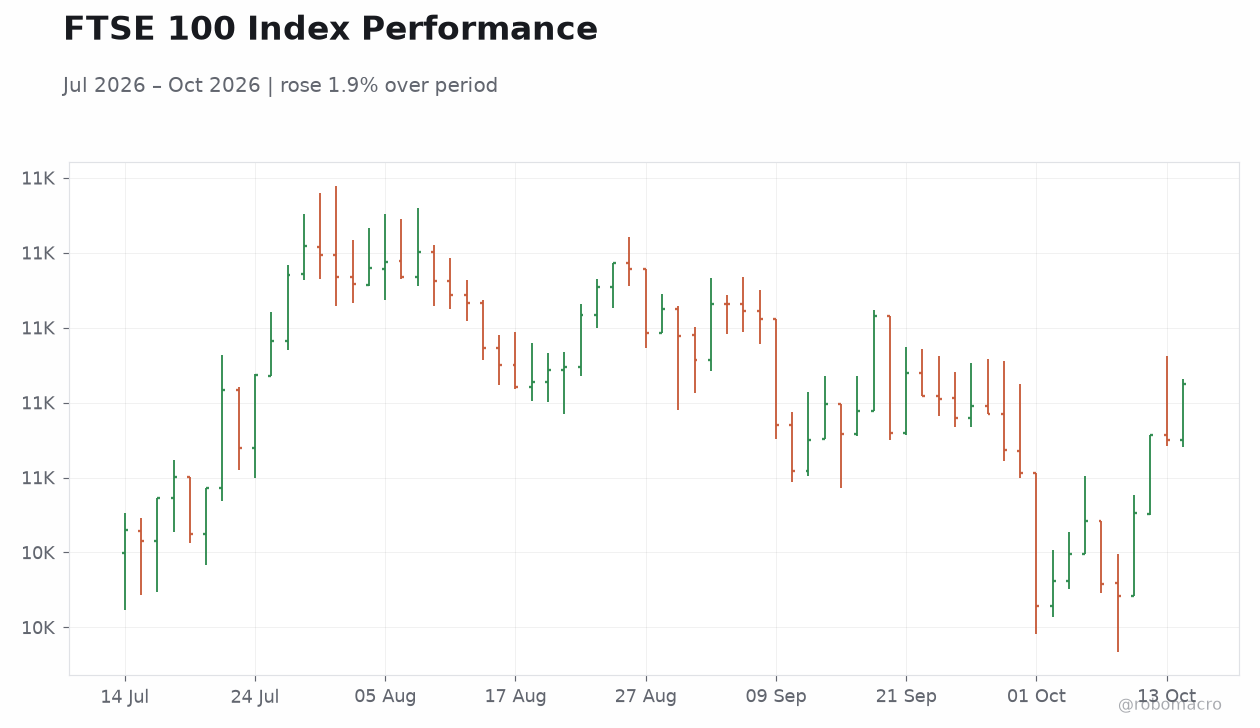
| FTSE 100 | 10,701.83 | +0.48% |
| FTSE 250 | 24,360.80 | +0.09% |
| GBP/USD | 1.32 | -0.11% |
| GBP/EUR | 1.18 | -0.30% |
| GBP/JPY | 209.05 | -0.40% |
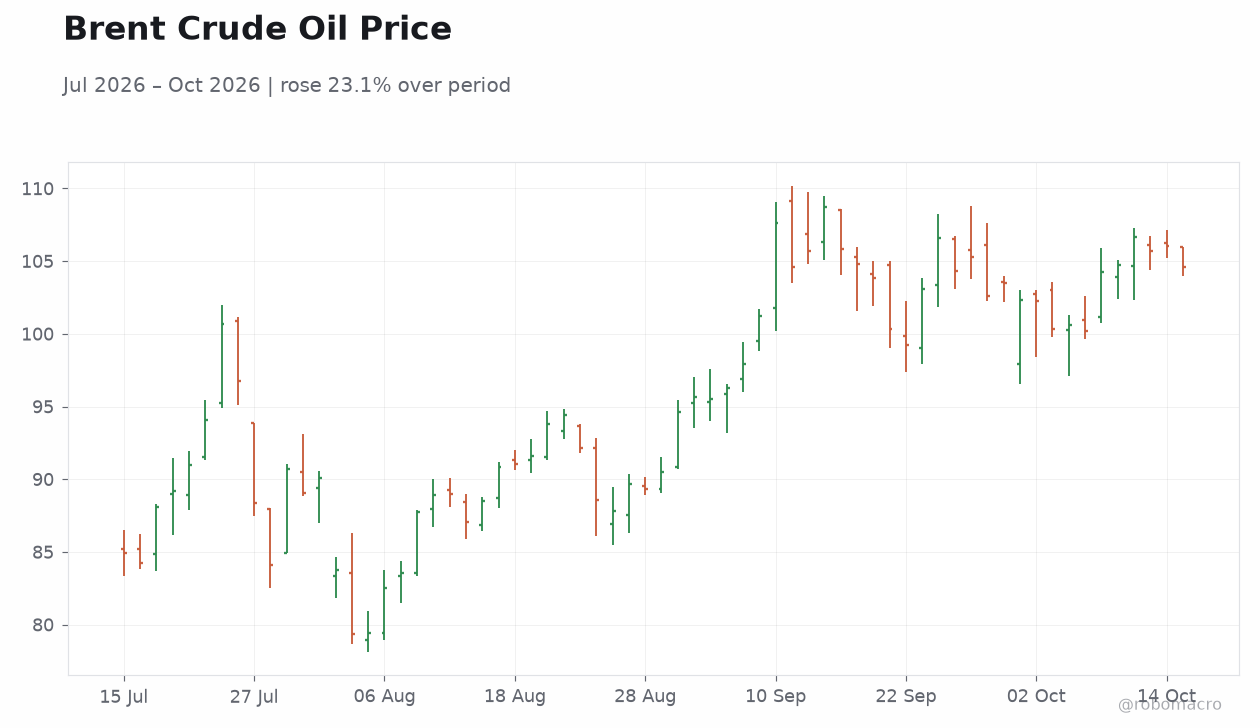
| Brent Crude | 104.50 | -1.47% |
| Gold | 4,161.80 | +1.31% |
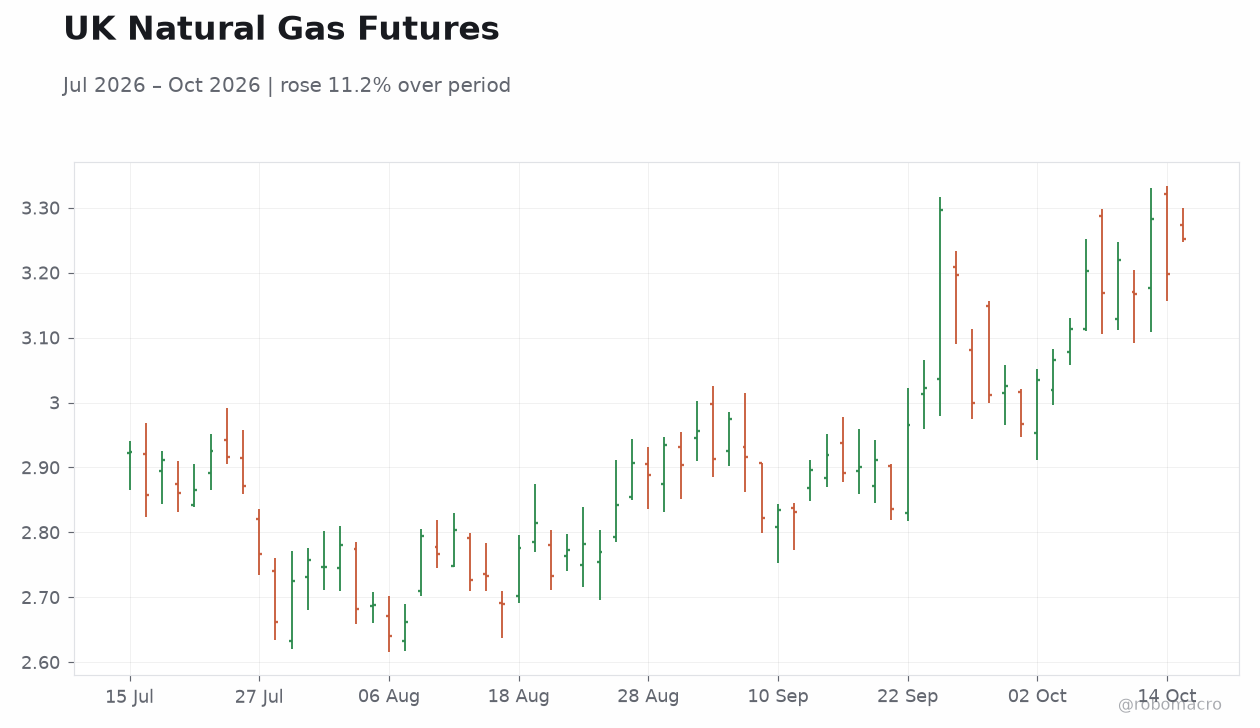
| UK Nat Gas | 3.25 | +1.69% |
| Bitcoin | 80,495.31 | -3.13% |
| UK 2Y Gilt | 4.72% | +3 bp |
| UK 10Y Gilt | 5.43% | -2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BoE Mann Speech | - | - | - |
| BRC Retail Sales Monitor Year-over-Year | 0.50 | 0.70 | 1 |
| BoE Greene Speech | - | - | - |
| BoE Dhingra Speech | - | - | - |
| BoE Breeden Speech | - | - | - |
| BoE Gov Bailey Speech | - | - | - |
| BoE Pill Speech | - | - | - |
| BoE Pill Speech | - | - | - |
| BoE Woods Speech | - | - | - |
| GDP Month-over-Month | 0.40 | -0.10 | - |
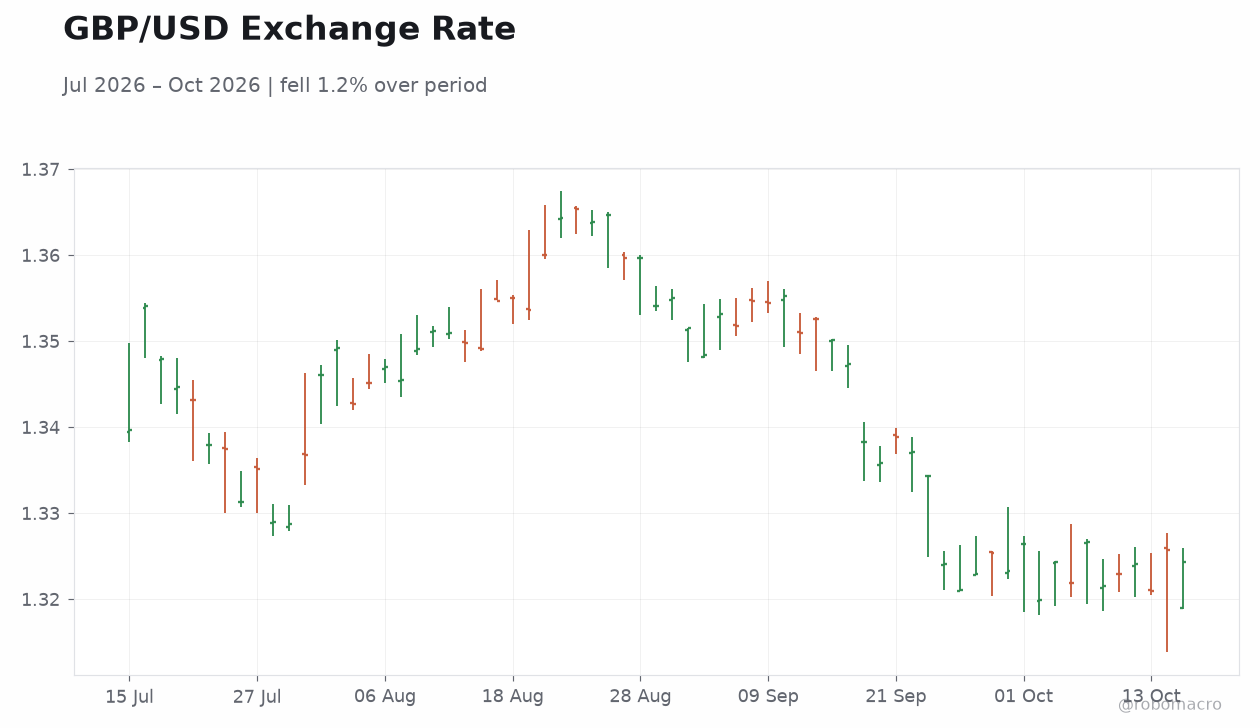 GBP/USD Exchange Rate | Type: market_hloc | GBP/USD: 1.324 (2026-10-15) | Range: 1.32–1.365 | Trend(6pt): 1.34,1.347,1.36,1.339,1.321,1.324
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| BoE Cleland Speech | - | - | 03:50 |
| BoE Breeden Speech | - | - | 04:45 |
| BoE Gov Bailey Speech | - | - | 22:00 |
| Saturday (2026-10-17) | |||
| BoE Gov Bailey Speech | - | - | 02:45 |
- BoE chief economist Pill casts doubt on market pricing of four further rate hikes, urging patience
- Sterling slips against euro and yen; FTSE 100 gains 0.48% as exporters rally
- August GDP, production and trade data due this morning at 09:30 London time
Yesterday's Recap
UK equities closed higher on Wednesday, with the FTSE 100 up 0.48% to 10,701.83 as a softer pound lifted export-heavy sectors. The FTSE 250 edged up 0.09% to 24,360.80. Sterling weakened across the board: GBP/USD slipped 0.11% to 1.32, GBP/EUR fell 0.30% to 1.18 and GBP/JPY lost 0.40% to 209.05.
In fixed income, the 10-year gilt yield eased 2 bp to 5.43% while the two-year rose 3 bp to 4.72%, flattening the front end. On data, the BRC Retail Sales Monitor showed year-over-year sales growth of 1.0%, beating both the prior 0.5% and the 0.7% consensus — a modest comfort on household demand. The speaker roster dominated: Governor Bailey, Chief Economist Pill and Deputy Governor Breeden all appeared, with Pill's scepticism over aggressive market-implied hiking paths the key takeaway.
Brent crude fell 1.47% to $104.50, a mild tailwind for the inflation picture, while gold rallied 1.31% to $4,161.80 and UK natural gas added 1.69%.
The Day Ahead
Today's focus is the August GDP release at 09:30 London time, with month-on-month growth expected at -0.1% versus July's 0.4% print. The three-month average is seen at 0.5%. Industrial production is forecast at -0.1% after a 0.2% prior, and manufacturing production at -0.1% following a strong 0.9% reading.
The goods trade balance is seen at a £21.8 billion deficit, with the non-EU component also due; the prior total shortfall was £20.97 billion. Consensus looks for cooling after July's AI-investment-boosted surge, and an upside surprise would complicate the pre-Budget stagnation narrative. BoE speakers continue in force: Cleland is due at 03:50 London time and Breeden returns at 04:45, with further appearances later in the session.
Any commentary building on Pill's rate-path scepticism will move short-sterling pricing.
Other Economic Notes
The pre-Budget picture is darkening in the consensus view, with several outlets flagging predicted UK declines ahead of the fiscal event — even as the IMF has publicly praised the government's plans to reduce annual borrowing. ↓ p.2