UK Macro Daily(Beta Mode)
BoE Hike Bets Build as Gilts Rally
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| FTSE 100 | 10,729.80 | +0.07% |
| FTSE 250 | 24,795.90 | +1.40% |
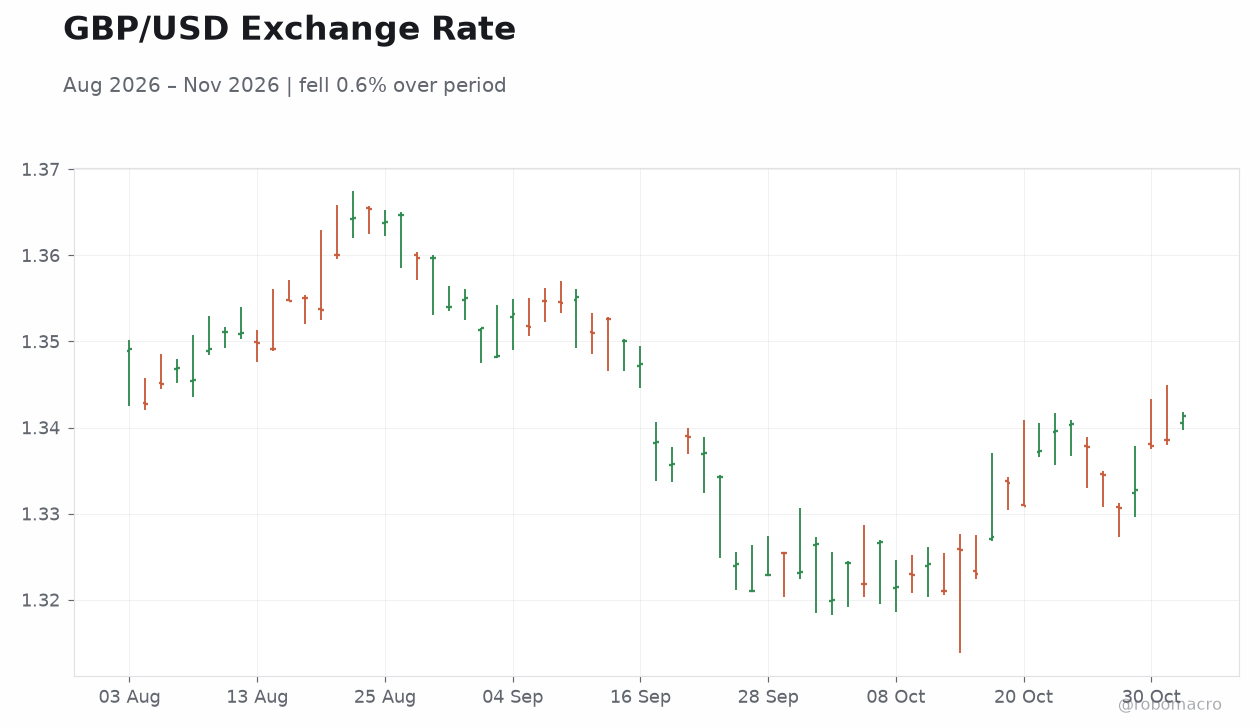
| GBP/USD | 1.34 | +0.21% |
| GBP/EUR | 1.20 | -0.17% |
| GBP/JPY | 211.70 | +0.31% |
| Brent Crude | 105.47 | +0.67% |
| Gold | 3,933.10 | -0.92% |
| UK Nat Gas | 2.88 | +0.67% |
| Bitcoin | 76,479.48 | -2.26% |
| UK 2Y Gilt | 4.68% | -2 bp |
| UK 10Y Gilt | 5.28% | -5 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
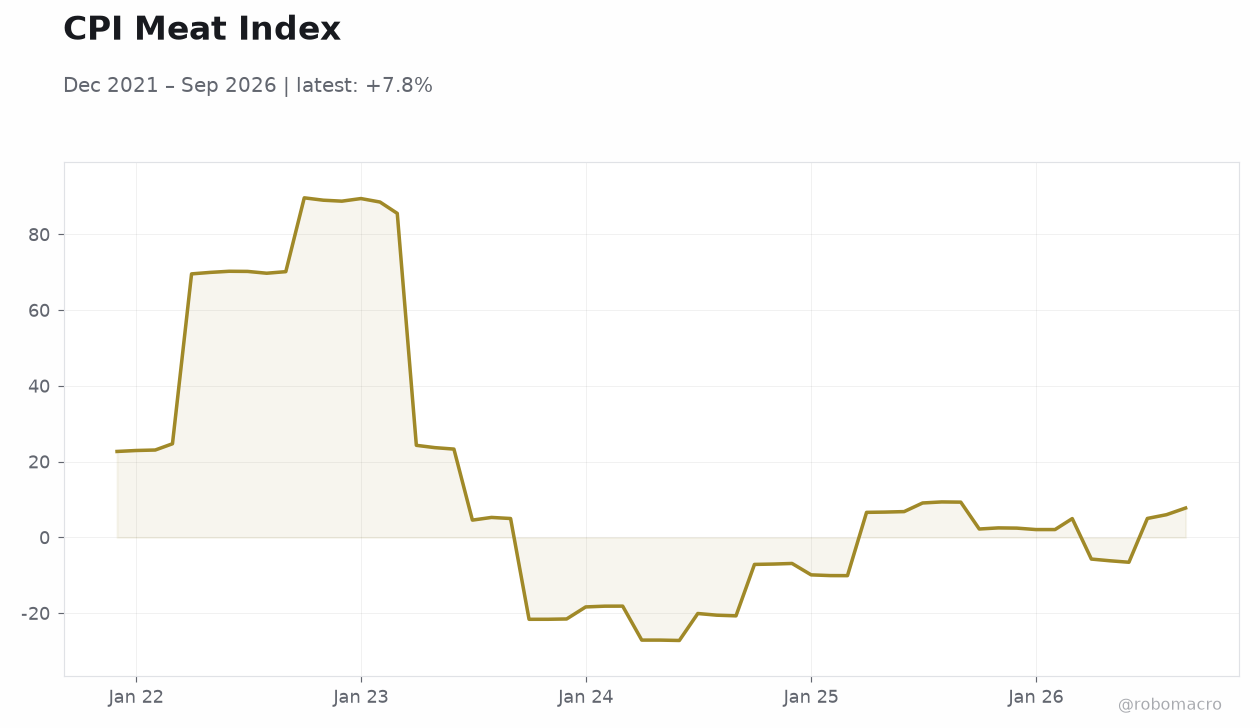 CPI Meat Index | Type: macro_line | CPI Meat YoY (%): 7.764 (2026-09-01) | Range: -27.2–89.65 | Trend(6pt): 22.7,88.54,-27.1,6.821,6.006,7.764
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Thursday (2026-11-05) | |||
| S&P Global Construction PMI | 46.10 | 46.50 | 04:30 |
| BoE Interest Rate Decision | 3.75 | 4 | 07:00 |
| BoE MPC Vote Cut | 0 | - | 07:00 |
| BoE MPC Vote Hike | 3 | - | 07:00 |
| BoE MPC Vote Unchanged | 6 | - | 07:00 |
| BoE Monetary Policy Report | - | - | 07:00 |
| MPC Meeting Minutes | - | - | 07:00 |
| Friday (2026-11-06) | |||
| Lloyds House Price Index Month-over-Month | 0 | 0.10 | 02:00 |
- BoE expected to raise Bank Rate from 3.75% to 4.00% on Thursday, the first hike since 2023, with markets focused on guidance for further tightening.
- Gilt curve rallied despite hike expectations: 10-year yield eased 5 bp to 5.28%, 2-year down 2 bp to 4.68%.
- Sterling firm at 1.34 versus USD; FTSE 250 outperformed (+1.40%) while energy-driven inflation pressures mount.
Yesterday's Recap
No UK data releases were scheduled for Monday 2 November, leaving markets to position ahead of Thursday's Bank of England decision. Gilts rallied across the curve, with the 10-year yield easing 5 bp to 5.28% and the 2-year down 2 bp to 4.68% — a move that sits awkwardly with imminent tightening, suggesting investors are pricing a "one-and-done" hike rather than a sustained cycle. Sterling drifted higher against the dollar to 1.34 (+0.21%) but slipped versus the euro to 1.20 (-0.17%), reflecting softer eurozone dynamics.
The FTSE 250 jumped 1.40% to 24,795.90, outperforming the FTSE 100's marginal 0.07% gain to 10,729.80, though bank shares remained under pressure following the Budget's bank tax increase. Brent crude firmed 0.67% to $105.47, keeping energy-driven inflation firmly in focus, while gold fell 0.92% to $3,933.10.
The Day Ahead
The UK calendar is empty on Tuesday 3 November and Wednesday 4 November, with attention fixed squarely on Thursday's BoE Interest Rate Decision, Monetary Policy Report and MPC Minutes at 07:00. Consensus points to a 25 bp increase to 4.00%, though the vote split remains unknown and will be scrutinised for the balance between hawks and holdouts. The accompanying Monetary Policy Report will be critical for judging the committee's inflation path and whether further hikes are signalled.
Thursday also brings the S&P Global Construction PMI (consensus 46.5, previous 46.1). Friday sees the Lloyds House Price Index and a high-impact BoE Pill speech at 07:15.
Other Economic Notes
UK CPI stands at 3.50% year-on-year as of September, with energy-driven inflation forcing tighter policy and warnings it could reach 5% this winter. Unemployment at 4.70% remains contained, but manufacturers report being battered by rising costs, squeezing margins as input prices climb. The Budget's modest fiscal loosening — funded partly by a bank tax increase — has done little to shift voter expectations for the economy, and bank shares have borne the brunt.
Housing activity remains fragile, with construction PMI stuck in contraction territory below 50. The stagflationary mix of elevated inflation, weak activity and rising costs leaves the MPC walking a narrow path.