UK Macro Daily(Beta Mode)
BoE Hike Looms as Gilt Yields Hold
Market Snapshot
| Asset | Level | Change |
|---|---|---|
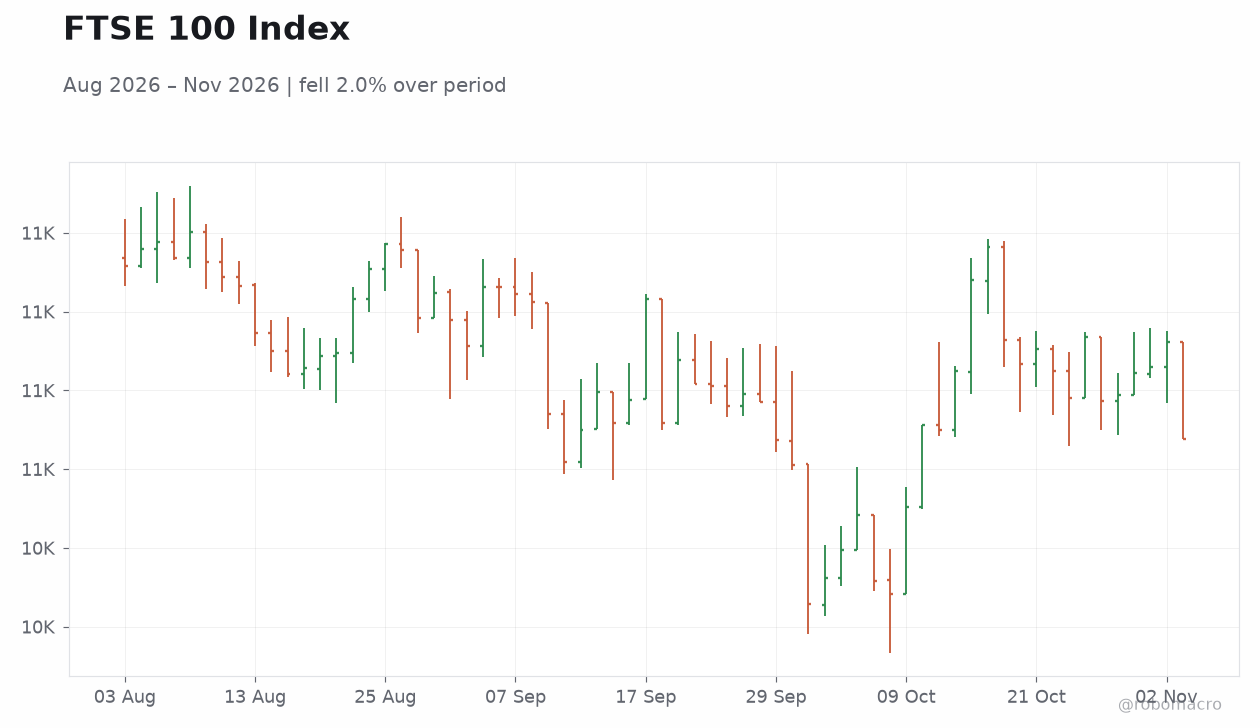
| FTSE 100 | 10,638.43 | -1.14% |
| FTSE 250 | 24,674.90 | -0.49% |
| GBP/USD | 1.35 | +0.38% |
| GBP/EUR | 1.20 | -0.06% |
| GBP/JPY | 212.70 | +0.45% |
| Brent Crude | 103.51 | -0.09% |
| Gold | 4,007.60 | +1.71% |
| UK Nat Gas | 2.88 | -0.52% |
| Bitcoin | 77,706.91 | +1.34% |
| UK 2Y Gilt | - | - |
| UK 10Y Gilt | 5.28% | 0 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
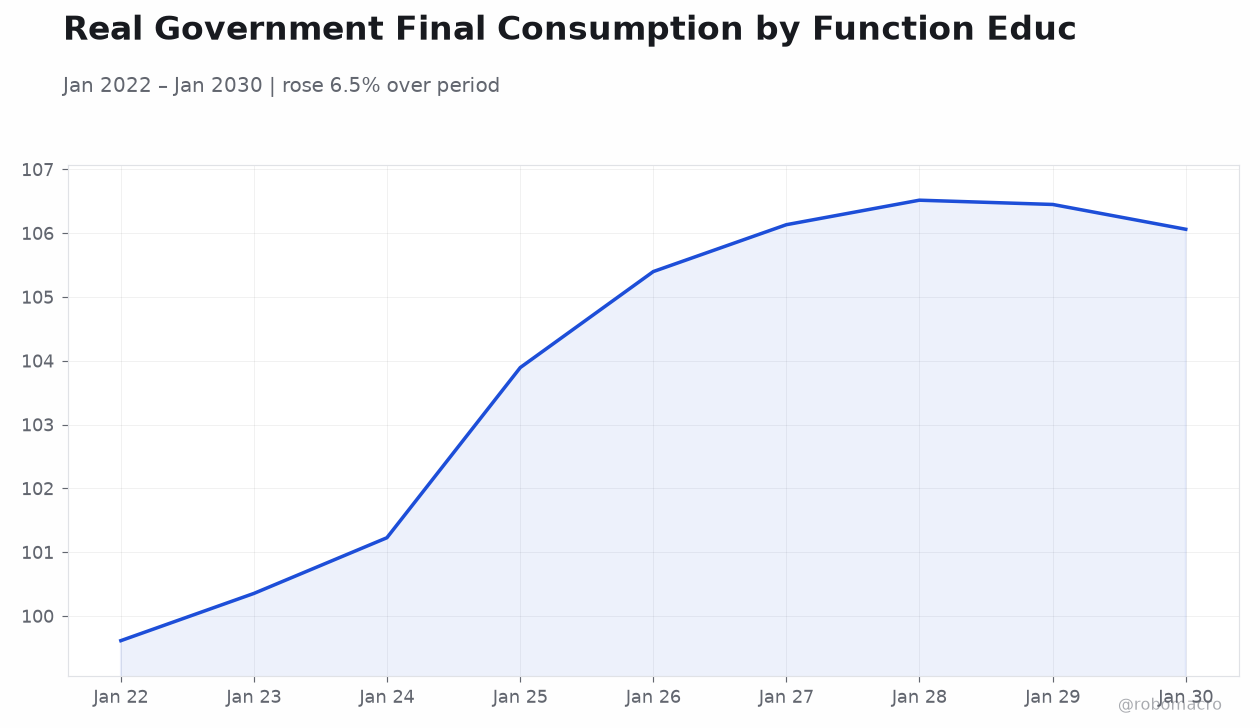
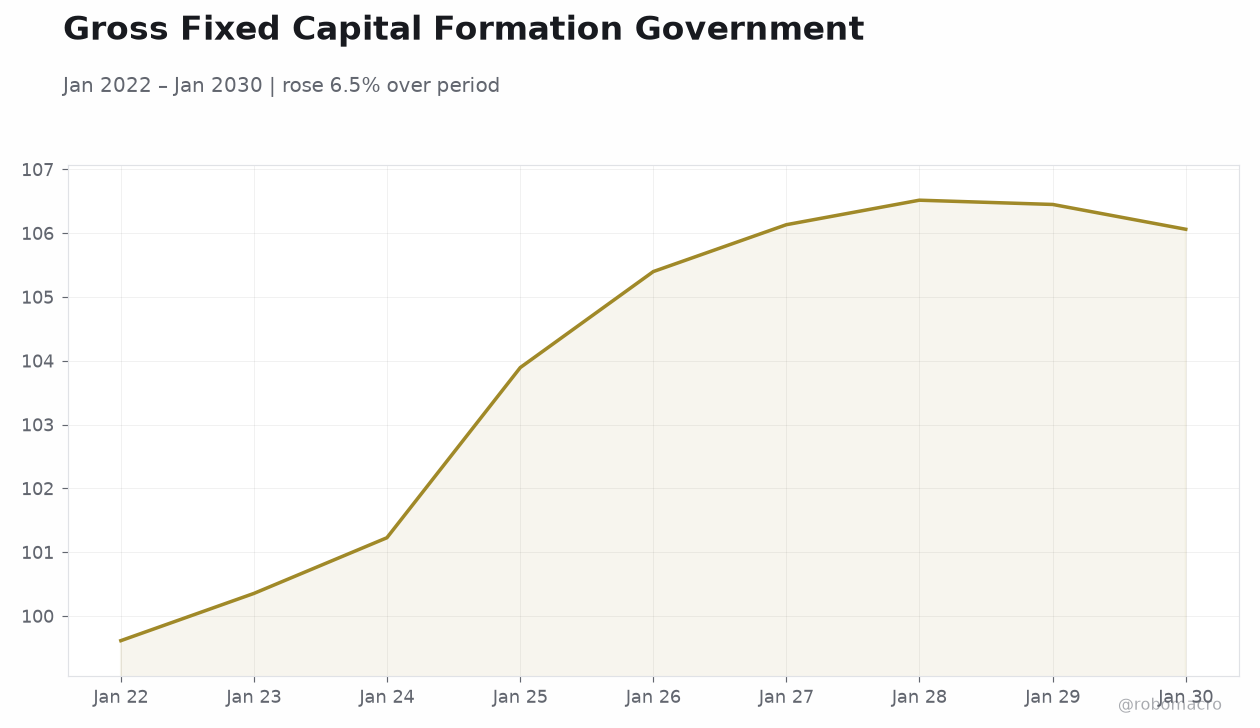 Gross Fixed Capital Formation Government | Type: macro_line | Gross Fixed Capital Formation Government: 106.1 (2030-01-01) | Range: 99.61–106.5 | Trend(5pt): 99.61,101.2,105.4,106.5,106.1
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Thursday (2026-11-05) | |||
| S&P Global Construction PMI | 46.10 | 46.50 | 04:30 |
| BoE Interest Rate Decision | 3.75 | 4 | 07:00 |
| BoE MPC Vote Cut | 0 | - | 07:00 |
| BoE MPC Vote Hike | 3 | - | 07:00 |
| BoE MPC Vote Unchanged | 6 | - | 07:00 |
| BoE Monetary Policy Report | - | - | 07:00 |
| MPC Meeting Minutes | - | - | 07:00 |
| Friday (2026-11-06) | |||
| Lloyds House Price Index Month-over-Month | 0 | 0.10 | 02:00 |
- BoE expected to raise Bank Rate to 4.00% on Thursday from 3.75%, with markets pricing further tightening beyond this meeting
- Sterling firm near 1.35 versus USD as UK-EU trade breakthrough supports GBP sentiment
- FTSE 100 fell 1.14% to 10,638 as risk appetite soured; gold surged 1.71% to $4,007.60
Yesterday's Recap
UK markets delivered a mixed session on Tuesday, with the FTSE 100 shedding 1.14% to close at 10,638.43 while the mid-cap FTSE 250 slipped 0.49% to 24,674.90. Sterling outperformed, with GBP/USD rising 0.38% to 1.35 and GBP/JPY climbing 0.45% to 212.70, though GBP/EUR edged 0.06% lower to 1.20. The UK 10-year gilt yield held steady at 5.28%, unchanged on the day, reflecting cautious positioning ahead of Thursday's Bank of England decision.
Brent crude was broadly flat at $103.51, down 0.09%, while UK natural gas eased 0.52% to 2.88. Gold rallied sharply, gaining 1.71% to $4,007.60, signalling persistent demand for defensive assets. No UK data releases were scheduled for the session, leaving markets to trade on positioning and external risk factors.
The Day Ahead
Attention turns to Thursday's packed UK calendar, headlined by the Bank of England interest rate decision at 07:00 ET, where consensus points to a hike to 4.00% from 3.75%. The accompanying Monetary Policy Report and MPC meeting minutes will be scrutinised for the committee's forward guidance and any signals on the pace of subsequent tightening. Earlier, S&P Global Construction PMI for November is due at 04:30 ET, with consensus at 46.5 versus a prior 46.1 — still firmly in contraction territory.
Friday brings the Lloyds House Price Index at 02:00 ET, with month-over-month consensus at 0.1% following a flat prior reading, alongside a high-impact speech from BoE's Pill at 07:15 ET. Markets will parse Pill's remarks for clues on the terminal rate path.
Other Economic Notes
The UK housing market remains a key transmission channel for monetary policy, with mortgage lenders including Nationwide, Barclays and Halifax cutting rates despite the imminent BoE hike — a sign that competition and expectations of a peak in Bank Rate are feeding through to retail pricing. Construction activity continues to lag, with the PMI stuck well below the 50 threshold, underscoring weakness in commercial and residential building. UK CPI at 3.50% remains materially above target, keeping the MPC's credibility under pressure.
The labour market shows unemployment at 4.70%, a level that suggests some softening but not outright deterioration. Sterling's resilience despite equity weakness points to rate-differential support.