UK Macro Daily(Beta Mode)
BoE Set to Hike as Gilts Diverge
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| FTSE 100 | 10,829.21 | +1.79% |
| FTSE 250 | 24,915.70 | +0.98% |
| GBP/USD | 1.35 | +0.42% |
| GBP/EUR | 1.20 | -0.08% |
| GBP/JPY | 213.00 | +0.06% |
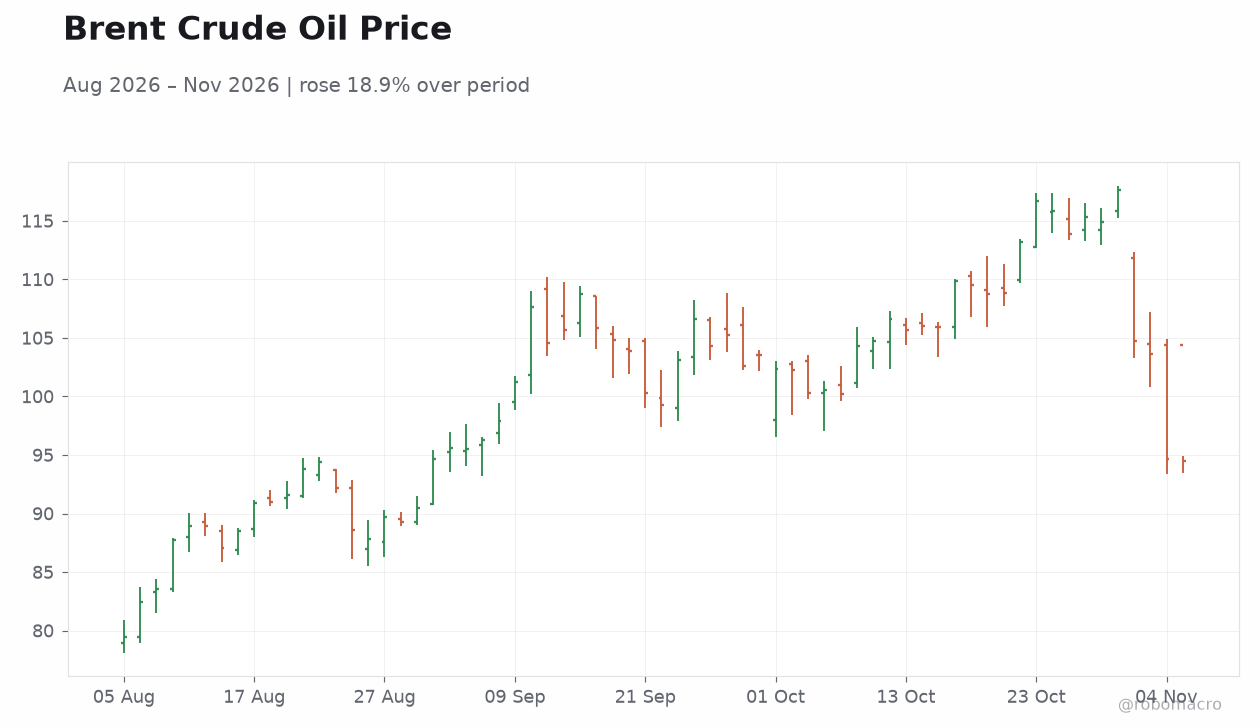
| Brent Crude | 94.58 | -0.04% |
| Gold | 4,123.60 | +1.24% |
| UK Nat Gas | 2.95 | -0.37% |
| Bitcoin | 80,351.75 | +3.89% |
| UK 2Y Gilt | 4.64% | +2 bp |
| UK 10Y Gilt | 5.18% | -10 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
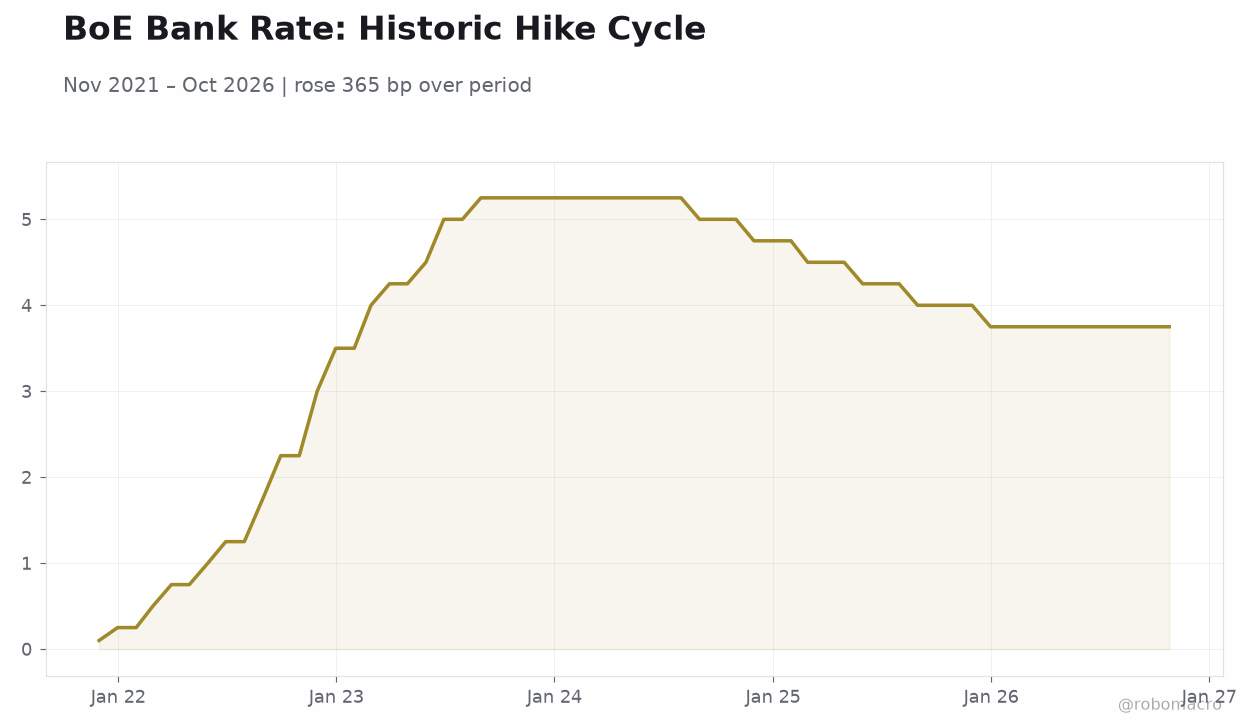 BoE Bank Rate: Historic Hike Cycle | Type: macro_line | Bank Rate (%): 3.75 (2026-10-26) | Range: 0.1–5.25 | Trend(5pt): 0.1,4,5.25,4,3.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| S&P Global Construction PMI | 46.10 | 46.50 | 04:30 |
| BoE Interest Rate Decision | 3.75 | 4 | 07:00 |
| BoE MPC Vote Cut | 0 | - | 07:00 |
| BoE MPC Vote Hike | 3 | - | 07:00 |
| BoE MPC Vote Unchanged | 6 | - | 07:00 |
| BoE Monetary Policy Report | - | - | 07:00 |
| MPC Meeting Minutes | - | - | 07:00 |
- BoE expected to raise Bank Rate to 4.00% from 3.75%, the first hike in over three years, with the Monetary Policy Report and minutes due alongside.
- Sterling at a seven-week high near 1.35 versus the dollar as markets position for a historic rate call.
- UK 10-year gilt yield eased 10 bp to 5.18% while the 2-year edged up 2 bp to 4.64%, steepening pressure across the curve.
Yesterday's Recap
No UK data releases were scheduled for 4 November, leaving markets to trade on positioning ahead of today's Bank of England decision. The FTSE 100 rallied 1.79% to 10,829.21 and the FTSE 250 added 0.98% to 24,915.70, with risk appetite supported by firmer global equities. Sterling gained 0.42% against the dollar to 1.35, a seven-week high, while GBP/EUR slipped 0.08% to 1.20.
Gilt markets diverged sharply: the 10-year yield fell 10 bp to 5.18% as of 2 November, while the 2-year rose 2 bp to 4.64% as of 3 November, steepening the curve. Gold jumped 1.24% to $4,123.60 and Bitcoin rose 3.89% to $80,351.75, signalling broad risk-on sentiment. Brent crude was flat at $94.58, down 0.04%.
The Day Ahead
The S&P Global Construction PMI for November prints at 04:30 ET, with consensus at 46.5 versus a previous 46.1, still deep in contraction territory. The main event is the BoE Interest Rate Decision at 07:00 ET, where consensus points to a hike to 4.00% from 3.75%, alongside the Monetary Policy Report and MPC Meeting Minutes. The vote split will be scrutinised for the balance between hike, hold and cut preferences.
Tomorrow brings the Lloyds House Price Index at 02:00 ET, with month-over-month consensus at 0.1% versus a flat previous reading, followed by a high-impact BoE Pill speech at 07:15 ET.
Other Economic Notes
UK CPI stands at 3.50% year-over-year as of 30 September, well above target and the core justification for today's expected hike. Unemployment is 4.70% as of 31 July, a labour market that remains relatively tight by historical standards. Mortgage repayments have surged roughly 60% according to industry coverage, amplifying the transmission of higher rates to household balance sheets.
The construction PMI consensus of 46.5 underscores persistent weakness in housing-adjacent activity even as services growth reportedly strengthens the case for tightening. The tension between a slowing real economy and sticky inflation defines the policy dilemma.