UK Macro Daily(Beta Mode)
Bailey Flags AI Supply Shock as GDP Eyed
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| FTSE 100 | 10,673.90 | -1.01% |
| FTSE 250 | 24,706.30 | +0.82% |
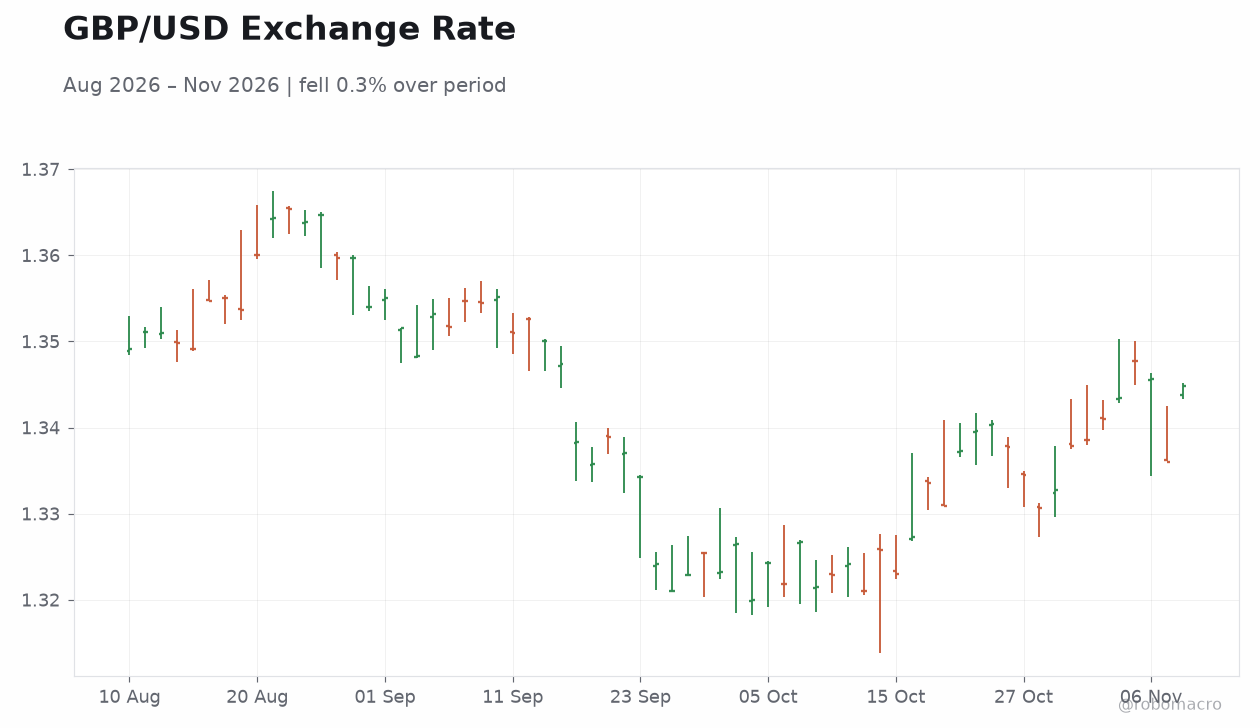
| GBP/USD | 1.34 | +0.66% |
| GBP/EUR | 1.20 | -0.10% |
| GBP/JPY | 212.51 | +0.49% |
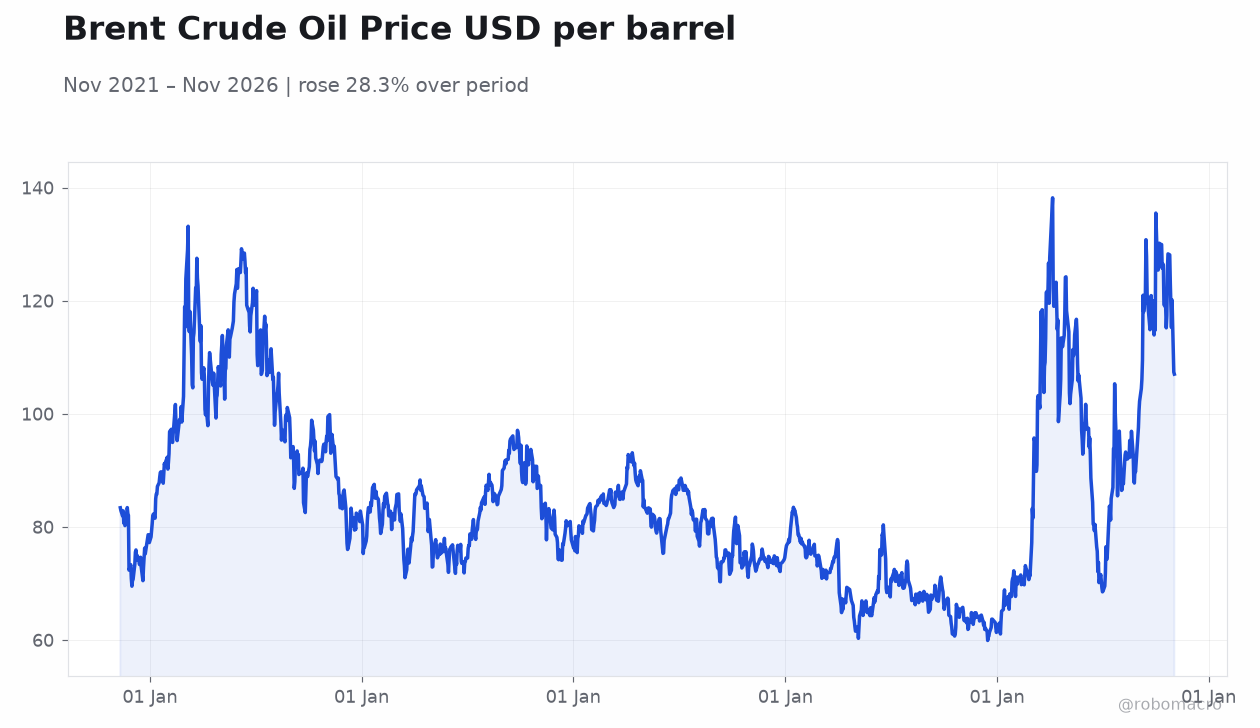
| Brent Crude | 91.74 | -0.90% |
| Gold | 4,130.60 | +0.39% |
| UK Nat Gas | 3.24 | +0.59% |
| Bitcoin | 74,647.70 | +0.08% |
| UK 2Y Gilt | 4.57% | 0 bp |
| UK 10Y Gilt | 5.13% | -2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BoE Gov Bailey Speech | - | - | - |
| BRC Retail Sales Monitor Year-over-Year | 1 | 1.20 | - |
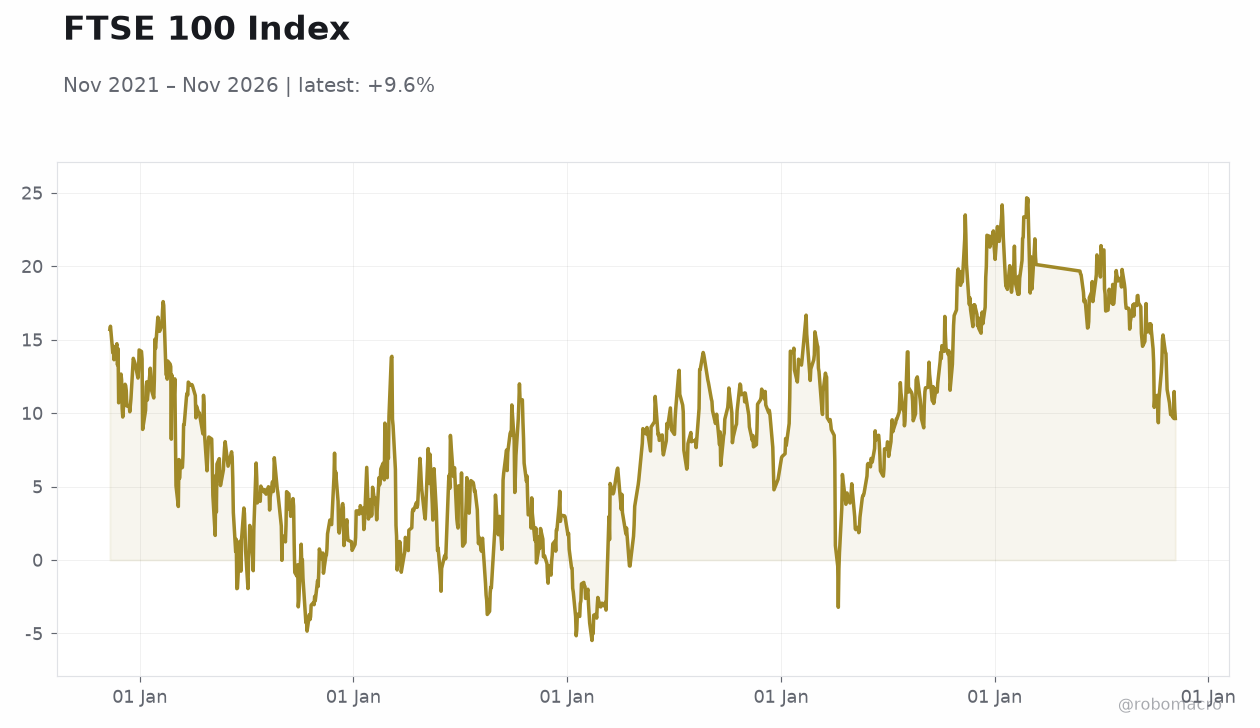 FTSE 100 Index | Type: macro_line | FTSE 100 Index: 9.636 (2026-11-06) | Range: -5.477–24.66 | Trend(6pt): 15.7,1.066,-3.952,9.329,10.29,9.636
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| BoE Lombardelli Speech | - | - | 07:30 |
| BoE Pill Speech | - | - | 13:30 |
| Wednesday (2026-11-11) | |||
| RICS House Price Balance | -32 | -32 | 19:01 |
| Thursday (2026-11-12) | |||
| GDP Growth Quarter-over-Quarter Preliminary | 0.50 | 0.70 | 02:00 |
| GDP Growth Year-over-Year Preliminary | 1.40 | 1.90 | 02:00 |
| GDP Month-over-Month | 0.10 | 0 | 02:00 |
| Business Investment Quarter-over-Quarter Prel | 1.80 | - | 02:00 |
| GDP 3-Month Avg | 0.70 | 0.70 | 02:00 |
- BoE Governor Bailey used his Zurich speech to flag early signs of an AI-driven positive supply shock while warning overvalued AI stocks pose financial-stability risk
- Sterling firmed 0.66% to 1.34 against the dollar as markets position for Thursday's preliminary Q3 GDP, with consensus at 0.7% q/q versus 0.5% prior
- Gilt curve steepened modestly, 10-year easing 2 bp to 5.13% while 2-year held at 4.57%, ahead of two high-impact BoE speeches today
Yesterday's Recap
Monday's UK session was dominated by Bank of England Governor Andrew Bailey's SIAF lecture in Zurich, where he argued central bank independence remains essential and highlighted early evidence of an AI-driven positive supply shock, while cautioning that stretched AI equity valuations could trigger a bubble. No hard UK data printed, leaving markets to trade the policy tone. Sterling outperformed, GBP/USD rising 0.66% to 1.34 and GBP/JPY gaining 0.49% to 212.51, while GBP/EUR slipped 0.10% to 1.20.
The FTSE 100 fell 1.01% to 10,673.90, weighed by energy weakness as Brent crude dropped 0.90% to $91.74, though the domestically-focused FTSE 250 rose 0.82% to 24,706.30. Gilts were steady to firmer, with the 10-year yield easing 2 bp to 5.13% and the 2-year unchanged at 4.57%. Gold added 0.39% to $4,130.60 and UK natural gas edged up 0.59% to 3.24.
The Day Ahead
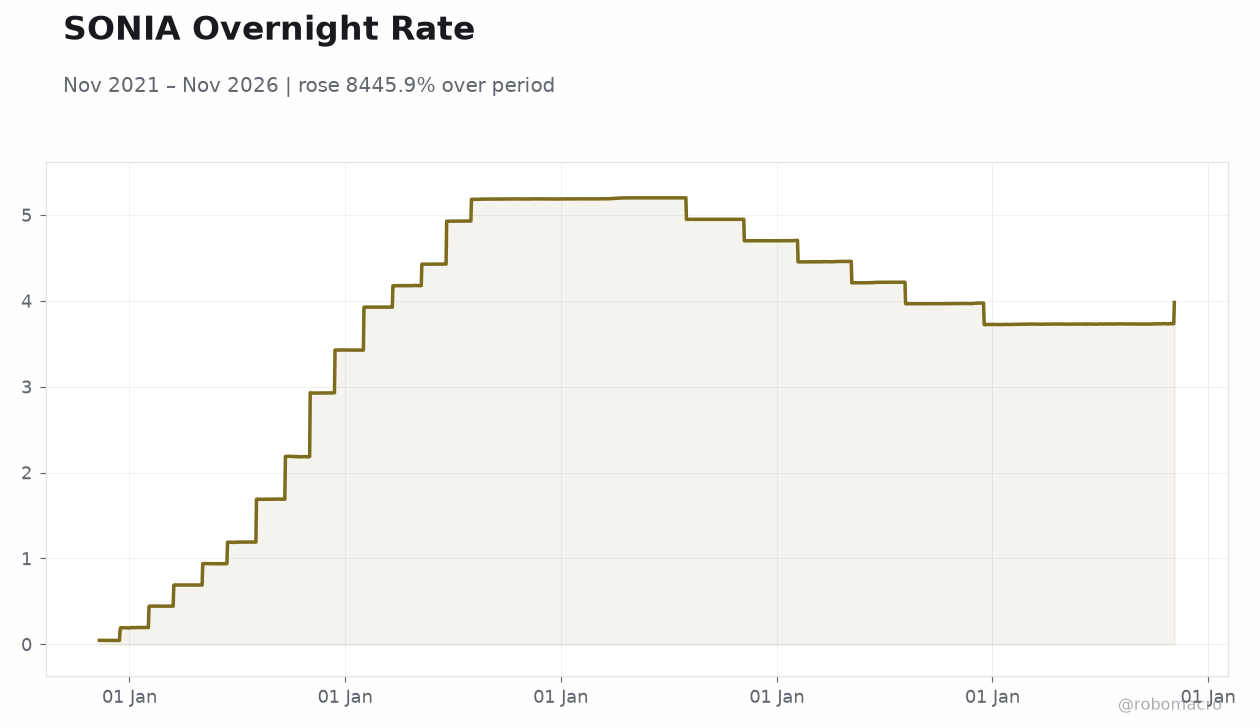
Two high-impact BoE appearances anchor today's calendar, with MPC member Lombardelli speaking at 07:30 ET and Chief Economist Pill at 13:30 ET — both will be scrutinised for signals on the December 17 decision path after the Bank Rate was set at 4.00% on November 5. No tier-one UK data releases are scheduled, so flow will be driven by policy commentary and positioning ahead of Thursday's GDP block. Wednesday brings the BRC retail sales monitor and RICS house price balance, with the latter expected to hold at -32, still deep in contractionary territory.
Thursday's preliminary Q3 GDP is the week's pivotal print, with consensus at 0.7% q/q and 1.9% y/y against 0.5% and 1.4% prior respectively, alongside monthly GDP, business investment, industrial production and the goods trade balance.
Other Economic Notes
The UK backdrop remains stagflationary in character, with CPI at 3.50% as of September and unemployment at 4.70%, well above target and inconsistent with rapid easing. Thursday's GDP consensus of 0.7% q/q would mark a meaningful acceleration from 0.5%, but monthly GDP is expected flat at 0.0% and industrial production is forecast to contract 0.4% m/m, suggesting momentum is uneven. ↓ p.2