US Macro Daily(Beta Mode)
Manufacturing Rebounds, Services PMI Eyed
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,568.92 | +0.36% |
| Nasdaq 100 | 28,180.26 | +0.68% |
| Dow Jones | 51,786.72 | -0.38% |
| Russell 2000 | 2,812.45 | +0.23% |
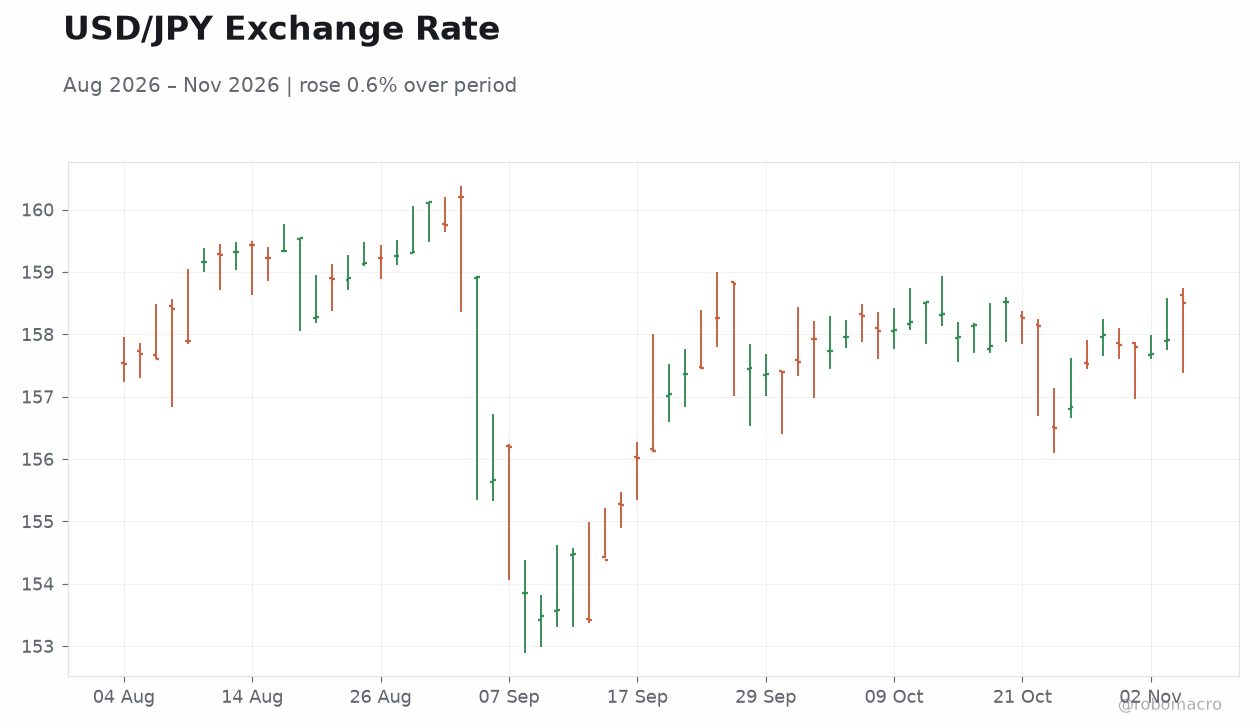
| USD/JPY | 158.51 | +0.37% |
| EUR/USD | 1.13 | +0.54% |
| GBP/USD | 1.35 | +0.52% |
| Gold | 4,053.80 | +2.88% |
| WTI Crude | 95.24 | -0.88% |
| Bitcoin | 78,566.49 | +1.58% |
| US 2Y Treasury | 4.61% | +2 bp |
| US 10Y Treasury | 4.95% | +4 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
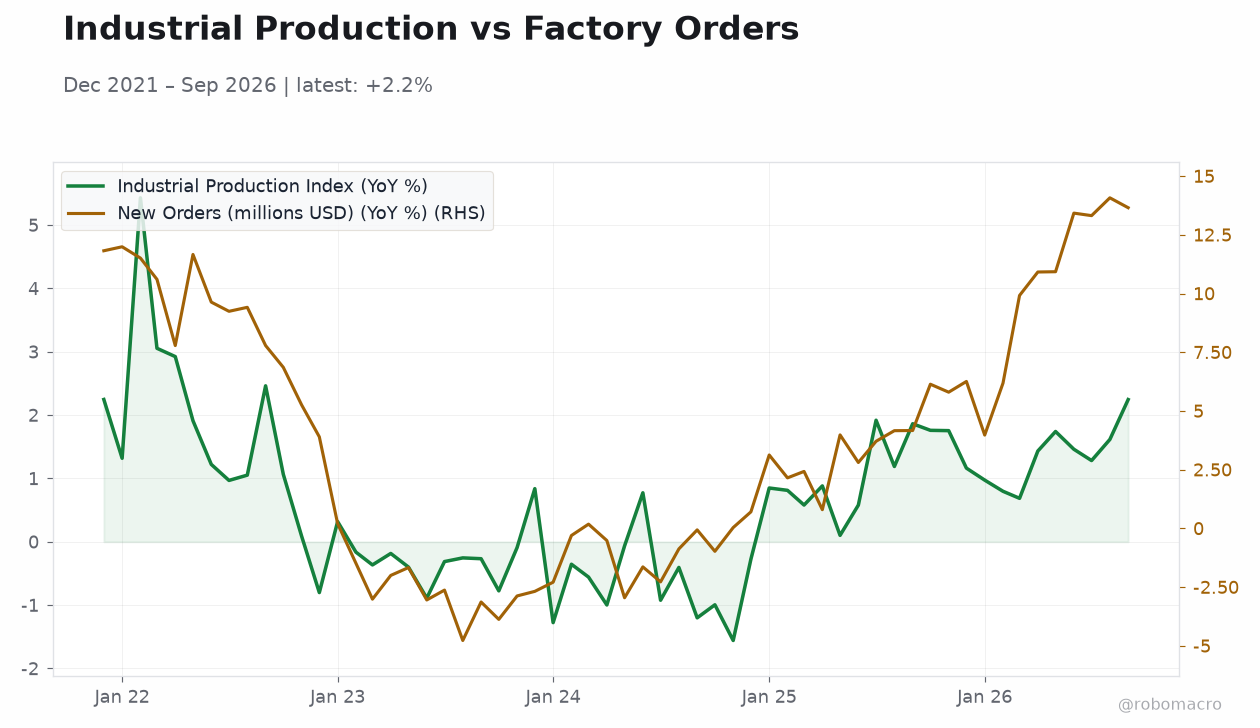
| ISM Manufacturing PMI | 54.50 | 54.60 | 55.50 |
| ISM Manufacturing Employment | 52.70 | - | 52.40 |
| Fed Goolsbee Speech | - | - | - |
| Atlanta Fed GDPNow | 3.20 | - | 3.70 |
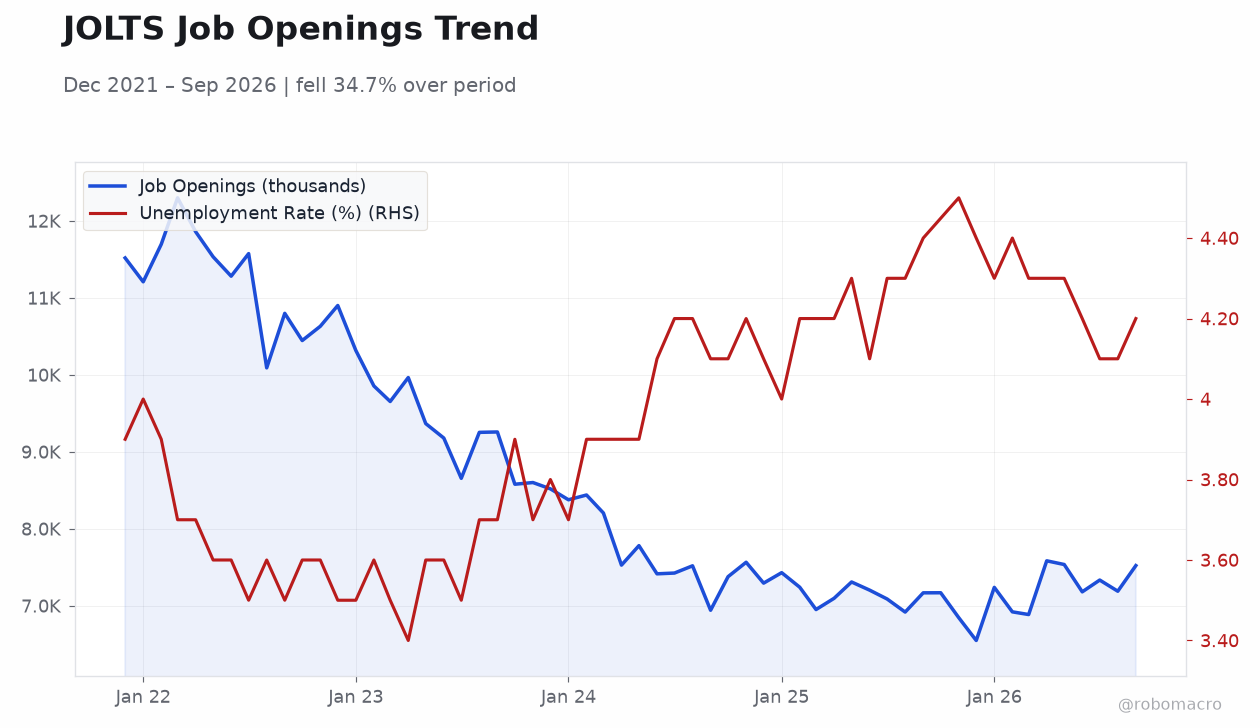
| JOLTs Job Openings | 7.2m | 7.1m | 7.5m |
| Factory Orders Month-over-Month | 0.30 | 1.20 | 1.80 |
| API Weekly Crude Oil Stocks | -2.0m | 2.1m | -5.3m |
| API Weekly Crude Oil Stocks | -2.0m | 2.1m | -5.3m |
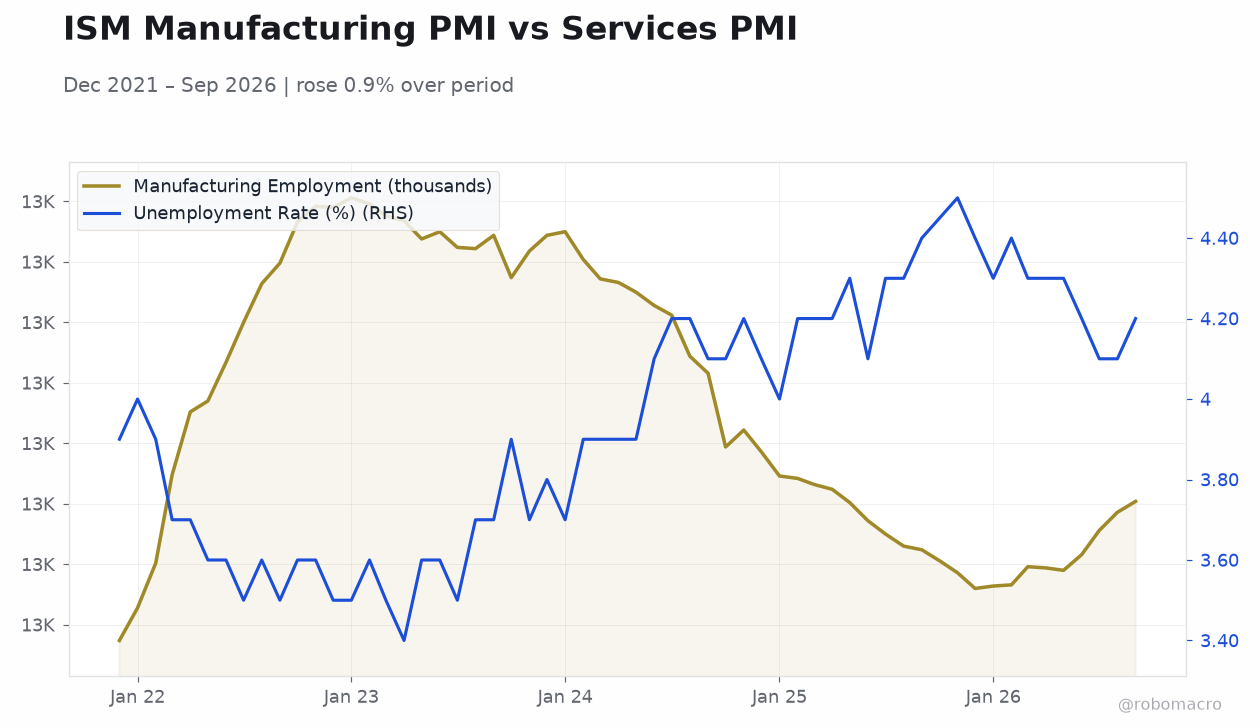 ISM Manufacturing PMI vs Services PMI | Type: macro_line | Manufacturing Employment (thousands): 1.265e+04 (2026-09-01) | Range: 1.254e+04–1.29e+04 | Trend(6pt): 1.254e+04,1.29e+04,1.283e+04,1.264e+04,1.264e+04,1.265e+04 | Unemployment Rate (%): 4.2 (2026-09-01) | Range: 3.4–4.5 | Trend(5pt): 3.9,3.6,3.9,4.1,4.2
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| MBA 30-Year Mortgage Rate | 7.37 | - | 07:00 |
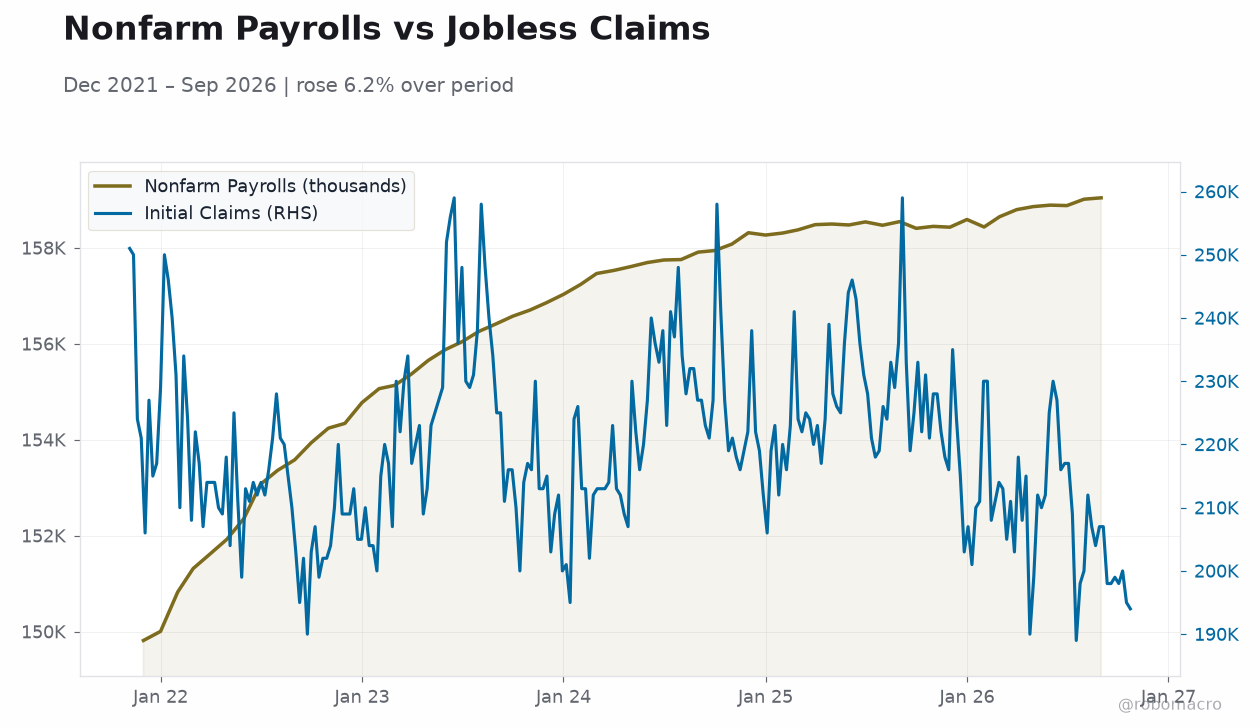
| ADP Employment Change | 90,000 | 69,000 | 08:15 |
| Exports Level | 315,200m | - | 08:30 |
| Imports Level | 420,800m | - | 08:30 |
| Trade Balance | -105,600m | -108,000m | 08:30 |
| Services Sector PMI | 54.90 | 54.80 | 10:00 |
| EIA Weekly Crude Oil Inventory | -1.9m | -1.7m | 10:30 |
| EIA Weekly Gasoline Inventory | 3.9m | - | 10:30 |
- ISM Manufacturing PMI jumped to 55.5, beating consensus of 54.6 and up from 54.5 prior, signaling accelerating factory activity
- JOLTs job openings surged to 7.523 million versus 7.1 million expected, pointing to resilient labor demand
- Gold rallied 2.88% to $4,053.80 while the 10-year Treasury yield climbed 4 bp to 4.95%, reflecting inflation hedging amid strong data
Yesterday's Recap
US manufacturing activity accelerated, with ISM Manufacturing PMI printing at 55.5 against a 54.6 consensus and 54.5 prior reading, while the employment subindex eased modestly to 52.4 from 52.7. Factory Orders rose 1.8% month-over-month, well above the 1.2% consensus and the prior 0.3% gain, suggesting capital goods demand remains firm. The labor market showed unexpected tightness as JOLTs job openings climbed to 7.523 million versus 7.1 million expected, reversing the prior 7.19 million reading.
Atlanta Fed GDPNow was revised up to 3.7% from 3.2%, reinforcing the narrative of above-trend growth. Equity markets were mixed: the S&P 500 added 0.36% to 7,568.92 and Nasdaq 100 gained 0.68%, while the Dow slipped 0.38%. Treasuries sold off, with the 2-year yield rising 2 bp to 4.61% and the 10-year up 4 bp to 4.95%.
Gold surged 2.88% to $4,053.80, and API data showed a crude draw of 5.267 million barrels versus expectations for a 2.1 million build.
The Day Ahead
Markets turn to the ISM Services PMI at 10:00 ET, with consensus at 54.8 versus the prior 54.9, a key read on whether service-sector momentum is holding after the manufacturing upside surprise. ADP Employment Change at 08:15 ET is expected at 69,000, down from the prior 90,000, offering a preview ahead of Friday's payrolls report. The trade balance is due at 08:30 ET, with consensus at -$108.0 billion versus -$105.6 billion prior, alongside exports and imports levels.
MBA 30-year mortgage rate data at 07:00 ET will be watched for housing affordability signals after the prior 7.37% reading. EIA weekly crude inventories at 10:30 ET follow the API's larger-than-expected draw.
Other Economic Notes
The combination of a manufacturing rebound, firm factory orders, and an upside JOLTs surprise complicates the disinflation narrative, with CPI running at 3.70% year-over-year as of September. GDP growth of 3.40% QoQ SAAR in Q2 and GDPNow at 3.7% for the current quarter suggest the economy is reaccelerating rather than cooling. Retail sales growth of 6.29% YoY and unemployment at 4.20% point to a consumer and labor market that remain supportive of demand.
↓ p.2