US Macro Daily(Beta Mode)
CPI Test Looms as Fed Split Widens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
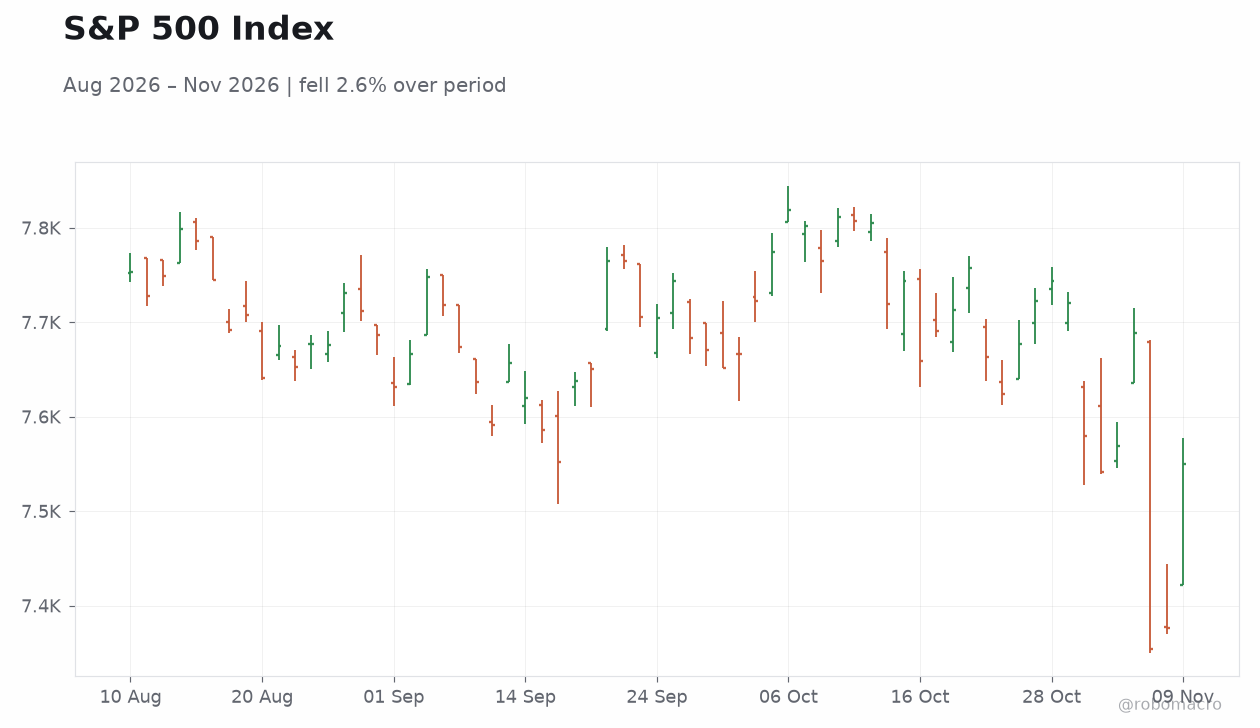
| S&P 500 | 7,549.94 | +2.35% |
| Nasdaq 100 | 27,907.63 | +3.40% |
| Dow Jones | 52,389.75 | +2.15% |
| Russell 2000 | 2,840.81 | +3.15% |
| USD/JPY | 158.17 | -0.08% |
| EUR/USD | 1.12 | +0.69% |
| GBP/USD | 1.34 | +0.50% |
| Gold | 4,084.20 | -0.74% |
| WTI Crude | 85.89 | -1.11% |
| Bitcoin | 74,197.10 | -1.36% |
| US 2Y Treasury | 4.56% | +5 bp |
| US 10Y Treasury | 4.88% | +2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Speech by Fed's Bowman | - | - | - |
| Fed Goolsbee Speech | - | - | - |
| Speech by Fed's Barkin | - | - | - |
| Speech by Fed's Bowman | - | - | - |
| Fed Goolsbee Speech | - | - | - |
| Speech by Fed's Waller | - | - | - |
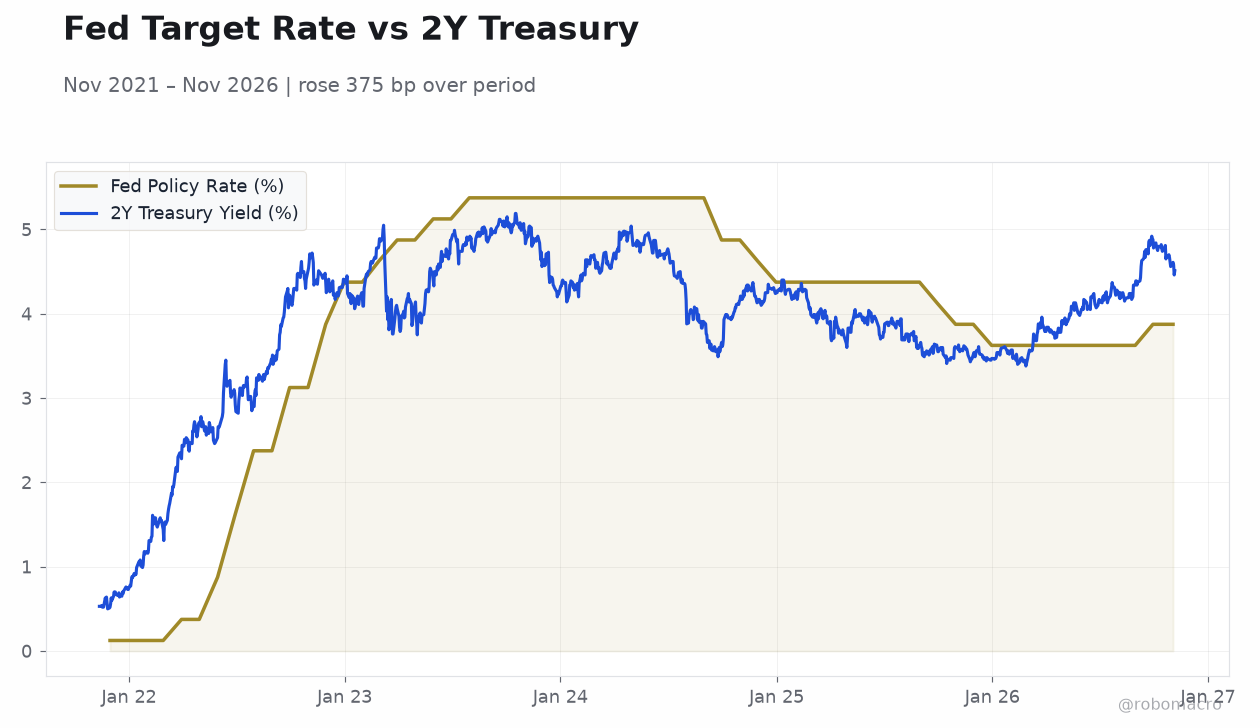 Fed Target Rate vs 2Y Treasury | Type: macro_line | Fed Policy Rate (%): 3.875 (2026-11-03) | Range: 0.125–5.375 | Trend(5pt): 0.125,4.625,5.375,4.375,3.875 | 2Y Treasury Yield (%): 4.51 (2026-11-06) | Range: 0.5–5.19 | Trend(6pt): 0.53,4.52,4.8,3.76,4.46,4.51
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| ADP Employment Change Weekly | 16,750 | - | 08:15 |
| Core Inflation Rate Month-over-Month | 0.30 | 0.20 | 08:30 |
| Inflation Rate Month-over-Month | 0.60 | 0.30 | 08:30 |
| CPI s.a | 336.30 | - | 08:30 |
| Consumer Price Index | 336.94 | 337.02 | 08:30 |
| Speech by Fed's Logan | - | - | 09:35 |
| Eia Short-Term Energy Outlook | - | - | 12:00 |
| Speech by Fed's Bowman | - | - | 13:30 |
| Speech by Fed's Schmid | - | - | 13:30 |
| API Weekly Crude Oil Stocks | -5.3m | - | 16:30 |
- October CPI lands at 08:30 ET with consensus at +0.3% headline and +0.2% core m/m, a critical input for the December 9 FOMC after September's 0.6% headline jump
- Fed Governor Waller has floated a 50 bp hike if inflation fails to slow, while Goolsbee warns the AI data center buildout is "overheating" the economy
- Equities ripped higher Monday (Nasdaq +3.40%, Russell +3.15%) even as the 2-year yield rose 5 bp to 4.56% and the dollar softened — an unusual risk-on/rates-up mix
Yesterday's Recap
Monday's session was dominated by Fed communications rather than hard data, with Bowman, Goolsbee and Barkin all on the tape. Governor Waller's remarks drew the sharpest market reaction: he said he would support a 25 bp hike in December and argued policymakers should weigh a 50 bp move if inflation fails to slow — the largest increase since 2022. Chicago Fed President Goolsbee countered that the AI data center buildout is "overheating" the economy, a notably hawkish framing from a typically dovish voice.
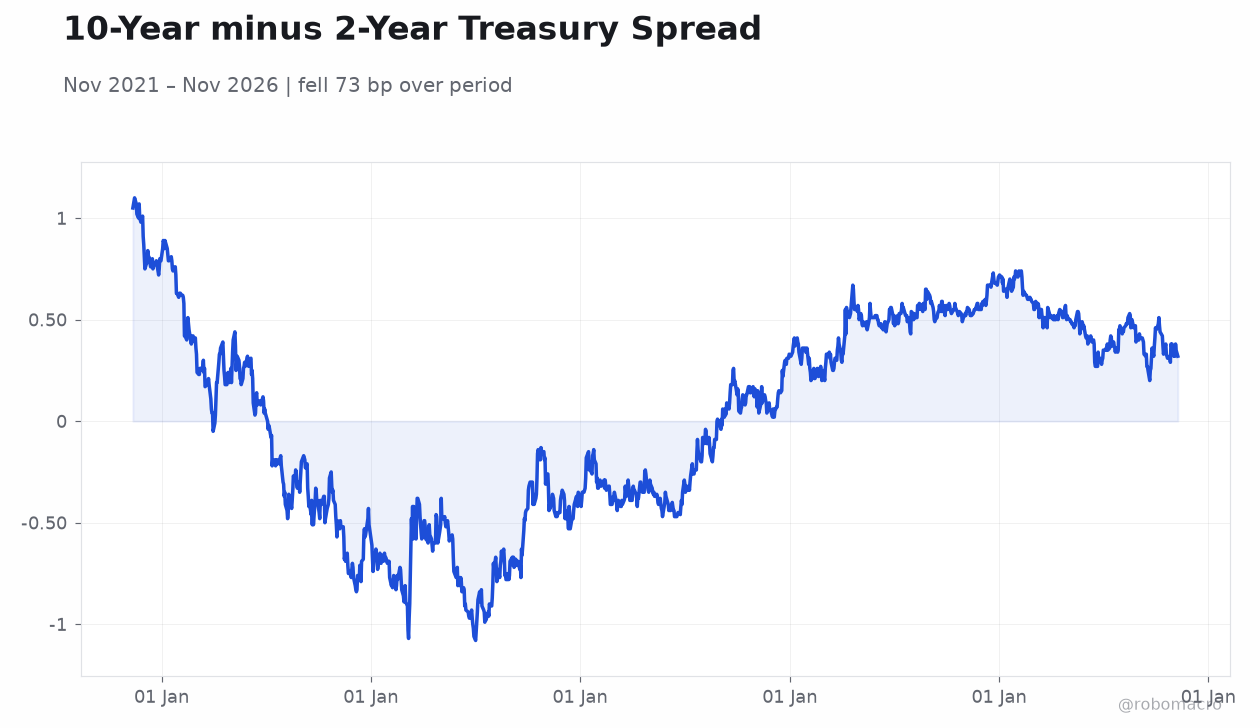
Despite the hawkish tone, equities staged a broad rally: the S&P 500 gained 2.35% to 7,549.94, the Nasdaq 100 surged 3.40% to 27,907.63, and the Russell 2000 added 3.15%. Rates moved the other way, with the 2-year yield up 5 bp to 4.56% and the 10-year up 2 bp to 4.88%, steepening the curve modestly. The dollar softened against major crosses (EUR/USD +0.69% to 1.12), while gold fell 0.74% to $4,084.20 and WTI slipped 1.11% to $85.89.
The Day Ahead
All eyes are on the 08:30 ET October CPI release, with consensus at +0.3% headline m/m (down from 0.6%) and +0.2% core m/m (down from 0.3%); the index level is expected at 337.02 versus 336.94 prior. A hot core print would validate Waller's call for a larger hike and likely pressure front-end rates. ADP's weekly employment change (08:15 ET) offers an early labor-market read, though its signal value is limited.
Fed speakers populate the afternoon: Logan at 09:35 ET, then Bowman and Schmid together at 13:30 ET, giving markets multiple chances to recalibrate December expectations. The EIA Short-Term Energy Outlook at 12:00 ET will be watched for updated crude demand assumptions after Monday's oil selloff.
Other Economic Notes
The macro backdrop remains uncomfortably strong for the Fed: Q3 GDP grew 3.40% annualized, retail sales are running 6.29% y/y, and unemployment sits at just 4.10% — hardly conditions that argue for easing. September CPI at 3.70% y/y remains well above target, and the 0.6% m/m headline print that month is the key reason December hike odds have firmed. ↓ p.2