Published every Sunday afternoon 100% AI-generated — not financial advice
Energy prices retreat from recent peaks, shifting the inflation backdrop
The week of September 14–18, 2026 placed the global expansion in its mid-phase, where the reversal in energy prices interacted with uneven activity data to sustain a data-dependent policy equilibrium. Brent crude declined 6.05 percent to 99.29 after the prior week’s 6.83 percent surge to 104.61, while WTI fell 5.24 percent to 96.08. This move reduced near-term imported inflation risks for net-energy importers without altering the broader growth trajectory. We note that the configuration leaves central banks unwilling to shift parameters on the basis of a single week’s commodity print, extending the pattern observed since late August.
Activity signals remained mixed and failed to produce a uniform read-across. US equities showed divergence, with the S&P 500 closing higher while the Dow Jones declined 1.7 percent to 51,683. In the euro area, French fiscal concerns widened sovereign spreads after growth outlook revisions, yet no high-impact data releases occurred. Japan recorded equity gains alongside USD/JPY strength, while several emerging-market currencies depreciated against the dollar. The dominant narrative therefore centers on cooling energy costs that ease one source of price pressure even as USD strength and selective labor-market or fiscal concerns persist.
Developed-market outcomes cluster around resilience and continued data dependenc e
US, euro-area, Japanese and UK developments illustrated selective resilience without policy recalibration. The Bank of England kept its policy rate unchanged on a split vote after headline CPI rose to a multi-month high in line with consensus and earnings growth moderated. UK labor-market data showed unemployment steady, reducing immediate wage-pressure concerns ahead of the next meeting. In the euro area, German 10-year Bund yields eased while French 10-year yields rose 12 basis points to 4.57 percent, reflecting fiscal-spread widening rather than broad rate repricing.
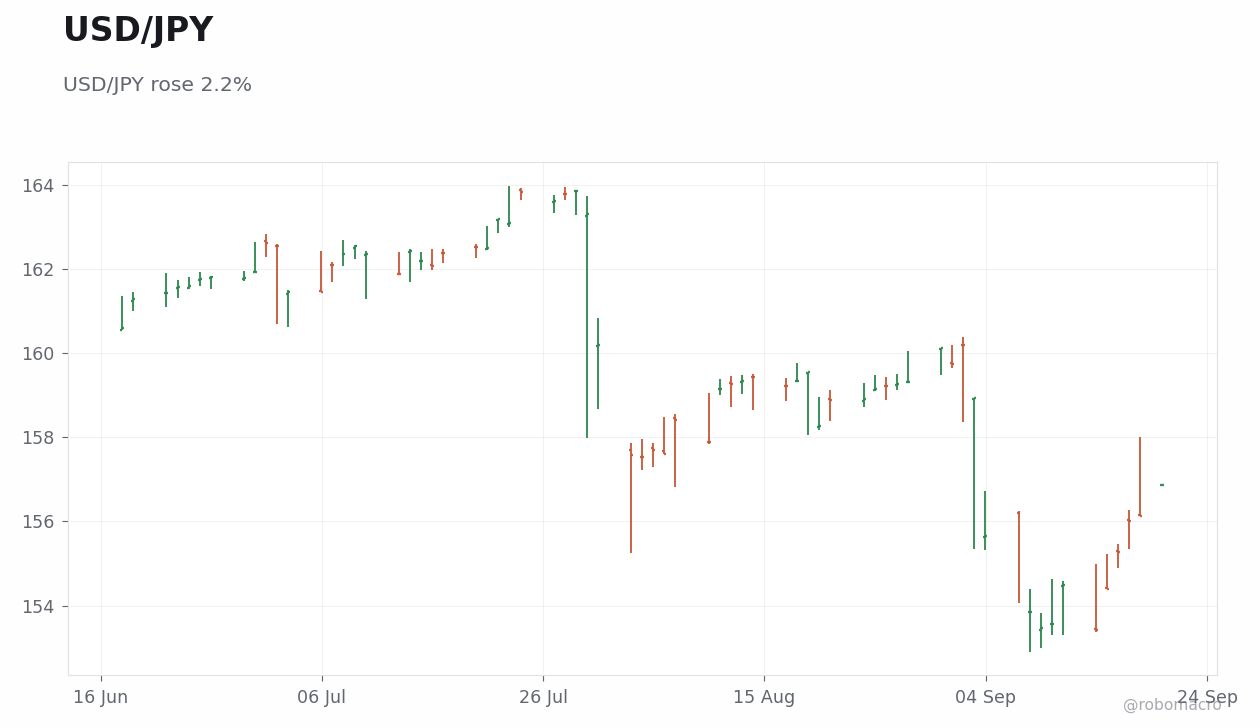
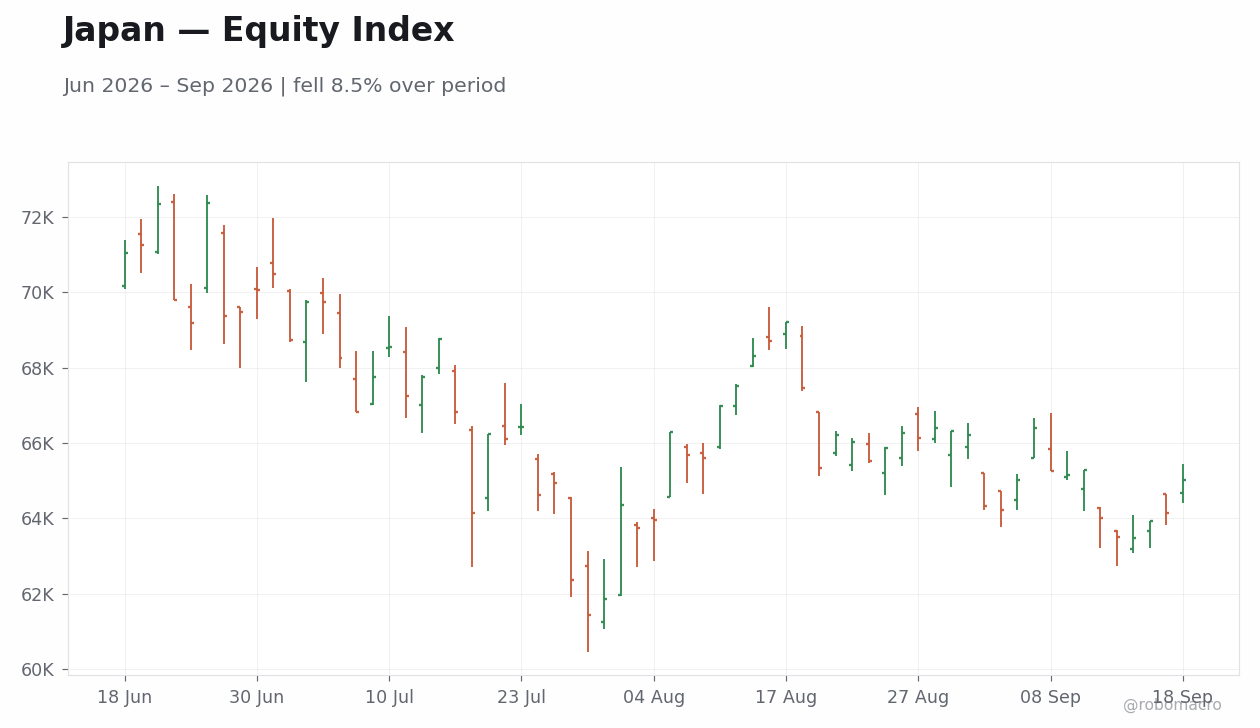
Japan posted clearer equity strength as the Nikkei 225 advanced 2.4 percent, coinciding with USD/JPY rising 2.24 percent to 156.85. Commodity prices diverged inside the same market, with Brent down 6.05 percent and gold up 1.68 percent. Nordic and other European equity indices registered net gains, including OMX Helsinki 25 rising 3.08 percent, even as Brent’s decline eased imported inflation exposure. Across these economies the common thread remains tolerance for divergent prints while policy settings stay anchored to incoming data.
Emerging-market flows split along commodity and currency lines
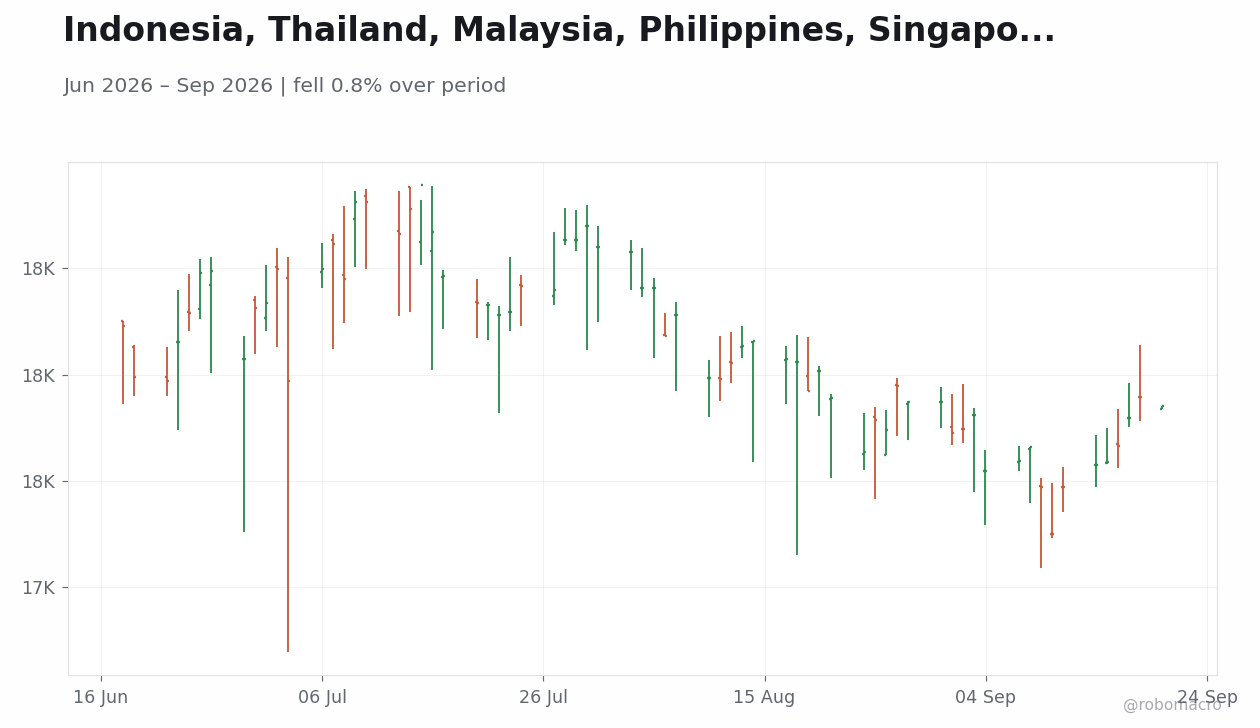
EM data flows reflected the energy reversal and broad USD strength. USD/IDR rose 0.62 percent to 17,740, USD/MYR advanced 0.84 percent to 4.08 and USD/THB gained 0.60 percent to 33.29, pressuring ASEAN importers even after Brent’s decline left import costs elevated. Regional equities closed lower, with JCI declining 1.43 percent and KLCI falling 1.91 percent. In Latin America, USD/COP advanced 2.89 percent, USD/CLP rose 2.48 percent and USD/PEN gained 3.58 percent while copper rose 5.71 percent to 6.69, supporting Chile and Peru external positions.
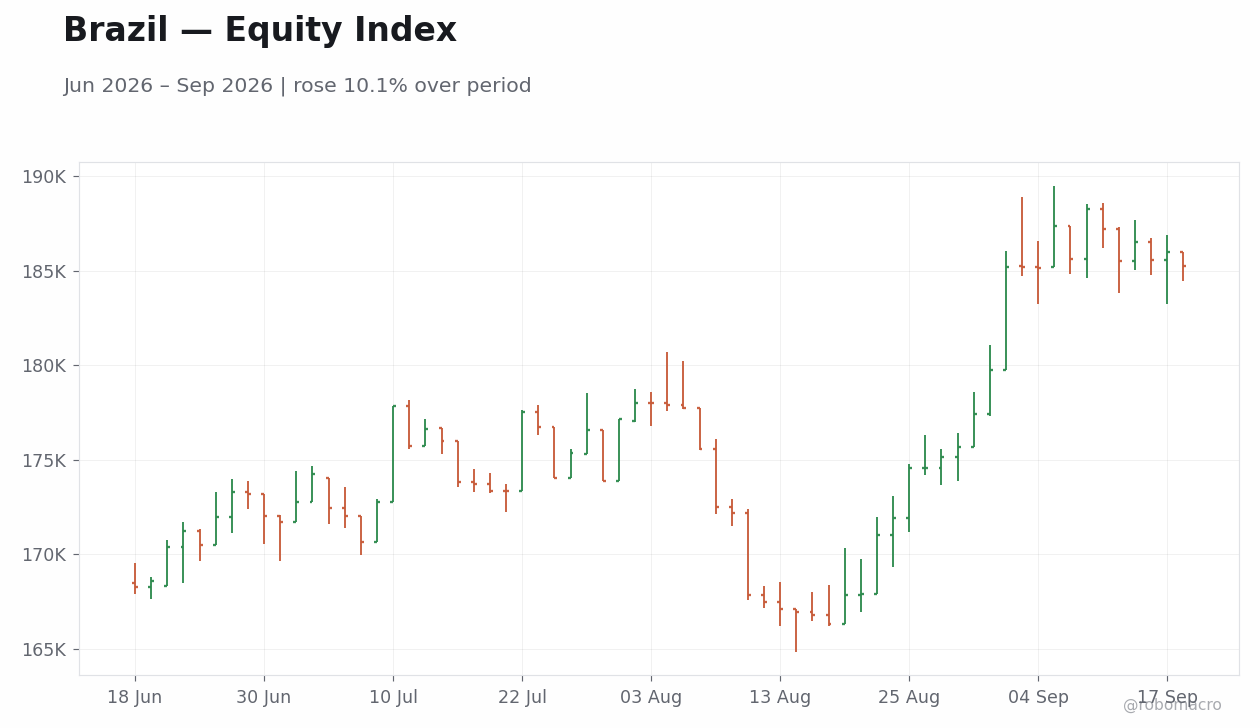
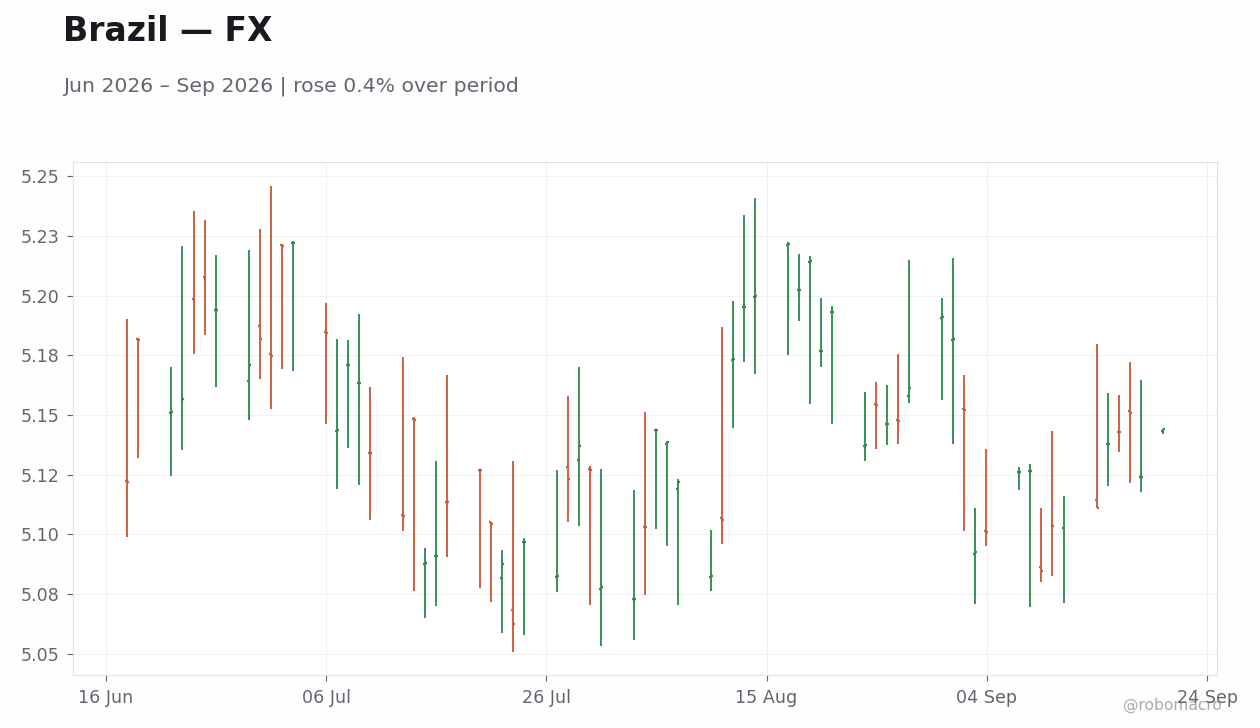
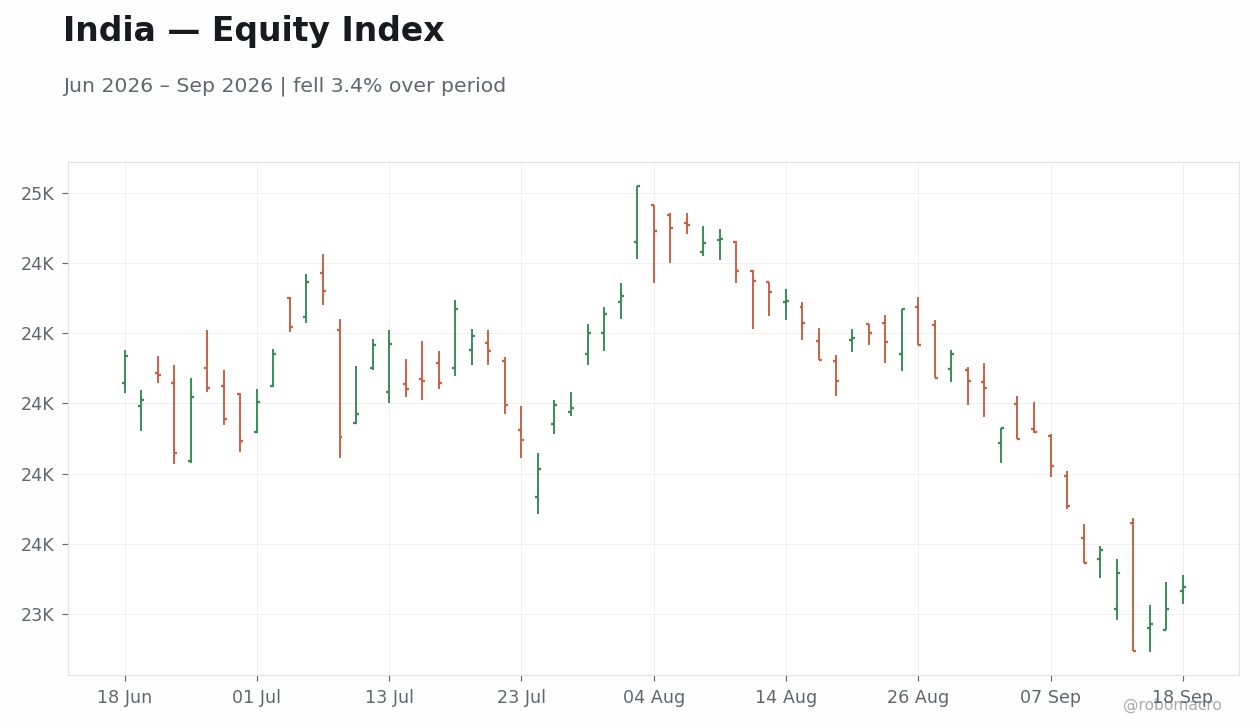
India’s August CPI exceeded consensus, narrowing the window for near-term Reserve Bank of India easing, yet Nifty 50 still closed the week at 23,346.40. Brazil’s Bovespa ended at 185,229 after a 0.15 percent decline as USD/BRL rose 0.65 percent to 5.14. South Africa’s JSE Top 40 fell 0.78 percent while USD/ZAR rose 0.42 percent to 16.25. Central banks in Colombia, Chile, Peru and South Africa maintained unchanged rates with no communications recorded, leaving policy paths dependent on prior prints and upcoming inflation releases.
Cross-asset prices reveal commodity divergence and USD dominance
Rates, FX, equities and commodities together signaled easing energy-driven inflation pressure alongside persistent external-rate differentials. The 2-year Treasury yield rose 11 basis points to 4.67 percent while the 10-year yield moved 1 basis point lower to 4.94 percent. German 2-year yields advanced 8 basis points to 3.27 percent and Japanese 2-year yields rose 1 basis point to 1.85 percent. Equity markets produced the clearest divergence, with KOSPI closing at 6,894.23 after a 3.14 percent gain and the S&P 500 showing modest weekly resilience.
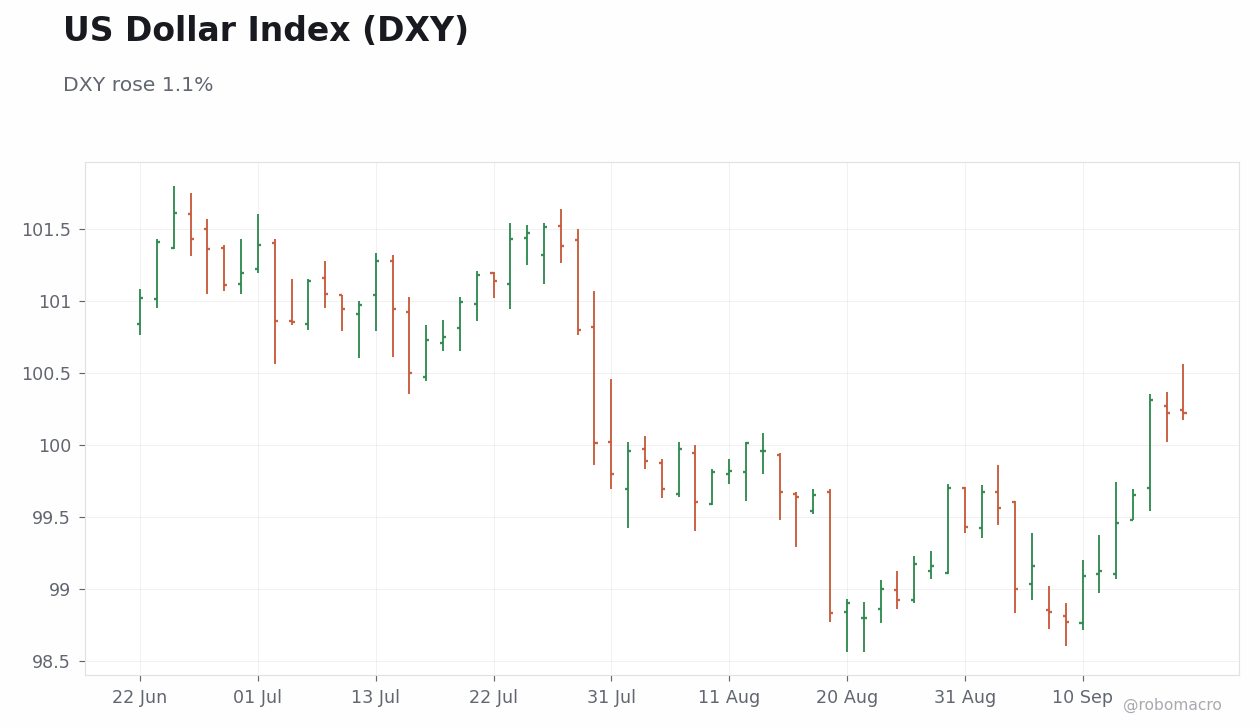
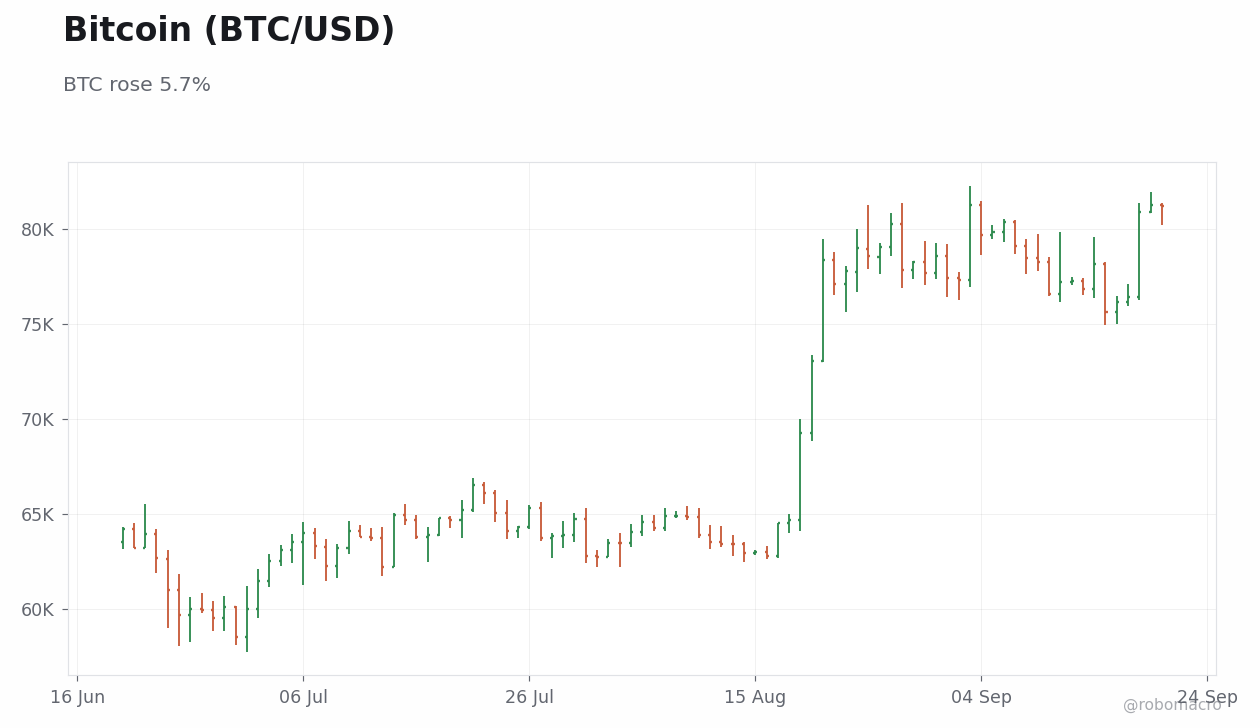
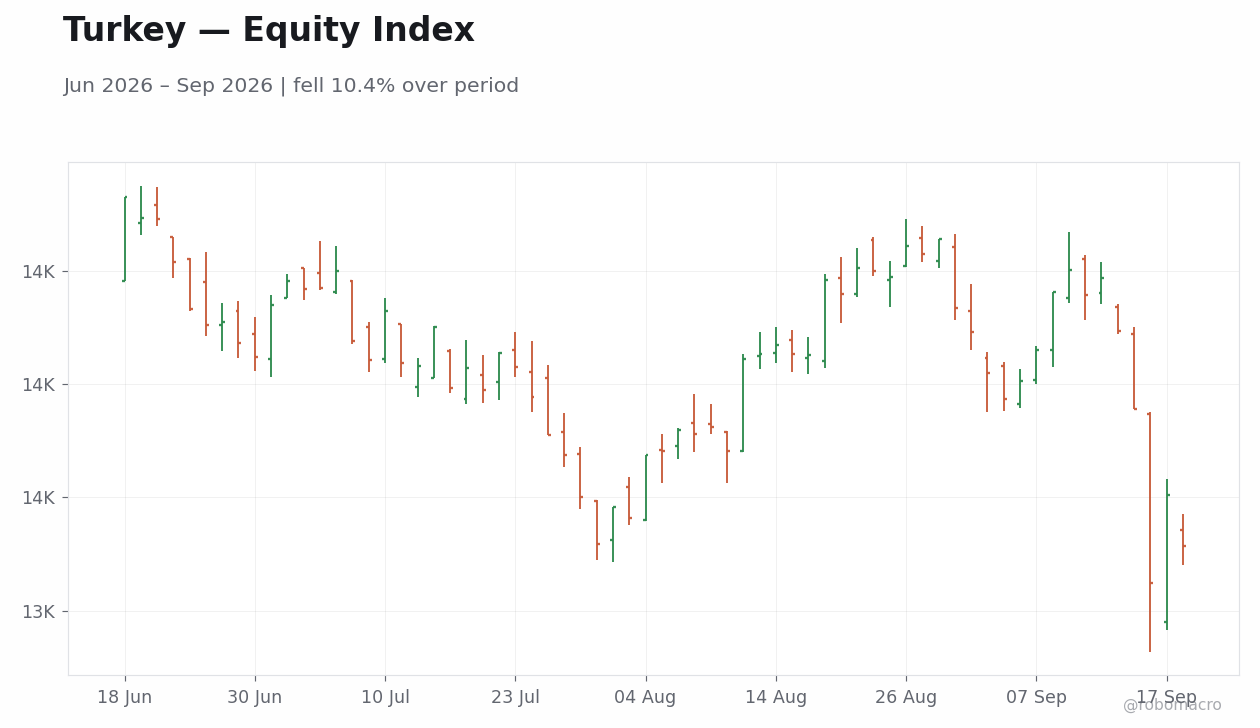
FX markets underscored USD strength, with DXY advancing 1.1 percent to 100.22. Gold rose 1.68 percent to 4,424.9 while Bitcoin gained 5.68 percent to 81,199.98, illustrating selective risk-asset appetite amid commodity reversal. Brent’s 6.05 percent decline reversed part of the prior energy advance, reducing imported-inflation risks for Hungary, Turkey and other net importers even as regional equities posted losses, including BIST 100 falling 6.68 percent to 13,284.40.
Policy outlook remains anchored to data dependence across regions
Global central-bank settings showed no material shifts during the week. The Bank of Canada maintained its data-dependent stance amid external trade developments. BanRep, BCCh and BCRP held policy rates unchanged with no meetings or guidance updates. The Bank of Korea emphasized data dependence while advancing won internationalization measures. No communications occurred from Banco de Mexico, BCRA or the Central Bank of the Republic of Turkey, leaving rate paths dependent on prior monthly inflation and reserve prints.
The configuration sustains a data-dependent equilibrium in which energy-price relief competes with selective fiscal or labor-market concerns. French fiscal revisions and widening spreads illustrate one source of divergence, while India’s higher-than-expected August CPI shows another. Policymakers absorbed the commodity reversal without immediate recalibration, consistent with the stance maintained since late August.
Forward look centers on incoming inflation prints and commodity follow-through
Next week’s focus will fall on inflation releases and any follow-through in energy prices after the sharp weekly reversal. Markets will watch whether the decline in Brent to 99.29 sustains or reverses, given its direct effect on imported inflation across Asia and Europe. US equity and Treasury moves, alongside USD/JPY at 156.85, will provide further signals on external-rate differentials. EM currency stability and any shifts in central-bank rhetoric will determine whether the current data-dependent equilibrium persists into late September.
| Economy | Real GDP (% y/y) | Consumer Prices (% y/y) | ||||
|---|---|---|---|---|---|---|
| 2026E | 2027E | 2028E | 2026E | 2027E | 2028E | |
| Americas | ||||||
| United States | 2.3 | 2.1 | 2.1 | 3.2 | 2.1 | 2.2 |
| Canada | 1.5 | 1.9 | 1.7 | 2.5 | 2.1 | 2.0 |
| Mexico | 1.6 | 2.2 | 2.1 | 3.9 | 3.4 | 3.0 |
| Brazil | 1.9 | 2.0 | 2.4 | 4.0 | 3.4 | 3.0 |
| Argentina | 3.5 | 4.0 | 3.8 | 30.4 | 15.7 | 9.6 |
| Colombia | 2.3 | 2.5 | 2.6 | 5.9 | 5.2 | 3.4 |
| Chile | 2.4 | 2.6 | 2.3 | 2.9 | 3.3 | 3.0 |
| Peru | 2.8 | 2.8 | 2.8 | 2.5 | 1.8 | 2.0 |
| Asia / Pacific | ||||||
| Japan | 0.7 | 0.6 | 0.6 | 2.2 | 2.3 | 2.0 |
| China | 4.4 | 4.0 | 4.0 | 1.2 | 1.5 | 1.8 |
| India | 6.5 | 6.5 | 6.5 | 4.7 | 4.0 | 4.0 |
| Australia | 2.0 | 1.7 | 1.9 | 4.0 | 3.2 | 2.6 |
| New Zealand | 2.1 | 2.4 | 2.4 | 3.1 | 2.3 | 2.1 |
| South Korea | 1.9 | 2.1 | 2.2 | 2.5 | 1.9 | 2.0 |
| Indonesia | 5.0 | 5.1 | 5.2 | 3.0 | 2.6 | 2.5 |
| Malaysia | 4.7 | 4.3 | 4.3 | 1.9 | 2.0 | 2.0 |
| Philippines | 4.1 | 5.8 | 6.1 | 4.3 | 3.2 | 3.0 |
| Singapore | 3.5 | 2.7 | 2.5 | 2.3 | 1.9 | 2.0 |
| Thailand | 1.5 | 2.1 | 2.3 | 0.9 | 1.0 | 1.2 |
| Taiwan | 5.2 | 3.0 | 2.4 | 1.5 | 1.6 | 1.6 |
| Vietnam | 7.1 | 6.7 | 6.2 | 4.9 | 4.6 | 3.7 |
| Western Europe | ||||||
| Euro area | 1.1 | 1.2 | 1.4 | 2.6 | 2.2 | 2.1 |
| Germany | 0.8 | 1.2 | 1.2 | 2.7 | 2.3 | 2.0 |
| France | 0.9 | 0.9 | 1.2 | 1.8 | 1.7 | 1.9 |
| Italy | 0.5 | 0.5 | 0.8 | 2.6 | 2.4 | 2.3 |
| Spain | 2.1 | 1.8 | 1.8 | 3.0 | 2.3 | 2.5 |
| United Kingdom | 0.8 | 1.3 | 1.6 | 3.2 | 2.4 | 2.0 |
| Sweden | 2.0 | 1.9 | 2.1 | 1.5 | 1.8 | 2.6 |
| Norway | 1.5 | 1.3 | 1.1 | 3.3 | 2.6 | 2.2 |
| Denmark | 2.0 | 1.6 | 1.6 | 2.0 | 2.2 | 2.2 |
| Switzerland | 1.3 | 1.3 | 1.8 | 0.5 | 0.5 | 0.6 |
| Netherlands | 1.2 | 1.4 | 1.4 | 2.7 | 2.4 | 2.3 |
| Poland | 3.3 | 2.4 | 2.6 | 3.3 | 3.3 | 3.9 |
| Czech Republic | 2.2 | 2.2 | 2.1 | 2.4 | 2.2 | 2.5 |
| Hungary | 1.7 | 2.0 | 2.3 | 3.8 | 3.5 | 3.1 |
| Romania | 0.7 | 2.5 | 2.7 | 7.8 | 3.9 | 4.3 |
| EMEA Emerging | ||||||
| Turkey | 3.4 | 3.5 | 3.8 | 28.6 | 21.4 | 17.0 |
| South Africa | 1.0 | 1.3 | 1.5 | 3.9 | 3.4 | 3.0 |
| Israel | 3.5 | 4.4 | 3.7 | 2.3 | 2.1 | 2.0 |
| Saudi Arabia | 3.1 | 4.5 | 3.6 | 2.3 | 2.1 | 2.0 |
| UAE | 3.1 | 5.3 | 4.6 | 2.5 | 2.0 | 2.0 |
| Egypt | 4.2 | 4.8 | 5.5 | 13.2 | 11.1 | 8.1 |
| Nigeria | 4.1 | 4.3 | 4.1 | 16.0 | 15.9 | 12.7 |
| Kenya | 4.5 | 4.7 | 5.1 | 5.9 | 5.9 | 5.7 |
| Global Aggregates | ||||||
| Global | 3.1 | 3.2 | 3.2 | 4.4 | 3.7 | 3.4 |
| Developed markets | 1.8 | 1.7 | 1.7 | 2.8 | 2.2 | 2.1 |
| Emerging markets | 3.9 | 4.2 | 4.2 | 5.5 | 4.6 | 4.1 |
| Central Bank | Instrument | Current Rate |
Last Change |
bp | Next Meeting |
Q1 2026 |
Q2 2026 |
Q3 2026 |
Q4 2026 |
|---|---|---|---|---|---|---|---|---|---|
| The Americas | |||||||||
| Federal Reserve | Fed funds upper | 3.75% | Dec 2025 | -25 | Oct 28 | 3.75 | 3.75 | — | — |
| Bank of Canada | O/N rate | 2.25% | Oct 2025 | -25 | Oct 28 | 2.25 | 2.25 | — | — |
| BCB (Brazil) | SELIC | 14.00% | Aug 2026 | -25 | Nov 4 | 14.75 | 14.25 | — | — |
| Banxico | O/N rate | 6.50% | May 2026 | -25 | Sep 24 | 6.75 | 6.50 | — | — |
| BCRA (Argentina) | Aggregates regime | n/v | — | — | — | — | — | — | — |
| BanRep (Colombia) | Repo | 12.00% | Jul 2026 | +75 | — | 10.25 | 11.25 | — | — |
| BCCh (Chile) | MPR | 4.50% | Dec 2025 | -25 | — | 4.50 | 4.50 | — | — |
| Europe / Africa | |||||||||
| ECB | Depo rate | 2.50% | Jun 2026 | +25 | Oct 29 | 2.00 | 2.25 | — | — |
| Bank of England | Bank rate | 3.75% | Dec 2025 | -25 | Nov 5 | 3.75 | 3.75 | — | — |
| Riksbank | Repo rate | 1.75% | Oct 2025 | -25 | Sep 24 | 1.75 | 1.75 | — | — |
| Norges Bank | Dep rate | 4.25% | May 2026 | +25 | Sep 24 | 4.00 | 4.25 | — | — |
| SNB | Policy rate | 0.00% | Jun 2025 | -25 | Sep 24 | 0.00 | 0.00 | — | — |
| CNB (Czech) | 2-wk repo | 3.75% | Jun 2026 | +25 | Nov 5 | 3.50 | 3.75 | — | — |
| NBH (Hungary) | Base rate | 5.50% | Aug 2026 | -25 | Sep 22 | 6.25 | 6.25 | — | — |
| NBP (Poland) | Ref rate | 3.75% | Mar 2026 | -25 | — | 3.75 | 3.75 | — | — |
| SARB | Repo rate | 7.00% | May 2026 | +25 | Sep 23 | 6.75 | 7.00 | — | — |
| CBRT (Turkey) | 1-wk repo | 37.00% | Jan 2026 | -100 | Oct 22 | 37.00 | 37.00 | — | — |
| Asia / Pacific | |||||||||
| RBA | Cash rate | 4.35% | May 2026 | +25 | Sep 29 | 4.10 | 4.35 | — | — |
| RBNZ | OCR | 2.75% | Sep 2026 | +25 | Oct 28 | 2.25 | 2.25 | — | — |
| BoJ | Pol rate | 1.00% | Jun 2026 | +25 | Oct 30 | 0.75 | 1.00 | — | — |
| PBoC | 1-yr LPR | 3.00% | May 2025 | -10 | — | 3.00 | 3.00 | — | — |
| RBI (India) | Repo rate | n/v | — | — | — | — | — | — | — |
| BoK (Korea) | Base rate | 2.75% | Jul 2026 | +25 | — | 2.50 | 2.50 | — | — |
| BI (Indonesia) | BI-Rate | 5.75% | Jun 2026 | +25 | Sep 23 | 4.75 | 5.75 | — | — |
| BSP (Philippines) | Rev repo | 5.00% | Aug 2026 | +25 | — | 4.25 | 4.75 | — | — |
| BoT (Thailand) | 1-day repo | 1.00% | Feb 2026 | -25 | Oct 28 | 1.00 | 1.00 | — | — |
| CBC (Taiwan) | Disc rate | n/v | — | — | — | — | — | — | — |
| MAS (Singapore) | SGD NEER | n/v | — | — | — | — | — | — | — |
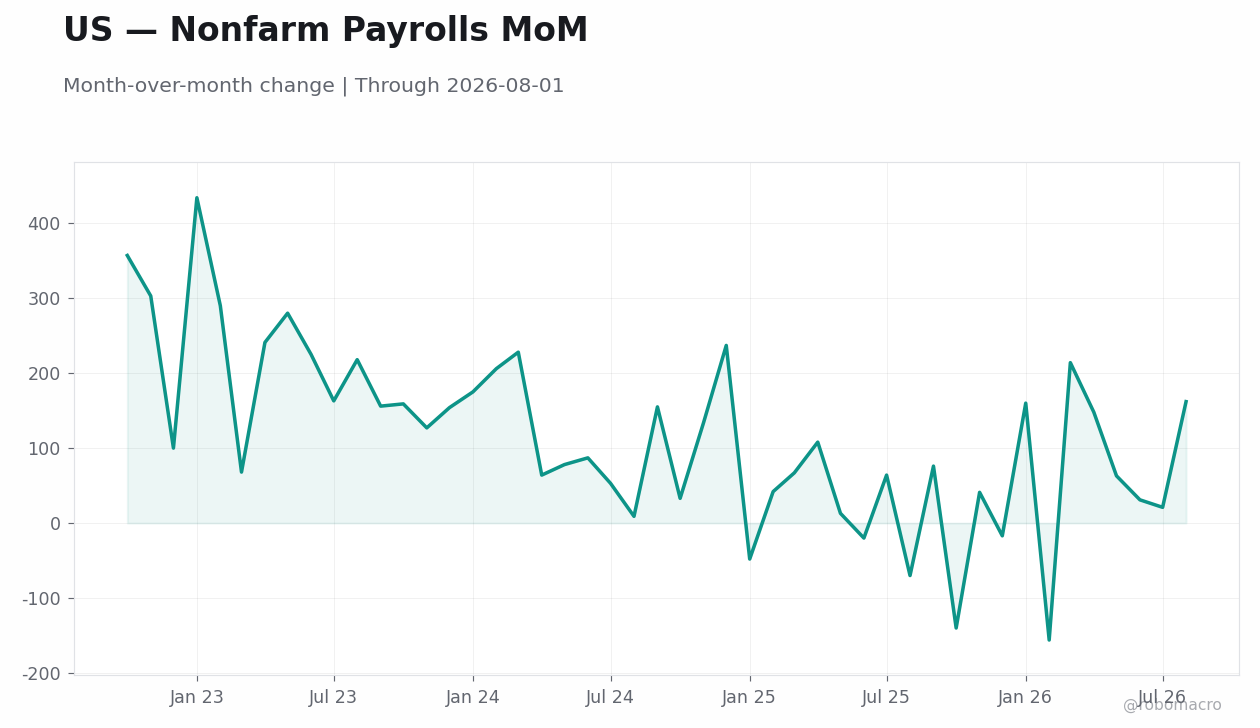
| Nonfarm Payrolls (m/m) | +96k | 80% CI +52k…+351k |
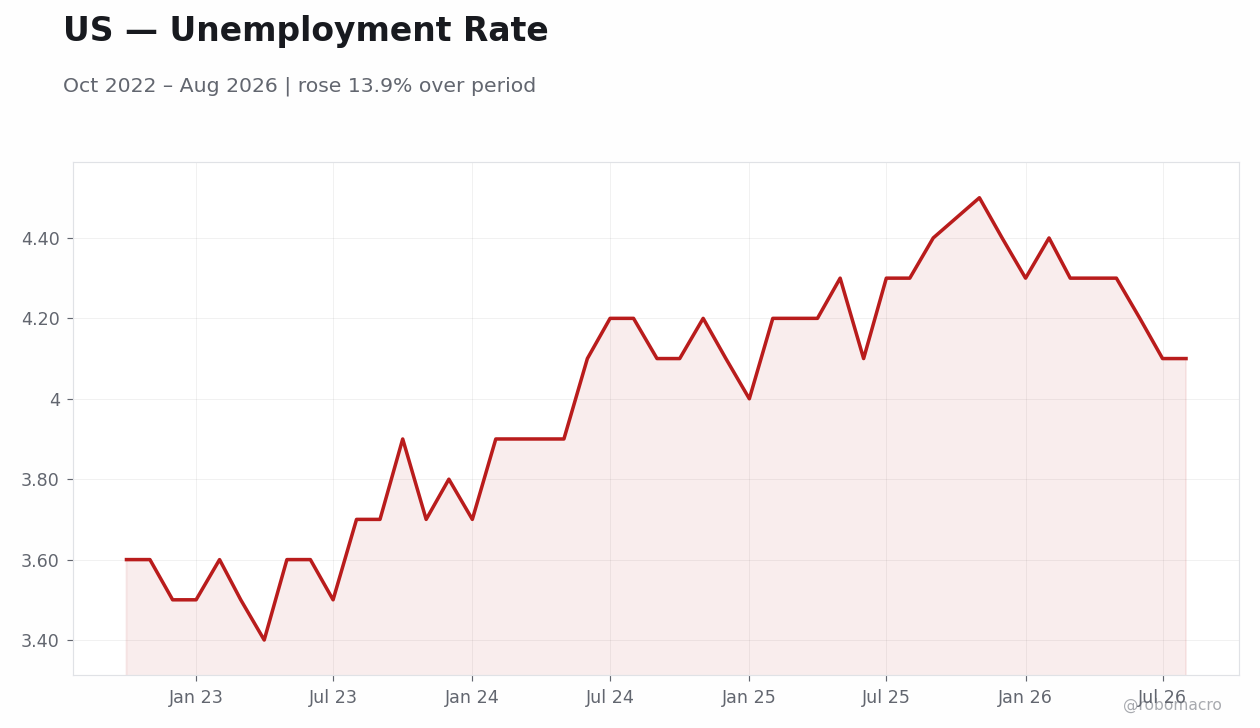
| Unemployment Rate | 4.1% | |
| Avg Hourly Earnings (y/y) | 3.3% |
| Economy | Activity Index | 4-wk Δ | 13-wk Δ | Week ending | Indicators | Signal |
|---|---|---|---|---|---|---|
| United States | 62.3 | +10.6 | +4.2 | 2026-09-11 | 7/7 | Expanding · Advancing |
| Italy | 57.5 | -4.1 | +21.2 | 2026-09-11 | 5/5 | Expanding · Retreating |
| Brazil | 52.9 | -2.6 | -1.5 | 2026-09-18 | 3/4 | Expanding · Retreating |
| Canada | 51.6 | +1.4 | -4.5 | 2026-09-11 | 6/8 | Expanding · Advancing |
| Spain | 51.3 | -6.9 | -0.7 | 2026-09-11 | 5/5 | Expanding · Retreating |
| Australia | 50.9 | +5.2 | +20.1 | 2026-09-11 | 3/3 | Expanding · Advancing |
| Poland | 49.8 | -7.0 | -17.3 | 2026-09-18 | 3/4 | Contracting · Retreating |
| Euro Area | 49.1 | -8.2 | +5.3 | 2026-09-11 | 5/5 | Contracting · Retreating |
| New Zealand | 46.6 | -1.4 | -4.6 | 2026-09-11 | 4/5 | Contracting · Retreating |
| France | 44.9 | -15.6 | -0.2 | 2026-09-11 | 4/5 | Contracting · Retreating |
| Germany | 42.7 | -4.7 | -3.0 | 2026-09-18 | 5/6 | Contracting · Retreating |
| Japan | 39.6 | -8.6 | -12.3 | 2026-09-11 | 5/5 | Contracting · Retreating |
Activity remains in expansion in United States, Italy, Spain, Canada, Brazil, Australia; while high-frequency trackers point to sub-trend activity in Euro Area, Germany, France, Japan, New Zealand, Poland. On a 4-week basis, momentum is improving in United States, Canada, Australia and cooling in Euro Area, Germany, France, Italy, Spain, Japan, Brazil, New Zealand, Poland. RoboMacro's labor ensemble nowcasts the next US payrolls print at +96k.


Week in Review
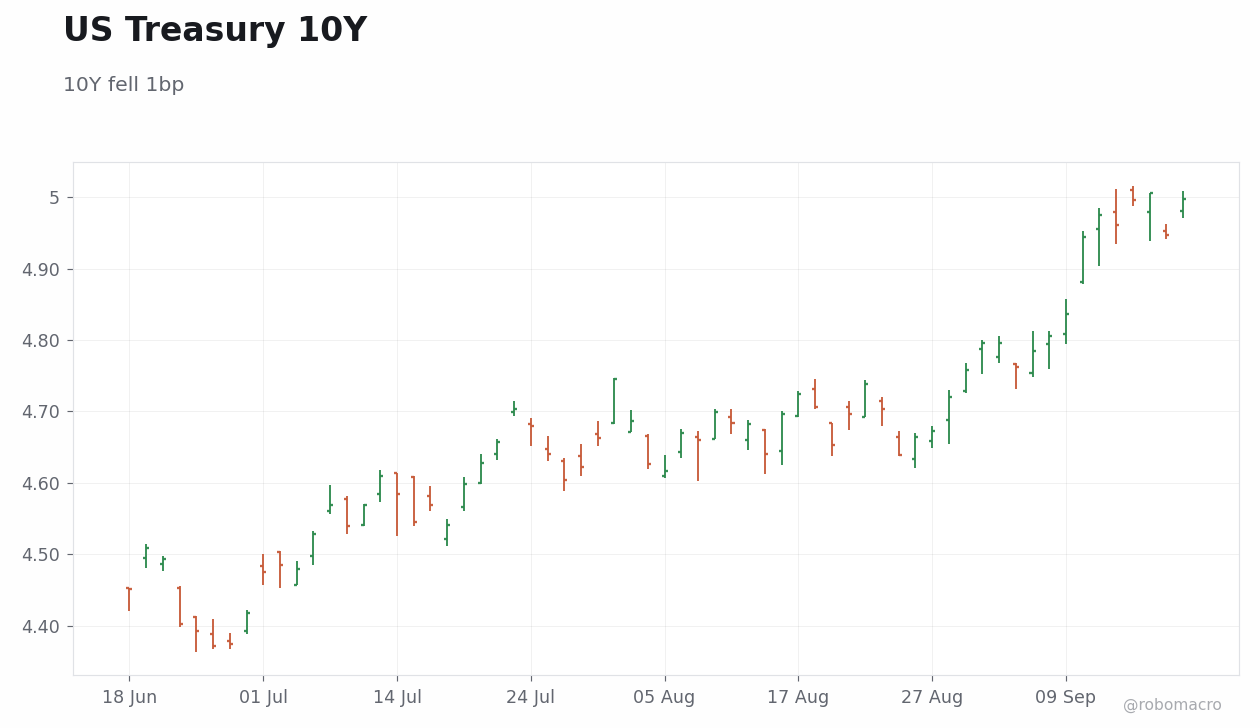
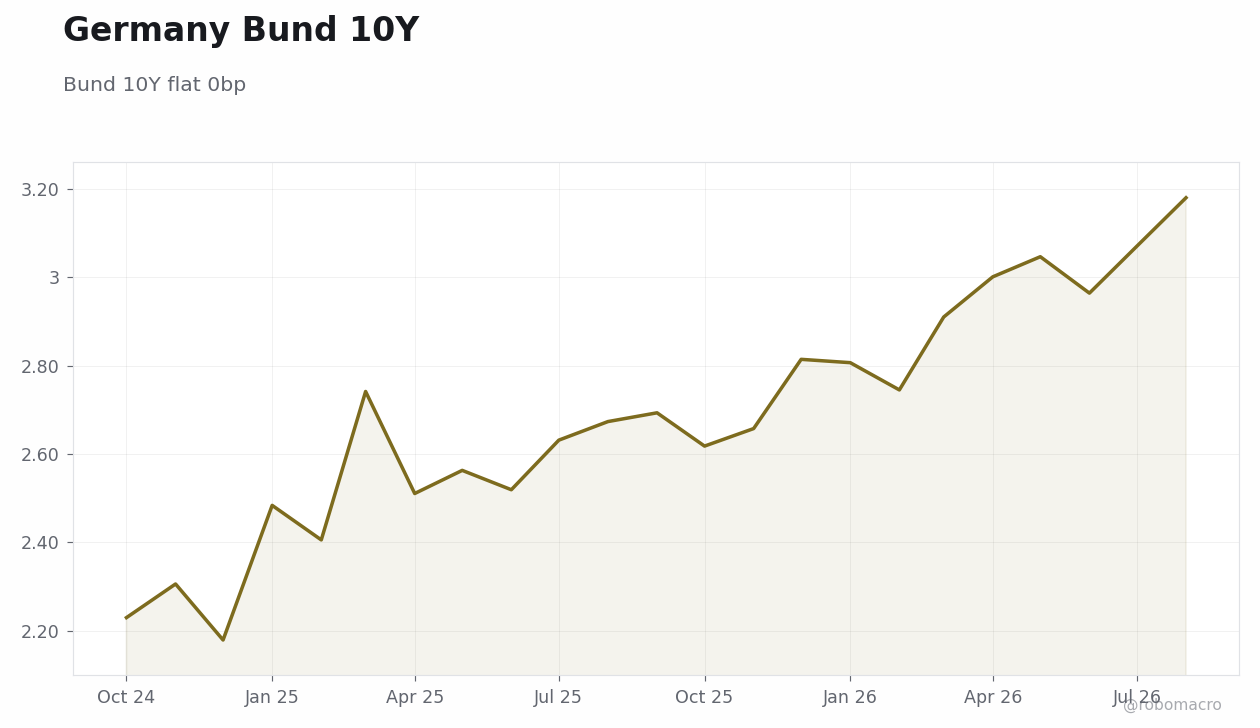
UK 30-year gilt yields fell 18bp to 5.75%. US 10-year Treasury yields declined 1bp to 4.94% and 30-year yields fell 8bp to 5.29%. The US 2-year yield rose 11bp to 4.67%. German 10-year Bund yields were unchanged at 3.52% while 30-year yields fell 6bp to 3.84%. Japanese 10-year JGB yields held steady at 2.99%. The US 10-year yield climbed from 4.9610 on Monday to 5.0060 on Wednesday before easing to 4.9470 on Thursday and closing at 4.9980 on Friday.
Curve & Spreads
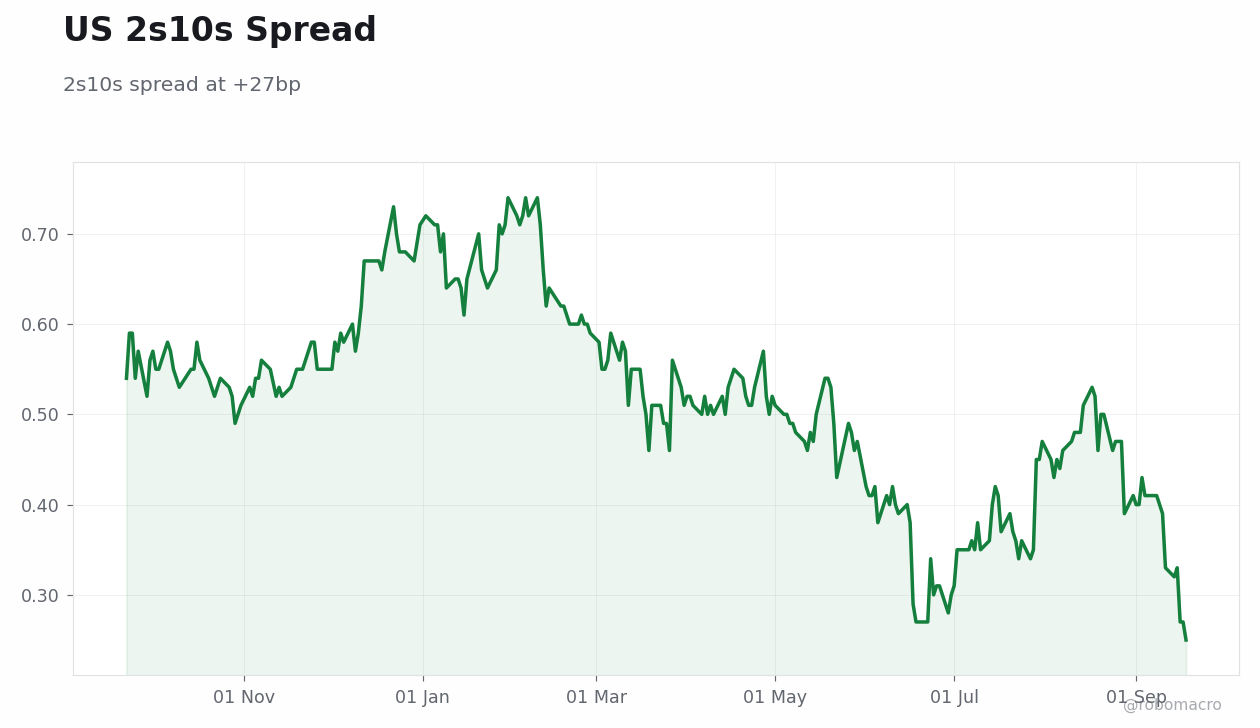
The US 2s10s spread stood at +27bp, compared with +25bp in Germany and +57bp in the UK. The UK curve is materially steeper than the relatively flat profiles in the US and Germany. This upward-sloping shape across major DM markets implies positive growth expectations with investors requiring compensation for longer-duration risk. The flatter US and German curves suggest more contained growth optimism relative to the UK.
EM Bonds
Turkish 10-year yields stood at 35.27% while Brazilian 10-year yields were at 14.30%. South African 10-year yields closed at 8.84%, Mexican yields at 9.46%, and Indonesian yields at 7.16%. Turkish yields moved significantly higher on the week. These EM yield levels remain markedly higher than DM counterparts such as the US 10-year at 4.94% and German 10-year at 3.52%, underscoring a wide spread differential that compensates for elevated risk and inflation differentials.
Central Bank Read
Yield curve steepening in major developed markets implies an easing bias from central banks. In the US, front-end rates rose with the 2-year yield up 11bp while back-end yields fell with the 30-year down 8bp. The UK exhibited a parallel pattern with the 2-year yield rising 2bp against an 18bp decline in the 30-year. German markets saw the 2-year yield increase 8bp while the 30-year eased 6bp. These front-end versus back-end moves suggest policy settings are expected to adjust lower to support activity should growth moderate.
Week Ahead
The economic calendar next week is light with no major CPI, payrolls, GDP or central bank meetings listed. This quiet schedule places greater weight on any Treasury auctions for gauging demand and duration risk. Broader risk sentiment and external developments will likely drive yield moves in the absence of high-impact prints. Participants will monitor for any surprises that could alter the easing bias currently priced into curves.
| Country | 2Y | 2Y WoW | 10Y | 10Y WoW | 30Y | 30Y WoW | 2s10s |
|---|---|---|---|---|---|---|---|
| United States | 4.67% | +11bp | 4.94% | -1bp | 5.29% | -8bp | +27bp |
| United Kingdom | 4.72% | +2bp | 5.29% | -7bp | 5.75% | -18bp | +57bp |
| Germany | 3.27% | +8bp | 3.52% | +0bp | 3.84% | -6bp | +25bp |
| France | 3.55% | +15bp | 4.57% | +12bp | 5.17% | +5bp | +102bp |
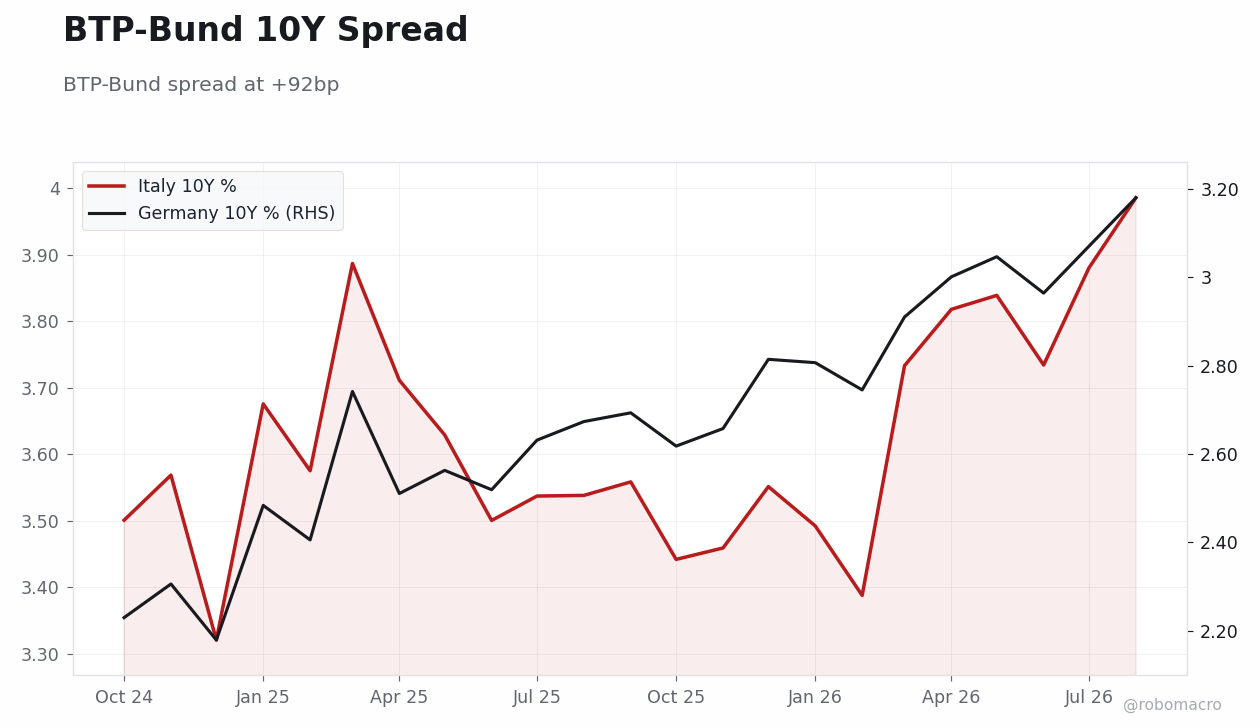
| Italy | 3.53% | +13bp | 4.44% | +9bp | 5.05% | +1bp | +91bp |
| Spain | 3.35% | +10bp | 3.99% | +2bp | 4.49% | -5bp | +64bp |
| Japan | 1.85% | +1bp | 2.99% | +0bp | 4.08% | +3bp | +114bp |
| Canada | — | — | 3.88% | -6bp | 4.19% | -8bp | — |
| Australia | 5.01% | -4bp | 5.29% | -9bp | 5.70% | -12bp | +29bp |
| China | 1.25% | -0bp | 1.68% | -1bp | 2.16% | -1bp | +43bp |
| India | 6.48% | +22bp | 7.06% | +5bp | 7.61% | -1bp | +58bp |
| Brazil | 13.83% | +0bp | 14.30% | +0bp | — | — | +46bp |
| Mexico | — | — | 9.46% | -1bp | — | — | — |
| South Korea | 3.99% | +8bp | 4.47% | -7bp | 4.58% | -14bp | +48bp |
| Indonesia | — | — | 7.16% | +0bp | 7.23% | +0bp | — |
| Turkey | 37.50% | +92bp | 35.27% | +80bp | — | — | -223bp |
| South Africa | — | — | 8.84% | -6bp | 9.20% | -8bp | — |
| Poland | — | — | 6.31% | +1bp | — | — | — |
Turkey’s 2-year yield jumped 92bp to 37.50% and its 10-year rose 80bp to 35.27%, the largest weekly gains. India’s 2-year added 22bp to 6.48%. France’s 2-year climbed 15bp to 3.55% while Italy’s rose 13bp to 3.53%. Offsetting these moves, the UK 30-year fell 18bp to 5.75% and Australia’s 30-year declined 12bp to 5.70%. The US 2-year increased 11bp to 4.67% as the 30-year eased 8bp to 5.29%, widening the 2s10s spread by 27bp. France and Japan recorded the widest 2s10s levels at 102bp and 114bp. Core European and Australian long-end yields converged lower while selected EM curves steepened sharply.


Week in Review
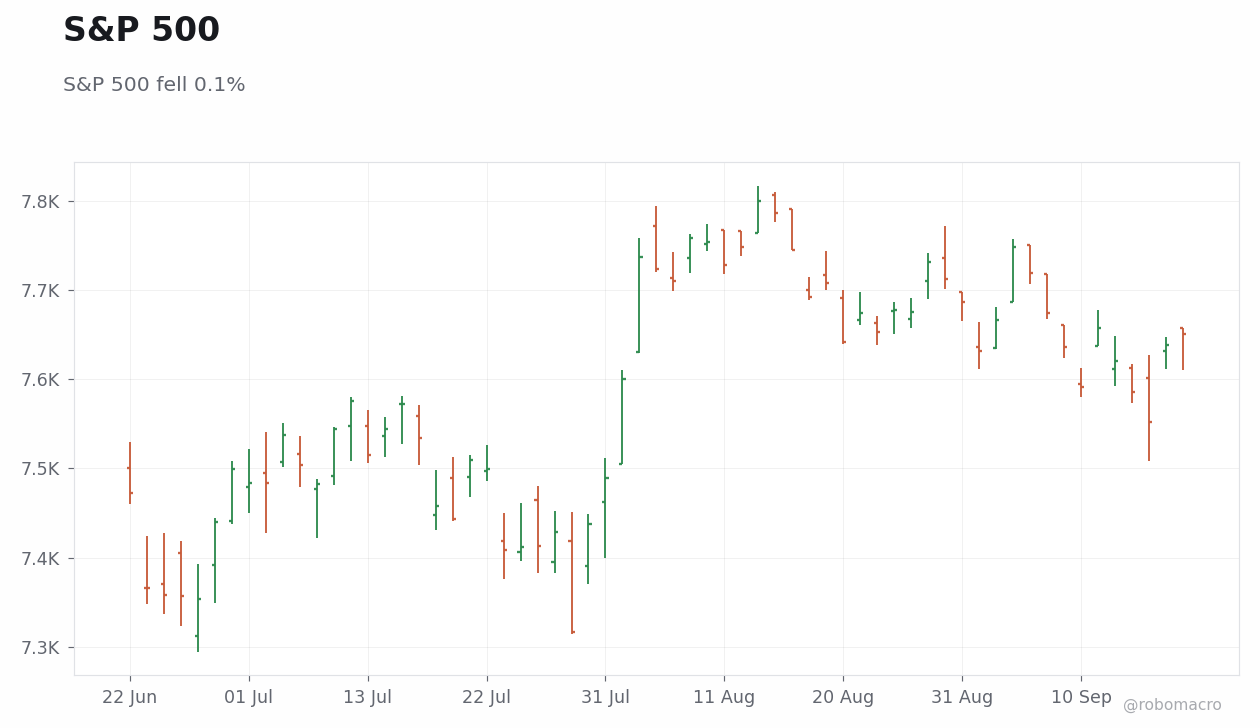
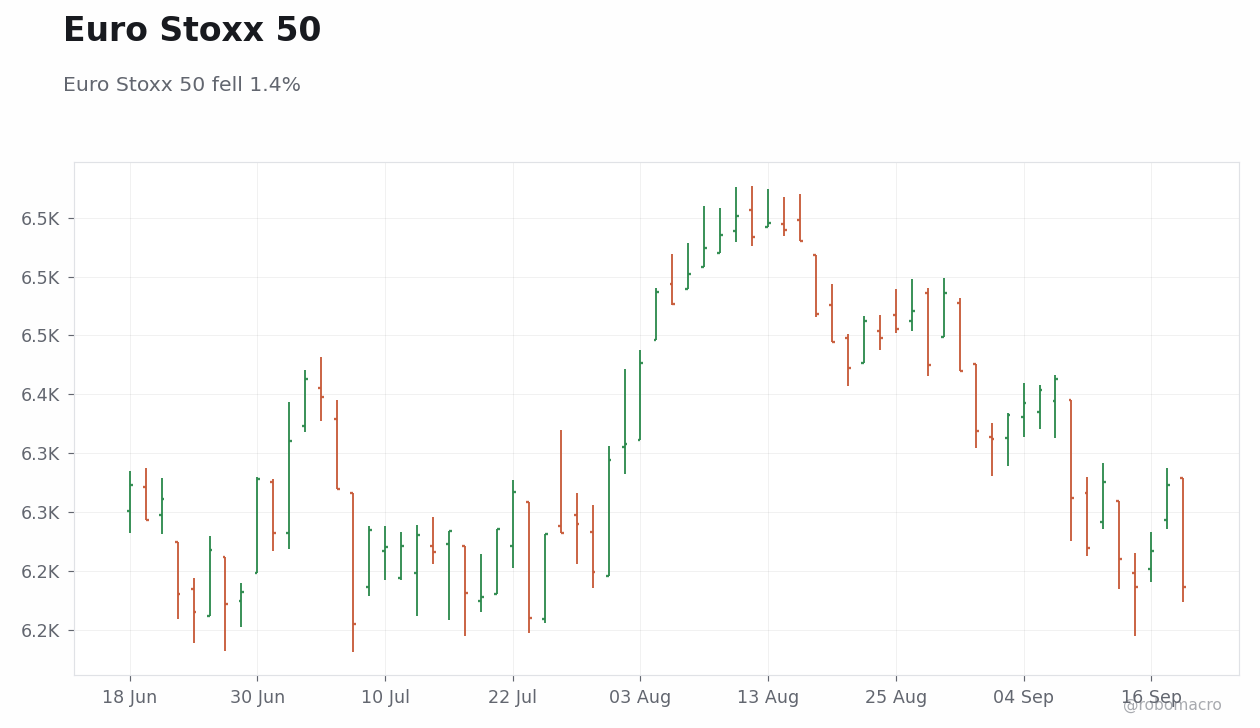
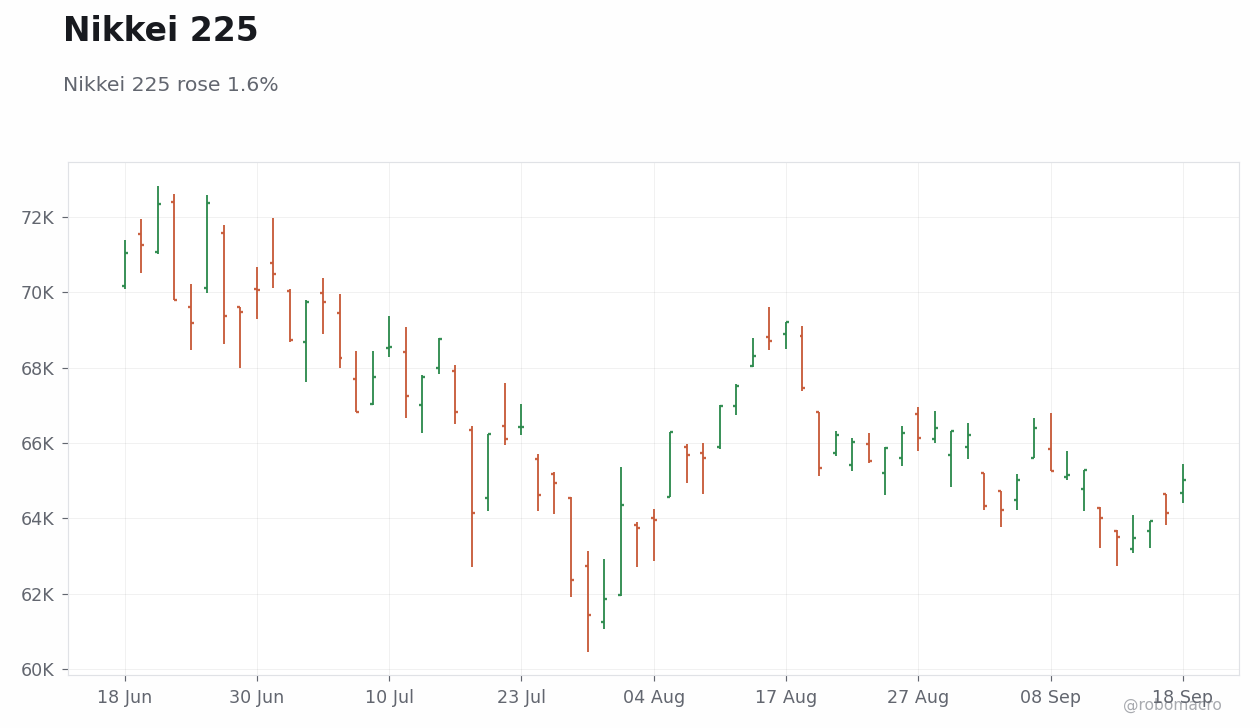
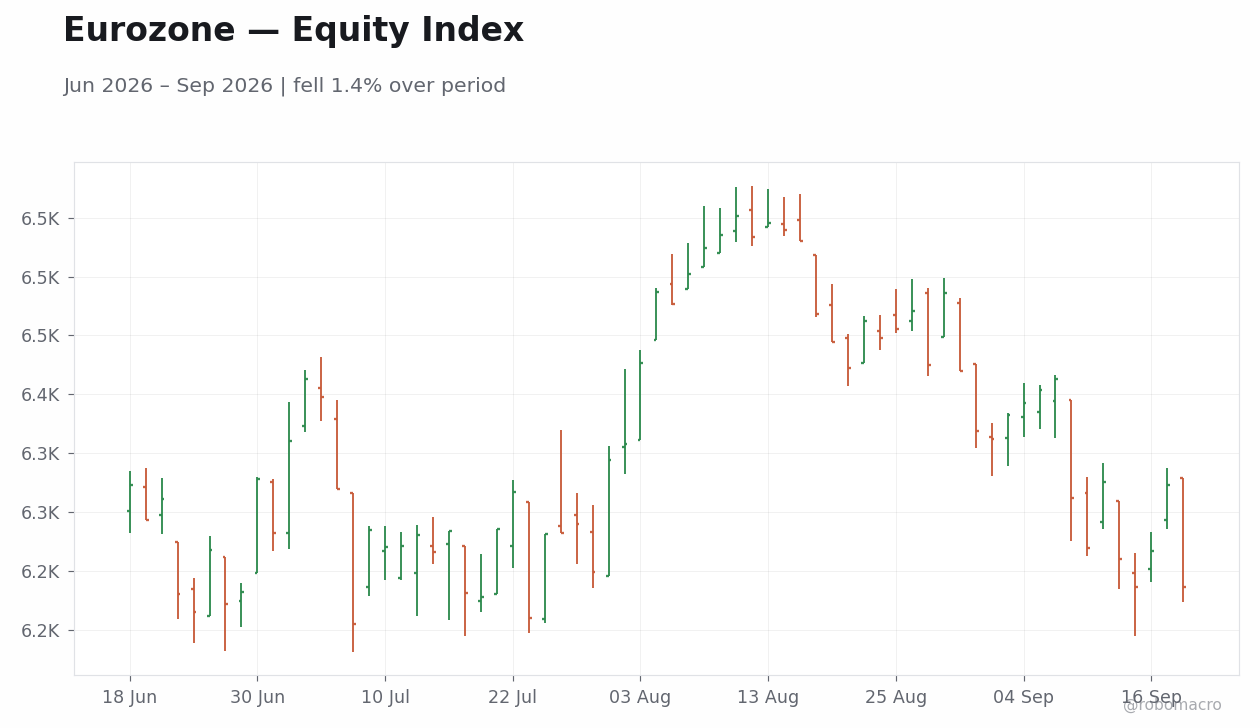
The S&P 500 declined 0.1% on the week to close at 7,650. The index fell from Monday's close of 7,620 to 7,586 on Tuesday and 7,552 on Wednesday before rebounding to 7,638 on Thursday and ending at 7,650 on Friday. US equities were mixed as the Nasdaq 100 gained 0.9% to 29,644 while the Dow Jones fell 1.7% to 51,683 and the Russell 2000 fell 1.5% to 2,860. In Europe the Euro Stoxx 50 declined 1.4% to 6,236 with the DAX down 1.0% to 25,304 and the CAC 40 down 1.4% to 8,065, although the FTSE 100 rose 0.1% to 10,659. Asian equities diverged as the Nikkei 225 advanced 1.6% to 65,019 having risen from 63,493 on Monday, while the Hang Seng fell 0.2% to 24,751. Emerging markets indices generally fell with the Ibovespa down 1.1% to 185,229, the IPC Mexico down 0.9% to 63,376 and the JSE Top 40 down 2.3% to 105,242.
Regional Divergences
Equity performance diverged across regions last week. Asia outperformed with the Nikkei 225 gaining 1.6% compared to losses in Europe where the Euro Stoxx 50 fell 1.4%, the DAX fell 1.0% and the CAC 40 fell 1.4%. The US market was little changed overall with the S&P 500 down 0.1% but with notable underperformance in the Dow Jones at 1.7% lower. These regional differences were connected to persistent French fiscal concerns, mixed momentum signals across the euro area, Japanese equity resilience, and commodity volatility affecting Latin American and South African equities. Emerging market weakness was most pronounced in the JSE Top 40 while Brazilian and Mexican indices reflected external oil volatility and carry-trade flows.
Volatility & Risk Appetite
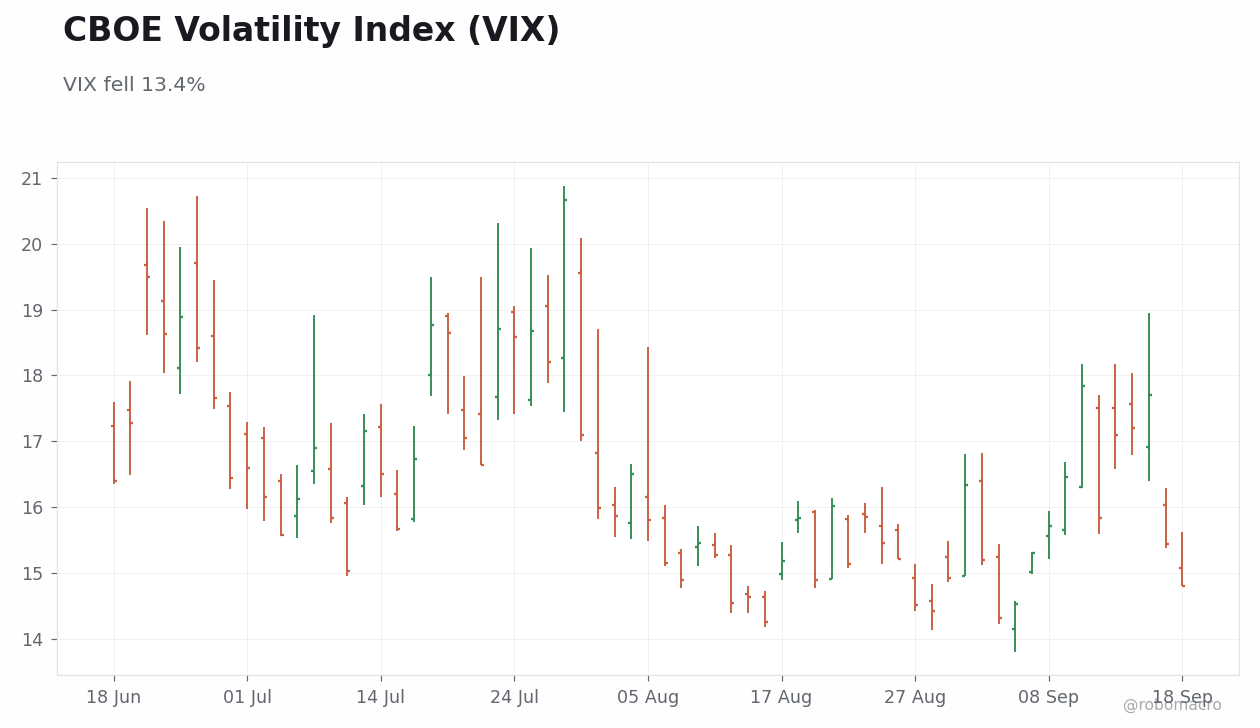
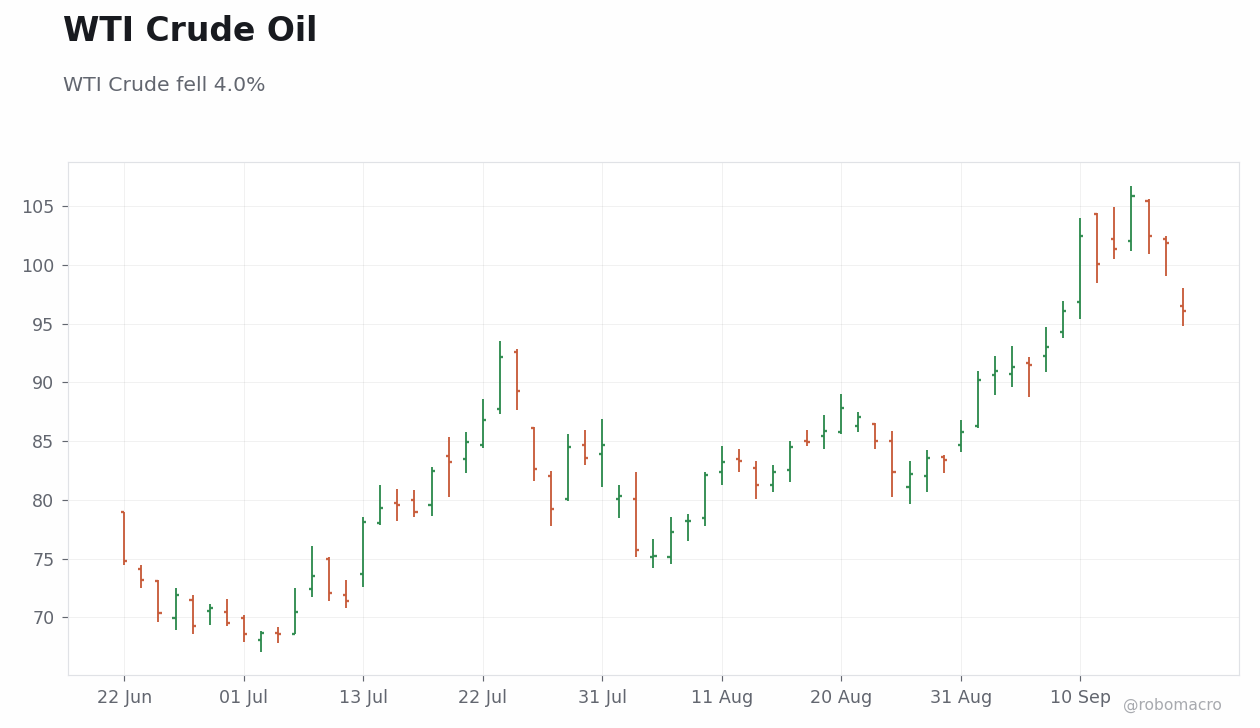
The VIX closed the week at 14.8 on Friday. Growth outperformed value with the Nasdaq 100 rising 0.9% versus the Dow Jones decline of 1.7%. Small caps underperformed large caps as evidenced by the Russell 2000's 1.5% drop against the S&P 500's 0.1% decline. Sector signals from commodity moves highlighted pressure on energy names given WTI Crude's 4.0% decline to 96.08 and Brent Crude's 5.1% fall to 99.29, while Copper's 3.4% gain to 6.69 and Gold's 0.4% rise to 4424.90 indicated better performance for materials and precious metals sectors. Overall risk appetite remained cautious but selective with lower volatility supporting a partial recovery in equities toward the end of the week.
Week Ahead
The economic calendar for the week ahead is quiet with no major data releases highlighted. Corporate earnings reports will take center stage as companies provide updates on performance. Without significant CPI, payrolls or central bank meetings on the schedule, the risk of sudden risk-off moves from hot economic data is reduced. Equity markets may therefore trade on company-specific news and any shifts in global risk sentiment derived from commodity and currency moves.
| Index | Level | WoW | MTD | YTD |
|---|---|---|---|---|
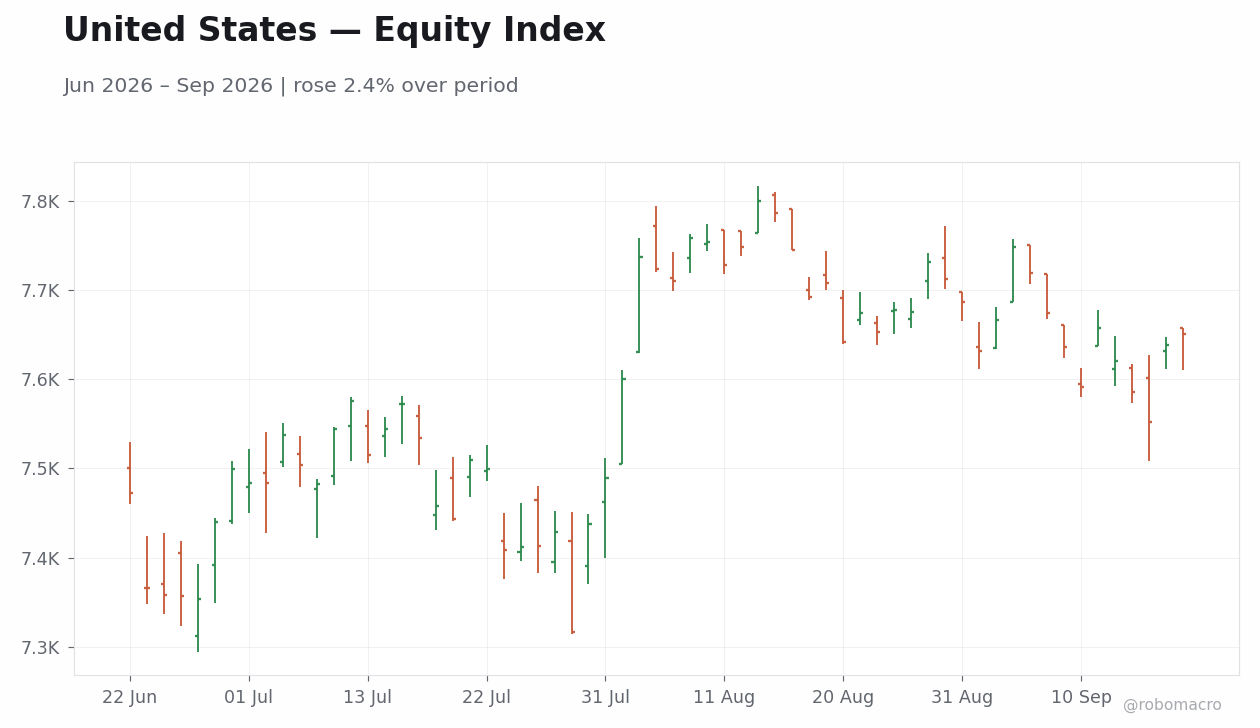
| S&P 500 | 7,650 | -0.1% | +0.2% | +11.6% |
| Nasdaq 100 | 29,644 | +0.9% | +1.9% | +17.6% |
| Dow Jones | 51,683 | -1.7% | -2.0% | +6.8% |
| Russell 2000 | 2,860 | -1.5% | -2.0% | +14.0% |
| S&P/TSX | 35,807 | +0.3% | -0.1% | +12.3% |
| FTSE 100 | 10,659 | +0.1% | -1.2% | +7.1% |
| Euro Stoxx 50 | 6,236 | -1.4% | -2.1% | +5.3% |
| DAX | 25,304 | -1.0% | -2.6% | +3.1% |
| CAC 40 | 8,065 | -1.4% | -2.9% | -1.6% |
| FTSE MIB | 51,545 | -1.8% | -0.7% | +13.6% |
| IBEX 35 | 19,514 | -1.6% | -1.6% | +11.6% |
| Nikkei 225 | 65,019 | +1.6% | -1.8% | +25.4% |
| Hang Seng | 24,751 | -0.2% | -2.3% | -6.0% |
| S&P/ASX 200 | 8,731 | -0.1% | -3.7% | +0.0% |
| KOSPI | 6,894 | -0.2% | +0.8% | +60.0% |
| Nifty 50 | 23,346 | -0.2% | -3.0% | -10.7% |
| Ibovespa | 185,229 | -1.1% | +3.1% | +15.4% |
| IPC Mexico | 63,376 | -0.9% | -1.8% | -1.2% |
| JSE Top 40 | 105,242 | -2.3% | -2.9% | -2.8% |
Global equities posted mixed results in the week of September 14–18. The Nikkei 225 led gains, rising 1.6% to 65,019, while the Nasdaq 100 advanced 0.9% to 29,644. At the other end, the JSE Top 40 fell 2.3% to 105,242 and the Dow Jones dropped 1.7% to 51,683. The Russell 2000 declined 1.5% to 2,860, underperforming the S&P 500 which eased just 0.1% to 7,650. European indices broadly retreated, led by the FTSE MIB’s 1.8% fall to 51,545 and the CAC 40’s 1.4% decline to 8,065. Year-to-date performance remained divergent, with the KOSPI up 60.0% against the Hang Seng’s 6.0% loss. The S&P/TSX edged 0.3% higher to 35,807 while the FTSE 100 added 0.1% to 10,659. Next week’s focus will center on sustaining regional divergences evident in the latest levels.
| Index | WoW | MTD | YTD |
|---|---|---|---|
| S&P 500 | -0.1% | +0.2% | +11.6% |
| Nasdaq 100 | +0.9% | +1.9% | +17.6% |
| Dow Jones | -1.7% | -2.0% | +6.8% |
| Russell 2000 | -1.5% | -2.0% | +14.0% |
| S&P/TSX | +0.3% | -0.1% | +12.3% |
| FTSE 100 | +0.1% | -1.2% | +7.1% |
| Euro Stoxx 50 | -1.4% | -2.1% | +5.3% |
| DAX | -1.0% | -2.6% | +3.1% |
| CAC 40 | -1.4% | -2.9% | -1.6% |
| FTSE MIB | -1.8% | -0.7% | +13.6% |
| IBEX 35 | -1.6% | -1.6% | +11.6% |
| Nikkei 225 | +1.6% | -1.8% | +25.4% |
| Hang Seng | -0.2% | -2.3% | -6.0% |
| S&P/ASX 200 | -0.1% | -3.7% | +0.0% |
| KOSPI | -0.2% | +0.8% | +60.0% |
| Nifty 50 | -0.2% | -3.0% | -10.7% |
| Ibovespa | -1.1% | +3.1% | +15.4% |
| IPC Mexico | -0.9% | -1.8% | -1.2% |
| JSE Top 40 | -2.3% | -2.9% | -2.8% |


Week in Review
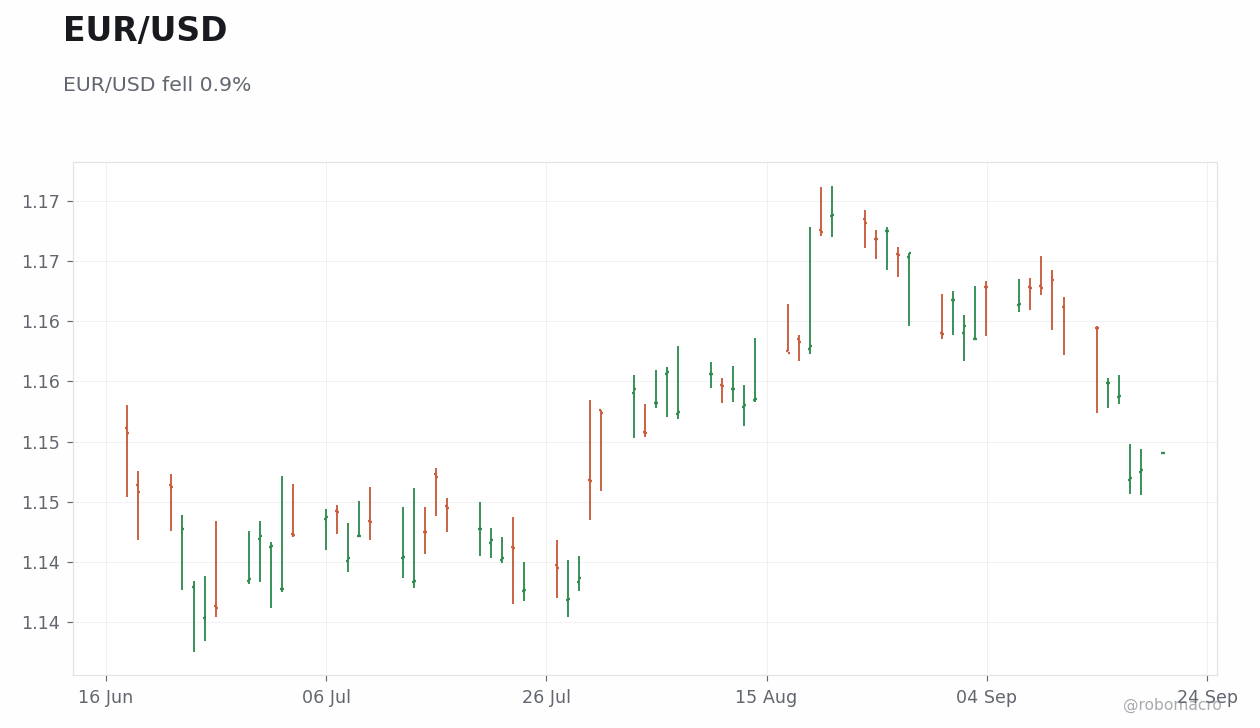
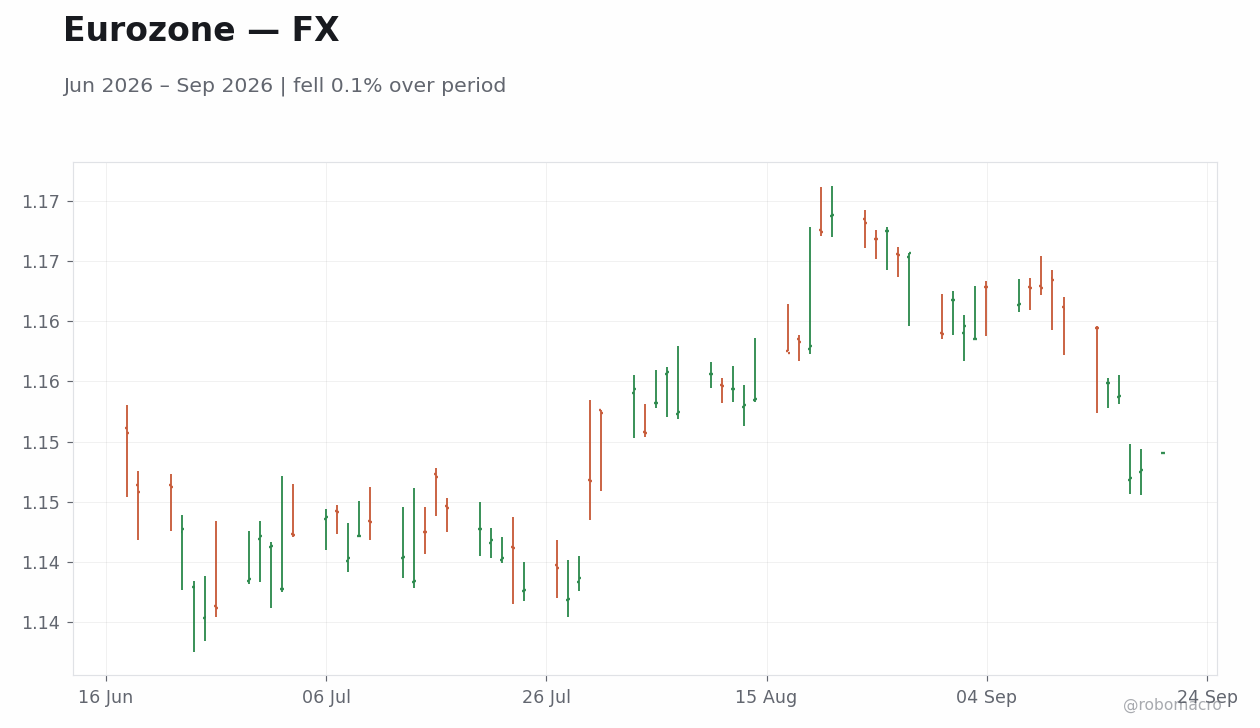
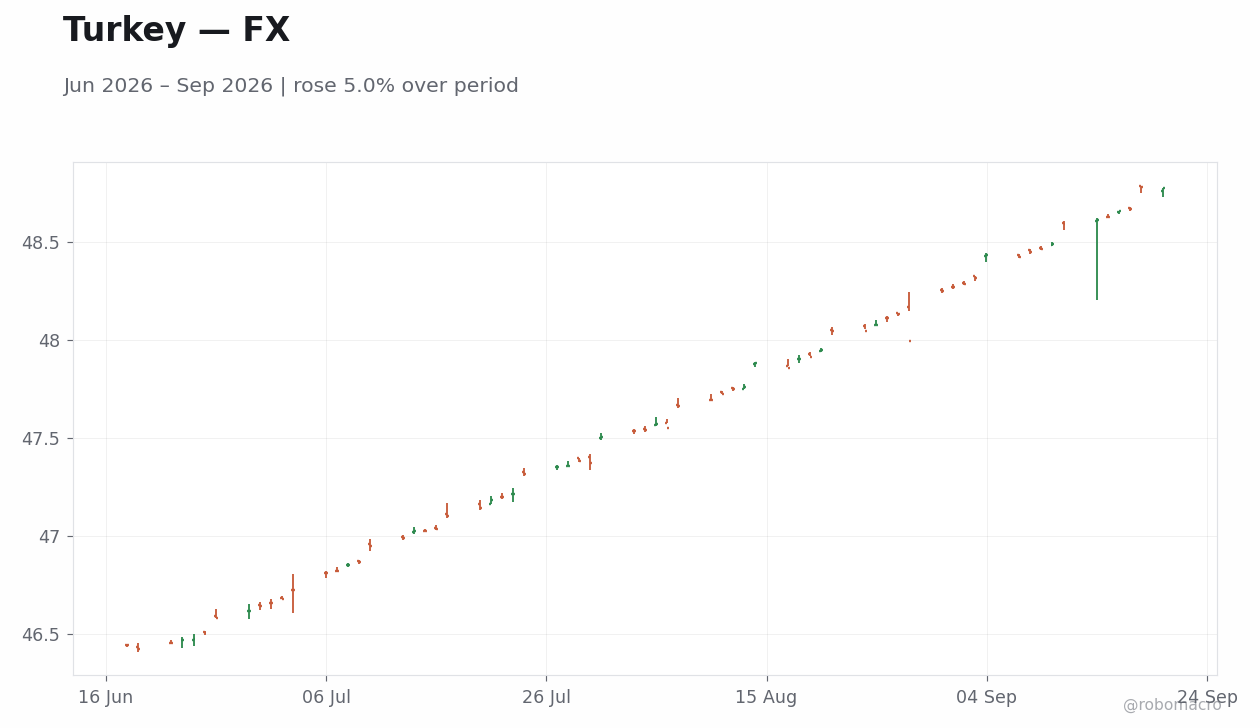
The DXY rose 1.1% on the week to 100.22. The index advanced from 99.7 on Tuesday to 100 on Wednesday and held that level through Friday. In G10 FX, EUR/USD declined 0.9% to 1.1490, falling from 1.1594 on Monday to 1.1476 on Friday. GBP/USD fell 1.0% to 1.3387, sliding from 1.3526 on Monday to 1.3358 on Friday, while USD/JPY surged 2.2% to 156.85, climbing from 153 on Monday to 156 on Friday. Across EM, USD/BRL rose 0.7% to 5.1442, USD/MXN gained 1.3% to 17.20, USD/ZAR rose 0.4% to 16.25, USD/TRY edged higher by 0.3% to 48.77, and USD/CNY eased 0.2% to 6.6970.
Dollar & G10
Favorable shifts in rate differentials supported the dollar’s gains against most G10 currencies. EUR/USD closed the week at 1.1490 after declining 0.9%, while GBP/USD finished at 1.3387, down 1.0% on the week. USD/JPY advanced 2.2% to 156.85, extending its uptrend as the yen remained under pressure. These moves left the DXY at 100.22, reflecting broad-based dollar strength amid divergent rate trajectories across the US, Europe, UK, and Japan.
EM FX
EM FX showed varied performance against the dollar amid falling commodity prices and diverging bond yield differentials. USD/BRL rose 0.7% to 5.1442 and USD/MXN increased 1.3% to 17.20, consistent with softening oil prices pressuring commodity-linked currencies. USD/ZAR gained 0.4% to 16.25 while USD/TRY rose 0.3% to 48.77 as local yield moves diverged from developed markets. USD/CNY bucked the trend, easing 0.2% to 6.6970, highlighting selective resilience in Asian EM FX.
Bitcoin & Crypto
Bitcoin rose 5.7% to $81,202. The cryptocurrency traded at 76,150 on Wednesday, rose to 76,404 on Thursday, surged to 80,901 on Friday, and reached 81,234 on Saturday. Ethereum gained 6.4% to $2,635. Solana outperformed, rising 11.3% to $110, while XRP advanced 5.3% to $1, as digital assets extended their recovery amid improved risk sentiment.
Week Ahead
The economic calendar next week is light, with no major central bank rate decisions scheduled. Any trade balance data from EM countries could influence currency positioning, though no specific releases are listed. Markets will monitor for follow-through from recent US Senate developments on cryptocurrency regulation. No on-chain events or protocol upgrades are highlighted for the period.


Week in Review
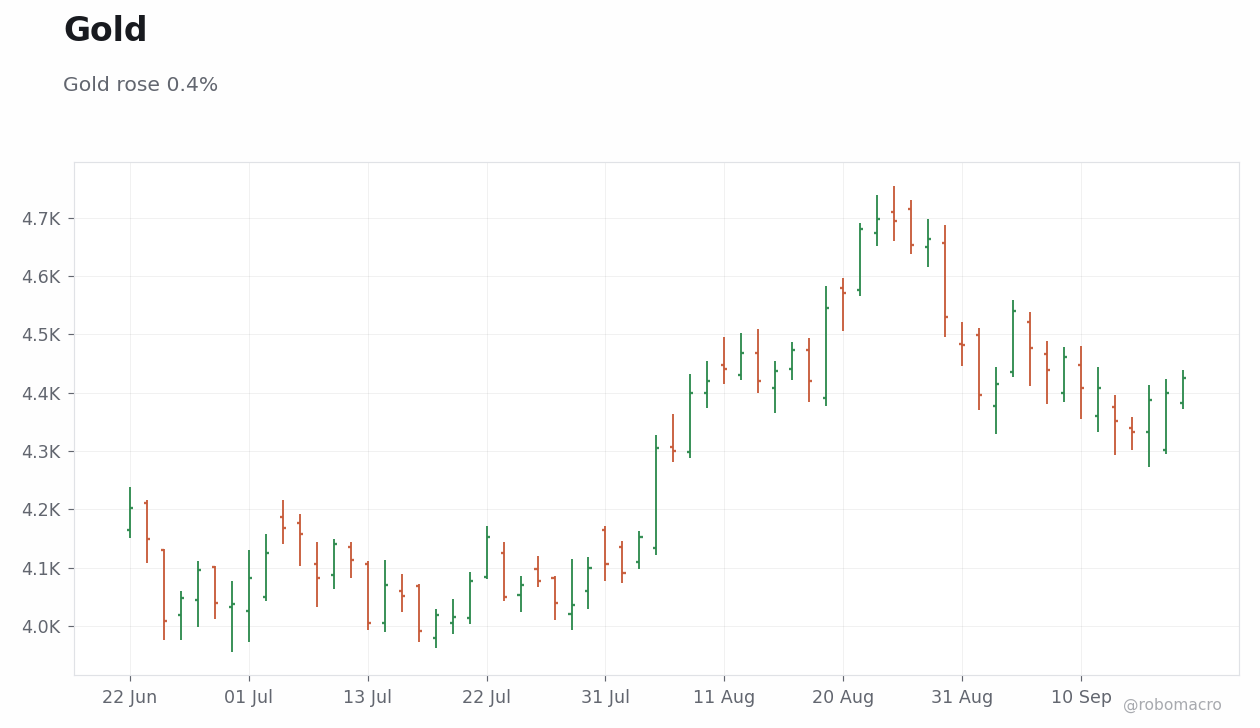
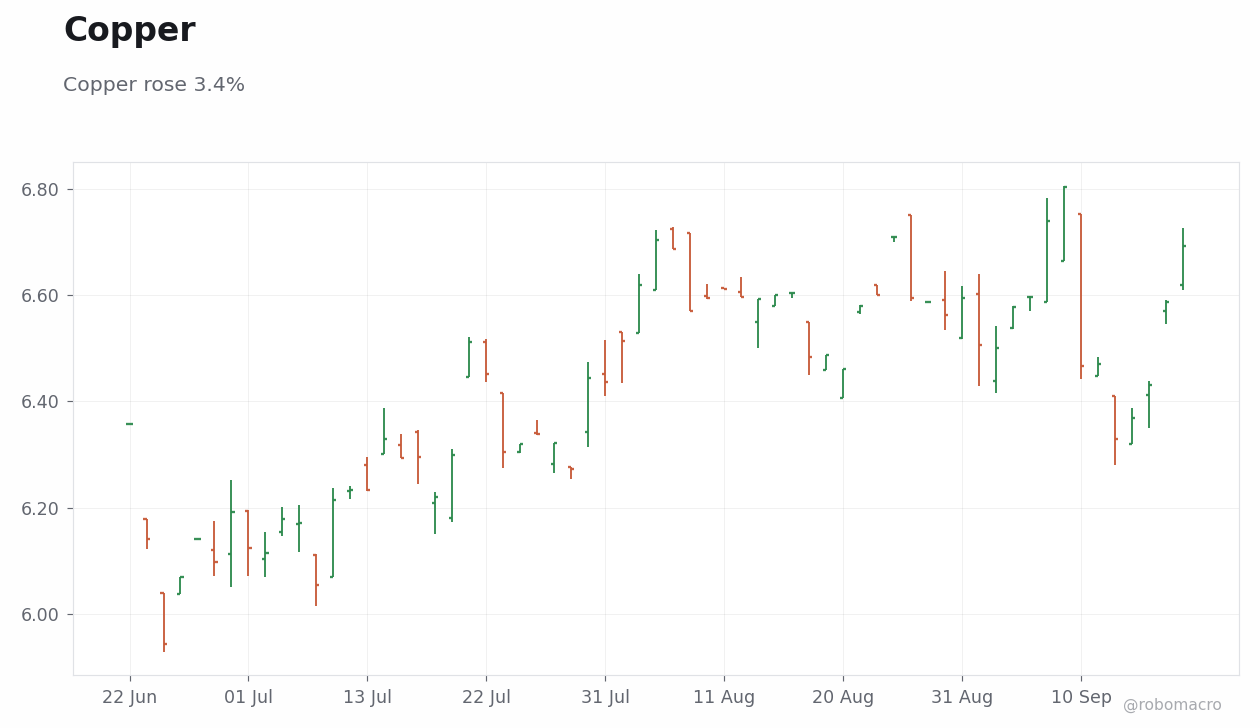
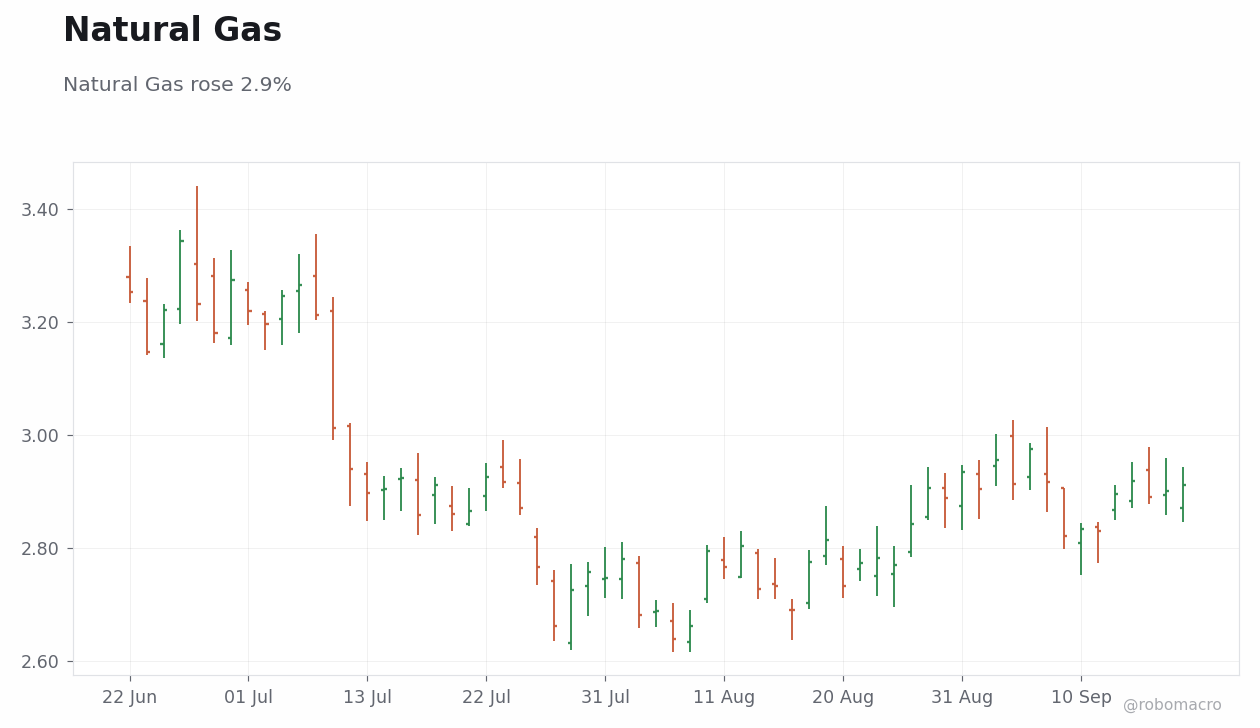
Brent Crude recorded the largest move, falling 5.1% on the week to 99.29. WTI Crude declined 4.0% to 96.08, trading at 106 on Tuesday before moving to 102 on Wednesday, holding at 102 on Thursday and closing at 96.1 on Friday. Gold rose 0.4% to 4424.90, advancing from 4,333 on Tuesday to 4,388 on Wednesday, 4,400 on Thursday and 4,425 on Friday. Silver surged 4.0% to 67.15, climbing from 63.2 on Tuesday to 64.3 on Wednesday, 65.5 on Thursday and 67.1 on Friday. Copper gained 3.4% to 6.69, rising steadily from 6.3685 on Tuesday to 6.4315 on Wednesday, 6.5865 on Thursday and 6.6915 on Friday. Natural gas increased 2.9% to 2.91 while wheat rose 1.0% to 714.25 despite a 6.5% month-to-date decline.
Energy Complex
WTI Crude ended at 96.08 after a 4.0% weekly decline while Brent Crude fell 5.1% to 99.29. Geopolitical tensions remained prominent after an attack on Saudi Arabia’s East-West pipeline disrupted a key route and added pressure to already tight diesel markets. JPMorgan highlighted the absence of a clear endgame for oil markets amid these developments. Natural gas closed at 2.91 after a 2.9% weekly gain, with daily closes showing a move from 2.9190 on Tuesday to 2.8910 on Wednesday before edging higher to 2.9010 on Thursday and 2.9120 on Friday. The complex reflected broader uncertainty even as select non-energy commodities held firmer.
Metals & Ags
Gold rose 0.4% to 4424.90 while silver advanced 4.0% to 67.15, driving a narrowing in the gold-silver ratio as silver outperformed. Daily closes for gold showed consistent gains from 4,333 on Tuesday through to 4,425 on Friday, and silver moved steadily higher from 63.2 to 67.1 across the same period. Copper climbed 3.4% to 6.69, reinforcing a positive growth signal with uninterrupted daily progress from 6.3685 on Tuesday to 6.6915 on Friday. Wheat gained 1.0% to 714.25 on the week, though its 6.5% month-to-date decline highlighted ongoing pressure in agriculture. The divergence between precious metals resilience and industrial metals strength pointed to mixed underlying drivers across the complex.
Week Ahead
The economic calendar next week contains no commodity-relevant events. There are no EIA crude or gas inventory releases, no OPEC meetings, no China PMI or industrial production data, and no US CPI print scheduled that would influence real yields and gold. Central bank meetings capable of moving commodity currencies including CAD, AUD and BRL are also absent. In the absence of scheduled releases, focus will shift to non-calendar risks such as geopolitical developments, weather patterns for natural gas and agriculture, and OPEC diplomacy.
| Pair | Level | WoW | MTD | YTD |
|---|---|---|---|---|
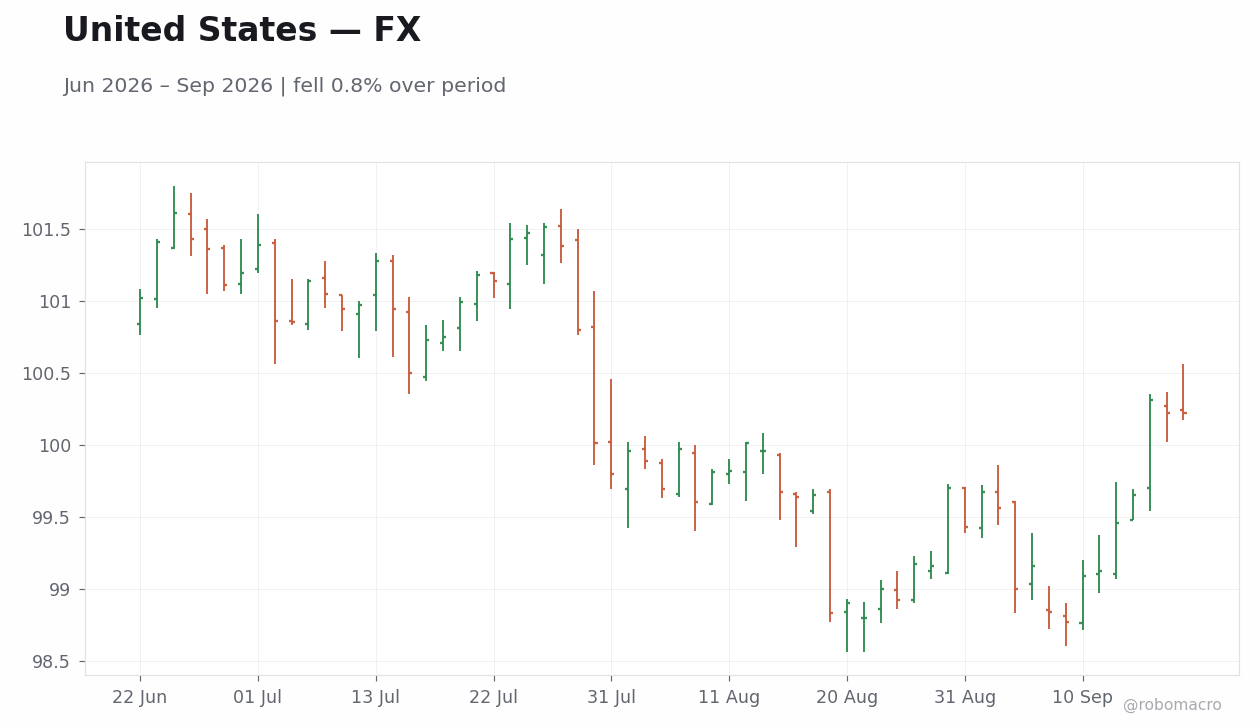
| DXY | 100.22 | +1.1% | +0.6% | +1.8% |
| EUR/USD | 1.1490 | -0.9% | -1.1% | -2.2% |
| GBP/USD | 1.3387 | -1.0% | -1.2% | -0.6% |
| USD/JPY | 156.85 | +2.2% | -1.8% | +0.1% |
| AUD/USD | 0.7121 | -0.4% | -0.7% | +6.6% |
| NZD/USD | 0.5724 | -1.5% | -3.4% | -0.6% |
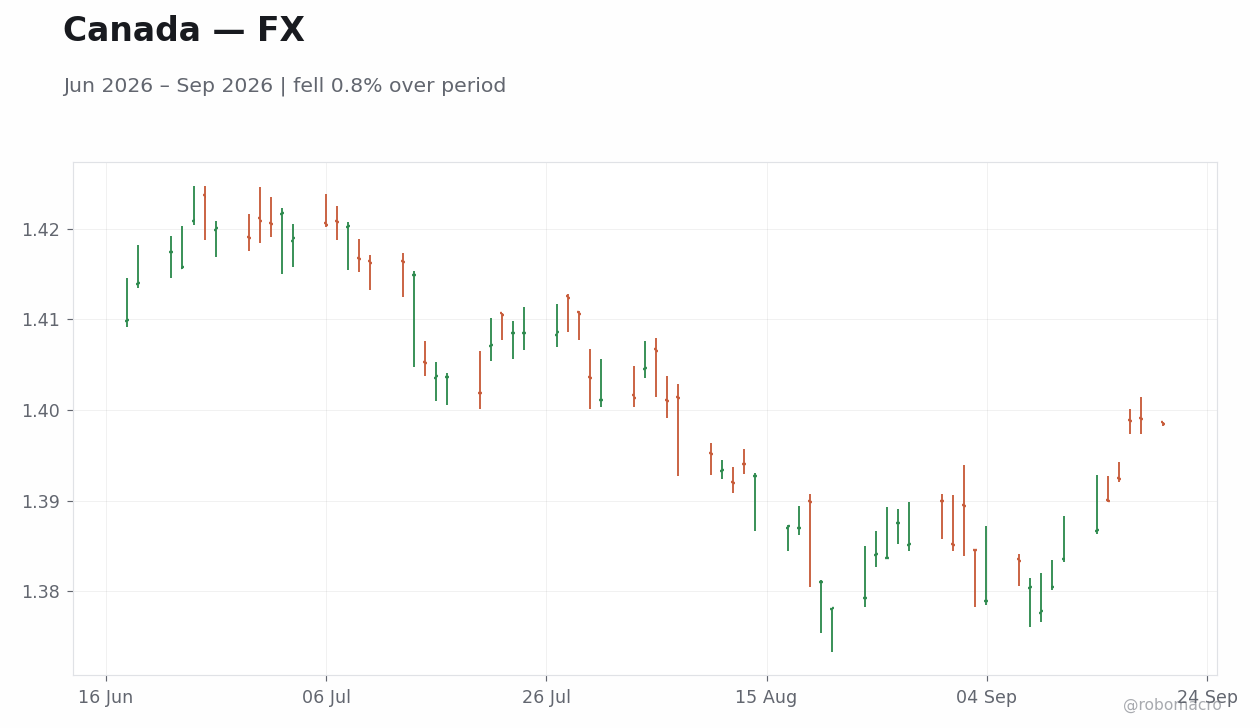
| USD/CAD | 1.3985 | +0.8% | +1.0% | +2.0% |
| USD/CHF | 0.8218 | +1.1% | +1.7% | +3.8% |
| USD/CNY | 6.6970 | -0.2% | -0.4% | -4.3% |
| USD/BRL | 5.1442 | +0.7% | -0.7% | -6.8% |
| USD/MXN | 17.20 | +1.3% | +1.1% | -4.4% |
| USD/INR | 95.86 | +0.9% | +0.8% | +6.6% |
| USD/ZAR | 16.25 | +0.4% | +1.0% | -1.8% |
| USD/TRY | 48.77 | +0.3% | +1.1% | +13.4% |
| Commodity | Level | WoW | MTD | YTD |
|---|---|---|---|---|
| WTI Crude | 96.08 | -4.0% | +6.5% | +67.6% |
| Brent Crude | 99.29 | -5.1% | +4.9% | +63.4% |
| Gold | 4424.90 | +0.4% | +0.7% | +2.2% |
| Silver | 67.15 | +4.0% | +3.9% | -4.8% |
| Copper | 6.69 | +3.4% | +2.8% | +18.6% |
| Natural Gas | 2.91 | +2.9% | +0.3% | -19.5% |
| Wheat | 714.25 | +1.0% | -6.5% | +41.0% |
| Iron Ore | 97.57 | -0.5% | -1.8% | -9.0% |
| Asset | Level | WoW | MTD | YTD |
|---|---|---|---|---|
| Bitcoin | $81,202 | +5.7% | +4.9% | -8.5% |
| Ethereum | $2,635 | +6.4% | +9.0% | -12.2% |
| Solana | $110 | +11.3% | +10.4% | -12.9% |
| XRP | $1 | +5.3% | +4.5% | -24.8% |
DXY climbed 1.1% to 100.22, led by USD/JPY’s 2.2% jump to 156.85. EUR/USD slipped 0.9% to 1.1490 and GBP/USD fell 1.0% to 1.3387, while NZD/USD posted the largest decline at 1.5% to 0.5724. USD/CAD rose 0.8% to 1.3985 and USD/MXN advanced 1.3% to 17.20, extending the greenback’s broad advance. USD/CHF matched DXY’s gain with a 1.1% increase to 0.8218. In contrast, USD/CNY eased 0.2% to 6.6970, the only major pair to post a weekly decline against the dollar. USD/INR added 0.9% to 95.86 and USD/TRY rose 0.3% to 48.77, underscoring divergent EM performance. Markets will next focus on upcoming central-bank communications and U.S. data releases for further USD direction.
| Asset | Level | WoW |
|---|---|---|
| S&P 500 | 7650.5 | +0.4% |
| Nasdaq 100 | 29644.17 | +1.8% |
| Dow Jones | 51682.64 | -1.4% |
| Russell 2000 | 2860.4 | -1.1% |
| USD/JPY | 156.85 | +2.2% |
| EUR/USD | 1.15 | -0.9% |
| GBP/USD | 1.34 | -1.0% |
| Gold | 4424.9 | +1.7% |
| WTI Crude | 96.08 | -5.2% |
| Bitcoin | 81175.48 | +5.6% |


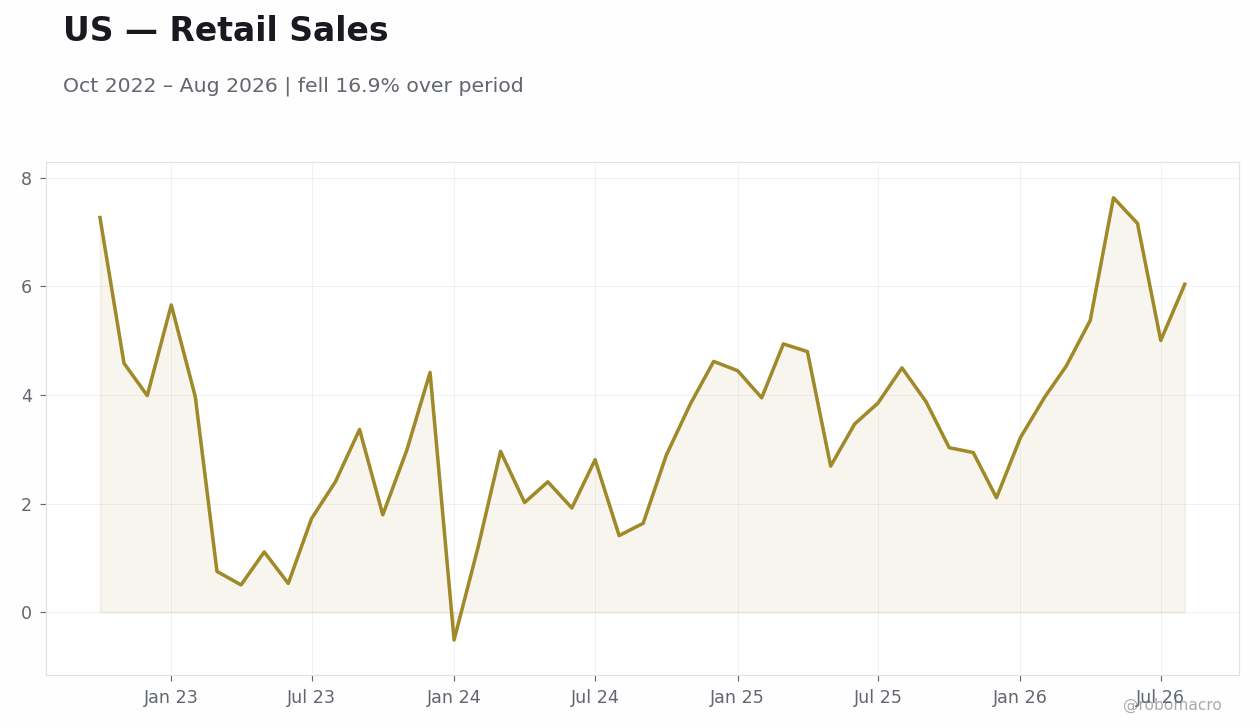
Retail Sales Surprise Lifts Growth Outlook US data releases were absent this week. Consumer resilience continued to support the growth outlook.
FOMC Tightens Policy Amid Persistent Inflation The FOMC maintained its data-dependent stance. Markets absorbed policy signals without immediate reversal in positioning.
Energy Prices Drive Cross-Asset Volatility WTI crude declined on the week after an earlier spike. The move lifted shorter-dated Treasury yields intraday before reversing. Equity indices posted mixed daily moves but ended mixed on net.
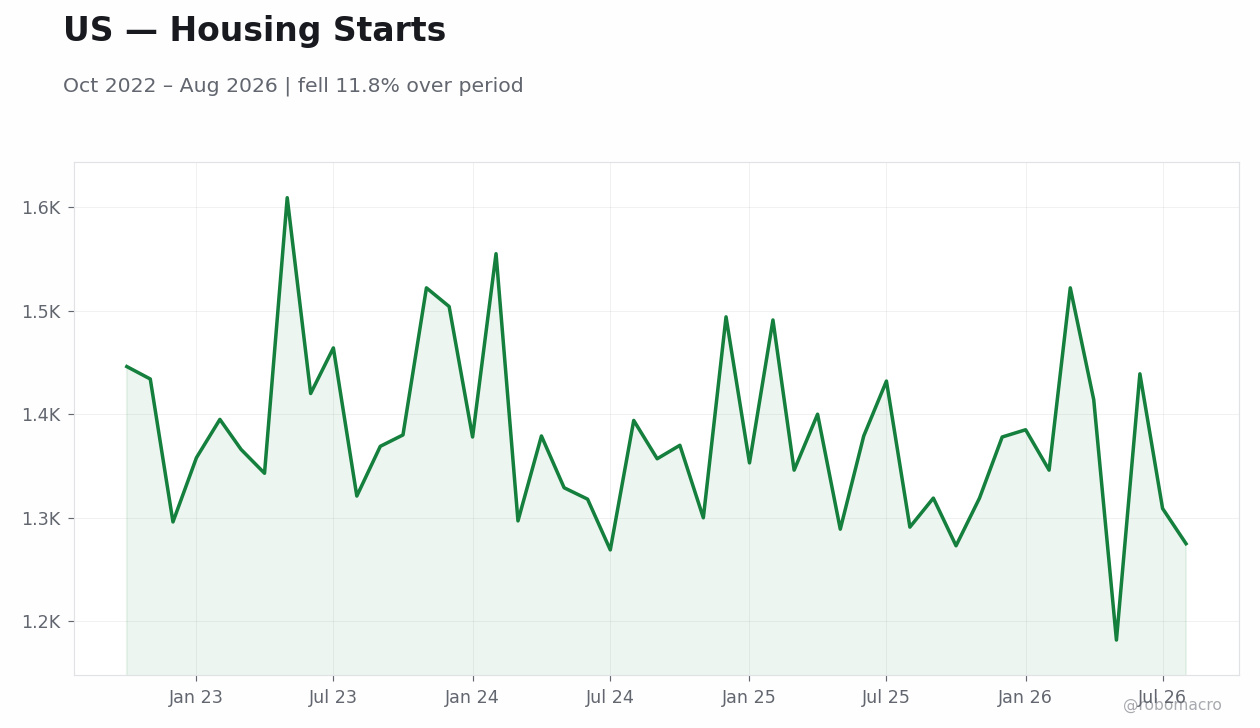
Labor and Regional Data Diverge Regional manufacturing indicators softened. Housing metrics showed mixed momentum. These releases reinforced the data-dependent policy stance.
The FOMC maintained its data-dependent stance. The decision arrived against a backdrop of resilient consumer demand and softening regional manufacturing indicators. Treasury yields rose following earlier energy-price moves. Forward guidance remained focused on incoming inflation and employment prints. The configuration extends the tightening cycle while leaving the medium-term path tethered to the next round of activity and price data.
Market pricing reflected resilient risk appetite in select equity indices alongside energy-price volatility. WTI crude declined after an earlier advance. Treasury yields moved higher across the curve. The configuration supports a data-dependent policy approach while imported energy costs remain a watch item.
Calendar data unavailable
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-21 | Chicago Fed National Activity Index | - | - |
| 2026-09-22 | ADP Employment Change Weekly | - | - |
| 2026-09-22 | API Weekly Crude Oil Stocks | - | - |
| 2026-09-23 | MBA 30-Year Mortgage Rate | - | - |
| 2026-09-23 | S&P Global Composite PMI Flash | - | - |
| 2026-09-23 | S&P Global Manufacturing PMI Flash | - | - |
| 2026-09-23 | S&P Global Services PMI Flash | - | - |
| 2026-09-23 | EIA Weekly Crude Oil Inventory | - | - |
| 2026-09-23 | EIA Weekly Gasoline Inventory | - | - |
| 2026-09-24 | Current Account Balance | -226.8bn | - |


Monday features a speech by a Fed official alongside the Chicago Fed National Activity Index. Tuesday brings ADP Employment Change Weekly along with additional Fed speakers. Wednesday includes the S&P Global Composite, Manufacturing, and Services PMI Flash prints plus EIA crude inventory data. Thursday offers the usual round of jobless claims and housing metrics. Friday closes the period with no high-impact releases scheduled. Markets will scrutinize the PMI flash readings for confirmation of manufacturing trends and any updates on services resilience. Fed speakers will provide further color on the policy reaction function.
Oil’s weekly decline eases imported inflation pressure relative to the prior advance but leaves volatility elevated. Positioning in equities remains constructive after the net S&P 500 gain, yet higher Treasury yields suggest limited room for further duration extension. Upside inflation surprises could keep the policy rate path steeper than currently priced, while labor softening would support the data-dependent equilibrium. Flow considerations favor energy-exposed sectors on any rebound in crude. The configuration leaves markets sensitive to the next PMI and employment prints.
Equities closed the week with the S&P 500 rising 0.4% net. The Nasdaq 100 rose 1.78% while the Dow Jones fell 1.41%. Bonds saw the 2-year Treasury yield climb and the 10-year reach higher levels. FX markets featured USD/JPY advancing 2.24% while EUR/USD declined 0.89%. Commodities showed WTI crude dropping 5.24% after an earlier peak, while gold rose 1.68%. Bitcoin gained 5.64%. The oil reversal supported risk assets into the weekend.
Energy price swings dominated cross-border spillovers, with WTI moving lower over the seven days. Prior-week Brent levels continued to influence imported inflation expectations in net-energy importers. Trade-related commentary around US tariffs on select goods resurfaced in emerging-market data flows. Geopolitical announcements added modest risk-on tone to select commodity names without altering broader positioning.
| Asset | Level | WoW |
|---|---|---|
| Euro Stoxx 50 | 6236.2 | -0.4% |
| DAX | 25304.06 | -0.5% |
| CAC 40 | 8065.02 | -0.7% |
| EUR/USD | 1.15 | -0.9% |
| EUR/GBP | 0.86 | +0.1% |
| EUR/JPY | 179.97 | +1.2% |
| Gold | 4424.9 | +1.7% |
| Brent Crude | 99.29 | -6.0% |
| Bitcoin | 81162.44 | +5.6% |


Fiscal pressures intensify in France French officials revised the growth forecast lower and confirmed the budget deficit would exceed target levels, triggering wider sovereign spreads over German Bunds. These developments coincided with a quiet data calendar.
German price data surprises to the upside No wholesale price or sentiment readings were released. Italian trade data provided an offset through a wider surplus.
Equities and yields diverge amid energy moves The Euro Stoxx 50 posted a net decline for the week while the DAX also fell. German 2-year yields ended lower. Brent crude’s decline removed some near-term imported inflation pressure.
Political and external sector signals remain mixed Domestic political developments highlighted ongoing headwinds without immediate policy shifts. The euro finished lower against the dollar. No ECB speakers appeared on the calendar during the five-day period.
The ECB maintained its data-dependent approach to the deposit rate, which remained unchanged with no speakers or minutes released during the week. French fiscal concerns reinforced the case for monitoring incoming prints before any adjustment. ZEW and trade data provided mixed signals that did not shift the medium-term rate path. Officials continued to emphasize incoming prints on inflation and growth rather than pre-committing to near-term moves. The absence of new forward guidance left markets focused on the upcoming flash PMIs and IFO release. Energy-price volatility added another layer to the inflation outlook without prompting immediate recalibration. The policy stance remains balanced between persistent price pressures and softening sentiment indicators.
No high-impact data prints occurred across the major member states. French fiscal revisions added downside risk to the growth outlook without altering the ECB’s data-dependent stance on the deposit rate. The configuration leaves the cycle in a mid-phase where political uncertainty coexists with softening sentiment indicators.
Calendar data unavailable
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-22 | Consumer Confidence Index | -34.0 | - |
| 2026-09-22 | Trade Balance | -7.7bn | - |
| 2026-09-23 | S&P Global Composite PMI Flash | - | - |
| 2026-09-23 | S&P Global Manufacturing PMI Flash | - | - |
| 2026-09-23 | S&P Global Services PMI Flash | - | - |
| 2026-09-23 | S&P Global Manufacturing PMI Flash | - | - |
| 2026-09-23 | S&P Global Composite PMI Flash | - | - |
| 2026-09-23 | S&P Global Services PMI Flash | - | - |
| 2026-09-24 | Business Confidence | 103 | - |
| 2026-09-24 | Consumer Confidence Index | - | - |
Flash PMIs for France, Germany, and the euro area are scheduled, alongside the Netherlands unemployment rate, France business and consumer confidence figures, Germany’s IFO Business Climate Level, and GfK Consumer Confidence. Spanish trade balance and additional French PMI details round out the calendar. These releases will inform the growth and inflation outlook ahead of the next ECB decision. Deviations in the flash PMIs are expected to drive near-term Bund yield and euro moves.
French fiscal slippage and widening spreads represent the clearest near-term downside risk to euro-area cohesion. Political setbacks may delay reform momentum and weigh on business confidence. Brent’s weekly decline reduces imported inflation pressure but leaves energy-exposed sectors vulnerable to reversal. Positioning appears light on euro-area duration given the yield decline, while equity flows favored defensives. Upside surprises in flash PMIs could support a modest re-pricing of the rate path, whereas further fiscal headlines would likely pressure peripheral spreads. Volatility remains elevated around political and energy developments.
Euro Stoxx 50 closed lower on the week while the DAX and CAC 40 also declined. German 10-year Bund yields eased and the 2-year yield moved lower. EUR/USD ended lower, EUR/GBP rose modestly, and EUR/JPY gained ground. Brent crude fell sharply after trading higher earlier in the week, while gold advanced. Daily equity moves were mixed. The French spread widening drove the divergent bond and equity reaction.
Brent crude’s decline removed some imported inflation pressure across net-energy importers. EUR/USD weakness reflected broader dollar strength amid divergent growth signals. Gold’s advance underscored ongoing safe-haven demand. No major trade or geopolitical events altered cross-border flows in the past seven days beyond the energy-price move.
| Asset | Level | WoW |
|---|---|---|
| Nikkei 225 | 65018.95 | +2.4% |
| USD/JPY | 156.85 | +2.2% |
| EUR/JPY | 179.97 | +1.2% |
| GBP/JPY | 209.31 | +0.9% |
| Gold | 4424.9 | +1.7% |
| Brent Crude | 99.29 | -6.0% |
| Bitcoin | 81180.57 | +5.7% |


Policy Decision and Market Reaction Markets registered the policy rate outcome with the Nikkei 225 closing the week higher by 2.4 percent. USD/JPY finished higher by 2.24 percent while Japan 10-year government yields moved little changed.
External Demand Data Trade and orders data released during the week showed external and capex weakness that tempered expectations for an aggressive follow-up step at the next meeting.
Inflation and Price Trends August inflation data indicated the first slowdown in four months. Producer price pressures remained supportive of further tightening. Brent crude declined 6.05 percent week-over-week, reducing imported inflation risks.
Equity and Currency Flows The Nikkei 225 rose over the five sessions, supported by the policy outcome. USD/JPY moved higher, reflecting the post-decision environment. Gold advanced 1.68 percent while Bitcoin gained 5.65 percent over the same period.
The Bank of Japan raised the policy rate after reviewing August inflation that slowed for the first time in four months. No board member speeches or minutes were released during the week, leaving the decision statement and Governor Ueda’s press conference as the primary signals. Trade balance and machinery orders data showed external and capex weakness that tempered expectations for an aggressive follow-up step at the next meeting. Officials emphasized data dependence, noting that incoming prints on activity and prices will guide the pace of additional normalization. The decision reinforced the gradual tightening path without altering the focus on incoming quarters’ data flow.
Calendar data unavailable
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-23 | S&P Global Manufacturing PMI Flash | - | - |
| 2026-09-23 | S&P Global Services PMI Flash | - | - |
| 2026-09-27 | BoJ Monetary Policy Meeting Minutes | - | - |

S&P Global Manufacturing PMI Flash and Services PMI Flash are scheduled for September 23 and will provide the first read on third-quarter activity momentum. Bank of Japan Monetary Policy Meeting Minutes from the recent decision are due on September 27 and will detail the board’s assessment of inflation trends and external risks. These releases arrive ahead of the next meeting and will inform views on whether the policy rate requires further adjustment in coming quarters. Softer PMI outcomes could reinforce the case for a measured pace, while resilient prints may support continued normalization. Cross-border capital flow dynamics will remain sensitive to any divergence between Japanese and global activity signals.
External demand data highlight downside risks to growth if sustained into coming quarters. Brent crude’s weekly decline reduces near-term imported inflation pressures but leaves the economy exposed to renewed energy volatility. Machinery orders missing consensus on both month-over-month and year-over-year bases signal potential capex softening that may require offsetting domestic demand strength. Equity market resilience suggests limited immediate concern over policy tightening, though any acceleration in yen strength could pressure exporters.
| Asset | Level | WoW |
|---|---|---|
| S&P/TSX | 35806.7 | +0.3% |
| USD/CAD | 1.4 | +0.8% |
| EUR/CAD | 1.61 | -0.1% |
| WTI Crude | 96.08 | -5.2% |
| Natural Gas | 2.91 | +0.6% |
| Gold | 4424.9 | +1.7% |
| Brent Crude | 99.29 | -6.0% |
| Bitcoin | 81199.99 | +5.7% |


Limited data releases No high-impact Canadian economic releases were scheduled during the week.
Equity and currency response The S&P/TSX Composite closed the week at 35806.7, up 0.29% from the prior Friday, while USD/CAD rose 0.85% to 1.40.
Commodity reversal WTI crude declined to 96.08 and Brent crude declined to 99.29.
Policy signal from data flow With no major domestic prints, the Bank of Canada’s data-dependent stance remained unchanged. Markets focused on external tariff developments.
The Bank of Canada maintained its policy stance through the period. With no major domestic data releases, officials continued to emphasize monitoring of incoming information and external trade developments.
Calendar data unavailable
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-23 | New Housing Price Index Month-over- | -0.10 | - |
| 2026-09-24 | Retail Sales Month-over-Month Final | 0.60 | - |
| 2026-09-24 | Retail Sales Month-over-Month Preli | -0.80 | - |
| 2026-09-24 | Retail Sales excluding Autos Month- | 0.50 | - |


Retail Sales excluding Autos Month-over-Month and Retail Sales Month-over-Month Final are scheduled for release on September 24. These prints will provide an update on consumer spending momentum. Stronger-than-expected results could support steady policy at the next Bank of Canada meeting. Weaker figures would add to evidence of softening activity. No other high-impact Canadian releases are listed for the period. Market participants will also track any further commentary on tariff effects and their potential transmission to growth and inflation.
The decline in WTI and Brent introduces downside risk to near-term inflation prints while also easing imported price pressures. Trade tensions remain the dominant external variable. The data flow this week supports a cautious outlook where retail sales outcomes could influence expectations around the timing of any policy adjustment.
| Asset | Level | WoW |
|---|---|---|
| IPC Bolsa | 63375.93 | -1.3% |
| USD/MXN | 17.19 | +1.3% |
| EUR/MXN | 19.78 | +0.4% |
| WTI Crude | 96.08 | -5.2% |
| Silver | 67.15 | +5.7% |
| Gold | 4424.9 | +1.7% |
| Brent Crude | 99.29 | -6.0% |
| Bitcoin | 81199.98 | +5.7% |


Quiet Calendar Leaves Markets to External Drivers The week delivered an empty domestic data docket, with zero scheduled releases for inflation, activity, labor, or trade. Markets therefore tracked global oil moves and cross-border positioning. IPC Bolsa declined on the week. USD/MXN advanced, reversing part of the prior appreciation.
Oil Price Reversal Weighs on Sentiment WTI Crude and Brent Crude posted sharp weekly declines. These moves reduced near-term support for energy-linked fiscal revenues and equity flows. The 5Y government yield rose amid thin trading, widening the spread versus the policy rate and signaling higher term premium in the absence of fresh inflation or growth prints.
Peso and Equity Divergence Persists EUR/MXN moved higher while Bitcoin posted a gain that provided limited offset to local risk assets. The absence of any Banxico minutes, speeches, or rate signals kept expectations anchored at the prevailing policy rate. Nearshoring updates highlighted ongoing private projects, yet external regulatory requests introduced incremental friction without altering the week’s thin-volume price action.
Yield Curve and Carry Dynamics Short-term rates remained stable while the 5Y segment bore the brunt of the week’s modest risk reduction. Remittance inflows and steady USMCA trade flows continued to underpin the current account, though no new monthly figures were released to quantify the buffer. Overall, the data-empty week reinforced the prior multi-week pattern of tolerance for divergent external prints without immediate domestic policy recalibration.
Banco de Mexico held the policy rate unchanged with no speakers, minutes, or forward-guidance updates during the week. The empty calendar provided no new inflation or activity signals to alter the data-dependent stance. Mexico 5Y yields rose while the policy rate stayed unchanged, widening the spread and reflecting term-premium adjustments rather than any shift in official communication. Prior comments on currency pressure and export margins remain the most recent domestic input into the rate path, with no subsequent prints to modify that assessment. The configuration leaves the upcoming decision window dependent on the next batch of activity and price data rather than this week’s flow.
Calendar data unavailable
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-24 | Central Bank Interest Rate Decision | 6.5 | - |

The upcoming Central Bank Interest Rate Decision will provide the first policy signal in several weeks. With no domestic releases scheduled between now and then, attention will center on whether incoming global energy prices and US data surprises alter the assessment of imported inflation risks. Any commentary around the decision will likely reiterate data dependence for coming quarters. Market participants will also monitor USMCA-related statements and nearshoring project updates for their potential impact on growth forecasts. The absence of fresh inflation or unemployment prints keeps the focus on external drivers ahead of the decision. Subsequent weeks will bring the next round of activity indicators that feed directly into the rate-path evaluation.
Sharp weekly declines in WTI and Brent highlight downside energy-price risk that could ease imported inflation pressures but also reduce fiscal revenue visibility. External pressure on technology export controls introduces a new regulatory layer that may slow nearshoring execution without derailing the broader investment pipeline. Peso weakening and the 5Y yield rise suggest markets are repricing term premium faster than the data-dependent policy stance can adjust. Upside scenarios rest on sustained remittance and trade flows supporting the current account, while downside risks center on further oil volatility feeding through to growth expectations in coming quarters.
| Asset | Level | WoW |
|---|---|---|
| Bovespa | 185229.0 | -0.1% |
| USD/BRL | 5.14 | +0.7% |
| EUR/BRL | 5.91 | -0.3% |
| Vale | 14.21 | -2.7% |
| Petrobras | 20.8 | -1.6% |
| WTI Crude | 96.08 | -5.2% |
| Gold | 4424.9 | +1.7% |
| Bitcoin | 81199.98 | +5.7% |


Market action reflected external commodity pressure. WTI crude declined 5.24% to 96.08, weighing on Petrobras, which fell 1.65% to 20.8. Equity and FX moves remained contained. Bovespa posted a 0.15% weekly decline to 185229 amid intraday swings, while USD/BRL rose 0.65% to 5.14. External assets provided contrast. Gold advanced 1.68% to 4424.9 and Bitcoin rose 5.68% to 81199.98. The week’s price action centered on commodity reversal rather than domestic data surprises.
Domestic activity indicators showed softening momentum that aligns with extension of the easing cycle. No officials spoke publicly during the week. The absence of fresh high-impact data leaves external conditions, including commodity prices and global growth signals, as the primary inputs for the balance-of-risks assessment in coming quarters.
Calendar data unavailable
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-22 | BCB Copom Meeting Minutes | - | - |

No high-impact Brazilian releases are scheduled through September 27. Focus shifts to external commodity prices and global risk sentiment, which will influence Vale and Petrobras performance and imported inflation dynamics. Iron-ore and oil stability remain central to export earnings and the inflation outlook. Market participants will monitor any external growth signals that could alter the balance of risks for the central bank’s medium-term policy path.
The WTI crude decline to 96.08 reduces imported inflation pressure but could weigh on fiscal revenues if sustained. Election-related fiscal measures introduce upside risk to spending that may complicate debt dynamics even as lower policy rates reduce debt-service costs. Drought conditions in key basins add downside risk to agricultural output and hydropower generation, with potential pass-through to food prices. Markets appear to underweight the persistence of domestic demand softening, which could support a longer easing cycle. Upside scenarios rest on commodity stabilization supporting export earnings, while downside scenarios center on fiscal slippage or renewed energy volatility.
| Asset | Level | WoW |
|---|---|---|
| MERVAL | 3021926.0 | -2.0% |
| USD/ARS | 1514.0 | +0.4% |
| EUR/ARS | 1739.12 | +2.1% |
| Gold | 4424.9 | +1.7% |
| Brent Crude | 99.29 | -6.0% |
| Soybean | 1303.5 | +1.4% |
| Bitcoin | 81194.2 | +5.7% |


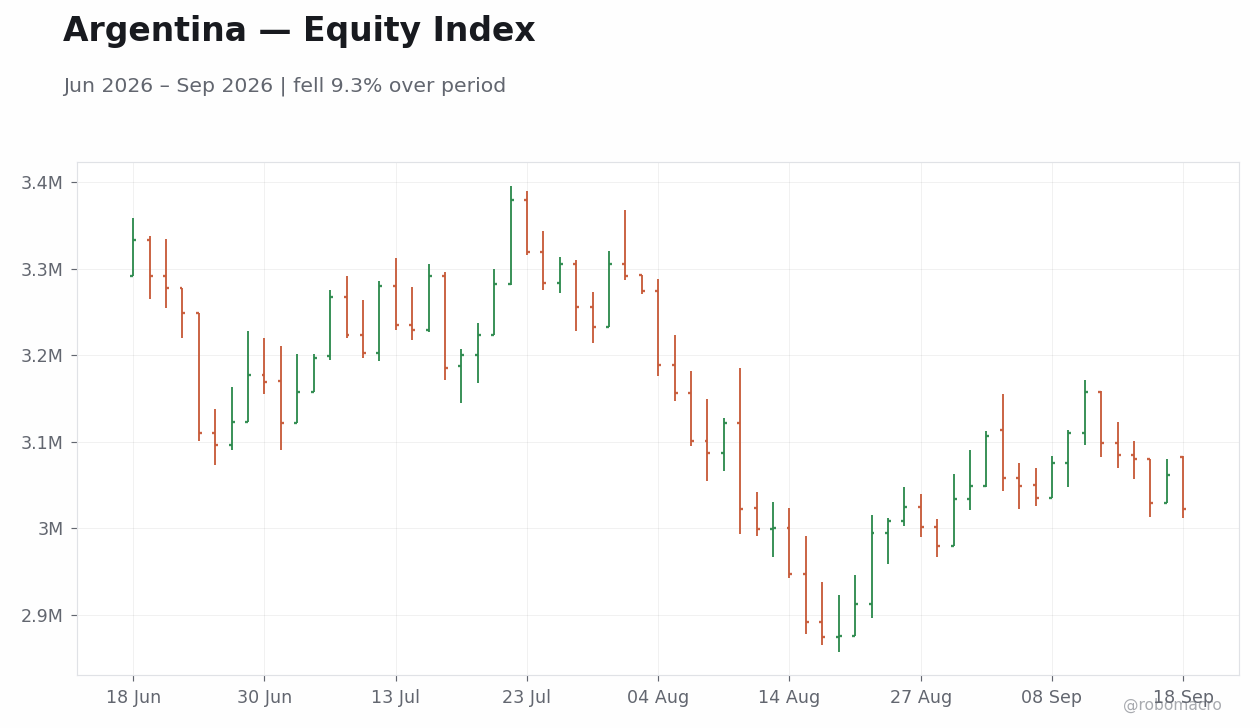
Equity Market Performance Argentine equities posted a net decline over the five trading days with the MERVAL index closing at 3,021,926 after successive daily losses. The absence of any inflation, activity or fiscal releases left trading volumes thin and price action driven by external factors.
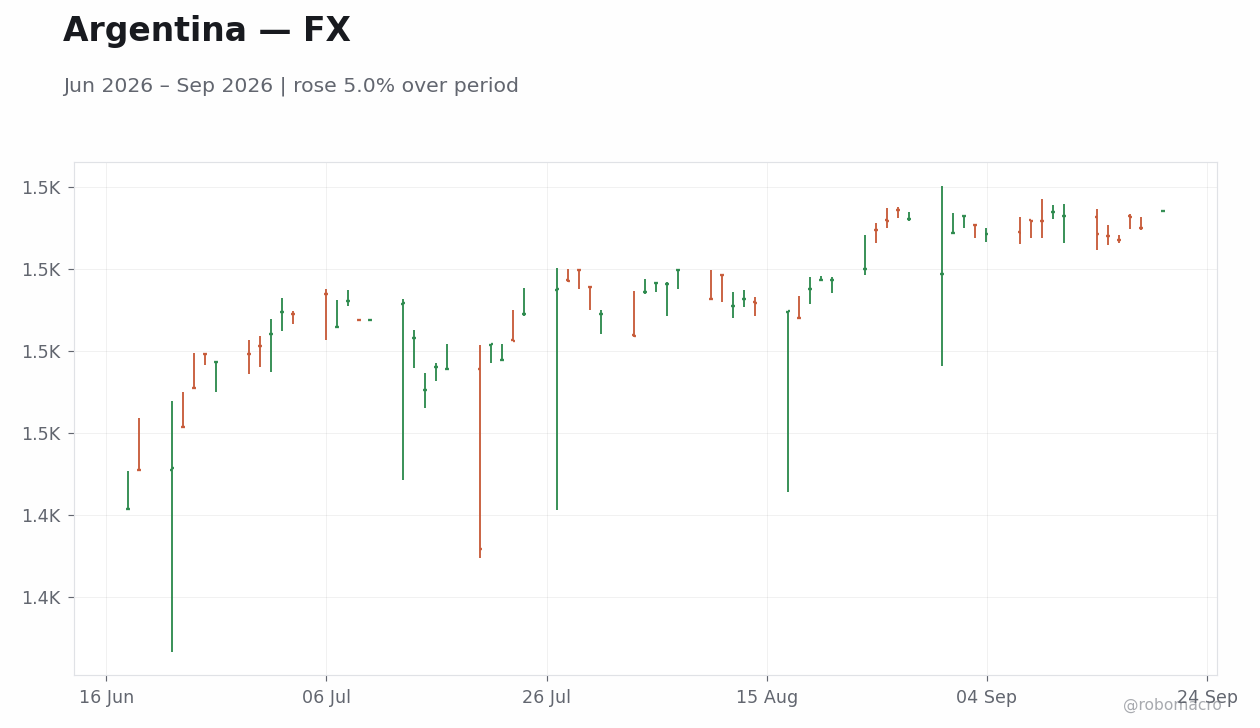
Currency and Commodity Dynamics USD/ARS finished the week at 1,514 after a modest 0.37 percent advance while EUR/ARS rose 2.09 percent to 1,739.12, reflecting cross-rate adjustments rather than broad peso pressure. Brent crude’s 6.05 percent decline to 99.29 reversed earlier weekly gains and reduced immediate imported-inflation pressure, while soybean futures advanced 1.42 percent to 1,303.50, providing modest support to export receipts.
Policy and Data Vacuum The domestic calendar recorded zero high-impact events across all five days, extending the data-dependent equilibrium that has characterized recent weeks.
External Transmission Global rate pressures transmitted through commodity channels rather than direct capital-flow shifts, leaving local fixed-income liquidity thin. The week’s arc therefore showed resilience in the peso despite equity weakness, with commodity price moves providing the dominant external signal.
The Central Bank of Argentina issued no statements, minutes or reserve updates during the week, maintaining the policy rate at its prior level amid the complete absence of fresh inflation or activity prints. Prior monthly data on export volumes and the real effective exchange rate remain the last available anchors for assessing the real policy stance. Brent’s sharp decline to 99.29 reduced near-term imported cost pressures that had built in earlier weeks, while soybean strength at 1,303.50 continued to support reserve accumulation targets under the IMF programme. The data vacuum leaves the BCRA’s forward guidance unchanged and explicitly tied to the next round of monthly releases rather than any intra-week signals. Officials have not altered their emphasis on fiscal primary-balance compliance as the key precondition for containing monetary financing risks.
Calendar data unavailable
No Argentine economic releases are scheduled for September 21–27, extending the empty domestic calendar into the following week. Markets will therefore monitor external commodity prints and any follow-up statements from the Milei administration on fiscal execution. Soybean export flows and reserve accumulation metrics may surface through secondary channels and will remain central to current-account assessments ahead of the next BCRA communication window. Global oil and grain price stability will continue to shape terms-of-trade expectations that feed into inflation trajectories over coming quarters. The absence of domestic data keeps the policy-rate path data-dependent, with upcoming decisions conditioned on the prior month’s inflation and fiscal outcomes rather than new weekly prints. Traders will watch USD/ARS forward points for any shift in intervention signals once external volatility subsides.
The week’s commodity reversal, with Brent falling sharply while soybeans held gains, shifts the near-term inflation risk balance toward the downside relative to the prior three weeks of energy advances. Equity weakness without corresponding peso depreciation suggests markets are not yet pricing renewed external pressure on reserves. Upside scenarios hinge on sustained soybean export proceeds supporting reserve targets, while downside risks center on any renewed Brent spike that could re-ignite imported cost pressures before the next inflation print. The data vacuum leaves fiscal consolidation progress as the primary domestic variable that could alter the BCRA’s tolerance for liquidity conditions in coming quarters.
| Asset | Level | WoW |
|---|---|---|
| MSCI Chile | 39.45 | +0.7% |
| MSCI Peru | 90.75 | +2.3% |
| USD/COP | 3180.99 | +2.9% |
| USD/CLP | 959.0 | +2.5% |
| USD/PEN | 3.37 | +3.6% |
| Copper | 6.69 | +5.7% |
| Gold | 4424.9 | +1.7% |
| Brent Crude | 99.29 | -6.0% |
| Bitcoin | 81202.36 | +5.7% |


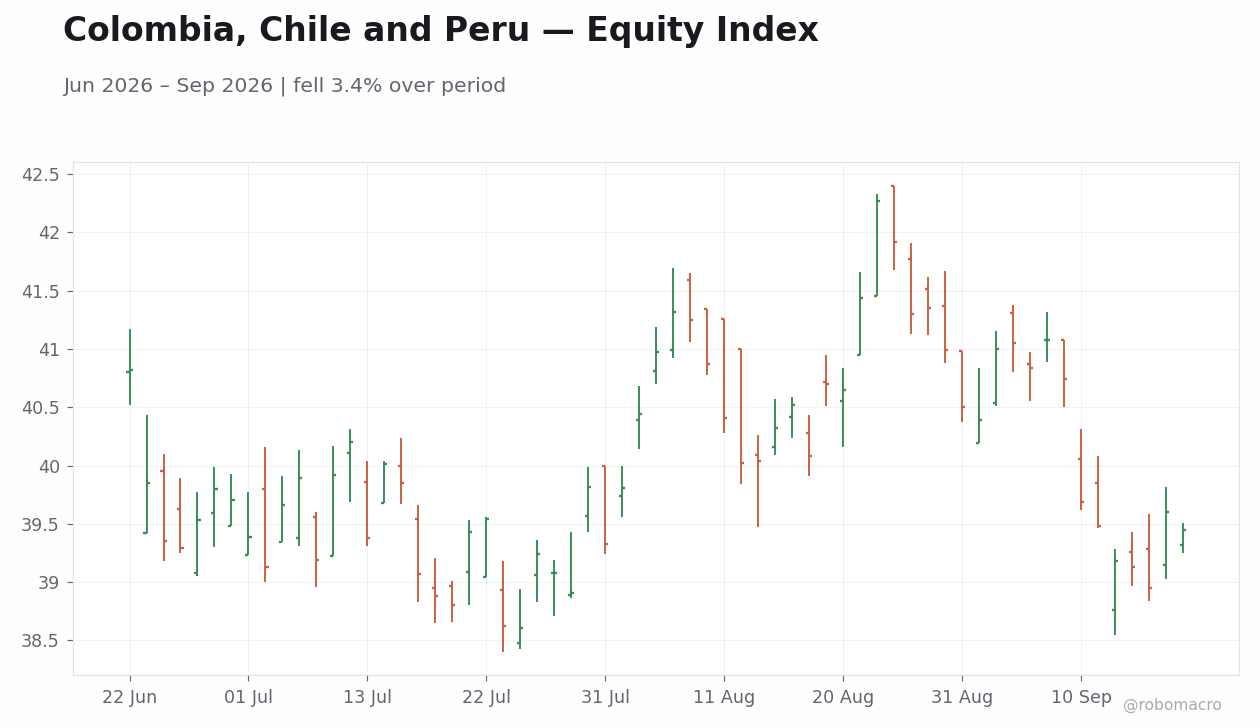
Commodity price reversal dominates external balances. Brent crude declined 6.05 percent to 99.29 while copper advanced 5.71 percent to 6.69. The oil move reduced projected royalty and tax receipts for Colombia while copper strength provided offsetting support for Chile and Peru mining exports. MSCI Peru rose 2.3 percent to 90.75, outpacing MSCI Chile’s 0.69 percent gain to 39.45.
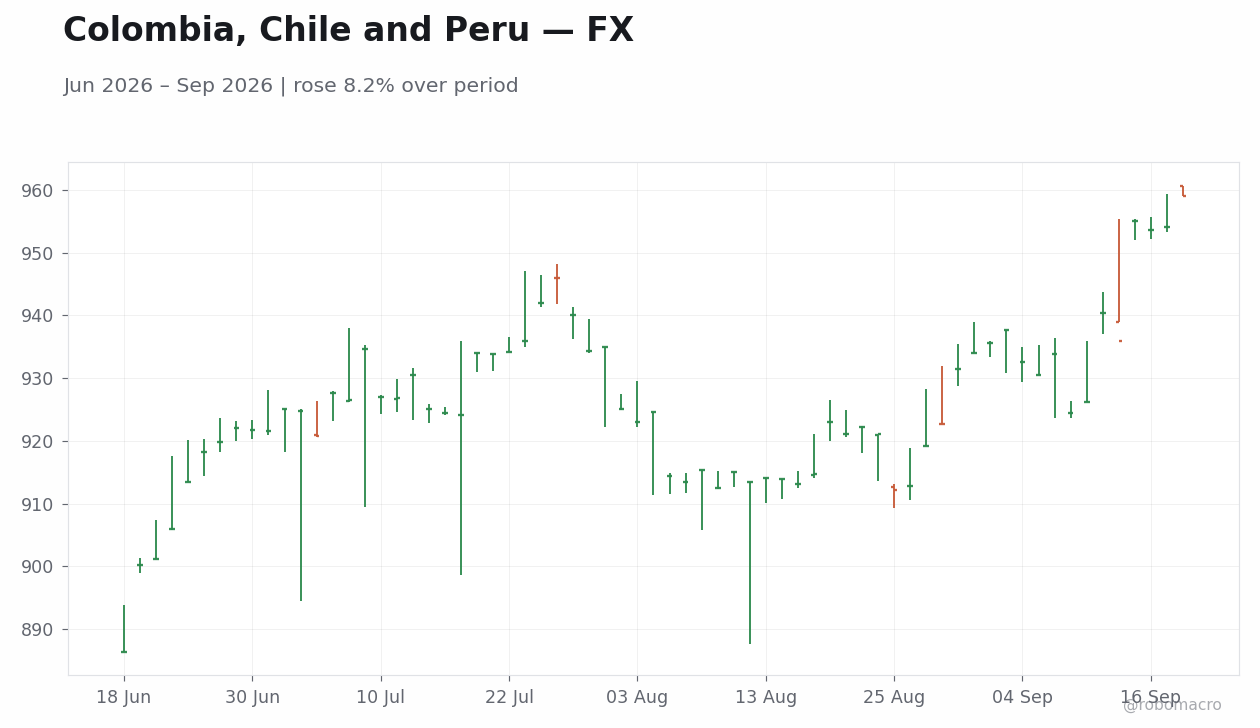
Currency depreciation accelerates across the bloc. USD/COP advanced 2.89 percent to 3180.99, USD/CLP rose 2.48 percent to 959.00 and USD/PEN climbed 3.58 percent to 3.37, reflecting broad USD momentum.
Equity and fiscal linkages remain commodity-tied. MSCI Chile posted gains while broader equity performance stayed tied to the divergent oil-copper configuration. Gold’s 1.68 percent weekly rise to 4424.9 offered secondary support to Peruvian and Colombian producers, yet fiscal balances remained sensitive to commodity price swings.
Absence of domestic prints leaves external drivers in control. No CPI, GDP, trade-balance or labor-market releases occurred in any of the three economies, confirming external factors as the dominant influence on markets and policy expectations.
BanRep, BCCh and BCRP held policy rates steady with no announcements from any of the three central banks during the week. Officials delivered no speeches or minutes that altered forward guidance, preserving the explicit data-dependent stance. The sharp Brent decline to 99.29 and concurrent copper advance to 6.69 supplied opposing signals for imported inflation versus export receipts, yet the absence of fresh activity or price prints left rate-path expectations unchanged. Data flows therefore reinforced the existing equilibrium in which policymakers absorb commodity volatility without immediate recalibration ahead of upcoming decisions.
Calendar data unavailable


Attention next week centers on external commodity trajectories and any follow-through from global risk signals rather than scheduled domestic releases. No CPI, GDP, trade-balance or central-bank meetings appear on the calendar for Colombia, Chile or Peru. Copper and Brent price movements will continue to shape fiscal and current-account expectations, with higher copper levels supporting Chile and Peru mining royalties while any further Brent softening would weigh on Colombia’s oil-linked revenues. USD strength against COP, CLP and PEN remains the dominant transmission channel for external financing costs ahead of the next policy meetings. Sovereign bond auctions and secondary-market yield movements will also warrant monitoring. Regional equity flows are likely to stay light absent domestic catalysts.
The week’s 6.05 percent Brent drop versus the 5.71 percent copper gain highlights asymmetric exposure across the three economies, with Colombia facing downside fiscal risk while Chile and Peru receive upside mining support. Continued USD/COP, USD/CLP and USD/PEN advances could compress import purchasing power and widen external financing gaps if commodity support fades. The lack of domestic data prints leaves the outlook vulnerable to rapid shifts in global energy and metals prices, potentially altering inflation trajectories ahead of upcoming central-bank decisions. Markets appear to price limited near-term policy response, yet any sustained oil weakness could challenge the data-dependent equilibrium.
| Asset | Level | WoW |
|---|---|---|
| FTSE 100 | 10659.1 | -0.4% |
| FTSE 250 | 24205.4 | +1.6% |
| GBP/USD | 1.34 | -1.0% |
| GBP/EUR | 1.17 | -0.1% |
| GBP/JPY | 209.31 | +0.9% |
| Brent Crude | 99.29 | -6.0% |
| Gold | 4424.9 | +1.7% |
| UK Nat Gas | 2.91 | +0.6% |
| Bitcoin | 81189.43 | +5.7% |


Labor market shows resilience amid cooling wage growth. The labor release delivered an unemployment rate in line with or slightly below consensus, while employment gains slowed from the prior month. Average earnings growth moderated year-over-year, matching forecasts and marking a clear deceleration. These figures arrived against vacancies already at multi-year lows, confirming selective softening without broad deterioration.
Inflation prints confirmed the energy impulse without altering the near-term path. Headline CPI rose in line with consensus and above the prior print, while the monthly rate accelerated. Core inflation held steady, providing the Bank of England with evidence that the earlier Brent advance had not yet fed through aggressively into underlying measures.
Policy expectations remained anchored despite mixed signals. The decision left the policy rate unchanged on a split vote favoring steady policy. Minutes highlighted the balance between contained wage growth and the recent CPI uptick, leaving forward guidance explicitly data-dependent. Earlier GDP data had lifted growth forecasts, yet markets absorbed the combination without repricing near-term moves.
Cross-border energy volatility shaped domestic asset responses. Brent’s decline over the final sessions reduced imported-inflation concerns that had built since the prior advance. Sterling closed the week lower against the dollar, while gilt yields eased modestly after the labor print before rising on the CPI release.
The Bank of England held the policy rate unchanged on a split vote, with a minority favoring a hike. Minutes emphasized that recent labor-market weakness, including vacancies at multi-year lows, reinforced the case for steady policy amid subdued demand. Recent labor data showing slower earnings growth reduced near-term tightening urgency, while the CPI rise kept inflation risks visible but contained within core measures. Forward guidance left the medium-term rate path explicitly tied to incoming activity and price data rather than any pre-set calendar. No additional MPC speeches altered positioning during the week.
Labor data showed unemployment unchanged versus consensus, with employment change below the prior reading. Average earnings growth slowed year-over-year, matching forecasts and indicating cooling wage pressures that reduced immediate inflation concerns. Headline CPI advanced in line with consensus and above the prior print, while core CPI held steady versus expectations. The monthly CPI rate rose, aligning with forecasts. These prints confirmed the energy-driven lift in headline inflation without pushing core measures higher, supporting the view that the cycle remains in its mid-phase where imported price shocks compete with domestic demand softness. The combination leaves the Bank of England’s medium-term rate path data-dependent, with the policy rate unchanged and minutes underscoring tolerance for divergent prints. Retail sales data scheduled for the following day were expected to test whether consumer demand had already begun to reflect the earlier energy surge.
Calendar data unavailable
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-23 | S&P Global Manufacturing PMI Flash | - | - |
| 2026-09-23 | S&P Global Services PMI Flash | - | - |
| 2026-09-23 | CBI Industrial Trends Orders Level | -25.0 | - |
| 2026-09-24 | GfK Consumer Confidence | -14.0 | - |
| 2026-09-25 | CBI Distributive Trades Level | - | - |


Early-week releases include the CBI Industrial Trends Orders Level, offering an early read on manufacturing sentiment. Mid-week features the S&P Global Manufacturing and Services PMI Flash prints. Later in the week the CBI Distributive Trades Level and GfK Consumer Confidence print are due. These releases will test whether recent GDP and labor data have begun to influence business and household expectations. Central bank speakers remain limited, with attention focused on any follow-through from the latest minutes. Markets will monitor whether the Brent decline alters inflation forecasts ahead of the next decision window.
The sharp Brent reversal reduced imported-inflation risks that had built over recent weeks, shifting the balance toward downside growth scenarios if energy prices stabilize lower. Positioning appears light on sterling after the week-over-week decline in GBP/USD, leaving room for volatility if PMI prints surprise on either side. Upside risks center on stronger-than-expected services PMI, which could reinforce the mid-phase expansion narrative. Downside risks include further labor-market softening that might prompt earlier policy recalibration than currently priced. Flow considerations suggest gilt markets remain sensitive to any shift in quantitative-tightening language in future minutes. The stable unemployment rate provides an anchor, yet slower employment gains signal the cycle may be transitioning toward reduced momentum.
Equities closed the week with the FTSE 100 at 10659.1, down 0.36% week-over-week. The FTSE 250 ended at 24205.4, up 1.56% week-over-week. Bonds saw the 10-year gilt yield finish lower from the prior close, while the 2-year gilt yield was little changed. FX markets showed GBP/USD at 1.34, down 1.02% week-over-week, with GBP/EUR at 1.17, down 0.13%, and GBP/JPY at 209.31, up 0.86%. Commodities recorded Brent crude at 99.29, down 6.05% week-over-week after intraday peaks near 109, while gold rose 1.68% to 4424.9.
Energy-price volatility dominated cross-border spillovers, with Brent’s weekly decline reversing part of the prior advance that had lifted imported-inflation risks across developed markets. Supply signals eased after the earlier spike. Trade dynamics showed limited immediate impact on UK data, though the broader commodity impulse continued to influence sterling crosses. Geopolitical developments remained peripheral to UK asset moves over the seven-day window.
| Asset | Level | WoW |
|---|---|---|
| OMX Stockholm 30 | 3264.33 | +1.4% |
| Oslo Bors | 2117.33 | +0.3% |
| OMX Copenhagen 25 | 1870.16 | +0.5% |
| OMX Helsinki 25 | 6558.77 | +3.1% |
| USD/SEK | 9.83 | +1.3% |
| USD/NOK | 9.41 | +1.3% |
| EUR/SEK | 11.29 | +0.3% |
| EUR/NOK | 10.81 | +0.3% |
| Brent Crude | 99.29 | -6.0% |
| Gold | 4424.9 | +1.7% |
| Bitcoin | 81189.72 | +5.7% |


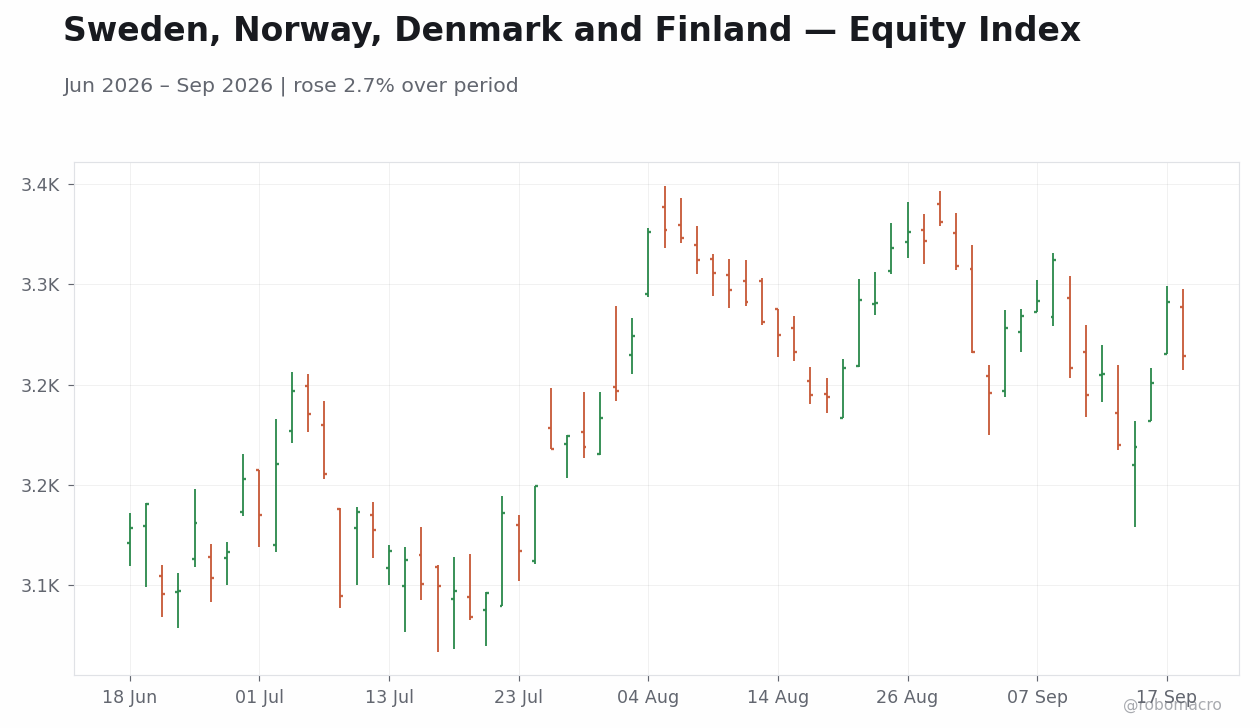
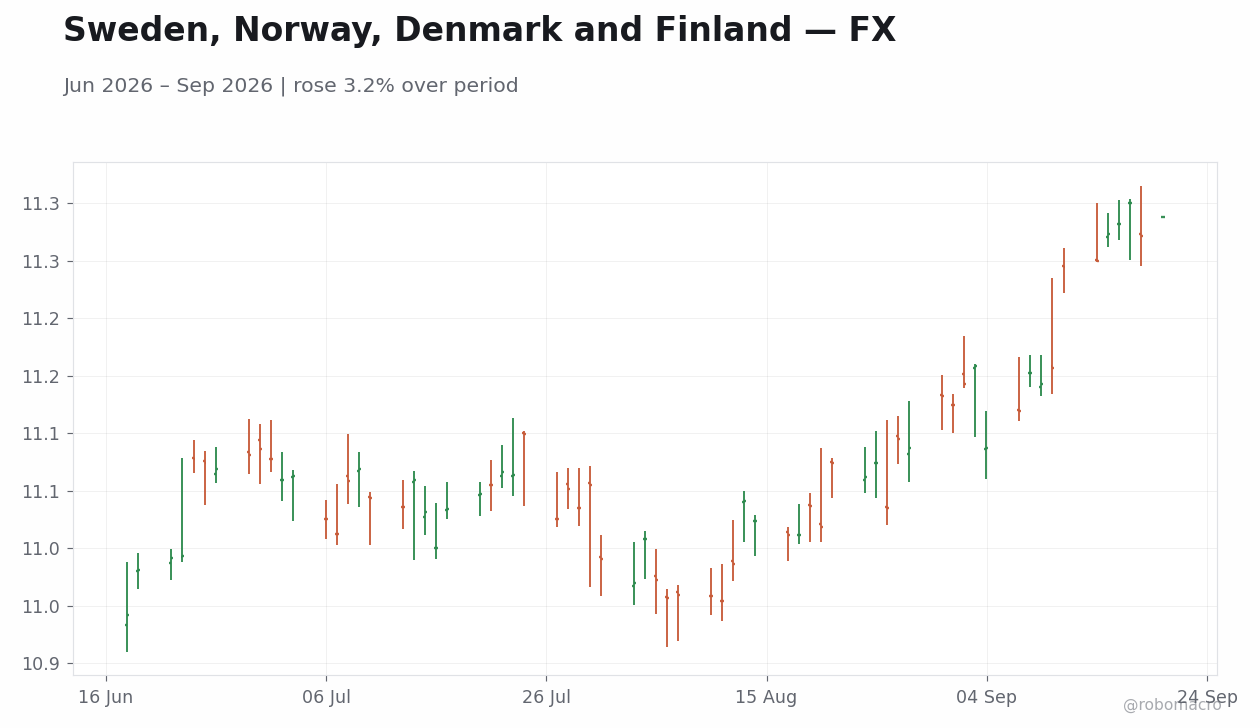
Equity and commodity divergence Nordic equities posted net gains for the week even as Brent crude declined sharply. The OMX Helsinki 25 advanced 3.08 percent to 6,558.77 and the OMX Stockholm 30 rose 1.38 percent to 3,264.33, while Oslo Børs gained 0.35 percent to 2,117.33. Daily moves showed resilience after an initial slide on September 15, with the OMX Stockholm 30 climbing on September 16 and further on September 17.
Currency and yield stability USD/SEK rose 1.29 percent to 9.83 and USD/NOK advanced 1.29 percent to 9.41, reflecting broad Nordic currency softening against the dollar. EUR/SEK increased 0.34 percent to 11.29. Nordic government yields moved modestly higher.
Policy and survey signals Nordic central banks kept policy settings unchanged. No macroeconomic releases occurred in any of the four countries during the week.
Nordic central banks maintained steady policy settings. Norges Bank continued to balance inflation considerations against growth, with no fresh domestic data altering the assessment ahead of the next decision. The Bank of Finland reiterated a positive economic trajectory, consistent with the ECB’s data-dependent stance. These communications reinforced a steady policy signal across the region without immediate recalibration.
Calendar data unavailable
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-24 | Riksbank Rate Decision | - | - |
| 2026-09-24 | Norges Bank Interest Rate Decision | - | - |
| 2026-09-24 | Press Conference by Riksbank | - | - |

Attention centers on upcoming central bank communications. Norges Bank will weigh inflation and growth considerations against Brent crude movements. No other high-impact releases are listed for Sweden, Norway, Denmark or Finland in the coming days. Danmarks Nationalbank’s next adjustment will remain tied to ECB actions to preserve the ERM II peg. The Bank of Finland will continue to track euro-area inflation prints for implications on the deposit rate trajectory. These decisions will shape rate expectations for coming quarters.
The sharp 6.05 percent weekly decline in Brent crude to 99.29 introduces downside risk to Norway’s fiscal revenues and NOK support, while lowering imported inflation pressures for Sweden and Finland. Swedish political developments add uncertainty ahead of potential government formation. Equity gains across the region may overstate resilience if external demand weakens further, given the export orientation of Swedish and Finnish manufacturing. The absence of domestic data this week leaves policy boards reliant on prior prints, raising the possibility that upcoming decisions could surprise if growth or inflation readings shift materially.
| Asset | Level | WoW |
|---|---|---|
| BIST 100 | 13284.4 | -6.7% |
| iShares Poland | 44.41 | -1.6% |
| EUR/PLN | 4.36 | +0.9% |
| EUR/HUF | 364.15 | +0.3% |
| EUR/CZK | 24.31 | +0.4% |
| USD/TRY | 48.77 | +0.3% |
| Brent Crude | 99.29 | -6.0% |
| Gold | 4424.9 | +1.7% |
| Bitcoin | 81189.71 | +5.7% |


Equity and Commodity Moves Drive Price Action Equity indices recorded net weekly declines. The BIST 100 fell 6.68% while iShares Poland declined 1.62%. Brent crude dropped 6.05% after trading higher mid-week.
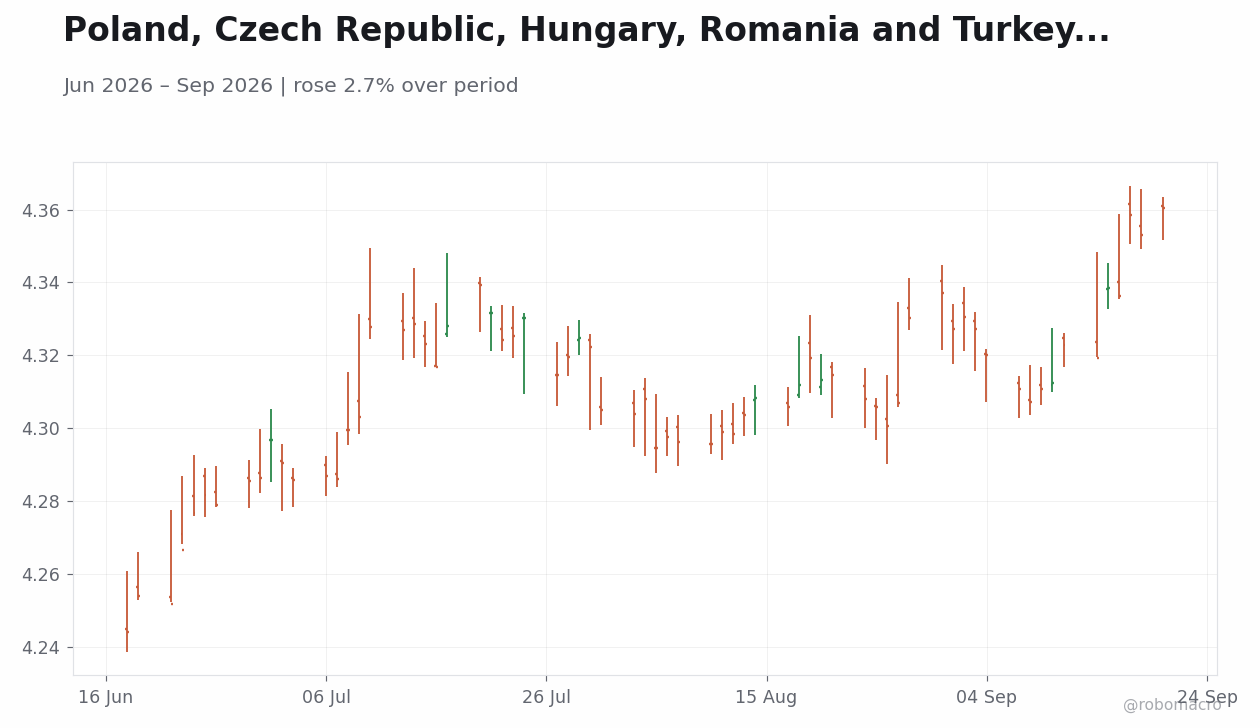
FX Markets Show Modest Regional Depreciation EUR/PLN advanced 0.95% to 4.36. EUR/HUF rose 0.35% to 364.15, EUR/CZK gained 0.40% to 24.31, and USD/TRY increased 0.34% to 48.77.
Thin Calendar Leaves Markets Externally Driven No high-impact macroeconomic releases took place in the five economies. Price action reflected global risk sentiment and commodity swings.
No policy decisions or minutes were issued by NBP, CNB, MNB, BNR or CBRT. Forward guidance across the five central banks stayed data-dependent. The thin domestic calendar leaves rate paths anchored to incoming inflation and activity prints rather than this week’s flow.
No high-impact data prints occurred in Poland, the Czech Republic, Hungary, Romania or Turkey. The absence of domestic releases left growth and inflation assessments dependent on external factors, including commodity prices.
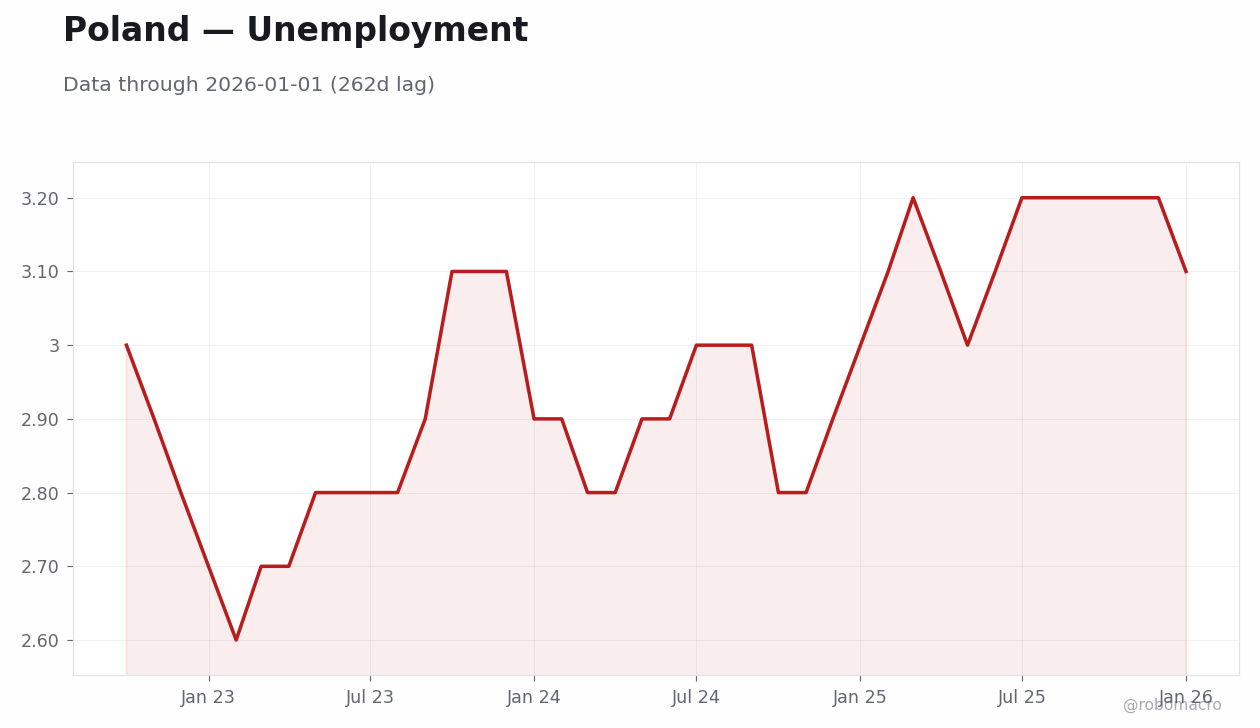
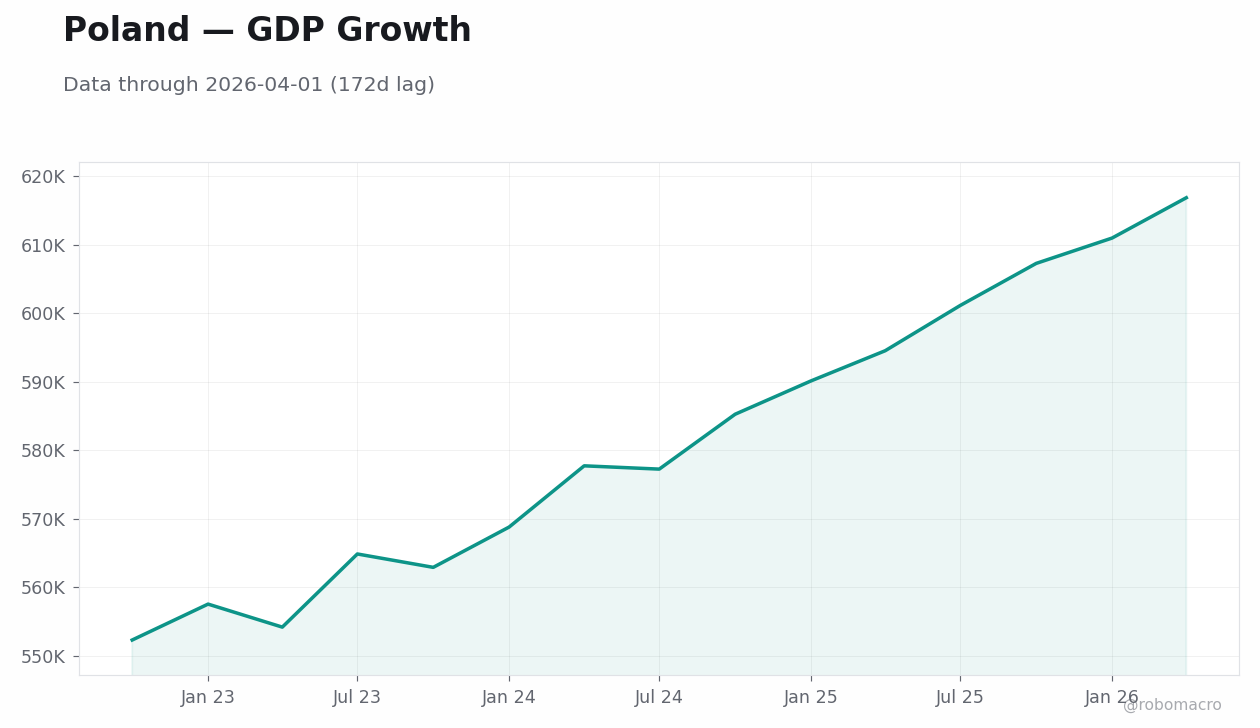
Next week’s scheduled indicators include Turkish business confidence and capacity utilization data plus Polish wage, employment and producer price prints. These releases will provide the first updates on sentiment and cost pressures since the prior week.
Calendar data unavailable
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-22 | Central Bank Interest Rate Decision | - | - |
| 2026-09-23 | Unemployment Rate | - | - |

Turkey Business Confidence and Capacity Utilization Rate are scheduled for September 21. Poland Corporate Sector Wages Year-over-Year, Employment Growth Year-over-Year and Producer Price Index Year-over-Year follow the same day.
Poland Unemployment Rate is due September 23. No central-bank meetings or sovereign bond auctions are listed for Poland, the Czech Republic, Hungary or Romania. Markets will focus on Turkish sentiment data and Polish labor and cost metrics for any shift in rate-path expectations. Energy price stability will remain a key variable for imported inflation.
Equity weakness may extend if commodity prices rebound. Light positioning leaves room for volatility around next week’s Turkish and Polish releases. Any renewed external risk-off move could trigger safe-haven flows.
Equities posted net weekly losses. The BIST 100 closed at 13,284.40 after a 6.68% decline. iShares Poland fell 1.62% to 44.41.
Bonds showed limited price discovery as Poland and Hungary 10-year yields remained unavailable.
FX markets delivered modest depreciation across the complex. EUR/PLN rose 0.95% to 4.36, EUR/HUF advanced 0.35% to 364.15, EUR/CZK gained 0.40% to 24.31, and USD/TRY increased 0.34% to 48.77.
Commodities recorded the largest moves. Brent crude declined 6.05% to 99.29. Gold rose 1.68% to 4,424.90 and Bitcoin gained 5.66% to 81,189.71. The commodity retreat reduced near-term imported inflation concerns for net-energy importers.
Brent crude’s weekly decline eased imported inflation pressure across net-energy importers. Global equity resilience outside Turkey contrasted with the BIST 100 drop. Trade linkages with the euro area remain the dominant external channel for Poland and the Czech Republic while Hungary and Turkey face greater commodity-price sensitivity.
| Asset | Level | WoW |
|---|---|---|
| JSE Top 40 | 105242.1 | -0.8% |
| USD/ZAR | 16.25 | +0.4% |
| EUR/ZAR | 18.65 | -0.6% |
| Platinum | 1806.4 | +1.7% |
| Gold | 4424.9 | +1.7% |
| Brent Crude | 99.29 | -6.0% |
| Naspers | 71460.0 | -1.9% |
| Bitcoin | 81189.71 | +5.7% |


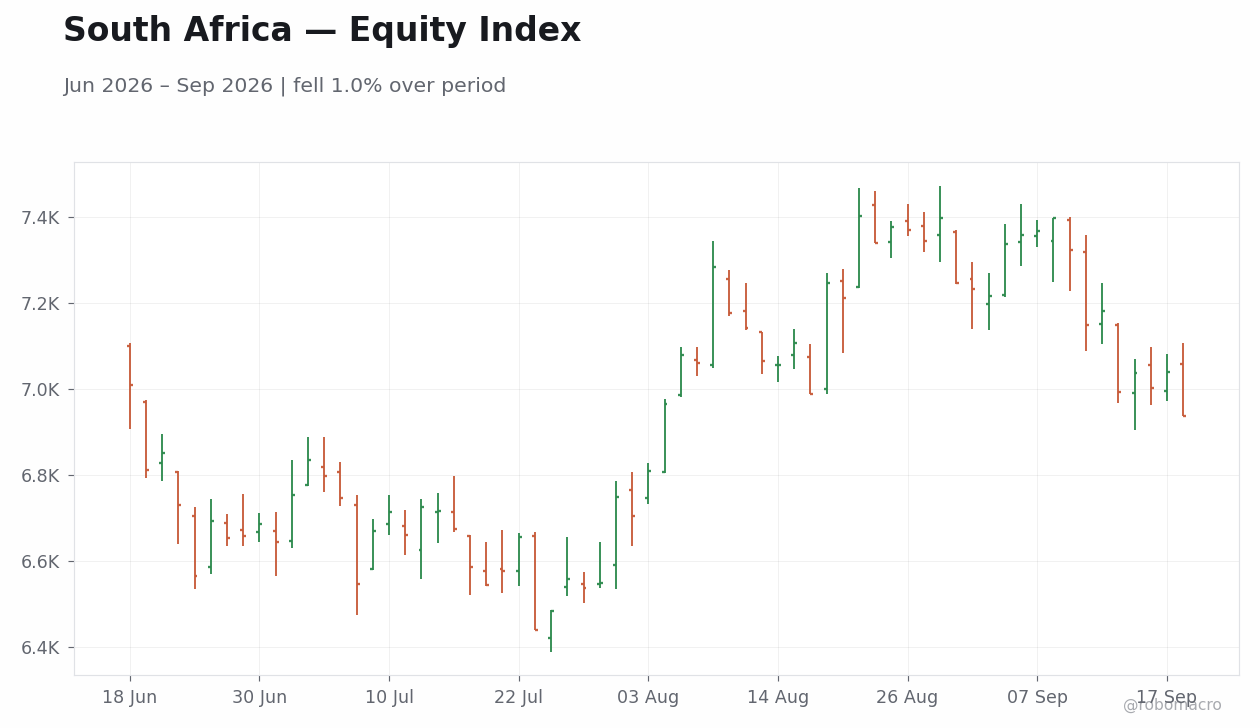
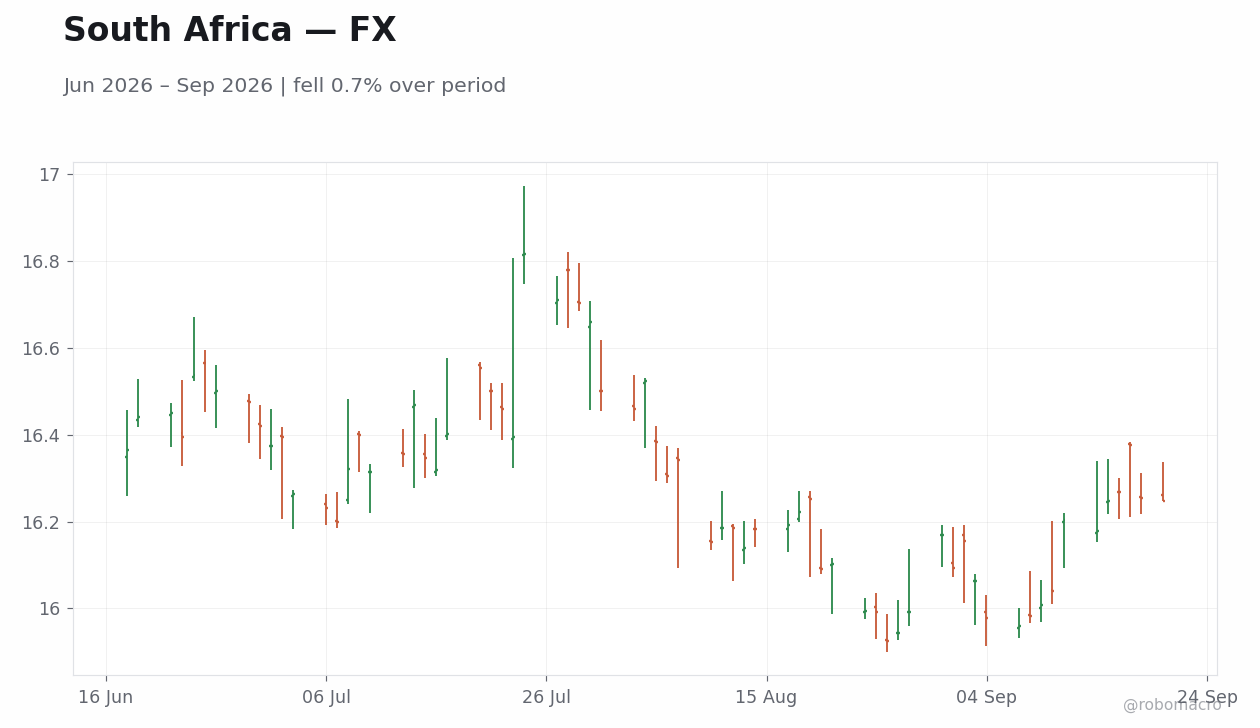
Equity and FX Performance South African equities closed the week lower as the JSE Top 40 fell 0.78 percent to 105242.1 from the prior Friday close. USD/ZAR finished at 16.25 after a net 0.42 percent advance. EUR/ZAR eased 0.55 percent to 18.65. Naspers declined 1.93 percent to 71460.0, contributing to the equity retreat.
Commodity and Yield Drivers Brent crude dropped 6.05 percent to 99.29, while gold rose 1.68 percent to 4424.9 and platinum advanced 1.72 percent to 1806.4. Government yields moved higher. These moves occurred against a backdrop of no domestic data releases.
Absence of Domestic Catalysts The economic calendar recorded zero high-impact events for South Africa between September 14 and September 18. Markets therefore priced external factors, including the sharp Brent decline and global equity flows, without fresh CPI or growth prints. Bitcoin rose 5.66 percent to 81189.71, providing a partial offset to equity weakness. The configuration left rate expectations unchanged from the prior data-dependent equilibrium.
No South African Reserve Bank speakers, minutes, or decisions took place during the week. The policy rate remained at its prior level with no forward guidance updates. The sharp 6.05 percent decline in Brent to 99.29 reduced near-term imported inflation risks. The Inflation Rate Month-over-Month and Year-over-Year releases scheduled for September 23 will supply the next direct read on price pressures ahead of the next MPC meeting. Absent new communications, the data-dependent stance observed in prior weeks continues to govern expectations for the rate path.
Calendar data unavailable
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-23 | Inflation Rate Month-over-Month | 0.20 | - |
| 2026-09-23 | Inflation Rate Year-over-Year | 4.3 | - |
| 2026-09-23 | Central Bank Interest Rate Decision | 7.0 | - |


The Inflation Rate Month-over-Month and Inflation Rate Year-over-Year prints on September 23 will provide the first domestic gauge of price trends. These medium-impact figures will inform assessments of whether energy price relief is feeding through to headline inflation ahead of the next MPC meeting. No other South African data releases appear on the calendar through September 25. The releases matter for the rate path because they will clarify whether the recent Brent decline has altered the inflation outlook that has kept the policy rate on hold. Global commodity volatility remains the dominant external variable for rand positioning into the coming decision window.
The 6.05 percent Brent drop to 99.29 shifts the near-term inflation impulse lower, reducing downside risks to the rand from imported costs. Equity underperformance and rising yields highlight sensitivity to external risk sentiment. The absence of data this week leaves the market reliant on the September 23 Inflation Rate prints to reassess the growth-inflation balance. Upside scenarios hinge on continued commodity support for mining equities, while downside scenarios center on renewed energy price spikes that could pressure the rand beyond the 16.25 level.
| Asset | Level | WoW |
|---|---|---|
| ASX 200 | 8731.2 | -0.2% |
| NZX 50 | 13739.14 | +1.3% |
| AUD/USD | 0.71 | -0.4% |
| NZD/USD | 0.57 | -1.5% |
| AUD/NZD | 1.24 | +1.0% |
| BHP | 61.05 | +0.8% |
| Gold | 4424.9 | +1.7% |
| Brent Crude | 99.29 | -6.0% |
| Bitcoin | 81189.72 | +5.7% |


NZ data resilience amid external weakness New Zealand data showed resilience relative to external conditions, reducing immediate downside risks to the growth outlook.
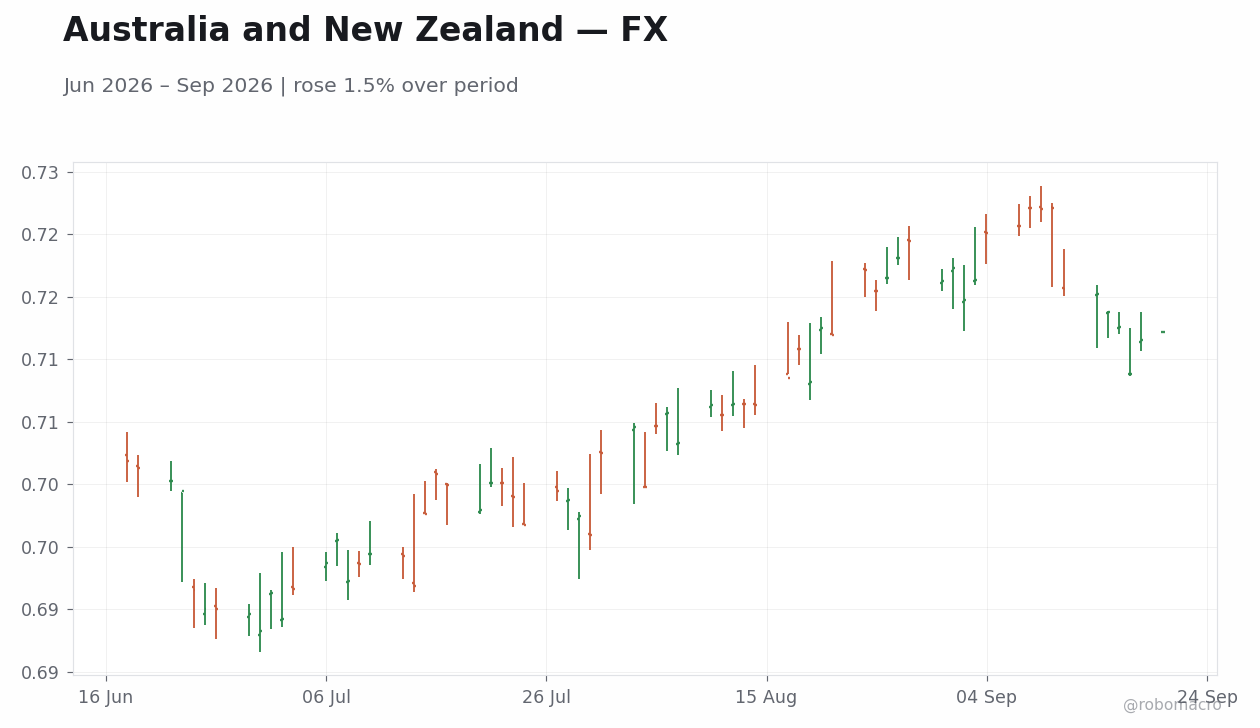
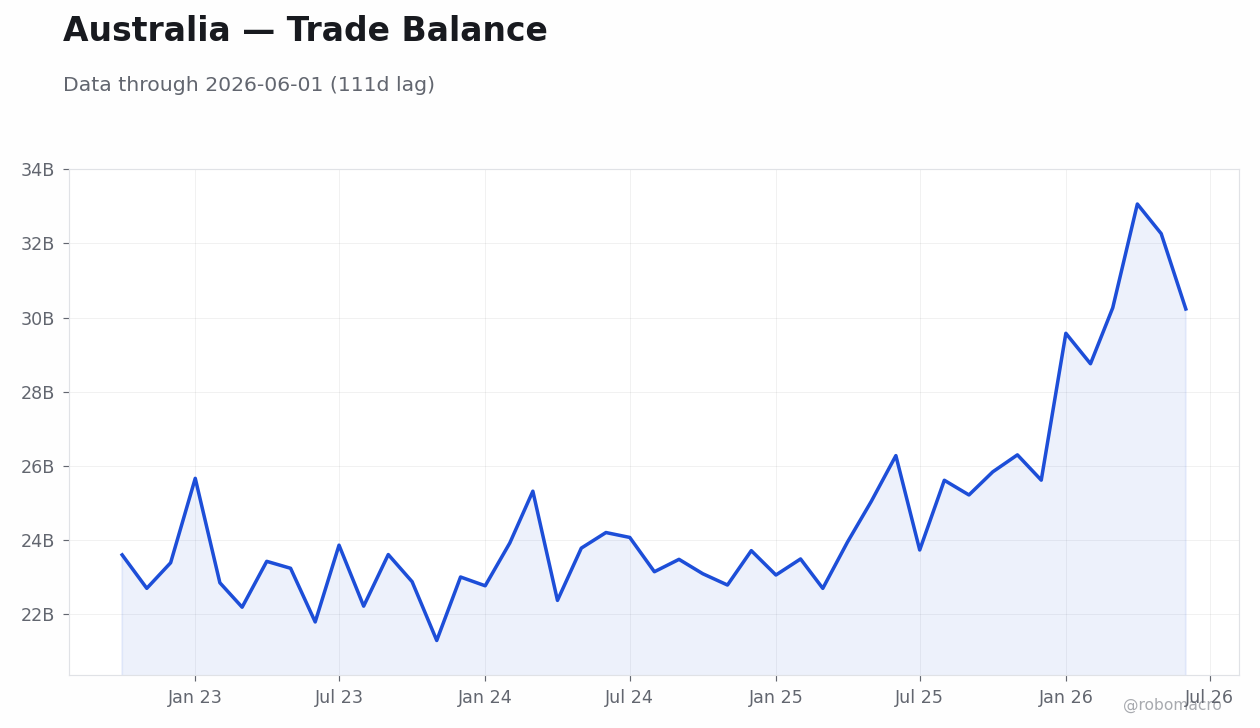
Commodity price reversal and currency divergence Brent crude ended at 99.29 after a 6.05% weekly decline. AUD/USD held at 0.71 while NZD/USD closed at 0.57, widening AUD/NZD to 1.24 as Australian commodity linkages outperformed.
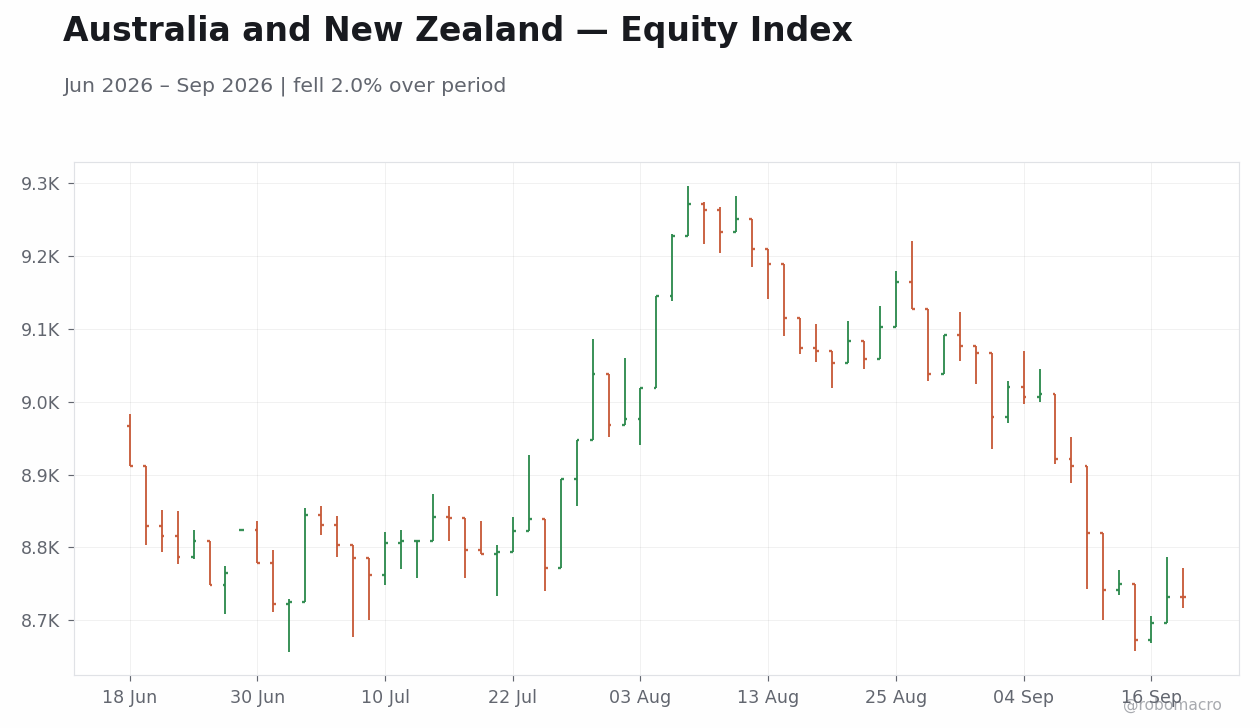
Equity and yield stability despite mixed flows The ASX 200 ended at 8731.2 after a 0.21% weekly decline, with BHP at 61.05; the NZX 50 advanced 1.32% to 13739.14. Australian yields remained stable as RBA communication offset softer housing and employment signals.
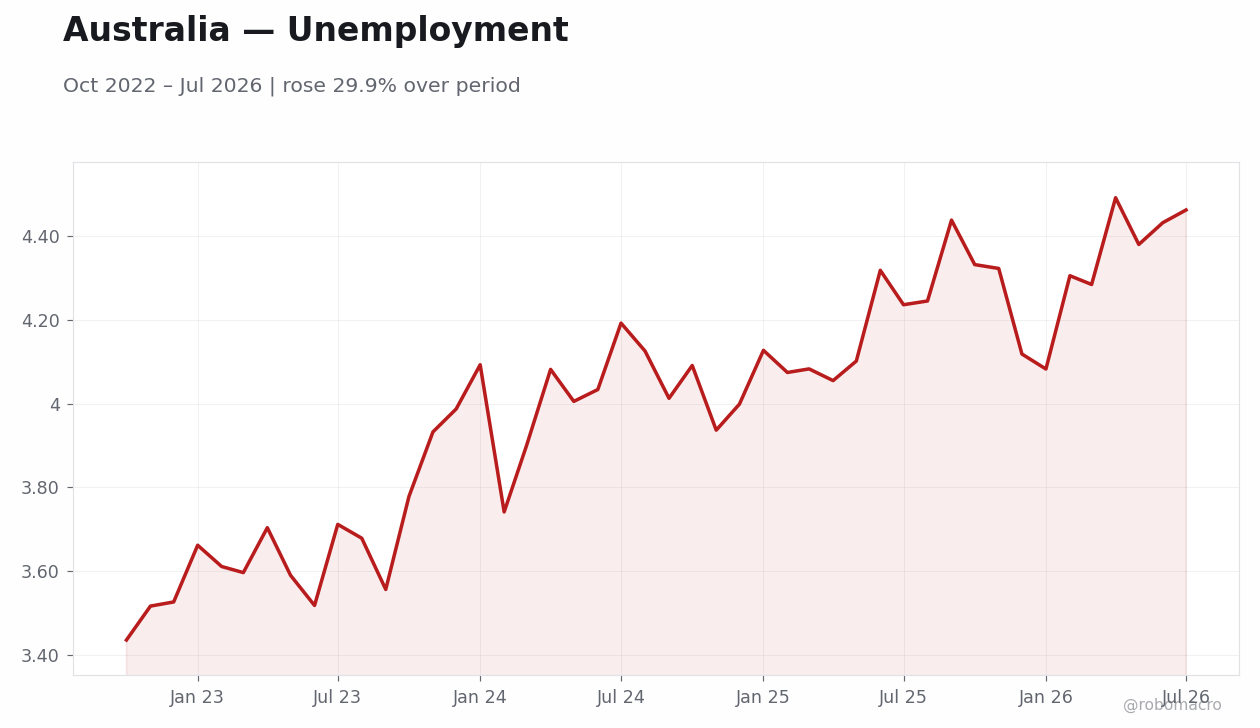
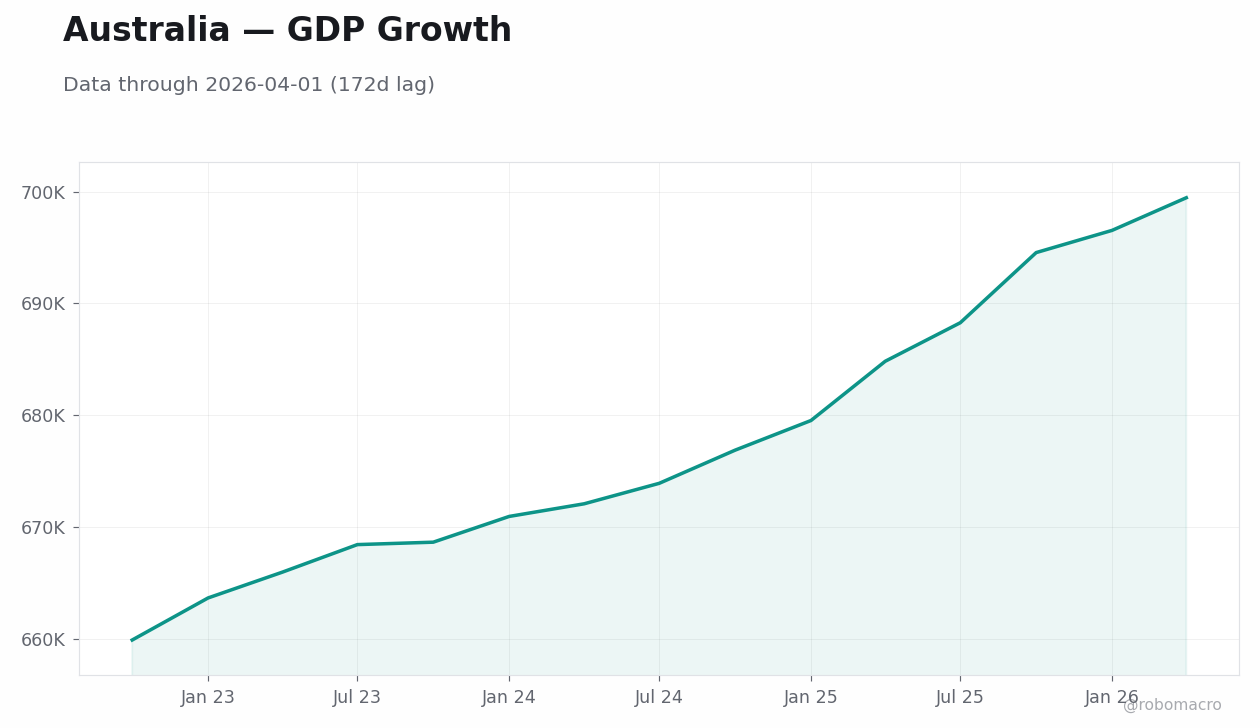
Policy signal from official communication RBA communication kept the policy rate path data-dependent. Westpac’s leading index confirmed moderating but positive Australian momentum consistent with the RBA’s stance.
Broader cycle context The week’s configuration left both economies in a mid-phase expansion where energy volatility competed with selective labor-market softening, extending the data-dependent equilibrium without shifting central-bank parameters.
RBA communication kept the policy rate explicitly data-dependent ahead of the next meeting, with no indication of easing until inflation is fully subdued. New Zealand’s activity data reduced near-term growth concerns for the RBNZ. The combination of Australian inflation persistence and New Zealand’s activity beat points to continued divergence in the two policy paths, with both banks absorbing the data without immediate parameter shifts.
Calendar data unavailable
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-22 | S&P Global Manufacturing PMI Flash | - | - |
| 2026-09-22 | S&P Global Services PMI Flash | - | - |
| 2026-09-23 | Employment Change | -16K | - |
| 2026-09-23 | Full-Time Employment Change | 16K | - |
| 2026-09-23 | Unemployment Rate | 4.5 | - |


Australia’s S&P Global Manufacturing PMI Flash and Services PMI Flash are scheduled for September 22 and will provide the first read on September activity momentum. Employment Change, Full-Time Employment Change and the Unemployment Rate follow on September 23. RBA Deputy Governor Hunter speaks on September 21. These releases will help assess whether the recent moderation in Australian growth remains above stall speed ahead of the next policy decision. New Zealand trade balance data close the period on September 18, extending the external-balance focus. The data flow will inform whether the RBNZ can maintain its current OCR setting through coming quarters or faces renewed pressure from softer external demand.
The decline in Brent crude to 99.29 reduces imported inflation risks for both economies but leaves the RBA exposed if energy prices reaccelerate. New Zealand’s activity data lowers downside growth scenarios yet highlights sensitivity to China demand weakness visible in iron-ore and dairy price moves. Australian employment and PMI prints next week carry upside surprise potential that could reinforce the RBA’s hawkish communication, while a downside miss would challenge the data-dependent hold narrative. The AUD’s relative outperformance versus the NZD suggests markets continue to price policy divergence.
| Asset | Level | WoW |
|---|---|---|
| Shanghai Composite | 3911.87 | +0.7% |
| Hang Seng | 24750.78 | -0.7% |
| TAIEX | 47368.04 | +3.3% |
| USD/CNY | 6.7 | -0.2% |
| USD/HKD | 7.84 | +0.0% |
| Copper | 6.69 | +5.7% |
| Brent Crude | 99.29 | -6.0% |
| Gold | 4424.9 | +1.7% |
| Bitcoin | 81189.71 | +5.7% |


Equity markets diverged across Greater China. Shanghai Composite rose to close the week at 3,911.87. CSI 300 advanced over the week. Hang Seng declined to 24,750.78 while TAIEX rose to 47,368.04.
Currency and commodity moves reflected external factors. USD/CNY eased to 6.70 inside the managed band. USD/HKD remained near 7.84. Copper rose to 6.69 while Brent Crude fell to 99.29. Gold rose to 4,424.90.
Policy signals pointed to continuity. HKMA adjusted its base rate in line with external moves, keeping USD/HKD near the prevailing level. CBC maintained its benchmark rate given export resilience.
HKMA adjusted its base rate to track external policy moves, reinforcing the USD/HKD peg near 7.84 with no shift in aggregate balance. CBC held its policy rate given semiconductor export resilience. No PBoC MLF operations or liquidity injections were announced during the week. Forward guidance from the central banks stayed tied to incoming activity and inflation prints. The configuration leaves the medium-term rate outlook data-dependent.
Market data showed equity divergence across Greater China, with mainland and Taiwan indices advancing while Hong Kong declined. USD/CNY moved lower inside the band while USD/HKD stayed near the peg. Copper advanced and Brent Crude declined, producing opposing signals for growth-sensitive commodities. Gold rose. These moves left the cross-asset configuration mixed, with external demand factors supporting Taiwan equities and commodity price swings adding volatility to mainland-linked assets.
Calendar data unavailable
Markets will monitor daily PBoC liquidity operations and any State Council commentary. Taiwan trade data and semiconductor export trends are expected to provide the next read on external demand. Hong Kong aggregate balance figures will be watched for liquidity effects. Cross-strait investment flows and broader Asia currency moves will influence positioning. USD/CNY reference rate daily fixes will continue to guide expectations inside the managed band.
Equity positioning remains cautious, with mainland indices showing limited follow-through after recent data. Volatility in copper and Brent will continue to drive daily equity swings given their role as China growth proxies. Flow data suggest foreign investors remain selective, favoring Taiwan semiconductor names over broader mainland exposure.
Shanghai Composite rose 0.68% to 3,911.87 while CSI 300 gained over the week. Hang Seng fell 0.67% to 24,750.78. TAIEX climbed 3.28% to 47,368.04. USD/CNY declined 0.16% to 6.70. USD/HKD held near 7.84. Copper advanced 5.71% to 6.69 while Brent Crude fell 6.05% to 99.29. Gold rose 1.68% to 4,424.90. No China 2-year or 10-year government yield levels were reported during the period.
Brent Crude’s decline reversed the prior week’s advance, easing imported inflation risks for net-energy importers across Asia. External rate differentials remain supportive of the yuan band. Broader Asia currency strength against the dollar supported modest USD/CNY easing during the week.
| Asset | Level | WoW |
|---|---|---|
| KOSPI | 6894.23 | +3.1% |
| KOSDAQ | 827.12 | +2.5% |
| USD/KRW | 1385.95 | +3.1% |
| Samsung | 261000.0 | +4.8% |
| SK Hynix | 1857000.0 | +9.4% |
| Brent Crude | 99.29 | -6.0% |
| Gold | 4424.9 | +1.7% |
| Bitcoin | 81189.71 | +5.7% |


Equity performance and sector rotation South Korean equities posted a 3.14 percent weekly advance, closing at 6,894.23. Semiconductor names drove the net gain, with SK Hynix rising 9.43 percent to 1,857,000 and Samsung adding 4.82 percent to 261,000.
Currency and external flow dynamics USD/KRW climbed 3.07 percent to 1,385.95, reducing export competitiveness. The stronger won transmitted into lower export prices and prompted firms to adjust earnings expectations.
Policy signals and liquidity measures Authorities issued RFI-K operating guidelines and eased convertibility rules to support won internationalization. Brent crude declined 6.05 percent to 99.29, easing input costs for importers.
Bond market and yield response Yields moved modestly higher in response to external rate differentials. No high-impact domestic releases occurred during the week, leaving price action driven by currency and commodity signals.
Bank of Korea communications kept the policy rate path explicitly data-dependent. Officials reiterated warnings on AI-chip leverage while advancing operational tools for won internationalization, including RFI-K guidelines. August export prices declined on the stronger won, underscoring the competitiveness channel. Incoming current-account and sentiment prints will shape forward guidance rather than any pre-set trajectory.
Calendar data unavailable
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-22 | Consumer Confidence Index | - | - |
The Consumer Confidence Index release will provide the next domestic survey reading on household spending intentions. Market participants will assess whether the print confirms resilience in domestic demand or signals softening that could influence the Bank of Korea’s growth-inflation assessment. External drivers such as U.S. inflation prints and Brent crude movements will continue to shape sentiment ahead of the next policy meeting.
The stronger won continues to pressure export competitiveness while a wider U.S.-Korea rate gap sustains upside pressure on USD/KRW. AI valuation concerns triggered mid-week equity volatility, highlighting downside risks to semiconductor earnings if global demand weakens. Progress on won internationalization and liquidity support measures could stabilize funding conditions. The absence of fresh activity data leaves the outlook sensitive to the upcoming Consumer Confidence Index and any follow-through on RFI-K implementation.
| Asset | Level | WoW |
|---|---|---|
| JCI | 6441.16 | -1.4% |
| KLCI | 1665.56 | -1.9% |
| STI | 5656.11 | -1.1% |
| USD/IDR | 17740.0 | +0.6% |
| USD/THB | 33.29 | +0.6% |
| USD/MYR | 4.08 | +0.8% |
| USD/PHP | 62.83 | +0.2% |
| USD/SGD | 1.28 | +0.7% |
| Brent Crude | 99.29 | -6.0% |
| Gold | 4424.9 | +1.7% |
| Bitcoin | 81202.15 | +5.7% |


Oil volatility dominates FX and current-account risks. Brent crude closed the week at 99.29 after a 6.05 percent decline. The move kept import costs elevated for net-energy importers. USD/IDR rose 0.62 percent to 17,740, with gains recorded on four of five sessions. The currency move coincided with broad USD strength, amplifying pass-through pressures on fuel subsidies and current-account balances.
Regional equities close lower amid broad USD strength. JCI ended 1.43 percent lower at 6,441.16, KLCI fell 1.91 percent to 1,665.56, and STI declined 1.08 percent to 5,656.11. USD/MYR rose 0.84 percent to 4.08 while USD/SGD gained 0.68 percent to 1.28. USD/THB finished 0.60 percent weaker at 33.29.
Malaysia inflation print anchors near-term stability. No high-impact releases occurred across the six economies during the week. Oil and USD moves remained the dominant drivers.
Thailand external-demand signals remain constructive. No fresh data prints altered the growth outlook. Attention stayed on regional oil-price spillovers.
Bank Indonesia kept its policy rate unchanged ahead of the 23 September decision. Bank of Thailand maintained its data-dependent stance. Bank Negara Malaysia received a steady inflation print that reinforced its unchanged policy bias. Bangko Sentral ng Pilipinas and the Monetary Authority of Singapore continued monitoring USD strength without fresh guidance. State Bank of Vietnam faced no new data releases that would alter its current rate path. The week’s oil-driven currency moves supplied the clearest inputs for the next round of policy communications.
Calendar data unavailable
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-23 | Central Bank Interest Rate Decision | 5.8 | - |

Bank Indonesia’s 23 September policy-rate decision will incorporate the latest rupiah and oil-price data. Malaysia’s September inflation release later in the period will provide the next read on price pressures. Thailand’s export momentum will feed into Bank of Thailand deliberations on growth versus imported-inflation trade-offs. Singapore’s MAS will continue managing the Singapore-dollar NEER band. The Philippines and Vietnam calendars remain light. Across the region, elevated external-debt levels will keep central banks focused on data-dependent adjustments.
Sustained Brent levels near 99.29 raise the possibility of wider current-account deficits for Indonesia and the Philippines if currency weakness persists. Thailand’s growth outlook may prove sensitive to any reversal in electronics exports. Markets appear to underweight the cumulative effect of USD strength on ASEAN import costs, suggesting scope for larger inflation surprises in the next data cycle.
| Asset | Level | WoW |
|---|---|---|
| Nifty 50 | 23346.4 | +1.0% |
| Sensex | 74294.96 | +0.4% |
| USD/INR | 95.86 | +0.9% |
| EUR/INR | 110.12 | +2.5% |
| Reliance | 1226.4 | -2.5% |
| HDFC Bank | 731.0 | +3.2% |
| Brent Crude | 99.29 | -6.0% |
| Gold | 4424.9 | +1.7% |
| Bitcoin | 81202.15 | +5.7% |


Inflation overshoot dominates the data flow. August CPI printed above both consensus and the prior reading and remained the central reference point for the entire week.
Trade data signalled resilient external demand. The trade deficit narrowed, coinciding with a wider current-account deficit while the balance-of-payments surplus stayed in positive territory.
Equity markets recovered after an initial dip. Nifty 50 fell mid-week before closing at 23,346.40, up 0.99% for the period, while Sensex ended at 74,294.96.
Oil price relief emerged late in the week. Brent crude declined to 99.29, a 6.05% drop that offset some of the earlier imported-inflation impulse.
Rupee traded in a narrow band. USD/INR moved to 95.86, supported by Reserve Bank of India dollar sales.
No domestic releases altered the policy backdrop. The economic calendar contained zero high-impact events, leaving the August CPI print and external drivers as the dominant influences.
Sectoral rotation remained modest. Reliance closed at 1,226.40 after a 2.47% weekly decline while HDFC Bank rose 3.21% to 731.00, illustrating limited breadth in the equity advance.
Liquidity operations stayed steady. The Reserve Bank of India continued absorbing excess cash, keeping interbank rates unchanged at the policy rate corridor.
External resilience persisted. India’s forex reserves ranking as the fourth-largest globally provided a buffer even as the rupee faced pressure from higher US yields.
The August CPI print reinforced the Reserve Bank of India’s data-dependent stance by exceeding consensus and the prior reading. No speeches, minutes, or policy decisions were released during the week, leaving the policy rate unchanged. The narrowing trade deficit and the balance-of-payments surplus showed external buffers remain intact despite the wider current-account deficit. These outcomes keep the focus on incoming inflation and growth prints for upcoming decisions. The absence of new forward guidance means the central bank will continue to assess whether the inflation level persists into the next data cycle before any adjustment to the policy rate path.
Calendar data unavailable
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-23 | HSBC Composite PMI Flash | - | - |
| 2026-09-23 | HSBC Manufacturing PMI Flash | - | - |
| 2026-09-23 | HSBC Services PMI Flash | - | - |

HSBC Composite PMI Flash, Manufacturing PMI Flash, and Services PMI Flash are scheduled for September 23 and will provide the first activity readings after the August CPI overshoot. Any downside surprise would reinforce the case for caution at the Reserve Bank of India. Stronger prints would highlight sustained domestic demand momentum and keep imported inflation risks from the prior energy price spike in focus for coming quarters. No other high-impact Indian releases appear on the calendar through September 25. The PMI outcomes will feed directly into assessments of whether the inflation print marks a temporary spike or a more persistent elevation. Market participants will also monitor any follow-through comments from Reserve Bank of India officials on liquidity absorption operations. These data points will shape expectations for the timing of any policy rate adjustment at the next meeting.
The CPI overshoot raises the possibility that inflation remains above the prior trajectory for longer than expected, shifting the growth-inflation balance toward caution at the Reserve Bank of India. A sharper decline in Brent crude could ease imported price pressures faster than anticipated and reopen room for easing in coming quarters. Narrowing of the trade deficit supports external resilience, yet any reversal in the balance-of-payments surplus would test rupee stability around 95.86. Equity gains on Nifty 50 remain modest relative to the inflation surprise, suggesting limited conviction in a sustained recovery. The lack of new policy communication leaves the outlook exposed to any surprise in the September 23 PMI prints that could alter the data-dependent equilibrium.
| Asset | Level | WoW |
|---|---|---|
| BIST 100 | 13284.4 | -6.7% |
| USD/TRY | 48.77 | +0.3% |
| EUR/TRY | 56.02 | -0.6% |
| GBP/TRY | 65.3 | -0.7% |
| Gold (TRY) | 4424.9 | +1.7% |
| Brent Crude | 99.29 | -6.0% |
| EUR/USD | 1.15 | -0.9% |
| Bitcoin | 81204.37 | +5.7% |


Market moves dominate the week. The BIST 100 posted a 6.68 percent weekly decline, closing at 13,284.40. Currency and commodity moves contained. USD/TRY rose 0.33 percent to 48.77 while Brent crude fell 6.05 percent to 99.29, providing limited offset to domestic equity pressure. No macro data releases altered the narrative. The economic calendar contained zero high-impact Turkish prints between September 14 and 20, so attention remained fixed on market moves. Policy vacuum persists. With no Central Bank of the Republic of Turkey communications or data prints, markets received no fresh signals on the policy rate trajectory. Forward guidance remains data-dependent. Officials continued to tie any future policy adjustments to the next round of releases.
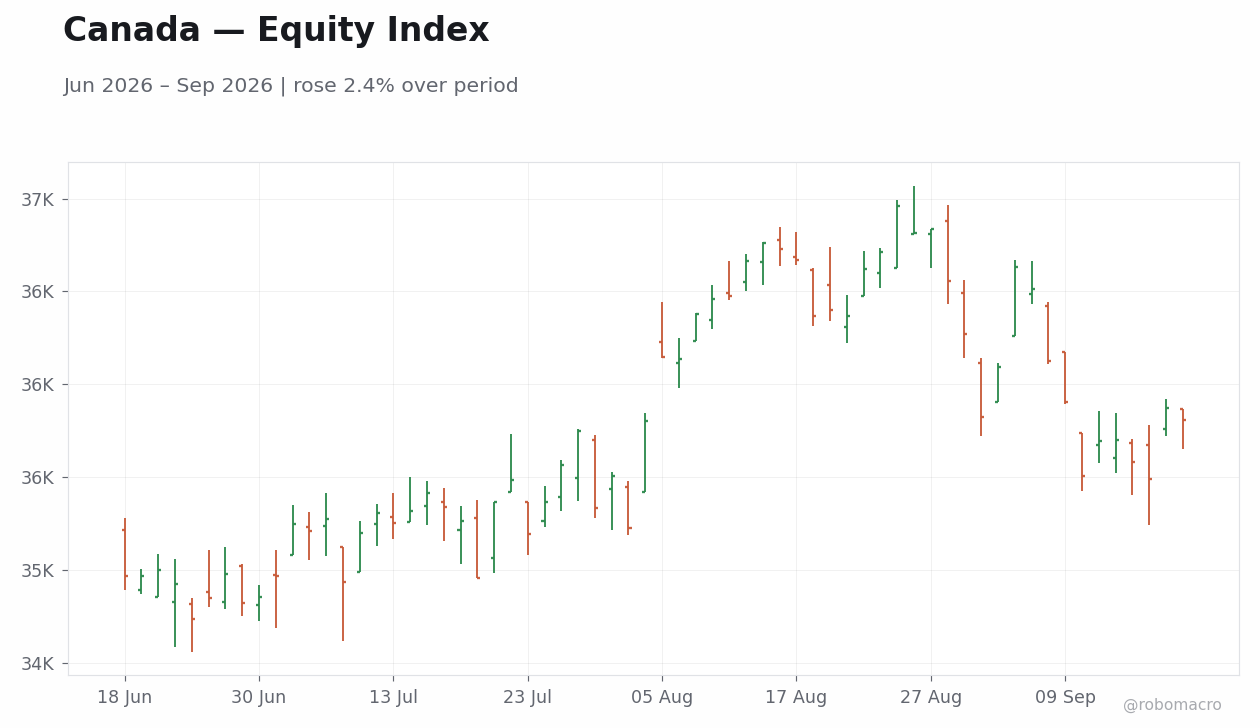
The Central Bank of the Republic of Turkey remained silent throughout the week with no speeches, minutes, or rate decisions. Capacity utilization and business confidence data scheduled for the following week will provide the next inputs for assessing price pressures. The absence of fresh activity or inflation prints left the policy rate on its existing path. Officials have previously emphasized data dependence, and the current week supplied no new figures that would alter that stance.
Calendar data unavailable
| Date | Release | Prior | Cons. |
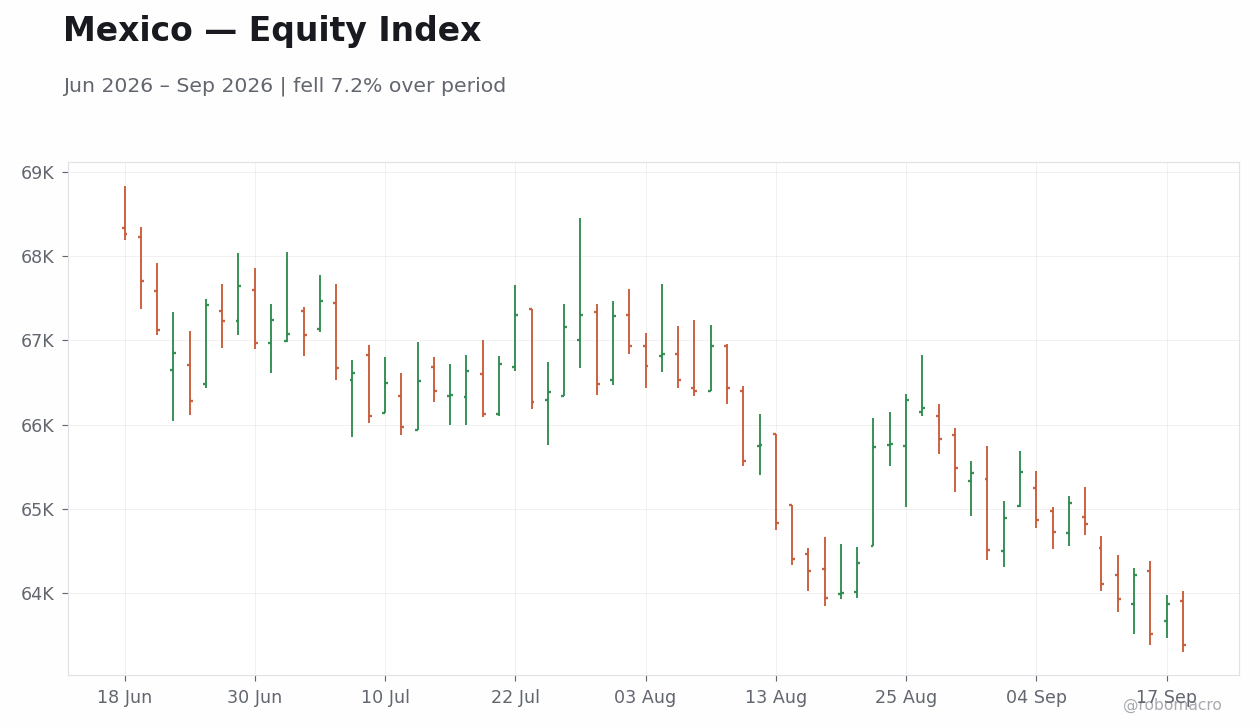
|---|---|---|---|
| 2026-09-21 | Business Confidence | 103 | - |
| 2026-09-22 | Consumer Confidence Index | 90.8 | - |
Business Confidence and Capacity Utilization Rate will print on September 21 at 03:00, offering the first domestic activity signals since mid-September. Consumer Confidence Index follows on September 22. These releases will inform assessments of demand momentum ahead of the next Central Bank of the Republic of Turkey decision. Capacity utilization near the prior 73.5 level would suggest stable but subdued manufacturing conditions. Business confidence around the prior 102.8 reading would point to unchanged sentiment. Both indicators feed directly into inflation and growth forecasts that guide the policy rate path over coming quarters. Any downside surprise could reinforce expectations for a steady policy rate, while resilience would keep tightening bias on the table.
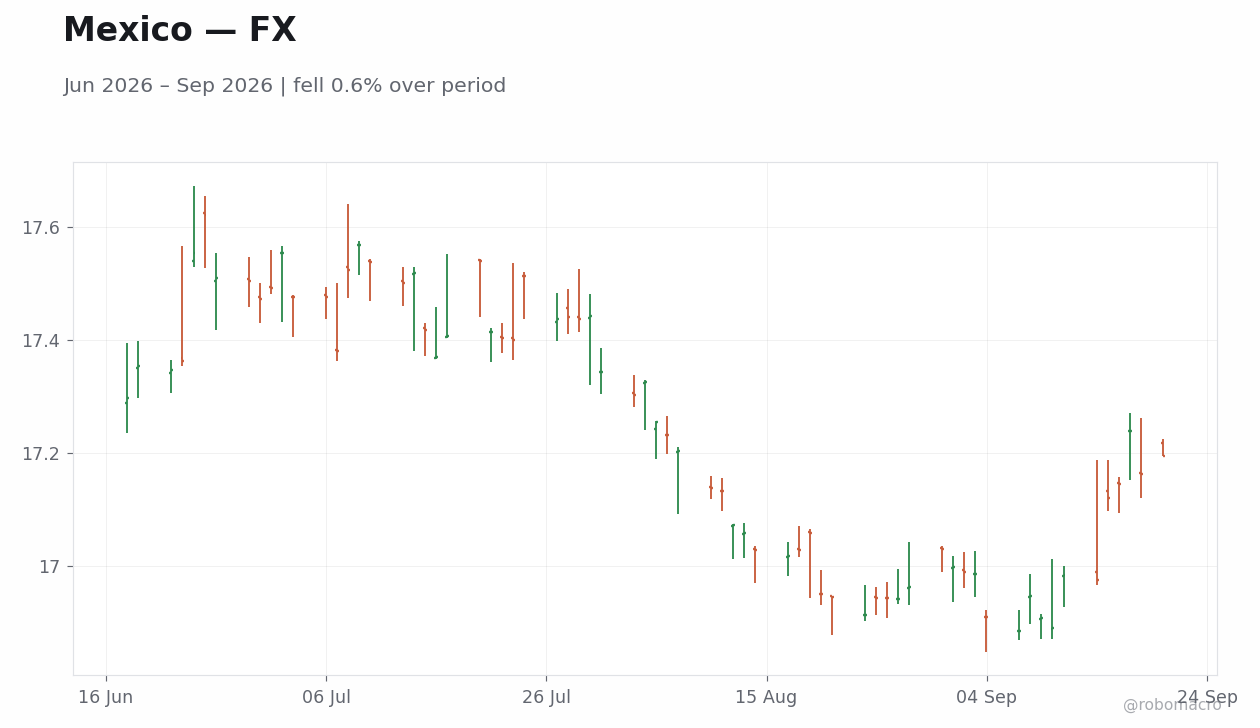
Brent crude’s 6.05 percent weekly decline reduces imported-inflation risk yet leaves the currency vulnerable if capital outflows accelerate. The lack of high-impact data this week means the next round of prints will carry extra weight for the policy rate outlook. Markets appear to be pricing limited immediate spillovers.
| Asset | Level | WoW |
|---|---|---|
| Saudi Aramco | 25.9 | +0.7% |
| MSCI Saudi | 37.43 | -1.0% |
| MSCI UAE | 19.93 | -0.6% |
| MSCI Qatar | 16.95 | -2.1% |
| MSCI Kuwait | 37.49 | -0.7% |
| Brent Crude | 99.29 | -6.0% |
| WTI Crude | 96.08 | -5.2% |
| Gold | 4424.9 | +1.7% |
| USD/SAR | 3.76 | +3.2% |
| USD/AED | 3.67 | +0.0% |
| USD/KWD | 0.31 | -0.2% |
| Bitcoin | 81204.37 | +5.7% |


Oil and equity market moves Brent crude and WTI both declined over the week. MSCI Saudi posted a net 0.98 percent decline to 37.43 while Saudi Aramco rose 0.7 percent to 25.9. MSCI UAE ended 0.6 percent lower at 19.93 and MSCI Qatar fell 2.13 percent to 16.95.
Central bank and policy backdrop No central bank meetings or high-impact data releases occurred across the GCC. August inflation and other macroeconomic prints remained outside the high-impact threshold.
FX and commodity response USD/SAR advanced 3.24 percent to 3.76. Gold rose 1.68 percent to 4424.9.
Non-oil activity backdrop No domestic policy signals or macroeconomic prints altered the growth trajectory. External energy prices remained the dominant input for fiscal and external balance assessments.
No central bank meetings took place. The path for subsequent meetings remains dependent on incoming inflation and activity data. External energy prices continue to shape the data-dependent stance across the GCC central banks.
Calendar data unavailable
Saudi Arabia’s Construction Cost Index release on September 21 will provide the first update on input costs. Turkey business confidence and capacity utilization figures the same day may offer indirect signals for regional demand. Poland wage and employment prints on September 21 carry low direct relevance. No central bank meetings or sovereign auctions appear on the GCC calendar through September 25. Markets will track any further updates on energy prices and compliance signals that could influence the next policy rate decisions. The absence of high-impact domestic releases leaves external energy prices as the dominant inputs for rate path assessments in coming quarters.
Equity markets registered limited moves despite the oil price decline, with MSCI Saudi down 0.98 percent. Rate path decisions remain data-dependent. Oil price swings would support or pressure fiscal balances depending on direction while imported inflation risks stay contained provided inflation prints remain stable.
| Time | Country | Event | Our Est. | Consensus | Prior | Impact |
|---|---|---|---|---|---|---|
| MONDAY, SEPTEMBER 21 | ||||||
| 03:00 | 🇹🇷 | Business Confidence | — | — | 102.8 | ●●○ |
| 08:30 | 🇺🇸 | Chicago Fed National Activity Index | — | — | — | ●●○ |
| TUESDAY, SEPTEMBER 22 | ||||||
| 00:30 | 🇳🇱 | Consumer Confidence Index | — | — | -34 | ●●○ |
| 03:00 | 🇨🇭 | Current Account Balance | — | — | 15.5B | ●●○ |
| 03:00 | 🇹🇷 | Consumer Confidence Index | — | — | 90.8 | ●●○ |
| 04:00 | 🇪🇸 | Trade Balance | — | — | -7.7B | ●●○ |
| 07:00 | 🇧🇷 | BCB Copom Meeting Minutes CB | — | — | — | ●●● |
| 08:00 | 🇭🇺 | Central Bank Interest Rate Decision CB | — | — | — | ●●● |
| 08:15 | 🇺🇸 | ADP Employment Change Weekly | — | — | — | ●●○ |
| 09:00 | 🇳🇬 | Central Bank Interest Rate Decision CB | — | — | 26.5 | ●●● |
| 16:30 | 🇺🇸 | API Weekly Crude Oil Stocks | — | — | — | ●●○ |
| 17:00 | 🇰🇷 | Consumer Confidence Index | — | — | — | ●●○ |
| 19:00 | 🇦🇺 | S&P Global Manufacturing PMI Flash | — | — | — | ●●○ |
| 19:00 | 🇦🇺 | S&P Global Services PMI Flash | — | — | — | ●●○ |
| WEDNESDAY, SEPTEMBER 23 | ||||||
| 01:00 | 🇮🇳 | HSBC Composite PMI Flash | — | — | — | ●●○ |
| 01:00 | 🇮🇳 | HSBC Manufacturing PMI Flash | — | — | — | ●●○ |
| 01:00 | 🇮🇳 | HSBC Services PMI Flash | — | — | — | ●●○ |
| 03:15 | 🇫🇷 | S&P Global Composite PMI Flash | — | — | — | ●●○ |
| 03:15 | 🇫🇷 | S&P Global Manufacturing PMI Flash | — | — | — | ●●○ |
| 03:15 | 🇫🇷 | S&P Global Services PMI Flash | — | — | — | ●●○ |
| 03:30 | 🇩🇪 | S&P Global Manufacturing PMI Flash | — | — | — | ●●● |
| 03:30 | 🇩🇪 | S&P Global Composite PMI Flash | — | — | — | ●●○ |
| 03:30 | 🇩🇪 | S&P Global Services PMI Flash | — | — | — | ●●○ |
| 03:30 | 🇮🇩 | Central Bank Interest Rate Decision CB | — | — | 5.8 | ●●● |
| 03:30 | 🇵🇱 | Unemployment Rate | — | — | — | ●●○ |
| 04:00 | 🇿🇦 | Inflation Rate Month-over-Month | — | — | 0.20 | ●●○ |
| 04:00 | 🇿🇦 | Inflation Rate Year-over-Year | — | — | 4.3 | ●●○ |
| 04:30 | 🇬🇧 | S&P Global Manufacturing PMI Flash | — | — | — | ●●● |
| 04:30 | 🇬🇧 | S&P Global Services PMI Flash | — | — | — | ●●● |
| 06:00 | 🇬🇧 | CBI Industrial Trends Orders Level | — | — | -25 | ●●○ |
| 07:00 | 🇺🇸 | MBA 30-Year Mortgage Rate | — | — | — | ●●○ |
| 08:30 | 🇨🇦 | New Housing Price Index Month-over-Month | — | — | -0.10 | ●●○ |
| 09:00 | 🇿🇦 | Central Bank Interest Rate Decision CB | — | — | 7 | ●●● |
| 09:45 | 🇺🇸 | S&P Global Composite PMI Flash | — | — | — | ●●○ |
| 09:45 | 🇺🇸 | S&P Global Manufacturing PMI Flash | — | — | — | ●●○ |
| 09:45 | 🇺🇸 | S&P Global Services PMI Flash | — | — | — | ●●○ |
| 10:30 | 🇺🇸 | EIA Weekly Crude Oil Inventory | — | — | — | ●●○ |
| 10:30 | 🇺🇸 | EIA Weekly Gasoline Inventory | — | — | — | ●●○ |
| 20:30 | 🇯🇵 | S&P Global Manufacturing PMI Flash | — | — | — | ●●○ |
| 20:30 | 🇯🇵 | S&P Global Services PMI Flash | — | — | — | ●●○ |
| 21:30 | 🇦🇺 | Employment Change | — | — | -15,800 | ●●○ |
| 21:30 | 🇦🇺 | Full-Time Employment Change | — | — | 16,300 | ●●○ |
| 21:30 | 🇦🇺 | Unemployment Rate | — | — | 4.5 | ●●○ |
| Time | Country | Event | Our Est. | Consensus | Prior | Impact |
|---|---|---|---|---|---|---|
| THURSDAY, SEPTEMBER 24 | ||||||
| 02:45 | 🇫🇷 | Business Confidence | — | — | 103 | ●●○ |
| 02:45 | 🇫🇷 | Consumer Confidence Index | — | — | — | ●●○ |
| 03:30 | 🇸🇪 | Riksbank Rate Decision CB | — | — | — | ●●● |
| 03:30 | 🇨🇭 | SNB Interest Rate Decision CB | — | — | 0 | ●●● |
| 04:00 | 🇩🇪 | IFO Business Climate Level | — | — | — | ●●● |
| 04:00 | 🇳🇴 | Norges Bank Interest Rate Decision CB | — | — | — | ●●● |
| 05:00 | 🇸🇪 | Press Conference by Riksbank CB | — | — | — | ●●● |
| 08:30 | 🇨🇦 | Retail Sales Month-over-Month Final | — | — | 0.60 | ●●○ |
| 08:30 | 🇨🇦 | Retail Sales Month-over-Month Preliminary | — | — | -0.80 | ●●○ |
| 08:30 | 🇨🇦 | Retail Sales excluding Autos Month-over-Month | — | — | 0.50 | ●●○ |
| 08:30 | 🇺🇸 | Current Account Balance | — | — | -226.8B | ●●○ |
| 08:30 | 🇺🇸 | Weekly Jobless Claims | — | — | — | ●●○ |
| 10:00 | 🇺🇸 | New Home Sales Level | — | — | — | ●●○ |
| 10:00 | 🇺🇸 | New Home Sales Month-over-Month | — | — | — | ●●○ |
| 12:00 | 🇪🇬 | Central Bank Interest Rate Decision CB | — | — | — | ●●● |
| 15:00 | 🇲🇽 | Central Bank Interest Rate Decision CB | — | — | 6.5 | ●●● |
| 19:01 | 🇬🇧 | GfK Consumer Confidence | — | — | -14 | ●●○ |
| FRIDAY, SEPTEMBER 25 | ||||||
| 02:00 | 🇩🇪 | GfK Consumer Confidence | — | — | — | ●●● |
| 06:00 | 🇬🇧 | CBI Distributive Trades Level | — | — | — | ●●○ |
| 08:30 | 🇺🇸 | Durable Goods Orders Month-over-Month | — | — | — | ●●● |
| 08:30 | 🇺🇸 | Durable Goods Orders excluding Transp Month-over-Month | — | — | — | ●●○ |
| 10:00 | 🇺🇸 | Michigan Consumer Sentiment Final | — | — | — | ●●○ |
| SUNDAY, SEPTEMBER 27 | ||||||
| 19:50 | 🇯🇵 | BoJ Monetary Policy Meeting Minutes CB | — | — | — | ●●● |
AI-Generated Content: This publication is 100% generated by artificial intelligence systems and should not be considered as financial advice, investment recommendation, or professional research. All analysis, forecasts, and commentary are algorithmically produced.
Data Sources: Market data from public exchange and market-data providers. US Treasury yields from the Federal Reserve (FRED constant-maturity series). Macroeconomic data from central banks and national statistics offices. Economic calendar data from RoboMacro Economic Calendar. All data subject to revision and may be delayed.
No Warranty: RoboMacro makes no warranty, express or implied, regarding the accuracy, completeness, or reliability of the information contained in this publication. Data may be delayed, incomplete, or contain errors. Past performance is not indicative of future results.
Not Financial Advice: Nothing in this publication constitutes investment advice, tax advice, legal advice, or any other form of professional advice. Any opinions expressed are AI-generated and do not represent the views of any individual or organisation. Readers should consult qualified professionals before making investment decisions.
Nowcasts and Model Output: The US labour nowcast is the median of a ten-model ensemble. Activity indices are composite z-scores of weekly public high-frequency indicators, seasonally adjusted, published only for weeks meeting a minimum indicator-coverage threshold; the as-of date and coverage are shown on every row. All model output carries significant uncertainty.
Contact: [email protected] | robomacro.com
Publication: Global Macro Watch is published weekly on Sundays, covering the preceding Monday-to-Friday week. © 2026 RoboMacro. All rights reserved.