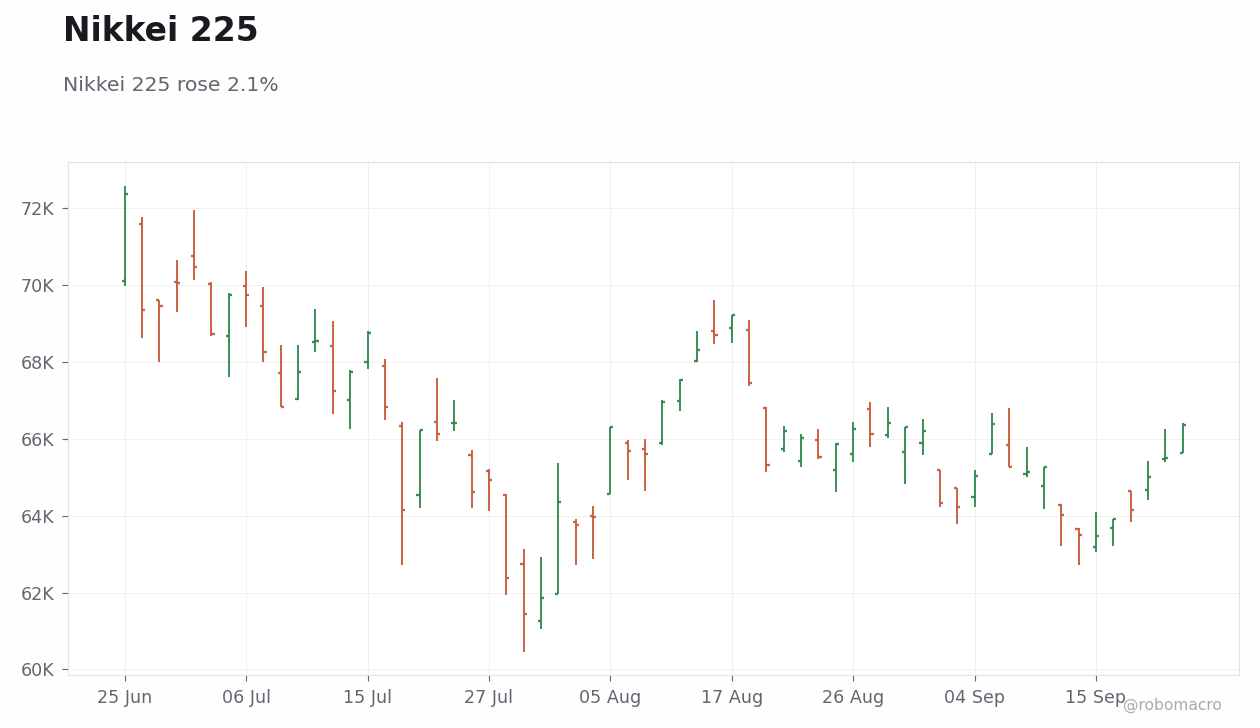
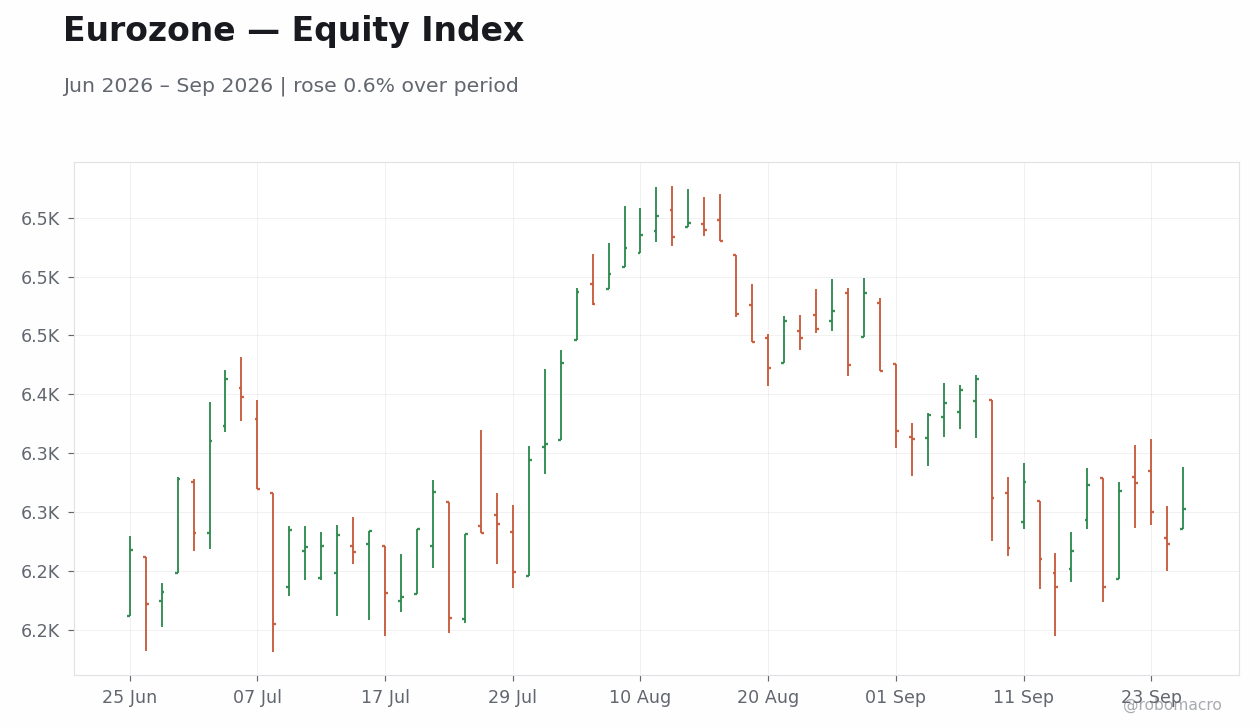
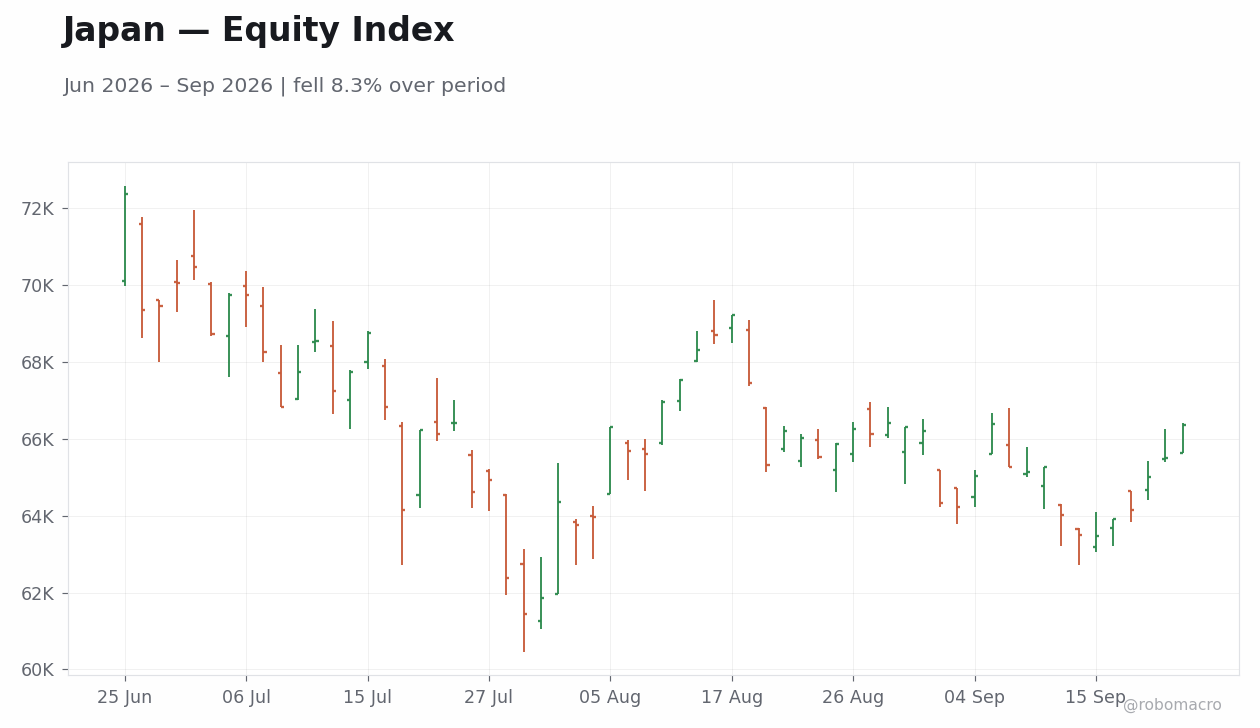
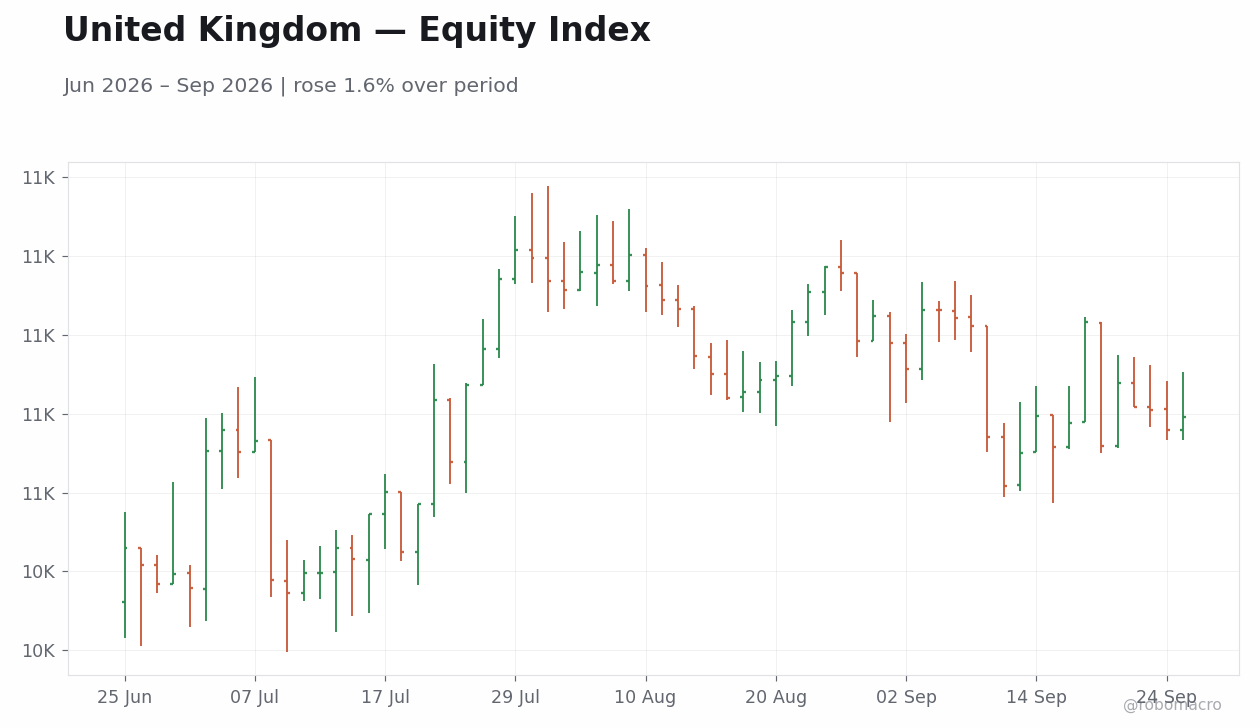
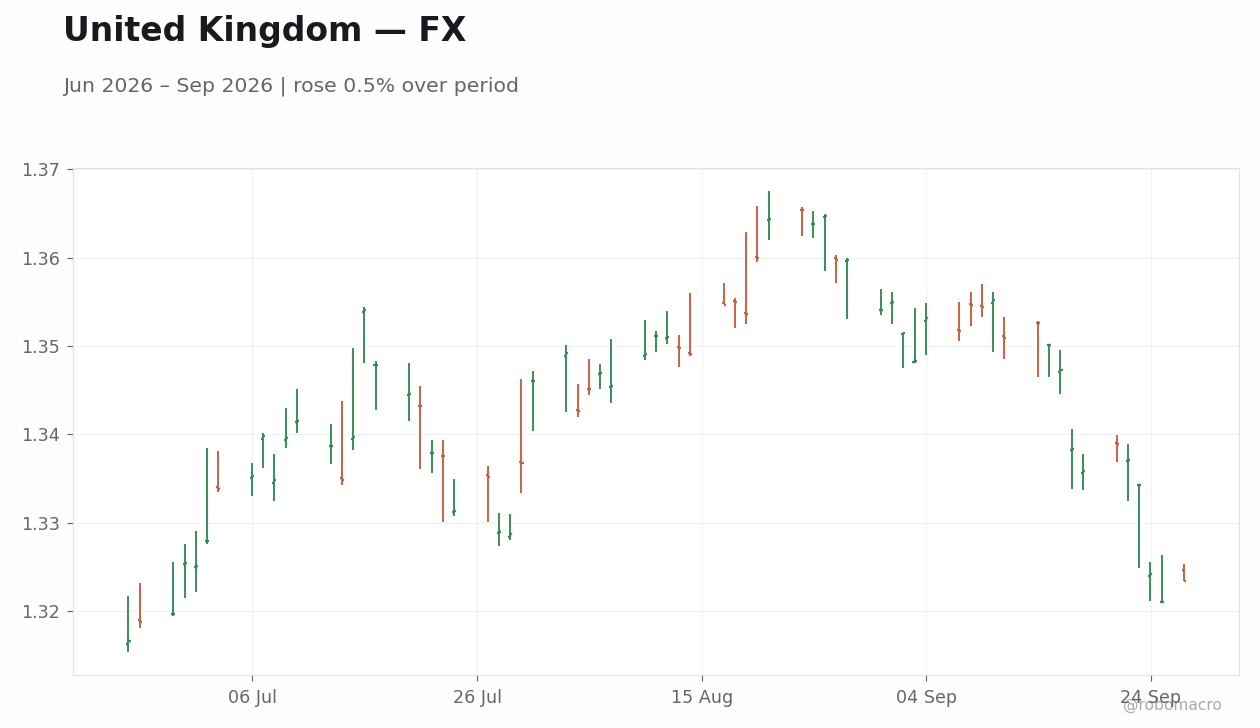
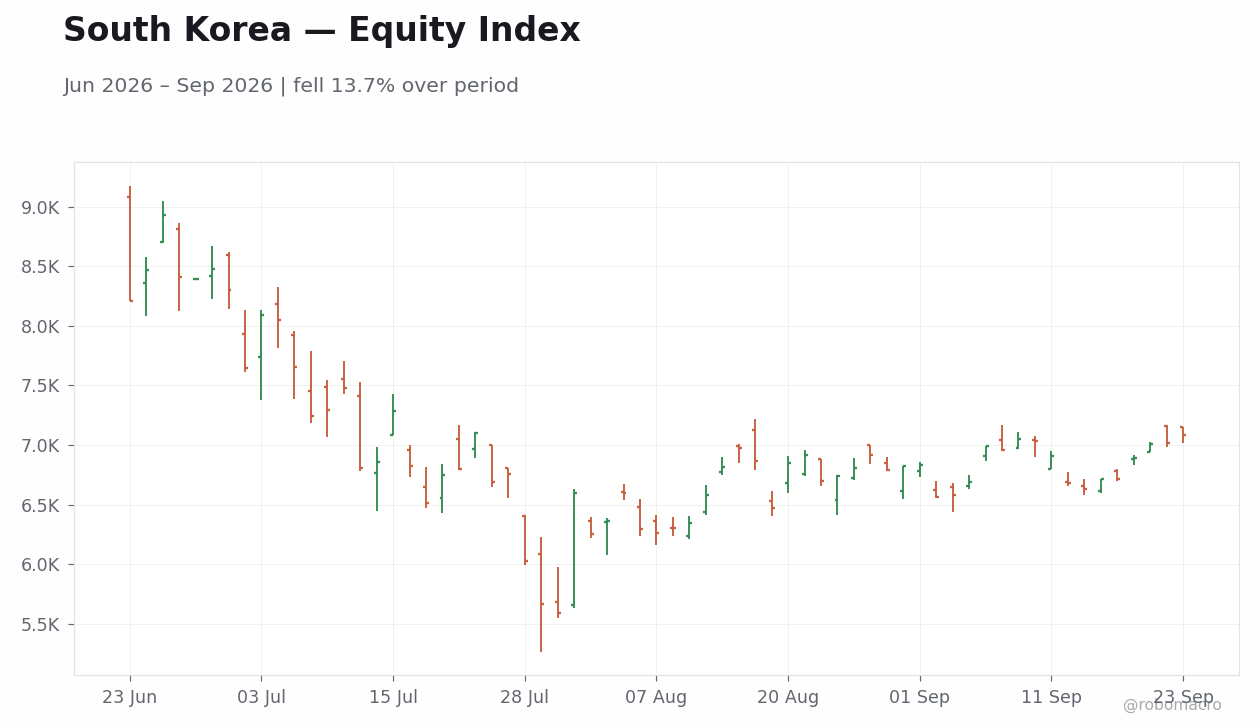
Risk appetite remained the dominant market signal during the week of September 21–25, 2026. Equity indices posted selective advances that outpaced volatility-adjusted moves in rates and currencies, placing the global cycle in a mid-phase expansion where investors continued to price resilience rather than imminent policy relief. KOSPI rose 5.4 percent while Nasdaq 100 gained 3.2 percent, both exceeding their typical weekly volatility. IPC Mexico advanced 2.5 percent and Nikkei 225 closed 1.3 percent higher at 66,364.2. In contrast, S&P 500 posted a net 0.27 percent decline to 7,743.41 and FTSE 100 fell 0.41 percent to 10,695.3. The configuration shows risk appetite holding without broad participation, consistent with a data-dependent policy equilibrium that has persisted since late August.
The week’s equity leadership aligned with activity beats that reinforced expansion momentum rather than commodity-driven inflation relief. US S&P Global Manufacturing PMI Flash exceeded consensus, marking the clearest activity beat. German Ifo Business Climate rose and the composite PMI jumped to a multi-month high, while France services PMI flash also beat expectations. These prints lifted Euro Stoxx 50 intraday even as manufacturing softness persisted. India HSBC Composite PMI Flash advanced in both manufacturing and services, confirming the clearest activity acceleration of the week. South Korea consumer confidence rose, supporting household resilience. The data flow indicates that equity markets rewarded regions where private-sector expansion remained intact, rather than those merely benefiting from lower energy prices.
Published every Sunday afternoon 100% AI-generated — not financial advice
DM outcomes cluster around selective resilience
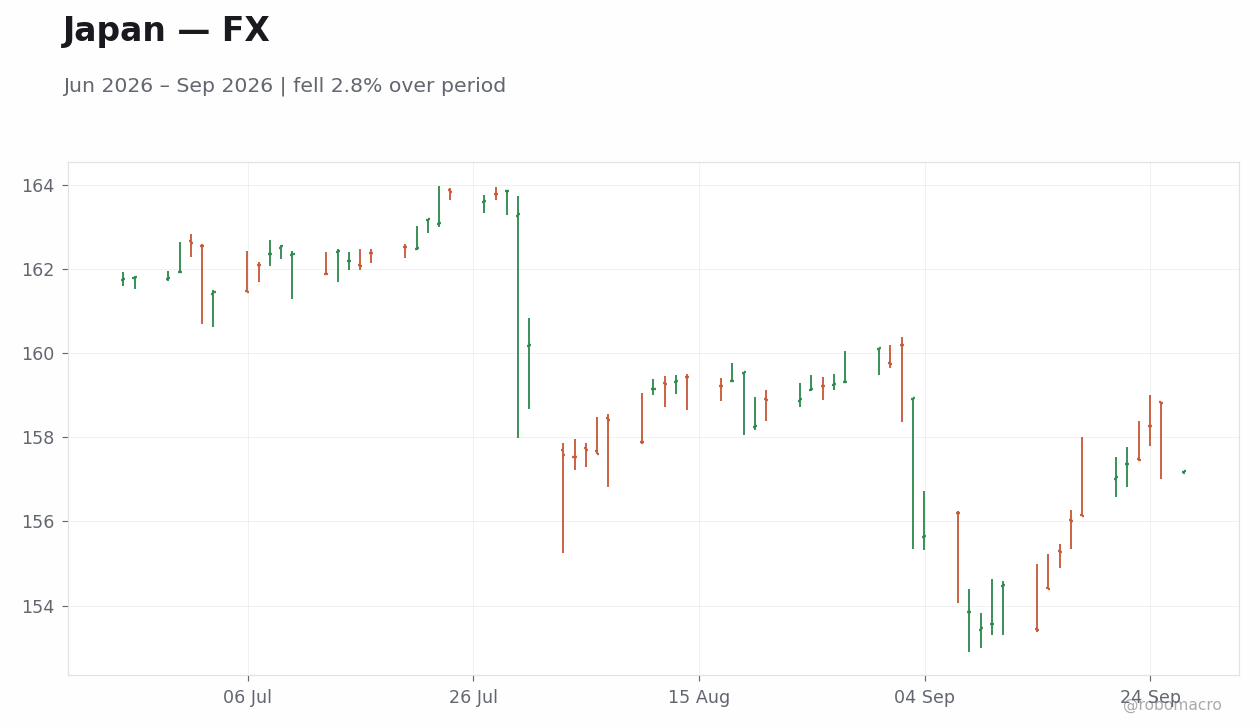
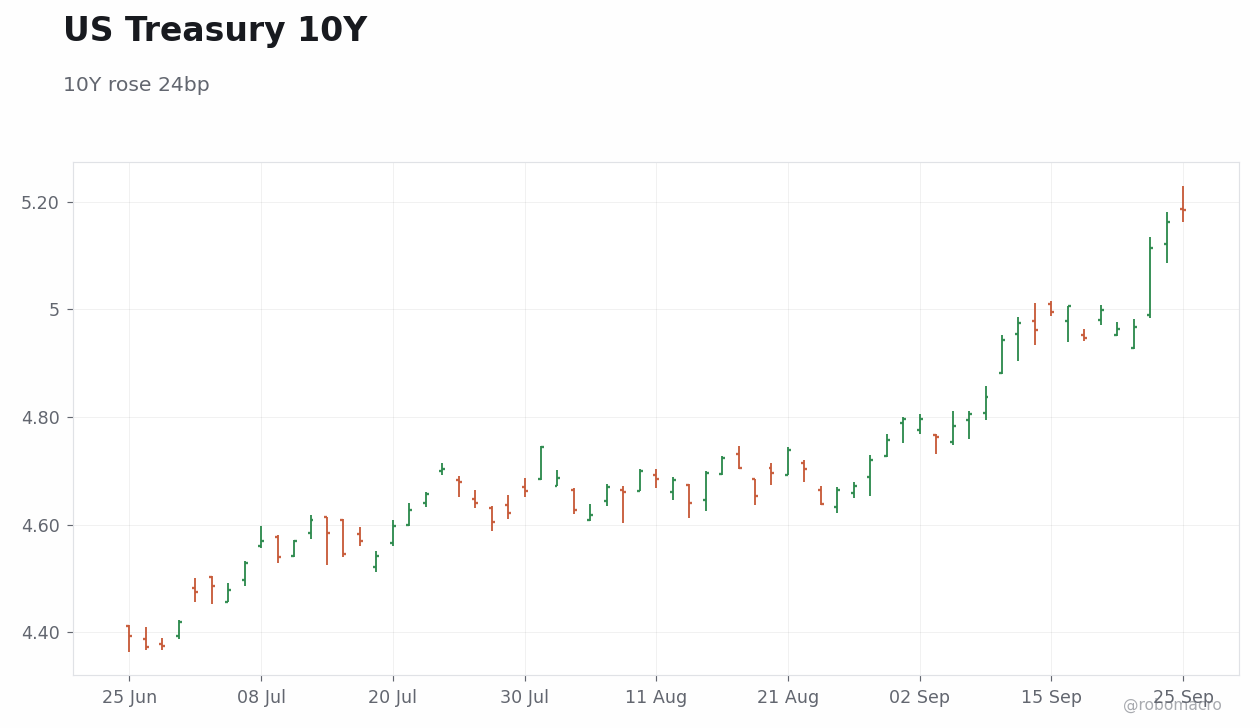
Developed-market equity performance diverged along domestic activity lines. US 10-year Treasury yield rose 24 basis points and the 2-year yield also advanced after Federal Reserve speakers including Williams, Jefferson, Barkin, and Barr delivered hawkish signals on persistent inflation. The S&P 500 closed lower despite the manufacturing PMI beat, illustrating tighter financial conditions coexisting with risk appetite elsewhere. Euro-area equities benefited from German and French services strength that offset manufacturing weakness, while German 10-year Bund yields held steady. Japan recorded Nikkei 225 gains alongside USD/JPY closing at 157.2. UK markets showed uneven momentum, with S&P Global Manufacturing PMI Flash advancing while services PMI eased; the Bank of England maintained its policy rate on a split vote after inflation data aligned with prior readings. Nordic policy spreads widened after Norges Bank raised its policy rate while the Riksbank held steady, contributing to equity divergence between OMX Stockholm 30 and Oslo Bors.
EM data flows split along equity leadership and currency pressure
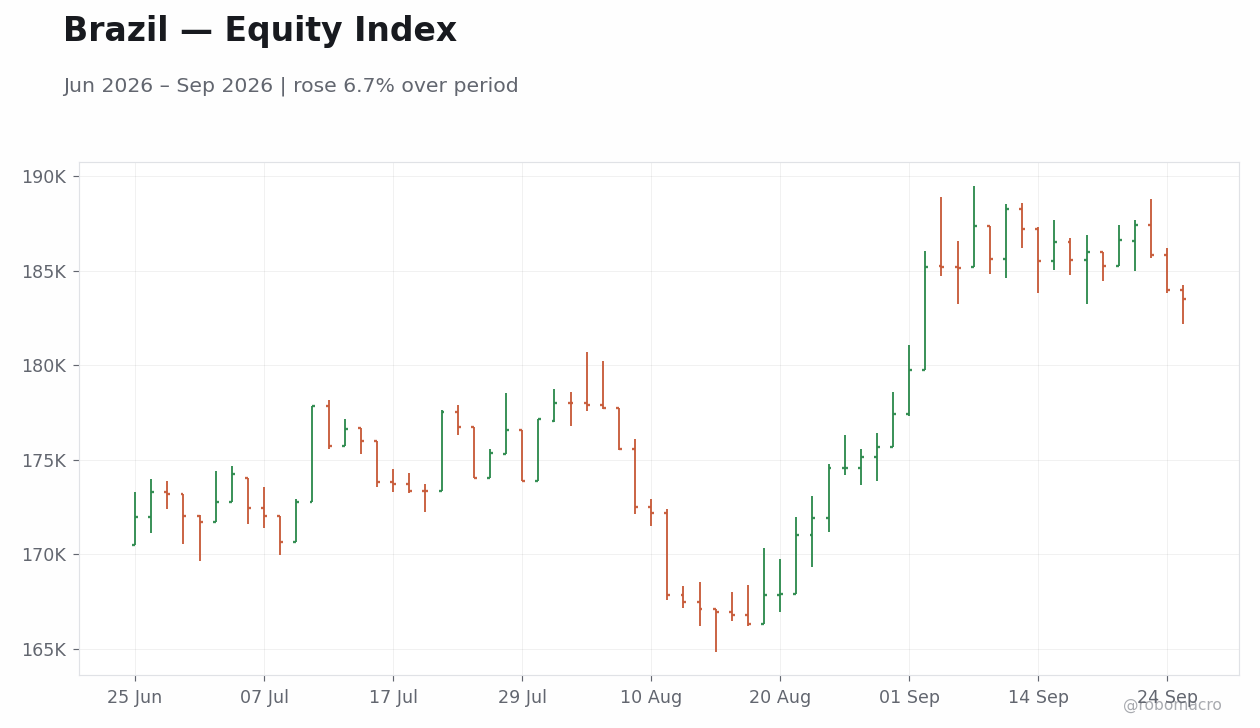
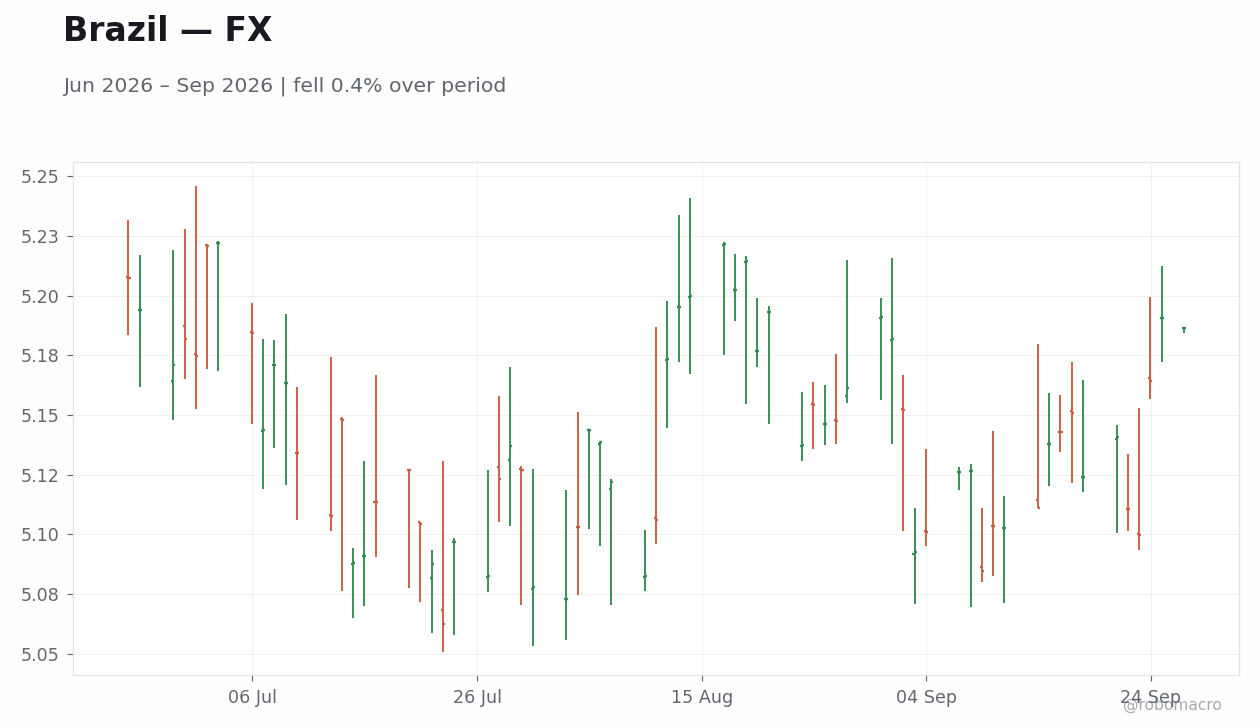
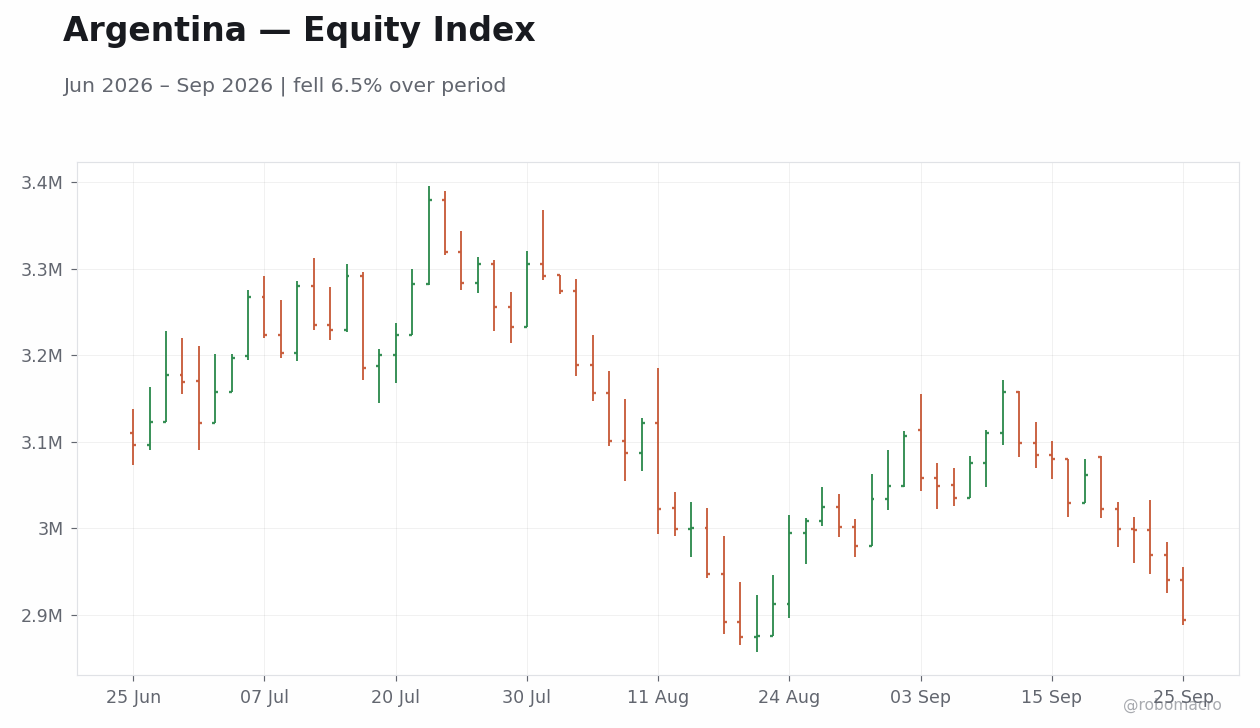
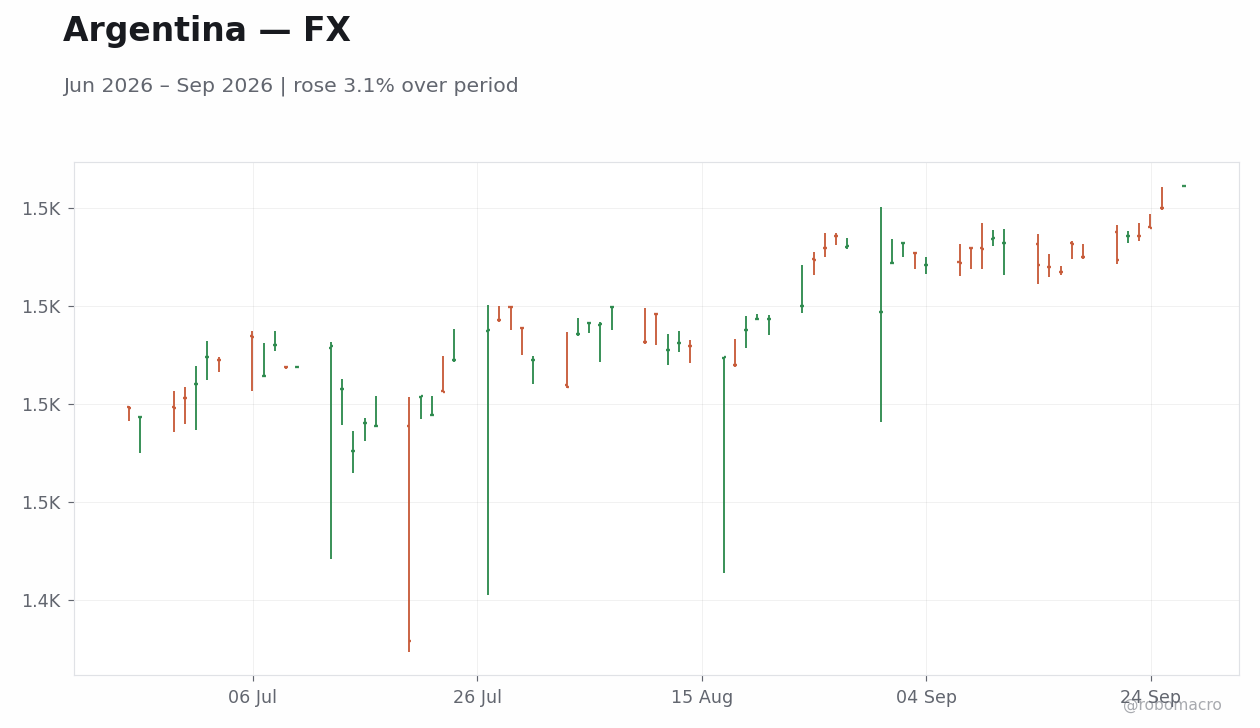
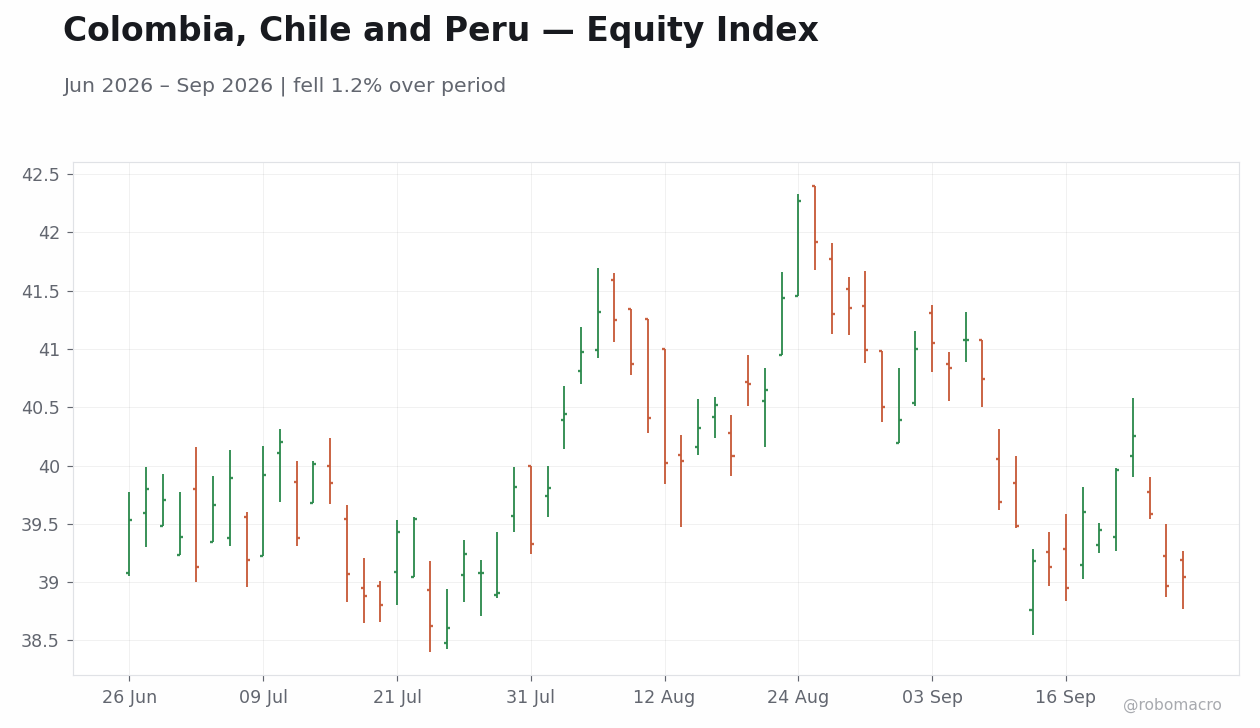
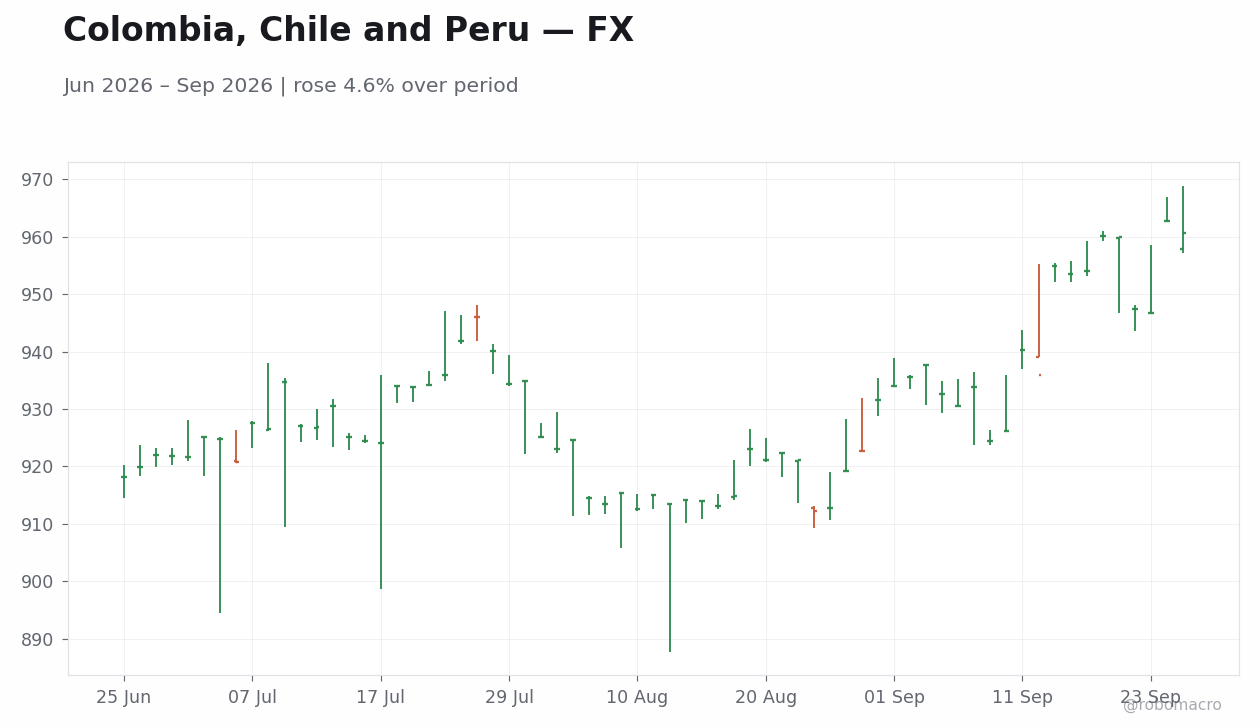
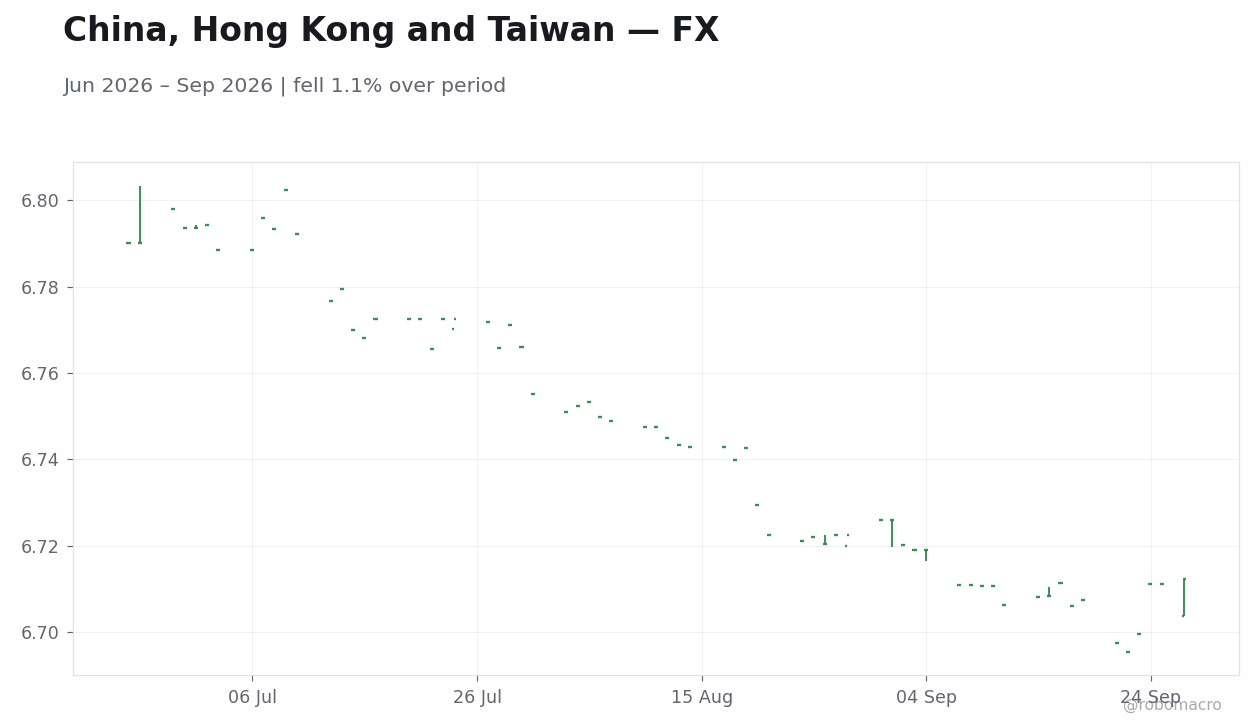
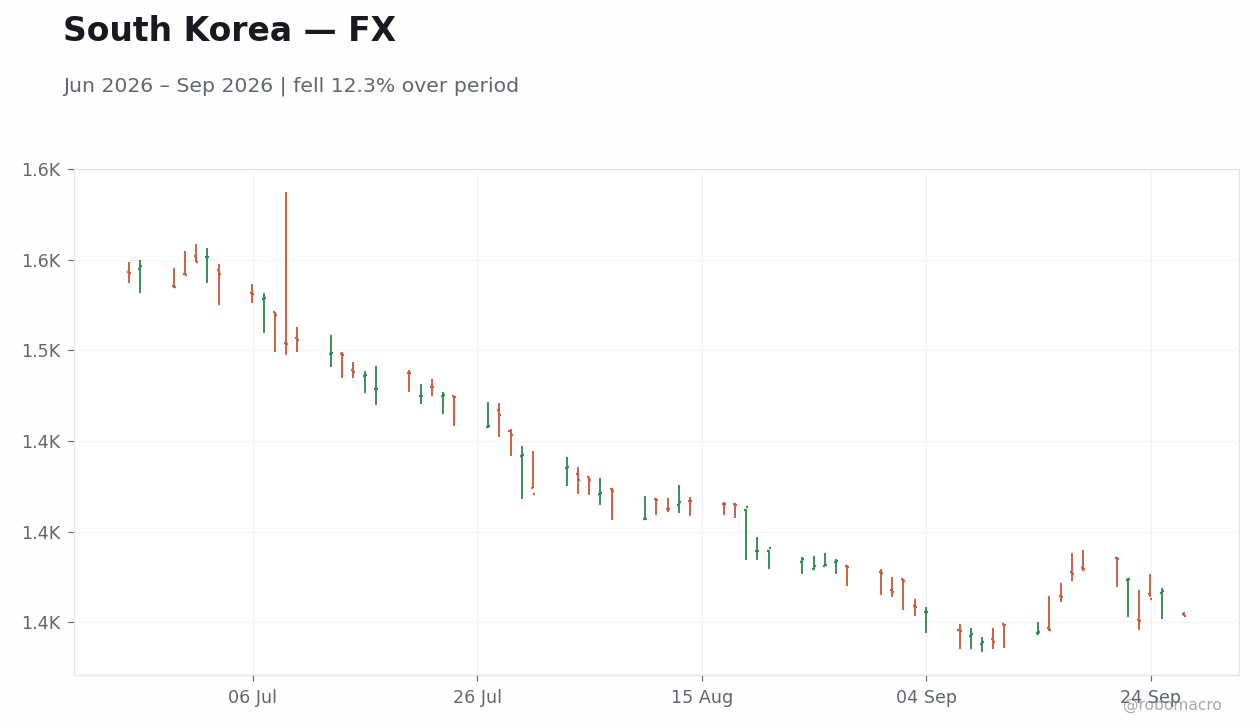
Emerging-market outcomes reflected the same risk-appetite gradient. KOSPI outperformance coincided with an export surge that drove USD/KRW 2.27 percent lower. IPC Mexico rose 2.5 percent to 64,992.23 even as USD/MXN advanced 2.92 percent to 17.73. In contrast, Bovespa fell 1.67 percent to 183,477 and USD/BRL rose 0.89 percent to 5.19 after Brazil lowered its 2026 GDP growth forecast. MERVAL declined 3.51 percent to 2,893,751.00 while USD/ARS rose 1.0 percent to 1,524.50. Regional currencies in Colombia, Chile, and Peru weakened sharply, with USD/PEN and USD/COP both advancing more than 3.5 percent. Greater China equities diverged, with TAIEX rising 0.64 percent to 48,024.60 while Shanghai Composite fell 1.56 percent to 3,888.37 and Hang Seng declined 2.13 percent to 24,510.09. The pattern shows risk appetite favoring export-linked or activity-beat markets while pressuring those facing fiscal or depreciation headwinds.
Cross-asset configuration confirms contained inflation pressure
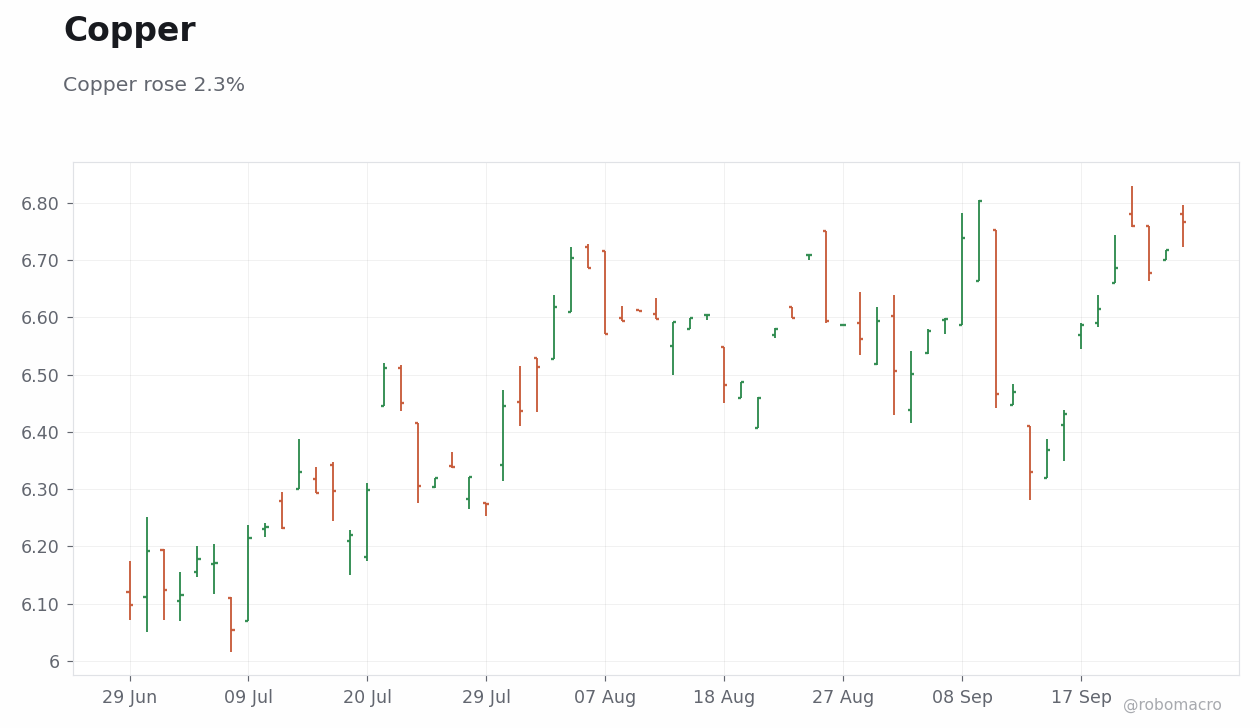
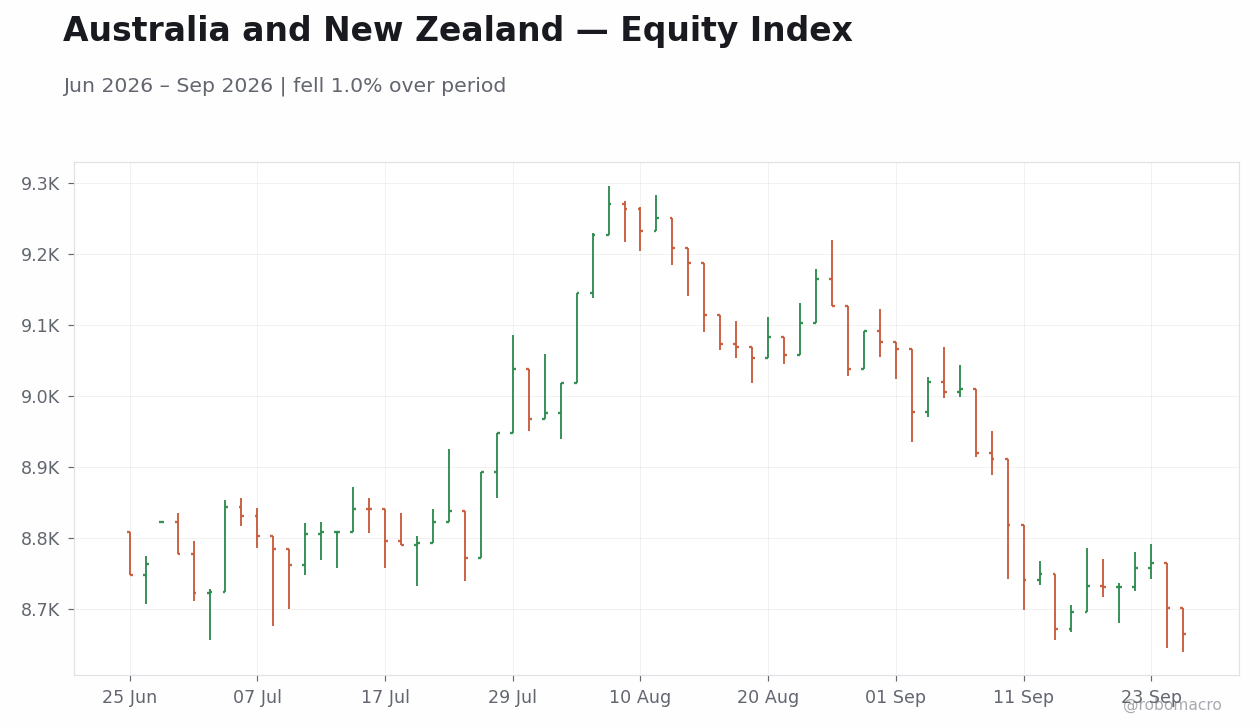
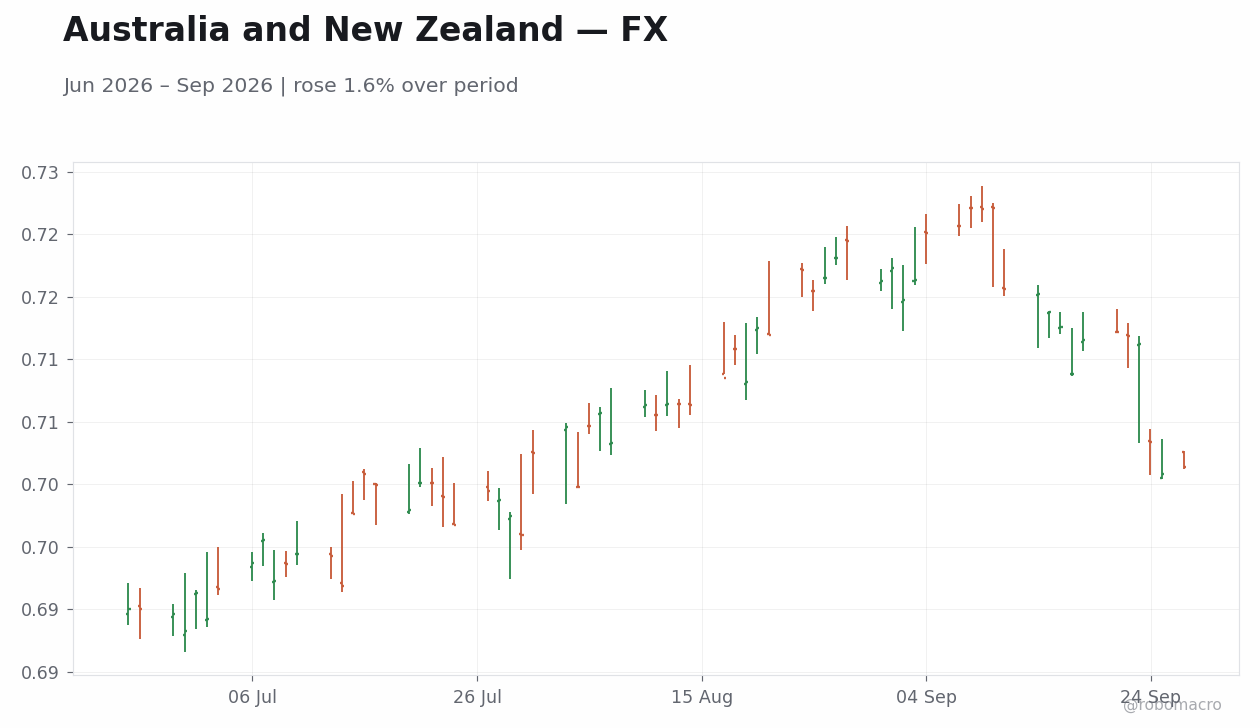
Rates, FX, and commodities together reinforced the risk-appetite narrative without triggering broad repricing. US 10-year yields rose 24 basis points while France 10-year yields advanced 15 basis points, reflecting fiscal-spread concerns rather than generalized rate-hike expectations. South Korea 10-year yields fell 15 basis points and Brazil 10-year yields declined 18 basis points. AUD/USD weakened 1.5 percent to 0.70 alongside ASX 200 falling 0.77 percent to 8,665.00. WTI crude fell 3.52 percent to 92.41 and Brent declined 2.89 percent to 97.44, trimming imported inflation pressure for net importers while reducing fiscal revenue prospects for Norway. Copper advanced 1.19 percent to 6.77 amid stable China demand signals. The cross-asset tape shows energy relief coexisting with tighter US financial conditions and selective equity leadership, leaving policy expectations anchored to incoming prints.
Policy outlook stays data-dependent across regions
Central banks maintained their explicit data-dependent stance. Banco de Mexico held its policy rate with no statement shift. Copom minutes released on 22 September reaffirmed Brazil’s data-dependent approach. South African Reserve Bank raised its policy rate with hawkish guidance reinforcing the 3 percent inflation target after inflation undershot consensus. Bank Indonesia held its policy rate on 22 September while expanding hedging incentives. Hungary’s MNB held steady and lowered its inflation target effective 2028. RBI Deputy Governor Poonam Gupta stated inflation is likely to remain within the target band. The common thread remains refusal to recalibrate parameters on the basis of a single week’s commodity or equity move.
Forward look centers on Brazil elections and next data prints
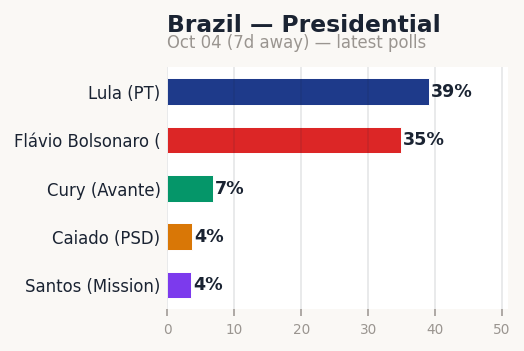
Investors will next focus on Brazil’s presidential election scheduled for 4 October 2026, where polls show Lula at 39.1 percent and Flávio Bolsonaro at 34.9 percent. The outcome will shape expectations for redistributive spending versus market liberalization. Additional attention will turn to US labor-market and inflation releases, euro-area final PMI prints, and any further Bank of Korea or RBI communications. The configuration leaves risk appetite positioned for continued differentiation based on activity beats rather than broad policy shifts.
| Economy | Real GDP (% y/y) | Consumer Prices (% y/y) | ||||
|---|---|---|---|---|---|---|
| 2026E | 2027E | 2028E | 2026E | 2027E | 2028E | |
| Americas | ||||||
| United States | 2.3 | 2.1 | 2.1 | 3.2 | 2.1 | 2.2 |
| Canada | 1.5 | 1.9 | 1.7 | 2.5 | 2.1 | 2.0 |
| Mexico | 1.6 | 2.2 | 2.1 | 3.9 | 3.4 | 3.0 |
| Brazil | 1.9 | 2.0 | 2.4 | 4.0 | 3.4 | 3.0 |
| Argentina | 3.5 | 4.0 | 3.8 | 30.4 | 15.7 | 9.6 |
| Colombia | 2.3 | 2.5 | 2.6 | 5.9 | 5.2 | 3.4 |
| Chile | 2.4 | 2.6 | 2.3 | 2.9 | 3.3 | 3.0 |
| Peru | 2.8 | 2.8 | 2.8 | 2.5 | 1.8 | 2.0 |
| Asia / Pacific | ||||||
| Japan | 0.7 | 0.6 | 0.6 | 2.2 | 2.3 | 2.0 |
| China | 4.4 | 4.0 | 4.0 | 1.2 | 1.5 | 1.8 |
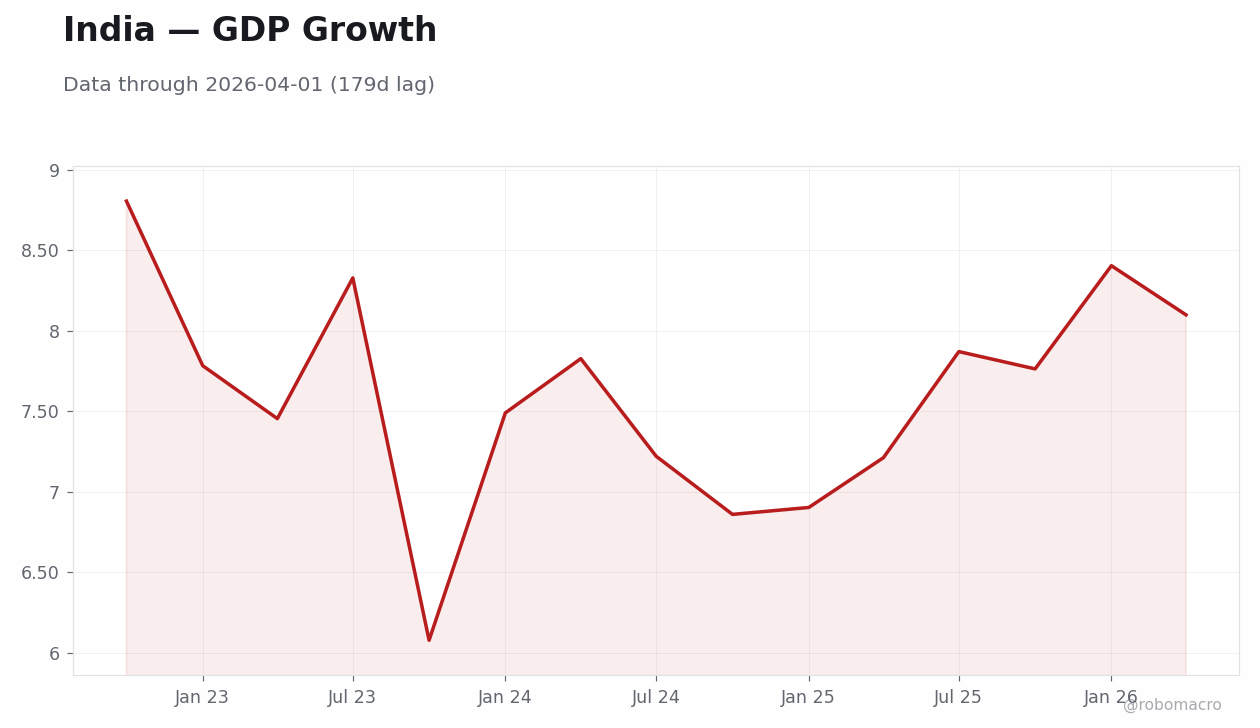
| India | 6.5 | 6.5 | 6.5 | 4.7 | 4.0 | 4.0 |
| Australia | 2.0 | 1.7 | 1.9 | 4.0 | 3.2 | 2.6 |
| New Zealand | 2.1 | 2.4 | 2.4 | 3.1 | 2.3 | 2.1 |
| South Korea | 1.9 | 2.1 | 2.2 | 2.5 | 1.9 | 2.0 |
| Indonesia | 5.0 | 5.1 | 5.2 | 3.0 | 2.6 | 2.5 |
| Malaysia | 4.7 | 4.3 | 4.3 | 1.9 | 2.0 | 2.0 |
| Philippines | 4.1 | 5.8 | 6.1 | 4.3 | 3.2 | 3.0 |
| Singapore | 3.5 | 2.7 | 2.5 | 2.3 | 1.9 | 2.0 |
| Thailand | 1.5 | 2.1 | 2.3 | 0.9 | 1.0 | 1.2 |
| Taiwan | 5.2 | 3.0 | 2.4 | 1.5 | 1.6 | 1.6 |
| Vietnam | 7.1 | 6.7 | 6.2 | 4.9 | 4.6 | 3.7 |
| Western Europe | ||||||
| Euro area | 1.1 | 1.2 | 1.4 | 2.6 | 2.2 | 2.1 |
| Germany | 0.8 | 1.2 | 1.2 | 2.7 | 2.3 | 2.0 |
| France | 0.9 | 0.9 | 1.2 | 1.8 | 1.7 | 1.9 |
| Italy | 0.5 | 0.5 | 0.8 | 2.6 | 2.4 | 2.3 |
| Spain | 2.1 | 1.8 | 1.8 | 3.0 | 2.3 | 2.5 |
| United Kingdom | 0.8 | 1.3 | 1.6 | 3.2 | 2.4 | 2.0 |
| Sweden | 2.0 | 1.9 | 2.1 | 1.5 | 1.8 | 2.6 |
| Norway | 1.5 | 1.3 | 1.1 | 3.3 | 2.6 | 2.2 |
| Denmark | 2.0 | 1.6 | 1.6 | 2.0 | 2.2 | 2.2 |
| Switzerland | 1.3 | 1.3 | 1.8 | 0.5 | 0.5 | 0.6 |
| Netherlands | 1.2 | 1.4 | 1.4 | 2.7 | 2.4 | 2.3 |
| Poland | 3.3 | 2.4 | 2.6 | 3.3 | 3.3 | 3.9 |
| Czech Republic | 2.2 | 2.2 | 2.1 | 2.4 | 2.2 | 2.5 |
| Hungary | 1.7 | 2.0 | 2.3 | 3.8 | 3.5 | 3.1 |
| Romania | 0.7 | 2.5 | 2.7 | 7.8 | 3.9 | 4.3 |
| EMEA Emerging | ||||||
| Turkey | 3.4 | 3.5 | 3.8 | 28.6 | 21.4 | 17.0 |
| South Africa | 1.0 | 1.3 | 1.5 | 3.9 | 3.4 | 3.0 |
| Israel | 3.5 | 4.4 | 3.7 | 2.3 | 2.1 | 2.0 |
| Saudi Arabia | 3.1 | 4.5 | 3.6 | 2.3 | 2.1 | 2.0 |
| UAE | 3.1 | 5.3 | 4.6 | 2.5 | 2.0 | 2.0 |
| Egypt | 4.2 | 4.8 | 5.5 | 13.2 | 11.1 | 8.1 |
| Nigeria | 4.1 | 4.3 | 4.1 | 16.0 | 15.9 | 12.7 |
| Kenya | 4.5 | 4.7 | 5.1 | 5.9 | 5.9 | 5.7 |
| Global Aggregates | ||||||
| Global | 3.1 | 3.2 | 3.2 | 4.4 | 3.7 | 3.4 |
| Developed markets | 1.8 | 1.7 | 1.7 | 2.8 | 2.2 | 2.1 |
| Emerging markets | 3.9 | 4.2 | 4.2 | 5.5 | 4.6 | 4.1 |
| Central Bank | Instrument | Current Rate |
Last Change |
bp | Next Meeting |
Q1 2026 |
Q2 2026 |
Q3 2026 |
Q4 2026 |
|---|---|---|---|---|---|---|---|---|---|
| The Americas | |||||||||
| Federal Reserve | Fed funds upper | 4.00% | Sep 2026 | +25 | Oct 28 | 3.75 | 3.75 | — | — |
| Bank of Canada | O/N rate | 2.25% | Oct 2025 | -25 | Oct 28 | 2.25 | 2.25 | — | — |
| BCB (Brazil) | SELIC | 13.75% | Sep 2026 | -25 | Nov 4 | 14.75 | 14.25 | — | — |
| Banxico | O/N rate | 6.50% | May 2026 | -25 | Nov 5 | 6.75 | 6.50 | — | — |
| BCRA (Argentina) | Aggregates regime | n/v | — | — | — | — | — | — | — |
| BanRep (Colombia) | Repo | 12.00% | Jul 2026 | +75 | — | 10.25 | 11.25 | — | — |
| BCCh (Chile) | MPR | 4.50% | Dec 2025 | -25 | — | 4.50 | 4.50 | — | — |
| Europe / Africa | |||||||||
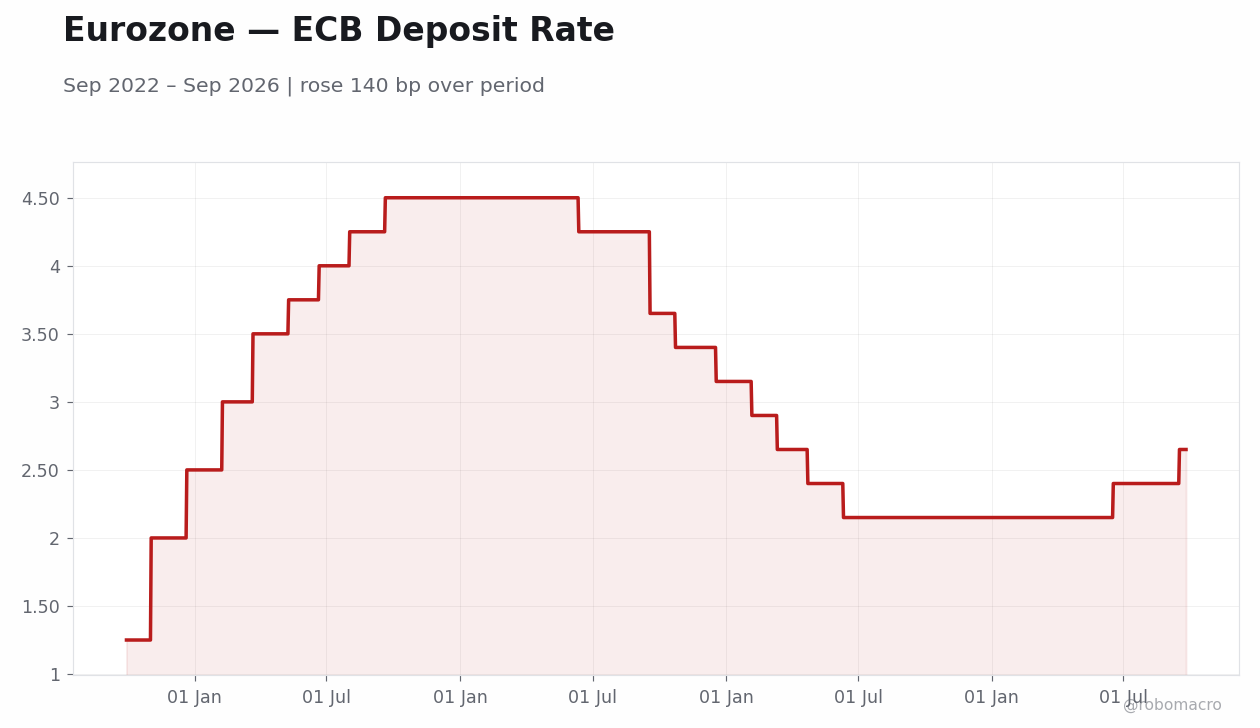
| ECB | Depo rate | 2.50% | Sep 2026 | +25 | Oct 29 | 2.00 | 2.25 | — | — |
| Bank of England | Bank rate | 3.75% | Dec 2025 | -25 | Nov 5 | 3.75 | 3.75 | — | — |
| Riksbank | Repo rate | 1.75% | Oct 2025 | -25 | Nov 4 | 1.75 | 1.75 | — | — |
| Norges Bank | Dep rate | 4.25% | May 2026 | +25 | Nov 5 | 4.00 | 4.25 | — | — |
| SNB | Policy rate | 0.00% | Jun 2025 | -25 | Dec 10 | 0.00 | 0.00 | — | — |
| CNB (Czech) | 2-wk repo | 3.75% | Jun 2026 | +25 | Nov 5 | 3.50 | 3.75 | — | — |
| NBH (Hungary) | Base rate | 5.50% | Aug 2026 | -25 | Oct 20 | 6.25 | 6.25 | — | — |
| NBP (Poland) | Ref rate | 3.75% | Mar 2026 | -25 | — | 3.75 | 3.75 | — | — |
| SARB | Repo rate | 7.00% | May 2026 | +25 | Nov 19 | 6.75 | 7.00 | — | — |
| CBRT (Turkey) | 1-wk repo | 37.00% | Jan 2026 | -100 | Oct 22 | 37.00 | 37.00 | — | — |
| Asia / Pacific | |||||||||
| RBA | Cash rate | 4.35% | May 2026 | +25 | Sep 29 | 4.10 | 4.35 | — | — |
| RBNZ | OCR | 2.75% | Sep 2026 | +25 | Oct 28 | 2.25 | 2.25 | — | — |
| BoJ | Pol rate | 1.00% | Jun 2026 | +25 | Oct 30 | 0.75 | 1.00 | — | — |
| PBoC | 1-yr LPR | 3.00% | May 2025 | -10 | — | 3.00 | 3.00 | — | — |
| RBI (India) | Repo rate | n/v | — | — | — | — | — | — | — |
| BoK (Korea) | Base rate | 2.75% | Jul 2026 | +25 | — | 2.50 | 2.50 | — | — |
| BI (Indonesia) | BI-Rate | 5.75% | Jun 2026 | +25 | Oct 21 | 4.75 | 5.75 | — | — |
| BSP (Philippines) | Rev repo | 5.00% | Aug 2026 | +25 | — | 4.25 | 4.75 | — | — |
| BoT (Thailand) | 1-day repo | 1.00% | Feb 2026 | -25 | Oct 28 | 1.00 | 1.00 | — | — |
| CBC (Taiwan) | Disc rate | n/v | — | — | — | — | — | — | — |
| MAS (Singapore) | SGD NEER | n/v | — | — | — | — | — | — | — |
| Nonfarm Payrolls (m/m) | +96k | 80% CI +38k…+215k |
| Unemployment Rate | 4.1% | |
| Avg Hourly Earnings (y/y) | 3.2% |
| Economy | Activity Index | 4-wk Δ | 13-wk Δ | Week ending | Indicators | Signal |
|---|---|---|---|---|---|---|
| Brazil | 63.8 | +7.9 | +10.7 | 2026-09-25 | 3/4 | Expanding · Advancing |
| United States | 61.4 | +8.4 | +6.4 | 2026-09-18 | 7/7 | Expanding · Advancing |
| Poland | 60.3 | +8.4 | +4.5 | 2026-09-25 | 3/4 | Expanding · Advancing |
| Canada | 55.5 | +0.5 | +9.5 | 2026-09-18 | 6/8 | Expanding · Advancing |
| Italy | 52.7 | -1.8 | -0.5 | 2026-09-18 | 5/5 | Expanding · Retreating |
| Germany | 50.1 | +5.4 | +5.5 | 2026-09-25 | 5/6 | Expanding · Advancing |
| Japan | 48.8 | -19.9 | +17.2 | 2026-09-25 | 4/5 | Contracting · Retreating |
| Australia | 47.9 | +3.5 | +7.0 | 2026-09-18 | 3/3 | Contracting · Advancing |
| New Zealand | 47.5 | -4.2 | -4.5 | 2026-09-18 | 4/5 | Contracting · Retreating |
| Euro Area | 46.3 | -1.4 | -3.0 | 2026-09-18 | 5/5 | Contracting · Retreating |
| Spain | 44.3 | -2.4 | -10.9 | 2026-09-18 | 5/5 | Contracting · Retreating |
| France | 42.4 | -2.2 | -6.4 | 2026-09-18 | 4/5 | Contracting · Retreating |
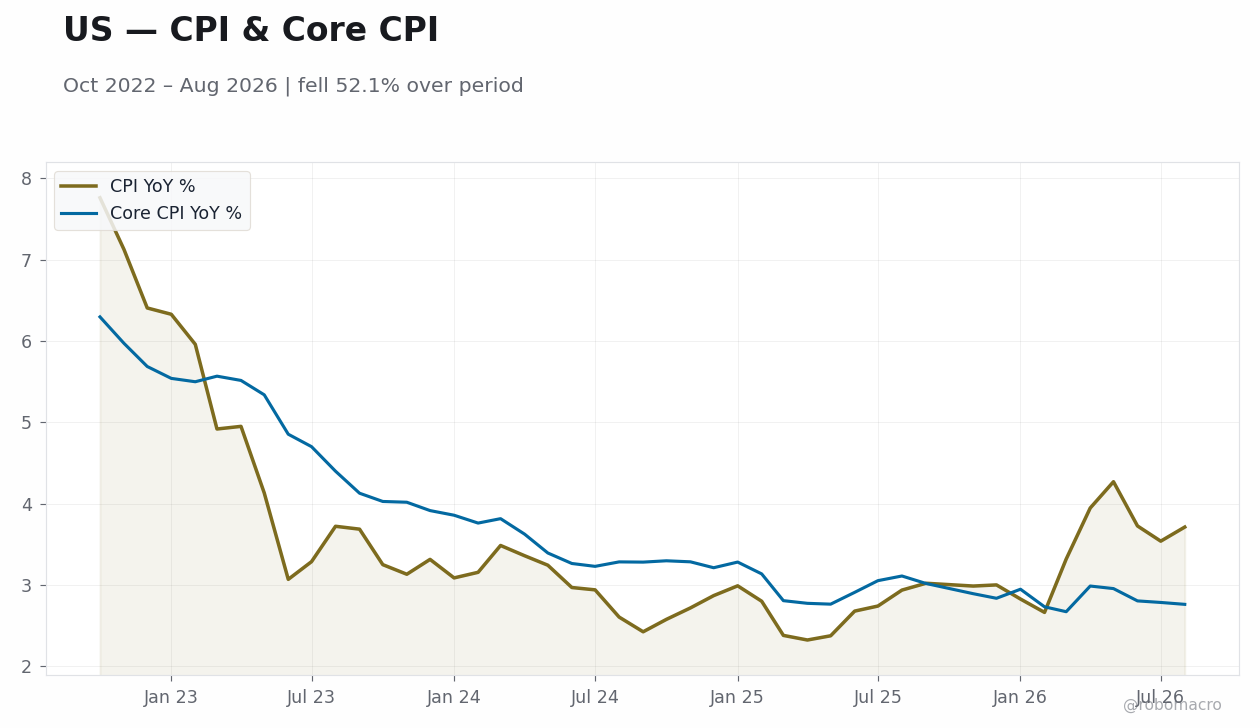
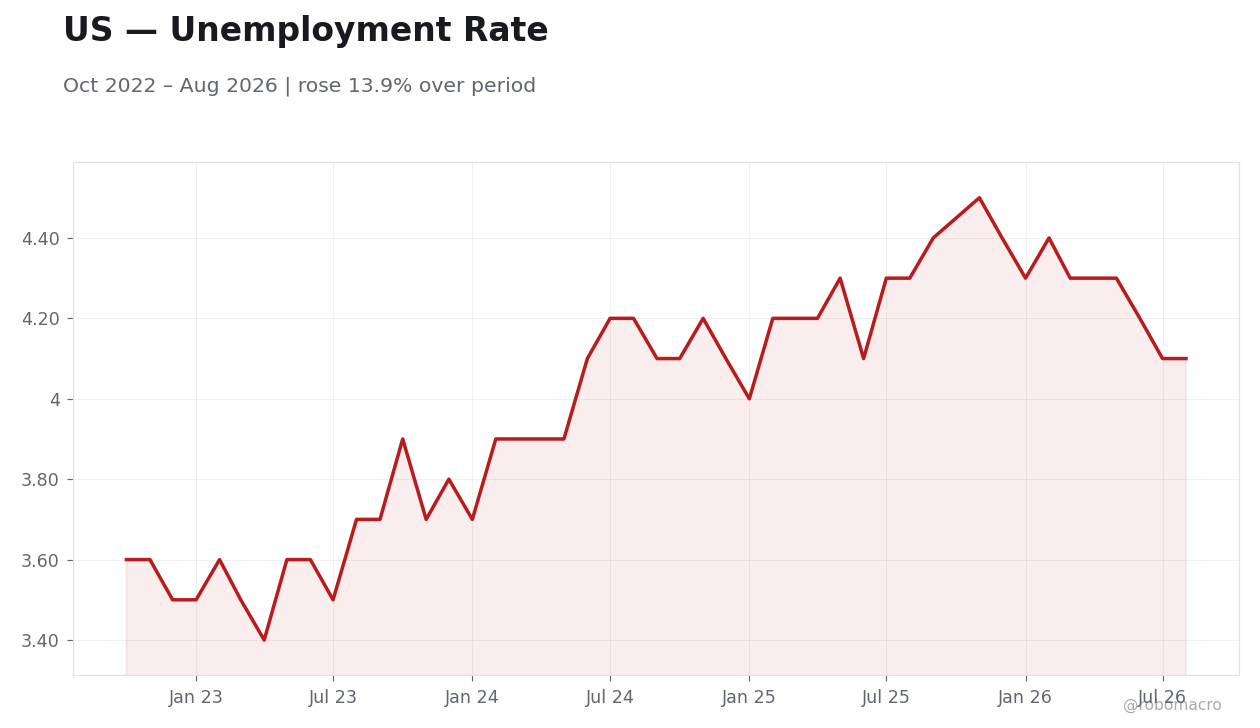
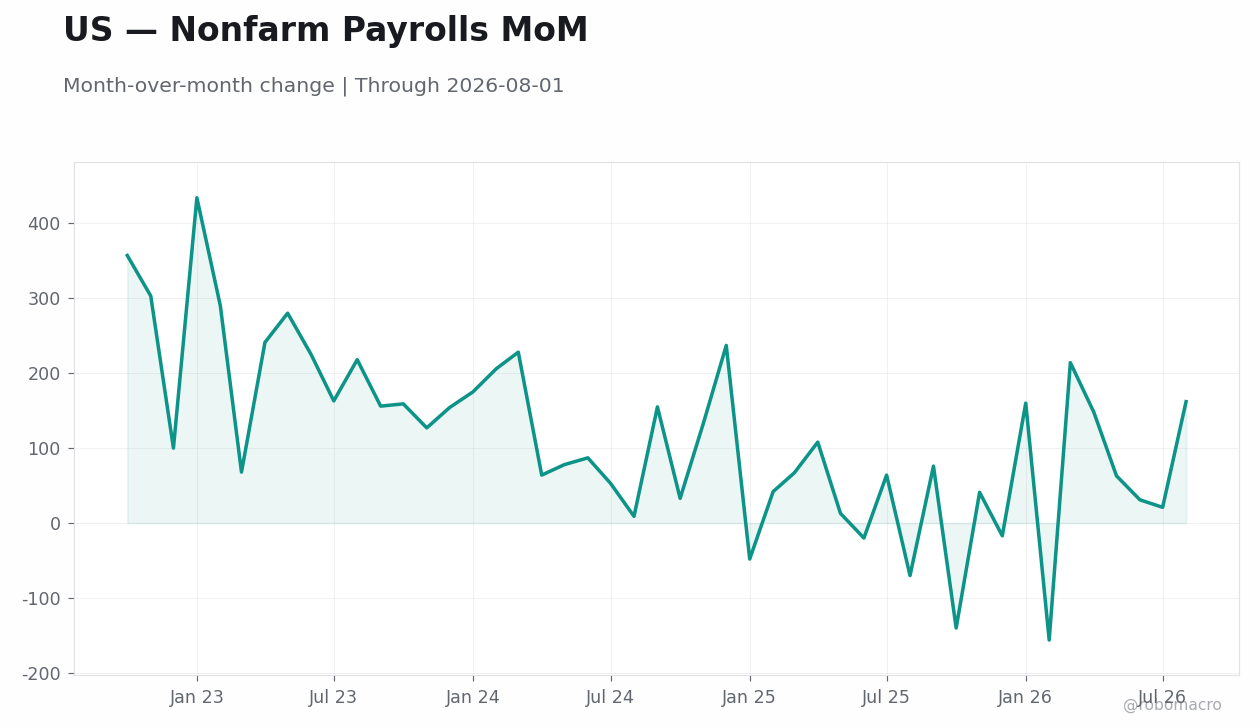
Activity remains in expansion in United States, Germany, Italy, Canada, Brazil, Poland; while high-frequency trackers point to sub-trend activity in Euro Area, France, Spain, Japan, Australia, New Zealand. On a 4-week basis, momentum is improving in United States, Germany, Canada, Brazil, Australia, Poland and cooling in Euro Area, France, Italy, Spain, Japan, New Zealand. RoboMacro's labor ensemble nowcasts the next US payrolls print at +96k.


Week in Review
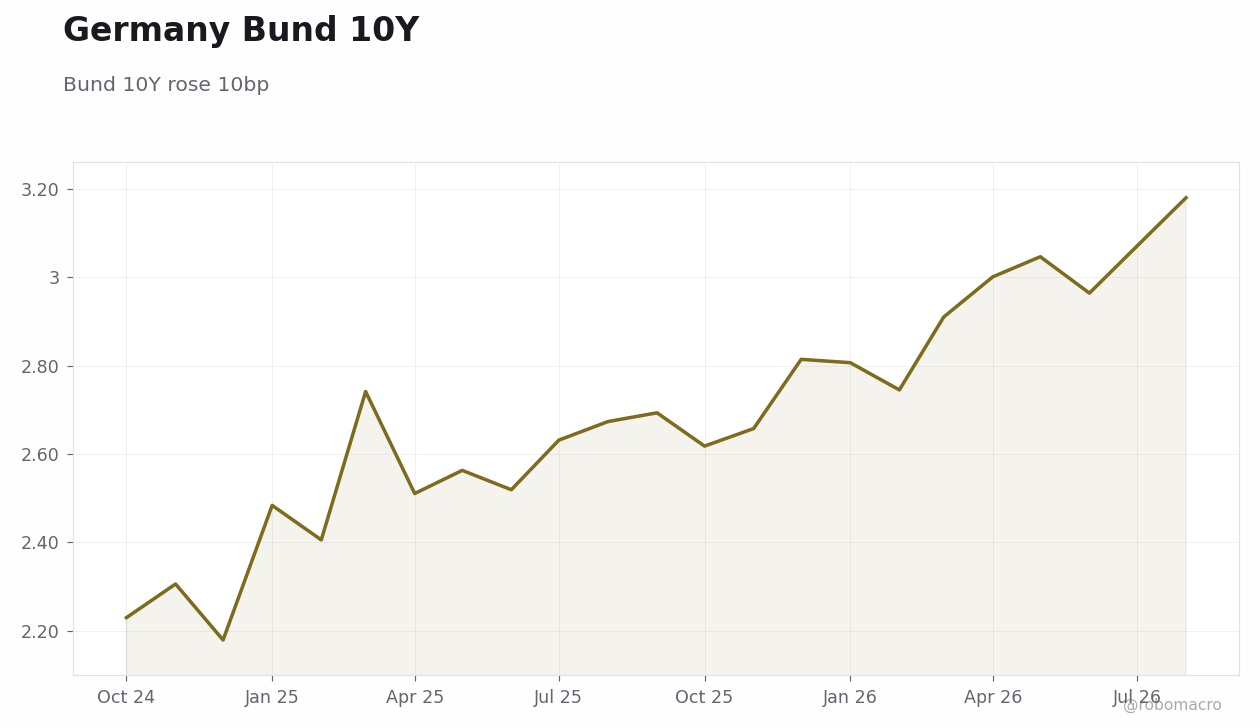
U.S. Treasury yields resumed their upward trajectory with the 10-year note rising 24 basis points to 5.18%. The intra-week path showed acceleration mid-week as the US 10Y yield increased from 4.9630 on Monday to 5.1840 by Friday, with notable jumps on Wednesday to 5.1140 and Thursday to 5.1620. German Bund yields climbed 10bp to 3.62%. UK 10-year gilt yields rose 6bp to 5.35%. Japanese government bond yields moved up 8bp to 3.07%. These increases occurred alongside resilient economic data that reinforced demands for higher compensation on longer-maturity debt.
Curve & Spreads
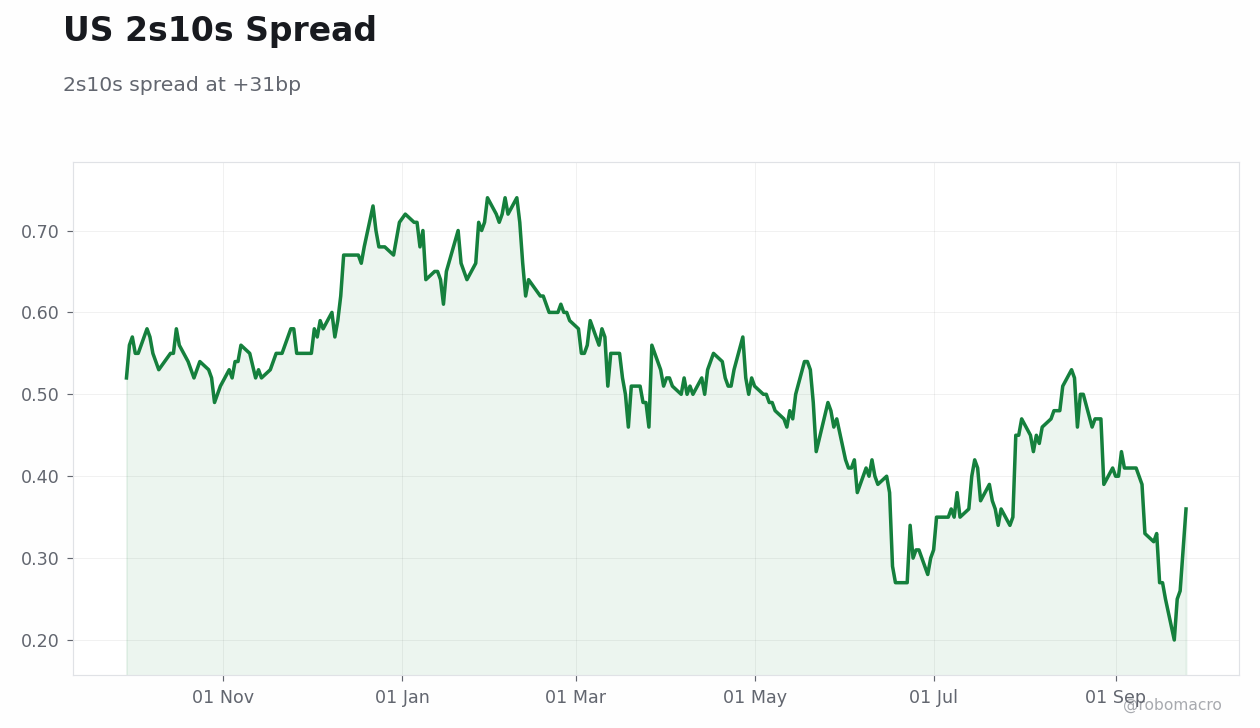
The U.S. 2s10s spread stood at +31bp, compared to Germany at +34bp and the UK at +66bp. The UK curve is materially steeper than those in the U.S. and Germany. This curve shape implies firmer growth expectations in the UK while the narrower spreads elsewhere point to more cautious growth outlooks.
EM Bonds
Turkish 10-year yields stand at 35.61% with the 2s10s at -125bp. Brazilian 10-year yields are at 14.12%. South African 10-year yields stand at 8.94% while Indonesian 10-year yields are at 7.08%. These EM yield levels remain markedly higher than DM counterparts such as the U.S. at 5.18% and Germany at 3.62%, underscoring the substantial spread differential investors demand.
Central Bank Read
Yield curve shapes across DM point to varied policy expectations. In the U.S. the 2-year yield rose 20bp to 4.87% while the 10-year rose 24bp to 5.18%, leaving the 2s10s at +31bp; the curve implies a tightening bias. German front-end yields rose 2bp to 3.28% against a 10bp increase in the 10-year to 3.62%, producing a +34bp 2s10s that similarly implies a tightening bias. By contrast the UK 2s10s at +66bp, driven by a 3bp decline in the 2-year to 4.69% alongside a 6bp rise in the 10-year, implies an easing bias. Front-end versus back-end moves overall indicate central banks will stay data-dependent with policy anchored to incoming inflation and activity prints.
Week Ahead
The economic calendar next week contains no major CPI/inflation prints, payrolls/jobs data, Fed, ECB, BoE or BoJ meetings, or GDP releases. Treasury auctions will therefore serve as the primary gauge of demand at current yield levels. These auctions matter most for duration risk because they will test investor appetite after the week’s sharp back-end selloff. Any deviation in auction demand could quickly amplify volatility in longer-maturity bonds.
| Country | 2Y | 2Y WoW | 10Y | 10Y WoW | 30Y | 30Y WoW | 2s10s |
|---|---|---|---|---|---|---|---|
| United States | 4.87% | +20bp | 5.18% | +24bp | 5.47% | +18bp | +31bp |
| United Kingdom | 4.69% | -3bp | 5.35% | +6bp | 5.87% | +12bp | +66bp |
| Germany | 3.28% | +2bp | 3.62% | +10bp | 3.92% | +8bp | +34bp |
| France | 3.60% | +5bp | 4.73% | +15bp | 5.30% | +12bp | +113bp |
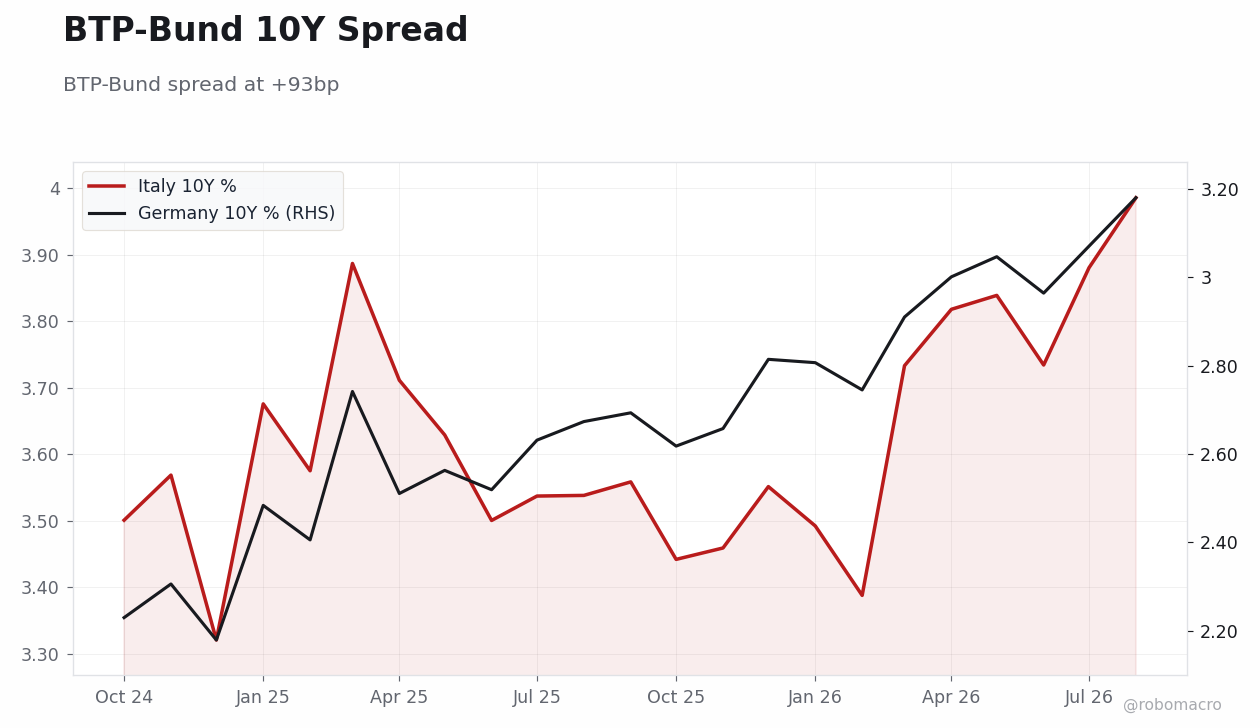
| Italy | 3.56% | +3bp | 4.55% | +11bp | 5.12% | +7bp | +99bp |
| Spain | 3.37% | +2bp | 4.08% | +9bp | 4.56% | +7bp | +71bp |
| Japan | 1.94% | +8bp | 3.07% | +8bp | 4.16% | +8bp | +114bp |
| Canada | 3.34% | +2bp | 3.92% | +5bp | 4.22% | +3bp | +59bp |
| Australia | 5.01% | -0bp | 5.39% | +9bp | 5.75% | +5bp | +38bp |
| China | 1.25% | +0bp | 1.67% | -1bp | 2.12% | -5bp | +42bp |
| India | 6.55% | +8bp | 7.11% | +5bp | 7.63% | +2bp | +56bp |
| Brazil | 13.83% | -0bp | 14.12% | -18bp | — | — | +28bp |
| Mexico | — | — | 9.52% | +6bp | — | — | — |
| South Korea | 3.97% | -1bp | 4.40% | -15bp | 4.58% | -12bp | +43bp |
| Indonesia | — | — | 7.08% | -7bp | 7.21% | -2bp | — |
| Turkey | 36.86% | -64bp | 35.61% | +34bp | — | — | -125bp |
| South Africa | — | — | 8.94% | +10bp | 9.26% | +6bp | — |
| Poland | — | — | 6.40% | +9bp | — | — | — |
US Treasury yields led the advance, with the 10Y rising 24bp to 5.18% and the 2Y adding 20bp to 4.87%, steepening the 2s10s to +31bp. The 30Y followed with an 18bp gain to 5.47%. Turkey’s 2Y posted the largest decline, falling 64bp to 36.86%, while South Korea’s 10Y dropped 15bp to 4.40% and Brazil’s 10Y eased 18bp to 14.12%. In Europe, France’s 10Y climbed 15bp to 4.73%, outpacing Germany’s 10bp rise to 3.62%. Japan’s entire curve shifted higher by 8bp across tenors, lifting the 2s10s to +114bp. UK yields diverged, with the 2Y easing 3bp to 4.69% even as the 30Y added 12bp to 5.87%. China’s 30Y declined 5bp to 2.12%, the only notable move lower in Asia ex-Japan.


Week in Review
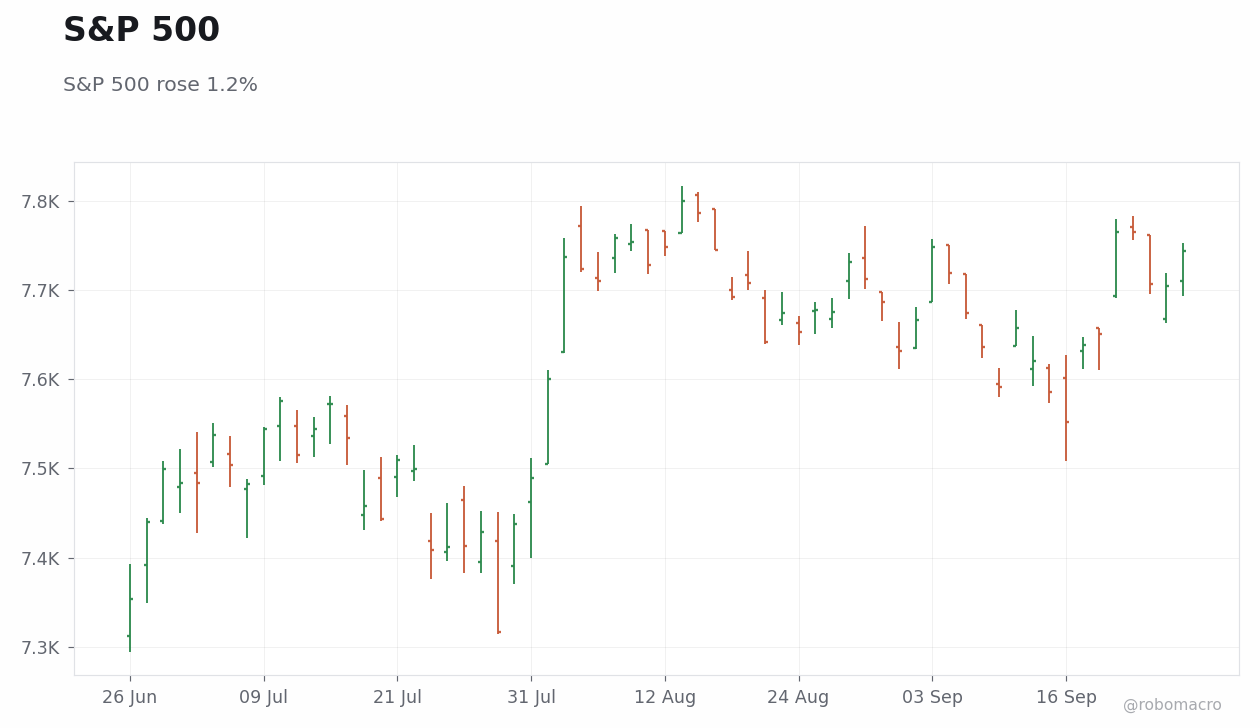
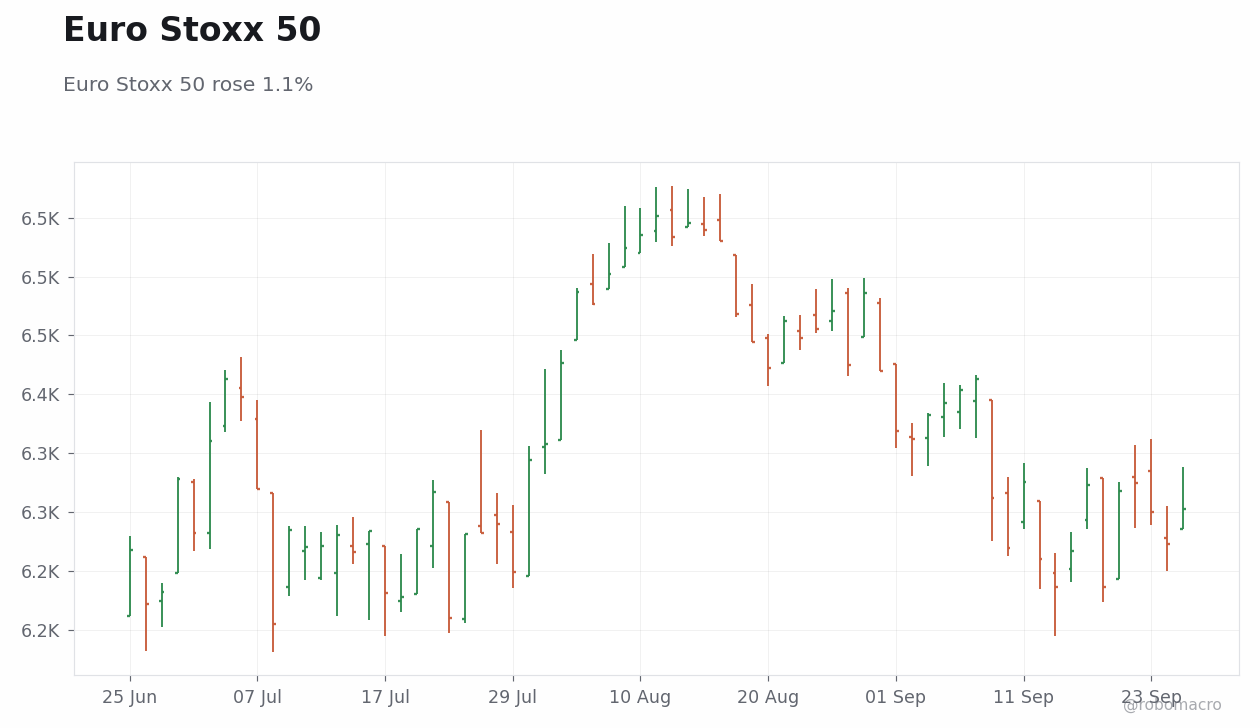
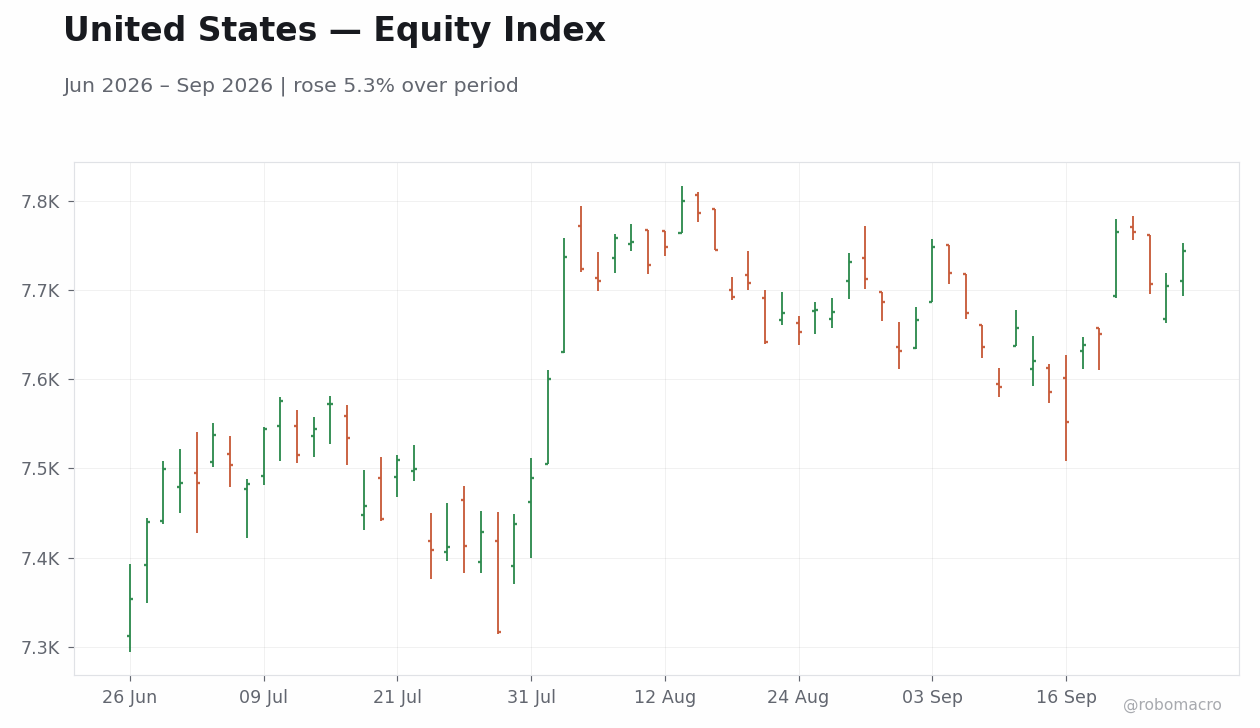
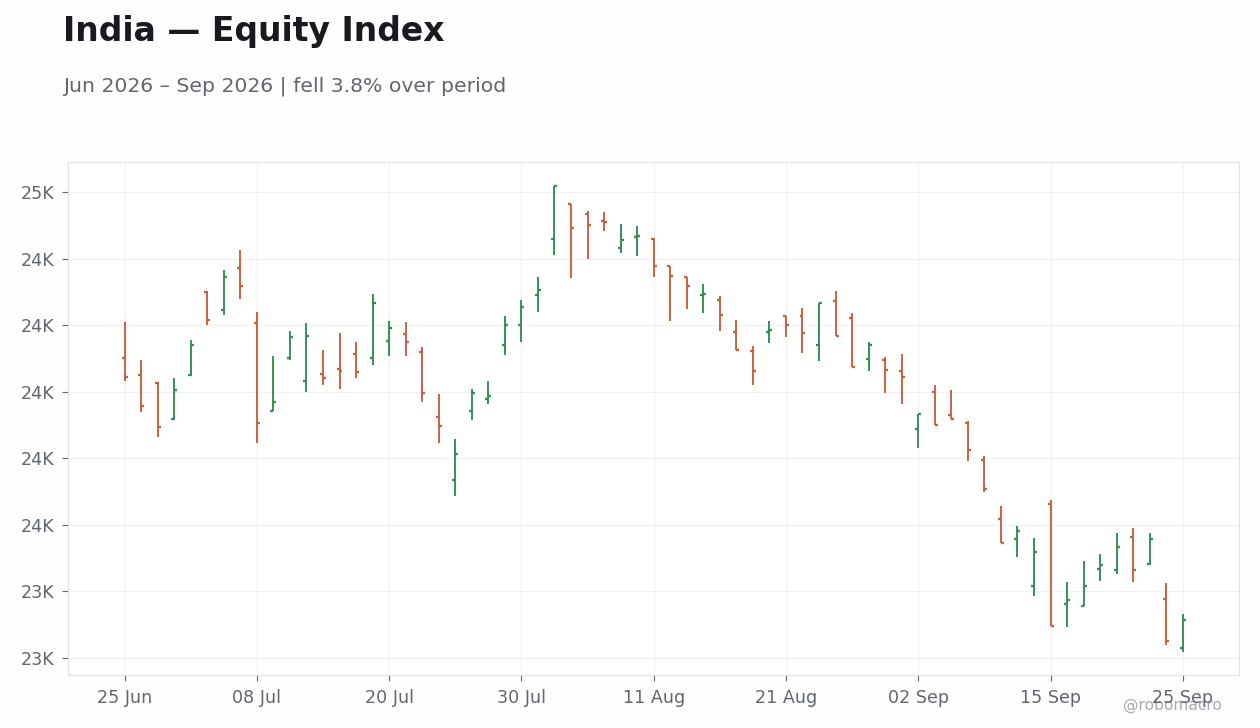
The S&P 500 rose 1.2% to 7,743. The index closed at 7,765 on both Monday and Tuesday before falling to 7,706 on Wednesday and 7,704 on Thursday, then rebounding on Friday. The Nasdaq 100 climbed 3.2% to 30,608 while the Dow Jones gained 0.3% to 51,829 and the Russell 2000 fell 0.8% to 2,838. In Europe the Euro Stoxx 50 rose 1.1% to 6,303, the FTSE 100 gained 0.3% to 10,695, the DAX added 0.4% to 25,409, the CAC 40 rose 0.2% to 8,078 and the FTSE MIB advanced 0.6% to 51,867. Asian equities were led by the Nikkei 225 which rose 2.1% to 66,364 after closing at 63,923 mid-week before climbing steadily. Emerging markets diverged with the KOSPI surging 5.4% to 7,081, the IPC Mexico up 2.5% to 64,992, while the Hang Seng fell 1.0% to 24,510, the Nifty 50 declined 0.9% to 23,140, the Ibovespa dropped 0.9% to 183,477 and the JSE Top 40 fell 2.0% to 103,152.
Regional Divergences
The Nasdaq 100's 3.2% WoW gain significantly outpaced the Dow Jones 0.3% and Russell 2000 negative 0.8% move, underscoring US large-cap resilience amid manufacturing PMI strength and data-dependent policy signals. European benchmarks showed narrower dispersion with the Euro Stoxx 50 up 1.1%, the DAX up 0.4% and the CAC 40 up 0.2%, consistent with PMI beats and business climate improvement that lifted the region to its first weekly gain in several weeks. Asian performance diverged sharply as the Nikkei 225 rose 2.1% and the KOSPI surged 5.4% while the Hang Seng fell 1.0%, the Nifty 50 declined 0.9% and the S&P/ASX 200 fell 0.8%. Emerging markets reflected local policy and data variation with the IPC Mexico up 2.5% contrasting losses in the Ibovespa, JSE Top 40 and Nifty 50. These splits aligned with country-specific catalysts including resilient US activity, European expansion signals and mixed EM responses to domestic growth forecasts and rate paths.
Volatility & Risk Appetite
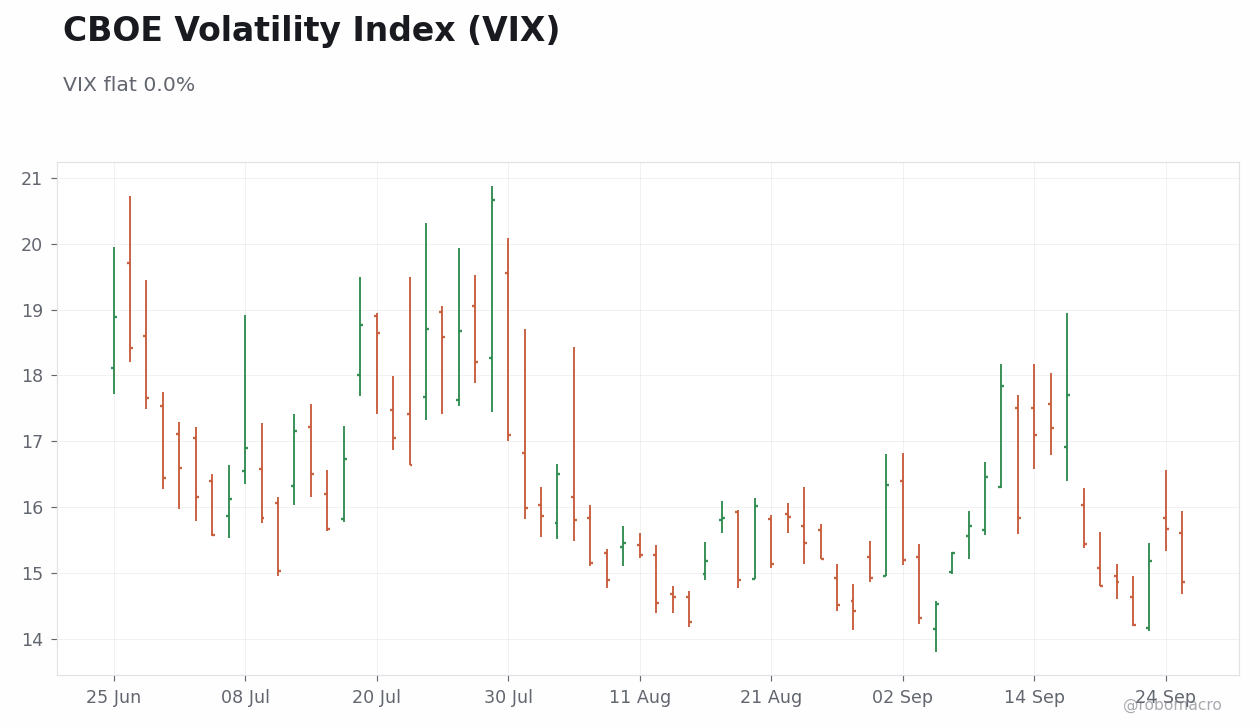
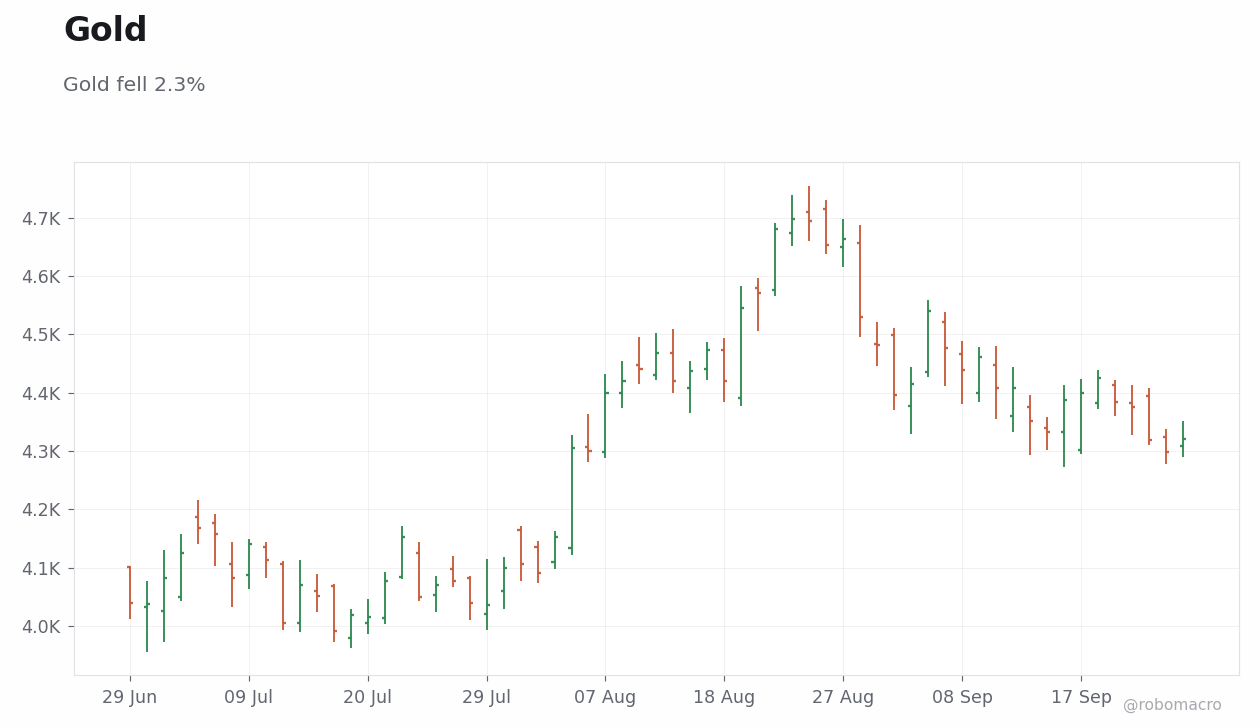
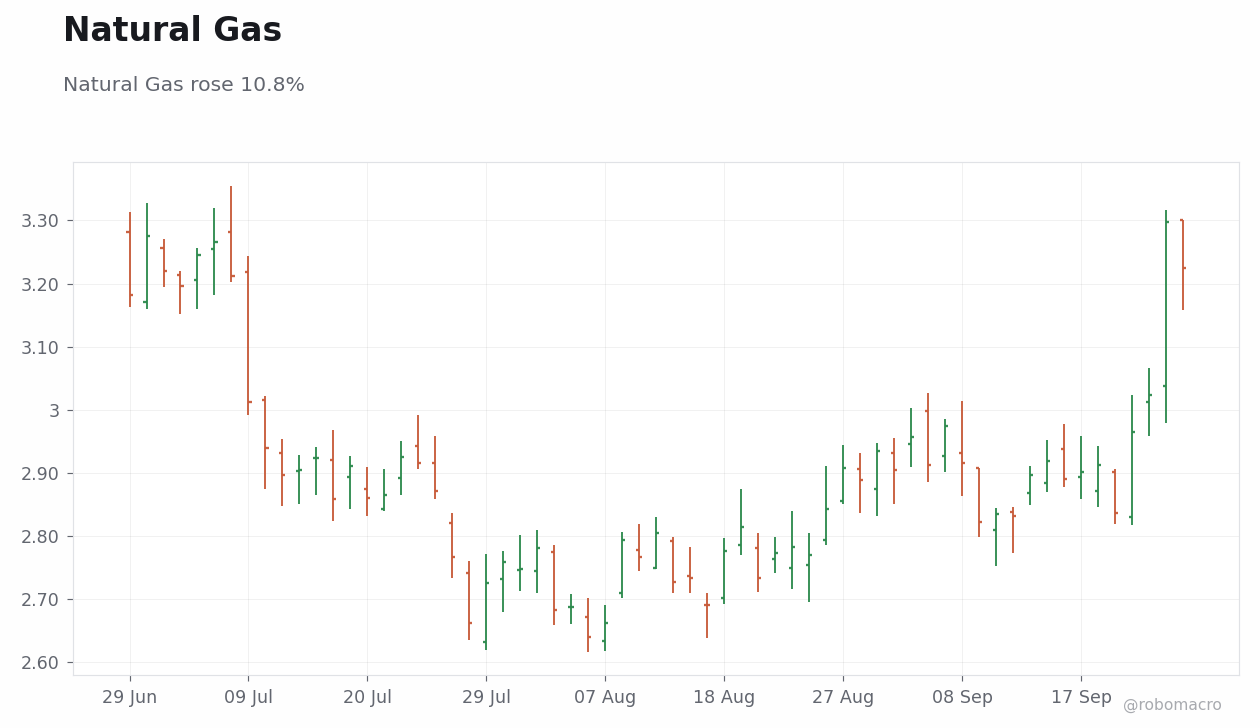
The VIX closed at 14.9 on Friday after reaching 15.7 on Thursday. Growth clearly outperformed value with the Nasdaq 100 rising 3.2% versus the Dow Jones 0.3% weekly gain. Small caps lagged large caps as the Russell 2000 fell 0.8% against the S&P 500's 1.2% advance. Commodity moves delivered mixed sector signals with WTI Crude falling 7.9%, Brent Crude falling 6.2% and gold declining 2.3%, suggesting relief in energy-sensitive areas, while copper rose 2.3% and natural gas rose 10.8%, pointing to selective industrials and materials optimism amid the week's risk appetite profile.
Week Ahead
The economic calendar next week is light with no major CPI, payrolls or GDP prints scheduled. Earnings reports from key sectors will continue and several PMI releases are due across major economies. These events pose the biggest risk to equity markets if they deliver surprises relative to current resilient manufacturing and services trends, with hot data potentially tilting toward risk-off given prevailing data-dependent central bank stances. A benign earnings backdrop would instead favor risk-on continuation.
| Index | Level | WoW | MTD | YTD |
|---|---|---|---|---|
| S&P 500 | 7,743 | +1.2% | +1.5% | +12.9% |
| Nasdaq 100 | 30,608 | +3.2% | +5.3% | +21.4% |
| Dow Jones | 51,829 | +0.3% | -1.8% | +7.1% |
| Russell 2000 | 2,838 | -0.8% | -2.8% | +13.1% |
| S&P/TSX | 35,801 | -0.0% | -0.1% | +12.3% |
| FTSE 100 | 10,695 | +0.3% | -0.9% | +7.5% |
| Euro Stoxx 50 | 6,303 | +1.1% | -1.0% | +6.4% |
| DAX | 25,409 | +0.4% | -2.2% | +3.5% |
| CAC 40 | 8,078 | +0.2% | -2.7% | -1.4% |
| FTSE MIB | 51,867 | +0.6% | -0.1% | +14.3% |
| IBEX 35 | 19,700 | +0.9% | -0.6% | +12.6% |
| Nikkei 225 | 66,364 | +2.1% | +0.2% | +28.0% |
| Hang Seng | 24,510 | -1.0% | -3.2% | -6.9% |
| S&P/ASX 200 | 8,665 | -0.8% | -4.4% | -0.7% |
| KOSPI | 7,081 | +5.4% | +3.6% | +64.3% |
| Nifty 50 | 23,140 | -0.9% | -3.8% | -11.5% |
| Ibovespa | 183,477 | -0.9% | +2.1% | +14.3% |
| IPC Mexico | 64,992 | +2.5% | +0.7% | +1.3% |
| JSE Top 40 | 103,152 | -2.0% | -4.8% | -4.7% |
US equities advanced unevenly, led by the Nasdaq 100’s 3.2% gain to 30,608 while the Russell 2000 fell 0.8%. The S&P 500 rose 1.2% to 7,743 as the Dow Jones added just 0.3%. In Asia, the KOSPI jumped 5.4%, outpacing the Nikkei 225’s 2.1% rise to 66,364, whereas the Hang Seng slipped 1.0%. European indices posted modest gains, with the Euro Stoxx 50 up 1.1% and the FTSE MIB adding 0.6%. Latin America diverged as the IPC Mexico climbed 2.5% against the Ibovespa’s 0.9% decline. The JSE Top 40 led declines, falling 2.0%. Emerging-market underperformance was clearest in the Nifty 50 and S&P/ASX 200, both down 0.9% and 0.8%. Next week, attention turns to US and European inflation prints and any shifts in central-bank rhetoric.
| Index | WoW | MTD | YTD |
|---|---|---|---|
| S&P 500 | +1.2% | +1.5% | +12.9% |
| Nasdaq 100 | +3.2% | +5.3% | +21.4% |
| Dow Jones | +0.3% | -1.8% | +7.1% |
| Russell 2000 | -0.8% | -2.8% | +13.1% |
| S&P/TSX | -0.0% | -0.1% | +12.3% |
| FTSE 100 | +0.3% | -0.9% | +7.5% |
| Euro Stoxx 50 | +1.1% | -1.0% | +6.4% |
| DAX | +0.4% | -2.2% | +3.5% |
| CAC 40 | +0.2% | -2.7% | -1.4% |
| FTSE MIB | +0.6% | -0.1% | +14.3% |
| IBEX 35 | +0.9% | -0.6% | +12.6% |
| Nikkei 225 | +2.1% | +0.2% | +28.0% |
| Hang Seng | -1.0% | -3.2% | -6.9% |
| S&P/ASX 200 | -0.8% | -4.4% | -0.7% |
| KOSPI | +5.4% | +3.6% | +64.3% |
| Nifty 50 | -0.9% | -3.8% | -11.5% |
| Ibovespa | -0.9% | +2.1% | +14.3% |
| IPC Mexico | +2.5% | +0.7% | +1.3% |
| JSE Top 40 | -2.0% | -4.8% | -4.7% |


Week in Review
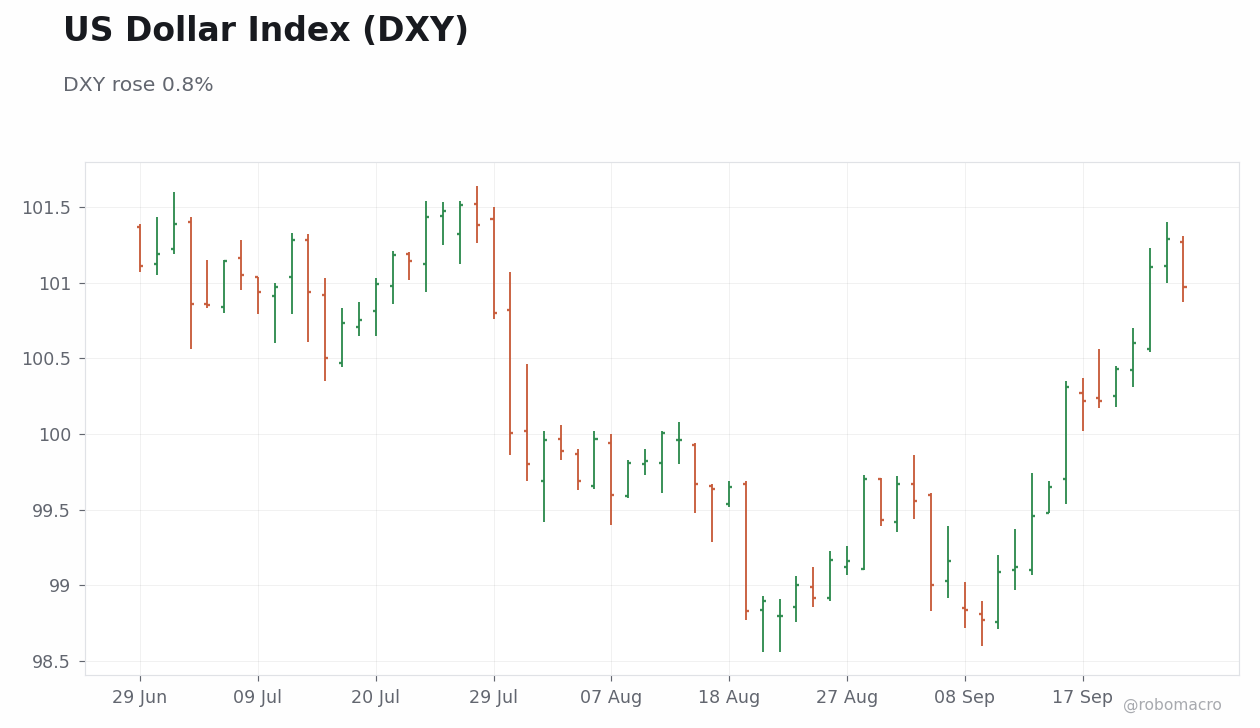
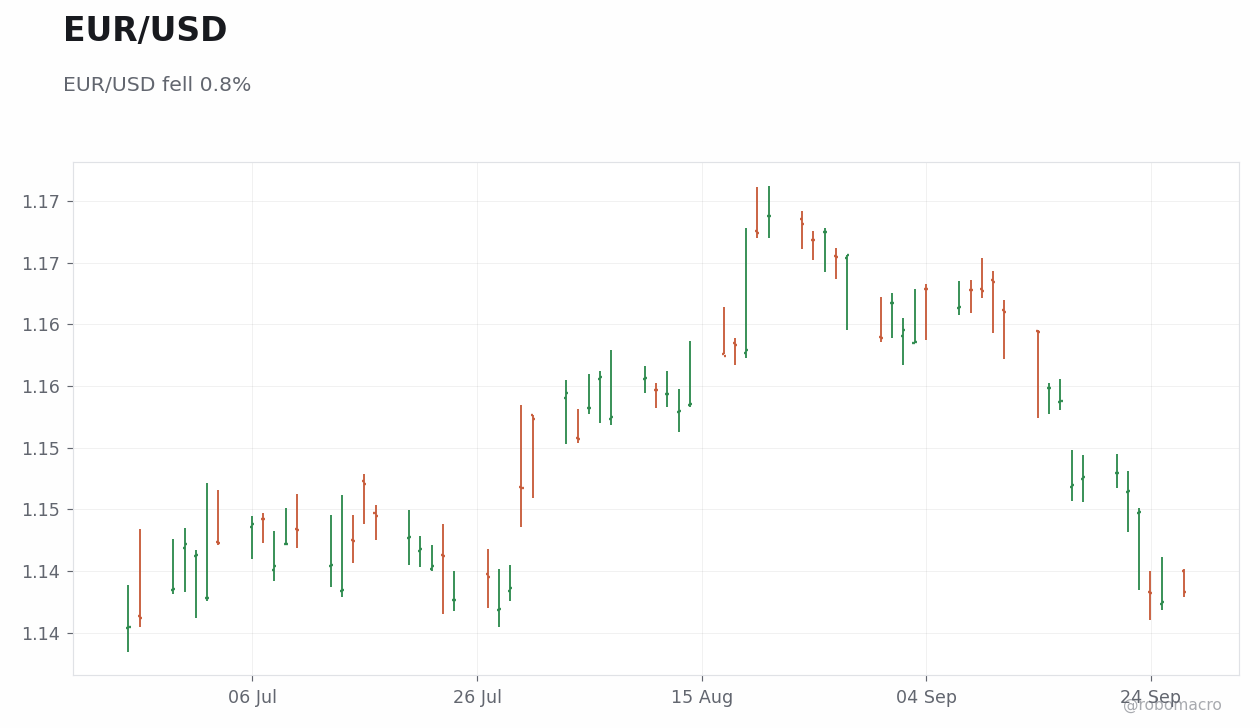
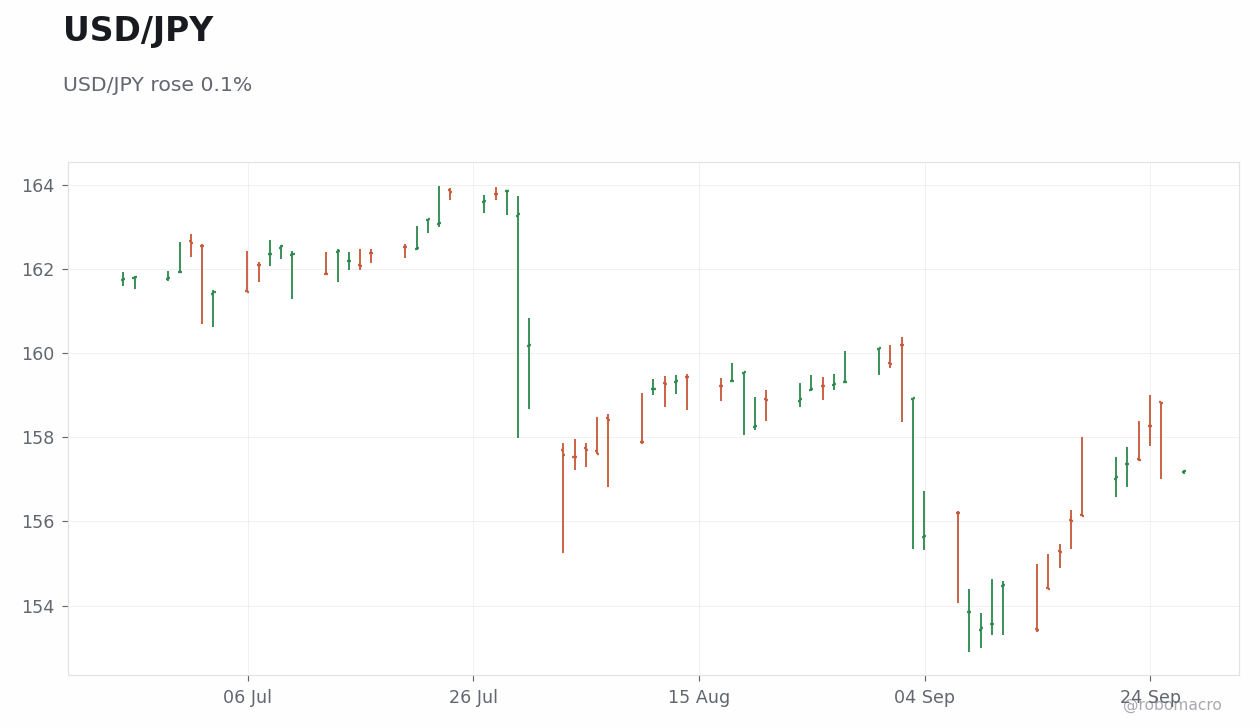
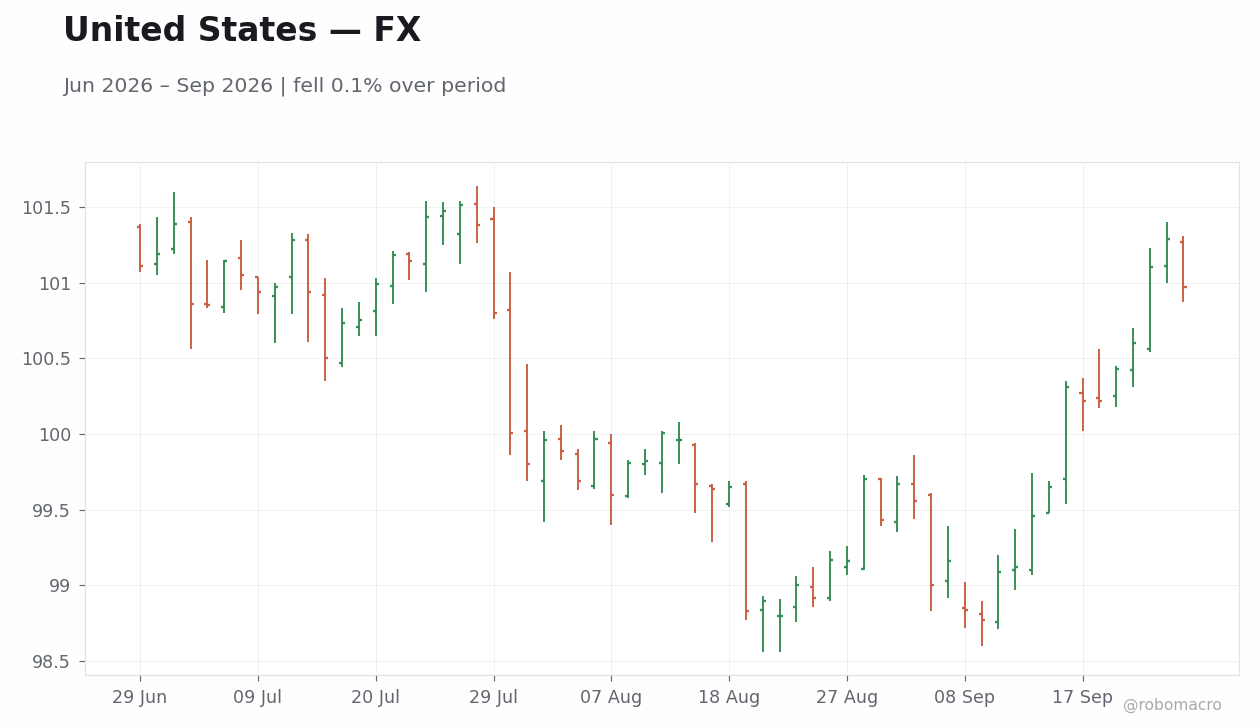
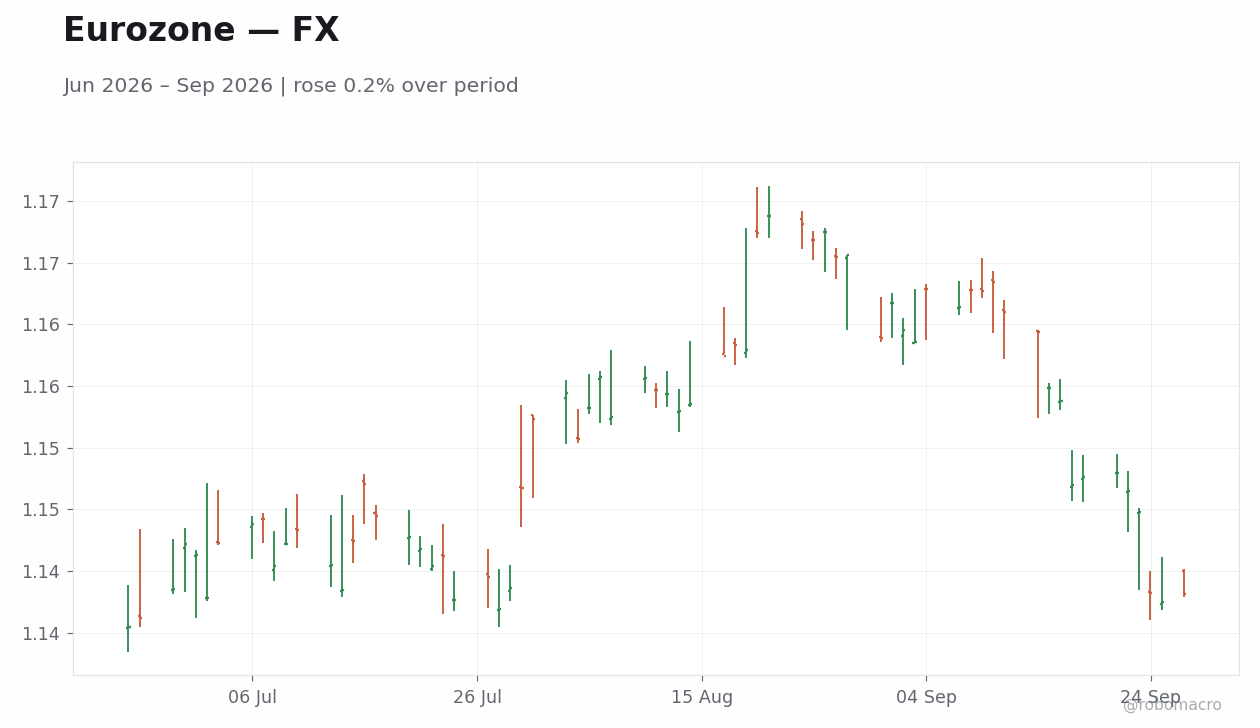
The DXY rose 0.8% on the week to 100.97, holding steady at 101 in daily closes from Tuesday to Friday. In G10 currencies, EUR/USD dropped 0.8% to 1.1383 after falling from 1.1480 on Monday through to 1.1375 on Friday, while GBP/USD declined 1.2% to 1.3233 from 1.3389 to 1.3211. USD/JPY was virtually unchanged, gaining just 0.1% to 157.20 even as it rose to 159 by Friday's close from earlier levels of 157. EM FX saw USD/MXN jump 2.9% to 17.73, USD/BRL rise 0.8% to 5.1842, USD/ZAR increase 0.2% to 16.27, USD/TRY advance 0.4% to 48.96, and USD/CNY up 0.2% to 6.7123.
Dollar & G10
Diverging bond market moves helped drive DXY higher as rate differentials widened, reinforced by hawkish signals from Federal Reserve officials emphasizing data dependence and persistent inflation. EUR/USD ended at 1.1383 after posting a 0.8% weekly loss. GBP/USD fell 1.2% to 1.3233, remaining near three-month lows after the dollar rally. USD/JPY closed at 157.20 with a 0.1% weekly gain as the yen rallied on the back of cooling oil prices.
EM FX
EM FX was predominantly softer versus the dollar amid shifting commodity prices and local bond dynamics. USD/MXN surged 2.9% to 17.73 following the Banco de Mexico policy rate hold. USD/BRL gained 0.8% to 5.1842 as Brazil lowered its 2026 GDP growth forecast. USD/ZAR rose 0.2% to 16.27, USD/TRY climbed 0.4% to 48.96, and USD/CNY ticked 0.2% higher to 6.7123.
Bitcoin & Crypto
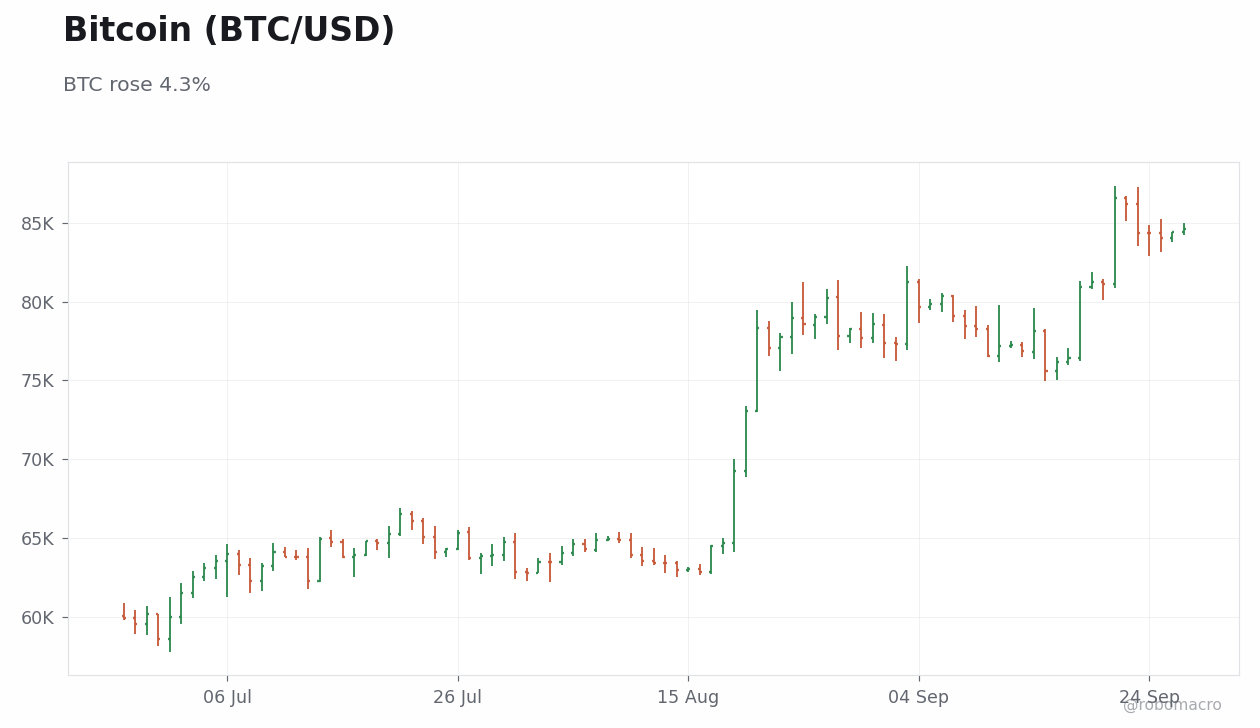
Bitcoin advanced 4.3% to $84,614, experiencing an intra-week pullback from 84,383 on Wednesday and 84,035 on Friday before recovering to 84,406 on Saturday. Ethereum increased 1.7% to $2,688. Solana posted strong gains of 10.6% to $123 and XRP rose 8.0% to $2, highlighting selective strength in the crypto space. Digital assets benefited from risk-on sentiment even as news emerged regarding exchange security challenges.
Week Ahead
With no major central bank rate decisions or key CPI and payrolls data on the calendar next week, markets will continue to focus on incoming economic prints to shape rate expectations. Trade balance releases in select EM countries could influence FX positioning. Crypto markets will watch for any regulatory updates, though the period appears quiet on protocol upgrades. Overall, the data-dependent stances reiterated by policymakers are set to remain the dominant theme.


Week in Review
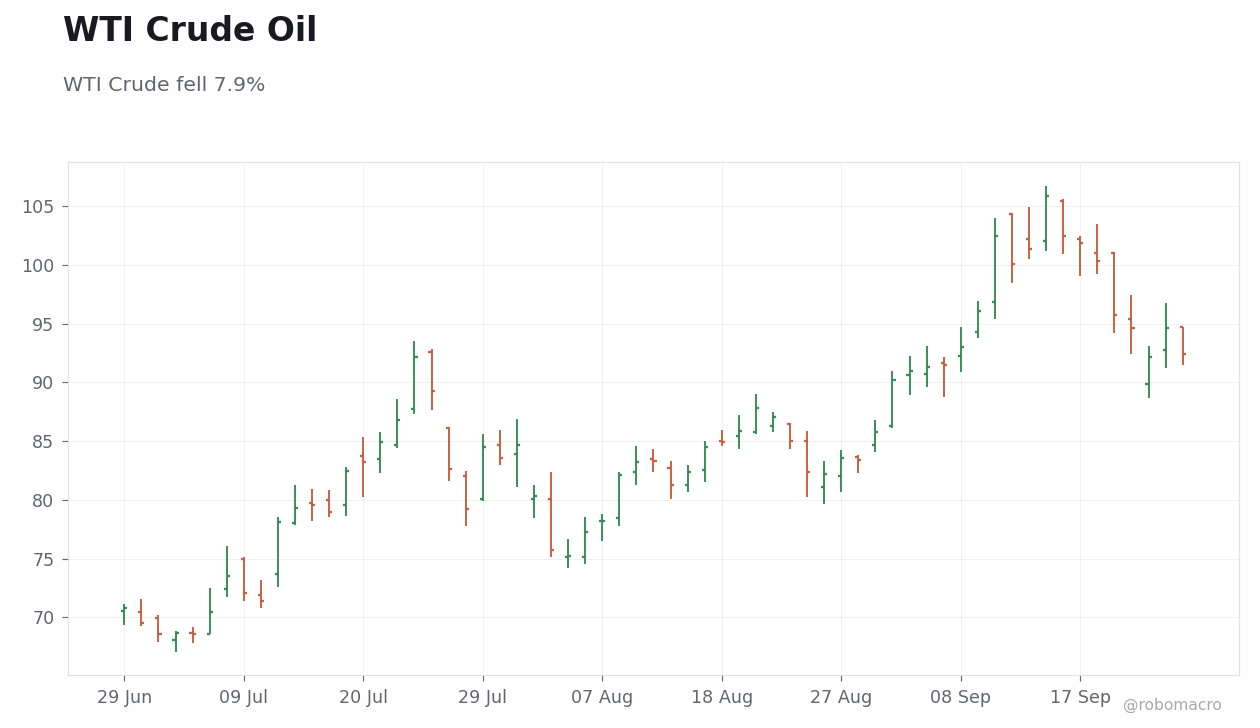
Natural Gas led commodity performance with a +10.8% weekly gain to 3.23. WTI Crude fell 7.9% to 92.41 while Brent Crude declined 6.2% to 97.44, together weighing on the broader energy complex. Daily closes showed WTI Crude moving from 94.6 on Tuesday to 92.2 on Wednesday, rebounding to 94.6 on Thursday before settling at 92.4 on Friday. In metals, Gold retreated 2.3% to 4321.20 and Silver fell 2.6% to 64.80, while Copper rose 2.3% to 6.77, offering a positive growth signal. Wheat declined 1.5% to 703.25 amid softer agricultural prices that saw an 8.0% drop on the month. Overall, the week featured divergent moves across energy, metals, and agriculture against a backdrop of cooling oil prices on geopolitical hopes.
Energy Complex
WTI Crude settled the week at 92.41 after a 7.9% decline while Brent Crude closed at 97.44, down 6.2%. Natural Gas surged 10.8% to 3.23, climbing from 2.9650 on Tuesday through 3.2970 on Thursday before closing at 3.2250 on Friday. The energy retreat aligned with market narratives of progress toward reopening the Strait of Hormuz, easing near-term supply disruption fears. This pullback in oil occurred even as select central banks maintained data-dependent stances that kept broader financial conditions firm. The divergent weekly paths left the complex balancing geopolitical relief against underlying demand resilience.
Metals & Ags
Gold closed at 4321.20 after a 2.3% weekly decline, sliding from 4,376 on Tuesday to 4,321 on Friday, while Silver ended at 64.80 following a 2.6% drop. The gold-silver ratio edged higher as both precious metals posted losses. Copper gained 2.3% to 6.77, reinforcing a constructive signal for global industrial activity amid broader equity resilience in several regions. Wheat fell 1.5% to 703.25, contributing to an 8.0% monthly decline that highlighted softer agricultural momentum. These moves left metals and agriculture reflecting mixed growth and inflation expectations without clear directional conviction.
Week Ahead
The economic calendar for next week contains no commodity-relevant events, with no EIA crude or gas inventories, OPEC meetings, China PMI or industrial data, US CPI releases, or central bank meetings affecting commodity currencies such as CAD, AUD, or BRL explicitly scheduled. Market attention will therefore shift to non-calendar risks including geopolitical developments around energy chokepoints, potential OPEC diplomacy, and weather patterns that could influence natural gas demand and agricultural yields. Any escalation or de-escalation tied to the Strait of Hormuz narrative could quickly reshape oil sentiment. Participants will also monitor USD moves for indirect effects on dollar-denominated commodity pricing.
| Pair | Level | WoW | MTD | YTD |
|---|---|---|---|---|
| DXY | 100.97 | +0.8% | +1.3% | +2.6% |
| EUR/USD | 1.1383 | -0.8% | -2.0% | -3.1% |
| GBP/USD | 1.3233 | -1.2% | -2.3% | -1.8% |
| USD/JPY | 157.20 | +0.1% | -1.6% | +0.3% |
| AUD/USD | 0.7014 | -1.5% | -2.2% | +5.0% |
| NZD/USD | 0.5660 | -1.1% | -4.4% | -1.7% |
| USD/CAD | 1.4139 | +1.0% | +2.1% | +3.1% |
| USD/CHF | 0.8275 | +0.6% | +2.4% | +4.5% |
| USD/CNY | 6.7123 | +0.2% | -0.2% | -4.1% |
| USD/BRL | 5.1842 | +0.8% | +0.1% | -6.0% |
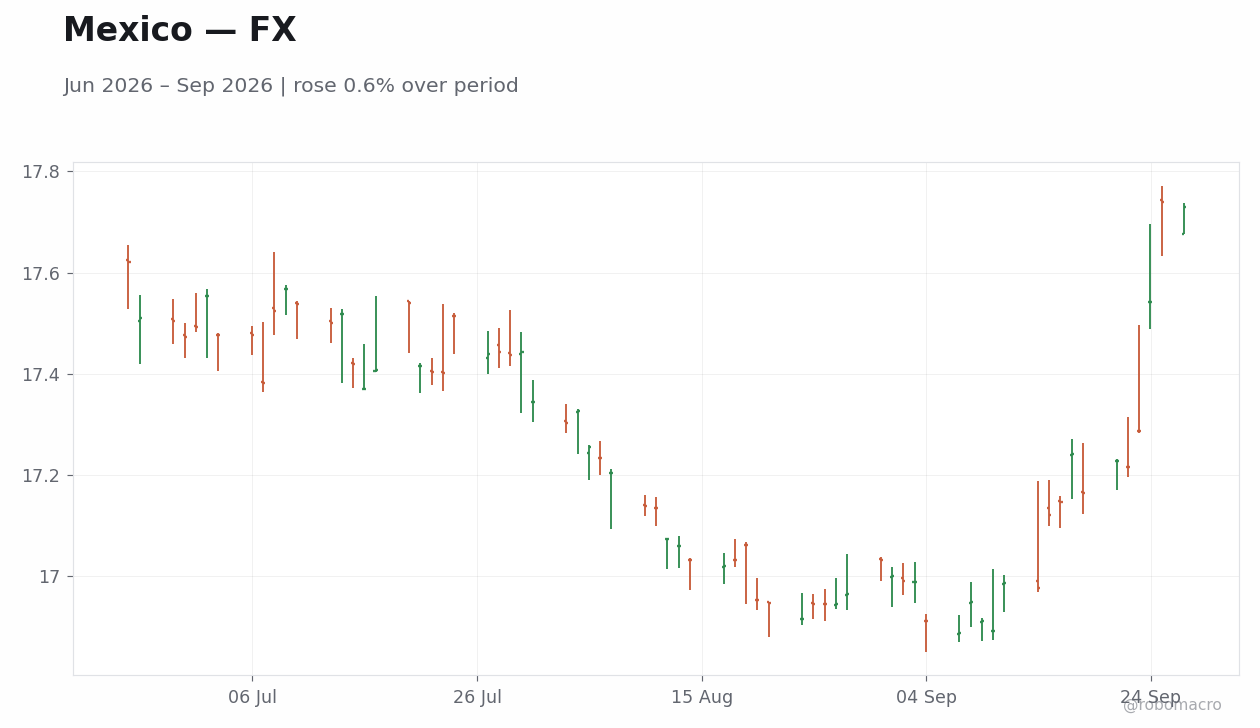
| USD/MXN | 17.73 | +2.9% | +4.3% | -1.4% |
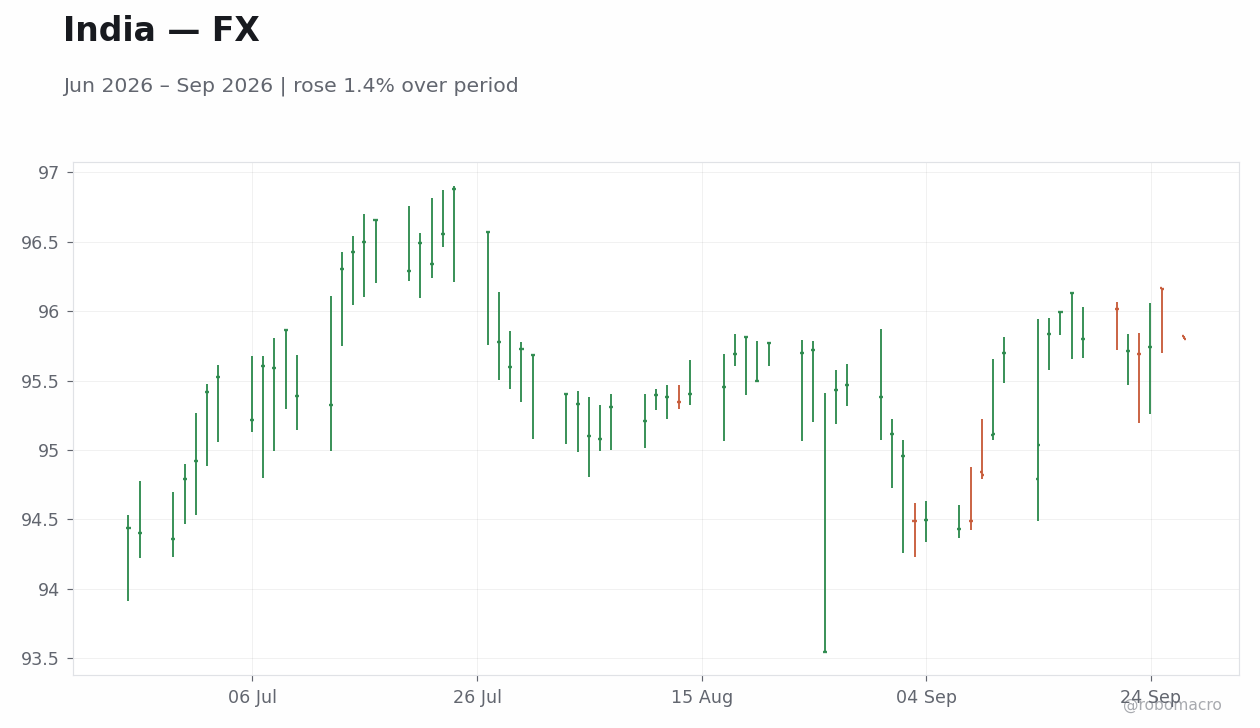
| USD/INR | 95.80 | -0.2% | +0.7% | +6.5% |
| USD/ZAR | 16.27 | +0.2% | +1.1% | -1.7% |
| USD/TRY | 48.96 | +0.4% | +1.4% | +13.9% |
| Commodity | Level | WoW | MTD | YTD |
|---|---|---|---|---|
| WTI Crude | 92.41 | -7.9% | +2.4% | +61.2% |
| Brent Crude | 97.44 | -6.2% | +3.0% | +60.4% |
| Gold | 4321.20 | -2.3% | -1.7% | -0.2% |
| Silver | 64.80 | -2.6% | +0.3% | -8.2% |
| Copper | 6.77 | +2.3% | +4.0% | +20.0% |
| Natural Gas | 3.23 | +10.8% | +11.1% | -10.9% |
| Wheat | 703.25 | -1.5% | -8.0% | +38.9% |
| Iron Ore | 97.06 | -0.5% | -2.3% | -9.4% |
| Asset | Level | WoW | MTD | YTD |
|---|---|---|---|---|
| Bitcoin | $84,614 | +4.3% | +9.3% | -4.6% |
| Ethereum | $2,688 | +1.7% | +11.2% | -10.4% |
| Solana | $123 | +10.6% | +22.9% | -3.1% |
| XRP | $2 | +8.0% | +12.6% | -18.9% |
The DXY index rose 0.8% to 100.97. USD/MXN led gains with a 2.9% advance to 17.73, outpacing USD/CAD’s 1.0% increase to 1.4139. AUD/USD posted the steepest decline, falling 1.5% to 0.7014, followed by GBP/USD’s 1.2% drop to 1.3233. EUR/USD eased 0.8% to 1.1383 while NZD/USD slipped 1.1% to 0.5660. USD/JPY remained nearly unchanged at 157.20, contrasting with USD/INR’s modest 0.2% decline to 95.80. EM currencies showed clear divergence as USD/MXN outperformed USD/ZAR, which rose just 0.2% to 16.27. USD/TRY added 0.4% to 48.96. Markets will monitor MTD trends into the following week.
| Asset | Level | WoW |
|---|---|---|
| S&P 500 | 7743.41 | -0.3% |
| Nasdaq 100 | 30608.13 | +0.4% |
| Dow Jones | 51828.62 | -0.4% |
| Russell 2000 | 2837.55 | -1.3% |
| USD/JPY | 157.2 | +0.1% |
| EUR/USD | 1.14 | -0.9% |
| GBP/USD | 1.32 | -1.1% |
| Gold | 4321.2 | -1.4% |
| WTI Crude | 92.41 | -3.5% |
| Bitcoin | 84523.8 | +4.2% |


Activity data surprised to the upside. Manufacturing and services PMI prints exceeded expectations and extended the pattern of selective resilience observed in recent weeks as energy prices retreated. The Chicago Fed National Activity Index slipped while the ADP Employment Change rose, keeping labor-market signals mixed rather than uniformly soft.
Yields repriced higher on policy communication. The 10-year Treasury yield advanced from the Monday close while the 2-year yield ended higher after moving lower earlier in the week. Speeches by Fed’s Williams, Jefferson, Barkin, and Barr reinforced the data-dependent stance without introducing dovish language, consistent with the approach taken by the Bank of England and ECB in recent weeks.
Equities showed narrow leadership. The Nasdaq 100 gained 0.41 percent to 30,608.13 over the week while the Russell 2000 fell 1.31 percent to 2,837.55. WTI crude dropped 3.52 percent to 92.41, providing further relief to imported inflation risks. USD/JPY held near 157.20 with a modest 0.10 percent weekly gain, maintaining the currency strength noted across recent reports.
Cross-border spillovers remained contained. EUR/USD declined 0.86 percent to 1.14 and GBP/USD fell 1.13 percent to 1.32, reflecting the yield differential that widened after the Fed speakers. Gold declined 1.43 percent to 4,321.20, tracking the broader commodity price softening that has eased pressure on net-energy importers. The configuration leaves the US expansion in its mid-phase, where stronger PMI readings coexist with higher yields and a data-dependent Federal Reserve.
Federal Reserve speakers dominated the week with no policy decision scheduled. Chicago Fed President Goolsbee spoke, followed by New York Fed President Williams, Vice Chair Jefferson, and Richmond Fed President Barkin. Governor Barr also spoke. The officials reiterated the data-dependent framework without providing fresh forward guidance on the policy rate path.
The stronger-than-expected PMI prints and steady ADP employment reading reinforced the case for patience at the Federal Reserve. Yields rose in response to the cumulative hawkish tone, with the 10-year yield reaching higher levels. This repricing aligns with the pattern observed after the Bank of England’s split vote and the ECB’s continued emphasis on incoming data in prior weeks. The medium-term rate path remains tethered to subsequent activity and inflation releases rather than any single week’s communication. No explicit references to near-term easing appeared in the public remarks.
Manufacturing and services PMI prints beat consensus by a wide margin and exceeded prior readings, pointing to faster expansion than markets had priced. The Composite PMI also rose. These readings suggest the growth outlook remains supported even as energy prices have cooled from recent peaks.
The Chicago Fed National Activity Index missed the prior reading, yet the ADP Employment Change exceeded the prior print, indicating labor demand held steady rather than deteriorated. MBA 30-Year Mortgage Rate rose, reflecting the parallel move higher in Treasury yields. EIA and API crude inventory prints showed builds, contributing to the 3.52 percent weekly decline in WTI to 92.41.
Taken together, the data releases reinforce a cycle position where growth momentum persists above stall speed while inflation risks from energy have moderated. The combination supports the Federal Reserve’s continued data-dependent approach to the policy rate without immediate pressure for recalibration. Revisions in the PMI series were positive, contrasting with the modest downside surprise in the Chicago Fed index and aligning with the resilience theme that has dominated recent weekly reports.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Mon 21 | US | Fed Goolsbee Speech | - | - | - |
| Mon 21 | US | Chicago Fed National Activ | 0.08 | - | -0.04 |
| Mon 21 | US | 3-Month Treasury Bill Auct | 4.0 | - | 4.0 |
| Mon 21 | US | 6-Month Treasury Bill Auct | 4.1 | - | 4.2 |
| Mon 21 | US | Un General Assembly | - | - | "" |
| Tue 22 | US | ADP Employment Change Week | 16K | - | 20K |
| Tue 22 | US | Redbook Retail Sales Year- | 8.5 | - | 7.6 |
| Tue 22 | US | Richmond Fed Manufacturing | 4.0 | 5.0 | -2.0 |
| Tue 22 | US | Richmond Fed Manufacturing | 11.0 | - | -5.0 |
| Tue 22 | US | Richmond Fed Services Reve | -8.0 | - | 0 |
| Tue 22 | US | Speech by Fed's Williams | - | - | - |
| Tue 22 | US | Speech by Fed's Jefferson | - | - | - |
| Tue 22 | US | 6-Week Bill Auction | 3.9 | - | 3.9 |
| Tue 22 | US | Speech by Fed's Barkin | - | - | - |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-28 | Dallas Fed Manufacturing Index | 11.6 | - |
| 2026-09-28 | Speech by Fed's Barkin | - | - |
| 2026-09-29 | S&P/Case-Shiller Home Price Year-ov | 2.1 | 2.2 |
| 2026-09-29 | JOLTs Job Openings | 7.3mn | 7.2mn |
| 2026-09-29 | Cb Consumer Confidence | 89.4 | - |
| 2026-09-29 | Fed Goolsbee Speech | - | - |
| 2026-09-29 | Speech by Fed's Musalem | - | - |
| 2026-09-29 | Speech by Fed's Williams | - | - |
| 2026-09-29 | API Weekly Crude Oil Stocks | 1.8mn | - |
| 2026-09-30 | MBA 30-Year Mortgage Rate | 7.1 | - |


The calendar for the coming week features limited high-impact US releases. Markets will monitor any additional Federal Reserve speakers for incremental shifts in tone following the recent hawkish tilt. Treasury auctions and corporate earnings will provide secondary market drivers in the absence of fresh CPI or employment data.
Attention will turn to early prints that could influence the next policy assessment, including any revisions to prior PMI or labor figures. The S&P Global and ISM manufacturing and services surveys will be watched for confirmation of recent flash readings. Oil inventory data will continue to influence WTI crude, which closed at 92.41 after a 3.52 percent weekly decline. Cross-border developments in Europe and Asia will be monitored for any spillover effects on USD crosses that ended the week at 157.20 for USD/JPY. Positioning ahead of month-end flows may amplify moves in equities and yields.
The week’s data shift the outlook toward sustained growth resilience, reducing the probability of an abrupt softening signal in the near term. Upside risks center on further PMI strength that could keep the Federal Reserve on hold longer than some market participants anticipate. Downside risks include any reversal in the energy price decline that has eased imported inflation recently.
Market positioning appears extended in the direction of higher yields after the advance in the 10-year Treasury. Volatility remains contained, with Bitcoin showing the largest weekly gain at 4.17 percent while equities posted modest net changes. Flow considerations favor selective equity leadership in technology-related names, as evidenced by the Nasdaq 100 outperformance. The configuration leaves limited room for surprise dovish repricing unless subsequent data materially disappoint relative to recent manufacturing prints.
The S&P 500 closed the week at 7,743.41 for a net 0.27 percent decline while the Nasdaq 100 rose 0.41 percent to 30,608.13 and the Dow Jones fell 0.42 percent to 51,828.62. The Russell 2000 posted the weakest performance with a 1.31 percent drop to 2,837.55. Treasury yields moved higher across the curve, with the 10-year yield ending higher after a weekly advance from the prior close and the 2-year yield finishing higher.
In FX, USD/JPY rose 0.10 percent to 157.20 while EUR/USD declined 0.86 percent to 1.14 and GBP/USD fell 1.13 percent to 1.32, consistent with the yield differential widening after Fed speeches. WTI crude fell 3.52 percent to 92.41 and gold declined 1.43 percent to 4,321.20. Bitcoin advanced 4.17 percent to 84,523.80. Energy price weakness provided a tailwind for growth-sensitive assets while higher yields capped broader equity gains.
Energy price declines continued to ease imported inflation risks for net importers, with WTI falling 3.52 percent to 92.41 after Brent’s decline the prior week. USD strength against EUR and GBP mirrored the pattern seen in other Asian currencies recently. Geopolitical developments contributed to the oil price retreat, providing a modest positive spillover for US inflation dynamics.
Trade and investment flows showed continuity, with no major new tariff announcements altering the external backdrop that has supported US GDP growth. The configuration reinforces the data-dependent equilibrium across major central banks without introducing fresh cross-border shocks in the last seven days.
| Asset | Level | WoW |
|---|---|---|
| Euro Stoxx 50 | 6302.82 | -0.2% |
| DAX | 25408.64 | -0.7% |
| CAC 40 | 8077.8 | -0.8% |
| EUR/USD | 1.14 | -0.9% |
| EUR/GBP | 0.86 | +0.2% |
| EUR/JPY | 178.88 | -0.8% |
| Gold | 4321.2 | -1.4% |
| Brent Crude | 97.44 | -2.9% |
| Bitcoin | 84523.8 | +4.2% |


Services momentum offsets manufacturing drag. Eurozone private-sector activity accelerated as the German composite PMI reached a multi-month high, beating consensus. French services PMI flash exceeded expectations while German services PMI also advanced. These gains occurred even as German manufacturing PMI eased modestly and French manufacturing slipped.
Fiscal and political noise weighs on sentiment. Chancellor Merz described CDU regional election losses as a setback, coinciding with Scope’s downgrade of French debt. German 2-year Bund yields rose intraday before easing later in the week. French business confidence missed expectations while GfK consumer confidence deteriorated.
Energy retreat supports the inflation backdrop. Brent crude declined, extending the prior week’s drop and reducing near-term imported price pressure for the euro area. The Netherlands consumer confidence index improved and Spain’s trade balance narrowed. Equity markets closed mixed, with the Euro Stoxx 50 ending the week down modestly while the DAX fell.
Data dependence remains the dominant policy theme. No ECB speakers appeared and the deposit rate stayed unchanged. Markets absorbed the services-led growth signal without repricing near-term easing odds. The week therefore reinforced a mid-cycle expansion in which activity divergence and fiscal spreads coexist with cooling commodity prices.
No ECB Governing Council members spoke during the week and the deposit rate remained unchanged. The latest services PMI beats reinforce the view that underlying growth momentum is firmer than the soft manufacturing prints alone would suggest. We therefore continue to expect the ECB to remain on hold until incoming data show a clearer and sustained moderation in both activity and core inflation.
Bundesbank commentary highlighted that inflation is likely to stay elevated while growth has slowed, citing the Iran conflict and low water levels as temporary drags. The absence of fresh forward guidance leaves the medium-term rate path anchored to the next round of inflation and activity releases. Markets correctly interpreted the data as consistent with the current policy stance rather than an imminent shift.
The German Ifo Business Climate index rose, beating consensus and pointing to improving business sentiment after three consecutive soft prints. German composite PMI flash surged, driven by the services component. German manufacturing PMI eased only modestly, remaining above consensus.
French services PMI flash exceeded expectations while the French composite also beat forecasts. French manufacturing PMI came in below consensus. France business confidence held steady, missing the forecast, and consumer confidence matched the prior reading while beating consensus.
Spain’s trade balance improved and the Netherlands consumer confidence index rose. These releases collectively signal that services-led growth is offsetting manufacturing softness and fiscal concerns, supporting a steady rather than accelerating inflation path and leaving the ECB’s data-dependent stance intact.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Mon 21 | DE | 11-Month Bubill Auction | 2.6 | - | 3.0 |
| Mon 21 | DE | 5-Month Bubill Auction | 2.5 | - | 2.7 |
| Mon 21 | FR | 12-Month BTF Auction | 3.2 | - | 3.2 |
| Mon 21 | FR | 3-Month BTF Auction | 2.7 | - | 2.6 |
| Mon 21 | FR | 6-Month BTF Auction | 2.9 | - | 2.9 |
| Mon 21 | NL | 3-Month Treasury Bill Auct | 2.5 | - | 2.7 |
| Mon 21 | NL | 6-Month Treasury Bill Auct | 2.6 | - | 2.7 |
| Tue 22 | NL | Consumer Confidence Index | -34.0 | - | -33.0 |
| Tue 22 | FI | Headline Unemployment Rate | 9.9 | - | 9.1 |
| Tue 22 | ES | Trade Balance | -7.7bn | - | -5.2bn |
| Tue 22 | AT | Atb 2027-03-25 (G) Auction | - | - | 2.8 |
| Tue 22 | BE | Consumer Confidence Index | -7.0 | - | -10.0 |
| Tue 22 | DE | 5-Year Bobl Auction | 3.1 | - | 3.3 |
| Tue 22 | IE | Wholesale Prices Month-ove | 3.2 | - | -0.80 |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-29 | Inflation Rate Month-over-Month Pre | 0.70 | - |
| 2026-09-29 | Inflation Rate Year-over-Year Preli | 4.3 | 4.7 |
| 2026-09-29 | Unemployment Benefit Claims | 22K | - |
| 2026-09-29 | Business Confidence Index | -3.9 | - |
| 2026-09-30 | Retail Sales Month-over-Month | -3.4 | 1.4 |
| 2026-09-30 | Retail Sales Year-over-Year | -2.5 | - |
| 2026-09-30 | Inflation Rate Year-over-Year Preli | 2.4 | - |
| 2026-09-30 | Inflation Rate Month-over-Month Pre | 0.70 | -0.50 |
| 2026-09-30 | Headline Unemployment Rate | 6.4 | 6.4 |
| 2026-09-30 | Unemployed Persons Level | 3.0mn | - |
Finland and Singapore release business and consumer confidence indices on 28 September, providing early sentiment reads ahead of euro-area data. Norway retail sales and Sweden trade balance follow on the same day. Poland employment and wage data appear mid-week alongside several low-impact Eastern European releases.
No high-impact euro-area releases are scheduled until the following week, leaving markets to focus on any follow-up commentary from recent PMI prints. French fiscal developments and German political noise will remain in view. Investors will monitor Brent crude volatility for its effect on near-term inflation expectations ahead of the next ECB meeting.
French debt dynamics and Scope’s downgrade keep sovereign-spread widening as a live risk, particularly if political constraints limit fiscal headroom. German regional election losses raise the possibility of slower reform implementation. Services strength may prove less durable if the recent Brent decline reverses, reintroducing imported price pressure.
Positioning appears light on euro-area duration given the steady 10-year yield. Volatility remains contained. Upside surprises in next week’s confidence indicators could extend the recent equity rebound, while further GfK deterioration would reinforce downside growth risks.
Euro Stoxx 50 closed the week at 6302.82, down 0.24 percent. The DAX fell 0.65 percent to 25408.64 while the CAC 40 declined 0.75 percent to 8077.80. German 10-year Bund yields ended unchanged after rising early in the week and then easing.
EUR/USD fell 0.86 percent to 1.14. EUR/JPY dropped 0.78 percent to 178.88. Brent crude declined 2.89 percent to 97.44 while gold fell 1.43 percent to 4321.20. Bitcoin rose 4.17 percent to 84523.80, providing the clearest positive outlier among risk assets.
Brent’s weekly decline eased imported inflation pressure for the euro area after the prior week’s drop. USD strength persisted, with EUR/USD falling even as the dollar index faced mixed US data. China’s shift toward high-value-added exports continued to weigh on German market share, as noted in recent ECB analysis.
Geopolitical tensions linked to the Iran conflict and Middle East booking weakness at TUI remain relevant for near-term sentiment. No new tariff announcements affected euro-area trade flows in the past seven days. The configuration leaves the euro area exposed to external commodity and currency moves while domestic services data provide the main offset.
| Asset | Level | WoW |
|---|---|---|
| Nikkei 225 | 66364.2 | +1.3% |
| USD/JPY | 157.2 | +0.1% |
| EUR/JPY | 178.85 | -0.8% |
| GBP/JPY | 207.86 | -1.1% |
| Gold | 4321.2 | -1.4% |
| Brent Crude | 97.44 | -2.9% |
| Bitcoin | 84521.01 | +4.2% |


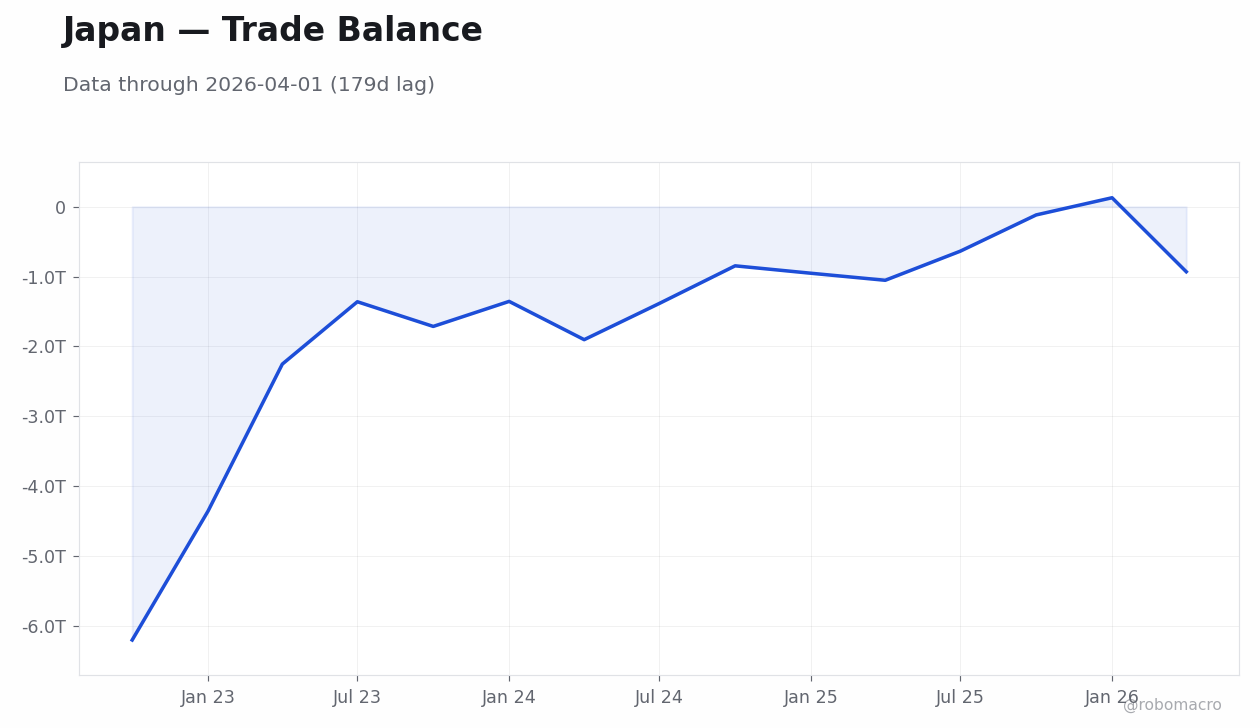
Policy tightening amid yen pressure The Bank of Japan maintained its tightening path. USD/JPY settled at 157.2, reflecting a net 0.1 percent weekly gain.
Equity resilience with sector leadership The Nikkei 225 posted a 1.3 percent weekly advance to 66,364.2.
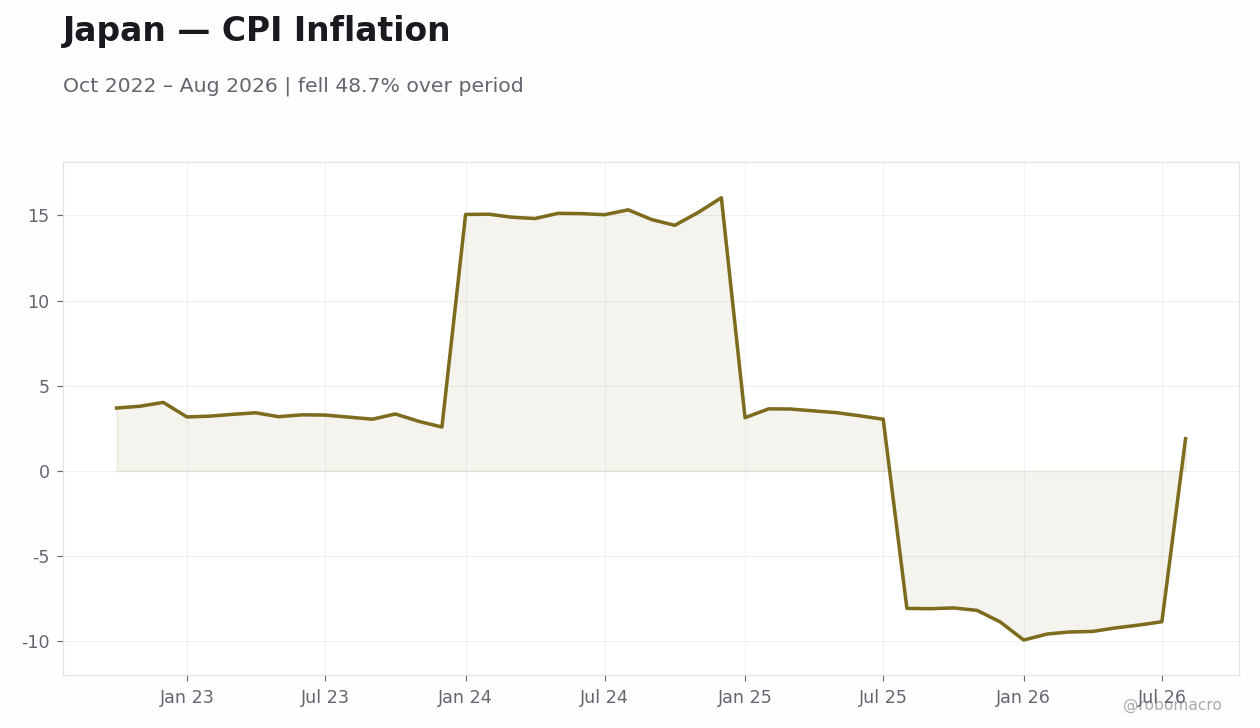
Inflation and activity data diverge Private-sector momentum indicators softened, tempering expectations for accelerated follow-up tightening.
Yield curve and funding signals JGB yields moved higher, consistent with gradual repricing of the policy path.
Commodity and external backdrop Brent crude closed at 97.44, adding imported inflation risks.
Intervention rhetoric intensifies Officials highlighted yen weakness, with USD/JPY prompting renewed monitoring of exchange-rate developments.
The Bank of Japan maintained its policy tightening stance amid inflation pressures from a weak yen. Upcoming minutes will provide further detail on the committee’s assessment of the current level and the balance of risks. Officials continue to frame normalization as gradual and data-dependent ahead of the next policy meeting.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Wed 23 | JP | S&P Global Manufacturing P | 54.9 | 55.0 | 54.1 |
| Wed 23 | JP | S&P Global Services PMI Fl | 52.5 | - | 51.6 |
| Wed 23 | JP | S&P Global Composite PMI F | 53.5 | - | 52.5 |
| Thu 24 | JP | 3-Month Treasury Bill Auct | 1.2 | - | 1.3 |
| Sun 27 | JP | BoJ Monetary Policy Meetin | - | - | - |
| Date | Release | Prior | Cons. |
|---|---|---|---|
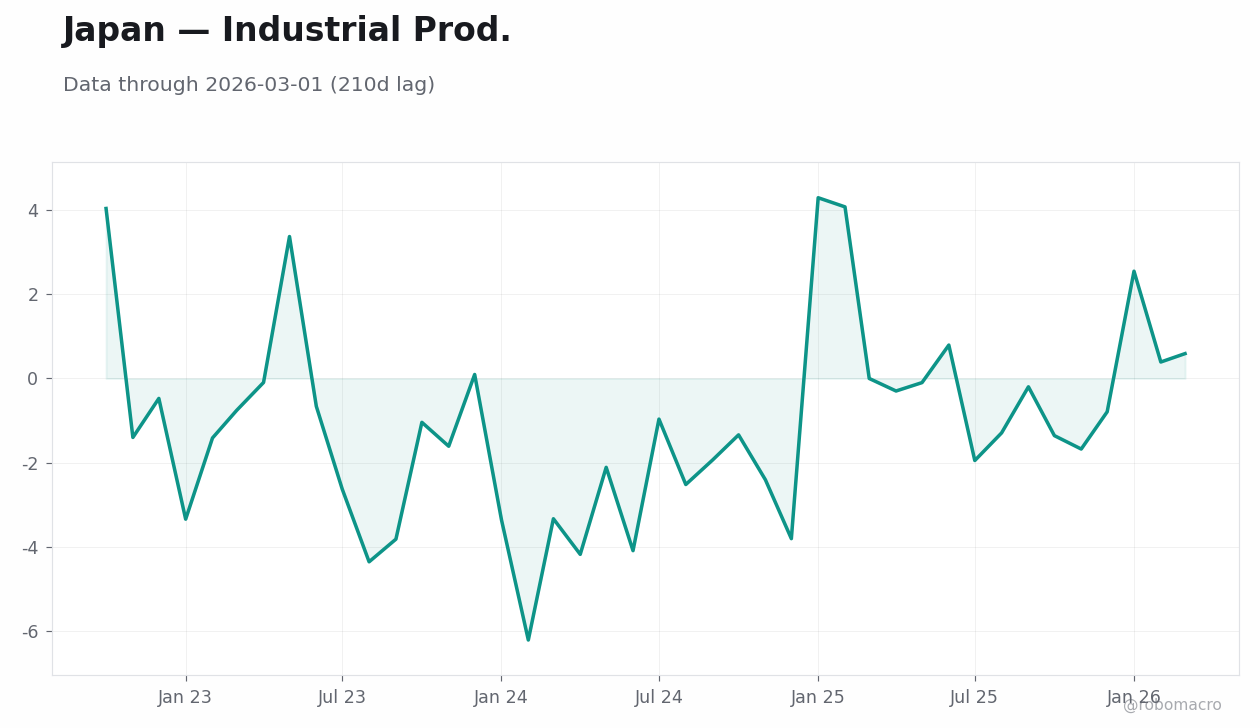
| 2026-09-29 | Industrial Production Month-over-Mo | -0.20 | 1.7 |
| 2026-09-29 | Retail Sales Year-over-Year | 4.0 | 3.3 |
| 2026-09-30 | Housing Starts Year-over-Year | 8.2 | 7.0 |
| 2026-09-30 | Tankan Large Manufacturers Index | 22.0 | 25.0 |
| 2026-09-30 | BoJ Summary of Opinions | - | - |
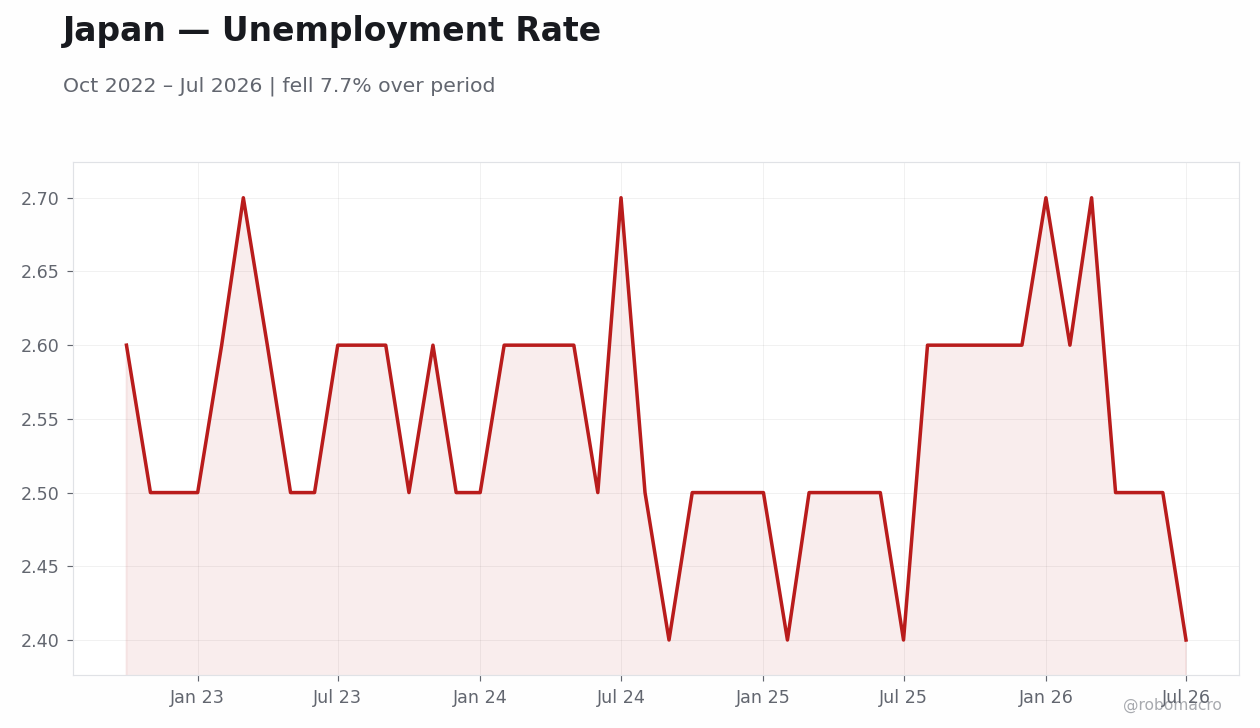
| 2026-10-01 | Headline Unemployment Rate | 2.4 | 2.4 |


Attention centers on the Bank of Japan Monetary Policy Meeting Minutes. No high-impact domestic releases are scheduled early in the period, leaving external drivers such as U.S. data and global equity flows to influence yen positioning. Lower-tier indicators including retail sales and trade balance prints will feed into the growth and inflation assessment. Markets will monitor any official commentary on exchange-rate developments. These releases matter because they will inform whether the recent policy stance sufficiently addresses imported inflation risks or whether further adjustments remain under consideration.
Yen depreciation reintroduces intervention risks that could cap further upside in USD/JPY and pressure exporter margins. Softer activity indicators raise the possibility that domestic demand momentum is fading faster than expected, potentially requiring a slower normalization pace. Brent crude volatility adds uncertainty to imported inflation trajectories. The combination of higher yields and contained CPI suggests markets may be underweighting the data-dependent nature of the next policy steps. Upside scenarios hinge on sustained equity gains supporting the Nikkei 225, while downside risks center on renewed yen strength if intervention rhetoric intensifies.
| Asset | Level | WoW |
|---|---|---|
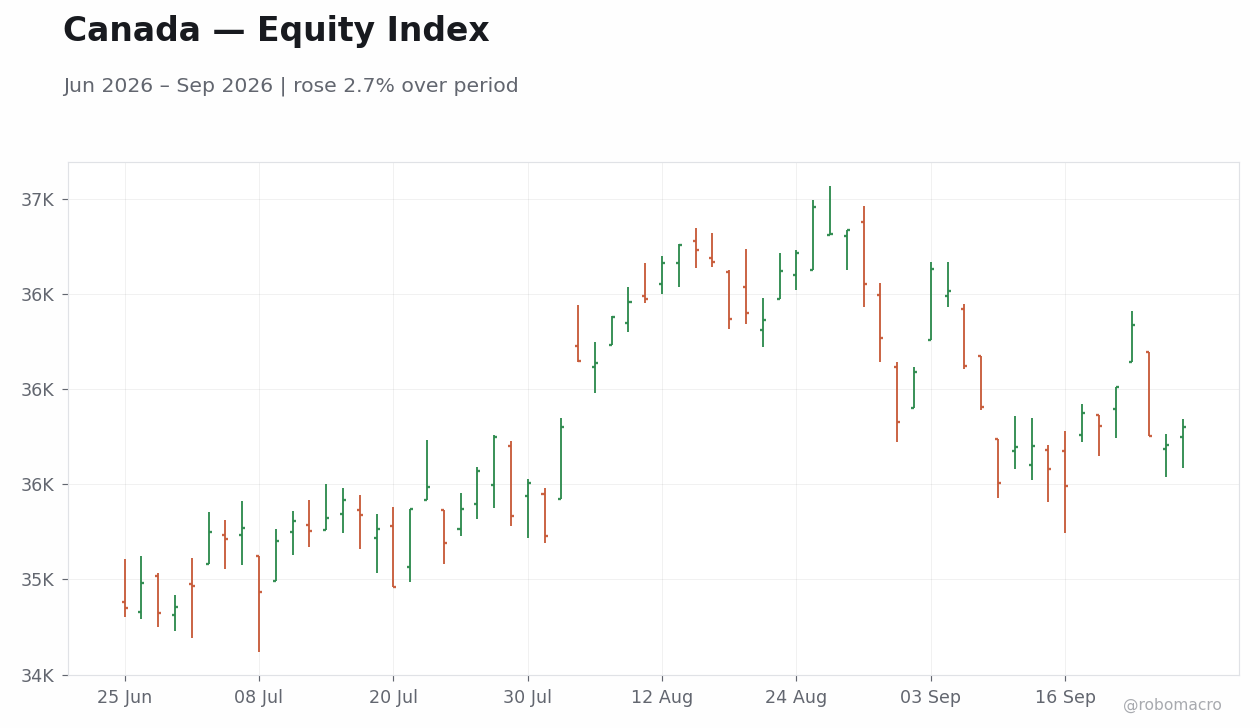
| S&P/TSX | 35800.9 | -0.6% |
| USD/CAD | 1.41 | +1.0% |
| EUR/CAD | 1.61 | +0.1% |
| WTI Crude | 92.41 | -3.5% |
| Natural Gas | 3.22 | +13.7% |
| Gold | 4321.2 | -1.4% |
| Brent Crude | 97.44 | -2.9% |
| Bitcoin | 84523.8 | +4.2% |


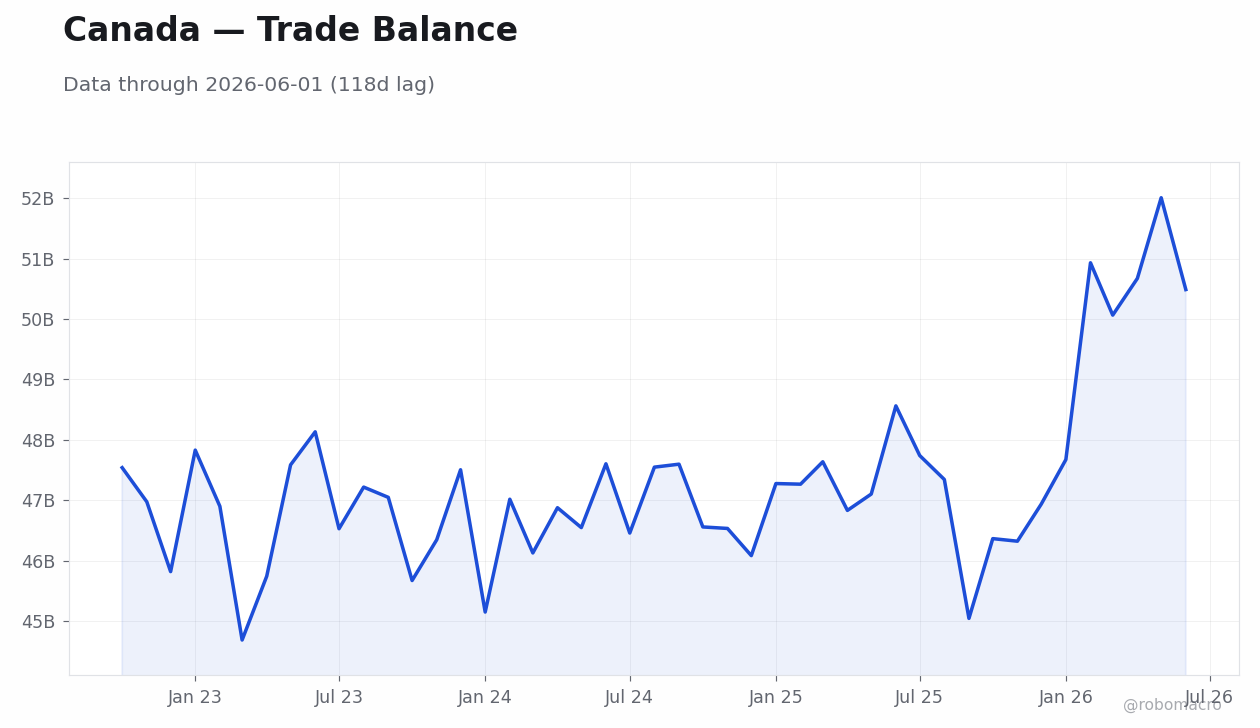
Retail Sales Signal Consumer Weakness Retail sales contracted on the week, providing the first material domestic activity read and confirming consumer weakness.
CAD and Markets Reflect External Pressure USD/CAD rose to 1.41, up 0.99 percent week-over-week. The S&P/TSX Composite ended at 35800.9, down 0.58 percent for the week. WTI Crude fell 3.52 percent to 92.41 while Natural Gas rose 13.72 percent to 3.22.
Data Dependence Remains the Through-Line No Bank of Canada decision occurred, yet officials anchored rate expectations to incoming domestic prints. The configuration leaves the expansion in a data-dependent equilibrium consistent with the prior three weeks.
The September 24 Retail Sales prints reinforced the case for monitoring consumer momentum ahead of upcoming decisions. Officials maintained the policy rate at its current level, with communications underscoring that any adjustment will rest on the evolution of Canadian activity and price data rather than global commodity volatility.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Wed 23 | CA | 10-Year Bond Auction | 3.7 | - | 4.0 |
| Thu 24 | CA | Retail Sales Excluding Aut | 0.50 | -0.50 | -0.70 |
| Thu 24 | CA | Retail Sales Month-over-Mo | 0.60 | -0.80 | -0.70 |
| Thu 24 | CA | Retail Sales Month-over-Mo | - | - | 1.3 |
| Thu 24 | CA | Average Weekly Earnings Ye | 3.4 | - | 3.2 |
| Thu 24 | CA | Manufacturing Sales Month- | -0.40 | - | 1.1 |
| Thu 24 | CA | Retail Sales Year-over-Yea | 5.2 | - | 5.1 |
| Thu 24 | CA | 2-Year Bond Auction | 3.2 | - | 3.5 |
| Thu 24 | CA | CFIB Business Barometer | 57.6 | - | 47.9 |
| Fri 25 | CA | Wholesale Sales Month-over | 0.30 | - | -1.5 |
| Fri 25 | CA | Government Budget Balance | 990.0mn | - | -4.8bn |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-29 | GDP Month-over-Month | 0.30 | 0 |
| 2026-09-29 | GDP Month-over-Month Prel | - | - |
| 2026-10-01 | S&P Global Manufacturing PMI Index | 53.0 | - |


Monday brings no high-impact Canadian releases, allowing markets to absorb the prior week’s retail sales signal. Later in the period, the next round of inflation and labour-market indicators will provide fresh inputs for the Bank of Canada’s assessment of domestic demand. These prints matter because they directly inform whether the recent consumer contraction persists into the coming quarters. Global commodity and CAD moves will remain secondary to the domestic data flow when officials evaluate the policy rate path. Overall, the calendar keeps the focus on whether activity readings challenge or support the current stance ahead of upcoming decisions.
The retail sales contraction raises downside risks to near-term growth if tariff effects broaden beyond energy-exposed sectors. Energy price volatility, with WTI down 3.52 percent and Natural Gas up 13.72 percent week-over-week, continues to complicate the inflation outlook without shifting the data-dependent stance.
| Asset | Level | WoW |
|---|---|---|
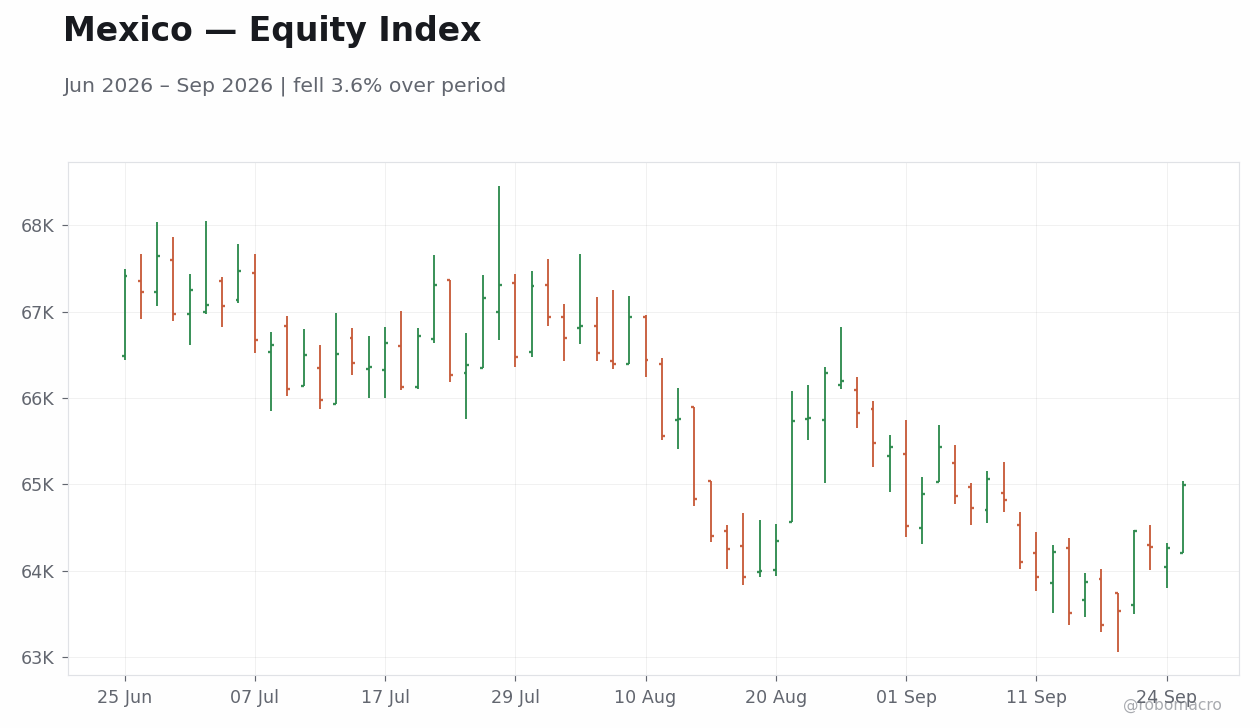
| IPC Bolsa | 64992.23 | +2.3% |
| USD/MXN | 17.73 | +2.9% |
| EUR/MXN | 20.17 | +2.0% |
| WTI Crude | 92.41 | -3.5% |
| Silver | 64.8 | -1.6% |
| Gold | 4321.2 | -1.4% |
| Brent Crude | 97.44 | -2.9% |
| Bitcoin | 84549.75 | +4.2% |


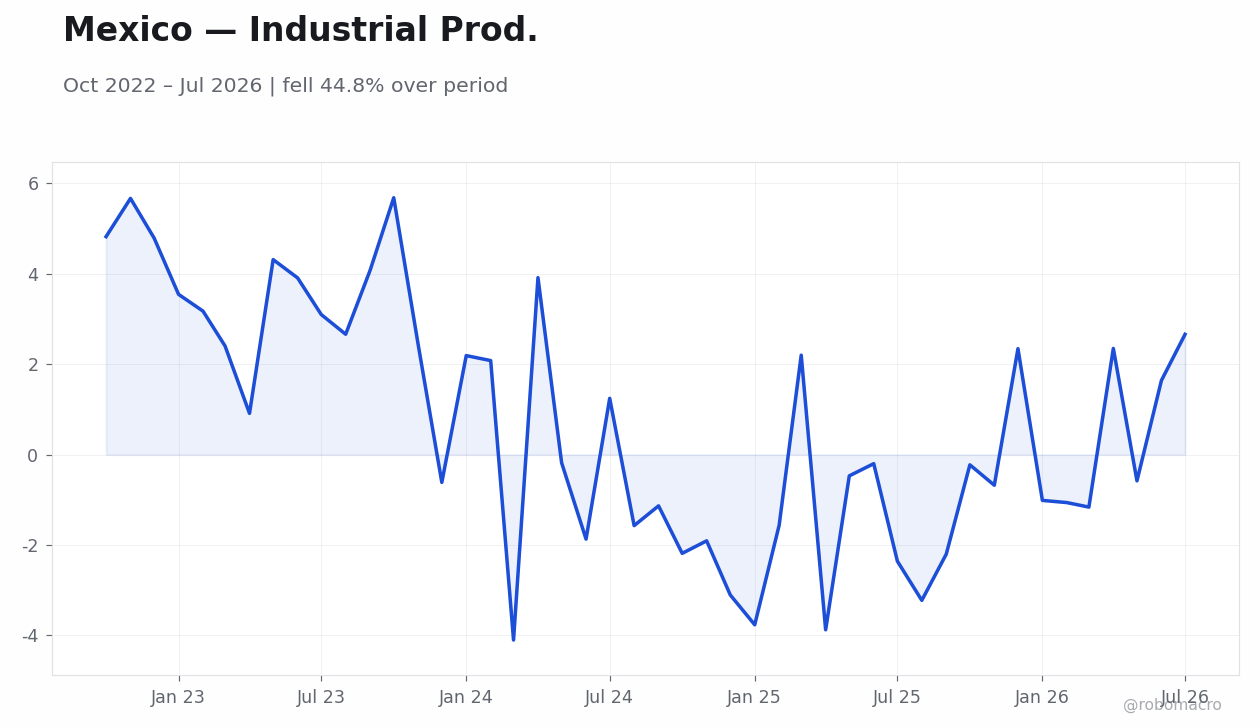
Yield curve steepening amid policy hold Mexican fixed-income markets repriced higher term premia through the week. The increases occurred with no domestic data releases between September 21 and 25.
Peso depreciation alongside equity resilience USD/MXN advanced 2.92 percent to 17.73 while EUR/MXN rose 2.02 percent to 20.17. IPC Bolsa nevertheless closed 2.29 percent higher at 64,992.23.
Oil price volatility without domestic data flow WTI crude declined 3.52 percent to 92.41 while Brent fell 2.89 percent to 97.44. The absence of inflation or activity prints left markets focused on external commodity moves and the September 24 Banxico decision.
Hurricane Polo and external trade signals Seasonal risks to coastal output emerged without immediate market impact. Mexico’s government expressed cautious optimism on US trade talks despite a delayed negotiation round.
Corporate investment and nearshoring continuity Investment announcements aligned with ongoing USMCA supply-chain positioning even as local yields rose.
Consensus alignment on the rate decision The September 24 hold matched consensus and the prior level. No Banxico speakers appeared during the week to alter forward guidance.
Banco de Mexico kept the policy rate on September 24, matching the prior setting and consensus forecast. The decision occurred without new inflation or activity data in the preceding four sessions. Officials issued no statements or minutes during the week, leaving the data-dependent stance unchanged from the prior meeting. The rise in yields reflected market adjustment to the unchanged rate path rather than any shift in official communication. With no further releases scheduled before the next decision, incoming CPI and activity prints will determine whether the committee maintains the current level or signals adjustment in coming quarters.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Tue 22 | MX | Retail Sales Month-over-Mo | -0.20 | 0.20 | -0.10 |
| Tue 22 | MX | Retail Sales Year-over-Yea | 2.9 | 2.1 | 1.8 |
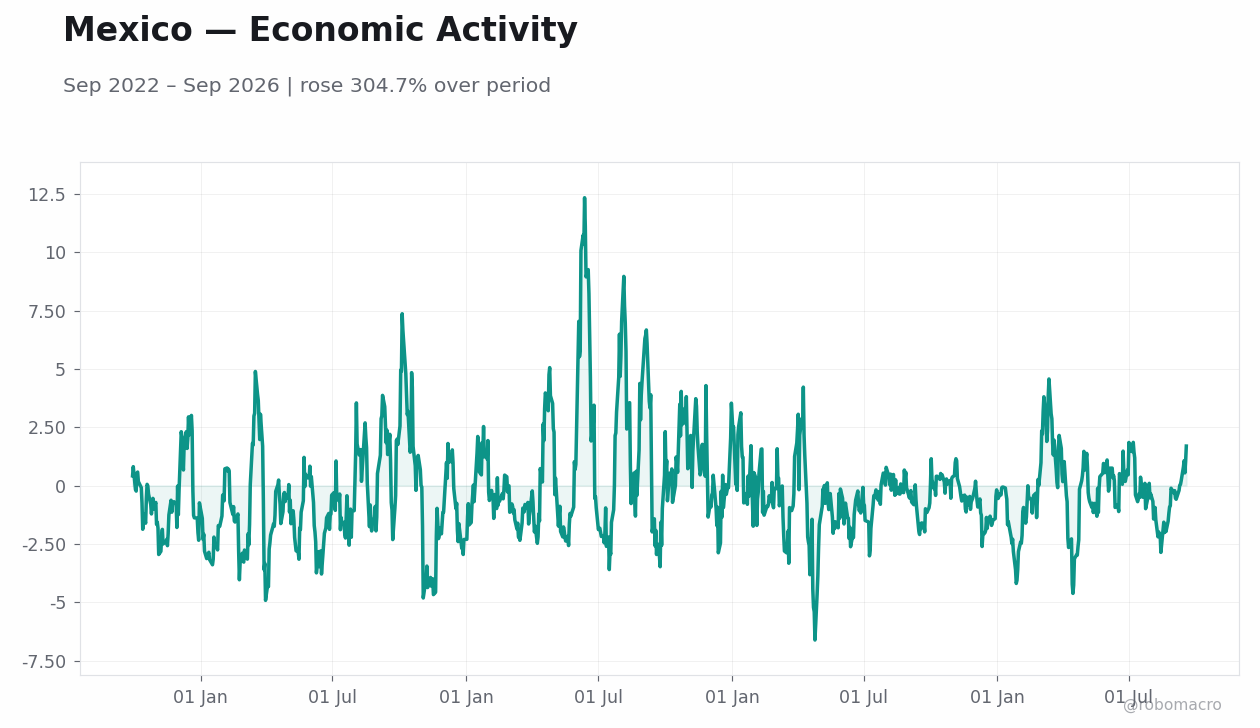
| Thu 24 | MX | Economic Activity Month-ov | -0.10 | 0.20 | 0.80 |
| Thu 24 | MX | Economic Activity Year-ove | 2.8 | 2.5 | 3.4 |
| Thu 24 | MX | Mid-month Core Inflation R | 0.08 | 0.20 | 0.17 |
| Thu 24 | MX | Mid-month Core Inflation R | 3.9 | 3.8 | 3.8 |
| Thu 24 | MX | Mid-month Inflation Rate M | 0.10 | 0.26 | 0.33 |
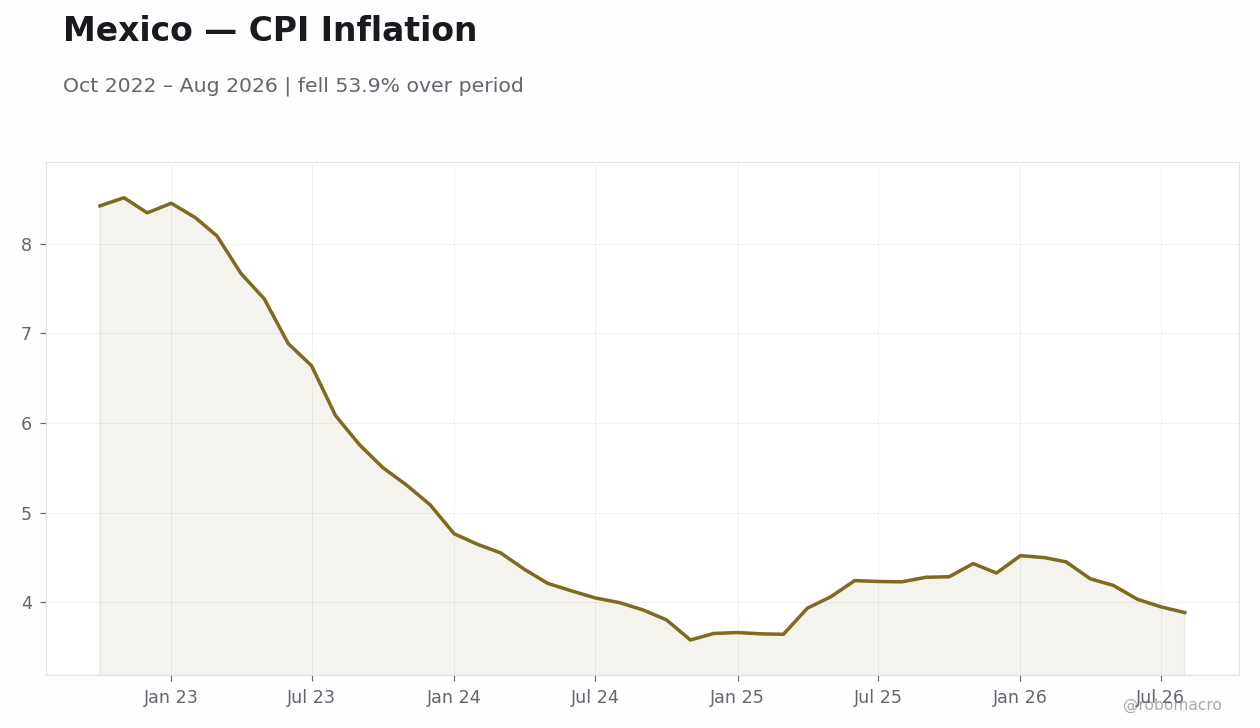
| Thu 24 | MX | Mid-month Inflation Rate Y | 3.3 | 3.4 | 3.4 |
| Thu 24 | MX | Central Bank Interest Rate | 6.5 | 6.5 | 6.5 |
| Fri 25 | MX | Headline Unemployment Rate | 2.9 | 3.0 | 3.0 |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-28 | Trade Balance | -848.0mn | - |
| 2026-10-01 | Business Confidence Index | 48.1 | - |


No high-impact Mexican data releases are scheduled for September 28 through October 2. Attention will therefore remain on external drivers including US activity prints and global oil-price movements that influence imported inflation. The next Banco de Mexico decision will incorporate any September CPI or industrial production figures released after the current week. Markets will watch for any follow-up commentary from officials on inflation convergence to the 3 percent target. Peso stability and carry-trade flows will continue to reflect the rate differential with the Federal Reserve. Any acceleration in nearshoring-related investment announcements could provide incremental support to growth expectations ahead of upcoming decisions.
The peso depreciation and yield increase highlight sensitivity to external financing conditions after the policy hold. Oil-price swings demonstrated continued exposure for fiscal and inflation dynamics. Upside scenarios center on sustained USMCA trade flows and FDI announcements that could offset higher local yields. Downside risks include further storm activity affecting coastal infrastructure and any delay in US trade negotiations. The market appears to have priced limited near-term easing, consistent with the data-dependent signal delivered on September 24.
| Asset | Level | WoW |
|---|---|---|
| Bovespa | 183477.0 | -1.7% |
| USD/BRL | 5.19 | +0.9% |
| EUR/BRL | 5.9 | +0.1% |
| Vale | 13.61 | -3.8% |
| Petrobras | 20.37 | -1.3% |
| WTI Crude | 92.41 | -3.5% |
| Gold | 4321.2 | -1.4% |
| Bitcoin | 84545.13 | +4.2% |


Copom Minutes and Steady Policy Signal The Copom minutes published on 22 September contained no change in language around the policy rate and stressed continued vigilance on the August CPI print. Markets interpreted the document as consistent with the prior August decision to hold rates steady. Growth Forecast Downgrade The government’s reduction of the 2026 GDP projection highlighted the cumulative effect of restrictive policy on domestic demand. Labor productivity data for Q2 showed only a modest gain, offering limited offset to the softer outlook. Market Price Action Bovespa closed the week at 183,477 after a 1.67 percent decline, with Vale falling 3.82 percent to 13.61 and Petrobras declining 1.26 percent to 20.37. USD/BRL ended at 5.19 after a 0.89 percent rise, while the 5-year yield moved higher. External and Fiscal Overlays WTI crude volatility, including a 3.52 percent weekly drop to 92.41, weighed on energy-linked names without altering the broader real depreciation trend. Recent fiscal measures added to concerns already reflected in longer-term yields. Drought and Sectoral Pressures Severe drought conditions in key basins raised separate risks to agricultural output and hydropower, though these factors did not produce immediate data releases during the week. State-level primary deficit projections further framed the fiscal backdrop. Positioning and Flows Equity and currency moves occurred on light volumes with no high-impact domestic releases after the minutes, leaving positioning driven by external commodity prints and domestic fiscal commentary. Sectoral contributions were noted but did not shift the macro narrative.
The Copom minutes released on 22 September reiterated the committee’s assessment that the CPI print and policy rate remain appropriate in a data-dependent framework. No new forward guidance was offered on the timing or pace of any future adjustments. Officials highlighted fiscal risks and external shocks as factors requiring continued monitoring without signaling an imminent shift. The absence of fresh activity or inflation prints during the remainder of the week left the policy signal unchanged from the prior decision. Labor productivity’s modest Q2 gain and the government’s 2026 GDP forecast reinforced the restrictive stance implied by current settings.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Tue 22 | BR | BCB Copom Meeting Minutes | - | - | - |
| Thu 24 | BR | FGV Consumer Confidence | 84.7 | - | 84.2 |
| Thu 24 | BR | BCB National Monetary Coun | - | - | - |
| Fri 25 | BR | IPCA mid-month CPI Month-o | -0.40 | 0.53 | 0.70 |
| Fri 25 | BR | IPCA mid-month CPI Year-ov | 4.2 | 4.3 | 4.5 |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-29 | Headline Unemployment Rate | 5.3 | - |
| 2026-10-02 | Industrial Production Month-over-Mo | 0.20 | - |


No high-impact Brazilian data releases are scheduled for the opening days of the period. Attention will center on any follow-up speeches by Banco Central do Brasil officials that could clarify the inflation-targeting tolerance ahead of the next meeting. Global commodity benchmarks, particularly WTI crude and iron-ore prices, will influence BRL and equity flows given Brazil’s external accounts. Fiscal commentary around the primary deficit and election-related spending measures may continue to affect longer-term yields. Participants will also watch for any updates on drought conditions that could affect agricultural and energy balances in coming quarters. The combination of steady policy-rate expectations and external drivers should keep near-term volatility contained unless new fiscal or commodity shocks emerge.
The GDP forecast cut for 2026 increases the probability that weaker domestic demand will keep inflation below target for longer, potentially allowing the policy rate to remain elevated without additional tightening. Fiscal slippage from election-timed transfers and state-level deficit projections could push 10-year yields higher if primary-balance concerns intensify. Drought-related risks to hydropower and agriculture represent an upside inflation scenario that the Banco Central do Brasil has not yet incorporated into its baseline. Markets appear to underweight the persistence of the current policy rate given the absence of any near-term easing signals in the minutes, leaving room for repricing if activity data disappoint further in coming quarters.
| Asset | Level | WoW |
|---|---|---|
| MERVAL | 2893751.0 | -3.5% |
| USD/ARS | 1524.5 | +1.0% |
| EUR/ARS | 1734.5 | +3.1% |
| Gold | 4321.2 | -1.4% |
| Brent Crude | 97.44 | -2.9% |
| Soybean | 1319.0 | -0.7% |
| Bitcoin | 84545.9 | +4.2% |


Equity and currency pressure amid data vacuum Argentine markets recorded a clear downward arc from 21 to 25 September. The MERVAL index closed Friday at 2,893,751.00 after successive daily declines. USD/ARS advanced steadily to 1,524.50, with the peso posting a 1.0 percent weekly depreciation. No Argentina-specific economic releases occurred on any day, leaving price action driven by external commodity moves and thin local liquidity.
Commodity volatility weighed on export expectations Brent Crude ended the week 2.89 percent lower at 97.44. Soybean futures closed at 1,319.00 after a net 0.68 percent weekly decline. These moves directly affect export proceeds that support reserve accumulation under the current IMF programme. Gold declined 1.43 percent to 4,321.20, offering no offset to local risk assets.
Social indicators deteriorated further Poverty metrics rose further in the first half of the year. The latest CPI reading continued to constrain real wage recovery and domestic demand.
Policy speech added external focus The president’s UN General Assembly address criticised the organisation and stated Argentina would act alone on the Falklands dispute. The remarks overshadowed otherwise quiet trading but did not alter local market pricing. Bitcoin rose 4.19 percent to 84,545.90 yet provided no material support to Argentine equities or the peso.
Overall narrative remains one of gradual adjustment The week confirmed the continuation of peso softening and equity weakness observed in prior periods, with the absence of fresh prints leaving fiscal consolidation and reserve dynamics as the dominant anchors. The Central Bank’s downward revision to growth forecasts aligned with the subdued activity backdrop.
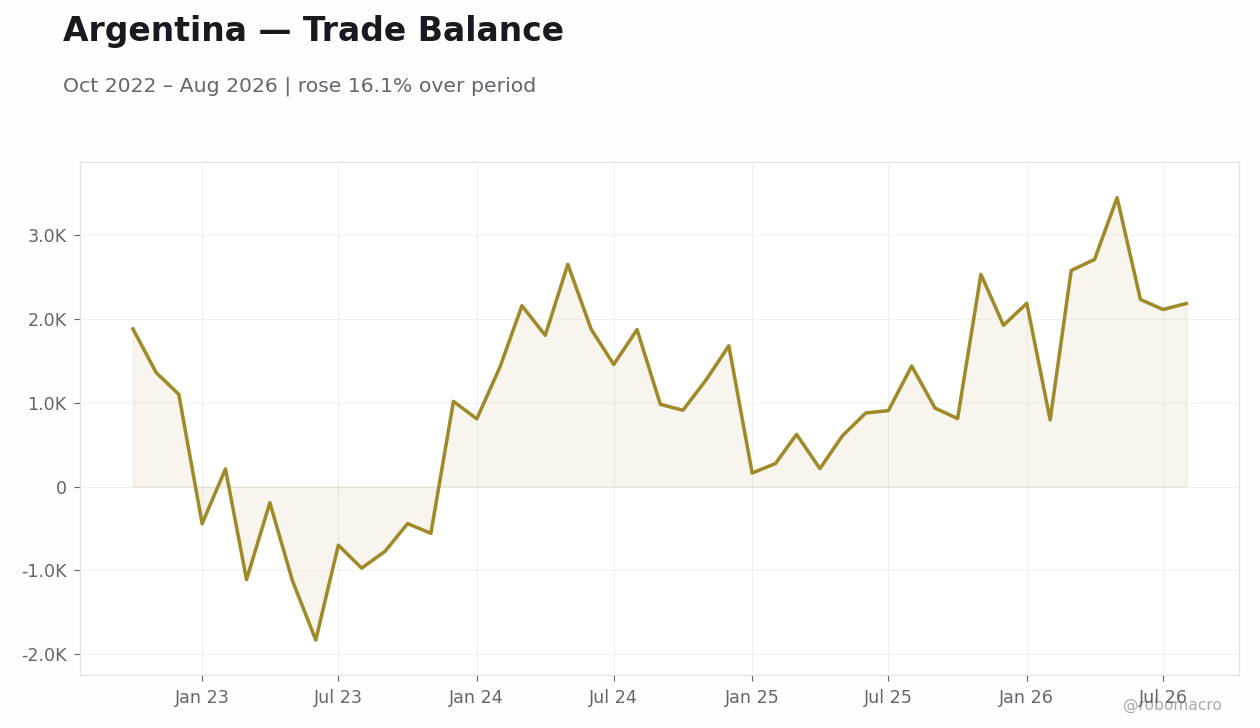
The Central Bank of Argentina cut its growth forecasts during the week, signalling caution ahead of the next policy decision. The latest CPI reading remained elevated with no new inflation prints released to alter the disinflation trajectory. Officials continued to tie any future adjustments in the policy rate to incoming activity and fiscal data rather than to a pre-set schedule. The quiet domestic calendar left reserve accumulation metrics and primary balance compliance as the key inputs for forward guidance. Commodity revenue shortfalls observed this week will feed directly into assessments of external buffers ahead of upcoming IMF reviews. The data-dependent framework therefore stays intact, with the latest growth forecast revision underscoring the bank’s focus on sustainable disinflation over near-term easing.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Wed 23 | AR | Retail Sales Year-over-Yea | 13.4 | - | 23.0 |
| Thu 24 | AR | Economic Activity Year-ove | 2.7 | 1.9 | -1.4 |

The calendar for 28 September–2 October shows no high-impact Argentina releases, keeping attention on external drivers and any BCRA communications. Traders will monitor soybean and Brent price action for signals on export receipts that support reserve accumulation. Global central-bank commentary from developed markets may influence emerging-market flows and peso demand. Fiscal target compliance under the IMF programme remains the central focus, with any Treasury bill auctions watched for signs of funding pressure. The absence of domestic prints means policy expectations will continue to rest on the latest CPI level and the recently lowered growth forecasts. Markets will also track any follow-up statements after the UN address for implications on external relations. Overall, the quiet schedule reinforces the data-dependent stance ahead of the next Central Bank of Argentina decision.
The rise in poverty highlights downside risks to consumption if real wages remain constrained by elevated inflation. Continued dependence on soybean and Brent prices creates upside and downside scenarios for reserve accumulation and fiscal receipts. A sustained decline in export proceeds could widen the external financing gap and test IMF programme compliance. The peso’s 1.0 percent weekly depreciation against the dollar suggests markets are pricing ongoing adjustment rather than rapid stabilisation. The Central Bank’s growth forecast cut may signal that activity data will remain soft, limiting room for policy rate reductions in coming quarters. Thin trading volumes and the empty calendar leave room for volatility if global commodity or risk sentiment shifts abruptly.
| Asset | Level | WoW |
|---|---|---|
| MSCI Chile | 39.04 | -2.3% |
| MSCI Peru | 90.94 | -0.2% |
| USD/COP | 3293.49 | +3.7% |
| USD/CLP | 960.63 | +0.1% |
| USD/PEN | 3.39 | +3.8% |
| Copper | 6.77 | +1.2% |
| Gold | 4321.2 | -1.4% |
| Brent Crude | 97.44 | -2.9% |
| Bitcoin | 84534.31 | +4.2% |


Equity Divergence Amid Commodity Swings MSCI Chile fell over the five-day period while MSCI Peru ended slightly lower and MSCI Colombia held flat.
Currency Pressure and Fiscal Yield Moves USD/COP and USD/PEN both climbed more than 3.5 percent, while USD/CLP edged higher. Colombia’s 10-year government yield moved higher, contrasting with Peru’s 10-year yield easing.
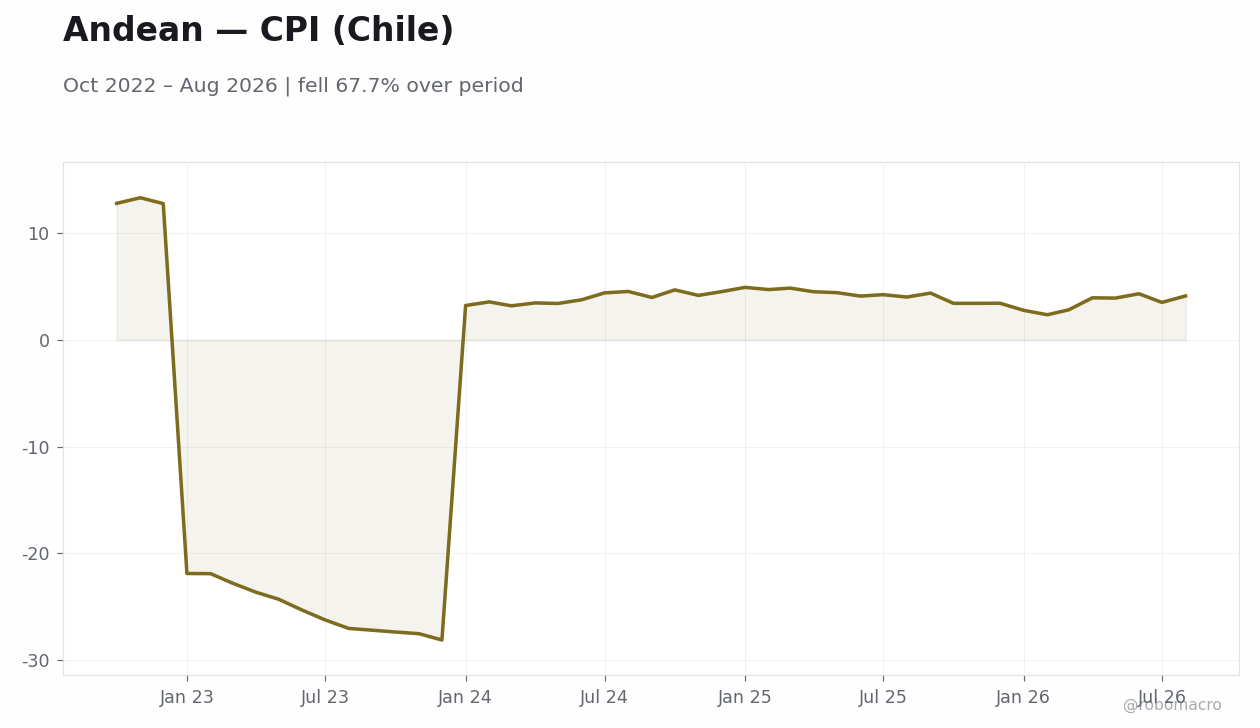
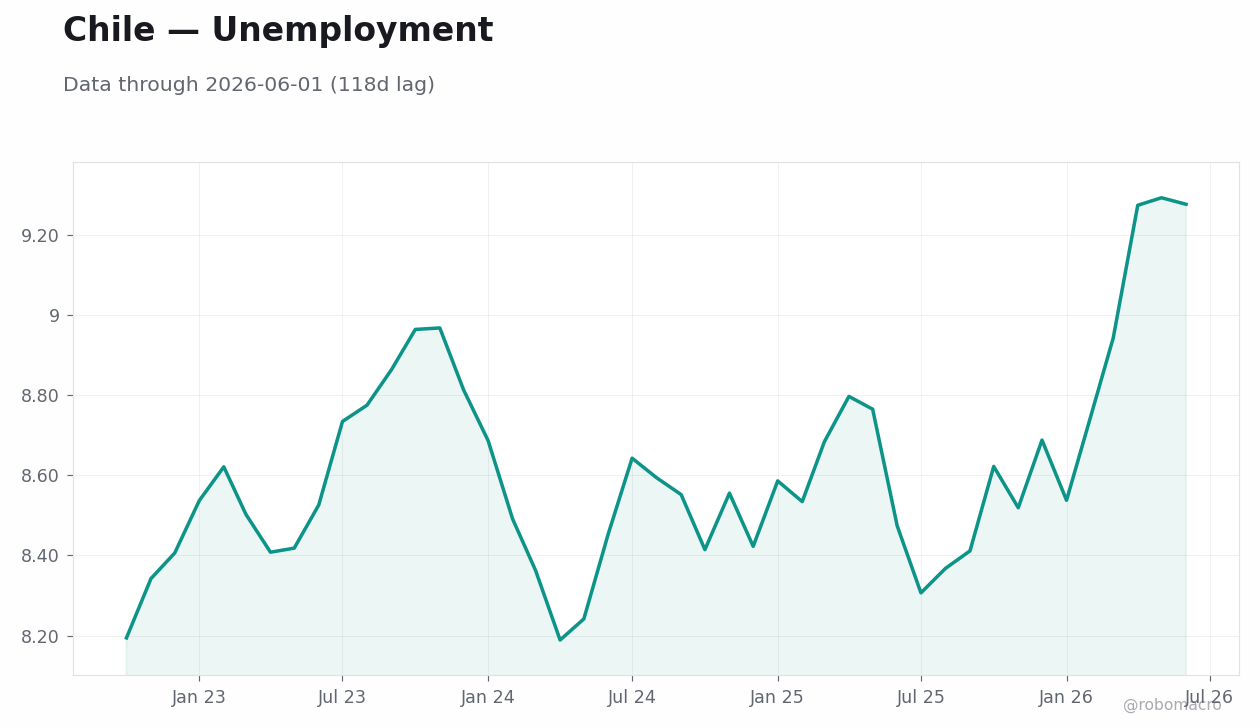
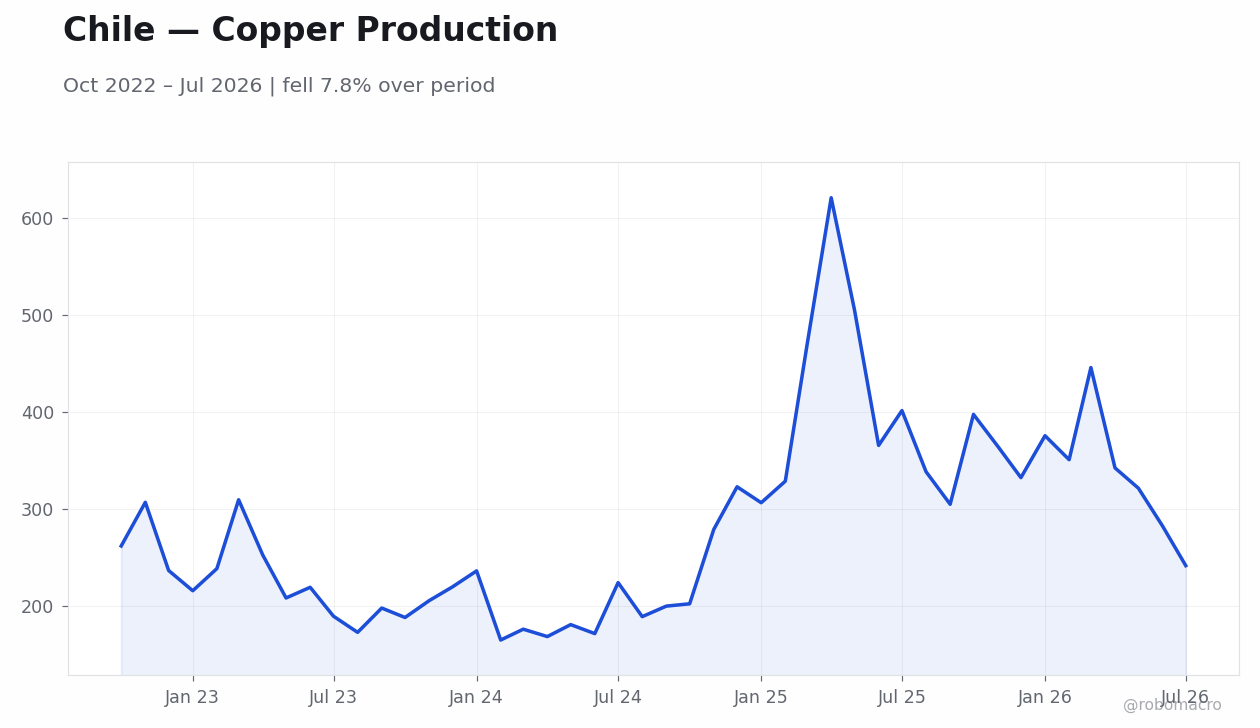
Commodity-Driven Fiscal Signals Without Data Releases Brent crude declined while copper posted a net gain, narrowing Colombia’s oil-linked revenue outlook yet supporting Chile and Peru export receipts. No CPI, GDP or trade figures were released in any of the three countries. The absence of domestic prints left external USD strength and commodity volatility as the sole drivers of price action across the week.
No BanRep, BCCh or BCRP speakers, minutes or decisions were reported during the week. Policy rates remained unchanged. Absent inflation or activity prints, the data flow provided no new information to alter the existing policy-rate path for any of the three central banks. Officials therefore maintained the data-dependent stance observed in prior weeks without fresh forward guidance.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Mon 21 | CO | Imports Year-over-Year | 27.0 | - | 22.9 |
| Mon 21 | CO | Trade Balance | -2.5bn | - | -3.3bn |
| Thu 24 | CL | Monetary Policy Meeting Mi | - | - | - |
| Thu 24 | CL | Producer Price Index Year- | 20.5 | - | 23.6 |
| Thu 24 | CO | Business Confidence Index | 6.1 | - | - |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-30 | Central Bank Interest Rate Decision | 12.0 | 12.0 |


No high-impact releases are scheduled for Colombia, Chile or Peru in the coming five days. Markets will continue to monitor copper and Brent levels for signals on royalty income and fiscal balances ahead of the next BanRep, BCCh and BCRP decisions. External USD moves will likely remain the dominant influence on COP, CLP and PEN volatility given the empty domestic calendar. Copper strength would support improved current-account readings for Chile and Peru in coming quarters, while Brent movements will influence Colombia’s near-term revenue pressure. The lack of scheduled CPI or GDP prints leaves policy-rate expectations anchored to global commodity trends until the subsequent meeting cycle.
The week’s currency depreciation raises imported-inflation risks for Peru and Colombia without offsetting domestic data to quantify the pass-through. Copper’s modest net gain leaves Chile and Peru fiscal balances sensitive to any reversal in the commodity, while Brent’s decline widens Colombia’s external-borrowing gap relative to earlier austerity projections. The absence of activity prints keeps the growth-cycle assessment dependent on external drivers. Market pricing appears to embed continued commodity volatility rather than any shift in the three central banks’ rate trajectories.
| Asset | Level | WoW |
|---|---|---|
| FTSE 100 | 10695.3 | -0.4% |
| FTSE 250 | 24261.1 | -0.9% |
| GBP/USD | 1.32 | -1.1% |
| GBP/EUR | 1.16 | -0.3% |
| GBP/JPY | 207.89 | -1.1% |
| Brent Crude | 97.44 | -2.9% |
| Gold | 4321.2 | -1.4% |
| UK Nat Gas | 3.22 | +13.7% |
| Bitcoin | 84534.31 | +4.2% |


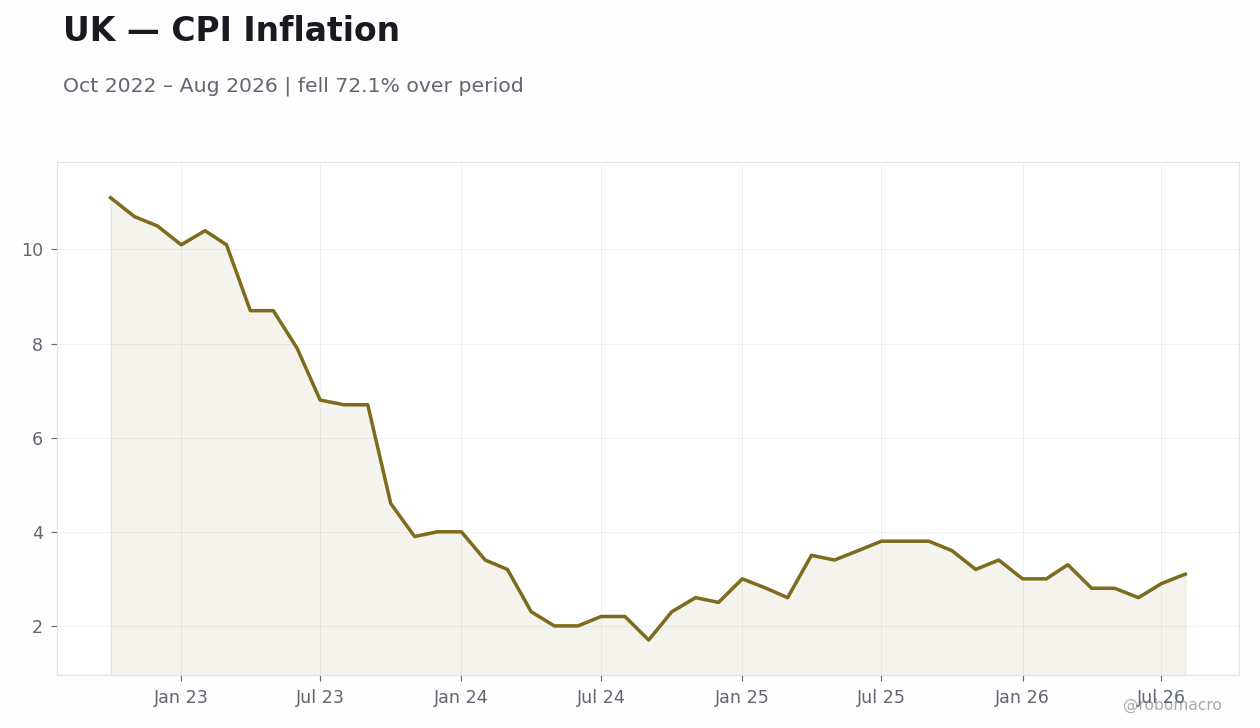
Inflation print anchors policy expectations. UK headline CPI aligned with the prior multi-month high and left the Bank of England comfortable maintaining the policy rate. The decision came on a split vote with no immediate shift in forward guidance despite the energy-price reversal. Markets absorbed the outcome without repricing near-term easing odds.
Activity surveys deliver mixed signals. The CBI Industrial Trends Orders Level surprised to the upside while the S&P Global Manufacturing PMI Flash advanced. Services PMI Flash, however, eased, pointing to softening momentum in the dominant services sector. These prints arrived against a backdrop of public-sector borrowing overshooting in August data released mid-week.
Equity and gilt markets diverge on fiscal and risk flows. The FTSE 100 fell 0.41% week-over-week to close at 10695.3 while the FTSE 250 declined 0.94% to 24261.1. Gilt yields moved higher. Sterling posted net losses, with GBP/USD settling at 1.32 for a 1.13% decline.
Energy and commodity moves shape imported-price backdrop. Brent crude ended the week at 97.44 after a 2.89% decline, easing one channel of imported inflation pressure. UK natural gas rose 13.72% to 3.22 amid separate supply dynamics. The configuration leaves the expansion in its mid-phase, where selective resilience in manufacturing surveys coexists with softer services and consumer readings.
The Bank of England held the policy rate citing Middle East energy threats and the latest CPI print. Speakers Bean, Dhingra and Breeden delivered remarks on September 24 that reinforced the data-dependent stance without altering forward guidance. OECD commentary released the same day noted that UK inflation has cooled faster than expected and supported holding the rate steady, highlighting the UK's different starting monetary position relative to peers. No minutes or Inflation Report updates appeared during the week. The configuration leaves the medium-term rate path anchored to subsequent activity and price prints rather than any pre-commitment to adjustment. Public-sector borrowing data added fiscal context but did not prompt immediate policy reaction from the central bank.
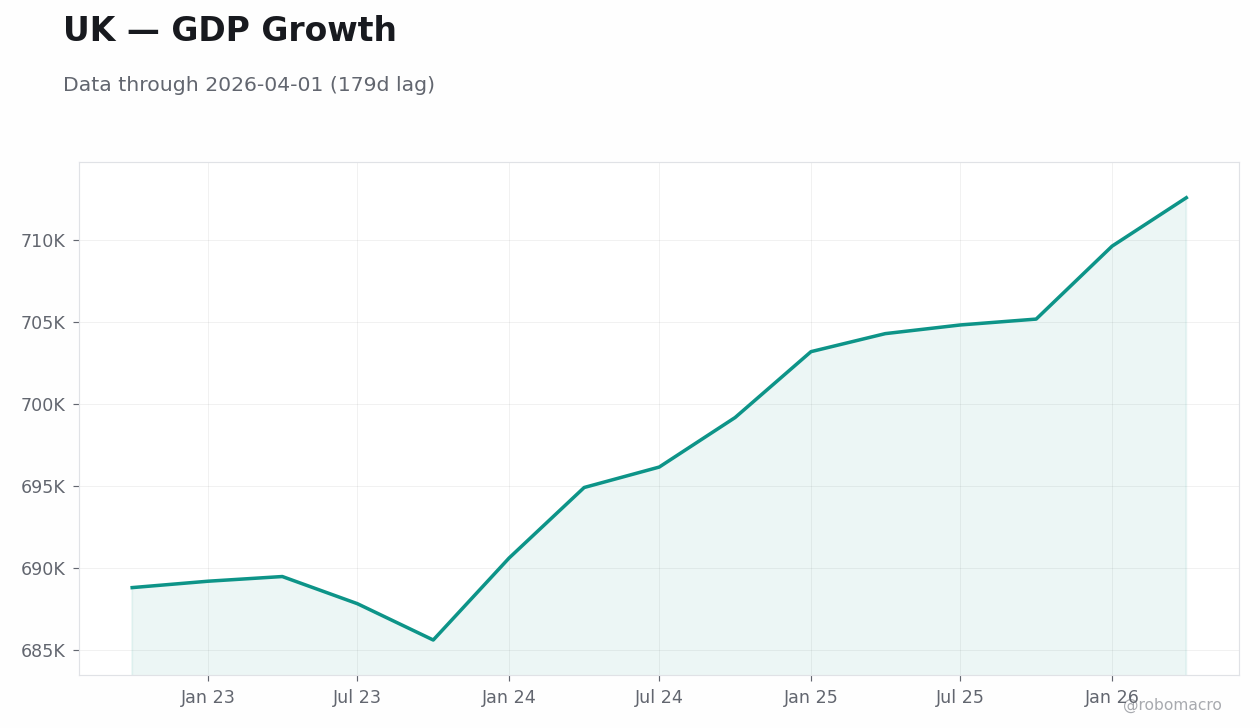
The week featured four high-impact domestic releases that together painted an uneven picture of the UK cycle. CBI Industrial Trends Orders Level printed materially above consensus and reversed the prior reading, which pointed to improving manufacturing sentiment. S&P Global Manufacturing PMI Flash rose and exceeded expectations, confirming a modest expansion in factory activity. Services PMI Flash, by contrast, came in below consensus and prior, indicating a slight loss of momentum in the larger services component. CBI Distributive Trades Level missed expectations, extending the soft retail signal seen in earlier housing and approvals data. GfK Consumer Confidence Index improved modestly, offering an offset on the household side. These outcomes leave the growth outlook tilted toward selective resilience rather than broad acceleration, with inflation still above target yet cooling faster than some peers. The data reinforce a Bank of England rate path that remains explicitly data-dependent without any immediate recalibration signaled in official communications.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Tue 22 | GB | Public Sector Net Borrowin | -2.0bn | -15.7bn | -18.3bn |
| Tue 22 | GB | Treasury Gilt 2032 Auction | 4.6 | - | 4.8 |
| Tue 22 | GB | CBI Industrial Trends Orde | -25.0 | -34.0 | -9.0 |
| Wed 23 | GB | S&P Global Manufacturing P | 51.7 | 51.5 | 52.0 |
| Wed 23 | GB | S&P Global Services PMI Fl | 52.5 | 52.0 | 51.7 |
| Wed 23 | GB | S&P Global Composite PMI F | 52.5 | 52.0 | 51.7 |
| Thu 24 | GB | BoE Bean Speech | - | - | - |
| Thu 24 | GB | BoE Dhingra Speech | - | - | - |
| Thu 24 | GB | CBI Distributive Trades | -48.0 | -50.0 | -55.0 |
| Thu 24 | GB | BoE Breeden Speech | - | - | - |
| Thu 24 | GB | GFK Consumer Confidence In | -14.0 | -16.0 | -13.0 |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-28 | BoE Ramsden Speech | - | - |
| 2026-09-29 | BoE Consumer Credit | 2.0bn | - |
| 2026-09-29 | Mortgage Approvals | 56K | 58K |
| 2026-09-29 | Mortgage Lending Level | 4.3bn | - |
| 2026-09-29 | BoE Taylor Speech | - | - |
| 2026-09-30 | Current Account Balance | -22.1bn | -25.6bn |
| 2026-09-30 | Nationwide Housing Prices Month-ove | 0.20 | 0.20 |
| 2026-09-30 | Nationwide Housing Prices Year-over | 1.6 | - |
| 2026-10-01 | BoE Mann Speech | - | - |
| 2026-10-01 | BoE Mills Speech | - | - |


Attention next week turns to the absence of high-impact UK releases on the immediate calendar, with markets instead focused on global spillovers and pre-Budget positioning. Monday features no domestic data while Tuesday and Wednesday calendars remain light on UK-specific prints. Thursday brings potential follow-through from OECD growth forecasts that projected stronger 2026 expansion before a 2027 slowdown. Central-bank speakers are not currently scheduled, leaving sterling and gilt curves sensitive to any fiscal headlines or energy-price updates. The GfK and PMI outcomes from this week will serve as the latest reference points for assessing consumer and services momentum. Markets will monitor any updates on the windfall-tax proposals and their potential impact on mortgage rates flagged by UK Finance.
This week's borrowing overshoot and mixed PMI prints shift the outlook toward tighter fiscal headroom ahead of next month's Budget, raising downside risks to growth if tax measures accelerate activity shifts away from London. Upside scenarios center on further energy-price declines that could ease imported inflation more than currently priced. Market mispricing signals appear in the divergence between manufacturing resilience and services softening, which could produce volatility around any surprise in upcoming retail or labor data. Positioning in gilts reflects reduced easing odds while sterling flows remain vulnerable to broader dollar strength. The configuration leaves volatility elevated around fiscal announcements rather than monetary-policy surprises.
Equities posted modest net losses with the FTSE 100 closing at 10695.3 for a 0.41% weekly decline while the FTSE 250 fell 0.94% to 24261.1. Daily moves included a gain on September 22 followed by three consecutive small declines. Bonds saw the 10-year gilt yield rise and the 2-year yield advance, reflecting reduced near-term easing expectations after the inflation print and borrowing overshoot. FX recorded GBP/USD falling 1.13% to 1.32 and GBP/JPY declining 1.13% to 207.89, with the largest daily drop occurring on September 24. Commodities showed Brent crude declining 2.89% to 97.44 while UK natural gas surged 13.72% to 3.22 on separate supply factors.
Energy-price reversal continued to ease imported inflation risks for the UK as Brent settled at 97.44 after a 2.89% weekly decline. US-Iran diplomatic progress contributed to the commodity move and supported modest risk-on flows in global equities. Broader USD strength pressured GBP/USD to 1.32 while OECD forecasts highlighted faster UK growth this year before a 2027 slowdown. Trade and sanctions developments involving Turkey, Oman and the UAE added to the geopolitical backdrop without direct UK data impact in the past seven days.
| Asset | Level | WoW |
|---|---|---|
| OMX Stockholm 30 | 3295.03 | -0.4% |
| Oslo Bors | 2082.8 | -1.2% |
| OMX Copenhagen 25 | 1836.48 | -1.2% |
| OMX Helsinki 25 | 6521.77 | -1.0% |
| USD/SEK | 9.91 | +0.8% |
| USD/NOK | 9.5 | +1.0% |
| EUR/SEK | 11.29 | +0.0% |
| EUR/NOK | 10.83 | +0.2% |
| Brent Crude | 97.44 | -2.9% |
| Gold | 4321.2 | -1.4% |
| Bitcoin | 84524.26 | +4.2% |


Policy decisions split the Nordic bloc. The Riksbank held its policy rate with the subsequent press conference underscoring subdued CPI year-over-year, while Norges Bank lifted its policy rate after a split economist vote. This gap expansion occurred against Brent crude’s decline. Sweden’s 10-year yield eased while Norway’s 10-year yield rose.
Equity and currency moves tracked the oil reversal. OMX Stockholm 30 closed the week at 3295.03 while Oslo Bors declined to 2082.80. USD/SEK rose 0.81 percent to 9.91 and USD/NOK advanced 1.03 percent to 9.50, consistent with lower petroleum revenue expectations for the krone. OMX Copenhagen 25 fell 1.19 percent to 1836.48 and OMX Helsinki 25 declined 0.97 percent to 6521.77 over the same five sessions.
Inflation and activity data remained sparse. No high-impact releases beyond the central bank meetings appeared in the September 21–25 window, leaving Sweden’s and Norway’s inflation readings as the dominant reference points. The absence of fresh prints reinforced the data-dependent stance already signaled in prior weeks. Danish and Finnish markets showed limited movement, with the EUR/DKK peg and ECB alignment keeping Danmarks Nationalbank and Bank of Finland on hold.
Fiscal and external balance signals pointed to divergence. Lower Brent levels reduced near-term transfers to Norway’s sovereign wealth fund while Sweden’s export sector faced stable but low domestic price pressure. The week’s equity and FX tape therefore reflected policy separation more than broad regional growth shifts.
The Riksbank held its policy rate and signaled in the press conference that incoming inflation and growth data would guide any subsequent adjustment. Norges Bank raised its policy rate, citing persistent CPI year-over-year and ongoing expansion despite the Brent decline. Danmarks Nationalbank maintained its peg to the ECB deposit rate with no independent signals issued during the week. Bank of Finland, operating within the ECB framework, offered no separate commentary. The data flow therefore left the Riksbank on a measured path while Norges Bank tightened further on the basis of its higher inflation reading.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Tue 22 | FI | Headline Unemployment Rate | 9.9 | - | 9.1 |
| Tue 22 | DK | Consumer Confidence Index | -13.1 | - | -13.7 |
| Wed 23 | DK | Business Confidence Index | 97.9 | - | 100 |
| Wed 23 | NO | Headline Unemployment Rate | 4.2 | - | 4.5 |
| Wed 23 | SE | 2033 Sgb Auction | 2.6 | - | 3.0 |
| Wed 23 | SE | 2037 Sgb Auction | 3.3 | - | 3.1 |
| Thu 24 | FI | Export Prices Year-over-Ye | 8.5 | - | 8.7 |
| Thu 24 | FI | Import Prices Year-over-Ye | 7.3 | - | 7.6 |
| Thu 24 | FI | Producer Price Index Year- | 6.9 | - | 7.3 |
| Thu 24 | NO | Loan Growth Year-over-Year | 4.3 | - | 4.5 |
| Thu 24 | SE | Riksbank Rate Decision | 1.8 | 1.8 | 1.8 |
| Thu 24 | NO | Norges Bank Interest Rate | 4.2 | 4.5 | 4.5 |
| Thu 24 | NO | Norges Bank Monetary Polic | - | - | - |
| Thu 24 | SE | Riksbank Press Conference | - | - | - |


Norway Retail Sales month-over-month and Sweden Trade Balance are scheduled early in the period and will provide the first post-decision activity read. Finland Business Confidence Index and Consumer Confidence Index follow, offering sentiment gauges ahead of the next ECB and Riksbank meetings. No central bank decisions are listed for the Nordic region in the immediate window. The releases will inform assessments of domestic demand resilience after the recent oil price move. Trade balance figures matter for krona valuation and external financing conditions. Retail sales data will help gauge whether Norway’s higher policy rate is beginning to affect consumption. Overall the calendar remains light, keeping focus on the forward guidance already delivered by the Riksbank and Norges Bank.
The policy spread now in place between Norges Bank and the Riksbank introduces scope for further krona and krone divergence if inflation prints continue to differ. Brent’s weekly decline reduces near-term imported price pressure for Sweden and Denmark yet lowers fiscal inflows for Norway, tilting the growth-inflation balance in opposite directions. Equity underperformance in Oslo Bors relative to OMX Stockholm 30 suggests markets are already embedding some of this separation. Upside risks center on stronger-than-expected retail sales or trade data that could support the higher Norwegian rate path. Downside risks include further commodity weakness that could challenge Norges Bank’s inflation outlook while leaving the Riksbank’s subdued CPI trajectory intact.
| Asset | Level | WoW |
|---|---|---|
| BIST 100 | 12899.4 | -3.3% |
| iShares Poland | 44.85 | -1.8% |
| EUR/PLN | 4.37 | +0.3% |
| EUR/HUF | 365.16 | +0.3% |
| EUR/CZK | 24.32 | -0.0% |
| USD/TRY | 48.97 | +0.4% |
| Brent Crude | 97.44 | -2.9% |
| Gold | 4321.2 | -1.4% |
| Bitcoin | 84531.26 | +4.2% |


Poland output and rating shock dominate regional sentiment. Poland’s August industrial production rose but fell short of market expectations, adding to growth concerns in the region’s largest EU economy. Moody’s cut the sovereign rating to A3, citing widening budget deficits and complicating Prime Minister Tusk’s fiscal plans. The Russian airspace breach triggered jet scrambles and heightened NATO-border rhetoric.
Hungary pauses easing and adjusts target. The MNB held the base rate steady and released fresh macroeconomic forecasts, citing stable inflation risks. The Monetary Council lowered its inflation target from 2028 onward after reviewing medium-term price stability metrics. The forint depreciated against the euro on the week.
Turkey sentiment prints diverge while equities lag. Business confidence slipped to 102.0 from 102.8, highlighting persistent demand weakness, while consumer confidence improved to 91.9. President Erdoğan highlighted economic resilience and a $100 billion US trade target. The BIST 100 closed the week after a 3.29 percent decline. NBP continued gold purchases in August, staying on track for its 700-ton target and supporting reserve diversification across the region.
The MNB held the policy rate steady on September 22 and lowered its inflation target effective 2028, the first such shift since 2005, after the committee reviewed medium-term price stability metrics. Updated forecasts signaled the end of the summer easing cycle while keeping the stance explicitly data-dependent. NBP continued gold purchases in August, remaining on track for the 700-ton target and supporting reserve diversification. No rate decisions or minutes were released by the CNB, BNR or CBRT. Turkish business and consumer confidence prints left inflation expectations largely unchanged. The week’s data and MNB communication reinforce a medium-term rate path that stays anchored to incoming activity and price prints rather than any single commodity or geopolitical impulse.
Poland’s August industrial output rose year-over-year but missed consensus, underscoring softening momentum. Corporate sector wages grew 5.6 percent year-over-year against a 6.6 percent consensus and 6.8 percent prior, marking a clear miss that eases near-term wage-pressure concerns for the NBP. Employment growth held at -0.8 percent year-over-year, in line with expectations. Turkey’s business confidence index declined to 102.0 from 102.8, while consumer confidence rose to 91.9 from 90.8, producing mixed readings on domestic demand. Hungary’s capacity utilization and external debt prints were not released, leaving the MNB decision as the dominant policy signal. The data configuration points to a mid-cycle expansion where imported energy costs and fiscal concerns compete with contained wage growth, keeping central banks on a data-dependent path without immediate recalibration. Romania and Czech Republic releases remained absent, reinforcing the uneven activity backdrop across the five economies.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Mon 21 | PL | Corporate Sector Wages Yea | 6.8 | 6.6 | 5.6 |
| Mon 21 | PL | Employment Growth Year-ove | -0.80 | -0.80 | -0.80 |
| Mon 21 | CZ | External Debt | 238.4bn | - | 251.5bn |
| Tue 22 | PL | Retail Sales Year-over-Yea | 3.9 | 4.2 | 3.8 |
| Tue 22 | HU | 3-Month Dtb Auction | 5.2 | - | 5.2 |
| Tue 22 | HU | Central Bank Interest Rate | 5.5 | 5.5 | 5.5 |
| Tue 22 | HU | Deposit Interest Rate | 4.5 | - | 4.5 |
| Tue 22 | PL | M3 Money Supply Year-over- | 11.3 | 11.2 | 11.3 |
| Wed 23 | PL | Headline Unemployment Rate | 5.8 | 5.9 | 5.8 |
| Wed 23 | HU | 6-Month Dtb Auction | 5.1 | - | 5.2 |
| Thu 24 | CZ | Business Confidence Index | 100 | - | 98.4 |
| Thu 24 | CZ | Consumer Confidence Index | 102 | - | 105 |
| Thu 24 | PL | Business Confidence Index | -5.1 | - | -5.8 |
| Thu 24 | HU | 12-Month Dtb Auction | 5.1 | - | 5.1 |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-30 | Inflation Rate Year-over-Year Preli | 3.4 | 3.6 |


The calendar for September 28–October 02 remains light across the five economies, with no high-impact data releases scheduled for Poland, Czech Republic, Hungary, Romania or Turkey. Markets will monitor any follow-up comments from MNB officials on the new inflation target path and forint implications. Polish security developments and fuel-price commentary may generate further domestic discussion on cost-of-living pressures. Broader euro-area data and ECB rhetoric will provide indirect signals for regional FX positioning ahead of month-end flows. No sovereign bond auctions or EU fund disbursements are listed. Traders will watch Turkish statements on US trade expansion and CBRT reserve management. Global commodity moves, particularly Brent, will continue to influence imported inflation assessments for net-energy importers.
The Moody’s downgrade and Polish geopolitical tensions have shifted positioning toward greater caution on zloty and CEE equities, with iShares Poland down 1.8 percent on the week. Upside risks center on continued Brent declines that ease imported inflation for Poland, Hungary and the Czech Republic. Downside scenarios include further fiscal-spread widening if Polish budget concerns intensify ahead of 2027 elections. Market mispricing appears in the forint’s modest depreciation despite the MNB’s target adjustment, suggesting limited immediate repricing of the medium-term path. Volatility remains contained but could rise on any escalation in NATO-border rhetoric. Flow considerations favor reserve diversification via gold for NBP while EU fund support continues to underpin fiscal positions in Romania and Poland.
Equities closed lower across the board, with the BIST 100 falling 3.29 percent and iShares Poland declining 1.8 percent after daily drops on September 24 and September 23. The iShares Poland index posted a modest gain on September 25. FX markets saw EUR/PLN rise 0.29 percent, EUR/HUF advance 0.28 percent, and USD/TRY climb 0.41 percent, reflecting zloty and forint pressure from Polish geopolitical headlines. EUR/CZK edged 0.02 percent lower. Brent crude declined 2.89 percent after a sharp drop on September 25, easing imported inflation exposure for net-energy importers. Gold fell 1.43 percent while Bitcoin rose 4.18 percent. Sovereign yields remained stable with no fresh prints, leaving Hungarian 10-year yields at the prior level.
Brent crude’s weekly decline reduced near-term imported inflation risks for the region’s net-energy importers without altering broader growth trajectories. USD strength persisted, with EUR/PLN and EUR/HUF posting modest gains that pressured local currencies. French fiscal concerns continued to widen euro-area sovereign spreads, providing indirect context for Polish rating dynamics. No major shifts in global equity or commodity flows altered the data-dependent equilibrium observed since late August. Trade and defense messaging between Turkey and the United States remained a localized positive amid broader EM currency depreciation against the dollar.
| Asset | Level | WoW |
|---|---|---|
| JSE Top 40 | 103152.2 | -2.1% |
| USD/ZAR | 16.27 | +0.2% |
| EUR/ZAR | 18.52 | -0.7% |
| Platinum | 1797.7 | -0.0% |
| Gold | 4321.2 | -1.4% |
| Brent Crude | 97.44 | -2.9% |
| Naspers | 70938.0 | -0.9% |
| Bitcoin | 84531.25 | +4.2% |


Policy Tightening Dominates The South African Reserve Bank delivered a rate hike on 23 September, marking the first move higher after holding steady in August. The decision followed the prior week’s energy-price surge and arrived alongside an inflation print that undershot consensus. Markets absorbed the tightening without immediate rand volatility, with USD/ZAR closing the week higher.
Inflation and Activity Signals The month-over-month inflation reading came in flat, below the prior period, while the year-over-year outcome undershot consensus. These figures arrived against the backdrop of a Q2 GDP contraction reported in the preceding period, underscoring the tension between price pressures and weak domestic demand.
Market and Yield Response The JSE Top 40 declined over the five-day period, with Naspers also lower. South Africa 10Y government yields eased on the day of the decision before stabilising, while the 5Y yield slipped. Brent Crude’s weekly decline provided partial offset to imported-price concerns yet failed to alter the central bank’s tightening signal.
External and Domestic Context Gold declined while platinum was little changed, limiting support for mining equities. The rand traded in a narrow range, reflecting positioning ahead of and after the MPC announcement rather than any shift in external flows.
The South African Reserve Bank raised the policy rate on 23 September and paired the move with explicit reinforcement of the 3% inflation target. Officials highlighted persistent price pressures above the midpoint of the target band despite the year-over-year outturn. The decision followed the prior setting and came after Q2 GDP had contracted quarter-over-quarter. No additional speakers or minutes were released during the week, leaving the hawkish statement as the clearest forward signal. The data configuration—modest inflation undershoot alongside the energy-price reversal—suggests the Bank will continue to condition upcoming decisions on incoming prints rather than pre-commit to further steps.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Mon 21 | ZA | 182-Day T-Bill Auction | 7.6 | - | 7.7 |
| Mon 21 | ZA | 273-Day T-Bill Auction | 7.8 | - | 7.9 |
| Mon 21 | ZA | 364-Day T-Bill Auction | 7.9 | - | 8.0 |
| Mon 21 | ZA | 91-Day T-Bill Auction | 6.9 | - | 7.0 |
| Tue 22 | ZA | Leading Business Cycle Ind | -1.0 | - | -0.90 |
| Tue 22 | ZA | 2038 Bond Auction | 9.1 | - | 8.9 |
| Tue 22 | ZA | 2039 Bond Auction | 9.2 | - | 9.0 |
| Tue 22 | ZA | 2042 Bond Auction | 9.4 | - | 9.2 |
| Wed 23 | ZA | Inflation Rate Month-over- | 0.20 | - | 0 |
| Wed 23 | ZA | Inflation Rate Year-over-Y | 4.3 | 4.5 | 4.4 |
| Wed 23 | ZA | Core Inflation Rate Month- | 0.50 | - | 0 |
| Wed 23 | ZA | Core Inflation Rate Year-o | 4.2 | 4.2 | 4.1 |
| Wed 23 | ZA | Central Bank Interest Rate | 7.0 | 7.2 | 7.2 |
| Wed 23 | ZA | Prime Overdraft Rate | 10.5 | - | 10.5 |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-30 | Trade Balance | 20.1bn | - |


No high-impact South African data releases are scheduled for the period 28 September–2 October. Attention will therefore remain on follow-through commentary from MPC members regarding the policy rate and the durability of the 3% inflation anchor. Global commodity moves, particularly Brent Crude and platinum, will continue to influence imported inflation risks and export revenues. The absence of domestic indicators leaves the rand and bond market sensitive to any external risk sentiment shifts that could affect the growth–inflation balance ahead of the next meeting. Fiscal updates on debt-service costs and potential Gulf sovereign-wealth inflows into the property vehicle may also surface as secondary themes. Overall, the data-dependent stance established this week implies that any surprise in global energy prices or domestic activity prints will be scrutinised for implications on the coming quarters’ rate path.
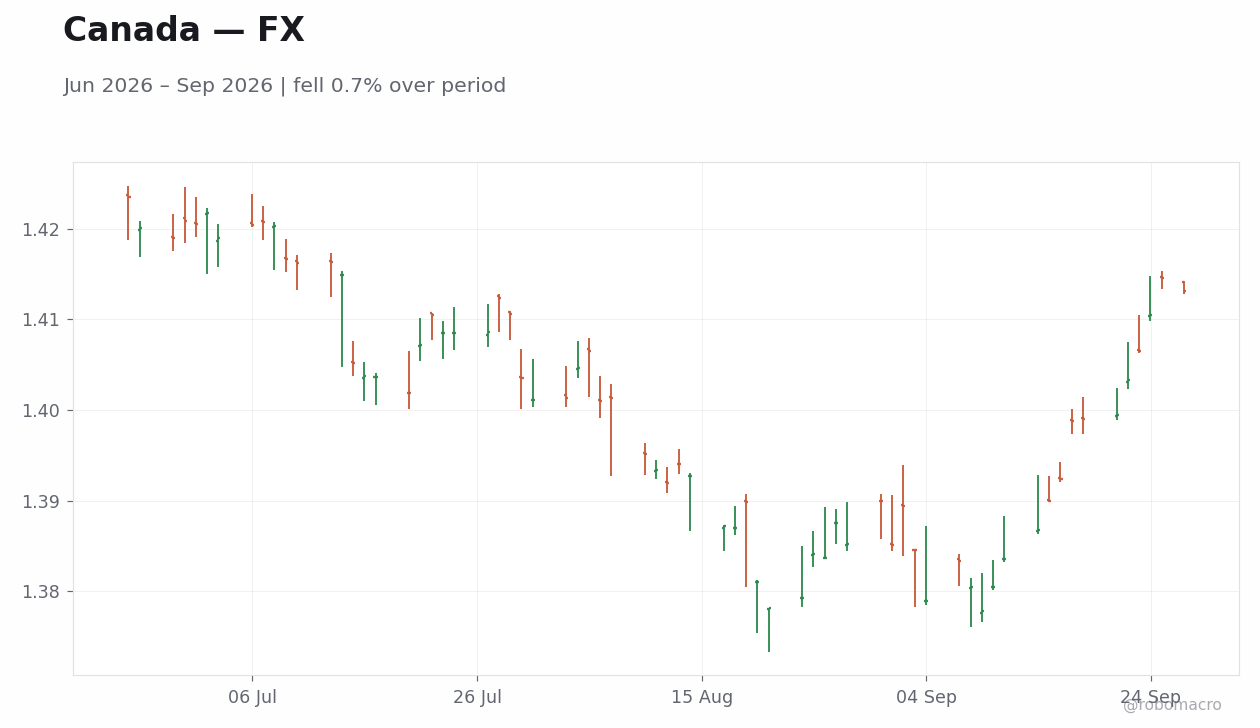
The hike reduces the probability of an immediate reversal but raises downside risks to already weak activity indicators if borrowing costs remain elevated. A further decline in Brent Crude would ease imported-price pressures and potentially allow the SARB to pause at the next decision, while any rebound would reinforce the hawkish tilt. Equity-market underperformance signals that investors are pricing slower growth rather than faster disinflation. The rand’s limited reaction to the decision suggests markets may be underweighting the persistence of inflation above the 3% target in the near term.
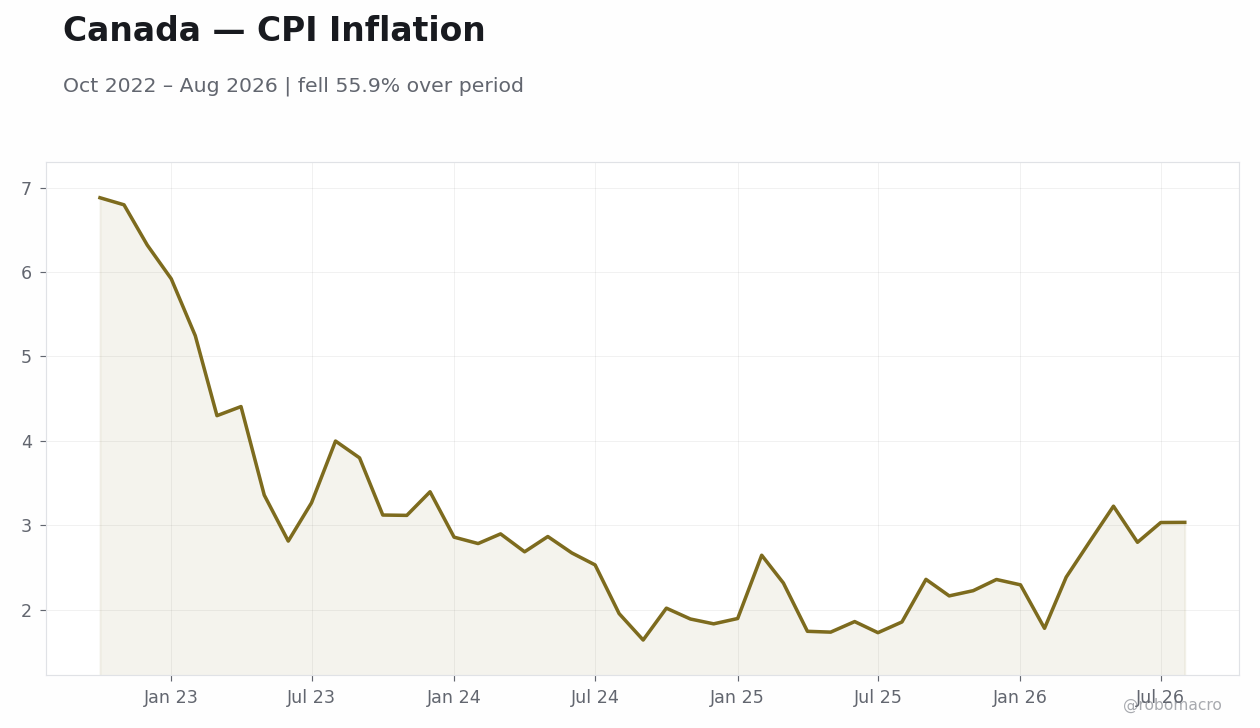
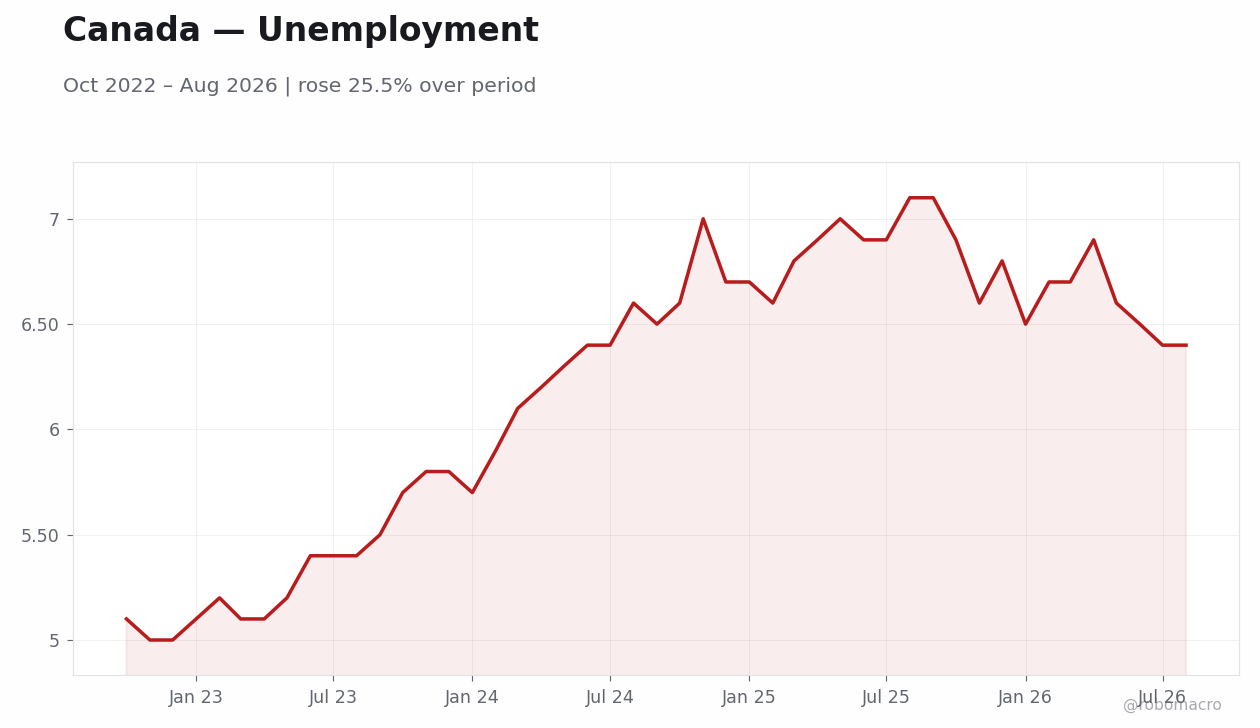
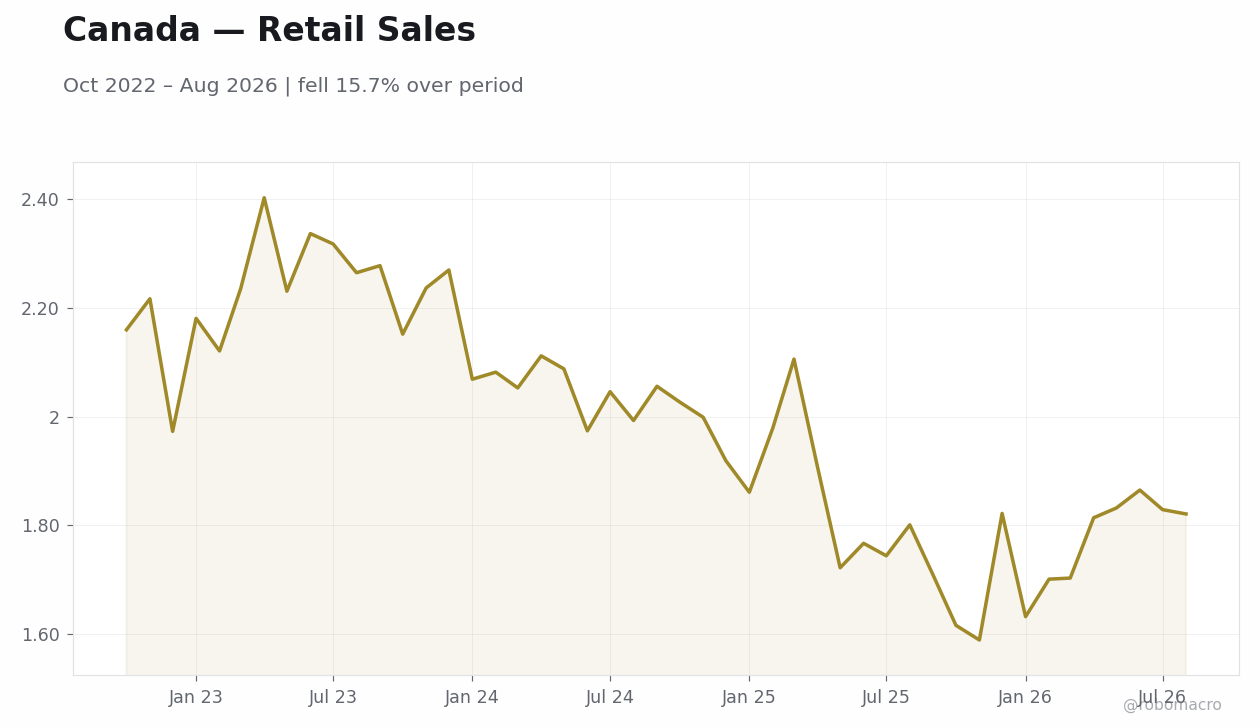
| Asset | Level | WoW |
|---|---|---|
| ASX 200 | 8665.0 | -0.8% |
| NZX 50 | 13811.11 | -0.1% |
| AUD/USD | 0.7 | -1.5% |
| NZD/USD | 0.57 | -1.1% |
| AUD/NZD | 1.24 | -0.7% |
| BHP | 60.72 | -0.1% |
| Gold | 4321.2 | -1.4% |
| Brent Crude | 97.44 | -2.9% |
| Bitcoin | 84527.31 | +4.2% |


RBA Hawkish Rhetoric Dominates Market Moves RBA Governor Bullock highlighted materialising inflation risks from oil prices and the bank’s prioritisation of price stability even if unemployment rises. This commentary weighed on equities and left the ASX 200 at 8665.00 after an early-week gain. Australian 2-year and 10-year yields declined, reflecting the tension between softer activity data and unchanged policy vigilance.
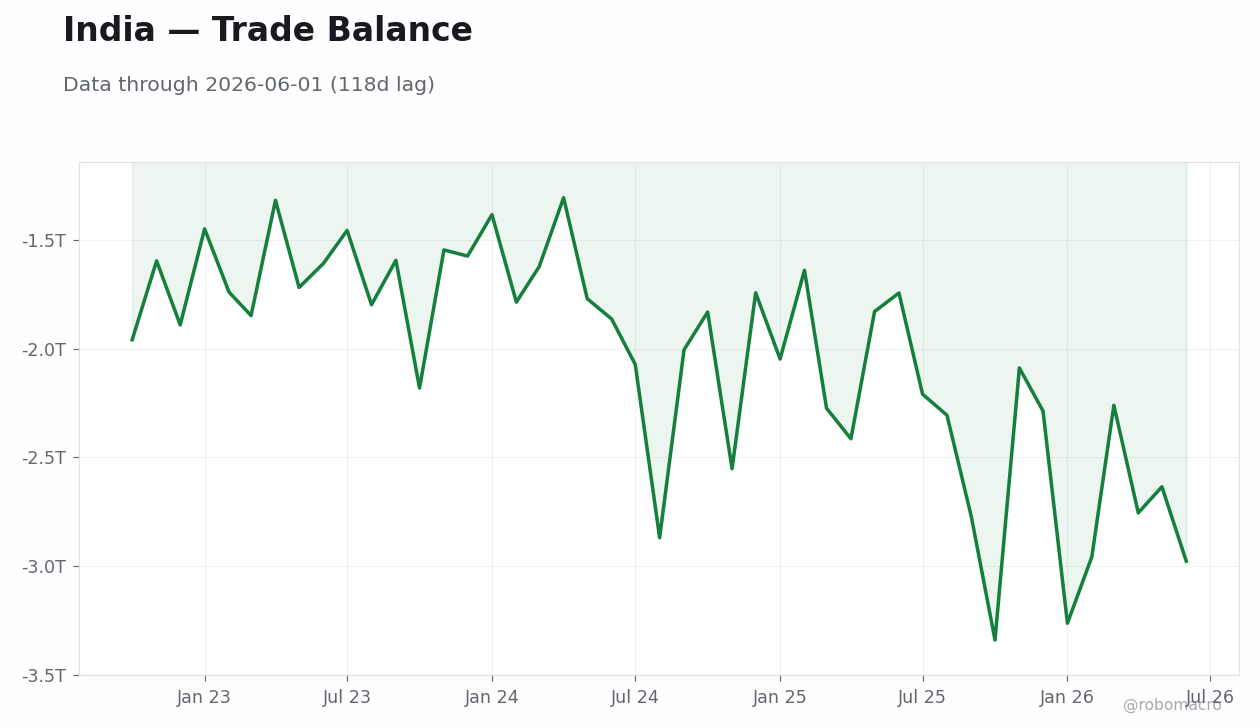
Labour Market Prints Deliver Mixed Signal Employment rose more than expected while the unemployment rate increased to a multi-year high. Full-time employment declined, underscoring uneven labour-market momentum. Markets absorbed the RBA’s inflation focus without repricing the cash-rate path lower.
PMI Flash Readings Confirm Activity Softening S&P Global Manufacturing and Services PMI Flash readings declined, consistent with the broader pattern of mixed activity signals. These outcomes reinforced the data-dependent stance at both the RBA and RBNZ. The NZX 50 posted a smaller weekly decline of 0.07 percent to 13811.11, supported by modest NZD resilience.
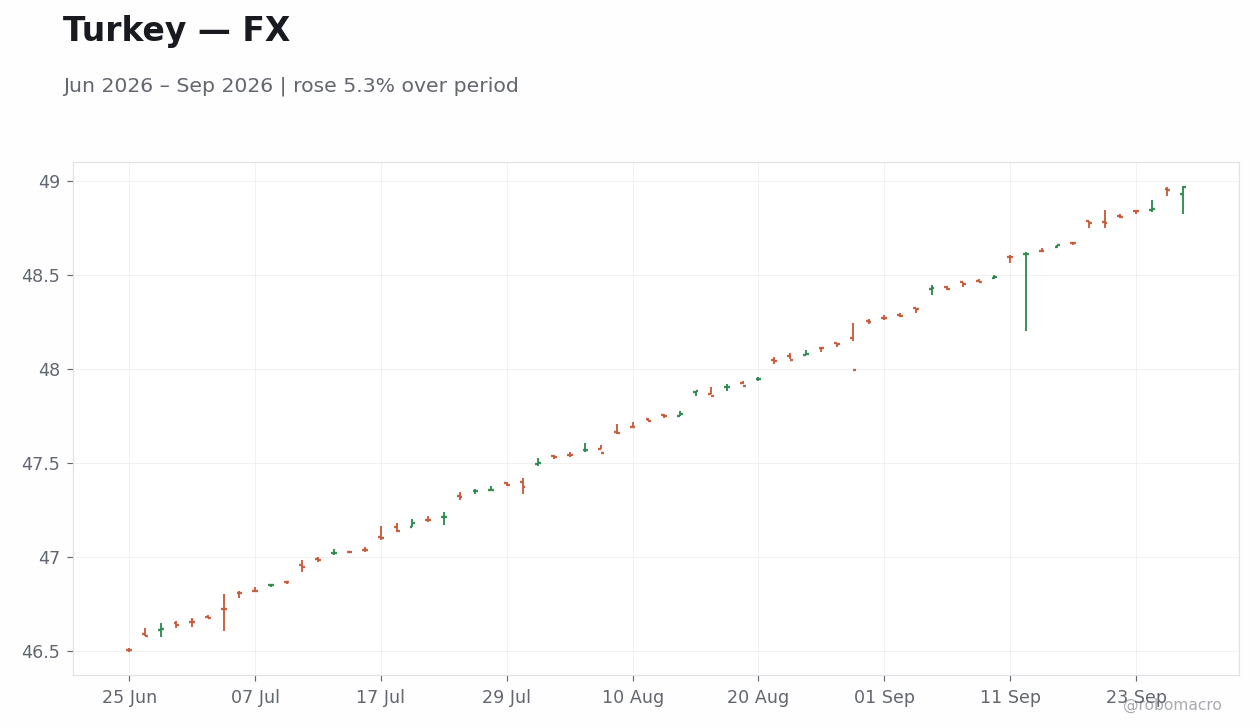
Commodity and Currency Linkages Amplify External Pressure Brent crude volatility offered limited relief to imported-inflation concerns. AUD/USD fell 1.52 percent week-over-week to 0.70 while NZD/USD declined 1.11 percent to 0.57, highlighting commodity-currency sensitivity to RBA rhetoric and global risk sentiment. BHP closed at 60.72, down 0.10 percent for the week.
RBA Governor Bullock’s remarks explicitly flagged materialising inflation risks from oil prices and shifted emphasis toward price stability over employment outcomes, leaving the cash rate unchanged with CPI still above target. Subsequent commentary reiterated a neutral stance on house prices while sustaining vigilance ahead of the next meeting. The RBNZ maintained its OCR unchanged with CPI YoY elevated, signalling gradual tightening expectations without new speeches altering the path. Australia’s September labour data, showing unemployment rising alongside employment gains, did not prompt officials to soften their inflation focus. The configuration keeps both central banks anchored to incoming prints rather than any single week’s activity or commodity move.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Mon 21 | AU | RBA Hunter Speech | - | - | - |
| Mon 21 | NZ | 1-Year Bill Auction | 3.6 | - | 3.6 |
| Mon 21 | NZ | 6-Month Treasury Bill Auct | 3.2 | - | 3.1 |
| Tue 22 | AU | S&P Global Manufacturing P | 52.0 | - | 49.3 |
| Tue 22 | AU | S&P Global Services PMI Fl | 53.2 | - | 51.4 |
| Tue 22 | AU | S&P Global Composite PMI F | 52.7 | - | 50.8 |
| Wed 23 | AU | Employment Change | -16K | 20K | 40K |
| Wed 23 | AU | Full-Time Employment Chang | 15K | - | -6300 |
| Wed 23 | AU | Headline Unemployment Rate | 4.5 | 4.5 | 4.6 |
| Wed 23 | AU | Labor Force Participation | 66.9 | 66.9 | 67.1 |
| Wed 23 | AU | Part-Time Employment Chang | -31K | - | 46K |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-29 | RBA Interest Rate Decision | 4.3 | 4.6 |
| 2026-09-29 | RBA Press Conference | - | - |
| 2026-09-29 | ANZ Business Confidence | 53.7 | - |
| 2026-09-29 | Building Permits Month-over-Month P | -3.6 | -0.90 |
| 2026-09-29 | Inflation Rate Month-over-Month | 1.0 | - |
| 2026-09-29 | Inflation Rate Year-over-Year | 3.5 | 4.1 |
| 2026-09-29 | RBA Trimmed Mean CPI Month-over-Mon | 0.50 | - |
| 2026-09-29 | RBA Trimmed Mean CPI Year-over-Year | 3.6 | - |
| 2026-09-30 | Trade Balance | 1.9bn | 2.1bn |


Monday brings Malaysia’s Producer Price Index and Finland’s Business and Consumer Confidence Indices, providing early external context for commodity and sentiment linkages to Australia. Mid-week releases include Norway Retail Sales and Sweden Trade Balance, which may influence global risk appetite and AUD/NZD flows. Later in the period, attention turns to any RBA or RBNZ speakers for further guidance on the rate path ahead of upcoming decisions. China-related trade signals remain relevant given Australia’s export exposure, while New Zealand participants will monitor dairy and tourism indicators for domestic demand clues. The absence of high-impact local data leaves global bond moves and commodity prints as the primary drivers for rate-path expectations in coming quarters. Markets will assess whether the recent unemployment increase and PMI contractions alter the balance of risks at either central bank.
The week’s combination of rising unemployment and PMI contractions below 50 raises downside growth risks that could challenge the RBA’s inflation-first stance if sustained into the next meeting. Upside inflation scenarios remain tied to Brent crude rebounds above 100, which could reinforce hawkish guidance and pressure AUD further below 0.70. The market appears to underweight the persistence of RBA rhetoric despite the higher jobless rate, leaving scope for repricing if officials continue to prioritise recent CPI outcomes. New Zealand faces parallel external risks from softer global demand, with NZD/USD at 0.57 offering limited buffer. Overall, the data-dependent equilibrium observed in prior weeks continues, with limited tolerance for further activity misses without policy recalibration.
| Asset | Level | WoW |
|---|---|---|
| Shanghai Composite | 3888.37 | -1.6% |
| Hang Seng | 24510.09 | -2.1% |
| TAIEX | 48024.6 | +0.6% |
| USD/CNY | 6.71 | +0.2% |
| USD/HKD | 7.84 | -0.0% |
| Copper | 6.77 | +1.2% |
| Brent Crude | 97.44 | -2.9% |
| Gold | 4321.2 | -1.4% |
| Bitcoin | 84530.94 | +4.2% |


Yuan management takes center stage. The PBoC guided the daily reference rate above market expectations, supporting measured stability in the yuan. USD/CNY touched a weekly low before closing at 6.71. Policy communication emphasized external demand resilience, consistent with China’s elevated share of global container exports.
Equity markets show clear regional divergence. Mainland indices posted net losses, with the Shanghai Composite declining 1.56 percent to 3,888.37. The CSI 300 also moved lower. In contrast, the TAIEX advanced 0.64 percent to 48,024.60. Hong Kong’s Hang Seng Index ended 2.13 percent lower at 24,510.09 amid mixed property and trade sentiment.
Policy signals reinforce data dependence. The HKMA adjusted its base rate to maintain the currency-board link. The PBoC signaled stepped-up counter-cyclical support and offshore liquidity operations. No high-impact data releases occurred in mainland China, Hong Kong or Taiwan.
Trade diplomacy provides incremental relief. Bilateral discussions produced a trade-truce extension and targeted tariff measures on non-sensitive goods, alongside establishment of an artificial intelligence dialogue. These outcomes eased near-term tensions without altering the economy’s external-demand orientation.
The PBoC guided the daily reference rate above market expectations while announcing offshore liquidity operations via the HKMA. The HKMA raised its base rate following the Federal Reserve decision, preserving the currency-board framework. PBoC statements emphasized stepped-up counter-cyclical support and yuan stability, with no shift in the medium-term rate path signaled. The policy configuration leaves the PBoC focused on liquidity operations and external-demand management rather than outright easing or tightening. CBC maintained its data-dependent stance with no new communications during the period. Overall, this week’s measures reinforced tolerance for gradual yuan appreciation within controlled parameters.
No macroeconomic data releases were scheduled or published for mainland China, Hong Kong or Taiwan during the week. The absence of fresh activity indicators left analysts reliant on prior external-demand signals. These prints collectively suggest the cycle remains in a mid-phase expansion where external demand offsets softer domestic momentum. The data configuration reinforces expectations that the PBoC will maintain counter-cyclical adjustments rather than broad rate shifts. With no surprises versus consensus on the calendar, the focus stayed on policy communication and bilateral trade outcomes.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Mon 21 | HK | Current Account Balance | 36.4bn | - | 96.0bn |
| Tue 22 | TW | Export Orders Year-over-Ye | 61.9 | - | 71.4 |
| Tue 22 | TW | Headline Unemployment Rate | 3.3 | - | 3.3 |
| Wed 23 | TW | Industrial Production Year | 23.9 | - | 23.5 |
| Wed 23 | TW | Retail Sales Year-over-Yea | 7.8 | - | 6.5 |
| Wed 23 | TW | M2 Money Supply Year-over- | 7.4 | - | 6.8 |
| Wed 23 | HK | Inflation Rate Month-over- | 0.20 | - | 0.10 |
| Wed 23 | HK | Inflation Rate Year-over-Y | 1.7 | - | 1.7 |
| Thu 24 | HK | Exports Year-over-Year | 50.7 | - | 53.0 |
| Thu 24 | HK | Imports Year-over-Year | 41.0 | - | 60.0 |
| Thu 24 | HK | Trade Balance | -4.9bn | - | -71.2bn |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-29 | NBS Manufacturing PMI | 49.8 | 50.1 |
| 2026-09-29 | NBS Non-Manufacturing PMI | 49.0 | 49.3 |
| 2026-09-29 | RatingDog Manufacturing PMI | 51.5 | 51.6 |
| 2026-09-29 | RatingDog Services PMI | 51.4 | 51.1 |
Markets will monitor the PBoC’s daily USD/CNY reference rate for any adjustments. HKMA preparations for new CMU products and wholesale CBDC pilots may draw commentary. Taiwan semiconductor order books will continue to reflect AI-driven demand. Property-sector sentiment in mainland China and Hong Kong will be watched for resilience. No major data releases are scheduled for the region on September 28–30. Investors will track any follow-up on trade measures and the AI dialogue framework. Cross-strait trade flows and State Council liquidity guidance remain focal points.
The week’s equity divergence signals potential positioning shifts, with mainland indices underperforming while Taiwan benefited from semiconductor strength. Yuan stability measures reduced near-term appreciation pressure but left room for further PBoC intervention if external demand weakens. Upside scenarios center on sustained trade-truce extension and AI dialogue progress, which could support copper and equity flows. Downside risks include renewed protectionism concerns and any reversal in Brent crude that could reintroduce imported inflation pressure. Market mispricing appears limited given the absence of data surprises. Overall, the data and policy mix points to a cautious stance with limited room for aggressive rate-path repricing.
Equities delivered mixed weekly results, with the Shanghai Composite closing at 3,888.37 for a 1.56 percent decline and the Hang Seng finishing at 24,510.09 after a 2.13 percent drop, while the TAIEX rose 0.64 percent to 48,024.60. FX markets saw USD/CNY advance 0.22 percent to 6.71, with USD/HKD holding steady at 7.84. Copper rose 1.19 percent to 6.77, supported by China demand proxies, while Brent crude fell 2.89 percent to 97.44 and gold declined 1.43 percent to 4,321.20. Bitcoin gained 4.18 percent to 84,530.94 amid broader risk-on flows. The configuration reflected yuan stability measures offsetting equity weakness in mainland indices.
Bilateral discussions produced a trade-truce extension and targeted tariff measures on non-sensitive goods, directly easing tensions that had weighed on regional supply chains. The agreement on an artificial intelligence dialogue acknowledged competitive dynamics without altering near-term trade flows. These developments occurred against a backdrop of Brent crude price movement that reduced imported inflation risks for the region. Broader USD strength kept USD/CNY movements contained within guided ranges. The configuration leaves Greater China exposed to any follow-through on tariff relief while global activity signals remain mixed.
| Asset | Level | WoW |
|---|---|---|
| KOSPI | 7080.92 | +1.0% |
| KOSDAQ | 844.48 | +1.0% |
| USD/KRW | 1353.42 | -2.3% |
| Samsung | 285500.0 | +4.2% |
| SK Hynix | 1862000.0 | -0.3% |
| Brent Crude | 97.44 | -2.9% |
| Gold | 4321.2 | -1.4% |
| Bitcoin | 84533.89 | +4.2% |


Equity Market Performance KOSPI advanced 1.04 percent to close at 7,080.92 while KOSDAQ gained 0.98 percent to 844.48, with gains concentrated in semiconductor names. Samsung Electronics rose 4.2 percent to 285,500 and SK Hynix posted a net 0.32 percent decline to 1,862,000 over the five sessions. The moves occurred alongside Brent crude’s 2.89 percent weekly drop to 97.44, which eased input-cost pressure on manufacturers.
Currency and Export Dynamics USD/KRW fell 2.27 percent to 1,353.42 as export strength supported the won. The Bank of Korea described the appreciation as fast but not excessive, aligning with external demand strength that underpins the current policy stance. Korea 3-year government yields eased and 10-year yields declined, producing modest curve flattening.
Sentiment and Fiscal Signals The Consumer Confidence Index rose, providing the week’s sole high-impact data point. The Asian Development Bank raised its 2026 GDP forecast, citing semiconductor-led external demand. Reports indicated South Korea’s tax windfall could rise on the chip boom, adding fiscal space without immediate spending implications.
Liquidity and Holiday Preparations The Bank of Korea supplied additional liquidity to meet seasonal demand ahead of the Chuseok holiday. Trading volumes declined sharply as investors reduced positions before the extended break. Bitcoin rose while gold declined, reflecting selective risk appetite that did not alter the broader equity-led narrative.
The Bank of Korea supplied holiday liquidity and tested a 24-hour won settlement system without altering its policy rate. Officials noted the won’s appreciation was fast but not excessive, consistent with export data that supports the current stance. The CPI reading and rate-hike cost estimate reinforced measured communication. No speeches or minutes were released during the week, leaving the data-dependent framework intact ahead of the next meeting. The ADB’s 2026 GDP upgrade and the Consumer Confidence Index rise together signal that incoming activity prints continue to anchor the rate path without prompting an immediate shift.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Tue 22 | KR | Consumer Confidence Index | 104 | - | 107 |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-28 | Business Confidence Index | 81.0 | - |
| 2026-09-30 | Exports Year-over-Year | 68.7 | - |
| 2026-09-30 | S&P Global Manufacturing PMI Index | 52.3 | - |
| 2026-10-01 | Inflation Rate Year-over-Year | 3.1 | - |
Monday opens with Malaysia’s Producer Price Index and several low-impact European confidence readings that carry limited direct read-across to Korea. Mid-week features Norway retail sales and Sweden trade balance prints whose commodity content may influence global energy prices relevant to Korean importers. No high-impact Korean releases are scheduled, so attention will center on external demand signals and any follow-up comments on the 24-hour won settlement trial. The data flow will inform whether the export surge observed this week extends into the coming period and sustains the Bank of Korea’s current policy signal. Participants will also monitor any updates on delayed payments to Korean firms and refining margin developments tied to Europe’s jet-fuel shortfall. The absence of domestic indicators leaves the next meeting’s assessment dependent on the cumulative growth and inflation prints that follow.
The tax windfall on chip exports creates fiscal headroom that could offset household pressure from elevated CPI and home prices, yet K-shaped consumption polarization remains a downside risk. Brent crude’s weekly decline eased imported inflation but reversed sharply intraday, leaving volatility as a persistent theme for net-energy importers. The won’s appreciation supports the external sector yet raises the possibility of faster policy normalization if export momentum fades in coming quarters. Market participants appear to underweight the liquidity injection’s signal that the Bank of Korea is prioritizing stability over immediate tightening, while the ADB’s GDP upgrade suggests growth resilience that could challenge any dovish tilt at upcoming decisions.
| Asset | Level | WoW |
|---|---|---|
| JCI | 6241.89 | -2.2% |
| KLCI | 1671.62 | +0.3% |
| STI | 5711.12 | +0.6% |
| USD/IDR | 17912.0 | +0.6% |
| USD/THB | 33.37 | +0.0% |
| USD/MYR | 4.07 | -0.3% |
| USD/PHP | 62.46 | -0.7% |
| USD/SGD | 1.28 | +0.1% |
| Brent Crude | 97.44 | -2.9% |
| Gold | 4321.2 | -1.4% |
| Bitcoin | 84533.89 | +4.2% |


Rupiah pressure dominates regional flows Bank Indonesia held its benchmark rate steady on September 22 after the rupiah prompted explicit intervention pledges in both forex and bond markets. The currency finished the week at 17,912, up 0.6 percent from the prior Friday close, while foreign capital inflows provided partial offset.
Equity markets diverge on limited domestic data JCI declined 2.24 percent to 6,241.89 across the week. In contrast, KLCI posted a 0.28 percent net gain to 1,671.62 and STI rose 0.63 percent to 5,711.12, supported by smaller currency moves outside Indonesia.
Commodity volatility shapes import-cost backdrop Brent crude closed the week at 97.44, a 2.89 percent weekly decline. The swings eased near-term imported inflation risks for Thailand and the Philippines while adding pressure to Indonesia’s fuel import bill.
Policy continuity signals from Jakarta Bank Indonesia confirmed household gold mobilization and signed a cross-border QR payments MoU with the Hong Kong Monetary Authority, reinforcing liquidity support measures alongside the unchanged rate. No CPI, GDP, or trade releases occurred in any of the six economies, leaving the data calendar empty for the full week.
Regional currencies show contained moves USD/THB rose 0.03 percent to 33.37, USD/MYR fell 0.27 percent to 4.07, and USD/PHP declined 0.67 percent to 62.46, illustrating limited spillover from the rupiah episode. Thailand advanced its semiconductor investment target and opened a new export facility, adding a modest positive growth note.
Bank Indonesia kept the policy rate steady on September 22 and introduced additional hedging incentives while pledging all-out efforts to stabilize the rupiah. Officials cited elevated US Treasury yields and Brent as immediate pressures and confirmed that household gold would support reserves. No other central bank among BoT, BNM, BSP, MAS, or SBV held meetings or released minutes during the week. The data-light environment and absence of inflation or growth prints left the policy signal unchanged, with BI’s intervention tools now positioned as the primary defense mechanism ahead of the next decision.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Mon 21 | SG | Unemployment Rate Final | 2.0 | 2.0 | 1.9 |
| Tue 22 | SG | MAS 12-Week Bill Auction | 1.7 | - | 1.8 |
| Tue 22 | SG | MAS 4-Week Bill Auction | 1.7 | - | 1.7 |
| Wed 23 | SG | Core Inflation Rate Year-o | 2.0 | 2.2 | 2.2 |
| Wed 23 | SG | Inflation Rate Month-over- | -0.20 | - | 0.60 |
| Wed 23 | SG | Inflation Rate Year-over-Y | 2.2 | 2.3 | 2.3 |
| Wed 23 | ID | Loan Growth Year-over-Year | 13.6 | - | 13.4 |
| Wed 23 | ID | Central Bank Interest Rate | 5.8 | 5.8 | 5.8 |
| Wed 23 | ID | Deposit Facility Rate | 4.8 | 4.8 | 4.8 |
| Wed 23 | ID | Lending Facility Rate | 6.5 | 6.5 | 6.5 |
| Wed 23 | ID | M2 Money Supply Year-over- | 8.3 | - | - |
| Thu 24 | ID | M2 Money Supply Year-over- | 8.3 | - | 8.2 |
| Thu 24 | SG | 6-Month T-Bill Auction | 1.7 | - | 1.9 |
| Thu 24 | PH | Government Budget Balance | -106.3bn | - | -161.3bn |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-10-01 | Inflation Rate Year-over-Year | 3.2 | - |
| 2026-10-01 | Trade Balance | 130.0mn | - |

Malaysia’s Producer Price Index year-over-year is scheduled for September 28 with no consensus provided. Singapore will conduct a 15-year bond auction on the same day. No high-impact releases or central-bank meetings are listed for Indonesia, Thailand, Philippines, or Vietnam through October 2. The next Bank Indonesia decision remains the key domestic anchor for the rupiah path, while BoT, BNM, BSP, MAS, and SBV continue to operate in a data-dependent mode without scheduled communications. Thin domestic calendars will keep attention on external drivers including Brent crude and US yields.
Persistent rupiah weakness near 17,912 raises the possibility that Bank Indonesia may need to deploy further non-rate tools or reconsider the policy setting if outflows accelerate. Oil volatility continues to swing imported inflation risks for net importers without altering the broader growth trajectory. JCI’s 2.24 percent weekly decline contrasts with gains in KLCI and STI, highlighting uneven capital allocation across ASEAN. The absence of fresh activity or price data leaves the region exposed to external shocks until the next round of inflation or trade prints arrives.
| Asset | Level | WoW |
|---|---|---|
| Nifty 50 | 23140.5 | -1.2% |
| Sensex | 73895.74 | -1.3% |
| USD/INR | 95.8 | -0.2% |
| EUR/INR | 109.03 | -0.9% |
| Reliance | 1226.0 | -1.7% |
| HDFC Bank | 735.6 | -0.5% |
| Brent Crude | 97.44 | -2.9% |
| Gold | 4321.2 | -1.4% |
| Bitcoin | 84533.89 | +4.2% |


PMI prints lift activity signals. The HSBC Composite PMI Flash rose from the prior reading, while manufacturing and services both advanced, confirming firmer momentum across both sectors. These outcomes exceeded the previous prints and aligned with S&P’s upgrade of its FY27 growth forecast, citing resilient domestic demand.
Equity and currency tape mixed. Nifty 50 ended the week at 23140.5 after a 1.17 percent decline, while Sensex closed at 73895.74 for a 1.29 percent drop. USD/INR finished at 95.8 after a 0.22 percent weekly decline.
Liquidity management and reserves. The RBI absorbed liquidity through a variable rate reverse repo auction to drain surplus liquidity, following record forex swaps the prior week. Forex reserves declined, yet the central bank’s interventions helped stabilise the currency alongside Brent crude’s 2.89 percent weekly decline to 97.44.
External sector resilience. Software services exports expanded, with the United States accounting for the majority of the total. The India-New Zealand free-trade agreement, effective 20 October, targets a doubling of bilateral goods and services trade by 2030.
Policy expectations steady. Markets absorbed RBI Deputy Governor Poonam Gupta’s remarks that inflation should stay inside the target band despite shocks and that the rupee has scope to appreciate on balance-of-payments strength. The short-term policy rate remained unchanged with no fresh guidance issued during the week.
RBI Deputy Governor Poonam Gupta stated that inflation is likely to remain within the target band despite shocks and that the rupee has a fair case to stabilise and appreciate given underlying balance-of-payments resilience. The central bank conducted a variable rate reverse repo auction to manage surplus liquidity after earlier record forex swaps. Forex reserves declined, yet the combination of dollar sales and liquidity drainage supported the rupee’s 0.22 percent weekly decline to 95.8. These operations occurred against the backdrop of stronger PMI prints that reinforced the view of contained price pressures. No MPC member speeches or policy rate adjustments were scheduled, leaving the short-term rate unchanged and the data-dependent stance intact.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Mon 21 | IN | Infrastructure Output Year | 5.4 | - | 4.8 |
| Wed 23 | IN | HSBC Composite PMI Flash | 54.3 | - | 56.5 |
| Wed 23 | IN | HSBC Manufacturing PMI Fla | 52.8 | - | 55.7 |
| Wed 23 | IN | HSBC Services PMI Flash | 54.1 | - | 55.8 |
| Fri 25 | IN | Foreign Exchange Reserves | 780.8bn | - | 765.9bn |
| Fri 25 | IN | M3 Money Supply Year-over- | 16.7 | - | - |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-28 | Industrial Production Year-over-Yea | 6.7 | 6.0 |
| 2026-09-28 | Manufacturing Production Year-over- | 7.3 | - |

The coming week features limited India-specific releases, with attention centred on follow-through from the HSBC PMI prints and any updates on private capex estimates for 2026-27. Traders will monitor rupee movements amid external signals, including potential US-Iran developments and global bond yield shifts. RBI liquidity management via VRRR auctions is expected to continue as the central bank addresses surplus conditions. The India-Mexico trade pact talks are slated to finalise terms of reference in early October, which could influence external sector flows. Comments from RBI officials on balance-of-payments strength and rupee valuation will be watched for any incremental guidance ahead of upcoming decisions. Broader sentiment will hinge on whether the recent PMI momentum sustains into final September readings and how that data informs the Reserve Bank of India’s assessment of growth and inflation in coming quarters.
The week’s stronger PMI outcomes and upgraded growth forecasts shift the domestic outlook toward resilience, yet the 1.17 percent Nifty 50 decline and 1.29 percent Sensex drop highlight sensitivity to global equity flows. Brent crude’s 2.89 percent weekly decline to 97.44 eased imported inflation pressure, but any reversal could test the RBI’s inflation-band assessment. Forex reserve drawdowns underscore the cost of currency stabilisation, while persistent liquidity absorption via VRRR operations signals ongoing management challenges. Upside risks centre on sustained PMI strength and software export gains supporting the rupee’s appreciation case; downside scenarios include renewed oil volatility or external yield spikes pressuring USD/INR. The market appears to underweight the balance-of-payments resilience cited by Deputy Governor Gupta relative to the data flow.
| Asset | Level | WoW |
|---|---|---|
| BIST 100 | 12899.4 | -3.3% |
| USD/TRY | 48.97 | +0.4% |
| EUR/TRY | 55.72 | -0.5% |
| GBP/TRY | 64.81 | -0.7% |
| Gold (TRY) | 4321.2 | -1.4% |
| Brent Crude | 97.44 | -2.9% |
| EUR/USD | 1.14 | -0.9% |
| Bitcoin | 84532.19 | +4.2% |


Equity and fund-market pressure dominated the tape. The BIST 100 posted a net 3.29 percent decline to 12,899.40. USD/TRY edged 0.41 percent higher to 48.97 over the same five-day window, while EUR/TRY finished 0.45 percent lower at 55.72.
Activity indicators showed mixed results. Capacity Utilization Rate printed at 74.2 on September 21, up from the prior 73.5 reading. Business Confidence Index declined to 102.0 from 102.8 on the same date.
Commodity and external factors provided limited relief. Brent Crude declined 2.89 percent to 97.44, easing some imported-cost pressure for the week. Gold priced in TRY fell 1.43 percent to 4,321.20.
Policy continuity remained the dominant market assumption. The absence of any Central Bank of the Republic of Turkey communication kept focus squarely on the data flow rather than forward guidance shifts.
Cross-asset performance reflected selective resilience. Bitcoin rose 4.18 percent to 84,532.19 while EUR/USD slipped 0.86 percent to 1.14, illustrating that local equity and currency moves were driven more by domestic concerns than by broad external risk sentiment.
No Central Bank of the Republic of Turkey speakers or minutes were released during the week. The latest Capacity Utilization Rate increase to 74.2 and Business Confidence Index decline to 102.0 together point to a still-resilient domestic demand backdrop that does not yet require an immediate policy adjustment. With no new forward guidance issued, the data-dependent stance observed in prior weeks continues to govern expectations for the timing of any upcoming decisions. The combination of stable or slightly firmer activity prints and contained currency volatility supports the view that officials will maintain the current policy rate setting into the next meeting cycle.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Mon 21 | TR | Business Confidence Index | 103 | - | 102 |
| Mon 21 | TR | Capacity Utilization Rate | 73.5 | - | 74.2 |
| Mon 21 | TR | Central Government Debt | 15471.0bn | - | 15894.0bn |
| Tue 22 | TR | Consumer Confidence Index | 90.8 | - | 91.9 |
| Thu 24 | TR | Foreign Exchange Reserves | 68.4bn | - | 62.8bn |
| Fri 25 | TR | Tourist Arrivals Year-over | -0.30 | - | -0.03 |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-09-30 | Balance of Trade Final | -7.3bn | -5.2bn |
| 2026-09-30 | Headline Unemployment Rate | 8.1 | - |


The coming week begins with limited high-impact Turkish releases, shifting attention to external data that could influence imported inflation and growth expectations. Malaysia’s Producer Price Index and Nordic retail and trade figures on Monday will provide early signals on global cost pressures that feed into Turkey’s import bill. Mid-week euro-area and US activity prints will help frame the broader growth backdrop ahead of the Central Bank of the Republic of Turkey’s upcoming decision. Any further clarity on the fund-industry situation will be watched for its potential effect on domestic liquidity and credit conditions. Officials’ comments, if any, will be parsed for confirmation that the policy rate path remains tied to the incoming inflation and activity sequence rather than to short-term market volatility. The overall data flow should reinforce the data-dependent equilibrium that has prevailed through recent quarters.
Fund-industry pressure continues to widen the performance gap between large-cap and small-cap equities, raising the possibility of further liquidity strains if outflows accelerate. A sustained rebound in Brent Crude from the 97.44 level could reintroduce imported inflation risks and test the Central Bank of the Republic of Turkey’s tolerance for currency volatility. Conversely, continued improvement in Capacity Utilization Rate would support a more benign growth-inflation configuration. The market appears to be pricing limited near-term policy reaction, yet any escalation in the fund crisis could force a reassessment of fiscal and regulatory support measures that have so far contained broader spillovers.
| Asset | Level | WoW |
|---|---|---|
| Saudi Aramco | 25.78 | -0.5% |
| MSCI Saudi | 37.05 | -0.3% |
| MSCI UAE | 20.24 | +0.9% |
| MSCI Qatar | 16.75 | -0.8% |
| MSCI Kuwait | 36.8 | -0.5% |
| Brent Crude | 97.44 | -2.9% |
| WTI Crude | 92.41 | -3.5% |
| Gold | 4321.2 | -1.4% |
| USD/SAR | 3.75 | +3.1% |
| USD/AED | 3.67 | +0.0% |
| USD/KWD | 0.31 | -0.0% |
| Bitcoin | 84532.2 | +4.2% |


Geopolitical tensions drive oil volatility. Houthi threats prompted Brent crude to decline before partial recovery, while Saudi Aramco ended the week at 25.78. The East-West pipeline restart allowed Aramco to resume Yanbu exports, easing supply concerns.
Equity markets show limited reaction. MSCI UAE advanced 0.9 percent to 20.24, while MSCI Qatar declined 0.8 percent to 16.75 and MSCI Kuwait fell 0.51 percent to 36.80. MSCI Saudi closed at 37.05. Saudi Aramco traded in a narrow range, reflecting contained equity moves despite the oil decline.
Non-oil diversification metrics improve. Non-oil expansion continued alongside overall GDP growth, with Saudi digital economy reaching nearly 16 percent of GDP and the UAE leading the Arab Digital Economy Index.
Data calendar remains quiet. No PMI, CPI, or trade releases occurred in Saudi Arabia, UAE, Qatar, Kuwait, Oman, or Bahrain during the week, leaving the growth narrative anchored to prior forecasts rather than fresh prints. Foreign business registrations rose, broadening the investor base without immediate volume spikes in equity trading.
Pipeline and security developments provide offset. France signaled readiness to help secure Saudi energy infrastructure at Yanbu, and US commitments were reaffirmed, reducing near-term disruption risks after the pipeline restart. USD/SAR held at 3.75 while USD/AED held at 3.67, consistent with peg mechanics.
GCC central banks kept policy rates unchanged throughout the week, with no speakers, minutes, or decisions released. The absence of domestic inflation or activity data left rate settings aligned with external anchors, extending the data-dependent stance observed since late August. Saudi non-oil growth estimates reinforced the view that diversification reduces sensitivity to single-week commodity moves. Officials focused on navigation security statements at the UN General Assembly rather than monetary signals. The pipeline restart and infrastructure protection commitments supported fiscal resilience without prompting any adjustment to current policy parameters.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Tue 22 | SA | Construction Cost Index | 104 | - | 104 |
| Thu 24 | SA | Exports Level | 88.1bn | - | 84.4bn |
| Thu 24 | SA | Imports Level | 71.5bn | - | 70.0bn |
| Thu 24 | SA | Trade Balance | 16.6bn | - | 14.4bn |

No high-impact releases are scheduled for Saudi Arabia, UAE, or Qatar in the coming sessions. Attention will center on OPEC+ compliance updates and any follow-through from the East-West pipeline operations. Broader global data, including US labor and inflation prints, will influence the external rate environment that mechanically guides GCC policy through currency pegs. Qatar LNG capacity timelines and regional navigation security discussions may generate additional commentary. Investors will monitor Aramco export volumes for signs of sustained flexibility after the Hormuz bypass. The next central bank meetings remain data-dependent, with incoming activity and price prints determining whether current settings are maintained into coming quarters. Geopolitical developments along the Red Sea will continue to shape near-term risk sentiment across the region.
Houthi threats and the subsequent pipeline restart highlight persistent supply-route vulnerabilities that could reprice regional risk premia if tensions escalate. Brent’s 2.89 percent weekly decline to 97.44 eased immediate imported inflation pressure yet left energy-exposed fiscal balances exposed to further downside. Mixed equity performance, with MSCI UAE gaining while MSCI Qatar and Kuwait declined, suggests selective investor focus on diversification progress rather than uniform commodity beta. The lack of fresh domestic data leaves the outlook reliant on prior forecasts, creating scope for revisions if non-oil momentum softens. Upside scenarios center on sustained pipeline operations and continued foreign business inflows, while downside risks stem from renewed Red Sea disruptions that could challenge the current policy-rate equilibrium.
| Time | Country | Event | Our Est. | Consensus | Prior | Impact |
|---|---|---|---|---|---|---|
| MONDAY, SEPTEMBER 28 | ||||||
| 06:00 | 🇬🇧 | BoE Ramsden Speech CB | — | — | — | ●●● |
| 06:30 | 🇮🇳 | Industrial Production Year-over-Year | — | 6 | 6.7 | ●●○ |
| 06:30 | 🇮🇳 | Manufacturing Production Year-over-Year | — | — | 7.3 | ●●○ |
| 08:00 | 🇲🇽 | Trade Balance | — | — | -848.0M | ●●○ |
| 10:30 | 🇺🇸 | Dallas Fed Manufacturing Index | — | — | 11.6 | ●●○ |
| 13:30 | 🇺🇸 | Speech by Fed's Barkin | — | — | — | ●●○ |
| 17:00 | 🇰🇷 | Business Confidence Index | — | — | 81 | ●●○ |
| TUESDAY, SEPTEMBER 29 | ||||||
| 00:30 | 🇦🇺 | RBA Interest Rate Decision CB | — | 4.6 | 4.3 | ●●● |
| 01:30 | 🇦🇺 | RBA Press Conference CB | — | — | — | ●●● |
| 03:00 | 🇪🇸 | Inflation Rate Month-over-Month Preliminary | — | — | 0.70 | ●●○ |
| 03:00 | 🇪🇸 | Inflation Rate Year-over-Year Preliminary | — | 4.7 | 4.3 | ●●○ |
| 03:00 | 🇨🇭 | KOF Leading Indicators | — | 105.8 | 106.7 | ●●○ |
| 04:30 | 🇬🇧 | BoE Consumer Credit | — | — | 2.0B | ●●○ |
| 04:30 | 🇬🇧 | Mortgage Approvals | — | 58,000 | 56,050 | ●●○ |
| 04:30 | 🇬🇧 | Mortgage Lending Level | — | — | 4.3B | ●●○ |
| 06:00 | 🇫🇷 | Unemployment Benefit Claims | — | — | 21,500 | ●●○ |
| 06:00 | 🇪🇸 | Business Confidence Index | — | — | -3.9 | ●●○ |
| 08:00 | 🇧🇷 | Headline Unemployment Rate | — | — | 5.3 | ●●○ |
| 08:30 | 🇨🇦 | GDP Month-over-Month | — | 0 | 0.30 | ●●○ |
| 08:30 | 🇨🇦 | GDP Month-over-Month Prel | — | — | — | ●●○ |
| 09:00 | 🇺🇸 | S&P/Case-Shiller Home Price Year-over-Year | — | 2.2 | 2.1 | ●●○ |
| 10:00 | 🇺🇸 | JOLTs Job Openings | — | 7.2M | 7.3M | ●●● |
| 10:00 | 🇺🇸 | Cb Consumer Confidence | — | — | 89.4 | ●●○ |
| 11:30 | 🇬🇧 | BoE Taylor Speech CB | — | — | — | ●●● |
| 13:00 | 🇺🇸 | Fed Goolsbee Speech CB | — | — | — | ●●● |
| 13:30 | 🇺🇸 | Speech by Fed's Musalem | — | — | — | ●●○ |
| 14:00 | 🇺🇸 | Speech by Fed's Williams | — | — | — | ●●○ |
| 16:30 | 🇺🇸 | API Weekly Crude Oil Stocks | — | — | 1.8M | ●●○ |
| 19:50 | 🇯🇵 | Industrial Production Month-over-Month Preliminary | — | 1.7 | -0.20 | ●●○ |
| 19:50 | 🇯🇵 | Retail Sales Year-over-Year | — | 3.3 | 4 | ●●○ |
| 20:00 | 🇳🇿 | ANZ Business Confidence | — | — | 53.7 | ●●○ |
| 21:30 | 🇦🇺 | Building Permits Month-over-Month Prel | — | -0.90 | -3.6 | ●●○ |
| 21:30 | 🇦🇺 | Inflation Rate Month-over-Month | — | — | 1 | ●●○ |
| 21:30 | 🇦🇺 | Inflation Rate Year-over-Year | — | 4.1 | 3.5 | ●●○ |
| 21:30 | 🇦🇺 | RBA Trimmed Mean CPI Month-over-Month | — | — | 0.50 | ●●○ |
| 21:30 | 🇦🇺 | RBA Trimmed Mean CPI Year-over-Year | — | — | 3.6 | ●●○ |
| 21:30 | 🇨🇳 | NBS Manufacturing PMI | — | 50.1 | 49.8 | ●●● |
| 21:30 | 🇨🇳 | NBS Non-Manufacturing PMI | — | 49.3 | 49 | ●●○ |
| 21:45 | 🇨🇳 | RatingDog Manufacturing PMI | — | 51.6 | 51.5 | ●●● |
| 21:45 | 🇨🇳 | RatingDog Services PMI | — | 51.1 | 51.4 | ●●○ |
| WEDNESDAY, SEPTEMBER 30 | ||||||
| 01:00 | 🇯🇵 | Housing Starts Year-over-Year | — | 7 | 8.2 | ●●○ |
| 02:00 | 🇩🇪 | Retail Sales Month-over-Month | — | 1.4 | -3.4 | ●●○ |
| 02:00 | 🇩🇪 | Retail Sales Year-over-Year | — | — | -2.5 | ●●○ |
| 02:00 | 🇬🇧 | Current Account Balance | — | -25.6B | -22.1B | ●●○ |
| 02:00 | 🇬🇧 | Nationwide Housing Prices Month-over-Month | — | 0.20 | 0.20 | ●●○ |
| 02:00 | 🇬🇧 | Nationwide Housing Prices Year-over-Year | — | — | 1.6 | ●●○ |
| 02:45 | 🇫🇷 | Inflation Rate Year-over-Year Preliminary | — | — | 2.4 | ●●● |
| 02:45 | 🇫🇷 | Inflation Rate Month-over-Month Preliminary | — | -0.50 | 0.70 | ●●○ |
| 03:00 | 🇹🇷 | Balance of Trade Final | — | -5.2B | -7.3B | ●●○ |
| 03:00 | 🇹🇷 | Headline Unemployment Rate | — | — | 8.1 | ●●○ |
| 03:30 | 🇵🇱 | Inflation Rate Year-over-Year Preliminary | — | 3.6 | 3.4 | ●●○ |
| 03:55 | 🇩🇪 | Headline Unemployment Rate | — | 6.4 | 6.4 | ●●○ |
| 03:55 | 🇩🇪 | Unemployed Persons Level | — | — | 3.0M | ●●○ |
| 03:55 | 🇩🇪 | Unemployment Level Change | — | 2,000 | 4,000 | ●●○ |
| 04:00 | 🇮🇹 | Business Confidence Index | — | — | 89.9 | ●●○ |
| 04:00 | 🇮🇹 | Consumer Confidence Index | — | — | 94.5 | ●●○ |
| 05:00 | 🇮🇹 | Inflation Rate Year-over-Year Preliminary | — | — | 3.3 | ●●● |
| 05:00 | 🇮🇹 | Inflation Rate Month-over-Month Preliminary | — | 0 | 0.50 | ●●○ |
| 07:00 | 🇺🇸 | MBA 30-Year Mortgage Rate | — | — | 7.1 | ●●○ |
| 08:00 | 🇩🇪 | Inflation Rate Year-over-Year Preliminary | — | — | 2.9 | ●●● |
| 08:00 | 🇩🇪 | Inflation Rate Month-over-Month Preliminary | — | 0.50 | 0.20 | ●●○ |
| 08:00 | 🇿🇦 | Trade Balance | — | — | 20.1B | ●●○ |
| 08:15 | 🇺🇸 | ADP Employment Change | — | 70,000 | 38,000 | ●●○ |
| 08:30 | 🇺🇸 | Core PCE Price Index Month-over-Month | — | 0.30 | 0.20 | ●●● |
| 08:30 | 🇺🇸 | GDP Growth Quarter-over-Quarter Final Estimate | — | 1.6 | 2.1 | ●●● |
| 08:30 | 🇺🇸 | Personal Income Month-over-Month | — | 0.40 | 0.40 | ●●● |
| 08:30 | 🇺🇸 | Personal Spending Month-over-Month | — | 0.80 | 0.20 | ●●● |
| 08:30 | 🇺🇸 | GDP Price Index Quarter-over-Quarter Final | — | — | 3.6 | ●●○ |
| 08:30 | 🇺🇸 | Goods Trade Balance Adv | — | -108.5B | -118.8B | ●●○ |
| 08:30 | 🇺🇸 | PCE Price Index Month-over-Month | — | 0.40 | 0.20 | ●●○ |
| 08:30 | 🇺🇸 | PCE Price Index Year-over-Year | — | — | 3.7 | ●●○ |
| 08:30 | 🇺🇸 | Retail Inventories Ex Autos Month-over-Month Adv | — | — | 0.80 | ●●○ |
| 08:30 | 🇺🇸 | Wholesale Inventories Month-over-Month Adv | — | 1.1 | 1.3 | ●●○ |
| 09:45 | 🇺🇸 | Chicago PMI | — | 51.3 | 47.1 | ●●○ |
| 10:30 | 🇺🇸 | EIA Weekly Crude Oil Inventory | — | — | 3.0M | ●●○ |
| 10:30 | 🇺🇸 | EIA Weekly Gasoline Inventory | — | — | -1.7M | ●●○ |
| 12:00 | 🇷🇺 | Headline Unemployment Rate | — | 2.2 | 2.3 | ●●○ |
| 13:30 | 🇺🇸 | Speech by Fed's Barkin | — | — | — | ●●○ |
| 14:00 | 🇨🇴 | Central Bank Interest Rate Decision CB | — | 12 | 12 | ●●● |
| 17:10 | 🇺🇸 | Fed Goolsbee Speech CB | — | — | — | ●●● |
| 18:00 | 🇺🇸 | Speech by Fed's Kashkari | — | — | — | ●●○ |
| 19:50 | 🇯🇵 | Tankan Large Manufacturers Index | — | 25 | 22 | ●●● |
| 19:50 | 🇯🇵 | BoJ Summary of Opinions | — | — | — | ●●○ |
| 20:00 | 🇰🇷 | Exports Year-over-Year | — | — | 68.7 | ●●○ |
| 20:30 | 🇰🇷 | S&P Global Manufacturing PMI Index | — | — | 52.3 | ●●○ |
| 21:30 | 🇦🇺 | Trade Balance | — | 2.1B | 1.9B | ●●● |
| Time | Country | Event | Our Est. | Consensus | Prior | Impact |
|---|---|---|---|---|---|---|
| THURSDAY, OCTOBER 1 | ||||||
| 00:00 | 🇮🇩 | Inflation Rate Year-over-Year | — | — | 3.2 | ●●○ |
| 00:00 | 🇮🇩 | Trade Balance | — | — | 130.0M | ●●○ |
| 02:00 | 🇷🇺 | S&P Global Manufacturing PMI Index | — | — | 48.8 | ●●○ |
| 02:30 | 🇨🇭 | Inflation Rate Year-over-Year | — | — | 0.80 | ●●○ |
| 02:30 | 🇨🇭 | Retail Sales Year-over-Year | — | 2.2 | 2.3 | ●●○ |
| 03:15 | 🇪🇸 | S&P Global Manufacturing PMI Index | — | 50.2 | 49.5 | ●●○ |
| 03:30 | 🇨🇭 | procure.ch Manufacturing PMI | — | 56 | 57.1 | ●●○ |
| 03:45 | 🇮🇹 | S&P Global Manufacturing PMI Index | — | 49.9 | 49.6 | ●●○ |
| 04:00 | 🇮🇹 | Headline Unemployment Rate | — | 5.7 | 5.8 | ●●○ |
| 08:00 | 🇲🇽 | Business Confidence Index | — | — | 48.1 | ●●○ |
| 08:00 | 🇬🇧 | BoE Mann Speech CB | — | — | — | ●●● |
| 08:30 | 🇺🇸 | Weekly Jobless Claims | — | 199,000 | 197,000 | ●●○ |
| 09:05 | 🇺🇸 | Speech by Fed's Barkin | — | — | — | ●●○ |
| 09:05 | 🇺🇸 | Speech by Fed's Collins | — | — | — | ●●○ |
| 09:05 | 🇺🇸 | Speech by Fed's Schmid | — | — | — | ●●○ |
| 09:10 | 🇬🇧 | BoE Mills Speech CB | — | — | — | ●●● |
| 09:30 | 🇨🇦 | S&P Global Manufacturing PMI Index | — | — | 53 | ●●○ |
| 10:00 | 🇺🇸 | ISM Manufacturing PMI | — | 54.8 | 54.6 | ●●● |
| 10:00 | 🇺🇸 | ISM Manufacturing Employment | — | — | 51.2 | ●●○ |
| 15:30 | 🇺🇸 | Speech by Fed's Williams | — | — | — | ●●○ |
| 18:45 | 🇺🇸 | Speech by Fed's Logan | — | — | — | ●●○ |
| 19:00 | 🇰🇷 | Inflation Rate Year-over-Year | — | — | 3.1 | ●●○ |
| 19:30 | 🇯🇵 | Headline Unemployment Rate | — | 2.4 | 2.4 | ●●○ |
| FRIDAY, OCTOBER 2 | ||||||
| 00:30 | 🇳🇱 | Inflation Rate Year-over-Year Preliminary | — | — | 3.3 | ●●○ |
| 03:00 | 🇪🇸 | Unemployment Level Change | — | 17,600 | 44,419 | ●●○ |
| 04:00 | 🇮🇹 | Retail Sales Month-over-Month | — | -0.10 | -0.40 | ●●○ |
| 08:00 | 🇧🇷 | Industrial Production Month-over-Month | — | — | 0.20 | ●●○ |
| 08:30 | 🇺🇸 | Headline Unemployment Rate | 4.1% M | 4.2 | 4.1 | ●●● |
| 08:30 | 🇺🇸 | Payroll Jobs Growth | — | 100,000 | 162,000 | ●●● |
| 08:30 | 🇺🇸 | Annual Wage Growth | — | — | 3.1 | ●●○ |
| 08:30 | 🇺🇸 | Labor Force Participation | — | — | 61.6 | ●●○ |
| 08:30 | 🇺🇸 | Monthly Wage Growth | — | 0.30 | 0.30 | ●●○ |
| 10:00 | 🇺🇸 | Factory Orders Month-over-Month | — | -0.10 | 0.90 | ●●○ |
| 10:00 | 🇺🇸 | Speech by Fed's Logan | — | — | — | ●●○ |
AI-Generated Content: This publication is 100% generated by artificial intelligence systems and should not be considered as financial advice, investment recommendation, or professional research. All analysis, forecasts, and commentary are algorithmically produced.
Data Sources: Market data from public exchange and market-data providers. US Treasury yields from the Federal Reserve (FRED constant-maturity series). Macroeconomic data from central banks and national statistics offices. Economic calendar data from RoboMacro Economic Calendar. All data subject to revision and may be delayed.
No Warranty: RoboMacro makes no warranty, express or implied, regarding the accuracy, completeness, or reliability of the information contained in this publication. Data may be delayed, incomplete, or contain errors. Past performance is not indicative of future results.
Not Financial Advice: Nothing in this publication constitutes investment advice, tax advice, legal advice, or any other form of professional advice. Any opinions expressed are AI-generated and do not represent the views of any individual or organisation. Readers should consult qualified professionals before making investment decisions.
Nowcasts and Model Output: The US labour nowcast is the median of a ten-model ensemble. Activity indices are composite z-scores of weekly public high-frequency indicators, seasonally adjusted, published only for weeks meeting a minimum indicator-coverage threshold; the as-of date and coverage are shown on every row. All model output carries significant uncertainty.
Contact: [email protected] | robomacro.com
Publication: Global Macro Watch is published weekly on Sundays, covering the preceding Monday-to-Friday week. © 2026 RoboMacro. All rights reserved.