Published every Sunday afternoon 100% AI-generated — not financial advice
Policy Divergence Defines Mid-Cycle Stance
Central-bank divergence now sets the dominant tone for global policy. On 5–9 October 2026 the tape registered 13.49 on the divergence metric, confirming the theme has not cooled. The Federal Reserve maintained its data-dependent stance after September labor-market data showed softening. ECB speakers including Philip Lane and Olli Rehn reiterated the same approach around the 2.50 percent deposit rate. Bank of Japan Governor Ueda delivered no fresh signals on 6 October. Bank of England Governor Bailey and Deputy Governor Greene instead highlighted embedded inflation pressures. These contrasting signals leave rate paths apart even as the global cycle remains in its mid-phase.
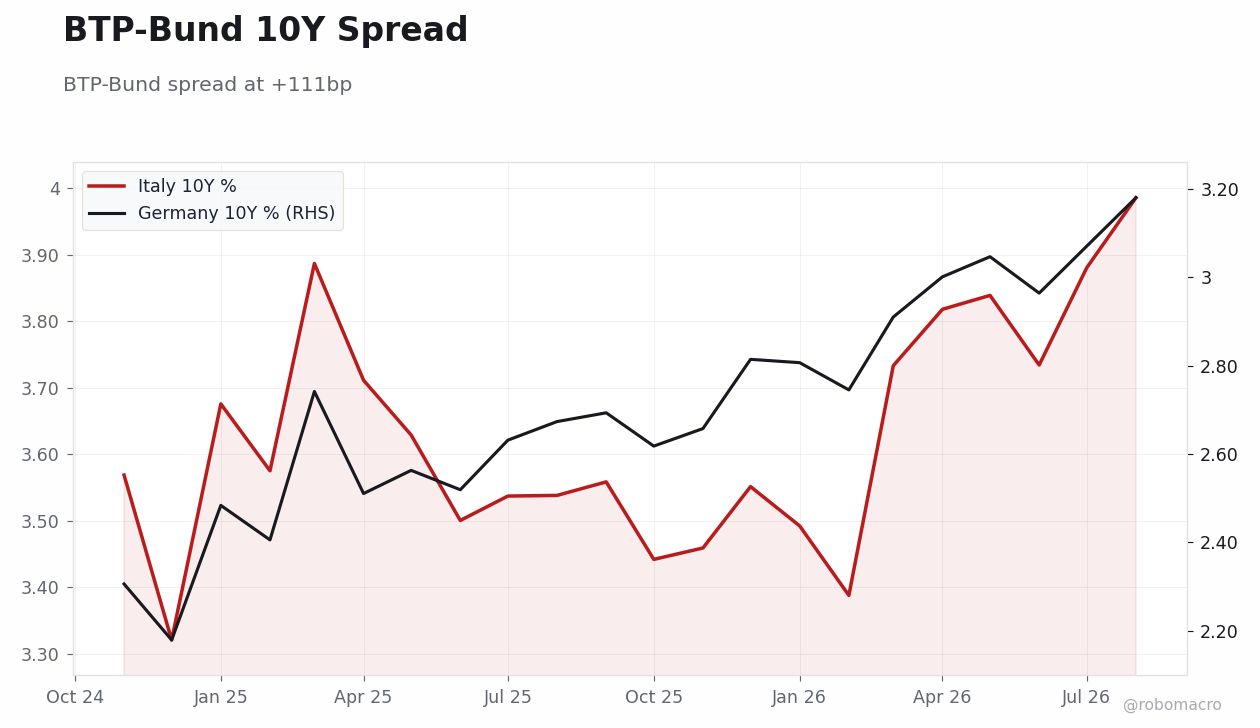
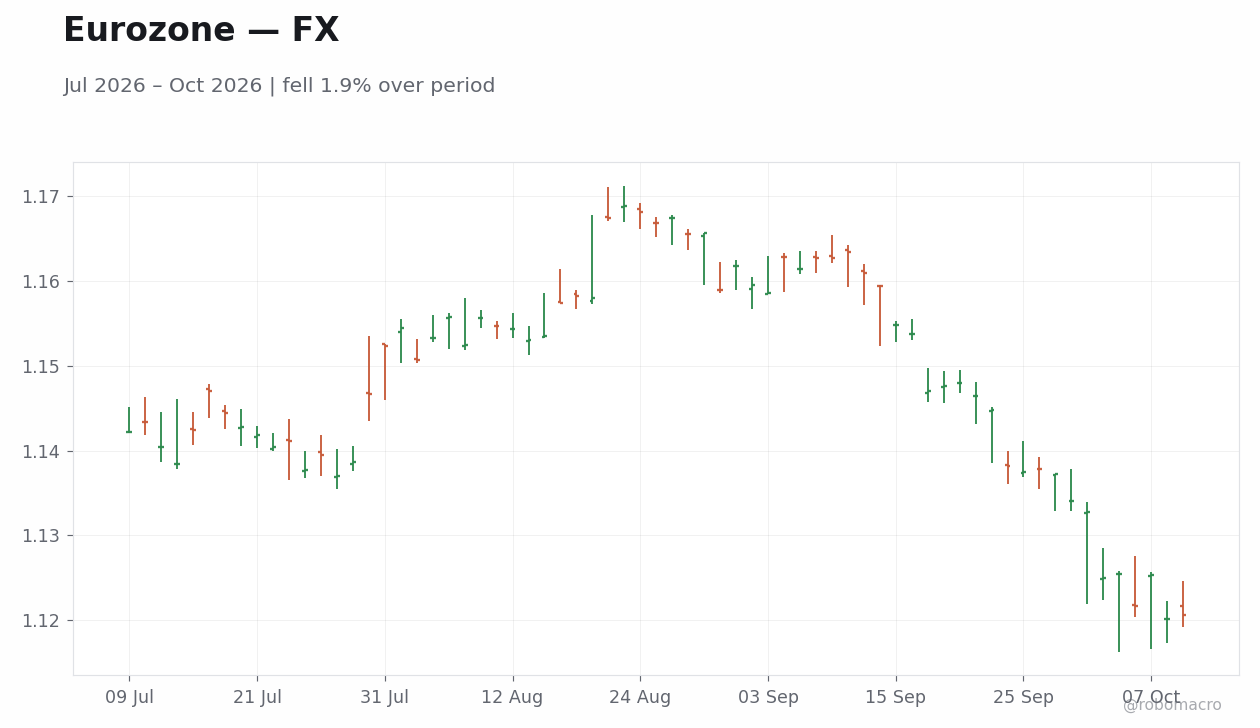
The configuration transmits uneven price signals across borders. US 10-year yields moved lower while German 10-year Bund yields ended at 3.50 percent. EUR/USD closed at 1.12 after a 0.43 percent decline. Markets price persistent US yield advantage rather than any single domestic surprise. The pattern observed in the prior week, when USD/MXN advanced 2.23 percent, continues without interruption. Central banks therefore tolerate divergent prints without immediate recalibration.
DM Outcomes Cluster Around Selective Resilience
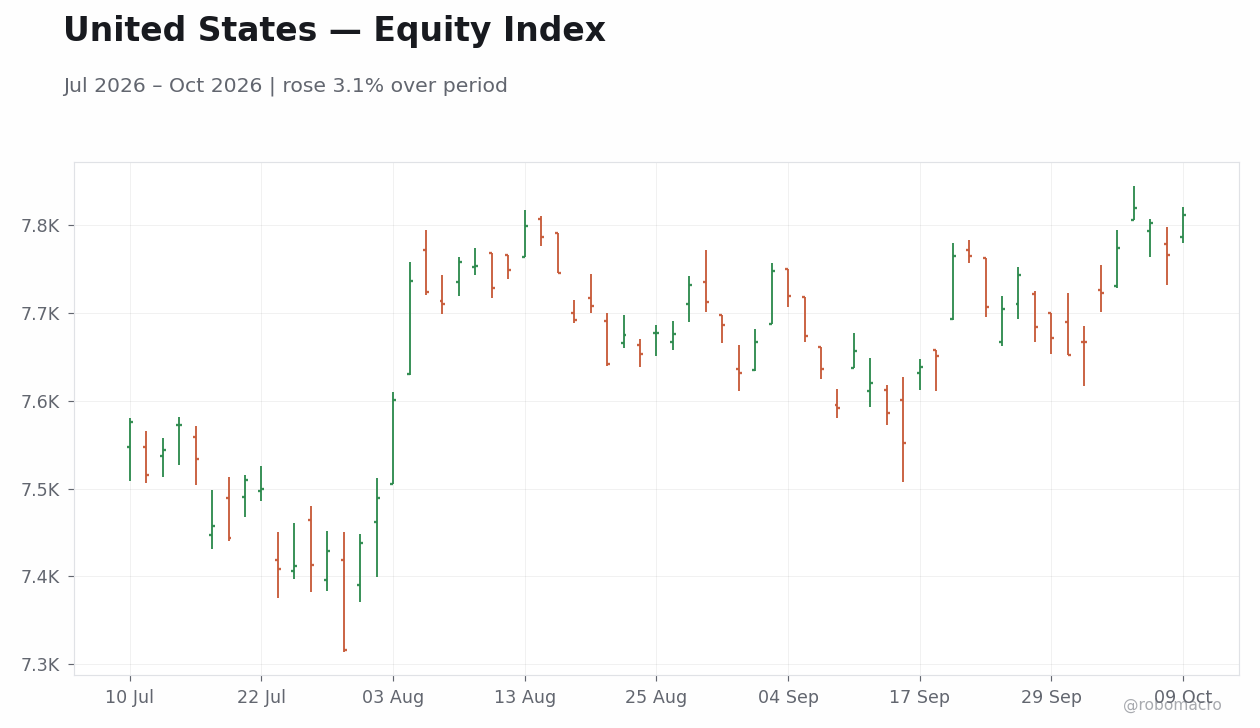
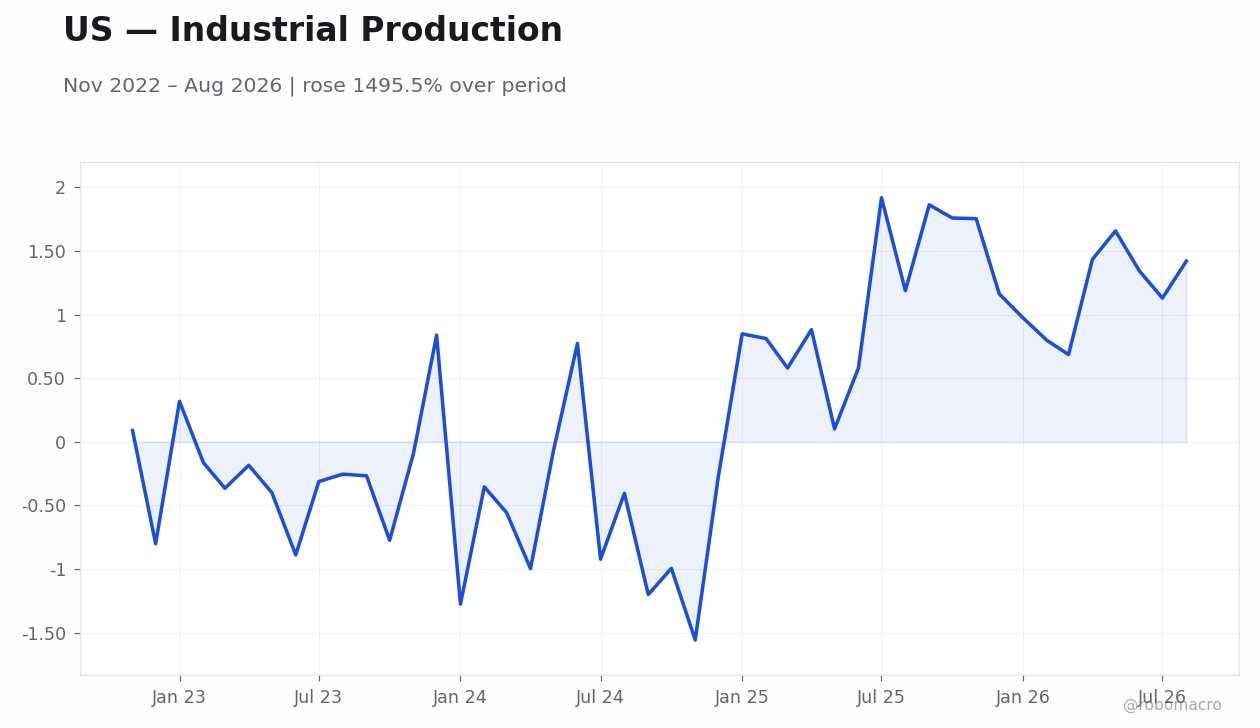
Developed-market data flows illustrate the same divergence. US labor-market softening lifted the S&P 500 0.48 percent to 7,811.54 while the Nasdaq 100 and Russell 2000 declined. Services activity eased and the trade deficit widened. In the euro area, German industrial production rebounded strongly month-over-month on 7 October after a prior contraction, yet factory orders declined sharply on 6 October. French fiscal concerns widened the France-Germany 10-year spread to levels last seen during the euro crisis. Spanish services PMI rose to 58.3 on 5 October while Italian services PMI fell to 51.7. These prints underscore north-south divergence inside the currency union.
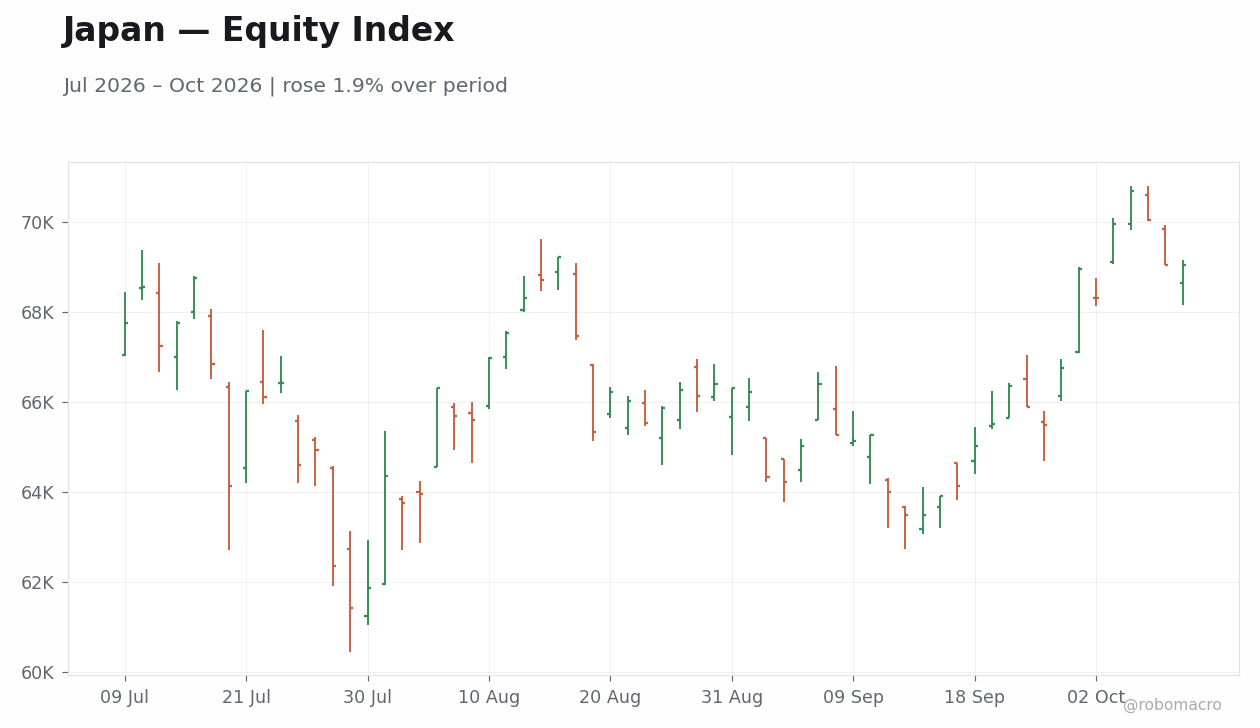
The United Kingdom posted clearer domestic resilience. S&P Global Construction PMI beat consensus on 6 October even as the sector stayed in contraction. RICS House Price Balance missed expectations. FTSE 100 closed the week higher while the 10-year gilt yield rose. Nordic central banks left policy settings unchanged. Swedish CPIF inflation rose year-on-year in September, reinforcing Riksbank tightening signals. Japan recorded a current-account surplus expansion that beat consensus, yet the Nikkei 225 ended at 69,030.92 after a 1.31 percent decline. Across these economies the common thread remains tolerance for mixed prints while forward guidance stays anchored to incoming data.
EM Data Flows Split Along Currency Lines
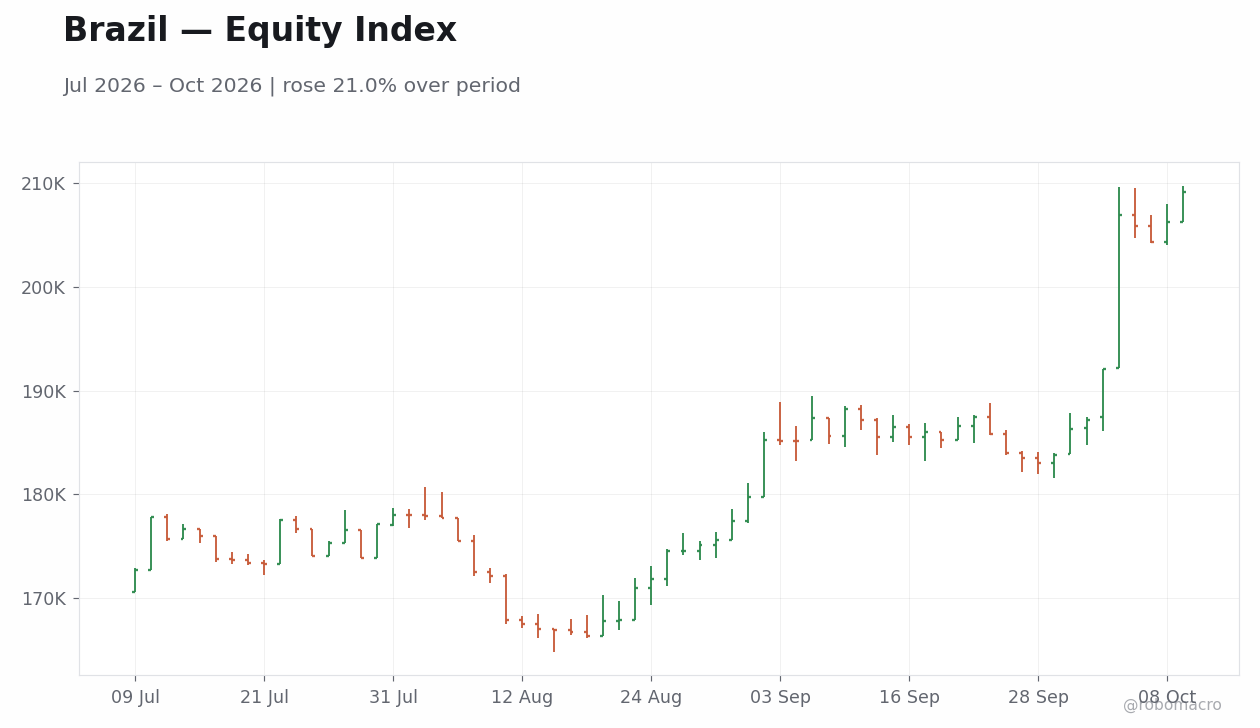
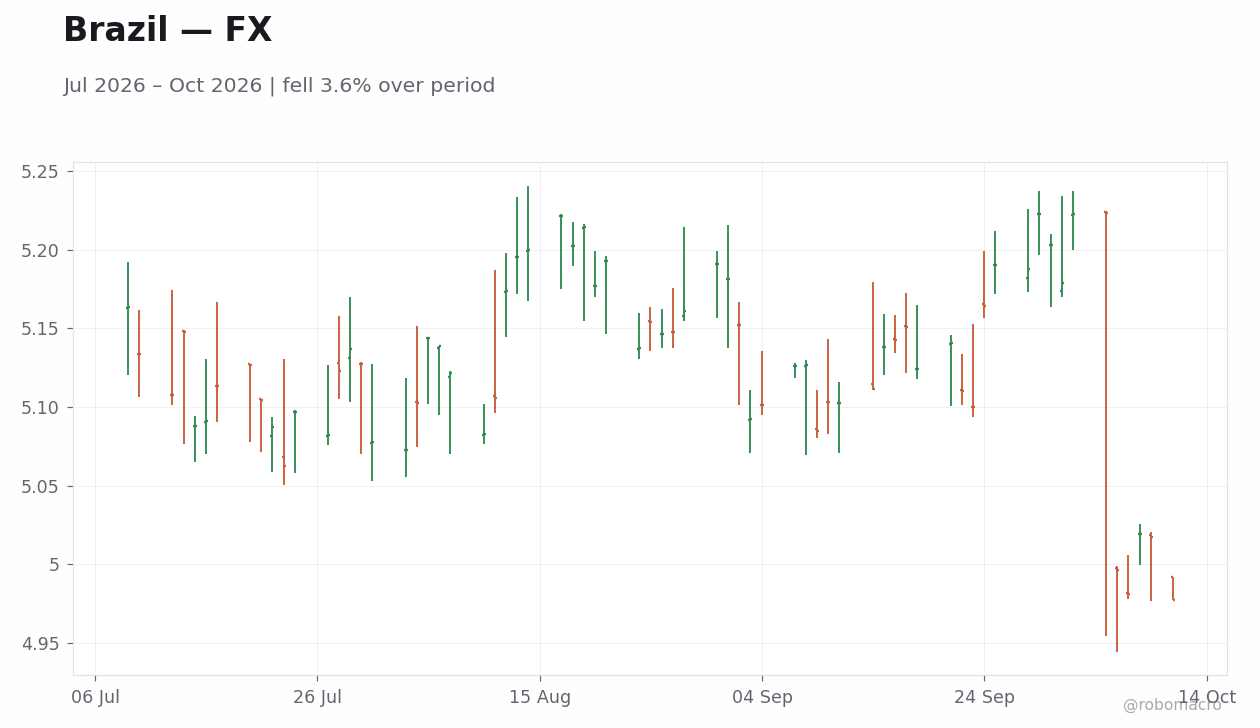
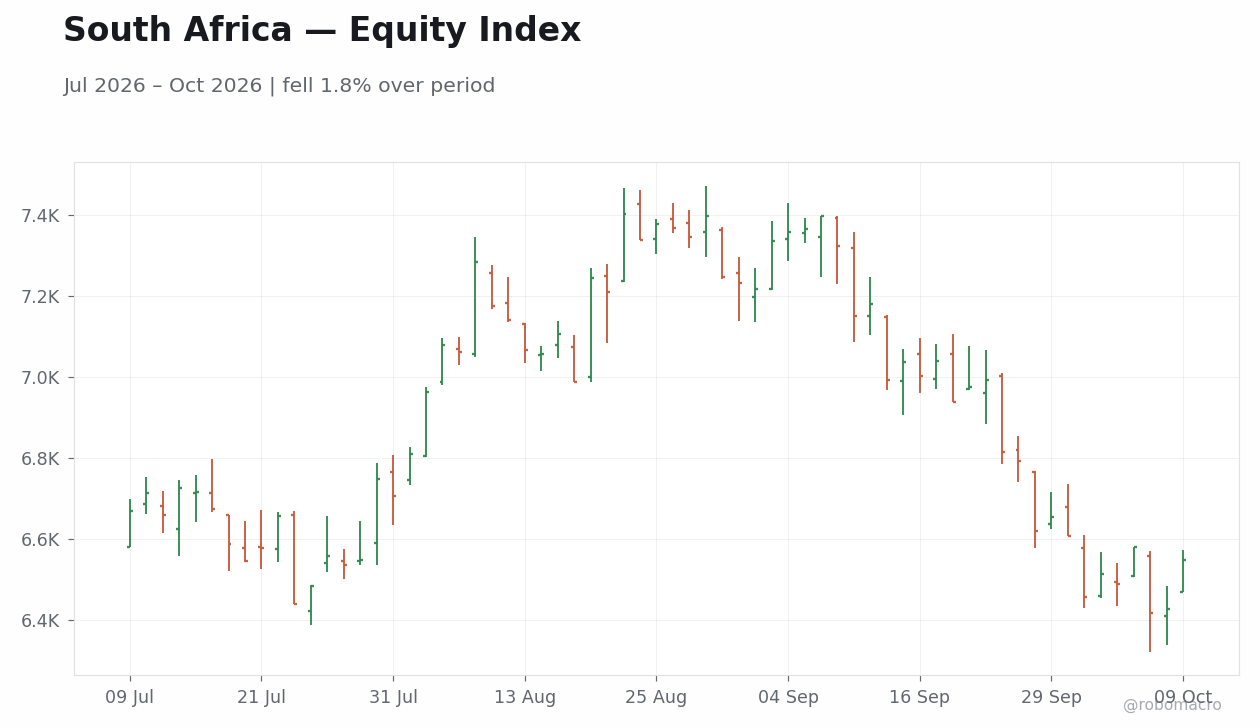
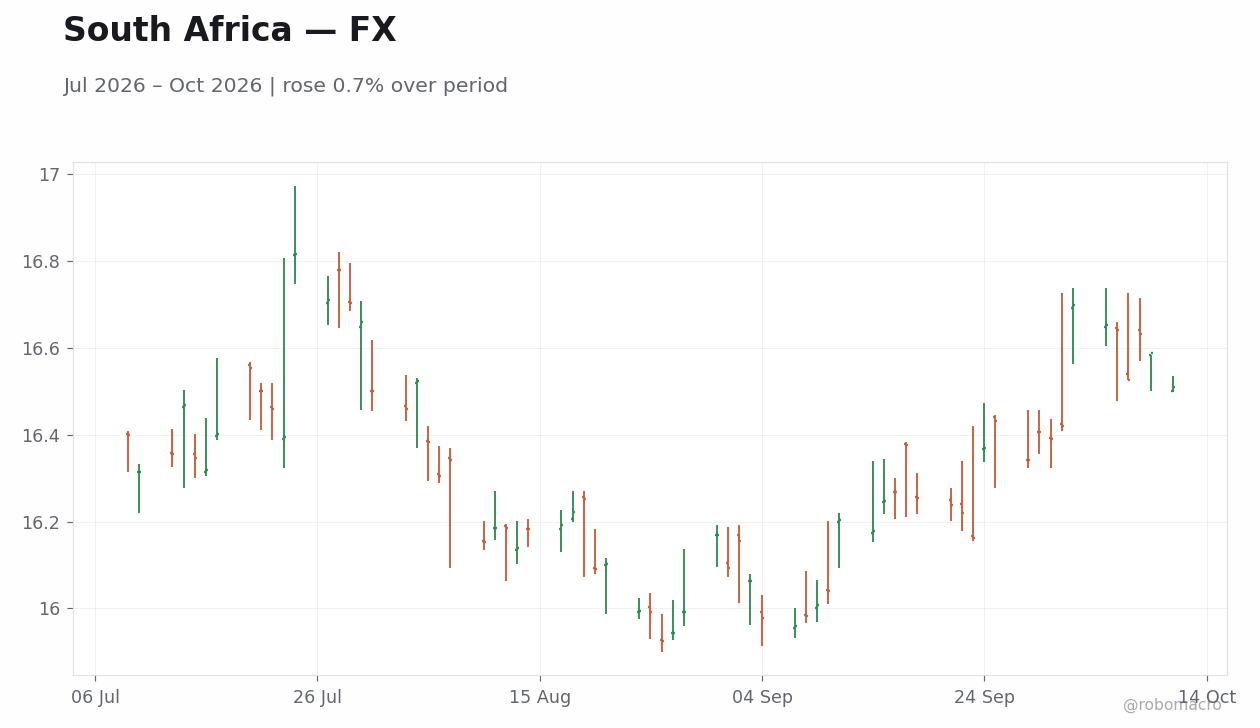
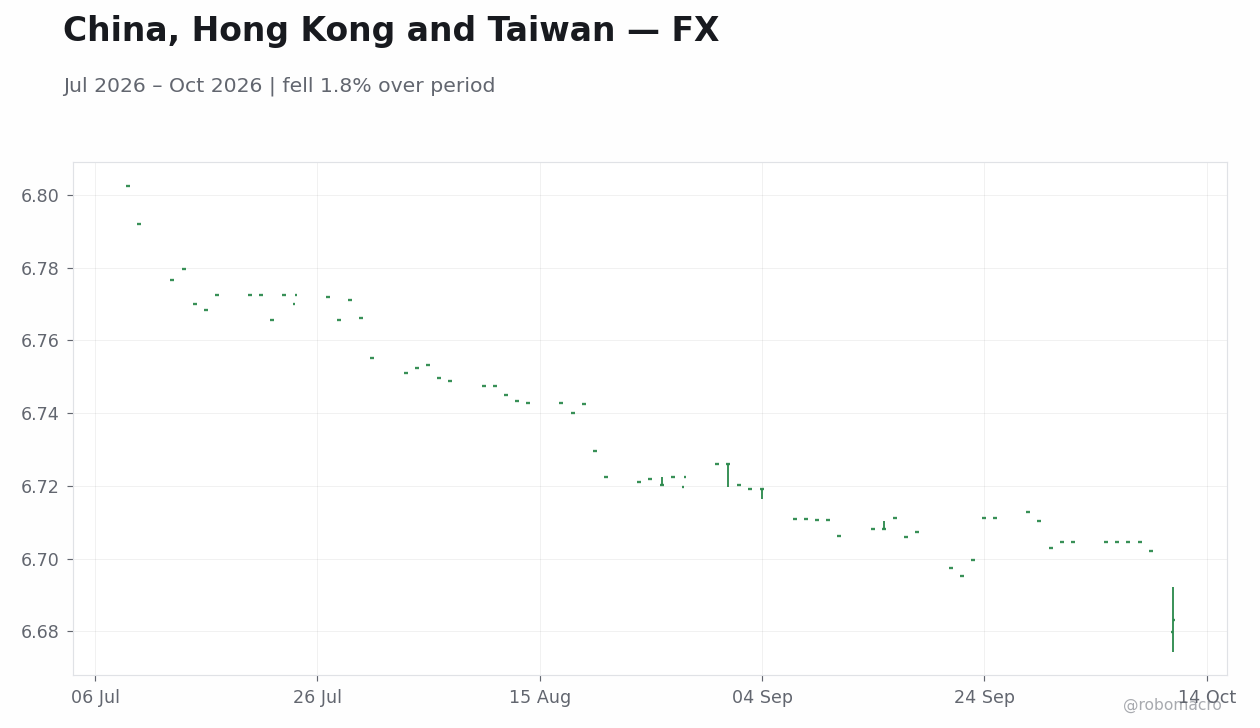
Emerging-market outcomes split along currency and domestic-demand lines. Mexico September inflation rose less than expected, supporting expectations for steady monetary policy. USD/MXN advanced 1.45 percent. Brazil equities advanced as the Bovespa closed at 209,067 and USD/BRL declined to 4.98. South Africa JSE Top 40 closed at 100,764.3 after a 0.08 percent gain while USD/ZAR fell 0.86 percent to 16.51. Taiwan September exports reached a record high, lifting TAIEX before a close at 49,313.44. USD/CNY settled at 6.68 after a 0.32 percent decline.
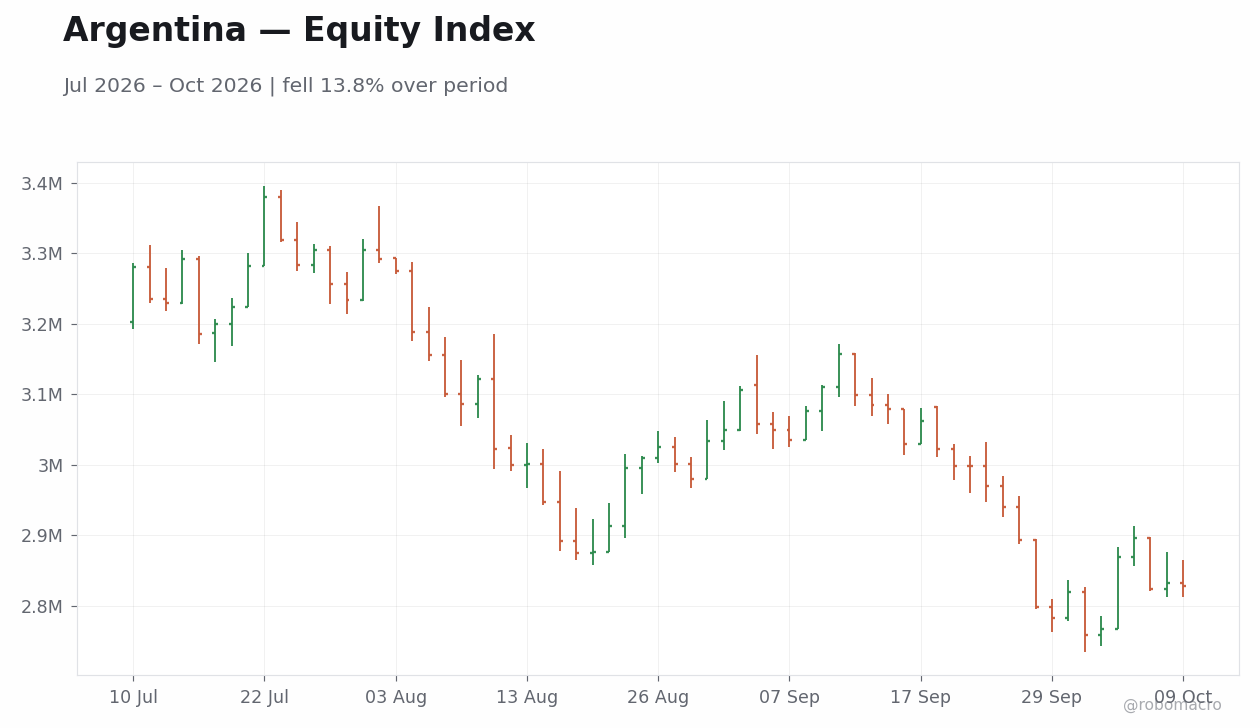
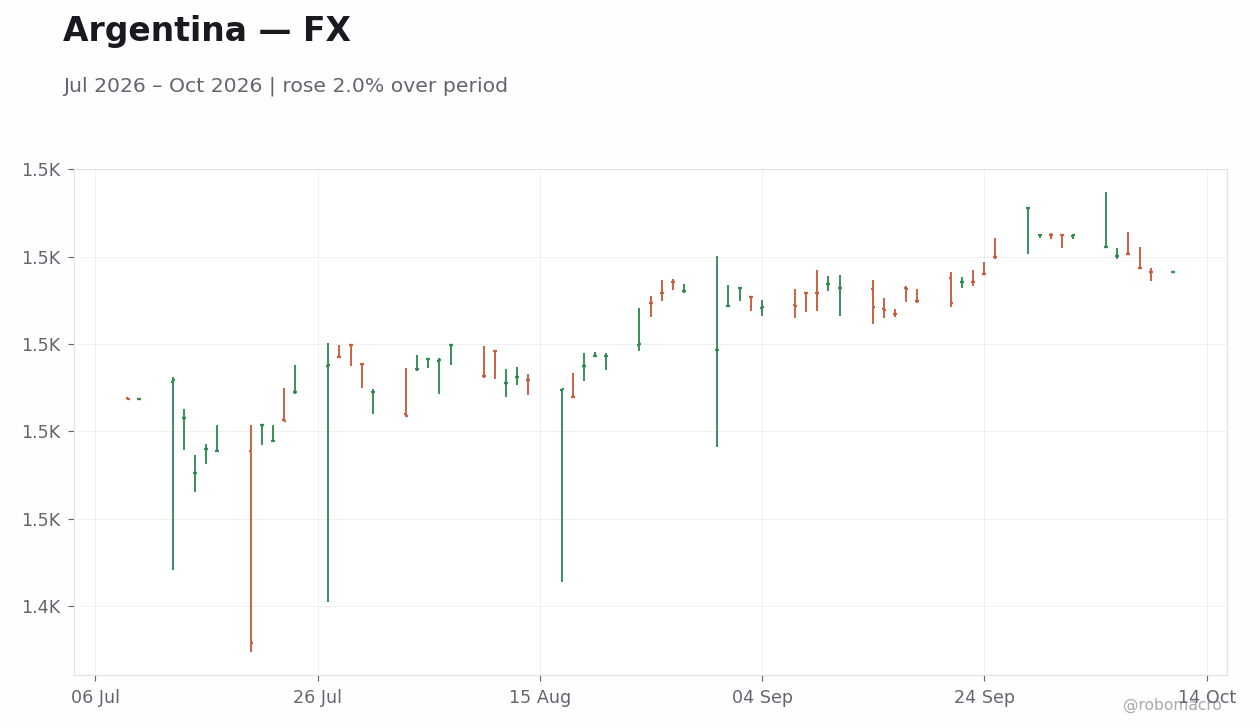
Regional equity indices posted net losses in several ASEAN markets. The STI fell 4.63 percent to 5,401.89 while the KLCI declined 1.43 percent to 1,608.45. No policy-rate adjustments occurred from BI, BoT, BNM, BSP, MAS or SBV. Argentina MERVAL closed at 2,828,027 after a 1.44 percent decline. USD/ARS eased 0.38 percent to 1,516.50. These moves reflect external dollar strength transmitting faster than most central banks can adjust.
Cross-Asset Moves Reinforce Divergence
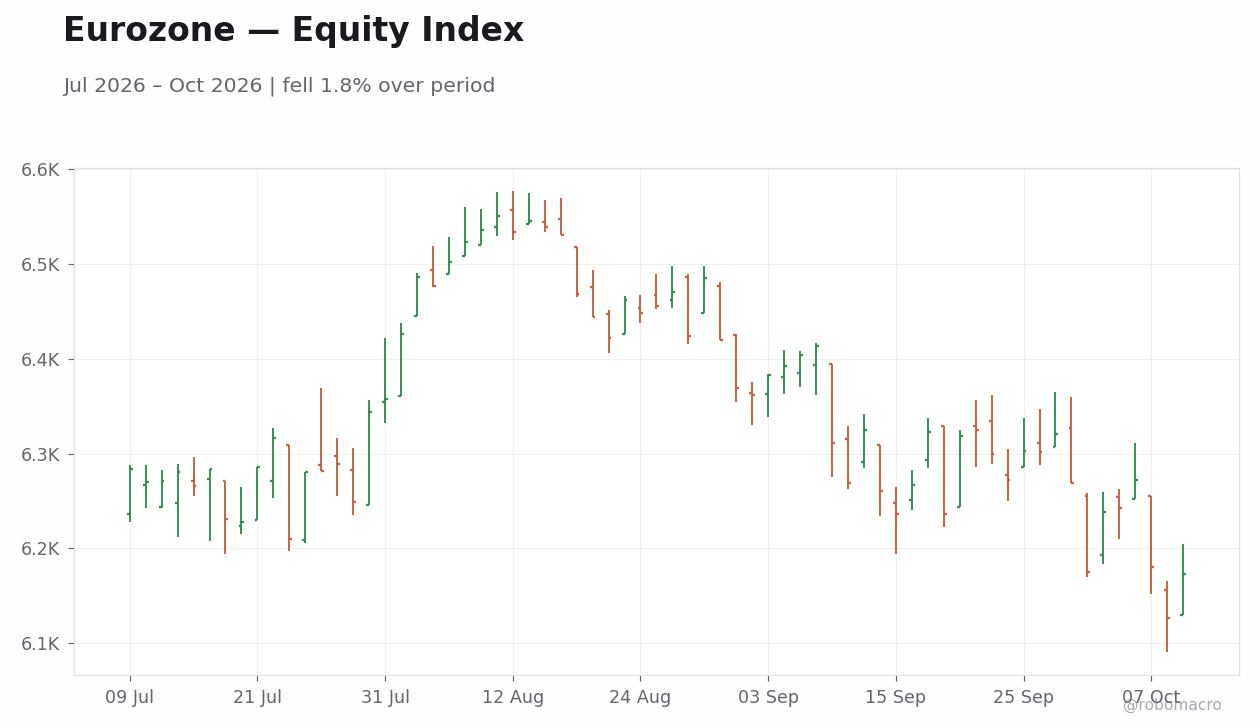
Rates, FX, equities and commodities together confirm the policy split. Brazil 10-year yields fell 173 basis points. Mexico 10-year yields fell 21 basis points. Japan 10-year yields fell 10 basis points. Copper rose 3.1 percent to 6.69. Brent crude advanced 4.39 percent to 104.72. Gold rose 1.43 percent to 4,216.30. Bitcoin declined 3.34 percent to 83,595.06. Euro Stoxx 50 closed at 6,173.37 after a 1.1 percent decline while DAX fell 0.66 percent to 25,087.27. These moves occurred alongside selective equity resilience in Brazil and Mexico.
Policy Outlook Leaves Paths Apart
Global central-bank communication reinforced patience. The ECB continues to monitor services divergence between Spain’s 58.3 PMI beat and Italy’s 51.7 miss. Bundesbank President Nagel flagged rising gas prices as an inflation risk for Germany. No Governing Council member signaled an imminent shift in the 2.50 percent deposit rate path. The Bank of Korea leadership changes reinforced a data-dependent stance. SARB held its policy rate steady with inflation contained. These settings leave rate paths apart into year-end.
Forward Look Centers on External Drivers
Dutch trade balance data on 12 October and Danish inflation prints on the same day will offer early reads on external demand. No high-impact German or French releases are scheduled for 13 October. ECB speakers are expected to maintain the data-dependent message. Markets will watch for any comments on the 2.50 percent deposit rate amid the recent Brent advance. French fiscal developments will continue to influence peripheral spreads. External factors such as US data and commodity moves remain the dominant drivers for the week ahead.
| Economy | Real GDP (% y/y) | Consumer Prices (% y/y) | ||||
|---|---|---|---|---|---|---|
| 2026E | 2027E | 2028E | 2026E | 2027E | 2028E | |
| Americas | ||||||
| United States | 2.3 | 2.1 | 2.1 | 3.2 | 2.1 | 2.2 |
| Canada | 1.5 | 1.9 | 1.7 | 2.5 | 2.1 | 2.0 |
| Mexico | 1.6 | 2.2 | 2.1 | 3.9 | 3.4 | 3.0 |
| Brazil | 1.9 | 2.0 | 2.4 | 4.0 | 3.4 | 3.0 |
| Argentina | 3.5 | 4.0 | 3.8 | 30.4 | 15.7 | 9.6 |
| Colombia | 2.3 | 2.5 | 2.6 | 5.9 | 5.2 | 3.4 |
| Chile | 2.4 | 2.6 | 2.3 | 2.9 | 3.3 | 3.0 |
| Peru | 2.8 | 2.8 | 2.8 | 2.5 | 1.8 | 2.0 |
| Asia / Pacific | ||||||
| Japan | 0.7 | 0.6 | 0.6 | 2.2 | 2.3 | 2.0 |
| China | 4.4 | 4.0 | 4.0 | 1.2 | 1.5 | 1.8 |
| India | 6.5 | 6.5 | 6.5 | 4.7 | 4.0 | 4.0 |
| Australia | 2.0 | 1.7 | 1.9 | 4.0 | 3.2 | 2.6 |
| New Zealand | 2.1 | 2.4 | 2.4 | 3.1 | 2.3 | 2.1 |
| South Korea | 1.9 | 2.1 | 2.2 | 2.5 | 1.9 | 2.0 |
| Indonesia | 5.0 | 5.1 | 5.2 | 3.0 | 2.6 | 2.5 |
| Malaysia | 4.7 | 4.3 | 4.3 | 1.9 | 2.0 | 2.0 |
| Philippines | 4.1 | 5.8 | 6.1 | 4.3 | 3.2 | 3.0 |
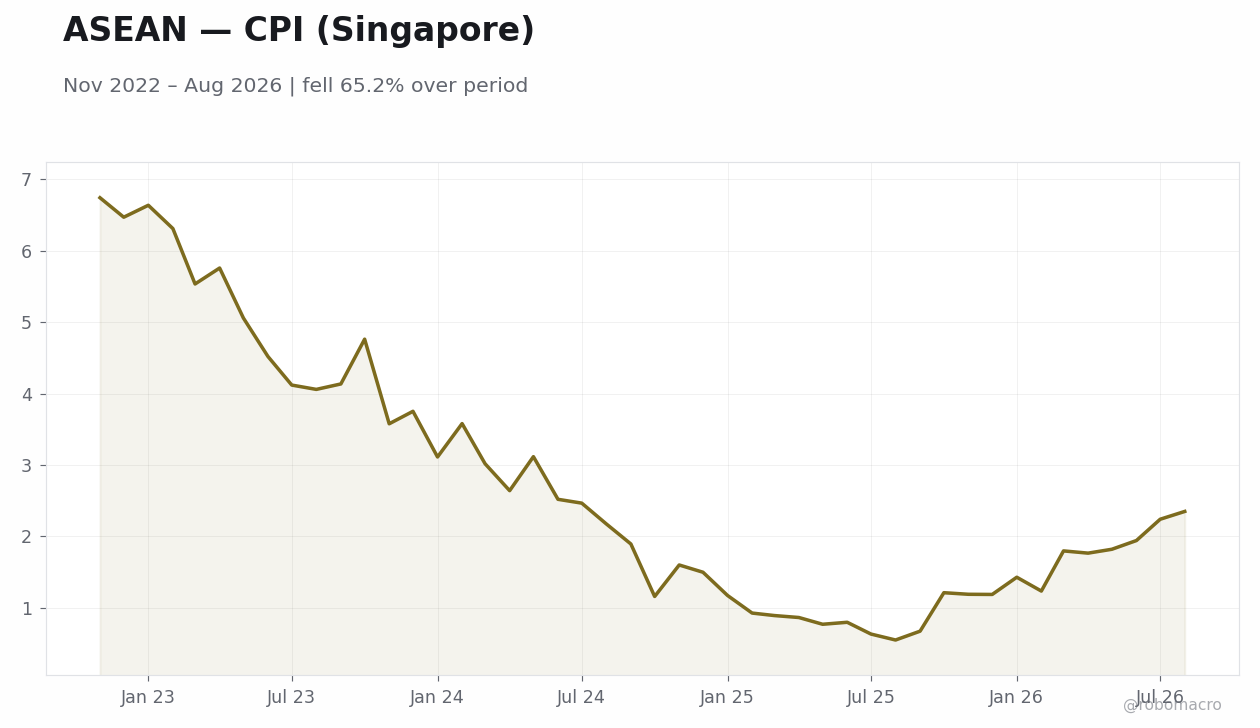
| Singapore | 3.5 | 2.7 | 2.5 | 2.3 | 1.9 | 2.0 |
| Thailand | 1.5 | 2.1 | 2.3 | 0.9 | 1.0 | 1.2 |
| Taiwan | 5.2 | 3.0 | 2.4 | 1.5 | 1.6 | 1.6 |
| Vietnam | 7.1 | 6.7 | 6.2 | 4.9 | 4.6 | 3.7 |
| Western Europe | ||||||
| Euro area | 1.1 | 1.2 | 1.4 | 2.6 | 2.2 | 2.1 |
| Germany | 0.8 | 1.2 | 1.2 | 2.7 | 2.3 | 2.0 |
| France | 0.9 | 0.9 | 1.2 | 1.8 | 1.7 | 1.9 |
| Italy | 0.5 | 0.5 | 0.8 | 2.6 | 2.4 | 2.3 |
| Spain | 2.1 | 1.8 | 1.8 | 3.0 | 2.3 | 2.5 |
| United Kingdom | 0.8 | 1.3 | 1.6 | 3.2 | 2.4 | 2.0 |
| Sweden | 2.0 | 1.9 | 2.1 | 1.5 | 1.8 | 2.6 |
| Norway | 1.5 | 1.3 | 1.1 | 3.3 | 2.6 | 2.2 |
| Denmark | 2.0 | 1.6 | 1.6 | 2.0 | 2.2 | 2.2 |
| Switzerland | 1.3 | 1.3 | 1.8 | 0.5 | 0.5 | 0.6 |
| Netherlands | 1.2 | 1.4 | 1.4 | 2.7 | 2.4 | 2.3 |
| Poland | 3.3 | 2.4 | 2.6 | 3.3 | 3.3 | 3.9 |
| Czech Republic | 2.2 | 2.2 | 2.1 | 2.4 | 2.2 | 2.5 |
| Hungary | 1.7 | 2.0 | 2.3 | 3.8 | 3.5 | 3.1 |
| Romania | 0.7 | 2.5 | 2.7 | 7.8 | 3.9 | 4.3 |
| EMEA Emerging | ||||||
| Turkey | 3.4 | 3.5 | 3.8 | 28.6 | 21.4 | 17.0 |
| South Africa | 1.0 | 1.3 | 1.5 | 3.9 | 3.4 | 3.0 |
| Israel | 3.5 | 4.4 | 3.7 | 2.3 | 2.1 | 2.0 |
| Saudi Arabia | 3.1 | 4.5 | 3.6 | 2.3 | 2.1 | 2.0 |
| UAE | 3.1 | 5.3 | 4.6 | 2.5 | 2.0 | 2.0 |
| Egypt | 4.2 | 4.8 | 5.5 | 13.2 | 11.1 | 8.1 |
| Nigeria | 4.1 | 4.3 | 4.1 | 16.0 | 15.9 | 12.7 |
| Kenya | 4.5 | 4.7 | 5.1 | 5.9 | 5.9 | 5.7 |
| Global Aggregates | ||||||
| Global | 3.1 | 3.2 | 3.2 | 4.4 | 3.7 | 3.4 |
| Developed markets | 1.8 | 1.7 | 1.7 | 2.8 | 2.2 | 2.1 |
| Emerging markets | 3.9 | 4.2 | 4.2 | 5.5 | 4.6 | 4.1 |
| Central Bank | Instrument | Current Rate |
Last Change |
bp | Next Meeting |
Q1 2026 |
Q2 2026 |
Q3 2026 |
Q4 2026 |
|---|---|---|---|---|---|---|---|---|---|
| The Americas | |||||||||
| Federal Reserve | Fed funds upper | 4.00% | Sep 2026 | +25 | Oct 28 | 3.75 | 3.75 | 4.00 | — |
| Bank of Canada | O/N rate | 2.25% | Oct 2025 | -25 | Oct 28 | 2.25 | 2.25 | 2.25 | — |
| BCB (Brazil) | SELIC | 13.75% | Sep 2026 | -25 | Nov 4 | 14.75 | 14.25 | 13.75 | — |
| Banxico | O/N rate | 6.50% | May 2026 | -25 | Nov 5 | 6.75 | 6.50 | 6.50 | — |
| BCRA (Argentina) | Aggregates regime | — | Jul 2025 | — | — | — | — | — | — |
| BanRep (Colombia) | Repo | 12.25% | Sep 2026 | +25 | Oct 30 | 10.25 | 11.25 | 12.00 | — |
| BCCh (Chile) | MPR | 4.50% | Dec 2025 | -25 | — | 4.50 | 4.50 | 4.50 | — |
| Europe / Africa | |||||||||
| ECB | Depo rate | 2.50% | Sep 2026 | +25 | Oct 29 | 2.00 | 2.25 | 2.50 | — |
| Bank of England | Bank rate | 3.75% | Dec 2025 | -25 | Nov 5 | 3.75 | 3.75 | 3.75 | — |
| Riksbank | Repo rate | 1.75% | Oct 2025 | -25 | Nov 4 | 1.75 | 1.75 | 1.75 | — |
| Norges Bank | Dep rate | 4.50% | Sep 2026 | +25 | Nov 5 | 4.00 | 4.25 | 4.50 | — |
| SNB | Policy rate | 0.00% | Jun 2025 | -25 | Dec 10 | 0.00 | 0.00 | 0.00 | — |
| CNB (Czech) | 2-wk repo | 3.75% | Jun 2026 | +25 | Nov 5 | 3.50 | 3.75 | 3.75 | — |
| NBH (Hungary) | Base rate | 5.50% | Aug 2026 | -25 | Oct 20 | 6.25 | 6.25 | 5.50 | — |
| NBP (Poland) | Ref rate | 3.75% | Mar 2026 | -25 | — | 3.75 | 3.75 | 3.75 | — |
| SARB | Repo rate | 7.25% | Sep 2026 | +25 | Nov 19 | 6.75 | 7.00 | 7.25 | — |
| CBRT (Turkey) | 1-wk repo | 37.00% | Jan 2026 | -100 | Oct 22 | 37.00 | 37.00 | 37.00 | — |
| Asia / Pacific | |||||||||
| RBA | Cash rate | 4.35% | May 2026 | +25 | Nov 3 | 4.10 | 4.35 | — | — |
| RBNZ | OCR | 2.75% | Sep 2026 | +25 | Oct 28 | 2.25 | 2.25 | 2.75 | — |
| BoJ | Pol rate | 1.25% | Sep 2026 | +25 | Oct 30 | 0.75 | 1.00 | 1.25 | — |
| PBoC | 1-yr LPR | 3.00% | May 2025 | -10 | — | 3.00 | 3.00 | 3.00 | — |
| RBI (India) | Repo rate | 5.25% | Dec 2025 | -25 | — | 5.25 | 5.25 | — | — |
| BoK (Korea) | Base rate | 3.00% | Aug 2026 | +25 | — | 2.50 | 2.50 | — | — |
| BI (Indonesia) | BI-Rate | 5.75% | Jun 2026 | +25 | Oct 21 | 4.75 | 5.75 | 5.75 | — |
| BSP (Philippines) | Rev repo | 5.00% | Aug 2026 | +25 | — | 4.25 | 4.75 | 5.00 | — |
| BoT (Thailand) | 1-day repo | 1.00% | Feb 2026 | -25 | Oct 28 | 1.00 | 1.00 | 1.00 | — |
| CBC (Taiwan) | Disc rate | 2.00% | Mar 2024 | +12.5 | — | — | — | — | — |
| MAS (Singapore) | SGD NEER | Mild appr. | Apr 2026 | slope+ | — | — | — | — | — |
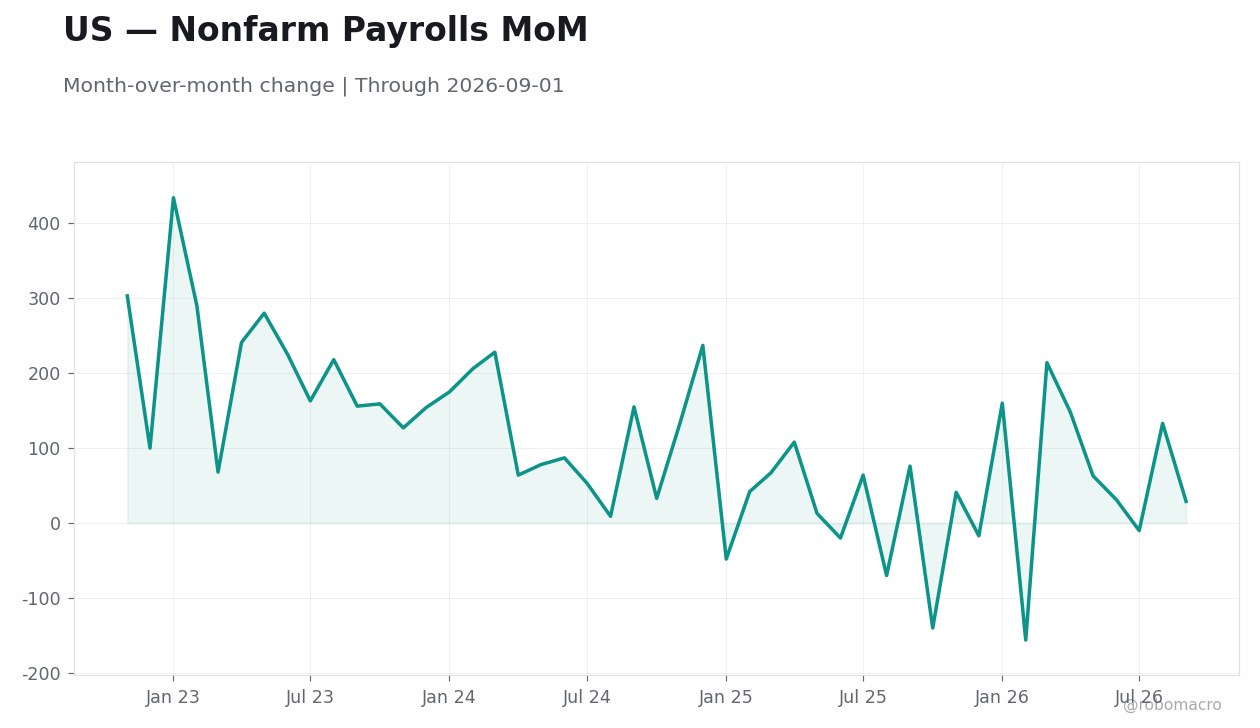
| Nonfarm Payrolls (m/m) | +72k | 80% CI +16k…+299k |
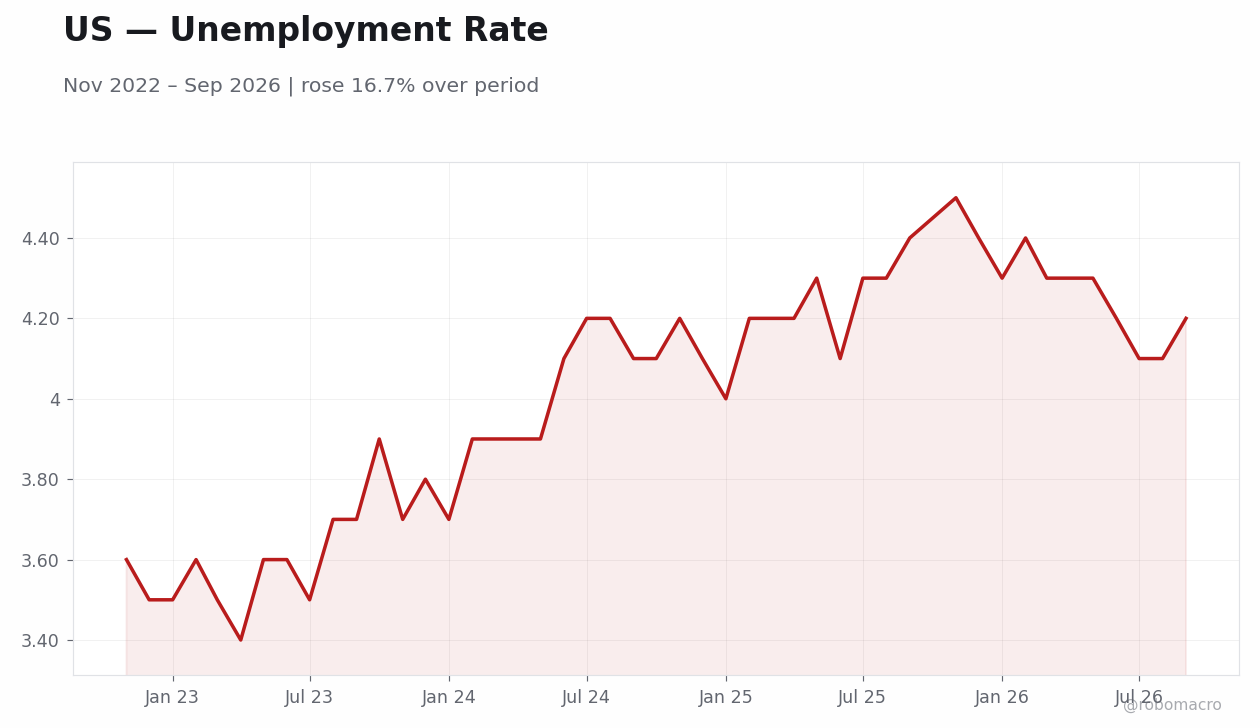
| Unemployment Rate | 4.2% | |
| Avg Hourly Earnings (y/y) | 3.2% |
| Economy | Activity Index | 4-wk Δ | 13-wk Δ | Week ending | Indicators | Signal |
|---|---|---|---|---|---|---|
| Brazil | 63.6 | +10.4 | -3.7 | 2026-10-09 | 3/4 | Expanding · Advancing |
| Canada | 63.2 | +2.8 | +6.1 | 2026-10-02 | 4/8 | Expanding · Advancing |
| Australia | 60.5 | +14.5 | +13.5 | 2026-10-02 | 3/3 | Expanding · Advancing |
| Italy | 60.0 | +1.1 | +12.2 | 2026-10-02 | 5/5 | Expanding · Advancing |
| United States | 56.0 | -9.1 | -0.9 | 2026-10-02 | 7/7 | Expanding · Retreating |
| Japan | 54.3 | +10.1 | +2.1 | 2026-10-09 | 4/5 | Expanding · Advancing |
| Spain | 54.2 | +0.8 | +2.0 | 2026-10-02 | 5/5 | Expanding · Advancing |
| Euro Area | 49.9 | +0.4 | +1.8 | 2026-10-02 | 5/5 | Contracting · Flat |
| Poland | 45.8 | -14.1 | -12.8 | 2026-10-09 | 3/4 | Contracting · Retreating |
| Germany | 42.0 | -8.5 | -5.2 | 2026-10-09 | 5/6 | Contracting · Retreating |
| New Zealand | 39.1 | -3.3 | -19.2 | 2026-10-02 | 5/5 | Contracting · Retreating |
| France | 37.7 | -7.5 | -15.2 | 2026-10-02 | 4/5 | Contracting · Retreating |
Activity remains in expansion in United States, Italy, Spain, Japan, Canada, Brazil, Australia; while high-frequency trackers point to sub-trend activity in Euro Area, Germany, France, New Zealand, Poland. On a 4-week basis, momentum is improving in Italy, Spain, Japan, Canada, Brazil, Australia and cooling in United States, Germany, France, New Zealand, Poland. RoboMacro's labor ensemble nowcasts the next US payrolls print at +72k.


Week in Review
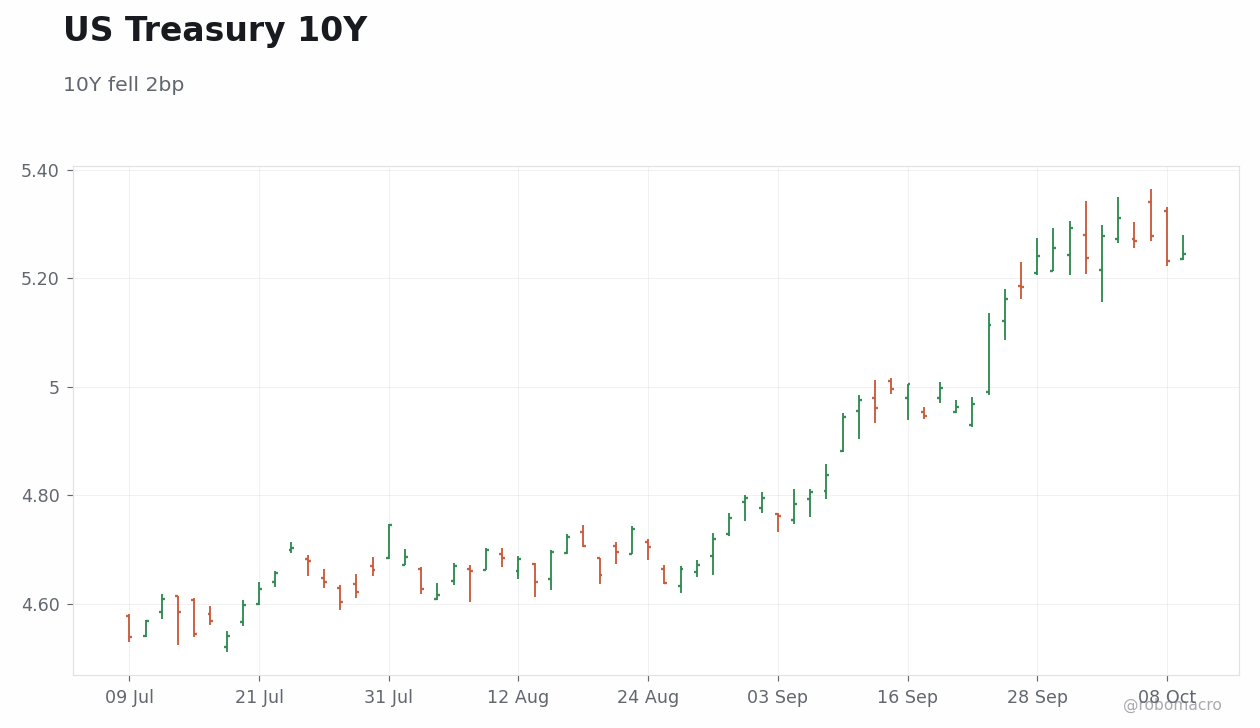
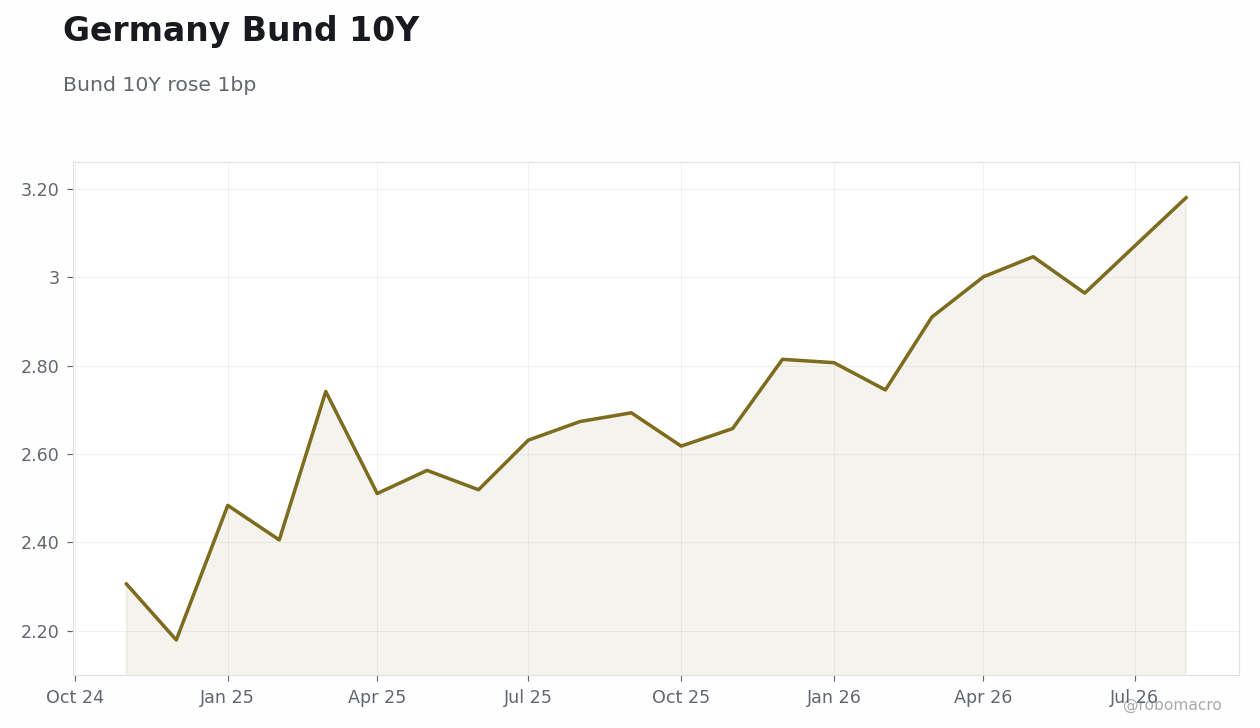
Japanese 10-year yields fell 10bp to 3.02% while 30-year yields dropped 15bp to 4.06%, the largest developed-market move. US 10-year Treasury yields fell 2bp to 5.22%. The intra-week path showed the US 10-year yield at 5.3110 on Monday, falling to 5.2690 on Tuesday, rising to 5.2770 on Wednesday, declining to 5.2310 on Thursday and closing at 5.2440 on Friday. UK 10-year gilt yields rose 5bp to 5.42%. German 10-year bund yields rose 1bp to 3.47%. These shifts occurred as Treasury yields stabilized and the global bond selloff slowed amid mixed equity performance and softening labor-market data.
Curve & Spreads
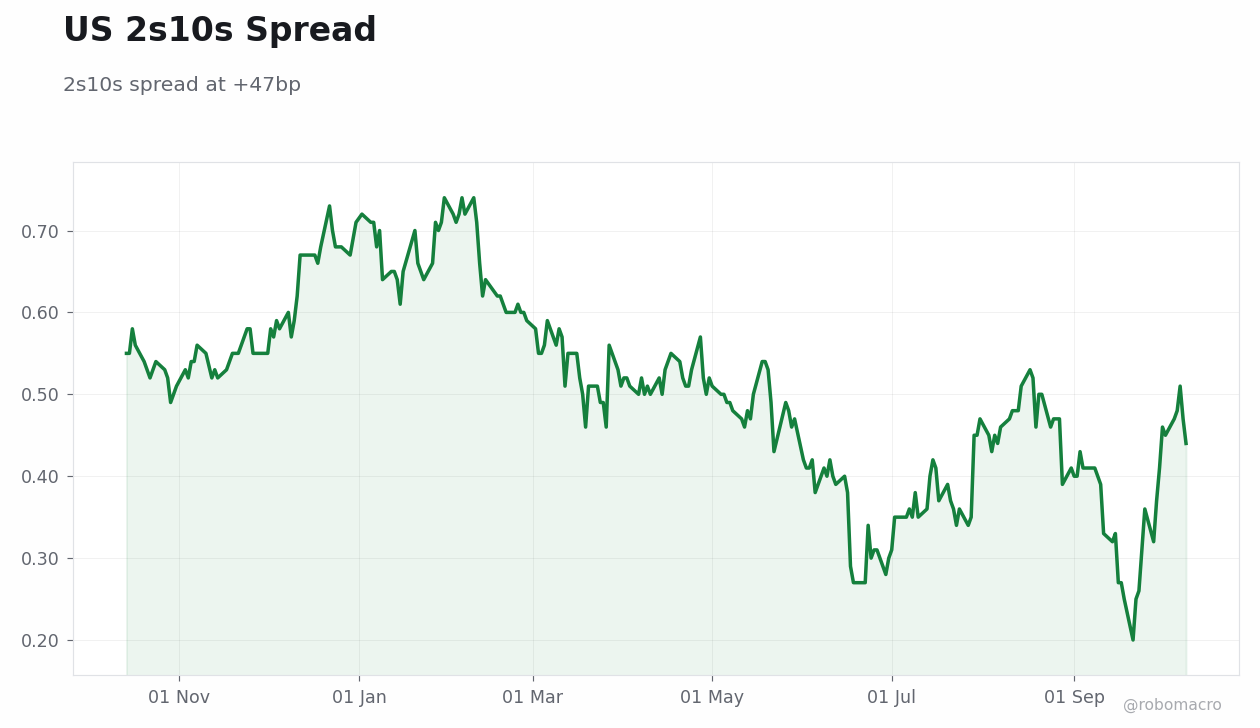
The US 2s10s spread stands at +47bp, compared with +68bp in the UK and +38bp in Germany. These positively sloped curves suggest markets are pricing moderate growth expectations rather than contraction. The steeper UK curve relative to the US and especially Germany implies directionally firmer growth expectations in Britain. Overall curve shape across these markets points to expectations of gradual economic improvement without sharp acceleration.
EM Bonds
Turkish 10-year yields stood at 35.61% with a 2s10s spread of -408bp. Brazilian 10-year yields moved significantly lower to 12.54%. South African 10-year yields stood at 8.96% while Indonesian 10-year yields stood at 7.24%. These EM levels remain substantially elevated versus DM counterparts such as the US 10-year at 5.22% and German 10-year at 3.47%, leaving a wide spread differential that reflects meaningful risk premia. EM curves traded distinctly from the milder positive slopes seen in core markets.
Central Bank Read
Yield curve shape across major DMs implies an easing bias. In Japan, the back end fell more sharply with the 30-year down 15bp versus the 2-year down 1bp, consistent with this tilt. US 2-year yields fell 3bp while 10-year yields fell 2bp, showing limited steepening that still aligns with an easing bias. UK 2-year yields rose 6bp versus 5bp on the 10-year, while German 2-year and 10-year yields each rose 1bp. These front-end versus back-end moves, alongside data dependence from Federal Reserve and ECB speakers, reinforce that policy settings are expected to adjust gradually to softening activity without abrupt shifts.
Week Ahead
The economic calendar next week contains no major CPI or inflation prints, payrolls or jobs data, central bank meetings for the Fed, ECB, BoE or BoJ, or GDP releases. Treasury auctions will therefore represent the primary scheduled events for rate markets. With limited high-impact data, duration risk will likely be driven more by positioning flows and ongoing interpretation of recent softening labor-market and services prints. This light schedule should keep volatility contained unless external news alters the current data-dependent policy stance.
| Country | 2Y | 2Y WoW | 10Y | 10Y WoW | 30Y | 30Y WoW | 2s10s |
|---|---|---|---|---|---|---|---|
| United States | 4.75% | -3bp | 5.22% | -2bp | 5.60% | -1bp | +47bp |
| United Kingdom | 4.74% | +6bp | 5.42% | +5bp | 5.94% | +3bp | +68bp |
| Germany | 3.09% | +1bp | 3.47% | +1bp | 3.85% | +2bp | +38bp |
| France | 3.63% | -10bp | 4.87% | +0bp | 5.42% | -1bp | +123bp |
| Italy | 3.48% | -7bp | 4.58% | -3bp | 5.19% | +2bp | +110bp |
| Spain | 3.29% | -8bp | 4.10% | -1bp | 4.62% | -1bp | +81bp |
| Japan | 1.91% | -1bp | 3.02% | -10bp | 4.06% | -15bp | +110bp |
| Canada | 3.19% | -9bp | 3.88% | -7bp | 4.24% | -5bp | +69bp |
| Australia | 4.95% | +12bp | 5.36% | +3bp | 5.82% | +0bp | +41bp |
| China | 1.25% | +1bp | 1.70% | -0bp | 2.12% | -1bp | +45bp |
| India | 6.63% | -5bp | 7.29% | +8bp | 7.72% | +4bp | +66bp |
| Brazil | 12.39% | -141bp | 12.54% | -173bp | — | — | +14bp |
| Mexico | — | — | 9.30% | -21bp | — | — | — |
| South Korea | 3.92% | -5bp | 4.39% | -4bp | 4.45% | -9bp | +48bp |
| Indonesia | — | — | 7.24% | +8bp | 7.25% | -4bp | — |
| Turkey | 39.69% | -66bp | 35.61% | 0bp | — | — | -408bp |
| South Africa | — | — | 8.96% | -5bp | 9.30% | -8bp | — |
| Poland | — | — | 6.35% | +5bp | — | — | — |
US Treasury yields declined modestly, with the 2-year falling 3bp to 4.75% and the 10-year easing 2bp to 5.22%. UK gilts rose across the curve, the 2-year adding 6bp to 4.74%. Euro-area bonds diverged, as French and Spanish 2-year yields dropped 10bp and 8bp while German yields ticked 1bp higher. Japan’s long end led the decline, with the 30-year yield down 15bp to 4.06%. Australia’s front end sold off, the 2-year jumping 12bp to 4.95%. Brazil posted the largest moves, its 10-year yield plunging 173bp. Steeper 2s10s spreads emerged in France (+123bp) and Italy (+110bp). Next week, focus centers on inflation releases and central-bank commentary.


Week in Review
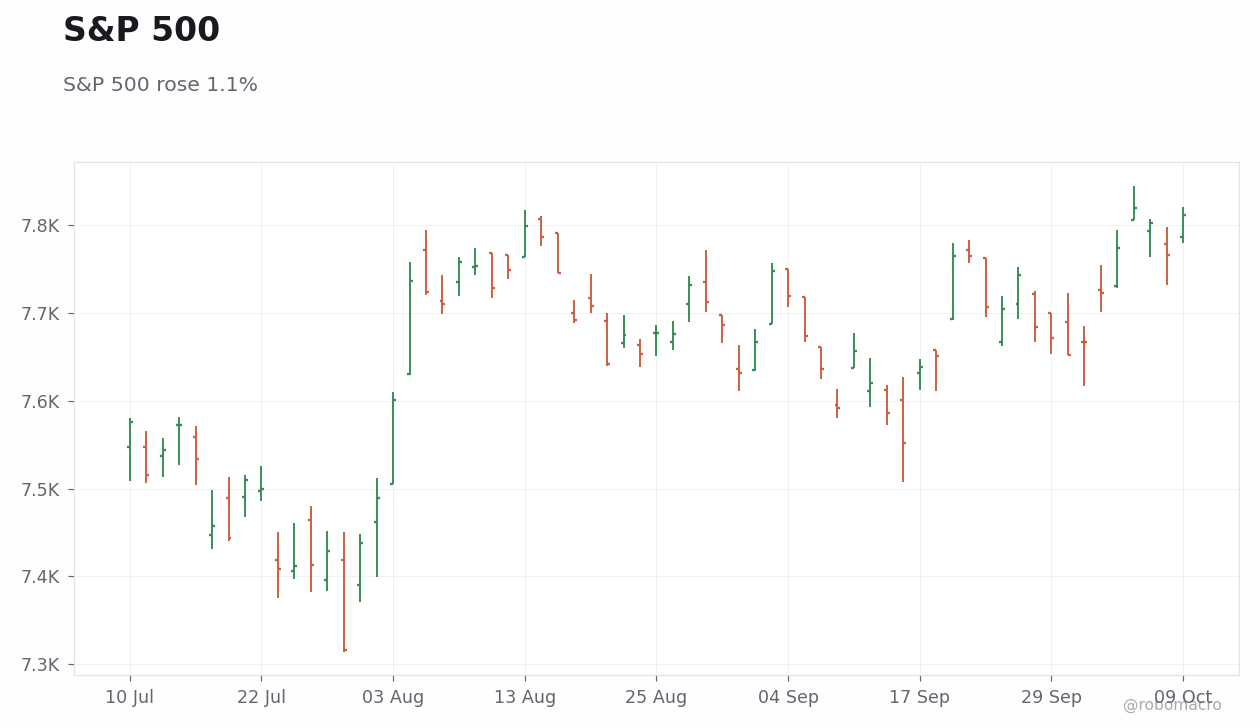
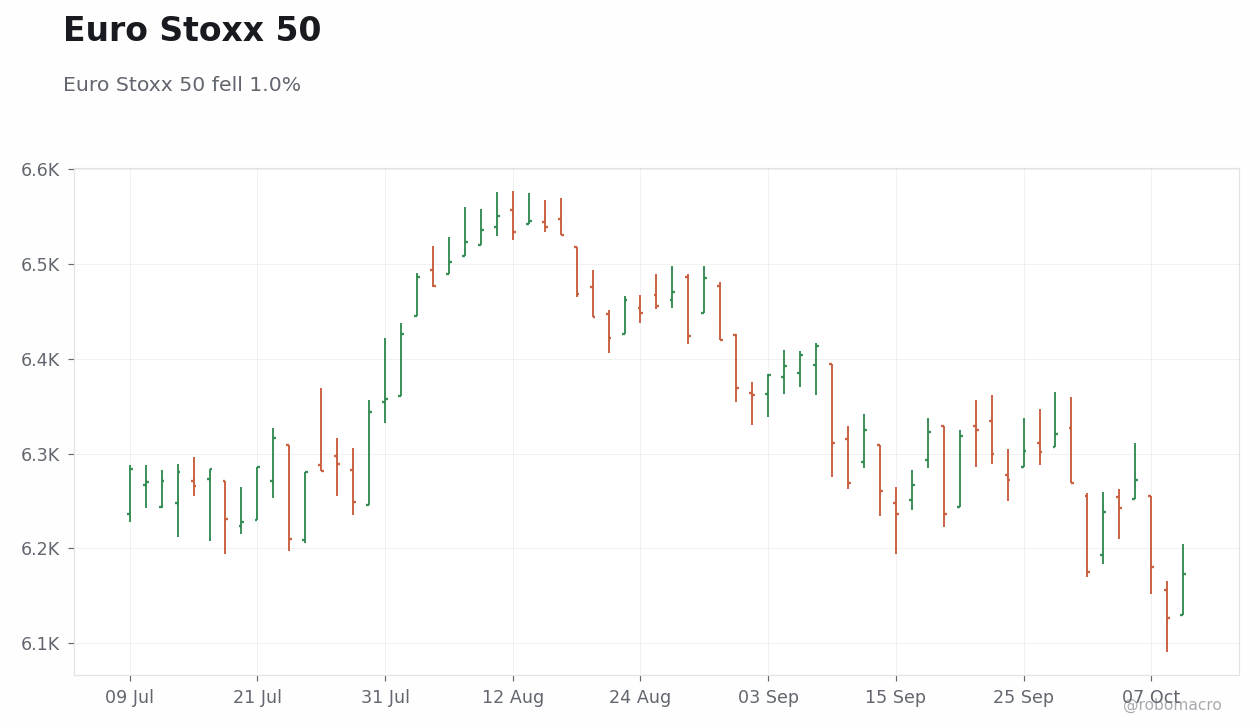
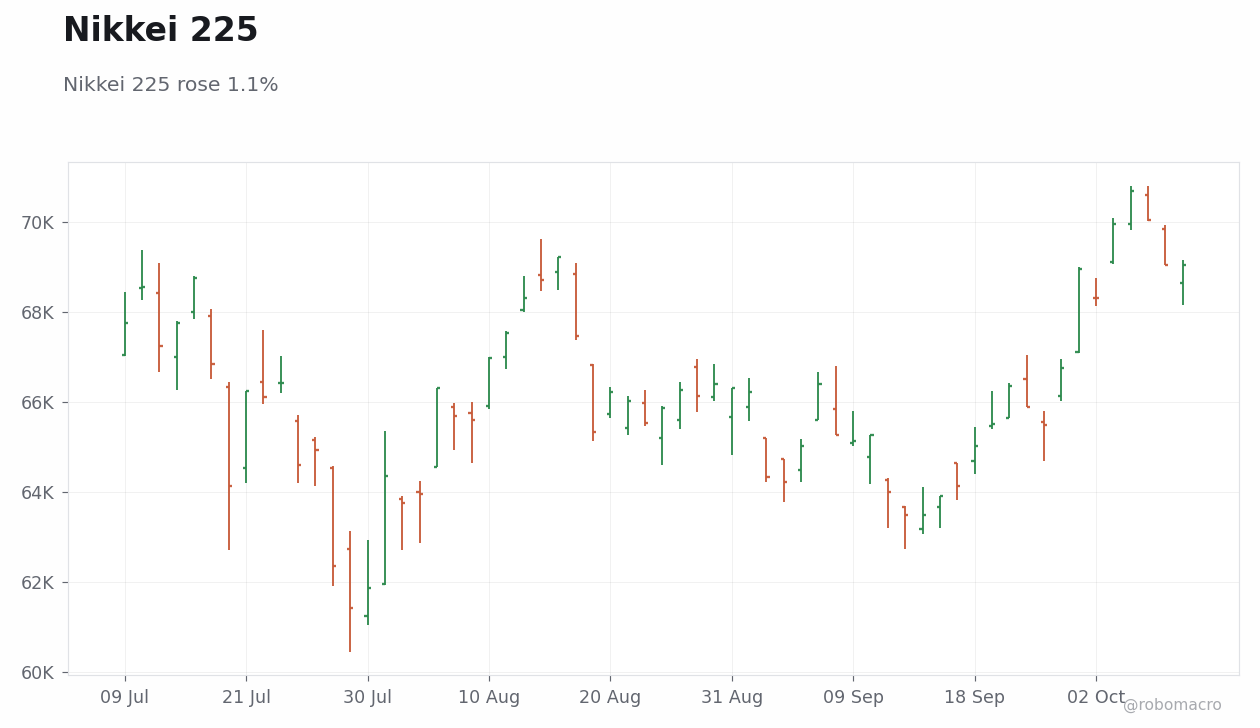
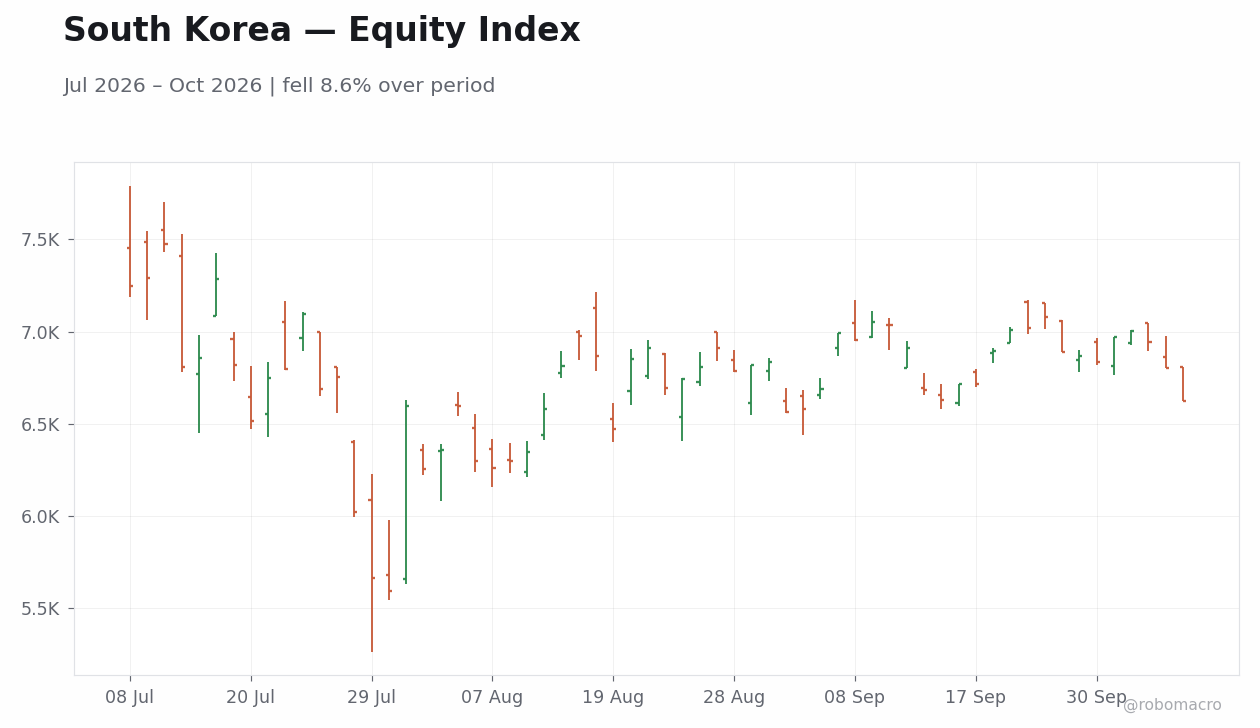
The S&P 500 rose 1.1% to 7,812. It climbed from 7,774 on Monday to 7,819 on Tuesday before falling back through 7,802 on Wednesday and 7,765 on Thursday to recover on Friday. The Euro Stoxx 50 fell 1.0% to 6,173 as European equities underperformed amid manufacturing volatility and fiscal concerns in key countries. The Nikkei 225 gained 1.1% to 69,031 while Asian markets showed mixed results with the KOSPI down 5.0% to 6,626. Emerging markets diverged with the Ibovespa up 8.8% to 209,067 and the IPC Mexico up 2.4% to 66,049. Overall global equities posted net gains in the US and parts of EM but faced headwinds in Europe and select Asian markets.
Regional Divergences
US indices diverged from Europe where the Euro Stoxx 50 fell 1.0% compared to the S&P 500's gain of 1.1%. This gap reflected labor-market softening that supported US stocks while French fiscal stress and German industrial production swings pressured European bourses including a 1.2% drop in the CAC 40 and 1.5% decline in the FTSE MIB. Asian performance varied with the Nikkei 225 up 1.1% and Hang Seng up 1.0% but the KOSPI falling 5.0%. Latin American equities stood out with the Ibovespa surging 8.8% contrasting the more muted moves in other EM indices like the Nifty 50 which rose 0.4%. These regional divergences highlight the importance of local macro catalysts from services and industrial data in driving equity performance this week.
Volatility & Risk Appetite
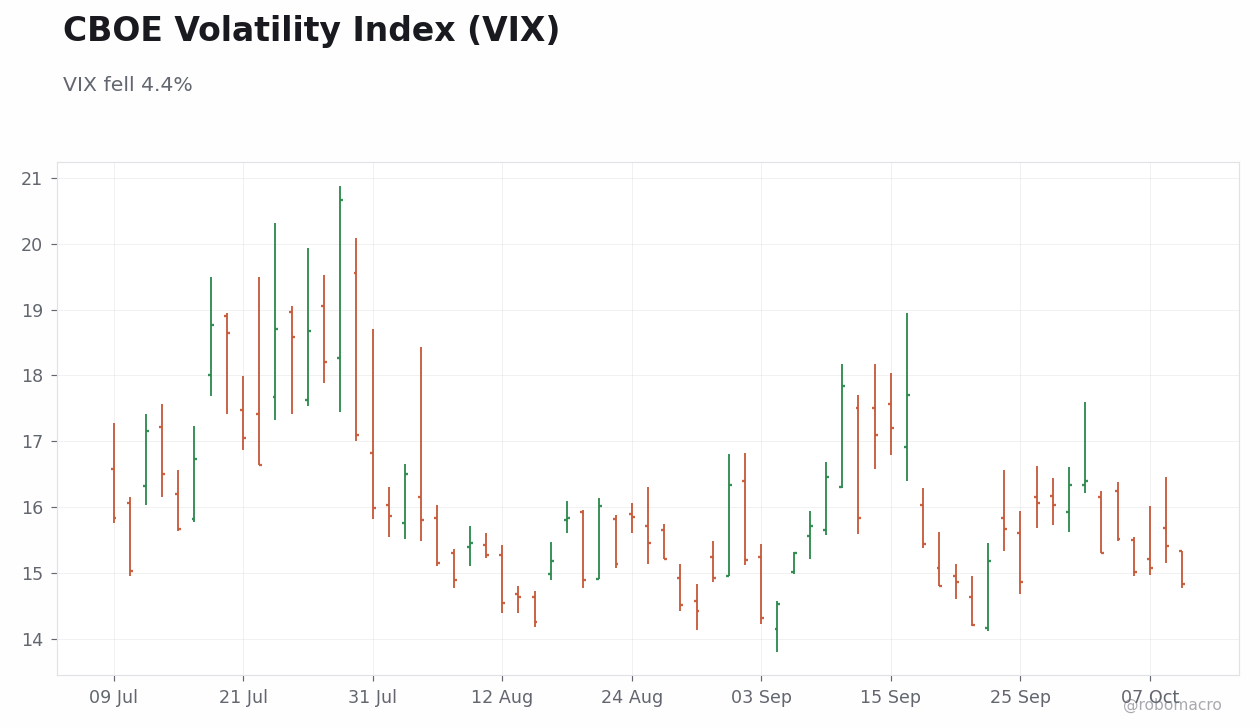
The VIX closed at 14.8 on Friday down from 15.5 at the start of the week. Growth underperformed value with the Nasdaq 100 rising 0.2% versus the Dow Jones advance of 0.9%. Small caps lagged large caps as the Russell 2000 fell 0.9% compared to the S&P 500's 1.1% gain. Commodity moves signaled mixed sector sentiment with advances in WTI Crude and Brent Crude suggesting resource sector resilience while gold's rise indicated ongoing safe haven demand amid bond market turmoil. Rate moves pointed to shifting risk appetite with curves reflecting varied inflation and growth expectations across countries leading to selective equity flows.
Week Ahead
The economic calendar for next week appears relatively light based on scheduled releases. Corporate earnings from major global firms will therefore be a primary focus for equity investors. Any PMI releases or other activity data could provide further insight into the diverging regional growth trends noted this week. Softer economic prints would support risk-on sentiment in equities while stronger than expected inflation figures would pose risks to current valuations and favor a more cautious approach.
| Index | Level | WoW | MTD | YTD |
|---|---|---|---|---|
| S&P 500 | 7,812 | +1.1% | +1.9% | +13.9% |
| Nasdaq 100 | 30,883 | +0.2% | +1.2% | +22.5% |
| Dow Jones | 51,655 | +0.9% | +1.4% | +6.8% |
| Russell 2000 | 2,807 | -0.9% | +0.0% | +11.9% |
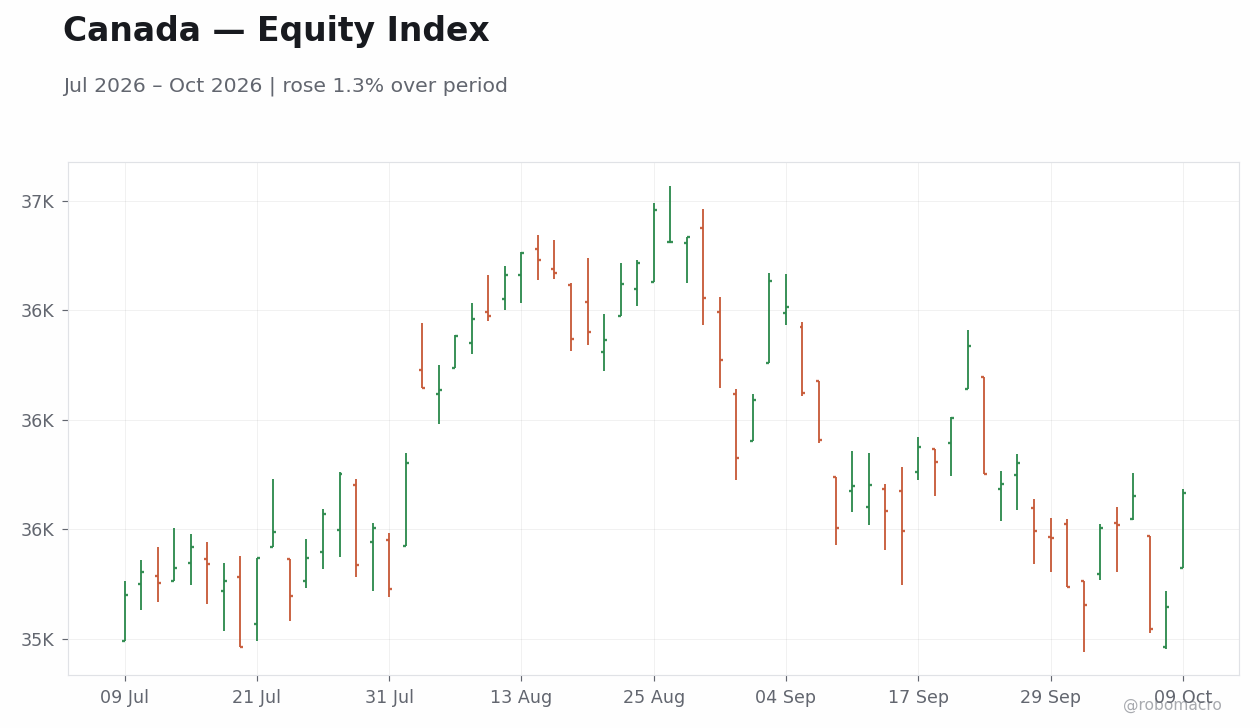
| S&P/TSX | 35,665 | +0.5% | +1.4% | +11.9% |
| FTSE 100 | 10,552 | +0.9% | +1.2% | +6.0% |
| Euro Stoxx 50 | 6,173 | -1.0% | -0.0% | +4.2% |
| DAX | 25,087 | -0.6% | +0.6% | +2.2% |
| CAC 40 | 7,803 | -1.2% | -0.4% | -4.8% |
| FTSE MIB | 49,746 | -1.5% | -1.0% | +9.6% |
| IBEX 35 | 19,033 | -0.3% | +0.1% | +8.8% |
| Nikkei 225 | 69,031 | +1.1% | +0.1% | +33.2% |
| Hang Seng | 24,211 | +1.0% | +1.0% | -8.1% |
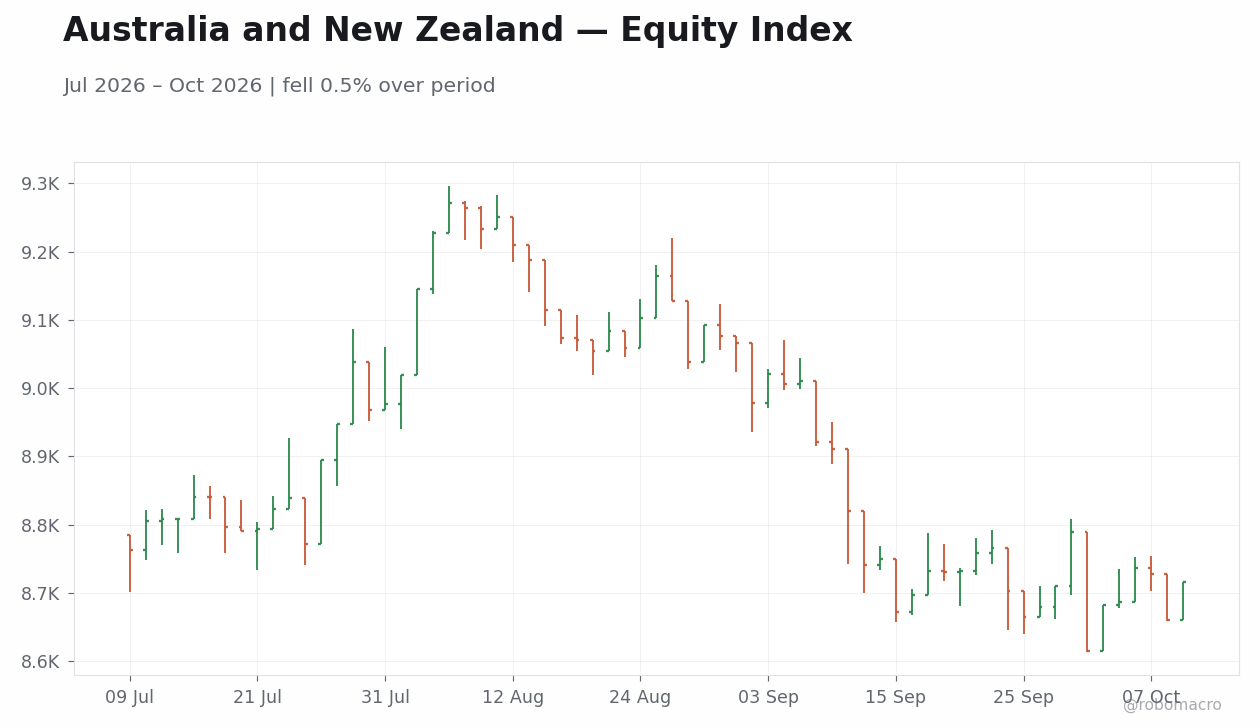
| S&P/ASX 200 | 8,717 | +0.4% | +1.2% | -0.1% |
| KOSPI | 6,626 | -5.0% | -5.0% | +53.8% |
| Nifty 50 | 22,520 | +0.4% | +0.4% | -13.9% |
| Ibovespa | 209,067 | +8.8% | +11.7% | +30.2% |
| IPC Mexico | 66,049 | +2.4% | +3.5% | +3.0% |
| JSE Top 40 | 100,764 | -0.0% | +0.6% | -6.9% |
US equities posted modest gains, with the S&P 500 rising 1.1% to 7,812 and the Dow Jones adding 0.9%, while the Russell 2000 declined 0.9%. Brazil’s Ibovespa led global advances with an 8.8% surge to 209,067, followed by Mexico’s IPC at +2.4%. European indices fell across the board, led by the FTSE MIB’s 1.5% drop and the CAC 40’s 1.2% decline. In Asia, the Nikkei 225 gained 1.1% to 69,031, but the KOSPI slumped 5.0%, highlighting sharp regional divergence. The Hang Seng rose 1.0% while the Nifty 50 edged up just 0.4%. Year-to-date, the Nikkei 225 leads with a 33.2% gain, contrasting with the Nifty 50’s 13.9% decline. Next week’s focus will center on inflation prints and central-bank commentary for further equity direction.
| Index | WoW | MTD | YTD |
|---|---|---|---|
| S&P 500 | +1.1% | +1.9% | +13.9% |
| Nasdaq 100 | +0.2% | +1.2% | +22.5% |
| Dow Jones | +0.9% | +1.4% | +6.8% |
| Russell 2000 | -0.9% | +0.0% | +11.9% |
| S&P/TSX | +0.5% | +1.4% | +11.9% |
| FTSE 100 | +0.9% | +1.2% | +6.0% |
| Euro Stoxx 50 | -1.0% | -0.0% | +4.2% |
| DAX | -0.6% | +0.6% | +2.2% |
| CAC 40 | -1.2% | -0.4% | -4.8% |
| FTSE MIB | -1.5% | -1.0% | +9.6% |
| IBEX 35 | -0.3% | +0.1% | +8.8% |
| Nikkei 225 | +1.1% | +0.1% | +33.2% |
| Hang Seng | +1.0% | +1.0% | -8.1% |
| S&P/ASX 200 | +0.4% | +1.2% | -0.1% |
| KOSPI | -5.0% | -5.0% | +53.8% |
| Nifty 50 | +0.4% | +0.4% | -13.9% |
| Ibovespa | +8.8% | +11.7% | +30.2% |
| IPC Mexico | +2.4% | +3.5% | +3.0% |
| JSE Top 40 | -0.0% | +0.6% | -6.9% |


Week in Review
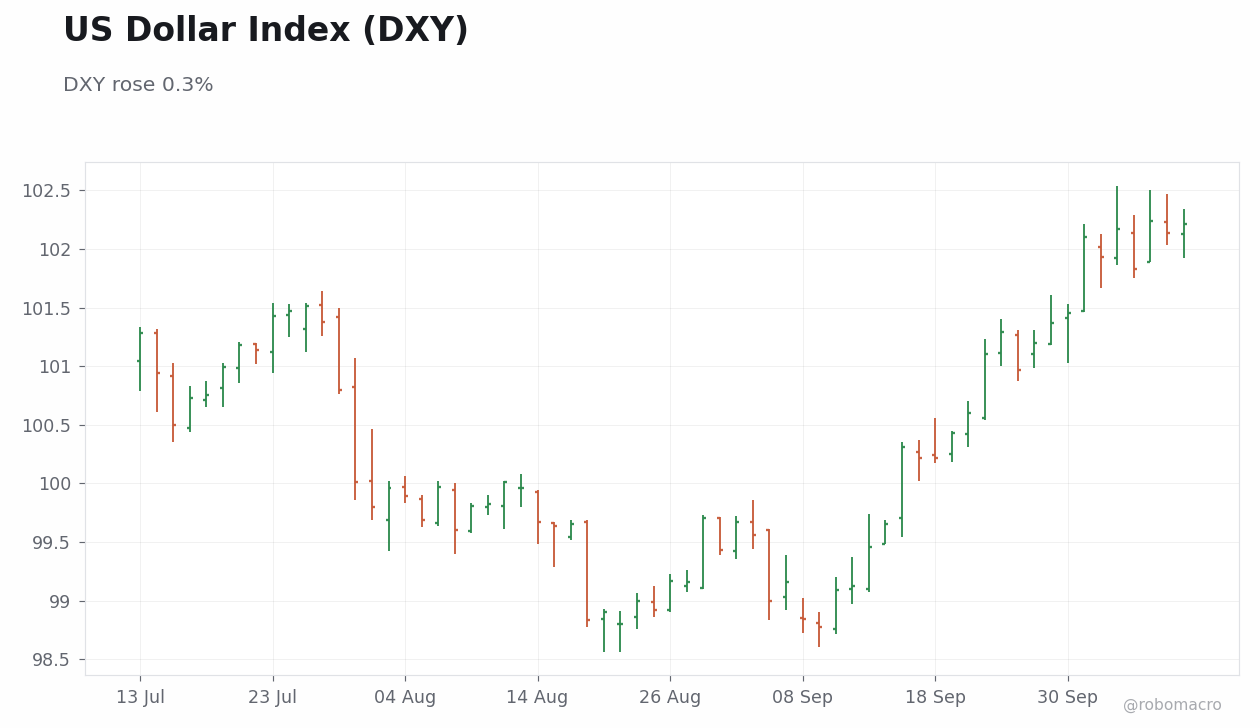
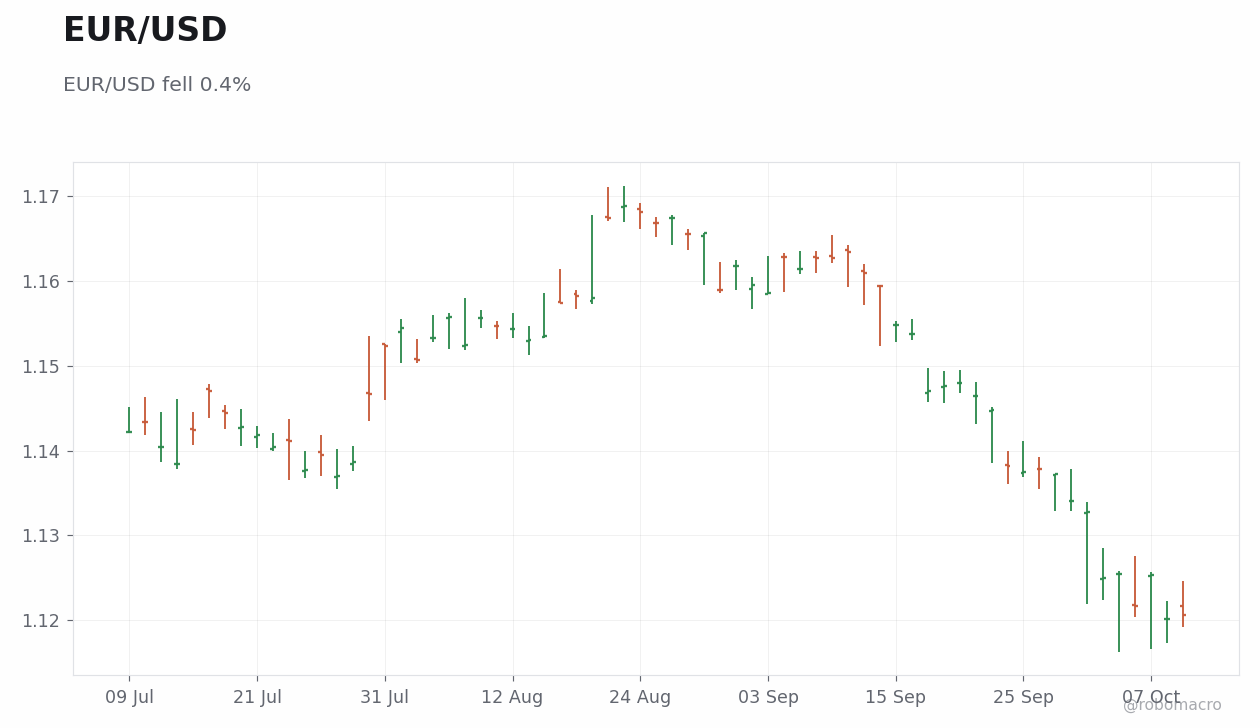
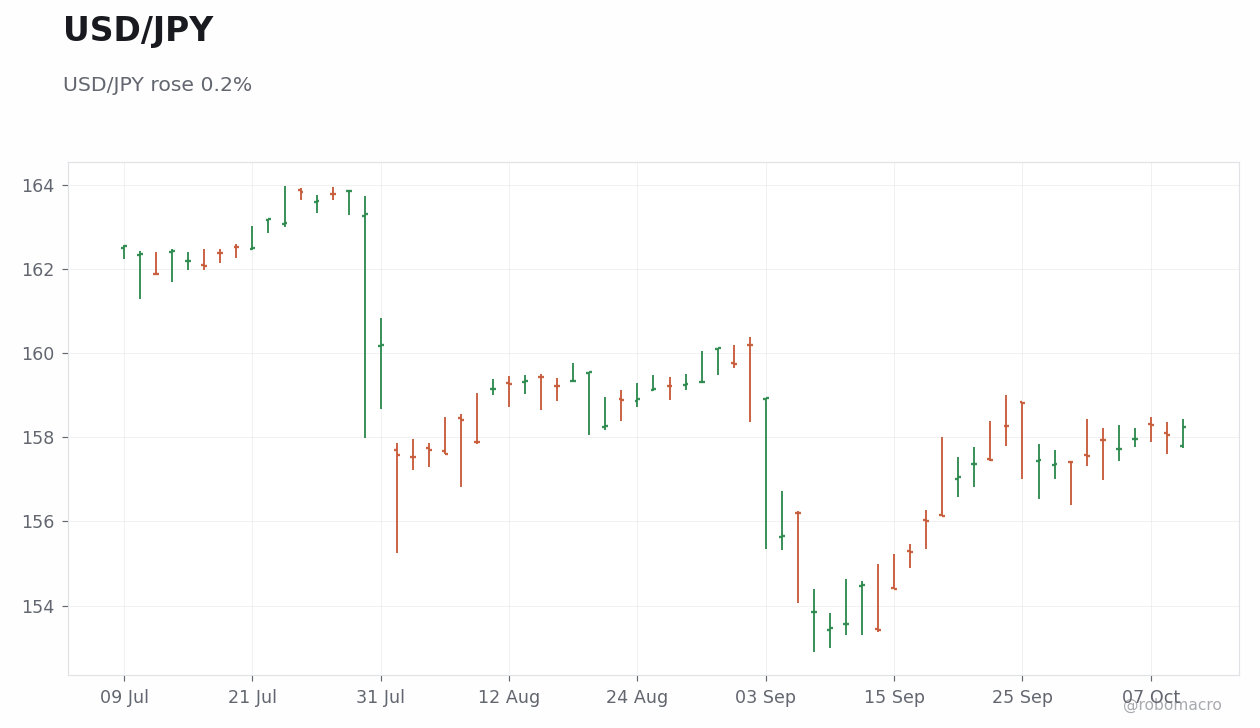
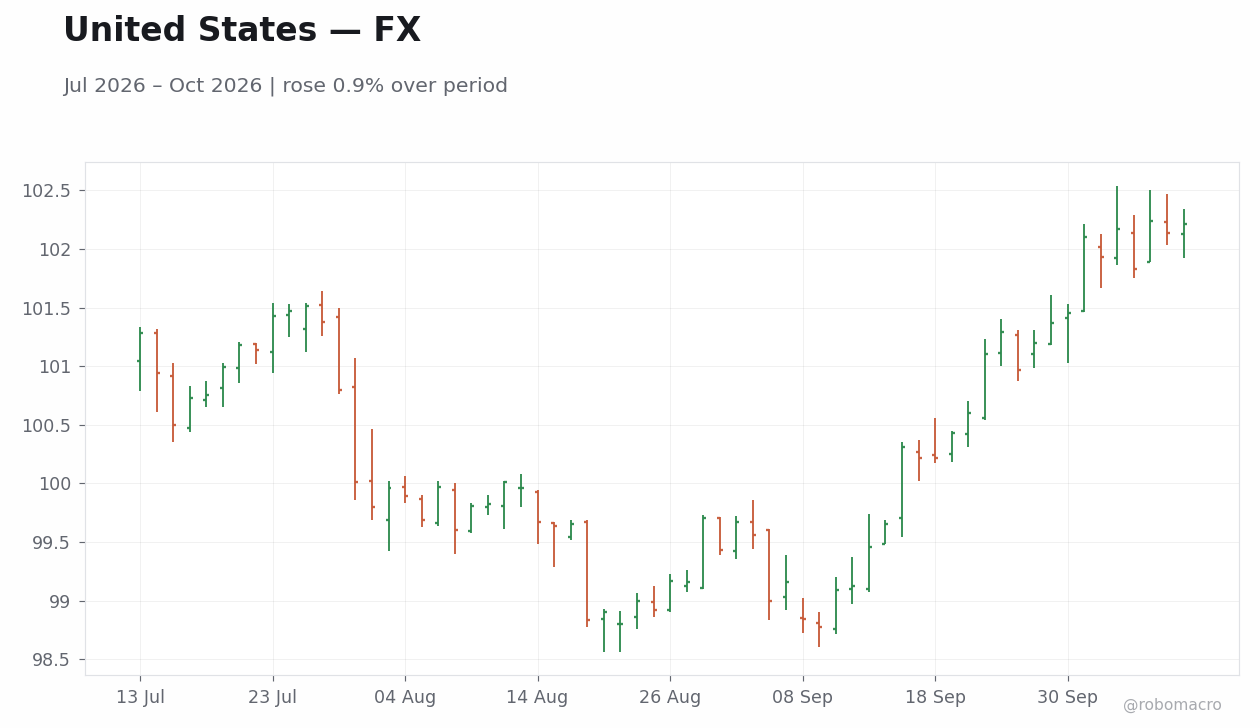
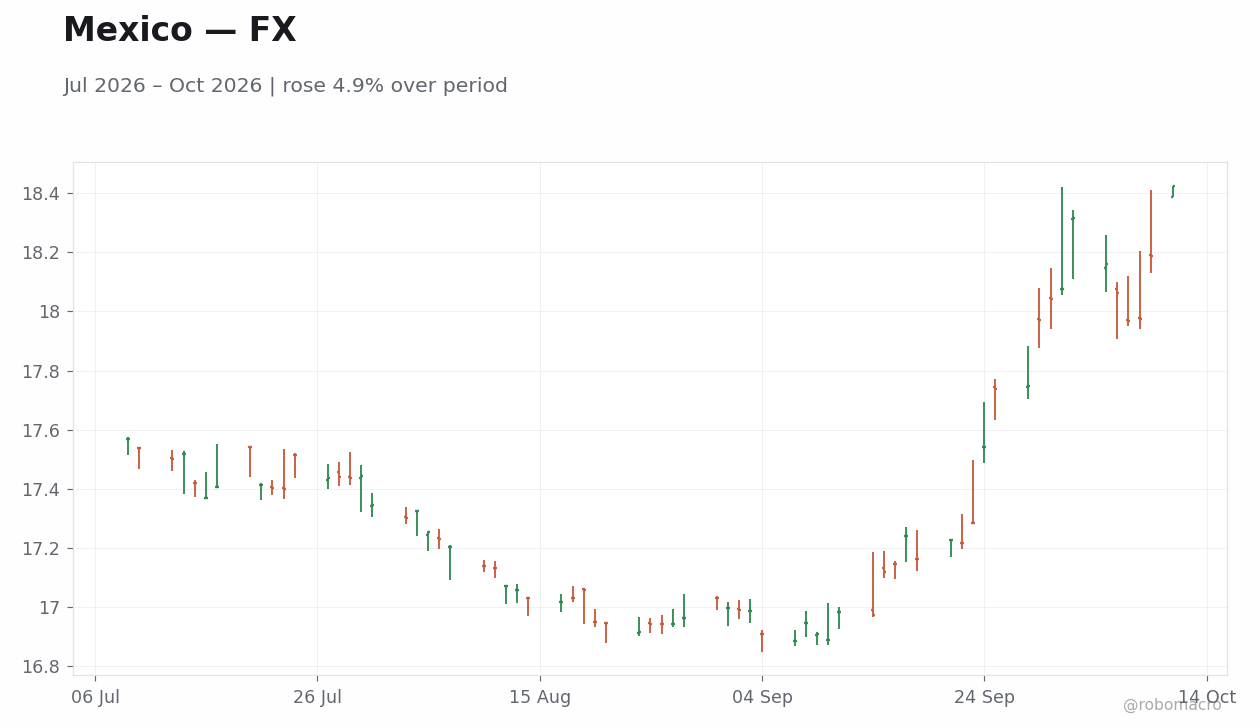
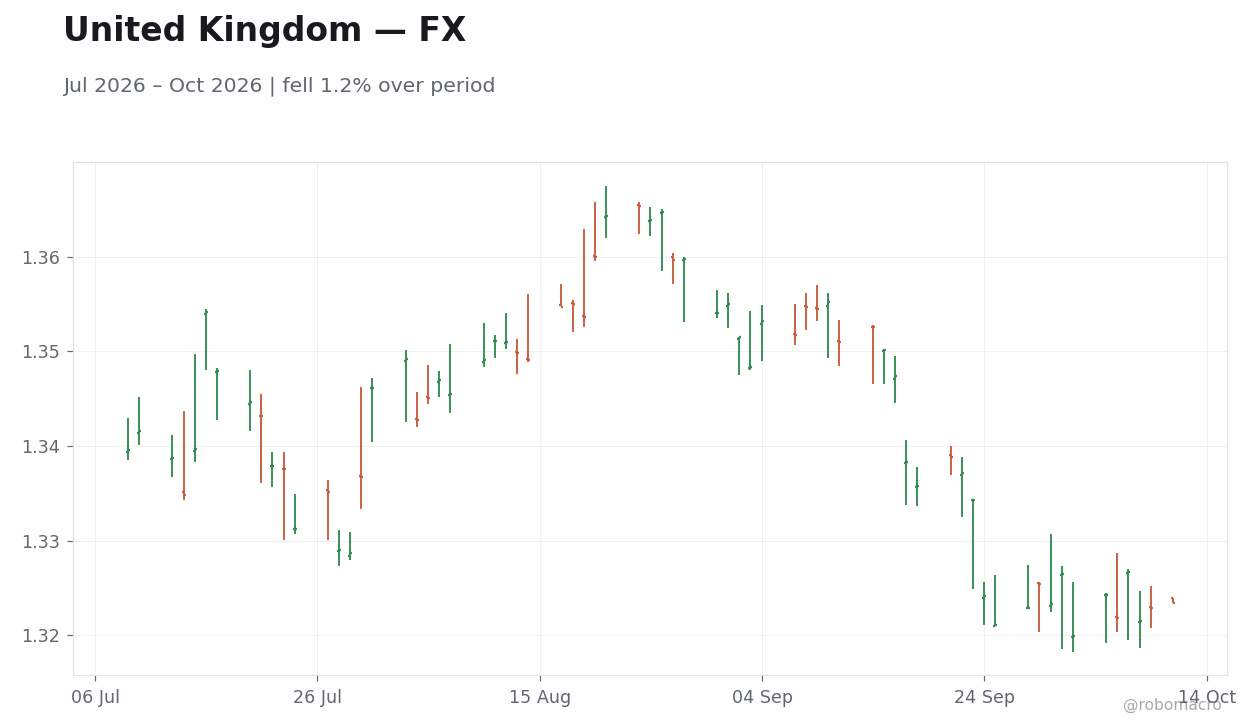
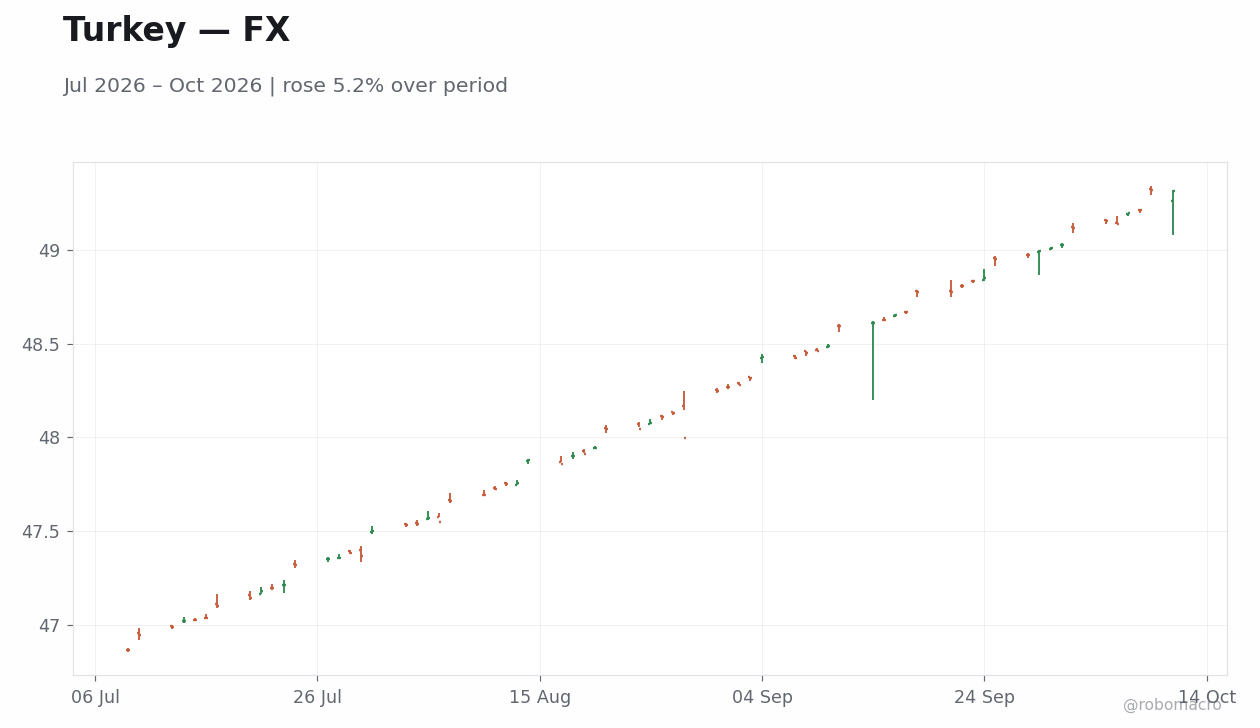
The DXY rose +0.3% on the week to 102.21. The index remained stable in daily trading, closing at 102 each day from Tuesday through Friday. In G10 FX, EUR/USD fell 0.4% to 1.1206, moving from a Monday close of 1.1255 to 1.1217 on Tuesday, rebounding to 1.1254 on Wednesday before declining to 1.1201 on Thursday and ending at 1.1206 on Friday. GBP/USD declined 0.1% to 1.3234 while USD/JPY gained 0.2% to 158.25, AUD/USD rose 0.5% to 0.6988 and NZD/USD fell 0.1% to 0.5612. EM FX showed notable divergence, led by USD/BRL dropping 4.7% to 4.9772, USD/MXN rising 1.4% to 18.43, USD/ZAR falling 0.9% to 16.51, USD/CNY easing 0.3% to 6.6830, USD/INR rising 0.5% to 96.78 and USD/TRY increasing 0.3% to 49.31.
Dollar & G10
Diverging rate differentials offered underlying support for the dollar, with US yields easing while UK and Australian yields rose, reinforcing dollar strength against most G10 currencies amid mixed European data and French fiscal concerns. Softening US labor-market data lifted equities but left the dollar steady overall as Federal Reserve speakers reiterated data dependence with no shift in forward guidance. EUR/USD settled at 1.1206 after a 0.4% decline on the week. GBP/USD closed at 1.3234, down 0.1%, while USD/JPY ended at 158.25 with a 0.2% gain.
EM FX
EM currencies diverged sharply, led by a strong performance in the Brazilian real as USD/BRL fell 4.7% to 4.9772 amid falling local yields and a supportive commodity backdrop. The Mexican peso weakened with USD/MXN rising 1.4% to 18.43 as local yields declined. The South African rand strengthened as USD/ZAR fell 0.9% to 16.51 while USD/TRY rose 0.3% to 49.31 despite local rate volatility. USD/CNY eased 0.3% to 6.6830, reflecting selective EM risk appetite even as Chinese data remained mixed and Indian yields showed differentiation.
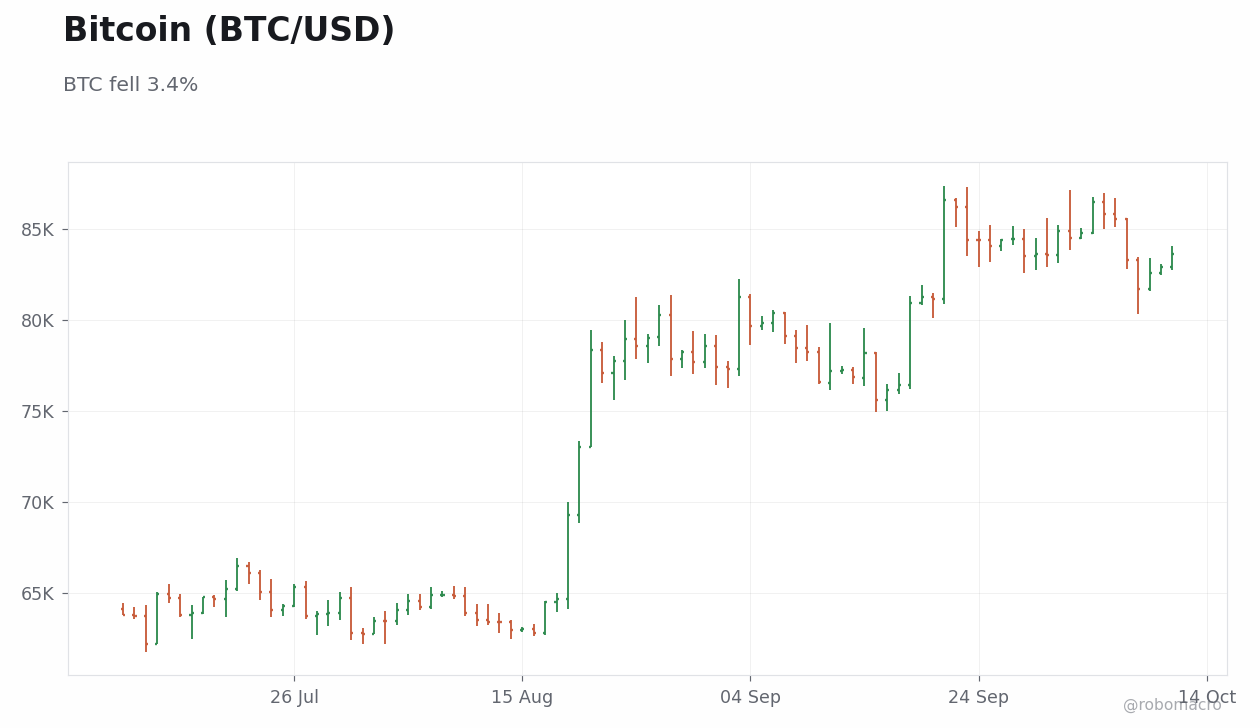
Bitcoin & Crypto
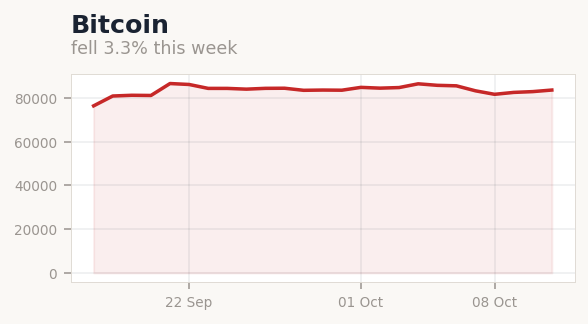
Bitcoin fell 3.4% to $83,583. Price action showed an intra-week decline from 83,276 on Wednesday to 81,676 on Thursday before a partial recovery to 82,546 on Friday and 82,912 on Saturday. Ethereum underperformed with a 7.1% drop to $2,533. Solana declined 8.6% to $111 and XRP fell 7.6% to $1 as broader risk sentiment remained cautious amid ongoing focus on regulatory clarity and the current Bitcoin cycle dynamics.
Week Ahead
A light calendar next week leaves FX and crypto sensitive to any central bank speaker comments on data dependence and rate differentials. No major CB meetings, CPI releases or payrolls data appear scheduled. Trade balance data could influence select EM FX pairs though none are highlighted for the immediate week. In digital assets, continued discussion around regulatory measures for foreign exchange markets and potential crypto clarity could shape sentiment, with no specific on-chain events or ETF deadlines noted.


Week in Review
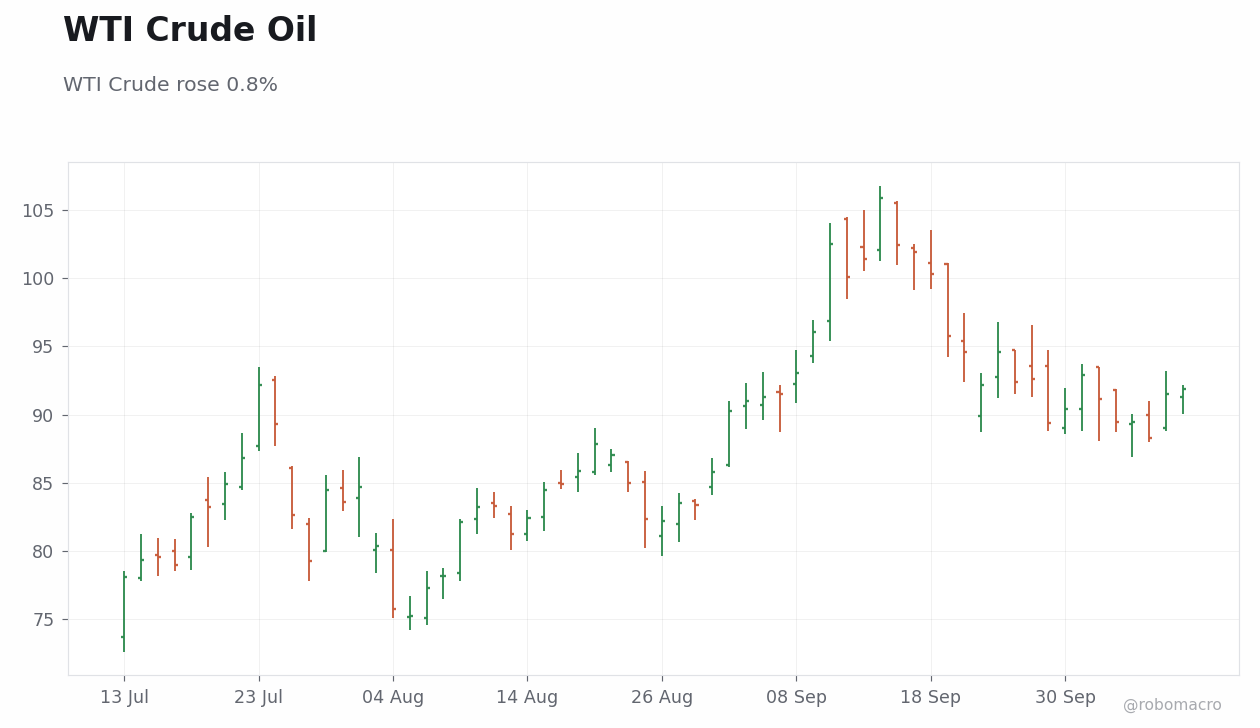
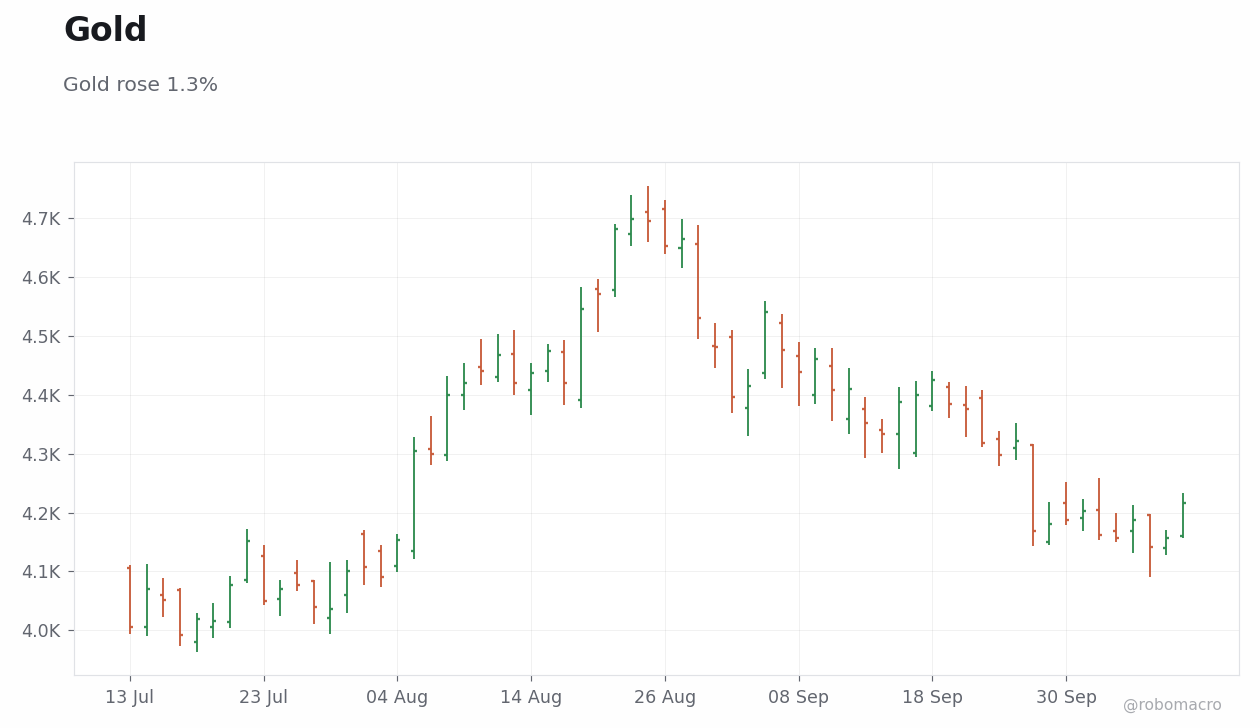
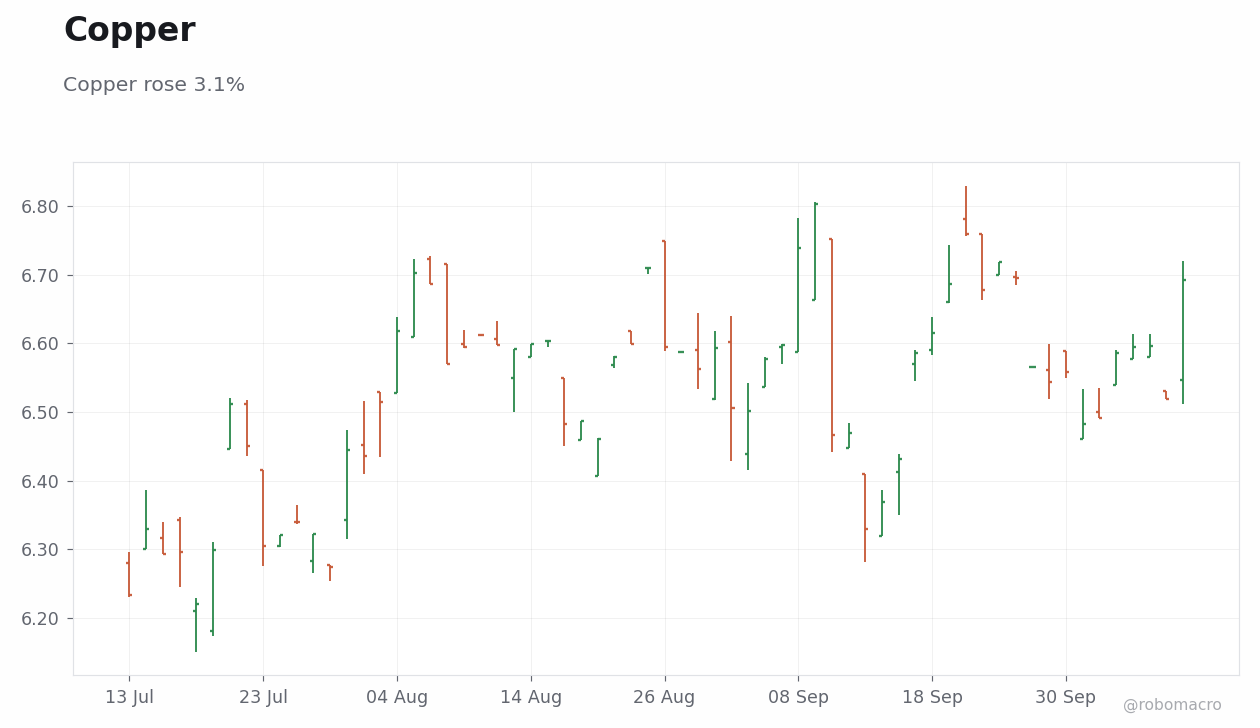
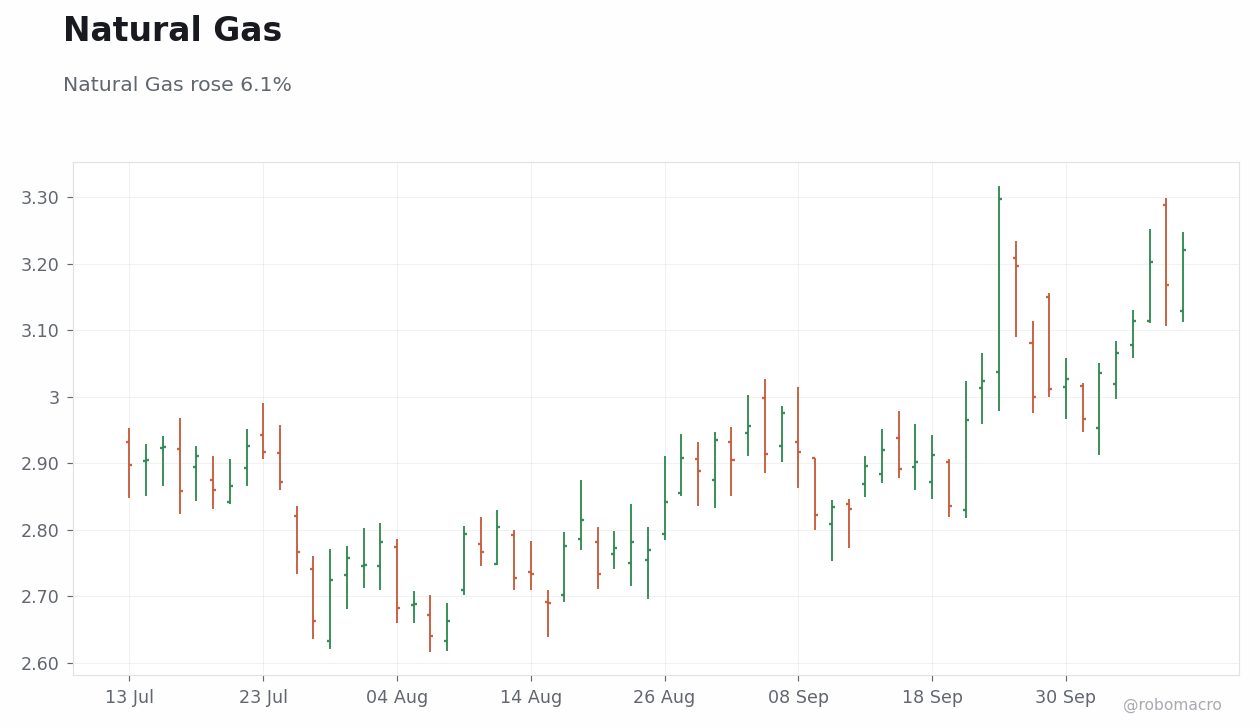
Natural gas was the biggest mover, surging +6.1% week-over-week to 3.22 amid broader gains in the energy complex. WTI Crude rose +0.8% to 91.85 and Brent Crude advanced +2.4% to 104.72, with the former falling to 88.3 on Wednesday before recovering to 91.8 on Friday. Metals also posted gains as gold climbed +1.3% to 4216.30 after declining to 4,141 mid-week and silver rose +1.8% to 61.05 following a drop to 59.1 on Thursday. Copper stood out with a +3.1% increase to 6.69, rebounding from 6.5190 to close at 6.6920, signaling positive growth momentum. In agriculture, wheat declined -1.8% to 671.00 while iron ore fell -0.7% to 90.68. These moves occurred against a backdrop of mixed European data and fiscal concerns in France that supported safe-haven buying in gold.
Energy Complex
WTI Crude settled at 91.85 after a +0.8% weekly gain while Brent Crude reached 104.72, higher by +2.4%. Natural gas outperformed with a +6.1% rise to 3.22, closing at 3.2200 on Friday after fluctuating between 3.1140 and 3.2030 during the week. The strength in the energy complex was supported by geopolitical narratives and potential supply risks. Recent news around global developments underscored the importance of monitoring OPEC actions even in the absence of formal meetings this period. Overall, the complex demonstrated resilience despite some softening in certain economic indicators.
Metals & Ags
Gold ended at 4216.30 after rising +1.3% while silver advanced +1.8% to 61.05, leading to a directional narrowing in the gold-silver ratio. Daily price action in gold showed recovery from a Wednesday low of 4,141 to close at 4,216. Copper’s solid +3.1% weekly performance to 6.69, rebounding from a Thursday low of 6.5190 to 6.6920, pointed to improving sentiment around global growth prospects, in line with positive copper project news. Wheat prices eased -1.8% to 671.00, reflecting contained agricultural pressures. Iron ore similarly declined -0.7% to 90.68 over the period.
Week Ahead
The economic calendar for the following week features no EIA crude or gas inventories reports, no OPEC meetings, no China PMI or industrial data releases, no US CPI figures that could influence inflation and real yields impacting gold, and no central bank meetings affecting commodity currencies such as those for CAD, AUD or BRL. Given the lack of scheduled commodity-relevant events, participants will instead monitor non-calendar risks including geopolitical developments, weather impacts on natural gas and agriculture, and any OPEC diplomacy updates. These factors are likely to drive volatility in the complex, particularly for energy and precious metals. Additionally, any shifts in growth expectations could be felt in industrial metals like copper.
| Pair | Level | WoW | MTD | YTD |
|---|---|---|---|---|
| DXY | 102.21 | +0.3% | +0.1% | +3.9% |
| EUR/USD | 1.1206 | -0.4% | -1.1% | -4.6% |
| GBP/USD | 1.3234 | -0.1% | -0.2% | -1.8% |
| USD/JPY | 158.25 | +0.2% | +0.4% | +1.0% |
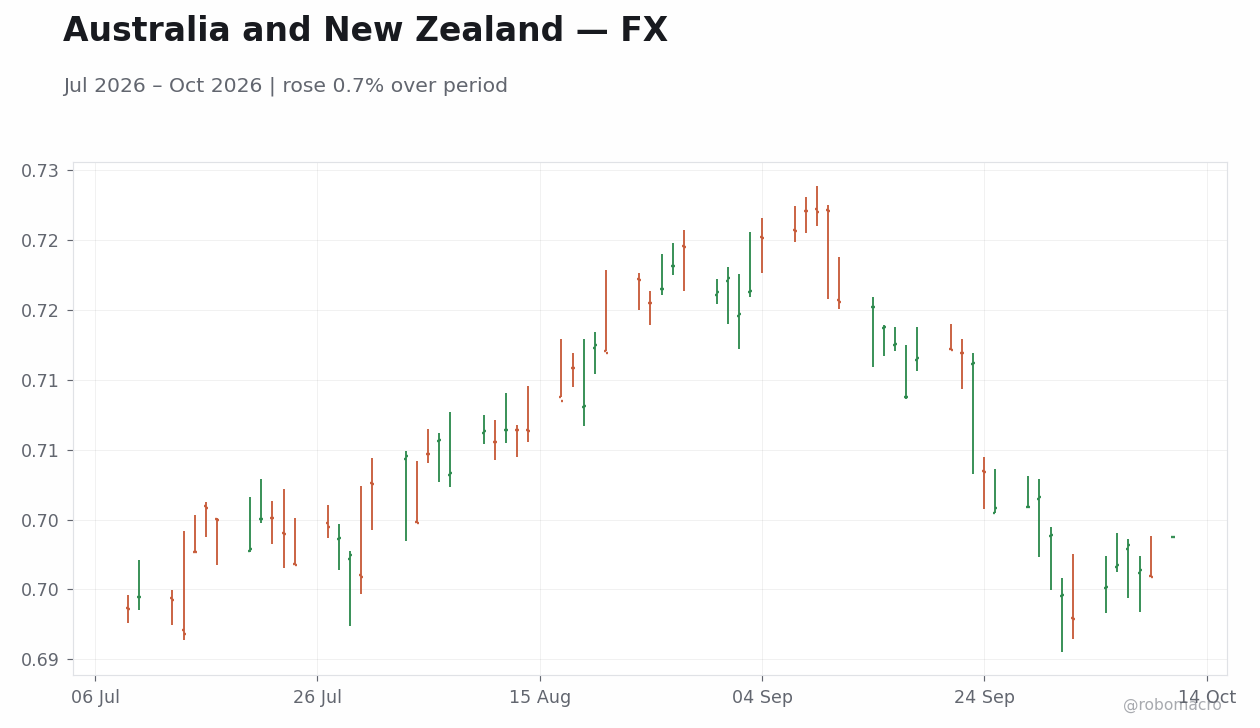
| AUD/USD | 0.6988 | +0.5% | +0.6% | +4.6% |
| NZD/USD | 0.5612 | -0.1% | -0.4% | -2.5% |
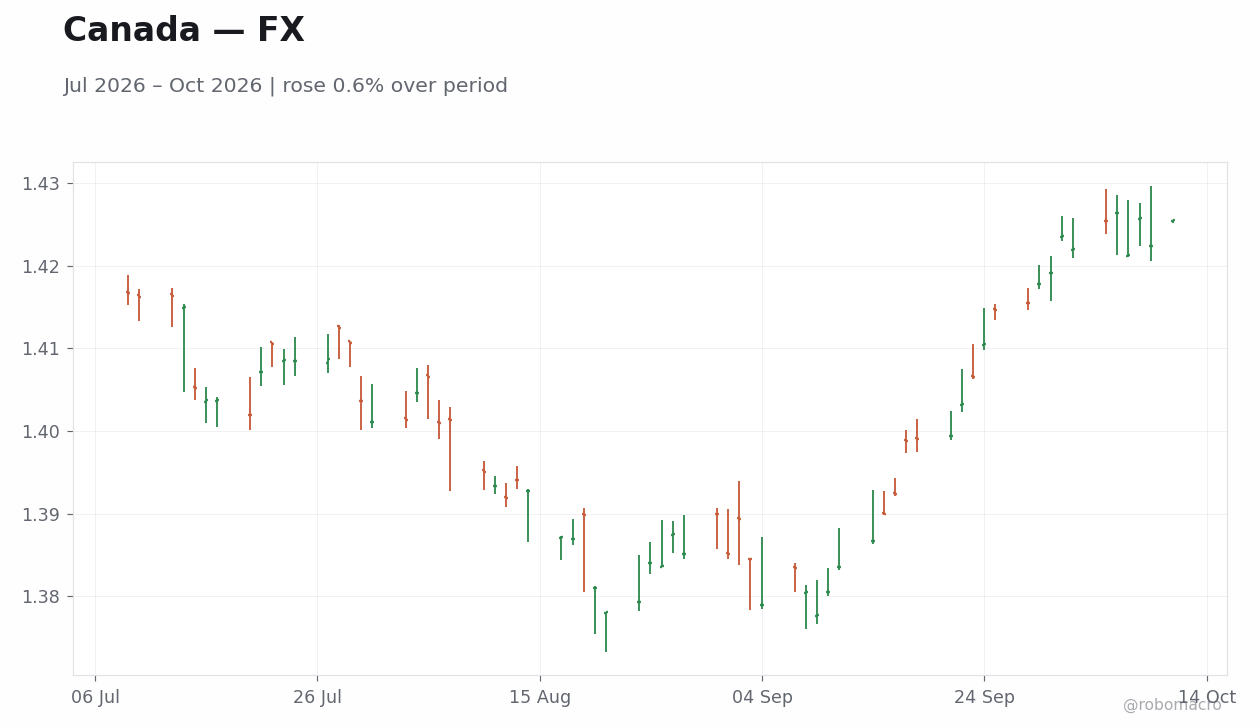
| USD/CAD | 1.4255 | +0.0% | +0.1% | +3.9% |
| USD/CHF | 0.8285 | +0.1% | -0.9% | +4.6% |
| USD/CNY | 6.6830 | -0.3% | -0.3% | -4.5% |
| USD/BRL | 4.9772 | -4.7% | -3.9% | -9.8% |
| USD/MXN | 18.43 | +1.4% | +1.9% | +2.5% |
| USD/INR | 96.78 | +0.5% | +0.9% | +7.6% |
| USD/ZAR | 16.51 | -0.9% | +0.6% | -0.2% |
| USD/TRY | 49.31 | +0.3% | +0.6% | +14.7% |
| Commodity | Level | WoW | MTD | YTD |
|---|---|---|---|---|
| WTI Crude | 91.85 | +0.8% | -1.1% | +60.2% |
| Brent Crude | 104.72 | +2.4% | +2.4% | +72.4% |
| Gold | 4216.30 | +1.3% | +0.3% | -2.6% |
| Silver | 61.05 | +1.8% | +0.5% | -13.5% |
| Copper | 6.69 | +3.1% | +3.2% | +18.6% |
| Natural Gas | 3.22 | +6.1% | +8.5% | -11.0% |
| Wheat | 671.00 | -1.8% | -1.7% | +32.5% |
| Iron Ore | 90.68 | -0.7% | -1.5% | -15.4% |
| Asset | Level | WoW | MTD | YTD |
|---|---|---|---|---|
| Bitcoin | $83,583 | -3.4% | -1.5% | -5.8% |
| Ethereum | $2,533 | -7.1% | -6.4% | -15.6% |
| Solana | $111 | -8.6% | -6.2% | -12.4% |
| XRP | $1 | -7.6% | -6.0% | -25.2% |
The dollar index rose 0.3% to 102.21 as EUR/USD fell 0.4% to 1.1206. AUD/USD led G10 gains, advancing 0.5% to 0.6988, while NZD/USD slipped 0.1%. In emerging markets, USD/BRL plunged 4.7% to 4.9772, the week’s largest decline, contrasting with USD/MXN’s 1.4% rise to 18.43. USD/INR added 0.5% to 96.78 amid broad EM divergence. USD/ZAR declined 0.9% to 16.51 while USD/TRY edged 0.3% higher to 49.31. USD/CNY eased 0.3% to 6.6830. Markets will monitor upcoming inflation prints and central bank speeches for direction. Positioning data and flow trends remain key into next week.
| Asset | Level | WoW |
|---|---|---|
| S&P 500 | 7811.54 | +0.5% |
| Nasdaq 100 | 30883.15 | -0.6% |
| Dow Jones | 51654.95 | +0.8% |
| Russell 2000 | 2806.98 | -1.4% |
| USD/JPY | 158.25 | +0.3% |
| EUR/USD | 1.12 | -0.4% |
| GBP/USD | 1.32 | -0.1% |
| Gold | 4216.3 | +1.4% |
| WTI Crude | 91.85 | +2.7% |
| Bitcoin | 83595.06 | -3.3% |


Labor market shows clear softening. Employment data delivered a sizable downside surprise relative to prior trends while the unemployment rate rose. Equity markets responded with the S&P 500 advancing.
Services activity edges lower. The ISM Services PMI missed consensus and the prior reading, confirming a modest loss of momentum in the dominant sector.
Trade and inventory data reinforce mixed signals. The trade deficit widened as imports rose faster than exports. EIA crude inventories posted a draw, supporting the subsequent WTI advance. Atlanta Fed GDPNow remained near trend before a minor revision. Michigan Consumer Sentiment fell below consensus.
Policy communication stays steady. Multiple Federal Reserve speakers reiterated data dependence without altering guidance. The September FOMC minutes offered no fresh signals on the medium-term path.
Cross-asset price action reflects resilience. The S&P 500 closed the week higher while the Nasdaq 100 and Russell 2000 declined. The 10-year yield finished lower after intra-week swings. Gold advanced and WTI crude rose.
Federal Reserve speakers throughout the week maintained a data-dependent stance without altering guidance. The September FOMC minutes provided no incremental signals on the rate path or balance-sheet plans. Multiple addresses reiterated focus on incoming labor and inflation prints. The soft employment print and services PMI did not prompt any shift in rhetoric. Atlanta Fed GDPNow near trend and the wider trade deficit were noted but left medium-term expectations unchanged. The configuration keeps the committee anchored to sequential data releases rather than any single surprise. Forward guidance therefore remains consistent with the prior meeting outcome.
Employment data printed well below prior expectations, a sizable downside surprise that lifted the unemployment rate. ISM Services PMI missed consensus and the prior reading, pointing to slightly softer service-sector momentum. The trade balance widened to a larger deficit as imports rose faster than exports. ADP employment change offered limited counter-signal to payroll weakness. Atlanta Fed GDPNow remained near trend before a minor revision, consistent with above-trend growth. Michigan Consumer Sentiment fell below consensus, hinting at early consumer caution. EIA crude inventories drew against an expected build, supporting energy prices without immediate inflation pass-through. These releases together depict a labor market cooling while activity and GDP indicators remain resilient, keeping the Federal Reserve on a data-dependent path.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Mon 5 | US | Ny Fed Bill Purchases 4 To | - | - | - |
| Mon 5 | US | Composite PMI Final | 56.0 | 58.4 | 58.4 |
| Mon 5 | US | Services PMI Final | 56.5 | 58.7 | 58.8 |
| Mon 5 | US | Services Sector PMI | 55.4 | 55.0 | 54.9 |
| Mon 5 | US | Services Business Activity | 61.7 | - | 56.5 |
| Mon 5 | US | Services Employment Index | 47.8 | - | 50.1 |
| Mon 5 | US | Services New Orders Index | 60.9 | - | 59.8 |
| Mon 5 | US | Services Prices Index | 72.6 | - | 74.0 |
| Mon 5 | US | 3-Month Treasury Bill Auct | 4.1 | - | 4.0 |
| Mon 5 | US | 6-Month Treasury Bill Auct | 4.3 | - | 4.2 |
| Tue 6 | US | Logistics Managers Index | 66.6 | - | 70.2 |
| Tue 6 | US | ADP Employment Change Week | 20K | - | 24K |
| Tue 6 | US | Exports Level | 310.7bn | - | 315.2bn |
| Tue 6 | US | Imports Level | 403.6bn | - | 420.8bn |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-10-12 | Fed Hammack Speech | - | - |
| 2026-10-13 | Speech by Fed's Waller | - | - |
| 2026-10-13 | ADP Employment Change Weekly | 24K | - |
| 2026-10-13 | Existing Home Sales | 4.0mn | 4.0mn |
| 2026-10-13 | Existing Home Sales Month-over-Mont | -2.0 | - |
| 2026-10-13 | Speech by Fed's Barkin | - | - |
| 2026-10-13 | Monthly Budget Statement | -167.0bn | - |
| 2026-10-13 | Speech by Fed's Collins | - | - |
| 2026-10-14 | Speech by Fed's Bowman | - | - |
| 2026-10-14 | MBA 30-Year Mortgage Rate | 7.5 | - |


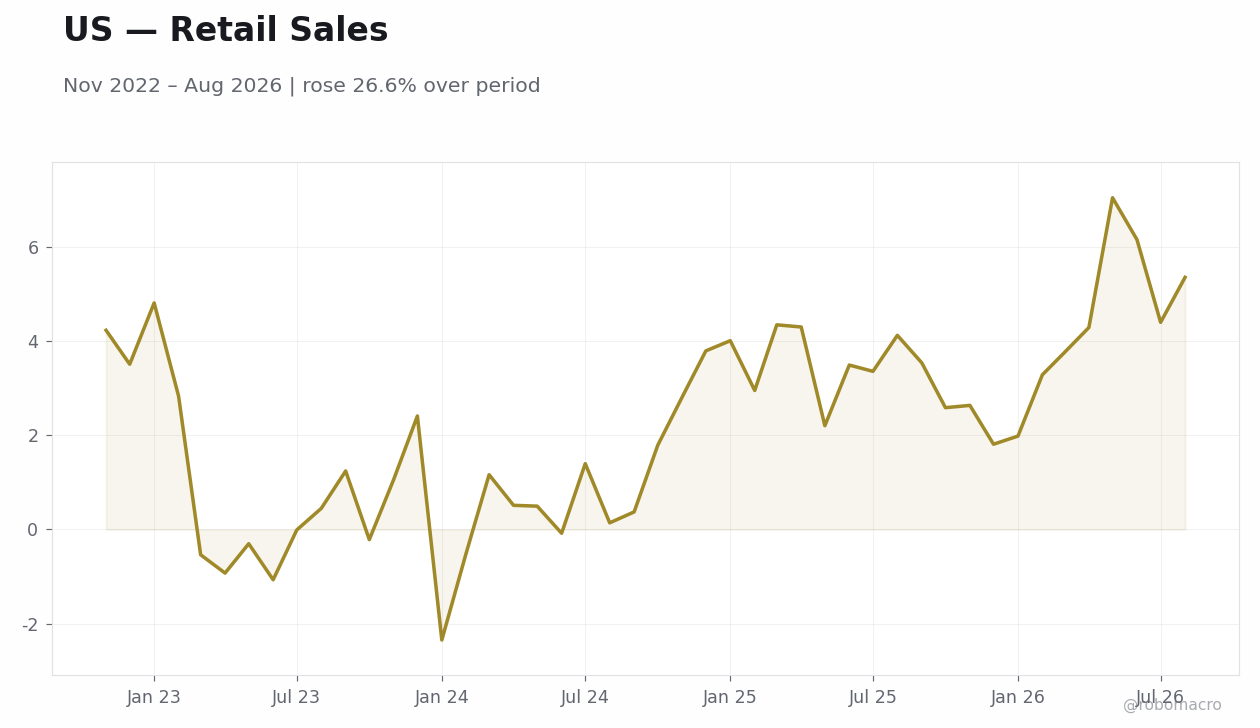
Monday features no high-impact United States releases, allowing markets to digest the prior week’s labor and trade prints. Tuesday brings the CPI report. Wednesday includes PPI and initial jobless claims. Thursday delivers retail sales and import prices. Friday rounds out the week with the University of Michigan final sentiment reading and several Federal Reserve speakers. The Atlanta Fed GDPNow update and any additional central-bank commentary will also be monitored. These releases will inform the growth and inflation backdrop ahead of the next policy meeting. Positioning will focus on whether the recent labor softening persists into the new data flow.
Employment data and the unemployment rate shift the near-term growth outlook toward a slower pace while activity indicators remain above trend. Upside risks center on resilient GDPNow readings and continued equity support from large-cap names. Downside risks include further services PMI weakness or a widening trade deficit pressuring sentiment. Markets appear to price steady policy settings given the absence of guidance shifts from Federal Reserve speakers. Volatility remains contained as gold and crude posted gains while the dollar held near 158.25 versus the yen. Positioning shows rotation away from small caps, with the Russell 2000 declining for the week.
The S&P 500 rose 0.48 percent to 7,811.54 while the Nasdaq 100 declined 0.62 percent to 30,883.15 and the Russell 2000 fell 1.41 percent to 2,806.98 over the week. The 10-year Treasury yield closed lower after intra-week swings. The 2-year yield finished lower. EUR/USD eased 0.43 percent to 1.12 while USD/JPY advanced 0.32 percent to 158.25. WTI crude gained 2.71 percent to 91.85. Gold climbed 1.43 percent to 4,216.30. Bitcoin fell 3.34 percent to 83,595.06. Equity gains concentrated in large-cap names while small caps lagged amid the widening trade deficit and higher mortgage rates.
Dollar strength persisted against a range of crosses, with EUR/USD closing at 1.12 and USD/JPY at 158.25. European inflation prints above forecast and modest Bund yield increases failed to offset the move. China’s NBS Manufacturing PMI beat consensus in the prior week, lifting mainland equities while additional mortgage support was announced. South Korea exports exceeded expectations, supporting KOSPI. Energy price moves, including Brent’s earlier reversal, eased imported inflation risks for net importers without altering the broader US cycle. Trade and currency spillovers therefore remain the primary external inputs for the United States outlook.
| Asset | Level | WoW |
|---|---|---|
| Euro Stoxx 50 | 6173.37 | -1.1% |
| DAX | 25087.27 | -0.7% |
| CAC 40 | 7803.33 | -0.4% |
| EUR/USD | 1.12 | -0.4% |
| EUR/GBP | 0.85 | -0.4% |
| EUR/JPY | 176.84 | -0.4% |
| Gold | 4216.3 | +1.4% |
| Brent Crude | 104.72 | +4.4% |
| Bitcoin | 83595.06 | -3.3% |


| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Mon 5 | ES | S&P Global Services PMI | 57.8 | 56.8 | 58.3 |
| Mon 5 | ES | S&P Global Composite PMI | 55.8 | - | 56.8 |
| Mon 5 | IT | S&P Global Services PMI | 55.2 | - | 51.7 |
| Mon 5 | IT | S&P Global Composite PMI | 53.6 | - | 51.0 |
| Mon 5 | FR | Composite PMI Final | 48.5 | 51.2 | 51.1 |
| Mon 5 | FR | Services PMI Final | 48.0 | 51.4 | 51.2 |
| Mon 5 | DE | Composite PMI Final | 51.8 | 53.8 | 53.8 |
| Mon 5 | DE | Services PMI Final | 49.7 | 52.9 | 52.9 |
| Mon 5 | FR | 12-Month BTF Auction | 3.2 | - | 3.3 |
| Mon 5 | FR | 3-Month BTF Auction | 2.7 | - | 2.8 |
| Mon 5 | FR | 6-Month BTF Auction | 2.9 | - | 3.0 |
| Tue 6 | DE | Factory Orders Month-over- | 3.2 | -1.0 | -10.6 |
| Tue 6 | FR | Industrial Production Mont | -0.60 | 0.30 | -0.30 |
| Tue 6 | FR | Government Budget Balance | -145.9bn | - | -159.6bn |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-10-14 | Wholesale Prices Month-over-Month | 0.90 | 0.70 |
| 2026-10-14 | Wholesale Prices Year-over-Year | 6.8 | - |
| 2026-10-15 | Headline Unemployment Rate | 4.0 | - |
| 2026-10-16 | Trade Balance | 8.2bn | 7.5bn |
| Asset | Level | WoW |
|---|---|---|
| Nikkei 225 | 69030.92 | -1.3% |
| USD/JPY | 158.25 | +0.3% |
| EUR/JPY | 176.84 | -0.4% |
| GBP/JPY | 208.92 | +0.0% |
| Gold | 4216.3 | +1.4% |
| Brent Crude | 104.72 | +4.4% |
| Bitcoin | 83595.06 | -3.3% |


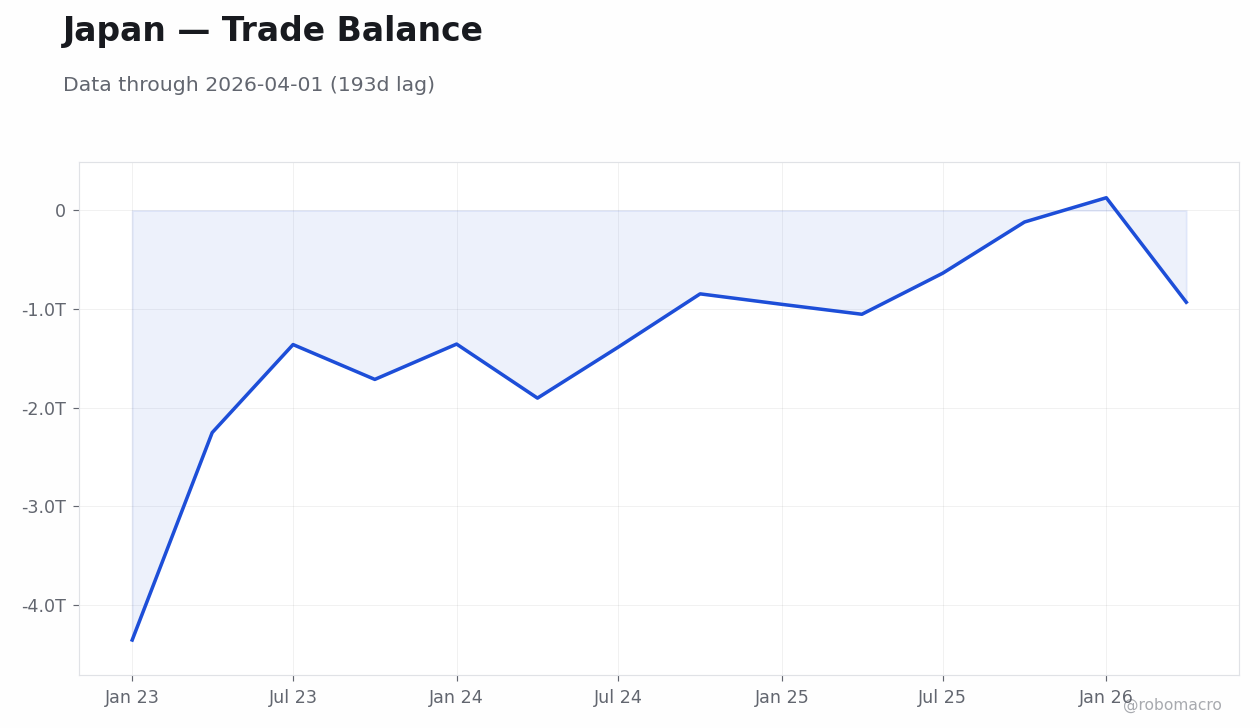
External Balances Strengthen Japan’s August current account surplus reached a level materially above consensus and the prior print, driven by income balance and trade resilience.
Household Spending Shows Mixed Signals Household spending month-over-month missed consensus on October 8, while the year-over-year reading improved. Consumer confidence held at 35.4 on October 5, a modest beat of consensus but below the prior reading.
Equity Markets Navigate Volatility The Nikkei 225 closed the week at 69030.92 after a 1.31 percent decline.
Yields Grind Higher on Fiscal Focus The 10-year JGB yield rose while the 2-year yield finished lower. Finance Minister Takaichi reiterated fiscal discipline commitments amid rising debt-servicing costs.
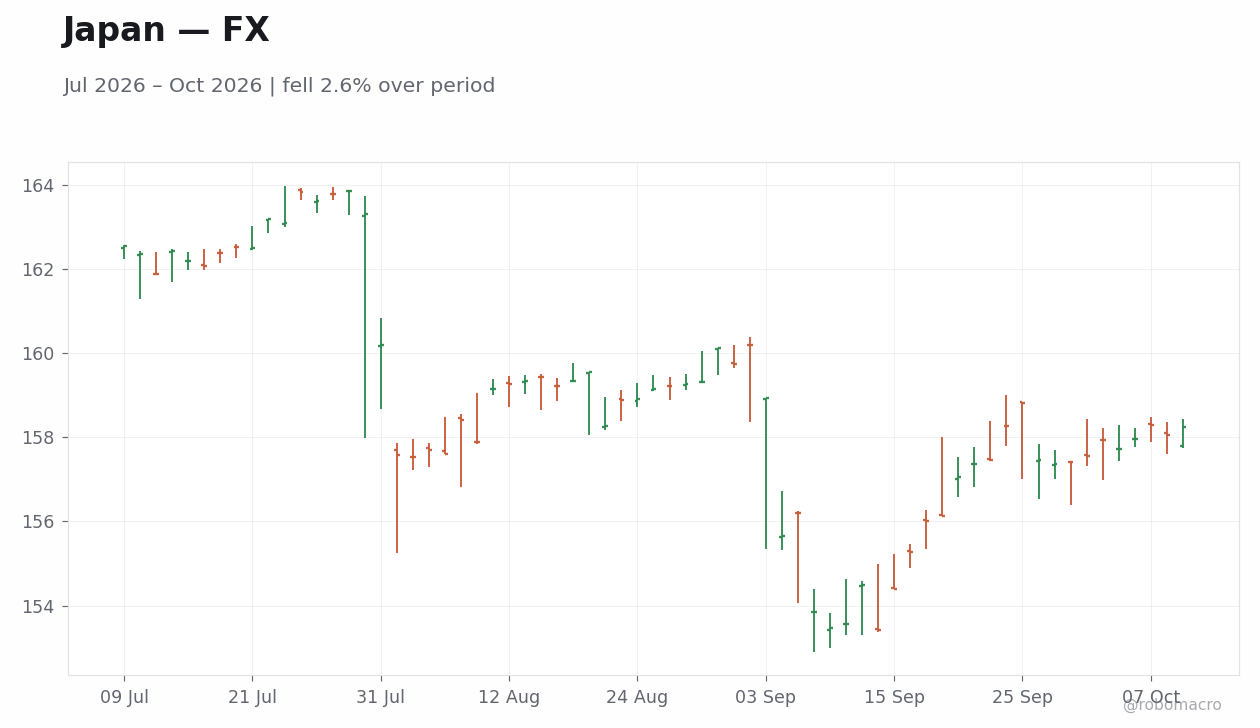
Dollar-Yen Remains Elevated USD/JPY settled at 158.25, up 0.32 percent for the week, as the wide US-Japan yield differential continued to dominate.
Inflation Breadth Expands The Bank of Japan’s regional assessment upgraded two of nine regions and held steady in seven, citing spreading price pressures beyond major urban centers.
Risk Sentiment Diverges Brent crude rose 4.39 percent to 104.72 while gold gained 1.43 percent to 4216.30, leaving Japan’s terms-of-trade picture mixed despite the equity pullback.
Governor Ueda’s October 6 remarks contained no new guidance on the timing or pace of further adjustments to the policy rate, leaving the Bank of Japan’s data-dependent posture unchanged. The regional branch report’s upgrade in two districts and steady assessment in seven others pointed to broadening wage-price dynamics that support the normalization trajectory already under discussion. The outsized current account surplus reinforced the structural income balance that has historically buffered yen weakness, yet officials continued to flag FX volatility as a risk to the inflation outlook. Household spending data offered limited new information on domestic demand, consistent with the Bank’s emphasis on monitoring the full range of incoming releases before the next policy meeting. No speakers altered the forward guidance that policy will remain accommodative until inflation is sustainably above target.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Mon 5 | JP | Consumer Confidence Index | 35.5 | 35.3 | 35.4 |
| Mon 5 | JP | 10-Year JGB Auction | 3.0 | - | 3.1 |
| Tue 6 | JP | BoJ Gov Ueda Speech | - | - | - |
| Tue 6 | JP | Reuters Tankan Index | 21.0 | - | 22.0 |
| Tue 6 | JP | Average Cash Earnings Year | 4.3 | 3.7 | 3.8 |
| Tue 6 | JP | Overtime Pay Year-over-Yea | 4.5 | - | 5.2 |
| Tue 6 | JP | Foreign Exchange Reserves | 1207.5bn | - | 1178.4bn |
| Tue 6 | JP | Boj Jgb Purchase | - | - | - |
| Wed 7 | JP | Coincident Index Prelimina | 121 | - | 119 |
| Wed 7 | JP | Leading Economic Index Pre | 118 | 118 | 118 |
| Wed 7 | JP | Current Account Balance | 2989.0bn | 3194.6bn | 4062.0bn |
| Wed 7 | JP | Foreign Bond Investment Le | -682.3bn | - | -347.6bn |
| Wed 7 | JP | Foreign Stock Investment L | -354.2bn | - | 2191.9bn |
| Wed 7 | JP | 30-Year JGB Auction | 4.1 | - | 4.1 |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-10-14 | Machinery Orders Month-over-Month | -3.7 | 2.5 |
| 2026-10-14 | Machinery Orders Year-over-Year | 11.2 | - |
| 2026-10-14 | BoJ Koeda Speech | - | - |


The calendar opens with limited high-impact Japanese releases, keeping focus on Bank of Japan communications and external data flows. Trade balance figures from the Netherlands and current account data from Denmark on October 12 will provide indirect context for global demand affecting Japanese exports. Mid-week inflation prints in Denmark and the euro area on October 13–14 will be watched for any spillover into imported price pressures. Later in the week, UK and Canadian activity indicators on October 15–16 will inform the broader growth backdrop that shapes yen carry-trade dynamics. The absence of domestic high-frequency releases leaves markets reliant on any additional regional branch commentary or senior official remarks for signals on the upcoming policy decision. Sustained strength in external balances would reinforce the case for gradual normalization, while any further softening in household spending could temper expectations for near-term adjustments.
The strong current account print reduces near-term external vulnerability but leaves the yen exposed to any renewed widening in the US-Japan yield gap. Equity volatility around the 69000 level signals that fiscal credibility concerns could re-emerge if long-term JGB yields push higher without corresponding growth improvement. Upside risks center on further regional inflation upgrades that could accelerate the Bank of Japan’s normalization path, while downside risks stem from persistent household spending weakness that might delay the next policy move. Markets appear to underweight the cumulative effect of two consecutive weeks of regional branch upgrades, which could shift the balance of communications toward earlier tightening if price pressures continue to broaden.
| Asset | Level | WoW |
|---|---|---|
| S&P/TSX | 35664.6 | +0.4% |
| USD/CAD | 1.43 | +0.0% |
| EUR/CAD | 1.59 | -0.6% |
| WTI Crude | 91.85 | +2.7% |
| Natural Gas | 3.22 | +5.0% |
| Gold | 4216.3 | +1.4% |
| Brent Crude | 104.72 | +4.4% |
| Bitcoin | 83595.06 | -3.3% |


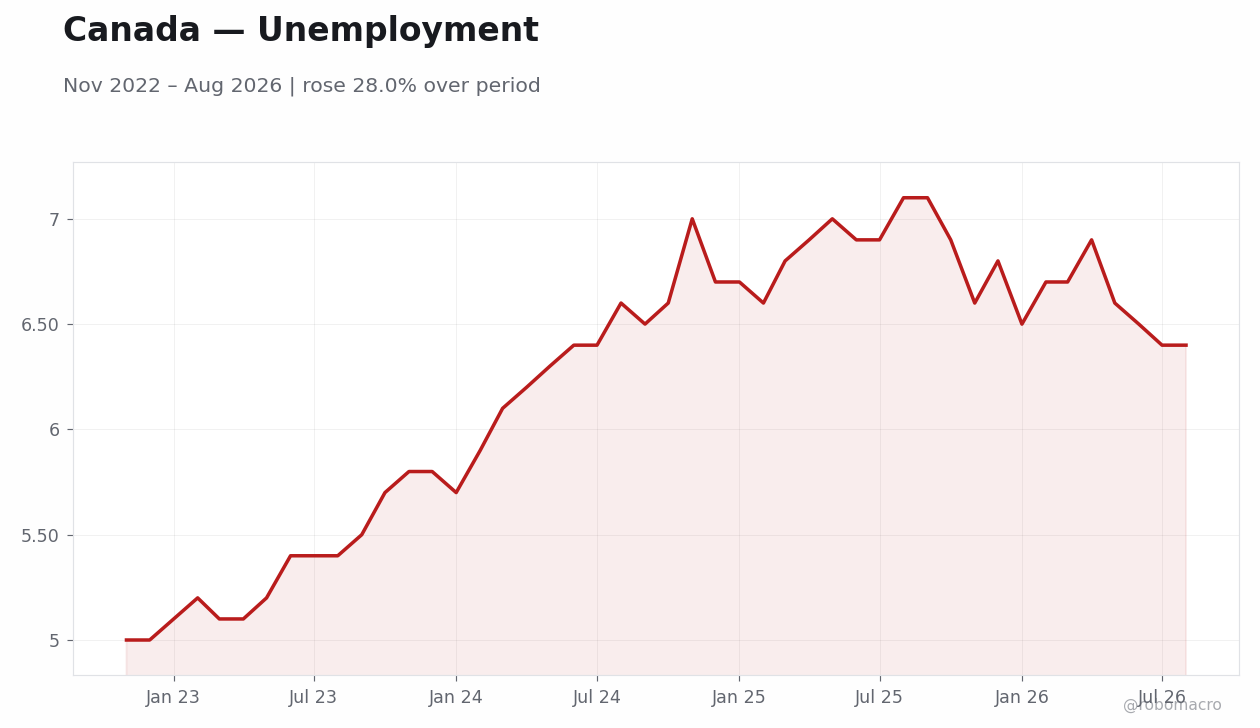
Labor Market Weakness Emerges The September Labour Force Survey delivered the clearest signal of softening domestic demand, with employment declining after August’s drop and full-time positions falling. The unemployment rate rose while labor-force participation eased. These figures extended the cooling trend visible in prior months and reinforced concerns over household income momentum heading into the next Bank of Canada decision window.
Trade Data Provides Counterbalance August trade balance data released mid-week showed a sharp widening to a substantial surplus, exceeding forecasts by a wide margin and reflecting robust energy export volumes ahead of potential tariff adjustments. The print offset some of the labor-market concern and supported CAD stability, with USD/CAD closing the week at 1.43.
Business Sentiment Cools The Ivey PMI Seasonally Adjusted index slumped on October 6, undershooting consensus and marking the steepest one-month decline in recent readings. Despite the miss, the level still indicated expansion and aligned with earlier reports of uneven services momentum. Equity markets digested the mixed signals, with the S&P/TSX finishing at 35664.6 for a 0.41 percent weekly gain.
Yields and Commodities Shape Price Action Canada 2-year yields ended lower after trading in a narrow range, while the 10-year yield settled modestly higher. WTI crude advanced 2.71 percent to 91.85 and Brent rose 4.39 percent to 104.72, providing support to energy-linked sectors even as broader tariff uncertainty lingered. The data configuration leaves growth expectations anchored to incoming labor and external-demand prints rather than any single domestic surprise.
The Bank of Canada receives fresh evidence of labor-market softening that will inform the upcoming decision. Employment losses in September and the rise in the unemployment rate extend the pattern of monthly payroll declines seen since August. The oversized trade surplus offers partial offset through stronger export income, yet the Ivey PMI miss signals fading momentum in private-sector activity. Officials have previously emphasized data dependence and the need to monitor housing-supply constraints alongside inflation; these releases reinforce the case for steady policy settings until the next meeting. No speeches or minutes were released during the week to alter that baseline signal.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Mon 5 | CA | S&P Global Composite PMI | 47.8 | - | 48.7 |
| Mon 5 | CA | S&P Global Services PMI | 46.8 | - | 48.3 |
| Tue 6 | CA | Trade Balance | 790.0mn | 1.7bn | 4.2bn |
| Tue 6 | CA | Exports Level | 76.0bn | - | 77.9bn |
| Tue 6 | CA | Imports Level | 75.2bn | - | 73.7bn |
| Tue 6 | CA | Ivey PMI Seasonally Adjust | 64.3 | 65.2 | 58.2 |
| Wed 7 | CA | 2-Year Bond Auction | 3.5 | - | 3.3 |
| Fri 9 | CA | Headline Unemployment Rate | 6.4 | 6.5 | 6.5 |
| Fri 9 | CA | Employment Change | -42K | 7000 | -68K |
| Fri 9 | CA | Full-Time Employment Chang | -36K | - | -35K |
| Fri 9 | CA | Labor Force Participation | 65.0 | - | 64.8 |
| Fri 9 | CA | Part-Time Employment Chang | -5800 | - | -33K |
| Fri 9 | CA | Average Hourly Wages Year- | 2.0 | - | 2.3 |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-10-14 | BoC Gov Macklem Speech | - | - |
| 2026-10-15 | BoC Rogers Speech | - | - |
| 2026-10-16 | BoC Gov Macklem Speech | - | - |
| 2026-10-16 | Housing Starts Level | 229K | 230K |


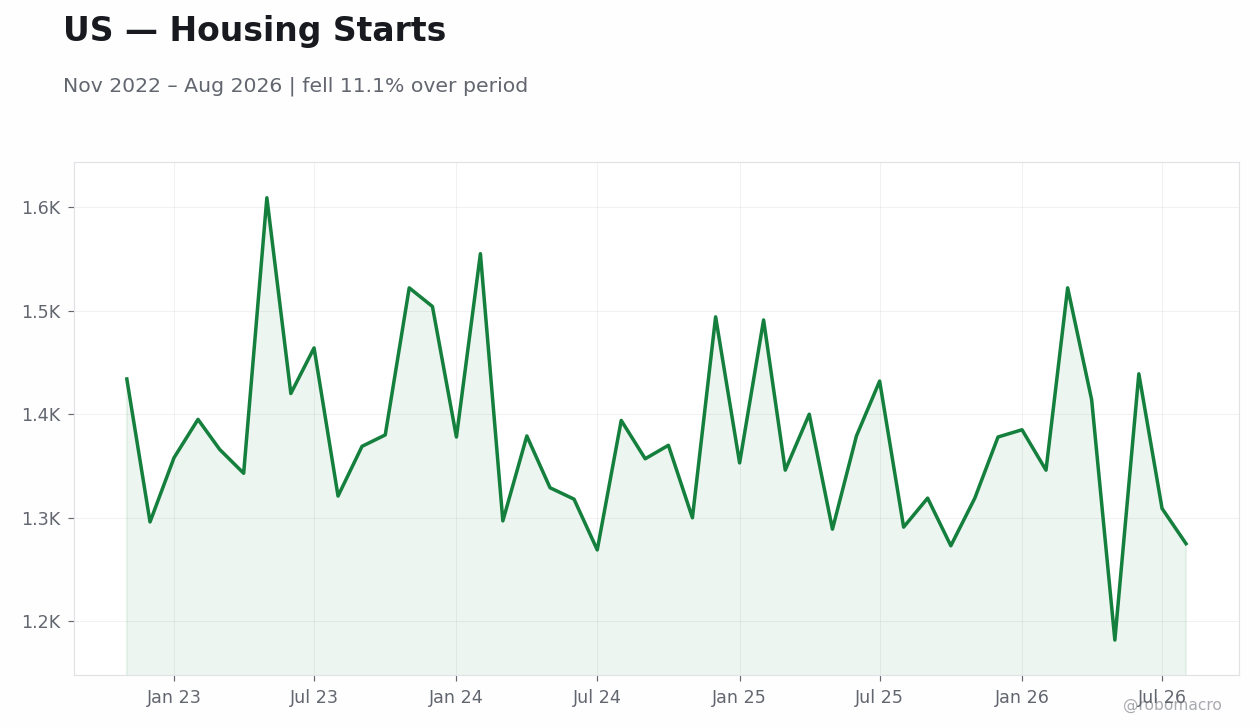
The calendar for October 12–16 contains limited high-impact Canadian releases, leaving markets to focus on external data that could influence CAD and growth assessments. Trade-balance and inflation prints from key partners will be watched for any read-through to Canadian export demand ahead of the next Bank of Canada meeting. Any further labor-market indicators or housing data would carry added weight given the September employment contraction. The absence of domestic events shifts attention to how global commodity moves and tariff developments affect the growth outlook for coming quarters. Officials are expected to maintain their data-dependent stance, with the recent payroll weakness likely to keep easing expectations in play until fresh evidence arrives.
The sharp employment miss raises downside risks to near-term growth and could amplify calls for additional policy accommodation if the trend persists. A sustained trade surplus provides an upside buffer through stronger external demand, yet tariff uncertainty remains an unquantified drag on both exports and investment. The Ivey PMI decline, while still expansionary, highlights the risk that services momentum fades faster than expected and feeds into weaker consumption. Markets appear to underweight the cumulative labor softening visible across the past two months; further downside surprises would shift the balance toward earlier easing at upcoming decisions.
| Asset | Level | WoW |
|---|---|---|
| IPC Bolsa | 66048.57 | +1.6% |
| USD/MXN | 18.42 | +1.4% |
| EUR/MXN | 20.57 | +0.7% |
| WTI Crude | 91.85 | +2.7% |
| Silver | 61.05 | +0.3% |
| Gold | 4216.3 | +1.4% |
| Brent Crude | 104.72 | +4.4% |
| Bitcoin | 83585.54 | -3.4% |


Equity resilience amid peso pressure Mexican equities advanced through the week despite external headwinds. The IPC Bolsa posted a 1.65 percent weekly gain.
Currency and commodity crosscurrents USD/MXN closed higher, rising 1.45 percent. Brent crude climbed 4.39 percent while WTI crude gained 2.71 percent, providing partial offset to peso weakness.
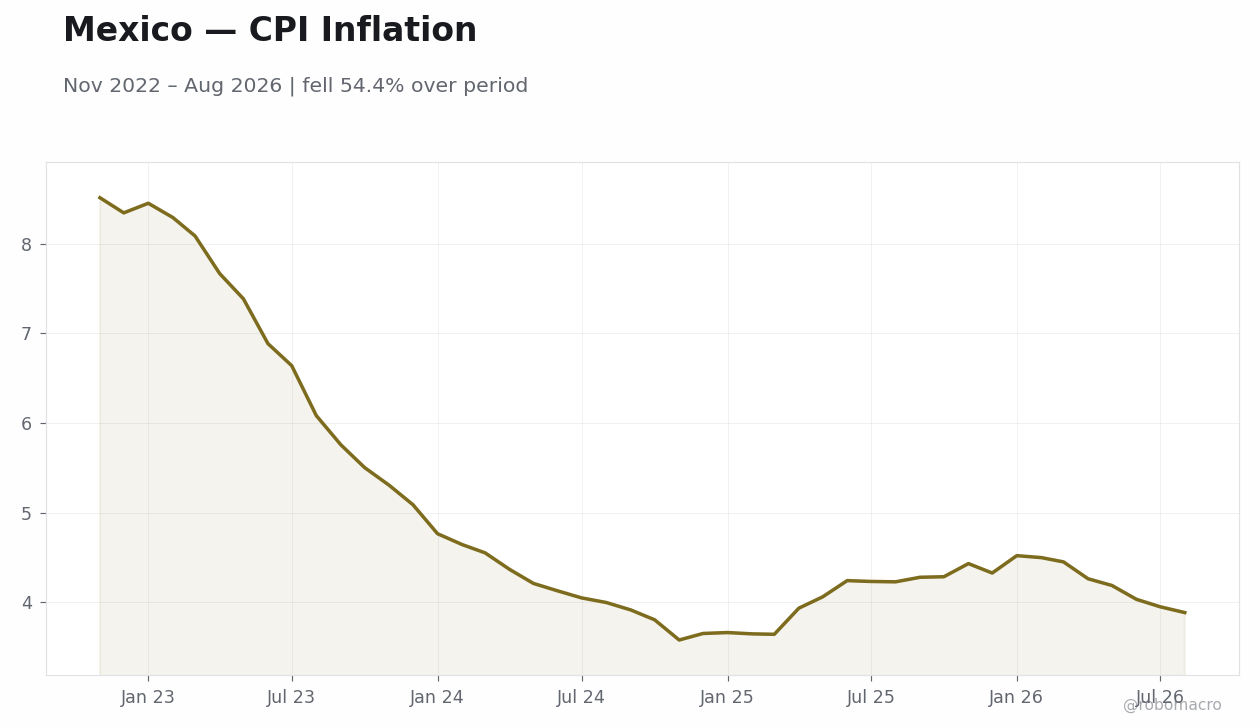
Inflation and sentiment data September inflation accelerated less than consensus forecasts. The Consumer Confidence Index declined, marking the second consecutive monthly drop. These prints arrived against a backdrop of zero high-impact releases on October 5 and October 8.
Policy signal from data flow The modest inflation overshoot and weaker confidence reading reinforced expectations that Banco de Mexico would maintain its current policy stance at the upcoming decision. Nearshoring investment announcements continued to support the external account even as remittance inflows buffered household spending.
Broader market context The week’s price action extended the dollar-broadening pattern. Equity outperformance relative to regional peers reflected domestic resilience.
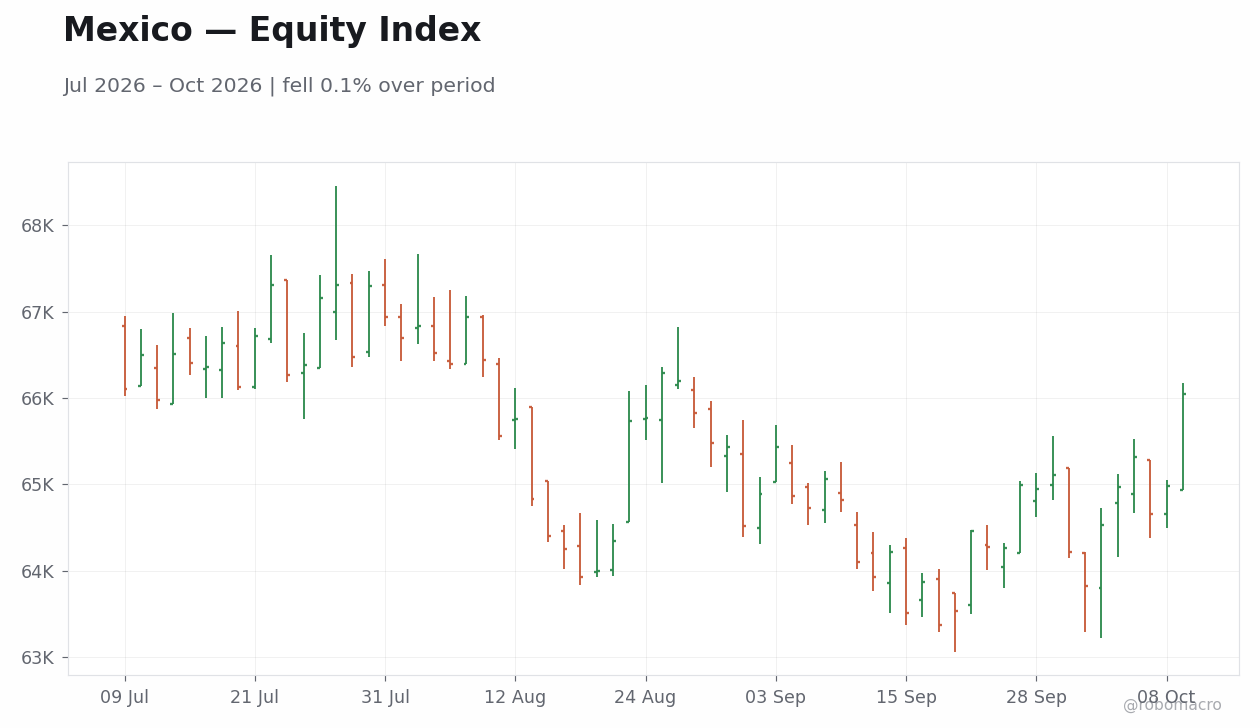
Banco de Mexico left the policy rate unchanged following the September inflation release that showed only modest acceleration. Officials received data indicating the annual rate rose less than consensus, preserving room for the current stance ahead of the next meeting. The Consumer Confidence Index decline supplied an early signal of softening domestic demand that could influence the timing of any future adjustment. No speeches or minutes were released during the week, leaving the inflation outcome as the clearest policy input. The data flow suggests officials will continue to emphasize persistence in core components when assessing the path for coming quarters.
Calendar data unavailable


Attention next week centers on any follow-up commentary from Banco de Mexico officials regarding the September inflation outcome and its implications for the rate path. No high-impact Mexican releases appear on the calendar through October 16, shifting focus to external data that could affect MXN flows. Global oil price volatility tied to supply disruptions will remain relevant for fiscal revenues and the trade balance. Traders will monitor USMCA-related updates for signs of sustained nearshoring momentum. The absence of fresh domestic prints leaves the inflation trajectory and growth indicators from prior months as the dominant inputs for the upcoming policy decision. Market participants will parse any signals on how officials weigh inflation persistence against activity momentum in coming quarters.
Continued dollar breadth poses downside risk to the peso if US yield support persists. Softer consumer confidence raises the possibility that private consumption could weaken faster than expected, challenging the growth outlook. Oil price gains provide an upside buffer for PEMEX-linked revenues but could reverse quickly on weather or geopolitical developments. The modest inflation overshoot leaves limited room for early easing, yet any further downside surprise in activity data could shift the balance toward earlier adjustment.
| Asset | Level | WoW |
|---|---|---|
| Bovespa | 209067.0 | +1.0% |
| USD/BRL | 4.98 | -4.7% |
| EUR/BRL | 5.58 | -4.9% |
| Vale | 13.62 | -3.8% |
| Petrobras | 25.3 | +4.8% |
| WTI Crude | 91.85 | +2.7% |
| Gold | 4216.3 | +1.4% |
| Bitcoin | 83585.55 | -3.4% |


Market moves reflected shifting external and domestic sentiment. The Bovespa closed the week at 209067. USD/BRL fell to 4.98.
Fixed-income markets recorded compression in yields. Term premia declined across the curve amid reduced uncertainty over the fiscal outlook.
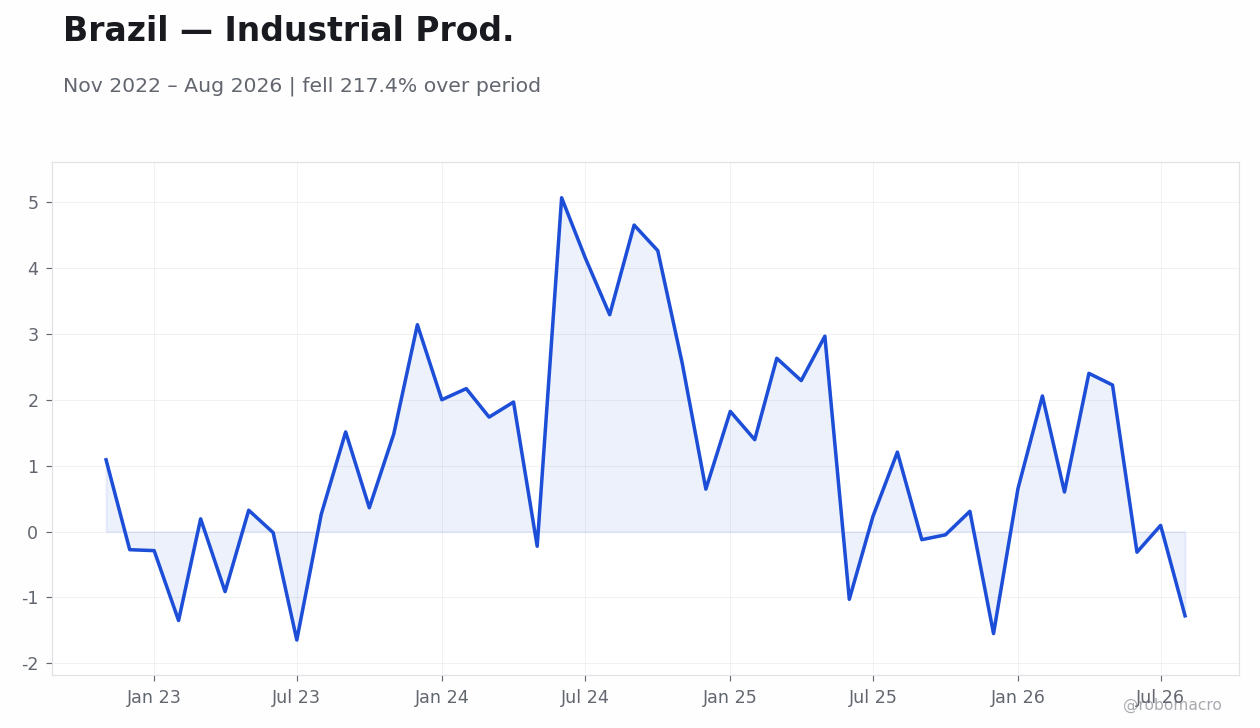
Services activity data softened. The dominant sector showed signs of contraction after earlier resilience in industrial output.
External accounts remained supportive. Commodity-export strength continued to underpin the trade position.
Inflation prints showed modest reacceleration. September readings exceeded consensus, consistent with the rolling off of favorable base effects.
Equity rotation followed the initial advance. Petrobras outperformed while Vale lagged on softer iron-ore sentiment.
Foreign flows turned positive. Equity inflows increased notably during the week.
Commodity prices provided mixed support. WTI crude rose to 91.85, aiding Petrobras, while gold advanced to 4216.3.
Banco Central do Brasil officials maintained their data-dependent stance with no speeches or minutes released during the week. The September services contraction and the modest IPCA overshoot together suggest the inflation trajectory remains consistent with the prior assessment that price pressures are moderating only gradually. The large trade surplus reinforces the external-balance resilience that has allowed the central bank to keep the policy rate at elevated levels without immediate external pressure. Forward guidance continues to emphasize incoming activity and inflation prints ahead of upcoming decisions, with the services PMI now adding to evidence that domestic demand is cooling after earlier resilience. The combination of softer growth signals and contained inflation reacceleration leaves the rate path anchored to the same sequential assessment framework used in prior communications.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Mon 5 | BR | S&P Global Services PMI | 50.5 | - | 49.2 |
| Mon 5 | BR | S&P Global Composite PMI | 49.1 | - | 47.4 |
| Mon 5 | BR | BCB Focus Market Readout | - | - | "" |
| Tue 6 | BR | Trade Balance | 7.4bn | 7.2bn | 7.7bn |
| Fri 9 | BR | Inflation Rate Month-over- | -0.32 | 0.73 | 0.82 |
| Fri 9 | BR | Inflation Rate Year-over-Y | 4.2 | 4.5 | 4.6 |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-10-14 | Business Confidence Index | 44.9 | - |
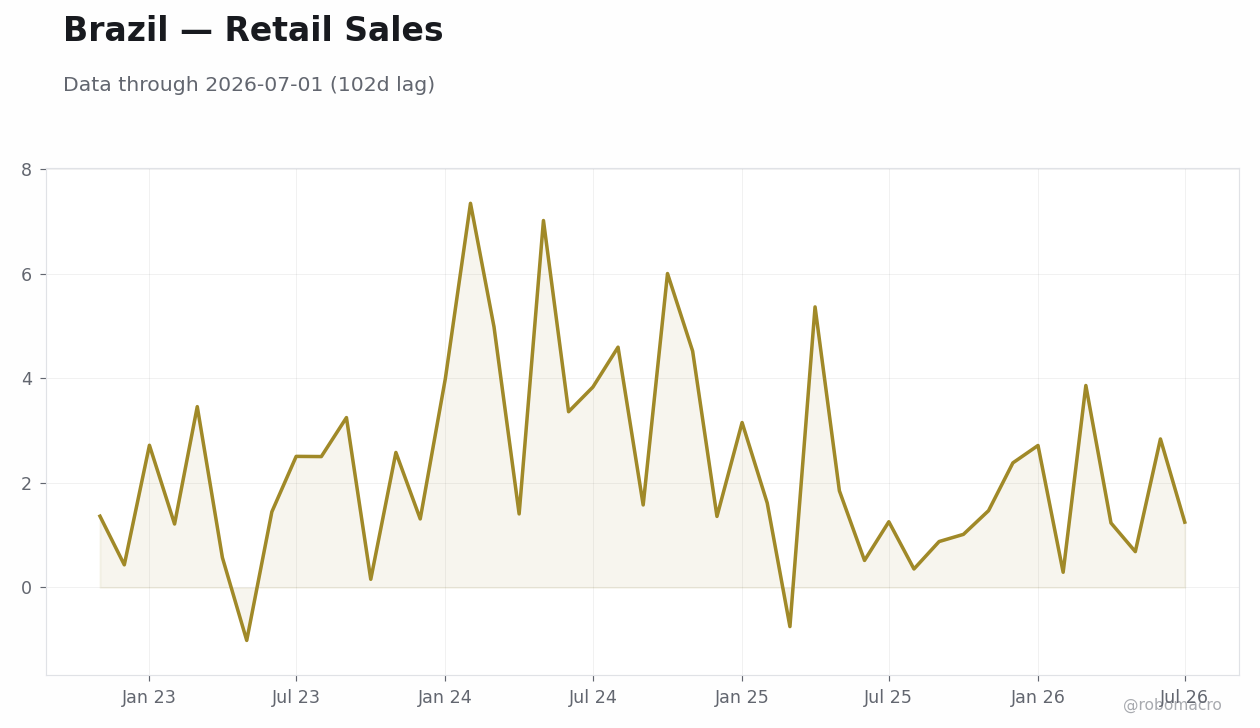
| 2026-10-15 | Retail Sales Month-over-Month | -0.80 | - |


The calendar is light for Brazil-specific releases next week, with attention centered on any runoff-related statements that could further shape fiscal expectations. Markets will monitor incoming global data for spillovers to commodity prices and the real, given the economy’s sensitivity to export revenues. The next inflation prints will be watched closely for confirmation that the September reacceleration remains base-effect driven rather than signaling renewed underlying pressure. Any additional commentary from Banco Central do Brasil speakers will be parsed for updates on how the recent activity softening factors into the assessment of the policy-rate trajectory. Trade-balance follow-through data will provide further color on whether the September surplus marks a sustained improvement in external accounts. Overall, the absence of high-impact domestic releases leaves the focus on the election outcome and its implications for the fiscal framework ahead of upcoming decisions.
The compression in term premia leaves yields vulnerable to any signs that the runoff winner’s fiscal package falls short of investor expectations. Services PMI contraction raises downside risks to growth in coming quarters if the softening broadens beyond the services sector. Upside inflation surprises could limit the scope for policy-rate normalization even if activity data continue to cool. The large trade surplus provides a buffer against external shocks, yet sustained dollar strength elsewhere in emerging markets could still transmit pressure to the real. Markets appear to be pricing a durable improvement in the fiscal-monetary mix, but any reversal in that narrative would likely produce outsized moves in both yields and the currency.
| Asset | Level | WoW |
|---|---|---|
| MERVAL | 2828027.0 | -1.4% |
| USD/ARS | 1516.5 | -0.4% |
| EUR/ARS | 1698.25 | +2.1% |
| Gold | 4216.3 | +1.4% |
| Brent Crude | 104.72 | +4.4% |
| Soybean | 1292.0 | +0.9% |
| Bitcoin | 83587.24 | -3.4% |


Equity and currency stability amid empty calendar Argentine markets operated without any scheduled economic releases, leaving price action in the MERVAL and USD/ARS as the sole domestic signals. The MERVAL posted an early advance before further gains gave way to profit-taking that produced a net 1.44 percent weekly decline to 2,828,027. USD/ARS moved lower through the week to close at 1,516.50.
Commodity tailwinds and fiscal narrative Brent crude rose 4.39 percent to 104.72, while soybeans finished 0.88 percent higher at 1,292.00. These moves reinforced export revenue prospects for energy and agricultural shipments. Fiscal consolidation efforts under the current administration and interest in lithium and copper projects provided the through-line for sentiment in the absence of fresh activity or trade prints.
Cross-asset decoupling from global moves EUR/ARS rose 2.12 percent over the week to 1,698.25 even as USD/ARS firmed, while Bitcoin fell 3.35 percent to 83,587.24. The peso’s stability occurred against a backdrop of dollar strength in other emerging-market crosses.
The Central Bank of Argentina maintained its managed-band framework with no adjustments to liquidity operations or forward guidance during the week. USD/ARS closed each session consistent with the crawling-peg path that has anchored the currency. Daily money-market operations remained the primary tools for managing peso liabilities. With no new inflation or activity data released, the policy-rate setting stayed data-dependent and unchanged ahead of the next meeting. The absence of surprises in the exchange-rate band reinforced the signal that reserve-accumulation targets continue to guide intervention rather than any shift in the monetary stance.
Calendar data unavailable

The domestic calendar carries no high-impact releases in the coming sessions, extending the quiet period into the following week. Market participants will continue to monitor BCRA daily operations for any signals on liquidity management and the trajectory of monetary aggregates. Soybean export registrations and Brent crude price movements will remain the key external inputs for reserve accumulation and fiscal revenue forecasts. The next policy decision will be assessed against the strength of energy and agricultural export flows.
The week’s equity volatility and peso stability highlight the market’s focus on fiscal consolidation progress rather than near-term data surprises. Upside scenarios center on sustained Brent crude above 104 and continued foreign interest in resource projects, which could accelerate reserve accumulation. Downside risks include any slippage in soybean export volumes that could complicate external accounts. The configuration leaves the policy-rate path anchored to incoming external-account data, with limited room for recalibration until fresh prints emerge.
| Asset | Level | WoW |
|---|---|---|
| MSCI Chile | 37.73 | -0.7% |
| MSCI Peru | 90.68 | -0.0% |
| USD/COP | 3186.55 | -0.2% |
| USD/CLP | 975.06 | -0.4% |
| USD/PEN | 3.43 | +2.2% |
| Copper | 6.69 | +1.6% |
| Gold | 4216.3 | +1.4% |
| Brent Crude | 104.72 | +4.4% |
| Bitcoin | 83589.08 | -3.3% |


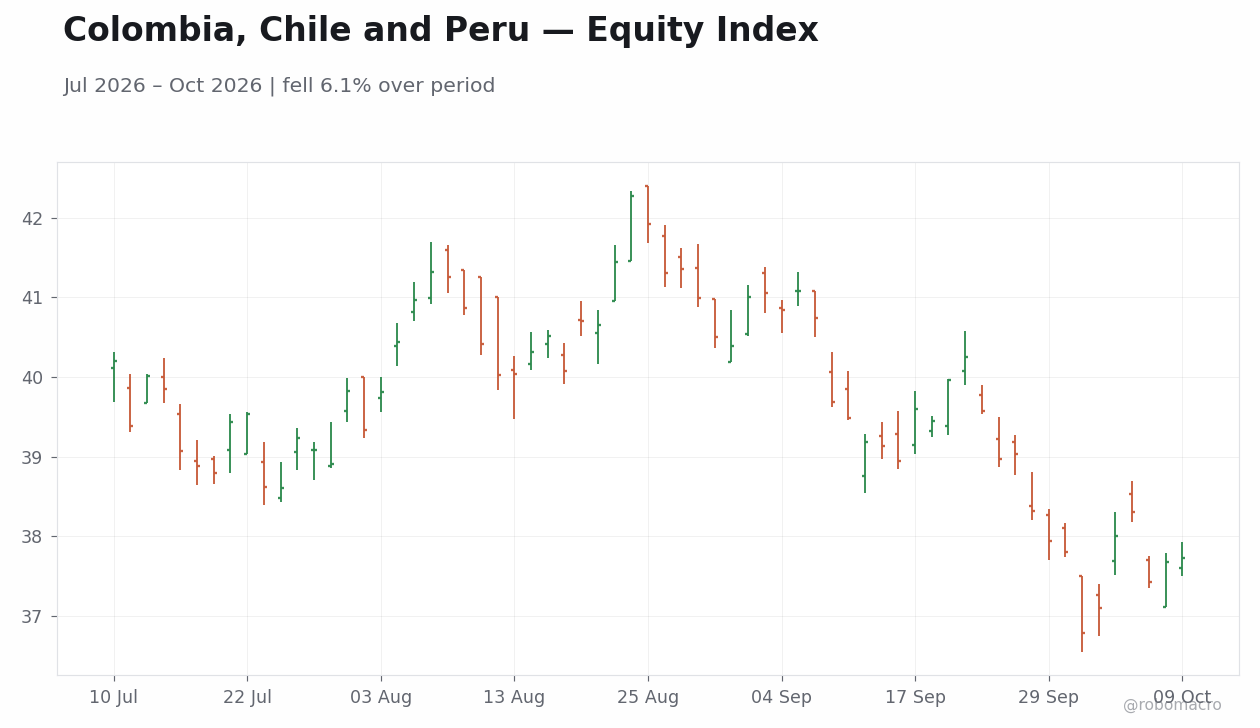
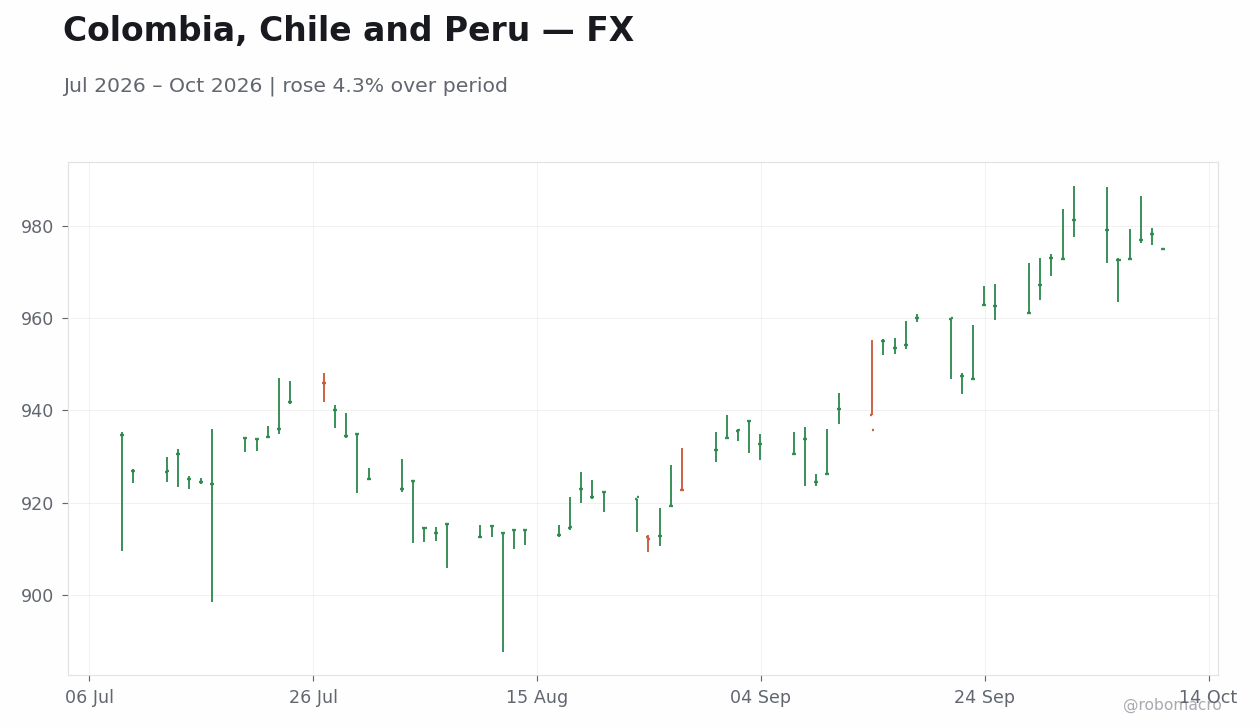
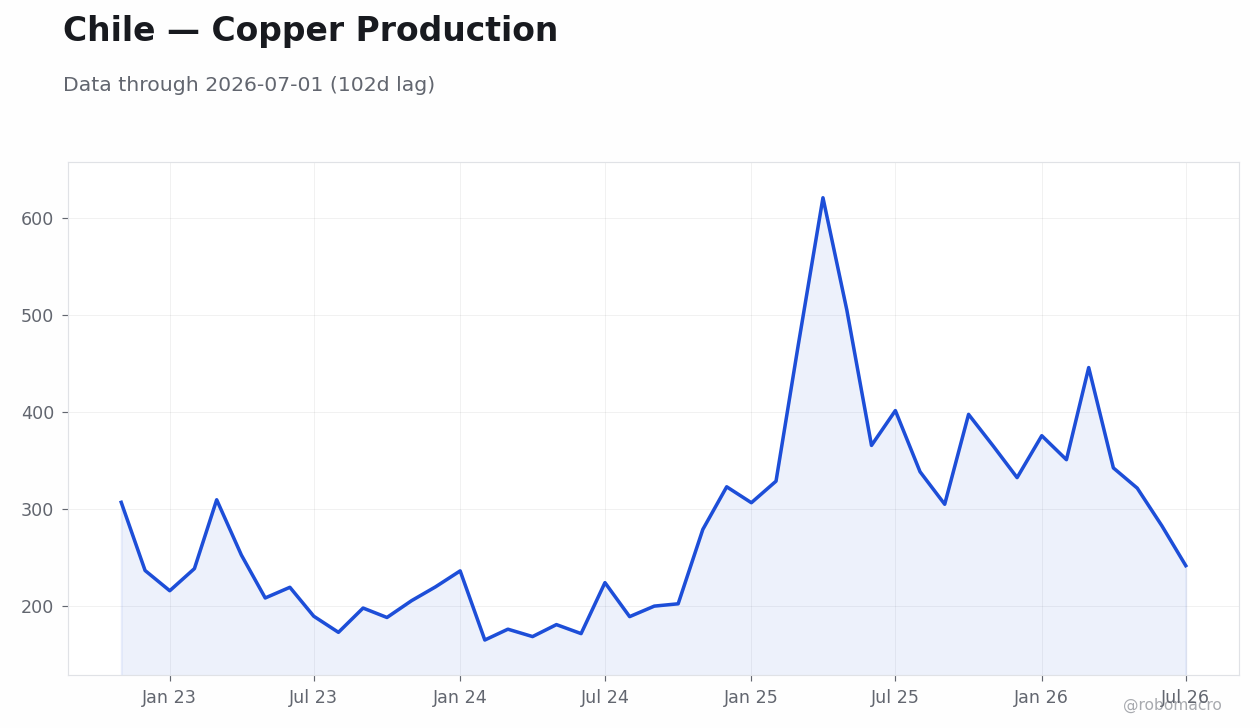
Equity and commodity price action MSCI Chile declined week-over-week after an early-session gain that was later reversed. MSCI Peru ended the week down just 0.01 percent, while MSCI Colombia showed limited movement. Copper rose 1.62 percent to 6.69 and Brent crude advanced 4.39 percent to 104.72, providing direct support to Chilean and Peruvian mining revenues and Colombian oil-linked fiscal balances. Gold climbed 1.43 percent to 4216.30, offering additional lift to Peruvian export receipts.
Currency divergence USD/PEN advanced 2.21 percent to 3.43, marking the clearest weekly depreciation among the three currencies. In contrast, USD/COP fell 0.22 percent to 3186.55 and USD/CLP declined 0.40 percent to 975.06. These moves occurred alongside Brent strength that coincided with relative COP resilience mid-week.
Absence of domestic data No CPI, GDP, trade balance or employment prints were released in Colombia, Chile or Peru between October 5 and 11. The empty calendar left external commodity flows and global risk sentiment as the dominant drivers of price action. Regional equity indices therefore tracked copper and oil moves more closely than any local activity signal.
Regional context versus prior weeks The current week’s mixed FX outcome shows partial reversal of recent external pressure, particularly for COP and CLP, even as PEN continued to weaken. The data suggest commodity price gains offset some external dollar momentum without producing uniform currency appreciation across the bloc.
No BanRep, BCCh or BCRP meetings or communications occurred during the week. Regional policy rates remained unchanged, consistent with the settings reported in prior weeks. With no inflation or activity prints released, officials received no new domestic data to reassess the balance of risks around the current policy stance. The absence of surprises leaves the three central banks in a holding pattern ahead of the next scheduled decisions, where incoming commodity prices and external demand signals will continue to inform inflation trajectories. The data showed no shift in the policy signal from any of the three institutions.
Calendar data unavailable


No high-impact releases are scheduled for Colombia, Chile or Peru between October 12 and 18. Markets will therefore continue to monitor external copper, gold and Brent price action for effects on export revenues and fiscal balances. Copper movements will remain central for Chilean and Peruvian terms of trade ahead of the next BCCh and BCRP meetings. Brent levels will influence Colombian current-account and revenue assessments. Any follow-through from recent commodity volatility could affect FX volatility across USD/COP, USD/CLP and USD/PEN. External US and Chinese data prints will also feed into regional inflation and growth outlooks for the coming quarters.
Commodity price swings remain the dominant near-term driver for the region, with Brent’s weekly gain and copper’s advance already shifting external balances. A sustained reversal in either commodity would pressure fiscal accounts in Colombia and mining royalties in Chile and Peru. The continued weakening of PEN despite gold and copper gains highlights asymmetric FX sensitivity that could widen current-account gaps if the move persists. External yield support could transmit further pressure faster than domestic policy can offset. The lack of local data leaves the outlook more exposed to global risk sentiment than to any single Andean release.
| Asset | Level | WoW |
|---|---|---|
| FTSE 100 | 10552.1 | +0.5% |
| FTSE 250 | 24213.8 | +0.4% |
| GBP/USD | 1.32 | -0.1% |
| GBP/EUR | 1.18 | +0.4% |
| GBP/JPY | 208.92 | +0.0% |
| Brent Crude | 104.72 | +4.4% |
| Gold | 4216.3 | +1.4% |
| UK Nat Gas | 3.22 | +5.0% |
| Bitcoin | 83588.95 | -3.3% |


Construction sector shows tentative stabilization. The S&P Global Construction PMI rose on 6 October, exceeding consensus and the prior reading, though the index remained below the 50 expansion threshold. This beat provided the week’s strongest domestic activity signal and supported modest equity gains early in the period. Housing indicators delivered a contrasting message later in the week.
Housing market data disappoints. Lloyds House Price Index printed flat month-over-month and year-over-year on 7 October against expectations of a modest monthly rise, while the RICS House Price Balance fell, missing consensus. These prints reinforced concerns over property sector momentum ahead of the next Bank of England meeting.
Policy communication maintains hawkish tone. Governor Bailey and Deputy Governor Greene both highlighted persistent inflation risks in speeches on 8 October. The combination kept market focus on the policy rate path without immediate recalibration signals.
Equity and fixed-income markets diverge modestly. The FTSE 100 advanced week-over-week while the 10-year gilt yield climbed, producing a steeper curve. Sterling posted a net decline against the dollar, consistent with external dollar strength observed in prior weeks.
Governor Bailey and Deputy Governor Greene both spoke on 8 October, underscoring risks from embedded inflation and the potential need for sustained policy restrictiveness at the current rate. Mann had earlier flagged that inflation pressures remain embedded, aligning with services firms’ fastest price rises since May. The October Credit Conditions Survey released on 8 October offered no immediate shift in lending expectations. These communications reinforced the Bank of England’s data-dependent stance without altering forward guidance on the policy rate path. The week’s construction beat and housing misses together suggest limited immediate pressure for rate adjustment, keeping the medium-term outlook anchored to incoming inflation and activity prints. No minutes or new quantitative signals emerged to alter the prevailing hawkish tilt.
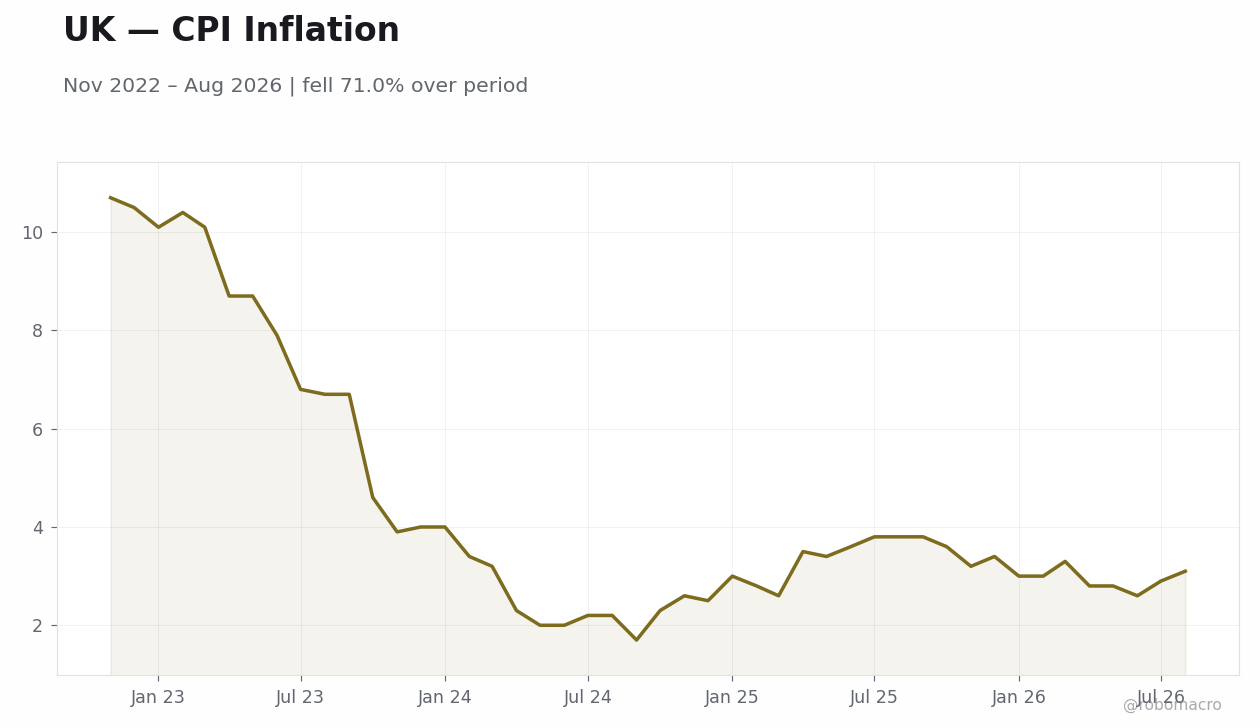
The S&P Global Construction PMI delivered the clearest beat among domestic releases and indicated slower contraction in building activity. Final September services PMI reached a level above the preliminary reading, with firms reporting the fastest price increases since May driven by fuel and wage costs. Lloyds House Price Index month-over-month came in flat on 7 October against consensus, while the year-over-year reading held steady versus the prior period. The RICS House Price Balance deteriorated, missing expectations and confirming softening survey momentum in the property sector. These housing misses occurred alongside Brent crude advancing, adding to input cost pressures already visible in services pricing. The data collectively point to a mid-cycle expansion where construction shows selective resilience but housing remains a drag, supporting the Bank of England’s data-dependent approach to the policy rate. Inflation signals stayed anchored around the recent CPI year-over-year level, with no immediate shift in the growth or disinflation outlook implied by the week’s prints.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Mon 5 | GB | Composite PMI Final | 52.5 | 51.7 | 52.0 |
| Mon 5 | GB | Services PMI Final | 52.5 | 51.7 | 52.1 |
| Tue 6 | GB | BoE Mann Speech | - | - | - |
| Tue 6 | GB | S&P Global Construction PM | 44.3 | 45.2 | 46.1 |
| Tue 6 | GB | Index-Linked Treasury Gilt | 1.7 | - | 1.9 |
| Wed 7 | GB | Lloyds House Price Index M | -0.30 | 0.20 | 0 |
| Wed 7 | GB | Lloyds House Price Index Y | -0.40 | - | 0 |
| Wed 7 | GB | BBA Mortgage Rate | 6.6 | - | 6.6 |
| Wed 7 | GB | Treasury Gilt 2031 Auction | 4.3 | - | 4.8 |
| Wed 7 | GB | Treasury Gilt 2028 Auction | 4.1 | - | 4.3 |
| Wed 7 | GB | RICS House Price Balance | -28.0 | -30.0 | -32.0 |
| Thu 8 | GB | BoE Credit Conditions Surv | - | - | "" |
| Thu 8 | GB | BoE Greene Speech | - | - | - |
| Thu 8 | GB | BoE Gov Bailey Speech | - | - | - |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-10-12 | BoE Breeden Speech | - | - |
| 2026-10-12 | BoE Mann Speech | - | - |
| 2026-10-12 | BRC Retail Sales Monitor Year-over- | 0.50 | 0.70 |
| 2026-10-12 | BoE Greene Speech | - | - |
| 2026-10-13 | BoE Dhingra Speech | - | - |
| 2026-10-13 | BoE Breeden Speech | - | - |
| 2026-10-14 | BoE Gov Bailey Speech | - | - |
| 2026-10-14 | BoE Pill Speech | - | - |
| 2026-10-14 | BoE Pill Speech | - | - |
| 2026-10-14 | BoE Woods Speech | - | - |


Attention next week turns to the absence of high-impact UK releases through 16 October, with the calendar featuring only lower-tier items such as trade balance data from peer economies. Markets will monitor any follow-through from the 8 October BoE speeches and the Credit Conditions Survey for clues on lending conditions. Global factors including US CPI and potential fiscal headlines will likely drive sterling and gilt moves more than domestic prints. The policy rate remains the focal point, with positioning expected to stay light ahead of the next scheduled Bank of England communication. Energy price volatility around Brent levels could continue to influence inflation expectations. Cross-border spillovers from euro-area and US data will shape relative yield differentials and GBP crosses.
The week’s housing misses raise downside risks to domestic demand if property weakness persists into the next quarter. Construction resilience offers a modest offset but remains insufficient to alter the broader mid-cycle narrative. Positioning in gilts appears extended after the yield rise, leaving room for reversal if global yields ease. Sterling’s weekly decline against the dollar highlights sensitivity to external dollar strength rather than local data surprises. Volatility in Brent crude near recent levels introduces upside inflation risks that could reinforce the Bank of England’s hawkish rhetoric. Flow considerations suggest limited conviction ahead of a quiet domestic calendar, with any fiscal surprises capable of widening gilt spreads.
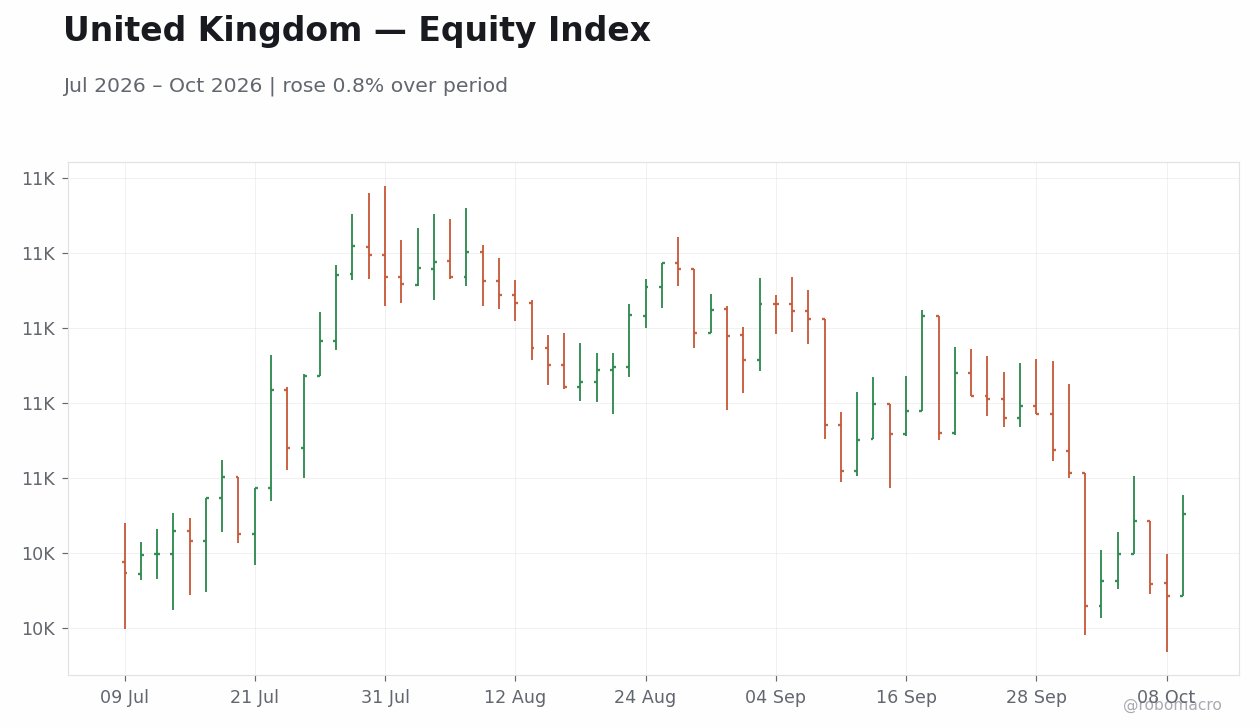
The FTSE 100 rose week-over-week to close at 10552.1, with daily moves including a gain on 6 October followed by a decline on 7 October before recovering on 9 October. The FTSE 250 posted a smaller weekly advance to 24213.8. The 10-year gilt yield increased while the 2-year yield rose, producing modest curve steepening. GBP/USD declined net to 1.32, with intraday swings on 6 October and 7 October. Brent crude surged to 104.72, providing support to energy-weighted FTSE components, while UK natural gas advanced to 3.22 and gold gained to 4216.3.
Dollar strength observed in prior weeks continued to transmit external pressure, with GBP/USD closing at 1.32 amid broad USD gains against multiple crosses. Brent crude’s advance to 104.72 added imported cost pressures relevant for UK inflation dynamics. Euro-area inflation prints exceeding forecasts in the prior period provided limited offset to sterling moves. Geopolitical developments around energy supply routes reinforced commodity volatility without direct UK-specific spillovers in the last seven days.
| Asset | Level | WoW |
|---|---|---|
| OMX Stockholm 30 | 3258.14 | +0.0% |
| Oslo Bors | 2068.38 | +0.1% |
| OMX Copenhagen 25 | 1824.92 | +0.8% |
| OMX Helsinki 25 | 6378.67 | -0.3% |
| USD/SEK | 9.99 | -0.4% |
| USD/NOK | 9.56 | -0.7% |
| EUR/SEK | 11.19 | -0.9% |
| EUR/NOK | 10.69 | -1.2% |
| Brent Crude | 104.72 | +4.4% |
| Gold | 4216.3 | +1.4% |
| Bitcoin | 83595.07 | -3.3% |


Swedish Inflation Surprise Swedish CPIF inflation rose year-on-year in September on energy prices and a softer krona, according to preliminary Statistics Sweden estimates released October 8. The print exceeded prior readings and aligned with Riksbank hawkish commentary that kept tightening in play despite broader cooling narratives.
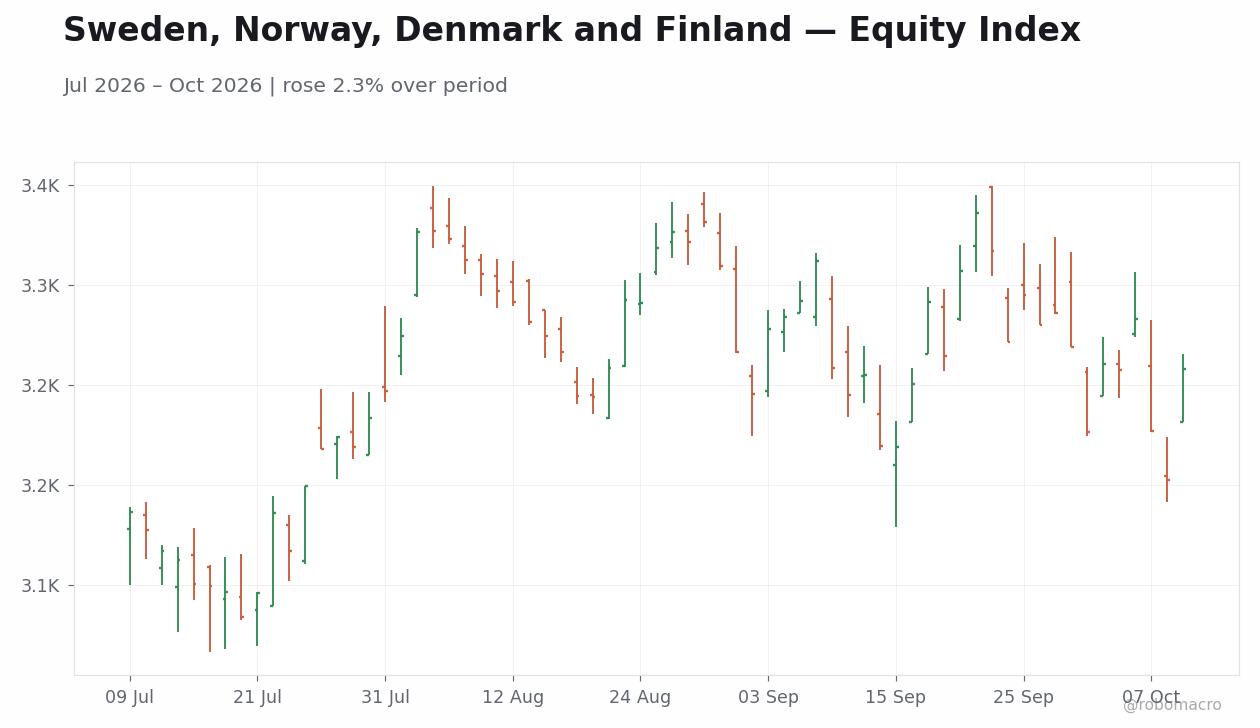
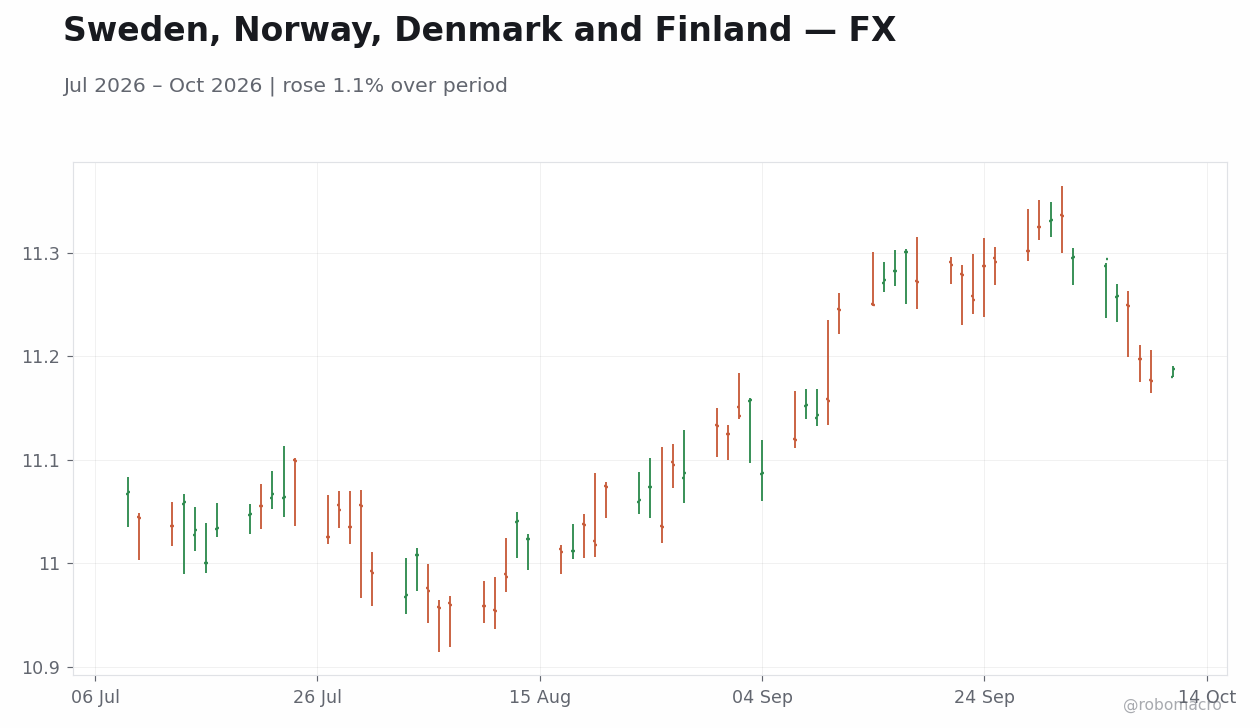
Equity and Currency Divergence Nordic equities showed limited conviction through October 5-9, with OMX Stockholm 30 closing at 3,258.14 for a 0.02% weekly gain while OMX Helsinki 25 fell 0.26% to 6,378.67. Oslo Bors edged up 0.06% to 2,068.38 and OMX Copenhagen 25 advanced 0.77% to 1,824.92. USD/SEK declined 0.41% to 9.99 and USD/NOK fell 0.65% to 9.56 over the same period, reflecting modest Nordic currency support amid external dollar flows.
Fixed Income and Fiscal Backdrop Sweden 10-year government yields moved higher on October 8 after easing earlier in the week. Brent crude climbed 4.39% to 104.72, providing a tailwind for Norwegian fiscal revenues even as Oslo equities lagged.
Policy and External Context The Riksbank conducted routine certificate sales and government bond auctions that influenced liquidity without altering policy settings. Bank of Finland officials highlighted risks from prolonged Middle East conflict to euro-area growth, an indirect channel for Finnish export exposure. No tier-one data releases occurred in Norway, Denmark or Finland, leaving price action driven by the Swedish inflation print and global commodity moves.
The Swedish CPIF print in September supplied the clearest domestic signal for the Riksbank, with officials noting that underlying inflation remains steady enough to keep a rate hike under consideration at upcoming decisions. Riksbank auction terms and certificate operations maintained liquidity management without new forward guidance. Norges Bank received no fresh domestic data but observed Brent crude strength that supports the output gap assessment ahead of its next meeting. Danmarks Nationalbank saw no intervention pressure on EUR/DKK while Bank of Finland commentary focused on external euro-area risks from Middle East developments rather than domestic conditions. The data flow left all four central banks in a data-dependent stance with no shifts in communicated rate paths.
Calendar data unavailable


Denmark will release current account balance, harmonised inflation rate year-over-year, inflation rate month-over-month and trade balance on October 12, providing the first fresh inflation read for Danmarks Nationalbank. Sweden faces no high-impact releases but will monitor Riksbank auction results for liquidity effects. Norway’s calendar remains empty of tier-one prints, leaving Brent crude movements as the dominant input for Norges Bank’s fiscal and inflation outlook. Finland transmits ECB signals only, with no separate domestic events scheduled. Markets will assess whether the prior week’s Swedish inflation surprise alters the collective Nordic rate path at the next policy meetings. External euro-area and US data will supply additional context for growth and inflation expectations across the region.
The Swedish CPIF acceleration introduces upside risk to the Riksbank’s inflation outlook that could compress the timeline to the next decision if subsequent prints confirm the trend. Norway faces downside exposure if Brent crude reverses, widening the output gap and delaying Norges Bank tightening. Thin domestic calendars leave the region vulnerable to external commodity and dollar shocks that have already driven USD/SEK to 9.99 and USD/NOK to 9.56. Markets appear to underweight the persistence of energy-driven inflation in Sweden relative to the broader cooling narrative observed elsewhere.
| Asset | Level | WoW |
|---|---|---|
| BIST 100 | 12266.0 | -1.4% |
| iShares Poland | 43.82 | +0.7% |
| EUR/PLN | 4.38 | -0.0% |
| EUR/HUF | 364.62 | -0.9% |
| EUR/CZK | 24.34 | -0.3% |
| USD/TRY | 49.31 | +0.3% |
| Brent Crude | 104.72 | +4.4% |
| Gold | 4216.3 | +1.4% |
| Bitcoin | 83586.31 | -3.4% |


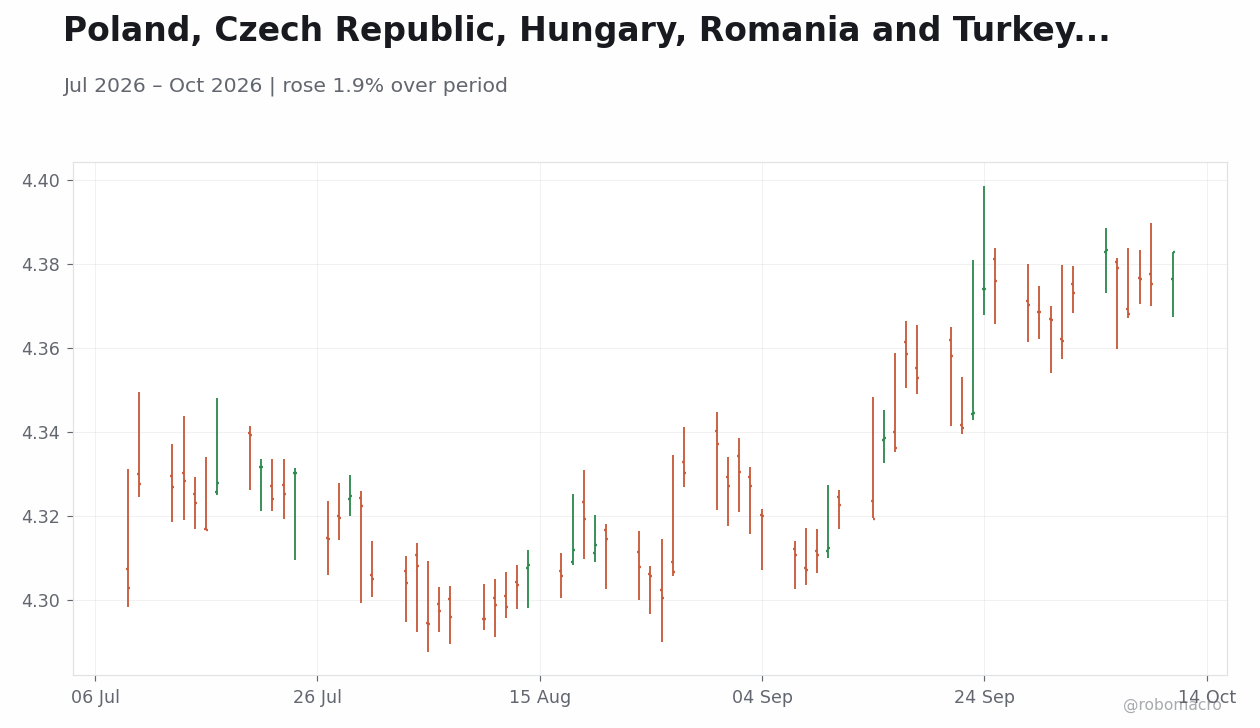
** Quiet data calendar leaves external drivers in charge. Regional markets navigated a week devoid of scheduled high-impact releases across Poland, Czech Republic, Hungary, Romania and Turkey, directing attention to commodity swings and euro-area spillovers. BIST 100 surrendered earlier gains to close the week lower. Polish equities via iShares Poland ETF advanced mid-week before paring back, ending with a modest weekly gain.
Currency moves remain contained. EUR/PLN traded in a narrow band with a negligible net weekly change, while EUR/HUF declined on forint outperformance. The Czech koruna firmed modestly as EUR/CZK fell. USD/TRY edged higher, underscoring lira stability relative to broader EM crosses.
Commodity volatility shapes sentiment. Brent crude advanced, providing a mixed signal for energy importers Poland, Hungary and Czech Republic while supporting fiscal positions in Romania. NBP's gold purchases reinforced reserve diversification trends, coinciding with gold's weekly rise. Bitcoin's drop highlighted the broader retreat from risk assets that pressured BIST 100 and Polish equities.
Policy signals stay data-dependent. NBP's seventh straight hold aligned with expectations that the fuel-price cap would continue cooling near-term inflation prints. Hungary, Poland and Bulgaria continued trailing EU peers in post-pandemic recovery fund drawdowns, keeping fiscal support timelines in focus. Overall positioning reflected tolerance for external price signals without immediate domestic recalibration.
** NBP maintained its policy rate for a seventh consecutive meeting, consistent with expectations that the fuel-price cap would continue damping near-term inflation. The bank continued gold purchases, advancing reserve diversification toward stated targets. CNB, MNB, BNR and CBRT released no new decisions or minutes during the week. Forward guidance across the group remained data-dependent, with no speakers altering prior outlooks on the medium-term rate path. Poland's central bank developments continued to draw attention to domestic rate-setting processes without immediate implications for the current hold stance. The quiet data calendar left unchanged the assessment that external commodity prints will feed into headline inflation before any policy recalibration. Hungary and Czech Republic officials stayed aligned with typical ECB spillover monitoring given their trade linkages. Overall, this week's stability reinforced expectations for unchanged settings until fresh inflation or activity figures arrive later in the month.
** The week featured zero high-impact economic releases in Poland, Czech Republic, Hungary, Romania or Turkey according to the daily calendars, leaving analysts without fresh CPI, GDP, industrial production or labor-market prints to assess. Prior consensus expectations for any inflation moderation tied to Poland's fuel-price cap therefore went untested in official data. No revisions to prior unemployment or trade figures emerged to alter cycle assessments for the CEE economies. The absence of surprises reinforced the view that disinflation trends in the region continue to mature at a gradual pace consistent with external commodity influences. Romania's lower gas import reliance positioned it as relatively insulated from Brent-driven headline pressures compared with Poland and Hungary. Overall, the data void left central-bank rate paths anchored to the prior quarter's activity resilience rather than any fresh signals. Market participants therefore carried forward the same medium-term outlook that had prevailed.
Calendar data unavailable


** The economic calendar for the coming week shows no scheduled high-impact releases across Poland, Czech Republic, Hungary, Romania or Turkey. Attention will therefore turn to external euro-area and US data that could influence regional FX and bond flows. Any ECB commentary or US labor-market updates may transmit through EUR crosses given the four EU members' trade exposure. Turkish assets are likely to track Brent crude direction and domestic political developments. Poland's fuel-price cap effects may generate secondary commentary ahead of the next CPI print. Hungary and Czech Republic remain sensitive to any shifts in euro-area yield differentials. Romania's external financing conditions will stay in focus amid the broader EM risk backdrop. Limited liquidity is expected early in the week, with positioning likely to build ahead of potential month-end flows. Central-bank speakers from the region are not currently flagged on the calendar.
** The week's data void leaves the outlook exposed to external commodity and risk-sentiment shocks rather than domestic surprises. Brent's advance raises upside risks to near-term headline inflation for energy importers Poland, Hungary and Czech Republic. Downside scenarios center on further global equity weakness that could pressure BIST 100 and Polish assets. Market mispricing signals appear limited given the contained FX moves, though USD/TRY stability may mask underlying lira pressures if oil remains elevated. Positioning remains light ahead of the empty calendar, suggesting flows could amplify any external catalyst. Volatility in gold and Bitcoin underscores the broader retreat from non-yielding assets that may continue to weigh on regional risk appetite. Upside growth resilience in Poland's services sector could support the NBP's hold longer than some expect if external disinflation stalls.
** Equities delivered mixed net results, with BIST 100 declining while iShares Poland posted a gain. Mid-week divergence saw the Polish ETF rally before both indices fell sharply amid global risk deterioration. Fixed-income visibility stayed limited as Poland and Hungary 10-year yields were not reported in daily snapshots. FX markets showed modest CEE currency appreciation against the euro, with EUR/HUF and EUR/CZK declining, while USD/TRY rose. Commodity moves dominated catalysts, as Brent crude advanced on supply concerns and gold climbed. Bitcoin's weekly decline amplified the risk-off tone that pressured Turkish and Polish equities.
** Dollar strength observed in prior weeks continued to transmit external price signals, with regional currencies showing only modest net changes against the euro. Brent crude's advance added imported inflation pressure for net-energy importers while supporting fiscal positions elsewhere in the region. Euro-area inflation prints exceeding forecasts in prior weeks kept ECB spillover risks elevated for Poland, Czech Republic and Hungary. Geopolitical developments carry potential trade and migration implications for Poland as the largest CEE economy. Gold's weekly gain reinforced reserve diversification trends already underway at NBP. Overall, last-seven-day global macro inputs remained dominated by commodity and risk-asset volatility rather than any single policy shift.
| Asset | Level | WoW |
|---|---|---|
| JSE Top 40 | 100764.3 | +0.1% |
| USD/ZAR | 16.51 | -0.9% |
| EUR/ZAR | 18.47 | -1.4% |
| Platinum | 1693.3 | -0.8% |
| Gold | 4216.3 | +1.4% |
| Brent Crude | 104.72 | +4.4% |
| Naspers | 72169.0 | +2.2% |
| Bitcoin | 83592.22 | -3.3% |


Equity and commodity price action The JSE Top 40 advanced 0.08 percent to 100,764.3 over the five sessions. Naspers gained 2.22 percent to 72,169, lifting the index on the final day. Platinum ended 0.8 percent lower on the week at 1,693.3, while gold rose 1.43 percent to 4,216.3. Brent crude surged 4.39 percent to 104.72, adding cost pressure to the transport component of the CPI basket.
Currency resilience amid external flows USD/ZAR declined 0.86 percent to 16.51, with daily closes ranging from 16.51 to 16.64. EUR/ZAR fell 1.44 percent to 18.47 over the same period. The rand’s modest net gain occurred against a backdrop of continued capital-outflow commentary and no domestic data prints to alter the external price signal.
Policy-signal inputs from surveys The SARB’s direct business-survey programme gathered fresh readings on capacity utilisation and pricing power during the week. No MPC minutes or speeches were released, keeping the inflation target as the operative anchor. The absence of high-impact releases left market participants focused on qualitative inputs rather than hard data surprises.
Broader market context Bitcoin fell 3.34 percent to 83,592.22, while regional equity divergence continued with South African mining counters outperforming on platinum and gold moves. The data flow confirmed the pattern of external commodity and dollar drivers transmitting faster than domestic releases could offset.
The SARB kept the policy rate unchanged with inflation contained, and the bank’s new firm-level surveys now supply direct evidence on slack and pricing behaviour for the next policy assessment. Officials received no new quantitative releases this week, so the survey results on capacity utilisation will shape the committee’s view of whether the current stance remains consistent with the inflation target band. The programme’s emphasis on business pricing power provides a forward-looking qualitative signal that complements the last published inflation print. Absent speeches or minutes, the data dependence already signalled in prior communications continues to govern expectations for upcoming decisions. The surveys therefore represent the clearest incremental input into the rate-path assessment this week.
Calendar data unavailable


Monday brings no scheduled South African releases, leaving external drivers and any follow-through in the SARB survey programme as the main focus. Tuesday’s calendar is also empty of domestic prints, so attention will remain on commodity price effects on the inflation outlook ahead of the next meeting. Wednesday offers no high-impact data, keeping the emphasis on qualitative survey updates and their implications for capacity utilisation. Thursday likewise lists no events, allowing markets to assess whether the recent Brent move alters the inflation trajectory. Friday closes the period without new figures, reinforcing the data-dependent stance. Across the five sessions the absence of releases means the survey results on pricing power will remain the primary domestic signal for the rate path in coming quarters. The lack of consensus-challenging prints keeps expectations centred on continuity unless the surveys reveal material shifts in slack.
The week’s commodity-driven equity gains and rand stability mask the risk that sustained Brent levels could lift the transport component of CPI and test the upper half of the inflation target band. Downside scenarios centre on further platinum weakness, which would pressure mining earnings and the JSE Top 40. Upside risks include continued gold strength that could support the rand and ease imported-inflation concerns. The SARB’s survey initiative may reveal greater slack than currently priced, potentially shifting the reaction function at upcoming decisions if capacity utilisation readings disappoint. Markets appear to underweight the pass-through from energy prices given the lack of offsetting domestic data, leaving the inflation outlook more sensitive to external moves than the quiet calendar suggests.
| Asset | Level | WoW |
|---|---|---|
| ASX 200 | 8716.6 | +0.3% |
| NZX 50 | 13749.35 | +0.4% |
| AUD/USD | 0.7 | +0.5% |
| NZD/USD | 0.56 | -0.1% |
| AUD/NZD | 1.24 | +0.3% |
| BHP | 60.94 | -1.5% |
| Gold | 4216.3 | +1.4% |
| Brent Crude | 104.72 | +4.4% |
| Bitcoin | 83592.22 | -3.3% |


Consumer sentiment deterioration Australian households registered further erosion. The Westpac Consumer Confidence Index fell, extending the prior monthly decline. Sub-indices reflected broad pessimism on family finances and the economic outlook, consistent with the impact of the prevailing policy rate on mortgage holders.
Industrial contraction signal The Ai Group Industry Index slumped, confirming a sharp contraction across manufacturing, construction and services. This breadth of weakness contrasts with earlier resilience in services and points to faster loss of momentum on the industrial side of the economy than previously anticipated.
Equity and currency resilience Despite the data, the ASX 200 advanced 0.35 percent to close at 8716.6 while the NZX 50 rose 0.37 percent to 13749.35. AUD/USD gained 0.52 percent to 0.7 and NZD/USD eased 0.09 percent to 0.56, leaving AUD/NZD up 0.27 percent at 1.24. BHP declined 1.53 percent to 60.94 even as Brent crude rose 4.39 percent to 104.72 and gold advanced 1.43 percent to 4216.3.
Cross-Tasman divergence New Zealand markets showed more muted price action. The NZX 50 posted a smaller weekly gain than the ASX 200, and NZD underperformed AUD, reflecting differing policy settings and inflation trajectories.
Commodity tailwinds Brent crude’s 4.39 percent weekly advance to 104.72 provided external support for Australian resource exporters. Gold’s 1.43 percent rise to 4216.3 further aided sentiment in the mining complex, partially offsetting the domestic activity data.
Policy context unchanged No RBA or RBNZ meetings or minutes were released. The data flow therefore fed directly into existing assessments of the speed of easing at both central banks without altering current policy-rate levels.
Labour-market backdrop Market commentary continued to reference the RBA’s view that the labour market remains too tight, with unemployment expected to hold steady. This narrative sits alongside the weak consumer and industry prints, creating a mixed picture for the growth outlook.
External influences Dollar strength observed in prior weeks continued to transmit external pressure, yet local equity indices still managed modest gains. The configuration left Australian and New Zealand assets differentiating on commodity support rather than domestic demand strength.
Data confirmation of expectations The consumer and industry releases both missed the direction implied by earlier resilience signals. The magnitude of the Ai Group drop in particular challenged the assumption of a gradual slowdown and reinforced the case for monitoring activity indicators closely ahead of upcoming decisions.
Through-line of the week The dominant arc was one of softening domestic demand indicators offset by commodity-driven market resilience. The combination left the RBA and RBNZ on unchanged settings while highlighting downside risks to growth without immediate policy recalibration.
The RBA and RBNZ maintained their policy rates. No speeches or minutes were released, so the policy signal derived entirely from the data prints. The Westpac Consumer Confidence Index and Ai Group Industry Index both point to weaker household and industrial momentum than earlier in the tightening cycle. These outcomes reinforce the RBA’s existing emphasis on labour-market tightness as the key variable for the next decision while supporting the RBNZ’s more measured approach given New Zealand’s lower starting inflation. Officials at both banks have previously stressed data dependence; the latest activity readings therefore increase the weight on forthcoming labour-market and inflation releases in shaping the path of easing over coming quarters.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Mon 5 | AU | Westpac Consumer Confidenc | -5.2 | - | -4.7 |
| Mon 5 | AU | Westpac Consumer Confidenc | 84.4 | - | 80.4 |
| Mon 5 | AU | ANZ-Indeed Job Ads Month-o | 2.6 | - | 2.2 |
| Tue 6 | AU | Ai Group Industry Index | -1.6 | - | -24.2 |
| Tue 6 | AU | Ai Group Construction Inde | -4.7 | - | -34.5 |
| Tue 6 | AU | Ai Group Manufacturing Ind | -14.9 | - | -8.7 |
| Tue 6 | AU | Building Permits Month-ove | -1.9 | -6.1 | -6.1 |
| Tue 6 | AU | Building Permits Year-over | 10.9 | 10.3 | 10.3 |
| Tue 6 | AU | Private House Approvals Mo | -1.9 | 3.7 | 3.7 |
| Wed 7 | AU | Consumer Inflation Expecta | 4.9 | - | - |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-10-12 | NAB Business Confidence Index | -8.0 | - |
| 2026-10-12 | RBA Meeting Minutes | - | - |
| 2026-10-14 | Employment Change | 40K | 20K |
| 2026-10-14 | Full-Time Employment Change | -6300 | - |
| 2026-10-14 | Headline Unemployment Rate | 4.6 | 4.6 |
| 2026-10-15 | Business NZ PMI | 53.1 | - |
| 2026-10-18 | Trade Balance | -1.3bn | - |


Attention turns to Australian labour-market indicators and any updates on inflation or retail sales that will feed directly into the RBA’s assessment ahead of its next meeting. The RBNZ will similarly watch domestic activity prints and commodity price developments for signals on dairy and export revenues. Consensus expectations for unemployment remain steady, which would keep the RBA’s focus on whether the labour market has cooled sufficiently to justify further easing. Stronger-than-expected employment data would reinforce the case for holding the policy rate while softer outcomes would increase the probability of an earlier adjustment. In New Zealand, any revisions to growth or inflation forecasts would shape expectations for the OCR path. Commodity price volatility, particularly in iron ore and Brent crude, will remain an external input for both central banks given its transmission to terms of trade and imported inflation. Markets will also monitor any RBA or RBNZ speakers for incremental shifts in language on the balance of risks to activity versus prices.
The sharp drop in the Ai Group Industry Index raises the possibility that industrial weakness could broaden faster than the RBA’s current labour-market focus anticipates, tilting the growth outlook lower. Conversely, continued Brent crude strength at 104.72 could sustain imported inflation pressures and delay easing at both central banks. The divergence between depressed consumer sentiment and resilient equity indices suggests markets may be underweighting downside consumption risks. External dollar strength observed in prior weeks remains a transmission channel that could amplify any further domestic data misses. Upside surprises in upcoming labour-market prints would support the current policy-rate settings, while repeated misses on activity would shift the balance toward earlier adjustments over coming quarters.
| Asset | Level | WoW |
|---|---|---|
| Shanghai Composite | 3813.79 | +0.1% |
| Hang Seng | 24211.35 | +0.7% |
| TAIEX | 49313.44 | -0.8% |
| USD/CNY | 6.68 | -0.3% |
| USD/HKD | 7.85 | 0.0% |
| Copper | 6.69 | +1.6% |
| Brent Crude | 104.72 | +4.4% |
| Gold | 4216.3 | +1.4% |
| Bitcoin | 83585.55 | -3.4% |


Export momentum offsets equity consolidation. Taiwan’s September exports printed at a record high, up sharply YoY, confirming sustained AI-driven semiconductor demand that pushed the TAIEX to an intraday high before a 0.80% weekly decline to 49,313.44. Mainland benchmarks posted modest net gains, with the Shanghai Composite closing at 3,813.79 after a 0.05% weekly advance.
Yuan policy draws external scrutiny. USD/CNY fell 0.32% to 6.68 as the PBoC defended its fixing regime against external pressure, stating the market determines the exchange rate and there is no intent to weaken the currency for trade advantage. The yuan’s strength versus its basket coincided with portfolio inflows that supported onshore assets even as Hong Kong’s Hang Seng rose 0.71% to 24,211.35.
Commodity price surge raises cost concerns. Brent crude advanced 4.39% to 104.72 while copper gained 1.62% to 6.69, reflecting improved China demand sentiment yet adding input-cost pressure for regional manufacturers. Gold climbed 1.43% to 4,216.30 alongside continued PBoC accumulation.
Policy accommodation remains intact. The absence of tier-one data releases left markets focused on PBoC liquidity operations and the HKMA’s handling of the 7.85 USD/HKD boundary, which held steady with no aggregate-balance intervention signals. Cross-strait trade flows and EU-China negotiations provided the dominant narrative arc for the week.
The PBoC stated that the market decides the yuan’s exchange rate and rejected claims of undervaluation aimed at boosting exports, keeping the fixing regime unchanged. Officials reiterated no intention to weaken the currency for trade advantage during the EU trade commissioner’s Beijing visit. The HKMA maintained the 7.85 weak-side convertibility undertaking with no aggregate-balance drainage signals reported. The CBC faced no policy meetings but benefited from Taiwan’s record export print that supported the TAIEX early in the week. Continued PBoC gold buying through September extended the streak even as bullion prices moved higher. With August CPI subdued and no new inflation prints, the medium-term rate path remains anchored to accommodation. Liquidity operations stayed neutral, consistent with the PBoC’s patient stance ahead of fourth-quarter fiscal support measures.
No high-impact economic releases occurred for China, Hong Kong or Taiwan during the week, leaving the data calendar empty across all four days. This vacuum shifted attention to the Taiwan export print, which exceeded prior records and confirmed sharp YoY growth on semiconductor strength. The subdued August CPI reading continued to anchor expectations for PBoC accommodation, with the 10-year yield remaining near recent lows as disinflation persisted. Export momentum aligned with copper’s 1.62% weekly gain, suggesting industrial demand stabilization rather than acceleration. The lack of fresh inflation or activity prints left the medium-term growth outlook unchanged from the prior month’s modest rebound signals. Brent’s 4.39% surge to 104.72 introduced an external cost channel that could feed into October producer-price readings. Overall, the data void reinforced a data-dependent stance at the PBoC and CBC, with no revisions to consensus growth or inflation trajectories required this week.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Wed 7 | CN | Foreign Exchange Reserves | 3438.0bn | - | 3400.0bn |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-10-13 | Inflation Rate Year-over-Year | 0.80 | 1.1 |
| 2026-10-13 | Inflation Rate Month-over-Month | 0.40 | - |
| 2026-10-13 | Producer Price Index Year-over-Year | 3.8 | 4.4 |
| 2026-10-13 | Exports Year-over-Year | 25.0 | 25.3 |
| 2026-10-13 | Imports Year-over-Year | 28.2 | 23.5 |
| 2026-10-13 | Trade Balance | 119.1bn | 114.5bn |
Monday brings no tier-one releases for the region, keeping focus on any PBoC open-market operation commentary and EU-China trade talks. Tuesday may feature early Taiwan supply-chain checks ahead of TSMC revenue data. Wednesday could see Hong Kong aggregate-balance updates that test the 7.85 boundary. Thursday is expected to include any State Council property-support signals and cross-strait trade flow updates. Friday closes the week with potential PBoC liquidity signals and CBC speaker remarks on export momentum. Consensus expects no immediate policy shifts, but the record export print will likely keep semiconductor demand in focus. Brent at 104.72 raises the stakes for any October producer-price commentary. Overall, markets will watch whether yuan strength at 6.68 persists amid external pressure.
The week’s data void leaves positioning vulnerable to any surprise in October inflation prints or EU tariff announcements. Upside risks center on continued AI-driven export strength that could lift TAIEX further from 49,313.44. Downside risks include Brent remaining above 104 and feeding into regional input costs, potentially pressuring margins for manufacturers. Market mispricing appears limited, with USD/CNY at 6.68 already reflecting PBoC pushback on appreciation demands. Volatility stayed contained, though Hong Kong’s daily swing on October 9 highlighted sensitivity to property and trade headlines.
Equities delivered mixed weekly results, with the Hang Seng advancing 0.71% to 24,211.35 while the TAIEX declined 0.80% to 49,313.44 after an early semiconductor-led rally. The Shanghai Composite edged 0.05% higher to 3,813.79. In FX, USD/CNY fell 0.32% to 6.68 as the PBoC rejected undervaluation narratives, while USD/HKD remained pinned at 7.85. Bonds saw continued outperformance in mainland China, with the 10-year yield holding near recent lows against rising global yields. Commodities showed Brent crude rising 4.39% to 104.72 on supply-curb news and copper climbing 1.62% to 6.69 on demand hopes. Gold advanced 1.43% to 4,216.30 even as the PBoC extended purchases. Bitcoin fell 3.35% to 83,585.55, unwinding prior risk-on flows.
Dollar strength observed in prior weeks continued to transmit external signals, with USD/CNY still able to firm 0.32% to 6.68 despite the broader USD bid. EU-China trade tensions escalated during the commissioner’s Beijing visit, directly affecting yuan policy commentary. Brent’s 4.39% weekly gain to 104.72 added imported inflation pressure for net-energy importers across North Asia. Gold’s 1.43% advance to 4,216.30 occurred alongside the PBoC’s ongoing accumulation, illustrating safe-haven demand independent of domestic data. No major geopolitical spillovers beyond trade negotiations materialized in the last seven days.
| Asset | Level | WoW |
|---|---|---|
| KOSPI | 6625.93 | -4.5% |
| KOSDAQ | 892.27 | -3.0% |
| USD/KRW | 1340.02 | -0.2% |
| Samsung | 262000.0 | -3.7% |
| SK Hynix | 1681000.0 | -5.2% |
| Brent Crude | 104.72 | +4.4% |
| Gold | 4216.3 | +1.4% |
| Bitcoin | 83600.87 | -3.3% |


Equity divergence and export resilience Korean equities showed clear bifurcation through the week. The KOSPI fell 4.54% to 6625.93 by Friday, while the KOSDAQ declined 3.01% overall to 892.27. Samsung Electronics fell 3.68% to 262000 and SK Hynix declined 5.19% to 1681000, yet both firms posted record earnings momentum that supported corporate fundamentals.
Currency stability amid external dollar pressure The won held firm despite broad dollar strength elsewhere. USD/KRW closed the week at 1340.02 after a net 0.19% decline, with the currency supported by semiconductor export strength. Commerzbank analysts cited continued export performance as the key support for KRW stability.
Inflation print and fixed-income response Recent CPI data prompted Bank of Korea commentary that underlying pressures are building. Korean government bond yields eased early before rising modestly later in the week, while the 10-year yield moved lower. The curve flattened modestly as duration demand persisted.
Corporate and policy backdrop Korea’s current-account surplus expanded on the chip boom, and the household debt ratio fell to a multi-year low. M&A volume rose sharply in the first nine months. The Bank of Korea reshuffled international and FX leadership while former Governor Rhee flagged productivity concerns tied to the 52-hour workweek.
Flow dynamics and external influences Foreign investors continued net selling of Korean equities. Brent crude rose 4.39% to 104.72, adding to imported-inflation concerns that weighed on sentiment late in the week. No domestic data releases occurred after the CPI print, leaving price action driven by flows and external signals.
The Bank of Korea appointed Choi Young-joo as Deputy Governor and reshuffled its international and FX leadership during the week. The new governor publicly backed CBDCs while ruling out stablecoins, maintaining focus on operational resilience rather than immediate policy adjustment. Recent CPI data prompted official statements that underlying price pressures are building and that near-term inflation should remain near recent levels. The record current-account surplus and continued export strength were cited as supporting the external balance without altering the data-dependent rate outlook. No MPC meetings or forward-guidance shifts occurred, leaving the policy-rate path anchored to incoming inflation and growth prints ahead of the next decision.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Mon 5 | KR | Foreign Exchange Reserves | 442.3bn | - | 440.6bn |
| Mon 5 | KR | 2-Year KTB Auction | 3.8 | - | - |
| Tue 6 | KR | 30-Year KTB Auction | 4.6 | - | - |
| Wed 7 | KR | Current Account Balance | 42.1bn | - | 46.1bn |
| Wed 7 | KR | Ktbi Auction | 1.6 | - | - |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-10-15 | Headline Unemployment Rate | 2.7 | - |

The calendar remains light for South Korea, with no high-impact CPI, GDP, or trade releases scheduled. Markets will track follow-through from the finance minister’s dual mandate to tame inflation while supporting growth. Attention will center on any comments from the newly appointed Deputy Governor or international leadership on currency and external-balance issues. Semiconductor earnings momentum, including Samsung’s record quarterly profit projection, will continue to influence equity flows. External drivers such as Brent crude movements and global risk sentiment will remain key inputs for won dynamics. The data-dependent stance at the Bank of Korea implies that any shift in the policy-rate path will require clear confirmation from subsequent inflation or activity prints rather than single-week observations.
Persistent foreign equity outflows create downside risk to KOSPI sustainability even with strong corporate earnings. Brent crude’s 4.39% weekly rise to 104.72 adds imported-inflation pressure that could keep the Bank of Korea on hold longer than expected. The won’s strength versus the yen supports export competitiveness but raises sensitivity to any official commentary on currency strength. Leadership transitions at the Bank of Korea introduce uncertainty around communication style without immediate changes to the rate path. The absence of domestic data next week leaves the outlook exposed to external yield and commodity moves that have already transmitted through USD/KRW stability at 1340.02.
| Asset | Level | WoW |
|---|---|---|
| JCI | 6093.76 | -0.4% |
| KLCI | 1608.45 | -1.4% |
| STI | 5401.89 | -4.6% |
| USD/IDR | 17879.0 | -0.2% |
| USD/THB | 33.48 | -0.1% |
| USD/MYR | 4.08 | +0.0% |
| USD/PHP | 62.8 | +0.4% |
| USD/SGD | 1.28 | +0.1% |
| Brent Crude | 104.72 | +4.4% |
| Gold | 4216.3 | +1.4% |
| Bitcoin | 83615.51 | -3.3% |


Equity Market Divergence Indonesian equities led ASEAN performance, with the JCI closing the week at 6,093.76 for a net 0.41 percent decline. The STI posted the largest weekly loss at 4.63 percent to 5,401.89. Malaysia’s KLCI ended 1.43 percent lower at 1,608.45.
Currency Stability Amid Oil Volatility The rupiah finished 0.17 percent firmer at 17,879 per dollar, while the baht closed 0.15 percent stronger at 33.48. The ringgit was essentially flat at 4.08, the peso weakened 0.42 percent to 62.80, and the Singapore dollar edged 0.08 percent weaker at 1.28. Brent crude advanced 4.39 percent to 104.72, adding imported-cost pressure for net-energy importers across the region.
Policy Commentary and Structural Signals No tier-one data releases occurred in any of the six ASEAN economies, leaving price action driven by external commodity moves and central-bank communications.
Cross-Asset Context Gold rose 1.43 percent to 4,216.30 while Bitcoin fell 3.31 percent to 83,615.51, reflecting a mixed risk tone that did not derail the rupiah’s relative outperformance.
No forward guidance shifts were issued by BI, BoT, BNM, BSP, MAS or SBV. The absence of domestic data surprises left policy signals anchored to officials’ emphasis on stability and external resilience rather than any immediate recalibration of settings.
Calendar data unavailable
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-10-13 | GDP Growth Quarter-over-Quarter Adv | 1.4 | - |
| 2026-10-13 | Monetary Policy Statement | - | - |

The calendar remains light on tier-one releases across the six economies, with attention likely to center on any additional central-bank commentary and external drivers. Markets will monitor follow-through from BI’s rupiah outlook statements ahead of the next policy meeting. MAS will continue NEER-band management amid regional currency moves. Data dependence remains the dominant theme for upcoming decisions at BI, BoT, BNM, BSP, MAS and SBV.
The 4.39 percent weekly advance in Brent crude to 104.72 raises imported-inflation risks for net-energy importers Thailand, the Philippines and Indonesia, potentially complicating inflation-targeting paths. Equity sell-offs of 4.63 percent in Singapore and 1.43 percent in Malaysia suggest markets may be under-pricing the speed of external commodity transmission into regional risk assets.
| Asset | Level | WoW |
|---|---|---|
| Nifty 50 | 22520.45 | -0.2% |
| Sensex | 72472.33 | +0.1% |
| USD/INR | 96.78 | +0.5% |
| EUR/INR | 108.35 | +0.2% |
| Reliance | 1170.3 | -1.4% |
| HDFC Bank | 707.25 | +0.3% |
| Brent Crude | 104.72 | +4.4% |
| Gold | 4216.3 | +1.4% |
| Bitcoin | 83600.87 | -3.3% |


RBI Policy Shift Markets adjusted to the latest policy decision amid persistent inflation pressures, including higher imported costs from Brent crude.
Equity and Currency Response Nifty 50 posted a net weekly decline of 0.16 percent to close at 22,520.45. Sensex finished at 72,472.33, up 0.12 percent for the week, while USD/INR advanced 0.47 percent to 96.78. Reliance Industries fell 1.36 percent to 1,170.30 and HDFC Bank rose 0.35 percent to 707.25.
Demand and External Backdrop Brent crude levels near 104.72 dollars per barrel remained relevant for imported inflation assessments.
Markets adjusted to the latest policy decision with language that referenced calibrated tightening and the possibility of additional moves at future meetings. The data on services activity and crude prices together point to a rate path that remains responsive to incoming inflation prints.
| Date | Ctry | Event | Prior | Cons. | Actual |
|---|---|---|---|---|---|
| Tue 6 | IN | HSBC Composite PMI Final | 54.3 | - | 55.9 |
| Tue 6 | IN | HSBC Services PMI Final | 54.1 | - | 55.2 |
| Wed 7 | IN | RBI Interest Rate Decision | 5.2 | 5.5 | 5.5 |
| Wed 7 | IN | Cash Reserve Ratio | 3.0 | 3.0 | 3.0 |
| Wed 7 | IN | Foreign Exchange Reserves | 747.6bn | - | 734.6bn |
| Date | Release | Prior | Cons. |
|---|---|---|---|
| 2026-10-12 | Inflation Rate Year-over-Year | 4.8 | - |

No high-impact Indian data releases are scheduled for the first half of the coming week. Attention will center on liquidity conditions and money-market rates. Later in the week, any updates on FII flows or rupee stability will be monitored. Brent crude levels near 104.72 dollars per barrel will remain relevant for imported inflation assessments ahead of upcoming decisions.
Equity volatility around the decision, with Nifty 50 closing down 0.16 percent, highlights sensitivity to external shocks. Brent crude levels near 104.72 dollars per barrel raise the risk that imported inflation could influence the pace of policy adjustments. The rupee's 0.47 percent weekly advance in USD/INR terms suggests external balance pressures could intensify if dollar strength persists.
| Asset | Level | WoW |
|---|---|---|
| BIST 100 | 12266.0 | -1.4% |
| USD/TRY | 49.31 | +0.3% |
| EUR/TRY | 55.18 | -0.3% |
| GBP/TRY | 65.23 | +0.2% |
| Gold (TRY) | 4216.3 | +1.4% |
| Brent Crude | 104.72 | +4.4% |
| EUR/USD | 1.12 | -0.4% |
| Bitcoin | 83584.23 | -3.4% |


Equity and currency tape under external pressure BIST 100 posted a net 1.43 percent decline to 12,266 over the five trading sessions and finished the week below its prior close, consistent with selective EM equity underperformance during periods of broad dollar gains. USD/TRY advanced 0.33 percent to 49.31.
TRY crosses and commodity linkages EUR/TRY ended 0.27 percent lower at 55.18. GBP/TRY rose 0.18 percent to 65.23. Gold priced in lira advanced 1.43 percent to 4,216.30, outpacing the move in USD/TRY and reflecting domestic safe-haven demand. Brent crude rose 4.39 percent to 104.72, providing a partial offset for Turkey’s external accounts.
Absence of domestic data releases No Turkish high-impact releases appeared in the October 5–11 calendar, leaving market participants to interpret external dollar strength and regional EM flows. The lira’s modest depreciation aligned with the 0.33 percent USD/TRY gain. Bitcoin’s 3.35 percent weekly decline to 83,584.23 offered no direct read-through to Turkish flows.
Multi-week context integration Prior weeks showed sustained dollar breadth against EM currencies. BIST 100’s 1.43 percent drop occurred alongside regional equity softness. The data suggest external yield differentials continued to transmit price signals faster than domestic factors could counter.
No Central Bank of the Republic of Turkey speakers or minutes were released during the week. The policy rate remained unchanged with no forward guidance updates. Incoming data on inflation and activity will shape assessments ahead of the next meeting, as the absence of domestic releases left the rate path anchored to prior communications. The 0.33 percent rise in USD/TRY and 1.43 percent decline in BIST 100 did not alter the central bank’s data-dependent stance. Officials have previously emphasized monitoring imported price pressures, and the week’s Brent increase to 104.72 will factor into those evaluations without prompting immediate recalibration.
Calendar data unavailable
Monday brings no high-impact Turkish releases, allowing markets to focus on external data that could influence imported inflation. Mid-week activity indicators will provide the first read on October momentum and help calibrate expectations for the next Central Bank of the Republic of Turkey decision. Inflation prints later in the period will directly inform assessments of price pressures in coming quarters. Trade balance figures, if released, will highlight external account resilience amid the recent Brent advance to 104.72. The data flow will test whether recent lira stability at 49.31 persists or requires policy adjustment. Officials are expected to maintain a data-dependent posture, with any surprises in activity or prices feeding directly into rate-path deliberations. No meetings are scheduled.
The week’s limited domestic data left external dollar strength as the dominant driver, with BIST 100 and USD/TRY moves reflecting that configuration rather than local surprises. Upside risks center on sustained Brent levels near 104.72 supporting the current account, while downside risks include further equity pressure if regional EM outflows intensify. The market appears to price continued external transmission without immediate Central Bank of the Republic of Turkey response, yet any acceleration in imported inflation could shift that view. The multi-week pattern of dollar breadth suggests the current lira levels around 49.31 remain vulnerable to renewed US yield support in coming quarters.
| Asset | Level | WoW |
|---|---|---|
| Saudi Aramco | 25.7 | +1.1% |
| MSCI Saudi | 36.06 | -1.3% |
| MSCI UAE | 19.32 | -2.2% |
| MSCI Qatar | 15.99 | -2.2% |
| MSCI Kuwait | 36.02 | +0.2% |
| Brent Crude | 104.72 | +4.4% |
| WTI Crude | 91.85 | +2.7% |
| Gold | 4216.3 | +1.4% |
| USD/SAR | 3.75 | +3.4% |
| USD/AED | 3.67 | +0.0% |
| USD/KWD | 0.31 | +0.5% |
| Bitcoin | 83615.51 | -3.3% |


Energy prices advance. Brent crude rose 4.39 percent to 104.72 and WTI gained 2.71 percent to 91.85. Saudi Arabia and six OPEC+ peers kept output targets unchanged.
Equity markets post mixed results. MSCI Saudi closed the week at 36.06 after a 1.26 percent decline, MSCI UAE fell 2.18 percent to 19.32, MSCI Qatar dropped 2.21 percent to 15.99, and MSCI Kuwait edged up 0.21 percent to 36.02. Aramco shares advanced 1.1 percent to 25.7.
Currency pegs remain stable. USD/SAR printed 3.75 after a 3.44 percent weekly move, USD/AED remained at 3.67, and USD/KWD settled at 0.31.
Commodity and risk-asset moves diverge. Gold rose 1.43 percent to 4,216.30 while Bitcoin fell 3.31 percent to 83,615.51.
Data flow shows divergent price action. Regional equity indices posted net weekly declines across five of six markets amid the energy price advance.
GCC central banks maintained steady policy communication aligned with data dependence and external yield signals. No rate decisions or minutes were released during the week. Officials continued to monitor oil-supply developments and fiscal trajectories without altering forward guidance. The data suggest that upcoming decisions will stay anchored to incoming activity and inflation prints.
Calendar data unavailable

The next week features a light data calendar for GCC economies. Monday brings no high-impact releases for Saudi Arabia, the UAE or Qatar. Mid-week updates on tanker transits through the Strait of Hormuz and insurance-rate movements will inform supply-risk assessments ahead of the next OPEC+ compliance review. Later in the period, investors will parse any new detail on Asian crude-storage plans announced by Saudi Arabia and the UAE. These releases matter for the rate path because stronger non-oil readings would support steady policy while renewed fiscal pressures could prompt closer scrutiny of spending trajectories in coming quarters. Markets will also track equity flows into regional ETFs.
The data show Brent already 4.39 percent higher on the week, yet regional equities still declined. Upside scenarios center on rapid compression of the risk premium. Downside scenarios involve sustained transit constraints that could pressure current-account balances and force tighter fiscal stances. The configuration leaves the growth cycle exposed to external shocks.
| Time | Country | Event | Our Est. | Consensus | Prior | Impact |
|---|---|---|---|---|---|---|
| MONDAY, OCTOBER 12 | ||||||
| 05:30 | 🇬🇧 | BoE Breeden Speech CB | — | — | — | ●●● |
| 06:30 | 🇮🇳 | Inflation Rate Year-over-Year | — | — | 4.8 | ●●○ |
| 08:50 | 🇬🇧 | BoE Mann Speech CB | — | — | — | ●●● |
| 12:50 | 🇺🇸 | Fed Hammack Speech CB | — | — | — | ●●● |
| 19:01 | 🇬🇧 | BRC Retail Sales Monitor Year-over-Year | — | 0.70 | 0.50 | ●●○ |
| 20:30 | 🇦🇺 | NAB Business Confidence Index | — | — | -8 | ●●● |
| 20:30 | 🇦🇺 | RBA Meeting Minutes CB | — | — | — | ●●● |
| 23:00 | 🇬🇧 | BoE Greene Speech CB | — | — | — | ●●● |
| TUESDAY, OCTOBER 13 | ||||||
| 03:45 | 🇺🇸 | Speech by Fed's Waller | — | — | — | ●●○ |
| 08:15 | 🇺🇸 | ADP Employment Change Weekly | — | — | 23,750 | ●●○ |
| 10:00 | 🇺🇸 | Existing Home Sales | — | 4.0M | 4.0M | ●●● |
| 10:00 | 🇺🇸 | Existing Home Sales Month-over-Month | — | — | -2 | ●●○ |
| 12:00 | 🇬🇧 | BoE Dhingra Speech CB | — | — | — | ●●● |
| 13:00 | 🇺🇸 | Speech by Fed's Barkin | — | — | — | ●●○ |
| 14:00 | 🇺🇸 | Monthly Budget Statement | — | — | -167.0B | ●●○ |
| 16:00 | 🇺🇸 | Speech by Fed's Collins | — | — | — | ●●○ |
| 20:00 | 🇸🇬 | GDP Growth Quarter-over-Quarter Advance Estimate | — | — | 1.4 | ●●○ |
| 20:00 | 🇸🇬 | Monetary Policy Statement | — | — | — | ●●○ |
| 21:30 | 🇨🇳 | Inflation Rate Year-over-Year | — | 1.1 | 0.80 | ●●● |
| 21:30 | 🇨🇳 | Inflation Rate Month-over-Month | — | — | 0.40 | ●●○ |
| 21:30 | 🇨🇳 | Producer Price Index Year-over-Year | — | 4.4 | 3.8 | ●●○ |
| 23:00 | 🇨🇳 | Exports Year-over-Year | — | 25.3 | 25 | ●●● |
| 23:00 | 🇨🇳 | Imports Year-over-Year | — | 23.5 | 28.2 | ●●● |
| 23:00 | 🇨🇳 | Trade Balance | — | 114.5B | 119.1B | ●●● |
| 23:30 | 🇬🇧 | BoE Breeden Speech CB | — | — | — | ●●● |
| WEDNESDAY, OCTOBER 14 | ||||||
| 01:30 | 🇬🇧 | BoE Gov Bailey Speech CB | — | — | — | ●●● |
| 02:00 | 🇩🇪 | Wholesale Prices Month-over-Month | — | 0.70 | 0.90 | ●●○ |
| 02:00 | 🇩🇪 | Wholesale Prices Year-over-Year | — | — | 6.8 | ●●○ |
| 02:00 | 🇬🇧 | BoE Pill Speech CB | — | — | — | ●●● |
| 02:05 | 🇨🇦 | BoC Gov Macklem Speech CB | — | — | — | ●●● |
| 05:40 | 🇺🇸 | Speech by Fed's Bowman | — | — | — | ●●○ |
| 07:00 | 🇺🇸 | MBA 30-Year Mortgage Rate | — | — | 7.5 | ●●○ |
| 08:30 | 🇺🇸 | Core Inflation Rate Month-over-Month | — | 0.20 | 0.30 | ●●● |
| 08:30 | 🇺🇸 | Core Inflation Rate Year-over-Year | — | 2.5 | 2.4 | ●●● |
| 08:30 | 🇺🇸 | Inflation Rate Month-over-Month | — | 0.60 | 0.40 | ●●● |
| 08:30 | 🇺🇸 | Inflation Rate Year-over-Year | — | 3.6 | 3.4 | ●●● |
| 08:30 | 🇺🇸 | CPI s.a | — | — | 334.1 | ●●○ |
| 08:30 | 🇺🇸 | Consumer Price Index | — | — | 335.0 | ●●○ |
| 10:00 | 🇧🇷 | Business Confidence Index | — | — | 44.9 | ●●○ |
| 13:30 | 🇺🇸 | Speech by Fed's Barkin | — | — | — | ●●○ |
| 16:30 | 🇺🇸 | API Weekly Crude Oil Stocks | — | — | -2.1M | ●●○ |
| 19:50 | 🇯🇵 | Machinery Orders Month-over-Month | — | 2.5 | -3.7 | ●●○ |
| 19:50 | 🇯🇵 | Machinery Orders Year-over-Year | — | — | 11.2 | ●●○ |
| 20:30 | 🇦🇺 | Employment Change | — | 20,000 | 39,500 | ●●○ |
| 20:30 | 🇦🇺 | Full-Time Employment Change | — | — | -6,300 | ●●○ |
| 20:30 | 🇦🇺 | Headline Unemployment Rate | — | 4.6 | 4.6 | ●●○ |
| 21:30 | 🇯🇵 | BoJ Koeda Speech CB | — | — | — | ●●● |
| 22:55 | 🇺🇸 | Speech by Fed's Bowman | — | — | — | ●●○ |
| 23:40 | 🇬🇧 | BoE Pill Speech CB | — | — | — | ●●● |
| 23:40 | 🇬🇧 | BoE Woods Speech CB | — | — | — | ●●● |
| Time | Country | Event | Our Est. | Consensus | Prior | Impact |
|---|---|---|---|---|---|---|
| THURSDAY, OCTOBER 15 | ||||||
| 00:30 | 🇳🇱 | Headline Unemployment Rate | — | — | 4 | ●●○ |
| 02:00 | 🇬🇧 | GDP Month-over-Month | — | -0.10 | 0.40 | ●●● |
| 02:00 | 🇬🇧 | GDP 3-Month Avg | — | — | 0.40 | ●●○ |
| 02:00 | 🇬🇧 | Goods Trade Balance | — | -21.8B | -21.0B | ●●○ |
| 02:00 | 🇬🇧 | Goods Trade Balance Non-EU | — | — | -9.7B | ●●○ |
| 02:00 | 🇬🇧 | Industrial Production Month-over-Month | — | -0.10 | 0.20 | ●●○ |
| 02:00 | 🇬🇧 | Manufacturing Production Month-over-Month | — | 0.10 | 0.90 | ●●○ |
| 03:50 | 🇬🇧 | BoE Cleland Speech CB | — | — | — | ●●● |
| 04:45 | 🇬🇧 | BoE Breeden Speech CB | — | — | — | ●●● |
| 05:00 | 🇨🇦 | BoC Rogers Speech CB | — | — | — | ●●● |
| 08:00 | 🇧🇷 | Retail Sales Month-over-Month | — | — | -0.80 | ●●○ |
| 08:30 | 🇺🇸 | Producer Price Index Month-over-Month | — | 0.50 | 0.40 | ●●● |
| 08:30 | 🇺🇸 | Core PPI Month-over-Month | — | 0.30 | 0.20 | ●●○ |
| 08:30 | 🇺🇸 | NY Empire State Manufacturing Index | — | 3.2 | 7.6 | ●●○ |
| 08:30 | 🇺🇸 | Philadelphia Fed Manufacturing Index | — | 26.5 | 37.8 | ●●○ |
| 08:30 | 🇺🇸 | Retail Sales Control Group Month-over-Month | — | — | 1.4 | ●●○ |
| 08:30 | 🇺🇸 | Weekly Jobless Claims | — | 197,000 | 197,000 | ●●○ |
| 09:30 | 🇺🇸 | Retail Sales Month-over-Month | — | 0.30 | 1.2 | ●●● |
| 09:30 | 🇺🇸 | Retail Sales Excluding Autos Month-over-Month | — | 0.50 | 1.4 | ●●○ |
| 10:00 | 🇺🇸 | Business Inventories Month-over-Month | — | 0.40 | 0.80 | ●●○ |
| 12:00 | 🇺🇸 | EIA Weekly Crude Oil Inventory | — | — | -3.2M | ●●○ |
| 12:00 | 🇺🇸 | EIA Weekly Gasoline Inventory | — | — | 382,000 | ●●○ |
| 16:30 | 🇺🇸 | Fed Hammack Speech CB | — | — | — | ●●● |
| 17:30 | 🇳🇿 | Business NZ PMI | — | — | 53.1 | ●●○ |
| 19:00 | 🇰🇷 | Headline Unemployment Rate | — | — | 2.7 | ●●○ |
| 22:00 | 🇬🇧 | BoE Gov Bailey Speech CB | — | — | — | ●●● |
| 23:30 | 🇺🇸 | Fed Chair Warsh Speech CB | — | — | — | ●●● |
| FRIDAY, OCTOBER 16 | ||||||
| 00:15 | 🇨🇦 | BoC Gov Macklem Speech CB | — | — | — | ●●● |
| 06:00 | 🇮🇹 | Trade Balance | — | 7.5B | 8.2B | ●●○ |
| 08:15 | 🇨🇦 | Housing Starts Level | — | 230,000 | 229,000 | ●●○ |
| 08:30 | 🇺🇸 | Export Prices Month-over-Month | — | — | 0.60 | ●●○ |
| 08:30 | 🇺🇸 | Import Prices Month-over-Month | — | 0.60 | 0.70 | ●●○ |
| 09:15 | 🇺🇸 | Industrial Production Month-over-Month | — | 0.30 | 0 | ●●○ |
| 16:00 | 🇺🇸 | Net Long-term TIC Flows | — | 125.7B | -27.9B | ●●○ |
| SATURDAY, OCTOBER 17 | ||||||
| 02:45 | 🇬🇧 | BoE Gov Bailey Speech CB | — | — | — | ●●● |
| SUNDAY, OCTOBER 18 | ||||||
| 17:45 | 🇳🇿 | Trade Balance | — | — | -1.3B | ●●○ |
AI-Generated Content: This publication is 100% generated by artificial intelligence systems and should not be considered as financial advice, investment recommendation, or professional research. All analysis, forecasts, and commentary are algorithmically produced.
Data Sources: Market data from public exchange and market-data providers. US Treasury yields from the Federal Reserve (FRED constant-maturity series). Macroeconomic data from central banks and national statistics offices. Economic calendar data from RoboMacro Economic Calendar. All data subject to revision and may be delayed.
No Warranty: RoboMacro makes no warranty, express or implied, regarding the accuracy, completeness, or reliability of the information contained in this publication. Data may be delayed, incomplete, or contain errors. Past performance is not indicative of future results.
Not Financial Advice: Nothing in this publication constitutes investment advice, tax advice, legal advice, or any other form of professional advice. Any opinions expressed are AI-generated and do not represent the views of any individual or organisation. Readers should consult qualified professionals before making investment decisions.
Nowcasts and Model Output: The US labour nowcast is the median of a ten-model ensemble. Activity indices are composite z-scores of weekly public high-frequency indicators, seasonally adjusted, published only for weeks meeting a minimum indicator-coverage threshold; the as-of date and coverage are shown on every row. All model output carries significant uncertainty.
Contact: [email protected] | robomacro.com
Publication: Global Macro Watch is published weekly on Sundays, covering the preceding Monday-to-Friday week. © 2026 RoboMacro. All rights reserved.