v6 · IRF · evaluation
A 20% metals-supply cut. Every path is a model impulse response versus baseline, not a forecast and not financial advice.
This note traces the model response to a 20% metals-supply cut. Every path is an impulse response versus an unchanged baseline — not a forecast of what will happen in the world and not a reading of market data. The chapters that follow are already sorted by the size of the GDP response.
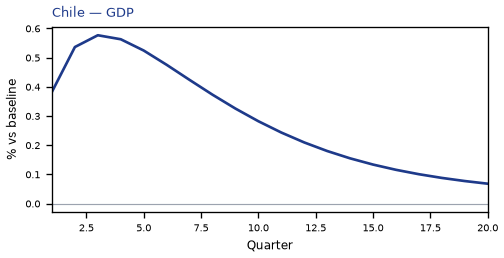
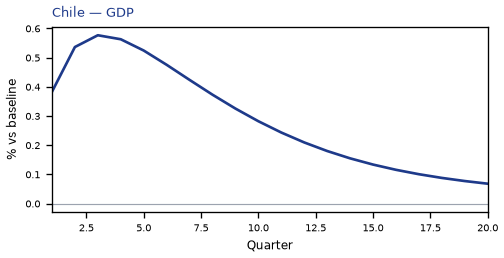
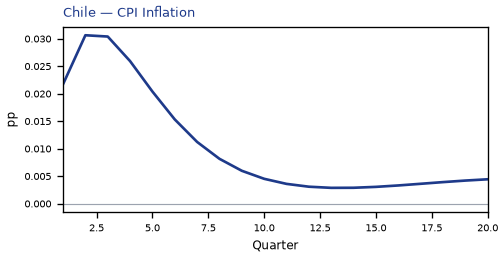
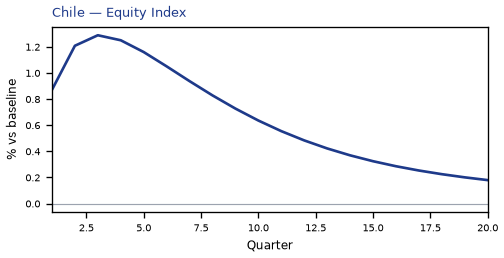
Chile takes the largest GDP move on this path. GDP expands by 0.58% versus baseline by Q3 — a first-order GDP response. Equities firm 1.29%, and the three-year CPI impulse is +0.18 percentage points. The move shows up first in the trade balance, then in private investment and government spending. That is the main adjustment: a change in financial conditions and real income, then the usual lag into activity and prices. It is the conditional elasticity to the shock that was switched on, not a prediction that this path will be realised.
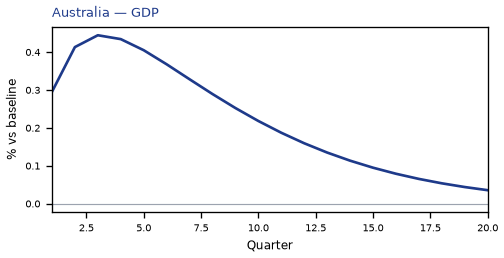
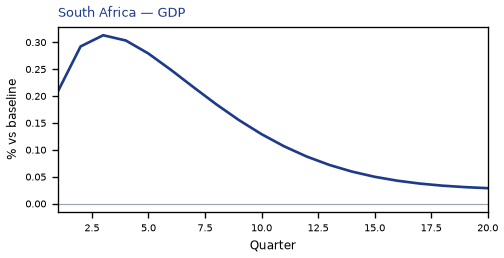
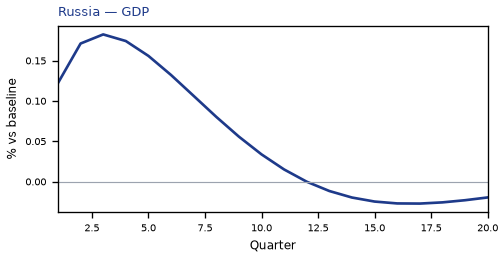
Spillovers are not a carbon copy of that first path. Australia expands by 0.44% versus baseline by Q3 — a first-order GDP response. Equities firm 1.08%, and the three-year CPI impulse is +0.06 percentage points. The move shows up first in the trade balance, then in private investment and government spending. South Africa expands by 0.31% versus baseline by Q3 — a first-order GDP response. Equities firm 1.22%, and the three-year CPI impulse is +0.15 percentage points. The move shows up first in the trade balance, then in private investment and government spending. Russia expands by 0.18% versus baseline by Q3 — a moderate GDP response. Equities firm 0.28%, and the three-year CPI impulse is +0.18 percentage points. The move shows up first in the trade balance, then in private investment and government spending. The contrast is the point: the largest spillover is not a scaled copy of the first economy.
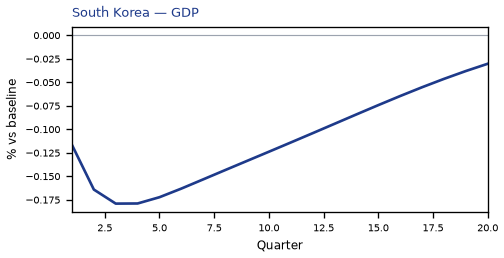
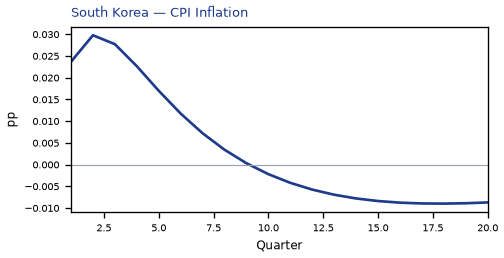
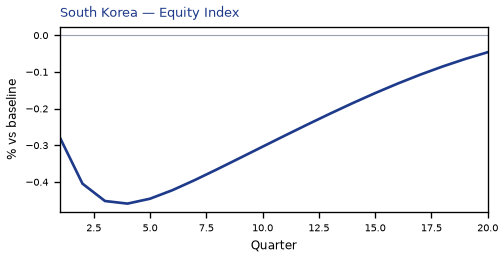
South Korea contracts by 0.18% versus baseline by Q3 — a moderate GDP response. Equities soften 0.46%, and the three-year CPI impulse is +0.13 percentage points. The move shows up first in the trade balance, then in private investment and household consumption.
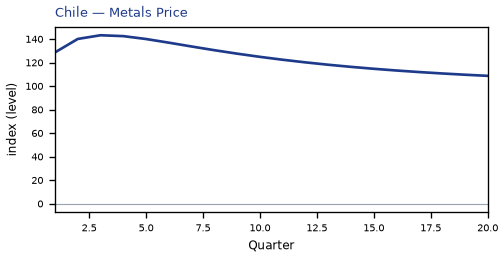
For the lead economy, Chile, the financial backdrop looks like this. On the government curve, benchmark bond prices cheapen 0.65% by Q5, and unused tenors stay in the background rather than getting a sentence each; the home currency is stronger versus the dollar (-12.67% in Q3); the metals price index moves to 143.2 in Q3. Treat those as the financial backdrop, not as extra shocks, unless they appear in the active treatment.
Read GDP as percent of baseline GDP: −0.52 is minus half a percent, never −52%. A 200 basis-point move is 2.00 percentage points on the policy rate. CPI over three years is the sum of twelve quarterly impulses, not an annualised rate. A rising real exchange rate is a real depreciation — a weaker, more competitive home currency.
The remaining economies are smaller spillovers, written in the same order in the chapters that follow. Each chapter is a desk note, not a catalog of every series. This material is a model-based summary and is not financial advice.
27,000 numbers (30 countries × 45 series × Q1–Q20) · impulse responses · not financial advice
The main impact of a 20% metals-supply cut on Chile is a large rise in GDP of 0.58% by Q3. This is a model impulse response versus baseline, not a forecast. Equities firm 1.29% by Q3. The three-year CPI impulse is +0.18 percentage points.
Demand and trade. The trade balance (net exports — this model does not split imports from exports) improves to +3.81% in Q3; private investment rises 1.54% by Q2; government spending rises 1.26% by Q3; government debt rises 0.38% by Q11; related moves also show up in household consumption.
Labour. Real wages rise 0.66% by Q20; employment rises 0.46% by Q7; unemployment eases by -0.18 percentage points in Q7.
Prices. Firms' marginal cost rises 0.35% by Q3; CPI inflation, domestic inflation stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.65% by Q5; 10-year bond prices cheapen 0.42% by Q1; 5-year bond prices cheapen 0.38% by Q1; 30-year bond prices cheapen 0.32% by Q1; related moves also show up in 2-year bond prices, the local policy rate, 3-month government yields; the rest of the government curve barely moves.
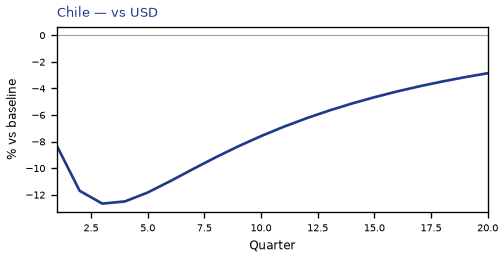
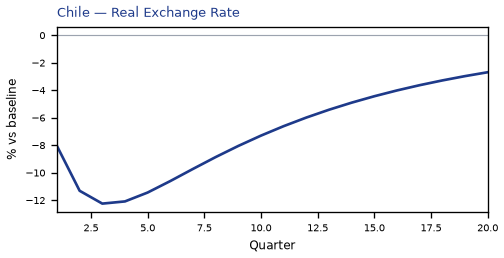
Exchange rates. The home currency is stronger versus the dollar (-12.67% in Q3); the real exchange rate shows a real appreciation (a stronger home currency), peaking at -12.25% in Q3; the NEER prints a trade-weighted appreciation (+11.80% in Q3).
Equities and risk. Equity prices rise 1.29% by Q3; Tobin's Q (the value of installed capital) rises 1.08% by Q2; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices rise 0.50% by Q11; bank credit is close to unchanged.
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output rises 3.78% by Q3; services output rises 0.35% by Q3; the capital stock stays close to baseline.
The GDP response has mostly faded by Q15 (Q20 is still +0.07%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
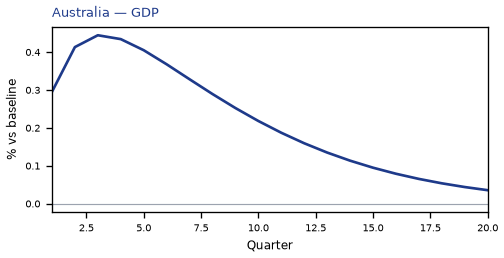
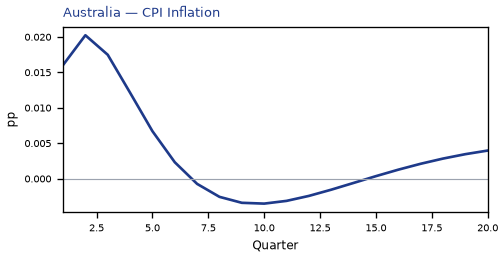
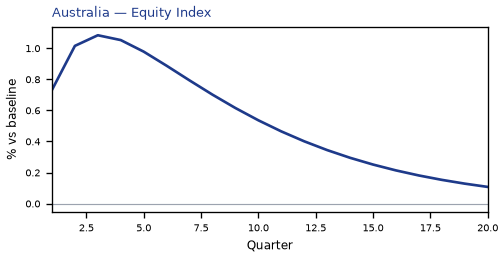
The main impact of a 20% metals-supply cut on Australia is a large rise in GDP of 0.44% by Q3. This is a model impulse response versus baseline, not a forecast. Equities firm 1.08% by Q3. The three-year CPI impulse is +0.06 percentage points.
Demand and trade. The trade balance (net exports — this model does not split imports from exports) improves to +2.96% in Q3; private investment rises 1.14% by Q2; government spending rises 0.52% by Q3; household consumption rises 0.29% by Q4; related moves also show up in government debt.
Labour. Real wages rise 0.42% by Q20; employment rises 0.39% by Q7; unemployment eases by -0.20 percentage points in Q7.
Prices. Firms' marginal cost rises 0.27% by Q3; CPI inflation, domestic inflation stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 1.26% by Q7; 10-year bond prices cheapen 0.66% by Q1; 5-year bond prices cheapen 0.60% by Q2; 30-year bond prices cheapen 0.49% by Q1; related moves also show up in 2-year bond prices, the local policy rate, 3-month government yields; the rest of the government curve barely moves.
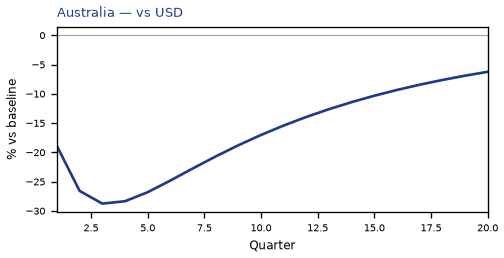
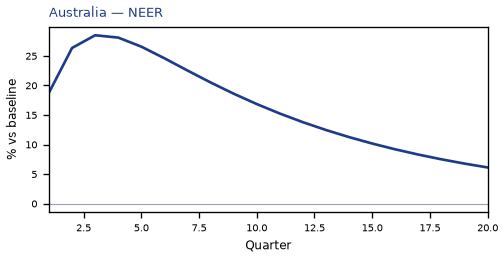
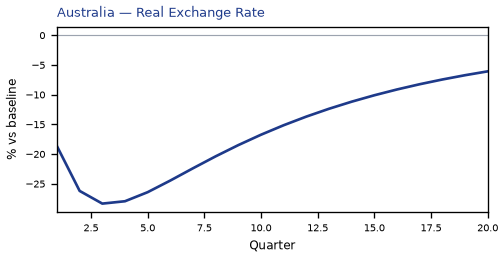
Exchange rates. The home currency is stronger versus the dollar (-28.77% in Q3); the NEER prints a trade-weighted appreciation (+28.49% in Q3); the real exchange rate shows a real appreciation (a stronger home currency), peaking at -28.35% in Q3.
Equities and risk. Equity prices rise 1.08% by Q3; Tobin's Q (the value of installed capital) rises 0.80% by Q2; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices rise 0.29% by Q12; bank credit is close to unchanged.
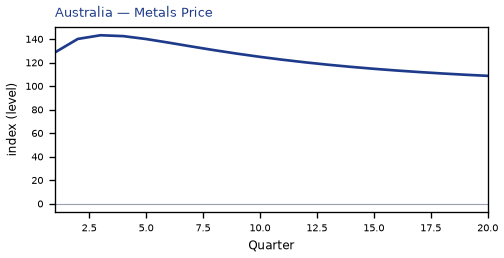
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output rises 8.57% by Q3; services output rises 0.32% by Q3; the capital stock stays close to baseline.
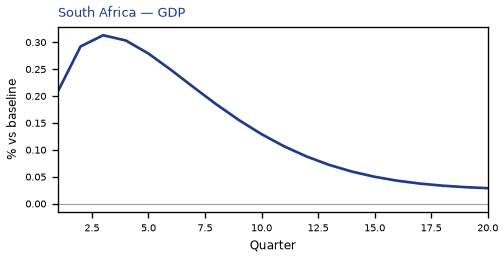
The GDP response has mostly faded by Q15 (Q20 is still +0.04%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
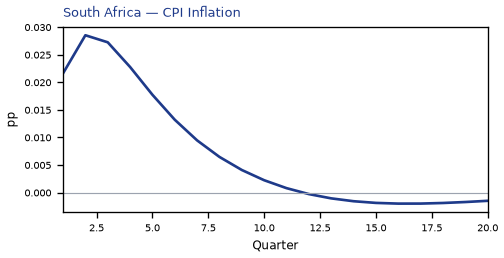
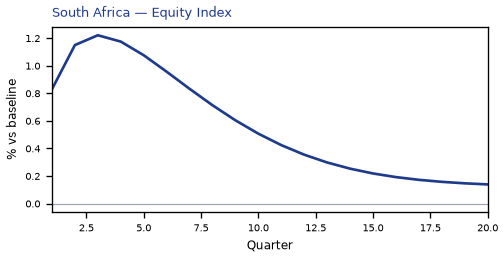
The main impact of a 20% metals-supply cut on South Africa is a large rise in GDP of 0.31% by Q3. This is a model impulse response versus baseline, not a forecast. Equities firm 1.22% by Q3. The three-year CPI impulse is +0.15 percentage points.
Demand and trade. The trade balance (net exports — this model does not split imports from exports) improves to +2.12% in Q3; private investment rises 0.80% by Q2; government spending rises 0.27% by Q3; household consumption rises 0.18% by Q4; related moves also show up in government debt.
Labour. Real wages rise 0.36% by Q19; employment rises 0.25% by Q7; unemployment eases by -0.07 percentage points in Q6.
Prices. Firms' marginal cost rises 0.19% by Q3; CPI inflation, domestic inflation stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.50% by Q5; 5-year bond prices cheapen 0.21% by Q1; 2-year bond prices cheapen 0.19% by Q2; 10-year bond prices cheapen 0.18% by Q1; related moves also show up in 30-year bond prices, the local policy rate, 3-month government yields; the rest of the government curve barely moves.
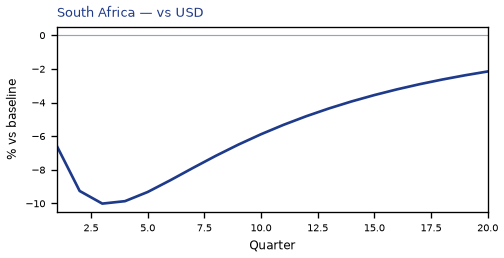
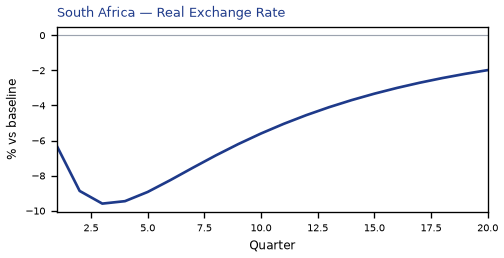
Exchange rates. The home currency is stronger versus the dollar (-10.01% in Q3); the real exchange rate shows a real appreciation (a stronger home currency), peaking at -9.59% in Q3; the NEER prints a trade-weighted appreciation (+9.29% in Q3).
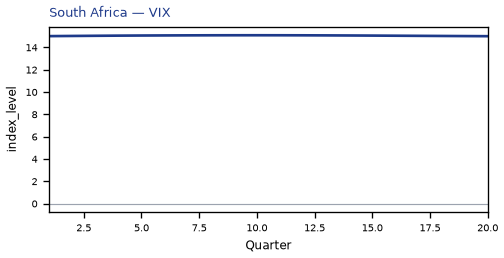
Equities and risk. Equity prices rise 1.22% by Q3; Tobin's Q (the value of installed capital) rises 0.56% by Q2; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices rise 0.25% by Q10; bank credit is close to unchanged.
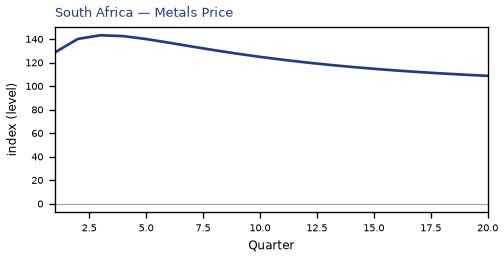
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output rises 2.93% by Q3; services output rises 0.20% by Q3; the capital stock stays close to baseline.
The GDP response has mostly faded by Q13 (Q20 is still +0.03%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
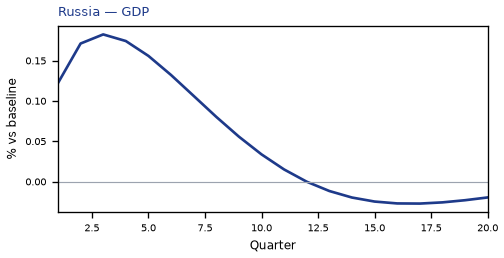
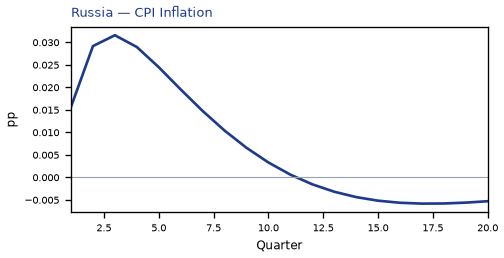
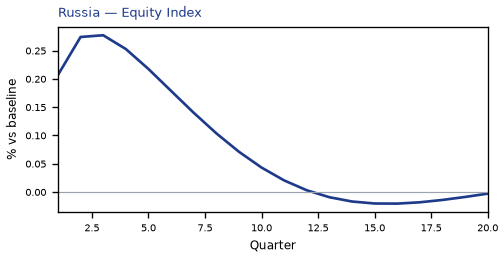
The main impact of a 20% metals-supply cut on Russia is a moderate rise in GDP of 0.18% by Q3. This is a model impulse response versus baseline, not a forecast. Equities firm 0.28% by Q3. The three-year CPI impulse is +0.18 percentage points.
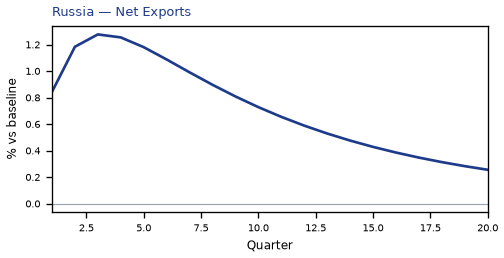
Demand and trade. The trade balance (net exports — this model does not split imports from exports) improves to +1.28% in Q3; private investment rises 0.44% by Q2; government spending rises 0.38% by Q3; household consumption rises 0.10% by Q4; government debt stays close to baseline.
Labour. Real wages rise 0.25% by Q15; employment rises 0.13% by Q7; unemployment eases by -0.05 percentage points in Q6.
Prices. Firms' marginal cost rises 0.11% by Q3; CPI inflation, domestic inflation stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.41% by Q5; 5-year bond prices cheapen 0.21% by Q1; 2-year bond prices cheapen 0.20% by Q2; 10-year bond prices cheapen 0.13% by Q1; related moves also show up in the local policy rate, 3-month government yields, 2-year government yields; the rest of the government curve barely moves.
Exchange rates. The home currency is stronger versus the dollar (-0.98% in Q3); the NEER prints a trade-weighted appreciation (+0.62% in Q3); the real exchange rate shows a real appreciation (a stronger home currency), peaking at -0.56% in Q3.
Equities and risk. Tobin's Q (the value of installed capital) rises 0.31% by Q2; equity prices rise 0.28% by Q3; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices rise 0.13% by Q8; bank credit is close to unchanged.
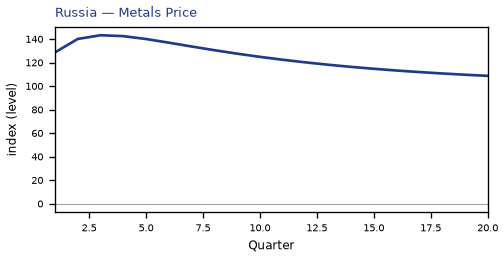
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output rises 0.20% by Q3; services output rises 0.10% by Q3; the capital stock stays close to baseline.
The GDP response has mostly faded by Q10 (Q20 is still -0.02%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
The main impact of a 20% metals-supply cut on South Korea is a moderate drop in GDP of 0.18% by Q3. This is a model impulse response versus baseline, not a forecast. Equities soften 0.46% by Q4. The three-year CPI impulse is +0.13 percentage points.
Demand and trade. The trade balance (net exports — this model does not split imports from exports) softens to -1.05% in Q3; private investment falls 0.54% by Q3; household consumption falls 0.11% by Q4; government debt falls 0.09% by Q16; government spending stays close to baseline.
Labour. Real wages fall 0.15% by Q20; employment falls 0.13% by Q10; unemployment rises by +0.06 percentage points in Q8.
Prices. Firms' marginal cost falls 0.10% by Q4; CPI inflation, domestic inflation stay close to baseline.
Policy rates and the government curve. Benchmark bond prices rally 0.29% by Q18; 10-year bond prices rally 0.23% by Q10; 5-year bond prices rally 0.20% by Q12; 30-year bond prices rally 0.17% by Q10; related moves also show up in 2-year bond prices, the local policy rate, 3-month government yields; the rest of the government curve barely moves.
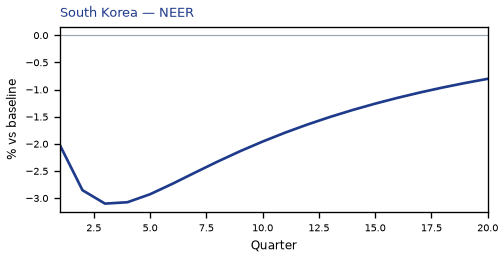
Exchange rates. The NEER prints a trade-weighted depreciation (-3.10% in Q3); the real exchange rate shows a real depreciation (a weaker, more competitive home currency), peaking at +1.36% in Q3; the home currency is weaker versus the dollar (+0.95% in Q4).
Equities and risk. Equity prices fall 0.46% by Q4; Tobin's Q (the value of installed capital) falls 0.38% by Q3; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices fall 0.15% by Q14; bank credit is close to unchanged.
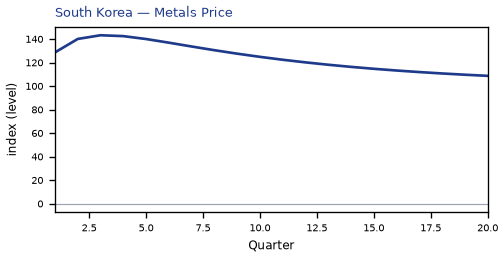
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output falls 0.47% by Q3; services output falls 0.11% by Q3; the capital stock stays close to baseline.
The GDP response has mostly faded by Q19 (Q20 is still -0.03%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
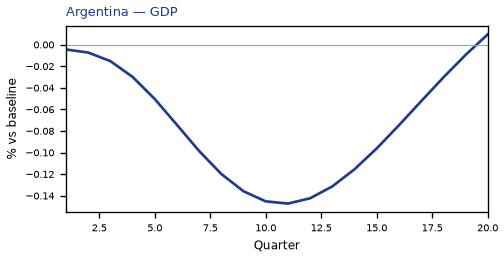
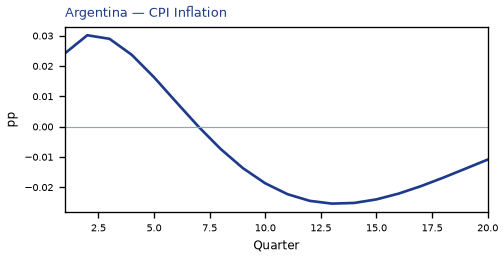
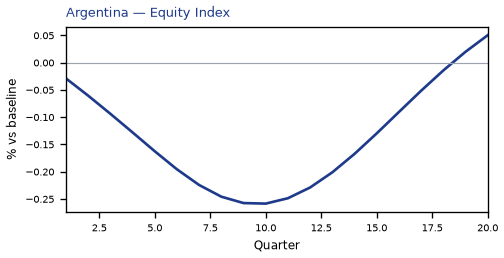
The main impact of a 20% metals-supply cut on Argentina is a moderate drop in GDP of 0.15% by Q11. This is a model impulse response versus baseline, not a forecast. Equities soften 0.26% by Q10.
Demand and trade. Private investment falls 0.34% by Q8; government debt falls 0.10% by Q20; household consumption, the trade balance, government spending stay close to baseline.
Labour. Real wages fall 0.24% by Q20; employment falls 0.12% by Q15; unemployment stays close to baseline.
Prices. Firms' marginal cost falls 0.09% by Q11; CPI inflation, domestic inflation stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.29% by Q3; 5-year bond prices rally 0.25% by Q8; 2-year bond prices rally 0.19% by Q11; 10-year bond prices rally 0.13% by Q8; related moves also show up in the local policy rate, 3-month government yields, 2-year government yields; the rest of the government curve barely moves.
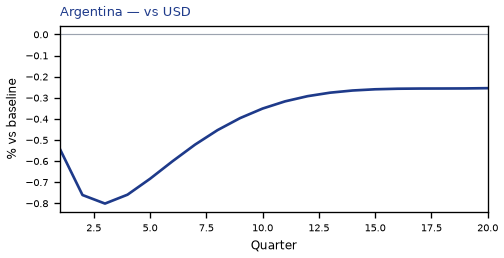
Exchange rates. The home currency is stronger versus the dollar (-0.80% in Q3); the NEER prints a trade-weighted depreciation (-0.51% in Q5); the real exchange rate shows a real appreciation (a stronger home currency), peaking at -0.38% in Q3.
Equities and risk. Equity prices fall 0.26% by Q10; Tobin's Q (the value of installed capital) falls 0.24% by Q8; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices fall 0.13% by Q15; bank credit is close to unchanged.
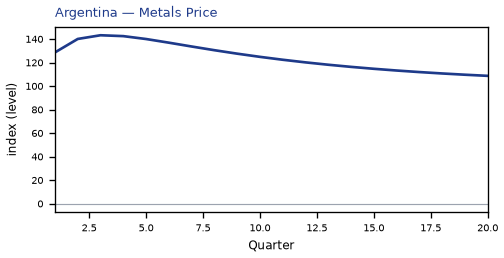
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output rises 0.11% by Q3; services output falls 0.08% by Q11; the capital stock stays close to baseline.
The GDP response has mostly faded by Q18 (Q20 is still +0.01%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
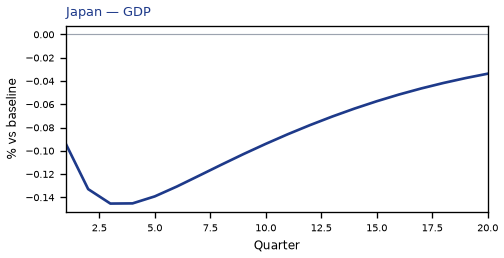
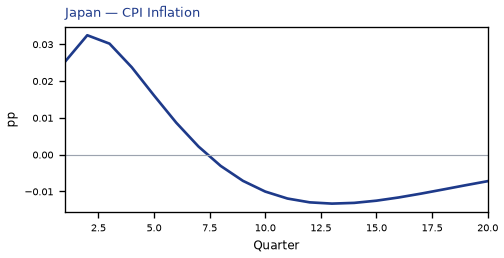
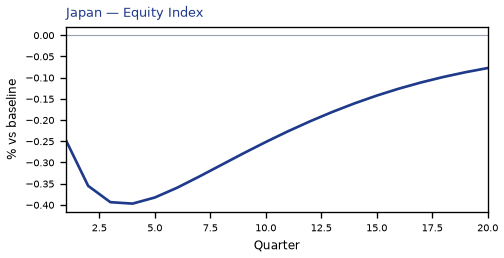
The main impact of a 20% metals-supply cut on Japan is a moderate drop in GDP of 0.15% by Q3. This is a model impulse response versus baseline, not a forecast. Equities soften 0.40% by Q4. The three-year CPI impulse is +0.09 percentage points.
Demand and trade. The trade balance (net exports — this model does not split imports from exports) softens to -0.85% in Q3; private investment falls 0.40% by Q3; household consumption falls 0.09% by Q4; government spending, government debt stay close to baseline.
Labour. Employment falls 0.11% by Q8; unemployment rises by +0.08 percentage points in Q8; real wages stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.17% by Q5; the rest of the government curve barely moves.
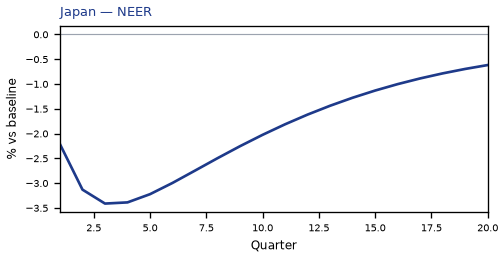
Exchange rates. The NEER prints a trade-weighted depreciation (-3.41% in Q3); the real exchange rate shows a real depreciation (a weaker, more competitive home currency), peaking at +0.99% in Q4; the home currency is weaker versus the dollar (+0.57% in Q4).
Equities and risk. Equity prices fall 0.40% by Q4; Tobin's Q (the value of installed capital) falls 0.28% by Q3; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices fall 0.11% by Q15; bank credit is close to unchanged.
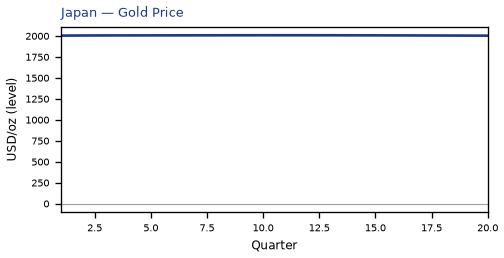
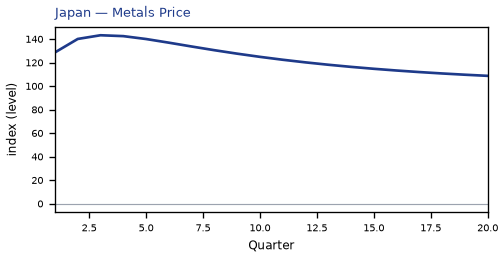
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output falls 0.34% by Q4; services output falls 0.10% by Q3; the capital stock stays close to baseline.
The GDP response has mostly faded by Q20 (Q20 is still -0.03%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
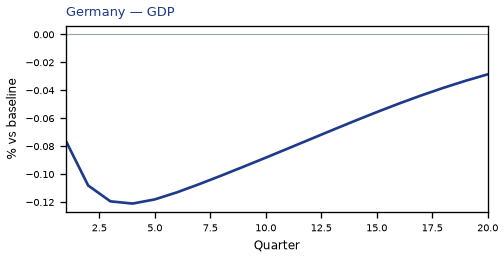
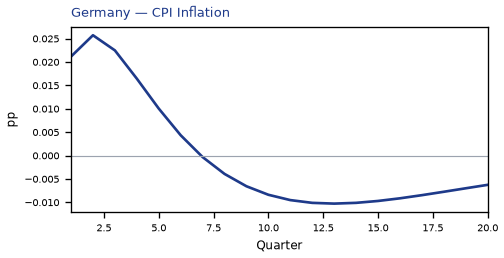
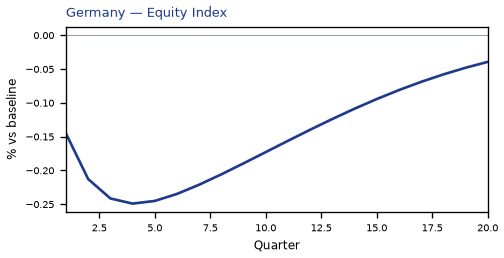
The main impact of a 20% metals-supply cut on Germany is a moderate drop in GDP of 0.12% by Q4. This is a model impulse response versus baseline, not a forecast. Equities soften 0.25% by Q4. The three-year CPI impulse is +0.06 percentage points.
Demand and trade. The trade balance (net exports — this model does not split imports from exports) softens to -0.63% in Q3; private investment falls 0.38% by Q4; household consumption, government spending, government debt stay close to baseline.
Labour. Employment falls 0.09% by Q10; real wages fall 0.08% by Q20; unemployment rises by +0.07 percentage points in Q9.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.37% by Q5; 10-year bond prices rally 0.11% by Q13; 5-year bond prices rally 0.10% by Q15; 30-year bond prices rally 0.09% by Q13; related moves also show up in 2-year bond prices, the local policy rate, 3-month government yields; the rest of the government curve barely moves.
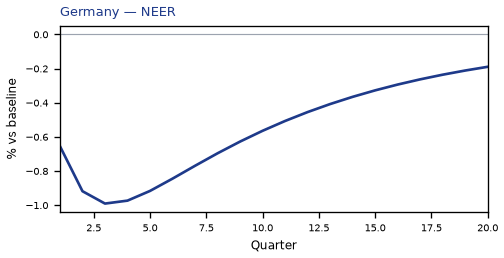
Exchange rates. The NEER prints a trade-weighted depreciation (-0.99% in Q3); the real exchange rate shows a real depreciation (a weaker, more competitive home currency), peaking at +0.87% in Q3; the home currency is weaker versus the dollar (+0.46% in Q3).
Equities and risk. Tobin's Q (the value of installed capital) falls 0.27% by Q4; equity prices fall 0.25% by Q4; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices fall 0.11% by Q15; bank credit is close to unchanged.
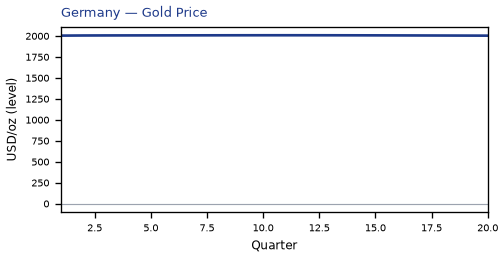
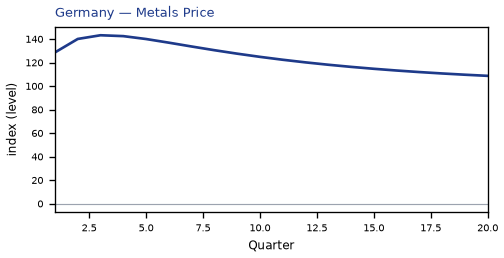
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output falls 0.30% by Q3; services output falls 0.08% by Q4; the capital stock stays close to baseline.
The GDP response has mostly faded by Q20 (Q20 is still -0.03%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
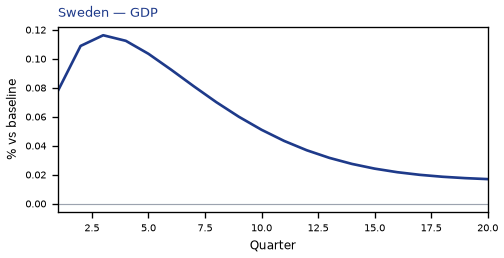
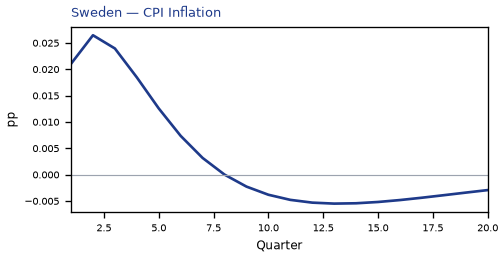
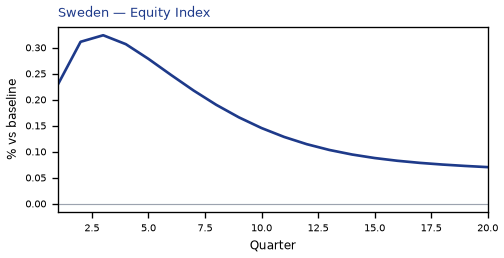
The main impact of a 20% metals-supply cut on Sweden is a moderate rise in GDP of 0.12% by Q3. This is a model impulse response versus baseline, not a forecast. Equities firm 0.32% by Q3. The three-year CPI impulse is +0.10 percentage points.
Demand and trade. The trade balance (net exports — this model does not split imports from exports) improves to +0.84% in Q3; private investment rises 0.28% by Q2; household consumption, government spending, government debt stay close to baseline.
Labour. Real wages rise 0.13% by Q18; employment rises 0.08% by Q8; unemployment eases by -0.05 percentage points in Q6.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.47% by Q5; 5-year bond prices cheapen 0.12% by Q1; 2-year bond prices cheapen 0.12% by Q2; the local policy rate rises 0.08 percentage points by Q5; related moves also show up in 3-month government yields, 2-year government yields; the rest of the government curve barely moves.
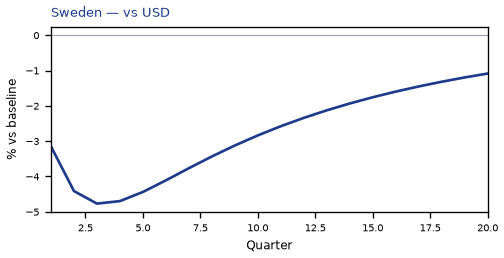
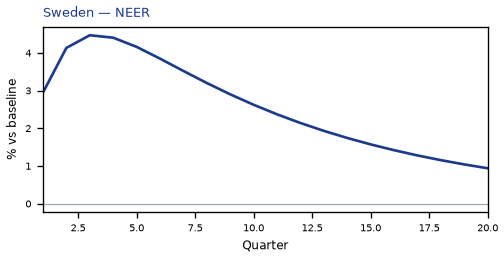
Exchange rates. The home currency is stronger versus the dollar (-4.77% in Q3); the NEER prints a trade-weighted appreciation (+4.47% in Q3); the real exchange rate shows a real appreciation (a stronger home currency), peaking at -4.35% in Q3.
Equities and risk. Equity prices rise 0.32% by Q3; Tobin's Q (the value of installed capital) rises 0.20% by Q2; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices and bank credit are close to unchanged.
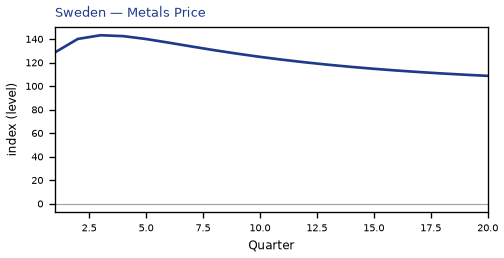
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output rises 1.33% by Q3; services output rises 0.08% by Q3; the capital stock stays close to baseline.
The GDP response has mostly faded by Q14 (Q20 is still +0.02%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
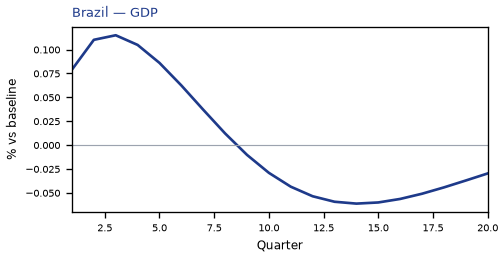
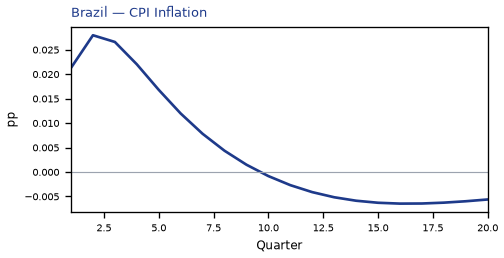
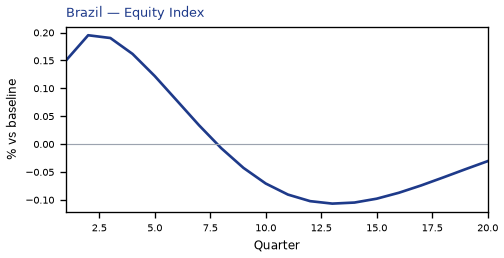
The main impact of a 20% metals-supply cut on Brazil is a moderate rise in GDP of 0.12% by Q3. This is a model impulse response versus baseline, not a forecast. Equities firm 0.20% by Q2. The three-year CPI impulse is +0.13 percentage points.
Demand and trade. The trade balance (net exports — this model does not split imports from exports) improves to +0.85% in Q3; private investment rises 0.20% by Q2; government spending rises 0.13% by Q3; household consumption, government debt stay close to baseline.
Labour. Real wages rise 0.14% by Q13; employment, unemployment stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.68% by Q4; 2-year bond prices cheapen 0.24% by Q2; 5-year bond prices cheapen 0.17% by Q1; the local policy rate rises 0.16 percentage points by Q4; related moves also show up in 3-month government yields, 10-year bond prices, 2-year government yields; the rest of the government curve barely moves.
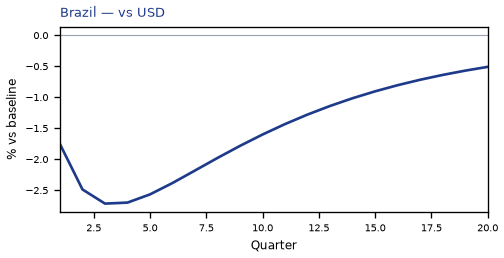
Exchange rates. The home currency is stronger versus the dollar (-2.72% in Q3); the real exchange rate shows a real appreciation (a stronger home currency), peaking at -2.30% in Q3; the NEER prints a trade-weighted appreciation (+1.90% in Q3).
Equities and risk. Equity prices rise 0.20% by Q2; Tobin's Q (the value of installed capital) rises 0.14% by Q2; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices and bank credit are close to unchanged.
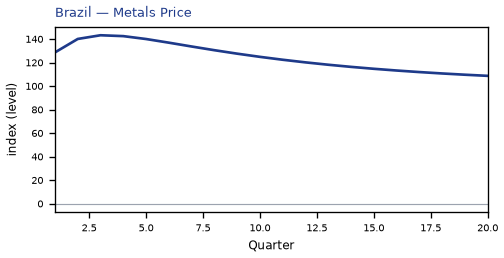
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output rises 0.71% by Q3; services output, the capital stock stay close to baseline.
The GDP response has mostly faded by Q8 (Q20 is still -0.03%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
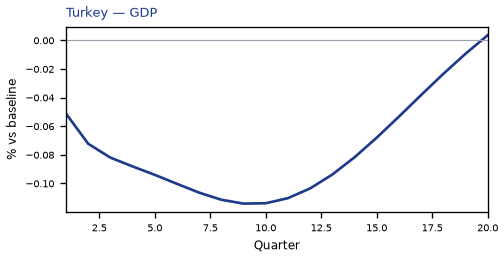
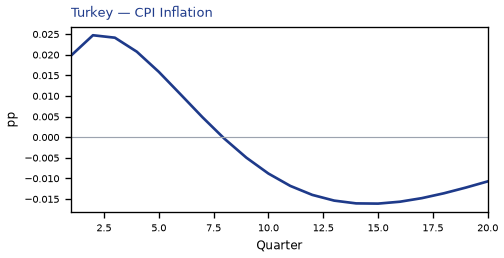
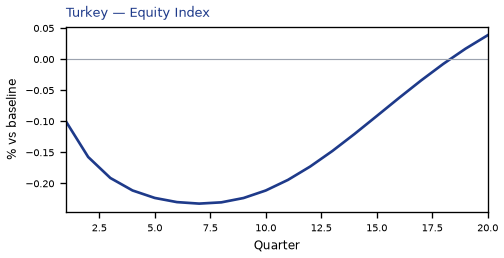
The main impact of a 20% metals-supply cut on Turkey is a moderate drop in GDP of 0.11% by Q9. This is a model impulse response versus baseline, not a forecast. Equities soften 0.23% by Q7. The three-year CPI impulse is +0.08 percentage points.
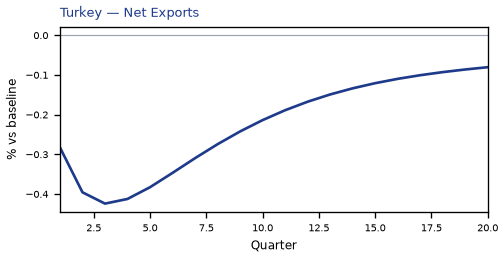
Demand and trade. The trade balance (net exports — this model does not split imports from exports) softens to -0.42% in Q3; private investment falls 0.37% by Q5; government debt falls 0.11% by Q17; household consumption, government spending stay close to baseline.
Labour. Real wages fall 0.17% by Q20; employment falls 0.10% by Q14; unemployment stays close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.29% by Q4; 5-year bond prices rally 0.19% by Q9; 10-year bond prices rally 0.14% by Q9; 2-year bond prices rally 0.12% by Q13; related moves also show up in 30-year bond prices, the local policy rate, 3-month government yields; the rest of the government curve barely moves.
Exchange rates. The NEER prints a trade-weighted depreciation (-0.34% in Q6); the real exchange rate shows a real depreciation (a weaker, more competitive home currency), peaking at +0.29% in Q8; the home currency is stronger versus the dollar (-0.18% in Q2).
Equities and risk. Tobin's Q (the value of installed capital) falls 0.26% by Q5; equity prices fall 0.23% by Q7; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices fall 0.13% by Q14; bank credit is close to unchanged.
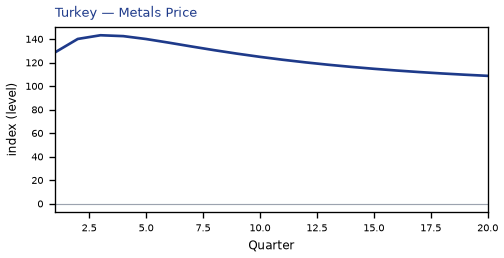
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output falls 0.12% by Q8; services output, the capital stock stay close to baseline.
The GDP response has mostly faded by Q18 (Q20 is still +0.00%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
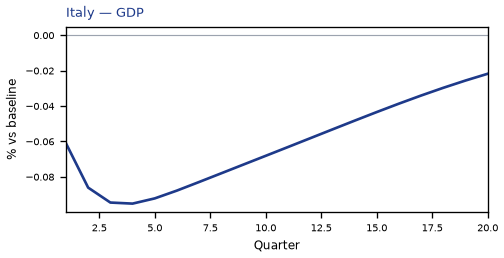
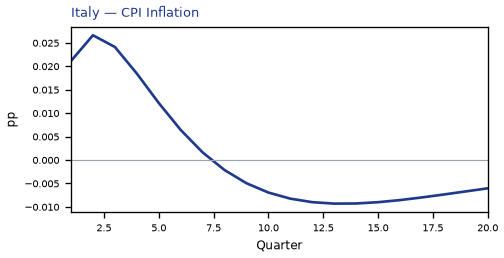
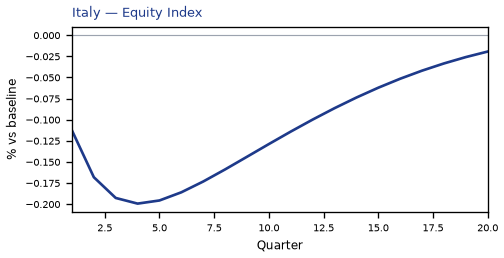
The main impact of a 20% metals-supply cut on Italy is only a small drop in GDP of 0.10% by Q4. This is a model impulse response versus baseline, not a forecast. Equities soften 0.20% by Q4. The three-year CPI impulse is +0.08 percentage points.
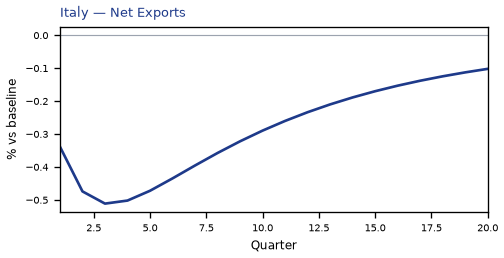
Demand and trade. The trade balance (net exports — this model does not split imports from exports) softens to -0.51% in Q3; private investment falls 0.32% by Q4; household consumption, government spending, government debt stay close to baseline.
Labour. Employment, unemployment, real wages stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.37% by Q5; 10-year bond prices rally 0.11% by Q13; 5-year bond prices rally 0.10% by Q15; 30-year bond prices rally 0.09% by Q13; related moves also show up in 2-year bond prices, the local policy rate, 3-month government yields; the rest of the government curve barely moves.
Exchange rates. The real exchange rate shows a real depreciation (a weaker, more competitive home currency), peaking at +0.44% in Q3; the NEER prints a trade-weighted depreciation (-0.38% in Q3); the home currency is stronger versus the dollar (-0.10% in Q18).
Equities and risk. Tobin's Q (the value of installed capital) falls 0.22% by Q4; equity prices fall 0.20% by Q4; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices fall 0.08% by Q15; bank credit is close to unchanged.
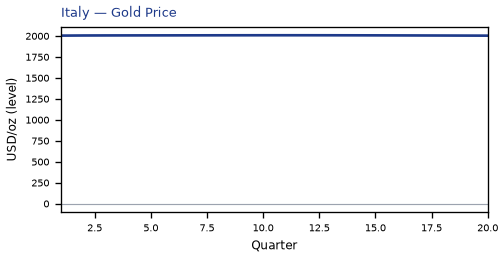
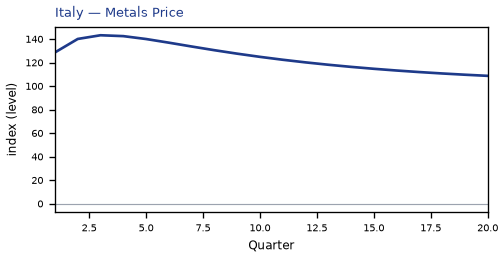
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output falls 0.15% by Q3; services output, the capital stock stay close to baseline.
The GDP response has mostly faded by Q20 (Q20 is still -0.02%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
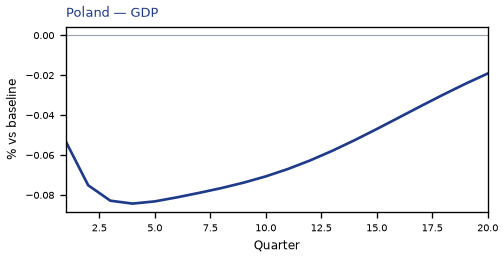
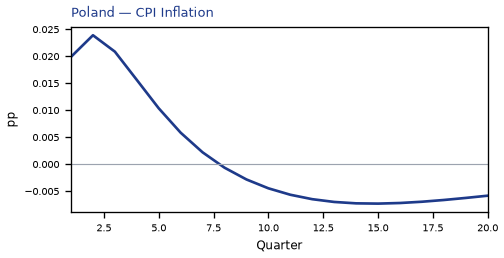
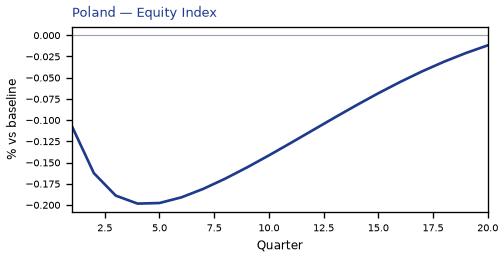
The main impact of a 20% metals-supply cut on Poland is only a small drop in GDP of 0.08% by Q4. This is a model impulse response versus baseline, not a forecast. Equities soften 0.20% by Q4. The three-year CPI impulse is +0.08 percentage points.
Demand and trade. The trade balance (net exports — this model does not split imports from exports) softens to -0.42% in Q3; private investment falls 0.33% by Q4; household consumption, government spending, government debt stay close to baseline.
Labour. Employment, unemployment, real wages stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.30% by Q4; 10-year bond prices rally 0.13% by Q12; 5-year bond prices rally 0.12% by Q13; 30-year bond prices rally 0.10% by Q12; related moves also show up in 2-year bond prices, the local policy rate, 3-month government yields; the rest of the government curve barely moves.
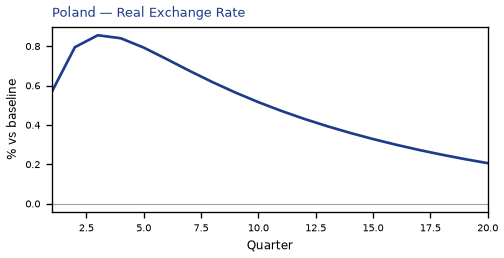
Exchange rates. The real exchange rate shows a real depreciation (a weaker, more competitive home currency), peaking at +0.86% in Q3; the NEER prints a trade-weighted depreciation (-0.70% in Q3); the home currency is weaker versus the dollar (+0.44% in Q3).
Equities and risk. Tobin's Q (the value of installed capital) falls 0.23% by Q4; equity prices fall 0.20% by Q4; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices fall 0.09% by Q15; bank credit is close to unchanged.
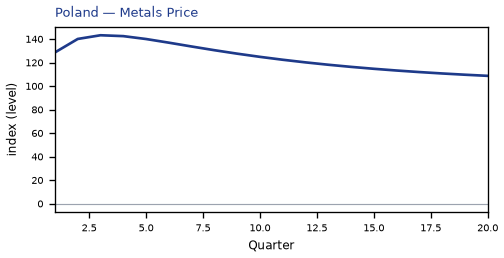
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output falls 0.28% by Q3; services output, the capital stock stay close to baseline.
The GDP response has mostly faded by Q20 (Q20 is still -0.02%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
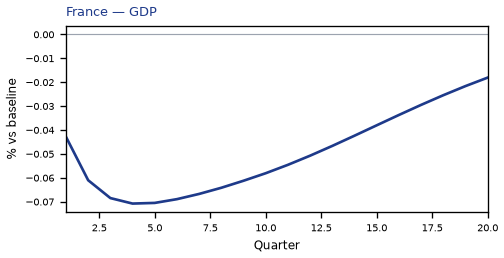
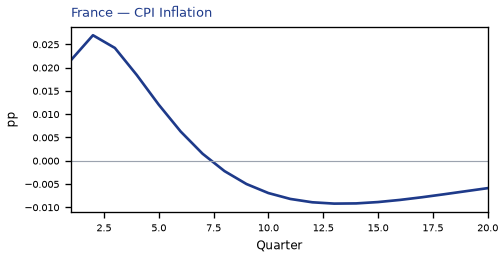
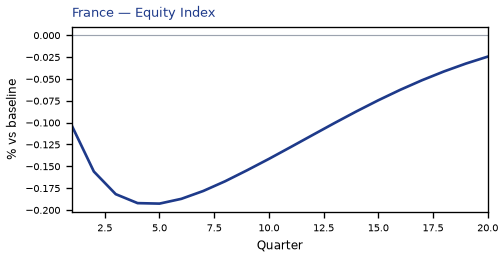
The main impact of a 20% metals-supply cut on France is only a small drop in GDP of 0.07% by Q4. This is a model impulse response versus baseline, not a forecast. Equities soften 0.19% by Q5. The three-year CPI impulse is +0.08 percentage points.
Demand and trade. The trade balance (net exports — this model does not split imports from exports) softens to -0.34% in Q3; private investment falls 0.27% by Q4; household consumption, government spending, government debt stay close to baseline.
Labour. Employment, unemployment, real wages stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.37% by Q5; 10-year bond prices rally 0.11% by Q13; 5-year bond prices rally 0.10% by Q15; 30-year bond prices rally 0.09% by Q13; related moves also show up in 2-year bond prices, the local policy rate, 3-month government yields; the rest of the government curve barely moves.
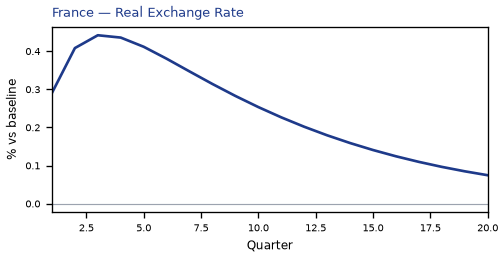
Exchange rates. The real exchange rate shows a real depreciation (a weaker, more competitive home currency), peaking at +0.44% in Q3; the NEER prints a trade-weighted depreciation (-0.25% in Q3); the home currency is stronger versus the dollar (-0.10% in Q18).
Equities and risk. Equity prices fall 0.19% by Q5; Tobin's Q (the value of installed capital) falls 0.19% by Q4; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices and bank credit are close to unchanged.
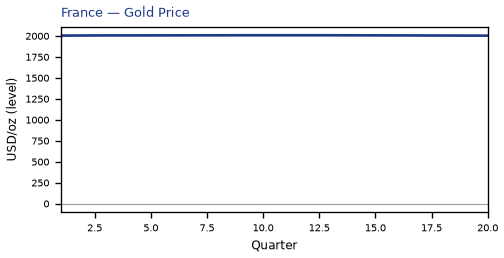
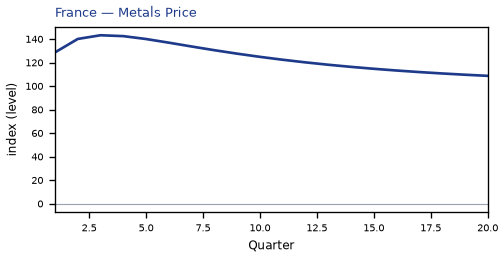
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output falls 0.15% by Q3; services output, the capital stock stay close to baseline.
By Q20, GDP is still -0.02% from baseline.
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
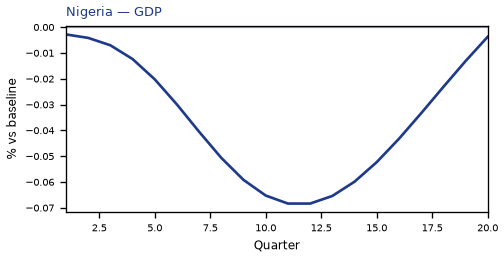
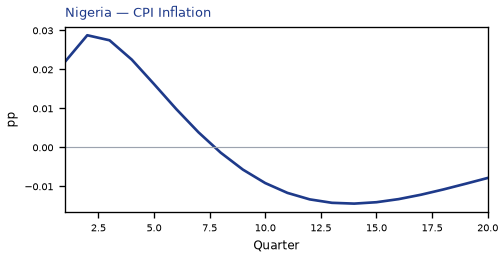
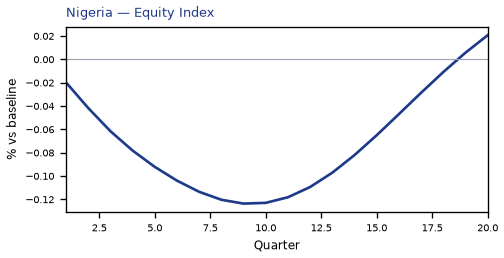
The main impact of a 20% metals-supply cut on Nigeria is only a small drop in GDP of 0.07% by Q12. This is a model impulse response versus baseline, not a forecast. Equities soften 0.12% by Q9. The three-year CPI impulse is +0.09 percentage points.
Demand and trade. Private investment falls 0.20% by Q7; government debt falls 0.14% by Q20; household consumption, the trade balance, government spending stay close to baseline.
Labour. Real wages fall 0.08% by Q20; employment, unemployment stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.22% by Q4; 5-year bond prices rally 0.14% by Q10; 2-year bond prices cheapen 0.12% by Q1; 10-year bond prices rally 0.11% by Q10; related moves also show up in the local policy rate, 3-month government yields, 2-year government yields; the rest of the government curve barely moves.
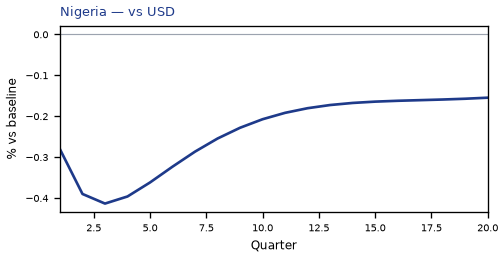
Exchange rates. The home currency is stronger versus the dollar (-0.41% in Q3); the NEER prints a trade-weighted depreciation (-0.31% in Q4); the real exchange rate shows a real depreciation (a weaker, more competitive home currency), peaking at +0.08% in Q11.
Equities and risk. Tobin's Q (the value of installed capital) falls 0.14% by Q7; equity prices fall 0.12% by Q9; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices and bank credit are close to unchanged.
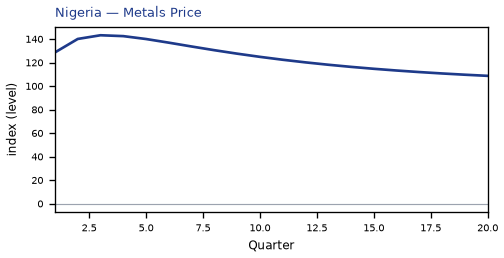
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output, services output, the capital stock stay close to baseline.
The GDP response has mostly faded by Q19 (Q20 is still -0.00%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
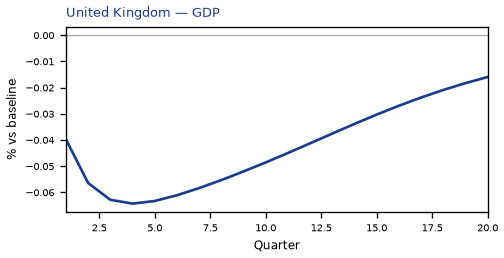
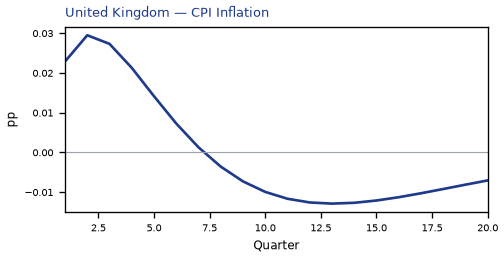
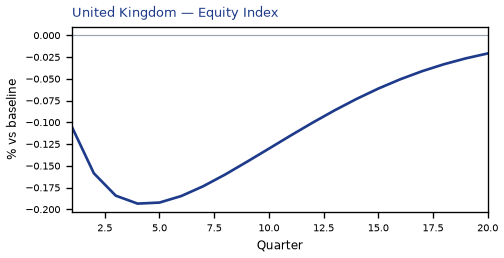
The main impact of a 20% metals-supply cut on the United Kingdom is only a small drop in GDP of 0.06% by Q4. This is a model impulse response versus baseline, not a forecast. Equities soften 0.19% by Q4. The three-year CPI impulse is +0.08 percentage points.
Demand and trade. The trade balance (net exports — this model does not split imports from exports) softens to -0.34% in Q3; private investment falls 0.20% by Q4; household consumption, government spending, government debt stay close to baseline.
Labour. Employment, unemployment, real wages stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.15% by Q6; the rest of the government curve barely moves.
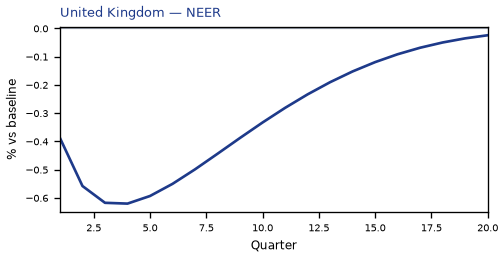
Exchange rates. The NEER prints a trade-weighted depreciation (-0.62% in Q4); the real exchange rate shows a real depreciation (a weaker, more competitive home currency), peaking at +0.51% in Q4; the home currency is stronger versus the dollar (-0.16% in Q19).
Equities and risk. Equity prices fall 0.19% by Q4; Tobin's Q (the value of installed capital) falls 0.14% by Q4; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices and bank credit are close to unchanged.
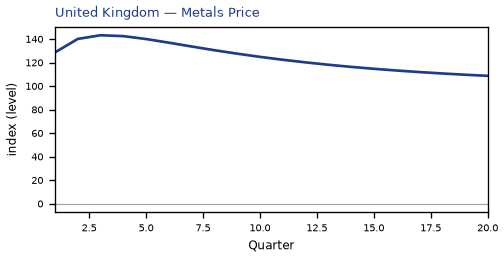
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output falls 0.16% by Q4; services output, the capital stock stay close to baseline.
The GDP response has mostly faded by Q20 (Q20 is still -0.02%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
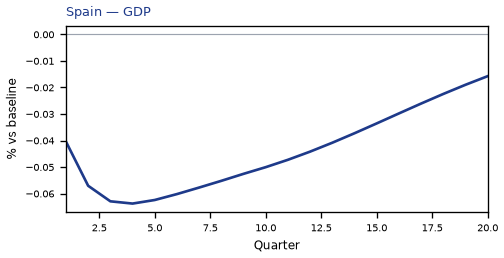
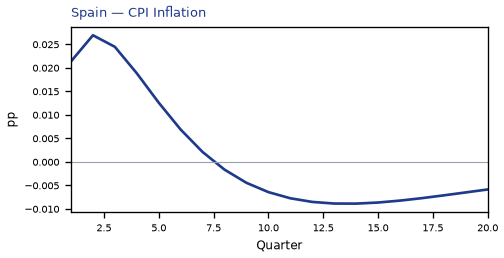
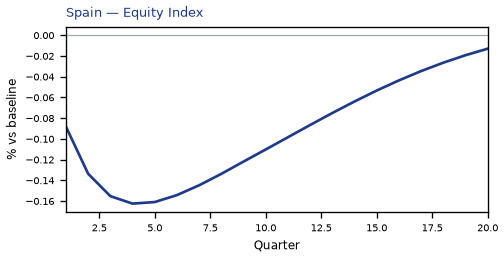
The main impact of a 20% metals-supply cut on Spain is only a small drop in GDP of 0.06% by Q4. This is a model impulse response versus baseline, not a forecast. Equities soften 0.16% by Q4. The three-year CPI impulse is +0.08 percentage points.
Demand and trade. The trade balance (net exports — this model does not split imports from exports) softens to -0.34% in Q3; private investment falls 0.24% by Q4; household consumption, government spending, government debt stay close to baseline.
Labour. Employment, unemployment, real wages stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.37% by Q5; 10-year bond prices rally 0.11% by Q13; 5-year bond prices rally 0.10% by Q15; 30-year bond prices rally 0.09% by Q13; related moves also show up in 2-year bond prices, the local policy rate, 3-month government yields; the rest of the government curve barely moves.
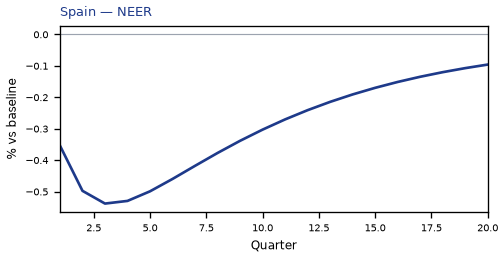
Exchange rates. The NEER prints a trade-weighted depreciation (-0.54% in Q3); the real exchange rate shows a real depreciation (a weaker, more competitive home currency), peaking at +0.44% in Q3; the home currency is stronger versus the dollar (-0.10% in Q18).
Equities and risk. Tobin's Q (the value of installed capital) falls 0.17% by Q4; equity prices fall 0.16% by Q4; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices and bank credit are close to unchanged.
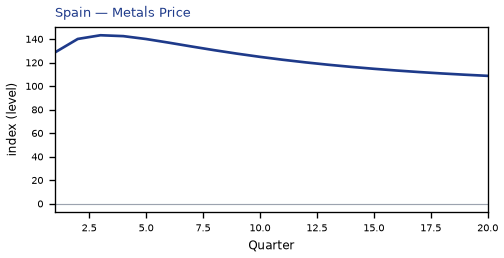
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output falls 0.14% by Q3; services output, the capital stock stay close to baseline.
The GDP response has mostly faded by Q20 (Q20 is still -0.02%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
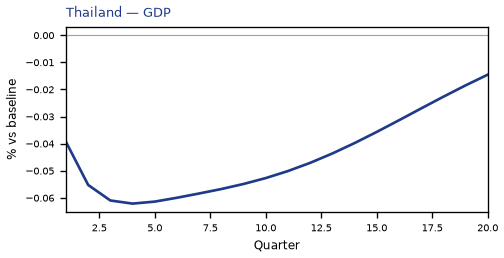
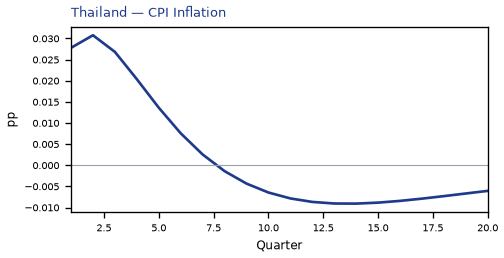
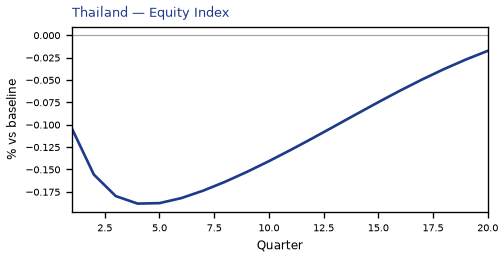
The main impact of a 20% metals-supply cut on Thailand is only a small drop in GDP of 0.06% by Q4. This is a model impulse response versus baseline, not a forecast. Equities soften 0.19% by Q4. The three-year CPI impulse is +0.10 percentage points.
Demand and trade. The trade balance (net exports — this model does not split imports from exports) softens to -0.33% in Q3; private investment falls 0.24% by Q4; household consumption, government spending, government debt stay close to baseline.
Labour. Employment, unemployment, real wages stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.22% by Q4; 10-year bond prices rally 0.13% by Q12; 5-year bond prices rally 0.12% by Q13; 30-year bond prices rally 0.10% by Q11; related moves also show up in the local policy rate, 3-month government yields; the rest of the government curve barely moves.
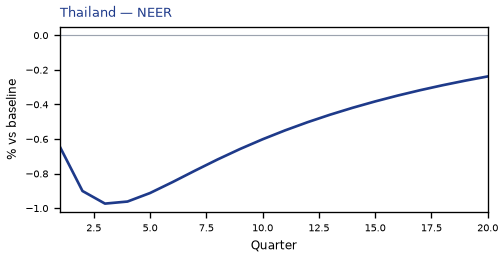
Exchange rates. The NEER prints a trade-weighted depreciation (-0.97% in Q3); the real exchange rate shows a real depreciation (a weaker, more competitive home currency), peaking at +0.25% in Q4; the home currency is stronger versus the dollar (-0.17% in Q3).
Equities and risk. Equity prices fall 0.19% by Q4; Tobin's Q (the value of installed capital) falls 0.17% by Q4; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices fall 0.08% by Q14; bank credit is close to unchanged.
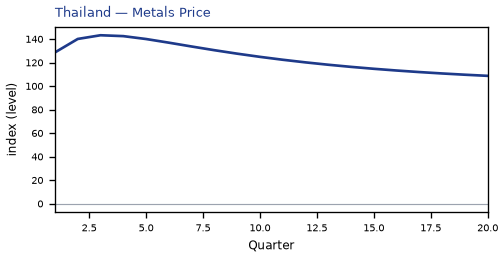
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output falls 0.10% by Q4; services output, the capital stock stay close to baseline.
The GDP response has mostly faded by Q20 (Q20 is still -0.01%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
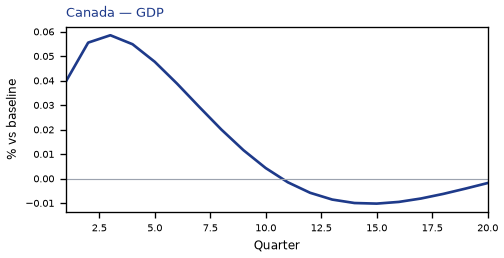
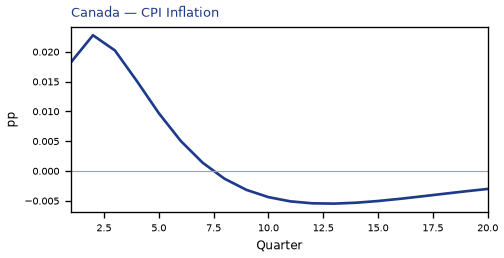
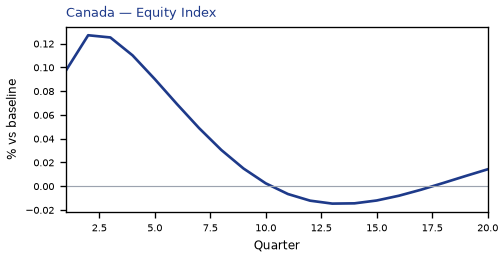
The main impact of a 20% metals-supply cut on Canada is only a small rise in GDP of 0.06% by Q3. This is a model impulse response versus baseline, not a forecast. Equities firm 0.13% by Q2. The three-year CPI impulse is +0.07 percentage points.
Demand and trade. The trade balance (net exports — this model does not split imports from exports) improves to +0.42% in Q3; government spending rises 0.10% by Q3; private investment rises 0.09% by Q2; household consumption, government debt stay close to baseline.
Labour. Employment, unemployment, real wages stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.60% by Q5; 2-year bond prices cheapen 0.16% by Q2; 5-year bond prices cheapen 0.14% by Q1; the local policy rate rises 0.10 percentage points by Q5; related moves also show up in 3-month government yields, 2-year government yields, 10-year bond prices; the rest of the government curve barely moves.
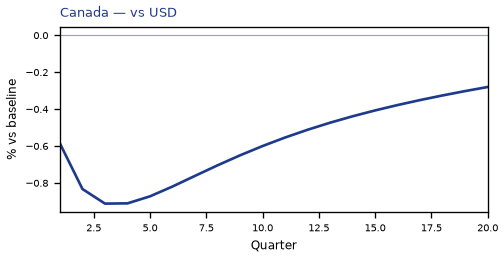
Exchange rates. The home currency is stronger versus the dollar (-0.91% in Q3); the real exchange rate shows a real appreciation (a stronger home currency), peaking at -0.50% in Q4; the NEER prints a trade-weighted appreciation (+0.49% in Q4).
Equities and risk. Equity prices rise 0.13% by Q2; the VIX (global equity-implied volatility), Tobin's Q (the value of installed capital) stay close to baseline.
Housing and credit. House prices and bank credit are close to unchanged.
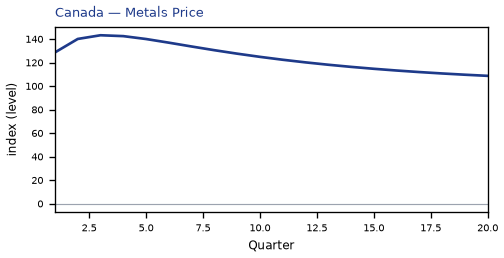
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output rises 0.16% by Q4; services output, the capital stock stay close to baseline.
The GDP response has mostly faded by Q9 (Q20 is still -0.00%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
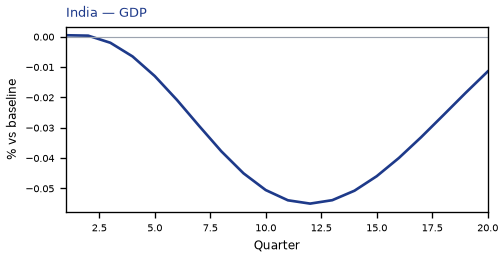
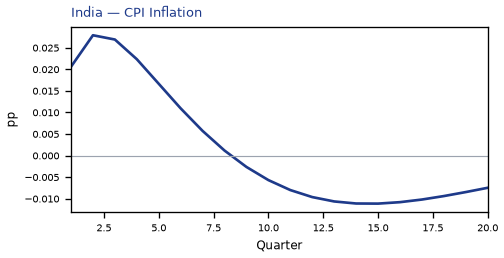
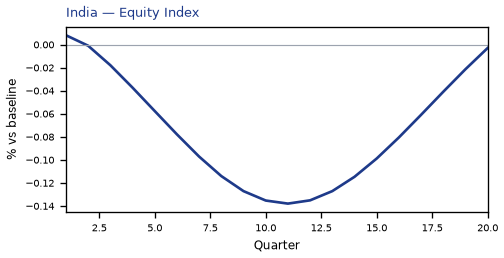
The main impact of a 20% metals-supply cut on India is only a small drop in GDP of 0.06% by Q12. This is a model impulse response versus baseline, not a forecast. Equities soften 0.14% by Q11. The three-year CPI impulse is +0.11 percentage points.
Demand and trade. Private investment falls 0.17% by Q7; the trade balance (net exports — this model does not split imports from exports) improves to +0.08% in Q4; household consumption, government spending, government debt stay close to baseline.
Labour. Employment, unemployment, real wages stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.50% by Q4; 5-year bond prices rally 0.14% by Q12; 2-year bond prices cheapen 0.14% by Q2; 10-year bond prices rally 0.13% by Q11; related moves also show up in the local policy rate, 3-month government yields, 30-year bond prices; the rest of the government curve barely moves.
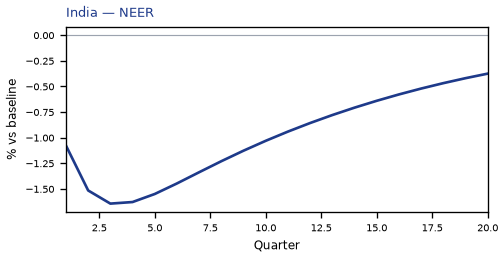
Exchange rates. The NEER prints a trade-weighted depreciation (-1.64% in Q3); the home currency is stronger versus the dollar (-0.22% in Q3); the real exchange rate shows a real depreciation (a weaker, more competitive home currency), peaking at +0.21% in Q5.
Equities and risk. Equity prices fall 0.14% by Q11; Tobin's Q (the value of installed capital) falls 0.12% by Q7; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices and bank credit are close to unchanged.
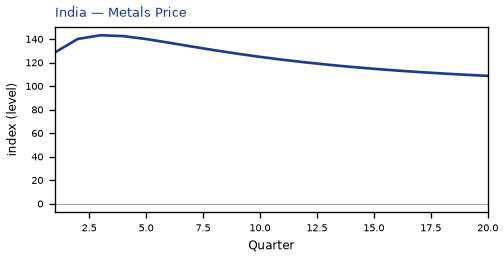
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output, services output, the capital stock stay close to baseline.
The GDP response has mostly faded by Q20 (Q20 is still -0.01%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
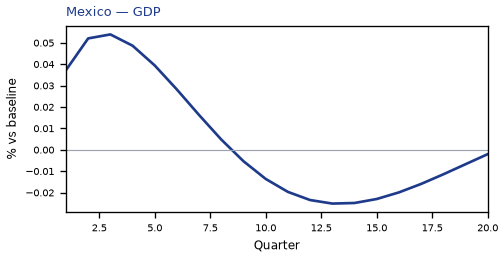
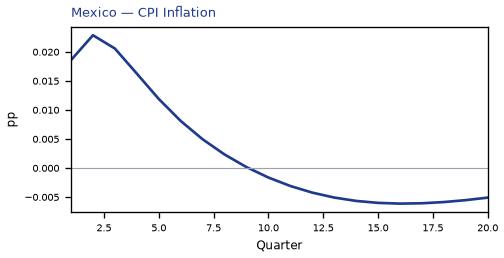
The main impact of a 20% metals-supply cut on Mexico is only a small rise in GDP of 0.05% by Q3. This is a model impulse response versus baseline, not a forecast. The three-year CPI impulse is +0.10 percentage points.
Demand and trade. The trade balance (net exports — this model does not split imports from exports) improves to +0.42% in Q3; government spending rises 0.10% by Q3; private investment falls 0.08% by Q9; household consumption, government debt stay close to baseline.
Labour. Real wages rise 0.08% by Q13; employment, unemployment stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.44% by Q4; 2-year bond prices cheapen 0.16% by Q2; 5-year bond prices cheapen 0.11% by Q1; the local policy rate rises 0.11 percentage points by Q4; related moves also show up in 3-month government yields, 10-year bond prices, 2-year government yields; the rest of the government curve barely moves.
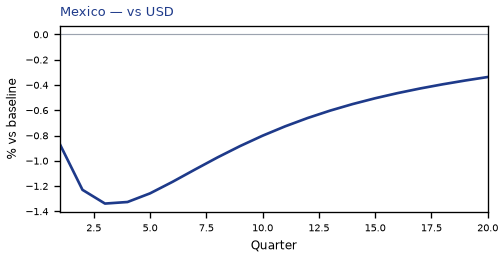
Exchange rates. The home currency is stronger versus the dollar (-1.34% in Q3); the NEER prints a trade-weighted appreciation (+1.07% in Q3); the real exchange rate shows a real appreciation (a stronger home currency), peaking at -0.92% in Q3.
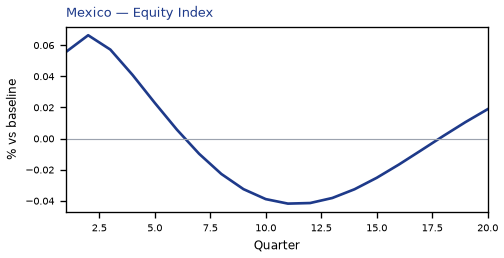
Equities and risk. Equity prices, the VIX (global equity-implied volatility), Tobin's Q (the value of installed capital) stay close to baseline.
Housing and credit. House prices and bank credit are close to unchanged.
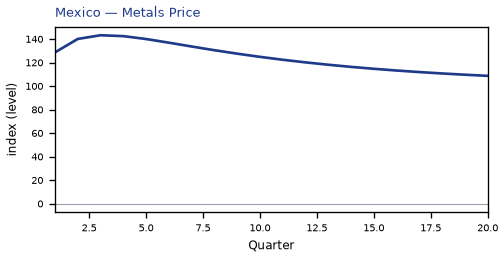
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output rises 0.29% by Q3; services output, the capital stock stay close to baseline.
The GDP response has mostly faded by Q8 (Q20 is still -0.00%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
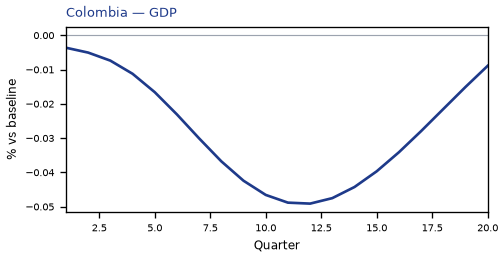
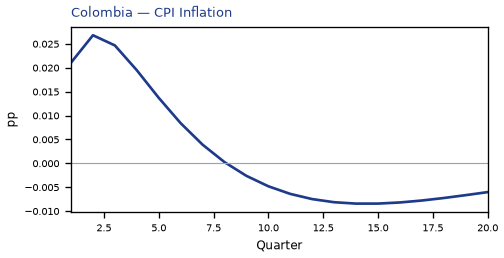
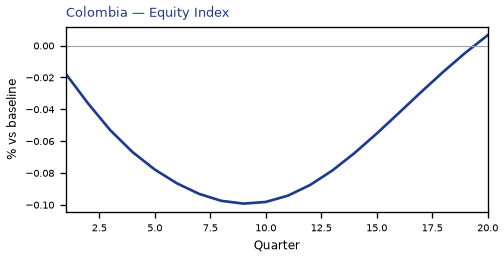
The main impact of a 20% metals-supply cut on Colombia is only a small drop in GDP of 0.05% by Q12. This is a model impulse response versus baseline, not a forecast. Equities soften 0.10% by Q9. The three-year CPI impulse is +0.10 percentage points.
Demand and trade. Private investment falls 0.18% by Q6; household consumption, the trade balance, government spending, government debt stay close to baseline.
Labour. Employment, unemployment, real wages stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.34% by Q4; 2-year bond prices cheapen 0.13% by Q1; 10-year bond prices rally 0.13% by Q11; 5-year bond prices rally 0.13% by Q12; related moves also show up in the local policy rate, 3-month government yields, 30-year bond prices; the rest of the government curve barely moves.
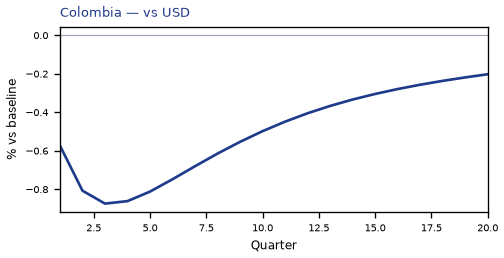
Exchange rates. The home currency is stronger versus the dollar (-0.87% in Q3); the real exchange rate shows a real appreciation (a stronger home currency), peaking at -0.46% in Q3; the NEER prints a trade-weighted appreciation (+0.22% in Q3).
Equities and risk. Tobin's Q (the value of installed capital) falls 0.13% by Q6; equity prices fall 0.10% by Q9; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices and bank credit are close to unchanged.
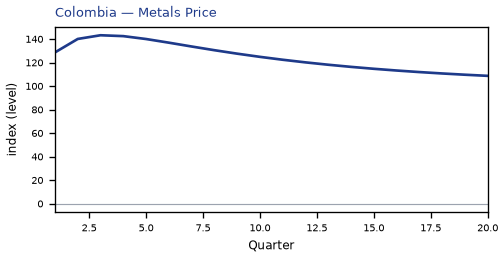
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output rises 0.13% by Q3; services output, the capital stock stay close to baseline.
The GDP response has mostly faded by Q20 (Q20 is still -0.01%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
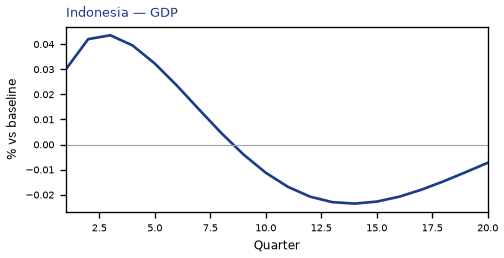
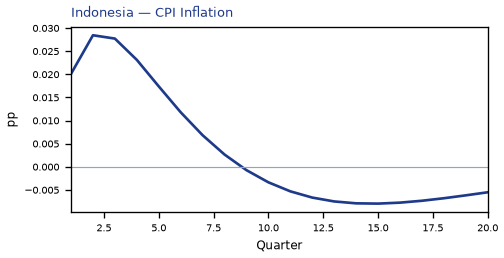
The main impact of a 20% metals-supply cut on Indonesia is only a small rise in GDP of 0.04% by Q3. This is a model impulse response versus baseline, not a forecast. The three-year CPI impulse is +0.12 percentage points.
Demand and trade. The trade balance (net exports — this model does not split imports from exports) improves to +0.34% in Q3; private investment falls 0.08% by Q9; household consumption, government spending, government debt stay close to baseline.
Labour. Real wages rise 0.09% by Q12; employment, unemployment stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.36% by Q5; 2-year bond prices cheapen 0.13% by Q2; 5-year bond prices cheapen 0.11% by Q1; 10-year bond prices rally 0.09% by Q13; related moves also show up in the local policy rate, 3-month government yields, 2-year government yields; the rest of the government curve barely moves.
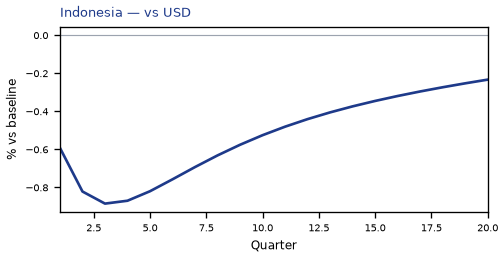
Exchange rates. The home currency is stronger versus the dollar (-0.88% in Q3); the NEER prints a trade-weighted depreciation (-0.62% in Q3); the real exchange rate shows a real appreciation (a stronger home currency), peaking at -0.47% in Q3.
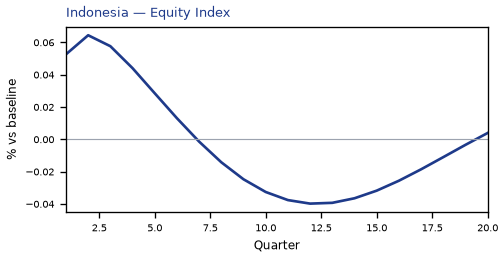
Equities and risk. Equity prices, the VIX (global equity-implied volatility), Tobin's Q (the value of installed capital) stay close to baseline.
Housing and credit. House prices and bank credit are close to unchanged.
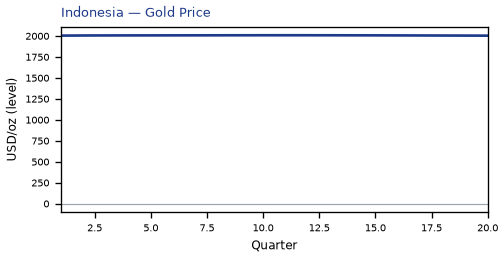
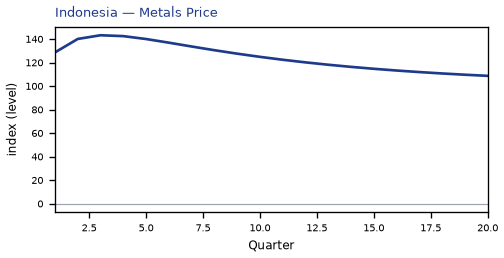
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output rises 0.15% by Q3; services output, the capital stock stay close to baseline.
The GDP response has mostly faded by Q8 (Q20 is still -0.01%).
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
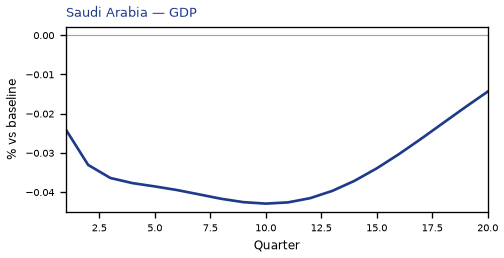
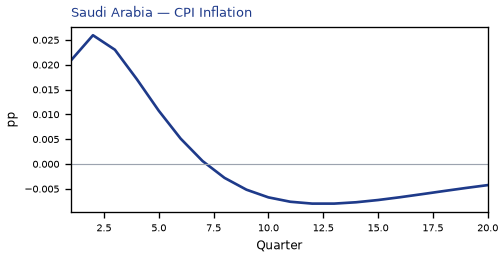
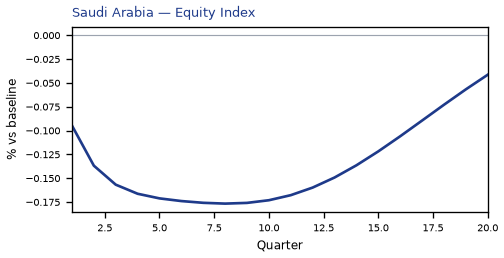
The main impact of a 20% metals-supply cut on Saudi Arabia is only a small drop in GDP of 0.04% by Q10. This is a model impulse response versus baseline, not a forecast. Equities soften 0.18% by Q8. The three-year CPI impulse is +0.07 percentage points.
Demand and trade. Private investment falls 0.22% by Q5; the trade balance (net exports — this model does not split imports from exports) softens to -0.21% in Q3; household consumption, government spending, government debt stay close to baseline.
Labour. Employment, unemployment, real wages stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.42% by Q4; 5-year bond prices rally 0.14% by Q12; 10-year bond prices rally 0.13% by Q11; 2-year bond prices cheapen 0.12% by Q2; related moves also show up in 30-year bond prices, the local policy rate, 3-month government yields; the rest of the government curve barely moves.
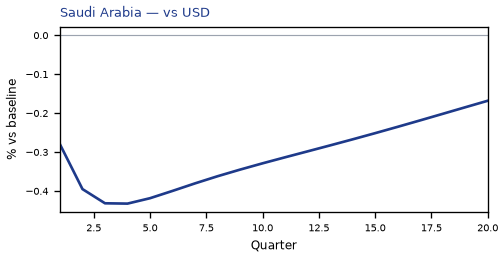
Exchange rates. The home currency is stronger versus the dollar (-0.43% in Q4); the NEER prints a trade-weighted depreciation (-0.13% in Q3); the real exchange rate stays close to baseline.
Equities and risk. Equity prices fall 0.18% by Q8; Tobin's Q (the value of installed capital) falls 0.16% by Q5; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices and bank credit are close to unchanged.
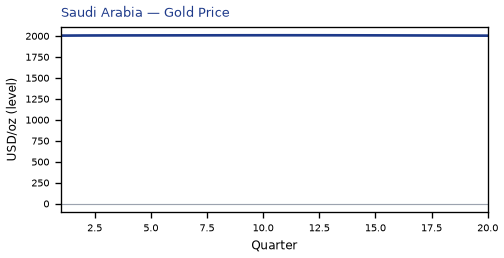
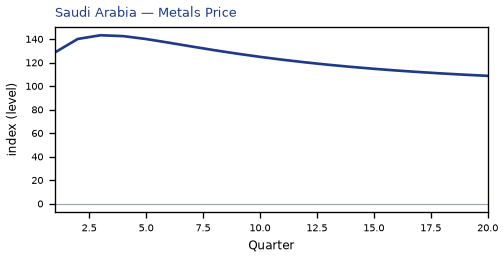
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output, services output, the capital stock stay close to baseline.
By Q20, GDP is still -0.01% from baseline.
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
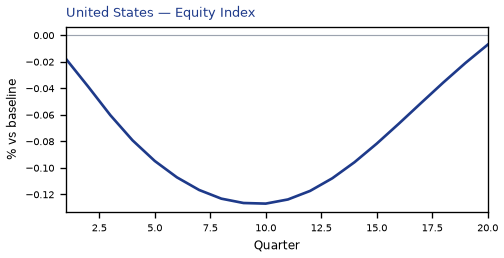
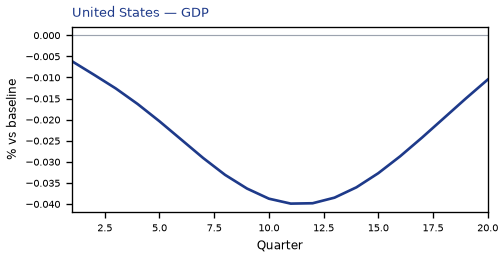
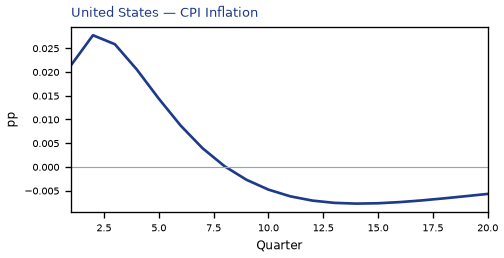
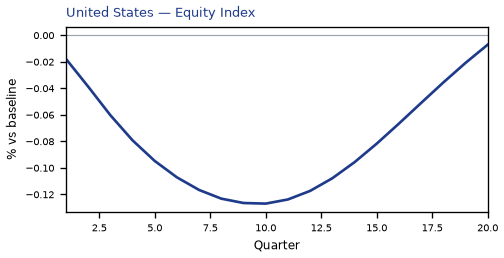
The main impact of a 20% metals-supply cut on the United States is only a small drop in GDP of 0.04% by Q11. This is a model impulse response versus baseline, not a forecast. Equities soften 0.13% by Q10. The three-year CPI impulse is +0.10 percentage points.
Demand and trade. Private investment falls 0.17% by Q6; household consumption, the trade balance, government spending, government debt stay close to baseline.
Labour. Employment, unemployment, real wages stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
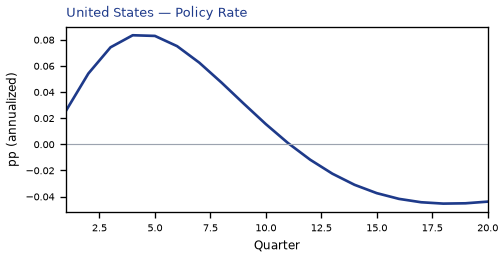
Policy rates and the government curve. Benchmark bond prices cheapen 0.55% by Q4; 5-year bond prices rally 0.14% by Q12; 10-year bond prices rally 0.13% by Q11; 2-year bond prices cheapen 0.12% by Q2; related moves also show up in 30-year bond prices, the local policy rate, 3-month government yields; the rest of the government curve barely moves.
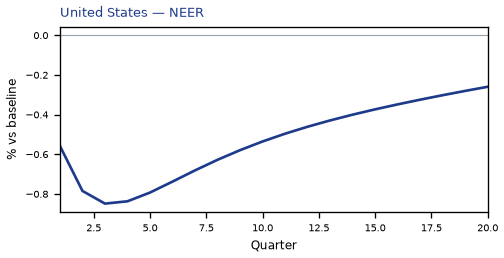
Exchange rates. The NEER prints a trade-weighted depreciation (-0.85% in Q3); the real exchange rate shows a real depreciation (a weaker, more competitive home currency), peaking at +0.42% in Q3.
Equities and risk. Equity prices fall 0.13% by Q10; Tobin's Q (the value of installed capital) falls 0.12% by Q6; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices and bank credit are close to unchanged.
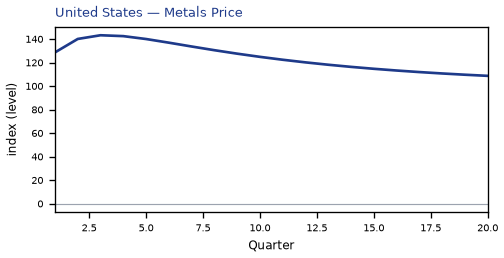
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output falls 0.13% by Q3; services output, the capital stock stay close to baseline.
By Q20, GDP is still -0.01% from baseline.
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
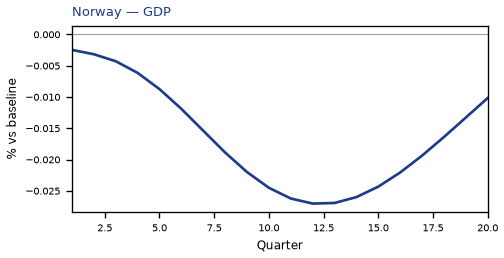
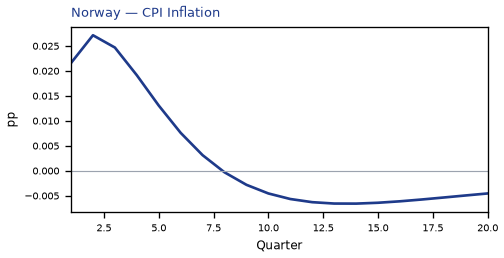
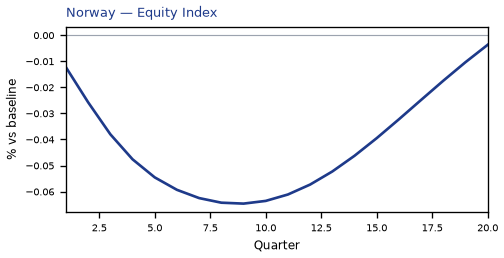
The main impact of a 20% metals-supply cut on Norway is only a small drop in GDP of 0.03% by Q12. This is a model impulse response versus baseline, not a forecast. The three-year CPI impulse is +0.10 percentage points.
Demand and trade. Private investment falls 0.12% by Q6; household consumption, the trade balance, government spending, government debt stay close to baseline.
Labour. Employment, unemployment, real wages stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.42% by Q5; 10-year bond prices rally 0.11% by Q13; 2-year bond prices cheapen 0.10% by Q2; 5-year bond prices rally 0.10% by Q14; related moves also show up in the local policy rate, 3-month government yields, 2-year government yields; the rest of the government curve barely moves.
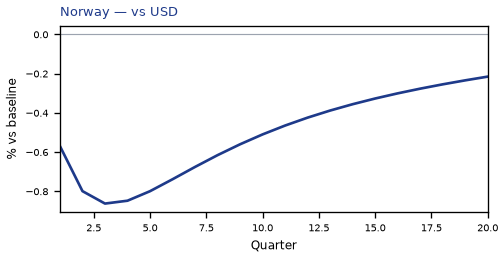
Exchange rates. The home currency is stronger versus the dollar (-0.86% in Q3); the real exchange rate shows a real appreciation (a stronger home currency), peaking at -0.44% in Q3; the NEER prints a trade-weighted depreciation (-0.22% in Q3).
Equities and risk. Tobin's Q (the value of installed capital) falls 0.09% by Q6; equity prices, the VIX (global equity-implied volatility) stay close to baseline.
Housing and credit. House prices and bank credit are close to unchanged.
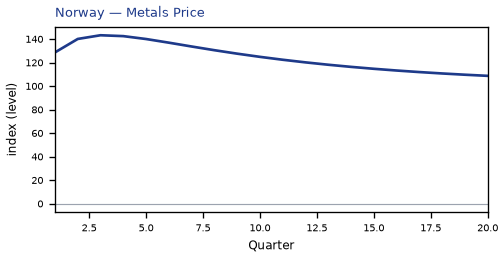
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output rises 0.13% by Q3; services output, the capital stock stay close to baseline.
By Q20, GDP is still -0.01% from baseline.
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
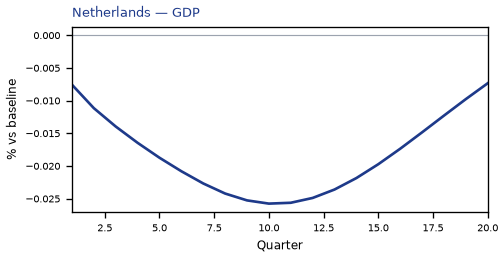
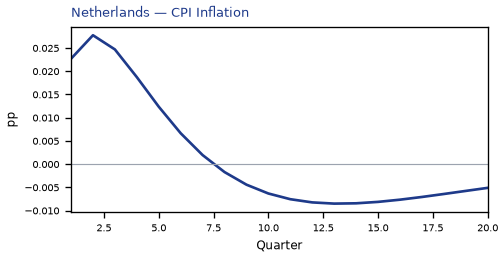
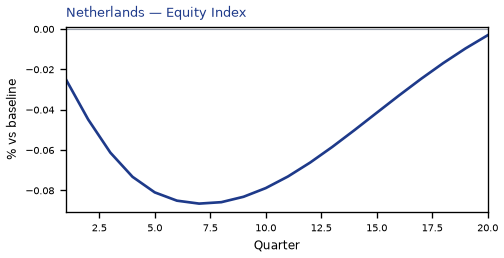
The main impact of a 20% metals-supply cut on the Netherlands is only a small drop in GDP of 0.03% by Q10. This is a model impulse response versus baseline, not a forecast. Equities soften 0.09% by Q7. The three-year CPI impulse is +0.09 percentage points.
Demand and trade. Private investment falls 0.13% by Q6; household consumption, the trade balance, government spending, government debt stay close to baseline.
Labour. Employment, unemployment, real wages stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.37% by Q5; 10-year bond prices rally 0.11% by Q13; 5-year bond prices rally 0.10% by Q15; 30-year bond prices rally 0.09% by Q13; related moves also show up in 2-year bond prices, the local policy rate, 3-month government yields; the rest of the government curve barely moves.
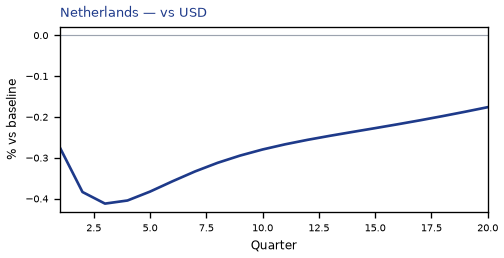
Exchange rates. The home currency is stronger versus the dollar (-0.41% in Q3); the NEER prints a trade-weighted depreciation (-0.12% in Q3); the real exchange rate stays close to baseline.
Equities and risk. Tobin's Q (the value of installed capital) falls 0.09% by Q6; equity prices fall 0.09% by Q7; the VIX (global equity-implied volatility) stays close to baseline.
Housing and credit. House prices and bank credit are close to unchanged.
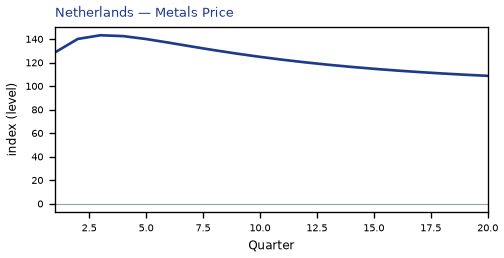
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output, services output, the capital stock stay close to baseline.
By Q20, GDP is still -0.01% from baseline.
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
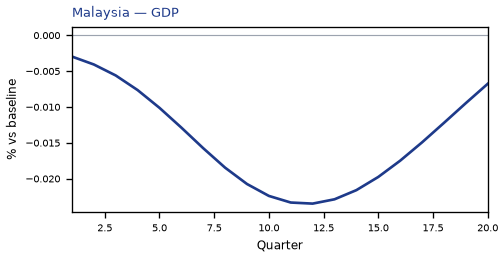
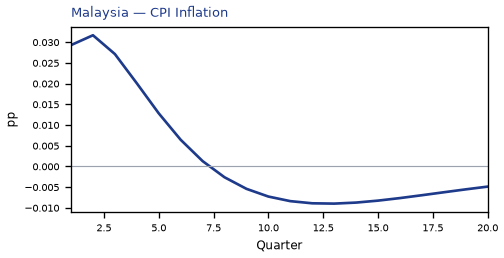
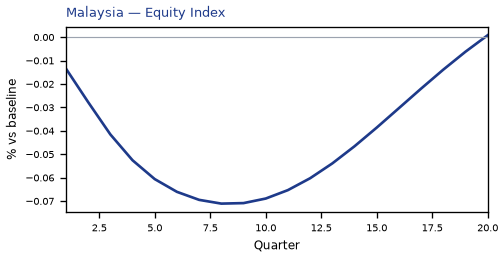
The main impact of a 20% metals-supply cut on Malaysia is only a small drop in GDP of 0.02% by Q12. This is a model impulse response versus baseline, not a forecast. The three-year CPI impulse is +0.10 percentage points.
Demand and trade. Private investment falls 0.11% by Q6; household consumption, the trade balance, government spending, government debt stay close to baseline.
Labour. Employment, unemployment, real wages stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.23% by Q5; 2-year bond prices cheapen 0.08% by Q2; 10-year bond prices rally 0.08% by Q13; the local policy rate rises 0.06 percentage points by Q5; related moves also show up in 3-month government yields; the rest of the government curve barely moves.
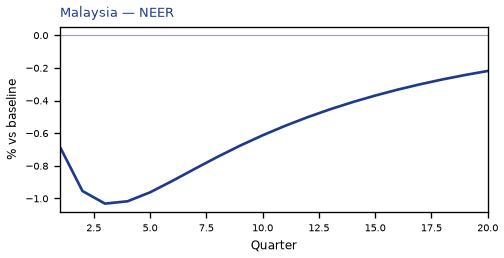
Exchange rates. The NEER prints a trade-weighted depreciation (-1.03% in Q3); the home currency is stronger versus the dollar (-0.61% in Q3); the real exchange rate shows a real appreciation (a stronger home currency), peaking at -0.19% in Q3.
Equities and risk. Equity prices, the VIX (global equity-implied volatility), Tobin's Q (the value of installed capital) stay close to baseline.
Housing and credit. House prices and bank credit are close to unchanged.
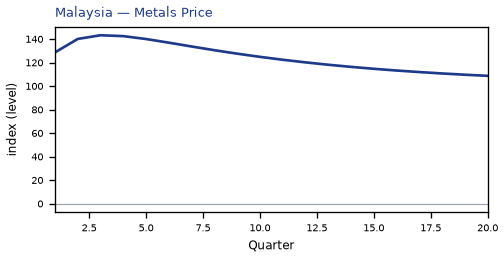
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output, services output, the capital stock stay close to baseline.
By Q20, GDP is still -0.01% from baseline.
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
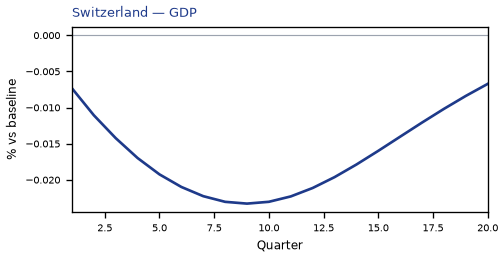
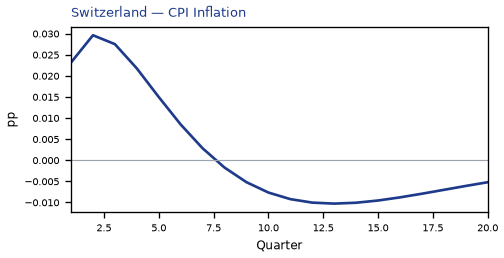
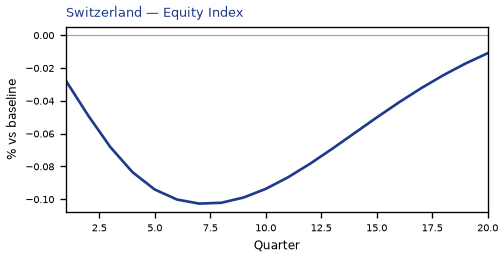
The main impact of a 20% metals-supply cut on Switzerland is only a small drop in GDP of 0.02% by Q9. This is a model impulse response versus baseline, not a forecast. Equities soften 0.10% by Q7. The three-year CPI impulse is +0.09 percentage points.
Demand and trade. Private investment falls 0.11% by Q6; household consumption, the trade balance, government spending, government debt stay close to baseline.
Labour. Employment, unemployment, real wages stay close to baseline.
Prices. CPI inflation, domestic inflation, firms' marginal cost stay close to baseline.
Policy rates and the government curve. Benchmark bond prices cheapen 0.29% by Q5; the rest of the government curve barely moves.
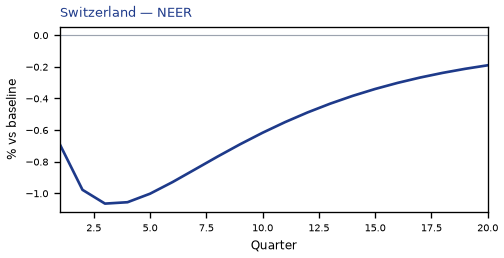
Exchange rates. The NEER prints a trade-weighted depreciation (-1.06% in Q3); the real exchange rate shows a real depreciation (a weaker, more competitive home currency), peaking at +0.46% in Q4; the home currency is stronger versus the dollar (-0.12% in Q18).
Equities and risk. Equity prices fall 0.10% by Q7; the VIX (global equity-implied volatility), Tobin's Q (the value of installed capital) stay close to baseline.
Housing and credit. House prices and bank credit are close to unchanged.
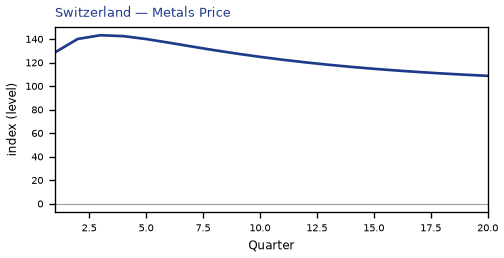
Commodities. The metals price index moves to 143.2 in Q3; other published commodity prices stay within 3% of their baselines.
Sectors and capital. Manufacturing output falls 0.14% by Q4; services output, the capital stock stay close to baseline.
By Q20, GDP is still -0.01% from baseline.
These figures are model IRFs versus baseline, not forecasts and not financial advice.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice
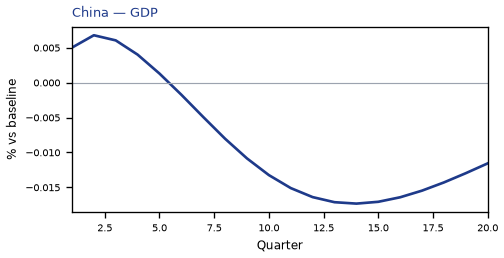
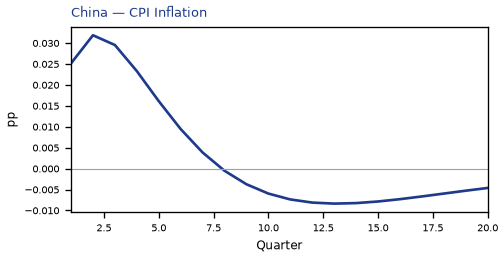
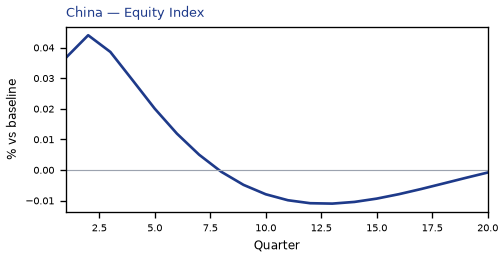
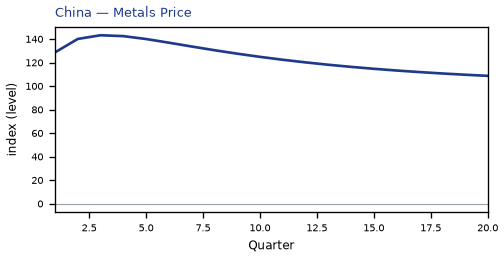
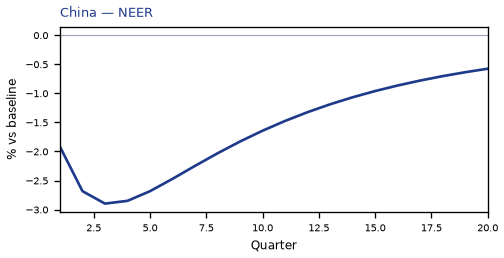
The main impact of a 20% metals-supply cut on China is a negligible drop in GDP of 0.02% by Q14. This is a model impulse response versus baseline, not a forecast. The three-year CPI impulse is +0.11 percentage points. This has almost no impact on China.
global_macro_v64 · contract v6.4 · Q1–Q20 JSON · not financial advice