RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Global Macro Watch
Week of July 27–31, 2026
  • Brent crude closed at 90.12 after a 1.99% weekly advance, reasserting the energy channel across regions.
  • China’s NBS Manufacturing PMI contracted for the first time in five months, confirming demand weakness.
  • Central banks from the Federal Reserve to the ECB, BoJ and SARB held policy rates steady with explicit data dependence.
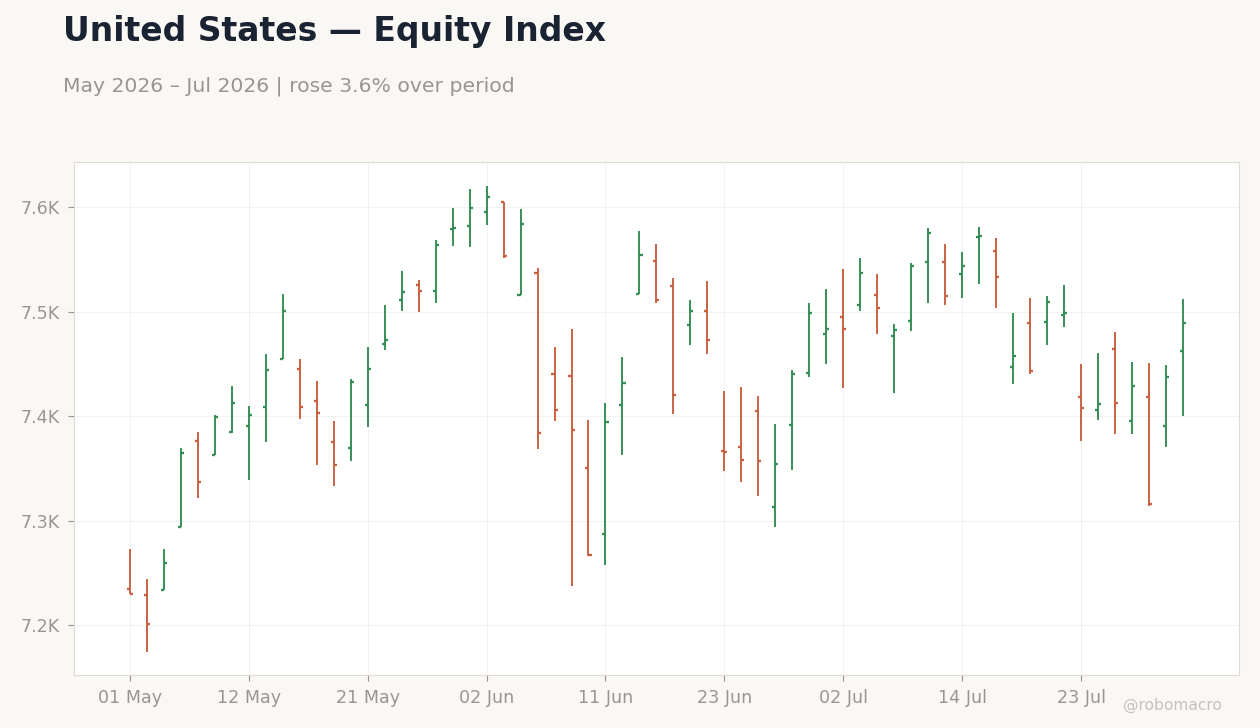
  • S&P 500 closed at 7489.72 for a 1.03% net gain while the 10-year Treasury yield eased three basis points.
Oil Advance Anchors Data-Dependent Stance
Join the AIeconomist.app Waitlist

Published every Sunday afternoon 100% AI-generated — not financial advice

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com

Global Cycle in Mid-Expansion as Energy Impulse Strengthens

We note that the week of July 27–31, 2026 finds the global expansion still anchored in its mid-phase, yet the dominant narrative has shifted decisively toward the renewed energy-price impulse. Brent crude closed at 90.12 after a 1.99% weekly advance while WTI crude posted a 2.49% gain, reversing earlier relief and re-anchoring financial conditions tighter through the rates and currency channels. The data therefore suggest that above-target inflation in the largest economy, now reinforced by energy prices, will continue to shape rate paths into the second half of 2026. Markets enter August with clearer evidence that the oil surge will interact with selective activity resilience to keep central banks data-dependent. Every major region absorbed this impulse without immediate contraction signals, yet the configuration leaves policy expectations anchored for delayed easing across developed markets and continued vigilance in emerging markets.

DM Outcomes Cluster Around Shared Data Dependence

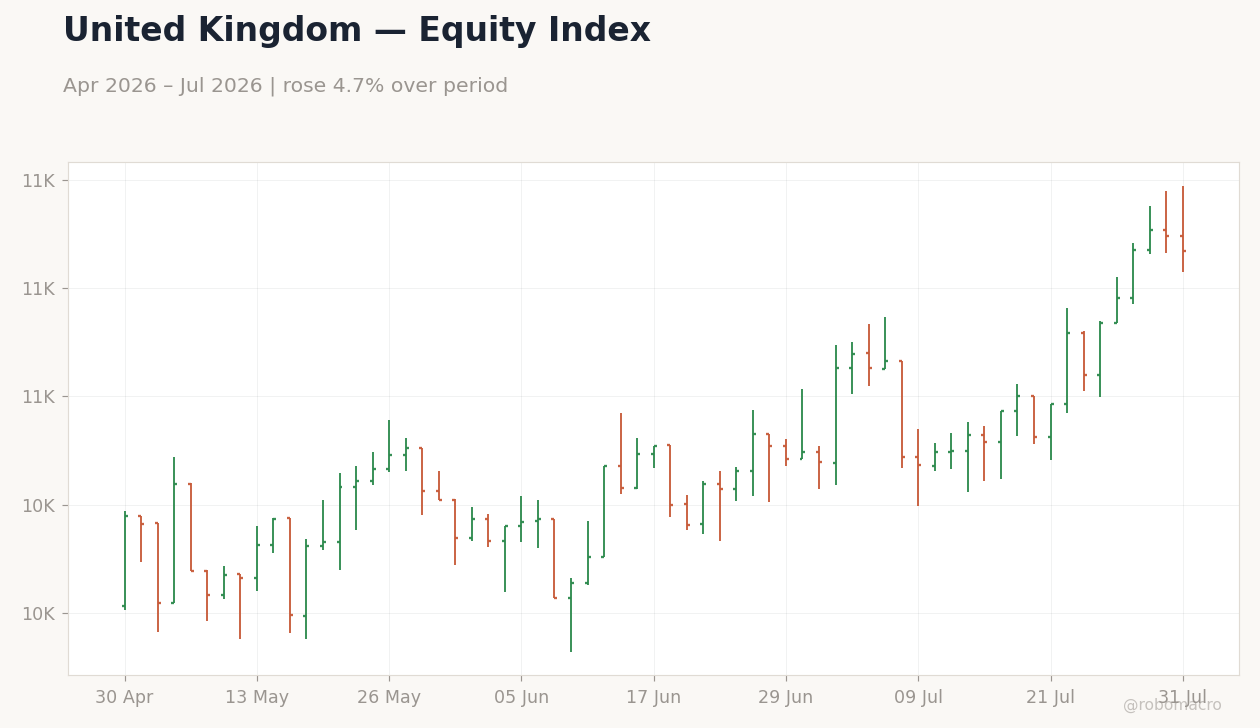
Across developed markets the read-through centers on selective resilience and common data dependence after the oil move. The Federal Reserve held the policy rate steady on July 30 with multiple dissents, underscoring data dependence amid above-target inflation while durable goods orders extended their prior decline. In the euro area, the July PMI rose above the 50 threshold in both Germany and France while the ECB kept its policy rate on hold with no shift in forward guidance. The Bank of Japan held its policy rate steady and released an unchanged quarterly outlook, even as suspected coordinated intervention drove USD/JPY lower. UK data showed resilient domestic lending and improved CBI Distributive Trades balance in July, prompting the Bank of England to maintain its policy rate. The common thread is that DM central banks are tolerating the energy impulse to support growth while monitoring incoming prints through the second half of 2026.

EM Data Split Along Commodity and Domestic Lines

Emerging-market outcomes split along commodity and domestic inflation lines during the week of July 27–31. Brazil’s labor market showed continued resilience while fiscal metrics pointed to widening imbalances, leaving the Banco Central do Brasil on hold. South Africa’s June CPI registered inside the target band, allowing the SARB to hold its policy rate steady with USD/ZAR closing at 16.47. In contrast, China’s NBS Manufacturing PMI contracted for the first time in five months, confirming demand weakness even as the PBoC conducted large-scale overnight reverse-repo operations. Australia’s June-quarter CPI printed below consensus on both a year-over-year and month-over-month basis, yet RBA Governor Bullock reiterated that underlying inflation remains too high. Mexico’s manufacturing exports held firm while BanRep held its policy rate at 12% on July 31, citing peso strength. The configuration leaves EM central banks navigating imported inflation pressures from Brent at 90.12 alongside divergent domestic prints.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com

Cross-Asset Markets Price Energy Impulse Directly

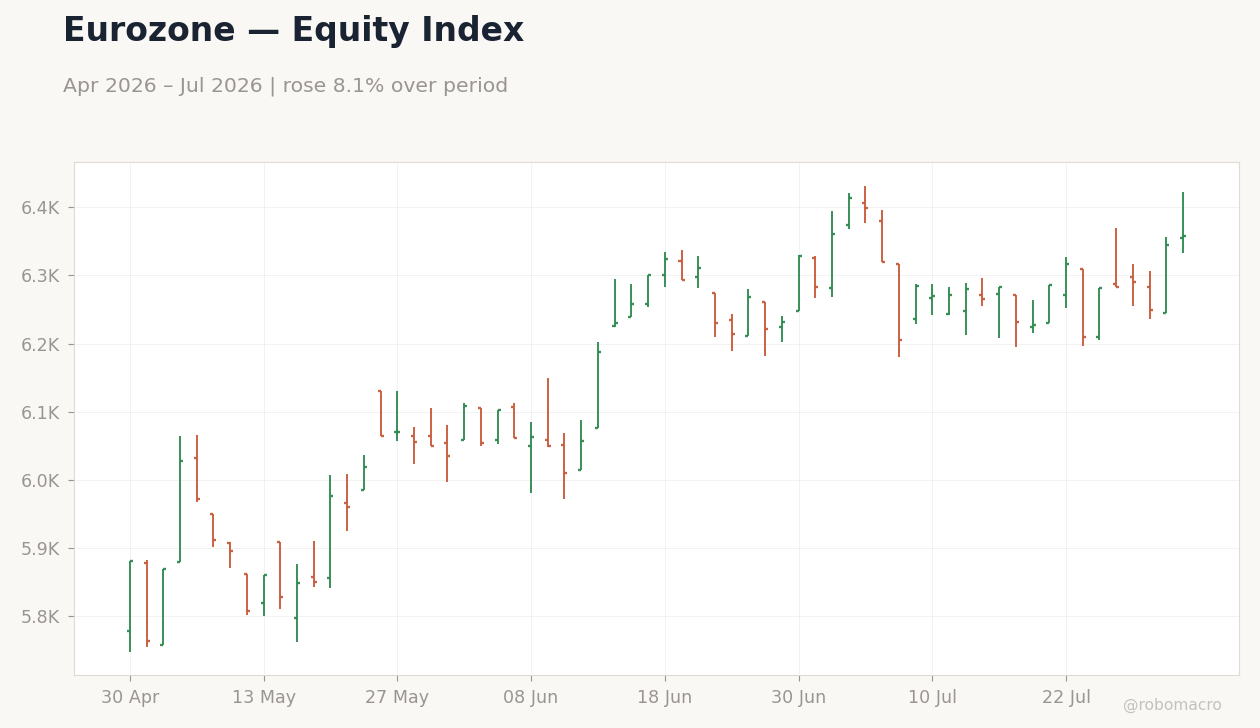
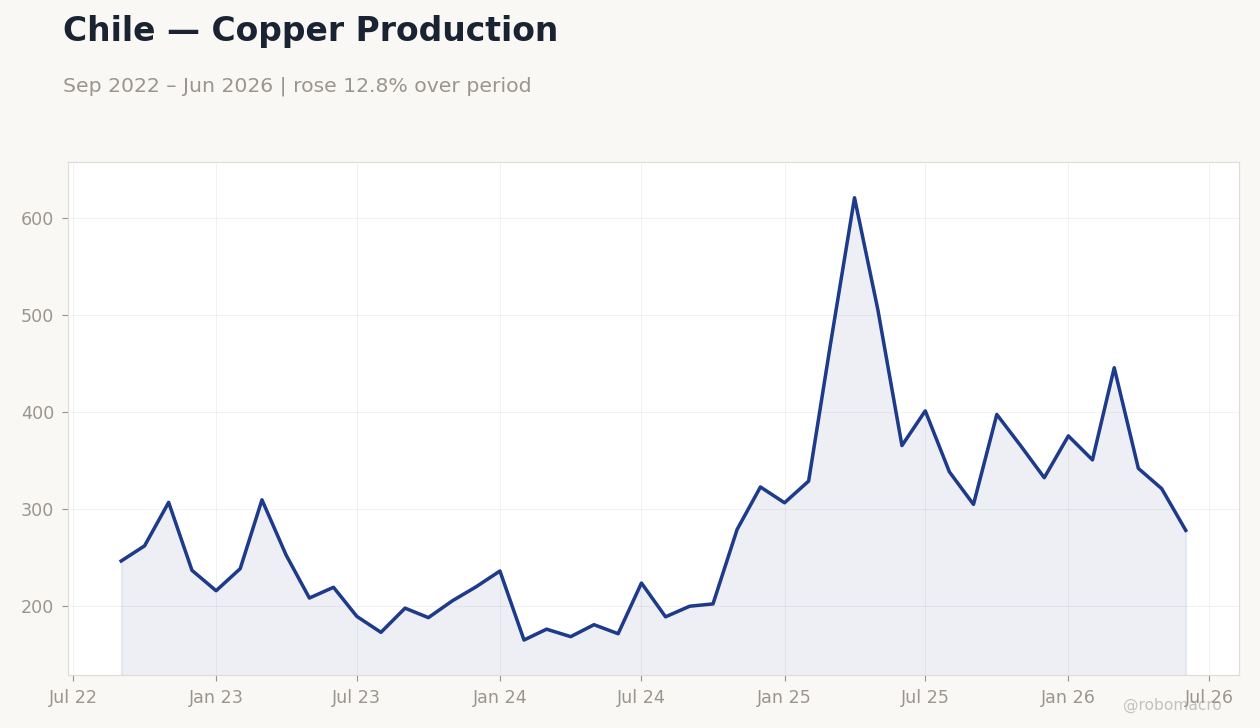
Cross-asset markets priced the oil impulse directly into curves, currencies and equities during the week. The S&P 500 closed at 7489.72 for a 1.03% net gain while the 10-year Treasury yield eased three basis points to 4.68%. Euro Stoxx 50 advanced alongside Brent crude, illustrating energy-price transmission into euro-area financial conditions. In Japan, USD/JPY fell after suspected coordinated intervention while the Nikkei 225 declined 0.4%. Regional 10-year yields fell sharply in Poland and South Korea while BIST 100 closed 2.3% lower amid the commodity impulse. Gold rose 0.8% to 4107.00 and copper advanced 2.0% to 6.47, supporting Colombia’s fiscal position while Chile and Peru tracked mixed equity and FX moves. The data therefore suggest that the energy channel is tightening financial conditions selectively rather than triggering broad risk-off flows.

Policy Outlook Centers on Prolonged Data Dependence

Global central bank communications during the week of July 27–31 reinforced a prolonged data-dependent stance. The Federal Reserve, ECB, Bank of Japan, Bank of Canada and SARB all held policy rates steady while citing incoming inflation and activity prints. Australia’s RBA officials reiterated that underlying inflation remains too high after the June-quarter CPI eased. In Latin America, BanRep and BCCh kept rates unchanged at 12% and 4.5% respectively, anchoring to peso strength and copper at 6.47. No major high-impact data releases occurred in ASEAN economies, leaving regional policy signals anchored to the prior June inflation prints and external euro-area resilience. The configuration leaves rate paths divergent, with DM officials tolerating the Brent advance at 90.12 and EM officials monitoring imported inflation through August.

Forward Look Centers on August Prints and Oil Path

Next week’s focus will center on August inflation prints, industrial production releases and any further central bank communications. Markets will watch whether Brent crude sustains levels near 90.12 or extends the 1.99% weekly gain recorded in the week of July 27–31. US durable goods orders and euro-area PMI follow-through will test whether the mid-expansion resilience observed in July persists. China’s Politburo meeting and PBoC liquidity operations will remain in focus after the NBS Manufacturing PMI contraction. EM FX reserves and trade balance data due in early August will inform whether the energy impulse continues to tighten conditions or allows selective easing. The data therefore suggest that the dominant narrative of oil-driven vigilance will carry into the first full week of August 2026.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Global Economic Outlook Summary
IMF World Economic Outlook projections, % change year-on-year. Real GDP and average consumer prices. Retrieved August 02, 2026.
Economy Real GDP (% y/y) Consumer Prices (% y/y)
2026E2027E2028E 2026E 2027E2028E
Americas
United States2.32.12.13.22.12.2
Canada1.51.91.72.52.12.0
Mexico1.62.22.13.93.43.0
Brazil1.92.02.44.03.43.0
Argentina3.54.03.830.415.79.6
Colombia2.32.52.65.95.23.4
Chile2.42.62.32.93.33.0
Peru2.82.82.82.51.82.0
Asia / Pacific
Japan0.70.60.62.22.32.0
China4.44.04.01.21.51.8
India6.56.56.54.74.04.0
Australia2.01.71.94.03.22.6
New Zealand2.12.42.43.12.32.1
South Korea1.92.12.22.51.92.0
Indonesia5.05.15.23.02.62.5
Malaysia4.74.34.31.92.02.0
Philippines4.15.86.14.33.23.0
Singapore3.52.72.52.31.92.0
Thailand1.52.12.30.91.01.2
Taiwan5.23.02.41.51.61.6
Vietnam7.16.76.24.94.63.7
Western Europe
Euro area1.11.21.42.62.22.1
Germany0.81.21.22.72.32.0
France0.90.91.21.81.71.9
Italy0.50.50.82.62.42.3
Spain2.11.81.83.02.32.5
United Kingdom0.81.31.63.22.42.0
Sweden2.01.92.11.51.82.6
Norway1.51.31.13.32.62.2
Denmark2.01.61.62.02.22.2
Switzerland1.31.31.80.50.50.6
Netherlands1.21.41.42.72.42.3
Poland3.32.42.63.33.33.9
Czech Republic2.22.22.12.42.22.5
Hungary1.72.02.33.83.53.1
Romania0.72.52.77.83.94.3
EMEA Emerging
Turkey3.43.53.828.621.417.0
South Africa1.01.31.53.93.43.0
Israel3.54.43.72.32.12.0
Saudi Arabia3.14.53.62.32.12.0
UAE3.15.34.62.52.02.0
Egypt4.24.85.513.211.18.1
Nigeria4.14.34.116.015.912.7
Kenya4.54.75.15.95.95.7
Global Aggregates
Global3.13.23.24.43.73.4
Developed markets1.81.71.72.82.22.1
Emerging markets3.94.24.25.54.64.1
Changes to Consensus GDP / CPI Forecasts This Week vs Jul 26
Argentina 2026 CPI: 42.0→30.4 ▼ -11.6pp  ·  Egypt 2026 CPI: 22.0→13.2 ▼ -8.8pp  ·  Nigeria 2026 CPI: 24.0→16.0 ▼ -8.0pp  ·  Romania 2026 CPI: 4.0→7.8 ▲ +3.8pp  ·  Taiwan 2026 GDP: 2.5→5.2 ▲ +2.7pp  ·  Romania 2026 GDP: 3.0→0.7 ▼ -2.3pp  ·  Colombia 2026 CPI: 3.8→5.9 ▲ +2.1pp  ·  Philippines 2026 GDP: 5.8→4.1 ▼ -1.7pp  ·  Australia 2026 CPI: 2.6→4.0 ▲ +1.4pp  ·  Thailand 2026 GDP: 2.9→1.5 ▼ -1.4pp  ·  Vietnam 2026 CPI: 3.5→4.9 ▲ +1.4pp  ·  Philippines 2026 CPI: 3.2→4.3 ▲ +1.1pp
E = IMF projection. Source: IMF World Economic Outlook, retrieved via the IMF DataMapper. Aggregates (Global, Developed markets, Emerging markets, Euro area) are the IMF's own groupings. A blank cell means the IMF does not publish a projection for that economy and year.
RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Global Central Bank Watch
Policy rates as of August 02, 2026. Current rates, last changes and meeting dates are verified against central bank publications and BIS policy-rate data. Quarter columns show realized quarter-end rates for quarters that have completed.
Central Bank Instrument Current
Rate
Last
Change
bp Next
Meeting
Q1
2026
Q2
2026
Q3
2026
Q4
2026
The Americas
Federal ReserveFed funds upper3.75%Dec 2025-25Sep 163.753.75——
Bank of CanadaO/N rate2.25%Oct 2025-25Sep 22.252.25——
BCB (Brazil)SELIC14.25%Jun 2026-25Aug 514.7514.25——
BanxicoO/N rate6.50%May 2026-25Aug 66.756.50——
BCRA (Argentina)Aggregates regime—Jul 2025——————
BanRep (Colombia)Repo12.00%Jul 2026+75—10.2511.25——
BCCh (Chile)MPR4.50%Dec 2025-25—4.504.50——
Europe / Africa
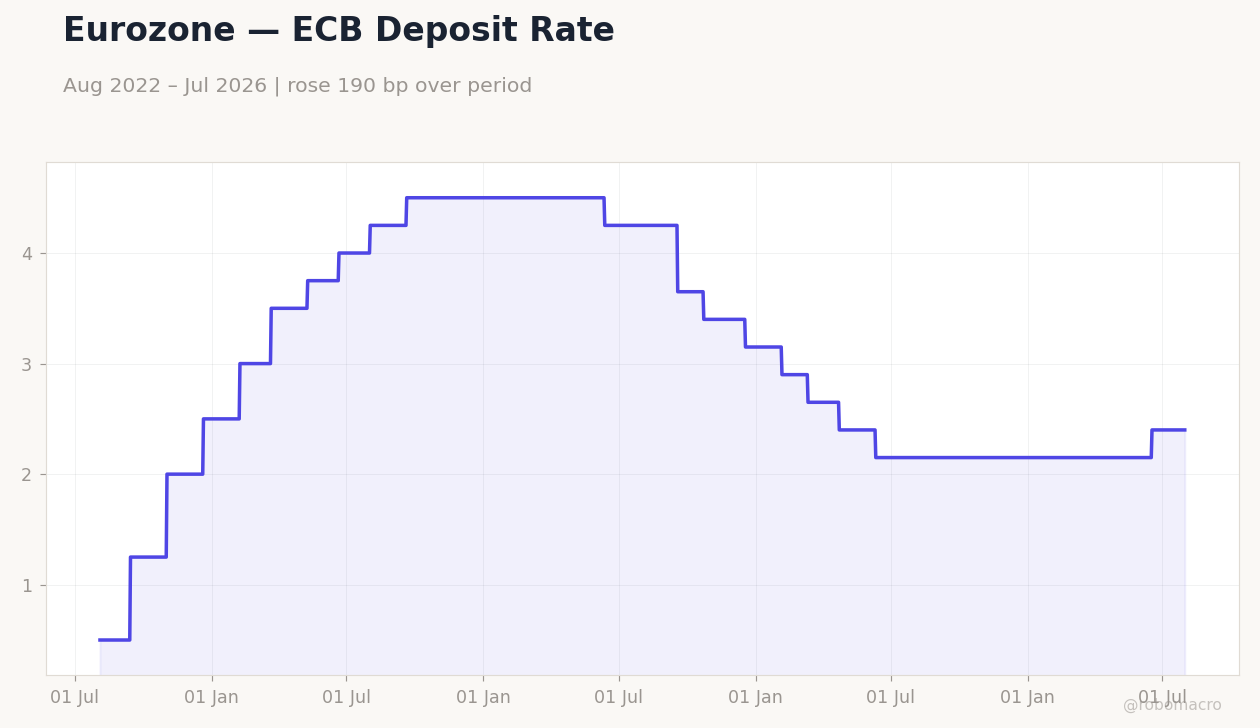
ECBDepo rate2.25%Jun 2026+25Sep 102.002.25——
Bank of EnglandBank rate3.75%Dec 2025-25Sep 173.753.75——
RiksbankRepo rate1.75%Oct 2025-25Aug 201.751.75——
Norges BankDep rate4.25%May 2026+25Aug 134.004.25——
SNBPolicy rate0.00%Jun 2025-25Sep 240.000.00——
CNB (Czech)2-wk repo3.75%Jun 2026+25Aug 63.503.75——
NBH (Hungary)Base rate5.75%Jul 2026-25Aug 256.256.25——
NBP (Poland)Ref rate3.75%Mar 2026-25Sep 23.753.75——
SARBRepo rate7.00%May 2026+25Sep 236.757.00——
CBRT (Turkey)1-wk repo37.00%Jan 2026-100Sep 1037.0037.00——
Asia / Pacific
RBACash rate4.35%May 2026+25Aug 114.104.35——
RBNZOCR2.50%Jul 2026+25Sep 22.252.25——
BoJPol rate1.25%Jun 2026+25Sep 180.751.00——
PBoC1-yr LPR3.00%May 2025-10—3.003.00——
RBI (India)Repo rate5.25%Dec 2025-25Aug 55.255.25——
BoK (Korea)Base raten/v——Aug 27————
BI (Indonesia)BI-Rate5.75%Jun 2026+25Aug 194.755.75——
BSP (Philippines)Rev repo4.75%Jun 2026+25Aug 274.254.75——
BoT (Thailand)1-day repo1.00%Feb 2026-25Aug 261.001.00——
CBC (Taiwan)Disc rate2.00%Mar 2024+12.5Sep 17————
MAS (Singapore)SGD NEERMild appr.Apr 2026slope+Jul 27————
Changes to Consensus Rate Views This Week vs Jul 26
NBH (Hungary) current rate: 6.00→5.75 ▼ -25bp
Every figure on this page is verified against official central bank publications or BIS policy-rate data; a cell we cannot verify is left blank ("n/v") rather than estimated. Quarter columns show realized quarter-end rates only — no forward rate path is published, because market-implied pricing is not sourced for these banks. Shaded rows denote regional groupings. Data as of Week of July 27–31, 2026.
RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Activity Tracking & NowcastReal-time growth pulse
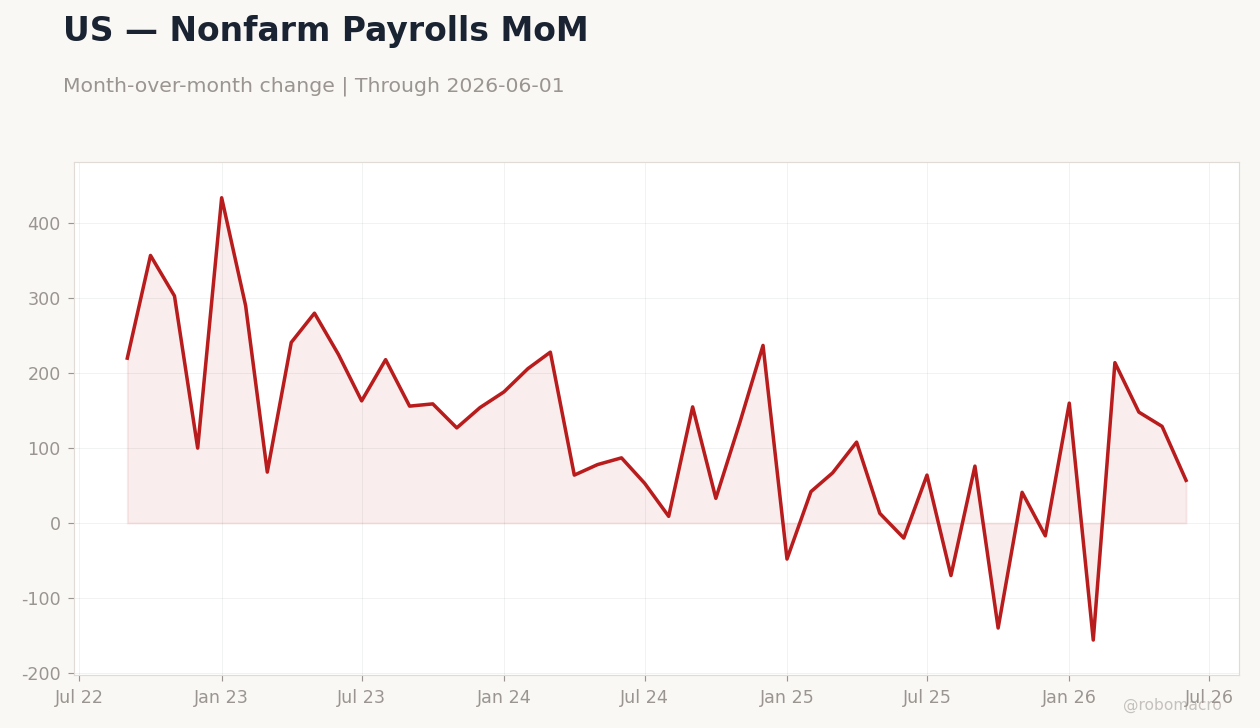
RoboMacro US Labor Nowcast — Jul 2026 NFP
Nonfarm Payrolls (m/m)+96k  80% CI +61k…+285k
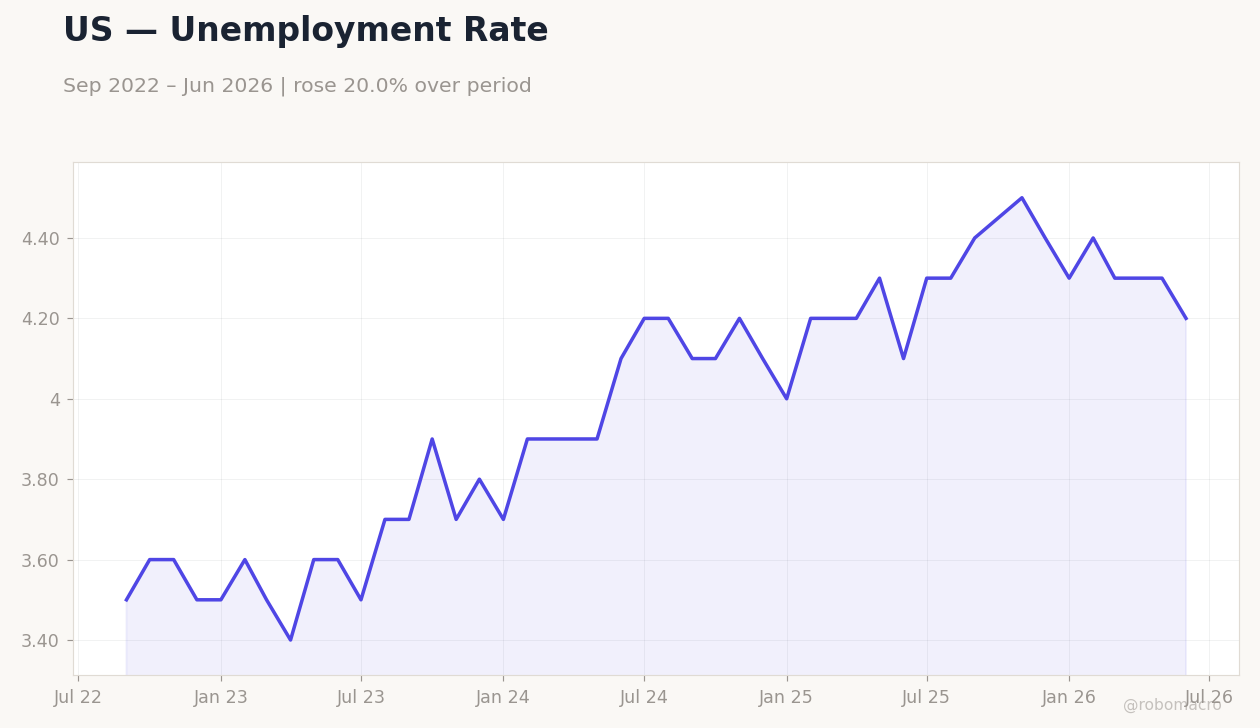
Unemployment Rate4.2%
Avg Hourly Earnings (y/y)3.5%
Point estimate = median of a 10-model ensemble (ElasticNet, LightGBM, MIDAS, SARIMAX, XGBoost, VAR, UC stochastic-trend, RF, MLP, naive-AR). Bands are model dispersion, not a forecast of revisions.
RoboMacro High-Frequency Activity Nowcast
Composite weekly activity index, diffusion-style (50 = neutral; >50 expansion), seasonally adjusted. Each economy combines 2–7 weekly public indicators — among them electricity and gas demand, flights, port calls, road traffic, card and payment volumes, job postings and tax deposits. A week is published only when indicators covering at least 70% of the index weight have reported and the week has closed; the as-of date and the share of indicators reporting are shown per row. Source: RoboMacro High-Speed Macro engine.
Economy Activity Index4-wk Δ13-wk Δ Week endingIndicators Signal
Brazil62.9+7.8+30.12026-07-313/4Expanding · Advancing
United States61.3+6.2+9.12026-07-247/7Expanding · Advancing
Canada61.0+11.6+6.72026-07-246/8Expanding · Advancing
Japan58.1+25.5+1.52026-07-245/5Expanding · Advancing
Poland56.3+9.0-7.52026-07-313/4Expanding · Advancing
Spain55.5+0.0+2.62026-07-245/5Expanding · Flat
France49.9-4.8+17.82026-07-244/5Contracting · Retreating
Euro Area47.3-4.5+4.12026-07-245/5Contracting · Retreating
Italy45.5-11.6-20.72026-07-245/5Contracting · Retreating
New Zealand43.8-11.1-24.32026-07-244/5Contracting · Retreating
Germany42.4-0.4+17.22026-07-315/6Contracting · Flat
Australia33.2-10.4-23.82026-07-243/3Contracting · Retreating

Activity remains in expansion in United States, Spain, Japan, Canada, Brazil, Poland; while high-frequency trackers point to sub-trend activity in Euro Area, Germany, France, Italy, Australia, New Zealand. On a 4-week basis, momentum is improving in United States, Japan, Canada, Brazil, Poland and cooling in Euro Area, France, Italy, Australia, New Zealand. RoboMacro's labor ensemble nowcasts the next US payrolls print at +96k.

Nowcasts are model-derived from high-frequency public data and update weekly as new releases arrive. Activity-index country coverage is expanding. A cross-country PMI matrix is planned pending a verified PMI data source.
RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Markets in ReviewRates & Fixed Income
Rates & Fixed Income Chart 1
Rates & Fixed Income Chart 2
Rates & Fixed Income Chart 3
Rates & Fixed Income Chart 4

Week in Review

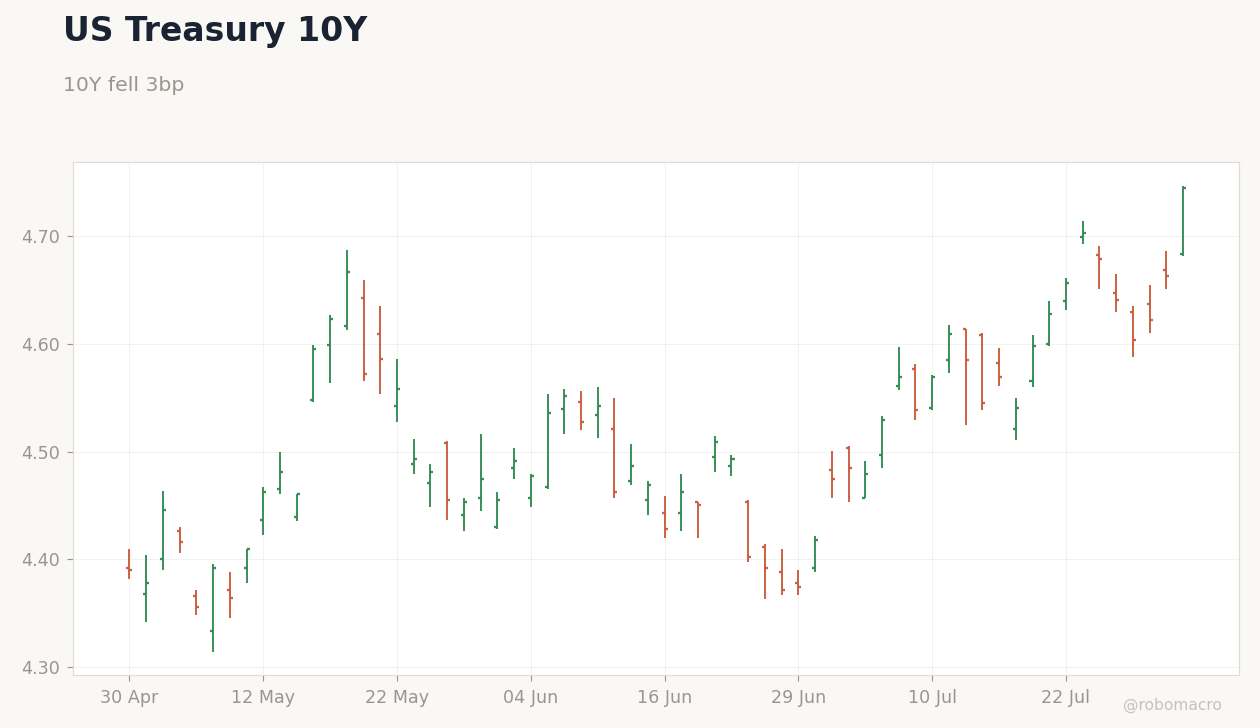
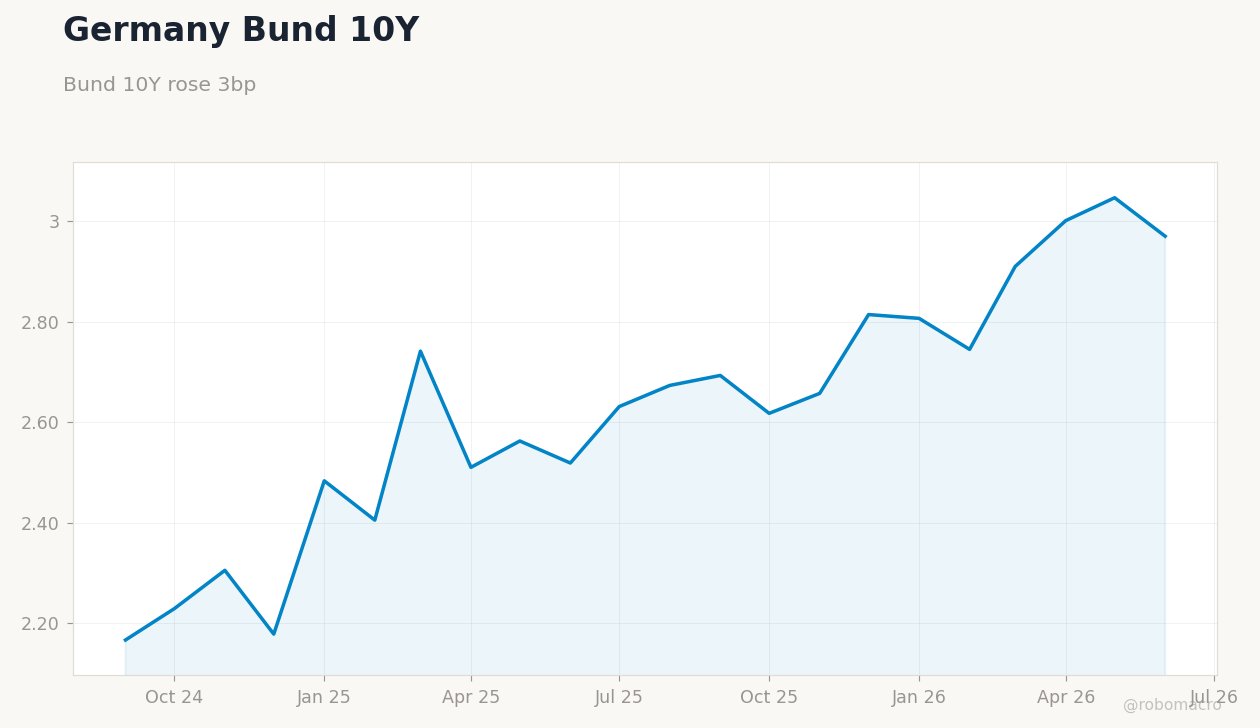
US 2-year yields fell 14bp to 4.23%, the most significant DM front-end move. The 10-year UST yield eased 3bp to 4.68% while the 30-year yield rose 4bp to 5.21%. German 10-year Bund yields rose 3bp to 3.20%, UK 10-year gilt yields declined 1bp to 5.04%, and Japanese 10-year yields rose 3bp to 2.80%. The intra-week path showed the US 10-year yield falling from 4.6410 on Monday to 4.6040 on Tuesday before climbing to 4.7450 on Friday. The 30-year yield followed suit, moving from 5.1250 on Monday to 5.2750 on Friday. These shifts occurred against a backdrop of revived inflation fears and resilient equity performance.
Curve & Spreads

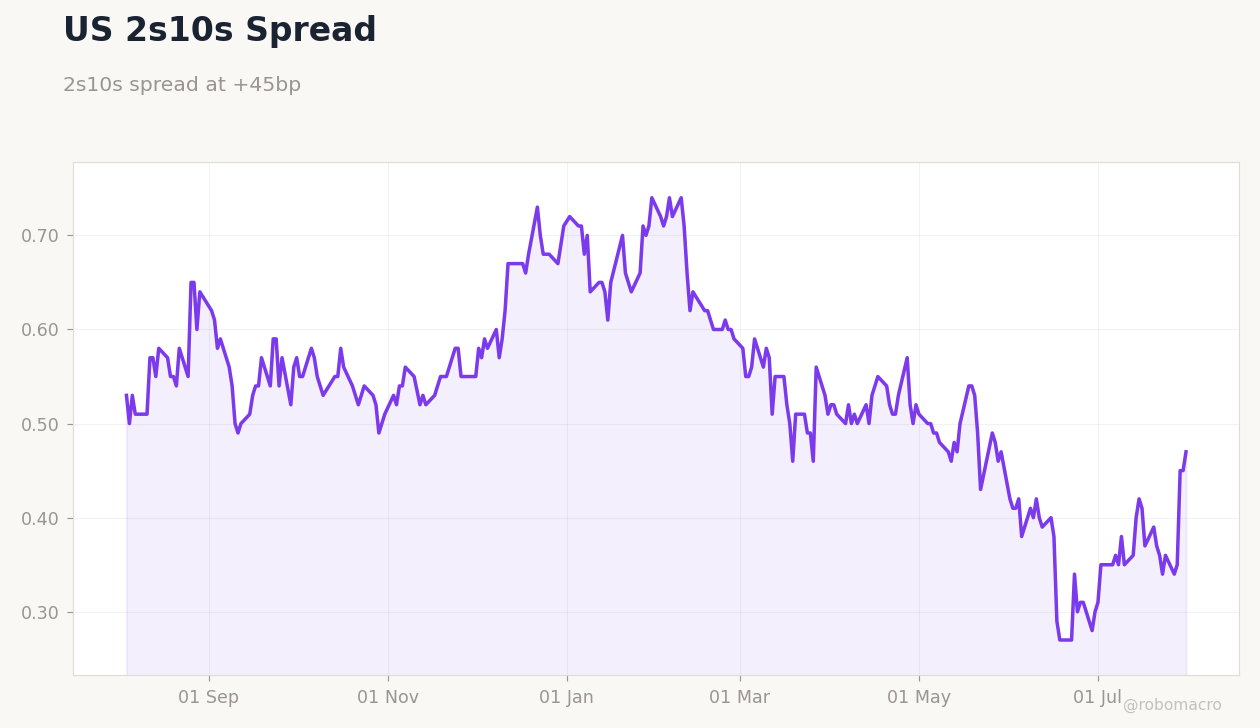
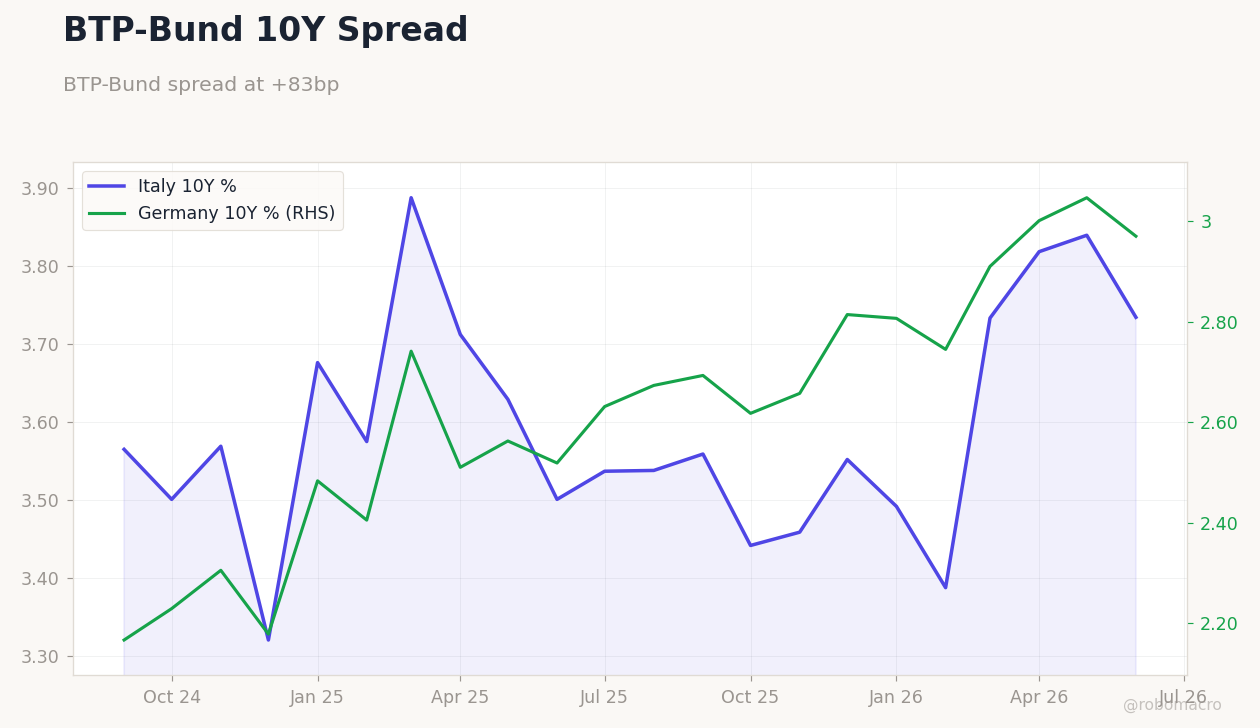
The US 2s10s spread stands at +45bp, compared with Germany at +39bp and the UK at +62bp. The UK curve is therefore steeper than both the US and German curves. All three remain positively sloped, implying directional expectations of stable to improving growth ahead rather than contraction. This shape suggests investors are positioned for eventual policy normalization without anticipating near-term economic weakness.

EM Bonds

Brazilian 10-year yields stand at 14.77%, Turkish 10-year yields at 35.16%, South African 10-year yields at 8.73%, and Indonesian 10-year yields at 7.34%. Turkish yields moved significantly lower alongside Brazilian yields. These EM levels remain multiples of DM counterparts such as the US 10-year at 4.68% and German 10-year at 3.20%, underscoring persistent risk premia and wider spread differentials. Turkey’s 2s10s spread at -691bp stays sharply inverted, contrasting with Brazil’s +82bp positive slope.
Central Bank Read

Most major central banks held policy rates steady while stressing data dependence. The yield curve shape implies an easing bias in several DM economies. Front-end rates generally outperformed the back end, with the US 2-year yield falling 14bp versus only a 3bp decline in the 10-year and a 4bp rise in the 30-year. Germany showed a similar pattern, with the 2-year yield down 1bp against a 3bp rise in the 10-year. Australia mirrored this dynamic with its 2-year yield falling 15bp versus an 8bp decline in the 10-year. These moves suggest markets are pricing in a gradual shift toward less restrictive policy even as officials remain data-dependent.
Week Ahead

Eurozone flash inflation data will be the primary release mattering most for duration risk, as any surprise could recalibrate ECB expectations and Bund positioning. US payrolls data will also be watched closely for its read on the Fed’s data-dependent stance and potential impact on UST yields. Treasury auctions mid-week will test demand after this week’s yield volatility. GDP releases in select economies round out the calendar and could influence growth expectations embedded in curve shape.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Markets in ReviewFixed Income
Global Government Bond Yields
Yields in %. WoW change in basis points, over the five trading sessions to the latest close. US tenors are Treasury constant-maturity yields (Federal Reserve); international tenors are benchmark government yields from public market data.
Country2Y2Y WoW10Y10Y WoW30Y30Y WoW2s10s
United States4.23%-14bp4.68%-3bp5.21%+4bp+45bp
United Kingdom4.42%+1bp5.04%-1bp5.78%+6bp+62bp
Germany2.81%-1bp3.20%+3bp3.70%+5bp+39bp
France2.99%-0bp4.00%+2bp4.77%+6bp+101bp
Italy3.02%-4bp4.03%+2bp4.81%+5bp+101bp
Spain2.89%-1bp3.66%+2bp4.34%+5bp+77bp
Japan1.51%-1bp2.80%+3bp3.98%+0bp+130bp
Canada2.92%+1bp3.67%+6bp4.05%+7bp+74bp
Australia4.52%-15bp4.96%-8bp5.48%-9bp+44bp
China1.26%-1bp1.71%-1bp2.19%-0bp+45bp
India6.01%-2bp6.81%-1bp7.47%+1bp+80bp
Brazil13.95%-34bp14.77%-7bp——+82bp
Mexico——9.20%-9bp———
South Korea3.65%-16bp4.25%-19bp4.50%-16bp+61bp
Indonesia——7.34%-4bp7.33%-5bp—
Turkey42.07%-34bp35.16%-23bp——-691bp
South Africa——8.73%-15bp9.21%-14bp—
Poland——5.78%-1bp———

US 2-year yields fell 14bp to 4.23% while the 30-year rose 4bp to 5.21%, steepening the 2s10s to +45bp. Australia posted the largest 2-year decline at 15bp to 4.52%, with 10-year yields down 8bp to 4.96%. South Korea saw the broadest sell-off in yields, with the 10-year dropping 19bp to 4.25%. Brazil and Turkey 2-year yields each declined 34bp, to 13.95% and 42.07% respectively. Canada 10-year yields rose 6bp to 3.67%, one of the few notable increases. The 2s10s curve steepened across most markets, reaching +130bp in Japan and +101bp in both France and Italy. European core and peripheral 10-year yields edged higher by 2-3bp. Focus next week remains on G10 inflation releases and month-end duration flows.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Markets in ReviewGlobal Equities
Global Equities Chart 1
Global Equities Chart 2
Global Equities Chart 3
Global Equities Chart 4

Week in Review

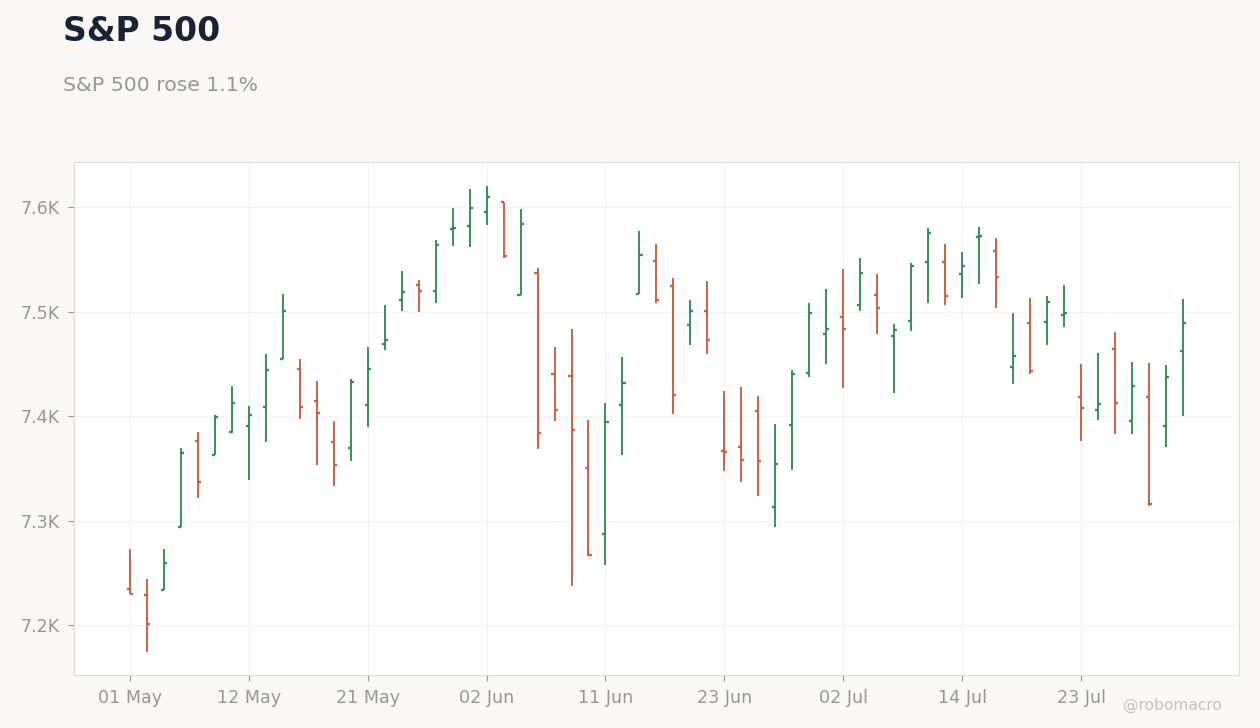
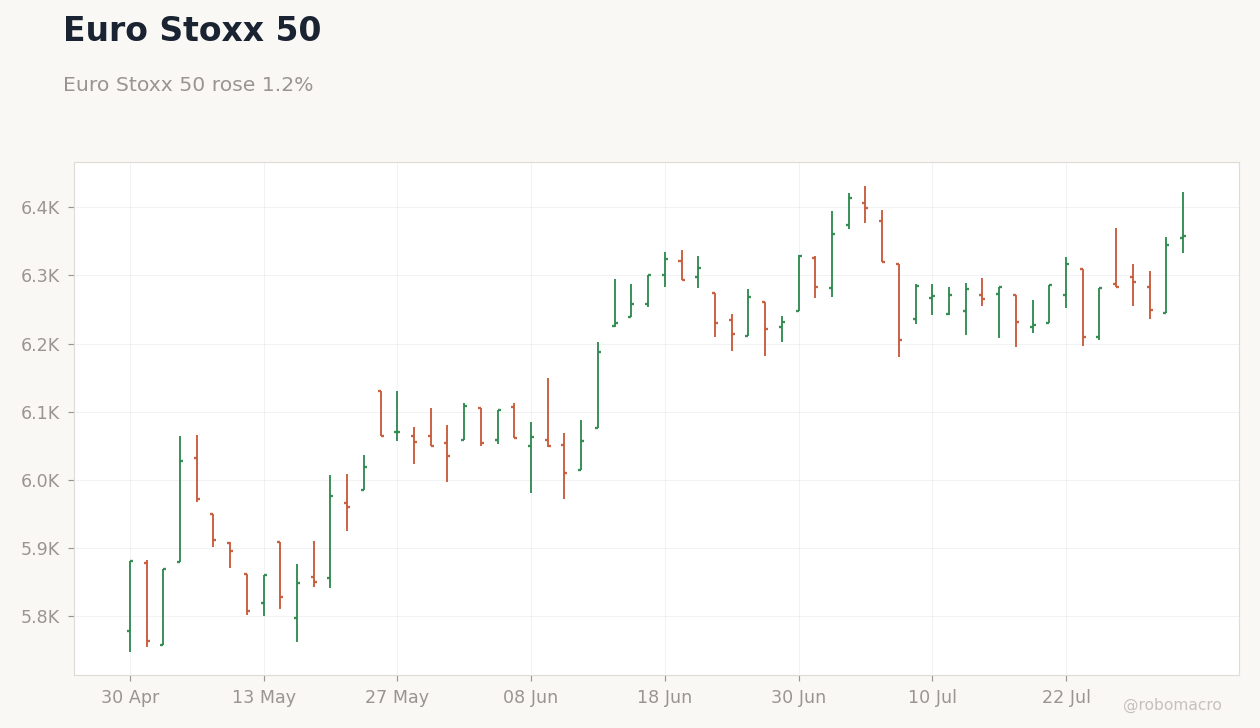
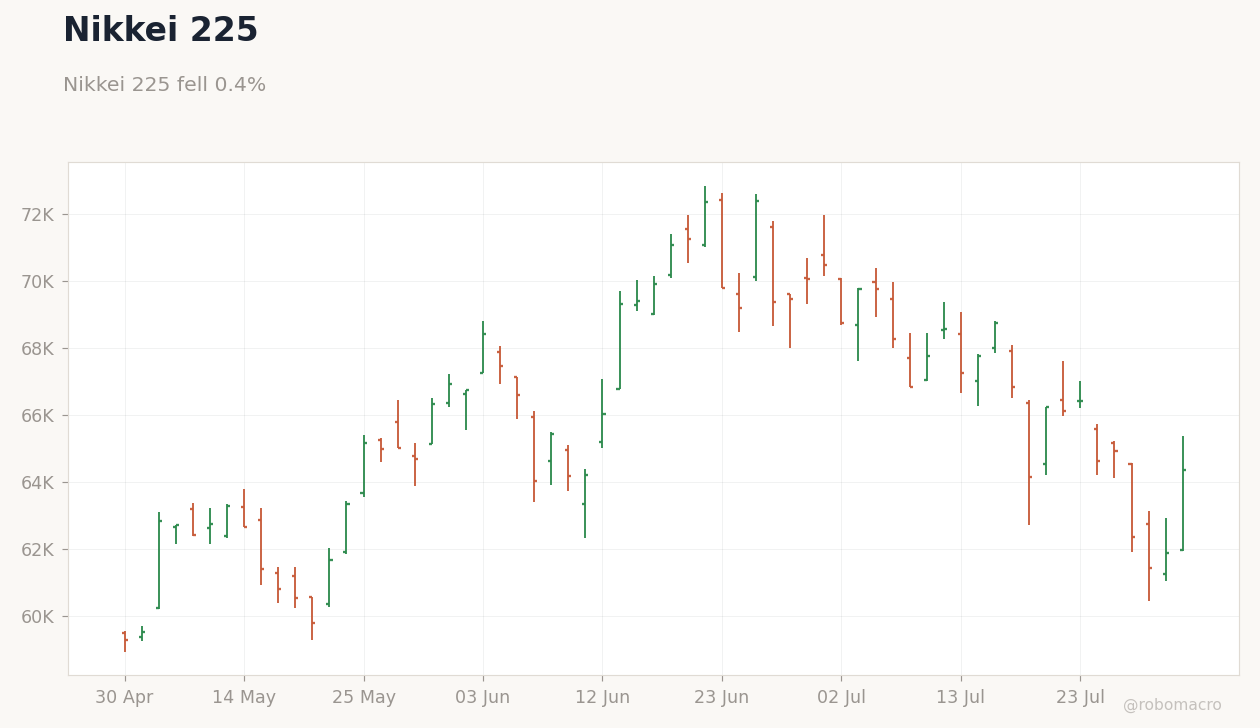
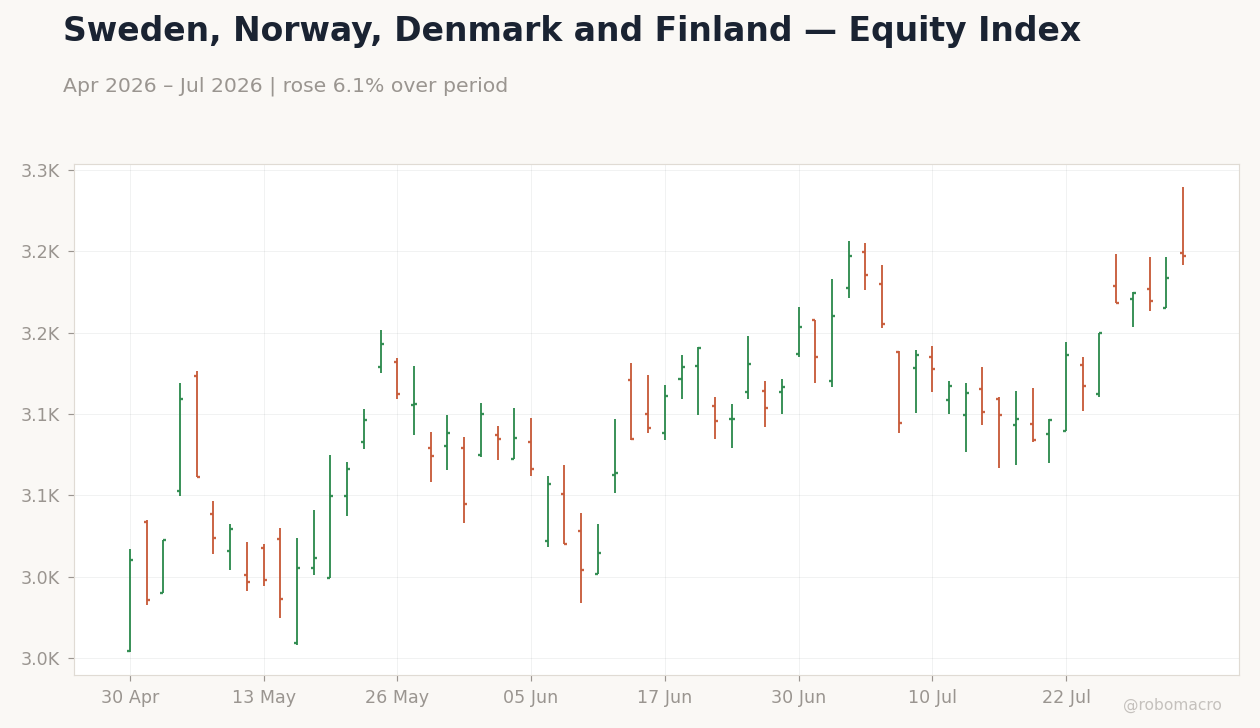
The S&P 500 rose +1.1% week-over-week to close at 7,490. Daily closes showed an uneven path, starting at 7,413 on Monday, rising to 7,429 on Tuesday before a sharp selloff to 7,316 on Wednesday, followed by a strong recovery to 7,438 on Thursday and 7,490 on Friday. In the US, the Dow Jones gained +1.0% while the Nasdaq 100 added +0.5% and the Russell 2000 edged +0.1%. European equities posted solid gains with the Euro Stoxx 50 up +1.2%, the DAX advancing +2.1%, the CAC 40 rising +1.6% and the FTSE 100 gaining +1.2%. Asian markets diverged as the Nikkei 225 fell -0.4% while the Hang Seng surged +3.7% and the CSI 300 dropped -5.3%. Emerging market indices were mostly positive, led by the Nifty 50 at +2.6%, the Ibovespa at +2.3% and the S&P/TSX declining -0.4%.

Regional Divergences

European bourses led with the DAX +2.1%, CAC 40 +1.6% and Euro Stoxx 50 +1.2% outperforming the S&P 500 +1.1%, consistent with PMI data exceeding expectations and the ECB holding policy rates. US large caps showed modest resilience while Japanese shares lagged with the Nikkei 225 -0.4% amid suspected coordinated FX intervention and a steady Bank of Japan policy rate. Within Asia, the Hang Seng +3.7% stood in contrast to the CSI 300 -5.3%, highlighting regional divergences in response to global cues. Emerging markets displayed selective strength, with the Nifty 50 +2.6% and Ibovespa +2.3% benefiting from resilient labor markets in Brazil and data-dependent policy stances in India and Canada. These moves aligned with country-specific catalysts including resilient Canadian GDP, Brazilian fiscal impulses and ongoing IMF program compliance in Argentina.

Volatility & Risk Appetite

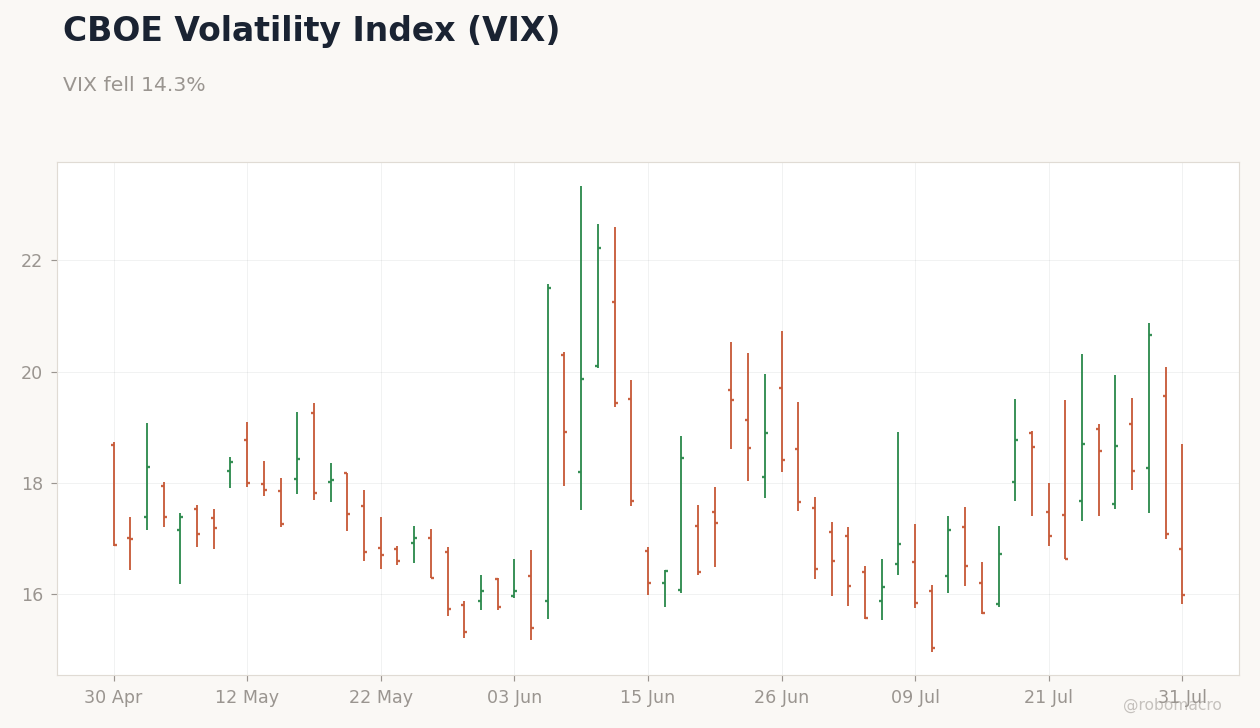
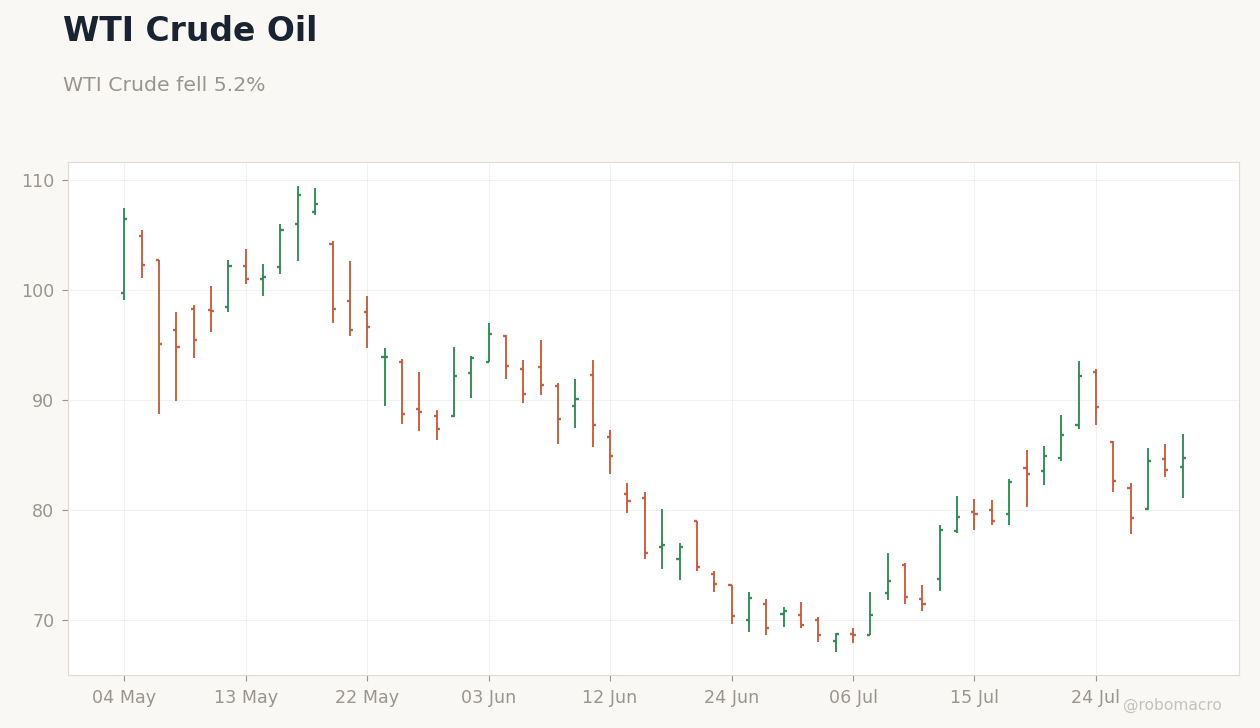
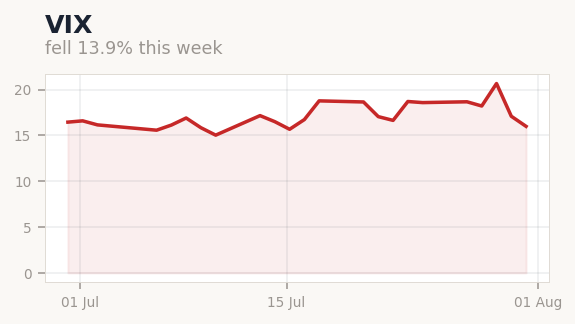
The VIX closed the week at 16.0 after peaking at 20.7 mid-week, signaling improved risk appetite by Friday. Growth underperformed value as the Nasdaq 100 +0.5% trailed the Dow Jones +1.0%. Small caps also lagged with the Russell 2000 +0.1% trailing the S&P 500 +1.1%. Commodity signals pointed to mixed sector implications, with WTI Crude -5.2%, Brent Crude -6.9% and Natural Gas -4.3% suggesting pressure on energy while Copper +2.3% and Gold +1.0% supported materials and defensive positioning. Overall, the decline in the VIX alongside the recovery in major equity indices from Wednesday lows reflected a shift toward risk-on sentiment by week end.

Week Ahead

The week ahead features the RBI policy decision in India alongside Q1 earnings as key drivers for Dalal Street. Earnings reports from major indices are expected to set the tone for global risk sentiment, particularly if results align with resilient labor and GDP data seen in recent country releases. These events pose the biggest risk to equity markets, with potential for risk-on moves on beats or risk-off reactions if inflation and fiscal metrics disappoint. Limited additional high-impact releases leave global cues and commodity trends as secondary influences on positioning.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Markets in ReviewGlobal Equities
Global Equity Indices
Week-on-week, month-to-date, year-to-date. WoW is the change over the seven calendar days to the latest close. Source: public market data.
IndexLevelWoWMTDYTD
S&P 5007,490+1.1%+0.1%+9.2%
Nasdaq 10028,274+0.5%-5.2%+12.2%
Dow Jones52,485+1.0%+0.3%+8.5%
Russell 20002,931+0.1%-2.7%+16.9%
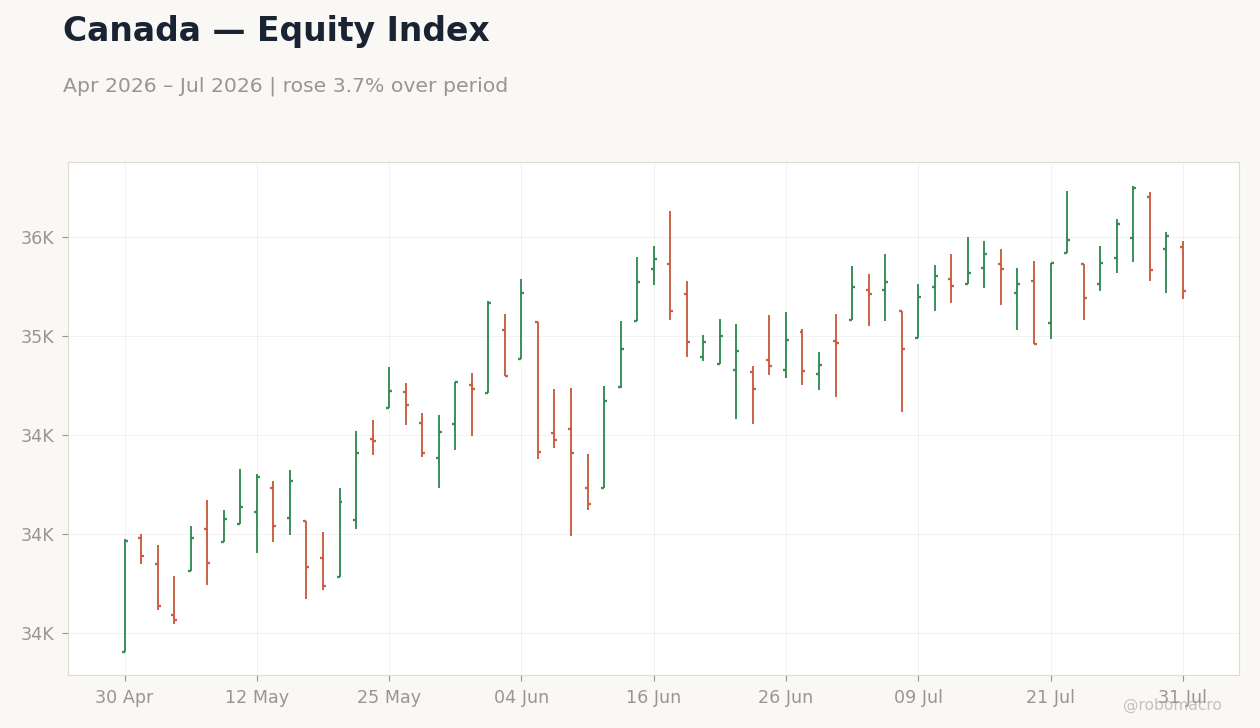
S&P/TSX35,226-0.4%+0.7%+10.5%
FTSE 10010,868+1.2%+3.7%+9.2%
Euro Stoxx 506,358+1.2%+1.2%+7.3%
DAX25,629+2.1%+2.4%+4.4%
CAC 408,510+1.6%+2.1%+3.8%
FTSE MIB52,173+0.7%+1.1%+15.0%
IBEX 3519,783+1.0%+1.9%+13.1%
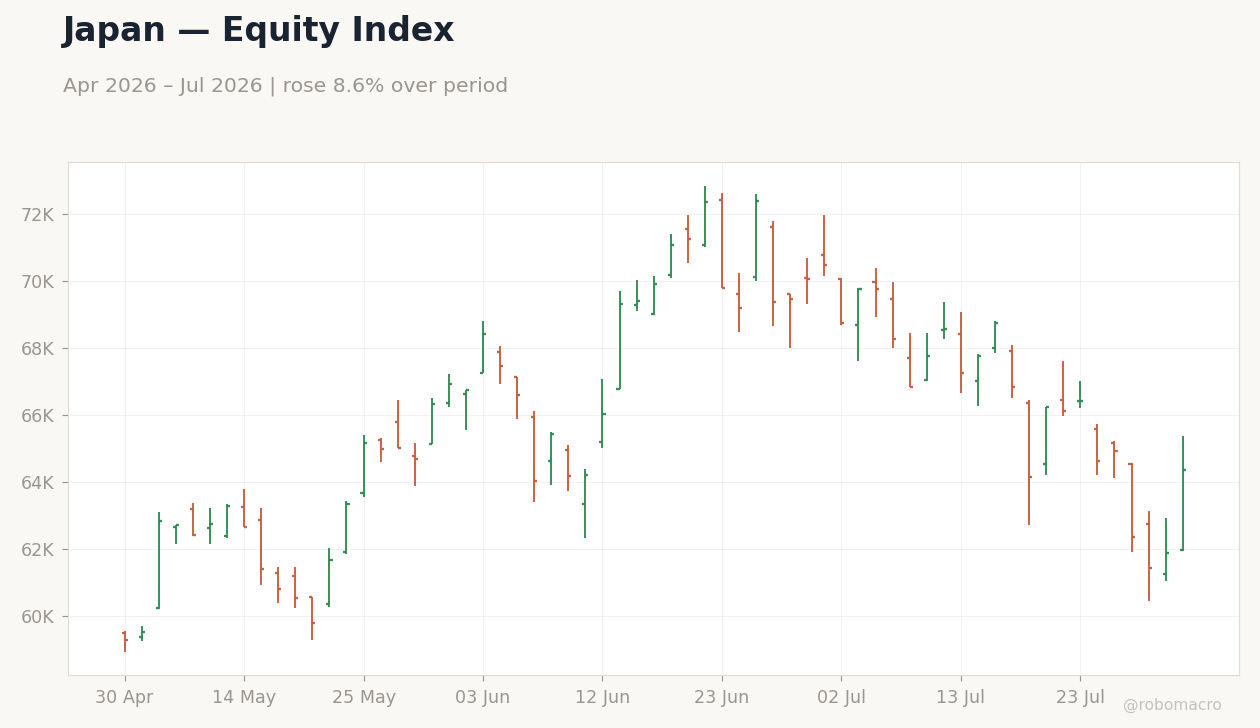
Nikkei 22564,362-0.4%-8.7%+24.2%
Hang Seng25,884+3.7%+12.3%-1.7%
CSI 3004,529-5.3%-8.7%-4.0%
S&P/ASX 2008,977+2.3%+2.9%+2.9%
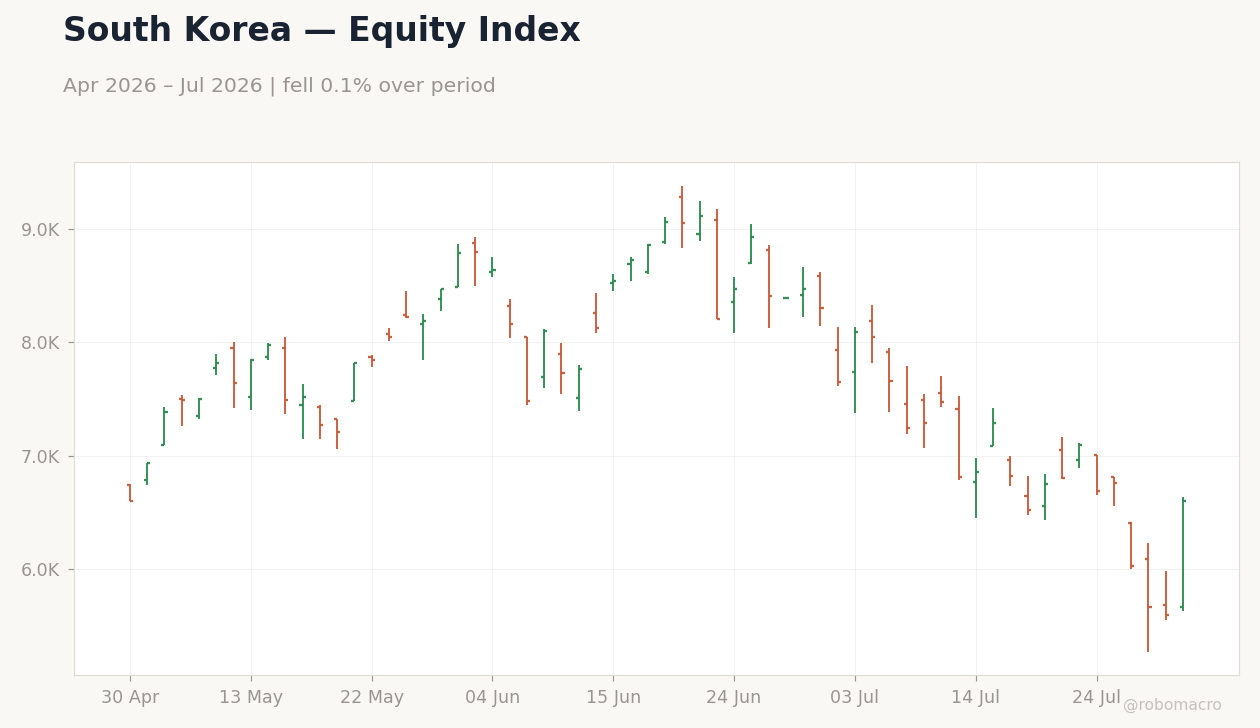
KOSPI6,595-1.4%-20.6%+53.0%
Nifty 5024,384+2.6%+1.6%-6.7%
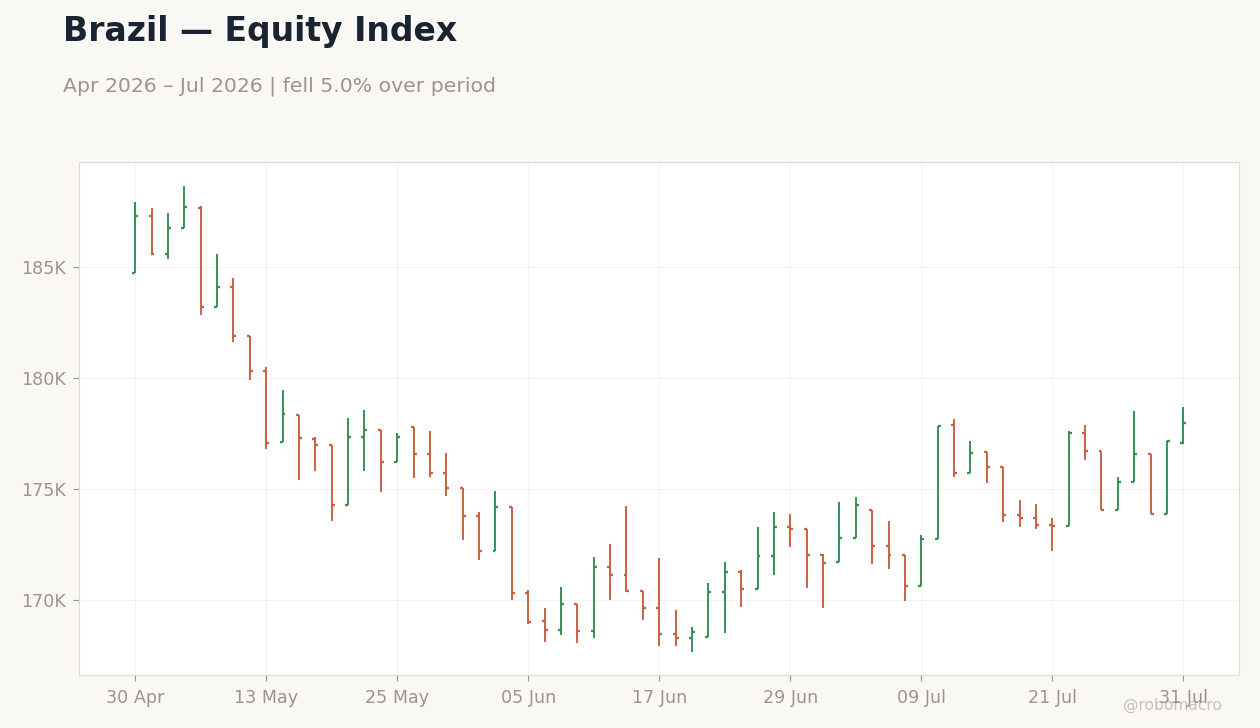
Ibovespa177,999+2.3%+3.7%+10.9%
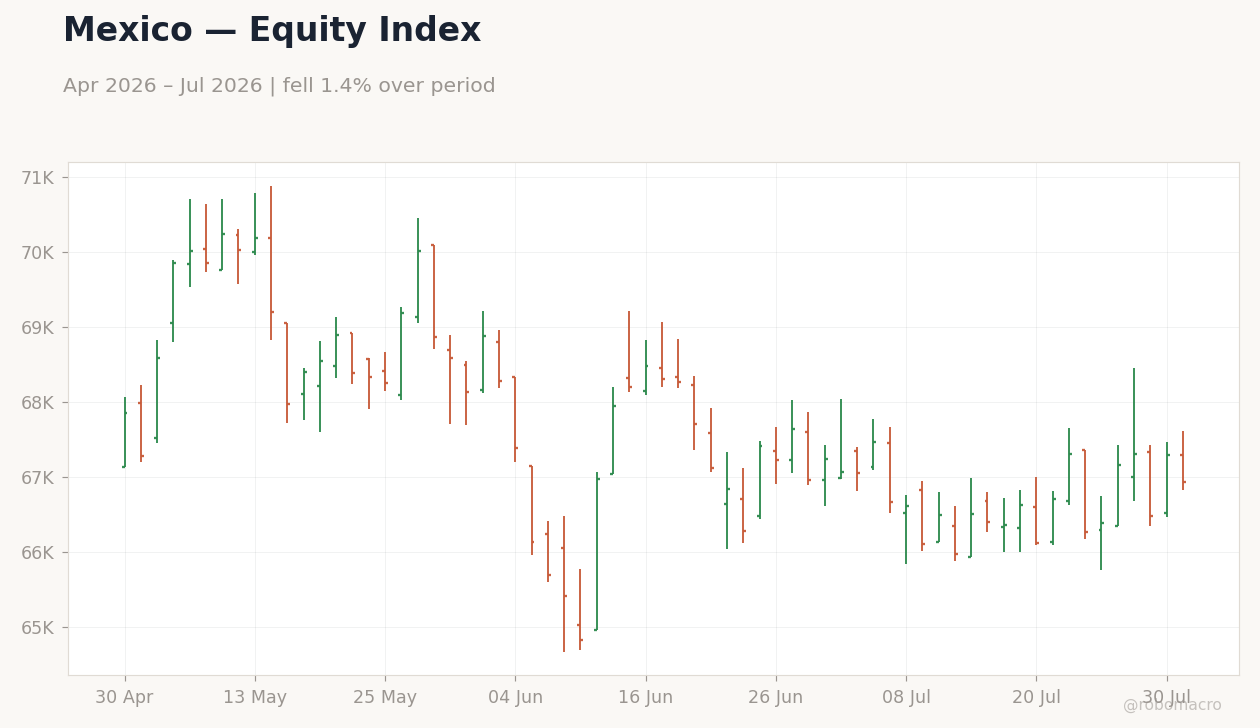
IPC Mexico66,937+0.8%-0.5%+4.4%
JSE Top 40103,258+1.8%+2.0%-4.6%

US equities posted modest gains, with the S&P 500 rising 1.1% to 7,490 and the Dow Jones adding 1.0% to 52,485, while the Nasdaq 100 advanced only 0.5%. The Russell 2000 edged up 0.1%. Europe outperformed, as the DAX climbed 2.1% to 25,629, the CAC 40 gained 1.6%, and the Euro Stoxx 50 rose 1.2%. Asia diverged sharply: the Hang Seng jumped 3.7% to 25,884, but the CSI 300 dropped 5.3% to 4,529 and the KOSPI fell 1.4%. The Nikkei 225 slipped 0.4%. Emerging markets were supported by the Nifty 50’s 2.6% advance and the Ibovespa’s 2.3% gain. Next week, focus turns to US jobs data and any follow-through in Chinese policy signals.

Equity Performance Heat Map
IndexWoWMTDYTD
S&P 500+1.1%+0.1%+9.2%
Nasdaq 100+0.5%-5.2%+12.2%
Dow Jones+1.0%+0.3%+8.5%
Russell 2000+0.1%-2.7%+16.9%
S&P/TSX-0.4%+0.7%+10.5%
FTSE 100+1.2%+3.7%+9.2%
Euro Stoxx 50+1.2%+1.2%+7.3%
DAX+2.1%+2.4%+4.4%
CAC 40+1.6%+2.1%+3.8%
FTSE MIB+0.7%+1.1%+15.0%
IBEX 35+1.0%+1.9%+13.1%
Nikkei 225-0.4%-8.7%+24.2%
Hang Seng+3.7%+12.3%-1.7%
CSI 300-5.3%-8.7%-4.0%
S&P/ASX 200+2.3%+2.9%+2.9%
KOSPI-1.4%-20.6%+53.0%
Nifty 50+2.6%+1.6%-6.7%
Ibovespa+2.3%+3.7%+10.9%
IPC Mexico+0.8%-0.5%+4.4%
JSE Top 40+1.8%+2.0%-4.6%
RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Markets in ReviewFX & Digital Assets
FX & Digital Assets Chart 1
FX & Digital Assets Chart 2
FX & Digital Assets Chart 3
FX & Digital Assets Chart 4

Week in Review

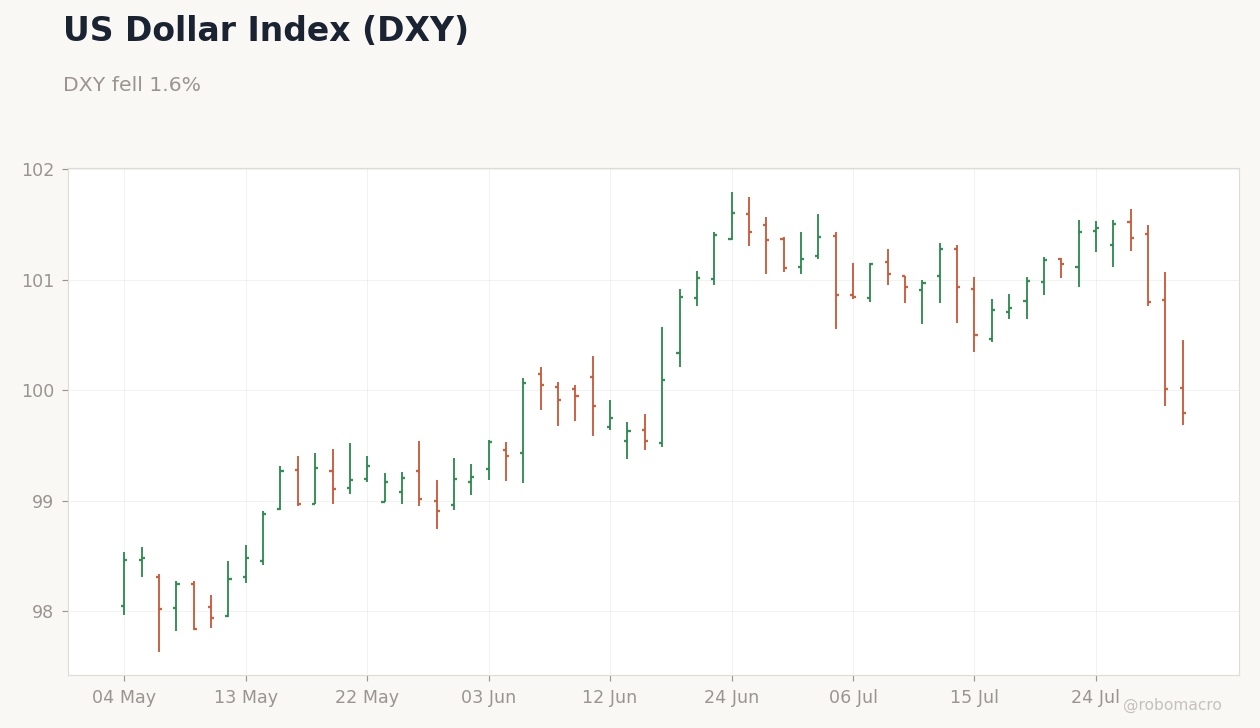
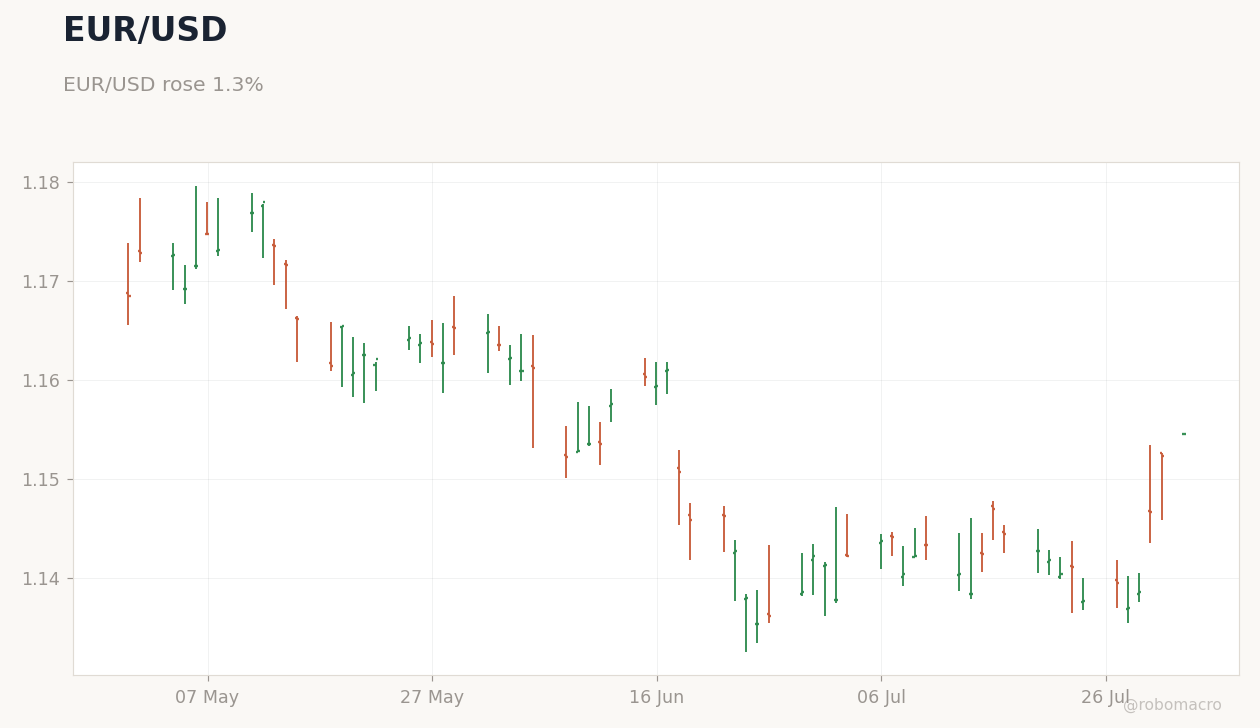
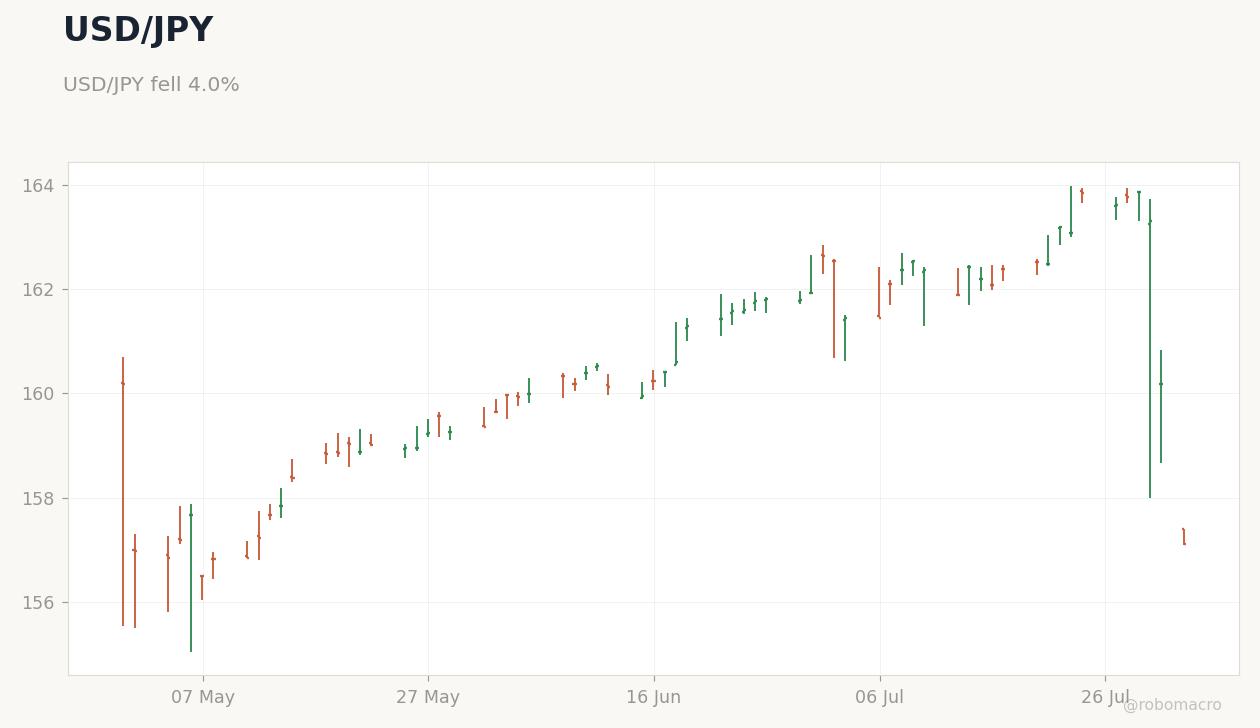
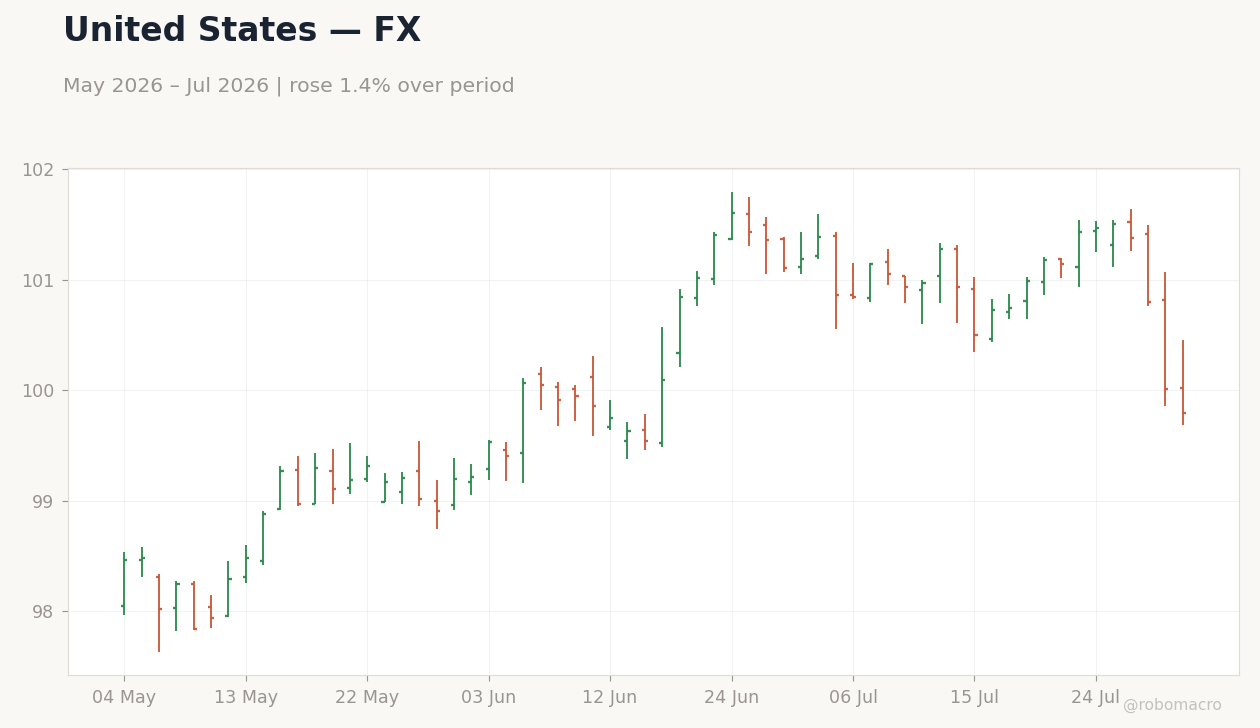
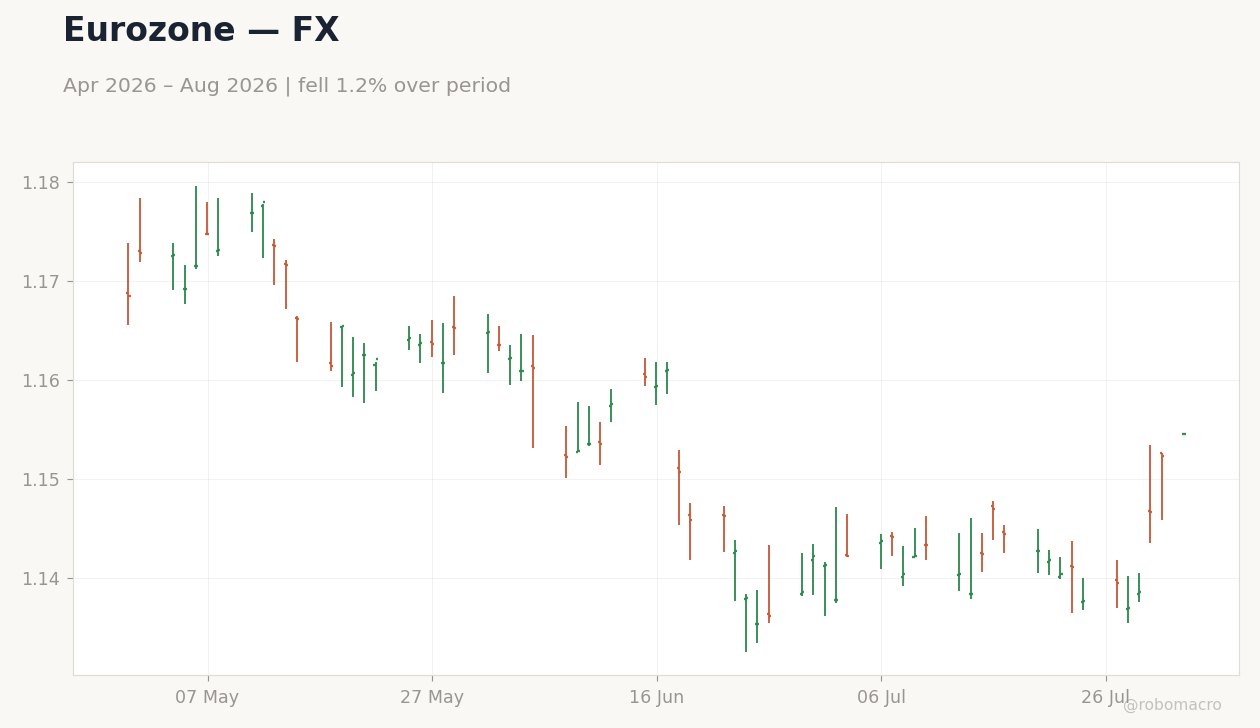
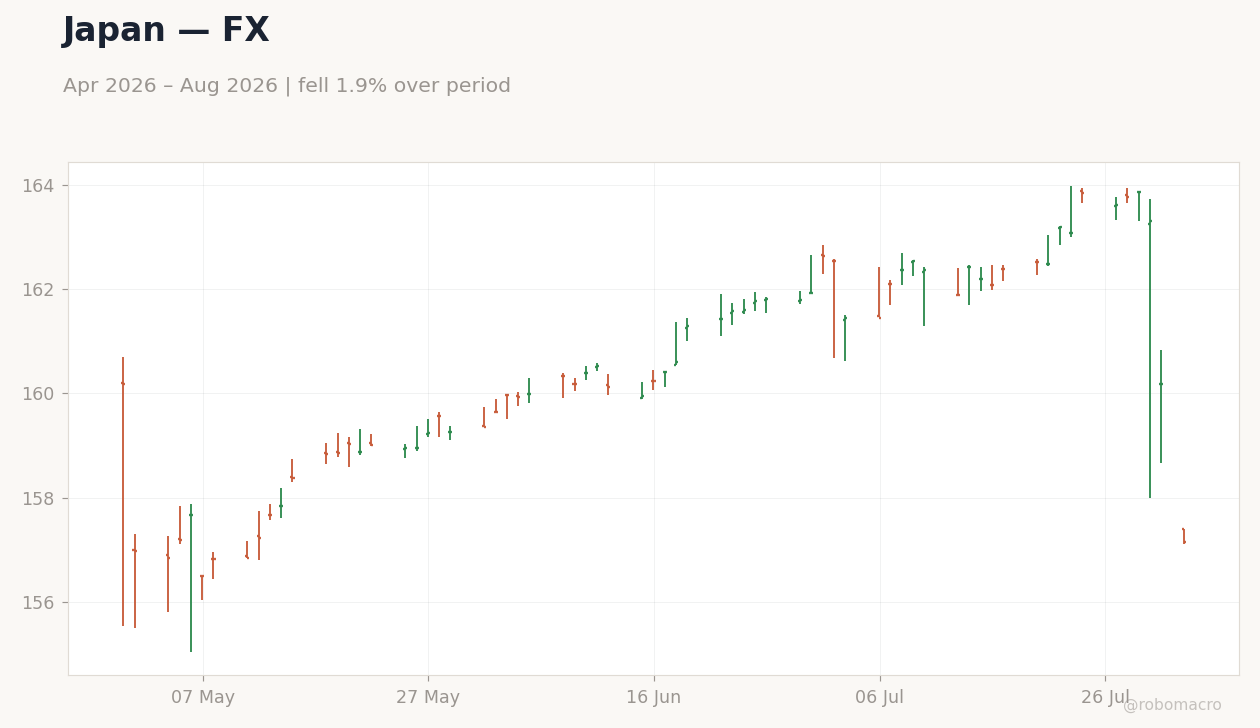
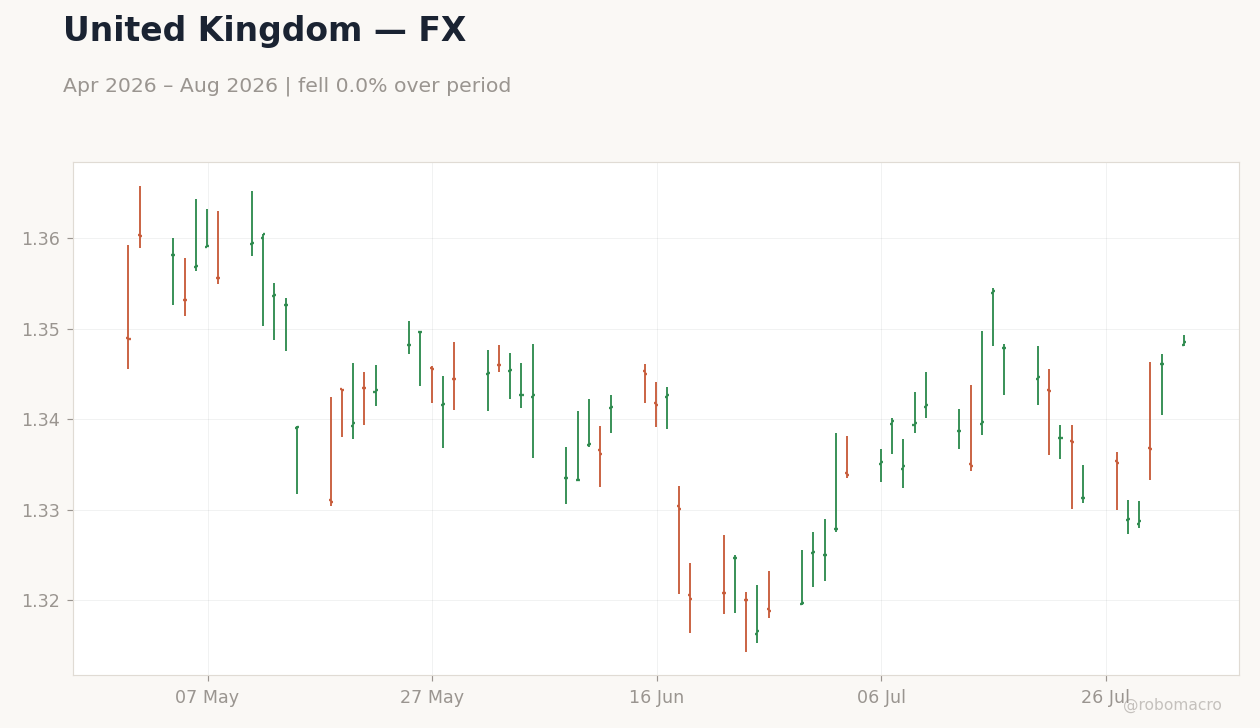
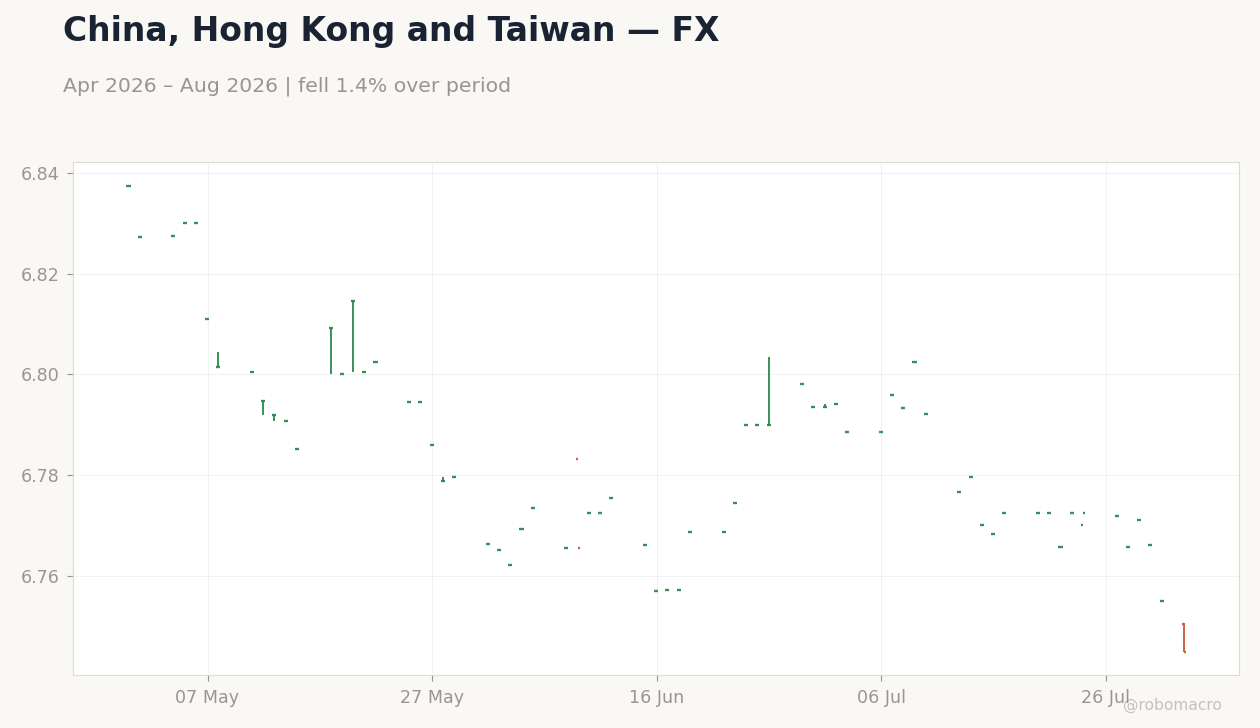
The DXY fell 1.6% week-over-week to 99.80. The index held near 101 on Tuesday and Wednesday before easing to 100 on Thursday and closing at 99.8 on Friday. G10 currencies strengthened broadly, with EUR/USD rising 1.3% to 1.1546, GBP/USD gaining 1.0% to 1.3486, AUD/USD advancing 0.9% to 0.7056, and NZD/USD climbing 1.7% to 0.5897. USD/JPY plunged 4.0% to 157.12, holding at 164 from Monday through Wednesday before declining to 163 on Thursday and 160 on Friday. In EM, USD/ZAR dropped 1.6% to 16.43, USD/MXN fell 1.1% to 17.33, USD/INR eased 1.2% to 95.39, and USD/CNY declined 0.4% to 6.7448 while USD/TRY rose 0.3% to 47.49.

Dollar & G10

DXY weakness developed amid shifts in rate differentials, with the US 2s10s at +45bp against wider spreads elsewhere including Japan at +130bp. US yields saw larger declines than peers in some cases, while the Australian 2s10s stood at +44bp. EUR/USD closed at 1.1546 after a 1.3% WoW gain, and GBP/USD ended at 1.3486 after a 1.0% WoW advance. USD/JPY fell to 157.12 after a 4.0% WoW decline, with the daily closes confirming a sharp reversal on Friday consistent with suspected intervention.

EM FX

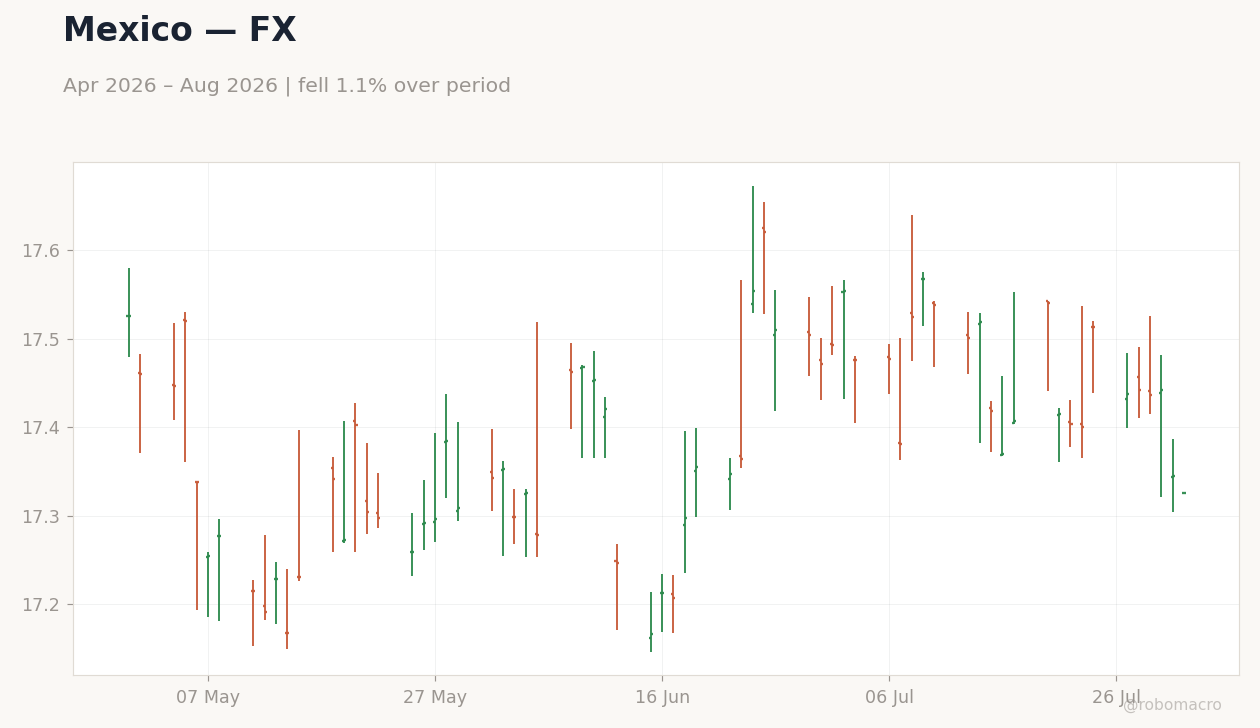
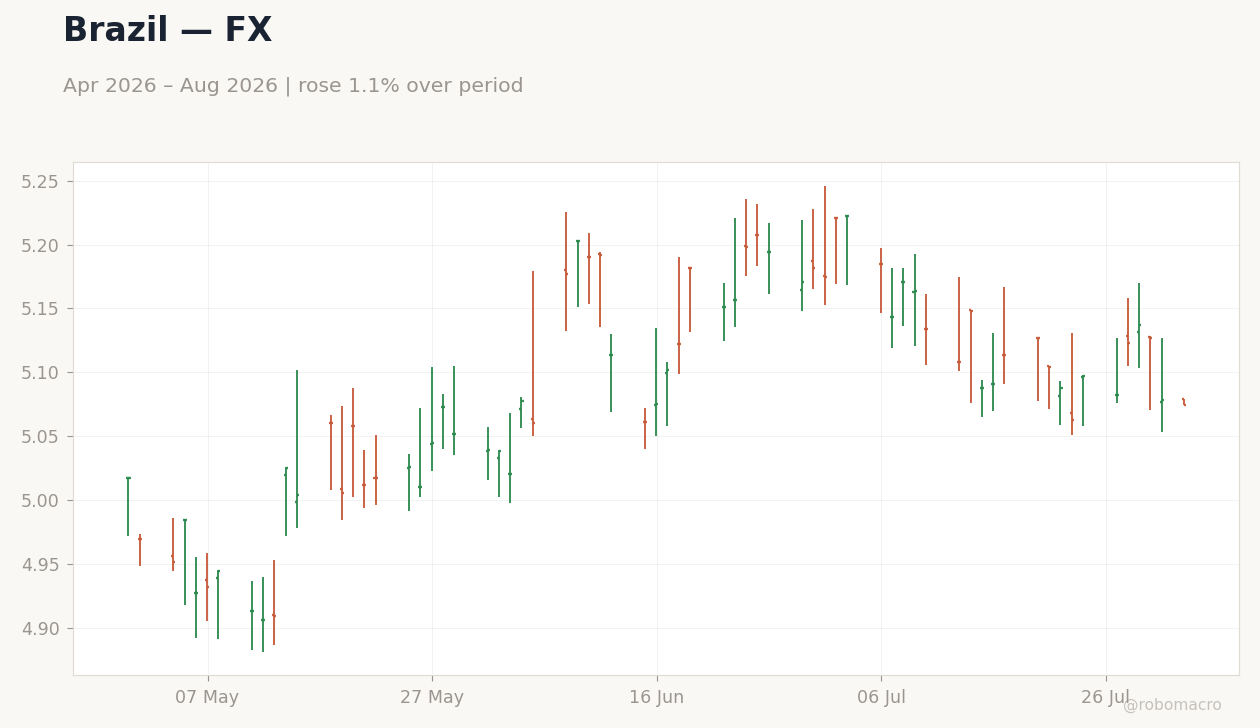
EM FX moves were mixed during the week. USD/ZAR declined 1.6% to 16.43 and USD/MXN fell 1.1% to 17.33, reflecting commodity resilience and local bond yield differentials. USD/BRL edged 0.1% lower to 5.0747 amid ongoing labor market strength, while USD/CNY eased 0.4% to 6.7448. USD/TRY rose 0.3% to 47.49 as the local curve remained inverted with 2s10s at -691bp, highlighting divergent pressures across high-yield EM.

Bitcoin & Crypto

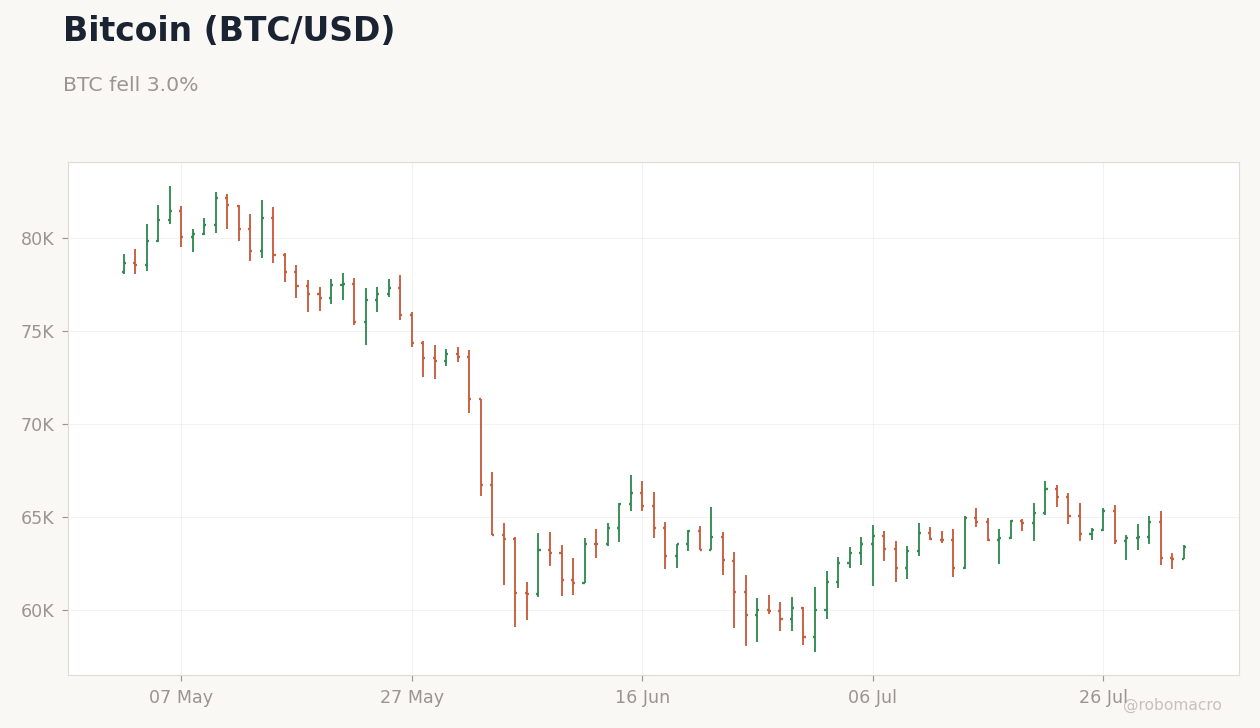
Bitcoin fell 3.0% to $63,366. Daily closes showed an initial rise from 63,908 on Wednesday to 64,725 on Thursday before reversing lower to 62,814 on Friday and 62,763 on Saturday, leaving crypto rangebound amid market volatility. Ethereum declined 3.8% to $1,879, Solana dropped 4.0% to $74, and XRP lost 2.8% to $1. The sector stayed within recent ranges as broader risk sentiment remained tentative.

Week Ahead

The economic calendar is light next week with no major central bank rate decisions scheduled. Focus will remain on incoming data shaping rate differentials, particularly any trade balance releases that could influence EM FX. Crypto markets will continue monitoring regulatory developments and ETF flows, though no specific protocol upgrades or deadlines are highlighted. Overall positioning stays data-dependent with attention on curve shape implications across G10 and EM.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Markets in ReviewCommodities
Commodities Chart 1
Commodities Chart 2
Commodities Chart 3
Commodities Chart 4

Week in Review

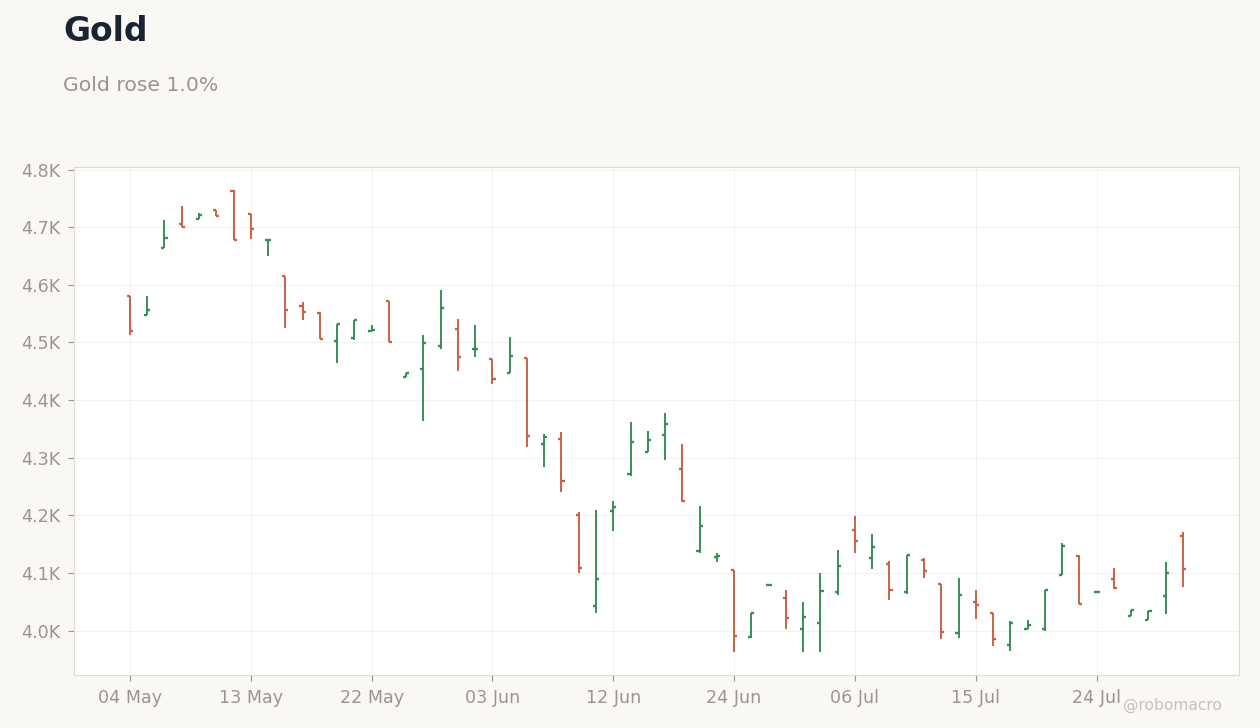
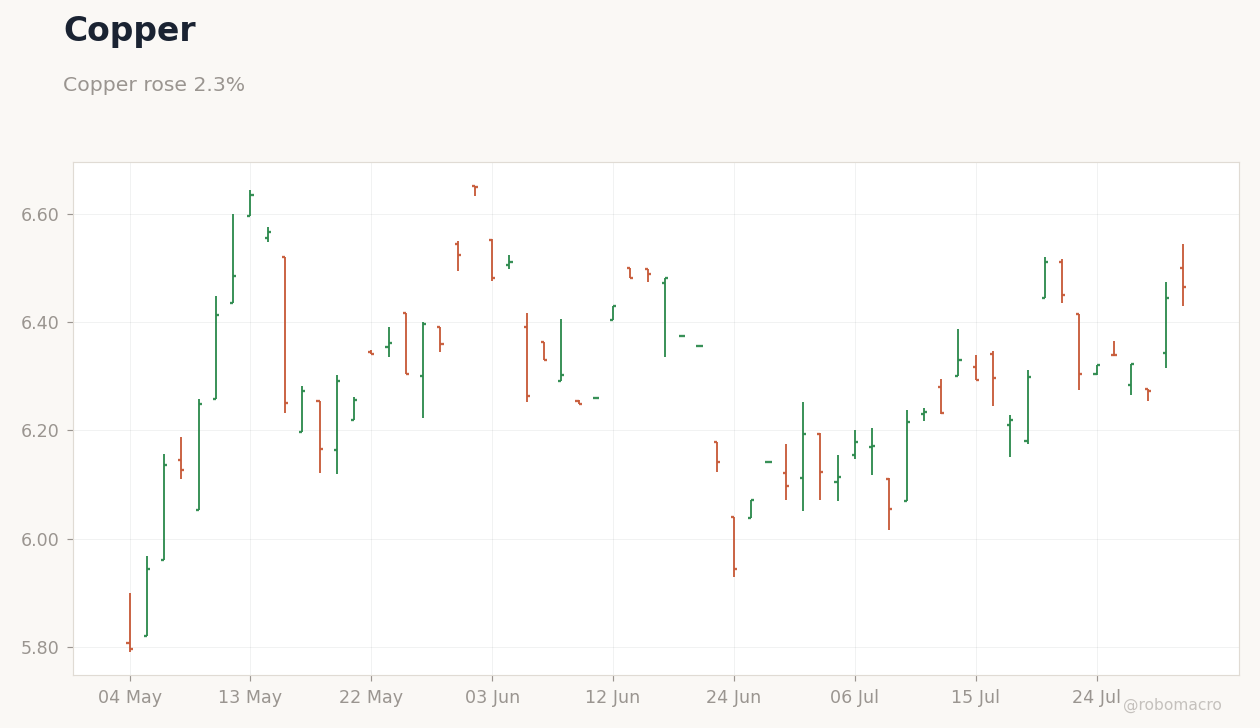
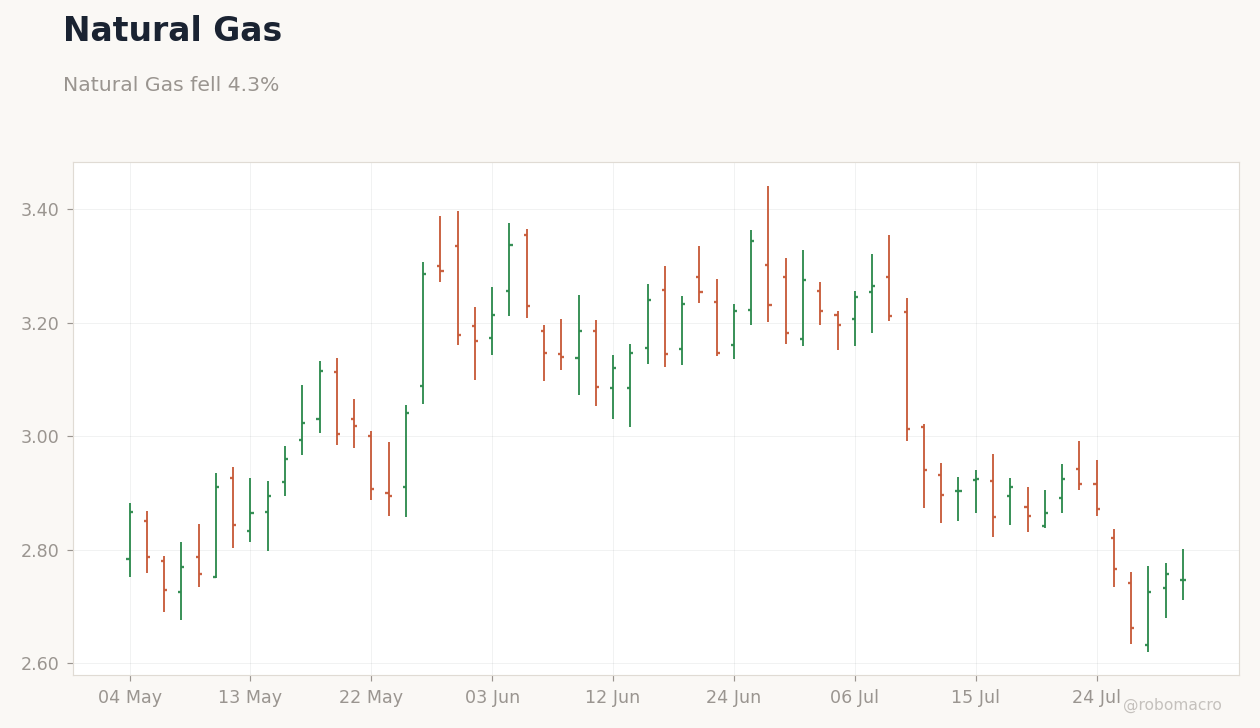
Brent Crude was the biggest mover, falling 6.9% week-over-week to 90.12. WTI Crude declined 5.2% to 84.67 though daily closes showed recovery from 79.3 on Tuesday to 84.5 on Wednesday before closing at 84.7 on Friday. Natural Gas fell 4.3% to 2.75 after rising from 2.6620 on Tuesday to 2.7580 on Thursday. Gold rose 1.0% to 4107.00, advancing from 4,036 on Tuesday to 4,100 on Thursday and 4,107 on Friday. Silver declined 1.5% to 57.79 after reaching 58.8 on Thursday. Copper gained 2.3% to 6.47 while Wheat fell 5.7% to 639.25, illustrating divergent trends across energy, metals, and agriculture.

Energy Complex

WTI Crude closed at 84.67 after a 5.2% weekly decline while Brent Crude settled at 90.12 after a 6.9% drop. Natural Gas ended at 2.75 following a 4.3% weekly loss. The energy complex reflected ongoing supply adjustments amid geopolitical considerations in key producing regions. OPEC+ policy signals remained a central theme influencing market positioning even as broader demand signals stayed mixed. These developments kept volatility elevated across the complex.

Metals & Ags

Gold closed at 4107.00 after a 1.0% weekly gain while Silver ended at 57.79 after a 1.5% decline, pushing the gold-silver ratio higher. Copper rose 2.3% to 6.47, serving as a constructive growth signal despite supply challenges facing the world’s largest producer. Wheat fell 5.7% to 639.25 on the week but remained up 8.3% month-to-date and 26.2% year-to-date. These moves highlighted continued differentiation within metals between precious and industrial segments as well as selective resilience in agricultural commodities.

Week Ahead

The economic calendar for next week has no commodity-relevant events, with no EIA crude or gas inventories releases, no OPEC meetings, no China PMI or industrial data, no US CPI print, and no central bank meetings that would directly affect commodity currencies such as CAD, AUD, or BRL. In the absence of scheduled data, non-calendar risks will dominate. Geopolitical developments, weather patterns, and OPEC diplomacy are expected to remain the primary drivers for commodity price action. Market participants will monitor these factors closely for directional cues across energy, metals, and agriculture.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Markets in ReviewFX, Commodities & Crypto
Foreign Exchange
Week-on-week, month-to-date, year-to-date. WoW is the change over the seven calendar days to the latest close. Source: public market data.
PairLevelWoWMTDYTD
DXY99.80-1.6%-1.1%+1.4%
EUR/USD1.1546+1.3%0.0%-1.7%
GBP/USD1.3486+1.0%0.0%+0.1%
USD/JPY157.12-4.0%0.0%+0.2%
AUD/USD0.7056+0.9%0.0%+5.7%
NZD/USD0.5897+1.7%0.0%+2.4%
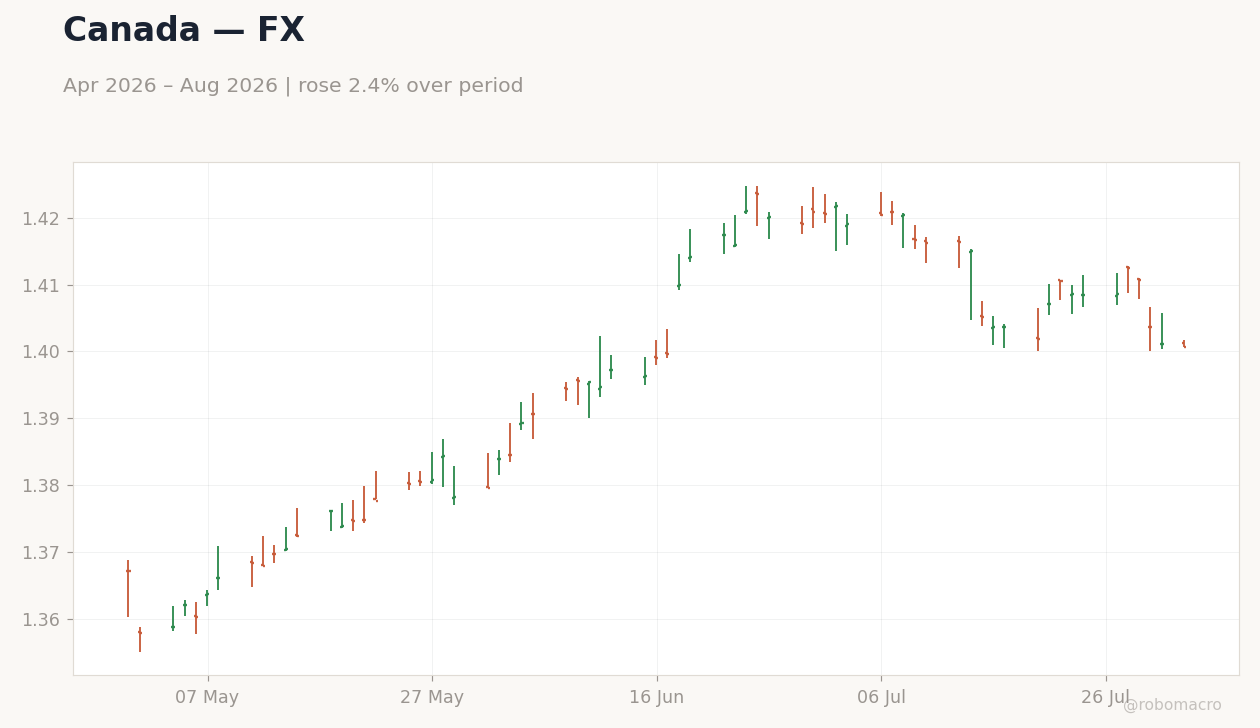
USD/CAD1.4004-0.6%0.0%+2.1%
USD/CHF0.8067-1.2%0.0%+1.9%
USD/CNY6.7448-0.4%0.0%-3.6%
USD/BRL5.0747-0.1%0.0%-8.0%
USD/MXN17.33-1.1%0.0%-3.7%
USD/INR95.39-1.2%0.0%+6.0%
USD/ZAR16.43-1.6%0.0%-0.7%
USD/TRY47.49+0.3%0.0%+10.4%
Commodities
Week-on-week, month-to-date, year-to-date. WoW is the change over the seven calendar days to the latest close. Source: public market data.
CommodityLevelWoWMTDYTD
WTI Crude84.67-5.2%+23.3%+47.7%
Brent Crude90.12-6.9%+25.5%+48.4%
Gold4107.00+1.0%-0.1%-4.8%
Silver57.79-1.5%-4.7%-18.1%
Copper6.47+2.3%+5.7%+14.6%
Natural Gas2.75-4.3%-14.1%-24.1%
Wheat639.25-5.7%+8.3%+26.2%
Iron Ore98.00-0.4%-0.2%-8.6%
Crypto Assets
Week-on-week, month-to-date, year-to-date. WoW is the change over the seven calendar days to the latest close. Source: public market data.
AssetLevelWoWMTDYTD
Bitcoin$63,366-3.0%+1.0%-28.6%
Ethereum$1,879-3.8%+1.9%-37.4%
Solana$74-4.0%+2.3%-42.0%
XRP$1-2.8%+2.0%-42.5%

DXY fell 1.6% to 99.80 as USD/JPY dropped 4.0% to 157.12, the largest move. EUR/USD rose 1.3% to 1.1546 while GBP/USD gained 1.0% to 1.3486. NZD/USD led G10 advances, up 1.7% to 0.5897, outpacing AUD/USD’s 0.9% gain to 0.7056. USD/CAD eased 0.6% to 1.4004 and USD/CHF declined 1.2% to 0.8067. In emerging markets, USD/ZAR fell 1.6% to 16.43 and USD/MXN dropped 1.1% to 17.33, while USD/TRY edged up 0.3% to 47.49. USD/CNY slipped 0.4% to 6.7448 amid broad USD softening. Next week, attention centers on upcoming central-bank speeches and inflation releases for USD direction.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
United States
Market Scorecard
AssetLevelWoW
S&P 5007489.72+1.0%
Nasdaq 10028274.2+0.8%
Dow Jones52485.03+0.5%
Russell 20002931.34-0.6%
USD/JPY157.16-4.0%
EUR/USD1.15+1.3%
GBP/USD1.35+1.0%
Gold4107.0+0.8%
WTI Crude84.67+2.5%
Bitcoin63384.14-3.0%
Chart 1
Chart 2
Chart 3
Chart 4
  • Durable goods orders rose modestly month-over-month, missing consensus and extending the prior decline, confirming capital spending softness.
  • Federal Reserve held the policy rate steady with multiple dissents, underscoring data dependence amid above-target inflation.
  • S&P 500 closed the week at 7489.72 for a 1.03% net gain while the 10-year Treasury yield eased.
  • WTI crude advanced after a 2.49% weekly gain, reinforcing the energy impulse.
  • We forecast +96k nonfarm payrolls for the Jul 2026 report (due Aug 7; 80% band +61k to +285k), unemployment at 4.2% — RoboMacro model ensemble.

Week in Review

Durable goods data disappoints on capital spending. Durable goods orders rose modestly month-over-month against consensus and after a prior decline, while the ex-transportation component increased less than expected. The Dallas Fed Manufacturing Index offered only marginal regional support. These figures arrived alongside a soft ADP employment change and a goods trade balance that narrowed less than consensus.

Labor market and housing prints show mixed resilience. S&P/Case-Shiller home prices accelerated year-over-year, beating expectations, while Conference Board consumer confidence declined. Weekly jobless claims came in below consensus. The configuration left the unemployment rate steady and reinforced the mid-expansion narrative.

Policy and market reaction anchor the week. The Federal Reserve held the policy rate steady with three dissenters favoring a hike. Equity indices posted a net gain in the S&P 500 despite intraday swings, while the 10-year Treasury yield closed lower. WTI crude finished higher after volatility tied to inventory draws. These moves extended the oil-driven tightening of financial conditions.

Cross-border and cycle context remains intact. The week’s data releases aligned with the prior three-week pattern of selective US resilience offset by energy-price pressure. GDP growth held at the prior advance estimate while the GDP price index rose. Markets therefore enter the next period with the same data-dependent stance that has kept the policy rate path unchanged since mid-year.

Fed Watch

The Federal Reserve held the policy rate steady with three hawks dissenting in favor of a hike. Chair commentary emphasized data dependence given the year-over-year CPI print and unemployment rate. No shift in forward guidance emerged from the decision or accompanying statement. The durable goods miss and Case-Shiller beat together left the medium-term rate path anchored to incoming inflation and activity data. Speakers maintained the stance that above-target inflation reinforced by energy prices warrants patience. The configuration aligns with the data-dependent posture carried forward from prior weeks.

Data Review

Durable goods orders rose modestly month-over-month against consensus and after a prior decline, while orders excluding transportation increased less than expected. The Dallas Fed Manufacturing Index edged higher. ADP employment change printed softly. The advance goods trade balance narrowed less than consensus. Wholesale inventories rose more than forecast, while retail inventories ex-autos fell. S&P/Case-Shiller home prices accelerated year-over-year, beating expectations. Conference Board consumer confidence slipped. Core PCE rose less than the prior reading, and the PCE price index increased year-over-year. These releases together signal continued mid-cycle expansion with above-target inflation reinforced by energy costs, leaving the Federal Reserve’s rate path data-dependent into the second half.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Data Review: Actual vs Consensus
DateCtryEventPrior Cons.Actual
Mon 27USDurable Goods Orders Month-4.02.50.30
Mon 27USDurable Goods Orders exclu1.80.800.60
Mon 27USDurable Goods Orders exclu-4.3-0.30
Mon 27USNon Defense Goods Orders e1.90.800.90
Mon 27USDallas Fed Manufacturing I0-1.3
Mon 27US2-Year Treasury Note Aucti4.2-4.3
Mon 27US6-Month Treasury Bill Auct3.8-3.9
Mon 27US3-Month Treasury Bill Auct3.7-3.8
Mon 27US5-Year Treasury Note Aucti4.2-4.4
Tue 28USADP Employment Change Week16K-15K
Tue 28USGoods Trade Balance Advanc-105.9bn-100.0bn-101.5bn
Tue 28USRetail Inventories excludi0.20--0.20
Tue 28USWholesale Inventories Mont0.300.200.30
Tue 28USRedbook Retail Sales Year-7.8-8.3
Week Ahead: Key Releases
DateReleasePriorCons.
2026-08-03ISM Manufacturing PMI Index53.354.0
2026-08-03ISM Manufacturing Employment Level49.7-
2026-08-04Exports Level317.7bn-
2026-08-04Imports Level395.3bn-
2026-08-04Trade Balance-77.6bn-73.0bn
2026-08-04JOLTs Job Openings Level7.6mn7.2mn
2026-08-04Factory Orders Month-over-Month-1.30.50
2026-08-04API Weekly Crude Oil Stocks3.3mn-
2026-08-05MBA 30-Year Mortgage Rate6.8-
2026-08-05ADP Employment Change98K75K
Chart 5
Chart 6
Chart 7
Chart 8

The Week Ahead

Monday brings the ISM Manufacturing PMI alongside the ISM Manufacturing Employment Level. Tuesday features the trade balance and JOLTs job openings. Factory orders are also due. Wednesday includes ADP employment change and the services sector PMI. EIA crude and gasoline inventory prints will also arrive. Thursday offers initial jobless claims and any revisions to prior data. Central bank speakers remain limited, keeping focus on the data flow and its implications for the September policy meeting. The releases will test whether the mid-expansion resilience observed this week persists.

Risks & Themes

The durable goods miss shifts the growth outlook modestly lower while the oil rebound keeps inflation risks tilted upward. Upside scenarios center on continued housing price gains supporting consumer spending. Downside risks include further softening in capital goods orders and any escalation in energy-driven price pressures. Market positioning shows limited volatility after the equity advance, yet the hawkish dissents at the FOMC meeting signal potential for earlier tightening if inflation reaccelerates. Flow data from the week indicate rotation out of small caps, with the Russell 2000 declining. The configuration leaves room for repricing if next week’s ISM and JOLTs prints surprise to the upside.

Cross-Asset

The S&P 500 advanced 1.03% to close at 7489.72 while the Nasdaq 100 gained 0.84% to 28274.20 and the Dow Jones rose 0.53% to 52485.03; the Russell 2000 declined 0.57% to 2931.34. The 10-year Treasury yield eased and the 2-year note closed lower. EUR/USD rose 1.33% to 1.15 and GBP/USD gained 1.00% to 1.35, while USD/JPY fell 3.95% to 157.16. WTI crude advanced 2.49% to 84.67 after a mid-week surge, and gold rose 0.80% to 4107.00. Equity gains concentrated in the final two sessions after the FOMC hold, while the dollar’s decline reflected reduced supply concerns and the 10-year yield’s net easing occurred despite the oil rebound.

Global Context

Brent crude strength noted in prior weeks continued to influence US financial conditions through the rates and currency channels. EUR/USD strength reflected relative policy divergence after the European data dependence highlighted in prior reports. Trade balance narrowing occurred against a backdrop of resilient US imports. Geopolitical risks around Middle East supply kept WTI supported. These cross-border spillovers reinforce the data-dependent stance at the Federal Reserve into the August window.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Eurozone
Market Scorecard
AssetLevelWoW
Euro Stoxx 506358.01+1.2%
DAX25629.24+1.1%
CAC 408509.64+1.2%
EUR/USD1.15+1.3%
EUR/GBP0.86+0.3%
EUR/JPY181.49-2.6%
Gold4107.0+0.8%
Brent Crude90.12+2.0%
Bitcoin63384.14-3.0%
Chart 1
Chart 2
Chart 3
Chart 4
  • Eurozone July PMI rose, exceeding expectations and confirming expansion above the 50 threshold in both Germany and France.
  • German Ifo Business Climate beat consensus while Spanish headline unemployment fell sharply.
  • European Central Bank policy rate remained on hold with no shift in forward guidance, as incoming data reinforced a data-dependent stance into the second half of 2026.
  • Cross-asset moves showed Euro Stoxx 50 advancing alongside Brent crude rising, illustrating energy-price transmission into euro-area financial conditions.

Week in Review

Expansion signals strengthen amid energy volatility. Eurozone July PMI lifted both German and French readings above the 50 threshold and reversing prior contractionary prints. German Ifo Business Climate improved for a third consecutive month, beating consensus. Spanish headline unemployment fell while French consumer confidence rose. French Q2 GDP growth printed in line with forecasts, avoiding a technical recession as domestic demand and exports rebounded. These prints collectively confirmed selective resilience in the largest euro-area economies during the final week of July 2026.

Labor-market and sentiment data offset earlier softness. Unemployment benefit claims in France dropped while German wholesale price trends from prior weeks continued to signal pipeline disinflation. Equity markets reflected the improved tone, with the DAX closing the week higher after a gain. German 10Y Bund yields settled lower amid cooling commodity pressures early in the week. The configuration left the euro-area expansion intact but subject to imported inflation channels.

Market pricing adjusted to mixed global risk sentiment. EUR/USD advanced while EUR/JPY declined. Brent crude volatility dominated daily moves, falling sharply on Monday before rebounding on Wednesday. The through-line across the five trading days was one of data-supported resilience tempered by external energy shocks, keeping central-bank expectations anchored for no near-term policy adjustment.

ECB Watch

No European Central Bank policy decision or minutes were released during the week. Speakers maintained the data-dependent stance, with no alteration to the existing guidance that the policy rate remains appropriate given current inflation and growth readings. German Ifo and Eurozone PMI beats reinforced the view that activity resilience allows the central bank to tolerate the energy-price impulse without immediate adjustment. Spanish unemployment improvement added to evidence that labor-market slack is diminishing slowly, supporting the medium-term rate path that keeps the first cut discounted well into the future. Official communications continued to emphasize monitoring of inflation persistence, with Brent strength cited as a risk factor that could delay any easing. The configuration leaves the deposit rate steady and forward guidance unchanged relative to the prior week.

Data Review

German Ifo Business Climate rose against consensus and prior, marking the strongest reading in three months and pointing to corporate resilience despite elevated energy costs. Eurozone July PMI beat expectations and showed clear rebounds in manufacturing and services sub-indices for both Germany and France. Spanish headline unemployment fell versus consensus and prior, representing the largest single-week decline in the recent series. French Q2 GDP growth printed in line with expectations, though the year-over-year figure eased. French consumer confidence climbed, exceeding the forecast and supporting the view that household spending stabilized in July.

These releases collectively indicate the euro-area cycle remains in mid-expansion, with labor-market improvement and business sentiment gains outweighing earlier GDP contraction prints. The data reinforce a gradual disinflation path at the pipeline level while highlighting that above-target headline inflation, now reinforced by Brent strength, will keep the European Central Bank focused on incoming prints rather than pre-committed easing. German 10Y Bund yields reflected the mixed inflation-growth balance, declining on the day of the Ifo beat yet remaining elevated from levels seen three weeks earlier. Overall, the releases shift the growth outlook modestly higher without altering the medium-term rate path implied by official communications.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Data Review: Actual vs Consensus
DateCtryEventPrior Cons.Actual
Mon 27FIBusiness Confidence4.0-7.0
Mon 27FIConsumer Confidence Index-5.3--5.3
Mon 27DEIFO Business Climate Level85.786.086.6
Mon 27DEIFO Current Conditions87.087.386.5
Mon 27DEIFO Expectations84.384.886.7
Mon 27BE2031 Belgian OLO Governmen--3.1
Mon 27BE2033 Belgian OLO Governmen2.8-3.3
Mon 27BE2035 Belgian OLO Governmen3.5-3.6
Mon 27FR12-Month French BTF Treasu2.7-2.8
Mon 27FR3-Month French BTF Treasur2.4-2.4
Mon 27FR6-Month French BTF Treasur2.6-2.6
Mon 27IEConsumer Confidence Index62.2-61.6
Tue 28FRConsumer Confidence Index84.085.086.0
Tue 28ESUnemployment Rate10.810.79.9
Week Ahead: Key Releases
DateReleasePriorCons.
2026-08-03Retail Sales Month-over-Month1.1-0.50
2026-08-03Retail Sales Year-over-Year1.8-
2026-08-03S&P Global Manufacturing PMI Index-50.7
2026-08-03S&P Global Manufacturing PMI Index-52.5
2026-08-04Unemployment Level Change-29K-20K
2026-08-04Retail Sales Month-over-Month0.200.10
2026-08-05Industrial Production Month-over-Mo-0.100.30
2026-08-05S&P Global Services PMI Index-54.4
2026-08-05S&P Global Services PMI Index--
2026-08-06Factory Orders Month-over-Month1.90.80

The Week Ahead

Monday brings German retail sales month-over-month alongside Spain and Italy S&P Global manufacturing PMI prints. Tuesday features Spanish unemployment level change and Italian retail sales month-over-month. Wednesday highlights French industrial production month-over-month and Spain S&P Global services PMI. Thursday includes German factory orders month-over-month and Italian industrial production month-over-month. Friday delivers German trade balance, exports month-over-month, industrial production month-over-month, and French unemployment rate. These releases will feed directly into Eurozone aggregates and shape the European Central Bank’s assessment of growth momentum ahead of the next policy meeting. Central-bank speakers are scheduled but carry lower market impact than the data prints.

Risks & Themes

This week’s data shift the outlook toward modestly firmer growth while leaving inflation risks tilted higher through the energy channel. Upside scenario centers on sustained PMI above the 50 threshold and further unemployment declines that could support euro-area equities. Downside scenario involves Brent crude extending gains, transmitting into higher German 10Y yields and pressuring EUR/USD. Market positioning shows limited net long exposure in euro-area equities after the weekly advance, suggesting room for further upside on positive surprises. Volatility remains elevated in commodities, with daily Brent swings exceeding 4% on two occasions, raising the probability of sharp cross-asset repricing. Flow considerations point to safe-haven demand into German Bunds on any renewed Middle East supply concerns.

Cross-Asset

Euro Stoxx 50 rose on the week while the DAX gained and CAC 40 advanced. German 10Y Bund yields closed lower from the Monday session amid safe-haven flows on Tuesday and Thursday. EUR/USD climbed, with daily gains on Thursday and Friday offsetting an early-week decline. EUR/JPY fell after closing as high as on Thursday. Brent crude posted a net gain, swinging from a sharp drop on Monday to a surge on Wednesday. Gold advanced, while Bitcoin declined. The cross-asset configuration showed equities and the euro benefiting from positive data surprises while commodity volatility transmitted directly into yield and currency moves.

Global Context

Brent crude strength over the past seven days transmitted directly into euro-area inflation expectations and financial conditions. Global equity resilience, with limited net changes in major indices outside the euro area, supported risk appetite that lifted Euro Stoxx 50. Trade dynamics showed no material shift in the last week, though prior energy-price impulses continued to re-anchor developed-market rate paths. Geopolitical risks around maritime supply routes kept commodity volatility elevated, directly affecting EUR/JPY. Cross-border spillovers from non-euro-area data remained contained, leaving euro-area markets focused on domestic releases rather than external shocks.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Japan
Market Scorecard
AssetLevelWoW
Nikkei 22564362.02-0.9%
USD/JPY157.16-4.0%
EUR/JPY181.49-2.6%
GBP/JPY211.91-3.0%
Gold4107.0+0.8%
Brent Crude90.12+2.0%
Bitcoin63384.13-3.0%
Chart 1
Chart 2
Chart 4
  • Suspected coordinated intervention drove USD/JPY lower week-over-week, reversing multi-week yen weakness.
  • Bank of Japan held the policy rate steady while releasing an unchanged quarterly outlook, with Governor Ueda speech following the decision.
  • July consumer confidence rose, beating consensus and confirming resilient household sentiment ahead of the decision.

Week in Review

Yen Reversal on Intervention Signals The yen strengthened sharply after repeated official warnings, with USD/JPY closing the week at 157.16. The move coincided with reports of joint Tokyo-Washington action. Cross rates followed, with EUR/JPY declining week-over-week to 181.49 and GBP/JPY falling to 211.91. Equity markets reflected the volatility, as the Nikkei 225 posted a net weekly decline despite a rebound on July 31.

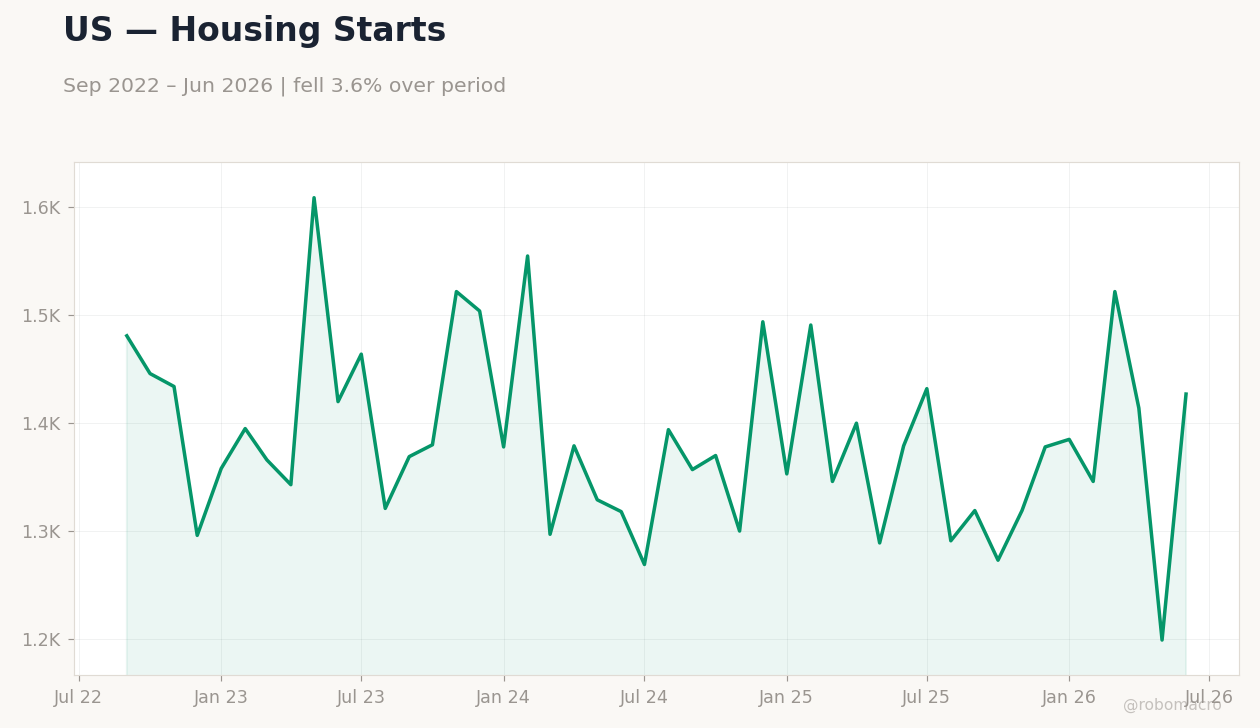
Data Resilience Amid Policy Hold The Bank of Japan maintained the policy rate at its prior level on July 30, accompanied by an unchanged quarterly outlook report. Consumer confidence rose versus consensus, while the unemployment rate held steady. Industrial production and retail sales data released alongside the decision showed mixed momentum but did not alter the hold decision. Housing starts year-over-year data due the same evening added a further domestic demand lens without shifting the immediate policy stance.

JGB Yield and Commodity Backdrop Ten-year JGB yields ended the week lower after trading higher mid-week, while the two-year yield moved higher. Brent crude closed higher after swinging through a wide range, adding imported price pressure. Gold rose week-over-week amid safe-haven flows tied to the yen move. Bitcoin finished lower for the week.

Through-Line Across the Five Days The arc began with positioning ahead of the July 30 decision, shifted to yen strength on intervention speculation, and concluded with a partial equity recovery once the hold was confirmed. No major consensus misses emerged in the activity prints, yet the combination of stronger consumer confidence and currency intervention reinforced the gradual normalisation path without accelerating it. The data therefore suggest that domestic demand indicators remain consistent with the Bank of Japan’s existing framework even as external pressures on the yen eased.

BoJ Watch

The Bank of Japan held the policy rate steady on July 30 and issued an unchanged quarterly outlook, with no alteration to forward guidance on the pace of normalisation. Governor Ueda’s July 31 speech followed the decision and reiterated data dependence without introducing new thresholds. July consumer confidence and stable unemployment supported the committee’s assessment that price pressures remain contained enough to avoid an immediate adjustment. The minutes scheduled for release next week will provide the first detailed record of how members weighed yen volatility against the easing in corporate services inflation. Household spending prints due next week will offer the next direct read on whether consumption trends remain aligned with the gradual rate path outlined in the latest outlook.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Data Review: Actual vs Consensus
DateCtryEventPrior Cons.Actual
Mon 27JPCoincident Index Final118-118
Mon 27JPLeading Economic Index Fin116117116
Tue 28JPBoJ JGB Purchase Level--""
Wed 29JPForeign Bond Investment Le-723.7bn--811.4bn
Wed 29JPForeign Stock Investment L-81.9bn-912.1bn
Wed 29JP2-Year Japanese Government1.4-1.5
Wed 29JP3-Month Treasury Bill Auct0.99-1.0
Thu 30JPConsumer Confidence Index33.834.234.9
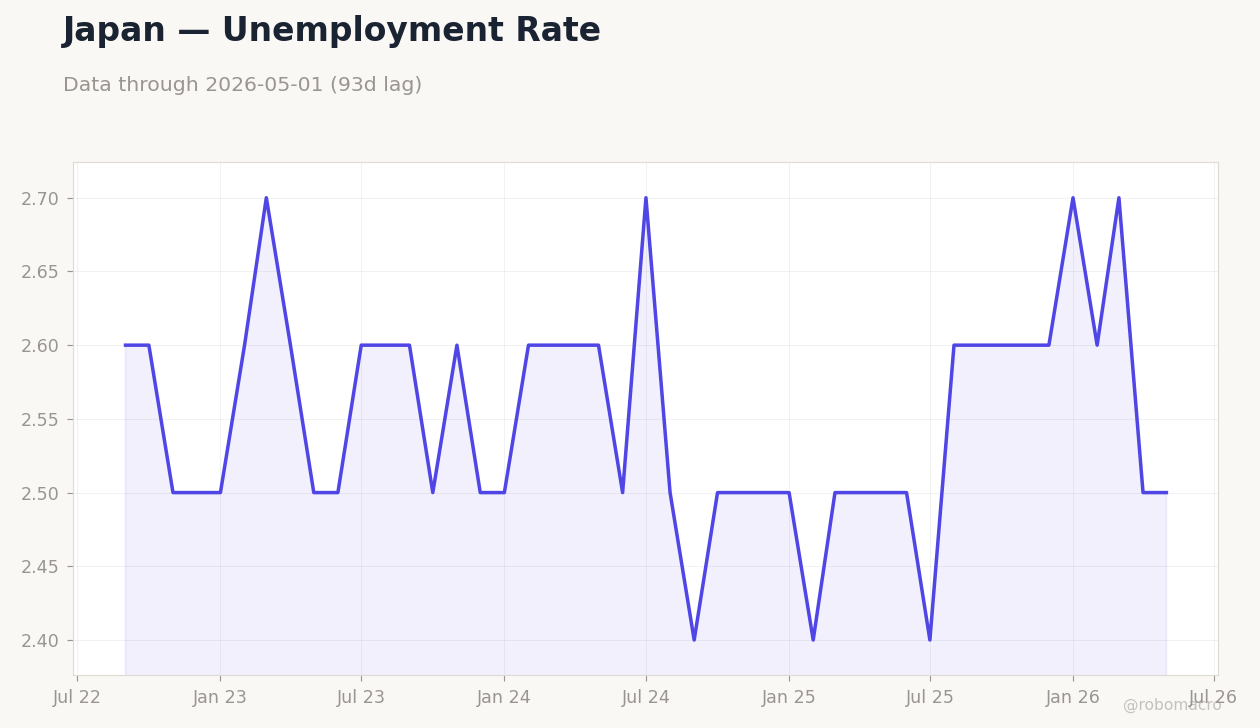
Thu 30JPUnemployment Rate2.52.52.5
Thu 30JPJobs/Applications Ratio1.21.21.2
Thu 30JPTokyo CPI Year-over-Year1.7-2.0
Thu 30JPTokyo Consumer Price Index1.9-2.0
Thu 30JPTokyo Core CPI Year-over-Y1.61.71.9
Thu 30JPIndustrial Production Mont0.100.701.3
Week Ahead: Key Releases
DateReleasePriorCons.
2026-08-04BoJ Monetary Policy Meeting Minutes--
2026-08-06Household Spending Month-over-Month3.7-
2026-08-06Household Spending Year-over-Year-0.400.90
2026-08-09BoJ Summary of Opinions Level--
2026-08-09Current Account Balance3968.0bn-

The Week Ahead

Monday brings no major Japanese releases, allowing markets to absorb the prior week’s intervention signals. Tuesday’s Bank of Japan Monetary Policy Meeting Minutes will detail internal discussion around the July 30 hold and any references to currency conditions. Thursday features household spending month-over-month and year-over-year prints, which will test whether the July consumer confidence beat translates into actual consumption. Sunday’s BoJ Summary of Opinions and current account balance release will round out the week with additional colour on policy views and external balances. These releases matter for the rate path because they will clarify whether domestic demand momentum supports the existing gradual normalisation stance or requires recalibration ahead of upcoming decisions. The data therefore suggest that officials will continue to monitor consumption and external accounts closely before any further adjustment.

Risks & Themes

The yen’s rapid reversal highlights the risk that renewed intervention could re-anchor financial conditions tighter than the data alone would imply, potentially slowing export momentum in coming quarters. Upside scenarios centre on sustained household spending strength that would allow the Bank of Japan to maintain its gradual path without external pressure. Downside scenarios involve a reacceleration in oil prices that could lift imported inflation and force faster normalisation than currently signalled. The data therefore suggest that the market may be underweighting the interaction between currency stability and the consumption cycle when assessing the timing of future policy steps.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Canada
Market Scorecard
AssetLevelWoW
S&P/TSX35226.1-1.0%
USD/CAD1.4-0.6%
EUR/CAD1.62+0.8%
WTI Crude84.67+2.5%
Natural Gas2.75-0.7%
Gold4107.0+0.8%
Brent Crude90.12+2.0%
Bitcoin63380.34-3.0%
Chart 1
Chart 2
  • Canada’s May GDP rose month-over-month, beating consensus after the prior print and reinforcing evidence of selective resilience.
  • The Bank of Canada Market Participants Survey identified US trade tensions as the leading risk to growth while minutes revealed internal divisions on the durability of the rebound.
  • The policy rate held steady with June CPI above target, leaving officials data-dependent ahead of the next decision.

Week in Review

GDP Outperformance Anchors Resilience Narrative Canada’s May GDP expanded month-over-month, surpassing consensus following the prior reading and confirming activity held firmer than expected through late spring.

Trade Tensions Dominate Survey Sentiment The Bank of Canada Market Participants Survey released July 27 flagged US trade tensions as the top economic risk, with respondents highlighting efficiency losses from resource misallocation amid ongoing tariff threats.

Equity and Currency Moves Reflect Mixed Signals The S&P/TSX posted a net decline while USD/CAD eased over the same period.

Energy Prices Drive Intraday Volatility WTI crude rose to 84.67 by July 31 and Brent crude moved higher, illustrating commodity swings that offset softer global demand signals.

Yield Curve Flattens Modestly Canada’s 10-year government yield declined while the 2-year yield edged up, consistent with markets pricing contained inflation.

Minutes Expose Policy Caution Bank of Canada minutes released July 30 showed officials split on the rebound’s durability, with mixed growth signals cited as reason for continued data dependence at the current policy rate.

Labor and Housing Data Provide Secondary Support Housing starts benefited modestly from lower borrowing costs and youth employment gains appeared in earlier prints, helping sustain consumer spending despite external tariff noise.

Cross-Asset Positioning Remains Selective Gold rose while Bitcoin closed lower, reflecting hedging flows amid trade uncertainty and limited net equity gains through the week.

Broader Cycle Context Holds The data arc confirms the expansion remains intact but tilts tighter through the commodity channel, with no outright contraction signals emerging from domestic releases.

BoC Watch

The Bank of Canada held the policy rate steady with June CPI recorded above target, underscoring the restrictive stance amid above-target inflation. The July 27 Market Participants Survey highlighted US trade tensions as the dominant risk, prompting Governor remarks that tariffs distort resource allocation and reduce efficiency. Minutes released July 30 revealed internal divisions over the durability of the rebound, with officials citing mixed growth signals as justification for sustained data dependence. The May GDP outperformance provides fresh evidence that activity can absorb targeted external pressures without immediate broad contraction. No forward guidance shifts emerged from the survey or minutes, leaving the rate path anchored to upcoming releases on growth sustainability.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Data Review: Actual vs Consensus
DateCtryEventPrior Cons.Actual
Mon 27CABoC Market Participants Su--""
Wed 29CABoC Summary of Deliberatio--""
Thu 30CAAverage Weekly Earnings Ye3.7-3.4
Thu 30CA5-Year Bond Auction3.1-3.2
Fri 31CAGDP Month-over-Month0.600.200.30
Fri 31CAGDP Month-over-Month Preli0.10-0.20
Fri 31CABudget Balance-1.1bn--310.0mn
Fri 31CABudget Balance-29.7bn--1.1bn
Week Ahead: Key Releases
DateReleasePriorCons.
2026-08-04Trade Balance4.2bn3.0bn
2026-08-04S&P Global Manufacturing PMI Index-50.2
2026-08-07Unemployment Rate6.56.5
2026-08-07Employment Change18K15K
2026-08-07Full-Time Employment Change600-
2026-08-07Labor Force Participation65.0-
2026-08-07Part-Time Employment Change18K-
2026-08-07Ivey PMI Seasonally Adjusted56.255.4

The Week Ahead

Attention centers on the August 4 Trade Balance release, where consensus expects a surplus after the prior figure, offering an early read on export resilience under tariff pressure. The same day’s S&P Global Manufacturing PMI is projected at a level that will test whether factory activity remains in expansion territory. On August 7 the Unemployment Rate is expected to hold steady alongside a modest Employment Change, data that will directly inform assessments of labor-market slack ahead of the next policy decision. Full-time and part-time employment components will be watched for signs of broadening weakness or continued resilience. The Ivey PMI, consensus below the prior reading, will provide a services-side gauge of demand momentum. These prints matter for the Bank of Canada rate path because they will clarify whether the May GDP surprise marks a durable upturn or a temporary rebound. Officials have signaled eight decision dates for 2027, reinforcing the steady cadence of data dependence into coming quarters. Any material downside surprise in employment or PMI readings could tilt the balance toward additional accommodation while upside surprises would support the current hold.

Risks & Themes

US trade tensions remain the dominant external risk, with the survey confirming they impose larger costs on growth than recent tariff measures alone. Oil price volatility could re-anchor financial conditions tighter if geopolitical supply risks reassert. Internal trade barriers continue to weigh on productivity more than external tariffs according to recent analysis, suggesting domestic policy adjustments may be needed to unlock efficiency gains. The minutes split on rebound durability highlights upside and downside scenarios around growth sustainability, with markets potentially underweighting the persistence of above-target inflation. A sequence of soft labor prints next week would challenge the resilience narrative while stronger trade and PMI outcomes would reinforce the case for holding the policy rate.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Mexico
Market Scorecard
AssetLevelWoW
IPC Bolsa66936.99-0.3%
USD/MXN17.33-0.6%
EUR/MXN19.99+0.6%
WTI Crude84.67+2.5%
Silver57.79-1.2%
Gold4107.0+0.8%
Brent Crude90.12+2.0%
Bitcoin63395.64-3.0%
Chart 1
Chart 2
  • Mexico's external accounts showed resilience as manufacturing exports held firm amid global energy volatility.
  • USD/MXN declined while IPC Bolsa posted a modest weekly loss as markets absorbed mixed commodity moves.
  • Policy rate and inflation trajectory left the restrictive stance intact ahead of the next decision.

Week in Review

Trade Balance Outperformance Anchors External Accounts Manufacturing exports tied to nearshoring supported external accounts even as WTI crude and Brent crude posted net weekly gains. The data reinforced consumption resilience visible in remittances and kept external accounts firm despite global energy volatility.

Equity and Currency Moves Show Contained Volatility IPC Bolsa closed lower for the week after trading in a narrow range. USD/MXN declined while EUR/MXN finished higher. Short-term rates held steady and long-term yields rose, steepening the curve.

GDP Rebound Expectations Build on Prior Contraction Preliminary second-quarter GDP prints scheduled for release carried expectations of a rebound from the prior contraction. Markets positioned lightly ahead of the figures, with no major Banxico communications altering the steady policy stance. Nearshoring FDI announcements added to manufacturing momentum visible in export data.

Inflation and Rate Path Remain Anchored Inflation remained inside the target band and consistent with the prevailing policy rate. The configuration left forward guidance unchanged ahead of the upcoming decision, with data dependence the dominant theme across the five-day period.

Banxico Watch

Banco de Mexico left the policy rate unchanged throughout the week, with the latest inflation signal providing no impetus for adjustment. No officials spoke, and the minutes from the prior meeting offered no shift in the restrictive stance. The trade surplus and steady peso reinforced the view that external resilience supports holding the rate into the next decision. Data dependence remains the guiding principle, with incoming growth and inflation prints the key inputs for upcoming deliberations. The configuration leaves the rate path unchanged absent material deviations in the flash GDP or subsequent inflation releases.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Data Review: Actual vs Consensus
DateCtryEventPrior Cons.Actual
Mon 27MXTrade Balance2.3bn2.3bn4.1bn
Thu 30MXGDP Growth Quarter-over-Qu-0.601.31.5
Thu 30MXGDP Growth Year-over-Year 0.201.52.2
Week Ahead: Key Releases
DateReleasePriorCons.
2026-08-03Business Confidence46.3-
2026-08-04Consumer Confidence Index43.8-
2026-08-06Central Bank Interest Rate Decision6.5-
2026-08-07Inflation Rate Month-over-Month-0.27-
2026-08-07Inflation Rate Year-over-Year3.4-
Chart 5

The Week Ahead

Business Confidence will provide the first read on post-GDP sentiment. Consumer Confidence follows and will test whether remittance and trade strength translate into household optimism. The Central Bank Interest Rate Decision carries the highest weight. Inflation Rate Month-over-Month and Year-over-Year prints will directly inform the inflation trajectory into coming quarters. These releases matter because they update the growth and price inputs that shape the restrictive stance ahead of subsequent decisions. Markets will assess whether the data sustain the current policy rate or prompt any recalibration in forward guidance.

Risks & Themes

The trade surplus reduces downside risks to external accounts but leaves the outlook sensitive to oil price swings. Nearshoring inflows continue to support manufacturing yet face potential friction from USMCA tariff alignment discussions. Upside scenarios center on a stronger-than-expected GDP rebound confirming consumption resilience, while downside cases involve any inflation reacceleration that delays easing. The market appears to underweight the persistence of the current CPI level relative to the policy rate, leaving room for data surprises to shift the balance toward a steadier restrictive path.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Brazil
Market Scorecard
AssetLevelWoW
Bovespa177999.0+1.5%
USD/BRL5.07-0.1%
EUR/BRL5.86+1.4%
Vale15.06+1.9%
Petrobras19.4+7.8%
WTI Crude84.67+2.5%
Gold4107.0+0.8%
Bitcoin63387.61-3.0%
Chart 1
Chart 2
  • Brazil’s labor market showed continued resilience.
  • Fiscal metrics pointed to widening imbalances and stronger impulse in Q2.
  • Banco Central do Brasil maintained its policy rate with no new communications during the week.

Week in Review

Tariff announcements and commodity moves pressured assets early. Markets opened under pressure from US tariff measures on Brazilian exports, sending the Bovespa lower while USD/BRL eased. WTI crude declined, weighing on Petrobras.

Fiscal data highlighted mid-week concerns. The H1 primary deficit marked the second-worst outcome on record and the fiscal impulse rose sharply in Q2. The Bovespa recovered some ground even as Petrobras extended losses alongside further declines in WTI.

Labor data provided the clearest domestic signal. The unemployment release confirmed labor-market strength. Equities closed the session lower before rebounding and finishing the period higher for a weekly gain.

Commodity and currency moves stayed linked. WTI crude ended the week higher while USD/BRL finished slightly lower. Petrobras shares rose sharply, outpacing Vale.

External trade frictions persisted. Officials signaled ongoing talks with the US while other bilateral flows offered partial offsets.

BCB Watch

Banco Central do Brasil maintained the policy rate throughout the week with no scheduled communications. The unemployment print reinforced the picture of labor-market strength that has accompanied the current GDP expansion. Fiscal impulse data and the H1 primary deficit added to concerns about near-term inflation pressures. Record tourism revenue underscored consumption resilience. These domestic prints leave the central bank’s data-dependent stance unchanged ahead of the next decision.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Data Review: Actual vs Consensus
DateCtryEventPrior Cons.Actual
Mon 27BRFGV Consumer Confidence88.7-88.3
Mon 27BRBCB Focus Market Readout--""
Tue 28BRCurrent Account Balance-3.2bn-2.5bn-2.3bn
Tue 28BRForeign Direct Investment 8.0bn5.0bn9.1bn
Tue 28BRIPCA Mid-Month Consumer Pr0.410.200.06
Tue 28BRIPCA Mid-Month Consumer Pr4.84.74.5
Wed 29BRNet Payrolls73K115K145K
Thu 30BRIgp-M Inflation Month-over-0.50-1.1-1.2
Thu 30BRBank Lending Month-over-Mo0.60-0.70
Thu 30BRUnemployment Rate5.65.45.4
Thu 30BRBCB National Monetary Coun---
Fri 31BRGross Debt to GDP81.181.581.9
Fri 31BRNominal Budget Balance-163.7bn-133.2bn-166.0bn
Fri 31BRProducer Price Index Month-0.30--0.77
Week Ahead: Key Releases
DateReleasePriorCons.
2026-08-04Industrial Production Month-over-Mo-0.20-
2026-08-05S&P Global Services PMI Index--
2026-08-05Central Bank Interest Rate Decision14.2-
2026-08-06Trade Balance9.8bn-

The Week Ahead

Industrial Production data will provide the first activity read after the latest labor print. Services PMI follows and will test momentum against the prevailing growth outlook. The Banco Central do Brasil Interest Rate Decision will be watched for any shift in forward guidance after recent fiscal figures. Trade Balance data will update the export picture after the tariff announcement. These releases will inform the central bank’s assessment of growth and price pressures.

Risks & Themes

The H1 primary deficit raises the prospect of further fiscal slippage ahead of medium-term targets and could keep inflation risks elevated even as the labor market remains firm. US tariff exposure introduces downside risk to the trade balance and commodity-linked sectors if negotiations stall. Softer activity prints next week could reinforce the view that labor-market strength is decoupling from broader momentum, while firmer outcomes would support the current policy stance. Record tourism inflows and the fiscal impulse point to consumption as the dominant growth channel, yet renewed oil-price volatility could transmit quickly into inflation and external accounts.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Argentina
Market Scorecard
AssetLevelWoW
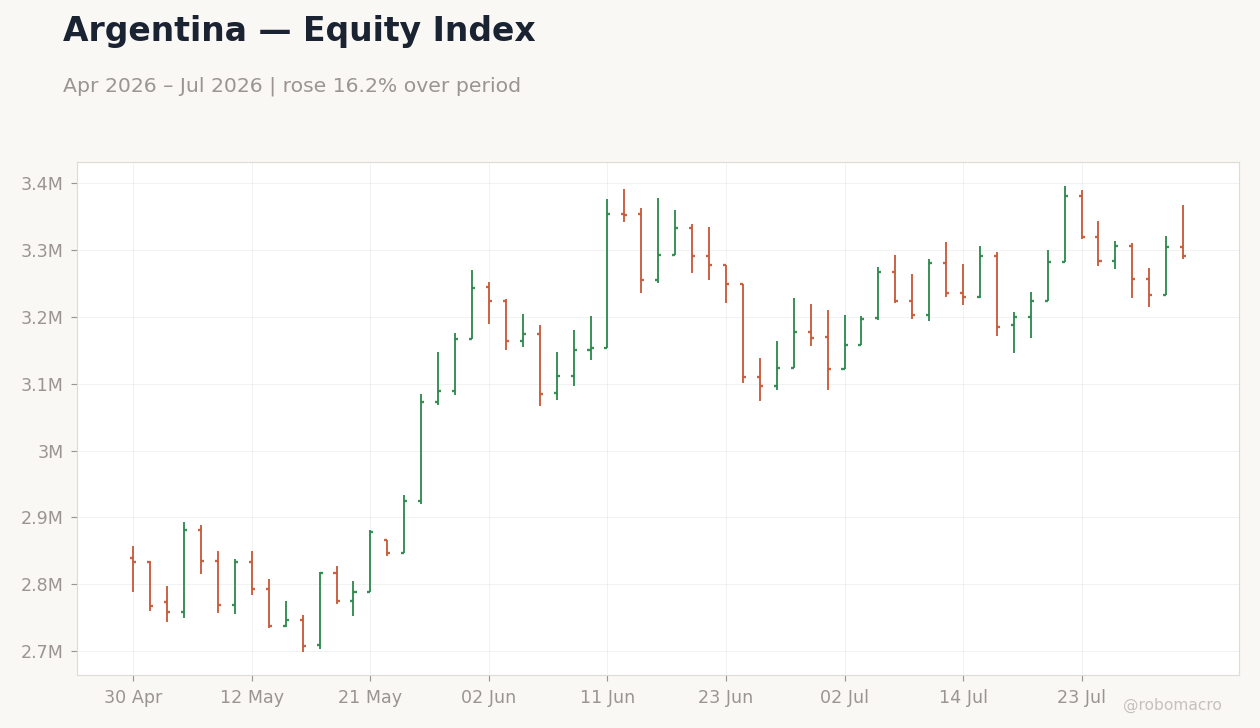
MERVAL3291323.0-0.4%
USD/ARS1485.0-0.7%
EUR/ARS1712.19+0.5%
Gold4107.0+0.8%
Brent Crude90.12+2.0%
Soybean1187.5-1.7%
Bitcoin63393.35-3.0%
Chart 1
Chart 2
Chart 4
  • Recent CPI readings confirmed the slow pace of disinflation and constrained near-term policy flexibility at the Central Bank of Argentina.
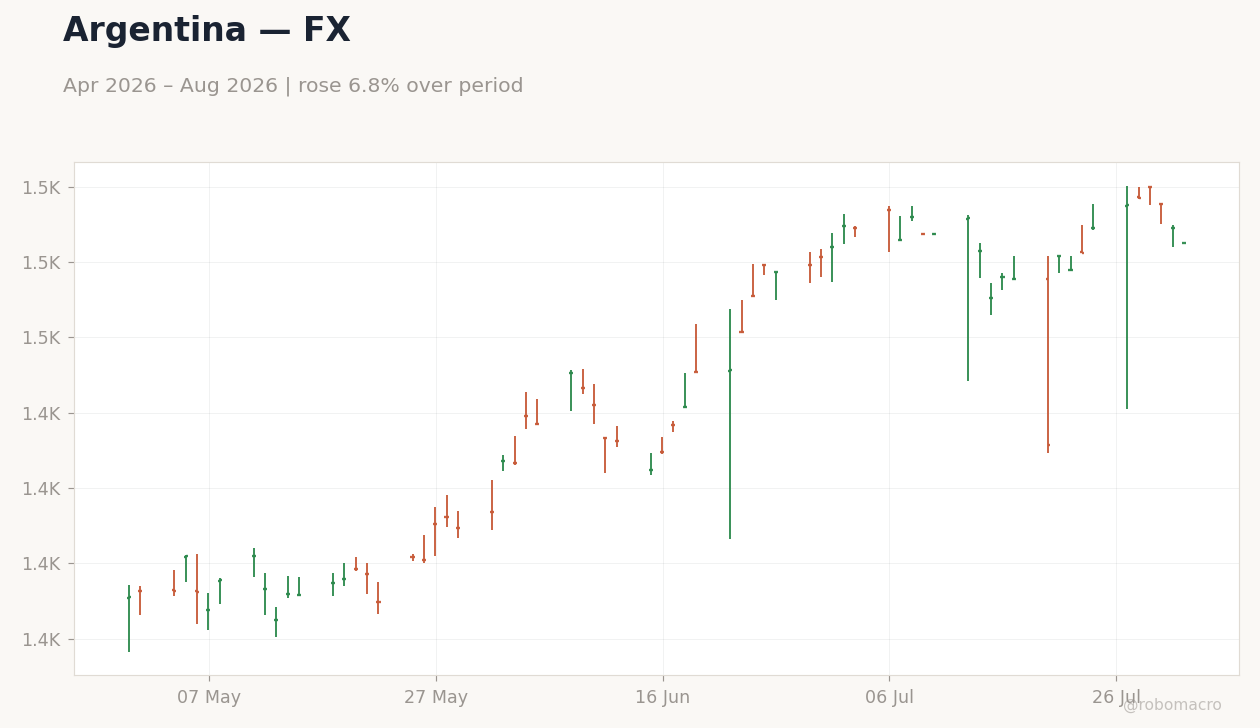
  • MERVAL posted a 0.42% weekly decline to close at 3,291,323 while USD/ARS fell 0.68% to 1,485, reflecting thin trading volumes and limited BCRA intervention amid commodity volatility.
  • IMF program compliance continued to anchor sentiment, with attention on fiscal consolidation targets and the sustainability of the current exchange-rate path.

Week in Review

Equity and FX Movements Argentine equity markets posted a net weekly decline as the MERVAL index fell 0.42% to close at 3,291,323. The official USD/ARS rate eased 0.68% to 1,485 over the five sessions, indicating restrained BCRA spot activity. EUR/ARS finished 0.50% higher at 1,712.19, tracking broader euro strength rather than domestic drivers.

Commodity Influences Brent crude recorded a net 1.99% weekly gain to 90.12 while soybean futures declined 1.74% to 1,187.50, trimming prospective export proceeds that support reserve accumulation. Gold advanced 0.80% to 4,107 and Bitcoin fell 2.98% to 63,393.35, producing mixed external signals for risk assets. These commodity moves occurred against a backdrop of zero scheduled INDEC or BCRA releases, leaving price action driven by global flows and month-end positioning.

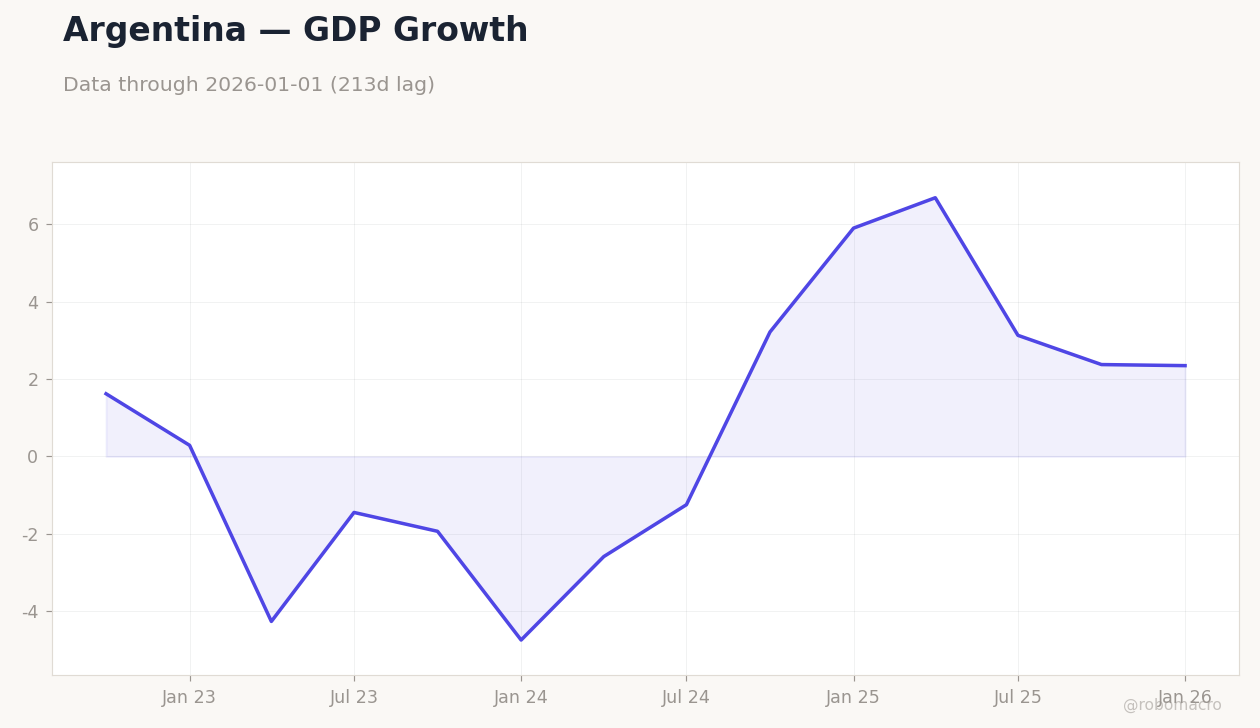
Policy and External Context Recent inflation benchmarks reinforced expectations that the Central Bank of Argentina will maintain caution on any adjustment to the monthly crawl pace. IMF program compliance continued to anchor sentiment after the latest disbursement following the second review, while private analysts incorporated stronger agricultural output into GDP forecasts. Fiscal consolidation advanced through strong demand for Treasury bills, supporting primary surplus targets without new domestic data prints to alter the trajectory.

BCRA Watch

The Central Bank of Argentina released no policy decisions or monetary aggregate updates during the week, leaving the policy rate path dependent on incoming reserve and inflation prints. President Milei’s stated intention to amend the central bank charter and eliminate future monetary financing channels provided the clearest forward signal, consistent with the administration’s primary surplus target for 2026. Recent CPI readings showed no acceleration but also no further moderation, indicating that any easing remains distant. IMF comments highlighted fiscal credibility while probing exchange-rate sustainability, underscoring that reserve accumulation from soybean and crude export flows will determine the timing of any crawl adjustment. The absence of BCRA interventions kept USD/ARS moves contained, reinforcing the data-dependent stance ahead of the next meeting.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com

Calendar data unavailable

The Week Ahead

The calendar lists no Argentine data releases or auctions for the week beginning August 3, shifting attention to global prints that could influence commodity revenues and peso flows. Indonesia’s July inflation rate year-over-year and trade balance on August 3 will provide early signals on emerging-market demand conditions relevant to Argentine export pricing. US activity and inflation data scheduled mid-week will shape broader risk sentiment and potential pressure on EM currencies including the peso. Traders will monitor any follow-up statements from the IMF mission expected in mid-August for guidance on the exchange-rate regime and reserve targets. Soybean export registrations and BCRA reserve updates remain the primary domestic focal points, with agricultural financing announcements from Banco Provincia likely to affect 2026/27 crop financing. The combination of external commodity volatility and the absence of local prints will keep focus on compliance with the IMF program and the sustainability of the current crawl pace ahead of upcoming decisions.

Risks & Themes

The week’s data leave the outlook anchored in fiscal consolidation and export-led reserve gains, yet recent CPI readings highlight the risk that disinflation stalls and delays any policy adjustment. Upside scenarios center on sustained Brent strength above 90 and soybean recovery that would accelerate reserve accumulation and support a stable crawl. Downside risks include renewed commodity weakness that could widen parallel-market spreads and pressure the primary surplus target. The market appears to underweight the interaction between the appreciated real effective exchange rate and limited domestic credit access, which may constrain private-sector adjustment even as net FDI inflows remain supportive. Political noise around regional trade relations adds volatility without altering the core data-dependent policy signal.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Colombia, Chile and Peru
Market Scorecard
AssetLevelWoW
MSCI Chile39.33+0.2%
MSCI Peru85.98+0.6%
USD/COP3202.9-0.4%
USD/CLP930.47-1.6%
USD/PEN3.39+1.6%
Copper6.47+2.0%
Gold4107.0+0.8%
Brent Crude90.12+2.0%
Bitcoin63390.94-3.0%
Chart 1
Chart 2
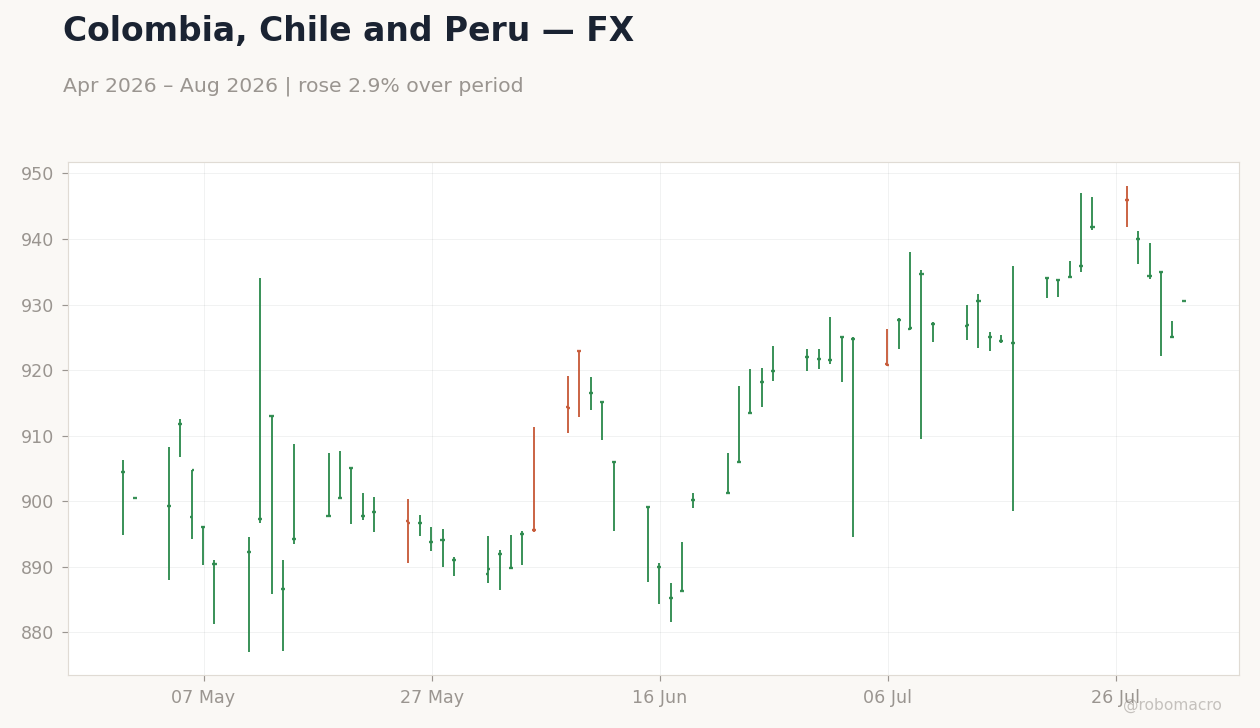
  • BanRep held its policy rate at 12% on July 31, citing peso strength.
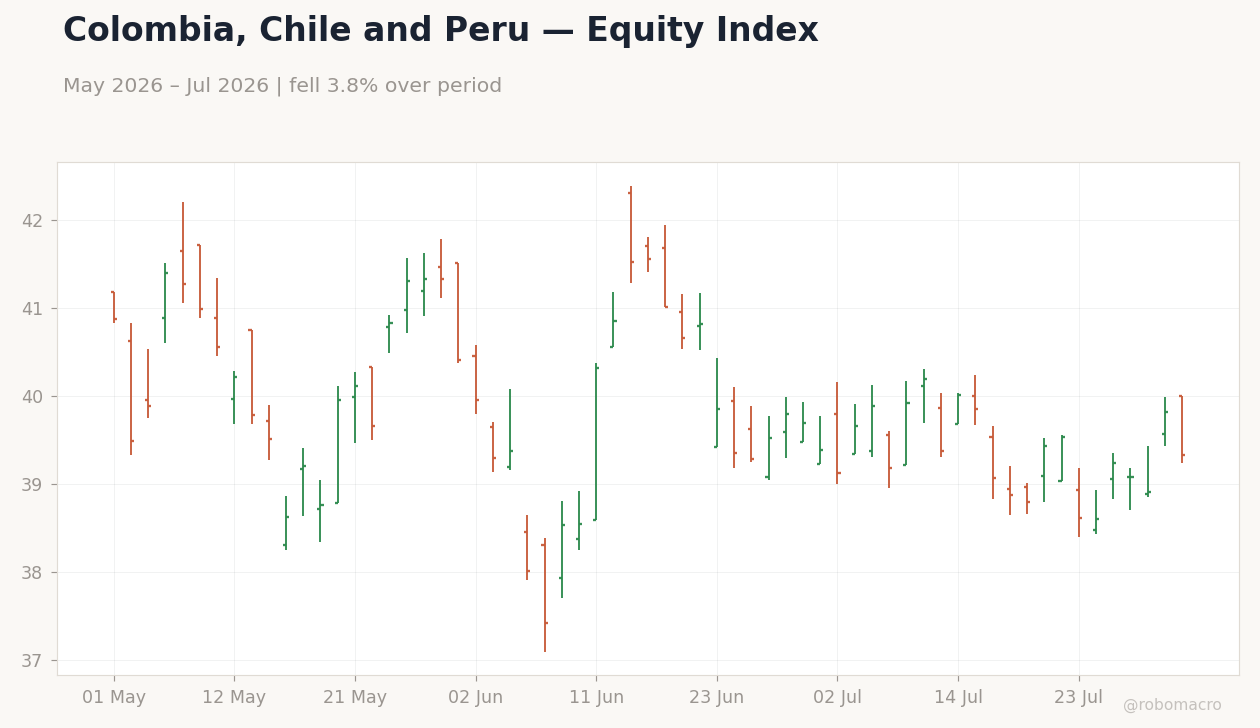
  • BCCh kept its policy rate unchanged at 4.5% across July 28–30 meetings while copper advanced 2.0% week-over-week to 6.47.
  • Brent crude rose 1.99% to 90.12 and gold gained 0.8% to 4107.00, supporting Colombia’s fiscal position while Chile and Peru tracked mixed equity and FX moves.

Week in Review

Policy Divergence Takes Shape Chile’s central bank held its policy rate at 4.5% on July 28, July 29 and July 30, matching consensus and leaving the short-term rate unchanged from the prior level. Colombia’s BanRep held at 12% on July 31 rather than delivering the priced increase, with the decision coinciding with peso strength. Peru recorded no policy meeting and released no major data prints during the week.

Commodity Price Swings Drive Cross-Border Flows Copper climbed 2.0% week-over-week to close at 6.47, lifting fiscal revenue prospects for both Chile and Peru. Brent crude rose 1.99% to 90.12, providing a modest offset to Colombia’s earlier oil-linked revenue concerns. Gold advanced 0.8% to 4107.00, adding support to Peru’s mining surplus.

Equity and Currency Markets Reflect Uneven Sentiment MSCI Chile ended the week at 39.33 after a net 0.23% gain, while MSCI Peru closed at 85.98 for a 0.6% weekly advance. MSCI Colombia remained flat at 9.02. USD/CLP declined 1.64% to 930.47 and USD/COP fell 0.44% to 3202.90, whereas USD/PEN rose 1.61% to 3.39.

Activity Data Underscore Limited Room for Further Easing Chile’s softer industrial output contributed to the BCCh decision to stay on hold. Colombia’s inflation backdrop and the new president-elect transition kept BanRep focused on inflation risks even after the hold. Peru’s incoming administration signaled continuity in the technocratic framework.

Andean Central Banks Watch

BCCh held its policy rate at 4.5% on three consecutive days, citing soft industrial output and limited scope for additional cuts after the prior easing cycle. BanRep’s July 31 hold at 12% reflected peso strength and left the door open for future tightening if inflation pressures persist. BCRP maintained its steady stance with no meeting or data releases altering the outlook. The data prints and official communications across the three banks reinforced a data-dependent approach, with Chile’s activity weakness and Colombia’s inflation stickiness shaping distinct near-term signals. Officials in Santiago and Bogotá emphasized monitoring of commodity revenues and imported inflation risks without providing explicit forward guidance on the timing of upcoming decisions.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Data Review: Actual vs Consensus
DateCtryEventPrior Cons.Actual
Tue 28CLCentral Bank Interest Rate4.54.54.5
Thu 30COBusiness Confidence-2.9--0.10
Fri 31CLCopper Production Year-ove-12.9-5.1
Fri 31CLIndustrial Production Year-7.5-1.3
Fri 31CLManufacturing Production Y-7.2-6.0-3.2
Fri 31CLRetail Sales Month-over-Mo0.30-1.5
Fri 31CLRetail Sales Year-over-Yea4.8-5.1
Fri 31CLUnemployment Rate9.49.49.4
Fri 31COUnemployment Rate8.08.18.0
Fri 31COCentral Bank Interest Rate12.012.5-
Fri 31COCentral Bank Interest Rate12.012.512.0
Fri 31COCement Production Year-ove4.6--
Fri 31COCement Production Year-ove4.6-4.3
Sat 1PEInflation Rate Month-over-0.23-0.29
Chart 7

The Week Ahead

Colombia, Chile and Peru face a quiet data calendar with no high-impact releases scheduled for the first half of the coming week. Indonesia’s inflation and trade prints on August 3 may offer indirect read-throughs for commodity demand affecting the Andean bloc. Copper and Brent price action will remain the dominant drivers for fiscal flows and external balances in Chile and Peru. Traders will watch for any post-meeting communications from BanRep following the July 31 hold to assess whether the door remains open for later tightening. Peru’s new administration may provide early signals on mining policy continuity that could influence investment flows. BCCh speakers are expected to reiterate the data-dependent stance ahead of the next decision. Regional FX volatility tied to gold and copper swings will continue to shape imported inflation risks for all three central banks.

Risks & Themes

The BanRep hold introduces uncertainty around Colombia’s inflation trajectory and could delay fiscal adjustments if oil revenues remain volatile. Copper’s 2.0% weekly gain eases near-term pressure on Chile’s Codelco and Peru’s mining sector, yet sustained strength is required to offset earlier production shortfalls. Divergent rate paths across the bloc may amplify currency volatility, with the peso’s recent strength potentially reversing if inflation data reaccelerate. Structural revenue challenges outside copper persist for Chile.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
United Kingdom
Market Scorecard
AssetLevelWoW
FTSE 10010868.1+0.8%
FTSE 25023975.0+0.3%
GBP/USD1.35+1.0%
GBP/EUR1.17-0.4%
GBP/JPY211.91-3.0%
Brent Crude90.12+2.0%
Gold4107.0+0.8%
UK Nat Gas2.75-0.7%
Bitcoin63382.0-3.0%
Chart 1
Chart 2
  • Bank of England maintained its policy rate amid resilient domestic lending data.
  • CBI Distributive Trades balance improved in July, beating consensus and signalling stronger retail conditions.
  • UK consumer credit and net mortgage lending both exceeded forecasts.
  • FTSE 100 posted a net weekly gain while 10-year gilt yields declined and GBP/USD advanced.

Week in Review

Resilient credit data offset softer external signals. UK household borrowing accelerated in the week of July 27–31, with consumer credit and net mortgage lending both exceeding forecasts. Mortgage approvals also rose above expectations. These figures reinforced the view that domestic demand remained intact even as global energy prices fluctuated.

Distributive trades beat highlighted consumer resilience. The CBI Distributive Trades balance improved and surpassed consensus, pointing to firmer retail spending. Equity markets responded with the FTSE 100 advancing. Sterling gained ground, with GBP/USD rising for a weekly increase.

Policy hold anchored market pricing. The Bank of England maintained its policy rate, consistent with the vote split and forward guidance that emphasised data dependence. Governor Bailey’s post-decision remarks focused on inflation persistence without altering the medium-term path. Ten-year gilt yields declined on the day of the decision. Brent crude closed the week higher after volatile daily swings that included a sharp surge on July 29.

Housing and labour backdrop remained stable. Nationwide house price trends and unemployment provided no immediate pressure for policy adjustment. Markets absorbed the oil impulse through the rates channel while equities posted limited net changes outside the final session. The configuration left financial conditions tighter via commodity prices yet supportive of growth through credit channels.

BoE Watch

The Bank of England held the policy rate with a vote split that aligned with the pre-meeting consensus. Governor Bailey’s post-decision speech emphasised data dependence and the need to monitor energy-driven inflation risks without shifting the medium-term outlook. The accompanying Monetary Policy Report and minutes offered no material change to projections, leaving the rate path anchored on incoming prints. Stronger-than-expected consumer credit and mortgage lending data reinforced the committee’s decision to maintain the current stance. CPI continued to show progress toward target while unemployment limited wage pressures. Markets interpreted the communications as consistent with a hold through the near term, with gilt yields declining on the day of the announcement. External analysis noted that energy shocks could keep inflation above target, yet the Bank of England’s official guidance remained focused on observed data rather than forward revisions.

Data Review

The standout release was the CBI Distributive Trades balance, which improved in July against consensus and the prior print, confirming stronger retail momentum than anticipated. BoE consumer credit and mortgage approvals both exceeded expectations. Net mortgage lending also rose above consensus and the prior level. These credit figures pointed to accelerating household demand that offset earlier softness in construction PMI. CPI and unemployment continued to show gradual disinflation alongside labour-market slack. The combination kept the Bank of England’s medium-term rate path on hold, with no immediate revision to growth or inflation projections. Energy price volatility added upside risk to the inflation outlook, yet the data releases themselves reinforced selective resilience rather than outright overheating. The prints collectively signalled that the UK cycle remained in mid-expansion with credit channels absorbing higher borrowing costs.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Data Review: Actual vs Consensus
DateCtryEventPrior Cons.Actual
Mon 27GBCBI Distributive Trades Le-54.0-45.0-26.0
Mon 27GBBRC Shop Price Inflation L1.21.20.90
Tue 28GBTreasury Gilt 2028 Tender 4.0-4.1
Tue 28GBTreasury Gilt 2040 Tender--5.3
Wed 29GBBoE Consumer Credit Level1.7bn1.7bn1.8bn
Wed 29GBMortgage Approvals Level57K57K58K
Wed 29GBMortgage Lending Level3.3bn4.0bn7.7bn
Wed 29GBM4 Money Supply Month-over0.200.200.80
Wed 29GBNet Lending to Individuals5.0bn5.5bn9.5bn
Wed 29GBCar Production Year-over-Y3.2--1.2
Thu 30GBBoE Interest Rate Decision3.83.83.8
Thu 30GBBoE MPC Vote Cut0-0
Thu 30GBBoE MPC Vote Hike2.0-3.0
Thu 30GBBoE MPC Vote Unchanged7.0-6.0
Week Ahead: Key Releases
DateReleasePriorCons.
2026-08-06S&P Global Construction PMI Index-40.2
2026-08-07Lloyds House Price Index Month-over0.200.20
2026-08-07Lloyds House Price Index Year-over-0.60-

The Week Ahead

The week of August 03–07 opens with limited domestic releases before mid-week construction data. S&P Global Construction PMI is scheduled, providing the first read on sector momentum after prior contraction signals. Lloyds House Price Index prints follow, testing whether recent cooling persists amid stable credit conditions. No Bank of England speakers are listed for the period, leaving markets to focus on the data flow. Euro-area flash HICP releases later in the week will shape external rate-cut pricing that spills into sterling assets. Traders will monitor any updates to quantitative tightening pace alongside the housing prints. The configuration leaves the policy rate path data-dependent with limited near-term repricing expected absent major surprises.

Risks & Themes

Stronger credit and distributive trades data shifted positioning toward reduced near-term easing odds while leaving the medium-term rate path unchanged. Upside risks centre on persistent energy prices that could extend inflation above target. Downside risks remain tied to any renewed softening in housing or construction prints that could reopen the door for earlier policy adjustment. Market flows showed limited volatility outside the oil-driven sessions, with gilt curves flattening modestly on the hold decision. Positioning appears balanced between domestic resilience and imported inflation pressures, with no clear mispricing signals in the observed moves. Volatility considerations centre on Brent crude swings that could transmit directly into UK energy costs and real yields.

Cross-Asset

Equities posted a net weekly gain as the FTSE 100 rose while the FTSE 250 advanced. Bonds saw 10-year gilt yields decline. FX markets showed GBP/USD climbing for a weekly gain. GBP/EUR eased while GBP/JPY fell. Commodities reflected Brent crude closing higher after a weekly rise that included a sharp surge on July 29. Gold advanced and UK natural gas declined.

Global Context

Middle East maritime incidents drove Brent crude volatility that spilled into UK energy prices during the week. Supply concerns lifted Brent after a sharp daily surge. Broader DM central banks maintained data-dependent stances amid the same oil impulse, with limited near-term policy repricing observed across curves. Trade and geopolitical spillovers remained contained within the seven-day window, supporting selective resilience in UK credit data despite external price pressures.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Sweden, Norway, Denmark and Finland
Market Scorecard
AssetLevelWoW
OMX Stockholm 303246.92+0.9%
Oslo Bors2018.08+1.4%
OMX Copenhagen 251841.22+0.4%
OMX Helsinki 256220.08+0.7%
USD/SEK9.51-1.7%
USD/NOK9.44-1.4%
EUR/SEK10.97-0.5%
EUR/NOK10.93+0.2%
Brent Crude90.12+2.0%
Gold4107.0+0.8%
Bitcoin63382.01-3.0%
Chart 1
Chart 2
  • Brent crude volatility dominated Nordic markets, ending the week at 90.12 after lifting Oslo Bors 1.35% week-over-week while supporting NOK strength.
  • Sweden’s June CPI contrasted sharply with Norway’s, driving divergent 10-year yield moves.
  • No Riksbank, Norges Bank, Danmarks Nationalbank or Bank of Finland decisions occurred, leaving policy signals anchored to the prior June inflation prints and external euro-area resilience.

Week in Review

Equity and FX Divergence Driven by Energy Prices Nordic equity markets posted modest net gains amid Brent crude swings that reversed early-week declines and ended at 90.12. The OMX Stockholm 30 closed at 3246.92 for a 0.9% week-over-week advance while Oslo Bors reached 2018.08, up 1.35%. OMX Copenhagen 25 finished at 1841.22, up 0.43%, and OMX Helsinki 25 closed at 6220.08, up 0.72%.

Currency Moves Reflect Inflation Backdrop USD/SEK fell 1.72% to 9.51 and USD/NOK declined 1.39% to 9.44, with EUR/SEK easing 0.5% to 10.97. These moves aligned with Sweden’s subdued June CPI versus Norway’s firmer print from the prior week. EUR/NOK rose 0.19% to 10.93.

Fixed-Income Markets Show Policy Divergence Sweden’s 10-year government yield held steady while Norway’s 10-year yield remained elevated, underscoring different inflation trajectories. Gold advanced 0.8% to 4107.00 and Bitcoin fell 3.0% to 63382.01 over the same period.

Limited Domestic Data Releases Shape Narrative The Nordic calendar contained no high-impact releases, with only low-impact prints such as Finland’s business confidence rising to 7 and consumer confidence steady at -5.3. External euro-area growth resilience and Brent price action therefore set the dominant tone.

Through-Line Centers on Selective Resilience The data arc confirmed that oil-price volatility interacted with pre-existing inflation differences to produce clearer cross-Nordic divergence without altering the broader mid-expansion backdrop.

Nordic Central Banks Watch

Riksbank and Norges Bank communications remained absent this week, leaving the June CPI prints as the latest verified benchmarks. Sweden’s reading reinforced the case for continued data dependence at the next policy meeting while Norway’s figure supported Norges Bank’s firmer stance. Danmarks Nationalbank stayed aligned with the EUR/DKK ERM II peg amid stable external conditions. Bank of Finland, operating within the ECB framework, transmitted unchanged deposit-rate signals from euro-area resilience. The data therefore suggest that upcoming decisions will continue to hinge on verified inflation and activity prints rather than forward guidance shifts.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Data Review: Actual vs Consensus
DateCtryEventPrior Cons.Actual
Mon 27FIBusiness Confidence4.0-7.0
Mon 27FIConsumer Confidence Index-5.3--5.3
Mon 27SEHousehold Lending Growth Y3.1-3.2
Tue 28DKRetail Sales Month-over-Mo1.0-0.50
Tue 28DKRetail Sales Year-over-Yea3.7-4.8
Tue 28SETrade Balance2.1bn-2.6bn
Wed 29NORetail Sales Month-over-Mo-2.4-1.8
Wed 29SEGDP Growth Quarter-over-Qu-0.200.701.4
Wed 29SEGDP Growth Year-over-Year 2.0-2.8
Wed 29SEGDP Month-over-Month0.90--0.20
Thu 30FIGDP Growth Quarter-over-Qu0.90-0.90
Thu 30FIGDP Growth Year-over-Year 1.1-1.8
Thu 30FIGDP Year-over-Year2.7-1.8
Thu 30DKUnemployment Rate2.7-2.7

The Week Ahead

Monday brings Indonesia inflation and trade balance releases that may influence broader commodity sentiment relevant to Norwegian fiscal flows. Tuesday features limited Nordic-specific items, directing attention to any euro-area PMI updates that feed into Bank of Finland and Danmarks Nationalbank assessments. Wednesday includes potential ECB-related commentary that could affect Finnish borrowing costs and Danish peg stability. Thursday and Friday calendars remain light on domestic releases, keeping focus on global growth prints that shape Riksbank and Norges Bank rate-path deliberations. These external indicators matter because they inform the inflation and activity backdrop ahead of the next policy meetings across the four central banks.

Risks & Themes

Brent crude’s weekly gain to 90.12 after intra-week swings introduces upside risk to Norwegian revenues but downside pressure on Swedish export competitiveness if energy costs remain elevated. Sweden’s low CPI versus Norway’s creates scope for further yield divergence. Upside scenarios center on sustained euro-area resilience supporting Finnish and Danish outlooks while downside risks arise if oil volatility transmits into wider Nordic inflation dispersion. The configuration leaves the growth cycle intact yet tilts policy expectations toward continued data dependence at upcoming decisions.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Poland, Czech Republic, Hungary, Romania and Turkey
Market Scorecard
AssetLevelWoW
BIST 10013458.1-2.3%
iShares Poland42.83+4.3%
EUR/PLN4.3-0.2%
EUR/HUF364.55+1.4%
EUR/CZK24.18+0.2%
USD/TRY47.49+0.3%
Brent Crude90.12+2.0%
Gold4107.0+0.8%
Bitcoin63373.85-3.0%
Chart 2
  • Hungary Q2 GDP expanded modestly, missing consensus and underscoring subdued domestic demand after prior rate cuts.
  • Polish preliminary July inflation is slated to rise, with the print due late July and set to inform NBP timing.
  • Regional 10-year yields fell sharply while BIST 100 closed the week lower.
  • Brent crude ended higher, reinforcing imported inflation pressure across net-energy importers in the region.

Week in Review

Hungarian growth disappoints amid tourism weakness. Hungary Q2 GDP grew modestly versus consensus, pointing to softer domestic demand despite earlier policy easing. Tourism arrivals declined in June as high temperatures and a stronger forint weighed on visitor numbers. The forint strengthened modestly, with EUR/HUF closing at 364.55 for a +1.43% wow move.

Polish inflation path draws renewed attention. Markets prepared for Poland’s preliminary July inflation release. The zloty outperformed peers, with EUR/PLN easing 0.25% wow to 4.30. Polish equities advanced, as the iShares Poland ETF rose 4.29% wow to 42.83.

Turkish assets face mixed external pressures. BIST 100 declined 2.3% wow to 13,458.10 while USD/TRY edged 0.29% higher to 47.49. Unemployment held steady.

CEE bond markets rally on thin volumes. Polish 10-year yields fell sharply and Hungarian 10-year yields dropped sharply. Limited data releases across the Czech Republic and Romania left markets focused on external ECB signals and Brent moves. Gold rose 0.8% wow to 4,107.00, reflecting cautious risk sentiment.

Regional FX shows selective resilience. EUR/CZK closed at 24.18 for a +0.25% wow gain while EUR/HUF advanced 1.43%. Brent crude volatility, ending at 90.12 after a +1.99% weekly gain, added imported cost pressure for Poland, Hungary and the Czech Republic. Bitcoin fell 3.01% wow to 63,373.85.

Emerging Europe Central Banks Watch

No policy rate decisions were scheduled from NBP, CNB, MNB, BNR or CBRT during the week. Hungarian GDP data will feed into MNB deliberations on the pace of any further easing. Polish markets watched the upcoming inflation preview for signals on NBP forward guidance. CBRT communications remained focused on external financing conditions amid the widening trade deficit consensus. Regional central banks continued to reference euro-area stability, with the ECB deposit rate providing an unchanged external anchor. The Hungarian growth miss and Polish inflation rebound expectation together suggest policy paths will stay data-dependent rather than pre-committed to additional cuts in the near term. Limited speaker activity across the five central banks left market attention on the released prints and their direct read-through to inflation and growth trajectories.

Data Review

Hungary’s Q2 GDP print highlighted the softest domestic demand reading in recent quarters. Tourism data for June showed clear weakness, consistent with the growth miss and the stronger forint level near 364.55 on EUR/HUF. Poland’s upcoming preliminary July inflation release will provide the first signal on whether the earlier disinflation trend has reversed. Turkey’s final June trade balance points to a widening external gap that could pressure the current account. No high-impact releases occurred in the Czech Republic or Romania, leaving those economies reliant on external euro-area demand signals. The absence of fresh inflation prints in Hungary and the Czech Republic kept focus on the Hungarian GDP miss and its implications for MNB policy sequencing. Brent’s weekly gain to 90.12 reinforced pipeline cost pressures for net importers, with the move directly feeding into regional inflation outlooks. Overall, the data configuration suggests the mid-expansion phase remains intact but tilts toward selective reacceleration in price pressures rather than broad-based growth momentum.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Data Review: Actual vs Consensus
DateCtryEventPrior Cons.Actual
Tue 28HU3-Month Hungarian Discount5.3-5.3
Wed 29HU6-Month Hungarian Discount5.3-5.3
Thu 30ROUnemployment Rate6.4-6.3
Thu 30HUGDP Growth Quarter-over-Qu0.80-0.40
Thu 30HUGDP Growth Year-over-Year 1.71.91.7
Thu 30HUTrade Balance799.0mn-1.3bn
Thu 30CZGDP Growth Quarter-over-Qu0.200.500.40
Thu 30CZGDP Growth Year-over-Year 2.22.22.0
Thu 30HU12-Month Hungarian Discoun5.2-5.2
Thu 30HU20-Year Green Bond Auction5.4-5.7
Fri 31HUProducer Price Index Year--0.70--0.40
Fri 31PLInflation Rate Year-over-Y2.53.03.0
Fri 31PLInflation Rate Month-over--0.500.800.80
Fri 31CZM3 Money Supply Year-over-5.3-6.3

The Week Ahead

Monday brings Turkey’s July inflation rate month-over-month alongside the year-over-year print. These releases will set the tone for CBRT policy expectations early in the window. No major data are flagged for Poland, Czech Republic, Hungary or Romania on Monday. Mid-week focus shifts to any follow-through from the Polish preliminary inflation outcome and Hungarian GDP miss. Central bank speakers from NBP and MNB are expected to comment on the inflation and growth prints, respectively. The Turkish trade balance final figure due late in the prior week will also influence external balance assessments. Markets will monitor Brent crude reaction to any geopolitical headlines, given its close at 90.12. Overall, the calendar remains light outside Turkey, keeping attention on external euro-area and commodity spillovers.

Risks & Themes

The Hungarian GDP miss raises downside risks to the regional growth outlook if domestic demand weakness spreads to Poland and the Czech Republic. Upside inflation surprises in Turkey and Poland could delay any further policy easing across the five central banks. Brent’s weekly gain to 90.12 signals continued imported cost pressure that could widen current-account gaps, particularly for Turkey. Positioning remains light ahead of the Polish inflation print, with limited summer volumes amplifying daily moves. Market mispricing appears concentrated in Hungarian assets, where the GDP outcome may not yet be fully reflected in forint levels near 364.55. Volatility in gold and bitcoin, with the latter down 3.01% wow, points to cautious global risk sentiment that could spill into higher-beta CEE equities. Flow considerations favor Polish assets given the ETF advance, while Turkish positioning faces headwinds from the widening trade deficit consensus.

Cross-Asset

Equities diverged sharply, with the iShares Poland ETF advancing 4.29% wow to 42.83 while BIST 100 fell 2.3% wow to 13,458.10. Polish outperformance reflected bank-sector gains and zloty strength, whereas Turkish equities faced continued lira pressure at USD/TRY 47.49. Bonds rallied across the region, with Polish 10-year yields declining sharply and Hungarian 10-year yields dropping sharply on thin summer volumes. FX markets showed modest net moves, as EUR/PLN eased 0.25% wow to 4.30 and EUR/HUF rose 1.43% wow to 364.55, while EUR/CZK gained 0.25% to 24.18. Commodities added volatility, with Brent crude closing at 90.12 after a +1.99% weekly gain and gold advancing 0.8% wow to 4,107.00. Bitcoin’s -3.01% weekly decline to 63,373.85 capped risk appetite across higher-beta regional assets.

Global Context

Brent crude’s +1.99% weekly gain to 90.12 reinforced the energy-price impulse that has re-anchored financial conditions tighter across emerging Europe. Eurozone CPI provided a stable external backdrop for Polish and Czech exports. US labor-market softening continued without triggering immediate contraction signals, keeping developed-market policy expectations data-dependent. Gold’s advance to 4,107.00 reflected ongoing safe-haven demand amid geopolitical tensions that also lifted Brent. The configuration leaves net-energy importers in the region exposed to further commodity-driven inflation while EU fund inflows continue to support the four EU members.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
South Africa
Market Scorecard
AssetLevelWoW
JSE Top 40103257.7+1.1%
USD/ZAR16.47-1.4%
EUR/ZAR19.02-0.1%
Platinum1658.7+2.4%
Gold4107.0+0.8%
Brent Crude90.12+2.0%
Naspers86748.0+6.7%
Bitcoin63367.51-3.0%
Chart 1
Chart 2
  • SARB held the policy rate steady as June CPI registered inside the target band, triggering an initial USD/ZAR spike before a weekly close at 16.47.
  • JSE Top 40 rose 1.13% to 103257.7 amid gains in gold to 4107.0 and platinum to 1658.7, while Brent crude ended at 90.12.
  • Trade balance release due July 31 carried a prior reading of -1,790m rand, with no other domestic prints during the week.

Week in Review

Policy Hold Anchors the Week South African markets absorbed the SARB decision to keep the repo rate unchanged on July 27 with June CPI inside the target band. The rand posted the largest single-day decline among major currencies as USD/ZAR climbed sharply. JSE Top 40 advanced on platinum strength.

Commodity and Currency Reversal USD/ZAR recovered to close the week at 16.47 for a 1.44% weekly decline. Gold reached 4107.0 while platinum settled at 1658.7, supporting resource names. Brent crude ended at 90.12.

Equity and Rate Curve Moves JSE Top 40 posted a net 1.13% gain to 103257.7 across four trading days. The short-term rate held steady while the long-term rate eased. Naspers climbed 6.66% to 86748.0.

External Data Focus Attention remained on the June trade balance scheduled for July 31 release against the prior -1790m rand print. No additional domestic indicators appeared in the seven-day window.

Through-Line Summary The data confirmed the SARB’s hold stance near the recent inflation level while commodity price swings drove the rand and equity arc.

SARB Watch

The SARB kept the policy rate unchanged on July 27 after June CPI registered inside the target band. No MPC speakers appeared during the week and the quarterly bulletin was flagged for later release. The decision aligned with the inflation print sitting inside the target band while external accounts remained the next scheduled data point. Officials offered no fresh forward guidance beyond the existing data-dependent framework. The hold left the rate path unchanged pending further inflation and credit prints.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Data Review: Actual vs Consensus
DateCtryEventPrior Cons.Actual
Mon 27ZA182-Day Treasury Bill Auct7.5-7.4
Mon 27ZA273-Day Treasury Bill Auct7.7-7.6
Mon 27ZA364-Day Treasury Bill Auct7.7-7.4
Mon 27ZA91-Day Treasury Bill Aucti7.1-7.0
Tue 28ZALeading Business Cycle Ind-2.0--0.30
Tue 28ZA2037 Bond Auction8.7-8.7
Tue 28ZA2038 Bond Auction8.8-8.9
Tue 28ZA2040 Bond Auction8.7-9.0
Wed 29ZAM3 Money Supply Year-over-9.6-9.3
Wed 29ZAPrivate Sector Credit Year8.6-7.8
Thu 30ZAProducer Price Index Month2.6--0.10
Thu 30ZAProducer Price Index Year-7.8-7.5
Thu 30ZABudget Balance-14.6bn-80.1bn
Fri 31ZATrade Balance4.4bn-17.8bn
Chart 5
Chart 7

The Week Ahead

Monday brings Indonesia inflation and trade balance prints that will shape global risk sentiment for the rand. Tuesday features additional Indonesian core inflation and export figures with potential spillovers to commodity currencies. Wednesday includes further regional inflation updates that could influence EM flows. Thursday carries no major South African releases but global risk appetite will set the tone ahead of the next SARB decision. Friday closes the window with limited domestic data, keeping focus on external accounts and any credit extension updates. These releases matter because they inform the inflation trajectory that the SARB will reference at upcoming decisions. Limited South African prints next week leave the rate path dependent on the prior hold signal and incoming global commodity moves.

Risks & Themes

The week’s hold reinforced a narrow path between fiscal restraint and infrastructure constraints that continue to cap growth. Oil price volatility introduces upside risk to imported inflation that could delay any later easing. A weaker-than-expected trade balance outcome on July 31 would widen external financing needs already flagged as large. Governance and regional diplomatic tensions add a separate layer of uncertainty that markets have not yet repriced into the currency. The configuration leaves the outlook tilted toward data dependence with limited room for surprise easing signals before the next meeting.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Australia and New Zealand
Market Scorecard
AssetLevelWoW
ASX 2008976.8+0.9%
NZX 5013699.28-1.1%
AUD/USD0.71+0.9%
NZD/USD0.59+1.7%
AUD/NZD1.2-0.8%
BHP60.31+0.3%
Gold4107.0+0.8%
Brent Crude90.12+2.0%
Bitcoin63371.62-3.0%
Chart 1
Chart 2
  • Australian June-quarter CPI printed below consensus on both a year-over-year and month-over-month basis, with the trimmed-mean measure also easing.
  • ANZ Business Confidence rose sharply while Australian building permits increased, signalling construction resilience.
  • RBA Governor Bullock and Assistant Governor Hunter both reiterated that underlying inflation remains too high, keeping the policy rate path data-dependent ahead of the next meeting.

Week in Review

Inflation print drives the narrative arc. Australian June-quarter CPI came in below the 4.0% consensus on a year-over-year basis and below the expected month-over-month increase. The RBA trimmed-mean measure eased further. Markets interpreted the undershoot as reducing the likelihood of an immediate policy adjustment at the next meeting.

Business sentiment and construction data diverged from the inflation signal. New Zealand ANZ Business Confidence rose sharply from the prior reading, while Australian preliminary building permits rebounded after a prior decline. These prints pointed to firmer domestic activity in both economies despite the softer price data.

Commodity and equity moves reflected the mixed backdrop. Brent crude ended the week at 90.12 after swinging higher during the period, while the ASX 200 closed at 8976.8 for a 0.93% weekly gain. The NZX 50 finished at 13699.28, down 1.09% over the same period. AUD/USD reached 0.71 and NZD/USD reached 0.59, narrowing the AUD/NZD cross to 1.20.

Policy communication reinforced data dependence. RBA Governor Bullock stated that underlying inflation remains too high even after the CPI release, while Assistant Governor Hunter’s remarks focused on productivity without altering the forward guidance. The data therefore suggest that both the RBA and RBNZ will continue to monitor incoming releases for the next decisions rather than shift stance on the basis of a single print.

Overall arc shows selective resilience amid cooling price pressures. The combination of the CPI miss, stronger business confidence, and firmer building permits left the expansion intact but tilted expectations toward a hold at upcoming meetings. Oil volatility added an external layer that offset some of the domestic disinflation signal.

ANZ Central Banks Watch

RBA Governor Bullock and Assistant Governor Hunter both spoke during the week and maintained that underlying inflation measures remain above target despite the June-quarter CPI print. The trimmed-mean outcome provided no immediate relief in their assessments. RBNZ communications were absent from the calendar, leaving the OCR on hold with attention shifting to the upcoming labour-market release. The data suggest that both central banks will keep the policy rate unchanged at the next meetings unless subsequent prints show further moderation in core measures. Australian PPI and building-permit outcomes will feed directly into the RBA’s assessment of pipeline pressures ahead of those decisions.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Data Review: Actual vs Consensus
DateCtryEventPrior Cons.Actual
Mon 27NZ1-Year Treasury Bill Aucti3.4-3.4
Mon 27NZ3-Month Treasury Bill Auct2.7-2.8
Mon 27NZ6-Month Treasury Bill Auct3.0-3.0
Mon 27AUSpeech by RBA's Gov Bulloc---
Tue 28AUInflation Rate Month-over--0.700.20-0.10
Tue 28AUInflation Rate Year-over-Y4.04.03.8
Tue 28AURBA Trimmed Mean Consumer 0.400.400.30
Tue 28AURBA Trimmed Mean Consumer 3.63.73.6
Tue 28AUConsumer Price Index102-102
Tue 28AUQuarterly Inflation Rate Q1.40.700.60
Tue 28AUQuarterly Inflation Rate Y4.14.13.9
Tue 28AUQuarterly RBA Trimmed Mean0.800.900.80
Tue 28AUQuarterly RBA Trimmed Mean3.53.73.6
Tue 28AURBA Weighted Median Consum0.90-0.30
Week Ahead: Key Releases
DateReleasePriorCons.
2026-08-04Employment Change Quarter-over-Quar0.200.10
2026-08-04Unemployment Rate5.35.4
2026-08-04Ai Group Industry Index-30.0-
2026-08-05Trade Balance-3.0bn-1.1bn

The Week Ahead

New Zealand employment-change and unemployment-rate data scheduled for the first day of the period will provide the primary labour-market signal for the RBNZ. Australian Ai Group Industry Index and trade-balance figures later in the week will round out the domestic calendar. These releases will inform assessments of growth momentum and external demand that feed into both the RBA and RBNZ rate paths. Officials from both banks are scheduled to speak, offering further scope to clarify the reaction function ahead of upcoming decisions. The configuration leaves policy expectations anchored to the incoming data flow rather than to any pre-set timeline.

Risks & Themes

The CPI undershoot has shifted the near-term growth-inflation balance toward greater data dependence for the RBA, while New Zealand business-confidence strength points to a more resilient domestic cycle. Upside risks centre on further commodity-price gains that could re-accelerate imported inflation and delay any easing at either central bank. Downside risks include a sharper labour-market deterioration in New Zealand that would reinforce the case for an earlier OCR adjustment. The market appears to be under-weighting the persistence of trimmed-mean inflation, which could keep both policy rates on hold for longer than currently positioned if subsequent releases fail to confirm the June-quarter moderation.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
China, Hong Kong and Taiwan
Market Scorecard
AssetLevelWoW
Shanghai Composite3832.26-0.7%
Hang Seng25884.43+2.7%
TAIEX43119.75-1.2%
USD/CNY6.74-0.4%
USD/HKD7.840.0%
Copper6.47+2.0%
Brent Crude90.12+2.0%
Gold4107.0+0.8%
Bitcoin63367.89-3.0%
Chart 2
  • China’s NBS Manufacturing PMI contracted for the first time in five months, missing consensus after the prior print and confirming demand weakness.
  • Hang Seng Index rose while Shanghai Composite declined, highlighting divergent regional equity flows amid PBoC liquidity support.
  • PBoC maintained daily USD/CNY fixes and conducted large-scale overnight reverse-repo operations to stabilize conditions ahead of the Politburo meeting.
  • Brent crude and copper advanced, reflecting energy-price spillovers and China demand signals that tightened financial conditions across Greater China assets.

Week in Review

Equity divergence signals selective resilience. Mainland indices closed the week lower with Shanghai Composite declining from the prior Friday close, while CSI 300 finished lower. Hong Kong’s Hang Seng advanced as property-policy signals lifted sentiment. Taiwan’s TAIEX ended lower after sharp mid-week losses on semiconductor rotation.

Liquidity operations anchor funding conditions. The PBoC conducted large-scale overnight reverse-repo operations and maintained daily USD/CNY fixes, limiting yuan volatility to a modest weekly decline. HKMA held its base rate steady following the Fed decision, keeping USD/HKD stable.

External demand offsets domestic softness. China-Africa trade reached a record level in the first half, supporting export momentum even as domestic PMI prints signaled contraction. Property-sector measures, including expanded mortgage relief in second-tier cities, provided modest equity support without reversing fixed-asset investment trends.

Commodity channel transmits global impulses. Copper and Brent crude gained ground, tightening imported-cost pressures on the mainland cycle. Gold advanced amid safe-haven flows.

Greater China Central Banks Watch

PBoC conducted large-scale overnight reverse-repo operations and maintained USD/CNY daily fixes, signaling preference for gradual yuan appreciation after the currency reached a multi-year high. HKMA left its base rate unchanged, preserving the USD/HKD peg. CBC foreign-reserve updates and Taiwan five-year yields at multi-year highs reflected gradual normalization expectations.

These operations occurred against the backdrop of the PMI contraction, which increases the case for further PBoC liquidity support in the near term. No new forward guidance emerged from official communications, leaving the policy-rate path data-dependent on subsequent activity and inflation prints. Panda-bond issuance expansion was flagged as an additional channel for domestic liquidity management.

Data Review

NBS Manufacturing PMI released July 30 printed below consensus after the prior reading, marking the first contraction in five months and confirming the export-rush unwind noted in July data. Non-Manufacturing PMI also fell short of consensus from the prior level, pointing to services momentum loss amid typhoon disruptions and domestic demand softness. Construction activity slumped to the lowest level since the pandemic start, extending the Q2 GDP miss pattern from prior weeks.

These prints reinforce that the mid-expansion phase in China remains intact yet tilts toward slower growth, with factory activity now contracting after five months above the threshold. The data connect directly to the PBoC’s continued liquidity injections, as weaker PMI outcomes increase the likelihood of additional reverse-repo and MLF operations in coming sessions. Export strength in the first-half trade surplus continued to support the yuan fix, while import growth widened the surplus and offset some domestic weakness.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Data Review: Actual vs Consensus
DateCtryEventPrior Cons.Actual
Mon 27HKExports Year-over-Year40.8-53.4
Mon 27HKImports Year-over-Year42.0-45.4
Mon 27HKTrade Balance-44.2bn--52.0bn
Mon 27TWConsumer Confidence Index65.0-64.6
Thu 30CNPolitburo Meeting---
Thu 30CNNBS Manufacturing PMI Inde50.350.049.2
Thu 30CNNBS Non Manufacturing PMI 50.250.049.0
Thu 30CNNBS General PMI Index50.6-49.3
Fri 31TWGDP Growth Year-over-Year 14.610.812.9
Fri 31HKGDP Growth Quarter-over-Qu2.9-0.30-0.60
Fri 31HKGDP Growth Year-over-Year 5.94.84.3
Week Ahead: Key Releases
DateReleasePriorCons.
2026-08-04Ratingdog Services PMI Index-53.7
2026-08-06Exports Year-over-Year27.0-
2026-08-06Imports Year-over-Year36.0-
2026-08-06Trade Balance125.6bn112.5bn
2026-08-08Inflation Rate Year-over-Year1.0-
2026-08-08Inflation Rate Month-over-Month-0.30-
2026-08-08Producer Price Index Year-over-Year4.1-
Chart 8

The Week Ahead

Ratingdog Manufacturing PMI is scheduled with consensus above 50, followed by Services PMI; both will test whether the NBS contraction was temporary. Trade Balance, Exports YoY, and Imports YoY release mid-week, with consensus pointing to a continued surplus after the prior print. Inflation Rate YoY and PPI YoY follow, providing fresh readings on price pressures after the oil-driven impulse.

PBoC liquidity operations and any Politburo signals will remain in focus, while HKMA aggregate-balance data and CBC reserve figures offer peg-stability updates. These releases matter because they will shape expectations for the medium-term rate path amid persistent domestic demand weakness and external commodity volatility.

Risks & Themes

The PMI contraction shifts the outlook toward greater downside risk for Q3 growth, with construction at pandemic lows amplifying property-sector liquidity strains. Upside scenarios hinge on stronger-than-expected trade data and nuclear-expansion approvals supporting energy demand. Market mispricing appears in the divergence between Hang Seng gains and mainland equity weakness, suggesting positioning remains cautious on domestic demand. Volatility in Brent crude and copper will continue to transmit global impulses, while yuan-fix stability reduces near-term FX flow pressure.

Cross-Asset

Equities showed net divergence with Hang Seng gaining while Shanghai Composite declined and TAIEX fell. Daily moves included a sharp Hang Seng rally and a TAIEX rebound after earlier drops.

Bonds reflected stable policy-rate expectations, with Taiwan five-year yields reaching multi-year highs on CBC hike speculation and HKMA base rate held steady. FX markets saw USD/CNY ease after PBoC fixes near recent levels, while USD/HKD remained anchored. Commodities posted gains, with copper advancing on China demand hopes and Brent crude rising amid supply signals; gold advanced.

Global Context

Brent crude’s weekly gain extended the oil-price impulse observed in prior weeks, tightening financial conditions through imported costs for China. US sanctions on shipping firms involved in Iranian oil added geopolitical pressure without immediate disruption to Greater China flows. Cross-border trade data showed China-Africa volumes at a record level, underscoring resilient external demand amid ASEAN diversification trends. These developments reinforce data dependence for PBoC, HKMA, and CBC policy paths over the next week.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
South Korea
Market Scorecard
AssetLevelWoW
KOSPI6595.45-2.4%
KOSDAQ719.76-5.9%
USD/KRW1436.6-1.5%
Samsung262500.0+3.4%
SK Hynix1718000.0-5.4%
Brent Crude90.12+2.0%
Gold4107.0+0.8%
Bitcoin63367.51-3.0%
Chart 1
Chart 2
  • Export resilience held while business confidence improved on manufacturing strength.
  • KOSPI recorded volatility and closed lower for the week, with Samsung advancing and SK Hynix declining.
  • Bank of Korea officials flagged elevated stock-market uncertainty after substantial equity outflows and convened emergency meetings, signaling tighter policy vigilance.

Week in Review

GDP and Confidence Prints Anchor the Narrative South Korea’s Q2 GDP beat shifted attention toward stronger second-half momentum, while consumer and business confidence indices improved on manufacturing optimism.

Export Momentum Holds Despite Volatility July exports rose above consensus, confirming semiconductor and auto shipments continued to offset domestic weakness.

Equity Markets Record Extreme Swings KOSPI moved lower on the week amid sharp daily swings before closing at 6595.45.

Chip Stocks Drive Index Moves Samsung advanced to 262500 won while SK Hynix closed at 1718000 won, reversing some earlier losses.

Won Strengthens on Multiple Channels USD/KRW declined to 1436.6, a 1.47 percent appreciation supported by exporter dollar sales and coordinated FX guidance.

Policy Response to Capital Flows Intensifies Authorities addressed illegal foreign-exchange transactions and intervened to defend the currency amid large equity outflows.

Oil and Yield Channels Add Pressure Brent crude rose to 90.12, illustrating imported cost pressures on refiners and households.

Labor and Growth Divergence Persists Unemployment stayed low with reports noting growth without jobs as chip profits expanded faster than employment gains.

Data Dependence Shapes the Week’s Arc The GDP surprise, confidence rebound, and export outperformance confirmed selective resilience even as equity volatility highlighted external risk sensitivity.

BoK Watch

Bank of Korea surveys showed business confidence rising, with officials noting the chip boom should limit further equity downside while warning of elevated stock-market uncertainty. Emergency meetings addressed large outflows and reinforced guidance for exporters to convert foreign-exchange receipts. Export strength and the Q2 GDP beat provided fresh evidence of external demand support that could sustain above-target inflation pressures into coming quarters. No Monetary Policy Committee meetings or senior speeches occurred, leaving the data prints as the primary input for upcoming decisions. The combination of resilient exports and manufacturing confidence suggests the policy rate path will remain data-dependent, with officials prioritizing inflation control over near-term easing signals.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Data Review: Actual vs Consensus
DateCtryEventPrior Cons.Actual
Mon 27KRConsumer Confidence Index107-107
Wed 29KRBusiness Confidence78.0-82.0
Thu 30KRIndustrial Production Mont-2.93.06.4
Thu 30KRIndustrial Production Year-1.12.55.8
Thu 30KRRetail Sales Month-over-Mo0.10-2.7
Fri 31KRExports Year-over-Year70.759.062.8
Fri 31KRImports Year-over-Year30.026.626.5
Fri 31KRTrade Balance36.1bn29.6bn30.3bn
Week Ahead: Key Releases
DateReleasePriorCons.
2026-08-03Inflation Rate Year-over-Year3.2-

The Week Ahead

Monday brings the S&P Global Manufacturing PMI Index, which will test whether recent business confidence gains extend into fresh factory momentum. Tuesday’s Inflation Rate Year-over-Year release will clarify whether energy and import costs are feeding through to headline prices ahead of the next meeting. Both prints matter for the Bank of Korea because sustained above-target inflation would support holding the policy rate while weaker readings could reopen discussion of the timing of any future adjustments. Wednesday through Friday contain no major domestic releases, shifting focus to regional data and any follow-up comments from the emergency FX coordination meetings. The absence of scheduled speakers keeps attention on the inflation and PMI outcomes as the clearest guides to the rate path over coming quarters. Markets will also monitor any updates on longer-term capital-flow implications.

Risks & Themes

The week’s equity swings highlight downside risks if global chip demand softens further or foreign outflows accelerate. Upside scenarios center on continued export outperformance suggesting semiconductor cycles could extend the growth-without-jobs pattern into coming quarters. Oil price volatility adds imported inflation risk that could keep the Bank of Korea on hold longer than expected if Brent retests recent highs. The won’s appreciation over the week may test exporter competitiveness if the move extends without offsetting productivity gains. Coordinated FX interventions with regional partners introduce policy uncertainty around future capital-flow management.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Indonesia, Thailand, Malaysia, Philippines, Singapore and Vietnam
Market Scorecard
AssetLevelWoW
JCI6236.13+0.8%
KLCI1724.9+0.7%
STI5628.5+0.1%
USD/IDR17990.0+0.2%
USD/THB33.39-0.7%
USD/MYR4.08-0.1%
USD/PHP61.24-0.7%
USD/SGD1.28-0.6%
Brent Crude90.12+2.0%
Gold4107.0+0.8%
Bitcoin63346.51-3.0%
Chart 1
Chart 2
  • Regional equities posted modest net gains, led by JCI and KLCI, while USD/IDR and USD/THB moved higher.
  • Brent crude posted a net weekly gain while gold advanced and Bitcoin declined.
  • No major high-impact data releases occurred in the region during the week.

Week in Review

Equity and currency moves JCI rose 0.81% to 6,236.13 while KLCI advanced 0.69% to 1,724.90. STI gained 0.15% to 5,628.50. USD/IDR ended at 17,990.0 after a 0.18% weekly increase. USD/THB eased 0.65% to 33.39, USD/MYR declined 0.13% to 4.08 and USD/PHP fell 0.74% to 61.24.

Commodity price moves Brent crude rose 1.99% to 90.12. Gold advanced 0.8% to 4,107.0 while Bitcoin declined 3.05% to 63,346.51.

External balances and inflation data set the stage Indonesia’s August 3 trade balance print follows a prior deficit of USD 1.61 billion, with consensus at USD -790 million. July inflation is expected near 3.2% versus the prior 3.34% reading.

Regional data dependence persists No major releases occurred in Thailand, the Philippines, Singapore or Vietnam during the week, leaving external drivers to dictate flows.

ASEAN Central Banks Watch

Limited communication from regional central banks left the focus on incoming data. The July inflation and trade balance prints due August 3 will inform whether price pressures remain contained near 3.2% and whether external balances support the current policy setting.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Data Review: Actual vs Consensus
DateCtryEventPrior Cons.Actual
Mon 27THIndustrial Production Year-1.3--3.1
Mon 27SGIndustrial Production Mont6.9--7.2
Mon 27SGIndustrial Production Year17.8-7.2
Tue 28MYProducer Price Index Year-7.8-9.2
Tue 28SGMAS 12-Week Treasury Bill 1.5-1.6
Tue 28SGMAS 4-Week Treasury Bill A1.4-1.5
Tue 28SGExport Prices Year-over-Ye14.6-12.7
Tue 28SGImport Prices Year-over-Ye18.5-13.6
Tue 28SGProducer Price Index Year-34.1-30.3
Wed 29SG2-Year Bond Auction1.6-1.8
Wed 29PHExports Year-over-Year7.6-24.1
Wed 29PHImports Year-over-Year28.2-19.6
Wed 29PHProducer Price Index Year-3.1-3.0
Wed 29PHTrade Balance-5.5bn--4.9bn
Week Ahead: Key Releases
DateReleasePriorCons.
2026-08-03Inflation Rate Year-over-Year3.33.2
2026-08-03Trade Balance-1.6bn-790.0mn
2026-08-04Inflation Rate Year-over-Year6.4-
2026-08-05GDP Growth Year-over-Year5.6-
2026-08-05Unemployment Rate4.8-
2026-08-06GDP Growth Quarter-over-Quarter0.90-
2026-08-06GDP Growth Year-over-Year2.8-
Chart 6

The Week Ahead

Indonesia’s August 3 trade balance and inflation prints lead the calendar, followed by Q2 GDP growth on August 5. The trade balance consensus sits at USD -790 million after the prior USD -1.61 billion deficit, while inflation is expected at 3.2% versus the prior 3.34%. Philippines inflation data on August 4 and unemployment and GDP prints on August 5-6 will provide the next reference points. No major releases are scheduled for Thailand, Malaysia, Singapore or Vietnam, leaving external oil moves and Indonesia-specific outcomes to shape regional sentiment. Markets will assess whether the data support steady policy rates across the region or require adjustments in coming quarters.

Risks & Themes

Oil price swings around current levels could tighten financial conditions further if the recent rebound extends, challenging growth forecasts in commodity importers. Consensus misses on Indonesia’s August 3-5 data could shift the balance between external stability and domestic price pressures. Markets appear to price limited near-term policy change, yet any sign of weaker Q2 GDP would heighten downside risks to the regional expansion.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
India
Market Scorecard
AssetLevelWoW
Nifty 5024383.6+1.6%
Sensex78094.64+1.6%
USD/INR95.39-1.2%
EUR/INR109.91+0.2%
Reliance1307.8+2.2%
HDFC Bank748.15+1.2%
Brent Crude90.12+2.0%
Gold4107.0+0.8%
Bitcoin63360.49-3.0%
Chart 1
Chart 2
  • Industrial production rose in June, beating consensus and confirming manufacturing resilience.
  • Private-sector PMI fell to a four-year low in July as services activity contracted sharply, highlighting divergent formal and consumption trends.
  • RBI sold dollars on multiple days and accumulated FCNR(B) inflows, lifting forex reserves while holding the short-term policy rate steady.

Week in Review

Industrial output surprise dominates the narrative. June industrial production beat consensus, with manufacturing output accelerating. Equity benchmarks responded with Nifty 50 advancing 1.62% week-over-week to 24,383.60 and Sensex rising 1.64% to 78,094.64. The data therefore suggest underlying factory momentum remained intact even as global oil prices fluctuated.

Services contraction offsets headline strength. Private-sector PMI reached its weakest level in more than four years, driven by a sharp services decline, while manufacturing held steadier. This divergence left domestic demand signals mixed despite the IP beat and above-normal monsoon rainfall that helped contain food-price pressures. Net FDI inflows declined amid higher repatriations, reducing external financing buffers even as June FDI supported infrastructure and services sectors.

Rupee stabilization through active intervention. USD/INR fell 1.22% week-over-week to 95.39 as the RBI conducted dollar sales and benefited from Brent crude volatility that ended the week at 90.12. Forex reserves climbed, reflecting sustained FCNR(B) deposits. The governor’s public assessment that the rupee is undervalued aligned with the reserve buildup and reduced near-term depreciation pressure.

Equity recovery after early-week losses. Markets snapped a five-session losing streak mid-week, with Reliance gaining 2.17% to 1,307.80 and HDFC Bank adding 1.16% to 748.15. Thin volumes and limited corporate earnings releases kept sentiment data-dependent. The configuration leaves the expansion intact but tilts attention toward consumption momentum flagged by the services PMI.

RBI Watch

RBI officials maintained a data-dependent stance with no MPC members speaking publicly during the week. The governor reiterated that the rupee is undervalued, consistent with the forex reserve increase and active dollar sales that capped USD/INR at 95.73 intraday. Industrial production and manufacturing reinforced the view of resilient formal-sector activity ahead of the next policy decision. Services PMI at a four-year low supplied the counter-signal on domestic demand, leaving the policy rate path anchored at the current short-term level. No forward guidance shifts emerged from released data or official remarks.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Data Review: Actual vs Consensus
DateCtryEventPrior Cons.Actual
Tue 28INIndustrial Production Year5.05.77.3
Tue 28INManufacturing Production Y5.2-7.8
Fri 31INGovernment Budget Value-1624.0bn--3078.0bn
Fri 31INForeign Exchange Reserves 676.2bn-682.4bn
Week Ahead: Key Releases
DateReleasePriorCons.
2026-08-05RBI Interest Rate Decision5.25.2

The Week Ahead

The RBI Interest Rate Decision on Wednesday will set the tone for the coming quarters, with consensus holding the rate steady. Markets will assess whether the industrial production outturn and services PMI weakness alter the balance of risks around upcoming decisions. No other major domestic releases are scheduled, shifting focus to global oil moves and their pass-through to CPI. Forex reserve updates and any fresh RBI liquidity operations will influence rupee direction near 95.39. The data therefore suggest the central bank will remain data-dependent into the next meeting, weighing manufacturing resilience against softer services momentum.

Risks & Themes

Stronger industrial production reduces downside growth risks but leaves consumption vulnerable if services PMI weakness persists. Oil price volatility continues to shape import costs and current-account pressure despite the rupee’s 1.22% weekly gain. Forex reserve accumulation provides a buffer yet has not eased banking liquidity, keeping the policy signal unchanged. The market appears to underweight the services contraction relative to the IP beat, creating scope for revisions if rural demand data disappoint in coming quarters.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Turkey
Market Scorecard
AssetLevelWoW
BIST 10013458.1-2.3%
USD/TRY47.49+0.3%
EUR/TRY54.89+1.7%
GBP/TRY64.03+1.2%
Gold (TRY)4107.0+0.8%
Brent Crude90.12+2.0%
EUR/USD1.15+1.3%
Bitcoin63361.05-3.0%
Chart 1
Chart 2
  • BIST 100 declined 2.3% week-over-week as Brent crude rose 1.99%.
  • USD/TRY advanced 0.29% while EUR/TRY gained 1.67% amid the commodity impulse.
  • No Central Bank of the Republic of Turkey communications or decisions occurred during the week.

Week in Review

Equity and Currency Moves Track Global Oil The BIST 100 posted a 2.3% weekly decline. USD/TRY rose 0.29% over the same period, with the largest single-day gain recorded on July 31. EUR/TRY climbed 1.67% and GBP/TRY advanced 1.24%, both driven by the same session-by-session pattern. Gold priced in TRY increased 0.8% while Bitcoin fell 3.03%.

Limited Domestic Data Flow The economic calendar contained no Turkey-specific releases between July 27 and August 2, leaving market moves to reflect external factors. Brent crude’s 1.99% weekly gain reinforced imported cost pressures already visible in prior weeks. The absence of fresh inflation or activity prints kept attention on the carry-trade and commodity channels. EUR/USD’s 1.33% advance provided modest additional support to TRY crosses.

Policy Vacuum Persists With no Central Bank of the Republic of Turkey speakers or minutes released, the policy rate path remained data-dependent by default. The week therefore produced no new forward guidance to alter expectations ahead of the next decision.

CBRT Watch

No Central Bank of the Republic of Turkey officials spoke and no minutes were published during the week. The policy rate therefore stayed on hold without fresh signals. Incoming inflation data next week will supply the next direct input for assessing whether current settings remain appropriate. The data dependence already articulated in prior communications continues to govern the timing of any upcoming decisions. Absent new guidance, the rate path will be evaluated solely against the inflation trajectory and growth prints that follow.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Data Review: Actual vs Consensus
DateCtryEventPrior Cons.Actual
Thu 30TRUnemployment Rate8.1-7.6
Thu 30TREconomic Confidence Index98.9-99.8
Thu 30TRLabor Force Participation52.8-52.9
Thu 30TRMPC Meeting Summary---
Thu 30TRForeign Exchange Reserves 65.4bn-62.4bn
Fri 31TRBalance of Trade Final-5.7bn-10.4bn-10.4bn
Fri 31TRExports Final22.4bn24.9bn24.9bn
Fri 31TRImports Final28.1bn-35.3bn
Fri 31TRTourism Revenues Level9.9bn-15.9bn
Fri 31TRTourist Arrivals Year-over-3.6--4.0
Week Ahead: Key Releases
DateReleasePriorCons.
2026-08-03Inflation Rate Month-over-Month0.991.8
2026-08-03Inflation Rate Year-over-Year32.131.8
Chart 5

The Week Ahead

Turkey’s Inflation Rate Month-over-Month and Inflation Rate Year-over-Year are scheduled for release on August 3. Consensus expects an acceleration in the month-over-month rate and a modest decline in the year-over-year rate. These prints will provide the first fresh inflation signal since the prior meeting and will shape the assessment of whether price pressures are moderating at the required pace. Stronger-than-expected outcomes would reinforce the case for maintaining the current policy rate into the next decision. Weaker readings could open scope for discussion of easing timing in coming quarters. No other high-impact Turkey releases appear on the calendar through August 7, leaving the inflation outcome as the dominant input for the Central Bank of the Republic of Turkey’s next policy review.

Risks & Themes

Higher Brent levels raise the risk that imported inflation will re-accelerate and delay any policy-rate reduction. A sharper BIST 100 decline could signal weaker domestic demand that eventually feeds into lower inflation, supporting an earlier adjustment. Continued TRY depreciation would add to imported-cost pressures and tilt the balance toward caution at upcoming decisions. The data dependence already in place leaves limited room for pre-emptive easing if inflation surprises to the upside on August 3.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Gulf Cooperation Council
Market Scorecard
AssetLevelWoW
Saudi Aramco26.58-0.1%
MSCI Saudi36.96-0.1%
MSCI UAE18.93+0.4%
MSCI Qatar17.38-1.4%
MSCI Kuwait36.69+1.0%
Brent Crude90.12+2.0%
WTI Crude84.67+2.5%
Gold4107.0+0.8%
USD/SAR3.76+2.9%
USD/AED3.67+0.0%
USD/KWD0.31-0.6%
Bitcoin63357.4-3.0%
Chart 1
Chart 2
  • Saudi Arabia’s economy contracted year-over-year while non-oil GDP expanded, confirming the oil-driven drag amid West Asia tensions.
  • Brent crude closed the week higher after a weekly gain, reversing earlier losses and lifting fiscal revenue prospects across the GCC.
  • Regional central banks held policy rates steady with no forward guidance shifts, keeping the policy rate path aligned to data dependence on oil and growth prints.

Week in Review

Geopolitical Tensions Drive Oil Repricing Brent crude ended higher after a weekly advance while WTI crude settled higher over the same period. Saudi Aramco closed at 26.58, down just 0.08% week-over-week. MSCI Saudi finished at 36.96, essentially flat at -0.05% for the week.

Saudi GDP Print Highlights Oil Dependence Saudi Arabia’s economy shrank year-over-year in the latest reading, directly tied to the oil slump and West Asia conflict, while non-oil GDP still posted a gain. This divergence underscores Vision 2030 progress yet leaves overall growth vulnerable to hydrocarbon swings.

Equity and Currency Cross-Currents MSCI UAE rose 0.37% to 18.93 while MSCI Qatar declined 1.41% to 17.38 over the week. USD/SAR moved to 3.76, up 2.94% week-over-week, and USD/KWD eased 0.64% to 0.31. Gold advanced 0.8% to 4,107.00 on safe-haven flows.

Fiscal and Diversification Signals The data therefore suggest that fiscal balances stayed resilient in the near term but face renewed pressure from any sustained output disruptions.

GCC Central Banks Watch

GCC central banks maintained current policy rate settings throughout the week with no decisions or minutes released. Officials continued to emphasise data dependence ahead of the next meeting, citing the need to monitor oil revenue stability and non-oil momentum. The Saudi GDP contraction and non-oil expansion provided fresh evidence that growth remains uneven, yet no explicit signals emerged on potential adjustments to the policy rate path. IMF commentary highlighted resilience under Vision 2030 without altering expectations for monetary stance. The configuration leaves policy expectations anchored to incoming prints on trade balances and activity rather than any shift in forward guidance.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Data Review: Actual vs Consensus
DateCtryEventPrior Cons.Actual
Thu 30SAGDP Growth Year-over-Year 3.0--4.8
Fri 31SAM3 Money Supply Year-over-8.9-8.4
Fri 31SAPrivate Bank Lending Year-6.6-6.8
Chart 6

The Week Ahead

Monday brings Indonesia inflation and trade balance data that will inform broader EM demand signals relevant to GCC exports. Tuesday features additional Indonesian core inflation and export figures that could influence commodity price sentiment. Wednesday includes further trade and inflation releases from the same source, offering incremental colour on regional growth. Thursday and Friday contain limited high-impact GCC-specific events, shifting focus to any OPEC+ compliance updates or maritime security statements. These releases matter for the rate path because stronger external demand prints would support oil revenues and reduce downside risks to fiscal balances. Conversely, softer outcomes could reinforce the case for holding the policy rate steady into upcoming decisions. Central banks will continue to watch global activity indicators for signs of sustained expansion or renewed weakness that could affect coming quarters’ growth outlook.

Risks & Themes

The week’s GDP contraction raises downside risks to overall growth if oil prices fail to sustain recent gains. Geopolitical escalation around Iran and Houthi activity could further reroute exports and widen fiscal gaps despite spare capacity buffers. Upside scenarios centre on continued non-oil expansion, which would validate diversification efforts and ease pressure on the policy rate path. Markets appear to underweight the persistence of security-driven volatility, as evidenced by only modest equity drawdowns despite repeated drone incidents. The data therefore suggest that any renewed oil impulse could tighten financial conditions faster than currently anticipated through the revenue channel.

RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Week Ahead CalendarAugust 03 – August 07, 2026
Time Country Event Our Est. Consensus Prior Impact
MONDAY, AUGUST 3
00:00🇮🇩Inflation Rate Year-over-Year—3.23.3●●○
00:00🇮🇩Trade Balance—-790.0M-1.6B●●○
02:00🇩🇪Retail Sales Month-over-Month—-0.501.1●●○
02:00🇩🇪Retail Sales Year-over-Year——1.8●●○
02:00🇷🇺S&P Global Manufacturing PMI Index———●●○
02:30🇨🇭Inflation Rate Year-over-Year——0.50●●○
03:00🇹🇷Inflation Rate Month-over-Month—1.80.99●●○
03:00🇹🇷Inflation Rate Year-over-Year—31.832.1●●○
03:15🇪🇸S&P Global Manufacturing PMI Index—50.7—●●○
03:30🇨🇭Procure.ch Manufacturing PMI Index—54.554.3●●○
03:45🇮🇹S&P Global Manufacturing PMI Index—52.5—●●○
08:00🇲🇽Business Confidence——46.3●●○
10:00🇺🇸ISM Manufacturing PMI Index—5453.3●●●
10:00🇺🇸ISM Manufacturing Employment Level——49.7●●○
19:00🇰🇷Inflation Rate Year-over-Year——3.2●●○
TUESDAY, AUGUST 4
03:00🇪🇸Unemployment Level Change—-20,300-28,700●●○
04:00🇮🇹Retail Sales Month-over-Month—0.100.20●●○
08:00🇧🇷Industrial Production Month-over-Month——-0.20●●○
08:00🇲🇽Consumer Confidence Index——43.8●●○
08:30🇨🇦Trade Balance—3.0B4.2B●●○
08:30🇺🇸Exports Level——317.7B●●○
08:30🇺🇸Imports Level——395.3B●●○
08:30🇺🇸Trade Balance—-73.0B-77.6B●●○
09:30🇨🇦S&P Global Manufacturing PMI Index—50.2—●●○
10:00🇺🇸JOLTs Job Openings Level—7.2M7.6M●●●
10:00🇺🇸Factory Orders Month-over-Month—0.50-1.3●●○
16:30🇺🇸API Weekly Crude Oil Stocks——3.3M●●○
18:45🇳🇿Employment Change Quarter-over-Quarter—0.100.20●●○
18:45🇳🇿Unemployment Rate—5.45.3●●○
19:00🇦🇺Ai Group Industry Index——-30●●○
19:50🇯🇵BoJ Monetary Policy Meeting Minutes CB———●●●
21:00🇵🇭Inflation Rate Year-over-Year——6.4●●○
21:45🇨🇳Ratingdog Services PMI Index—53.7—●●○
WEDNESDAY, AUGUST 5
00:00🇮🇩GDP Growth Year-over-Year——5.6●●○
00:30🇮🇳RBI Interest Rate Decision CB—5.25.2●●●
02:45🇫🇷Industrial Production Month-over-Month—0.30-0.10●●○
03:15🇪🇸S&P Global Services PMI Index—54.4—●●○
03:45🇮🇹S&P Global Services PMI Index———●●○
07:00🇺🇸MBA 30-Year Mortgage Rate——6.8●●○
08:15🇺🇸ADP Employment Change—75,00098,000●●○
09:00🇧🇷S&P Global Services PMI Index———●●○
10:00🇺🇸Services Sector PMI—54.254●●●
10:30🇺🇸EIA Weekly Crude Oil Inventory——-7.2M●●○
10:30🇺🇸EIA Weekly Gasoline Inventory——7,000●●○
16:05🇺🇸Speech by Fed's Cook———●●○
17:30🇧🇷Central Bank Interest Rate Decision CB——14.2●●●
21:00🇵🇭Unemployment Rate——4.8●●○
21:30🇦🇺Trade Balance—-1.1B-3.0B●●●
●●● High impact    ●●○ Medium impact    CB Central bank event    Our Est. = RoboMacro model forecast. Shown only where a model covers the release; a blank means we publish no estimate for it.    Source: RoboMacro Economic Calendar
RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com
Week Ahead CalendarAugust 03 – August 07, 2026
Time Country Event Our Est. Consensus Prior Impact
THURSDAY, AUGUST 6
02:00🇩🇪Factory Orders Month-over-Month—0.801.9●●○
03:00🇨🇭Unemployment Rate——2.9●●○
04:00🇮🇹Industrial Production Month-over-Month—0.30-0.30●●○
04:30🇬🇧S&P Global Construction PMI Index—40.2—●●○
08:30🇺🇸Nonfarm Productivity Quarter-over-Quarter Preliminary—0.700.30●●○
08:30🇺🇸Unit Labour Costs Quarter-over-Quarter Preliminary—2.71.8●●○
08:30🇺🇸Weekly Jobless Claims—200,000197,000●●○
14:00🇧🇷Trade Balance——9.8B●●○
15:00🇲🇽Central Bank Interest Rate Decision CB——6.5●●●
17:30🇺🇸Speech by Fed's Musalem———●●○
19:30🇯🇵Household Spending Month-over-Month——3.7●●○
19:30🇯🇵Household Spending Year-over-Year—0.90-0.40●●○
22:00🇵🇭GDP Growth Quarter-over-Quarter——0.90●●○
22:00🇵🇭GDP Growth Year-over-Year——2.8●●○
23:00🇨🇳Exports Year-over-Year——27●●●
23:00🇨🇳Imports Year-over-Year——36●●●
23:00🇨🇳Trade Balance—112.5B125.6B●●●
FRIDAY, AUGUST 7
01:30🇫🇷Unemployment Rate——8.1●●○
02:00🇩🇪Trade Balance—16.7B19.1B●●●
02:00🇩🇪Exports Month-over-Month——0.90●●○
02:00🇩🇪Industrial Production Month-over-Month—00.90●●○
02:00🇬🇧Lloyds House Price Index Month-over-Month—0.200.20●●○
02:00🇬🇧Lloyds House Price Index Year-over-Year——0.60●●○
02:45🇫🇷Trade Balance—-6.5B-6.9B●●○
03:00🇨🇭Consumer Confidence Index—-35-36●●○
08:00🇲🇽Inflation Rate Month-over-Month——-0.27●●○
08:00🇲🇽Inflation Rate Year-over-Year——3.4●●○
08:30🇨🇦Unemployment Rate—6.56.5●●●
08:30🇨🇦Employment Change—15,00018,200●●○
08:30🇨🇦Full-Time Employment Change——600●●○
08:30🇨🇦Labor Force Participation——65●●○
08:30🇨🇦Part-Time Employment Change——17,500●●○
08:30🇺🇸Payroll Jobs Growth—91,00057,000●●●
08:30🇺🇸Unemployment Rate4.2% M4.34.2●●●
08:30🇺🇸Annual Wage Growth——3.5●●○
08:30🇺🇸Labor Force Participation——61.5●●○
08:30🇺🇸Monthly Wage Growth—0.300.30●●○
10:00🇨🇦Ivey PMI Seasonally Adjusted—55.456.2●●●
10:00🇺🇸Speech by Fed's Barkin———●●○
SATURDAY, AUGUST 8
21:30🇨🇳Inflation Rate Year-over-Year——1●●●
21:30🇨🇳Inflation Rate Month-over-Month——-0.30●●○
21:30🇨🇳Producer Price Index Year-over-Year——4.1●●○
SUNDAY, AUGUST 9
19:50🇯🇵BoJ Summary of Opinions Level———●●○
19:50🇯🇵Current Account Balance——3968.0B●●○
●●● High impact    ●●○ Medium impact    CB Central bank event    Our Est. = RoboMacro model forecast. Shown only where a model covers the release; a blank means we publish no estimate for it.    Source: RoboMacro Economic Calendar
RoboMacro AI Economic Research

Global Macro Watch

Week of July 27–31, 2026 robomacro.com

Disclosures & Important Information

AI-Generated Content: This publication is 100% generated by artificial intelligence systems and should not be considered as financial advice, investment recommendation, or professional research. All analysis, forecasts, and commentary are algorithmically produced.

Data Sources: Market data from public exchange and market-data providers. US Treasury yields from the Federal Reserve (FRED constant-maturity series). Macroeconomic data from central banks and national statistics offices. Economic calendar data from RoboMacro Economic Calendar. All data subject to revision and may be delayed.

No Warranty: RoboMacro makes no warranty, express or implied, regarding the accuracy, completeness, or reliability of the information contained in this publication. Data may be delayed, incomplete, or contain errors. Past performance is not indicative of future results.

Not Financial Advice: Nothing in this publication constitutes investment advice, tax advice, legal advice, or any other form of professional advice. Any opinions expressed are AI-generated and do not represent the views of any individual or organisation. Readers should consult qualified professionals before making investment decisions.

Nowcasts and Model Output: The US labour nowcast is the median of a ten-model ensemble. Activity indices are composite z-scores of weekly public high-frequency indicators, seasonally adjusted, published only for weeks meeting a minimum indicator-coverage threshold; the as-of date and coverage are shown on every row. All model output carries significant uncertainty.

Contact: [email protected] | robomacro.com

Publication: Global Macro Watch is published weekly on Sundays, covering the preceding Monday-to-Friday week. © 2026 RoboMacro. All rights reserved.